Small Cap Value Report (Tues 22 Aug 2023) - SEE, CBOX, FEN

Good morning from Paul & Graham!
I have to leave it there today, so today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
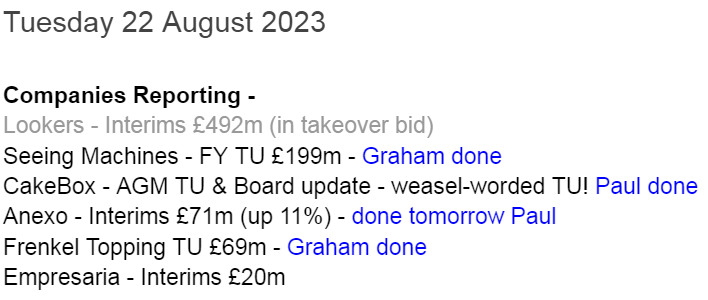
Agenda - quiet today, but we'll see what we can do -
Summaries of main sections
Seeing Machines (LON:SEE) - down 1% to 5.8p (£241m) - Trading Update (revenue ahead) - Graham - RED
These shares are lower despite revenues being ahead of expectations. The cash balance is down and the company has borrowed more from its lender and business partner. Working capital should unwind but I am uneasy with how the company presents continued cash burn.
Frenkel Topping (LON:FEN) - up 5% to 56p (£72m) - Trading Update (in line) - Graham - AMBER
This diversified professional services group provides an H1 trading update: it is tracking in line for full-year profit expectations. There are many subsidiaries and services to study but the overall track record is quite good and the stock may be fairly valued at this level.
Cake Box Holdings (LON:CBOX) - Up 6% to 160p (£64m) - AGM Statement - Paul - AMBER
An acceleration in store revenues is reported, and a reduction in the cost of some food ingredients, sounds positive. All rather spoiled by a refusal to indicate if profitability is in line with expectations or not, which is a change from the equivalent announcement this time last year - which obviously raises questions. Not a good move, when the company has had previous trust issues. In other respects, there are some positive aspects of this share.
Paul’s Section:
Cake Box Holdings (LON:CBOX)
Up 6% to 160p (£64m) - AGM Statement - Paul - AMBER
Board update - the non-exec Chairman is stepping down after 5+ years.
AGM Statement - the current financial year is FY 3/2024. Figures today are for the 17 weeks (c.4 months) to 30 July 2023.
Cake Box Holdings plc, the specialist retailer of fresh cream cakes, announces a trading update ahead of the Company's annual general meeting, being held at 11.00 am today.
Store LFL (like-for-like) revenues have accelerated from +5.4% previously reported for the first 11 weeks, to +6.8% for the first 17 weeks. Many thanks to Liberum’s analyst Wayne Brown, who crunched the numbers, and deduced this means +9.4% in the most recent 6 weeks - very good, and keeping up with inflation (slightly above actually). Although note that the prior year comps were soft (down 2.8% in the equivalent report for 2022 vs 2021).
Remember the stores are operated by franchisees, so this doesn’t directly come through into CBOX’s numbers (hence why revenues are only small at CBOX, but profits are good). It's a good business model, I think.
Input cost inflation - good news here too, with “some improvements” mentioned, eg. fresh cream prices falling, which has been passed on to franchisees, hence not a benefit to CBOX’s figures.
Marketing spend has been increased, no figures provided.
Cash - reported at £7.9m as of 30 July 2023, up a little from £7.4m reported at 31 March. I’m surprised it’s not up more actually, especially as the £2.2m dividend payment is noted as having been paid more recently, on 29 August. So really the figure now is likely to be about £5.2m. That’s enough cash though.
Note there is £1.3m of mortgage debt, although freeholds were valued at £8.7m, so I think it’s fine to ignore the small mortgages when reporting cash.
Overall the balance sheet is fine, when I’ve looked at it before.
Stores - 7 new franchised stores have opened so far this year (4 months). Total is now 212 at 30 July.
Outlook - I strongly object to the weasel words highlighted below. Note how it only talks about revenue being in line with market expectations. What about profit? It dodges the issue, and presumably hopes that nobody notices. This raises questions. Have brokers downgraded profit expectations on the quiet? No, forecasts seem unchanged.
As a result of the above progress on trading and strategy, the Group is on track to deliver year-on-year revenue growth, in line with market expectations.
Looking further ahead, with a strong balance sheet, underpinned by a highly cash generative business model, the recent investment in professionalising the Group's functions and its baking and distribution facilities along with the strengthened sales and marketing functions, the Group is well positioned to deliver shareholder value in the short- to mid-term.
Paul’s opinion - for me, what should have been a positive update, has been ruined by someone trying to be clever and only confirming that revenues are in line with expectations. The whole point of trading updates, is that they’re supposed to inform the market as to how profitability is performing vs market expectations.
Dodging that question makes me wonder whether profits might be slightly under what the market expects, or that they're not confident of achieving the full year profit forecasts? Note that in the equivalent trading update last year (31 August 2022), it said this (specifically reporting on profitability vs market expectations) -
Accordingly, due to the worsening outlook and increasing cost of living pressures on the consumer, the Group now expects full year profitability to be significantly below current market forecasts. [NB. last year, 31/8/2022]
So clearly the change in reporting this year, to reference revenues vs market expectations is a deliberate fudge. I see that as rather deceitful actually, not helpful given CBOX’s chequered history.
Forecasts are for only a marginal increase in adj EPS from 10.6p LY, to 10.9p this year (FY 3/2024). So the fact that it today deliberately dodged the question of confirming whether or not it was in line with profit expectations, raises a question over whether it can achieve any profit growth at all this year.
For that reason the PER of 14.7x doesn’t look particularly attractive to me - given the risk of a profit miss, implied by today’s wording of the TU.
The share price has also been boosted by apparent takeover interest from an Australian suitor, which was mooted at about 160p. Given that it’s owner/managed, I’m struggling to see why the founders would sell at this sort of level? (it peaked at c.400p in late 2021, before the accounting scandal emerged, and note that Directors had sold multiple millions-worth of shares before those problems emerged, which is why I still don’t trust this company I’m afraid - not helped by today’s update’s wording).
All of this is a pity, because I see CBOX as a fundamentally sound business, with good roll-out potential. If we’d had a nice clean update today, saying trading in line with expectations (profits!), then it might have been tempting. But for me, today’s update raises questions, at a company that I already had trust issues with. It’ll probably all turn out fine, and there might even be a possibility of a takeover bid, but for me that’s not enough to tempt me into this share - but there’s a fairly decent bull case for it, so overall I’ll go with AMBER.
You may not share my concerns of course, I'm only expressing a personal opinion as always. But at least it means we can have a range of opinions here, and investors can then make an informed choice on how to weigh the various factors.
Graham’s Section:
Seeing Machines (LON:SEE)
Share price: 5.8p (-1%)
Market cap: £241m
We last covered this one in March.
It is “the advanced computer vision technology company that designs AI-powered operator monitoring systems to improve transport safety”. It benefits both from regulatory safety requirements and from the voluntary adoption of driver assistance systems.
Today it publishes a full-year trading update. Highlights:
Revenue $57.8m is “ahead of the top of end market expectations” (sic).
Annualised recurring revenues $13.6m
Cash $36.8m.
Cash as of December 2022 was much higher at $52m (not mentioned in today’s RNS). The company says in a footnote that due to the timing of deliveries, both inventory and receivables have increased. But it reassures that this is temporary:
Inventory levels are sufficient to support demand for H1 FY2024 and will unwind along with receivables in the first half of FY24.
Even more importantly, the figure shown is “Cash”, not “Net cash”. Seeing Machines has the unusual tendency to report in this way.
Net cash is much lower: the company has a convertible note outstanding, which matures in October 2026. The conversion price is 11p so unless the share price improves, the note will need to be repaid in the normal way.
How much is outstanding for the convertible note? I thought it was $30m. However, a broker note from Cenkos says that the full amount has been drawn down under this facility, which is $47.5m.
Seeing Machines could have simply stated that they drew down the additional $17.5m that was available to them. Instead, in today’s update they refer to the complete $65m funding package from the lender, who is also their business partner (Magna).
With $47.5m outstanding in a convertible note, I think it’s reasonable to treat Seeing Machines as having a net debt position.
CEO comment:
We are very pleased with the progress made during what was a record quarter, and throughout the year, across both our Automotive and Aftermarket divisions. Crossing the 1 million threshold for the numbers of cars on the road with Seeing Machines' technology installed, up 143% year on year, represents a major milestone and a great achievement. With supply chain constraints now easing, our Guardian business continues to go from strength to strength, with over 51,000 heavy vehicles now connected, an annual growth rate of 30%. We can now expect Aviation to be a meaningful contributor to the Company's revenue and looming regulatory deadlines are driving the rapid adoption of Driver Monitoring Systems by automotive manufacturers. Our per-unit, margin accretive royalty model leaves us well positioned to capitalise on the opportunities ahead.
Graham’s view
I have been thinking about turning neutral on this stock, as its revenue and operational progress seem very impressive. The forward price to sales ratio is about 5x, which could be reasonable for a quality business with excellent growth prospects.
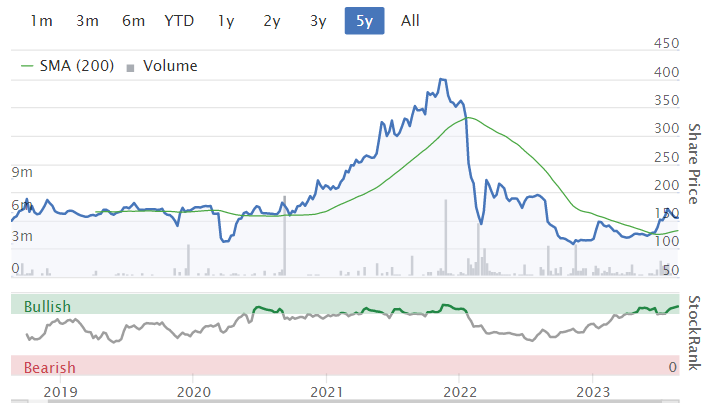
Up until now, I’ve been bearish, due to heavy cash burn and losses. Over the past two years, the chart has mostly agreed with me:

Today, I’m going to remain bearish. Some might consider this petty, but the deciding factor is that I don’t like the way that the company has dressed up a large reduction in its cash balance and a shift into a net debt position.
Sometimes you have to go with your gut, and my gut is telling me that this company is trying too hard to convince investors of its financial strength. So I’ll stick with my bearish view for now.
Frenkel Topping (LON:FEN)
Share price: 56p (+5%)
Market cap: £72m
This is “a specialist financial and professional services firm operating within the personal injury and clinical negligence marketplace”.
It releases an H1 trading update, with a table that looks good - revenue up very strongly, and profits rising with it. Not all of this is organic growth:

The range of services and group companies is vast for a small company.
Outlook - in line with expectations.
The business goes into the second half of the year carrying real momentum from H1, benefiting from the diversification of revenue and encouraging growth in transactional revenue. We do expect financial markets to remain challenging, which will continue to moderately impact AUM growth and the Company's recurring revenue generated from this. However, the Board maintains confidence in the full year outturn and its expectation for the year which are tracking in line with management's expectation.
Graham’s view
I don’t know enough about this one to speak with any authority on it. Back in February 2020, Paul noted the involvement of Harwood Capital and I see that they are still here with a 29.6% stake (just below the figure that triggers a mandatory takeover offer).

The involvement of Harwood isn’t necessarily good or bad news for private investors; it might be a decent and undervalued company but there is also an element of delisting risk to consider.
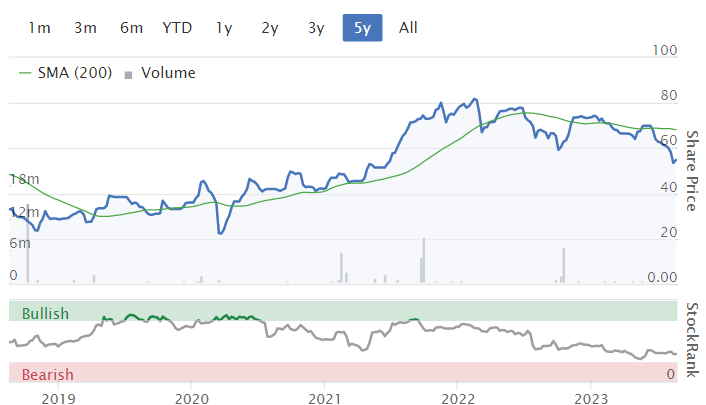
The overall financial trajectory of the company looks quite good (bear in mind that the share count has almost doubled over the period from 2017 to 2023):

For me personally, this isn’t a sector that excites me very much: whenever I read the words “professional services” and “personal injury”, I tend to look away.
However, Frenkel does own an investment manager - Ascensia - which has been developed “for Clients who have been awarded a settlement as a result of clinical negligence or personal injury”. The fees generated by this investment manager should be recurring and high-quality in nature.
At a PER of 11x-12x (depending on how you measure it), and with average “quality” metrics (ROE/ROCE), my working assumption must be that Frenkel Topping is fairly valued here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Rua Life Sciences (LON:RUA) - the AGM statement provided tangible progress on its heart valve and vascular graft products, detail on revenue expectations and reassuring cost control since its FY 2023 results announcement. Our valuation remains at £120.3m (542p per share). New research report here: https://www.equitydevelopment....
Artisanal Spirits (LON:ART) - Taiwan subsidiary uplifts Asian growth outlook *** Today’s announcement by The Artisanal Spirits Company that it has successfully launched a new subsidiary in Taiwan is important. The country is the world’s third largest market for Ultra-Premium Scotch Whisky globally, and thus one which should welcome the ASC’s unique offering of single cask malt whiskies. Moreover, the action is consistent with the ASC enjoying significant headroom for incremental revenue growth – notably through Asian expansion. We continue to argue that fair value for the shares is 150p, and Asian strength supports this view. New note out today: https://www.equitydevelopment....
A lot of talk over the past few weeks around director buying and how that can be a bullish sign, especially when the buys are sizable. I was a holder of On Beach group (LON:OTB) and enjoyed the 25% gain it experienced. One thing I did note was the huge trade caused a spike in the SP moving it up about 5% at the time. It was only once the announcement was made that this was the founder that the SP moved up 15% in a day.
My thought is that can we as nimble investors/traders look out for these sizable trades and jump in to get the potential bounce if it does turn out to be directors or people of worth. I have seen that among the JD Sports Fashion (LON:JD.) selloff today (which seems quite unfounded based on US company Dick's Sporting Goods (NYQ:DKS) warning on profits due to theft and poor performance of its outdoors area), a buy of 8million quid just came through, might well be Mike Ashley adding, which is a bullish sign for me. I am taking a gamble on this and have doubled my holding.
A second large trade, 10million quid this time, has also gone through. I expect the same buyer. Worth noting these trades have both gone through at 152p, when the SP is currently around 142p. A decent premium of around 7%.
"My thought is that can we as nimble investors/traders look out for these sizable trades and jump in to get the potential bounce if it does turn out to be directors or people of worth"
Apart from looking at pictures of carrot men with painful looking tip rot, throwing crumpled up paper - with my eyes shut- into a bin placed on the other side of the room, feeding a stray cat 3 times a day and trying not to get bladdered before the market shuts ....how do you think I fill my day in? :)
Enjoyed this =)
I have just noticed that UK gas prices are up 41% in the last month https://tradingeconomics.com/c.... This could end up being a nasty shock to the inflation falling consensus, if it results in electricity and gas prices jumping on 1 January. Basically, there is absolutely no chance of interest rates coming down if gas and electricity prices jump up to the £3k Energy Price Guarantee level. Of course, if we have a recession prices could fall the other way, maybe to £1.5k (versus the current £2k). Gas and electricity prices could well continue to drive interest rates (and share prices) for sometime yet...worth bearing in mind!
Ofgem will announce a c7% price reduction from 1 October on Friday, but are prices going to jump again in January? This time last year we had some ridiculous movements in gas prices and it looks like it might be starting to happen again from the chart - what do others think...is it time to lock into a fixed price energy deal whilst there are still reasonable 1 year fixes in place? Worth bearing in mind for interest rate sensitive stocks as I think we were all getting a tad complacent that gas prices would merrily fall back to lower levels.
Ofgem will announce a c7% price reduction from 1 October on Friday, but are prices going to jump again in January?
Not based on recent knowns or not materially anyway based on linked article (4 days ago)- it says that modest increases can be expected.
https//www.theguardian.com/mo...
I aint paid much attention but i get the feeling the price cap is a con and was set ridiculously high at the worst posible time for consumers. Note its meant to be price "cap" not the standard price too. We need something that puts consumers first -
what is abundantly clear is that even with the 41% increase prices are still well below the peaks of late 2021 onwards . Looking at price cap in october 2021 price was £1277 - we are now 50% above that level and yet the linked graph confirms prices are below october 2021 levels.
I suspect at present there is no incentive for any company to charge less the price cap even if they can make a decent profit - aint checked to see if that is the case but i would guess they are running like a proper cartel at present !
Hey ho spike back up in prices and another fixed term deal at the top on the way ?
"I suspect at present there is no incentive for any company to charge less the price cap even if they can make a decent profit" Octopus Evergy is charging less than the cap on their standard tariff - and they have others that are substantially less at night time. Definitely recommend people to have a look at their options, I became a customer of theirs via Bulb and have been impressed so far.
I had a look at Octopus, compared to BG, the unit price is the same but the Standing Charge is slightly less, about 1.65p per day on both, so 3.3p per day. So around £12 per annum. Not a big incentive to switch but I may do so, because I'm not happy with BG.
Standing charges have really gone up and are not being reduced.
This coming winter heating season is almost here, and I'd expect electricity generators and gas suppliers to have hedged some or all of their gas supply. So the current spike in spot prices should not interfere with the baked-in reduction in UK energy prices.
The Meerkats were not offering a single fixed rate offer yesterday when I looked, had to go with the variable rate on offer.
Share price movements - manipulated?
Just taking one share as an example Investec (LON:INVP) amongst others
22/2/2023 £5.30
28/3/2023 £4.36
30/5/2023 £4.06
14/6/2023 £4.76
26/6/2023 £4.31
27/7/2023 £4.95
9/8/2023 £4.82
18/8/2023 £4.39 (decline for no reason? down to £4.39)
22/8/2023 £4.65 (up 25p today again no reason or perhaps shares shorted now being bought back again).
Personally, sick of seeing this ridiculous movement in share prices, which seems to be the general theme nowadays.
I sold out of Investec (LON:INVP) following some large director sales, end of 2022, then there has been some more large sales few months back. There is also exposure to problems in South Africa, which was one of the reasons, the shares did fall back from around 500p.
Stock market prices tend to fluctuate!
proffittpar Im not seeing any manipulation to be honest.
Big drop on March 13 was Monday after SVS Bank collapsed. Trading update 16 March, price didnt move. Next day some big volume, dropped 3%. Traded sideways since.
'25 Forecasts are being nudged down since April
Since May Directors appear to be selling any shares they can get their hands on. This is only page 1
To be honest Im surprised its held up as well as it has.
Re trading updates. Companies can only 'reliably' report revenues, as profits usually need audit oversight. Forward looking statements about what the management 'believe' to be meeting market year end expectations are pretty vague on this basis to give an inkling of future expectations, and even there management should be careful about misleading the market. On AIM there is greater laxity about doing so, but if fully listed there would be an investigation of management if they were issue misleading statements, and creating a false market.
I do understand that previous Cake Box FD's have not covered themselves in glory, so an understandable wariness from Paul on this score, and Cake Box is not a company I am interested in, but perhaps a tad harsh on the general point of any profitability references in a trading statement
Re Cake Box Holdings (LON:CBOX) -
perhaps a tad harsh on the general point of any profitability references in a trading statement
I disagree strongly, because as I point out in the article, at the same AGM announcement last year, CBOX did clearly state how it was performing versus market expectations for profitability. So the fact that it was changed this year, is clearly a deliberate choice, so we should be asking why.
Let's not confuse the issue here. It is absolutely standard, and best practice, indeed necessary, for all trading updates to make it clear whether trading (i.e. profitability) is in line with expectations or not. Playing games with the wording, as CBOX has clearly done today, is not good enough. So my comments were perfectly reasonable I think.
I agree with Paul here. A lot of us colour code key words and statements in a company's RNS but what the skilled observer needs to look out for is what is not said in an Announcement. Here we have an indication of Profit mentioned one year but only Revenue the next. The directors aren't stupid so, to me, this is red rag to a bull and I've scrubbed it from my Watchlist. Brokers should be on the lookout for things like this as it could be interpreted as misleading the market.
Cake Box Holdings (LON:CBOX)
Trident
Companies can only 'reliably' report revenues, as profits usually need audit oversight. Forward looking statements about what the management 'believe' to be meeting market year end expectations are pretty vague on this basis to give an inkling of future expectations,
Huh - surely whether they are on track for meeting market expecatations ref their projection of profits is price sensitive and needs commenting on if they are not on target. I dont believe for a second they dont have targets and dont believe for a second they dont know where they are compared to what has previously been released to the market ref expectations (or what market expectations are ) . Surely if they are behind expectations they must say so - if they are on track surely its ok to confirm that ?
Its all about the profits ref business valuations and price sensitive info imho - are you saying the lack of bad news means they should be deemed to be on target ? or are you saying they should say nowt to us - update house broker and then let house broker update expectations - presuming they have a house broker.
If we take a random other aim listed company Somero their trading pdate said the following how come they dont have a problem being clear aned precise?
As such, the Board remains confident that 2023 results will fall in line with market expectations with revenues of approximately US$ 120m, EBITDA of approximately US$ 36m, and year-end cash of approximately US$ 32m.
Hi Trident, I was about to make exactly the same point. Some companies only ever refer to revenues in trading updates eg Hilton Foods (I know because i asked them why they didnt refer to profits in TUs). and some like Games Workshop (LON:GAW) are sometimes completely trappist about trading. This was a TU from March "Games Workshop Group PLC announces that trading in the three months to the end of February 2023 has been in line with expectations." Yup, thats all folks ! No other comment on trading. no figures, no qualitative guff. (Ok the dividend in the next paragraph was the giveaway).
So I think that Paul is being a bit harsh. However (!) looking back at Cake Box's other releases the previous FD did refer to profits as well as revenues. This may be the case of a new FD looking to under promise and over deliver. So there is no set formula. And if you have referred to profits in previous TUs its probably wise to keep up the trend.
I also believe a new CFO has been appointed in the past 12 months, which might be a reasonable explanation for the change in approach - though I agree with others in that it'd be best practice to say they're trading in line with market expectations (vs singling out just the revenue, which begs the question 'what about profits?')
I do love the thought of Cake Box Holdings (LON:CBOX) CFO being a weasel though (a good excuse to experiment with some AI created art!)
CEOs tastefully designed garden development coming along well.
In all seriousness, its an insight into an individual when he has no qualms felling protected trees, just to satisfy his lust for money and status.
Please could you take a look at the interims from Impellam (LON:IPEL) released at 1631 yesterday along with another extension to takeover talks?
Paul,
Many thanks for continuing work and guidance in this peculiar bear market. For myself I am largely sitting on the sidelines unless any existing holding provides a "bargain buy".
Regarding the "weasel words" from £ CBOX fully understand your thoughts in view of the history of this stock. However many stocks issue TUs and never mention profitability and investors and the market don't seem unduly concerned.
However there are certainly stocks where one cannot and do not trust management and where LTIPs and other incentive schemes are put in place specifically to enrich directors and senior management. So you are perfectly at liberty to call out those. Please continue to do so
Steve
Cake Box Holdings (LON:CBOX)
However many stocks issue TUs and never mention profitability and investors and the market don't seem unduly concerned.
More the shame on those companies and as Paul highlighted last year they did specifically mention profits. The fact others pay zero lip service to updating shareholders doesnt make it right or proper.
Hi,
I have been investing for a couple of years and also doing a bit of trading on II platform which is not really suitable for that to say the least. So I’m trying to find a good trading platform with DMA. I have a general question regarding the trading and more specifically the ones with the direct market access: what platforms do you use and what is your experience so far? Thank you in advance if you could share your thoughts. Many thanks.
DMA?
Sorry, It stands for direct market access.
Trading update for Rua Life Sciences (LON:RUA) again stresses its potential, but still no news on the necessary funding. SP up 20% may be misguided
Can you take a look at the £look announcement and any read across Vertu Motors (LON:VTU) ? Thanks
I was having a chat with someone looking for a job in IT at the weekend and he explained that the number of developer/programming jobs have fallen off a cliff because of AI being able to generate code. This will have so many implications for jobs, recruiters and economies (think about India for example). I have been playing with Chat GTP over the weekend and it's very impressive at creating an instantaneous CV tailored to a particular employer. I also asked it to create a short story in the style of Haruki Murakami, and it really did capture his distinctive writing style. Very Impressive - however its jokes are a bit crap!
I use ChatGPT almost daily to help write code, but it's certainly not a replacement (yet).
It's fantastic when you are creating code/solving problems that are mainstream and well understood. Anything obscure or niche is very hard for it at the moment.
There's a lot of hope from non-coding people in tech that programmers will become redundant. At present that's quite far off. What we are seeing is a lot of tools that will make developers a lot more effective and productive.
At the moment, there's simply no money for hiring. Funding has completely dried up and companies are really battening down the hatches unless they really have no choice.
Personally I think that in a year or so a lot of projects that are currently being put on hold will become urgent and we'll be back in a skills crunch.
I 'see' Seeing Machines (LON:SEE) SEE has mentioned the obligatory 'AI powered' reference into their statement – like they’ve had time to integrate the latest AI software into their product? mmmm
I remember when I ooo’ed and aaahh’ed at a friend’s new £1000 iPhone and its, what was science fiction, facial recognition abilities before trying to fool it with photos of the owner about 5 year back. Now my crappy £150 Samsung does it with its 4 cameras, screen based finger print reader(gawd knows how that works?) , Android operating system, free apps, 5”screen, battery, retailer markup, distributer markup, etc, etc. There are already Chinese cars you can buy with facial recognition and it doesn't seem like a huge step to incorporate eye monitoring. I’d be wary about investing in tech where there doesn’t appear to be any significant ‘hardware’ barriers to entry for their eye monitoring/sleepy operator technology? Hopefully there are, as cameras are dirt cheap and I think Seeing Machines (LON:SEE) need to make hay while the sun shines as their technological lead could go in an instant.
I think the big question to ask is: "Do they have data that no-one else has or can easily collect" - if an "AI" company has that then they have an effective moat. If they don't then as you say, it will be pretty easy to recreate with commodity off the shelf hardware.
They don't make cameras. They have 1.3 billion km of data (according to Bard). Tesla claim to have camera based DMS, but it proved useless in comparison to GM (Seeing Machines (LON:SEE) DMS) in a recent test. Facial recognition is simple compared to Driver monitoring I suspect, and it would seem Qualcomm, Magna, GM, CAT, Qantas, Collins Aerospace, Ford, TfL and others potentially hidden by NDA (Chinese?) agree. May not be much of a 'hardware' barrier to entry, but they're a software company.
Could you have a look at Anexo (ANX) please. Seems to be generating some cash at last
What's the catch on this one (apart from it being an ambulance chaser I suppose). It has some debt but that looks manageable and is due to fall. I see WH Ireland have some research on Research Tree. Looks like a PE of 4x forecasting a dividend yield of 3%. PBT of £25.2m boosted by the VW settlement.
Off topic as it seems a little quiet today.
Does any other vegetable growers seem to get all different size and shapes?
The visual representation of some of my mining investments.
Yes mining has been hanging recently but I have noticed it has perked up today.
Looks like the old carrot fly has got in there too
Keep your pecker up!
What's this colour on my screen, blue??!!
Perhaps I’m colour blind, it’s green for me
But some of them are false. My top riser today, up 6.8% according to Stockopedia, has moved not at all, checking live prices on my platform.
My morning smallcap tweet: Powerhouse powers backwards
Powerhouse Energy (LON:PHE) XLMedia (LON:XLM) Rua Life Sciences (LON:RUA) Seeing Machines (LON:SEE) Plexus Holdings (LON:POS) Haydale Graphene Industries (LON:HAYD), Cake Box Holdings (LON:CBOX), Frenkel Topping (LON:FEN)
◄Powerhouse Energy (PHE)► £1m placing at 0.5p, a 34% discount, to finance its new Technology Centre and keep the lights on. 0.5p is 86% below SP 2 yrs ago. [SP=0.76 Cap=30m]
◄XLMedia (XLM)► to be exclusive provider of sports betting content to a North Carolina's Capitol Broadcasting. [SP=11.51 Cap=30m]
◄RUA Life Sciences (RUA)► AGM stmt: rev in line and costs 20% below mgmt exp. Project updates. [SP=16.4 Cap=4m]
◄Seeing Machines (SEE)► guides FY-June rev $57.8m, ahead of the top of end market expectations. Consensus was $53.9m. ARR up 27% to $13.6m. [SP=5.85 Cap=243m]
◄Plexus (POS)► contract announced on the 6 Mar hiked to c.£8m from c.£5m. [SP=3.9 Cap=4m]
◄Haydale Graphene Industries (HAYD)► collaboration agreement with PETRONAS Technology Ventures to functionalise graphene for product applications. [SP=0.96 Cap=8m]
In line: CBOX, FEN