Small Cap Value Report (Tues 26 Sept 2023) - IQG, PCIP, BAG, VID, REDD, TBLD, ASC

Good morning from Graham and Paul!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
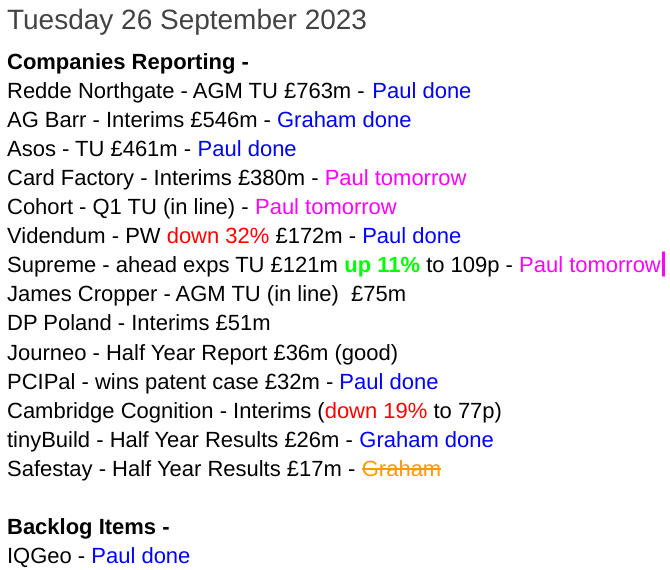
There's far too much for us to cover everything today, but this is what we'll attempt to review - I've parked some of these for tomorrow -
Summaries
IQGeo (LON:IQG) - down 8% y’day to 267p (£164m) - Interims - Paul - AMBER/RED
Very rapid growth from this interesting software company. Looks set to have a breakthrough year into profit (at last). However, the balance sheet concerns me, in particular excessive and overdue receivables, which needs explaining/resolving, as it could sow the seeds for a future write-off. Hence I'm wary because of this specific issue, and valuation looks like it's run ahead of things a bit.
PCI- PAL (LON:PCIP) - 49p pre-market (£32m) - Wins patent case - Paul - AMBER/GREEN
"Total victory" declared PCIP last night, in its UK High Court patent case. Expect a strong rebound in share price today. Well done to holders, this removes a big uncertainty and cash drain.
A G Barr (LON:BAG) - down 1% to 486p - Interim Results (in line) - Graham - GREEN
This Scottish soft drinks maker confirms it’s trading in line with recently upgraded expectations. It grabs volume and market share in an industry struggling with high inflation and lower volumes. I remain a fan of Barr, despite the significant sector challenges it faces.
Videndum (LON:VID) - down 33% to 370p (£172m) - Interims - Paul - RED
Another profit warning, but worse than that, it says an equity raise may now be needed to ease the excessive bank debt. There's also a worrying "material uncertainty" over going concern. We've previously warned here earlier this year about the problem level of bank debt. I see this as too risky until it's refinanced, so uninvestable for now.
Redde Northgate (LON:REDD) - up 2% to 340p (£773m) - AGM Statement - Paul - GREEN
A positive-sounding update, with demand still outstripping supply of vehicles, and residual values remaining strong. That won't last forever of course. So the impressive value stats (a yield above the PER, and full asset backing) may not last at these levels. Extremely tempting to pick up a few at this attractive valuation, I reckon.
tinyBuild (LON:TBLD) - down 21% to 9.9p (£19m) - 2023 Half Year Results (in line) - Graham - AMBER
I’m stubbornly sticking with a neutral stance here despite the company suffering very badly: revenues are sharply lower and recently downgraded expectations may be vulnerable in H2. It still has some cash and forecasts suggest that cash flow breakeven is possible next year.
ASOS (LON:ASC) - down 1% to 381p (£457m) - Trading Statement - Paul - AMBER/RED
Lots of information as usual in this year-end update, which is difficult to pull together. Profits at bottom end of range, and cashflow not as good as expected. But heavy discounting means inventories have been greatly reduced, which is encouraging. I need to see the full accounts to form a firmer view, but remain sceptical, as Asos still has big problems to sort out.
Paul’s Section:
IQGeo (LON:IQG)
Down 8% y’day to 267p (£164m) - Interims - Paul - AMBER/RED
IQGeo Group plc (AIM: IQG), a market leading provider of geospatial productivity and collaboration software for the telecoms and utility network industries, is pleased to announce its interim results for the six months ended 30 June 2023.
I haven’t looked at this company for over 5 years, when it used to be called Ubisense, but always seemed to be promising jam tomorrow, and generating losses, hence I lost interest.
Things seem to have moved on considerably since then, with a big rise in revenues, although still loss-making, and a multibagging share price.
It recently caught my eye when a fund manager was raving about it on a podcast, saying how interesting and useful its software is for utilities companies to track and identify their infrastructure. So I made a mental note to take a look at the next set of numbers, which were published yesterday (interim results).
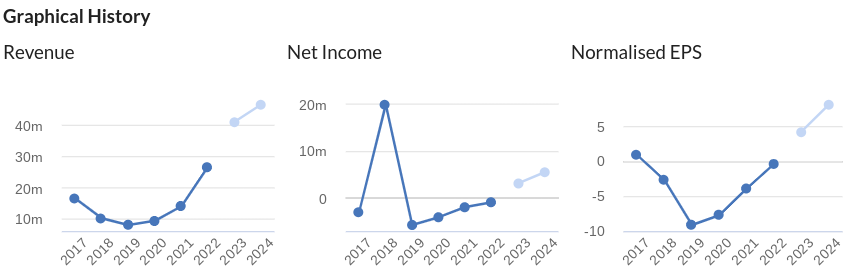
The Stocko graphs below show that it could be about to break into significant profitability (at long last) -
Key numbers for H1 results (to June 2023) -
Very strong revenue growth, up 124% (83% organic) to £20.5m in H1
Exit ARR (annual recurring revenue) is £16.9m, so less than half revenues are recurring (only 35% in H1), which is quite low for a software company.
Costs are also rising fast, which blunts the operational gearing.
Comsof acquisition is going well.
Outlook - in line exps, says outlook is very positive.
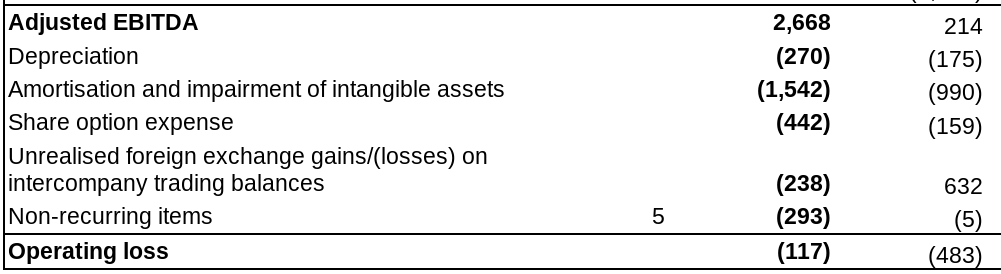
Adj EBITDA £2.7m (up strongly from £0.2m in H1 LY)
Loss before tax of £(177)k, slight improvement from £(483)k in H1 LY
Here’s the reconciliation from EBITDA to the small PBT loss (bold is this year, unbold is LY comparative)-
Balance sheet - I do enjoy it when I find a problem balance sheet, and there is definitely a problem here.
NAV of £21.8m is nearly all intangible assets (of £20.1m), so NTAV is threadbare at only £1.7m. To be fair, software companies don’t usually need much in assets, as there’s negligible fixed assets to finance, and customers often pay up-front. Even so, for £164 market cap company, I would have liked at least some asset backing.
Cash of £6.9m is OK, although trade creditors contains £8.2m deferred income (the amount customers have paid up-front).
This is the problem - receivables (unpaid customer invoices) looks far too high at £13.9m. This item should usually be about 60 days sales + VAT. So c.£8.2m would be about right. There’s actually another £5.7m over and above what’s reasonable. I cannot find any explanation as to why receivables is so high. So I looked at the 2022 Annual Report, and this also showed excessive receivables, with the notes showing that £908k was more than 90 days overdue, and £7.0m was 0-90 days overdue. It alluded to customers having financial problems, hence not having paid their invoices on time.
It looks as if the position has not been resolved in the latest interim numbers.
So we need to find out who these late-paying customers are, why they’re paying late (it might be disputed invoices, not necessarily financial stress), and whether it has since been resolved.
The danger is that IQG might be forced into making bad debt provisions against receivables, which would essentially mean that some previously reported profit was invalid.
Hence we have here the possible seeds for a future profit warning, if receivables write-offs are required. For this reason, I’m wary of this share, and wouldn’t invest unless the excessive receivables issue has been explained and resolved.
Paul’s opinion - looks an interesting company, but I think the market cap might have overshot on the upside for the time being. Also I would need to see the issue of excessive receivables explained/resolved, as that’s too large a risk factor at present, the way I read the numbers.
That said, the very rapid growth does look exciting
PCI- PAL (LON:PCIP)
49p pre-market (£32m) - Wins patent case - Paul - AMBER/GREEN
“Total victory” thundered PCIP last night in an RNS, concerning its expensive & protracted UK High Court battle over patents with competitor Sycurio. More details will follow shortly.
Paul’s opinion - this seems excellent news for PCIP, since the patent case cast a cloud over the company, and was absorbing a lot of fairly scarce cash. Therefore to remove this uncertainty, and financial drag (not to mention management time) is a big boost for the shares.
I think there was also a US action ongoing, so am not sure if/how that is affected by the UK court victory for PCIP. Also what happens with costs, who pays those?
It’s fun to guess what the share price might do (writing this at 07:50), I’m going to say a decent jump could be on the cards, maybe 60-75p today? That looks justified on fundamentals. Anything above that would be getting a little excessive I think. After all, PCIP is still very small, and modestly loss-making, albeit with strong organic growth, so let’s not get too euphoric!
Videndum (LON:VID)
Down 33% to 370p (£172m) - Interims - Paul - RED
Videndum plc ("the Company" or "the Group"), the international provider of premium branded hardware products and software solutions to the content creation market, announces its results for the half year ended 30 June 2023.
Chairman announces he’ll be stepping down at the 2024 AGM. The company seems to think he’s done a good job, but I doubt many shareholders would agree with that.
H1 figures are poor, with problems driven by macro, customer de-stocking, and the writers’ & actors strikes in Hollywood deferring film/TV projects and hence purchases of equipment by customers.
Revenues in H1 are down 25% at £165m
Adj PBT down 65% to £10.1m
Statutory loss before tax is very large, at £(50)m, so about £60m of adjustments there, mostly relating to discontinued operations - looks like something quite big went wrong then.
All the above is survivable, understandable, even. However this is the big problem (as we flagged here on 3 May 2023 - an acquisition splurge, funded by taking on excessive debt, now leaves the company in a precarious position.
Net debt of £216.1m is clearly way too high, although this includes £36.2m of lease liabilities, so net bank debt is £180m. It is close to covenant limits, but these have been relaxed for Dec 2023, so no immediate crisis.
Equity raise - here’s the bombshell that, for now, makes this share uninvestable for me - why take the solvency/dilution risk at this stage? I’d rather wait until after it’s refinanced, then look at it fresh, and maybe then benefit from a recovery in trading once the strikes have been resolved -
We have excellent relationships with our banks and the Group is proactively working to reduce leverage and recapitalise the business, which may require an equity raise.
Going concern - is bad, a material uncertainty -
As stated in note 1, these events or conditions, along with the other matters as set forth in note 1 to the condensed set of financial statements, indicate that a material uncertainty exists that may cast significant doubt on the company's ability to continue as a going concern.
Outlook - in a word, uncertain -
Encouraging news about the strikes, however, it is not clear when productions will restart, therefore there is a wide range of potential outcomes for FY 2023, and it is difficult to provide financial guidance. Nonetheless, when productions restart, the Group remains well positioned and we expect to benefit from a significant recovery in revenue
Balance sheet - is weak, with nil NTAV.
Obviously far too much bank debt too, which was a conscious decision management wrongly took, to acquire too many companies, using too much debt.
If even a humble shares blogger foresaw that management had overdone the debt-fuelled acquisitions, it does make me wonder why they did this? Surely it’s just recklessness, and a failure to plan for any downside scenarios?
My opinion - sorry for any subscribers here holding this share. I can understand that the various factors it mentions have hurt performance this year, and there should be a recovery in due course.
However, the weak, overly indebted balance sheet, means it doesn’t have the financial strength to be able to ride out a bad patch. This was caused by poor management decisions, to over-expand, using too much debt.
It’s specifically told us that it might need an equity raise. I’d say that’s almost a certainty actually. Who knows what terms that might be done on? The discount could be modest, or it could be huge, it’s total guesswork at this stage. So I see existing small shareholders as potential lambs to the slaughter, if whoever refinances it with fresh equity demands their pound of flesh.
The beauty is that small shareholders can sell up, and watch from the sidelines if we want to, a massive advantage over institutions, who are high and dry with their large stakes.
We’ll take a fresh look once it’s refinanced, but for now, I see this as much too risky.
Redde Northgate (LON:REDD)
Up 2% to 340p (£773m) - AGM Statement - Paul - GREEN
Strong start to FY2024 with good momentum and healthy demand
Redde is the no fault accident vehicle credit hire company that works co-operatively with insurance companies. Northgate is the white van hire business in UK & Spain. Simple to explain really, unless you’re the company itself, which comes out with this meaningless twaddle -
Redde Northgate plc (LSE:REDD), the leading integrated mobility solutions platform providing services across the vehicle lifecycle…
Today’s update sounds good - key points -
FY 4/2024 has “started very well”, strong trading, healthy demand.
Rentals - demand outstripping (improving) supply still.
Vehicle residual values still high, giving disposal profits.
Redde - new client win, and “robust pipeline”.
Share buyback - done £3.6m of £30.0m planned.
Debt maturities comfortable, out to 2031.
Dividends - final 16.5p, giving total 24.0p (yield 7.1%)
Paul’s opinion - this is looking very tempting again as an entry point. We know that profits are likely to fall at some point in future, as vehicle residual values normalise, so doing some sums to estimate how that might pan out is probably the key thing to research yourself. I don’t have any access to broker notes.
These value stats look highly appealing, especially the yield that’s higher than the PER, and full net tangible asset backing for the market cap. Chips and rice, as they say!
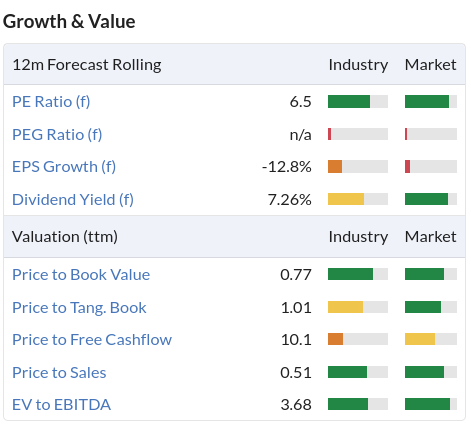
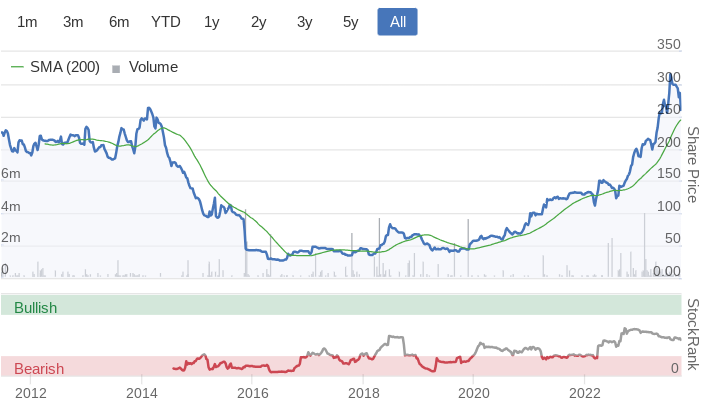
Note the very high StockRank too -
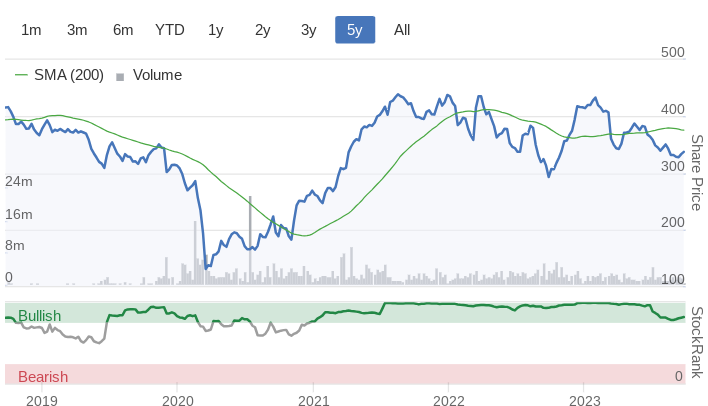
ASOS (LON:ASC)
Down 1% to 381p (£457m) - Trading Statement - Paul - AMBER/RED
This is for the final quarter, and FY 8/2023 (actually 53 weeks to 3 Sept 2023).
Checking back previous SCVRs, I was RED on both 10 May, and 26 May 2023, flagging up awful H1 results, the weak balance sheet, and a very expensive refinancing with specialist lender Bantry Bay. Although on 15 June 2023 I moderated to AMBER/RED, due to a trading update with some signs of improvement, stakebuilding by Frasers, and the potential strategic value of this large, well established online retailer.
Today’s year-end trading update is the usual mish-mash of cherry-picked figures and comments, which are difficult to combine into a coherent overall view. Some key facts & figures -
Revenues down 10% for FY 8/2023 (-12% in Q4) - as expected, since Asos is now chasing profitability, not growth.
Inventories down 30% in the year - this is highly significant I think, as it was seriously over-stocked, which puts a strain on cash. Although it’s having to discount prices (taking a lower gross margin, which has always been too low to begin with, Asos’s achilles heel), and says discounting will continue into FY 8/2024, which isn’t going to help profits.
EBIT at bottom end of £40-60m range is a bit disappointing, and bear in mind it faces large finance costs, which EBIT obviously ignores, so it’s probably loss-making overall still.
“Test and react” model is being used more, and working well - they’re rather late to the party here, other companies like Next and Boohoo have been using that strategy for many years.
Liquidity of £430m sounds ample.
Cash generation - it says has lagged expectations, due to timing differences.
“Partner fulfils” model for third party brands sounds good - which will reduce inventories, and handling costs, this is probably what Asos should have done from the start - just taking a % of the sale, and letting the brands do everything else, and take all the risk.
Exiting unprofitable customers - an increasing trend in eCommerce, and a good thing (e.g. serial returners of large proportions of good ordered, and people using them like a hire shop - wear once and then send back for a refund, etc). Charging for returns in some markets. These are all good, and necessary things - shoppers have been spoiled in the past with free, no quibble, unlimited returns, and it’s become widely abused.
Paul’s opinion - some signs of life at Asos, but it’s a big, lumbering, inefficient ship to turn around. I’d need to see the full accounts for FY 8/2023 before drawing any firm conclusions. I think the shares definitely have some strategic value, since its massive revenues, and established market position with millennials has to be worth something. Could Shein even come knocking on the door with a takeover bid?
The more I look at what Shein, Frasers, etc, are doing in this sector, the less I want to invest in it. Asos shares could go either way, and I don’t really have any particular view on what’s the most likely outcome. Given all the well-known problems at Asos, and its struggle to achieve any level of real profits, I’ve got to stick at a sceptical AMBER/RED for now. Then we’ll react to whatever the newsflow and numbers say in future.
Could the glory days return? Who knows!
Graham’s Section:
A G Barr (LON:BAG)
Share price: 486p (-1%)
Market cap: £544m
This is the soft drinks company whose leading brand is IRN-BRU. The complete list of brands can be found here (including Snapple, owned by Keurig Dr Pepper, which Barr has the right to distribute).
I covered Barr’s ahead-of-expectations trading update in August, and I’ve been positive on the stock in recent years.
The share price has been steady. Here’s the three-year chart:
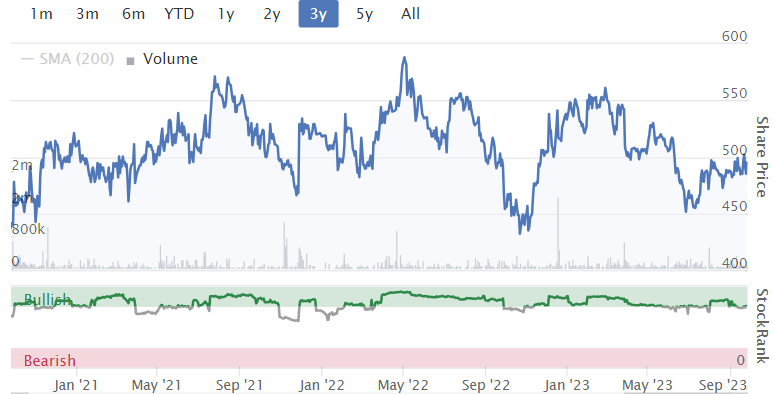
And now onto today’s H1 results, which come with the headline:
Strong first half performance - confident of delivering full year profit in line with recently increased market expectations.
I’ve highlighted some of the bits I find most important:
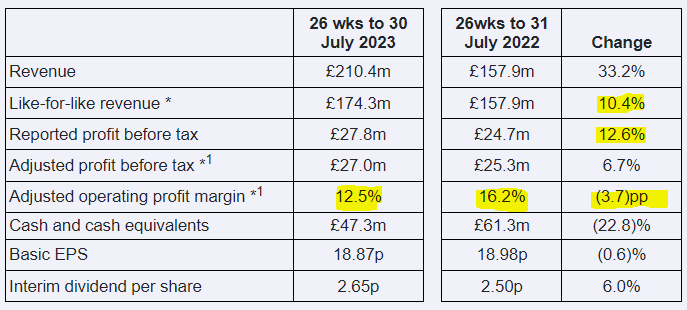
Total revenues are up 33% due to the acquisition of Boost Energy Drinks, but the 10.4% like-for-like growth is proof of a strong underlying performance.
I’m also enthused by the 12.6% growth in reported PBT, even if it’s growing more slowly than total revenues.
The decline in adjusted operating profit margin reflects “the impact of current lower margin Boost business model”.
However, they also say that they “chose not to pass on the full impact of cost inflation to customers in order to remain focused on offering consumers great value”. I’m always sceptical when companies say that they haven’t charged more out of generosity to their customers! But I believe that Barr has already raised prices significantly in the post-Covid era, and they may have felt that further large price increases were unnecessary.
Cash - Barr bought Boost for £20m and also spent a few million pounds increasing its ownership of Moma Foods, so this goes a low way towards explaining the fall in the company’s cash balance over the past year. But they still have a very healthy war chest for future acquisitions or internal capex.
I also note that the company says earnings per share would have grown 12% if not for the higher corporate tax rate. So I wouldn’t be overly concerned about the small decline in EPS.
CEO comment:
"We have made significant financial and strategic progress in the first half and have exciting plans in place for the balance of the year to sustain our growth momentum.
We remain confident in delivering a full year profit performance in line with our recently increased market expectations and are well positioned to deliver strong shareholder returns for the long-term."
As we’ve previously noted, this CEO is planning to retire over the next year - I’m expecting a very orderly transition as the company has plenty of time to find his successor.
Comments on the soft drinks industry are relevant for some other shares we cover here, including the likes of Nichols (LON:NICL) and Britvic (LON:BVIC) etc. The UK soft drinks market has increased in value by 8% in H1, even though volumes were down 4.2%. This implies double-digit price inflation. Barr says that they gained “both value and volume market share”. If that has come at the cost of a slightly reduced operating profit margin, perhaps it’s worth it!
Outlook excerpt:
We have strong plans in place across the business for the balance of the year to support our growth momentum. In August we communicated our expectation of delivering a full year profit performance marginally above the top end of analyst consensus. Despite the extended period of poor weather across the summer, we remain confident in delivering in line with these revised market expectations.
Graham’s view
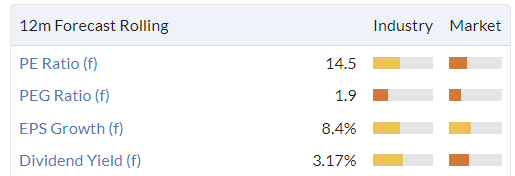
There’s no reason to change my view on A.G. Barr today - I’m a long-term fan of this one, and it remains attractively priced in my opinion:
There are some long-term concerns about the soft drinks industry:
Sugar tax (since 2018) - a sign of things to come, with increasing taxation and regulation of sugary drinks?
Packaging - the deposit return scheme will complicate matters if and when it is introduced (possibly in late 2025)
Competition - there are new entrants to the soft drinks market, particularly from popular YouTubers (e.g. Prime).
So for a variety of reasons, you could argue that Barr should trade on an average mid-teens earnings multiple, i.e. at its current valuation. However, I’ll stick to my guns and continue to give Barr the thumbs up, as I do consider it to be an above-average company trading at an average price.
tinyBuild (LON:TBLD)
Share price: 9.9p (-21%)
Market cap: £19m
tinyBuild (AIM:TBLD), a premium video games publisher and developer with global operations, is pleased to announce its unaudited results for the 6 months ended 30 June 2023.
The market seems to be less pleased than the company is!
Key points:
Revenues down 19% to $23.3m, “primarily due to a sharp drop in development service revenues and underperformance of Versus Evil”.
Adj. operating loss $4.7m
On the income statement, there is an actual operating loss of almost $32m.
The company suffers a $19m impairment of development costs it previously capitalised, along with various other impairments which add up to $28m of balance sheet damage. That explains the difference between the adjusted and the actual operating loss.
Cash: $14.3m, down from $26.5m at the end of December 2022.
The cash flow statement shows $6.5m of cash from operating activities, but then another $17m was spent on software development (the type of spending that just resulted in a huge impairment bill!).
The financial performance is clearly awful, but let’s see if the comments from the company can inspire any hope.
Outlook excerpt:
The combination of a weak macroeconomic environment, geopolitical instability and shifts in the industry dynamics, dampens the Company's growth potential in the near-term.
The pipeline for coming months includes a number of new titles (e.g. Critter Cove, Kill It With Fire 2) and further expansion of the catalogue (e.g. Cartel Tycoon launch on consoles), but headwinds observed in the first half of the year will likely continue to weigh on profitability.
So no, these comments are not going to inspire much hope, but they do also say that they are “on track to deliver results in line with recently-reset expectations”.
I’ve checked the latest note from Progressive Research; they say “meeting estimates will require a recovery in H2 benefitting from seasonality, strong performance from the H1 and H2 releases, and ongoing cost management”. So it sounds as if there is a lot that needs to go right, in order for this to happen.
The 2023 expectations are: revenues of $50m and adjusted PBT of $0.5m.
The 2024 expectations are: revenues of $53.7m and adjusted PBT of $1.1m.
CEO comment:
"The first half of 2023 was a story of two halves, with strong underlying direct sales to consumers, offset by a sudden drop in development service revenues. The speed of change in the video games industry is insane and we know we have to adapt quickly if we want to grow above peers. For this reason, we have been gradually shifting towards what we call the 1000-hour game…
"Our core strategy hasn't changed: we are building a diversified portfolio of own-IP, which gives us the best upside with the minimum risk.”
Graham’s view
Looking back on my notes from June, it would have been reasonable to give this one the thumbs down at the time - it released an absolute horror show profit warning at the time.
Today’s release raises doubts in my mind as to whether full-year expectations can be met, and the downbeat outlook comments suggest that investors should be very careful in terms of their growth expectations moving forwards.
On the other hand, the reason I stayed neutral in June was because the company said that it expected to finish 2023 with cash of between $10-$20 million. It reiterates this statement today, although the analyst at Progressive is estimating only $10.1m, the very bottom end of the range.
Cash is clearly moving in the wrong direction but surely the company is going to want to stop burning it before it gets itself into debt? Now with a sub-£20m market cap, the estimated year-end cash balance does account for a significant portion of the market cap (especially after today’s further share price decline).
Therefore, I still can’t bring myself to give this one the thumbs down. Their acquisitions from 2021 have been impaired; surely they aren’t going to waste their remaining cash pile on more bad deals? They say “M&A multiples still appear anchored to unrealistic expectations, so we stepped away from some potential acquisitions…”, which I take as a positive sign.
On the other hand, their development spend is still huge relative to the size of the company. $17m of capitalised spending in the last six month period is not far off the market cap of the entire company! There is a risk that they are going to spend themselves into shareholder oblivion - but I’ll keep a neutral stance for now, optimistically hoping that they can get back to cash flow breakeven next year, in line with market forecasts.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

97 comments
IQGeo (LON:IQG) - I hold
Hi Paul,
I was surprised when I saw that you had marked IQGeo as Amber/Red - particularly after such an incredible year of growth - however, I can understand your reasoning when there is little explanation in the results.
The trade receivables are high; however, so are the trade payables (extract below). Both have grown in proportion to each other and also match the incredible rate of revenue growth and therefore I feel less concerned.
I believe that two of their largest customers (American giants) are on 90 day payment terms and one of them pays on the first day of the quarter - which doesn't help the receivable figures!
I feel that it is also worth mentioning that IQGeo has grown so quickly that it is actually growing substantially within the period and therefore your "(60 days sales/ days in period) x period revenue (£20.5m) + VAT. So c.£8.2m" calculation may be undercooking it a little. The last 60 days (or 90 days for some sales) will have higher sales than the average 60 days of the period.
In addition, regarding the debtors only around £20K remains outstanding from 2022 or prior. Almost all of that £7m has been paid. There was a significant number of deals that were invoiced late in 2022 and these were settled early in 2023. This was mentioned by the FD.
In regards to profitability, the company has scaled up in preparation for further growth which I feel is justified considering what they achieved in the last 12 months and the incredibly long runway. I personally have a feeling that they are only just getting started.
The subscription and maintenance & support revenue have far higher margins and as the company matures these will become a much larger proportion of sales. This should lead to far higher profitability, which is in the current forecasts.
I suspect that the management team are once again underplaying the growth to analysts as they want to stop us all from getting too carried away. There have been numerous upgrades over the last 12 months and I would suspect that we will get another one closer to year end - they did £20.2 rev in H1 and Cavendish have them at £41.7m rev for the full year.
Fingers crossed and many thanks!
Pendragon (LON:PDG) And then there were three:
“The Board of Directors of Pendragon (the "Board") confirms that it has received an unsolicited proposal from AutoNation, Inc. ("AutoNation") to acquire the entire issued and to be issued share capital of Pendragon for 32 pence per share, in cash (the "AutoNation Proposal"). The AutoNation Proposal remains subject to a number of pre-conditions, including the completion of due diligence”
I do like a potential bidding war when I’m a shareholder
Any chance one of them could turn their attention to Vertu Motors (LON:VTU) ? Sharing is caring after all!
Redde Northgate (LON:REDD) Why are they carrying on with £60m of buybacks planned, on top of £53m last year, when they are paying 6% on £202m of bank debt? With interest rates of 1 or 2% this might be slightly more acceptable but currently this, IMO, is mismanagement of the financials.
The trend to buybacks is a complete gamble for most Boards as they have no greater knowledge of what is going to happen to the share price than we do. It is NOT a return to shareholders, it is an invitation to STOP being a shareholder. A return to shareholders rewards someone who CONTINUES TO HOLD - give me a dividend any day but not paid out by increasing debt.
If we want a higher EPS Consolidate. The marginal increase achieved through buybacks is by and large irrelevant most years. There are of course examples where this has made a huge difference over time and perhaps there are tax advantages for some organisations here or in the US that add value to them. Perhaps Boards should be made to publish the average price at which buybacks have been made each year before asking for permission to do more in the AGM resolutions? And for balance they could add the impact on EPS achieved by the exercise too.
Appreciate there are different views and Graham is keen on buybacks, for example. I think they should be banned, but don't really feel strongly about it!!
I’ve come to the, probably mistaken, view that the Boards of companies who authorise share buy-backs, when there is o/s debt, do so because they believe the return for shareholders is greater than paying down the debt.
The overall cost of their debt is 3.1% - it's also mainly fixed for a long period, while the overall level of debt looks comfortable too. Remember the debt is all asset backed agaisnt their vehicles.
They should be able to achieve a much higher return than 3.1% through buying back their own shares at current prices (at least 15% based on earnings yield) , so I'm personally more than happy for buybacks to continue.
I think the buyback decision is usually a little more complex - companies will identify an optimum level of debt for the business that balances the risks of leverage with the tax benefits of debt funding.
Interest is paid above the line (i.e. reduces earnings and therefore corporation tax), and the cost of debt is usually well below the implied cost of equity. Boards will seek to achieve the optimum balance to minimise their overall cost of capital and the tax bill.
If this indicates that the optimum position is higher leverage then they can take on more debt - the choice is then whether to use those funds to invest in the business or to retire equity. If deploying the funds as capex is difficult at that juncture then buying back shares may be the sensible alternative.
Of course the ehancement to EPS is highly favourable to management who probably have share awards where EPS growth is one of the key measures....
Yet Progressive Equity Research remain positive on the stock . I think it would be a good idea if would could make a list of all the research companies who have floated duds and print a list on Stockopedia would make interesting reading I'm sure !!
Supreme (LON:SUP)
More comments about ethical shares here today. Each to their own - for some it is gambling, others weapons etc.
Regarding SUP and under age purchases it is worth repeating this slide from the last presentation that I posted here a few weeks ago:
You can listen to the CEO discuss this from 22 mins 25 secs in here:
The challenge here is that just because they don't target younger audiences, it doesn't mean that younger audiences are not buying.
No it doesn’t. Just like they don’t buy alcohol nor tobacco nor go to over 18 nightclubs with fake IDs …. And and and……
The key is that Vaping is far better than smoking - it should be better regulated at point of sale to stop under 16s buying it (as far as poss) and disposables need replacing in this day and age. Supreme (LON:SUP) are probably the most vocal about regulation in the entire industry. Their model is not designed around vaping (tho clearly benefitting) it is around fast moving goods through a highly reputable supply network. Ultimately they will benefit from better regulation and their own products packaging etc are clearly designed for adults. The new distribution of 3rd party brands are not necessarily though which is a bit of a negative.
So is contributing £350000 to a political party
Which was done personally and not by the company.
No CEO should be allowed to donate to a political party irrespective of office or opposition.
There you go that solves that.
It does of course mean that both parties go bankrupt but hey ho.
Vaping might have started out as a smoking cessation product.
But it has now become a nicotine addiction product.
It's evil.
Supreme (LON:SUP) -statistically, less likely to contribute to early deaths than purveyors of sugar-laden drinks - but I don’t hear this objection being raised to A G Barr (LON:BAG) , Nichols (LON:NICL) Britvic (LON:BVIC) . We all have personal feelings about the ethics of companies we invest in - I, for instance wouldn’t invest in Record (LON:REC) because of its founder’s man-made climate change denial. However, I think that these personal preferences should only be advertised here where there is a chance that the objection has a reasonable possibility of impacting company and, therefore, share price performance. In this case - as it was with Boohoo (LON:BOO) and its environmental impact - there is a valid reason to mention it. However, as with Boohoo (LON:BOO) all sides of the argument need to be weighed up and I believe with both this board needs to take a balanced approach. Vaping has a valid role to play in reducing smoking and that worthwhile role shouldn’t be obscured by the unintended consequence of making vaping more widespread among young people than smoking might have been previously. Supreme (LON:SUP) have clearly stated that they agree with banning vaping for young people. Now do you think the sugary drinks manufacturers would be quite so enthusiastic about a similar ban?
Wonder if Saga (LON:SAGA) is a bit leaky ahead of update tomorrow? SP up over 7% this afternoon!
If you read Anthony Bolton's book, "Investing Against the Tide", he says that he dislikes the PEG ratio. He said that given a choice between a company on a PE of 20 growing at 20% pa and one on a PE of 5 growing at 5% pa, he'd take the latter every time. He didn't explain his reasoning, but I suspect his reasoning is that such a good valuation has a lot upside potential if the company is able to grow at even modest rates.
Apropos of nothing in particular, I tried Vimto once. It tastes like fizzy cough medicine. So it's a bit of a love-or-hate thing.
"Simple to explain really, unless you’re the company itself, which comes out with this meaningless twaddle"
This actually annoys me a little. Why can't companies just say what they do, instead of resorting to MBA-speak. Contrast that when I scanned through the BAE Systems (LON:BA.) website, where I learned that the submarine division describes its activities as "making submarines". See, that wasn't so difficult, was it?
Given private investors skill for picking the wrong sectors regularly, this is interesting (US)
Considering the weak market lately homebuilders/suppliers have held up well. Looks like stage 2 may be starting to emerge as investors look out to 2024?
That's interesting. All the hot-topic items are there: big tech, EVs, renewable energy, AI.
I'm surprised dividend investing scored so high. The US has high valuations, making yields pretty small. Also, the US tends to favour share buybacks in preference to dividends, so I imagine dividend investing is pretty difficult in the US.
I was actually talking to a British mate who has lived in America for a number of years. We had a debate about the US/UK divide, and he said that share buybacks were shown to be effective. Well, he's probably right, but I've got to say, I much prefer the old-school UK way of doing things, and I'm glad that the companies I tend to invest in think likewise.
It's interesting to hear about how commodities are lowest on the list. I was reading an article about how commodities do well in higher-inflation environments. It prompted me to reconsider things and hold onto my shares that are commodity-related.
Good news fromCML Microsystems (LON:CML) that the us authorities have approved the purchase of Microwave technology inc. let’s hope the synergies work and put a rocket under the share price which has been drifting
tinyBuild (LON:TBLD)
Highlighting that management have buried a bit of a shocker in Note 13 to the financial statements (in already horrendous results) highlighting that there have been two legal claims made against the company, one from the company they acquired (Versus Evil) and another from a Red Cerberus employee - pasted full excerpt below.
I'm a previous shareholder but now wouldn't go anywhere near this company. I believed in the story the CEO was telling but loss of key staff, references to ego projects such as 'the 1000 hour game', enormous write-offs of miss-allocated capital, poorly judged and executed M&A, lack of governance (three independent board members including previous CFO of Boohoo who have sleepwalked into the current position) and a CFO whose main credit is being voted number 1 stock picker in 2019 are all big red flags.
I think most questionable is how you could trust management's ability to generate a return on investment when they've just had to write-off an amount equal to the market cap of the company.
--
13 CONTINGENT LIABILITIES
In November 2021, tinyBuild acquired Versus Evil LLC ("Versus Evil") and Red Cerberus LLC ("Red Cerberus") from third parties ("claimants"). The claimants allege that tinyBuild breached three material obligations under the relevant Membership Interest Purchase Agreement (the "MIPA"). First, the claimants allege that tinyBuild was obligated and failed to make timely capital contributions to Versus Evil during fiscal years 2022 and 2023. Second, the claimants allege that tinyBuild was obligated and failed to release to the claimants certain funds that were held back under the terms of the MIPA. Third, the claimants allege that tinyBuild was obligated and failed to provide material support to Versus Evil that was promised under the MIPA.
In May 2020, a third party contracted with Red Cerberus to provide consulting services. tinyBuild acquired Red Cerberus in November 2021 along with the rights and obligations under the relevant Consulting Agreement and Nondisclosure Agreement with the third party. The third party alleges that in 2022, a Red Cerberus employee misappropriated the claimant's confidential information while employed by Red Cerberus and asserts potential losses in both the United States and Brazil. The third party has submitted a demand for indemnification against such losses to Red Cerberus.
The Group has obtained professional legal advice and considers that it had strong and convincing arguments for disputing the claims. At 30 June 2023, management considered probability of payment to be remote and no provision had been recognised.
Thirteen contingent liabilities, you say? That's an unlucky number for sure.
Perhaps we shouldn't be too surprised that the shares are down 43% today.
Where the coverage for Anglo Asian Mining? That was a favourite for many of you and I think Paul was upbeat about it for a long time. Down 43% today!
I can't find anything in the archive about Anglo Asian Mining (LON:AAZ) written by me. Jack did mention it in 2020 and 2021, so possibly that's where you're getting muddled up? Obviously that's long out-of-date now.
As a rule of thumb, if it has the words "mining", or "resources" in the name, then the chances of me having written about it are basically zero!
Paul.
Hi Ben
Anglo Asian Mining (LON:AAZ) has been drifting for a long while, obvious regional issues that are going on and for UK investors you really need to understand these below the headlines that occasionally make the UK based press.
The delay of one of the mines coming on line, and the statement today about the lowering quality of ore, resulting in less metal and lower profit, which is always a big flag in mining.
Is there anything buried within the news which means this might actually be a good entry opportunity, such as just gone through a fault and that the ore quality confidence is higher for next year? Or just something that might be heading to the 90% club?
I sold a while ago at a loss.
Tommy
Hi Ben, you'll never find much in the way of small miner info on the SCVR, miners not being particularly welcome. They are more likely to evaporate and disappear than any other sector IMHO. I hold Anglo Asian Mining (LON:AAZ) with bated breath, the dividends are cancelled so that doesn't help the SP. Azerbaijan and Armenia, both ex-USSR satellites, are at each others throats and by way of being in the Russian sphere of influence may both find themselves roped into the Federation which will sort out that problem and AAZ go the same way as Polymetal International as far as UK investors are concerned.
Silver
Hi Graham, many thanks for your views on tinyBuild (LON:TBLD) - I see cash at 14.3 not 13.3 - additionally they did acquire "Not games" for $1.5mn and up to a further $4.2mn depending on performance.
The current trade and other payables is $13.9 so hopefully H2 is significantly better than H1 (from looking at previous statements, very much H2 weighted) otherwise the $35m debt facility will be in play....
Hey, thanks for the comment beatingmrindex. That cash figure must be a typo, I'll fix it. Cheers. G
Lots of company results today but also plenty of funds with an overview of sectors and markets to meet too...
Register for FREE for our Trusts and Funds event Today http://us06web.zoom.us/webinar/regist…
Featuring @OceanDial; Polar Capital; @IEMplc; @JPMorganAM and much more!
http://melloevents.com/mello-investme…
I'd be interested in views here on % cash in their portfolios. I am currently effectively 36% cash including gilts, shorts and recommended cash bids. I still feel this is a little lighter cash position % than I'd like to be at this point in the cycle. I've set myself a target of trying to get to 40% without reducing income (easier than normal with cash at c3% and gilts at c5%). What are views on optimal cash % holdings?
I know its probably wishful thinking on trying to time the market, but the inverted yield curve indicates a >70% likelihood of a global recession within the next 6-12 months. The hike cycle has been paused, so central banks are waiting for something to break before moving rates down. Peak gloom and max. drawdown is historically once they have lowered several times aggressively (not now) which is still someway off in my view. I'm watching the US markets; until these break I can't bring myself to buy any more UK stocks in any size.
30% cash.
Topvest
I share your sentiments. Our 2 ISAs are currently 58% and 32% cash. I haven’t committed this year’s allowance of £20k to each putting one lot in a fixed rate cash ISA and the other in Premium Bonds for now! Very trying times.
15% cash
I am quite high, so the kids are fully invested in JISA. My sisters ISA about 70% cash after some recent sells. Mum, just moved 20% from stocks and shares to a cash ISA (monthly interest) and about 20% cash left in the stocks ISA. My ISA about 35% cash, SIPP some thing like 70%, the other pensions are all fully invested.
There is no wrong answer...
Re Cambridge Cognition Holdings (LON:COG) - the January acquisition of Winterlight which flew in the face of expectations that the organic growth was going to be sufficient to deliver objectives was a big red flag to me and I sold that day. No regrets since.
For balance, I’m an unhappy holder of Videndum (LON:VID. How I wish I’d sold when the strike hit and shares were twice as high.
It seems I’m much more active in reacting to perceived management missteps than to external mishaps. It goes back to my days running businesses when you just accept being tossed on the waves of economic fortune and don’t worry about the impact on the company’s valuation, unless you’re in an active sale process.
I must learn to consider the market reaction more!
Just on a point of order and a reminder to all.
Paul regularly reminds us that he and Graham prioritise their daily commentaries on shares that have had particularly interesting news and / or large share movements.
I see in todays comments there have been around 10/12 requests for a write up on shares that have hardly moved with requests being presumably prompted solely because they are held personally and there has been an 'in line' RNS and not much more.
I think we all need to restrict such requests to those with large share movements only, as Paul has asked us to.
Paul and Graham's time is a scarce resourse so let's not waste it.
Snazzy
Hmmmm, disagree - given how illiquid some shares are currently, I'm not sure using SP movement as the arbiter of what is interesting and not makes a lot of sense..
ASOS is pretty much inline, and has hardly moved at all, yet that's being looked at.
Paul and Graham are entitled to look at whatever they like, but asking members to stop discussing companies they find interesting is, in my opinion, an unfair request, and will worsen the quality of debate and discussion on the forum.
I sort of part agree .
I do think it’s a bit lazy asking Paul / Graham to review without doing a bit of an analysis not matter how basic / bad yourself and making a token effort to comment.
Personally and no disrespect to Paul / Graham I generally find the best insights come from other readers who may have had a longer holding and clear insight into the company they have known for many years .
Paul and Graham know a few companies very well but a lot of companies they can only touch upon .
The real golden nuggets tend to occasionally come from reader comments more so than the Paul / Graham analysis .
I think Paul / Graham will agree and I’m not denegrading their work and output .
I agree with you planetx. There is some fantastic reviews by subscribers who have spent a lot of time reviewing certain companies. As with Paul Graham and Roland’s reviews you need to take any comments and reviews as ideas but it is a good place for for ideas to start with. Long may readers continue to add their ideas here. And thanks to all that do contribute.
100% correct on this one.
Cohort plc (LON:CHRT) echoing Paul's earlier comments - ongoing momentum in order book reported and we keep outlook and fair value (650p/share) unchanged. New note published today with audio summary here: https://www.equitydevelopment....
PCIP - Been a long term holder here. I originally bought as one of you coffee cup shares Paul. Hopefully the court judgement will also remove uncertainty for potential customers and allow PCIP to reach its full potential. If court costs are recovered it hopefully will be profitable very soon.
Good Morning Paul, any chance of taking a look at todays Niox (LON:NIOX) update should you get a moment please?
My wife and I are in Pescara so I'm not as glued to Stockopedia as I normally am, it will not have escaped other holders of Vertu that the shares are attracting some buying. Do other subscribers also think that as the only sizeable quoted dealer left, once the fight for Pendragon ends, Lithia or Hedin in their apparent determination to be in the UK, could go for Vertu? If that happens what would be a fair bid price? Paul and Graham if you read this, any thoughts to pass on?
Videndum (LON:VID) sold my now very small holding, although it was much larger when bought. Thankfully I choose not to add. The straw that broke the camel's back was the 'Material concern' disclosure. There is bound to be an equity raise and disgruntled institutions will understandably require a significant discount to wherever the share price ends up.
It may well turn out to be a bargain at the the current price, but there are plenty of small cap bargains available at the moment without the worries of holding Videndum (LON:VID)
Material uncertainty
As a result of there being a plausible scenario whereby covenants are breached, the Board has determined that a material uncertainty exists that may cast significant doubt on the Group's ability to continue as a going concern, such that it may be unable to realise its assets and discharge its liabilities in the normal course of business. The key judgements surrounding the material uncertainty are the length and depth of the ongoing writers' and actors' strikes, as well as the length of time over how long it takes to recover once the strikes end, and the recovery from the broader macroeconomic challenges faced by the Group. Further detail on the assessment of going concern can be found within note 1 to the condensed financial statements.
I also sold out Videndum (LON:VID) this morning. The situation was just a lot worse than I thought. As well as the things you mention, I would just add that the plausible downside scenario where the new more lax covenants are breached and available liquidity falls to zero by July 2024 are only:
"that the strikes last until December 2023, there is continued destocking, and no improvement in macroeconomic environment".
I am not an expert on how long the actors's strike might continue but no improvement in macro and continued destocking do not appear remote scenarios at all.
Indeed, the likelihood of an equity raising looks high to me, although it may not be imminent. Alongside the relaxation of the covenants, there is "a requirement to prepare a deleveraging plan by February 2024 if certain [unspecified] conditions have not been met".
I was put out also by the balance sheet seeming to show £17.9m of cash but according to the cash flow statement and note 9 seemed to say cash at end June was £13.6m.
Hi Paul, if you have a moment could you look at the news from Oxford Biodynamics (LON:OBD), they have launched a Prostrate Cancer test that improves the current predictive levels from 55% to 95%. This is great news for OBD and for men (of a certain age) in general.
Stunning move up from Oxford Biodynamics (LON:OBD) today, well done to holders. We briefly discussed it here a while back, but I didn't pick up on the news early enough today to make it worth commenting. More a jam tomorrow thing, so not much we could say in a value report anyway. But always a pleasure to see something shooting up over 100% and people making a bob or two! :-)
Oxford Biodynamics (LON:OBD) -> nice news and been supported by very magnanimous shareholders over time…but there’s still a lot of expensive sales work to do with their prostrate screen and other EpiSwitch products…so jump deserved but I’ll guess that it’ll give back at least half in next two weeks
If the PSE test performs as indicated this will be a game changer for prostate cancer screening and current share price will look dirt cheap in time even taking into account sharp rise
EKF Diagnostics Holdings (LON:EKF) some indigestion at its South Bend enzyme fermentation facility as previously reported, but getting back on track. Very solid performance from its point of care division. All in all respectable interims in my view.
Cash of £9..2m, but £2.4m is 'frozen' in its Russian subsidiary, so £6.8m available. Surprisingly good dividend at the current share price and positive outlook. Bought in around the current price, Happy to hold.
Paul/Graham any thoughts?
PCI- PAL (LON:PCIP) I assume they will be awarded costs given the win was clear and absolute; a very useful injection for a small growing company! Well done the management for sticking to their guns.
Good guess at the share price Paul!
Good morning all,
If possible, please, could you have a look at LON:EKF.
Journeo (LON:JNEO)
Super half year results from these guys. Lots of net cash (after accounting for prepayments), order book up to £55m. Excellent organic and inorganic sales increases matched by profit.
very strong business momentum behind it now which I see as the most important angle.
Nice to see it ticking up - surely not a small cap going up on results??!!!!!! Am I hallucinating - they must have been good :)
Correction , their pipeline is 55m but their order book is still 27m but all looks good. Question I am starting to ask is how much is now built into the price and how much more can it grow. I continue to hold but am considering top slicing as its now my 4th largest holding.
Sorry - yes, pipeline is £55m though that is generally quite a well qualified one but order book of £27m is also good and that has gone up by about £3m since results so about £30m.
They should be doing around 20p eps this year and given net cash is a big chunk of the current share price a PER before cash adjustment of 11.5 * is far from expensive.
they’ve only just started their European and US expansion though so more than enough opportunity to continue growing at a good pace. I am not tempted to do any top slicing here but that’s a personal decision for each individual to make of course.
I like the momentum in sales, the platform in the US and the reach into Nordics which will facilitate the likes of Germany and Poland etc. clearly they produce a superb product and have good relationships with customers given the ongoing wins and expansions. I think that bodes well.
Deleted
My morning smallcap tweet: Esken hard questions at airport
Time Finance (LON:TIME) Supreme (LON:SUP) Eenergy (LON:EAAS) Esken (LON:ESKN) ASOS (LON:ASC) Driver (LON:DRV) EQTEC (LON:EQT) Knights group (LON:KGH) Cambridge Cognition Holdings (LON:COG) Belluscura (LON:BELL) £BTG Redde Northgate (LON:REDD), James Cropper (LON:CRPR), Cohort (LON:CHRT), Learning Technologies (LON:LTG), NAHL (LON:NAH), Alliance Pharma (LON:APH)
◄Time Finance (TIME)► Q1 to Aug Own-Book lending origination up 29%. Pretax up 44%. [SP=28 Cap=26m]
◄Supreme (SUP)► guides FY-Mar24 rev £195-205m (significantly ahead of market expectations) and adj EBITDA c.£28-30m, £3.5m above mkt exp. Vape sales strong. Co "acknowledges the wider concerns of youth vaping and remains fully supportive of any proactive measures or changes in legislation that potentially restricts specific products, packaging, flavours or point of sale in the UK". [SP=99 Cap=116m]
◄eEnergy (EAAS)► wins £3m contract to provide onsite solar energy generation to an existing customer. Worth £1.9m to eEnergy, recognised across FY23 and FY24. [SP=5.29 Cap=19m]
◄Esken (ESKN)► Carlyle Global Infrastructure Fund claims Southend Airport has breached term of a convertible loan. Esken will support LSA in defending the action vigorously. Still trying to sell the airport. [SP=3.07 Cap=31m]. I hold.
◄ASOS (ASC)► guides Q4-Sept rev down 12% or 15% at const FX. H2 cashflow improved by c.£140m. Adj gross margin up c.150bps in H2 cf 200bps guided. Can't see if it's in line overall. [SP=379.29 Cap=452m]
◄Driver (DRV)► guides FY-Sep rev slightly down. U/L pretax also slightly below prev guidance of £0.7m (-£1m). Significant commissions secured in Q4 which will benefit FY24. [SP=27 Cap=15m]
◄EQTEC (EQT)► completes technical and commercial feasibility work toward deployment of EQTEC solutions at the site of the former Gardanne power station in France. "I am confident we will secure a tariff, along with critical permits that move us closer to making Biogaz Gardanne a reality." [SP=0.06 Cap=6m]
◄Knights (KGH)► AGM stmt - momentum that was starting to build at the end of FY23 has continued into this FY. [SP=93 Cap=80m]
◄Cambridge Cognition (COG)► gets 3 yr £3m loan at 11.5% PA. Lender gets warrants for £540k of shares. [SP=94.8 Cap=33m]
◄Belluscura (BELL)► gets Hong Kong approval to distribute the X-PLOR portable oxygen concentrator. Wins first order there. [SP=37 Cap=50m]
◄Bytes Technology (BTG)► H1-Aug trading: not even a number just "continued to trade strongly". [SP=NA Cap=NA]
◄Redde Northgate (REDD)► AGM stmt - current trading momentum remains strong. Rental demand in UK&I outstrips supply. [SP=334 Cap=762m]. I hold.
In line: CRPR, CHRT, LTG, NAH, APH
For those that might have missed it, Graham has started a regular YouTube show covering UK shares.
https://youtube.com/@theinvestorinstitute?si=kyNhsOe88G8dPDXA
Very good it is too. A few nuggets yesterday, tho the highlight for me was the phrase 'disgusting set of accounts'
There's a couple today verging on nauseous numbers.
Good Morning Paul,
would appreciate you casting an eye over the financials in Cambridge Cognition Holdings (LON:COG) interim results if possible:
https://www.stockopedia.com/sh...
Nothing immediately jumps out at me ... difficult operating environment, but looking more positive near term (I hold)?
Commenting on the results, Matthew Stork, Chief Executive Officer of Cambridge Cognition, said: "We have made considerable progress over the first half of the year, both commercially and with the integration of our expanded technology platforms following the Winterlight and Clinpal acquisitions. Having grown the order book and maintained revenues in a challenging clinical trials market, we expect to report renewed revenue growth and movement towards sustainable profitability in our full year results."
"Trading conditions continued to be difficult in the first half of 2023, with some drug development companies cutting costs and others delaying clinical trials. Some companies providing solutions and services for clinical trials have reported declining performance in the period. While we increased the value of contracted orders from half-to-half, we did see some delays to contract awards that we anticipate will close in the second half of 2023 or in 2024."
many thanks!
I haven't had time to read through the results in huge amounts of detail but a few things have stuck out to me:
It feels like the next 12 months are a bit make or break. They'll either get back to growth and build back towards a net cash position or things remain slow and the debt becomes a bigger burden... Curious to hear other's thoughts on what might happen.
From memory, they are paid quite a substantial chunk of a contract upfront which sits in deferred income before being recognised when the work is delivered. Perhaps this is a risk of not understanding how the two play out - when markets soften that cash pile can quickly disappear as the work is delivered but when nothing new comes in to replace it there's far less working capital available for core overheads. hVIVO (LON:HVO) must likely share a similar risk, so important to understand how the sector is performing - surely quite hard to know unless you're in the industry?
" Loan financing has really taken the shine off. Gone from a cashed-up business (with 25% or so of the mcap in cash) to a not-insignificant £3mil loan on 11.5% interest and warrants to the lender... (smells a bit like death spiral lending...?)"
agreed, judging by the market reaction this seems wholly unwelcome. A bit at odds with the otherwise reassuring and optimistic commentary from Matthew Stork - not generally somebody given to hyperbole and spin if my character assessment is worth anything at all. Not sure what to think, but I also have to acknowledge to myself that I lack the deep financial analysis skills of somebody like Paul (which I think in cases like this are paramount)?
There are two pretty simple observations to be made with Cambridge Cognition Holdings (LON:COG) .
Many shareholders were probably hoping that the company was now self-funding, and have had a rude awakening. After so many years of low rates there is a degree of sticker shock to seeing 11.5%, but with tracker mortgages at 7% we probably need to rebase our expectations.
The big question is whether the acquisitions reflect management ambition, or a need to diversify because the original CANTAB product isn't going to generate the necessary growth they led the market to expect. Winterlight (cognitive assessment using voice) is clearly a natural add-on well within their field of expertise. No complaint about that one, and they paid a similar sales multiple to their own business.
Clinpal I'm not so sure about - it is a software platform that is more broadly applicable than to just neurological conditions - I'm not convinced they had to buy it and I worry about mission-creep - rather like buying the logistics company that delivers your product? So it was only y£1.7m, but I wonder if they would rather have that as cash now...
What is clear is that the company is now financially much higher-risk than it was. You have to hope the management have been very thorough and are confident that the £3m is sufficient to see them through to cash positive.
Stork doesn't strike me as a gambler, but I've been very wrong on character assessments many times, and he wouldn't be the first well-intentioned CEO to bite off more than he can chew.
Great news, Oxford Biodynamics (LON:OBD) has announced that their PSE test for Prostate Cancer is now available to patients in the US and the UK.
“PSE is a diagnostic prostate cancer test with unprecedented accuracy.” said Mathias Winkler, M.D., F.R.C.S., Consultant Urologist and Surgeon, Charing Cross Hospital and Imperial College London. “Nine of 10 cancers are found compared to 3 of 10 with PSA alone. Likewise, false-positive results are reduced avoiding unnecessary anxiety and expense. This is clearly highly desirable for men who are health-conscious or at risk of prostate cancer. “
Strong performance at Card Factory (LON:CARD) .
Debt reduced, cash up strongly, long term partnership with Matalan to roll out their cards to 223 stores.
https://www.investegate.co.uk/...
Down 5% on the good results, obviously :/
Card Factory (LON:CARD)
I suspect the negative market response is due to the rather vague FY '24 outlook comment 'the Board is confident in delivering a good outturn for the year'. That's about as helpful as a chocolate teapot!
Also the forecast FY '24 dividend of 1.35p (per Sharepad) will not now happen. Now no re-introduction of dividends until FY '25.
Snazzy
Card Factory (LON:CARD)
I think the continued confusion over when a dividend might be paid is caused by CardFactory's YE of 31/01, so we are in the second half of FY24 now and FY25 starts on 01/02/24 . I seem to remember on a vid I watched that CardFactory were hoping to reinstate dividend payments 'next year' and most investors took this to be in 2024. The following is from todays RNS and I think is consistent with what they had communicated before.
'Although the CLBILs have been repaid following the half-year end, the Group remains prohibited from making distributions under the terms of its financing facilities until such time as tranche 'A' of the term loans is fully repaid. Accordingly, there were no dividend payments made in either HY24 or the preceding year.
The final maturity date for tranche 'A' of the term loans is 31 January 2024, and accordingly the earliest that dividend payments will be considered is during the FY25 financial year.'
hi Helvellyn
Card Factory (LON:CARD)
Agree that there has been some confusion over when the dividends were likely to be introduced.
However the 1.35p dividend forecast for FY '24 (ending 31/1/24) on Sharepad came from the company's Brokers.
Broker's forecasts for FY '25 and FY '26 are 3.33p and 5.00p respectively.
Snazzy
Card Factory (LON:CARD) I’m just on todays results webinar and they’ve just confirmed what you both say above, that dividends can recommence once the loan is repaid. This will occur at the end of January 2024
I hold CARD too and am happy with the progress so far, particularly on the debt reduction (which was too high for comfort). Let’s hope some of the analysts on todays call ask some decent questions…(amusingly the question they couldn’t answer came from an online participant)
Card Factory (LON:CARD) Reading thru the report, costs are rising - Staff wage increases (9.6% rise in NLW from April), servicing debt increasingly expensive with base rates over 5%. Strengthening of $ recently means £ costs go up (50% purchases in $). So maybe not as strong going forwards as the headline suggests. Outlook statement comes across as cautious to me.
Hambledon vineyard is being aquired for £22.3m by Berry bros and Symington. They have 200 acres of vines. Chapel Down (OFEX:CDGP) has 950 acres of vineyards, market cap £78m. That suggests Chapel Down is under valued, though no idea of the Hambledon finances. I hold Chapel Down, in part to get the shareholder discounts they offer on the wines!
Fairly sobering update from Videndum (LON:VID).
Contains, apart from “we’ve suffered a material fraud”, two of the worst things an investor can hear:
1. debt pressures and other external factors “Which may require an equity raise”; and
2. for FY 2023 “it is difficult to provide financial guidance”.
The business is sound, with innovation and dominant positions in key growing market segments, and the rebound for revenue and profits will be there. Suspect it’s possibly it will be taken over before then.
So might be an interesting entry point for new investors once all the bad news is digested and in the price - suspect it may be down to 425p today, but let’s see.
Driver (LON:DRV) - Strategy on track, despite timing issues (new research: https://www.equitydevelopment....)
Driver Group has issued a trading update earlier than normal, citing a weak Q3 (reflecting a combination of timing issues and the later Easter) as reasons. Nevertheless, Q4 has witnessed a return to more normal patterns of trading and coupled with the rationalisation programme yet to impact results and the pipeline of orders looking more encouraging, we think the medium-term outlook appears favourable. The further improvement in net cash levels provides the Board with opportunities, not least in its capital allocation policy, including the further return of cash to shareholders. The NAV remains above the current share price.
We expect the NAV to decline modestly during H2, reflecting the slight reduction in profitability. However, at c.£15.8m / 29p per share, which is 8% above the current share price, this provides healthy support for the shares. With the current share price now below levels of previous buybacks and net cash higher during H2, we remain positive over the medium-term.
Reflecting the timing issues witnessed during H2, we reduce our fair value / share from 49p to 40p.
Supreme (LON:SUP) - AGM update - FY24 significantly ahead (new research report: https://www.equitydevelopment....)
In today’s AGM statement, Supreme plc reported that the strong momentum evident in FY23 has continued into the first half, as a result of which the Group now expects revenue for FY24 to be in the range £195-£205m, with (adj.) EBITDA of £28-£30m. This guidance is up to 6% ahead of our previous revenue outlook of £193.5m and up to 17% above our (adj.) EBITDA estimate of £25.6m.
The Group notes that of the incremental £3.5m in (adj.) EBITDA - versus a prior market consensus of £26.5m - £2.0m arises from the distribution of Elf Bar branded vaping products, and the remaining £1.5m from other core operations.
Our Fair Value remains at 200p/share, indicative of a FY24 EV/EBITDA of 8.5x.
Suprene
I really dislike this company.
I used to hold them my kids told me 70% of their year at school vapes .
It is a total scourge on our schoolchildren pedalled by vape manufacturers .
Hopefully vaping will be banned to at least under 18s
Anyone backing this company needs to go to the school gates of their most local school at 3.30 pm and watch the clouds of “vape” engulfing our teenagers as they walk home .
It was coo to smoke at school
It’s now cool to vape at school .
Suprene grows fat on these sales .
Please be honest here guys. This success is based on selling vapes to under 18s and this is sweeping through our schools .
Not for me this is a rotten company .
"Hopefully vaping will be banned to at least under 18s"
No need to change the present law. It's already illegal to sell vapes to under 18s. I seem to remember Supreme saying on a recent investor call that their average customer is mid 40s.
Hi planetx,
Whilst I respect and somewhat agree with your opinion there are an awful lot of people who are very grateful to 'vaping' as a means to totally quitting smoking and without it may have cost the NHS a lot of time and money.
The fact that I see very few people smoking these days can only be good news.
It's strange to see vaping now triggers such an emotional response from certain people who don't even smoke or vape. Plenty would like to see it banned totally. As you say tho Helvellyn it's a very useful tool in helping people quit smoking.
I don't like drunks or fat people, especially fat drunk people...but I don't want to ban chips or alcohol.
In Scotland they try to restrict alcohol and vaping, but want to legalise heroin. What a mixed up world.
Just to be clear, the Scottish Government proposes to decriminalise the possession of drugs for personal use & treat addiction to heroin as a health issue rather than a justice issue.
"Please be honest here guys. This success is based on selling vapes to under 18s.."
I'd be interested to see the evidence for this?
As I say go to the school gates at 3.30
70% of my sons class vape
50% of my daughters class vape
Ask any parent
Ask any teacher
Ask any head teacher
Then do the maths
It is so convenient for Suprene and investors to hide behind the “we’re helping smokers quit” but the real cash is being generated by getting teenagers vaping .
Or read the guardian ,
UK health expert raises alarm at vaping ‘epidemic’ among teenagers
Leading respiratory doctor fears generation could end up with long-term addictions and lung damage
Dr Mike McKean, vice-president of policy for the Royal College of Paediatricians and Child Health, said vaping was becoming an “epidemic” among teenagers even though it is illegal before the age of 18. If its rapid growth maintains the same trajectory, almost all children will vape within five years, he said.
I think we need to worry about nitrous oxide more - all those balloons you see people inhaling from?
Potentially catastrophic health implications after prolonged usage.
Sometimes I realise how out of touch I am on some things out here in mid Wales, I have not even heard about these balloons much less seen them. But then it takes so long to get anywhere in Wales now, I am bound to be a bit cut off. But as I look out of my window at the hills, there are some compensations
"70% of my sons class vape" Does your son go to Alcatraz :)
I'm happy to be proven wrong but based on below info theres been a rise in children vaping, and a fall in children smoking. Over the last two years it looks like disposable vape use has spiked, this is being addressed by government.
Its illegal to buy vapes under 18, so the simple answer is to enforce the law.
Just to say I don't smoke, vape or own shares in Supreme (LON:SUP)
From the same survey-
Conclusions
ASH highlight the large increase in disposable vape users compared to 2021 – which is a topic for a whole different article!
Also it notes that awareness of e-cigarettes is generally high at 90% but regular usage is still extremely low. With 3.1% of respondents only vaping regularly (more than once a week) and 3.9% occasionally (less than once a week
------------------------------------------
One of the most worrying aspects I think is that kids now think vaping is as harmful or worse than smoking. This nonsense can almost entirely be blamed on hysterical media reporting.
Perhaps you should take this up with the Head teacher or the schools board of governors, if you can see kids vaping at the school gates. Sounds like you have problem with Parents and Teachers.
I think if you look you will see everything .
Its pretty factual if you do some simple research, what I think is behind the curve is the recent increase in past 6-12 months which is nicely reflected in the Supreme numbers but not so nicely reflected in the lungs of our children
See House of Lords library 26 July 2022
"Vaping amongst teens ; A growing trend"-
I find this interesting. Everyone is entitled to their opinion but I have seen this opinion a few times recently, from a few people. But I don’t seem to see it when people discuss J D Wetherspoon (LON:JDW) , Diageo (LON:DGED) or even British American Tobacco (LON:BATS)
We all have our lines in the sand and personally, having lost close family members to alcoholism, mine would probably be somewhere else.
I should add vaping has helped my partner give up a lifetime addiction to smoking. I would prefer she did neither, but I would definitely pick vaping over smoking. The NHS website recommends it as a healthier (but not entirely risk free) alternative.
Planetx - lease take your personal opinions about human behaviour elsewhere. This forum is for discussion about investments. It's an expensive subscription and I do not want to have to wade through stuff which should be on Facebook or Twitter. There are numerous business listed on the stock exchange who deal in substances or hardware which are morally dubious, from alcohol and dubious pharmaceuticals to weaponry and (the current "evil") carbon emissions. We must each make up our own minds about whether to delete any particular business from our portfolios or watchlists. Please do not use this space to impose your ideas about business morality on others.
In the past I produced a report on an investor presentation by Supreme, for which Paul Scott was kind enough to thank me. I won't do that again because I don't want to suffer invective from moralisers.
Morning Paul and Graham
Would be interested in your views on NAHL (LON:NAH) Interims this morning. The transformation of the Personal Injury business away from being a pure claims management business to one that includes a wholly owned law firm (allowing them to process claims in house and capture all of the economics) is almost complete, and the long awaited cash flow has started to come through.
They generated £1.8m of free cash in the half versus a market cap of £26m (they also have £11m of Net debt, which they are now quickly reducing with free cash flow). Future cash flows and profits within the law firm should dramatically increase this number, and they have a similarly recession proof Critical Care business, that will earn c.£4m of EBIT itself this year. Looks pretty interesting to me!
MJ
In case helpful - Allenby (House broker) have a note out this morning too: https://www.allenbycapital.com...
Good AGM statement out of Redde Northgate (LON:REDD) . I have a substantial holding, and will continue to hold. The only future constraint is a decline in vehicle re-sale prices in the medium term. I note that the share buy back is going fairly slowly. No strong sellers out there?
Redde Northgate (LON:REDD) usually manage expectations quite well - the tone of today sounds like they might be running ahead of market expectations but maybe they will leave that for the December half-year report.
The decline in vehicle re-sale prices are not the only constraint though. It's both the margin on rental prices and disposal prices - both of which have been recently quite high. However, it sounds like from today's update they are remaining high.
Yu (LON:YU.) results out.
"Our financial KPI's continue to perform ahead of expectations. Revenue is up by 51% to GBP194.9m, cash has increased 133% to GBP36.6m, average monthly bookings have increased by 259% to GBP51.3m and EBITDA has grown over 400% to GBP13.7m, compared to H1 2022. We now forecast a new record performance to follow in H2 2023 and we expect to see EBITDA over GBP33m for FY 2023, up from current market expectations of cGBP19m"
https://uk.advfn.com/stock-mar...
Hope Paul can dig into the nunbers today. tia