Small Cap Value Report (Tues 8 August 2023) - HAT, SDG, SDI

Good morning from Paul & Graham.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections
H & T (LON:HAT) - up 2% to 410.4p (£178m) - Interim Results (EPS downgrade) - Graham - GREEN
The RNS doesn’t lay it out but there is an EPS downgrade from H&T’s broker due to a lower retail margin, higher operating expenses and higher interest costs. However, I believe that revenue growth and pawnbroking momentum remain very encouraging despite those points.
Sanderson Design (LON:SDG) - Up 2% to 104p (£74m) - Half Year Trading Update - Paul - GREEN
This luxury fabric & wallpaper group reassures again with an in line with expectations H1, and in line outlook for FY 1/2024. Strong balance sheet with plenty of net cash. Very low valuation seems to be anticipating a profit warning, which so far anyway has not materialised. Strong licensing profit is mopping up weakness elsewhere. I like it a lot, seems really cheap for quite a nice business. Thumbs up again.
SDI (LON:SDI) - down 1% to 122p (£127m) - Final Results (in line) - Graham - AMBER
This owner of a portfolio of scientific businesses reports an improvement in adjusted results, but statutory results are held back by impairments. Operational cash flow is promising and as this share price continues to drift lower it may start looking interesting to value investors.
Paul’s Section:
Sanderson Design (LON:SDG)
Up 2% to 104p (£74m) - Half Year Trading Update - Paul - GREEN
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, is pleased to announce its trading update for the six months ended 31 July 2023.
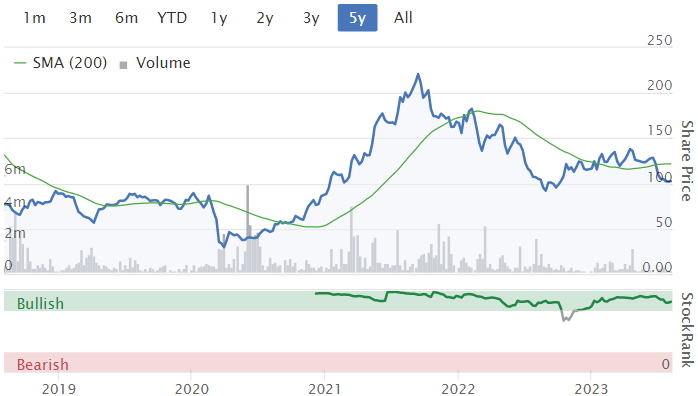
Background - SDG is one of my watchlist top picks for 2023, but despite reassuring updates it’s about 10% down year-to-date (YTD). We never know why people are selling share, but I think it’s safe to assume that general macro worries must be weighing in sentiment, as it is with so many small caps right now. Is this a risk, or a buying opportunity? We don’t know in the short-term, but I’m pretty confident SDG shares should do well in the medium to long-term, as it’s a decent business, with sound finances, and strong management.
Here are my previous comments on SDG this year (all marked as GREEN) -
8 Feb - In line TU. Thumbs up from me.
22 Feb - Major new licensing deal with Next. Underpins forecasts.
30 Mar - Major licensing agreement with Sainsburys.
27 Apr - FY 1/2023 in line with expectations. Outlook also in line. I like it, but macro uncertainty.
22 Jun - AGM TU in line expectations. I like it L/T, not sure about S/T due to macro uncertainty.
This is today’s news - it’s another in line update -
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, is pleased to announce its trading update for the six months ended 31 July 2023.
Strong performance from licensing underpins half year profitability
Company remains on track to meet the Board's full year profit expectations
A strong performance in the half year from the Group's high-margin licensing activities and encouraging growth in the US have mitigated the difficult market conditions in the UK discussed in the Company's AGM statement on 22 June 2023…
The strong contribution from licensing means that adjusted underlying profit before tax for the half year is expected to be slightly ahead of the same period last year (H1 FY23: £6.3m).
That all looks fine to me, I don’t think there’s any point in drilling down any further into the detail. Licensing is the stand-out performance, which is mopping up the shortfall elsewhere.
Net cash looks fairly static, and healthy, at £15.9m - which is significant for a company with a market cap of £74m. Hence I see little to no risk of dilution or insolvency, even in a downturn.
Outlook is mixed, but overall this reassures me -
Focus remains on the significant international growth opportunity in the US market and the growing pipeline of licencing opportunities, both of which will underpin trading in H2 FY24 and beyond.
The Group continues to benefit from a strong balance sheet and, whilst the outlook is uncertain, the Board's expectations for the Group's full year profits remain unchanged.
My opinion - I’ve been considering taking a starter size position here, but wanted to wait for a trading update, in case a profit warning might happen, reflecting tough macro. So far, that’s not happened, as we’ve got an in line update today, and they sound quite perky about the outlook.
For that reason, and with such a modest valuation (forward PER is only 7.4), I think this share has considerable appeal as a value investment, that should also re-rate upwards once the economy improves. It looks like a buying opportunity to me, and I might dip my toe in with a small opening position. Thumbs up. There's obviously still some macro risk, but I feel the low valuation provides for that risk. We can't avoid profit warnings, but in a balanced portfolio the good performers should offset the odd one that disappoints, that's what I'm finding this year so far.
Graham’s Section:
H & T (LON:HAT)
Share price: 410.4p (+2%)
Market cap: £178m
H&T Group plc (AIM:HAT), the UK's largest pawnbroker and a leading retailer of high quality new and pre-owned jewellery and watches, today announces its interim results for the six months ended 30 June 2023 ("the period").
I covered many aspects of this stock at the H1 update in July.
Here are the interim highlights:
Total revenue up 31% to £101.7m
PBT up 31% to £8.8m
Pawnbroking pledge book up 14% in six months to £114.6m.
In pawnbroking, redemption rates (i.e. customers repaying their loans and taking their items back) are “above historic levels, at c. 85% and have been consistent at this level for more than two years”.
Other parts of the business are doing well, too: retail sales are more than matching inflation (+11%) although the margin fell to 28% (last year: 42%).
The company gave us plenty of warning about this: they wanted to get certain luxury watches off their books “where we identified changes to the sentiment of some customers towards values”.
In its recent full-year results, Watches of Switzerland (LON:WOSG) said: “Luxury watch demand remains strong and continues to outpace supply, with our client registration lists extending and average selling prices growing.” So I don’t think there are any problems in the market for new watches.
Conditions in the used market have been more turbulent, and a helpful article from CNBC explains that the average price of a second-hand watch is down by 31% since March 2022. The hardest-hit brands are Rolex, Patek Philippe and Audemars Piguet.
From the article:
During the pandemic, many people who were stuck at home and flushed with stimulus cash took to luxury spending. With so many watch models unavailable at retail, enthusiasts flocked to the secondhand market.
It was interesting that the price hike mainly happened among three family-owned brands…
Now, individuals have been flooding the market with the very same inventories, dragging down overall prices.
In summary, there was a temporary boom in second-hand watch prices due to a shortage in new watches and the stimulus-driven/work-from-home spending spree. Cashing in some bitcoin winnings and buying a Rolex - thought to be another type of appreciating asset - was apparently a common strategy.
However, like other Covid-related disturbances, the impact of these trends may finally be coming to an end, as prices stabilise and new economic factors take on greater importance. H&T says that “overall, demand for high quality pre-owned watches remains high”.
Another key source of revenue for the company is currency conversion: currency volumes are up 19% and they have launched a “Click and Collect” service for customers.
Net debt increases from £3m to £17m over the six months. There aren’t many companies where I’m excited to see net debt rising, but I am in the case of high-quality, booming financial stocks. With a rapidly growing pledge book, it makes sense to borrow in order to fund this.
Operating expenses rose 19%, led by employee expenses which were up 21% (and account for the majority of operating expenses). Pay rises were implemented in January ahead of the new National Living Wage in April.
Outlook
The company has “a list of locations where we would like to open new stores”, but I’m relieved to see that store expansion has been modest. In H1, eight stores opened, and two closed, leaving the total number at 273. Over-expansion is a key risk in this industry!
A new point of sale system is growing in its functionality and will give H&T “a single view of the customer relationship across all products”.
For the retail website, “a major redevelopment of our online offering is planned”.
Funding - the company can now borrow £50m (up from £35m), although it must now pay a slightly higher margin over the benchmark interest rate.
Interim dividend - 6.5p (last year: 5p).
Estimates - broker Shore Capital has increased revenue estimates for all future years, thanks to continued momentum in the pawnbroking pledge book.
Their actions relating to profitability are more mixed, however.
The reduced retail margin, higher operating expenses and higher interest costs result in a 7% reduction in forecast adj. EPS for the current year, to 53.7p.
For next year, FY 2024, there is a 1% reduction in the adj. EPS forecast to 69.8p.
And they have increased their adj. EPS forecast for FY 2025.
Graham’s view
While it’s true that business is booming at H&T, the revised EPS estimates do give me pause for thought. Clearly, it is not all plain sailing, given those three headwinds which resulted in the EPS downgrade.
But then let’s remind ourselves of the value on offer here:
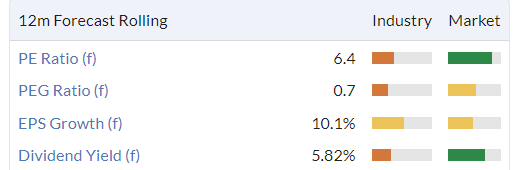
Not only is this stock offering cheapness on an earnings basis, it also offers asset backing with latest net assets at £167m.
And the quality isn’t bad. This will never be a company that earns sustainably high ROCE, but it does have the great habit of churning out profits year in, year out.

Therefore, despite a few headwinds and an EPS downgrade for the current year, I’m going to remain positive on these shares.
SDI (LON:SDI)
Share price: 122p (-1%)
Market cap: £127m
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing and control applications, is pleased to announce its final audited results for the year ended 30 April 2023.
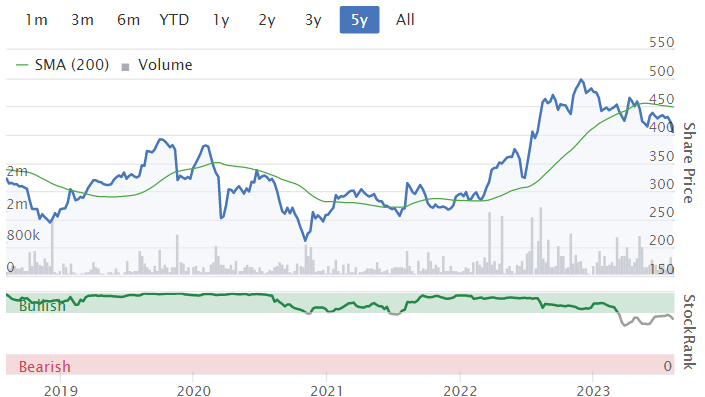
I last looked at this one in May, on the day of a nasty profit warning which saw the shares fall by 21%.
It was yet another post-Covid normalisation story: the company was forced to write off the prospect of any further sales related to PCR (the Covid testing technology).
The shares have drifted further since that mid-May profit warning:
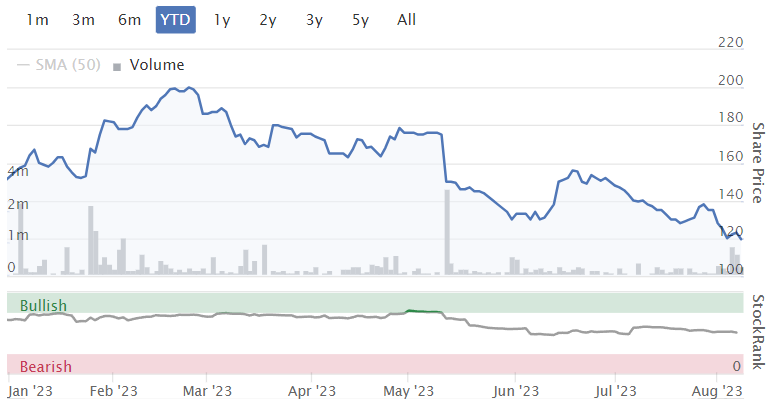
We have final results from the company as follows:
Revenue +36% to £67.6m (not organic growth and includes £8.5m of PCR revenues that won’t be repeated).
Adj. operating profit +5.8% to £12.8m
Actual operating profit falls from £10m to £6.8m, due to an impairment charge.
Scrolling down to the income statement, I see that the final profit for the year is £3.9 million, after interest expenses and taxes. That’s down from £7.5m last year.
The outlook is in line with expectations, the Chairman saying:
While we are mindful of the challenging external environment, we remain optimistic for the year ahead and we expect to deliver FY24 results in line with expectations."
Two acquisitions made during the year have “performed well”.
Organic growth is 0.9%, which is poor and worse than the figure disclosed for H1. Although if you exclude the declining PCR sales, organic growth is 6.4% - not too bad.
Goodwill impairment relates to two companies, acquired in late 2020/early 2021, which are less profitable now than they were in a Covid environment, and which need to be reorganised.
Outlook statement from the CEO is worth a read:
…Supply chain delays were prevalent in the first half of FY23. These still exist but have eased somewhat in recent months.
The market for acquisitions appears buoyant, and SDI expects to acquire additional businesses in the FY24 financial year.
The economic backdrop does remain a concern… However, SDI has started the FY24 financial year well and we are confident that we can continue to trade profitably and generate free cash flow over the coming financial year.
Funding: the CEO mentions higher interest rates on debt: the company finished the financial year with £13m of net debt, giving a net debt/EBITDA multiple of 0.9x (this would in general be considered a low-risk level).
At year-end, the company had drawn down £16m of its £25m facility at HSBC. To my eyes, that doesn’t leave a huge amount of headroom: £9m, plus £5m that might also be offered by HSBC through an additional facility.
The company says that it has enough funding to acquire new companies and invest in its current portfolio, but it spent £21m of cash on acquisitions during FY 2023. Another set of acquisitions of that scale in FY 2024 will, I think, require plenty of cash from operations to help fund it.
Balance sheet: net assets are £41m but are zero if you deduct the value of intangible assets.
Graham’s view: I continue to prefer Judges Scientific (LON:JDG) to SDI (LON:SDI) , but I think it’s important to study both and I also think there will be a level where SDI becomes an attractive value investment. Have we reached that level yet? Ultimately that’s up to you to decide, but from my point of view we might reach that level before too long.

Checking the cash flow statement (because the income statement is full of non-cash charges), I see the following:
£14.8m in (pre-tax, pre-interest) operating cash inflow before working capital movements (working capital movements were a drain on cash, but could improve in the current year). This is an improvement on last year.
Only about £1.5m was spent on capex/capitalised development spending. This is slightly less than last year.
Of course, we have to think about more than these two numbers, but they do say to me that SDI has the ability and the potential to generate substantial amounts of free cash flow.
I’m not ready to go green on SDI yet but I think it’s starting to look interesting at a sub-£130m market cap. I think I’d be very interested at a £100m market cap. For now I’m neutral. Any improvement to the organic growth figure would be highly encouraging.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
Anyone noticed this on China exports?
"Official figures show that exports fell by 14.5% in July compared with a year earlier, while imports dropped 12.4%.....July was the third month in a row that China's shipments overseas have declined, marking the sharpest fall since February 2020 at the height of the pandemic. Exports to the US, one of China's biggest buyers, fell 23.1% year-on-year. The European Union also bought 20.6% less from China."
These are terrible numbers for China and/or global trade. I'm not sure I have ever seen such negative numbers. Early signs of a global recession / the West cutting down on Chinese goods or maybe both?
When economic stat numbers in China are so massaged, do we even know if the MoM numbers, YoY numbers are actual realities?
From a macro perspective, I'm not sure if this China export data matters that much. The BRICS meeting at the end of this month is where to focus I believe. US hegemony is collapsing and BRICS+ are likely to be backing their new currency with gold a la the pre 1971 Bretton Woods system. The economy is one giant surplus energy equation, 80% of crude oil supply and 90% of Natural Gas supply is under the control of BRICs+ nations. To put is simply, this is really bad news for the west.
Yes I clocked Chinese export figures this morning. As you say pretty terrible.
Their prolonged authoritarian lockdown was a car crash, not to mention the constant military threats to Taiwan. Youth unemployment looks awful too. As inflation is at 0% I'd be surprised if they don't reach for the printing press soon.
No idea if it's representative but I buy lots of ironmongery for my business, almost all was made in China previously, now around half is coming from India.
Interesting movement in Saga (LON:SAGA) in the past fortnight. Wonder if they've finally got insurance and travel both moving in the right direction. Chart looks better if nothing else
Gulf Keystone Petroleum (LON:GKP) down another 20% today.
After months of weighing up the risks I bought on 23 March this year and 4 days later the pipeline was shut. Talk about bad timing!
Gulf Keystone Petroleum (LON:GKP) Why the sudden sell off today? They've announced their half year figures will be published at the end of the month, but I can't see what bad news triggered this dramatic sell off.
I hold. My take is that reality finally set in. No oil flowing since March, none of the old debts paid and so-called "politicians" in the areas affected not getting anywhere near sorting it out or wanting to. Shareholders who held after March gave the BOD the benefit of the doubt and kept hoping, Micawber like, for something to turn up, not a good strategy for investment but I'm as culpable as everyone else. Lesson learned and I will in future bale out at the first hint of any trouble in my other holdings.
I discovered the other day that there were some people who came straight in to the SCVR page and thus ignorant of other posts.
So, for you and others who have been discussing Sanderson Design (LON:SDG) today there are some interesting comments on SDG as well as other smallcaps by Chris McVey of Octopus talking to Paul Hill - Click here.
discovered the other day that there were some people who came straight in to the SCVR page and thus ignorant of other posts.
So, for you and others who have been discussing Sanderson Design(LON:SDG) today there are some interesting comments on SDG as well as other smallcaps by Chris McVey of Octopus talking to Paul Hill - Click here.
Thanks sharw
Interesting and useful . Chris Mcvey was excellent. I suppose they own the companies he was talking about so some very useful info
Paul, on Card Factory (LON:CARD) I believe you commented yesterday about return of dividends this year. Despite the data from Refinitiv on the Stocko page I don't think this will happen until FY25 as they have covenants restricting this - per extract from their annual results below:
'The Group remains prohibited from making distributions under the terms of its
financing facilities until such time as the CLBILS and Tranche 'A' of the term
loans are fully repaid. Accordingly, there were no dividend payments made in
either the current or the preceding year.
The final maturity date for tranche 'A' of the term loans is 31 January 2024,
and accordingly the earliest that dividend payments will be considered is
during the FY25 financial year.'
So looks like a possible Interim around October 24 at the earliest. Regardless progress is good and with Clintons looking dodgy they have scope to keep delivering. Hope this helps.
Buying and selling shares successfully is much more about thinking of the current situation and thinking ahead. With HAT for example it was a good buy around Springtime 2022 at just over £3.00. Interest Rates have continued to rise, so obvious this is a business that had to improve its core business.
Time is more important than Price and the management will by now, have sorted all the necessary and costly changes with these new times. I still feel an interesting buy at less than £4.00 especially with such a good dividend
Just sold hat after being long term holder. Frustrated with SP performance this year.
Poor performance probably due to recent fund raising. New chairman who immediately installed 3 additional non exec directors which is way over the top for a company of HAT size. Increase in borrowings/ bank facilities in what should be a cash positive business.
Much prefer RFX in same space.
H & T (LON:HAT)
H&T is a pawnbroker, Ramsdens is not - its other activities dwarf the pawnbroking side - it's fairer to say its a retailer and forex provider.
A rapidly growing pawnbroking business sucks up cash by definition - it's what they are lending out. It is only when growth moderates that cash flows back.
You pays your money and you takes your choice.
(Edit: don't hold either but have done in the past)
Ramsdens Holdings (LON:RFX) That is not born out in the latest HY gross profits. Pawnbroking is about the same as forex, jewellery retail is larger by about 30%.
H & T (LON:HAT) Yes, poor share price performance, but the company performing well which is all that should matter in the long run - the share price will catch up at some point. I hold both RFX and HAT but as others pointed out, RFX is more like a retailer with a fairly small pawnbroking book (from memory around 10 times smaller than HAT). HAT is my preferred of the 2 as I think the counter cyclical qualities of its pawnbroking side could act as a nice hedge if we have a bad downturn.
Reference the post today by davidjhill on Petrotal (LON:PTAL) I bought in at the end of April but sold at a 17% loss on 8 June when an RNS was published about a River Blockade which I accept has now been resolved.Once bitten twice shy comes to mind.
It's Peru! One could say something about Hochschild Mining (LON:HOC) too, I hold, not wishing to cut my losses.
The thing with Petrotal (LON:PTAL) is that you need to apply context to the headlines to really understand the risk.
The company is broadly seen as a trusted middleman to the indigenous local communities and government bodies so holds quite a lot of influence in these disputes. They effectively negotiated the deal that currently exists whereby the local communities get a royalty %age that goes into a fund for the benefit of the community. This is already quite large and have a growing positive impact on those communities. So the company is far from seen as the enemy, which headlines may imply. A bit like adding 1+1 and getting 3!
However, Petrotal also know that river blockades or the occasional dispute/protest will flare up every now and again, in the same way they know that the river has the propensity to get too low for full capacity barges during certain periods of the year at low rainfall. That is all built into the revenue and production forecasts so one should not be immediately alarmed when the anticipated happens. It is just normal business. Indeed if you are going to sell every time an rns comes out then agree it’s probably best not to be in it at all.
On the opposite side of that equation is the prodigious cash flow, and 20% annual shareholder returns including buy backs coupled with a production profile of reserves that can last a number of decades. Then add in the very high net cash position (around 1/2 market cap by early next year). The petroperu pipeline is also opening back up giving them more routes to export market and meaning that blockades or river levels will have less downtime effect on production, which will further increase cash flow.
I compare the risk and mitigating actions against the return available on most other stocks and personally view it favourably (as part of a diversified portfolio of course) when the context is taken into account.
I agree with Topvest that small and mid cap Investment Trusts are on a triple discount at the moment. I have been trying to reduce my exposure to individual stock risk and those 7am profit warnings! I have been buying Oryx International Growth Fund (LON:OIG) (top performer over 10 years) Blackrock Throgmorton Trust (LON:THRG) Jpmorgan UK Smaller Companies Investment Trust (LON:JMI) Downing Strategic Micro-Cap Investment Trust (LON:DSM) River and Mercantile UK Micro Cap Investment (LON:RMMC) as well as the mid cap trusts Henderson Opportunities Trust (LON:HOT) and JPMorgan Mid Cap Investment Trust (LON:JMF) - I have held North Atlantic Smaller Companies Investment Trust (LON:NAS) before because I'm a big fan of the Harwood Trusts and Christopher Mills.
Rockwood Strategic (LON:RKW) Odyssean Investment Trust (LON:OIT) Strategic Equity Capital (LON:SEC) are all on the watchlist.
bsharman
Downing Strategic Micro-Cap Investment Trust (LON:DSM) stands out amongst your list as one I definitely wouldn't buy! Results have been poor, albeit better this year.
And, in my opinion, their website is misleading when listing the top 5 equity positions - firstly Adept has been taken over.... But, more importantly, by specifying equity, it skips over their largest holding which is a loan note to Real Good Food (LON:RGD) . OK, I've not studied it in detail (and, maybe, it's secured against real assets), but it appears to be non performing and not substantially provisioned. If anyone knows more, I'd be v happy to be corrected.
I agree and I have held this one for quite a while now. I wouldn't be a buyer of Downing Strategic Micro-Cap Investment Trust (LON:DSM) now, but I wouldn't be a seller either. I was also considering Miton UK Microcap Trust (LON:MINI) as an alternative, but they haven't performed well either!
It's frustrating as most of the UK small cap investment trusts are quite poor in my opinion - something like River and Mercantile UK Micro Cap Investment (LON:RMMC) has had dreadful returns and I really don't like the look of the top 10 holdings. Odyssean looks one of the few good ones, but always tends to trade at a premium.
While I invest directly in small caps myself, I tend to stick to a few sectors that I know. For instance, I have no technology holdings as don't understand them. Would be nice to have a good UK small cap fund for a bit of diversification, but none grabbed me so far.
Be interested in your thoughts on SIG (LON:SHI) and their HY results Paul, part of a bombed out wider construction market that at some point will turn.
Palace Capital (LON:PCA) have just announced a further share buy back of up to 10% of its shares. On completion the company will have bought back over 20% of its equity since July 2022. Not sure at present how accretive this will be to NAV, but is a further positive announcement following the recent sales resulting in the virtual elimination of net debt.
I hold
2 August: "Palace Capital announces that it has sold 22 Market Street, an office property in Maidenhead to a client of Soor Capital for £9.6m. The sale price reflects a net initial yield of 7.3%, equating to a net price of £9.0m (after rent incentives), which is 9.7% ahead of the 31 March 2023 book value.
Following the sale and the use of some of the proceeds to repay £3.5m of bank debt, gross debt will be £20.2 million and cash reserves will be £20.1 million resulting in a net debt position of £0.1 million."
Today: "Since 4 July 2022, Palace Capital has purchased 4,488,633 ordinary shares of 10 pence each ("Shares").
As at 7 August 2023, including Shares which have been purchased but not yet settled, the Company holds 4,548,220 Shares in Treasury. The total number of Shares in issue is 41,840,295 (excluding Shares held in Treasury). ............
Following approval of the resolution relating to the market purchase of own shares at the Annual General Meeting held on 26 July 2023, the Company intends to purchase up to a further 4,284,029 Shares representing approximately 10% of the Company's Shares in issue with voting rights. The aggregate purchase price of all Shares acquired under the Programme will be no more than £11 million (excluding stamp duty and expenses) under the resolution passed at the 2023 AGM."
Worth 3 or 4% of NAV I calculate (fag packet esque mind). So maybe 12p.
But makes sense buying at a big discount to NAV given debt is almost eradicated and the company is effectively in managed wind down. I’ve added 10p to my estimated realisable NAV (rather then DCF theoretical model based on rates) of 350-60p so now expect to get back 360-370p over next couple of years.
Cheers David
Would seem that you are in the right ball park given today's share price reaction.
Petrotal (LON:PTAL) another good update. now sitting on $100m of net cash and paying 15% dividends whilst buying back shares.
Production strong, and have enough reserves for well over 20 years I believe so even at current share prices this can compound 15% before capital gains! I own in an ISA so tax free income. Surprised it doesn’t get more of a look in
Ondo Insurtech #ONDO
Leakbot detects water leaks. Save £££ and water - win win. Mkt Cap u£30m.
Reassuring inline TU from Sanderson Design (LON:SDG) for the six months to 31 July. Very impressive to be reporting figures so promptly. In fact the table shows results for the six months to 31 July 2024 - oops! I wonder how long before they will notice and issue a correction.
Despite flagging sales, licensing income (at higher margins) keeps overall profits steady and full-year expectations intact. Trading conditions in the UK are clearly tough so it is just as well that the US operations are pulling their weight.
"The strong contribution from licensing means that adjusted underlying profit
before tax for the half year is expected to be slightly ahead of the same
period last year (H1 FY23: £6.3m)."
"Focus remains on the significant international growth opportunity in the US
market and the growing pipeline of licencing opportunities, both of which will
underpin trading in H2 FY24 and beyond."
This remains a reassuringly high-quality operation in my view and I'm happy to hold.
Sanderson Design seem to have a lot of directors.
I have been having a modest look at Sanderson Design (LON:SDG) as a possible buy - I am generally underweight consumer sensitive stocks. The attractions seem a well-reputed management team, a strong net cash position and increasing (very high margin) licensing revenues. On a P/E basis the share looks cheap but I have been put off doing detailed analysis on the poor cash conversion over recent years.
Looking at Progressive's note this morning the forecast adj EPS of 14.2p (2025F) and 14.9p (2026F) only translate into 4.8p and 5.0p respectively of Free cash flow per share. Given that revenue is only growing at 3-4%, I was surprised to see such a large difference. On Progressive's forecasts, Sanderson is therefore trading on around 20x 2026F FCF, which does not appear that cheap. I would be grateful for any counterarguments.
Morning Wimbledonsprinter
I haven't seen the Progressive note yet but have owned Sanderson Design (LON:SDG) on several occasions, notably buying at 39p when the pandemic struck, so I know the company reasonably well. As a counter argument I would make the following observations:
I think that you have to view Sanderson Design (LON:SDG) in the context of the pervading economic gloom. To be trading in line in the current market is fairly impressive I would suggest.
It has close to £16m cash on the balance sheet, about 20% of market cap and the licensing income that continues to gain traction falls straight through to the bottom line. I would also add that it owns an irreplaceable archive, notably William Morris and Arthur Sanderson and is trading a little below book value. So to my mind a tempting bid target, albeit this is speculation but adds to the attraction of the shares. Finally there is the management team, led by Lisa Montague who has done an excellent job since arriving.
For what its worth I bought an opening position this morning at 106p. Time will tell whether this was wise or foolish.
In my view the arguments for/ against Sanderson Design (LON:SDG) are simple.
Pro: Amazing IP which will make this a take over target at some stage;
Good management team led by Lisa.
Con: discretionary product range at a time of flaky consumer sentiment.
Not sure that the buyers of Sanderson Design (LON:SDG) furnishings, fabrics and wall coverings are going to be a particularly price-sensitive bunch.
I like the IP, I like the dividend, I like that they are growing, even if only slightly (so many of my shares are forecasting growth followed by a decline into 2024.)
Sharepad, which provides rather longer forecasts that Stockopedia, has not dissimilar EPS forecasts to Progressive but their FCF per share forecasts are a bit higher - 2025 5.64p and 2026 of 7.4p. Forecast borrowings are 2025 -£17.67m and 2026 -£22.10 so they've cash in the bank which I also like.
Jonno
Looking at the last two years figures, the reasons for FCF at Sanderson Design (LON:SDG) being so far below earnings has been: 1) the large build up of inventories to the very high level of £27.7m , equivalent to 9 months cost of sales. (c£8m increase between Jan 21 and Jan 23); and 2) the accounting treatment of multi-year minimum guarantee licence agreements, where the revenue (upto the minimum guarantee amount) is all booked up front, although the cash might only be received over an extended period.
Point 1) has had a bigger effect than 2).
But both should unwind, meaning in future cash flow should be strong (and arguably higher than earnings). This makes Progressive’s note today even more confusing to me, why it should be forecasting such weak FCF for the rest of FY24, FY25 and FY26. If I were to think that the FCF line in Progressive note were unduly low, then this would be very bullish.
There is a separate discussion to have on why inventories have got so high and if this is a worry. Clearly a mitigating factor is the “timelessness” of many of the designs.
Wimbledonsprinter
Thank you for doing some more digging. I shall have a look at Progressive's musings this evening.
I seem to recollect Lisa Montague making reference to the increase in inventory, in the most popular SKUs. I don't know whether this was in her interview with Paul Scott or in April's full year results webinar presentation, available on the company website. Will let you know if I find it.
All the best
Jonno
Looking at the last two years figures, the reasons for FCF at Sanderson Design (LON:SDG) being so far below earnings has been: 1) the large build up of inventories to the very high level of 9 months cost of sales. (c£8m increase between Jan 21 and Jan 23); and 2) the accounting treatment of multi- year minimum guarantee licence agreements, where the revenue is all booked up front, although the cash might only be received over an extended period.
Point 1) has had a bigger effect than 2).
But both should unwind, meaning in future cash flow should be strong (and arguably higher than earnings). This makes Progressive’s note today even more confusing to me, why it should be forecasting such weak FCF for the rest of FY24, FY25 and FY26. If I were to think that the FCF line in Progressive note were unduly low, then this would be very bullish.
There is a separate discussion to have on why inventories have got so high and if this is a worry. Clearly a mitigating factor is the “timelessness” of many of the designs.
FCF being slightly depressed might be in part due to an increase in Capex over the next few years. The CFO in the most recent investor meet presentation said it'll rise to £6m (from approx £4m I believe) as they invest in digital printing technology / other improvements at their manufacturing sites. This to me shows how important the licensing income is. Without it I think they'd struggle to cover their fixed overheads / invest in their facilities during the general market downturn.
Likewise should boost results nicely if/when growth returns.
Really good info and views here on Sanderson Design (LON:SDG) but can't find any views on what has driven the SP decline post 22nd June AGM statement.
In the absense of anything news-wise do users thinks it's just general market /investor sentiment, or something else ?
Using the charting tool on here with similar companies there does not seem to be a correlation. Just interested in people's views on this prior to digging in further as indeed it seems an interesting one.
SDG decline
Probably quite simple
More sellers than buyers .
My morning smallcap tweet: Ransacking the room of gloom
Myhealthchecked (LON:MHC) Concurrent Technologies (LON:CNC) Videndum (LON:VID) Goodwin (LON:GDWN) H & T (LON:HAT) STM (LON:STM), Nanoco (LON:NANO), Sanderson Design (LON:SDG), Smartspace Software (LON:SMRT)
◄MyHealthChecked (MHC)► sounds like the sales of tests via Boots has disappointed. "It will take time and support to increase public awareness of the benefits of at-home testing and the ready availability of the products and service...It is always challenging to pioneer a major new category of products in the wellness testing market, however our long-term outlook remains positive." [SP=15.01 Cap=8m]
◄Concurrent Technologies (CNC)► ships new version of a flagship 3U VPX Plug-In Card which "extends the use case to Cyber and Radio applications, significantly increasing the estimated full lifetime value of the product". [SP=72.68 Cap=53m]
◄Videndum (VID)► H1 delayed "because more time is required". No shit Sherlock. Expectations are broadly unchanged. "Net debt to EBITDA is expected to be within our covenants and looking forward, given our strong relationships with our banks, we have agreed covenant amendments." [SP=564 Cap=263m]
◄Goodwin (GDWN)► FY-Apr rev up 10%, pretax £22.1m including £3.2m interest rate swap profit. Div 115p (107.80p). No current trading! [SP=4510 Cap=339m]
◄H&T (HAT)► H1-June pretax up 31%, retail sales up 11%. Div 6.5p up 30%. Op costs higher than expected due to inflation. [SP=402 Cap=177m]. I hold.
◄STM (STM)► PUSU offer deadline extended [SP=45 Cap=26m]
In line: NANO, SDG, SMRT
Thanks MrContrarian - Vivendum shares are probably going to take a big cold bath at the bell. Covenant waivers are never easy to stomach.
Just to say your podcast is brilliant. Thanks for making it. Hope Graham and Roland will make one too
Thank you Mo! I enjoy making the weekend podcasts, it helps me focus on the best share ideas that we cover each week, which might otherwise be quickly forgotten about. That's the trouble with trying to cover 550 companies, we're constantly flitting from one thing to the next!
The podcasts are fantastic, Paul. A great mix of comment, analysis, insights, humour and the occasional burp. A highlight of the weekend for me. Please keep it up.
Read through the H & T (LON:HAT) results and everything seems to be going to plan. 30% increase in profit and dividends. Whilst the price will never be racy I do think at some point this should re-rate quite a bit. Still my largest holding
I agree but the market doesn’t seem too. The share price of H & T (LON:HAT) has taken a dive in the last few weeks and it is difficult to understand why. Given the financial results and the ‘cost of living’ crisis their business should be in a strong position. It seems one negative (higher operational costs) offsets multiple strong factors. If I was to stick to my stop loss it would be gone but just can’t bring myself to sell a business which should be, and is, doing well in the current economic climate.
Problem is EPS has been cut 7% today by one broker at least, which isn't good.
I can't understand why they didn't have lower forecasts, which they could then beat. Makes the world of difference if you can put out ahead of forecast updates if only for momentum purposes.
Helps if management know how to play the game. In the long run it might not matter but it doesn't seem very smart to me.
SDI (LON:SDI) final results out.
2023 has been another challenging year for my portfolio. 2022 suffered from a string of profit warnings and disappointments. This year my invested companies have tended to report in line or better than expected but this has had limited positive impact on my performance. The negative sentiment towards the UK market had been the problem, not helped by outflows from retail funds, the strength of the pound and the UK being shunned by international investors.
I am now trimming my direct investments and switching a portion into a UK smaller company investment trust. There are numerous trusts that could fit the bill but my choice is Henderson Smaller Companies Investment Trust (LON:HSL) which invests mainly in FTSE 250 companies. Its share price and NAV have fallen by around 11% and 3% respectively this year. The discount to NAV has widened from 8% to 14%. The trust also has 13% gearing which has exacerbated the decline.
The question I keep asking-what is going to reverse this sentiment? Maybe its when investors start to believe the UK has got on top of inflation, or a weakening pound or a spate of takeovers. When sentiment does turn I suspect the momentum will be fast, hence the need to choose a liquid and well recognised trust.
What will reverse it?
A whole range of factors will retrospectively be cited as causing the nadir which will quickly come to be seen as the bear's "turning point".
Ultimately bear markets simply run out of steam, the bear denouement being there are no real sellers left - a feature of any bear market, particularly where panic and despair come into play, is that assets (in our case small cap shares) pass from weak holders to strong. When sentiment does eventually shift, and there is little liquidity, there will be a rally - perhaps slow at first but then stronger and at some point there might even be a "buyers panic".
When does sentiment change? It can be ahead of meaningful good news starting to flow (perhaps because all the bad news conceivable has already been priced into valuations) or only after it becomes evident the worst news has largely been flushed out, it being outweighed by good. Wish I knew as I'd be sitting on a beach.
Rockwood Strategic (LON:RKW) website is worth a look... nice interview with Richard on there by Edisson... not a big discount but a track record agnostic of market backdrop thus far. On my watch list for a mkt pull back. Already several fans on here. (no holding).
Hi Stevenlondon3 - yes, a difficult time for UK stocks. Re Henderson Smaller Companies Investment Trust (LON:HSL, the 1887 established small cap investment trust. You might be interested to see that it, along with Blackrock Smaller Companies Trust (LON:BRSC) AND Athelney Trust (LON:ATY) have all now made it to the Dividend Heroes AiC list https://www.theaic.co.uk/aic/n.... I hold all three and typically have half my portfolio in investment trusts, primarily UK Small Cap, UK Equity and Global Equity. The attractions of small cap investment trusts at the moment is that they are on a triple discount: unloved UK, unloved small cap and unloved investment trust standing on c20% discounts to NAV. Henderson Smaller Companies Investment Trust (LON:HSL) is very much growth focused, but a good value small cap trust worth considering is Aberforth Smaller Companies Trust (LON:ASL) in my view. All the Christopher Mills Harwood trusts are great at the activist end but don't really pay a dividend; North Atlantic Smaller Companies Investment Trust (LON:NAS, Oryx International Growth Fund (LON:OIG), Odyssean Investment Trust (LON:OIT) and Rockwood Strategic (LON:RKW).
I have avoided UK smaller company investment trusts in the past because it increases the exposure risk when I already hold a portfolio of smaller companies. I have used investment trusts to gain exposure to other countries or resources.
Exactly. Why so much focus only on UK Investment Trusts when they provide the opportunity to invest all round the World and cash in on Countries and Regions that have way outperformed the often dull UK market, and might well continue to do so? There are also bombed out sectors like Commercial Property and Private Equity where discounts are exceptionally wide at present. A few that used to be at premiums to NAV are now on big discounts.
The risk with only investing in UK is that if we hold several Trusts just in the same UK sector there is duplication where the Trusts have similar portfolios AND of doubling up and more our losses if the small company sector has a bad time.
Investment Trust discounts are exceptionally wide at present around 17% across the whole spectrum.
Tritax EuroBox (LON:EBOX) in Commercial Property Europe sector used to trade at a premium but is now on 40% discount and dividend ver 7%. If it just goes back to par with no increase in NAV there’s a 60% share price increase to be had.
Vietnam has been a great winner long term and is good value now after rare 40% market fall before recent recovery and on forward PE of just 10 compared with fully priced India on PE23.
Top performing Vietnam Trusts I hold are VinaCapital Vietnam Opportunity Fund (LON:VOF) and VietNam Holding (LON:VNH) and both are on double digit discounts.
Amedeo Air Four Plus (LON:AA4) which I bought a few months ago at 33p is now 47p but still on big discount and dividend yield is 14% ..and 20% at my buy price. It’s riskier than the others in this post but gives a taste of Investment Trust opportunities for investors prepared to look beyond UK small companies. I like those too and the small company shares so superbly analyses here, but there’s also a big wide world beyond the UK too.
Ken - what's your process for getting comfortable with the stated NAV on VinaCapital Vietnam Opportunity Fund (LON:VOF) and VietNam Holding (LON:VNH) ? Did you do detailed analysis on their holdings, used/relied on a third party due diligence, or satisfied with the fund's reported valuations?
I've never invested in trusts with overseas holdings before, and of course Vietnam is still emerging market level, so wondering how you got comfortable with their stated NAV values.
Hi Boon
I’ll try and add more tomorrow.
For now; we have to leave that due diligence to the Managers as it’s almost impossible for any of us to get up to speed, not least for language reasons, on Vietnamese and other foreign Companies held in Investment Trusts. The Managers are often residents and citizens of those Countries.
There’s no reason not to trust the updated daily NAV updates, except that for a Trust like VinaCapital Vietnam Opportunity Fund (LON:VOF) with some in non quoted but potentially exciting Companies then the asset value for them is uncertain.
The Vietnam Trusts are excellent in keeping their investors informed, including detailed monthly updates in addition to the standard Results figures and comment.
Also though this is paid for comment both Edison and Quoted Data issue some fab reports on Investment Trusts including this recent one on VOF:-
https://www.edisongroup.com/re...
I’ve invested in foreign Investment Trusts and when they existed their warrants and subscription shares for around 30 years and they’ve often proved fabulous investments, with Vietnam performance exceptional. I’ve held VOF and VietNam Holding (LON:VNH) for many years apart from temporary sales.
It’s the performance and quality of the Managers that matters, along with key must knows like discounts to NAV.
e.g VOF is 465p compared with 55p in 2009 and 140p in 2013.
VNH 300p …just 20p in 2009 and 97p in 2013. AND despite these gains the forward Vietnam PE is just 10 compared with India’s 23PE.
I don’t hold India Capital Growth Fund (LON:IGC) at present b cause India looks fully valued but sold after a great run. Quadrupled since covid falls.
I hold a lot of non UK Trusts and several UK Trusts too. Bargain sector is Commercial Property.
Vietnam by the way suffered a rare 40% decline recently for reasons covered in that Edison Report and the monthly updates from The Trusts, but now looks Vietnam looks to be at the start of yet another long bull run.
Agree .... I have the same approach.
Thanks Stevenlondon3 for introducing this thread. In the small cap I/Ts, I currently hold Smithson and BRock Throgmorton though it is about time I reviewed them.
Recently, I decided that the mid cap area might be a good beneficiary of any market up so I am feeding spare cash from time to time into both the Schroder and JP Morgan Mid Cap trusts where their top ten holdings are largely differentiated. I will watch, and maybe learn, something.