Small Cap Value Report (Wed 1 Mar 2023) - MEGP, PURP, IPF, NICL, INL

Good morning from Paul & Graham!
I'm not very good with dates, as you know. For some reason I thought it was Thursday until about my third cup of coffee. Now corrected!
I'll sign off today's report, as I need to move on to watching an IMC webinar from Beeks Financial Cloud (LON:BKS) (I hold). However. I've got some spare time later today, so will prepare some backlog items for tomorrow's report.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
£INL
Quick comment. This is looking increasingly likely, by the day, to go to zero,. Yesterday it said that more time is needed to complete the audit for FY 9/2022 accounts. I imagine PWC are probably having a feast on the fees. It’s hoping to publish accounts some time in March 2023. Today we’re told the Chairman & 2 NEDS have resigned. The Chairman stays on the Board for a maximum of 2 weeks, to allow time to reappoint a new Director (to avoid a breach of the Articles, which would require shares being suspended). Ironically, it says Stephen Wickes is returning to the Board (I suspect he’ll end up presiding over the collapse of the company he ran so badly for years).
My opinion - it’s been a bargepole job for me for a long time. I can’t see it lasting much longer, and the numbers cannot be relied upon. So it’s safest to assume the shares could be worth nothing. Hence purely now for gamblers only.
ME International (LON:MEGP)
133p (up 5% at 08:49)
Market cap £502m
Me Group International plc (LON: MEGP), the instant-service equipment group, announces its results for the 12 months ended 31 October 2022 ("FY 2022" or the "Period").
Highly attractive numbers in the highlight table, especially the big increase in profitability, and extremely generous dividends, whilst retaining a healthy net cash position. Really impressive stuff (hence why the share price has been so strong, as good results were flagged in advance) -

Reasons given for profit rising strongly - good demand, and price rises.
Outlook - no surprises here, it’s in line for FY 10/2023 so far -
Whilst still early into the financial year, the Board has seen a continuation of positive trading momentum and as a result, the Board anticipates that results for FY 2023 will be in line with current market expectations*, subject to any changes to the broader macroeconomic environment
* The Group's compiled analysts' consensus forecast for the financial year ended 31 October 2023 shows revenue of £284.8m, EBITDA of £91.1m and profit before tax of £58.5m.
Confusingly, the outlook section then gives the company’s own guidance, which is higher than market expectations. That seems to contradict the in line statement above, because the numbers below are higher than market expectations above -
Unless there are major changes to the macroeconomic, the Board remains confident in the Group's long-term growth opportunities and its ability to deliver its key strategic priorities. For the 2023 financial year, the Board expects the Group to achieve revenue between £280 and £300 million, EBITDA between £95 and £105 million and profit before tax between £61 and 65 million.
Valuation - I’m working from the adj, diluted EPS figures in this morning’s update note from Finncap (many thanks), and the current (at 08:50) live share price of 133p -
FY 10/2022 actual: 8.9p = PER 14.9
FY 10/2023 forecast: 11.6p = PER 11.5
FY 10/2024 forecast: 12.9p = PER 10.3
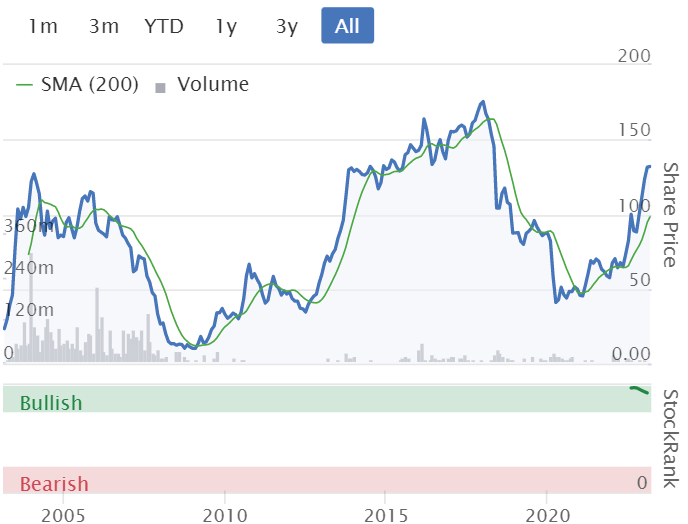
That strikes me as a reasonable (cheap, even) valuation, despite the strong share price of late. This share has roughly doubled in the last year, and I think that’s fully justified. This strikes me as a rise that is likely to stick, and continue, rather than a flash in the pan. But that is obviously dependent on future events, which as always, are unknown - investing is after all, educated guesswork to a considerable extent.
Divisional analysis - this was previously a bugbear of mine, that it wasn’t possible to see where the profits came from. This matters, because the photo booths part of the business has always had questionable longevity (although it’s lasted much longer than people expected - I remember the same conversation about 20 years ago!)
Things are much better now, with full transparency. MEGP comprises 2 main divisions, with the photobooths the key part, but the expanding laundry business now rapidly catching up, and it’s also higher margin. The other parts are financially almost insignificant (although I’m keen to try out the pizza vending, and orange squeezing machines, providing they are clean!)
Many thanks to Finncap, whose forecasts contain a table showing revenues & EBITDA for each division.
For FY 10/2023, photo booths are expected to generate EBITDA of £53m, laundry is £38m - which makes laundry a lot more significant than I realised. It’s growing strongly too, with a roll-out, and laundry makes an EBITDA margin of 50%, strikingly higher than the other divisions (including photo booths) which are 30-31%.
I think this higher margin, growing laundry business, deserves a higher rating than the more mature photo booths business. Note also that the next generation of photo booths is being rolled out, so capex will increase, and that might reduce the ability to be quite so generous with divis in the short term, maybe?
Balance sheet - NAV is c.£100m, which is very similar to the fixed assets figure. Hence the machines are basically funded with equity, which I like.
The rest of the balance sheet is dominated by the £136m cash pile, which is largely offset with loans of £82m (over 1 year), and £36m (under 1 year). This looks inefficient in terms of interest payable, so I cannot understand why the finances are structured like this. Surely it would make sense to save millions in net interest payable, by repaying at least some of these loans using surplus cash? If anyone speaks to management or advisers, this would be a key question to ask. There’s bound to be a reason for it, people running a highly successful business like this aren’t stupid.
Cashflow statement - very straightforward. It generates a ton of cash, which funds heavy ongoing capex, and big divis to shareholders. Increased debt was offset by increased cash, so there’s no worry about debt funding divis (which it isn’t).
My opinion - this is such a good business. I’ve enjoyed going through these numbers. As regards the photo booths business, the worry has always been people switching to submitting photos from their smartphones, thus removing the need for travel booths for ID purposes. Opinions vary on this, with some people pointing out that it can be quite a faff getting the photo exactly right for submission to authorities. I found this when doing my recent passport application, and ended up having to rig up a tripod in the communal hall outside my flat! It would have been so much easier to pop down to ASDAs and just use the photobooth there.
I’m really impressed with the size, growth, and margins of the laundry business. This share is no longer a binary bet on photo booths. Plus there’s growth potential from the other, smaller activities.
Wrapping it up, my personal opinion on this share is very positive. A firm thumbs up from me. If I held, I’d be trying to resist the temptation to bank the profits. I could see this getting up to 200p+ in the fullness of time. Providing nothing goes wrong of course.
Stockopedia's algorithms are strongly positive, with a top notch StockRank of 93.
Purplebricks (LON:PURP)
7.6p (pre market) £23m
Formal Sales Process (FSP) underway (previously announced 17 Feb).
“Several credible expressions of interest”.
Still possible that it may remain an independent, listed company.
Not currently in receipt of any takeover approach.
My view - often when companies put themselves up for sale, competitors get involved just to have a good look through the books. It would be interesting to hear the stats on how many FSPs actually result in a takeover deal. My hunch is that the answer is - not many. Personally I don’t see a lot of value in PURP, although it does still have plenty of cash, which is quite unusual in an FSP situation. Plus there's probably some value to the brand name. So who knows, holders might get a decent outcome, or they might not. It’s just a complete punt at this stage.
Graham’s Section:
International Personal Finance (LON:IPF)
Share price: 110p (+14%)
Market cap: £244m
This is a specialist lender, offering home credit and online loans to customers across Eastern Europe, Mexico and Australia (although not every product is available in every country).
They offer loans to customers on “low-to-moderate incomes including those with limited or no credit history, as well as customers who are regularly refused credit by banks”.
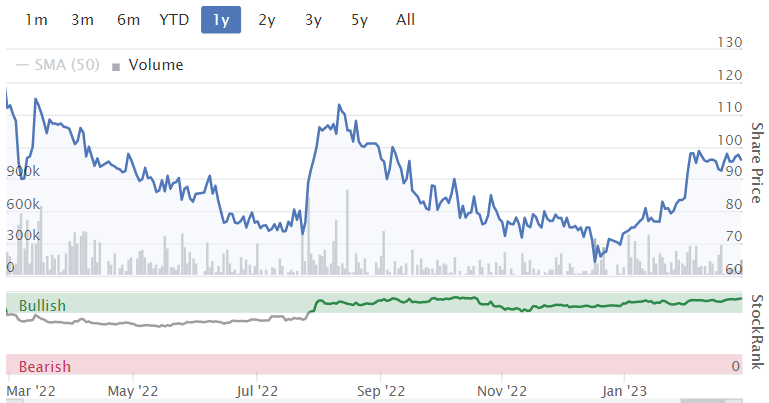
IPF shares lurched into what I considered to be bargain territory in late 2022 (see my October comments). They have since made a recovery:
During that 2022 sell-off, I noticed that IPF’s retail bond offered potentially very good value, and might also be worth a look. The December 2023 bond (ticker:IPF2) was yielding over 12%, with just over a year until maturity.
The yield on that bond has since tightened up, and it has been superseded by a new December 2027 retail bond. The yield on that bond (ticker:IPF3) is in the region of 12%, but with a 2027 maturity it does require a more significant level of trust in the company.
Anyway, that’s enough background. Given the recent share price strength, the market has clearly rediscovered its faith in IPF. Let’s see what these full-year results for FY December 2022 have to tell us.
Highlights:
Net loans/receivables up 14% to £870m (this is calculated by subtracting £500m of loss allowances from £1.37bn owed by customers)
Reported PBT up 14% to £77m
Full-year dividend up 15%
Impairment rate (as % of gross receivables) is 8.6%, up from the exceptionally low 4.9% in 2021.
Company commentary on the impairment rate:
This metric continues to be lower than pre-Covid-19 levels and has benefited from improved credit quality and strong execution on debt sale activity and post-charge off recoveries, delivering c.£15m more customer repayments than 2021. We expect our Group annualised impairment rate to rise to around 14% to 16% as we regrow the business and the Covid-19 period flows out of the calculations.
It’s worth noting that total customer numbers actually fell by 3% year-on-year, after the company tightened up its lending criteria for the highest-risk customers.
Balance sheet
There are balance sheet net assets of £445m (up from £367m year-on-year). So that’s 80% higher than the latest market cap.
The company has borrowed £554m and has further headroom of £76m. They say that their funding requirements are met “into 2024”, although they are also actively looking for new sources of funding.
It makes sense that they would continue to consider all their options when it comes to raising capital. Their cost of funding has risen to 13.3%, reflecting the general rise in interest rates. They have junk credit ratings from both Fitch (BB-) and Moody’s (Ba3).
Regulation
Poland has introduced a cap on non-interest fees to 45% of loan value, down from 100% previously. This went into force in December. There will also be new affordability rules and increased supervision.
IPF has responded by switching focus to digital instalment loans and a new credit card product. Customer representatives “will continue to visit their homes regularly to provide service and collect repayments. We have issued almost 10,000 cards and, encouragingly, the rollout is tracking ahead of our plans.”
Outlook
It’s a balanced outlook statement. An excerpt:
In 2023, our focus will be on transitioning our Polish business to the new lower TCC [total cost of credit], rolling out mobile wallet and continuing the very successful territory extension plan in Mexico home credit. We will also maintain strict control of costs and we see further opportunities to drive operational and structural cost efficiencies.
We have a strong balance sheet and robust funding position with headroom on our funding facilities to support our business plans into 2024. As previously outlined, we expect overall Group receivables growth in 2023 to be more modest and our returns to moderate as we transition the Polish business under the new lower TCC.
My view
I need to wrap this up now. My bottom line view is that I continue to find this one interesting at the current valuation.
Some bull and bear points to summarise my view. Bull points:
Impairment rate is still acceptable despite the inflation which will be affecting many of IPF’s customers.
With the help of that reasonable impairment rate, profitability remains very high.
Management are focused on excellent metrics which include an internal ROE calculation (15%-20%), payments to shareholders and balance sheet strength.
Balance sheet net assets 80% higher than the market cap.
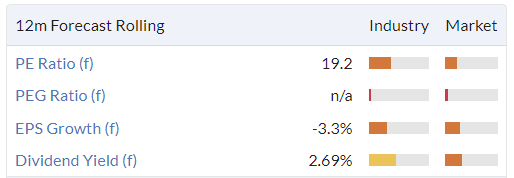
The other value metrics are also very tasty:

Bear points:
It’s inherently risky to invest in Eastern Europe and Mexico without local knowledge.
The average cost of debt for IPF of 13% is very high and reflects that debt markets treat it with great caution.
The junk credit ratings also reflect the high level of caution from debt investors.
Small changes in the impairment rate could have a very large impact on profitability. Remember that the company’s net receivables of £870m are stated after making a bad debt allowance of £500m.
Increased regulation is always a concern, and the Polish market is likely to be less profitable in future years as a result of the cap on the total cost of credit.
I have five bull points and five bear points. While I might live to regret it, I’m going to give this company the thumbs up. It’s a high-risk investment but there is just too much value on offer here, and not enough that is obviously wrong with it.
Nichols (LON:NICL)
Share price: £10.38 (+4%)
Market cap: £379m
This soft drinks group also produces results for the full-year ending December 2022.
Key points:
Revenues +14% to £165m
Adjusted PBT +14% to £25m
Actual PBT £14m
The adjusted numbers produce 27% ROCE, while the actual numbers produce 14% ROCE.
The “exceptional” items add up to £11m of costs. These include:
£1.5m to review and change the company’s supply chains. This project has resulted in new five-year manufacturing and distribution arrangements. While the amount spent on this project was unusually large in 2022, I’m not sure if it is a truly “exceptional” expense.
£0.5m to review the company’s “Out-Of-Home” route to market, with a view to improving profitability. More costs related to this project will be incurred in 2023. I think this is a very important mission and I hope that it finds success. But as with the supply chain review, I don’t consider it to be a truly “exceptional” item.
Impairments of almost £9m to both intangible and fixed assets. This flows from deterioration in the Out-of-Home division as trading in Cinema, Holiday and Theme Park venues has seen a “significant volume decline” versus pre-Covid levels. The impairment also reflects an increase in the company’s estimate of its own cost of capital (from 8% to 13%).
I do accept that these impairments are truly one-off in nature and it’s fine to adjust them out of the results. However, it is another reminder, if one were needed, to be wary of balance sheet values - not just intangible assets, but also fixed assets are often vulnerable to writedowns!
Cash flow and dividends are both healthy.
Free cash flow is still good at £14.6m, although lower than last year, as cash conversion reduces to 72% (from 103% last year).
The full-year dividend increases 20% to 27.7p. Half of adjusted EPS is being paid out to shareholders.
The company ended the year with a cash balance of £56m. That’s material given the market cap is less than £400m.
Balance sheet net assets are now £89m, down from £93m last year. With intangibles and fixed assets having been written down, this is a very liquid balance sheet with few liabilities and over £100m of current assets.
Strategic highlights - Vimto has outperformed the broader dilutes market by 2.3%.
Outlook - FY 2023 adjusted PBT is seen in line with expectations. Weakness in the Out-of-Home division will be offset by strength in International trading.
With a long-term track record of growth, a proven and diversified strategy in the UK and internationally, a quality range of brands and a strong balance sheet, the Board remains highly confident that the Group is very well positioned to deliver its long-term growth plans.
The consensus estimate is for an adjusted PBT of £25m in 2023, i.e. the same result as in 2022. Hopefully there will be fewer adjustments this time! The intangible assets have already been written down, and one of the strategic reviews has been completed already, so it should be a cleaner result in 2023.
My view
I’m in the camp which says that margins should normalise as inflation feeds through the system. I also note the company’s strategic reviews which are explicitly focused on improving margins and profitability.
The company has today published the actions it will take to improve the performance of the Out-of-Home segment. These include running it as a distinct division within Nichols, exiting underperforming contracts and categories, and improving financial reporting so that divisions and regions must report their ROCE.
Since my suspicion is that margins will improve, and since the management team is so focused on making it happen, I have to give this company the thumbs up. Even at the current, somewhat muted level of profitability, the PER is only around 20x. In my view this is a good price for a cash-rich, consumer-facing business with excellent heritage and a fine chance of seeing profits and returns improving in the years ahead.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Not sure if this is new news but I have just read that SThree (LON:STEM) is to be added to the FTSE250 index. I assume this explains the recent rise in SP (apart from it being a super stock!).
Getbusy (LON:GETB) ( I hold)
Polite request for a look at Getbusy. Numbers out today. Good growth across the board. Very sticky customer base. Opportunities to grow in other segments. Cash increased year on year. All growth self funded. High level of repeating revenues 95%. Finncap have become brokers and initiated today so a note is on Research Tree.
Post a management meeting, I still think they are under promising and over delivering which I'm happy with. Management remain big holders at over 40% of the equity.
I am also a holder but outraged by the Cash Distribution Plan. I had to read it several times and I am still not sure that I am reading it correctly.
But, if I am reading it correctly, if the company hits the stretch target of £150m Daniel Rabie will receive 15% (£22.5m) and Haworth would receive 10% (£15m). Can this really be correct???? I hope I am misinterpreting something.
Sure , we can say that if the stretch target is met, then shareholders will be happy. But these sums are outrageously large for a microcap and surely unnecessary to “incentivise” mangement to do the best job they can do.
I see that Finncap as NOMAD (appointed only 4 days previously) has been consulted by the independent NEDs as to the awards’ fairness and reasonableness.!!! It does not put AIM in a good light.
I’ve read outrage and derision on Getbusy (LON:GETB) today…
On the remuneration plan of mgt are getting a big payout as they have distributed £70m cash over 7 yrs then I’m not going to begrudge CEO £5m and CFO £1.5m and I’ll be delighted they’ve stuck around for next 7 yrs delivering this to us…and if it’s £150 gross cash distribution and they are deep in reward bonus…well the market cap is likely something at least 20x now.
The new loan facility requires some explanation. Maybe SVB pulled the old one for some reason (I’ve sought a biz loan from SVB in the past and they are pain in ass and changeable) and elder Rabie is providing a stopgap until they can get alternative
Mojomogoz. I hope you are correct re Getbusy (LON:GETB) Cash Distribution Plan. What is not clear from the text in the RNS, is it only talking normal dividends or also the sale of parts or all the company. My reading is that it includes the sale of the company - because that seems the only way to hit the targets - but I admit it is not crystal clear.
To sell the company for £150m within 7 years - does not seem too much of a “Stretch target” - say to get ARR to £40 or £50m and to sell at 3-4x ARR.
I would think management had done an OK job if that came to pass - not some stellar job. Management should not get some special reward for seeing the multiple expand.
You might be right in your dastardly inference! Qs to be asked. Based on interactions I trust mgt at Getbusy (LON:GETB) but they always have the opp to lose it. I wouldn’t be happy with a £70m take out (or even £150m) as I think the company will be worth much more.
Getbusy (LON:GETB)
I have contacted the management and as I understand the numbers the CEO and CFO would receive an incremental £7.5m at the stretch target of £150m. That would be split roughly equally between the two of them. As you say below the reward vs the length of time taken to get there is a relevant consideration.
WimbledonSprinter- I live in Wimbledon fyi!
Mike
Mike and Mojomogoz
Thanks for your replies. I have also contacted management, who I found very forthcoming and precise with their answers, which has changed my understanding a bit but not necessarily in the direction I wanted to hear.
I now understand that if the entire business were sold for cash within the 7-year timeline for £150m, then shareholders would receive £123.25m and the two recipients of the CDP would receive £26.75m.
Mike - I live within jogging distance of Wimbledon.
Aeorema Communications (LON:AEO) just announced a very strong TU for first half. it confirms growth and several negotiations ongoing.
based on revenue my modelling indicates c.2m profit possible next year with net CASH 1-2m all for an MV of c.7m.
the chart break out today is an all time high and a very strong multi year pattern. i hold but there is a wide spread, it there is low MV so doesnt suit those looking for quick trading gains.
Aeorema Communications (LON:AEO) i feel excellent risk/reward ratio esp. given the long term chart confirmation of increasing buyers.
Out of interest, how do you get to a pre-tax profit of £2m?
Last years pre-tax was £0.843m and H1 pre-tax is up around 30%. If that was repeated in H2 and next year, I get to £1.42m.
Of course growth could accelerate but I think they will also see higher admin costs because of wage inflation etc.
hi Daz3. Aeorema Communications (LON:AEO) my calcs are for FY ending June 24 i.e. the next full year after this June closes. given the confidence they state for global contracts i was going for higher growth and thus margin gains compared to H1 and last year. what is clear for me is the growth record and trajectory of the company. given such i also don't try and 'predict' market ratings. thus whether they hit c.£2m this in 18mth or 24mths i am relaxed about. what is clear on the upside for Aeorema Communications (LON:AEO) is that that level of profit, plus net CASH, would give a nice margin of safety if buying at MV of c.7m
Thanks for the reply 30 50 20.
I agree still very good value, as growth looks very likely for the next 18 months at least.
I do think they will be affected somewhat by cost pressures (although that should eventually feed into higher prices they charge their customers), so I'm a little more cautious than you on pre-tax profit growth
It's only a trading update, so not much detail, we'll have to wait for the interim's for more comment.
Thanks again
Very helpful write up on Nichols, Graham. Thanks. I hold and though a bit under water may top up.
Nichols (LON:NICL) This company usually gets a good report and is designated as a quality company but it’s shares have been in a downtrend since 2017? Don’t quality companies increase their value? The report details very competently it is going to run the company in the next 12months but I struggle to see that they will increase the value of my shares
Time will tell
On Purplebricks (LON:PURP) - does anyone have any updates / views on what happened to their stake in Homeday in Germany?
Homeday was a fast growing online real estate agent there. It was jointly owned by PurpleBricks, and Axel Springer (who are a big German media and tech group). AS is also the largest, or one of the largest, shareholders in PurpleBricks.
There were some complicated agreements in that joint ownership. I believe PB only owns a minority share now, as AS has had to pump in more cash, as Homeday is loss-making. And AS does have some sort of option to buy out the PB stake? But details are scarce.
At one point in the last few years, I had thought that potentially that Homeday stake could be worth anything from £10m to £50m to PB. But unsure now, as nothing has been talked about for a long time,.
Thanks for your extensive write up of International Personal Finance (LON:IPF) (I hold both shares and bonds) and it's worth noting that while now also offering both hybrid and online finance they work through a vast network of self employed agents in each of their countries. This gives them great insight into those markets and if you want an in-depth understanding of how they work it's worth watching their Mexico (2023) and Poland (2022) Investor webinars.
In my view the share price has suffered unjustifiably as IPF are lumped in with the doorstep lenders in the UK Morses Club (LON:MCL^B23) and Provident Financial (LON:PFG) and the troubles they been having. IPF's stance on financial inclusion is impressive and if they were treated as a fintech I'm sure they would be valued much more highly.
You're very welcome, Quilleron. Best of luck with both the shares and the bonds!
I also hold the bonds and with IPF3 unchanged on the day at the 101p offer price, yields a touch under 12%, which looks very safe on the results and outlook.
As Graham highlights, things can change quickly but IPF has been around for many years and have not to my knowledge missed a bond payment. In a downturn, the dividend is much more at risk
Provident Financial (LON:PFG) are no longer a doorstep lender Quilleron
“During 2021, the Group's evolution continued and involved the closure of its
home collected credit business, which carried the 'Provident' brand”
They now focus on credit cards, vehicle finance and personal loans & this has prompted the name change to Vanquis Banking Group
I hold both International Personal Finance (LON:IPF) & PFG, tho I do appreciate that not everyone is comfortable with this type of finance companies
ME International (LON:MEGP) comments are saying inline but the Net Profit and EPS are below Stockopedia figures? Forecast no growth next year?
Ricardo (LON:RCDO) interims in line. Transition towards environmental and energy consultancy continues with expected hiccups, notably restructuring in automotive and industrial (mobility) that encompasses high performance ICE engineering.
Significant increase in order book and order intake, debt reduced and nice 15% increase in the dividend. A fair few moving parts to digest, but all in all happy to remain invested.. The future looks promising and the shares are not overly expensive.
Paul/Graham any thoughts?
Morning Base Resources (LON:BSE)[I hold] Put in a great half year set of results on Monday. Plans for new mines with increased yield of rare earth minerals. Thought this should get a mention. Share price hardly moved , Coffee can share paying a good dividend .
FY23 half-year results to the ASX.
Record first half sales revenue of US$126.6m, EBITDA of US$80.7m and NPAT of US$44.6m.
Sustained demand for all products results in 32% increase in average price of product sold to US$681 per tonne.
Extension of Kwale Operations life with mining operations commencing on the Kwale North Dune in late February.
Exploration drilling in northern Tanzania and Kwale East commenced.
Toliara rare earths study progressing to pre-feasibility study phase.
Discussions on fiscal terms for the Toliara Project progressed substantially.
Half-year dividend of AUD 2.0 cents per share totalling AUD$23.6m (approximately US$16.0m) determined.
It was mentioned.... on Monday :D
Hi Believer
This has been on my radar for a while now, not least as I hold Kenmare Resources. However, have you any insight into why forecasts for FY/E 6/24 are so much lower than for 6/23?
Unless I'm missing something here this looks any easy beat?
Hi Norfolk
I think Base Resources (LON:BSE) forecast for 24 is so much lower as the existing resource will be running down. Its life has just been extended to run through 24 and the rest depends on new points of extraction coming on stream. The big issue for me though is the lack of permits to proceed in Madagascar as this appears to be the real future of the company.
Hopefully they will get the go ahead there and all the government blessings and everything and the share will fly. But that IMO is the risk you are taking. Kenmare Resources (LON:KMR) seems a comparatively solid, lower risk proposition. Might be just because I hold it that I take that view though!
Thanks very much for the information - sounds like i need to do a lot more digging - much like Base Resources......
This is from the Base Resources (LON:BSE) website re the Madagascan project:
"Base Resources is progressing the Toliara Project in south-west Madagascar, 45km north of the regional town and port of Toliara.
The Toliara Project is underpinned by the large, high grade, ilmenite rich, Ranobe deposit, and is considered by Base Resources to be one of the best mineral sands development projects in the world.
The project is well advanced with mining license and environmental approvals already in place and is currently progressing towards development"...
So it looks as though they do have the go-ahead??
SP has moved a bit today, the risk / reward still looks excellent imo. The MD has highlighted a few drivers:
Interestingly Trident Royalties (LON:TRR) recently bought a royalty over Kwale on the basis that prospects for life extensions beyond 2024 were positive. See RNS below…
https://www.investegate.co.uk/...
Yes, looks positive. I believe the issues weren’t in relation to ‘is there any ore left’ but were more to do with relationships with tribal land owners, which appear to now be resolved.
Inline results from ME International (LON:MEGP) but I can't work out why they have taken on board over £60 of new debt when they have net cash, and have such a cash generative business ? Makes no sense to me given today's high interest rates.
Can you point me to where this new debt is stated?
in the balance sheet and cash flow statement...
I get gross debt increasing by £38m (note19).
Looks like they drew down/borrowed long term debt to fund the repayment of £30m short term debt falling due in the next 12 months (note 21).
The lion's share of the cash generated during the year was invested in Capex and extracted in dividends. This would reflect contentment with the firm's capital structure ie debt levels.
Not so. They made £43m FCF and out of this they paid £35.5m in dividends. So even after capex and divs they have £7m in free cash. True, they have paid pack £25 in debt but they had bags of cash already on the balance sheet to do this, and a further £7m in free cash from this year so I see no need to take out an extra £60m, with interest rates the way they are now. Just seems bizarre to me.
When the short term debt is repaid from existing cash balances they'll have £106m cash, £72m gross debt and net cash of £34m.
This is similar to 31 October 2021 when they had cash £99m, gross debt £64m and net cash of £35m.
Rightly or wrongly, that's how he likes to run his balance sheet.
Loans carry fixed interest at between 0.49% and 1.2% (annual report note 15B), a lot less than prevailing short term rates.
He has been there a long time and I understand he felt 'let down' by banks during the financial crisis. Given the low rates he's managed to lock in, he may feel the flexibility provided by long term debt justifies the interest cost given geopolitical and market volatility.
The Annual Report also makes mention of their being keen to make appropriate acquisitions
I would imagine access to such cheap finance would enhance the attractiveness of acquiring businesses complementary to the existing ones making up ME Group
As a holder I shall watch with interest to see what they find
My morning smallcap tweet: Rats leaving the stinking ship
Inland Homes (LON:INL) Purplebricks (LON:PURP) Immotion (LON:IMMO) Mobile Tornado (LON:MBT) Harland & Wolff group (LON:HARL) Accrol group (LON:ACRL) Public Policy Holding (LON:PPHC) ME International (LON:MEGP), Ricardo (LON:RCDO)
◄Inland Homes (INL)► Chmn and both NEDs resign. Leaves only one director (CFO) so chmn will stay as a NED for up to 2 weeks to find another director. The new CEO left after a month in Jan, no reason given. Co finds some "related party issues (which may or may not fall to be treated as related party transactions under the AIM Rules) of which the Board was not informed at the relevant times". SP down 87% in 18 months. [SP=10.2 Cap=23m]
◄Purplebricks (PURP)► gets several credible expressions of interest in a takeover. [SP=7.55 Cap=23m]
◄Immotion (IMMO)► completes sale of of Location Based Entertainment business. [SP=3.4 Cap=14m]
◄Mobile Tornado (MBT)► £500k subscription at 2p, a 5% discount, to accelerate our business development activities. £260k of debt converted at shares at 2p. Guides FY-Dec rev down 12%. EBITDA -£0.29m (-£0.03m). In line? [SP=1.96 Cap=7m]
◄Harland & Wolff (HARL)► guides FY23 in line with re v £100m-£115m. Guides FY24 rev £200-230m and C/F breakeven. Backlog of contracts c.£900m over 7 years. [SP=16.57 Cap=29m]
◄Accrol (ACRL)► licenses Unilever's Lifebuoy brand for kitchen towels. Will sell it cheaper than the market leader. [SP=31 Cap=99m]. I hold.
◄Public Policy (PPHC)► buys MultiState Associates, a US government relations and public affairs group, for $22m. Guides FY22 rev up 10%. In line? Says U/L EBITDA margin is in line so why don't they tell us if rev is?. [SP=134 Cap=147m]
◄ME Group (MEGP)► [last nght] delayed promised FY RNS to today, no reason given. Accounts published on website last night look in line though. [SP=126.5 Cap=478m]. I hold.
In line: RCDO
ME International (LON:MEGP) (I hold) previously stated they'd publish year end results toward the end of February. What shareholders perhaps failed to appreciate was that they were measuring in hours rather than days so the only two RNS yesterday were to rattle the market by announcing in the morning their intent to publish later in the day, and announcing in the evening the results RNS would not in fact be until this morning but that the annual report would be available on their website yesterday evening, which it subsequently was.
One might have felt suspicious but as it turns out revenue and PBT were in line with expectations raised in November, which one might hope would be the case given the date of that update was already after the year end. For what it's worth EBITDA was a beat. Net cash on hand. The boards one third interim and two third final dividend policy appears to have led some holders to be looking for 6p or thereabouts with this results announcement, and therefore they might be disappointed at the proposal for 3p 'only', the 6p special dividend being included in the final dividend calculation, not quite such a special dividend then, but still 12p for the year is significant and more than 4x the previous year. I get the feeling reading the report that this company could grow faster, (I'm not specifically making the case for that) but highlighting the dividend policy may be a drag on ME International's capital allocation for new and upgraded hardware.
Laundry has grown well but photo booths continue to dominate having grown just as quickly! That may be structural or may reflect a Covid recovery. There are different ways of viewing the domination of the legacy photo operation, as the diversification into other automated services needs funding from something, preferably in my opinion, not from diluting fund raises. The board predict steady growth for the next five years.
ME International (LON:MEGP) My request is now on repeat as we now have the Annual Reports ;-)
EBITDA looks a beat, nice increase in dividend to 3p
Conservative accounts as befits an owner operator business
Happy to continue holding
are you a month ahead of yourself?
Good morning Paul. I would appreciate your views on this morning's results from ME International (LON:MEGP). Thank you.
You had me going, thought I missed a day somewhere ! (Paul I think it's wednesday - while I'm posting, a quick thankyou for your efforts, always enjoy the podcast as well)
You are getting ahead of yourself again
Morning Paul it's Wednesday!
Yes it's strange isn't it. I knew it was Wednesday, but typed Thursday, originally. Guess I'm just not a morning (or dates) person!