Small Cap Value Report (Wed 1 November 2023) - SPE, VTU, ECK, VARE, ASC

Good morning from Paul & Graham!
Graham's youtube link today - I'll have him on in the background whilst I'm finishing off my next section here on Asos!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Agenda
I've turned a couple of items grey, to indicate that the announcement isn't very important, so we won't elaborate on it in the main report, but quite useful to leave it in the list as a reader note -
Summaries
Sopheon (LON:SPE) - up 88% to 920p y’day (£98m) - Possible Cash Offer - Paul
Possible takeover bid at 1,000p/share seems to have been agreed by an American trade buyer, backed by private equity. The 104% premium is a remarkable outcome, so it's highly likely to go through, although is not quite a formal offer yet, despite due diligence having been successfully completed. The price is more than fair, given lacklustre financial and share price performance from Sopheon over the last 4 years. Likely to go ahead, I reckon.
Vertu Motors (LON:VTU) - up 1% to 76.7p (£261m) - Acquisition - Paul - GREEN
I only intended to flag that this latest (small) acquisition is nicely asset backed, with little goodwill involved in the transaction - adding to the appeal of Vertu’s acquisitive strategy. Below, I’ve summarised my take on the bull & bear points currently.
Eckoh (LON:ECK) - down 6% to 40p (£116m) - Half-Year Trading Update (rev miss) - Graham - AMBER
Sales are currently taking longer to close and Eckoh is now set to miss full-year revenue expectations. Revenue forecasts are trimmed 6% though profit forecasts are unchanged. It’s an uninspiring update and I’m struggling to find reasons to get excited about this one.
Various Eateries (LON:VARE) - down 2% to 27.5p (£24m) - Trading Update (in line) - Graham - RED
This restaurant/club operator has published an “in line” statement for FY 2023, although estimates for FY 2024 have been downgraded. I am wary of this sector and Various Eateries seems to be in a precarious position, with a dwindling cash balance as it attempts to expand.
ASOS (LON:ASC) - Down 10% to 357p (£424m) - Final Results - Paul - AMBER/RED
Poor figures - it's loss-making, badly run I think, and struggling to execute a turnaround. Debt is a worry too. However, there might be strategic value in the share, especially to stakebuilder Frasers (LON:FRAS) . So this could go either way, but weak fundamentals means I have to lean towards a negative view.
Paul’s Section:
Sopheon (LON:SPE)
Up 88% to 920p y’day (£98m) - Possible Cash Offer - Paul
“Agreement in principle” has been reached between Sopheon’s management, and Wellspring Worldwide Inc (specialist software) for a £10.00 (a large premium of 104%) cash takeover bid. Wellspring itself is controlled by an American private equity outfit called Resurgens Technology Partners. So this is both a trade sale, and a private equity sale.
Discussions are well advanced, with due diligence already completed. So this bid has clearly been in progress for some time, yet the market was not notified, hence there has been in effect a false market in SPE shares for possibly around 2-3 months, where material, price sensitive information was not disclosed to the market. The UK disclosure rules really must be changed, to force companies to tell the market as soon as meaningful takeover talks begin with a credible buyer. Everyone who has sold in the last couple of months has lost out, because they weren’t told that meaningful bid talks were being held. Why didn't Sky News or Betaville spill the beans, I wonder?!
Irrevocable support has been received from two large “key” shareholders, holding 37.3% (Barry Mence, and Rivermore).
A wobbly outlook comment will certainly give shareholders a good reason to vote for this deal, if it (as seems highly likely) progresses to an actual bid -
The Sopheon Board reiterates the outlook statement made in the interim results (as further described below) but also highlights that the current uncertainty regarding U.S. government budgets has the potential to cause delays in closing certain transactions in its pipeline.
Paul’s opinion - this is a cracking deal, that of course Sopheon shareholders are likely to accept - they’ve doubled their money overnight! An outstanding result, given such difficult market conditions, and worsening macro.
This is the point that people on bulletin boards go through the motions of pretending that they’re disappointed with the deal and the company is worth more. That’s nonsense, this is clearly an attractive valuation, as SPE management says in the announcement.
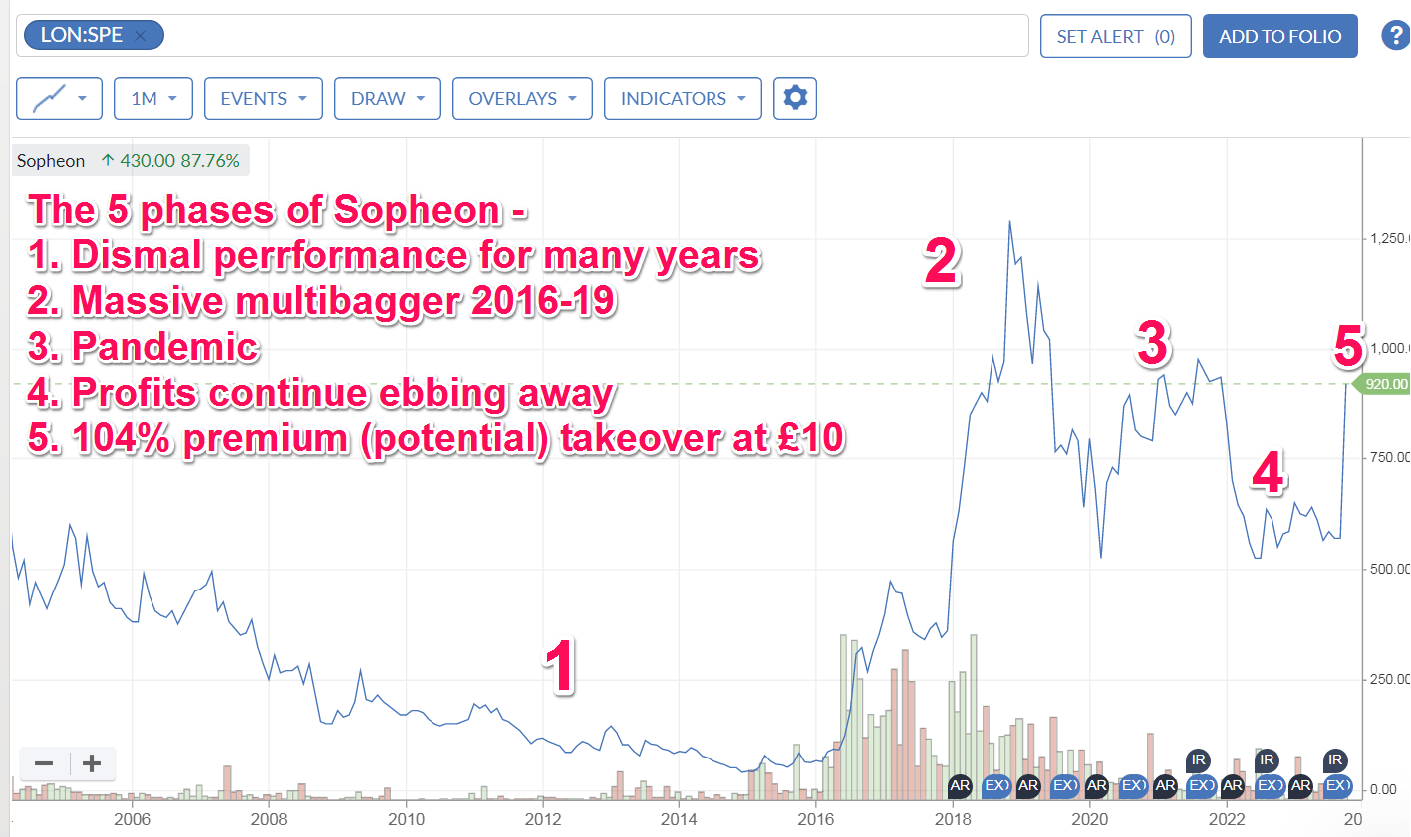
Performance at Sopheon has been lacklustre in recent years, with the high profitability achieved in 2017 & 2018 melting away gradually, with a 2023 result forecast to be not much above breakeven. That, and a nasty bear market, is why the shares have fallen by more than half from the Dec 2018 peak of about £12/share. So to receive £10/share now is a marvellous outcome in the circumstances I feel.
Here's my summary of SPE's life as a listed company -
Vertu Motors (LON:VTU)
Up 1% to 76.7p (£261m) - Acquisition - Paul - GREEN
Vertu further expands its footprint in the South West of England with the acquisition of Rowes Garage Limited
This is only a small deal, of 4 (mainly Honda) outlets in the South West, but something in the announcement caught my eye which is worth flagging - the asset backing. The £6.2m acquisition price includes freehold property valued at £3.6m. The goodwill element of the acquisition is only £0.9m.
Acquisitive groups often hollow out their balance sheets, and sometimes then end up in financial trouble, because acquisitions are mainly goodwill. However, in this sector, car dealers usually seem to own their freeholds, so the acquisition price in this case is not much above the net tangible assets being acquired - a good thing. There also seems a spin-off benefit of deepening the group's relationship with Honda.
To my mind, this makes VTU’s acquisitive strategy much more attractive than it would be in other, less asset-backed sectors. VTU seems to be a sector consolidator, buying up smaller independent groups of car dealers, and might itself end up being bid for by a larger group, possibly overseas?
Paul’s opinion - VTU is a long-standing favourite value share here in the SCVRs.
Bull points -
Particularly strong asset-backing,
Acquisitions seem sensible,
Management come across well in webinars, on top of the detail,
Good performance throughout the pandemic & vehicle supply disruption,
Divis/buybacks,
Low PER,
Bonanza of takeover activity in the sector, with seemingly everyone apart from VTU receiving bid approaches!
Bear points off the top of my head might include -
Uncertainty re change in business model being pushed by manufacturers might pan out,
Used car gross profit possibly falling as supply gradually normalises,
Higher interest charges now eating up a considerable portion of operating profit,
Uncertain demand for (high margin) servicing/repairs for EVs,
Wage & energy cost rises (probably peaked now?)
General macro factors.
Personally I banked my profits a while ago (mentioned here before I think), purely as I wanted funds to buy more Plexus Holdings (LON:POS) (I hold). Also, VTU has had a great run (in a very tough small caps market) in the last year. Although I strongly suspect I’ll be kicking myself if or when it announces a bid approach, which seems quite likely.
I only intended flagging the fact that acquisitions are solidly asset-backed, but ended up doing a recap on the share overall. I’m happy to stick with GREEN, given the likelihood of a bid, and the great asset backing, whilst acknowledging there are uncertainties about the future.
ASOS (LON:ASC)
Down 10% to 357p (£424m) - Final Results - Paul - AMBER/RED
Sale of Topshop? - Thomson Reuters useful news snippets in the Stockopedia “News” tab for Asos, says today that it has declined to comment on rumours that the fairly recently acquired Topshop brand (from the wreckage of Philip Green’s Arcadia group) is now up for sale. It had previously been widely reported in the press that talks are underway to sell Topshop to US brands giant Authentic Brands - who the internet says owns >50 consumer brands, and had revenue of $22bn in 2021, and is private equity backed (CVC and HPS).
It will be interesting to see how this pans out. The Topshop acquisition by Asos in Feb 2021 has clearly not boosted Asos’s results, or possibly might have masked even worse performance from the rest of Asos? Asos paid £265m cash for Topshop, which is looking a big mistake now, with hindsight, given Asos’s precarious financial position.
Final Results (a year + 3 days to 3 Sept 2023, which I’ll call FY 8/2023)
It’s the usual story from Asos - turnaround underway, but lousy figures. Lots of adjustments.
Some numbers -
Big revenues of £3,538m (down 9% reported, down 11% adjusted)
Low gross margin of only 44.2% (LY: 43.6%) - this has always been Asos’s achilles heel, which is why it has never made any significant profit (apart from a brief patch in the pandemic). It’s slowly dawning on the market, after 20 years of being a massive multibagger, that Asos isn’t actually a good business at all. Maybe we became intoxicated by the stellar revenue growth, with hardly anyone noticing that it didn’t make profits.
Profitability? It’s a loss before tax of £(70)m on an adjusted basis, and a draw-dropping £(297)m statutory loss before tax.
Net debt - doesn’t seem too bad, but that cash figure no doubt swings up & down a lot, is probably at or near a peak on reporting dates, otherwise it would have been used to pay down gross debt. Hence I imagine it needs the borrowing facilities, and is highly dependent on the £464m bond - carefully inspecting the terms of this is vital research if you’re thinking of buying or holding this share.
Note also the very expensive £31m cost of refinancing fees this year.
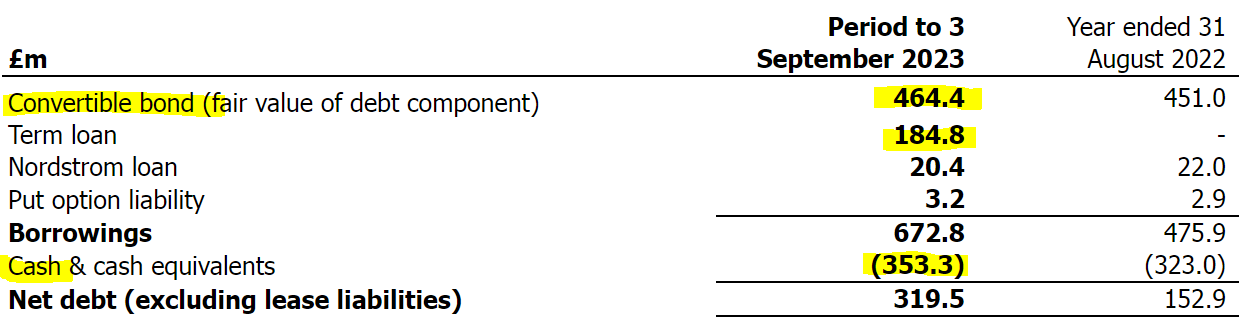
Balance sheet - overall is not strong, but not a disaster (providing it can keep the lenders sweet, and in compliance with covenants).
NAV is £867m, less intangible assets of £701m, gives NTAV of £166m.
Inventories have come well down, from £1,078m a year earlier, to £768m this time. That needs to come down further, and the commentary seems to acknowledge this.
Cashflow statement - looks bad to me. The benefit of de-stocking has been offset by reduced trade creditors. There’s nothing in operational cash generation to pay for the hefty capex, £136m of which is “purchase of intangible assets” - which sounds like some or all might be development spending? Physical capex spending was another £42m.
The gap of negative cashflow has been financed with £78m fresh equity issuance, and about £200m of extra borrowings.
This is absolutely not a healthy business, based on these numbers.
Outlook - is mainly aspirations, which are not of much interest to me, as Asos has such a bad track record of execution.
Specific guidance is useful, and here it is -
o Sales decline of 5 to 15%, with P4 FY23 trends (i.e., high double-digit declines) continuing through the first half of FY24 and a return to growth in the final quarter of FY24.
o Adjusted EBITDA positive.
o Stock back to pre-COVID levels (c.£600m as previously communicated).
o Capex of c.£130m.
o Positive cash generation, reducing our net debt position.
Adj EBITDA is meaningless here, due to the heavy capitalisation of costs into intangibles.
Paul’s opinion - I see this as a badly run, poorly performing, loss-making business.
So the shares are a punt on whether it can either be turned around, which I think will take time (if it can be achieved at all), or whether the strategic value of the business might result in some kind of takeover deal (all eyes are on large shareholder Frasers (LON:FRAS) )
I haven’t regurgitated here the turnaround plans, because it all strikes me as just fixing the absolute basics of how a business like this should be run. I was told years ago by a former (senior) finance member, that it was a very poorly managed business, with all sorts of deep-seated problems, and he seems to have been proven correct.
Are the shares any good? Not on fundamentals I’d say. However, to an acquirer? Who knows, maybe? If a shrewd operator got involved here, and stripped out a load of costs, then every 1% on the margin would be a £35m bottom line improvement.
So this could go either way.
Looking back at my previous notes here, I was red in our reviews on 14/3/2023, 10/5/2023, and 26/5/2023, but moderated to AMBER/RED on 15/6/2023 and 26/9/2023, to reflect the debt refinancing, and the stakebuilding by Frasers.
I think that’s the right stance to take now too, so I’ll stick at AMBER/RED - a poor quality business, struggling to be turned around, but might be of strategic value to an acquirer?
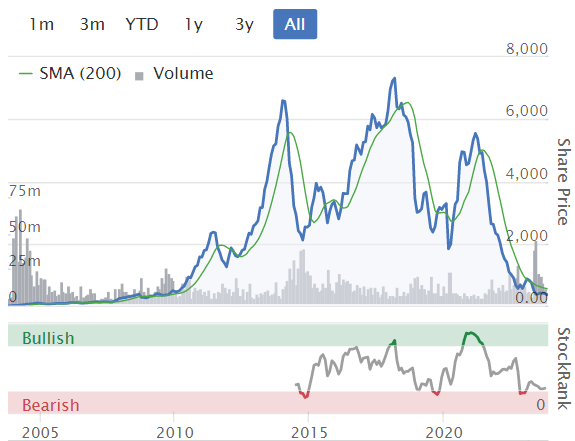
Eckoh (LON:ECK)
Share price: 40p (-6%)
Market cap: £116m
Eckoh plc (AIM: ECK), the global provider of Customer Engagement Data Security Solutions, today announces an update on trading for the six months ended 30 September 2023
Investors have been less than impressed with this company’s performance in recent years:
Starting with the good news: H1 trading is in line with expectations.
Revenues are £18.8m (last year: £19.6m), “reflecting the loss of a large (non-security) UK client” as previously disclosed.
H1 adjusted operating profit is c. £4.1m (last year: £3.5m).
Separately from revenues, the company has a forward-looking measure, “Total Contract Value”. This is the value of business signed during the period, including renewals. It’s up 40% year-on-year to £24.6m. This should bode well for future revenues.
Switching to cloud-based deliveries to customers: Eckoh says that this change has hurt revenue growth in the short-term, but is increasing the “visibility and quality” of earnings. Fair enough. 83% of revenue is now recurring (up from 79%).
Net cash at the end of H1 has risen modestly to £7.3m.
And now for the bad news: revenues aren’t meeting expectations for the full year.
Here’s the explanation:
The Company is, like others, experiencing a lengthening of sales cycles with new clients, especially in the contracting phase. Consequently, the completion of contracts is taking longer, and several sizeable enterprise deals where Eckoh is the chosen supplier, which were expected to close in the Period, will now shift to the second half. Despite this, Data Security Solutions annual recurring revenue ('ARR') for the key North American market still strongly increased year-on-year by 22% to $16.8m.
But the company still plans to hit profit forecasts:
Whilst the longer than expected sales cycles will marginally impact revenue, the Board is confident that the Company is on track to meet profit expectations for the full year.
Graham’s view
We have struggled to get excited about this company - see my comments a year ago and Paul’s comments in May. Growth hasn’t been particularly exciting and the valuation always seems to be a little on the high side.
Again today, we have declining real revenues and investors have to make do with a strong “total contract value” instead.
We also have lengthening sales cycles and a revenue downgrade for the current year. Investors must make do with the promise that large pipeline deals will be closed next year, and a promise that revenues are now higher quality than they were before.
Valuation also remains on the high side:
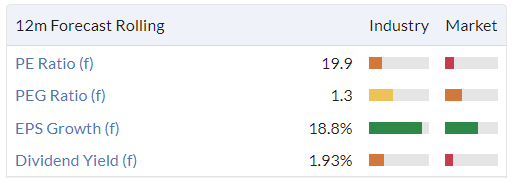
However, I do think that valuation has cooled from where it was before: trailing price to sales is now only about 3x (I think it was previously 4x).
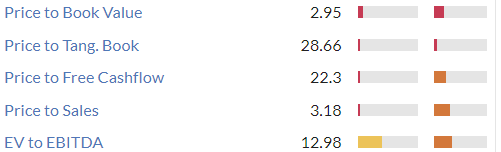
Let’s see if the current EV/sales multiple can tempt us.
With £7m of cash on the balance sheet, that gives it an enterprise value of about £109m.
The new revenue forecast for the current year from Singers is £39.6m (down 6% from their previous forecast).
So this is on a current EV/sales multiple of about 2.75x.
I can’t find any way to make this stock look cheap, unless you’re willing to use a very expensive peer group as comparables.
So I’m sticking with my neutral stance on this one.
Various Eateries (LON:VARE)
Share price: 27.5p (-2%)
Market cap: £24m
Paul last covered this one in June.
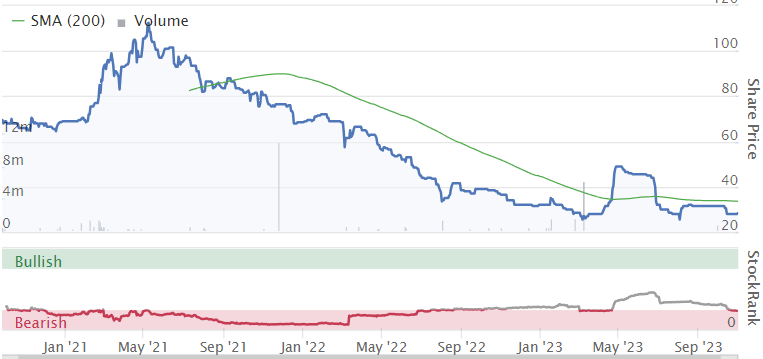
Here is its share price performance since listing in 2020:
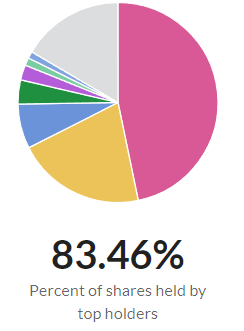
Very few shares are held by small shareholders:
Today’s full-year update for the financial year ending on October 1st 2023 is in line with expectations. Figures that follow are unaudited.
Key points:
Revenues slightly higher than expectations at £45.5m, up from last year primarily due to new site openings.
Like-for-like sales marginally up, excluding the benefit of reduced VAT in the prior year. If we include that benefit in the prior year, I expect that LFL sales would be lower.
Adjusted EBITDA £3.8m.
I tend to treat EBITDA as a nonsense figure for restaurants, as depreciation matters in this sector. However, Various Eateries does consider EBITDA to be important.
Indeed, the company provides two versions of adjusted EBITDA. Checking last year’s results, I see that it provided two different versions of it then, too.
That’s in addition to “actual” EBITDA. So all told, there are three different versions to understand!
Today’s update says that there was a Group EBITDA loss of £1.6m, before AIM costs of £0.6m. So I guess that means the actual EBITDA loss is £2.2m. That’s before we get into depreciation, etc.!
I tend to treat companies with an EBITDA loss very cautiously.
As an aside, I note that WH Ireland have reduced their revenue forecast for the current year (FY 2024) by 4%, despite today’s statement being “in line”.
Some reassuring comments on inflation:
Previously announced inflationary pressures persisted throughout the year but encouragingly some, including food and energy, are beginning to ease. Reducing operational costs and improving efficiency remain priorities, along with exploring technological solutions.
We also get a reminder that the company is not looking to maximise profits:
…a focus on the top line as opposed to short-term profit maximisation is fundamental to the success of any roll-out strategy. The Group has therefore continued to prioritise revenue and customer retention, deliberately not passing cost increases onto customers in full.
I’d be a bit more relaxed about this strategy if the company wasn’t in the restaurant business. If you offer customers a discounted deal now to get them in the door, fair enough - but then how can you have confidence that they will turn up when you want to charge them a full price in order to turn a profit? There aren’t any switching costs!
How long can the company survive without turning a profit? It says today that cash at bank is £1.9m. A year ago, it was £9.4m. Six months ago, it was £3.1m.
The company has loans from insiders including major shareholder Hugh Osmond and Executive Chairman Andy Bassadone. The interim balance sheet showed borrowings from related parties of £13m.
Graham’s view
I share Paul’s view that this stock should be given the thumbs down. I tend to dislike the restaurant/nightclub sector but this one strikes me as a dangerous investment even within this sector.
Reasons:
Unexciting like-for-like sales growth
Strategy of not passing on cost increases to customers properly - why will they turn up when the company does pass them on?
A dwindling cash balance.
Hopefully this one works out for everyone involved but significant dilution would be a good outcome for shareholders here, in my view.
(Paul adds - thanks Graham, a good review there, I agree with your scepticism. An embarrassing financial performance since listing (albeit in tough times), despite all its sites being new, with expensive fit-outs, I dread to think how this will perform once the sites are tatty, and needing refurbs. The tiny market cap, wobbly balance sheet, and only having 2 controlling shareholders, which Graham highlights, must surely mean that de-listing may be a considerable risk here?
There again, the sector might be about to turn upwards, given easing pressure on real incomes, with inflation declining. Could this be a time to buy in this sector, on a contrarian basis? The takeover bid for Restaurant (LON:RTN) might be pointing in that direction, who knows?! Is this another case (of many), where following star management with previous successes under their belts, doesn't work, or isn't worth paying a premium for?)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

101 comments
Restaurant (LON:RTN) Various Eateries (LON:VARE) .It is interesting comparing some US restaurant/fastfood companies' valuations and profitability with the few UK listed ones.
Chipotle Mexican Grill (NYQ:CMG) is particularly impressive and has had a particularly impressive run of late.Current market valuation of a mere $54.64 billion and on a 12 month forecast rolling p/e of almost 40 according to Stocko.
I think it was one of Bill Ackman's picks from a couple of years ago too when it was trading at around only $415 a share average.Where are our great UK listed eateries going wrong?The other side of the pond can clearly make the good old retail food industry work.Although admittedly J D Wetherspoon (LON:JDW) still does a good full english brekkie!
I bought Arix Bioscience (LON:ARIX) earlier this year a little above £1. I was building some exposure to busted out biotech in UK as I think its a capital cycle opportunity. I didn't think it a great vehicle or investor...but it was on a mighty discount at close to 50% and near 50% in cash with a significant portion of invested in public beaten down biotech equity and some writedown damage already in the private portfolio (no guarantee it wouldn't have some more but limited damage it could cause). So a bit of a dirty value play with leveraged exposure to future biotech aggressive beta (the cycle will turn).
Anyway, plenty grumbles about today's acquisition from RTW Biotech Opportunities (LON:RTW) ...whilst it would be nice to the cash up front and closer to NAV too...this was never going to happen in any acquisition in current environment...so that is wishful thinking and a sort of self flagellation regret.
Given my view above for why I bought Arix I actually like this transaction as I get real upgrade in terms of what the investment vehicle becomes...RTW are true class in the field relative to the rather 'opportunistic' Arix. The implied price of £1.43 for Arix is a nice reward for upgrading my biotech exposure too.
Obvs the market says meh today (lot of disgruntled retail throwing in the towel?). And given market conditions a fair amount of movement in values may happen before the deal is sealed.
Equals (LON:EQLS)
Looking at the size of the shareholdings of the two principals of the business their shareholdings, they appear to have under 2% in aggregate of issued share capital and perhaps a further circa 7/8% in 'in the money' option awards, and perhaps now that the business is both growing and cash generative they see a better opportunity for themselves by perhaps rolling some or all of their interests into a new vehicle. Private Equity certainly would certainly want to incentivise their management. The upside could be much greater than is currently on offer in a business which is not only growing quickly but now generating cash.
They may feel that they were in danger of being a sitting duck at the current market valuation for a take-out where their personal interests might not be best served, but would still be a nice pay day. However, they possibly might not want an overly full bid because they takes some future value off the table. If they did want to exit
Also, I am bit surprised there hasn't been more commentary about Argentex and comparing it to Equals which seemed to signal a bit of market softening.
Anyway it is certainly unusual to see strategic exercise which usually implies that they been out fishing for offers. Normally I associate such exercises where a Company has lost its way a bit, and is just paddling along which does not seem true of the Equals business.
Equals (LON:EQLS) looks an odd situation. A strategic review is often a negative and could imply some weakness in their approach / need for additional funding?
Contacting potential buyers is not normally a recipe for a high bid as it appears a bit desperate, particularly selectively naming the companies you have contacted in an RNS. Those companies are probably not too impressed! Time will tell.
I have rarely seen a company putting itself up for sale getting a really good offer. Best takeover offers get put forward by the 3rd party to a company not looking to be sold. Even better if a competing offer then comes in.
It will be interesting to see what arises. I don't hold, so good luck!
Agree re Equals (LON:EQLS)
In current environment its either in the hand of the gods in that Equals board believe they are the bomb and think they can rustle out a tempting offer (but if they are wrong they will severely harm their sp), or its a bit desperate as you say.
I'll confess I'm a payment company and fintech cynic (I operate a little in the latter on and off and have a lot of historic tho few years dated experience in the former). Payment biz + 'fintech' = grimtech often IMO. I note the great performance of some of these businesses but generally I wouldn't touch as I think their moats and barriers are poor and they are prone to rapid and surprising change being forced upon them (industry comp, big players moving goalposts, regs, etc). They are all trying to make a living under some behemoths and if these monsters become aware of a nuisance they can easily crush it. In addition, I might be wrong, but I don't think PE is generally that interested in the space as their is a long history of crap payment biz outcomes for PE (it was hot back in the late Noughties!...and has generally cooled since then) so I'd be a little concerned they are seeking these people out!
I met Equals a year plus ago and struggled to understand why they had a sustainable tech advantage or that they could grow and monetise some of their tech ideas. Growth and scale can be expensive and/or need a big brother to truly activate. Is there an end in sight for current Equals growth runway?
Not saying there can't be good grimtech/fintech businesses that are durable rather than hot rides. I just don't want to play. Obviously, recent share price performance of some of these businesses say I am wrong!
Mojo - I talk to a number of the PEs in this space and I can tell you they are definitely interested in being in the arena at the right price. At least one of them already is.
What that means for Equals (LON:EQLS) specifically I don’t know. But is run well and the product they have the banks aren’t really competing with. It’s a scratch.
I am probably specifically wrong re Equals (LON:EQLS) (I acknowledged a prejudice about general area!)
I stick stubbornly to believing that good later stage VC/PE is cautious (or should be!) on payment businesses. I think mickey mouse PE can be drawn in by seeming mix of growth and cash flow (both of which I think have tendency to hit wall surprisingly). That said mickey mouse PE is likely in increasingly poor health
Paul i saw in your comments on vertu that you had invested more in Plexus holdings which I did buy some time ago and have since sold. Any reason for your interest now in Plexus?
Hi knighty,
It would take some time to explain, but I've covered Plexus Holdings (LON:POS) (I hold) in my podcasts, when it was under our £10m lower limit here. As it's gone up a bit (very volatile) and is now over £10m, I'll cover it here next time it reports, FY 6/2023 figures are due out this month. They'll be poor, that's expected. It's FY 6/2024 when the excitement has started, as it won the largest ever (£8m) rental contract, which is all to be recognised as revenue this year, which should take it from losses to a small profit for FY 6/2024.
Also a licensing deal with Schlumberger (world's largest oil services group) was renewed for 6 years, and is due to launch a range of new products (using Plexus's IP) fairly soon. Royalties of 3-6% should then begin.
To research it yourself, I suggest reading the RNSs from the last year, there are only around 6 significant ones. Then check out the Cenkos notes available on Research Tree. That should give an idea of the potential.
On the downside, it's strapped for cash, but the management own 59% and don't want to dilute, so have personally propped it up with a convertible loan, another loan, and buying a long leasehold property from the company for cash.
Over to you, to DYOR! Obviously being higher risk, and loss-making since drilling dried up about 7 years ago, this one is not for widows and orphans. So it's a speculative idea, not a value share. But proven tech that has previously been profitable, and peaked at £300m market cap. The driver for adoption of its tech is recent discovery of wellhead methane leaks doing enormous environmental damage. Plexus is one of few companies that has a sealed-for-life solution, but the industry has ignored it, in favour of cheap, but poor quality Chinese wellheads. That's now changing, hence my interest in Plexus, now it's got a big potential tailwind to drive demand, and Schlumberger is looking after all the manufacturing & selling side of things, once they launch. Mgt says testing has gone very well, and we know the products work already.
Regards, Paul.
Thanks Paul for the info and for replying so quickly and I do come under the widows and orphans category so I will keep an eye on it maybe not over investing in it. Im really pleased that you have replied. Thank you, Regards John
I believe there is more news flow to come for Plexus Holdings (LON:POS)
A few days ago the UK granted 27 new licenses on projects https://www.reuters.com/busine...
They look like they should benefit with all the climate change talk on the Uk Governement websites and UN websites.
I also think that TechnipFMC is the large contract of 8million although I am also taking an interest in the OneSubsea JV which could have some of the Plexus technology. I can’t decide but overall looks a good space and watching these larger companies for news flow. https://www.businesswire.com/n...
Equals
Slightly bizarre RNS saying it is doing a strategic review and might be putting itself up for sale .
Scratching my head whether this is good news or bad news for shareholders.
I was a bit annoyed when Crestchic was sold as it was doing very well and it was one I was enjoying see grow .
Similarly equals which is now my largest holding.
Maybe management who are excellent by the way have a cunning plan, I certainly think hoisting a big for sale sign will generate sone significant interest .
Spivvy Betaville publish news on Equals (LON:EQLS) at 11:27am for a fee and like magic trading which was almost non existent picks up at exactly the same time.
How this is allowed is baffling. Insider information for cash.
Slightly bizarre RNS saying it is doing a strategic review and might be putting itself up for sale .
I could be wrong but my read is that the Equals (LON:EQLS) board has received a couple of illustrative offers from potential bidders and is tempted to bite, but wants to see a full process of price discovery. Hence letting the world and his wife know that they are at least listening to offers if anyone is so minded.
Equals
Yes think you are correct
I could not figure out why they would actually name potential buyers.
They must have cleared this in advance with the Intereted parties.
Can’t see any way they could name these potential buyers based on putting up the for sale “review”
Still quite bizarre .
2 quid a share strike price would do me .
Equals - Fleetcor Europe Limited and Madison Dearborn are an odd pair to have highlighted in the RNS. One is a USD16bn listed fintech, the other is a Chicago-based private equity firm. Both are valid potential bidders but it's unusual to see a trade rival up against a PE predator at this stage in the process.
That is unless Equals previously circulated an information memorandum actively seeking bids, and these are two fish that bit on the bait. The RNS does state that "the Company has contacted a limited number of potential counterparties"
Not necessarily planetx as they only said in the rns that they contacted a limited number of counterparts including those two. It doesn’t say how the approach was received or if any contact back so is nothing more than name dropping. If they had got as far as NDAs etc then they would certainly need to clear it.
It looks to me like Equals (LON:EQLS) are fishing. PE are definitely interested in this space and prepared to pay for good growth/management. If they can get 200p+ now that might be more appealing and more certain to large shareholders than waiting for value to out - particularly in this market. If not then no harm - they’ve baselined themselves against a private takeout and decided to use public markets.
I’d be surprised if they don’t get a bid now though. I think the only question will be how much and whether it is worthwhile and value for shareholders.
I just don’t see how they can make an approach and then simply name the companies approached .
I don’t think that would be allowed .
I could by extension send out an RNS saying we had invited Elon Musk / Tesla to buy my company .
If they had got as far as NDAs etc then they would certainly need to clear it.
If a prospectus and/or information memorandum has gone out from Equals, then it will normally have been preceded by an NDA, issued by their corporate finance advisors, for the potential bidder to sign in advance of receipt. Whether the would-be seller has made similar commitments to potential buyers will depend upon the progress of negotiations. Ultimately I’m not sure what to read into this because we could be anywhere between an advanced shoot-out between the named parties for ownership or a last desperate plea for external bids before these two walk away and the whole plan crumbles.
I agree there is no way of knowing given the information. Mgmt put out. Could be just a speculative approach to suss out the appetite in the market and gauge pricing.
Could have been an approach by a party and they’ve widened negotiations or none of the above.
Tricky - trading in line though and that had plenty of growth attached to forecast so who knows.
Reference the post by Michael C this morning on Sopheon (LON:SPE) Mr Mence is I believe the founding Director and holds 17% approx of the Company.
Rivomore or Rivermore according to Michael C hold 20% but are not shown in the Stockopedia list of Principal Shareholders.
In late March 2023 6 Directors added to their holdings.
Rivomore is listed in the Isle of Man.
I have a small position having first bought in Feb 2019.
I do endorse what Paul Scott says today that it is truly outrageous that takeover talks can go on for many months without any disclosure.
I have just re read my letter from The Takeover Panel dated 18th March 2021 .This followed Lord Lee's Zoom Meeting with the Director General and Deputy DG of the Panel.
After due consideration no changes were made. Now theres a surprise!!
Does anyone know whether ShareSoc has a policy to promote a change to regulation so that all share holders have to be informed about take over approaches? A simple RNS would do the job.
I am a member of Sharesoc and have asked them if they have a policy which supports an obligation being placed upon the directors of the company to issue an RNS when an offer is made to take over the company. This would include the terms of the offer and details of who is making the offer.
Just wondering how holders of Plexus Holdings (LON:POS) are reading the constant drop now in share price. Just no news or something else?
I have decided to become disciplined and not buy or sell anything else on AIM until at least one of my sad choices Zoo Digital (LON:ZOO) , Gaming Realms (LON:GMR) , or Plexus Holdings (LON:POS) at least breaks even.
On a positive note, I hold Warpaint London (LON:W7L) which is the one I have most conviction in and want to sell all of the above and buy more here. Also, some good luck this year with B.P. Marsh & Partners (LON:BPM) Time Finance (LON:TIME) and ME International (LON:MEGP) which I sold earlier for some gains - seems overshadowed now by these down times. Know this is the way it goes but still...
I haven't bought yet mainly because I was expecting the convertible to get sorted out after the share price rise. Then last week when they placed the Treasury shares it looked like positively paving the way for a placing and open offer etc The last contract announcement IMO was not really material.... so it's still quite a small co getting pushed around a bit in a weak market. I think it would really help to get a bit more cash on the balance sheet .... Do they need to invest in more wellheads? At some point I guess.....
Hi stockorocko,
Just wondering how holders of Plexus Holdings (LON:POS) are reading the constant drop now in share price. Just no news or something else?
I see Plexus Holdings (LON:POS) as being a tightly held, very volatile nanocap, which is extremely difficult to value at the moment - with a wide range of potential outcomes. Obviously I'm very bullish, hence why it's by far my largest personal portfolio holding, but I could be wrong in my reading of risk:reward.
The only thing we can practically guarantee, is that the share price is likely to remain highly volatile!
Regards, Paul (I hold).
Thank you Paul and you couldn't have been more clear re the risks and volatility. Re Plexus Holdings (LON:POS) I like the story of the non-leaking wellheads and that with the confidence shown by Schlumberger NV (NYQ:SLB) I thought it was a decent bet and hopefully will still be. I tell myself I have a long time horizon but then get frustrated watching the constant drop (I seem to often miss the volatility in the other direction). A small position so not about the money so much as thinking about my investment process and the implications of my approach for larger positions.
Thanks to all here for your comments, much appreciated!
Hi stockorocko
Given your comments in the 3 companies above being underwater I suspect you are making the mistake of being late to the party after the hot retail money has come in. What happens, particularly with these micro cap illiquid stocks, is that someone like Paul or another well followed commentator buys it and so people follow in. MMs rub their hands with glee because they know there is a following and they walk the price up and down, catching loose buyers and sellers alike whilst pocketing the spreads.
I try and avoid such stocks until I have seen it spike and retreat a good way. Then I look at the stock with a fresh lens and see if I want to buy the story. There are quite a few investors out there that get in first quickly driving the price. They also get out early with profits because they are really just arbitraging the strength of the commentators following vs the size of the company. Plexus Holdings (LON:POS) is a classic example. Was £5m cap when Paul started buying and around £9m when he had stopped. Management hold a high %age so not much free float. That plus a few bits of news spiked the price on lack of liquidity. Now you are seeing retracement of the spike. That doesn’t mean it won’t prove to be a good investment (it may do extremely well over time if Paul’s thesis proves correct) but it seems you bought late so end up carrying a much greater risk to capital than say Paul who may have a b/e at half the price.
Ps not having a go at you here Paul - just an example.
True, first check on a Monday shoot up is what has been "tipped" in the Broadsheets over the weekend, or IC during the week, think there is an example of that below!
Thank you for this and I believe you are correct. Good to recognise the pattern and as investors to think about your personality in these decisions- volatility may not be my thing although I don't mind it for the stocks I have most conviction in - something to think about before hitting the "buy" button.
It's sometimes also worth checking popular stock bulletin boards as if a popular one gets ahold of it or someone starts tweeting (xing?) about it, who other traders rate and follow, and it ends up on the top of their leaderboard for a day or 2, that can definitely lead to it being overbought temporarily.Usually it's oil and gas explorers and miners that dominate those websites but Plexus could have as it had a great velocity of movement.
Zoo Digital (LON:ZOO) A bit of a rollercoaster lately.I hold and bought after the first profit warning down to the 60p level.Very reactive obviously to the actor strike updates.'Apparently' they seem near a suitable conclusion for all involved.So after dropping again to around 30p , back up on the move towards 45p again.I decided to just hold too and not buy anymore.I'm bordering on vaguely positive as the ceo owns a fair whack and has bought some more recently post profit warning; and a director (chairman) bought a decent amount recently.I also believe the immediate threat of AI to the industry is overstated like renewables to oil and gas.
Equals (LON:EQLS) I hold
Just out
"The Board of Equals Group plc ("Equals" or the "Company") (AIM: EQLS) notes the recent market speculation, and confirms that it is conducting a review of the Company's strategic options (the "Strategic Review"). As part of this process, the Company has contacted a limited number of potential counterparties including Fleetcor Europe Limited and Madison Dearborn Partners, LLC to assess whether such parties could put forward a proposal that would deliver greater value to Equals' shareholders than pursuing a standalone independent strategy. Any such proposal could include an offer for the entire issued and to be issued share capital of the Company."
Equals (LON:EQLS) it is interesting that a number of good companies are effectively putting themselves up for sale frustrated by the lack of market recognition. They see that other private entities who have a much longer view and less prone to histrionics than investors are prepared to pay significantly more, understanding the true long term value on offer.
Whether this translates to an offer I don’t know and I really hope not in Equals (LON:EQLS) case (or at least not below 185p and ideally 200p+) but I suspect much more of this is going on under the surface. The only reason they released it was that something obviously leaked which won’t happen in every case so you’d imagine that for every 1 there are several others doing exactly the same.
Equals (LON:EQLS) just saw this and I must say I am surprised. It is one of my largest holdings and I was happily awaiting the continuation of its price graph's journey to the top right of the page. I suspect it would be dwarfed by either of the two named potential suitors. To me it is a shame because having invested diligently in the technical platform I felt they would be able to support a lot of growth without undue operational risk.
I suspect it will go ahead as the market cap is (to a large operator) trivial and will afford the acquirer access to a huge market with sleepy behemoth incumbents. I just hope it doesn't go for an equally trivial premium.
Oxford Metrics (LON:OMG) has splashed £8m from its reserves on the acquisition of a business in a related area. For all that the shares look cheap, I’d be pretty worried whether a new and unproven CEO, with little experience outside Vicon, can handle a group of companies which could soon comprise 5 or 6 subsidiaries if the reserves are applied to several acquisitions of this scale. I think that many who are attracted by the valuation need to give better consideration to the risks.
I would also point out that the valuation isn’t that attractive, relatively speaking. There are loads of better quality businesses with stronger moats on a p/e around 10x
I thought Oxford Metrics (LON:OMG) looked OK. Progressive have upped adj. PBT and EPS forecasts for this year by 10% + 9%
Cash forecast £60m . Market cap £116 So just over 10x ex cash I think? Trading update a week ago was positive. Im as tight as they come but this looks decent value to me.
So just over 10x ex cash I think? Trading update a week ago was positive. Im as tight as they come but this looks decent value to me.
Along with all the better-proven growing businesses on a similar rating. There are plenty to choose from. Why take the risk that OMG screw up an acquisition or two, which is pretty likely IMO
Oxford Metrics (LON:OMG) I think your negativity is unjustified here. They have an excellent track record of adding value to acquisitions - two exits in the last eight years, the most recent at an absolutely stunning premium to market value. I am not aware of any previous acquisitions they’ve made that have been value destructive. So, despite the change in CEO, I would say that the odds are that this acquisition is at least part of what shareholders have been waiting for - value accretive deployment of their massive cash balance. Given the size of that balance, risk/reward looks very good to me.
Obviously, I hold.
On Beach group (LON:OTB) putting Ryanair to shame. Hope this gets wider coverage:
Successful Application for Summary Judgment in Ryanair Refunds Case
On the Beach Group plc (LSE: OTB.L) today provides an update that the High Court of Justice found in its favour in its application for summary judgment against Ryanair for refunds paid to customers by On the Beach following flights which were cancelled or subject to a major change during the pandemic. The case was launched in October 2021.
The Court found that Ryanair had no real prospect of successfully defending the claims that it was obliged to refund the monies to On the Beach (i) under Regulation 29 (Right of Redress) of the Package Travel and Linked Travel Arrangements Regulations 2018; and (ii) under the law of unjust enrichment. As such, On the Beach has been awarded the sum of cGBP2m and will also be seeking its costs of the proceedings.
Since the commencement of this claim, On the Beach has continued to provide its customers with cash refunds in circumstances where Ryanair has not yet provided a refund and will be taking steps to recover these sums.
Shaun Morton, Chief Executive of On the Beach, commented:
"We welcome the High Court's decision to uphold our application for Ryanair to pay back what was owed. Today's outcome sends an important message on how refunds should be handled and emphasises the industry's responsibility to holidaymakers. On The Beach is committed to doing the right thing for its customers and provided full cash refunds for flights that were cancelled or subject to major changes during the pandemic whether or not airlines had complied with their obligations.
"We continue to call on the CMA to review the anti-competitive behaviour by certain low-cost airlines, protecting consumer choice with fair access to flights and a code of conduct for airlines and travel agents. It has taken a protracted and expensive legal process to reach today's outcome which could and should have been avoided. We urge the Department for Business and Trade to consider this in its current consultation on the Package Travel Regulations."
Delighted. I hate Ryanair and after they did me over many years ago on a flight out of Prestwick, I swore we would never fly Ryanair again and we haven't ("we" as in wife and family!). At least On Beach group (LON:OTB) seem to know how to behave.
Ryanair/O’Leary are an affront to the term “customer service”.
Do think O'Leary and Dominic Cummings are related? They have a very similar style.
ASOS (LON:ASC) Just some side-notes from me about this company that some may not be aware of. It's not a share I've ever owned, so I have been looking on with envy as others have made fortunes out of this company. Not so much lately, obviously. I generally don't copy what all the very prominent investors (and there are many really top-notch ones here) on this site do. I know it's a recipe for me to lose money. I know that it is impossible for me to copycat Paul. Paul has his way of doing things, and is very successful, but it's not a style that I can particularly wrap my head around, so it's best if I don't try to emulate him.
But back to Asos. Nick Beighton was CEO of ASOS until Oct 2021, when he resigned. He had grown the company from a £220m turnover to over £3b. According to Yahoo Finance, insiders hold 36% of this company. I assume that it mostly due to Beighton. This doesn't bode well.
Nick Sleep is a legendary investor who took a position in ASC some time ago, by which I mean at least over a year ago, rather than recently. I'm having trouble finding his purchase date, though. Sleep has a highly-concentrated portfolio. He owned a stake in Amazon for a long time, a hugely successful investment for him. Apparently he had 40% of his firm's assets invested in Amazon at one point. So I'm not kidding when I say "highly-concentrated." I think he sold Amazon to take a position in ASC. I think that he hasn't fully divested from Amazon, but I'm not sure.
His investment in ASC followed the same logic as AMZN. According to https://gilescapital.substack.... "ASOS may follow what Nick Sleep calls a 'Scale Economics Shared’ model. He says on his theory: “Scale
Economics Shared operations are quite different. As the firm grows in
size, scale savings are given back to the customer in the form of lower
prices. The customer then reciprocates by purchasing more goods., which
provides greater scale for the retailer who passes on the new savings as
well. "
A nice theory which clearly didn't work in this case. The takeaway from this is that devil is in the details. Not to mention that I like the idea of a company earning decent margins, rather than selling stuff whilst making little profits.
I think the US in particular has fallen into this way of thinking off of the back of Amazon. Don't worry about profits, just scale the business - magic happens here - profit.
Sleep once opined about the firms he invested in: "cultures are focused on the customer experience, not on the competition or the profit and loss statement. Our firms tend to chase the vision, not the money."
Hmmm, if you say so.So that's you're lot for today from me, Oh look, the markets are up for a change.
Mark, wasnt Nick Sleep involved with Nomad Investment Partnership? Then setup I.G.Y
Nomad had holdings in Asos, Ocado and Games Workshop.
Asos disclosed holding was Feb 2014 which at the time was about £70. He still had a holding with in 2023 and took part in the placing with I.G.Y
Quite a ride.
I know the sentiment is very doom and gloom at the moment... but how to reconcile this metric:
FTSE250 forward 12m EPS growth is projected at 11.8% on the homepage of Stocko.
Is this a sign that actually, UK corporates are in better health than all the news and share prices suggest?
Is this a sign that brokers haven't adjusted their forecasts yet, and we'll see a rash of profit warnings and downgrades in the months to come?
Would love to hear some thoughts! Personally, the Boon Fund is inching more towards 0% cash, and getting fully invested, mainly in small and mid-caps...
Yes I'm staying fully invested too as lots of bargains and happy to sit through any short-term volatility.
I do think it's also worth having a bit in bonds as they look really cheap and should act as a nice hedge if we have an equity market sell-off. I personally like the 20y+ US Treasury ETF as this effectively gives you geared exposure to any future fall in interest rates (very volatile so wouldn't have a huge position),
One interesting fact I learnt the other day is that the fall in the long dated treasury ETF over the past couple of years has exceeded the fall in the S&P 500 during the financial crisis - so the recovery potential on these could be significant and you're getting a 5% yield while you wait.
Was just looking at the exact same ETF Bouden
Theres lots of potential problems around but I think if you'd asked people in 2021 would you be interested in decent companies at below 10 or 12x multiples they'd have bitten your hand off.
The flip side of doom and gloom is when sentiment changes this can happen. AIM 12 month returns from the day market bottomed in 2003 and 2009.
I think most years the analysts are forecasting about 10% growth in most things.... no strong view of what overall growth maybe in 2024, an average of some decent positive numbers and also the reverse .... but clearly nominal growth is positive for those sectors managing to pass price through and retain volume. Most years however, the starting multiple is not 10x..... this isn't a buy signal but Im a lot happier sinking money in at these levels. Wouldn't be surprised if we start the year a little weak though.....
I did stumble over a Russel Napier report arguing that with the next election the UK will move into a more moderate and stable political environment. Contrary to intuition a labour govt might be positive esp. compared to EU where the politics may heat up next year. So historically cheap... yet over long time horizons the ROE in the UK matches other markets...not really something to hang your hat on but leaves room for hope that the UK can decouple positively at some point.....
Sopheon (LON:SPE)
'Irrevocable support has been received from two large “key” shareholders, holding 37.3% (Barry Mence, and Rivermore).'
Does this mean those shareholders were made insiders and told about this before other shareholders?
Is that how this sort of thing works?
I'm trying to persuade my wife that we should look again at investing in individual shares. My 6 figure SIPP which was used for that purpose is currently 100% in cash due to a series of burned fingers none of which was my fault - I wrote about our Wincanton experience here, nobody could have seen that profit warning coming . But when I see things like this going on I lose the will to be persuasive.
EDIT: Paul's post at 08:00 which I hadn't read before I posted explains where I have been going wrong. 'All of which reassures me that we don't have to live in terror of profit warnings. In a diversified portfolio of decent value/GARP shares, the odd profit warning is to be expected, and shouldn't derail the portfolio overall, as the winners should offset.' I haven't been any good at constructing a portfolio so I've had a disproprtionate number of losers.
I don't think you should worry about this ... you can't get an irrevocable without taking shareholders over the wall. Normally this is a phone call the day before and request to sign an agreement ... they are then inside and can't do anything until it's announced. Sometimes, very occasionally, this backfires and they end up being kept inside longer which is obviously restrictive for them.
Next (LON:NXT) doing well, I see. Look at the lovely margins of the business. I sold out some time ago. I can't find it in my records, it would have been over 5 years ago. One thing I've being realising over the last few months is that I really need to take a longer term of my holdings. I have been rotating holdings based on the Stocko screens but I really need to think longer term. So many good companies have slipped through my fingers. 4imprint (LON:FOUR), London Stock Exchange (LON:LSEG) , JD.Com (NSQ:JD), Greggs (LON:GRG) are companies that readily spring to mind; companies which I've held at some stage but decided to sell. Patience. I need more patience. There are so many quality stocks at reasonable prices to buy right now.
Just off the top of my head, for example, some large-cap FT100 companies earning decent returns: Next (LON:NXT) , RS (LON:RS1) . IMI (LON:IMI) , Burberry (LON:BRBY) , Experian (LON:EXPN) , Diageo (LON:DGE) , BAE Systems (LON:BA.) , Bunzl (LON:BNZL) , Unilever (LON:ULVR), Diploma (LON:DPLM) . I could probably find some other good ones if I tried. I own shares in the last 4 companies, FWIW. The chances of earning a decent return from a portfolio of these companies is good. They're not even obscure companies.
Next (LON:NXT) You think that you got it wrong.
I bought Next (LON:NXT) for 17p back in 1987. It was, I think my first share purchase and I remember going to the TSB (Trustee Savings Bank) to buy 500 shares; £85 was a lot of money to a young man back then.
It looked as if Next (LON:NXT) was going to the wall, but it sold its catalogue business, Grattan, which saved the company. The share price duly went up and clever clogs me sold at 51p, tripling my investment...doh!!.
If I had put the share certificate in a drawer and forgotten about it, at today's price it would be a 4000+ bagger.
I suspect many have a similar tale to tell.
Ah, the 80's. I was a trainee accountant at a small firm at the time. That was around the time that Tie Rack floated. It turned out that selling ties isn't such a great business. There was also Filofax, which caught the yuppie trend nicely. That was a nice fat-margin business. Unfortunately, success went to its head, and bought some trainee businesses (something like that, anyway), which turned out to be a dumb idea. A lot of companies cottoned onto the filofax craze, with banks giving out cheaper versions as gifts, if I recall.
I think there were two Next shops in the Southend high street at the time, a clear case of oversaturation. Patrick, another trainee, was into Next in a big way. He was a definite wannabe yuppie. I thought their clothes were expensive. A few years later I realised that the quality was a lot better, though. I had two shirts, one from Next, and one from Tesco. The one from Next was really good quality material. The one from Tesco was rather threadbare.
Next quality has definitely declined since those days. Maybe they should introduce a Next Finest brand.
Don't forget Sock Shop!
Ah yes, Sock Shop. And Body Shop, but that actually turned out to be a good investment.
love it Mark halcyon days through in the human league, minder, frank bruno and ford capri's.
Those days definitely were harder and grittier than now but equally life in a strange way was much simpler.
I can remember going out late teens when I started work on xmas eve and even the rough pubs were eight deep at the bar, daytime drinking and then all off to the local nightclub for the 2pm start to dance the night away.
I do say to my lads you don't know your born with tinder etc in my day you had to go up to a girl in a night club and be prepared to be told to ---- off to your face great times.
Next was a premium product in the 80s. I remember their early hardback Directory books, with fabric swatches and tissue paper. Very poncey! Next is run of the mill nowadays. For many years, Reiss became a natural successor of the Next of yesteryear but even that is declining in quality now.
MS International (LON:MSI) news on internet intends..
Explanation:
The International Guns, Missiles and Rockets Project Team, part of the UK Ministry of Defence (MOD) intends to award a 5-year contract to MSI Defence Systems Ltd (MSI-DSL) for Contracting for Availability (CfA) services for the 30mm Gun System across the Naval fleet from June 2024.
MS International (LON:MSI) Intention to award.....
The good news here is that the MoD support contract for the - existing - fleet of 30mm systems has been in contention for the last couple of years, with MSI providing support on a year by year basis. It's good to see this move to a non-competitive 5 year frame contract again.
Interesting that this confirmation comes so soon after the US contracts? The UK should have procured new systems from MSI before now but is very short of funds (like all our departments) It's hard to over-estimate the impact that US decisions have on our own defence spending. I'd hope to see the MoD buying some new systems before too long.
cheers
Mark
Hi Mark,
I remember you wrote what i thought to be a very good comment on MS International (LON:MSI) not that long ago, I would like to revisit that but cannot for the life of me find it. Would you point me in the right direction please.
Thank you.
Might be the comments in this https://www.stockopedia.com/co...
https://www.stockopedia.com/co...
Found it :-))
I hadn't scrolled down far enough , doh !!
Foresight Solar Fund (LON:FSFL)
Extracts from a new Edison research note on Foresight Solar Fund
"The board announced on 14 September 2023 that it was doubling its share buyback programme to £20m, believing that investing cash into FSFL, especially while it is trading at a 26% discount to NAV, is a highly competitive use of cash."
"FSFL has a progressive dividend policy and has increased its dividend over 25% from 6p/share (in 2014) to its target dividend for FY23 of 7.55p/share. Since IPO, FSFL has met every dividend target and it has forecast that the minimum dividend cash cover until at least 2025 will be 1.5x. The fund’s current dividend yield is 8.6%."
https://www.edisongroup.com/re...
MS International (LON:MSI) awarded another MOD contract for £50 million over 5 years from June 2024 for repair and maintenance of their own weapons and weapon systems. That's more than 10% of 2023 revenue . I would not have a clue about the margin on that though, anyone any ideas?
https://www.theconstructionind...
Interesting Hellvellyn - hasn’t been announced by MS International (LON:MSI) by looks of things?
Material I’d say - think we thought margins 20% so could add another £2m of annual profits.
I'm wondering if the frequent acquisitions at Vertu Motors (LON:VTU) is a form of protection against themselves being bid for - indeed, perhaps it might explain why VTU has apparently never received any bid interest (presumably bidders wouldn't want the additional complexity of integrating multiple recent acquisitions).
That's the way to do it!
Hi Bouden54,
I'm not sure that VTU would be trying to muddy the waters with acquisitions, they all seem well thought-through from what the company tells us - filling in geographic gaps, strengthening relationships with specific brands, etc.
I recall VTU's CEO saying in a webinar a while ago that sector consolidation was going to happen, and VTU saw things as acquire, or be acquired. I suppose that could be interpreted in different ways, so not entirely clear what his angle on it was.
Regards, Paul.
Vertu Motors (LON:VTU) I hold
In addition to the announcement of an acquisition, VTU also issued an RNS saying:
"Vertu Motors plc notes that its Companies House records have been falsely amended by a malicious actor, such that the public record maintained by Companies House currently states that 1) several of the Company's directors have resigned, and 2) two new directors have been appointed."
They go on to make clear that this is false and that they are liaising with Companies House as to how anyone could be able to do this.
There was news earlier this week on a radio program about scammers setting up companies with a registered address belonging to someone who is not connected to the company. In one example, a lady in a flat in London was on the receiving end of demands for tax from HMRC and lots of irate customers wanting their money back for goods they had ordered. She said that when she asked Companies House to remove the bogus records, she was told it was a legal process and that she would have to provide proof that she lived there and had nothing to do with the bogus company which might take months.
What a shocking state of affairs.
Great spot, thanks rwh3ue,
I glanced at that extra RNS from Vertu Motors (LON:VTU) re Companies House, but then instantly forgot to read it. A bit like going into a room in my apartment, only to wonder why I went in there. And spending hours looking for my glasses, which are on my head ;-)
Very handy to have you here to brief us on it, an interesting snippet, thanks!
Regards, Paul.
Vertu Motors (LON:VTU) I wanted to see if others had any differing opinions on Vertu than my own, in case i'm missing something about the attractiveness of the business.
From the way i see Vertu, whilst there may be an element of undervaluation to the business, i see the relative low PE and discount to NTAV as reflective of what is at its heart a sub par business.
In my view its a business which requires a large amount of invested capital, but doesn't get an adequate return on that investment. For example fixed assets and debt have increased by roughly £200 million over the past 5 years, but profit, return on equity and return on capital employed have remained static with little sign of return on that investment. overall it seems to suggest the business requires a large amount of capital to grow and delivers poor returns on those investments. Underlying that would suggest management is poor at allocating capital on behalf of shareholders, which is a bad sign for a business which is built on acquisitive growth.
In addition to that whilst the business has a large asset base, this increases the amount of yearly capex required each year to maintain their competetive positioning. And large amounts of debt used in its acquisitive business model increase interest fees, which together reduces the amount of free cash flow which can be produced and returned to shareholders.
So outside of the fact it may be a takeover target, why is it a good business to own?
Feeding off of Paul's points as well, i would think there would be material changes to the profit, assets and cash flow of the business over the next 5-10 years as the franchise car industry moved to the agency model. It's likely revenue will drop substantially as franchise car dealers are paid a commission on cars sold as opposed to cost of the vehicle (commission rate is being touted around 5% of car value, which would result in a 95% reduction in revenue on new car sales for Vertu.
In addition for a business which gets most of its profits from after market services such as repairs, the move towards EV's would be a worrying trend for that business as those cars with much fewer moving parts require significantly less maintenance and repairs that I.C.E vehicles, which would no doubt impact the profitability of that business greatly.
I'm really keen to hear alternative views, as its an industry im really interested in.
I must admit that I have added to my Vertu Motors (LON:VTU) holding today in the belief that its directors are doing the right thing.
I'm no expert on the sector, but if it was the case that the move to an agency model was going to kill future profits, then we surely wouldn't be seeing all these bids for the listed dealers. The acquirers must surely know the sector better than anyone else, and recent bids suggest they think it will remain highly profitable for many years.
Who on earth is buying Heiq (LON:HEIQ) - up 18% today to 15.0p, and why?
I was going to describe its InvestorMeetCompany ("IMC") webinar yesterday as a car crash. Thankfully not literally, as for the first time, we were treated to a CEO presenting a webinar via his mobile, inside a moving vehicle (the engine noise and clicking indicators gave that away!)
They didn't give a convincing reason for why customer demand has declined, and large losses incurred in 2022 and H1 2023, nor why it took them so long to produce 2022 results, leading to shares being suspended for about 5 months this year.
To be fair though, they were pretty up-front about the precarious financial position, with the slide on cash/debt being revealing - all the cash has come from drawing down bank borrowings, which are not actually committed facilities at the moment.
To me it all smelt of weak management, who don't seem to have been in control of anything really. In the past they've made lavish claims about the company's potential, but have dismally failed to execute. Instead the 2020 profits look like a one-off.
Looks very wobbly to me, poor risk:reward at this stage. Let's hope they're able to turn it around, as the last thing we need is another insolvency. It's fully listed, not on AIM, by the way.
Regards, Paul.
Maybe it'll set a new trend. Presentations from a hot tub or a jail cell or the mistresses bedroom.
I watched one where the CFO from Made Tech (LON:MTEC) was in her kitchen, dressed in what looked like pyjamas, while the dog scratched at the glass door trying to get in. Was funny and looked more like someone who sells jewellery part time on ebay rather than large government contracts, but surely they can go up a level.
HEIQ. If a CEO is presenting an investor meet on his mobile while driving, oh boy how many red flags here! Cant be bothered with private investors ? Cannot organise his own time for a important meeting? Something important came up that required urgent attention?
No position thankfully !
A lot of buying in Kromek (LON:KMK) which might be interesting. Had been drifting badly for a long while but suddenly attracting strong interest. Yes the $5m contracts are beneficial but they are not earth shattering. Wonder what is going on there - just illiquidity in reverse or something more?
Kromek (LON:KMK) Endorsed this morning by Simon Thompson in Investors Chronicle
Two largish contracts announced in a week may be having some impact - for me the key will be (finally) making a profit.
If Kromek (LON:KMK) ever finally hit profit and more importantly cash flow profitability (after capex) they will be worth a lot more - in my view several times more.
The problem is despite all the technology progress financial metrics are glacially slow to come through.
Re Sopheon (LON:SPE)
As I understand from Stockopedia the PE is 57 x the profit per share, so bid represents jam on top of jam!
Hi Aislabie :
Reminds me of being executor to my Mothers estate - amongst 20 or so shares [mainly £10 - 30k in value] the valuation showed a UK Gilt at £1,500,000 i.e. £1.5 million. Strange - I thought - but maybe she wanted to be overwieight on the least risky asset ? It took me a week to realise that the broker (un named) had quoted the gilts in pounds - but they are always priced in pence - so that holding was in fact worth £15k. No excuse as there had not been any corpotate action as there had been in your example. Had we put the estate into the hands of solicitors or others, they may have taken the statement at face value and asked us to stump up a [futher] £600k inheritance tax ! As you allude to, it is always good to keep an eye on any financial statement that you receive - whether better or worse than expected.
All the best
Geoff
Arix Bioscience (LON:ARIX) Not a great deal for ordinary shareholders. Acacia get £1.43 cash , us ordinary shareholders some shares in RTW Biotech worth £1.43 at moment. Given the cash ARIX had RTW Biotech have effectively done a nice (for them) funding/rights issue. If that is the best the strategic review could come up then I am amazed. They could have just sold the portfolio- and then return that plus the existing cash pile to shareholders. In my opinion they have not acted in the best interest of Arix shareholders.
I don’t own but had been looking at Arix Bioscience (LON:ARIX) as it struck me that cash plus listed investments equalled the share price and the private portfolio was in for free.
It would have been better for shareholders if they had realised and distributed those assets as capital and then done a deal around the private portfolio. Doesn’t feel like a good result
davidjhill Shareholders have been ignored to be frank(I could be blunter). I have emailed them to state this, but cannot see any change unless another company makes a move - which is unlikely.
I have great news for those of you who enjoy all the fabulous speakers at our Mello conferences and that includes Ed Croft, Paul Scott and Graham Neary this month....We have learned that the renowned fund manager and activist investor Christopher Mills has accepted our invitation to speak in the main theatre on Thursday 30th November. Andy Brough and Richard Crow are on stage that day too.
MelloLondon is our second in-person event of the year and will take place on Wednesday 29th and Thursday 30th November 2023 at the Clayton Hotel and Conference Centre in Chiswick, West London.
You can expect the usual mix of fantastic Keynote Speakers, 50 quality growth companies, Investment Trusts & Funds, Fund Managers, panel sessions and much more! To find out more information, click here: https://melloevents.com/mltickets/
There is a very informative thread and full details here https://www.stockopedia.com/co...
re Geiger Counter (LON:GCL) a deluge of positive info at the moment from Cameco (NYQ:CCJ) NAK Kazatomprom AO (LON:KAP) Yellow Cake (LON:YCA) to read/listen re background on Uranium, and prospects for the industry. Something of a sweet spot developing. Nexgen Energy (TSE:NXE) is the largest holding of Geiger Counter (LON:GCL) at 20% .... Cameco (NYQ:CCJ) was 12% at last fact sheet (30 September) and rose 8% yesterday on positive numbers. Both Geiger Counter (LON:GCL) and Yellow Cake (LON:YCA) trade at discounts to NAV.
Geiger Counter (LON:GCL) is one of my largest holdings, followed by Yellow Cake (LON:YCA) and I also own Cameco (NYQ:CCJ) and Centrus Energy (ASQ:LEU) . I cannot recall a time in the past three years when the discount on GCL was this large. They have been buying shares back in the market to try and close the discount with little impact so far. I suspect U3O8 will need to move above USD80 /llb before the UK market wakes up to the opportunity here. Sometimes I think just sell GCL and YCA and buy the equivalent Sprott products. What are your views Mr Howarth?
Vertu Motors (LON:VTU) another acquisition for Vertu (one of my main holdings) - "acquisition to be EPS accretive in first full year of ownership............funded by existing cash resources".
I know there's been talk here recently that the new and used car markets appear to be coming off their peak, but my personal experience of buying a small runaround 5 years ago for £5k, and selling it this week for £5.5k, suggests that there is still a lot of life in this sector.
Weir (LON:WEIR) I mention as stock has opened a little weak... not much to worry about but order flow has softened. In Q1 23 order flow was v. positive so I have been keeping an eye on John Wood (LON:WG.) Rotork (LON:ROR) etc Weir (LON:WEIR) has been derated of late...and trades on 14x which would be fine with a positive outlook. There is a capital markets day in December and I suspect this will focus on medium term margins.... I also observe that Caterpillar (NYQ:CAT) traded down on its results yesterday, and has totally broken down in trend.... which does create a bit of a short term headwind for the sector. There was a mini boom following Ukraine and obviously this means comparatives will be tough short term although longer term I still feel positive about the sector and theme. I don't own any of these stocks yet.... feels like the story could pick up again H2 2024.
I had wondered how well Stocko would handle the 100 to 1 consolidation of shares in Crimson Tide (LON:TIDE) (I hold). Well the answer is in , they got tripped up. But for the briefest of moments there was the pleasure of seeing my entire portfolio had risen by 103%. The moment passed but it was a fine dream.
The drip drip of takeover approaches and agreed offers is now a steady trickle week by week.
Often it will only get holders towards free value at best, but I guess it allows you to recycle proceeds into other opportunities.
Morning The Jayman.
Yes indeed, I've never seen anything like this, in my 25+ years in the market. A deeply depressed small (and mid) caps UK market, yet at the same time a takeover bid frenzy is going on, often at decent premiums, not just opportunistic offers. These are complete opposites, so to see this combination of bombed out valuations, and takeover bids galore, is not sustainable. Either the bids will stop, or the market as a whole will re-rate upwards. The latter seems only a matter of time, once FOMO* starts to trouble people holding cash on the sidelines.
That of course is tempered by worries about being caught on profit warnings.
As my 2023 watchlists show, you can get hit with multiple profit warnings, and still substantially out-perform the market, thanks to multiple takeover bids, and some strong performers. My main list is now 20% ahead of AIM YTD, and the "Runners Up" tab is 26% ahead of AIM YTD.
(the third tab, for speculative ideas, which I didn't publish, has done worse, but is still ahead of AIM, despite some absolute howlers. Again the takeover bids offset the losses).
All of which reassures me that we don't have to live in terror of profit warnings. In a diversified portfolio of decent value/GARP shares, the odd profit warning is to be expected, and shouldn't derail the portfolio overall, as the winners should offset.
Regards, Paul.
* Fear Of Missing Out.
Is there a decent ETF anyone would recommend in the UK small to mid cap space?
Oryx International Growth Fund (LON:OIG) : Not an ETF but good past performance and currently trading on a big discount to NAV. I hold.
See my comments on Vertu Motors (LON:VTU) - I'm hopeful this could be another. I hold, and it's already done well for me. Fingers crossed.
My morning smallcap tweet: Your gas mask for noxious nonsense
ASOS (LON:ASC) OptiBiotix Health (LON:OPTI) SysGroup (LON:SYS) Creo Medical (LON:CREO) Next (LON:NXT) Hercules Site Services (LON:HERC) Cellular Goods (LON:CBX) Gulf Marine Services (LON:GMS), Vianet (LON:VNET), Various Eateries (LON:VARE), Eckoh (LON:ECK)
◄ASOS (ASC)► FY-Sep. in line with rev down 10% and pretax -£296.7m (-£31.9m). guides FY24 rev down 5 to 15%, adj EBITDA positive, positive cash generation. Will hike marketing by £30m and "prioritise a shift 'Back to Fashion', leveraging ASOS' strengths to offer the best and most relevant product, styled the ASOS way, with an exciting and seamless customer experience geared around fashion and excitement." Its stylists better be an improve on its PR stylist. [SP=392.18 Cap=468m]
◄OptiBiotix Health (OPTI)► commercial update - lots of positivity but Show Me The Money. [SP=32.5 Cap=30m]
◄SysGroup (SYS)► guides H1-Sep rev down 3% and adj EBITDA £1.56m down 7%, Saw "growth in high value Managed IT services revenue...offset by lower Value-Added Resale sales". Co will be "leveraging our existing capabilities". Vacuous. [SP=43.5 Cap=21m]
◄Creo Medical (CREO)► FDA clears Speedboat UltraSlim improved endoscope device for sale in US. [SP=32.38 Cap=117m]
◄Next (NXT)► the bellweather's Q3 full price sales up 4%, 2% better than guided. Hikes FY pretax guidance by £10m (1%). [SP=6896 Cap=8795m]
◄Hercules Site Services (HERC)► hikes invoice discounting debt facility by £4m to £15m. [SP=25.88 Cap=16m]
◄Cellular Goods (CBX)► products now available in France and Germany. [SP=0.54 Cap=3m]
◄Gulf Marine Services (GMS)► wins two contract extensions for four years in total and one new contract for two years. "Improved day rates" but no $$$. [SP=11 Cap=112m]. I hold.
In line: VNET, VARE, ECK
Thanks MrContrarian - your daily summaries always valued and offer some light relief.
Amazed how quickly you manage to produce this too.
Loved yesterday's comment about the new overpriced Nike Ultrafly "the pinnacle trail racing shoe. A snip at £230. They'll certainly see you coming". Funniest and truest observation of my day yesterday.
Agreed, and personally i liked the “Losing the will to spiv” comment from a few days ago !!!!