Small Cap Value Report (Wed 10 Jan 2024) - JUP, MRK, BLV/TPFG, GRG, SDG, COST, SOS, AMS, NICL, CSFS, HSW

Good morning from Paul & Graham!
Today's mammoth report is now finished!
I've finally finished my long form article with my top 20 2024 share ideas, here's the link. It's the same shares as I put on my 2024 spreadsheet, originally linked to in the SCVR for 2/1/2024, so nothing's changed, I've just gone into a bit more detail about my selection process, and I reviewed each share in more detail to make sure I'm still happy with them. It's quite surprising how, only a week into the new year, we've already had some significant movers both up and down.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Live prices tracking spreadsheet for Paul & Graham's 2024 share ideas (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs) - search on any podcast provider for "Paul Scott small caps", or web link here.
Summaries
Jupiter Fund Management (LON:JUP) - down 16% to 74.7p (£407m) - Fund manager leaves, trading update (profit warning) - Graham - BLACK (PW), GREEN on fundamentals
A double blow for Jupiter shareholders as a “star” fund manager departs to set up on his own, although his replacements are already waiting in the wings. These shares are extraordinarily depressed; the market is pricing in disaster but I still see value to be had.
Marks Electrical (LON:MRK) down 28% to 66p (at 08:06) £69m - Trading Update (profit warning) - Paul - BLACK (PW), AMBER/RED on fundamentals
A nasty profit warning, caused by already low margins going even lower, due to consumers being very price-conscious, and selling third-party electrical brands has zero pricing power. Forecast EPS almost halved to just 2.59p, and who knows if/when margins might improve? Still looks significantly over-valued to me.
Belvoir (LON:BLV) - up 4% to 266.65p (£99m - Recommended All-Share Merger With TPFG - Graham - GREEN
Big news for estate agents as the two major listed franchisors announce that they wish to merge in an all-share deal (i.e. no cash is being paid, only a share swap). I was already a fan of both companies and believe that this is an excellent development for both of them.
Nichols (LON:NICL) - up 5% to £11.84p (£432m) - FY23 Trading Update - Graham - GREEN
There is a “slight” beat of profit forecasts here for 2023, as closing down unprofitable accounts in the Out-of-Home segment has led to benefits earlier than anticipated. A new member of the Nichols family joins the Board, and my positive stance is unchanged.
Cornerstone FS (LON:CSFS) (I no longer hold) - up 17% to 31p (£18m) - Trading Update - Paul - AMBER/GREEN
A modest beat against FY 12/2023 forecasts, which had already been raised considerably. Transformation year, moving from losses into a decent profit of £0.8m adj PBT. I've moderated my view from green to AMBER/GREEN simply because the share price has 5-bagged since May 2023, and the valuation now looks up with events I think. That said, 100% revenue growth in 2023 is startling, and if stellar growth continues, on high margins, then the numbers could go through the roof. I'm not terribly confident about payment/forex companies.
Hostelworld (LON:HSW) - up 6% to 141p (£174m) - FY23 Trading Update - Graham - GREEN
Hostelworld beats expectations as it continues to enjoy lovely momentum in trading in this post-Covid era. The balance sheet has been fixed with net debt remaining of less than 1x EBITDA. I admire the company’s progress greatly but valuation continues to look full.
Quick comments from here onwards
Greggs (LON:GRG) - up 7% to 2658p (£2.7bn) - Q4 Trading Update - Paul - AMBER/GREEN
Still expanding fast food chain, now with 2,473 shops (80% company, 20% franchised).
Strong Q4, and a strong year, with FY 12/2023 LFL sales up 13.7% - above inflation.
Confirms FY 12/2023 “in line with our previous expectations”.
“Inflationary pressures reducing”
Net cash £195m
Paul’s opinion - terrific business, and I like the sector for possible margin expansion, as food/energy prices might recede? But high wage inflation won’t help from April 2024. Very popular with subscribers here, hence why I’ve looked at it today. Maybe priced about right on c.PER 20x?
Sanderson Design (LON:SDG) - up 3% to 123p (£88m) - Licensing Agreement in USA - Paul - GREEN
A long-standing SCVR favourite value share. 2023 saw weaker demand for the core business (high end fabrics & wallpaper), but buoyant licensing income from its extensive historic design archive.
Today’s non-regulatory (Reach) contract announcement is not material overall, but I see it as encouraging, since SDG’s strategy is to increase its presence in the large US homewares market. The deal is for William Morris designs to be used on homeware products. Product launches are mid-2024, and £0.7m (almost pure profit) advance licensing income will be recognised this year FY 1/2024.
Paul’s opinion - this reinforces my positive view of SDG. Shares are edging up now, so we could be over the worst maybe? It was on my 2023 top ideas list, but didn’t quite make it onto 2024, but was a strong contender. Looks good value, and lovely balance sheet too.
Costain (LON:COST) - up 8% to 67.8p (£187m) - Trading Update - Paul - AMBER/GREEN
We gradually warmed to Costain in 2023, as the newsflow improved, turning green on 23/8/2023 due to cheap valuation, strong balance sheet, and improved forecasts. Although not a sector we like (low margin contracting).
Today it announces another “significant win” in the water sector.
Overall trading for FY 12/2023 is said to be in line. Net cash at year end is significantly above expectations, at £164m.
Paul’s opinion - looks quite interesting, PER only 5.4x. Note pension scheme (covered in our archive). Not my cup of tea, but providing they don’t screw up any big contracts, then it might be a share worth looking at. Small divis seem to be resuming this year.
Sosandar (LON:SOS) (Paul holds a few) - up 3% to 15.25p (£38m) - Trading Update - Paul - AMBER
This fashion brand dropped a bombshell on 18/10/2023 with a striking change of strategy to full price only sales, and has decided to open some physical shops. Trouble is, it also revealed that instead of a £3.1m forecast PBT for FY 3/2024, it would only be £0.1m. That completely threw me, and I’m amber on this share now (only holding a few personally, it’s not a conviction share for me at the moment).
Today it reveals a solid peak quarter’s trading (Oct-Dec 2023) - revenues up 23% vs LY. Gross margin is high, and up, at 58.3% (LY Q4: 56.8%) - includes lower margin wholesaling, so retail margin is higher still.
Net cash of £7.7m at Dec 2023 looks healthy, but bear in mind they’ll be depleting that for store fit-outs once physical sites begin to open. My guess is c.£150-250k capex per site, depending on size and condition, probably assisted by landlord incentives. They only need to do a handful of stores to see if the concept works or not. First site opens soon, spring 2024.
International - “successful launches” through partners in Canada & Australia. Strategic goal of £100m+ revenues, and 10%+ PBT margin sounds ambitious, but I wouldn’t bet against them achieving it. Overall - trading in line with expectations, which is basically at breakeven (£0.1m PBT).
Paul’s opinion - I’m keeping an open mind here, no strong view either way at the moment.
Advanced Medical Solutions (LON:AMS) - up 5% to 213p (£452m) - FY 12/2023 Trading Update - Paul - AMBER/GREEN
Winsford, UK: Advanced Medical Solutions Group plc (AIM: AMS), the world-leading specialist in tissue-healing technologies…
In line with expectations for FY 2023 and poised for strong growth in 2024
The Group is pleased to report Full Year 2023 results are expected to finish towards the middle of its published guidance ranges of £124-127 million for revenue and £25-27 million for adjusted profit before tax.
Furthermore, following the successful completion of a number of key strategic marketing initiatives and product launches during 2023 across the Group, AMS is primed to generate strong double-digit growth in 2024.
That’s all self-explanatory, and sounds quite good to me.
AMS warned on profits on 4/9/2023, but the 25% drop to 185p looked quite interesting, and I flagged that it might be worth a closer look here. The cash pile was 20% of the market cap then too.
Paul’s opinion - it looks quite good I think. Forward PER is almost 20x, but that comes down if cash is adjusted out. EV/EBITDA is 11.6x, not excessive for the sector. Previously a massive multibagger, but profit growth fizzled out over the last 6 years. If growth is now resuming, then things could get interesting again perhaps? I wonder if it has any key patents that it relies on to generate fairly high profit margins? Nice quality scores. I think I’ll up my view to AMBER/GREEN.
Paul’s Section:
Marks Electrical (LON:MRK)
Down 28% to 66p (at 08:06) £69m - Trading Update (profit warning) - Paul - BLACK (PW), AMBER/RED on fundamentals
Marks Electrical Group plc ("Marks Electrical" or "The Group"), a fast-growing online electrical retailer, provides a trading update for the nine months ended 31 December 2023 ("the period").
Bad luck to holders here. Today’s news is a continuation of the trends noted in its last profit warning that I reviewed here on 13 Oct 2023 - good revenue growth (now 22%, 9 months YTD), but margins under further pressure.
Today it says -
In a challenging trading environment where consumers remain highly price-conscious, our gross product margin did not increase to the levels we expected, and despite proactive action on other controllable costs, the impact of this in the peak trading period has had a material impact on our full year profit guidance.
Revised guidance - but no mention of what previous guidance was, which is so annoying and wastes our time having to look it up -
…we now expect our full year revenue to be in the range of £115-118m with EBITDA in the range of £5-6m
Broker updates - thanks to Canaccord and ED, both issue updates.
Canaccord drops FY 3/2024 EBITDA from £8.0m to £5.0m, down 38%. This ignores the £1.64m depreciation charge, so adj operating profit is only £3.36m.
EPS is more useful to me, that is now forecast at only 2.59p (adj, diluted) - almost halved from the c.5p achieved in the last 3 years.
Forecast gross margin dropping from 19.4% in FY 3/2023, to only 15.4% in FY 3/2024.
Equity Development has exactly the same forecast EBITDA and EPS.
Outlook doesn’t sound great either -
… remain cautious on the speed of recovery in consumer buying patterns, which we expect to temporarily impact the recovery of our gross product margin…
As we work tirelessly as a team to enhance our gross product margin in the remaining months of FY24 and into FY25, I also know from 37 years of trading that margin fluctuations are inevitable, they present us with an opportunity to learn, and will ultimately enable the Group to deliver long-term value creation and position us as the UK's leading premium electrical retailer."
Paul’s opinion - this looks bad, and I don’t think we can just assume that the margins will improve in future. As MRK says, consumers are “highly price-conscious”, and sector retailers have zero pricing power, because the products are not their brands. Hence many (most?) consumers just shop around for the best price online, once they have identified which product they want.
Good service helps I’m sure, but ultimately it’s all about price. That’s what a lamentable 15% gross margin is confirming.
Previously I thought MRK stood out as the best UK electricals retailer, due to its efficiency, and penny-pinching owner/manager (far too large shareholding at 74%). However, I think now its forecast earnings have halved, obviously due to competitive pressures (from a resurgent AO. maybe?), the sheen has really come off MRK shares.
We reviewed it a lot previously, liking the business, but only seeing it as amber (2023: 13/4, 14/6, and 10/8) due to the shares being too expensive each time.
I went a lot more negative with the sneakily concealed profit warning of 13/10/2023, slipped out via broker updates.
For me, today’s update has ruined everything. I would say the new base for EPS is probably around 3p, not 5p previously. It doesn’t deserve a PER of more than about 12, in my view. Hence I’m getting to 36p valuation - almost half today’s already reduced price.
Why would we want to gamble on it increasing future margins, given that we know this is a horribly competitive low margin sector? They might be able to improve margins, but probably not by much, is my guess. So upside could be 4p EPS, and a PER of say 15 - so 60p if I’m being generous. Today’s 66p share price is therefore asking us to pay up-front for both a partial earnings recovery, and a highish PER for a very low margin business. Why would we want to buy that scenario?
So sorry to bulls, but I’m turning more negative on this, it’s AMBER/RED.
There are no solvency concerns though, and you can’t beat the motivation of a 74% owner/manager to turn it around. So patience might pay off here in the long run, but in the shorter term, I think it’s still significantly over-valued. Should it be listed, or taken private?
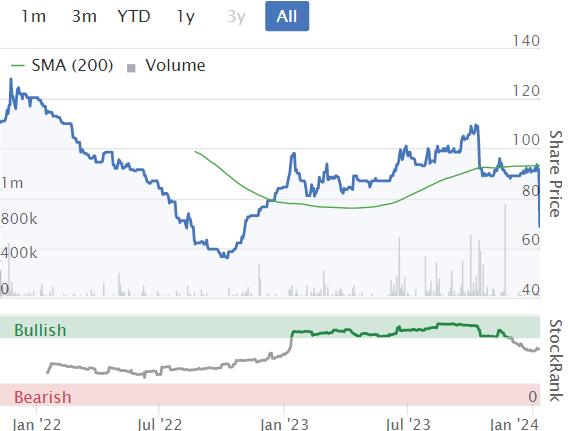
Heading back towards the autumn 2022 lows -
Cornerstone FS (LON:CSFS) (I no longer hold)
Up 17% to 31p (£18m) - Trading Update - Paul - AMBER/GREEN
Cornerstone FS plc (AIM: CSFS), a foreign exchange and payments solutions company offering multi-currency accounts to businesses and individuals through its proprietary technology platform, is pleased to provide an update on trading for the year ended 31 December 2023…
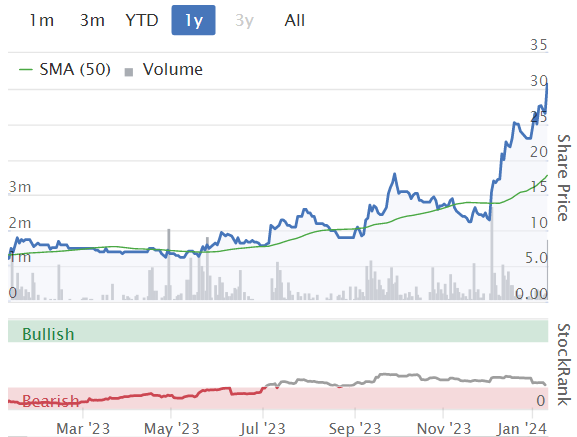
We’ve only looked at CSFS once, here on 4/12/2023 I was GREEN - flagging a series of positive trading updates which had reduced risk and transformed profitability, and its then modest valuation. It’s since doubled in price in just 5 weeks, so that’s been a nice little trade. For disclosure purposes, I sold mine recently to raise cash for more purchases of Tortilla Mexican Grill (LON:MEX) which is a pity as I missed today’s 17% further rise. Never mind!
Annoyingly the company quotes EBITDA, but Shore Capital translates for us - it raises FY 12/2023 adj PBT from £0.7m to £0.8m - a small beat. It’s a tremendous improvement on the PBT loss of £(1.3)m in FY 12/2022. The driver seems to be a doubling of revenues to £9.6m in 2023, and an effective sales team apparently.
Cash is £2.3m at Dec 2023, but the company forgets to mention that there are £2.2m of loan note liabilities, so net cash is only £0.1m.
Paul’s opinion - looks interesting. Shares have risen a lot, so I expect there are others who like me were happy to bank the profit. To reflect the big rise in valuation, I’ll shift down a gear from green to AMBER/GREEN
Graham's Section:
Jupiter Fund Management (LON:JUP)
Share price: 74.7p (-16%)
Market cap: £407m
This is a grim update from Jupiter, a fund manager which I’ve been positive on but which I did not consider for my 2024 list of best ideas.
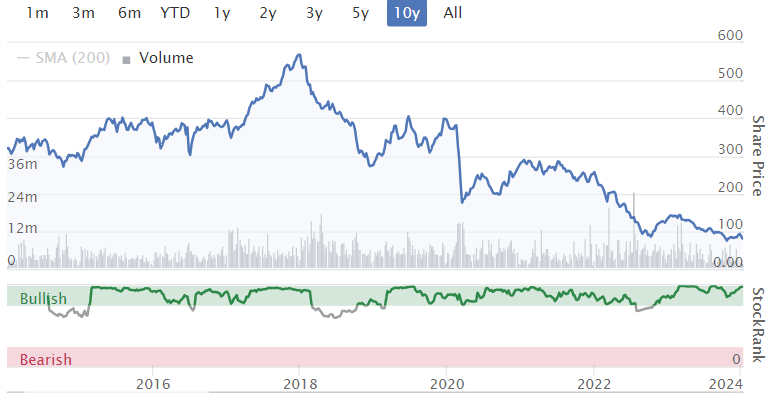
Jupiter has experienced a very long stream of outflows; its share price reflects a failure to compete in the modern investment environment where there are so many ETFs, international funds, and specialist asset classes to choose from:
I’ve been positive on the stock due to a valuation which has at times seemed absurdly cheap, and a new CEO with plans to streamline operations.
But today’s news does not inspire confidence.
Firstly, the company is losing Ben Whitmore, the current manager of funds with £10 billion of AuM (nearly a fifth of Jupiter’s entire AuM).
He is leaving “in order to pursue his ambition of establishing an independent value equities boutique in due course” - i.e. to create a business that could ultimately compete with Jupiter.
The blow is softened by the appointment of a new fund manager from JO Hambro. Two other recent hires will also be able to take over management of particular funds. There will be “an orderly and collaborative transition process”.
Additionally, Whitmore has agreed that “his new boutique, once established, will not compete with Jupiter for a period of two years from his leaving date in relation to both the UK Equity Income sector and the non-UK open-ended UCITS market”.
Secondly, we get a poor trading update for 2023:
…a delay in the funding of some institutional mandates combined with weaker than anticipated retail sentiment in October and November 2023 has led to an incrementally more negative flow outcome than we had anticipated. Total net outflows for 2023 are expected to be £2.2bn
Jupiter started 2023 with £50 billion of AuM, so about 5% of this was withdrawn during the year.
Retail/wholesale investors seem to be pulling out £1 billion each quarter, while institutional investors have been helping to offset this with some inflows.
Performance fees for 2023 will be more than £10m, which is higher than previous guidance.
Impairments: prior acquisitions will need to be written down on the balance sheet to reflect “lower asset valuations, muted demand for risk assets from retail clients and a higher cost of capital”.
Graham’s view
Despite worse-than-expected outflows, Jupiter’s total AuM still managed to rise during 2023 (to £52.2 billion), thanks to positive investment returns.
I find it remarkable that fund management companies can be so unpopular with their customers from time to time, and yet their AuM just keeps on rising. The market valuation will paint a different picture, of course - you now get around £108 of AuM for every £1 invested in Jupiter at the current share price. This is a truly distressed valuation in my book.
The loss of someone considered to be a “star” fund manager at Jupiter is of course a blow. However, it strikes me that the remaining investors in Jupiter funds have already displayed a great deal of loyalty (some might call it inertia) and that most of them are likely to stay with Jupiter even through a change of personnel. Some will of course want to follow the fund manager to his new company, but that company does not yet exist and the non-compete clause will provide temporary protection even when it does.
I’ve been positive on this stock and yet the share price has been moving the wrong way - so am I changing my stance? Not yet, no.
The stock has been trading at depressed levels relative to AuM and earnings for some time, but it’s now arguably becoming depressed relative to its balance sheet, too.
The interim statements showed £849m of net assets, including goodwill. That goodwill will get written down, but even excluding all intangibles the company still had a TNAV of £193m, consisting of highly liquid current assets.
That covers nearly half of the current market cap. At this level, shareholders would benefit very quickly if Jupiter stopped trying to be the acquirer and simply allowed itself to be acquired.
Belvoir (LON:BLV)
Share price: 266.65p (+4%)
Market cap: £99m
Property Franchise (LON:TPFG)
Share price: 340p (-1%)
Market cap: £111m
We have big news this morning as these two franchising estate agents have announced that they wish to merge.
It’s a recommended all-share merger so there is no cash payout for either side.
Instead, 48.25% of the new combined entity will be owned by Belvoir shareholders, while TPFG shareholders will hold the remaining 51.75%.
Under the proposals, every Belvoir share will be exchanged for 0.806 new TPFG shares.
It does imply a small premium for Belvoir, valuing each BLV share at 277.4p, which is 8% above last night’s close price.
Belvoir shareholder support: 31% of Belvoir shareholders are supporting the deal, so more votes will be needed to get it over the line under scheme of arrangement rules.
TPFG shareholder support: 56.7% of TPFG shareholders are supporting the deal.
Rationale for the deal
The combined group will have “more than 930 locations, managing approximately 152,000 tenanted properties across the UK (excl. Northern Ireland) and will be expected to sell more than 28,000 properties per annum”.
(GN note: more than 1 million properties are sold in the UK every year, so market share will still be less than 3%.)
Continuing:
As a result of the Merger, the geographic spread of the Combined Group would be enhanced and diversified, which the TPFG Board expects will provide more opportunities for franchisees to serve customers showing an interest in the Combined Group's services via the various platforms.
On top of that, there will be cost synergies including both simple short-term synergies (such as Belvoir’s AIM listing) and medium-term synergies such as “deployment of expertise gained in revenue generation through strategic initiatives”.
Belvoir has a “well-established financial services division” (in partnership with Mortgage Advice Bureau (Holdings) (LON:MAB1)) which will be strategically valuable for TPFG.
Management changes
Key facts:
The CEO and CFO of TPFG will continue as CEO and CFO of the combined group.
The CEO and CFO of Belvoir will step down from their current positions but “will continue to be engaged” for 12 months.
The new eight-person board will have five TPFG representatives and three Belvoir representatives.
Based on the above, we can’t really call this a merger of equals - it is more like a large acquisition for TPFG. Although Belvoir shareholders will own nearly 50% of the combination.
Timetable - the deal is expected to take place in Q1 2024 after votes and legal procedures.
Trading updates
Belvoir: Since 30 June 2023, the Belvoir Group has continued to trade comfortably in line with the Belvoir Board's expectations.
TPFG: Since 30 June 2023, TPFG has continued to trade in line with the TPFG Board's expectations.
Graham’s view
I have been positive on both of these companies and for similar reasons - e.g. here (BLV) and here (TPFG).
They are both highly successful franchisors in the estate agent business, with slightly different points of emphasis. TPFG owns the hybrid agent Ewemove, while Belvoir has a headstart in financial services with 308 advisers in their network.
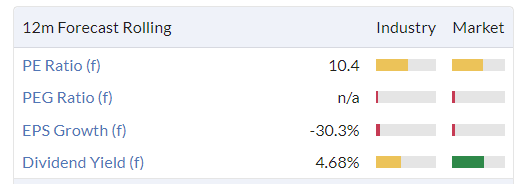
They both earn fabulous return metrics, which are strikingly similar.
BLV:
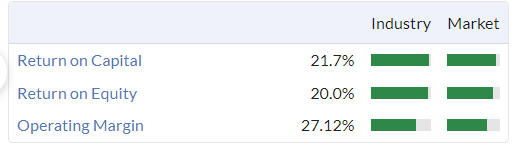
TPFG:
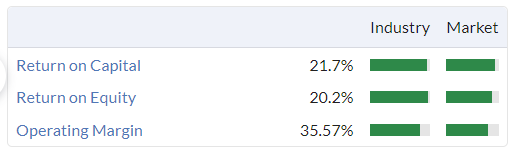
With two companies that are essentially doing the same thing, only with some differences in geography and expertise, it’s not difficult to justify a merger. The benefits are clear: a merger eliminates any harmful competition that may exist between them (from the point of view of shareholders), while also improving the reach and the capabilities of the combined entity.
I have been positive on both companies and I will remain positive on the combination, which I expect to be even stronger than the sum of its parts.
From a value perspective, it was much more exciting when these shares were trading at single-digit P/E multiples. At their current levels, having risen greatly during 2023, they are not quite as tantalising as they were before. But I do think this deal could help to turbo-charge future performance. In any case, I’m staying GREEN.
BLV share price:
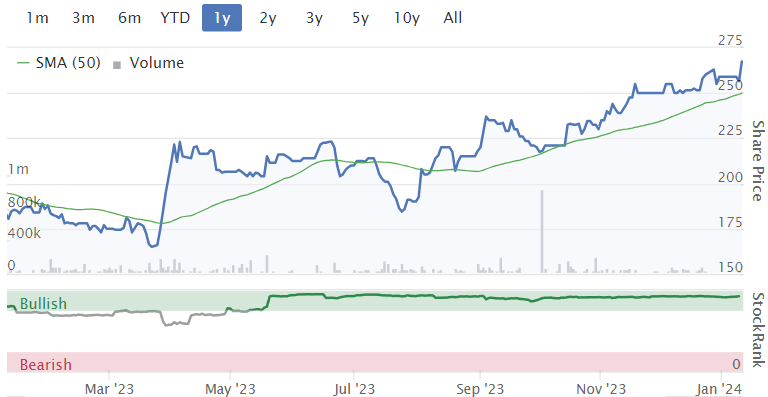
TPFG share price:
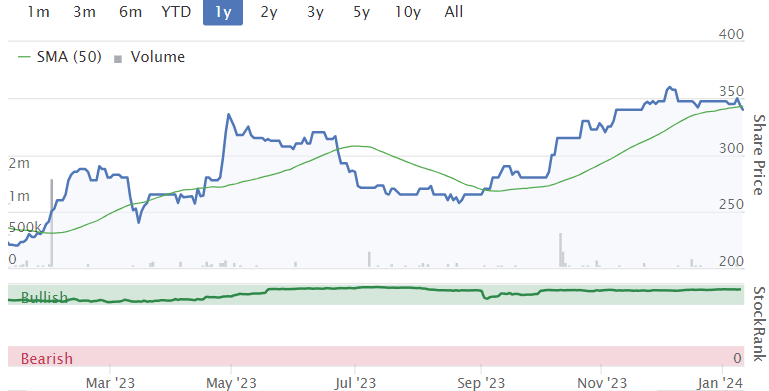
Nichols (LON:NICL)
Share price: £11.84 (+5%)
Market cap: £432m
This soft drinks group announces a full-year update.
2023 adjusted PBT will be “slightly above current market expectations”, i.e. slightly above £25.4m. This is a little higher than the adjusted PBT result for 2022 (£25.0m).
The long-awaited improvement in “Out of Home” business has finally arrived, with the company seeing “some of the benefits from the restructuring of our Out of Home (OoH) business earlier than initially anticipated.”
I included Nichols in my 2024 best ideas list, having reviewed its performance in my 2023 list. An improvement in Out of Home trading would go a long way towards restoring Nichols’ profit margins to their former glory, which is what I have been betting on!
Other key points from today’s update:
Revenue up 3.5% to £170.7m. “Out of Home” revenues declined as unprofitable accounts were shut down, while “Packaged” and “International” sales grew.
Gross margins “largely maintained” despite inflationary pressures early in the year.
Cash at the end of the year was £67 million (it was £56m a year ago).
Outlook: the main point here is that Out Of Home “will contribute positively to overall Group performance in 2024”, but this isn’t quantified. The OoH segment was already contributing positive adjusted PBT, so this doesn’t give away much information.
The overall tone is ambitious with management planning “to accelerate the rate of investment in its longer-term development over the next 12 months”.
Family business: we are reminded that this is a family business as Commercial Director Matt Nichols joins the Board as a NED.
Graham’s view
I included this company on my 2024 list within the past two weeks, and it has performed “slightly” ahead of expectations, so I have no reason at all to change my positive stance on this one!
There are many cheaper shares in the market today but few have the heritage and multi-decade track record of Nichols.
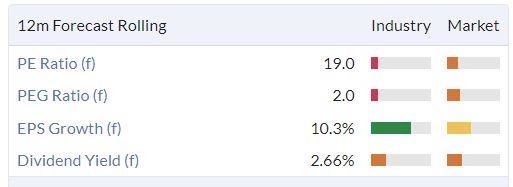
At a PER of 19x, it would be overly optimistic to hope for multiple expansion - but I think it is reasonable to hope for an improvement in margins feeding through to increased profitability over the medium-term.
Hostelworld (LON:HSW)
Share price: 141p (+6%)
Market cap: £174m
There’s continued strong momentum at Hostelworld with the following highlights from its year-end trading update:
Record levels of bookings (€619m) and revenues (€93.7m), both up 32% year-on-year.
Bookings up 37% year-on-year
As previously signalled, there is a lower average booking value due to more Asian destination bookings.
When it comes to profitability, adjusted EBITDA of c. €18.3m exceeds the upper end of market guidance (€17.5m - €18.0m).
Net debt further reduces to €12.3m (€22m at the beginning of 2023).
CEO comment excerpt:
Over 2023 we grew market share, delivered record revenues and increased operating leverage through a combination of reduced marketing spend (as a percentage of net revenue) and continued operating cost discipline to deliver EBITDA which exceeds the upper end of our guidance range. In particular, I am also pleased to report our full year marketing costs as a percentage of net revenue fall from 51% in the first half of the year to 50% on a full year basis...
Graham’s view
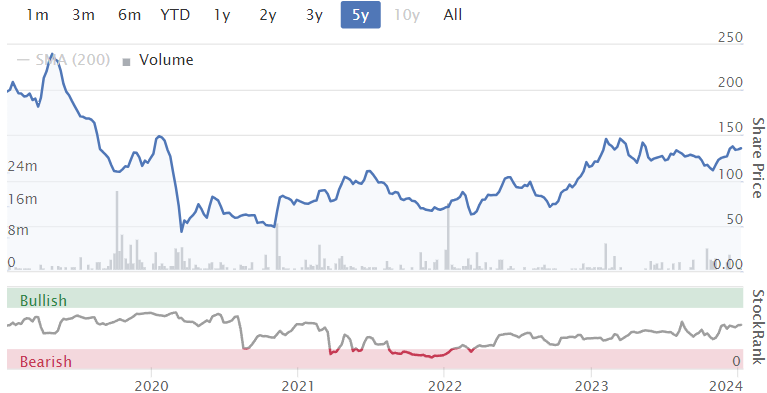
What started as a post-Covid recovery story has been sustained and seen the company power through its pre-Covid revenue numbers, at least on a nominal basis if not on a real basis.
This is reflected in a share price making steady progress:
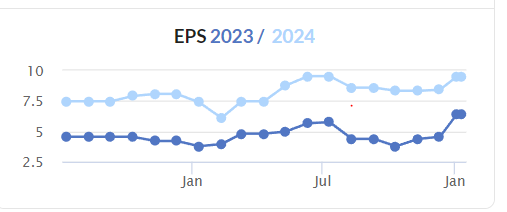
Not only have revenues been surging through their pre-Covid levels, the company has been beating profit expectations and upgrading forecasts:
I’ve kept a neutral stance on the stock. While I’ve been greatly impressed by the company’s momentum and how it has fixed its balance sheet, I’ve also been concerned that its valuation may already be up with events.
The market cap equates to over €200 million which is more than ten times a heavily adjusted EBITDA figure. A little more, if we add on the remaining debt figure.
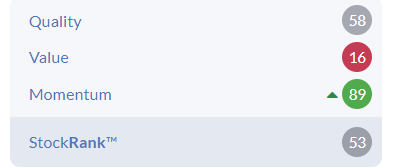
Therefore, while Hostelworld might still be undervalued at this level, it seems to me that there are more straightforward value opportunities to be had. The StockRank may have it right:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

97 comments
Thank for todays report Paul & Graham. Top Notch!
Thanks for the positive feedback Don't tell him Pike - love the username!
I work flat out in January, partly as penance the inevitable excesses in December, but also because it helps winter pass more quickly.
Avon Protection (LON:AVON)
I have a very small holding in these, which i would/should have added to in the last few months but i am always put off by the huge intra day SP volatility . Even with todays large volume, £1,000,000 worth of shares traded, which is roughly 2x normal daily volume the price jumps around with a complete mind of its own !!
I am missing something ?
With the removal of cookies by Google Chrome and others, publishers like Reach (LON:RCH) and Future (LON:FUTR) are likely to benefit hugely from data they collect by user sign-ups. Reach uses the data as follows:
Targeting by Reach
We combine the information you give to us (for example, sign up information for newsletters and competitions) with the information we receive when you use our websites and apps, and analyse it in order to help us to understand your preferences and interests. We then associate this with a unique identification number. This is then used to tailor the content and advertising that you see on our websites and in our apps, so it is more likely to be of interest to you. We don’t share this personalised analysis with anyone outside Reach. In particular, it is not shared with advertisers or with the third-party advertising networks that we work with other than in highly aggregated form so that your personal data cannot be identified.
The data we use for this purpose is as follows:
The page you view, and associated information such as how long you spend on them.
Your approximate location, to city or town level.
Your email address, name and sometimes username and postcode, which we will receive when you sign up for an account on one or more of our websites or apps, when you subscribe to our newsletters, when you enter one of our competitions or when you complete one of our surveys.
The newsletters you have subscribed to, the promotions and competitions you have entered and the surveys you have completed.
We will analyse this information to infer interests, preferences, and demographic characteristics, and associate it with an internal identification number. For example, if our website analytics tell us that you are located in the approximate area of Newcastle-upon-Tyne and you read our online title ChronicleLive (which is focused on local news for that area), and you sign up to receive an email newsletter about football from our national title The Mirror, then we could infer from that you are interested in things related to a local football club or to football generally.
We then divide up our identification numbers into groups based on the inferences we draw about them. Those groups are called “audience segments” or “audiences”. So, for example, an identifier associated with Newcastle, ChronicleLive and the football newsletter could be allocated to audiences likely to be interested in football, and events near Newcastle-upon-Tyne.
We then use those “audiences” to do two things: first, to help us to recommend content which is more likely to be interesting (for instance, more articles about football), and second to help us to target advertisements when advertisers buy advertising space from us directly.
The advertiser would never see the actual data that we use – it remains with Reach at all times. All we would share with them would be the criteria we used to target their advert, how many times their advert was shown and how many people clicked on it (but not who), so that they know how well the advert did and we know how much to charge them.
Reach (LON:RCH) sits on a p/e of 3.1 and a yield > 10%. There's a big pension deficit to sort out but recent rate rises should help as will cost cuts.
I've added in anticipation of better prospects as cookies are deprecated and results start to reflect this.
Unless they're planning to change the text yu show above, collecting some of that data, for example site usage, still relies on a user accepting cookies.
We own Sosandar (LON:SOS) and continue to back the judgement of the management who seem to know their customers and to have the confidence and ability to make strategic decisions.
Sosandar (LON:SOS) (I hold). Seconded! This is very much my view as well
Cheers to the people who mentioned and discussed Cornerstone FS (LON:CSFS) in the commentsa few months ago, when discussing larger players in the sector Argentex (LON:AGFX) and Equals (LON:EQLS)!Glad i continued to hold and added on a pullback a few weeks ago.One of my few UK listed winners last/this year:).After Jupiter Fund Management (LON:JUP) 's announcement yesterday i needed the emotional boost if nothing else.
I learnt today that Vertu Motors (LON:VTU) are in talks to purchase another West Country dealership. I hold.
hVIVO (LON:HVO) - Are the big boys finally investing here? Terrific volumes and a breakout in price. Paul reviewed HVO last week post a big contract win - https://www.stockopedia.com/co...
hVIVO (LON:HVO) rise should be no surprise. I expect some corporate action in the coming months - probably a Nasdaq type listing as this has been mooted several times by the board and recently they added to corporate advisors.
Notwithstanding the potential benefits of that the share appears well undervalued to me - I expect trading ahead of expectations and next years revenues to be almost in the bag. Margins are hitting 20% which is where a good CRO should be and the net cash as a %age of market cap is big so it has lots of firepower.
The other one I expect to move this year as an aside is Poolbeg Pharma (LON:POLB) - they have re-hired the key members of Amryt pharma with the intention of repeating the trick. (Sold for $1bn+). Poolbeg Pharma (LON:POLB) has plenty of cash and burns little so again has the firepower. But let’s see what happens - one to watch.
I've had a very nice run on Cornerstone FS (LON:CSFS) over the past month - the previous update, reported here, piqued my interest and I opened a very small position which has become rather larger very quickly. Now what? A month ago there appeared to be more value than was reflected in the share price, but I do wonder if there is anything in their tech that allows them to give a better offer than the more established players in this space? Is there any sort of moat or are they just a 'me too' challenger with nothing special under the bonnet? Business is obviously going a train for now, and generating good cash, but does this really have legs? Would be interested to hear from anyone with knowledge. Am torn between bailing out of a nice trade or hanging in there for the medium term.
Cornerstone FS (LON:CSFS)
I have mentioned this on the 11th December 2023 when still trading at 18p that it was just too cheap and that available research regarding revenues and free cash flows was too low.
After today’s trading update and at 30p this seems to be still undervalued and should be trading at much higher levels.
I expect another trading update in February or March stating that revenues and cash flows are well above market expectations as available research have this for £11-£12m-I expect them to be at least £18m for the current financial year.
DYOR
All the best
Yeah good call Yiannos. I like Cornerstone FS (LON:CSFS) but having failed to buy at 14p when I was going to I am struggling to buy at 30p. Was hoping for a pullback to 20p recently but todays rns has scuppered that. Oh well…..another fish that got away. I will keep an eye on it tho and take a position if there is any weakness. No point chasing on FOMO.
Thanks to your comment on 11/12 I investigated further. Research Tree have broker notes that give a target price and investment rational that obviously none of us can repeat nowadays... But thank you for the heads up y1. One to hang on to I think.
Thanks David
I bought more Cornerstone FS (LON:CSFS) today as I feel the growth is at early stages and hopefully there is a pullback to add.
I am for the last month watching Poolbeg Pharma (LON:POLB) but I haven’t (yet) bought any.
I ll appreciate more information on this one.
Hi - will try and summarise a bit of the inv case on Poolbeg Pharma (LON:POLB) when I have a bit of time - poss tomorrow
Cheers David.I would be interested in your views on Poolbeg Pharma (LON:POLB) too.Cathal Friel is one of the 'Covid Aim favourites' CEOs whose company is still thriving.He did seem a little 'pumpy' at the time even to my then much more naive self, especially when Link were selling for Woodford and the share price wasn't moving the way everyone wanted it to.But he's really produced the goods with hVIVO, even if he isn't the current ceo.
Me too if you get the time. Thank you David
Wow...I wouldn't touch a business Cathal Friel is involved in personally. Total bs artist. hVIVO (LON:HVO) got lucky and opportunistically got into its current line of biz when it really was not the plan. Best move Friel ever did was get the actually good and competent Mo Khan in to build out a real business...I like hVivo but my opinion is that it is overvalued at present and not time to buy as further development will take significant investment...this is not bad at all...just likely to challenge overly bullish sentiment.
Poolbeg Pharma (LON:POLB) I don't know well. But £14m cash with early stage drugs at best at phase1 of approval process and on a £50m valuation...well you'd better understand a lot (a lot!) about the chemistry they own and are developing. I'm gonna guess that no-one on these pages has that skill.
I like biotech/life sciences at the moment...but I know my limits so I own a basket of stocks at small weights looking for a trade off between valuation, funding and stage of proof...so probabilistic. Could be wrong (badly) on any one. IMO Poolbeg is very negative trade-off and would not get near my basket...
BUT interested to hear the counter
Some decent volume in Eagle Eye Solutions (LON:EYE) today if anyone's interested.
There's been an institution selling down (probably/possibly for fund redemptions). The large trades at 490p look to have cleared the overhang. I've been increasing recently as I view them as the global leader in what they do and digital loyalty schemes/coupons usage are only going to increase.
Ofgem accepted Shell Energy voluntary payment of £1.6m for overcharging customers.
Just to show Shell who's in charge they've also fined them the princely sum of £1. I'm sure there's some legal reason for this but no idea what.
Pennant
I’ve been building slowly in Pennant .
It seems a bit sleepy but seems to have good technology in the red hot “warfare” sector .
Have to say haven’t quite got my head around the product offering which is a bit lazy and management seem quite steady away .
It’s a bit of a historic jam tomorrow one reminds me a little of MSI but Pennant by definition will lag on increased orders .
Lawrence Hulse of Onward has taken 3% recently and Richard Staveley Rockwood his ex boss is I think on 8% and I think I overheard a somewhat annoyed Staveley make a comment along the lines “get his own bloody ideas” . I could have dreamt that so take it with a pinch of salt .
I did ask Staveley about it at Mello and recall he thinks they should “buy something bigger but that will need a fund raise” but quite honestly I was well over information overload threshold by that point and thinking of nothing more than heading home .
Any other Pennant holders can help build a picture or fill in the gaps or have I really got to DMOR .
Pennant International (LON:PEN) Not sure I can add to what you already know Planetx but I will do my best......
Yes they are a niche tech player in the defence sector and transport sector (airlines and railways). They provide training and safety modules for a lot of very sophisticated equipment and have been shifting increasingly from provision of lumpy hardware work to software and services, I believe this is now up to 75% of turnover. Margins are up to 47%. Clients are sticky and revenues are recurring. However given all the conflict in the world they are apparently bidding on more work then ever before, we await news on this....
They are very cheap, if they hit 2024 numbers then we're talking about 5p in cash on the balance sheet and 4.2eps (against a price of 30p today).
But it's the shareholder roster that makes this interesting, these guys have not bought into this nano just because it is cheap and steady. It's an old established company in a very hot sector and I think the shareholders see this as a vehicle to grow through acquisition and take advantage of their expertise.
I hold (unfortunately at higher levels) but can't see the downside at 30p so if you are buying in now then lucky you! Either this grows steadily and rerates or there is a big deal/acquisition which probably involves some sort of well supported placing, (although I can't see why they would dilute at these depressed levels).
Either way, bit of patience required and let's see what happens in 2024...
Interesting Burnt Onions and Planetx. My main issue with them at this point accepting they look cheap is liquidity. At these more bullish times following a depressing few years we are all sniffing around for bargains which leads us to a lot of micro stocks. In my role as a Stockbroker years ago I used to see lots of portfolios with illiquid micro stocks just sitting there as the buyers couldn't get rid at a price acceptable to them. I am concerned about this in particular this time round given a general lack of interest in small UK companies. Hope that at least alerts you to a potential concern. All the best.
Same here-illiquid for a reason.
Camtab, your point is absolutely valid, it's not something you can trade in and out of so I treat this sort of purchase like a private equity investment.
But the three young 'activist' fund managers in Richard Staveley, Lawrence Hulse and Richard Penny who have bought into it in the last 9 months have relatively limited funds and an abundance of choice as to where to invest so I think some sort of positive action will be sooner rather than later. And of course I wouldn't blindly follow them in unless the fundamentals backed it up. Just my honest opinion and read on the situation.
Morning All,
Any broker forecasts for CMC Markets (LON:CMCX) ?
Thanks.
Are we allowed to say ?
As the ones I have in front of me are from a paid subscription!
Perhaps Meghan can clarify this.
Thanks
Hello Yiannos,
Probably not then!!
Why not? Will Stocko not update with the latest forecasts soon anyway? CMC Markets (LON:CMCX)
Don’t know about Stocko (most of the times the figures are behind the curve!) but I was told off not to mention anything that is from a paid subscription.
Don’t understand the logic as every morning Paul and Graham update in their comments any new research numbers published mentioning as well the name of the broker providing the research (and rightly so).
Go on then!!
The issue with Jupiter Fund Management (LON:JUP) and their ilk is that there is a strong and sustained movement towards passive investment, which is eating their lunch. Investment Management companies are cheap for a reason. The financial services industry likes to de-risk and you can't under-perform if you invest on a passive basis. If you had simply bought a low-cost global market tracker last year you would have made 12%. If you had tracked the US market last year you would have made 25% for minimal cost and effort. You can see why its becoming the norm.
Jim
I'm waiting for BlackRock to unveil their A.I superstar fund manager WOPR.
"How about a nice game of Chess?"
"Later. Let's play Global Thermonuclear War."
OK, as long as the annual fees are under 0.07%
This argument has been used for 20+ years. In reality (ie on the ground) nothing is really changing. Yes, the use of ETFs is going up but so is the overall pot.
NothingV, I agree to a point but most institutional investors want a bespoke mandate, not simply to track a market. They might want, for example, a FTSE250 investment degraded mandate, with an alpha of over 1.2 with a beta of 0.9. They are not trying to match simple performance, their objectives are more sophisticated. As suck, managers such as Jupiter are still in significant demand but there’s no doubt about it, when markets and lack of activity collides with depressed sentiment, these stocks really to suffer. I hold Jupiter Fund Management (LON:JUP) and may well use this dip to top up.
GYM (LON:GYM) issued a trading update today. It seems quite positive overall but market reaction is muted.
This was last covered by Graham in September 2023 here where he was generally slightly negative. The reduction in debt seems critical to me and they are heading in the right direction so I picked up a few this morning.
GYM (LON:GYM) I agree with you DWit199, things are looking pretty positive here and you had a nice round of director buying 6 months ago. Personally I'm looking for a bit more debt reduction and maybe an interest rate cut before buying into the turnaround, probably another 6 months or so. But I definitely like the business, 10%+ free cash flow yield, can't see people ever ditching budget gym membership of £20 a month, not the millenials....
Hello,
I have swung from short to possibly long gradually with GYM (LON:GYM). Update better than i was expecting.
if GYM (LON:GYM) was in the US like e.g Planet Fitness (NYQ:PLNT) or in europe i.e Basic Fit NV (AMS:BFIT) it would be valued much higher and their model and cash generation rewarded but they aren't so it isn't!
if GYM (LON:GYM) was in the US ...
True, but if they were higher rated then I probably wouldn't buy. The hope here is that anticipation of increasing profitability with decreasing debt will drive a re-rating.
J D Wetherspoon (LON:JDW) . I hold
Just seen (Alliance News) -" Haven says partners with Wetherspoon to operate at its parks"
Looking forward to Paul's video when he mystery shops on one of his breaks. Loved the one on ME International (LON:MEGP) - also hold. Certainly highlighted how much forecourt owners are utilising their sites beyond just selling fuel
ME International (LON:MEGP) sailing in France last year, I noticed several of these washing machines at marinas. Perhaps no coincidence that the app is French?
After his positive comments following their recent trading update, I am waiting on Paul to mystery shop JD Sports' athleisure collection :-)
Mystery shopped at LON:JDW last night. Doom Bar £1.99 a pint. My amigo had a lager can be £13 a round down the road. £5.90 with a packet of cheese and onion thrown in. That's like wow!!
Good call on the Doom Bar !
Sosandar (LON:SOS)
i see little no no visibility here now - now they have taken the decison to expand for the medium term throwing profits down the drain in the process imho its very hard for investors to make much sense of whats going on - all they (the investors) are likely to get is rear mirror details of where the profits might have vanished generally speaking (whilkst progress and margins will be great) - with higher overheads that also chuck further uncertanties into the mix. I aint going to tell them how to run the business this strategic investement into physical stores might make perfect sense - i certainly know they should be better placed to know whats best for the long term - but at present as someone on the sidelines its uninvestible to they prove their new format will work.
Despite all the ringing from the rooftops about 10% pre tax profit margin current expectations are for 0.2% this year.
i dont understand why they didnt trial this new format on much smaller scale whilst still keeping decent % of the profits they previously promised.
Note no criticism of management here update confirms what expected figures are so at least they are being fairly open about the potential profits vanishing before they turn up.
Hopefully for holders they will get more detail about plans than i expect the company will provide. Woulkd be nice to see 3-4 years projectiosn and for progress top be checked to see if their "plan" is working. imho shouting 10% without numbers/dates to back in up is cloud cookoo land stuff for listed company.
I hold. Happy to sit and watch this play out. It’s primed now with the partners and I expect more international partners to be added. Adding retail will add capex of course, but I like the new strategy.
Personally I think the store expansion could be a bit of an ego thing. Yes it might make the business bigger in the years to come but, as you say, huge increase in risk given the capital required to make it happen, and fixed overheads should they experience a downturn in trading. I think directors have seen an opportunity to make the brand bigger, more visible and create a physical presence of their own, and perhaps feel encouraged by how forthcoming investors have been when the begging bowl comes out (34% CAGR grown in share count since 2018 according to Stocko.) Maybe they'll be less willing to prop them up next time fresh capital is required?
I sold out after the strategic decision to open their own shops. It may work out but I don't see how, with the state of the high street and the capex required. I really feel like this was a reponse to institutional investors asking 'how are you going to grow quickly?'
AdvancedAdvT (LON:ADVT) re admitted to trading today, with a sharp swing up on early trading, not surprised as it opened below NAV.
Vin Murria’s return no doubt keenly anticipated.
Held for a while and struggled to get a quote early doors on which to top up.
One of my top 5 for this year.
Glad I sold my holding a few months back for a small profit. Certainly looks over valued now as Paul rightly has been saying. Good call. Considering it previously went into the 50’sp last year I would not be surprised if Marks Electrical (LON:MRK) hit new lows now. Possible into 40’s or high 30’s. With broker forecasts downgraded for next year as well as this year it could be a while for recovery. But while still profit making and growing I’m not sure investors would want to pay a high PE atm.
Ripe for the owner to take back into his (full) ownership?
Quite possible. But at a lower price. While a recovery in the economy is likely this year I do think people will still struggle with money this year and will tighten their belts more, which will make it difficult for the retail and entertainment sectors. I’d be more inclined to see these sectors not recover until 2025.
I agree. I think there's an argument Marks Electrical (LON:MRK) could be viewed as a high growth company and command something quite punchy (esp. as top line has maintained pretty decent growth of 15%+) but, as Paul has consistently mentioned, the online electrical retail sector seems to be a race to the bottom on price, so despite all the flashy top line growth it's hard to tell whether there's a decently profitable business under the hood.
If they can rebuild margins then I think Marks will tick a lot of the right boxes - but time will tell. I wonder how much of the margin erosion is called by inflation, tough consumer environment (etc.) vs something more systematic re: the sector.
Hunting plc (LON:HTG) already tipped in the press as one to watch in '24, and a solid TU on 2023 released today. Updated note from us now out with fair value set at 407p, and there is a retail webinar by CEO and FD at 1.30pm TOMORROW for those interested. You can register here https://www.equitydevelopment....
New research note is freely accessible here, with audio summary: https://www.equitydevelopment....
If Ben Whitmore is the star investment manager of Jupiter Fund Management (LON:JUP) , where the share price is down almost 90% in 5 years, then I'd hate to see what his deputy might have achieved. There's a lot of over inflated self worth floating around this sector, with (rare exceptions excluded) not much to back it up.
I looked up how he has performed. From the RNS we know that he managed UK Special Situations Fund (which was in the top quartile for 3yr performance; AUM £2.1bn), Jupiter Income Trust (3rd quartile for 3yr performance ; AUM £1.6bn), Jupiter Global Value Unit Trust (AUM £1bn) and Jupiter Global Value SICAV. For the last two I cannot find their performance - unless the former is the 'Global Equity Absolute Return'. The performance figures are from their most recent annual report in 2022 pasted below.
I saw someone on Twitter/X joke that he won't be very good at managing his own boutique because he never meets clients. I have no idea about the validity of that comment but it's a reminder that if he is running his own firm he will have to work hard at bringing investors in, whereas at Jupiter Fund Management (LON:JUP) he can rely on their marketing spend. So I agree with Graham that the market potentially over-reacted to this news although the framing of the update was generally negative.
Re. Ben Whitmore at Jupiter, Trustnet is the place to go to see a good summary of his (and any other fund manager's) track record:
Trustnet - Ben Whitmore
Ashtead Technology Holdings (LON:AT.)
Hunting (LON:HTG) Taken from this morning's Hunting TU
Hunting's Subsea product lines have reported strong year-on-year growth, with revenue up c.40% in 2023 from $69m in 2022. The Spring business has secured a number of large orders for its titanium stress joint technology in the year in Guyana as well as the Black Sea, the latter being a new market for the Group which was awarded in mid-October.
I am not convinced that this is a directly comparable read across for Ashtead Technology's business but obviously not bad news.
Costain (LON:COST) profit inline but net cash £164.4m (2022 year-end: £123.8m), "significantly higher than market expectations of £128.6m". With MCap £173m at last night's close the EV is peanuts. Stocko likes it:
Comments on Costain (LON:COST) would be welcome please. Good TU with big increase in cash balance meaning an EV of only £8m, at last night's close!
Costain (LON:COST) (I hold)has cash of £164M. Market cap £172M. Turnover £1.4B. PE around 7. Low margins but If this turnaround gathers pace then it’s remarkably cheap. Chart looks like a clear bottom has been established.
New contract for £674M over 12 years (not £174M as in Paul’s brief above).
Comments would be appreciated.
I think a lot of the cash is the "client's money" which is in the form of advances and stage payments for the large projects they work on. The actual retained cash will be much less.
Not clients money.
It is the company’s money but needed to bid for projects as guarantees so effectively cannot be returned to shareholders.
Costain (LON:COST)
great points spglet/yiannos1
i think for clarity its best to drill down to actual balance sheet numbers here and mention all relevant parts to get some sort of picture ref liquid assets
at june 2023 -(this could be wildly outdated info now)
they had receivables 192 mill and cash 132 mill to total asset pot 325 mill
they had trade and other payables (i have ignored lease laibiites) 242 mill
To me its pointless mentioning the cash here without looking at what they owe out (and are owed in). so anyone simply quoting net cash here and not commenting on what they owe out isnt really providing much useful info.
net total here is plus £83 million if my maths is correct - thats a very healthy figure imho but this sum imho is a more accurate reflction of whats theirs to keep (if they stopped tomorrow and all debts were settled) than the actual cash total imho . Anyone quoting higher cash figure without mentioning a boat load of that is owed out aint giving the full picture imho.
Note there is alwasy risk here too if the debtors figure is high - contracting companies sometimes run into problems getting paid - and one wants to be cock sure accounting treatment is conservative - most of these contracting companies when they have failed have turned up with a ridiculously high amount of extra amounts owed out that simply werent previously factored into the figures.
Also the low margin bring risk too - if they are only booking 3% profit in the good times. If costs increased 5% that they couldt pas on then profit is wiped out plus some.
Many of these companies have ben fine for years but invariably at some stage most of these companies if tehy go for long enough will run into some mini disaster that undoes all the good work. The reality here that they probably need £80 mill exces on balance sheet to satisfy customers that they will be able to fulfill their contracts if times get tough.
i see the massive attraction here in good times if they could expand profits to £50 mill put pe of 15 that would be market cap of 750 mill - so companies like this can easily 2-3 bag if they have good run and the market thinks they are a company going places.
I could be tempted to have an investment in a company like this but i would only want to be invested here if the company is known to be in a sweet spot ref tehn future - increasing eps numbers on stocky and chunky contract wins looks positive in that regard.
Sanderson Design (LON:SDG)
Another licensing agreement in the USA. Well done to Lisa Montague and her team. I hold
"Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, is pleased to announce that its Morris & Co. brand has signed a licensing agreement with ENVOGUE International ("ENVOGUE"), a New York designer and distributor of fashion-forward products for the home.
This agreement represents the third major Morris & Co. licensing deal signed in the USA, following agreements with Ruggable LLC, the washable rug company, and with US retailer Williams Sonoma for Morris & Co. tableware and cookware. It also marks a further step in development of the Company in the important US market, which is a key strategic focus for the business.
The five-year agreement, covering the USA and Canada, is exclusive for the production of Morris & Co. bedlinen, bath linen and tote bags and is non-exclusive for a broad range of Morris & Co. products including cushions, ready-made curtains, bathroom accessories, doormats, kitchen mats, chairs, benches and poufs.
The first products from the agreement will be launched during the coming months for Spring/Summer 2024. Accelerated licensing income of £0.7 million will be recognised by the Group in the current financial year to reflect the minimum guaranteed revenues in the agreement.
ENVOGUE's customer base comprises premium stores and online retailers including Macy's, Bloomingdale's, Saks Fifth Avenue and Perigold."
I've been looking at Sanderson Design (LON:SDG) for ages and never quite got round to buying them worrying about how their UK sales would hold up while fewer houses are being built. I expect this problem to rectify over time though. However, I did pick up in the press that former chancellor Osbourne's family business (a posh wall paper company) is going through bad times and has ceased to be profitable: George Osborne’s family firm breaches Covid loan terms as profits slump 98% | George Osborne | The Guardian
Jim
Haven't got the figures off the top of my head, but I expect this would be the situation Sanderson Design (LON:SDG) would find themselves in (breakeven and/or loss-making) if it wasn't for the licensing income.
Sad to loose Belvoir (LON:BLV) , assuming the offer proceeds. I have held the shares for a long time.
Will miss Dorian and Louise, such a capable and likable management team. I note that the announcements include no comment from either, which I find somewhat unusual. The offer doesn't appear especially generous. It will be interesting to see the market reaction.
Damn annoying if it does proceed . Price far too low so hope shareholders reject.
It will be a great shame for the merged entity to lose Dorian and Louise who I have met several times pre covid at shareholder type event. Both very open personable characters. They may well resurface or have been in the property management business for year take the money and have a well earned retirement.
As it's an all share merger effectively Belvoir shareholders continue to get the upside with no additional risk, plus a small premium upfront. Well done to holders.
Brokers taking the chainsaw to Marks Electrical (LON:MRK) EPS forecasts. -51% this year, -36% next.
Looks way overvalued on these numbers. The CEO is taking the positives...."I also know from 37 years of trading that margin fluctuations are inevitable, they present us with an opportunity to learn" I'd expect the share price to be hammered.
No room at the inn for a short, unfortunately.
That's unfortunate, what to short it!
Want
So what has gone so quickly wrong, in the last few months, things were looking good only back in August.
Wolf, been waiting for you to post so I can thank you for flagging Nexteq (LON:NXQ) a couple of weeks ago. I like it, great value, great chart so I bought some. Very illiquid however, market makers have been caught out on this one and it took me about 12 trades just to build a small position but I think very limited downside from these levels and nice upside.
What a great forum this is, with quality investors sharing their best ideas, will be sure to pass on mine when I feel my ideas are ready to bloom...
No problem at all Burnt Onions. I'll keep posting anything that looks interesting if I see it.
My wife's thrilled I'm on here, she doesn't have to listen to me rant about breaks of the 10 day ema on volume surges any more :)
I'd also like to share my thanks, after the tip I researched it & couldn't find any reason why not to buy so I did
On the Property Franchise (LON:TPFG) / Belvoir (LON:BLV) transaction: TPFG benefits from the "merger" by obtaining BLV's financial services business with Michelle Brook taking a board seat. Belvoir is well ahead in this area and TPFG has been trying to catch up.
Both sets of shareholders obtain a potential benefit from costs savings (elimination of one set of listings costs and of duplicate functions - they only need one finance function, one set of documentation etc.) but against this there is execution risk.
TPFG is paying a small theoretical premium (277p vs. mid of 256p) that could evaporate on share price moves.
Overall, this looks a very good deal for TPFG as it catches up in financial services, but BLV shareholders (I am one) would be better off if the deal flushed out a cash bidder willing to pay a decent (50-60%) premium. Looking at the irrevocables section, TPFG does not yet have the votes from BLV shareholders.
The announcement also includes trading statements: "comfortably in line" for BLV and "in line" for TPFG.
My morning smallcap tweet: No sparks from Marks
Belvoir (LON:BLV) Property Franchise (LON:TPFG) Neometals (LON:NMT) Seeing Machines (LON:SEE) Hostelworld (LON:HSW) Distribution Finance Capital Holdings (LON:DFCH) Nightcap (LON:NGHT) Mercantile Ports & Logistics (LON:MPL) Light Science Technologies Holdings (LON:LST) Litigation Capital Management (LON:LIT) Sondrel (Holdings) (LON:SND) Totally (LON:TLY) Costain (LON:COST) Nichols (LON:NICL) 1Spatial (LON:SPA) Marks Electrical (LON:MRK) Cornerstone FS (LON:CSFS) Distil (LON:DIS), PROCOOK (LON:PROC), Sosandar (LON:SOS), GYM (LON:GYM), M Winkworth (LON:WINK)
◄Belvoir (BLV)► merger of equals with The Property Franchise Group. [SP=256.5 Cap=96m]. I hold.
◄The Property Franchise Group (TPFG)► see BLV [SP=344 Cap=111m]
◄Neometals (NMT)► 50% owned JV Primobius gets €18.8m order for a hydrometallurgical refinery. [SP=10.5 Cap=130m]
◄Seeing Machines (SEE)► appointment by three prominent commercial and bus manufacturers to supply Guardian Generation 3. No £££. [SP=5.35 Cap=222m]
◄Hostelworld (HSW)► guides FY-Dec rev up 32% and adj EBITDA c. €18.3m vs guidance of €17.5m-18m. [SP=133.5 Cap=165m]
◄Distribution Finance Capital (DFCH)► guides FY-Dex pretax £3m+, ahead of its prior expectations. [SP=23 Cap=40m]
◄Nightcap (NGHT)► Dec rev up 12% LFL and 66% total. H1 rev LFL still down 10%. In line? [SP=4.92 Cap=11m]
◄Mercantile Ports & Logistics (MPL)► serial disappointer warns FY-Dec rev c.£5.4m: "the recent acquisition of a port in the region had a short term impact on the trading volumes at Karanja in December...importers sought to clear stockpiles of existing supplies of coal". Debt restructuring talks taking longer than expected but remains confident of getting a facility with much more attractive terms. [SP=2.8 Cap=10m]
◄Light Science Technologies (LST)► guides FY-Nev rev up c.13% and pretax c.-£1.3m (-£2.72m). In line? Outlook: CEM division is seeing forward orders and stock levels return towards pre-pandemic levels. [SP=2.21 Cap=7m]
◄Litigation Capital Management (LIT)► successful resolution on an investment which forms part of LCM's Fund I portfolio. [SP=100 Cap=119m]
◄Sondrel (SND)► warns FY-Dec rev only c.£10m. £1.7m has slipped into Jan-Feb. Worsens cash crisis. [SP=6 Cap=5m]
◄Totally (TLY)► wins 1 year contract extension worth c.£13m PA. [SP=4.71 Cap=9m]
◄Costain (COST)► framework agreement with Northumbrian Water worth up to £670m over 12 years. Guides FY23 adj op profit in line. [SP=62.57 Cap=173m]
◄Nichols (NICL)► guides FY-Dec adj pretax slightly above current market expectations of £25.4m. Rev up 3.5%. [SP=1130 Cap=412m]
◄1Spatial (SPA)► three contract wins. [SP=51.43 Cap=57m]
◄Marks Electrical (MRK)► warns FY-Mar EBITDA only £5-6m as gross product margin did not increase to the levels expected. Rev £115-118m. [SP=91.5 Cap=96m]
◄Cornerstone FS (CSFS)► guides FY-Dec rev up 100%, ahead of market expectations, and adj EBITDA c. £1.4m+, significantly ahead. [SP=26.1 Cap=15m]
◄Distil (DIS)► tinpot spirit producer sees Q3 rev up 39%, gross profit up 23%. In line? [SP=0.53 Cap=5m]
In line: PROC, SOS, GYM, WINK
Thanks Mr C, always love your little updates to scan through first thing. Today's title gave me a fright though thinking you were talking about Marks and Spencer (LON:MKS) , Hopefully not a precursor for tomorrow's results.....
Belvoir (LON:BLV) , Property Franchise (LON:TPFG)
RECOMMENDED ALL-SHARE MERGER
OF
BELVOIR GROUP PLC
AND
THE PROPERTY FRANCHISE GROUP PLC
link
Belvoir (LON:BLV) it a takeover - but worded as a merger in order to justify the measly premium. Any takers?
Hi
I hold both Property Franchise (LON:TPFG) and Belvoir (LON:BLV) but they are held by different brokers. Would that cause any logitic problems do you know??
Steve
I think it's a shame that Dorian the CEO of Belvoir (LON:BLV) is not going to be on the board as I thought he had managed the company extremely well. Perhaps he is looking for a chance to go given he has been at the company for so long (and it looks like Property Franchise (LON:TPFG) are calling the shots).
I don't hold but have been a fan of Belvoir (LON:BLV) in the past.
I suspect this is a way for Dorian to retire comfortably. Perhaps surprised David Raggett of TPFG hasn't taken the chance too. He must be loving it too much. They all know each other very well and have been friendly rivals over the years.
Funny that it has ended like this. Remember Belvoir bid for TPFG 5 or 6 years ago? TPFG just laughed. Now it's come full circle. Thought they might go for M Winkworth (LON:WINK) rather than Belvoir (LON:BLV) . Certainly synergies are obvious here and CMA unlikely to be concerned as small share of market.
At the time of writing Belvoir (LON:BLV) is down over 2% and Property Franchise (LON:TPFG) down nearly 3%. Therefore the combined market cap is somwhat lower than the sum of the individual market caps before the announcement. It implies that the 'merger' would reduce shareholder value, or possibly ythat the market thinks it will not go ahead.
I hold both, and am not feeling richer!
Richard
I don't think Belvoir (LON:BLV) is down, Stocko say it is but my platform says it is up slightly. 258p to buy, 252.6 to sell. Stocko works on the last trade which is obviously a sale.
Property Franchise (LON:TPFG) however is down 4%.
Belvoir (LON:BLV) My big sadness with this ‘merger’ is the loss of Dorian and Louise
They have been excellent throughout at engaging with private investors, coming to investor events and always being accessible via email
I do hope they reemerge at another listed company as I would be happy to invest with them again
Agree with everything you've said Aston, fantastic operators and fantastic engagers with PI's. Will be missed!
Marks Electrical (LON:MRK) - Marks Electrical’s sales growth remained strong at 17.8% in Q3, and the company appears on track to match our full year expectations of an 18.7% increase following a strong 21.5% advance in the previous year. But as a company with a core strength in premium products, gross margins have come under pressure - customers’ buying patterns have been negatively impacted by the challenging trading environment. As a result, we cut our FY2024 EBITDA forecast from £8.0m to £5.0m (and reduce FY2025 expectations from £10.0m to £7.0m). Our new fair value is 100p / share. New report here: https://www.equitydevelopment....