Small Cap Value Report (Wed 10 July 2024) - LIO, SSPG, ZIG, IPX, MPAC, JDW. Brief: BDEV, GFTU, JSG, GYM, EQLS, HSW, WINK

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
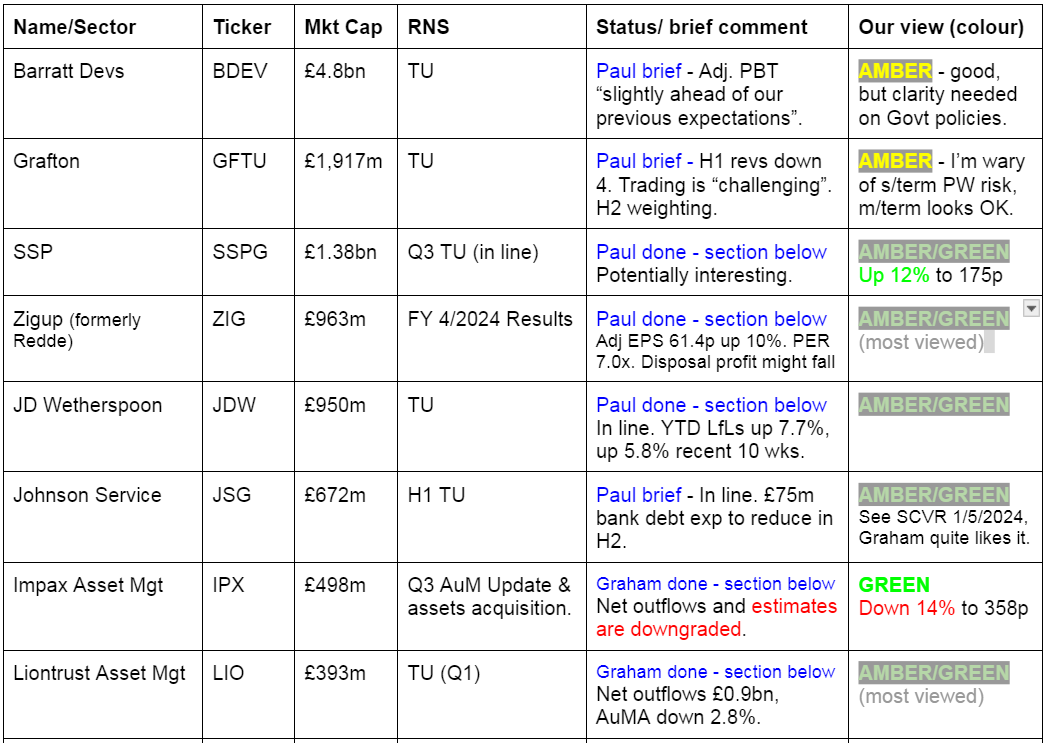
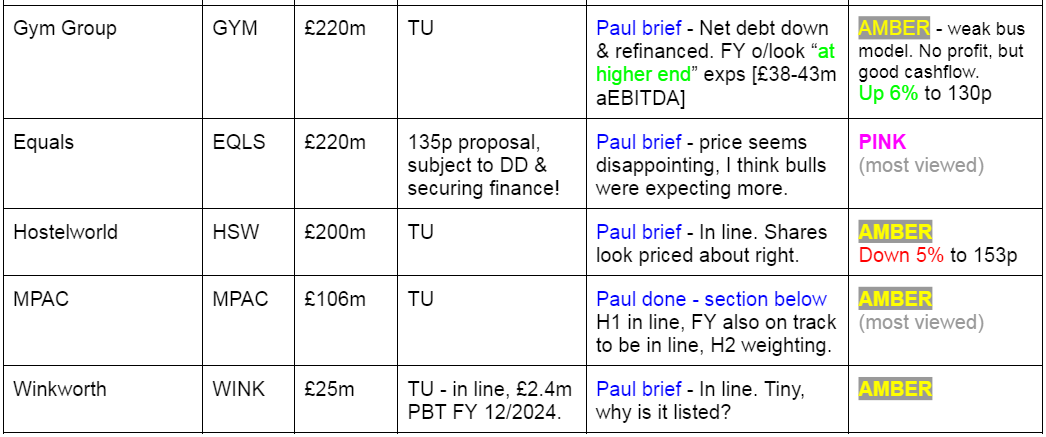
Summaries
Liontrust Asset Management (LON:LIO) - up 2% to 617.7p (£401m) - Trading Statement - Graham - AMBER/GREEN
This Q1 AuMA update shows net outflows of £0.9 billion, an improvement on Q4 and Q1 last year. The CEO sees positivity in the post-election political outlook and in macro conditions, which is reasonable, and LIO shares sit on a lowly valuation. Due to my previously expressed concerns, I remain AMBER/GREEN.
SSP (LON:SSPG) - up 11% to 173p (£1.38bn) - Q3 Trading Update - Paul - AMBER/GREEN
This came up on the top risers list, so I diverted my attention onto it. Attractive numbers, and a lowish PER, but the stretched balance sheet is unpleasant. Overall though, I could see this possibly beating (lowered) expectations as consumers recover. Worth a look.
ZIGUP (LON:ZIG) - up 1% to 430p (£973m) - FY 4/2024 Results - Paul - AMBER/GREEN
Strong results from this attractive value mid-cap. Generous divis & buybacks from its prodigious cashflows are the main attraction. Substantial balance sheet supports 84% of the market cap. However, with a third of profits coming from (potentially temporary?) profit on disposal, should we strip out that element, which would bring its valuation into reasonable rather than cheap? I like it still, but have moderated a notch from green to AMBER/GREEN, to allow for the nice recent bull run.
Impax Asset Management (LON:IPX) - down 11% to 370p (£491m) - Q3 AUM Update & Acquisition - Graham - GREEN
It’s a large reduction in AuM for Q3, the combination of significant outflows and negative market movements. Impax is expanding into fixed income which to me is a logical progression, and announces another deal today. I remain positive on value despite negative AUM and share price momentum.
Paul's Section:
SSP (LON:SSPG)
Up 11% to 173p (£1.38bn) - Q3 Trading Update - Paul - AMBER/GREEN
SSP Group plc, a leading operator of restaurants, bars, cafes and other food and beverage outlets in travel locations across 37 countries, issues a Trading Update covering the third quarter ("Q3") of its 2024 financial year (1 April to 30 June 2024) and the nine-month period ended 30 June 2024.
It says Q3 has seen continued good trading, due to increased demand for leisure travel.
Revenue growth in all regions globally in Q3 of +16% - this is broken down as +6% LfL, +5% “net gains” (I assume this means new site openings), and +5% “Acquisitions” (of companies as opposed to individual sites, I assume).
But it’s only in line with expectations, so no change to guidance.
UK - regulatory threat recedes, with the ORR deciding not to refer SSPG to the CMA (enough abbreviations there?!)
Guidance - these look attractive numbers for a £1.38bn market cap company - maybe these shares are cheap?
“Our planning assumptions are for revenue to be within the range of £3.4-£3.5bn, for underlying EBITDA to be within the range of £345-£375m and underlying operating profit to be within the range of £210-£235m, all stated on a pre-IFRS 16 basis and at constant currency based on average rates for FY23.”
Paul’s opinion - a nice bounce in share price today, hence me flagging it here. It looks to be a seasonal business, with a big H2 (April-Sept) weighting to profits. H1 adj operating profit was only £38m, but it says above £210-235m for FY 9/2024.
Balance sheet looks stretched to me, with negative NTAV of £(390)m, and too much interest-bearing debt, and heavy trade creditors on top.
Hence although the PER seems cheap, you have to adjust for the substantial debt, so maybe not quite as cheap as I initially thought.
Still, when many other hospitality companies are struggling to make any money at all, this one stands out as a success. Although the arguably captive customers eg at railway stations and high prices, do make me uneasy.
Divis have resumed, but only at about a third of pre-pandemic levels.
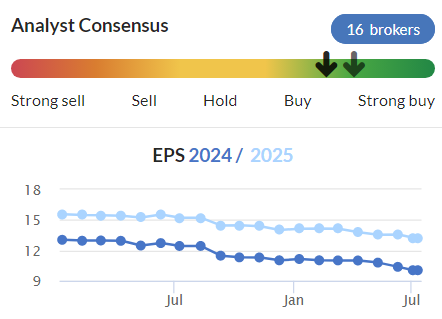
Share price has (surprisingly) not recovered from the pandemic plunge, but note share count has risen from c.550m pre-pandemic, to c.798m now. Also I see broker consensus forecasts have been in a gentle downward trend this year -
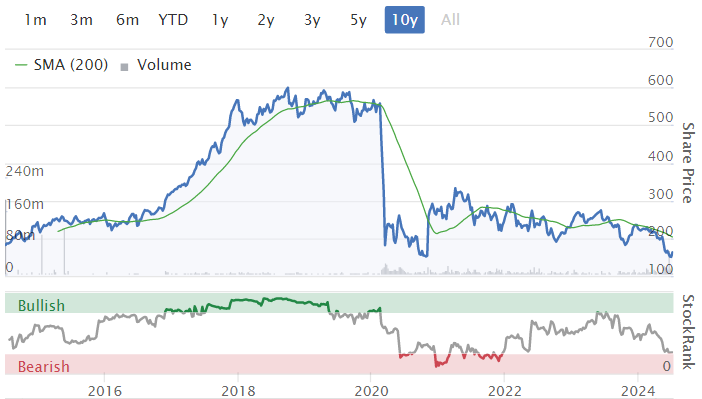
Ten-year chart below - irreparable damage caused by covid? Or an opportunity for it to recover? I’m not sure, it would need more work, but I’m leaning slightly towards a positive view, since it could see a beat against expectations possibly, as consumer real incomes have now returned to growth ? (and based on a good uplift in revenues announced today, but keeping forecasts unchanged - sometimes a precursor to an ahead of expectations update).
ZIGUP (LON:ZIG)
Up 1% to 430p (£973m) - FY 4/2024 Results - Paul - AMBER/GREEN
A daft new name, and a daft self-description too -
“ZIGUP plc (LSE:ZIG), the leading integrated mobility solutions platform providing services across the vehicle lifecycle, is pleased to announce its results for the full year ended 30 April 2024.”
This used to be called Redde Northgate (what was wrong with that name?!) after the two similar sized companies merged. It buys, then rents out vehicles. The old Northgate business was UK/Spain white van leasing. The Redde business was mainly providing courtesy cars on behalf of insurance companies, to no-fault car accident victims.
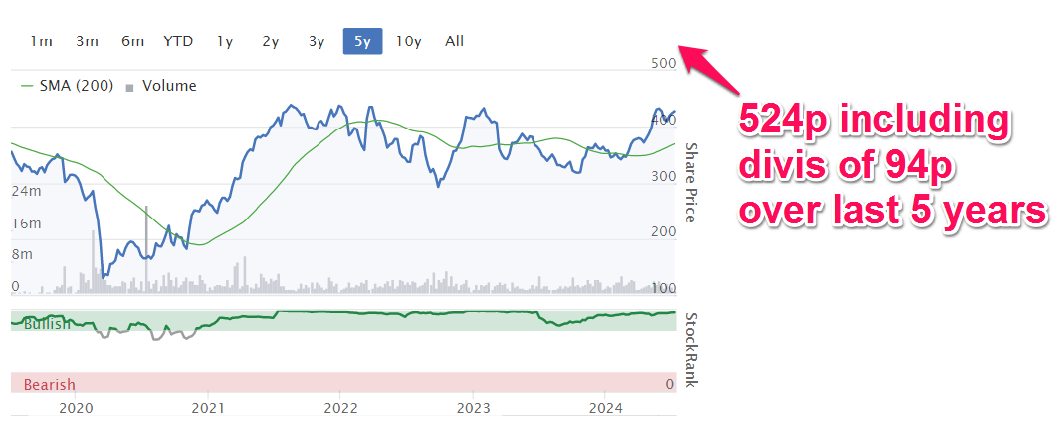
ZIG has a track record of being highly cash generative, which has enabled it to pay generous divis, and in recent years buybacks too (share count now c.226m, down from c.251m in 2022). So if you add up the divis, it’s paid out 93.9p in the last 5 years (from Aug 2019) to now. The share price has gone up from 355p in July 2019, to 430p now, so a 21% rise. Add in the 93.9p divis, and the total 5-year shareholder return has been +48% - not too shabby. Along the way you could have bought very much more cheaply during the pandemic, and it was an inspired purchase at the pandemic lows -
We are nearly always GREEN on this share, most recently -
26/9/2023 - 340p GREEN - “amazingly cheap” (that sounds like me!)
15/5/2024 - 420p GREEN - Graham - Good TU, upper end of forecast range.
Moving on to today’s FY 4/2024 results statement -
“Strong underlying results with positive pipeline, improving vehicle supply and growing footprint “
Highlights table shows some impressive numbers (I think the adjustments do seem reasonable) -
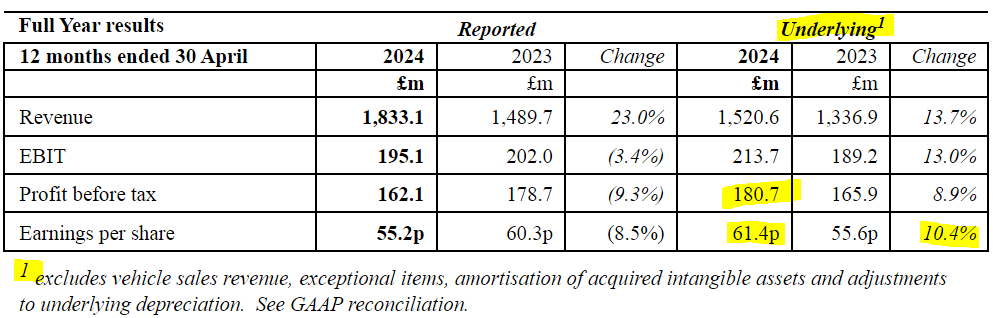
PER at 430p/share is a modest 7.0x
With low PER stocks, the key points to check are -
Is the balance sheet overloaded with debt? No, it’s absolutely fine. NTAV is very strong at £816m which is 84% of the market cap. The assets include a massive fleet of vehicles, which is worth far more than the borrowings that part-fund it.
Are profits sustainable? This is my key concern. Used vehicle values were heavily inflated during the pandemic, due to constrained supply, and car dealers have said values fell sharply in autumn 2023. Despite this, ZIG mentions another year of big profits on disposals -
“Disposal profits of £61.9m (2023: £51.5m); higher total sales volumes of 36,800 (2023: 18,200): LCV residual values moderating in line with our expectations, 7,000 cars and other non-fleet vehicles disposed at minimal PPUs”
(LCV is light commercial vehicles. PPU is profit per unit - note there’s a large table of definitions & abbreviations provided, helpfully).
So the key thing to research here is what’s likely to happen to secondhand vehicle values in future? Does ZIG benefit on an ongoing basis from profit on disposals (ie is the depreciation policy on vehicles conservative?), and does it make profits because it buys cheaply, in bulk? Or are these bumper disposal profits a one-off from the pandemic restricting new vehicle supply (hence temporarily boosting secondhand prices)? Now that supply is said to be normalising, then I presume ZIG’s profit on disposals would gradually fall, but no idea how much.
If we allow for the fact that £61.9m profit on disposals boosted overall adj PBT to £180.7m, that means disposals contributed 34% of total profits. Eliminate that, and EPS would drop to c.40p, pushing up the PER from 7.0x to 10.8x, which isn’t cheap any more - arguably that might be about the right price - as this sector doesn’t tend to command high valuations.
Cheap debt - whoever set up these 1.3% loan notes deserves a substantial bonus! An inspired move -
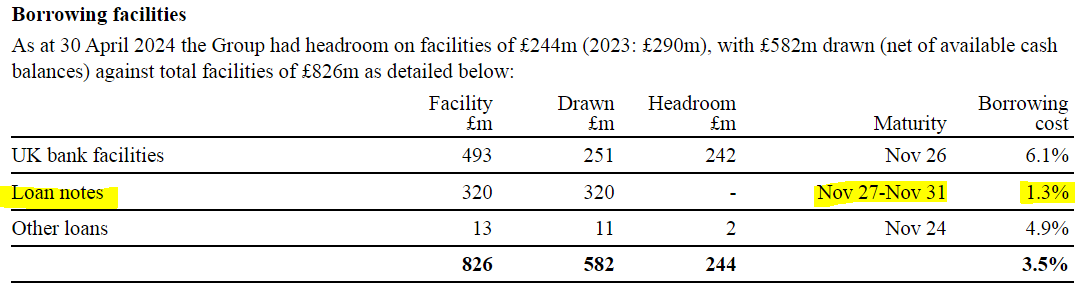
Remember debt is not a problem, and is only 41% of the value of the fleet - which are readily disposable assets.
Outlook - is too vague -
We have a healthy prospect pipeline across our businesses and demand for our services remains robust. LCV residual values have performed well as we had anticipated over the last few years and we expect they will moderate over the short term but remain elevated. We are confident that our proposition will continue to offer sustainable returns and that we will benefit from our differentiated position in the market, enabling the business to drive positive growth in underlying revenues, profitability and cashflow.
I can’t find anything about performance in the new financial year. There should be a comment about current trading vs market expectations, but that seems to be missing. All companies need to be strict about reporting this in every update, so it’s worrying what they duck out of saying this. Let me know if I’ve missed it, as I haven’t got time to read all the narrative, but have searched for “expectations” and “current” (trading), to no avail.
Dividends - and buybacks continue to be a key attraction of this share. The StockReport shows the yield at a very good 5.9%. Plus buybacks slowly enhance the share of the company you own, and drive up EPS and DPS.
Paul’s opinion - shares have had a good run up, and if I adjust out the disposal profits, now look possibly priced about right?
Main risks are probably used car/van prices lurching down again, as often (generally) when supply of anything has been restricted it can later over-compensate to the upside, creating a glut.
Also I recall years ago Redde shares halved in share price when a major customer was lost. So checking single client risk is important, although that’s a reduced risk since the Northgate merger, as it was more a Redde issue.
What else on the downside risks? A change in approach by insurance companies and regulators is something to consider.
Overall, I continue to like this share. Although if you look at the long-term share price, it hasn’t been particularly good, with the main attraction being an attractive (and growing) dividend yield.
Given all the above, I think it’s best to moderate a little from green to AMBER/GREEN - still positive, just not such an amazing bargain as it was, when you adjust out the (possibly unsustainable) profit on disposals.
Quickish Comments
MPAC (LON:MPAC)
Down 2% to 508p (£104m) - Trading Update [in line] - Paul - AMBER
Mpac Group plc, a global leader in high-speed packaging and automation solutions, issues a trading update ahead of the release of its unaudited results for the six months ended 30 June 2024.
There’s been a very strong bull run in MPAC shares in the last year, which largely escaped my notice, apart from here on 12/1/2024 with a very brief SCVR comment on an in line TU, flagging the positive order book & outlook comments, concluding: looks quite good. As it turns out my one line comment at 320p was not even halfway on a move up from 200p to >500p, so I should have given it more attention!
H1 update today is reassuring rather than price-moving -
“Trading in the first half was in line with the Board's expectations, with profits for the period substantially above the prior year and on track to meet market expectations for the full year.”
Other points - H2 weighting expected (prev flagged in May 2024 TU). Order intake same as H1 LY at £60m. Closing order book is £71m at June 2024. Good visibility over H2 revenues. H1 net debt £4.9m. Confident-sounding outlook comments about pipeline.
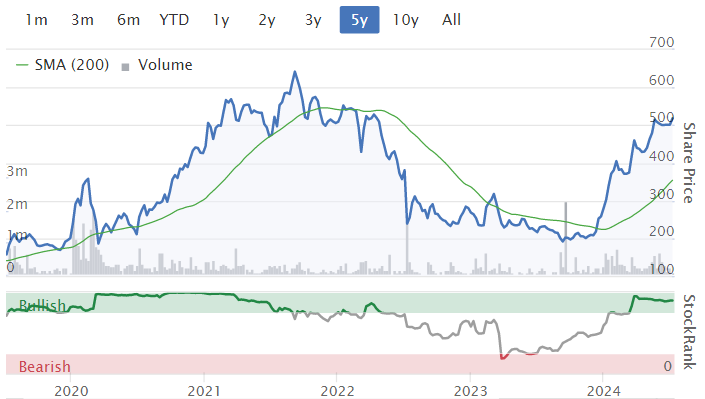
Paul’s view - the numbers here look good. Even after a big rise in share price, the fwd PER is only 12.4x. No divis since 2016 though. My only reservation with this company is that it has disappointed in the past - see the 5 year chart - due to lumpiness of orders.
The Dec 2023 balance sheet has £64m NAV, but half NAV is a pension surplus, and there’s £24m goodwill. Take those off, and there’s not much left. The pension scheme needs careful checking, as I recall it was previously a problem, which might have been resolved now, I’m not sure.
MPAC looks a good candidate for more detailed research into the products, competition, management, etc.
The bull run to date looks justified by the improved numbers. I’m happy with an AMBER view because the numbers have improved, which has already been reflected in a strong share price rise.
J D Wetherspoon (LON:JDW)
Down 1% to 761p (£941m) - Trading Update [in line] - Paul - AMBER/GREEN
I cooled a bit on the valuation of this cheap pubs chain, after an over-exuberant rally from 600p to 850p Oct 2023 to Jan 2024 took the PER up to about 20. However, it’s since eased down to 761p, whilst broker forecasts have been gently rising - taking the fwd PER down a more attractive 15.2x. At that level, I think it’s worth considering this unique value pubs group.
Today’s update contains some more detail, but the key point is this -
"The company continues to expect profits in the current financial year to be in line with market expectations."
Debt doesn’t worry me, as it is backed by plenty of freehold properties. A new 4-year facility “on attractive terms” was signed on 6/6/2024, further reassures.
Paul’s view - there could be more upside on forecasts I think, from a consumer recovery over the medium term. So this share seems moderately attractive to me again, and could be a reasonable performer over the next few years, so worth considering I’d say.
Graham’s Section:
Liontrust Asset Management (LON:LIO)
Up 2% to 617.7p (£401m) - Trading Statement - Graham - AMBER/GREEN
We have a Q1 update from this fund manager. I recently covered its full-year results (here) switching my stance to AMBER/GREEN. I am GREEN on nearly all fund managers, but have more concerns with LIO than I do with others in the sector.
Today’s update is as follows:
Q1 net outflows £0.9 billion (Q1 last year: net outflows £1.6 billion. Q4: net outflows £1.2 billion).
AuMA (assets under management and administration) £27 billion, down £0.8 billion or 2.8%.
CEO comment: talks positively about the political and macroeconomic outlook.
Graham’s view: it’s a smaller outflow than Q1 last year, but doesn’t do anything to change my view on this stock. I agree that the outlook for the sector should be positive, especially in the context of beaten-down fund manager valuations.
The LIO share price has taken a dive recently, after it seemed to gain positive momentum:
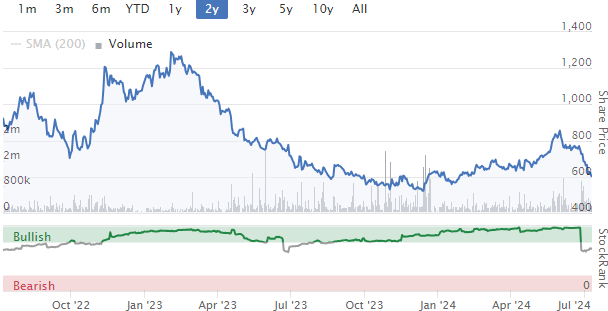
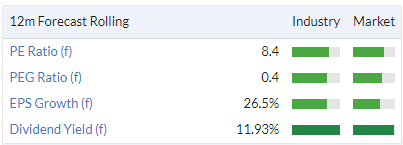
My view is unchanged: I see this as very cheap, but due to my concerns as expressed last time I prefer not to have an outright positive stance. With positive flows I could think about going GREEN again.
Impax Asset Management (LON:IPX)
Down 11% to 370p (£491m) - Q3 AUM Update & Acquisition - Graham - GREEN
Sentiment around this fund manager has also been poor recently:
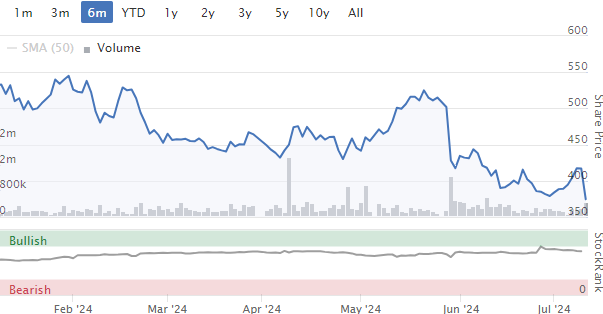
I took a look at it in May, when I thought its half-year report was robust (link).
Today we have both the Q3 AuM update and acquisition news.
AuM: net outflows £1.9 billion in Q3. For context, the net outflow across H1 was £2.7 billion. So things aren’t getting any better yet.
Market movements were also negative, so that AuM fell by 6.8% in just three months.
CEO comment is upbeat on prospects:
Aggregate net flows for the quarter to 30 June remained negative and dominated by our wholesale channel, despite a notable easing of outflows from key parts of our European distribution structure. Following a busy period for our direct sales team, our pipeline of potential new business is healthy.
Acquisition news
It’s another fixed income acquisition. As of the end of Q3, Impax only had £1.2 billion of fixed income AUM, or about 3% of total AuM. The vast majority of Impax funds are equity funds, and their strategy is to diversify beyond this asset class.
Today’s announced deal, which hasn’t closed yet, will add another c. $2.0bn (£1.6bn) of fixed income AuM.
The funds being acquired invest in “short-duration high yield and broad high yield ("HY") strategies”. They are “responsible” strategies, thereby aligning with the Impax ethos.
The seller is US-based SKY Harbor Capital Management.
This follows another recently announced deal which will acquire $0.5bn of fixed income AuM.
CEO comment on today’s acquisition announcement:
"This transaction marks an important milestone in our strategy to expand Impax's fixed income capabilities globally. Both founder-led specialist asset managers, SKY Harbor and Impax share a strong business culture and a complementary investment approach. The addition of SKY Harbor's deep expertise and track record in high yield investing and its team's experience in client service fit well with those brought by the Absalon team and will be a significant asset as we broaden our fixed income offering…
Graham’s view
When it comes to the acquisition, I think it makes perfect sense for Impax to expand its fixed income offering: fixed income is the much bigger asset class, and it often requires greater expertise to access. Bringing the Impax approach to fixed income is, for me, a logical next step.
No price is given for the deal, but there is little doubt that Impax can afford it. Checking the estimates from Paul Bryant at Equity Development this morning, I see that his new net cash estimate for FY Sep 2025 is £90.4m (previously: £111m).
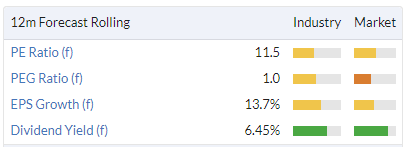
Speaking of those estimates, the new net income forecast for the current year (FY Sep 2024) is £38.2m (previously £39.4m). At the latest share price, and given today’s downgrades, I estimate that the PER is about 12.5x.
With AuM of £36.9 billion, plus another c. £3.1 billion coming from the acquisitions, Impax has about £40 billion in pro forma AuM. So for every £1 invested in the stock, you get about £81 of AuM. This is a deeply distressed valuation by historic standards (i.e. compared to before the current bearish era in UK equity flows).
This is a fund manager with a strong position in its niche. It has, I believe, long-term growth prospects that are above-average in the sector. So I’m happy to remain positive at this valuation, although momentum is currently against me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

116 comments
I'd recommend.... all the shares I hold of course :)
I keep a public list of all my holdings - this is the latest (from end of May - have not had time to do a June writeup, and it will likely be a Jun & Jul writeup).
Since end of May, I've topped up Time Finance (LON:TIME) after the good results (but maybe not a good buy anymore, since its gone from 40p to 51p now). Have partially sold PayPoint (LON:PAY) after a solid set of results.
And started building a new position... can't reveal yet as it is very illiquid, and I'm still trying to buy a few more bobs...
Also about to add a new position later today. This one I will be writing an in-depth article up on it once done, as I think I can buy whatever I need by the end of today.
So far, my portfolio is up +7% YTD to yesterday. Just slightly beating the FTSE All-Share. Not as much as in the prior 3 years, but I'll take 4 years in a row of consistently beating the FTSE... even if some years are slightly leaner than others!
GYM (LON:GYM)
Great point Abtan ref the size and probable non repeating nature of the initial one of structural work - very sensible to argue these costs will likely mostly not repeat so if w/off over original lease term will almost certainly make the profits look lower than can be achieved if we look longer term.
The great thing about this debate is that if this company is starting to make good real cash flow as it matures the debate should eventually be settled in the numbers - at some point it will become self evident that the cash flow really picks up speed - at a similar time depreciation charges will reduce (reducing balance) and I would expect that the overall % of sites not up to full speed yet members will drop - do sales should get a boost too. If this is happening then the numbers should reflect that and start to slap us in the face that they are good - in that respect bring on the 6 monthly results so we can get that detail - imho a drop in debt if 12 mill looks amazing but we have no idea if this is due to sustainable free cash flow or is due to other reasons eg temporary working capital swings
Re GYM (LON:GYM) it’s my understanding that they usually take on sites that are as near as possible empty shells…so fit out costs are predominantly equipment…and that equipment won’t generally last more than 10 years without looking/feeling knackered/old tech so the cadence of major Capex will track equipment lifecycle rather than 10 year lease expiration…I’ve no idea the extent to which this is smoothed by the available of landlord incentives tho…if it generally is then lease renewals may even see an uplift in run rate costs
GYM (LON:GYM)
Surely even if you have an empty shell you will need to do lots of one of building type work to get layout right and get all the plumbing and electricals up to level that is fit for purpose. I have to presume the fact its quoted as being 70% of initial spend per Abtans post means the initial costs are anything other than mostly equipment! and Abtan is therfore 100% right that the original costs are a decent % very one off in nature.
GYM (LON:GYM) …you’re correct…my suppositions were way off …
GYM (LON:GYM)
i think these chunky amounts do partly perhaps explain the polar opposite views here - completely ignore these costs and the business looks much better than it does with these costs factored in. If you are presuming that these costs will repeat and cant be amortised over period past the end of the lease then you probably are being too harsh on teh company - also though we cant ignore that these are real costs and do need to accounted fro when we work out whether the business can make it long term - over say the next 100 years facts are they will likely move many sites and have those cost perhaps repeated every 30 years on average or so per site. So perpahs a middle ground here is to take some longer reasonable timframe with these startup costs - i dont know maybe perhaps maybe manually adjust that depreciation so its over double of treble the tiomframe if its likely they wont really want to be changing sites if they can help it - seems clear to me they need to stay put at end of lease if they want to enusre that initial capital cost is minimised long term. In some respects with the £250 mill preiviously spent on leasehold imrpovements has been paid fro already so the depreciation that comes along can imho partly be ignored if its not likely to be repeated - only partly as they may have to moive sites soemtimes and have a new similar cost. Note these capital costs are nealy 50% depreciated already - so it does seem like the amounts aer getting written off pretty quickly - and that to me is probably the mising bit of the picture as to why they are still loss making. - if its reducing balnce stuff though and they have taken most of the hit profits should perk up if those charges are reducing by 50% plus once assets are worth half what they were.
I am still fence sitting here but keen to look at the figures to see how it all pans out.
GYM (LON:GYM)
There have been a number of comments today on GYM (LON:GYM) so I thought I'd throw in my own thoughts.
As far as I can see the underlying business was cash generative in FY23.
Below are my own workings:
The above isn't totally accurate as:
Overall though I see a cash generative business, with 4.3% of revenues being spent on maintenance capex in FY23.
The company has stated that they expect this figure to be 6% on average each year, which would have taken my £17.4m Adjusted Free Cash Flow figure down to around £14m...not exciting relative to the current market cap (£235m), but still decent and certainly not negative.
---
However, I chose not to invest when the market cap was lower because:
If at least the former of these starts coming down rapidly I would be more interested in getting involved.
---
The company claims that mature gyms:
Source: https://www.tggplc.com/media/1...
----
The business currently has 220 sites. If each of these was able to generate £250k per year on average, that's £55m of profit.
If I prudently assume £25m of Central Office costs (it was £21.4m in FY23) then PBT would be £30m.
£30m of largely recurring PBT doesn't look too bad versus the current £235m market cap, although of course a lot can change whilst sites get to maturity.
---
Perhaps I've missed something in my analysis above, but after reviewing everything again it certainly seems like there could be long term value here.
The obvious question is why do the accounts show a loss of £8.4 million?
GYM (LON:GYM) excellent analysis Abtan and very clearly presented.
I have a lot of respect for the opinions of the Gym dissenters but going to stick to my guns here, I think it’s a quality durable business with very sticky repeating revenues.
And you can see why expansion makes sense with such hefty head office costs equally as an owner one could stop expanding, halve head office costs and clear debt in rapid time and then enjoy the cash flow.
Anyway I’m happy with it, and thanks for your input, top quality and very useful.
Hi abtan,
Thanks for your analysis. Yes GYM generates cash. However, the key point is that this is only if you totally ignore the huge capex that was previously spent to set up all these gyms. The depreciation charge is designed to account for this. Hence once we take into account the depreciation charge, it doesn't make any profit at all.
Depreciation of physical capex (ie ignoring lease entries) is £24m pa charge (cashflow statement in Annual Report, for 2023).
As the gyms get older, then I would also expect maintenance capex to rise.
If I was trying to persuade people of the bull case for GYM, I would say something like this - the historical figures are lousy, and it has accumulated retained losses of £(102)m since it started, blowing just over half of the £190m total equity raised (share premium account in reserves section of balance sheet). However, at nearly 100% gross margins, if and when decent subscriber revenue growth kicks in, then the profit numbers could be transformed.
Looking at the balance sheet (note 14, 2023 Annual Report), the original cost of all its fixed assets is an astonishing £365.5m, which are now partly depreciated -
Think about that. Shareholders have funded £365.5m of capex to create a business that generates £17m free cashflow by your figures. That doesn't strike me as a very good return!
I don't care what figures GYM itself says it generates on ROCE, etc. I can see for myself that it's generating a very poor return from huge previous capex. That's why it's unprofitable, and doesn't pay divis.
LfL revenue growth of +9% in H1 was really good though, and at 100% margin, that could significantly improve the future numbers. So I'm not totally negative on GYM, and moved it up from red to AMBER today, due to the good LfL revenue growth, and the reduced bank debt & refinanced facility, which greatly reduce risk.
Interesting discussion today, I'm enjoying this, thanks to everyone who contributed!
Regards, Paul.
GYM (LON:GYM) great discussion today…one question I’d ask is whether they are going to be able to lease new sites in appropriate locations on the highly advantageous terms they were offered in ~recent years…my local gym allegedly got a 3 year rent free plus fit out contribution….on a 10 year lease…its now surrounded by new developments at far higher passing rents..& needs to renew their lease in ~3 years time.
GYM (LON:GYM)
That’s the way of the world with signing leases though - landlords hardly ever offer sitting tenants anything as they know most won’t leave - it’s fairly common to get incentives to move in - note gym will have to spread the freebies over the term if the lease so the numbers should not really be pimped and and discount as a % of lease term is probably neither here nor there - gym doesn’t have to take on any new sites it doesn’t want to do there should always be done locations where there are decent desks going - as a well known brand too landlords will love the certainty that gym will bring ref being around long term - ie they should never struggle to get good value and discounts are just part of the overall package that is a reasonable rent the landlord is happy with
I agree Paul, it has been an interesting, healthy debate, good engagement from everyone
GYM (LON:GYM)
Hi Paul
Thanks for continuing the discussion.
I was actually going to respond to Epitychia's response and mention the start-up capex, but you beat me to it.
I actually agree with nearly everything you wrote.
Here are some further thoughts:
Start-up Capex
Agreed on your points around depreciation here and needing to account for it. I think where my view differs is on how much of this capex is repeatable.
Here is a split of the £1.4m currently spent on opening a new gym.
I guess the question is whether the £980k "Building Works and Related Costs" is a fundamentally one-off cost, or if it repeats every 15 years (which is the depreciation schedule for this cost.)
If it's the former (which I believe it is) then there's a long runway of cash generation for each individual gym which stay open after 15 years.
I think it's important to mention the group only opened it's first branch (Hounslow) in 2008 (i.e. 16 years ago) and it which underwent a refit in 2023.
I can't imagine they spent another £980k doing this refit
Maintenance Capex
You said:
"As the gyms get older, then I would also expect maintenance capex to rise."
Agreed. And the company agrees too.
The £50k depreciation charge per year over 15 years accounts for an increase after year 10 (£30k pa ---> £50k pa) and a £300k refresh between years 8 and 12.
PPE
You mentioned that £365.5m has been spent on PPE since inception.
It's an interesting figure, but I wish it was possible to separate out initial/maintenance capex - that would be much more meaningful to our discussion.
Although one number that stood out was the £94m spent on Gym Equipment - I guess I was expecting this to be the largest figure.
I think this supports my belief that most maintenance capex is much lower than the start-up expenditure.
---
CASH GENERATION & THE PAST
A part of me doesn't really care what has been spent in the past.
I'm interested in how much cash the company generates now vs its current valuation.
I said that 220 gyms at full maturity could generate £55m of profit, or £30m after central costs are accounted for.
Would I buy a company worth £235m that gives me a relatively recurring profit of £30m per year?
Probably.
But sadly the debt is just too high right now and I want to see it come down.
And perhaps more importantly I don't have £235m.
Thanks again for continuing the discussion.
A
Perfect analysis Abtan, agree with all of that.
J D Wetherspoon (LON:JDW)
I second Pauls comments today
i like what wetherspoons are doing at present - clearly bigger pubs are best for their business model (volume) so getting rid of the smaller stuff that is probably more hassle than its worth makes sense - and then ensure you get the best out of the larger pubs they have. Take a look at the plans for the Mile castle in the toon which they are turning into a super spoons.
https://www.ladbible.com/lifes...
So although the appear to be only ticking over at present i think the future is bright here.
With the app its just so easy to turn up in any spoons and get your order in and sit back and it comes to you if you want to be lazy (going to bar can be quicker) - i was in glasgow for foo fighters and it was hard to get served at bar it was that choka but app order came pretty quickly - place was rammed too alot of the time when the sun came out.
bargain price of £3.20 for my full english and £1.60 for two hot chocolates on sunday morning in rotherham so they still have the value proposition that will get teh punters in - aint bought any spons shares since pre covid might be tempted to top up though if price comes down much more.
Any AIM under the radar top tips ?
I’ll be moving out of Equals in the next months freeing up a significant holding , probably do it in stages .
So need to start to think what to do with the cash that is released .
Apart from a few current holdings that I’ll maybe top up on (Wynnstay, Croma) pretty much nothing inspiring me .
Needs to be IHT qualifying in this case and looking for something that will Hold for 3-5 years so plenty of time
Hi Planetx,
I've recently been looking at/ taking positions in some nano/smallcap idea's, some tiny, some larger:
BBSN, CRDL, WPS, CTA, AEO, STG, CGEO, WATR, PEN, TON. Most (not all) are AIM, many will be IHT +ve.
Most are toeholds & I will increase on +ve news, or exit if things look shaky.
Fevertree Drinks (LON:FEVR)
Not a top tip as such but
Its not cheap based on current profits but fevertree is perhaps a decent shout. They have had cost issues the last few years , its not exactly easy or cheap trying to conquer america as you grow scale. balance sheet is rock solid and at some stage its perfect takeover candidate for one of the big boys or gals or other in then drinks industry. then again maybe it will bumble along doing very little as has been the case for the last couple of years. they are i am pretty sure number 1 tonic brand in the us as well as uk now. ref profits they seem to be trending back upwards too after issues they have had.
Hi planetX
Aim listed but unsure of the IHT aspect, but Van Elle Holdings (LON:VANL) looks too cheap. Cash positive, has recently developed interests in the water and energy sectors and will be one of the initial beneficiaries from any improvement in house building as it will be one of the first on site. Currently trading in line; I would also mention that Rockwood Strategic (LON:RKW) have a sizeable holding.
"Van Elle operates through three divisions: General Piling, Specialist Piling and Rail, and Ground Engineering Services; and is focused on diverse end markets including residential and housing, infrastructure and regional construction - across which the Group has completed more than 20,000 projects over the last 40 years. The Company acquired ScrewFast Foundations Limited in April 2021 and Rock & Alluvium Limited in November 2023."
From the trading update on 22 May.
Outlook
"Both the housing and infrastructure sectors are widely expected to recover in the near term, and whilst timing remains uncertain, the Group will benefit from increased volumes. Van Elle is also developing a strong position in the water and energy sectors, which are both expected to contribute materially to activity levels from FY26 and beyond.
The Group has been awarded new frameworks in Q4 FY24 including in Network Rail's CP7 civils and geotechnical programme, with the Coal Authority for national ground investigation services and for key customers in the energy sector. The Group will commence its first major energy transmission scheme in FY25 with further tender opportunities expected this year and is designing modular foundation solutions for several customers ahead of AMP8 in the water sector.
The Board remains conservative on the timing of a full recovery in the housing sector, but the Group is seeing early signs of progress with order intake and rig utilisation increasing over the last three months.
In Canada, the Group has continued to develop a strong position ahead of significant rail infrastructure opportunities including its appointment as a strategic partner within the Toronto region expansion programme.
The Group has identified a range of further cost saving measures, consisting of headcount reductions and efficiency projects, with targeted annualised savings in excess of £1m."
I bought a medium sized holding between 36p and 37p, so slightly adrift at the moment.
As always just my view.
Agree rmillaree- surpise the price did not go up after the Britvic takeover. (I hold FEVR)
I've recently take an position in S4 Capital (LON:SFOR) on the basis that it looks oversold (however it does have large debt). S4 Capital (LON:SFOR) has crossed the 50 day MA on the 2nd of July, when 2 directors bought a total of £500k and has risen from a low of 42p. This had reached a high of 870p during the last bull run in 2021, so the hope is that it won't stay at these levels and the price will improve in the next year or two.
How about Michelmersh Brick Holdings (LON:MBH) or Brickability (LON:BRCK) both should benefit from Labour's building policy.
Capita (LON:CPI)
Given everyone here (myself included) is long, the Capita chat is suspiciously quiet...
Did we all buy at 13.75p on the back of Staveley's interview last week, make a quick 50% and are now quietly deliberating what to do?
Speaking for myself I will probably start meekly selling a few at 20p and pretend I didn't piggy back that idea and that I had always been meaning to look at Capita ...........haha!
Joking aside thank you very much Messrs Hill/Staveley, the CPI trade was a real bonus.
I've been thinking about that, I'm going to wait for the 100% on this one, it might just come round quicker now. Capita (LON:CPI) I bought at 16p so may need to wait a bit longer
I have to be a bit careful.
I watched the cmd in June and opened a long sb position at ~13.9 later that day. and was utterly gobsmacked to be stopped out at ~18.7 this week.
It amounted to a v.v. nice meal out - not a new (cheap) car.
I think I said it before, I don't see any catalyst for a big change in the capita sp until they announce they are cashflow positive.
The new broom (Adolfo) is not English. This is a good thing. A *lot* of the employees and the business that is growing is overseas. Previous mgts were a bit uk centric. He is doing simple things that shouldve been done years ago.
... and some things that imo are a mistake. He is busy pushing GenAI. If you have access to it (copilot or gemini or lama or openai) ask a question and ask again the next day. You will probably get a slightly different answer. In any regulated or quality conscious environment that is (to me) an automatic red flag.
What would you think if you asked for a bank balance on two days and got two different answers when there have been no transactions?
All in all I am fairly positive on cpi ... but not yet.
ZIGUP (LON:ZIG) I own this share but I hate the new name
In other news
Peter Zeihan on the uk election and the country's future
Be aware he is v. much us based and there are not many countries he is 'long' on outside us/canada/Mexico and maybe vietnam/thailand/singapore
The picture of the uk he paints is a bit wonky.
But he has a point. When the trend is towards deglobalisation small countries need to be part of a trading bloc. We left the eu. We are a long way from Asia. nafta is the only place left. What to do.
It’s a shame we didn’t get Graham’s thoughts on MPAC (LON:MPAC) latest numbers. But to me it’s seem, profits are ahead of expectations beating forecasts H1 24 v H1 23, temporary net debt based on working capital expansion - which will unwind in H2 2024. With successful semi-solid battery production trials under Norwegian firm, Freyr, now moving into the commercial stage, it does strike as a bit odd that there is no mention of the battery production / clean energy part in today’s update? Something afoot maybe.
Thank you Paul! Much appreciated.
It’s a shame we didn’t get Graham’s thoughts on MPAC latest numbers. But to me it’s seem, profits are ahead of expectations beating forecasts H1 24 v H1 23, temporary net debt based on working capital expansion - which will unwind in H2 2024. With successful semi-solid battery production trials under Norwegian firm, Freyr, now moving into the commercial stage, it does strike as a bit odd that there is no mention of the battery production / clean energy part in today’s update? Something afoot maybe.
On 18 April Graham ranked Rank (LON:RNK) as GREEN when it was trading at 72p
"This casino, bingo hall and website operator provides an in line update. Net gaming revenue is growing at single digits, though the UK bingo halls and Spanish websites are doing better than that. I remain hopeful of a return to prior profitability: it’s moving in the right direction."
Broker site suggests a fair value of 118p, and recent chart signals are bullish with a possible uptick to 100-107p. Based on this I have bought some today.
On Beach group (LON:OTB) looks like the sun is finally beginning to shine on this after all the discussion here earlier in the year.
Less certain is the fortunes of Hostelworld (LON:HSW) currently down 5% on H1 statement.
Bookings 10% higher, driven by increase in Asia demand, but only 1% revenue increase and booking value down 10%
Just got an email through from Mello, thought I'd share. Seems the discount is for everyone as its a generic code.
MelloMonday is coming up next Monday 15th. You can get 50% off the ticket with code MM50. I believe Paul Scott will be in one of the panel sessions.
Not a small cap, but thought worth a mention: just reading Direct Line Insurance (LON:DLG) capital market day update today, and the very first highlight of the presentation is one of Paul's favorites:
We are announcing a refreshed strategy with the objective of establishing DLG as the customers' insurer of choice and delivering profitable growth.
Liontrust Asset Management (LON:LIO) Hi Paul - Thanks your thoughts on them and share your scepticism - I have just done a comparison rating them against Jupiter Fund Management (LON:JUP) and Polar Capital Holdings (LON:POLR) which stands out a mile above the others. Mind you, even Polar whilst having some good Funds - also have a few 'dogs' in their house!
Liontrust Asset Management (LON:LIO) long term performance is very good across their range. Last 2 or 3 years haven’t been great for some of the funds but that’s par for the course in long term Asset Management which is the game they are in. They have a good reputation as a good manager too. If you think markets are turning then imo they are highly operationally geared to that recovery and better placed than many.
An 11.5% covered yield that they’ve signalled will continue for next couple of years at least.
I don’t share the same scepticism
Liontrust have a couple of good funds (UK equity, European cash flow) but their purchases of other teams (Kames fixed income, Neptune etc) have been an almost unmitigated disaster. Geffen left after a couple of years, David Roberts "retired" and a few months later was back at a new shop. Performance is of course somewhat cyclical in all asset managers, but management of the business isn't.
Jupiter is not much better (if at all). The Merian purchase has been a disaster. Ben Whitmore left, following Buxton out the door, although they did at least manage to recruit Alex Savvides.
Polar, by comparison, has little turnover, the managers they pick up seem to grow AUM pretty efficient (UK Value, EM Stars etc). Performance fees across the board obviously help as well. And the tech franchise is obviously top notch as well, although a risk there if there is a big AI correction of course. I think the partnership structure suits them and benefits them massively.
Liontrust might be operationally geared for a short term pick up but Polar at 12x and 8% divi seems a much safer long term play for me. (Disclosure: long Polar).
We use a lot of Liontrust funds at work and I do rate them highly as an investment manager. However, for them and their ilk, the trend is very much against them. A lot of IFA's (ourselves included) are increasingly allocating towards global equity trackers which means that no matter how good an investment manager is they are swimming against the tide.
Nothingventured. thanks for the interesting comment. i've been reading all of the Liontrust Asset Management (LON:LIO) comments and excellent write ups by the SCVR Gents. Alongside CautiousValue, You seem to have excellent knowledge of the "industry". Can I ask you, if you have the time, to expand on what you mean, your comments about the increased allocation in Global equity trackers ? and swimming against the tide , and why that strategy now for IFA's. I found this comments particularly interesting and was hoping you could flesh out this idea for the those of us with less "local knowledge" . i have a new LIO starter position which is now 20% under water and i can't make a decision on whether to swallow the lose or double down and wait for time and dividends to come up with a solution (FWIW i don't think looking at historical price trends it will drop below the 550p mark and if it does all bets are off).
many thanks
Nothingventured can confirm but generally a lot of IFAs etc are moving passive because of Consumer Duty rules meaning any "active" decisions have a high barrier to prove their worth, and buying passive eliminates that administration.
And - simply - for the last few years buying global passive (and therefore big positions in the 'Magnificent 7') has massively outperformed almost any active strategy. You could liken it to the 'no one got fired for buying IBM' mantra, and whether that continues to work is up for debate.
many thanks CautiousV
Absolutely agree - In the past I would not even consider a tracker - but nowadays they are often providing better returns at cheaper cost and so easy to compare on sites like HL
I know my view goes against the grain here, but I regard the UK investment managers as pretty much un-investable because of this (and the rise in smart beta ETFs.
Liontrust Asset Management (LON:LIO) Looking through the performance of their main funds I'd say performance looks pretty poor (with one or two exceptions). The main problem is their funds lack any sort of differentiation - you really need to stand out in this crowded space and not surprised they are seeing continued outflows. Compare with Polar Capital Holdings (LON:POLR) which I expect to announce strong Q2 inflows any time soon - slightly more expensive but think always well worth paying up for quality. The key difference is POLR grow organically or by selectively adding new teams, not by continual acquisitions and then not knowing what to do with the new purchases.
Good call on the AUM increase at @POLR - agree their strategy of adding PMs / teams and remunerating them well is much more value add to shareholders than spending enormous amounts to acquire AUM via acquisition.
Good morning everyone,
I would like to share my concerns and my thoughts, I would love to hear your opinions.
Firstly, without getting a lot into politics, I am concerned how the new government will affect the stock market (positive or negative). I am sorry but taxing the private schools in order to bring more (unqualified) teachers is not a solution- I am into education.
Secondly, more to the point, I am looking at Whitbread (LON:WTB) a lot lately and I am considering buying a large amount of shares. I always look at every report that I can find on the internet plus their website and I just think it is a great price now and I cannot see why it was 30% higher on January. I quite like the business and it has nearly £4B of freehold property with a 13PER and 3% yield.
Any thoughts will be greatly appreciated.
Angelos
Whitbread (LON:WTB) - Hi Angelos. See Pauls report of 20th June (discussions tab) As to the share price - its just one example of the mysteries of the Market which has become so much more volatile in recent years.
ref taxes we dont like crapola happens and then life goes on as normal - the conservaties have materially increased taxes for many the last 3-4 years mostly via stealth taxes. I personally have seen very little to make me worry about the competence of labour compared to the tories , and i have no favouritessem geenrally for either party i simply look at how each is delivering overall - must say there is much that all the main parties get wrong and right - so its easy to focus on your pet peeve and see that as an example of something that may not be the case - personally other than targetting niches i dont see them doing much different to the tories.
Vat has always pretty much been charged on most non essentials - like it or not private school fees are not an essential so whilst its a shame the vat exemption is gone (irt probably wont save much overall) - it it what it is. tories have similarly stitched up BTL investors and companies (6% corp tax increase) - plus by freezing allowances we have all list out. Trust me when i say private schools will still be around in 5 years and the vat blip will be distant memory then - i do understand some people wil no longer be able to afford private education - i do have sympathy when goalposts for anything are moved at short notice.
Ref whitbread £WTB - i fully fully agree this looks good value at present - looks like there has been small recent dip in earnings projections so that probably explains weak shareprice. At p/e of 13 it could get cheaper but if i had spaer funds it would be near then top of my shopping list to have a modest holding.
Just a sad day when education, once thought of as a good thing, becomes the subject of class war/envy. I think that is the main investment concern - where might this lead?
i kinda agree that it wont acheive much - from an unbiased point of view though i am finding it hard to justify the vat exemption on the basis that its not an essential servive - so personally i dont view it as class war or envy - simply that other taxpayers should not be expected to subsidise this optional activity by granting the vat exemption that has existed previously. In that regard compared to other optional life choices it will be more of an even footing. I wont argue it may be pointless exercise if it forces kids back to state eduction and the money raised is all consumed supporting them. I fully understand my viewpoint will not be popular or shared with many.
This will have far less impact than
- Gordon Brown pushing a higher proportion of school leavers to take degrees
- The coalition introducing student loans
- The Tories repurposing apprenticeships so they can cover MBAs
Although, they could soften the impact by starting at 10% rate and raise it to 20% in 5% steps
There is no VAT exemption anomaly for private schools, education does not attract VAT. If Labour do put VAT on private education there will then be an anomaly. Which will, obv, have precisely the opposite effect to it's intention and make private education even more elitist.
i was looking at it from a very basic point vat point of view - clearly the choice of a private school is completely discretionary - there are state alternatives.
so i am not comparing to other forms of education that may be vat exempt as they are not really the same - ie you may need that education to progress you career - for those items there is rarely a "free alternative provided" provided by the state
. in that regard its highly consistent with the basics of vat imho that necessary stuff is more likely to be not vatable and discretionary stuff vatable.
is education essential - yes - is private education essential where there is a free state alternatice - clearly not !
https://sovos.com/en-gb/blog/v...
Which will, obv, have precisely the opposite effect to it's intention and make private education even more elitist.
I wont argue with that fact - i am not really trying to defend the policy - i am just trying to say as an independent onlooker some of the more sensationalist commentry seems to ignore the fact its clealry not an essential expense to those that incur it ( from vat point of view - end of)
'education does not attract VAT.'
Sorry to be pedantic but it's not that simple. It never is with tax.
School, higher or further education provided for a charge
If school, higher or further education is being provided for a charge (see paragraph 3.1), the VAT consequences are for an eligible body (see section 4):
For a non-eligible body (see section 4) the education, and other goods and services provided, is taxed in the normal way.
https://www.gov.uk/guidance/va...
hope this helps,
cheers
Mark
Mark, to also be pedantic, I think your posting of the rules supports the lay statement that 'education is exempt' (and not just in UK, it is across Europe)
The rules you highlight simply illustrate that for eligible bodies, the provision of education and closely related activities are exempt. (read: school meals/school trips.)
The fact that other activities do attract VAT (i.e. if certain establishments have other profit making ventures) is almost irrelevant for the debate - the provision of education is exempt of VAT, the rules simply prevent the provision of education exempting other non-education activities that that specific establishment may also operate.
Edward
the provision of education is exempt of VAT
if one wants to be pedantic its clear (to me) that not all education is vat exempt as you suggest its much more likely to be exempt if the education is provided by an eligible body - much less so or less so if its a commercial entity charging for education - for commercial entities it can be pot luck (or detailed planning) as to whether exemption applies or not. I have seen nvq's in dog grooming fail the criteria for exemption on very spurious grounds . for example with private tuition if its a sole trader doing the work themselves its exempt - not so if they engage someone to do the work for them. anyone saying education is all exempt is plain wrong it aint the answer is that it might be and it might not!
the provision of education is exempt of VAT
Was I too pedantic, or not pedantic enough?
The way the rules are written - iike most tax rules - is that businesses (that charge for education) are liable for paying tax (VAT) in the normal way ......... unless they are eligible for an exemption. Which is very much not the same thing as 'the provision of education is exempt of VAT'?
I'm not arguing for or against. Just making the (pedantic) point that, like most tax rules, the basis is that tax is applied as normal unless you can show you are eligible for an exemption.
Education as a whole is not exempt. Otherwise I would be able to set up a business today teaching tax rules (very badly) on line and not pay VAT? That would only be the case if I could show I was eligible for an exemption. Which I might not?
Hope that's clear? I did say I was being pedantic?
cheers
Mark
Angelos - without wishing to sound cranky, this is a small cap forum. We try (sometimes unsuccessfully!) not to get into political debates and it is rarely appropriate to discuss large caps either. So on both counts my answer is 'no opinion'.
small caps forum
I accept this is a small cap forum but most investors here do hold large caps which they are free to share their views. Graham and Paul are clearly discussing the small caps but they also make very useful comments on large caps which I always find it interesting. Graham himself has mentioned so many times that he is a long term holder of many large caps though he does not discuss it here.
Those who do not like to discuss the large caps can simply ignore it and go to the next section.
Regarding Whitbread (LON:WTB), I suggest you do some of your own research and stay at a few. My last few stays and I have noticed staff being worked off their feet at several hotels. Now nobody minds stepping up when colleagues are on holiday or ill, but morale seems to be slipping if this is long term conditions of work, and consequently customer service falls. A friend stays much more often in Premier Inns, and says the standard is varying far too much by hotel. A recent visit to Germany where I often use Premier Inns, and this time I didn't choose any as other similar quality hotels were cheaper and bookable via hotels.com where I get perks (cashback from Quidco, hotel rewards, and the ability to pay real exchange rate in Sterling with my Amex card).
On the market side, I believe revenge travel has finished and we are back to normal leisure demand, and business travel is definitely lower than pre-Covid, thus overall I believe current market is soft. Fully agree with Paul they were very naughty with last press release saying were trading well in UK, that's not what the numbers showed! I am wary when CEO puts name to this nonsense, I want honest appraisal of performance, I am more likely to buy a share if they say trading is poor, but tell us what they are doing to improve.
I think Whitbread (LON:WTB) looks cheap, but have sold down my holdings to just 64 shares (where you get the free breakfast). I will likely go back in when I see some positive numbers, see some progress on customer service, and the share price graph goes into an upswing.
Possible first stirrings in the IPO market. Apparently Rose bank Industries is floating tomorrow. The management team are the former Melrose movers and shakers. Haven't seen a Prospectus and not really keen on new issues but thought I'd flag this as a possible starting gun for a livelier AIM market in H2.
According to the FT they intend to repeat the Acquire, Improve, Sell model used previously and will return to the market for further funds once the first acquisition is identified. Plan is to move all the way up to Main Market fairly quickly.
No recommendation but interested in views here.
Their track record at Melrose was pretty stunning - an article in the Times said that from launch in 2005 Melrose delivered a 3400% total return to shareholders. Also good news that they've chosen to stick with London, having explored other potential venues. Might be worth putting a bit of cash their way for the next venture.
Equals
Management are now coming s across as pretty weak and showing traits that are not good .
Any good leadership team who believed in their business would not waste their or their shareholders time with jokers who make such low bids re orally after such a long time
They should grow a pair and do what any good leader would do and exercise the only negotiating technique that works and exercise the “ability and willingness to walk away “ .
PUSU
Should be renamed JFO .
Really weak, end the process , get on with building a great business .
Yep agree re Equals (LON:EQLS) - not worth bothering with 135p cash offers. Cease talks and get on with building the business. Not an offer I would vote for. This has wasted too much time - grow a pair and walk away.
Edit : I would add it seems that they are considering accepting or at least putting to shareholders by the tone of the rns. If they are finalising financial dd and setting up the vehicle then I’d be surprised if that were going ahead without some nod from management that terms are getting close to acceptable.
Agreed entirely. The mishandling of the initial bid approach where FLT were forced to deny their intention to bid was careless if not incompetent. On face value I think the shares look good value and expected the bid to be higher, which makes me wonder what’s wrong with it.
Equals (LON:EQLS)
A bit of a flop of an announcement. I wonder if future growth in value, if sustainable, is effectively being given to the management under incentives under a mixture of a partial cash out and roll up of their equity interest into a new vehicle (typical private equity structure). That way possible current 'undervalue' accrues to management and Private Equity investors.
Trident
Possibly so and if that’s the case pretty shocking behaviour by management .
Sadly typical of AIM. Market management to prioritise self interest and reward over shareholder responsibility .
Need to watch out for this on AIM , big banana skin territory for small cap investors .
Equals (LON:EQLS) Along with planetx, I tend to agree with your assessment. There must be a sweetener for management in the deal which comes at the expense of shareholders. I have kept a reasonable amount of interest in the hope that the deal actually goes through – management seem to want that to happen from the tone of the RNS. But I’ve also trimmed a moderate 20% to fund a new purchase that reflects my waning interest in the long-term prospects of the name.
Equals (LON:EQLS)
The management need to convince some large institutional investors that this is a good deal for them, as the current management holdings seem relatively small, and on only a quick scan the options awards seem quite constrained (others may view differently), so the main tack would have to be that the current management are disillusioned with AIM - thus sowing the seeds of doubt about a company where the management have itchy feet.
Since 26 Feb Gulf Keystone Petroleum (LON:GKP) is up some 60% from 92p to 144p. A lot of chatter that the Company will be sold but all hinges on the pipeline being re opened.
Any views appreciated.I hold.
Commented many times on Gulf Keystone Petroleum (LON:GKP) still a great long term value opportunity with or without the reopening of the pipeline.
No need repeating same things-you can search and find all. Not aware of any buyout (just the usual X nonsense!).
All the best
MPAC (LON:MPAC) - H1 Trading Update: positive momentum continues
In a Trading Update for the six months to 30 June 2024, Mpac reports strong order intake of c.£60m and a closing first half order book of c.£71m. Consequently, the Group expects to post H1 24 revenue of c.£61m, significantly ahead year-on-year, being 16% above H1 23 (£52.8m).
A consequence of the strength of first half order intake is, as anticipated, an expansion of working capital, required to provision inventory for new projects. This is expected to unwind in the second half alongside the gathering pace of performance towards the close of the year. The estimated H1 revenue of c.£61m represents 50.8% of our FY24 target (£120m), whereas at the same stage in FY23 (£52.8m), H1 revenue represented 46.2% of the full year outcome (£114.2m).
Having raised both our estimates and fair value in March, we maintain our current outlook.
Despite a strong run, Mpac’s share price is currently trading at 5% below its one-year high and the outlook indicates that the Group continues to offer compelling value. Our Fair Value of 530p/share is indicative of a FY25 EV/EBITDA multiple of 7.1x and PE of 12.1x, respectively 33% and 28% below the market cap weighted average of a group of Mpac peers, on multiples of 10.6x EV/EBITDA and 16.9x PE.
Link to report: https://www.equitydevelopment....
MPAC (LON:MPAC) Nice update, although the lack of any mention of the Freyer battery line and how that might unfold in the outlook is probably the reason for the slight pull back today. Especially after they dedicated a whole RNS to tell holders it was now operational a few months back.
Direct Line Insurance (LON:DLG) now going on price comparision sites, will this add competition to the market and lower prices?
Hilarious considering their USP has always been that they’re not on PCWs! If you can’t beat them…
Ref Direct Line ( LON: DLG) Their latest USP seems to screw existing clients that have been with them for ages by more than doubling their car insurance premiums.... They are all at it I know and so I have bought the Polar Capital Global Insurance Fund; which is doing quite well. If you can't beat em, join em
I'm not surprised. After looking around for car insurance recently, I always check with DL as an option. They were about 35% more expensive than all the other main players. They will need to sharpen up their pricing if they want to win customers imo.
Don't think it will add much "liquidity" into the PCWs; its already very competitive, and Direct Line Insurance (LON:DLG) IMO are not the cheapest (which is how PCWs rank policies).
Might give an incremental revenue boost to the likes of MONY (LON:MONY) , but I doubt it will be meaningful.
Still, I think Direct Line is making good progress. Very "back to basics" type of decisions in the new strategy, which is what they need after years of getting operationally and commercially lazy. I think either Aegis will be back with a revised offer later this year, or PE will take them out between 250p and 300p, and pump in more investment to go aggressively after growth. Once the ship is righted and floating alright.
(I hold in the Boon Fund)
ZIGUP (LON:ZIG)
Results out today and well worth a read for anyone interested imho this is a very well run business with management doing a great job. The level of communication with regard to how the business is doing is pretty exceptional here - one needs to read the results to get the full picture of how the different units are performing - they seem to be firing on all cylinders at present. The prior year benefitted from a £45 mill boost from change in depreciation policy (neutral this year negative future years as prior boost unwinds - full yearly changes detailed) this was necessary change as vehicles were being depreciated below market value.
Tailwinds here are going away as vehicle prices normalise - they have had some easy money the last couple of years with high used prices providing chomping profit on disposals. Imho the materiality of thus benefit is dwindling somewhat
Buybacks are working well as one would expect with business that is delivering operationally - that’s nearly 10% of shares bought back with the obvious benefit for shareholders in that they own more of the company than they did
can’t really see any negatives here at present they have confident outlook
Debt has increased a bit but is still manageable and 65% on fixed rates. Hopefully if interest rates have peaked finance costs may also have peaked. Would like debt a bit lower medium term but I fully support companies progressive dividend and buyback and expansion plans - which mean for now debt up - note debt has not increased as % of fleet size
Oh and share price fully backed by tangible assets
ZIGUP (LON:ZIG) the current capital value of the fleet exceeds debt by almost 2 to 1 so have no issues with that nor interest costs, which in a leasing business are basically absolutely normal. (As in you have to fund the assets you subsequently lease - so the margin and the book value to loan is important not the absolute size of debt).
The main risk for this type of business is that vehicle residual values plummet but that is also mitigated by the type of vehicles they lease, which generally don’t see steep falls unless an economy really tanks.
Don’t understand why this trades on a PER of 7 that just looks ludicrously cheap to me with a 6%+ dividend to boot. Never seems to get re-rated though.
ZIGUP (LON:ZIG)
Don’t understand why this trades on a PER of 7 that just looks ludicrously cheap to me with a 6%+ dividend to boot. Never seems to get re-rated though.
I think this company doesnt get the credit for the good job they have done moprhing into necessary B2B supplier of choice ref transport needs.
I think graham summed it up how this company is seen by many last time out when he said
The range of services supplied here - vans and cars for hire, vehicle repair and accident claims management - would never scream to me that a high rating was justified. The phrase “Integrated mobility” used by the company seems to be an attempt to paint a picture of something more advanced or more complicated than it really is.
based on info below i think the integrated mobility tag is perectly aceptable bearing in mind they provide the following servoces
vehicle provision , fleet management services , ev transitition , repair and maintenance services , accident mangement and asociated legal stuff , recovery services , vehicle sales , traffic managment services and insurance mobility ,refrigerated transport services .
I suspect perhaps they are still benefitting from high residual values and the new "low depreciation rate" - albeit that gain is all in the past ref specific change. I ssuypect they may have to take a hit going the other way at some stage when depreciation rates normalise. Plenty in the tank though ref stuff they are doing behind the scenes.
Never seems to get re-rated though.
this has been one of my luckier shares i originally bought at 180p back in 2020 and topped up a little bit last year at an average of 335p. it looks like its back near post covid peaks so i think its done ok unless you bought near a peak - albeit its clearly not jumped out of the range where 450p seems to have up till now been the limit. It is currently one of my top 5 holdings so if anything i would probably look to sell a bit if it made some quick progress up to £6. with 6% dividend yield and moeny being spent on buyacks - we probably shoudlnt be expecting quick share price appreciation anyway.
ZIGUP (LON:ZIG). My confidence in management took a real knock when they changed the company name to the ludicrous ZIGUP. Why do otherwise seemingly sensible people waste time and shareholder cash in doing this sort of thing?
The name change didn't convince me, though it's certainly not worth getting hung up about. But the SP is up over 10% since they did it, and maybe that's what really matters?
Is it not possible to get a large tax rebate on "rebranding"?
Impax Asset Management (LON:IPX) - "AUM down in Q3, another fixed income acquisition" - link to new research: https://www.equitydevelopment....
AUM declined over Q3 of FY24 from £39.6bn on 31 Mar 24 to £36.9bn on 30 Jun 24, a fall of 6.8%. That offsets a 5.9% increase over H1, resulting in AUM being down 1.3% over the first 9 months of FY24. Net flows and market movements / investment performance were negative in the quarter, -£1.89bn and -£0.81bn respectively. Impax noted that outflows were dominated by its wholesale channel, with some clients continuing to rotate out of equities, although outflows eased in key parts of its European operations. It noted the direct sales team enjoyed a busy period and that its new business pipeline is healthy.
Impax has previously stated that it had a strategic focus on increasing the proportion of overall AUM in this asset class, and in turn decreasing the proportion of its AUM in small and mid-cap equities. In this vein, it has announced an agreement (subject to terms and conditions) to acquire the European assets (cUS$2bn AUM) of US-based SKY Harbor Capital Management, LLC (SKY Harbor). It looks to be a very good fit. SKY Harbor was an early adopter of the integration of sustainability risks and opportunities into its investment process and specialises in the management of fixed income corporate high yield securities and leveraged loans.
Our FY24 & FY25 forecasts reduce slightly on the lower AUM level at the end of Q3. But overall, this update has a small impact on longer-term projections and our fundamental value remains at 800p per share (c90% above the share price) and Impax’s PER of 13.7 looks undemanding.
I have purchased more IPX after the fall. Liontrust Asset Management (LON:LIO) bought in on the sale BNP Paribas stake in 2020- at a price of around 5.40p and hold 8.4%. IPX are making changes in its focus-and given the new Gov's focus on sustainability they would seem well placed to benefit from this.
GYM (LON:GYM)
Because you know I'm all about that cash flow, bout that cash flow, not profits....
In the last 6 months, Revenues up 12%, Memberships up 55,000, 4 new sites and another 6-8 scheduled for the year AND all the time reducing debt by £2m a month.
That's what you can do when you have a cash flow machine.
Potential tailwinds to take the share price higher are lower interest rates and increases in monthly membership fees which incredibly still average £20 pcm (I pay £33 at my local Pure Gym) otherwise more of the same please, just keep opening sites and build out that cash machine.
Hi Burnt Onions,
I think that's a rather rose-tinted view, but thanks for highlighting the cashflow.
This table from the FY 12/2023 results is interesting, and does indeed show good free cashflow -
HOWEVER, Gym's site fit-outs & all the equipment in them was not paid for by the tooth fairy! That's why I don't think the depreciation charges should be ignored completely, as these are expensive sites to set up.
Depreciation charges were £24m (2023) and £26m (2022), which offsets more than all the free cashflow for the 2 years combined above.
So GYM is effectively generating no overall return on its heavy investments. The StockReport shows ROCE at only 2.7%, and ROE at -6.4%. I appreciate those figures might improve as the effects of the pandemic diminish and growth returns.
By focusing on free cashflow, but ignoring huge capex, I feel it only shows a positive picture because of the timing - you've ignored the huge up-front cash outflows, and are just focusing on the subsequent inflows. Net them off, and it's about zero. How is that attractive?
Regards, Paul.
PS - note the improvement from 2022 to 2023 all comes from a favourable movement in working capital. Adjust that out, and cashflow was flat Y-on-Y.
GYM (LON:GYM)
Excellent comments both Paul and Burnt Onions - i have held this company in the dim and distand past - i do wander if it has possibly now finally perhaps got itself back on track here.
With only 4 sites being opened and 4 in fit out (237 sites) capital spend may have perhaps been lower than average. Heck i aint gonna knock £11.8 mil debt reduction in 6 months though - albeit i would totally reserve final judgement till i see a full set of number here so easy to pimp working capital as we all know.
to me the standout good news here is that revenue if up 12% and lfl revenue up 9%. T these are pretty standout numbers (perhaps their rate of expansion means this is to be expected if sites take time to reach maturity) and probably exactly what is needed to get profits closer to cashflow.
The good news here is that once initial fitout is done ongoing capex is probably manageable. To me the total sales and lfl sales increased look very impressive at face value. As the company grows sites that should provide gode extra clean cashflow for future expansion - i am preuming they can lick the lack of overlal profits issue !
I am still on the sidelines though and reserve ultimate judgement - this company is not even expected to deliver a profit this year at the bottom line - so i fully share Pauls reservations ref cashflow not being the only show in town - if you cant return a material profit over the long term you wont be able to deliver positive cashflow ! thats pretty basic.
Ramping up sales and lfl sales in particular though is exactly what they need to do - so perhaps the corner has been turned here ?
GYM (LON:GYM)
Hi Paul,
Those Stockopedia ROCE numbers can't be right, Liberum's range, depending on maturity of sites, is 20%-30%.
Liberum also have net cash inflows of £44m for 2024 of which £13m is earmarked for maintenance and the rest either going towards a blend of interest payments, debt reduction and new sites.
This explains why debt was reduced by £10m last year and another £12m so far this year while all the time opening up another 8 sites plus another 6-8 for later this year at a cost of circa £1.5m each.
Depreciation is an accounting tool of the devil! these sites are not going to depreciate away to no value, but would be good to ask the CFO what rates are applied and what is the average life expectancy of all this kit, in my opinion I bet it is a lot longer than expected.
PS>Really enjoying the new format and as always thank you for your coverage, it is excellent even if I don't agree with you on GYM ;)
GYM (LON:GYM)
To be fair to Paul he posted the exact figures per the cashflow statement and if you look at the £10 mill inflow last year its clear that half of that was "working capital" boost that went the other way the prior year. So ignoring working capital boost probably £5 mill. I dont doubt your figures might be right but we probably need the results here to pass full judgement - you would agree as we stand here unless we get an upgraded today the company is expected to post a loss this year ?
Ref cash inflows if what is being quoted is before any interest payments imho thats somewhat meaningless number - i would always like to see number after interest has been settled. I do understand we dont choose the way the data is presented and it shoudl be fairly easy to work out interest charged.
Its easy for company to be in sweet spot ref cashflow where ongoing maintenance is at lowpoint of cycle - not saying this is the case here. anyuway hopefully its all good positive news in thnatn ten sales bost is doing the job of movinmg both needles in the right direction. In that regard upgrade ref profits expectations would be helpful.
Woiuld you say lag in time for sites to get up to peak efficiency could be main reason why there is a lack of profits expected here? from dim and distant memory i think that may be the case. If thats the case and 20% of sites are not fully up to speed yet but will be in 3-4 years thats a big positive as that extra revenue boost should turn up without any real investment needing to be done ?
Hi rmillaree,
Yes I would agree with your comments re site maturity and just to add a bit more detail that's £5m bank interest this year falling to £4.5m next year and £13m maintenance capex rising to £14m next year.
Cash generation £44m this year and £48m next year.
So taking 2024 that would them give them £26m to spend on debt reduction and new sites.
So as debt goes down and cash flow goes up with all the self funded new sites the GYM story should get better and better and hopefully one day these cash flows will manifest themselves in large buy backs and/or dividends.
Just think like an owner, it's a durable business and should compound over time.
Onions thanks for the analysis, I think your numbers make sense.
I tend to look at the total liabilities (less deferred tax) and add back both current assets & right of use assets to give a liquid position less liabilities. Either way there isn’t a lot of debt there, it’s coming down, expansion capex is forecast to be low. Numbers, using your £26m figure equate to a decent cashflow yield.
Hi Burnt Onions,
The FCF picture is not as clear as the one you are describing and if you dig deep into the numbers on a Y to Y basis the FCF is minimal.
I agree 100% with Paul on GYM (LON:GYM).
All the best
GYM (LON:GYM)
perhaps Burnt Onions is more looking forward and we are looking at the past as thats the only numbers available - in that regard i think we really need to see the 6 monthly figures to see if there is a real genuine improvement in cashflow now compared to last year (on non mpimped up basis) perhaps even then perhaps a 6 month period might be over rosy if their capital / maint spend is backloaded.
Its a shame we dont have a nice equity development type note detailing the whole picture last year this year and next - similar to what is available for norcros. If anyone knows if there are profit / cashflow number pinned down for this year and or next link would be handy.
Don’t know which way you are looking at-:)
Personally not interested about past performance.
All the best
GYM (LON:GYM)
well i cant look at the current 6 months yet as we dont have the figures - i think its best to park discussion till they are avilable - i was agreeing with you that prior year cashflow wasnt brilliant if you adjust for working capital changes.
ROCE and FCF reported do not make sense.
Most of that is up front fees and a business that will always need huge amounts of CAPEX (for either new/old sites).
Paul is spot on regarding GYM (LON:GYM) and even better analysis given on Knights group (LON:KGH) the other day.
All the best.
Thanks yiannos1 :-)
It took us a while, but we seem to be getting on now, I'm pleased to see!
Regards, Paul.
Hi Burnt Onions,
"Just think like an owner, it's a durable business and should compound over time."
If you think like an owner at GYM (LON:GYM) then surely you wouldn't open any more new sites, because the company's track record shows that the new sites don't generate any return on investment.
That was the same problem with GYM pre-pandemic too.
What are the benefits of opening even more sites, when they already have 200+ and can't make an overall profit from those? There are few economies of scale I would suggest, since it's selling a service, not goods.
We haven't mentioned competition either. There are plenty of other low cost gym operators, so almost no barriers to entry.
We can't just dismiss depreciation charges either. They are worked out by companies, and policed by auditors, to as accurately as possible mimic the real lifespan of various categories of assets, and spread the cost over their useful lives.
The one positive is that LFL revenue growth was very good, all coming from price hikes I think, which might be harder to continue hiking.
We're not going to agree, I can tell, so I'll leave it there, but good luck with your investment!
Regards, Paul.
I’m not sure I understand the back and forth. My concern is if a business generates cash pre-growth capex - I.e. what income, as an owner, I could generate if the business decided not to grow, maintain current sites and just run it as is. I’m potentially quite happy if a business nets off to zero post-growth capex if it’s self-funding that growth and the business grows in value. I think GYM muddies the water a bit as I assume it hasn’t been able to self fund that growth - hence big debt pile - but now it’s cash generative, paying down the debt and growing modestly, why is it mildly offensive to suggest it’s a decent business?
Genuinely and humbly a bit confused. This convo is proving why PR is pushing the statement ‘profitable growth’ - because they’re having to prove to P&L focused investors who are scared by depreciation that the significant capex is behind them and they’re now running it for cash - or continue to reinvest the cash to grow, hence net income is 0 over the long run!
Burnt
GYM (LON:GYM) You can find the Depreciation rates by having a quick gander at the Annual Report - Marvellous things Annual Reports. I've extracted the key paragraph below:
Depreciation is calculated to write down the cost of the assets on a straight-line basis over the estimated useful lives as follows:
leasehold improvements over the shorter of the useful life and the term of the lease;
fixtures, fittings and equipment between three and ten years;
gym and other equipment between five and ten years; and
computer equipment three years
And Return on Invest Capital is 19%. See the KPIs page.
I pay £85 a month at my gym in Chiswick !!
lol
Chancellor Rachel Reeves will launch a national wealth fund with £7.3bn of state funding in a race to “unlock investment” in UK growth industries.
The Labour government announced it would align the UK Infrastructure Bank and the British Business Bank to create the new national wealth fund, with the hope of mobilising billions of pounds of private investment into clean energy, ports, heavy industry and manufacturing.
Reeves and business secretary Jonathan Reynolds instructed officials on Tuesday to start work immediately, with the fund to be established in “less than a week”, the Chancellor said.
https://www.cityam.com/chancel...
As long as they don't go spending it on blue sky hydrogen projects that's a great idea.
My morning smallcap tweet: Much Ado About Nothing
Equals (LON:EQLS) Personal group (LON:PGH) Amala Foods (LON:DISH) Quadrise (LON:QED) Feedback (LON:FDBK) GYM (LON:GYM) Cordel (LON:CRDL) Acuity RM (LON:ACRM), Hostelworld (LON:HSW), MPAC (LON:MPAC)
◄Equals (EQLS)► The mountain labours and brings forth a mouse. Reveals indicative offer after 8 months of talks and it's only 135p. PUSU extended again. [SP=117 Cap=220m]. I hold.
◄Personal Group (PGH)► sells Lets Connect IT Solutions for £2m "simplify the Group's structure and product set and allow for a greater focus on these core offerings". [SP=168.05 Cap=53m]
◄Amala Foods (DISH)► update on RTO - continues talks with the FCA and "progress other work streams related to the Transaction and the development of the target business". [SP=0.12 Cap=1m]
◄Quadrise (QED)► continues to work with MSC and project counterparties to conclude the binding agreement between Quadrise, MSC and Cargill for the vessel trials on board the MSC Leandra. [SP=2.09 Cap=37m]
◄Feedback (FDBK)► collaboration agreement with Vertex In Healthcare, a specialist clinical IT firm with offices in the UK, UAE and South Africa, "to combine key technologies and resell each other's products". No minimum sales targets. [SP=63 Cap=8m]
◄The Gym Group (GYM)► guides FY-Dec at the higher end of market expectations which are for EBITDA Less Normalised Rent £38.0m-£43.1m. H1 rev up 12% and LFL 9%. [SP=122.6 Cap=220m]
◄Cordel (CRDL)► wins contract with Genesee & Wyoming, owner and lessor of more than 100 short line and regional freight railroads in North America. No $$$. [SP=4.5 Cap=9m]
◄Acuity RM (ACRM)► AGM stmt - H1 orders up 50%, 80% in Q2. "We expect to be able to announce an accelerating rate of order wins and developments in all areas of the business over the next 12 months." [SP=3.22 Cap=5m]
In line: HSW, MPAC
Equals (LON:EQLS) I would interested in Paul Hill's comments on this, as I understand he is still a big holder.
Seems like a damp squib to me.
David
Paul Hill's take on Equals offer:
Private equity house @TowerBrook Capital have a reputation for playing hard-ball.
Indeed news came today that they & consortium partner @railsr_ have submitted an "improved indicative non-binding proposal" of 135p/share (£276m fully diluted) in cash for international payments platform @equals__money .
Representing a modest 15% premium compared to last night's close of 117p - and lower than my own fair value of 170p.
https://x.com/CapitalPmh/statu...
Cancel
Liontrust Asset Management (LON:LIO) - Hopefully things turn for the better now. Yielding 10%+.
Trading Update - 3 months to 30th June
· Net outflows of £0.9 billion in the Period (2023: £1.6 billion).
· Assets under management and advice ("AuMA") were £27.0 billion as at 30 June 2024, a decrease over the Period of 2.8%.
Commenting, John Ions, Chief Executive Officer, said:
"Labour's large majority in last week's General Election should herald a period of stability that will be positive for financial markets. It is encouraging that the new government has a pro-growth agenda and is committed to the simplification of pensions.
Along with falling inflation and the expectation of a reduction in interest rates, this should encourage international investors to return to the UK and boost capital flows to the stock market. Given the ever-increasing need for individuals to save more for their retirement as well, this will significantly improve the outlook for asset managers.
https://newsfile.refinitiv.com...
Liontrust Asset Management (LON:LIO)
Given the improvement in UK markets this year you would have thought they would be performing better but AUM still decreasing and yet more net outflows.
Nevertheless they have a strong balance sheet, super attractive dividend yield (which is covered) and a low EV/AUM ratio, they are definitely not expensive.
I should be buying these for my income fund but am waiting for the first sign of a turnaround in flows or at least a flattening of the curve.
I still don't think the relationship between equities and bonds has normalised. If that is right it isn't the time to be buying fund managers.
Equals (LON:EQLS) possible offer and PUSU extension to 7th August
Strategic Review Update
Further to previous announcements in relation to its review of Equals' strategic options (the "Strategic Review"), the Board of Equals confirms that it has received an improved indicative non-binding proposal from the consortium (the "Consortium") comprising Embedded Finance Limited ("Railsr") and TowerBrook Capital Partners (U.K.) LLP ("Towerbrook") regarding a possible all-cash offer for the entire issued and to be issued share capital of Equals at a price of 135 pence per Equals Share (the "Proposal").
https://newsfile.refinitiv.com...
That was NOT worth the wait!