Small Cap Value Report (Wed 10 May 2023) - ECK, HVO, ASC, HAT, TET, JDW, CTO, VTU

Good morning from Paul & Graham!
Today's report is now finished at 12:14
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
I don't suppose we'll get through everything on this list today, but we'll have a good go at it!
Update - that's it for today. I think we covered the most interesting, and price-moving announcements.
Summaries of main sections:
(more detail below)
Eckoh (LON:ECK) - 42.5p (£124m) - FY 3/2023 trading update - Paul - AMBER
A good update, slightly ahead of expectations. Although strong growth seems to have come from an acquisition. Is there much underlying organic growth I wonder? N.America is doing well, but how about elsewhere?
hVIVO (LON:HVO) - 16.5p (£112m) - FY 12/2022 Results - Paul - AMBER
Very impressive organic growth, and a breakthrough year into significant profits. I like the bull case, but also have some questions & reservations below.
ASOS (LON:ASC) - down 6% to 598p (£598m) - H1 Results 2/2023 - Paul - RED
Paul is seriously unimpressed with poor H1 numbers, and a rapidly weakening balance sheet with too much debt. If its turnaround plan works, then Asos might recover, but it looks a tall order to me, so I'm steering clear.
H & T (LON:HAT) - down 1.5% to 405p (£197m) - AGM TU - Graham - GREEN
Trading is in line with expectations at this large pawnbroker as positive momentum from 2022 continues. With record lending taking place, I think these shares could be underpriced.
Treatt (LON:TET) - 650p (£392m) - Interims - Graham - AMBER
The outlook at this ingredients manufacturer is “in line” and they are on track to complete the transition to their new UK facility. But I don’t know how to justify the current market cap.
J D Wetherspoon (LON:JDW) - up 7% to 799p (£1,026m) - Q3 Trading Update - Paul - AMBER
A reassuring update, at top end of (lowered) expectations. This sector seems to be coming alive again, and JDW shares have now doubled in 8 months. Price possibly up with events now? There might be better, more overlooked bargains at the smaller end of the hospitality sector.
Quick Comments
Tclarke (LON:CTO)
Up 9% to 142.5p (£63m) - AGM Trading Update - Graham - GREEN
I gave an overview of the attractions of this share in March. Note that in November and again in January, its positive-sounding updates were both accompanied by broker downgrades. So I think it’s essential with this share (and with some other shares) to find a broker note if you want to know what’s really going on, and not to simply trust that the RNS is being 100% transparent about what is happening.
The broker note to go with today’s news does thankfully leave 2023 estimates unchanged, and the stock market has issued a collective sigh of relief and sent the shares up by 9%, despite an only “in line” trading update. Revenues are on track to exceed £500m this year for the first time but more interestingly the forward order book has surged to £720m, implying continued strong growth after that. The broker is now guiding for £600m of revenue in 2024.
The company reassures that it maintains its “strict selective approach when it comes to tendering”; remember that it’s targeting an operating margin of 3%. It also says that the visibility of its revenues outside London has improved thanks to growth in the healthcare sector and larger projects.
I don’t often give stocks in this sector the thumbs up but I’m going to very tentatively and cautiously do so here. I strongly believe that this sector should be valued at dirt-cheap levels. TClarke does have that cheap valuation, and yet it also has a good track record of profitability, cash on its balance sheet, and impressive growth prospects.
Vertu Motors (LON:VTU)
Up 4% to 60.25p (£210m) - Final Results 2/2023 - Paul - GREEN
Vertu Motors, the UK automotive retailer with a network of 189 sales and aftersales outlets, announces its final results for the year ended 28 February 2023 ("Year").
Everything looks good with the results - slightly ahead of upwardly revised expectations.
Key numbers -
Revenues £4.0bn
Adj PBT £39.3m (down a lot, as expected, from LY’s bonanza of £80.7m)
Diluted EPS (from broker notes): 8.7p
Forecasts from Zeus & Liberum average 9.85p for FY 2/2024 - a PER of only 6.1 - still too cheap in my opinion.
NTAV (company’s calculation) is 65.3p, above the share price.
Total divis 2.15p, a 3.6% yield, but covered by earnings about 4x
Share buybacks are a notable feature at VTU - the share count has fallen a lot, from 398m in 2017, to 349m now, enhancing shareholder value.
Current trading in Mar & Apr 2023 is good, up on last year.
Reiterates full year market expectations (brokers indicate upgrades are likely).
Sector consolidation underway, with VTU making some hefty acquisitions, but note goodwill only rose from £105m LY to £130m now - so it’s mainly buying net tangible assets with the acquisitions - enhancing the attractiveness of an acquisitive strategy.
Supply of new cars improving, and VTU says it has a high margin order book.
Pension schemes - fully funded, no cash contributions required, good.
Balance sheet £341m NAV, less £130m intangibles, gives NTAV of £211m, very healthy. Dominated by freehold property, and of course huge working capital debits & credits, which net off as is usual in this sector. No issues I can see, it looks very solid.
Note that £1.3m interest received, now interest rates have risen from zero. Although interest payable has also risen (by more).
Paul’s opinion - I think it’s too cheap, and should be priced maybe 100-120p per share. But for the time being, the market isn’t interested in bargain car dealer chains. For patient investors, I think this remains an excellent opportunity, and sooner or later there’s likely to be a flurry of takeover bids.
There’s a good argument for buying a basket of UK car dealers, as they’re all cheap, that way you’re more likely to receive a takeover bid premium.
Thumbs up from me, Vertu looks as solid as ever. And really cheap.
Paul’s Section:
Eckoh (LON:ECK)
42.5p
Market cap £124m
This update was issued on 25 April, and has triggered a nice move up in the share price, which has stuck. So I thought it would be interesting to check it out.
Eckoh plc (AIM: ECK), the global provider of Customer Engagement Security Solutions, is pleased to announce a trading update for the year ended 31 March 2023.
What does that mean? A slightly clearer description is included further down the announcement -
Our solutions enable payment transactions to be performed securely and help protect sensitive personal data across any customer engagement channel and device the customer chooses.
Protected by multiple patents, our solutions remove sensitive personal and payment data from contact centres and IT environments, as the best way to secure data is not to collect it. This allows organisations to be not just compliant but secure, increase efficiency, lower operational costs, and provide an excellent customer experience. This is our specialism.
It sounds similar to what PCI- PAL (LON:PCIP) does, but ECK is bigger, and profitable.
What’s the latest?
FY 3/2023 latest guidance is:
Revenues £39m, well up on £31.8m LY), but below forecast of £40.3m.
Adj operating profit £7.6m, slightly ahead of market expectations (of £7.5m), and well up on £5.2m LY.
Net cash £5.7m is £0.5m ahead of forecast, and well up on £2.8m LY.
That all looks pretty decent, but not spectacular, it’s only slightly ahead of expectations after all.
N.America region showed an impressive +34% organic growth in ARR (annualised recurring revenues) -although note this $15.9m mentioned below is only about a third of total revenue, so it's a highlight, rather than the full picture -
Excellent progress was made in the key North America region with Security Solutions exit ARR2 up organically 34% to $15.9m (FY22 $11.9m), driven by the Group's increasing focus on its largest growth market, which resulted in further large contract wins, increased cross-selling and strong renewals in the region. Growth in total contracted business of more than 50% during the year, together with a continued shift to cloud, underpins Eckoh's future ARR growth and demonstrates the increasing revenue visibility in the Group's business model going forward.
Positive commentary re products.
See update note from Singers (on Research Tree), many thanks to them for sharing this with us.
Valuation - Singers reckons EPS for FY 3/2023 will be 2.0p, so the PER is 21x
No change in EPS forecast for FY 3/2024, which I imagine is being prudent, showing no earnings growth.
Paul’s opinion - in a higher interest rate environment, an earnings yield of below 5% (PER of 20+) is more difficult to justify, and I am worried that investors have still not adjusted to lower valuations yet.
However, in this case, Eckoh is delivering strong growth. I wonder if it won some contracts just before the year-end, because broker consensus forecast was cut sharply in April, but now appears to be going up again?
Also, note that it made a £31m acquisition of Syntec in Dec 2021, which will I imagine have boosted the FY 3/2023 results. So investors need to check the figures carefully when they're published, to understand what growth is organic, and what is acquired. Prior to this acquisition, growth at Eckoh had been anaemic. Indeed, I’ve been following Eckoh for many years (it floated 22 years ago) and it had a great run from 2010 to 2014, but has really just oscillated sideways since. So I question whether it really is a growth company? Something to think about there!
Overall I’ll say I’m neutral, amber.
hVIVO (LON:HVO)
16.5p
Market cap £112m
This company claims to be a world leader in human trials for new drugs.
Revenue up 30% to £50.7m (all organic growth)
Healthy cash position of £28.4m, but has mostly come from customers paying up-front.
Big growth in operating profit: £6.0m for 2022 (LY: only £0.6m) - is this sustainable? All profit wiped out by £7m impairment in associate investment.
Adj diluted EPS 0.9p = PER 18.3x (LY small loss)
Contracted order book up 65% to £76m, giving very good visibility.
Special dividend of 0.45p/share, costing £3m, to be paid on 9 June 2023.
3 non-core assets being abandoned.
Big increase in EBITDA margin.
Guidance - 2023 revenue £55m, with full visibility from existing orders. EBITDA margin mid to high teens for 2023.
One recent contract cancelled.
Balance sheet - NTAV only £14m.
Cashflow - note £1.5m R&D tax credit received.
Paul’s opinion - I did buy some of these earlier this year, but kept finding myself top-slicing it to buy other things that I preferred (my current strategy is to hold only 10 positions, and not use any gearing), and ended up selling all of HVO in stages (not planned!). Also, after a really bad experience with WAND, I didn’t want to hold another share where so much of the valuation rests upon contract win announcements (which may not necessarily turn into reality).
That said, seeing the FY 12/2022 results come out in line, and with a nicely grown cash pile, I'm more comfortable now, and don’t think it’s another WAND.
Other questions I have - what insurance, at what cost, does the company have in case it inadvertently kills or seriously injures one of the human volunteers in its trials? Secondly, has it perhaps benefitted from any covid-related stimulus to its activities, since growth seems to have suddenly accelerated around the time of the pandemic?
I’m tempted to buy back in, as this does look an interesting company, and if it thrashes forecasts (as the CEO is fond of indicating on webinars), then the shares could do well.
HVO claims to be a world leader in its field. I wonder if we can get any third-party confirmation of that?
IMC webinar recording from 25 April 2023 might be worth viewing.
I think we’ve got some enthusiasts for HVO here amongst subscribers, so do post a comment if you have anything to add to my comments above.
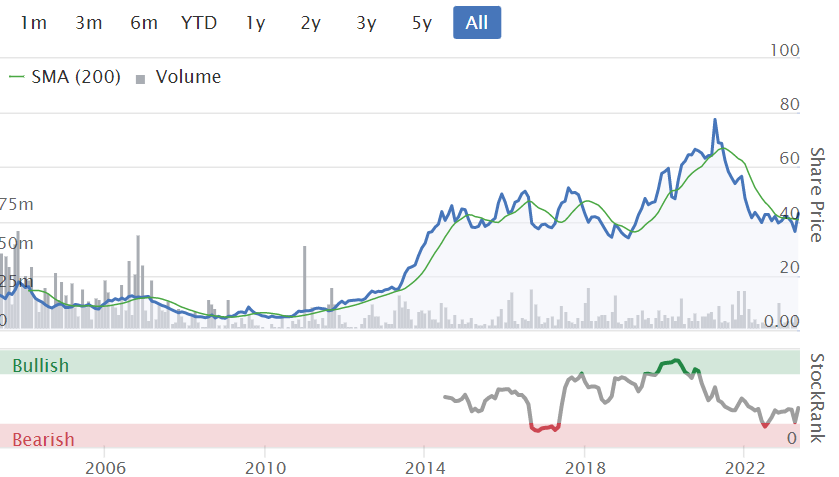
Note how the shares have disappointed & then soared in the past -
ASOS (LON:ASC)
636p (pre market)
Market cap £636m
H1 results from this former eCommerce glamour stock look awful to me. Although it had previously indicated that H1 would be weak, with a turnaround plan for H2 onwards providing the jam tomorrow hope/hype.
Anyway, I don’t think this share is any good, so I’ll briefly explain why.
H1 revenues £1.84bn (down 8% vs H1 LY)
Loss before tax of £(291)m - which looks disastrous to me.
Adjustments of £204m soften the loss to £(87)m. The biggest item in adjustments is a £128m stock write-off, which to me is not an adjustment, it’s an integral part of trading - i.e. bad product, being cleared at a loss.
Gross margin is too low - which has always been Asos’s problem, and the reason it’s never really made any sustainable profit or cashflow. 42.9% adjusted gross margin is just too low. It needs to be nearer 55% in this sector to make a decent profit. Also, the reported gross margin (after stock write-offs) is even worse, at 36.1% - which simply is not a viable business at that level.
Balance sheet - has taken a battering. NAV of £794m includes £703m intangibles, so NTAV is now only £91m, and falling fast - this could turn negative in future, I reckon.
Inventories look far too high still (more write-offs to come, I suspect), and this is all now funded by debt, which is growing rapidly. Net borrowings (excl. leases) rose to £432m, or £731m incl. Leases.
Bank facility has been extended to Nov 2024 - see note 18.
Convertible bonds - looks a remarkable deal done in 2021, with £500m borrowed, attracting interest of only 0.75% apparently, and unsecured. Scrutinising the terms of all the borrowings is absolutely key to whether the shares are worth anything. Breaching covenants could hand control to lenders, as with any company. Expiry April 2026 buys plenty of breathing space.
Going concern notes give a clean bill of health, but that doesn’t alter the fact that Asos is now entirely dependent on its borrowing facilities.
Outlook - lots of detail given, but the part which jumps out at me is the free cashflow guidance of negative £(100)m, at the bottom of a previously guided range of £0 to -£100m for FY 8/2023.
Paul’s opinion - this looks an absolute mess to me. Are the shares actually worth anything? I have serious doubts. The only value in them now, is hopes that a major turnaround in performance can be achieved. It strikes me that Asos grew way too quickly, which covered up the reality that it was a shambles internally. I’ve been saying that for years, because I knew someone senior internally, who told me that. Also it never really made any profit, because gross margins were too low. The story was always growth, and more growth (in revenues), and profit would somehow follow at a later date, which hasn't happened.
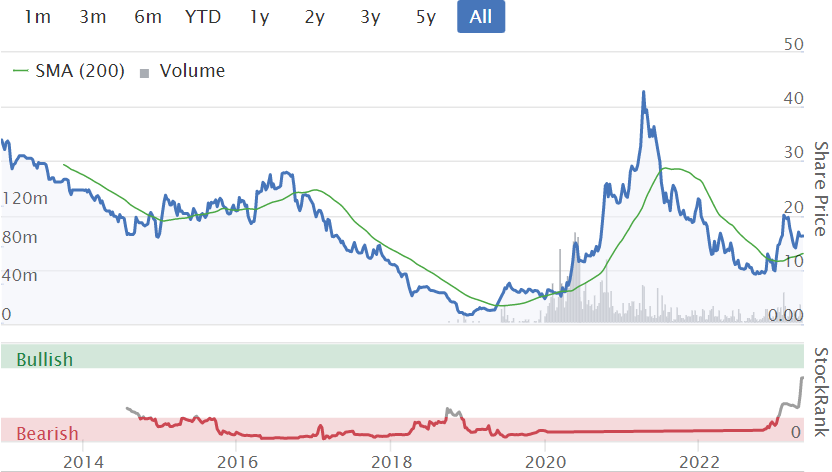
It started at 0, went up to a valuation of £5bn, and now looks as if it could be heading back to zero, in my view. Hence I wouldn’t touch it, unless a really credible turnaround becomes evident in the numbers, which certainly hasn’t even begun yet, as far as I can see from the actual numbers.
I suppose the bull case would be if you think it can turn trading around, and that online fashion might rebound. Chinese behemoth Shein seems to be seriously undermining the incumbents in this sector though.
There could also be positive help from sterling being stronger now, and freight costs reducing, and cheaper marketing costs maybe? On over £3bn annual sales, quite small improvements in margins could drop through nicely to the bottom line. Maybe there is some hope?
J D Wetherspoon (LON:JDW)
Up 7% to 799p
Market cap £1,026m
Shares in this value pubs chain have now doubled from the low in Oct 2022, remarkable stuff.
I reviewed its interim results (c. breakeven underlying trading) here in March 2023.
It’s delivering strong LFL sales vs LY (FY 7/2022) of +12.7% YTD - a bit above inflation, so that should be good for improved profitability.
Net debt is £738m. Remember that JDW cashed in the profits on its interest rate hedges, so financing costs will be higher now. It has plenty of freeholds, not revalued for about 24 years. Liquidity sounds fine, with £241m headroom.
Outlook sounds positive -
"The company expects profits in the current financial year to be towards the top of market expectations."
That’s good, but as you can see below, broker consensus forecasts have been lowered a lot, so then achieving the top end isn’t as impressive at it might first sound.
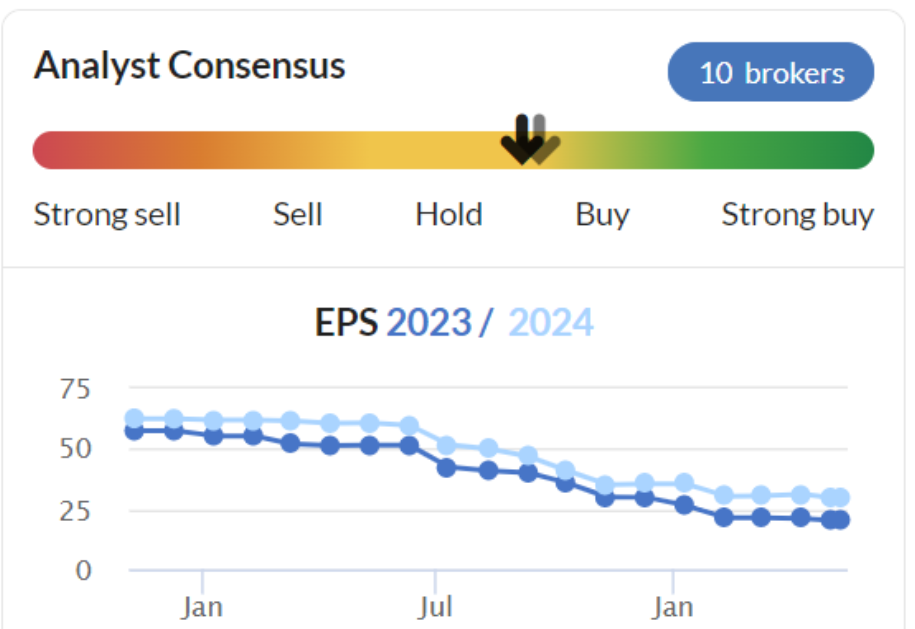
The rest of the update is Tim Martin largely repeating his previous (very valid) points about how much tax the hospitality sector raises, the need for an enterprise economy, rewarding staff, etc.
Paul’s opinion - I think hospitality is a very interesting sector right now, for strong recoveries. JDW has already doubled from the lows, so personally I’d be looking elsewhere in the sector for bombed out smaller companies, which in many cases are still near their lows.
Remember this sector is very operationally geared, with gross margins typically around 75%. So with inflation set to recede, full employment, and private sector wages rising in nominal terms, maybe people are more relaxed about spending in pubs & restaurants again? That's what a flurry of recent sector updates seem to be telling us.
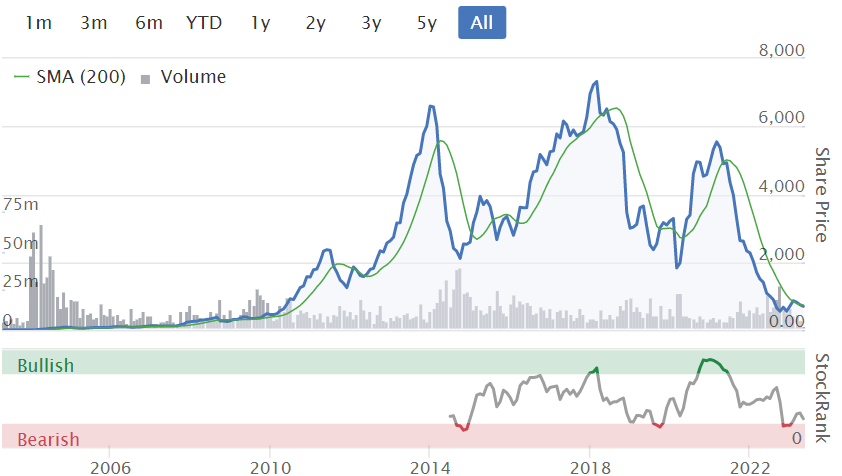
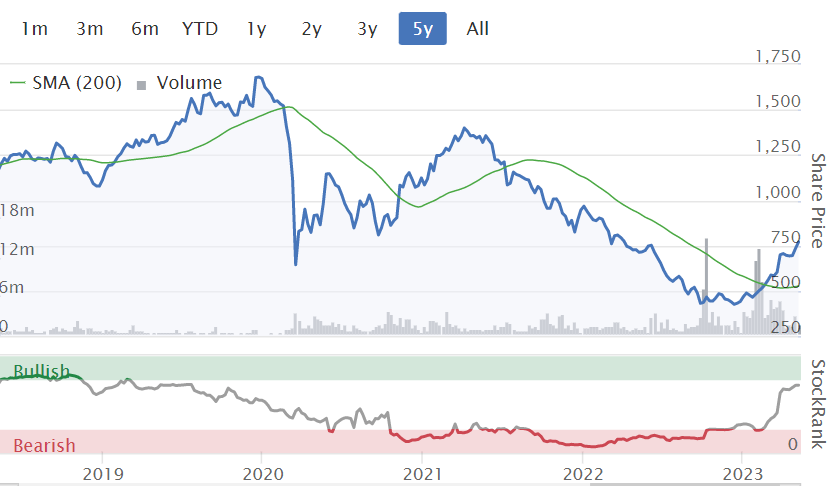
When you zoom out on the chart, the recent doubling in share price doesn't look quite so extreme. Although note there are c.20% more shares in issue now, vs pre-pandemic. Also, look at how the StockRank has shot up in recent months.
Graham’s Section
H & T (LON:HAT)
Share price: 450p (-1.5%)
Market cap: £197m
I am not currently a shareholder at H&T, but I remain interested in this company that I’ve been following for many years - the largest pawnbroker by a wide margin.
I covered their amazingly strong 2022 results in March, when they confirmed that the positive trends of last year had continued into 2023.
This morning brings an AGM update for the first four months of the year. It confirms that trading is in line with expectations.
Key points:
January and March were both record months for lending, as inflation increases the demand for short-term consumers loans (but the general supply of these loans is still constrained)
Pledge book rises to £106.5m at the end of April. It was £100.7m at the end of 2022.
Continued strong demand for pre-owned jewellery and watches; retail sales up 13%.
Retail margins have moderated: the company is increasing its jewellery prices and reducing inventories of certain higher value watch brands, “where we have seen recent changes to the sentiment of some customers towards value”.
In foreign currency, revenues are up 10% year-on-year, “but are yet to benefit from the peak trading period of the summer months”. I noted recently that Ramsdens Holdings (LON:RFX) was moving onto H&T’s turf in certain Southern areas. Could this impact the demand for H&T’s foreign currency services? Or maybe there will be enough customers for both companies to prosper?
Store expansion: seven new stores have been added so far this year, bringing the total to 274. I am relieved that this number is consistent with the “measured and carefully considered manner” with which they said they would open new stores.
CEO comment: he remarks that they “continue to believe that the Group has an opportunity for significant growth in the medium term across all of our product offerings.”
Graham’s view
It’s only an “in line” trading update, but remember that the momentum around earnings forecasts with this company is still quite good:
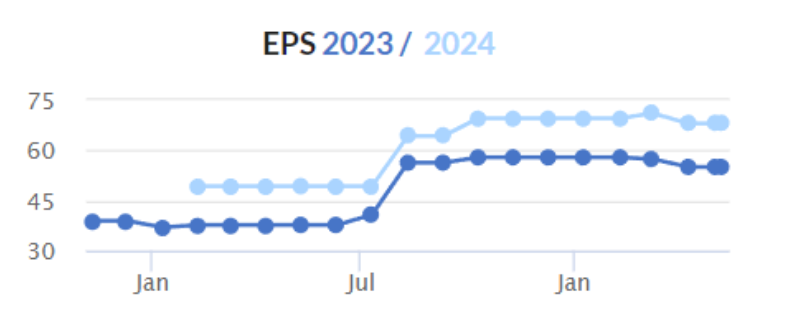
I am slightly concerned by this morning’s comments on the retail operation, where the company needs to be careful that it doesn’t overstock inventories.
But pawnbroking is the main driver of the company, not retailing, and it seems like conditions for pawnbroking could hardly be any better right now. That’s a sad comment on economic conditions, when companies like H&T have to fill a gap left by mainstream lenders in order to help people get by.
I see that Stockopedia’s Quality metrics for this share have been updated.
In March, the metrics were as follows:
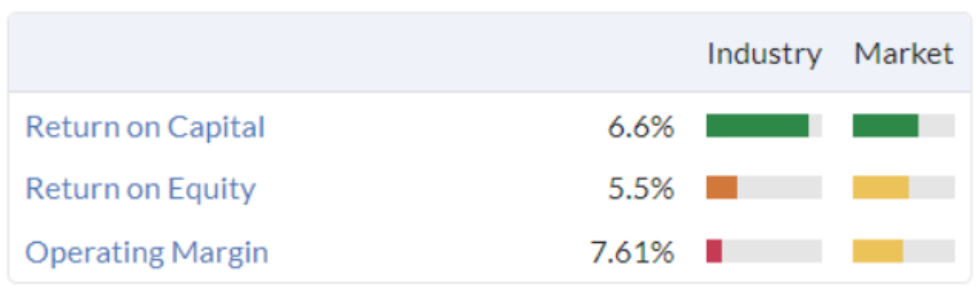
As expected, ROE is now 10%:
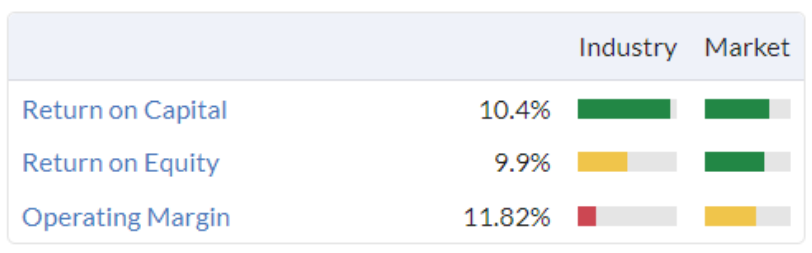
I’ll be the first to admit that generating an ROE of 10% indefinitely will be difficult for H&T. But I do think it has good momentum and might be able to do so for the next few years. It can even generate ROE higher than 10% in very favourable conditions. As such I don’t think this market cap (£197m) is particularly generous, and I’m happy to give it the thumbs up at a P/E ratio of only around 8x.
Treatt (LON:TET)
Share price: 650p
Market cap: £392m
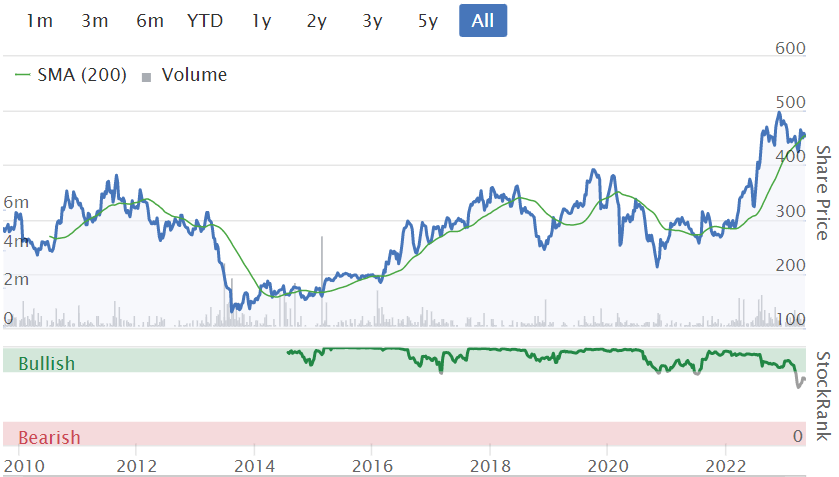
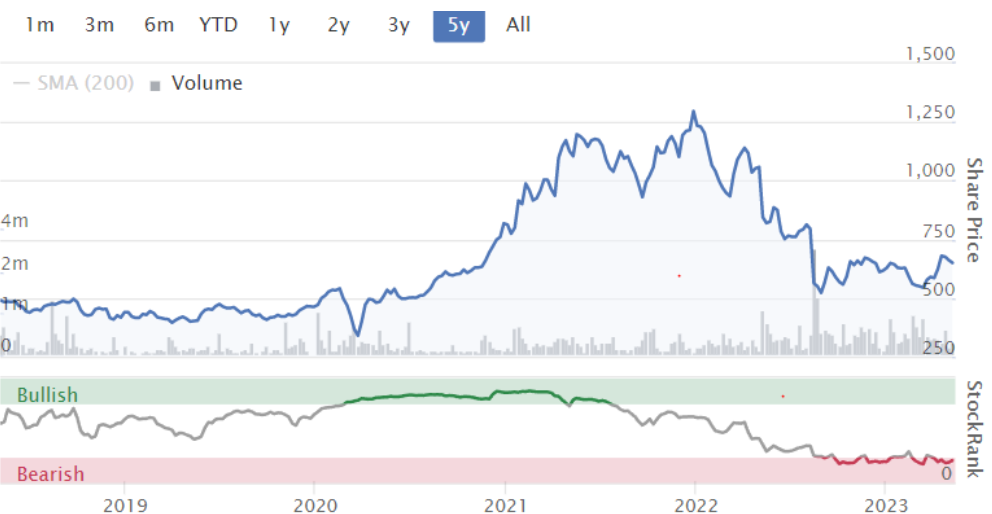
This ingredients manufacturer has given back all of the share price gains it enjoyed in 2021:
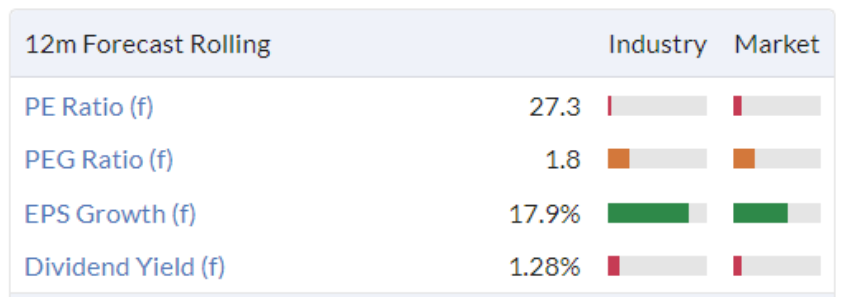
And it remains expensive (net income of only £13m last year):
Yesterday it announced interim results. Perhaps we can find some clues that it might grow into this valuation?
Trading is in line with expectations.
H1 revenues were up nearly 15%, helped by the reopening of China where sales were up 39%.
Revenues were also helped by the strength of the US dollar and other currencies received by Treatt. If you exclude gains from currency movements, H1 revenues were only up by 8.5%, a much more average result.
Adjusted PBT grew by 15% to £7.3m, and actual PBT wasn’t too far behind at £6.6m.
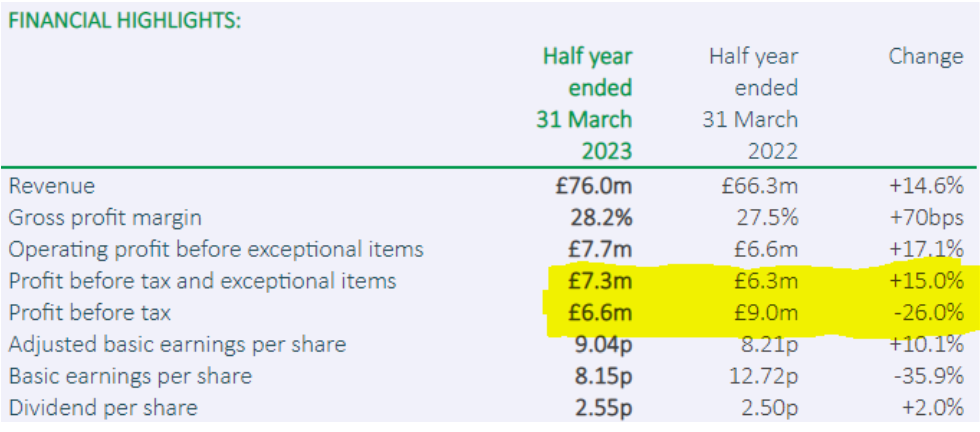
Gross margin strengthened as price increases were passed onto customers, and there were more high-margin sales in the citrus category (this category is now responsible for more than 50% of sales).
Treatt is providing “more complex, higher value, and bespoke citrus solutions for our large beverage customers”. Lower margin products were “actively managed downwards given our strategic focus”.
Net debt falls by a few million pounds to £18m.
CEO comment:
We remain well-positioned to capitalise on prevailing trends in a resilient beverage market. We are winning new customers and deepening our relationships with our existing ones. This has led to a very strong performance in our higher margin citrus category, growth in China following its re-opening and we have also seen some good early wins in the exciting coffee market.
The new UK factory will be completed by the end of this financial year:
Three years post completion, we expect to be generating a 10-15% return on investment ('ROI') from this site, with process efficiencies and initial headcount savings already taking effect.
Outlook:
We are pleased with the strong performance year to date and we have good confidence in Treatt's proposition and its ability to deliver growth, supported by positive market dynamics. Q2 momentum was particularly encouraging and we enter H2 with a strong order book and sales pipeline and trading continues in line with the Board's expectations for the full year.
Graham’s view
I’m not seeing enough evidence of fast growth to get me overly excited about this one. Top-line revenues have been boosted artificially by dollar strength, and without that you only get the 8% revenue growth which I currently consider to be the benchmark performance for decent companies.
The new UK factory should help to drive performance over the next few years, but even there Treatt is only expecting a 10-15% return on investment from this site. That would not be a bad performance by any means, but I’m sure there are many other companies that can generate a 10-15% ROI from their investments. In my book, that’s an average performance from a decent company. It’s not enough to justify a premium rating for the stock.
I’m tempted to give this one the thumbs down on valuation grounds, but I try to reserve the thumbs down for bad companies or companies with major problems. Treatt doesn’t have any major problems that I can see. It’s just too rich for my taste.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

103 comments
I see that there has been an announcement of another 25% redemption by NB Global Monthly Income Fund (LON:NBMI) at 80p against a current price of about 74p, ex-record date of 16 May 2023.
I hold (small in Mum's ISA aka Pension
Hi Paul,
I am shocked that you haven’t gone back into Vertu Motors plc. It is very very rare to find a listed company that in 4 years can manage profits equal to their market cap. I think your valuation 100-120p is a too conservative as its properties should be valued at least over 400m (considering the recent sale of 50% over book value). In addition the business is and will be profitable yearly, will pay a dividend of 5% and the share count will decrease. One to add and hold for the next 4-5 years for a target of over 200p.
Also , although I do hold hVIVO , I have to agree with you being a bit sceptical about it. Although I totally disagree that this is or might be another WANdisco , I was disappointed that their special dividend was only £3m after eagerly announcing that their cash balance has increased to over £25m.
Thanks
Further to A Counsel's bit, it would bit sometimes informative input from Paul/Graham if their sentiment changes on shares they've had high conviction (so called Coffee Can shares- ie hold and forget ( Saga , Boohoo etc) - S me of us don't have the skills t do in depth research and take the lead from SCVR
That's a lot of work for SCVR to keep track of! Just look at the new spreadsheet and the number of green stocks they have covered. Recently, when any of my shares have dropped 7%. I re-evaluate it. This share is now on my naughty step! Does it still pass my checklist? If it drops another 5% I do another re-evaluation and I generally sell but I have sometimes held. Its my re-evaluation that's important.
There seems to be a great deal of misinterpretation with respect to my earlier comment. To clarify:
Many responses to my comment were constructive and supportive and thanks for that. Maybe once I recover some confidence my future investment efforts in small cap stocks might be more productive!
It's been shockingly hard really for the last 2 years. I would say though that I luckily sold my Boohoo (LON:BOO) very early, based on the price action. Paul Tudor Jones (trader, worth $7bn) says that nothing good ever happens below the 200 day MA, and I try to stick to that if the position is substantive. That's why I got out of Boohoo; when the 200 day is like it is, you have to wait until it has flattened and is increasing again.. Having lived through quite a few bear markets I know how brutal it can be for small caps so I'd rather take the feeling of losing 25% than be worrying about the one of losing 90% and act accordingly. It's never easy, even in the good times we are still riding a wall of worry. I especially take notice of what Paul says when he finds a problem in the accounts and then I won't hold or buy them. Over the years he has made some cracking calls, starting with QXL in the dotcom era. Twenty three years later he highlighted Card Factory (LON:CARD) to us (when I had taken my eye off the ball).
Thumbs up to this. I have learnt alot not only from Paul & Graham over the last couple of years, but from alot of the other posters here - so thanks to many of you for making this a sane and balanced discussion forum.
From a personal perspective I have found the warnings from Paul and oaur Graham (thanks Cilla), more useful than their endorsements.
I cant help admit that I am relieved to hear that others are finding this a difficult period, by chance my investment journey started in mid 2021.. so a bit of a baptism of fire.
Don't beat yourself up. We all like a story and small caps should be a percentage of your portfolio on stuff you have some interest in - and hopefully divulge some of your deep diving. I'm specialising in mining at the moment and as usual its "the more you know the less you know" - and gold will go to 2500 - the Question is not if but when, and the way things are going not very long time.
Got into Boohoo and traded it up but did not exit in the clear 'dead cat bounces' on the way down. Hits say the 200dma then bale out whatever - strong willpower needed which is easy to say, hard to execute when in capital loss.
Trying Ichimoko now and hope to apply some discipline - at least the get out - gives four stop loss points so if not watching daily then have a chance of reducing losses. And if goes pear shaped only yourself to blame - but there are others of course, TradeView has loads of the things - all good fun.
Paul provides good macro as well which is very helpful at the start of the day.
I think it is a great sadness that ASOS (LON:ASC) (I don't and never have held) and Boohoo (LON:BOO) (I did hold and took a bath) cannot make online retail work. Trudging around souless "malls" seems such a waste of life.
My retailer of choice is LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) not because I can afford to shop there or would if I could, but because there are almost always people queuing to get into the stores and where I visit regularily, they often do a pop-up store to supplement their already enormous sea front store.
I bought for my son's JISA back in July 2021 (why I didn't buy for myself? Who the ...knows), after seeing people queuing the day that the shops were alowed to open after the second French lockdown. No they didn't want to visit granny or a close friend; they wanted to go shopping at Louis Vuitton and Hermes. Most odd but there you are.
Regards
Michael
which broker do you use for buying LVMH?
Hi tic_tac
This was actually in my son's SIPP now that I look (I wonder where it will be when he is able to cash it in at age 55?!) and that is with A J Bell but would be able to buy through the main broker I use Interactive Investor.
I do intend to buy I have just got to sort out what I am going to sell etc.
Regards
Michael
IG do not offer CAC / french, hence asking
Got no idea about perfume, handbags or expensive tipples, but like Watches of Switzerland (LON:WOSG) - new store opened in Canary Wharf with a couple of others in close proximity (clientele bankers, Chinese, Russian escapees etc - but probably less British). But is this a 'bubble' (see Sunak removed VAT reclaim duh!).
But its a watch, ok has some diamonds (small), gold (scared to wear it), worn by past Bonds (future unknown) and needs to be serviced every five minutes at huge cost otherwise doesn't er 'tell the time' - so only an investment which may or may not appreciate over time if can keep it safe an untouched - like Ferraris (in garage with trickle charger).
Ok Apple messed up making a cuboidal looking thing but suppose if want to read emails on it then at least has some function and ECG (scared to go there all that fitness stuff).
Maybe with ASOS and Boohoo the parents are closing off the money tap and suspect times about to get hard for the 'youf'. Have bought some great clothes from Amazon (but of course the little darlings don't like Sports Direct etc).
And 'trainers' - good lord in heaven - they don't even use leather anymore. Hence like Zotefoams (LON:ZTF) - but won't be putting in big bets.
CPI
Pre announcement the mkt was braced for 5% yr on yr.... which would have been quite hot. As suspected there wasn't much in this no as it added 0.4%...and lost 0.56% off the back...meaning headline came in under 5%. Should this mth on mth trend hold in May and June you will see big drops in the year on year number towards 4% and 3%. As I said we didn`t learn much today....should see positive falls in next two months but then the real interesting stuff comes in August onwards...... for now mkt has taken it well.
Paul, some of the tags have gone missing yet again.
Thanks Rusty2. I put them all back in manually.
on the JDW comment '
J D Wetherspoon (LON:JDW) - up 7% to 799p (£1,026m) - Q3 Trading Update - Paul - AMBER
A reassuring update, at top end of (lowered) expectations. This sector seems to be coming alive again, and JDW shares have now doubled in 8 months. Price possibly up with events now? There might be better, more overlooked bargains at the smaller end of the hospitality sector.'
It may be worth looking at Marston's (LON:MARS)
Georgia Capital (LON:CGEO) good update from these guys. TNAV now exceeds £21 so at £8.15 to buy you are getting assets at 40p in the £
The healthcare businesses are now normalising post covid so this is a really good thing as it should drive increased NAV and strong operating profits.
THE Nav of the business is made up of Bank of Georgia (LON:BGEO) (which I really like - and have held for a decade), cash, pharmacy, healthcare and education. All of these sectors should continue to do well and have robust demand across economic cycles so despite the geopolitical risk of Georgia itself a discount of 60% just feels way too wide.
I hold both Bank of Georgia (LON:BGEO) and Georgia Capital (LON:CGEO) too. Well run companies. I note that World bank had GDP prediction for Georgia 2023 around 3.8%, but the Qu1 result was 7%. Also BGEO had upgrade in its rating yesterday.
Hi Paul, any thoughts on ROL- Rotala?
Hi PatW,
Rotala (LON:ROL) is very small and obscure, so it's at the bottom of the list unfortunately.
I'll try to circle back to it, even if just for a quick comment.
Regards, Paul.
Rotala has an interesting story and an amazing stock rank for such a tiny company. I have a very small holding and I've top sliced some profits but I'm wondering if the recent dip provides and opportunity? Thanks
I may be in a minority of one here on the SCVR but I have lost a lot of confidence in the analysis provided here. I appreciate the DYOR mantra and accept all the investment decisions are one’s own. However, the analysis does influence further investigations and potential investment decisions. Maybe I have been spectacularly bad at this having taken thankfully small and admittedly speculative positions in Boohoo (LON:BOO) , Hostmore (LON:MORE) Unbound (LON:UBG) and Saga (LON:SAGA) which are now all down between c 70 to 98% (the disaster that is Unbound (LON:UBG!) All these companies were positively reviewed in the relatively recent past. I am sure I may be missing out on opportunities highlighted in the SCVR but given my past record I just don’t have any confidence in investigating them further.
But one has to take into account that the outlook for any given company can change over time, for better or worse.
use a stop loss, and exit each when down 10-15%.*
the analysis here is great, but it is not a substitute for an easy ride, or shortcut for doing your own work and taking resp. for your own decisions.
I got stung in boo and UBG but no regrets, and no blame passed. I too could have exited earlier.
this forum provides a rich and quality source of leads, and for every +ive post on the above shares you would have found opposing comments by subscribers below the articles.
you have to put in your own work.
the risk is comments like this peeve the writers and they leave, then we are in a much worse position overall.
[* edit, or whatever level, I am just illustrating a point]
ACounsell,
SCVR is less analysis and more opinion of little more than private investors. SCVR opinion boards are probably no worst than bulletin boards, but nothing beats having your own process and not being dependent on bulletin Boards and Pundits such as SCVR for your ideas.
BSV
hi ACounsel - what I would say is this. In my view the board is useful for generating ideas and also assessing your investments against community views. You can pick up all sorts of valuable snippets in those conversations. But......
1) Have a strategy - understand what you are buying and why. Does an investment imbalance your portfolio structure for example.
2) Try and ignore sentiment. If a poster owns a stock then even if they can see the downside there will be a natural bias towards enthusiasm. Hence if the idea resonates with you go and DYOR with an open mind. Use it as an idea generator for further investigation, not a buy/sell signal.
3) Size according to your strategy. Consider stop losses. Remember that small caps generate more volatile prices in general so a 10% SL may not be appropriate. I have plenty of things that can swing 25-30% so if I had a pre-determined SL of 10% I'd keep getting knocked out of my investments. There are other ways (eg when it breaks below the 200 day MA) or you could combine them.
4) Constantly reassess - the basis for owning a stock can change rapidly. Don't stick with the original thesis when events have changed.
Bottom line is that you have to put in your own work to determine what's right for your portfolio, risk appetite and circumstances but used in the right way the information on here can be very valuable.
ACounselL
The analysis here from Paul and Graham is outstanding and it’s a kick in the teeth for them to read comments like yours and to see support for it too. Have you read more recent comment on the shares you appear to have lost heavily on? No way has more recent comment been bullish on some of them.
Have you read the section below that appears every day; it’s VERY clear.? And they also make it clear that they are not tipping any of the shares they cover in such quality and detail. Competent investors do as is also advised and do their own research. Failure to sell on subsequent bad news that came in updates from the likes of Hostmore (LON:MORE) Boohoo (LON:BOO) and Unbound (LON:UBG) are the fault of the investor and no-one else.
“A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinionson them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
I am very sorry to read about your losses ACounsell and about your loss of confidence in the analysis provided. Other members are putting this more eloquently in replies "When the facts change, I change my mind --what do you do?
My biggest losses have come (still come) from not acting quickly when the facts on particular investments have changed. With all due respect, perhaps you have the same reluctance to take losses. The analysis on here is fair, honest and probing and I for one have benefited from it. I try to learn constantly from the SCVR's and also from quite a few clever investors who offer comments on here too. I hope you stay with Stockopedia and find investment success. Starting with the analysts' Green companies, then monitoring their progress makes sense. I've always struggled with 'Run your winners, cut your losers' but I'm working on doing just that.
ACounsell, it's an interesting comment so thank you for that. The thing about active investing is that everyone who does it needs to bring their own insights and personality to it. Similarly, when reading the views of others, it's vital to understand that other people are biased (not necessarily in a bad way) by their own perspective and strategy. Those stocks you mention have performed badly, but I would argue that the process which led to them being reviewed positively has also led to huge winners being identified in other market environments.
The point is not that the particular process is right or wrong, but that hopefully we can all learn from each other's methods. A broad spectrum of stocks are covered here and many features of the market are discussed.
Finally, I would add that Paul and I usually agree on stocks, but there are also many times when we differ. However there is no question that I have learned a ton from Paul's commentary and experience. One of the keys to long-term survival in this business is learning as much as you can from others - from their successes and from their failures. Because we all have both. If you have observed that certain ideas haven't worked, and you can identify why they didn't work, then you are one step closer to improving your investment strategy.
Best wishes
Graham
I am sure we all go through bad periods - but most of us come through with a better understanding. Over the years I have decided to stay clear of companies with MV less than £100m and frankly look for over £200m - They are just too volatile and too illiquid and too large a margin between buy and sell price, for my liking. So I gloss over many of the comments here and do a lot of 'sifting out' (e.g. Saga (LON:SAGA)) but am grateful for the input on companies such as Vertu Motors (LON:VTU) and £BLM.
Who are BLM?
Perhaps Belvoir (LON:BLV)? That's been favorably covered here and done well recently.
no - Bloomsbury Publishing (LON:BMY) - Bloomsbury - but they seem to be out of favour this week!
A 'social' organisation that Sillycon Valley Bank put a some of 'investors' money into. Maybe not your answer.
ACounsel, unlucky if you are only in those 4. I hold all of them, but have also done very well out of other companies that have had favourable comments here. But we make our own investment choices.
With regards to your "All these companies were positively reviewed in the relatively recent past" comment - Paul stated in July 22 that Unbound was a bargepole case and a good chance of hitting zero, so if we had acted on that we wouldn't be holding a 98% loss today, would we?
Keep up the good work Paul.
Unbound (LON:UBG) that was after it had fallen around 87%, Paul was initially keen and I believe held the shares.
Unbound (LON:UBG) that was after it had fallen around 87%, Paul was initially keen and I believe held the shares.
The facts changed. So I changed my opinion. That's what investors do.
Hi ACounsell, I have found investment to be a tough path. Lots of people offer their views but in the end only you take responsibility for it. So you need to do the DYOR very seriously. I have to say I find this an exceptionally good resource for putting me on the right tracks. I say that as an ex stockbroker. I remember late 80s all our research was based on the James Capel Red Book. The information on Stockopedia is far far better than that offered by the Red Book. No disrespect to any James Capel analysts intended just true! My opinion on your issue, and I hope you will forgive me for offering it, and I am assuming this is your portfolio which, it probably isn't, but all the holdings you mention are reliant on retail spending. You need to incorporate a macro and a sector view into your approach and then you need to diversify your sectors. So the analysis on The SCVR is a stock selection offering. It says if you are happy with the general equity investment vista, and you are happy with a particular sector, then you might consider this stock. But in summary yes the stocks you mention have been disappointing, and I am genuinely sorry you have lost on them.
We've analysed 508 unique companies here in just the last 10 months, so to cherry pick 4 that went wrong, and pretend that is typical of all our analysis, is absurd, and bordering on malicious I'd say.
It's also factually incorrect, as we have definitely NOT been reviewing Hostmore or Unbound positively in the recent past at all, quite the opposite! The facts changed for the worse during 2021-2, which was then reflected in the commentary here.
Anyway, if you think our work is rubbish there's a simple solution - don't read it!
Astonished to see follow up criticism of the incredible high quality analysis done by Paul and Graham here. Have any of those so quick to pull their analysis to pieces given even a moment’s thought to the time it takes just for starters. Go and look at the updates on all the Companies they’ve covered today. Just look at the wealth of detail, and that’s after having to go through updates and the figures before they can write anything. And then consider the time it takes to write it all. It’s beyond my understanding how on earth they manage to do it, day after day, and not get completely exhausted! Then Paul adds extras like his fabulous podcasts too. Aren’t some folk ungrateful.
And then to see those posts today rubbishing their work must be so dispiriting. It’s our fault and not theirs if our investments go wrong and we hang on to them when the story changes for the worse and even after major profits warnings all the way down to 90% or whatever losses. . Cut our losses when we get it wrong and don’t blame somebody else and certainly not superb analysts! Look again at their analysis just today. If that’s not high quality what is?
Note too that a lot of small company shares have done very badly for a good while. That won’t last for ever. Meanwhile if the focus of a portfolio is mostly just UK smaller companies why not widen it to a much more diversified portfolio?
e.g for investors with limited investment skills, consider pooled investments like Investment Trusts that enable us to invest all round the World. There are some exceptional bargains there too with the average discount to NAV having widened from 3% to an unusually wide 17% and some sectors (e.g Commercial Property) are seeing discounts over 40%.
Here’s Paul’s analysis on Unbound (LON:UBG) last January. It speaks for itself. Anyone who read that and still decided to hold should NOT be blaming Paul’s analysis fir their losses. “Complete Bargepole stock I’m afraid” alone was surely warning enough? AND note the reminder he was warning about Unbound AGAIN!
“3.7p down 42% at 08:46 - mkt cap £3m)
Probably my second to last comment on this share, to warn people off again. Bad profit warning today, together with excessive debt, means I think the equity is now probably worth nothing. It struggled to raise fresh equity at a deep discount last time (well short of the original amount it tried to raise, I know as a friend was inside on the deal). So next time, I doubt there will be any appetite at all to refinance it. Hence the bank probably now calling the shots. Small shareholders can at least salvage what’s left for a few pence, whereas bigger holders unfortunately are probably facing a wipe-out, sooner or later. It all now depends on what the attitude of the bank is. I imagine they’ll probably want a sale of the business, to recover some of their debt, which would probably leave trade creditors and equity holders with nothing. Who knows though, it could stagger on for a while, but the balance sheet looks insolvent to me. Management misled me previously, so I don’t believe anything they say. Complete bargepole stock, I’m afraid. I flagged, in strong terms, the likelihood of a 0p outcome here in July 2022. Previously, it had looked quite interesting, but subsequently turned out the forecasts were fantasy.”
A market cap of 1.6m really with revenue of 6m. Do we need to waste our eyeballs on this stuff. Sorry off to the USA - life's hard then you die - but harder in UK.
Take responsibility for your own mistakes. Shares go up, shares go down. They don't have a crystal ball.
Jesus wept - some you win some you lose get over it - thats very cherry picked set of companies from 500+ that have been covered in last 12 months. It not like the downside points of companies like saga , boohoo and hostmore have not been well laid out in the comments section. You have to have been pretty blind to have ignored the downside risk on something like Saga where the debt issue has been slapping everyone in the face for sometime - the fact the company has no solvency issues now doesnt mean that debt wont drag on performance later. To boot saga was predicting decent profits and is no longer doing so so that has been one that has turned bad due to later poor trading outlook - are you expecting commentators to predict the future too?
Hi ACounsell, I doubt that you are in a minority of one as some of those stocks you mention seem (initially) to have received some of the most positive views from the experts on this board. As it happens, I initially invested in Unbound (the former Electra Investment Trust) as the write-up on this board was positive but when I had more time a few days later to do some detailed research on it, I decided to sell it straight away. With Boohoo I held for much longer but when it became apparent that management did not have much of a grasp on how the company was performing, I sold it in December 2021. As others have said, it is important to have the time and ability to monitor your investments and act accordingly if performance changes, don't rely on updates on this board. Don't take anything you read as gospel as even CEO's sometimes give a wrong impression of a company's health when being interviewed by writers and commentators. I know this as I spent a period working as a writer for a stockbroker analysing shares in a particular sector and some time after interviewing one CEO, I remember him apologetically blaming members of the board for not telling him fully how bad things were (after my article was published of course). My experience is that I have enjoyed investing in areas where I have sectoral expertise because of my career and I think Paul does the same. In other areas I try to copy the approaches used by the most successful fund managers as they have an objective track record and some are willing to explain in some detail how they invest. Having said that, even though I invest in very few of the types of companies discussed on this board, I nevertheless find the articles and comments very informative and interesting even if you disgaree with some of them, and of course there are a variety of approaches to investing which can be successful, but good to develop one and stick to it.
Whilst sympathising, no-one gets every investment right and we should all do our own research before buying, as many on here have said.
I remain very grateful to Paul for pointing me in the direction of Avesco (taken over in 2016) as I would never have found that company without reading his SCVR comments. My biggest ever winner on an annualised basis.
ACounsell,
I completely agree with you. Since October 2021, I have tracked the performance of those stocks given a thumbs up and compared with simply buying the CUKS ETF.Paul's "thumbs up" stocks have returned -31%, whilst the ETF returned -16.5%. I think that most of the damage was done in 2022. Maybe 2022 was a bad year, but I see no evidence of the kind of outperformance that you might expect all the expert analysis to deliver.
No doubt most readers are quite reasonably using "thumbs up" stocks as a shortlist for further research. It is surely useful to know that, on average, these stocks have not outperformed the market over the last 18 months.
This kind of performance tracking should be provided with the SVCR in my opinion.
dodge1664,
I'd be interested to see how you calculate your figures.
Incidentally, just on a quick view, the AIM All Share index is down around 33%, roughly the same as what you claim (with no supporting evidence provided) is my thumbs ups, from Oct 2021 to now. So you're using the wrong benchmark for starters. There's been a massive bear market in small caps, and quite a high proportion of the shares in the small caps space are AIM-listed.
Just to clarify, our "thumbs up" is particularly focused on lowering risk - so a decent balance sheet is essential, it won't necessarily guarantee out-performance against the market, especially in a bear market, when almost everything gets sold off. We're just saying that a share passes some basic risk tests, and looks reasonably priced, hence a thumbs up indicates we think it's worth people taking a closer look at.
Maybe we just won't bother giving opinions on shares in future, it might be a lot easier that way.
Incidentally, you'll be delighted to hear that my Top 20 value/GARP picks ARE out-performing small caps handsomely, 20 stocks up +12% on average YTD, in a flat small caps market, and this list IS published already. Sorry if that contradicts your agenda!
Hi Paul
Don’t stop anything you are doing.
You will occasionally get those who wish to blame their lives issues and personal failings on others on a public forum.
However the vast majority of readers are highly appreciative of all the effort you put in, also the additional constructive comment it generates.
Having started my investment journey mid-2020, I have learnt from many sources - but by far the most informative are your and the teams posts and Stocko generally.
I’ve moved from jumping in and out of random positions in 2020, going with emotion to someone who increasingly is able to look at the bigger picture, DMyOR and come from a position of increasingly more knowledge.
I visit the site daily, and feel lucky to be part of a thought provoking positive community of many with much more experience than me to learn from.
As one quote from Warren Buffet that you use on the site says “risk comes from not knowing what you are doing” and it’s all our responsibility to ourselves to learn.
Up to you, but if someone posts that they have done “extensive research and found that someone else is to blame for all their lives issues” I wouldn’t.encourage them with a comment. They are only doing it for attention.
keep up the great work, learning is growing and I’m truly grateful for the growth I’ve experienced that has been prompted by your and the teams excellent work.
Regards
JW
I would never give credit to Paul and/or Graham for the shares that I invest in going up, so I can't blame them for the shares that go down :)
You have to DYOR & take full responsibility for the results. When you have a loss, make sure you learn the lesson and don't repeat the mistakes. To quote Oscar Wilde 'Experience is the hardest kind of teacher. It gives you the test first, and the lesson afterward'
Just to add, I really enjoy the podcasts, especially part 2.
I have to say the quality of the analysis on these reports is the best I've come across (especially if you consider the sheer number of companies that are covered). However, they should only be treated as a source of ideas, to complement your own much more detailed research. Only then can you decide if something is worth buying.
I personally avoided all the companies you mentioned, as I was very negative on retail/hospitality businesses last year - so that was more of a macro view that I held. I think investors need to start with a good top down view, as that will determine which sort of sectors you want to be invseted in.
With reference to the post today by bensummers I hold Polymetal International (LON:POLY) and have done since Nov 2020. I shall be writing to my broker HL to ask if they will be issuing any guidance on the decision by the Board of Polymetal to move their listing from the LSE to Kazakistan. This has been under consideration for some time. I only hold 1,000 shares.
hi Paul - hVIVO (LON:HVO) has no revenues coming from covid related stuff in its forecasts. It is the only commercial human challenge study provider so I don't think you need 3rd party confirmation of its world leader status.
A global pharma has recently announced that regulators in the US have approved its RSV vaccine that went through an hVIVO (LON:HVO) challenge study program, so if you want evidence of the tangible benefit to pharma and bio-tech you probably need look no further than that.
The cancelled contract was badly worded. It was in the half year but had previously been announced. hVIVO (LON:HVO) got something like a net £1m benefit from that for doing no work. Deposits are non refundable but capacity freed up can be re-sold. Cancelled contracts are par for the course in pharma as programs slip or new data comes to light etc. so it will happen from time to time. The benefit hVIVO (LON:HVO) have is that whilst a cancelled contract might reduce revenues the non refundable deposit means they still make most of the margin on the contract without doing the work - ie it is just profit that drops to the bottom line.
Interesting, thanks david. I do think it's vital to get third party confirmation of things that companies tell us. All too often, we rely entirely on what companies say, which can distort reality quite a lot in some cases.
After stuttering in 2022, this morning's update from Water Intelligence (LON:WATR) suggests that they are right back on track in 2023. Q1 revenue was ahead of my expectations in every segment and profits and earnings are kicking on again.
Very pleased.
Excellent update from Avation (LON:AVAP) this morning
Last plane now leased so fleet is fully utilised and growth can begin again. This also means profitability and cash generation will be up.
Nav looks like 275p and most lease companies trade 0.9 to 1.1* so at 120p the valuation looks highly anomalous. Brokers think 250p
Debt is all hedged at 6% (from memory leasing rates are in excess of 12%) so excellent margins. Remember the debt is a mortgage on the plane inventory so the debt capital gets paid off each year by the lease payments. At the end of the lease Avation (LON:AVAP) have a fully unencumbered plane that's less than half way through its useful life. They can then sell or re-lease. That's how the NAV grows.
2 new ATR planes on order so growth in fleet and profitability starting to come through this year. There is high demand for planes and ATR are very fuel efficient. Good to see they are getting certified for sustainable fuel too as this will facilitate marketing.
With air travel getting back to normal across the world I'm surprised this hasn't re-rated more yet. Patience I guess :)
Paul, can you take a look at Vertu Motors (LON:VTU) please?
Paul - do you anticipate getting to Vertu Motors (LON:VTU) today?
Yes, my comments on Vertu Motors (LON:VTU) are up now :-)
According to ADVFN there have just been 7 consecutive purchases of 4009 shares in Vertu Motors (LON:VTU) at 61.5p
What sort of trader does that, and why?
According to ADVFN there have just been 7 consecutive purchases of 4009 shares in Vertu Motors (LON:VTU) at 61.5p
Exercise of options, perhaps?
"According to ADVFN there have just been 7 consecutive purchases of 4009 shares in Vertu Motors (LON:VTU) at 61.5p
What sort of trader does that, and why?"
Answer - bots - they are all 'A' trades.
Intriguing. What's the purpose of using bots to trade in this way?
Tclarke (LON:CTO) The market dynamics probably prevent this from ever being a high margin business. The key to its successful growth appears to be based on meeting customers’ expectations and having a tight grip on bid pricing, aligned to excellent project and technical management skills. In essence; being better organised than its competitors. (I hold).
Further to your points Paul re Boohoo (LON:BOO) yesterday re its suppliers, there have been other news items recently which paint a negative picture of the business:
The results on 16 May should be interesting...
Paul
How do you manage to only hold 10 positions? Your total portfolio value must make it hard to buy or sell small caps when so many are illiquid.
I too value your podcasts highly. Thanks for doing them so regularly.
The Oakley announcement is a masterpiece of obfuscation and really useless to an investor
Hi Raidersfield,
Amazing how often that lovely word obfuscation is used these days in both business and politics
Even better look up Obscurantism on line if you are curious
Hi Raidersfield,
Amazing how often that lovely word obfuscation is used these days in both business and politics
Even better look up Obscurantism on line if you are curious
Hi Raidersfield,
Amazing how often that lovely word obfuscation is used these days in both business and politics
Even better look up Obscurantism on line if you are curious
Apologies all - Stocko gave me an error message twice after I clicked post - Seems it triplicated my little reply! I then didn't spot it in the editing period
The Q3 TU for J D Wetherspoon (LON:JDW) is worth reading, if only for the tables at the end about net contrubtion to HM Treasury, length of service of employees, and so on. Tim Martin is a good communicator. SP understandably firm this morning.
Slightly off topic but is anyone else who uses Google Sheets finding that it has stopped displaying share prices for some shares? Any idea of a workaround?
Hi PatrickL, yes I'm also finding that Google Sheets is not updating some share prices on my watchlists, which is a real nuisance, as the whole spreadsheet doesn't work. Let's hope it sorts itself out.
Yes, it does this from time to time. I have never found a workaround but it usually resolves itself in a few days.
I think Google finance used to cover overseas stocks (norway) but not now. Also more recently watkin jones. I thought this was just me.
if you are OK with Google macros, I remember one that parses yahoo finance. I am really only interested in one of my folios so I copy one of the views to clipboard, paste into sheets and then lookup (a little clunky)
** Breaking News!!! **
Google sheets share price lookup is working again!
My 2023 small cap value/GARP watchlist is now up 12% YTD, I'm pleased to say. So the commenter below who thinks all my analysis is crap, can stick that in his pipe and smoke it ;-)
Not using Google Sheets here, but my bit of macro code that scrapped and entered Google prices in Excel just failed (completely) , after years of trusty service! However, as a result I discovered the Shares data type in Excel 365, which does a more seamless job, and covers a number of stocks and prefs that I used to have to enter by hand.
Polymetal seem to be delisting from the UK re-domiciling in Kazakhistan...
https://uk.advfn.com/stock-mar...
anyone knows a broker that will allow you to trade stocks trading in Kazakhistan?
Vertu Motors (LON:VTU) I do love a business on a low price to sales ratio and Vertu is certainly that. Acquisition integration on track, profits ahead of expectations, strong sales, strong after sales, used car prices still strong, debt coming down, dividends up, more share buy backs, Net Tangibles in excess of the share price and in my opinion one of the best CEOs in Robert Forrester who has seen off the disruptors and proved the doomsayers so wrong. I think private equity takes this one out within 12 months, I believe TDR Capital have taken a 3% stake, I hold and will be topping up.
Paul, your podcasts are throughly entertaining, very informative and something I and many others look forward to every Saturday, hope to introduce myself and buy you a drink at Mello, thank you.
I hope it doesn't get take out if I am honest (and I've had nothing taken out for 4 years.) Management here seem to be doing a really good job of allocating resources between buybacks, dividends, paying debt and investing and continue to move the company forward.
Very little not to like here in my opinion
Re Vertu Motors (LON:VTU) Burnt Onions, it's our biggest holding and I agree with your assessment and forecast.
Have just been looking through the list of major shareholders - TDR not registered yet - Came across Tweedy Brown - a small US investment house - reckon they must be followers of Warren Buffet - good for them and all adds to encouragement for us small people
But how accurate is Stockopedia information on major shareholders? Came across one stock last week where it was very wrong. Vertu Motors (LON:VTU) has not been updated since January, 2023. But maybe 3% is too small to include?
I think it only lists out the top x holdings, so looks like 3% is only big enough to be included in others
I have no interest in Vertu Motors (LON:VTU) but find some of the comments here strange. From my use of Stocko I don't think that either 3% holding is too small or that there is a maximum number of holders in the institutions view. I suspect the simple fact is that they have failed to pick up this RNS (rather than from the 'motoring press'!): https://www.londonstockexchang...
If you really want to DYOR then go to https://find-and-update.compan... type 13634625 into the box then call up the 2022 report and a/cs and read 'Other Developments' pp5,6 and then 'Business Model' p7 ff.
Yes apparently the stake was taken via Constellation Automotive as revealed in the motor press last February. I don't know why Stockopedia doesn't show it.
Tweedy Browne is a very well-known, conservative US investment manager. It manages around $9bn which is indeed small by US money management standards but managers, employees past and present have a lot of 'skin in the game'.
An in line TS from Luceco (LON:LUCE) which I hold is welcome news following the slide in the share price over the last 12 months . In recent times your preference has been Volex (LON:VLX) in this sector but Stocko has Luceco winning hands down when you run the comparison checks . Would be interested in your thoughts .
Hi fred9566,
I've just had a quick look at Luceco (LON:LUCE) - too tired to write up anything now in the main report, but I think it looks quite good. Forget the surge to 400-500p in the pandemic, that was an aberration, as the company and the market mistook a pandemic boom in DIY for structural growth.
Has the share price now overshot on the downside? Maybe a bit, but I think it's probably come back down to where it should be, in tough macro conditions.
That said, I like that LUCE has the owner's eye, and seems well managed. A current year PER of about 11 isn't expensive by any means, especially with today's reassurance that it's trading in line.
4% dividend yield, and a high StockRank, so overall I'd say that I'm between AMBER and GREEN on Luceco, and certainly wouldn't try to dissuade anyone from buying or holding it.
Although as we were discussing yesterday, with the profit warning from Marshalls, the building supplies space does feel like it's not a great place to be right now, with new housebuilding starts well down on last year, and RMI also subdued. Tricky one! Your money, your choice :-)
Regards, Paul.
My morning smallcap tweet: Unbound's £10m injection from Marwyn wasn't a shoe-in.
Unbound (LON:UBG) SRT Marine Systems (LON:SRT) Live (LON:LVCG) Cellular Goods (LON:CBX) Skinbiotherapeutics (LON:SBTX) Avation (LON:AVAP) Cenkos Securities (LON:CNKS) Quantum Blockchain Technologies (LON:QBT) Vertu Motors (LON:VTU), Luceco (LON:LUCE), Grc International (LON:GRC), Tclarke (LON:CTO), H & T (LON:HAT), IXICO (LON:IXI)
◄Unbound (UBG)► Marwyn withdraws offer to buy £10m of shares at 10.5p, citing principally concerns over current trading. Q1 rev below mgmt exp. Profit broadly in line due to cost cuts. Co will probably need further covenant waivers. Talks on raising additional funding or refinancing. [SP=7.33 Cap=5m]. I hold goddamit.
◄SRT Marine Systems (SRT)► £20 million increase to medium term note capacity in anticipation of some significant new system contracts. [SP=NA Cap=NA]. I hold.
◄Live Company (LVCG)► sells two of its underperforming tours Mythical Beasts and Outer Space for £350k. Co will not get funding from Jason Lee as mooted. Talks to get finds elsewhere. [SP=NA Cap=NA]
◄Cellular Goods (CBX)► skincare range to sell on the leading Sephora website. [SP=0.59 Cap=3m]
◄SkinBioTherapeutics (SBTX)► positive update from Sederma (Croda) team on progress of its work with SkinBiotix. AxisBiotix-Ps sales have commenced in Spain. [SP=NA Cap=NA]
◄Avation (AVAP)► leases the last remaining aircraft from inventory. [SP=NA Cap=NA]
◄Cenkos Securities (CNKS)► AGM stmt: rev continues to track ahead of the average run-rate for H2 2022. [SP=38.04 Cap=22m]
◄Quantum Blockchain Technologies (QBT)► algorithm Method B "has theoretically [huh?] increased the rate of successful bitcoin mining by 2.6 times compared to standard." Cuts electricity consumption by 4.3%. Why so little? [SP=NA Cap=NA]
◄Vertu Motors (VTU)► FY-Feb ahead of expectations with adj EPS 9.16p (17.92p). Div 2.15p (1.7p). Current trading strong. Further £3m share buyback. [SP=57.63 Cap=201m]. I hold.
In line: LUCE, GRC, CTO, HAT, IXI
Morning Paul - podcasts (both parts) are really useful, entertaining and great to listen to whilst I'm in the car & supplement the SCVR & everything else I look at really well. It's difficult to find anything audio based which covers the smaller end of the UK market, so this really fills a gap!
Thanks very much for taking the time to pull them together and long may they continue!
Interesting update from Oakley Capital Investments (LON:OCI) today. I have a substantial holding. The largest holding, UI, is being sold and refinanced. This represents a sale worth over 25% of the fund, easily the largest holding in the fund.
I found the announcement rather opaque though; it didn't seem to overtly say that it's a cash deal, nor the impact on the NAV. Come on Oakley Capital Investments (LON:OCI) ; more clarity please.
Sorry, just realised that the impact on NAV versus March valuation is zero. They did say that in a slightly roundabout way ...
Agreed it wasn’t clear. Whilst it’s factored in its showing accuracy if their NAV which is why a lot of these have steep discounts at the moment.
Thanks for circling back to Eckoh (LON:ECK)
Podcast is one of my few weekly must do's Paul, now that I am happily and disorganisedly retired. Thanks from me too.
If you can get to Vertu Motors (LON:VTU) today, as a holder I would be very grateful.
Just a line to say, your podcast is superb. Thanks for your effort Paul.
How kind, thanks Mo! It's nice to get feedback, as it's usually a wall of silence, so I don't know if people find them useful/entertaining or not some of the time :-)
Hi Paul, Podcast is good and a happy mix of entertaining and info. I would just suggest if Graham can give you a couple of comments to mention from his reviews to go along with your excellent more detailed summary of your own reviews. Goodbyeeee !
Hi littledavesab,
With my podcasts, you have to remember that they're free to access. So I have to walk a tightrope between making them interesting, but also not giving away too much stuff that is useful to subscribers and behind the paywall.
Hence why I don't say much about Graham's sections, in a way it's intended as a teaser to encourage people to subscribe (hopefully)!
Regards, Paul.