Small Cap Value Report (Wed 11 Jan 2023) - COG, W7L, NICL, HSW, RCH, SCE, ABDP, SBRY, BOO, FRAS, DLG, ADM, TEG, LOOK

Good morning from Paul & Graham!
Today's report is now finished. Lots more to cover, but I've run out of time & energy!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda
Absolutely loads of updates today, plus some backlog items. So we'll focus mainly on short sections, covering as many companies as we can.
Paul's Section:
Cambridge Cognition Holdings (LON:COG) [quick comment] (I hold) - in line with market expectations trading update. Interesting acquisition of Winterlight Labs for £7m (£3m cash, £4m shares with 6m lock-in, c.10% dilution). Acquisition seems to be loss-making, but with exciting-sounding potential - it talks of “major growth”from specialism in speech-based digital biomarkers. Strong order book. Cross-selling opportunities. Sounds interesting, but does this mean the enlarged group will become loss-making again? Does that matter? Will be interesting to see how a market that’s turning more bullish sees this. It could add some spice to the way COG is perceived, if bullish conditions develop further maybe?
Warpaint London (LON:W7L) - another positive trading update, ahead of expectations, from this makeup company that has been on a roll for some time. I work out the valuation (in the absence of broker notes) and think it looks bang in the middle of what seems reasonable. Update - a note from Shore Capital has just come through! Therefore despite a strong run up in share price recently, I think the fundamentals justify & back up this price rise. More detail below. Thumbs up from me!
Reach (LON:RCH) 80p (down 27%) mkt cap £253m. [quick comment] - a disappointing Q4 and FY 12/2022 update has clobbered the share price by 27%. Main problem is worsening trend in advertising revenues - down 20% in Q4, down 16% YTD - due to macro & consumer uncertainty, advertisers are spending less, as I would expect. Circulation revenues up slightly in Q4 (due to cover price rises), YTD only down 1.7%. More cost-cutting of c.£30m planned. “Challenging market” to continue in 2023.
Profit warning - operating profit for FY 12/2022 below expectations by c.5% (previously £112.8m, now c.£107m). Is the 27% share price drop an over-reaction? Maybe not, as 2023 forecast (Singers) EPS comes down 16% to 22.7p. But the PER is only 3.5! Divis look well-covered, so should be a hefty yield too. Pension scheme uncertainty - still swallowing a lot of cash. My opinion - worth investigating further at this lowly valuation. Ad revenues could recover once recession over (in 2023 or 2024?). Seems strange that forecasts didn't already factor in a worsening ads revenue trend, given the macro picture. Why is the market surprised that it's slowing, isn't that obvious?
Surface Transforms (LON:SCE) (down 3% to 37p - mkt cap £88m) [quick comment] - shares have been drifting down recently, in a market where lots of small caps have been bouncing strongly. SCE is a specialist maker of high end brake discs. Today it says production problems in Nov & Dec have resulted in 2022 revenues of £5.1m falling short of forecast (shown on the StockReport as £6.4m). Although this is still well over double 2021 revenues.
Outlook for 2023 - says unchanged guidance, and expects a maiden profit.
My opinion - I’ve not researched SCE in great detail, but my general view is that the shares are almost impossible to value at this stage. It has exciting orders & big demand, but today’s update is a reminder that massively scaling up production of innovative, highly technical products, is not easy, and there will be problems along the way. The drop of only 3% in share price today suggests that SCE shareholders are already fully aware of this!
I’m happy to say this share does look one of the most credible jam tomorrow growth companies on the UK market, with real products and big orders. How to value it? You have to just make assumptions about future results, build in a margin of safety, and then hope that management are able to deliver, and that no competitors develop anything better & cheaper.
Very quick comments on some larger caps (possible read-across for small caps?) -
J Sainsbury (LON:SBRY) - reports a strong Christmas, and indicates profits towards top end of £630-690m range. Argos did well, benefiting from its own distribution network during postal strikes. Big pay rise (10%) for staff recently announced (putting pressure on other sectors for scarce staff). My view - surprised! The media have previously reported that Aldi/Lidl were winning market share, as people traded down. So SBRY also doing well is interesting. It does beg the question over whether the consumer downturn is actually as bad as we fear? Or have people had a Christmas splurge, before hunkering down in 2023?
JD Sports Fashion (LON:JD.) - shares up 7% today on a positive trading update. Revenue growth accelerated, and reached over+20% in December. Profits toward the top end of broker forecast range £933-985m. Outlook - guidance for FY 1/2024 is "just over £1 billion" profit. This share looks cheap to me, considering the phenomenal long-term performance of the business, and continued expansion internationally.
Boohoo (LON:BOO) - press reports that it's cutting 100 jobs in its London HQ. Doesn't suggest that things are going well. So I'm worried about the next update here, particularly as the evidence so far (e.g. from Next (LON:NXT) ) is that shoppers are returning to physical stores. Has fashion online peaked, or even in decline now? We'll find out when they next report.
Frasers (LON:FRAS) - is relaunching Missguided brand acquired (a boohoo competitor than failed) as concessions in its stores. There's been stunning EPS growth at FRAS in the last couple of years. The manic pace of brand acquisitions does worry me though, and I'd lean more toward JD Sports as a safer bet than this.
Direct Line Insurance (LON:DLG) - shares have crashed 27% today on a profit warning, and cancellation of the divis - a key consideration, as the forecast yield was almost 10%. It blames bad weather, causing more car accidents (and higher repair costs), underwriting losses on home policies for burst pipes, etc. Also notes drop in value of its commercial property investments. Has the value of the business really fallen 27% just because of one bad patch? Seems extreme. Looks as if there's sector read-across, with Admiral (LON:ADM) down 9% today. I'm wondering if this might affect Saga (LON:SAGA) too? So have decided to close my (small) position there, just to be on the safe side, and it has roughly doubled from the recent low. I'll watch from the sidelines, and decide whether or not to buy back when it reports shortly. Let's hope Sod's Law doesn't intervene with a takeover bid in the meantime, which is always a risk when you sit on the sidelines.
Lookers (LON:LOOK) - see section below, where I look through today's positive trading update, ahead of expectations for 2022, with profit guidance raised almost 10%. This results in a super-low PER, with a nice divi yield, buybacks, and strong asset backing also thrown in. We know that bumper profits are likely to ease back in future, but the 2023 forecasts are already set very conservatively, and it's still cheap on a low multiple of a soft target. Lots to like here, so I award it a thumbs up. (more detail below)
Graham's Section:
Nichols (LON:NICL) (£401m pre-market) - we covered the most recent interim results for Nichols in some detail here. Today we get a full-year trading update from this soft drinks group. Adjusted PBT for 2022 is anticipated to be in line with expectations, despite the “ongoing inflationary pressures” that have been repeatedly highlighted by management here. The key Vimto brand has performed well both at home and internationally, and it appears that the logistics issues that plagued the company have been resolved as Vimto’s H2 international revenues increased 48% year-on-year.
Furthermore, Nichols has continued to benefit from the post-Covid normalisation of trading as “Out of Home” revenues have bounced 43% year-on-year. Nichols is now finishing a Strategic Review with the goal of improving margins from this route to market. Given the inflationary pressures and the expected weakness in consumer demand in 2023, the company is not expecting adjusted PBT to increase this year, but it’s more optimistic for 2024 when it expects that inflation might cool and its strategic actions to improve margins will have taken effect.
I continue to view this as a company of the highest quality, even if it is currently “ex-growth”. Profits have stalled over the past 5 to 6 years, and so has the share price, even though the company’s revenues have grown considerably. I think the shares could be interesting here, if we take the view that margins can normalise and profits will finally start to grow again.
Hostelworld (LON:HSW) (£137m pre-market) - this online travel agent confirms that trading has been in line with guidance through December and the beginning of 2023. For the full-year 2022, it generated net bookings of 4.8 million, far higher than the Covid-stricken performance in 2021 which saw only 1.5 million bookings. Along with the revenue growth, the company is also improving its profitability with marketing (as a percentage of revenue) reducing from 70% in H1 to 52% in H2. The company has hit its target of positive adjusted EBITDA for the year of €1m (as I mentioned last time, doing this would require a €10m positive swing in performance from H1 to H2 - a fine achievement!).
The company is pitching itself as a social network for travellers and while I think scepticism around that claim is easy to justify, it’s harder to argue against the strong improvement in trading that the company has achieved. The strongest bear argument, in my opinion, relates to the balance sheet and the high-cost €30m debt (charging 9% + Euribor) which I fear is going to eat up a significant portion of the company’s operating profits in the near-term. For this reason, I’m neutral on the stock.
Ab Dynamics (LON:ABDP) (£370m) (-0.5%) [no section below] - this provider of vehicle testing services and products has issued an AGM statement for today’s meeting. Thankfully, performance has been in line with expectations during the first four months of FY August 2023. The order book is “solid”, with “good visibility” into H2, and the integration of its recent acquisition is proceeding as planned. Net cash remains positive at £17.6m despite the cost of the acquisition, and expectations for FY 2023 are unchanged.
This statement contains very little new information and so I have to keep my stance on this stock unchanged: I continue to believe in the quality of this business, and in its post-Covid recovery, and I have no reason to distrust management’s M&A strategy. My difficulty is that I can’t fathom how it can be worth nearly £400m, especially in a bombed-out UK small-cap market. With so many cheap investing opportunities in this market, I fail to understand why ABDP is rated as if it were a US tech stock.
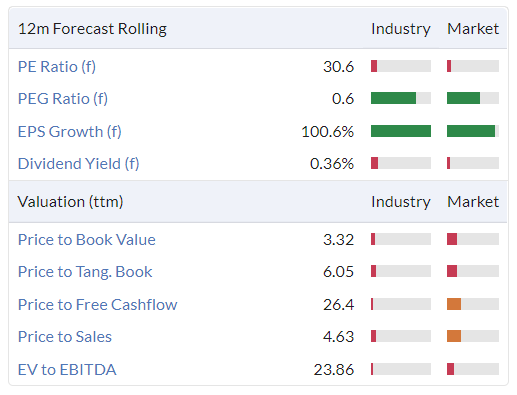
Ten Entertainment (LON:TEG) (£196m) (-2%) [no section below] - this bowling hall operator gives us a full-year update with some positive headlines. 2022 produced the company’s strongest ever trading performance: like-for-like revenues are up 5.5% against 2021, and up 39.8% against 2019 (the last pre-Covid year). Like-for-like revenues measure the same sites over the same time period. As discussed by Paul in September, it appears as though the company has reached a new baseline of higher visitor numbers and revenues at its sites. Adjusted PBT for 2022 is now set to come in at the “upper end of market expectations” (£25 - 26.1m).
Eleven centres were refurbished or upgraded during the year, i.e. almost a quarter of the entire portfolio, and the company reassures us that it is up to date with its capex spending. A handful of new centres are opening in 2023, too. Additionally, the company has finished the year with £10m of net cash and has helped its lowest paid staff members with pay rises brought forward six months.
In my view, there’s nothing to dislike in this announcement. While it may seem odd that the shares haven’t risen today, they are actually up 15% compared to a week ago, i.e. the market had already priced in this excellent trading update. Some may worry that the novelty of bowling might wear off as we move further into a post-Covid, “normal” trading environment. Personally, I like what I see here but as it’s a capital-intensive sector, I do think investors need to be careful not to overpay for shares such as this one. Therefore, it looks priced about right to me at a PER in the region 10x.
Paul’s Section:
Warpaint London (LON:W7L)
190p (pre market)
Market cap £146m
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands is pleased to announce a trading update for the year ended 31 December 2022.
This looks good - ahead of expectations -
“Particularly strong” trading in Q4
FY 12/2022 revenues guidance raised from previous £61m, to £64m
Adj PBT guidance of £10.0m - up from previous guidance of at least £9.0m.
Margins improved vs LY
Strong balance sheet (I confirm this is true!) with £5.8m cash and no debt.
FY 12/2022 results will be published in April 2023.
Outlook -
We enjoyed a strong trading performance in Q4 2022 across the Group, with sales growth in the US and online being particular highlights.
"We expect to see a continuing strong performance in 2023 and I look forward to updating further at the time of the release of the Group's results in April."
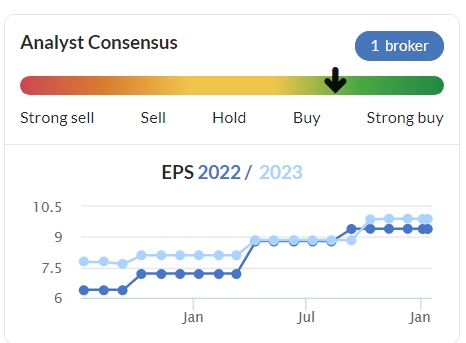
Broker updates - Shore Capital has put an update note on Research Tree, many thanks. It has raised 2022 to 10.5p, but leaves 2023 at 9.9p, which looks too pessimistic. Hence ahead of expectations TUs are likely in future, and upgrades. I like it this way, as modest forecasts should mean there's low risk of a profit warning.
Stockopedia broker consensus data is just from 1 broker, but shows a nice progression, and we’re now about 10% ahead of these numbers. So I would value the share on a multiple of maybe 10-12p EPS. What multiple? Maybe 15-20, since the company is growing nicely and keeps putting out positive updates.
That results in my valuation range between 150-240p. The actual share price is currently 190p, right in the middle of my range, suggesting that this share is fairly priced right now.
This is impressive given macro conditions. Bear in mind also this is as of yesterday. So there will be a further increase of about 10% in these lines after today's update -
My opinion - this is one of my favourite value/GARP shares, and we’ve been reporting positively on it for a while. The shares have had a nice run recently (as have many things), but the strong fundamentals and positive trading updates justify the price rise at W7L, whereas with some other companies I think rises have maybe been somewhat spurious/speculative, so could reverse.
Since the strong fundamentals support the current valuation, W7L looks good to me, so it receives a thumbs up.
Lookers (LON:LOOK)
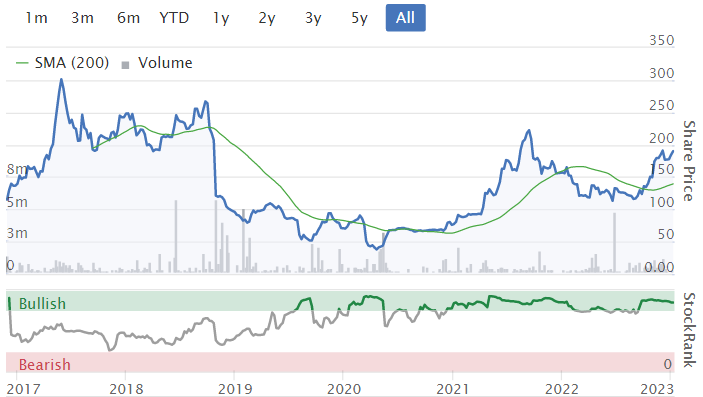
81.3p (up 4% at 11:33)
Market cap £313m
Lookers, one of the leading UK integrated automotive retail and service groups, today provides an update on the business, including trading for the three months ended 31 December 2022 ("Q4" or the "Period") and the full year.
Strong finish to 2022 - further increase in full year expectations
It's now expecting to make at least £80m underlying adj PBT for FY 12/2022.
2023 Outlook -
The Board is encouraged by the strength of trading in Q4 and the magnitude of our new car retail and fleet order banks entering into 2023. However, we are also conscious of the potential impact on consumer spending by external factors such as high inflation and interest rates. We begin the new financial year with confidence in the resilience of our business model and 'omni-channel' customer offering, and as such the Board's expectations for 2023 remain unchanged.
Liquidity - has net cash of c.£70m (up from just £3m a year earlier). Working capital is huge though, so there could be large movements of this number on a daily basis. I’d like to know what the average daily cash/debt figure is (for all companies), as that’s far more meaningful than a one-day snapshot (which can easily be manipulated to give a flattering picture).
Balance sheet - LOOK reminds us today that it owns freeholds in the books at £297m. It says that property & cash totals 95p per share, but this is misleading as it ignores liabilities. The actual NTAV per share, which includes everything apart from intangibles, is 58p per share - that’s the figure that matters, and it’s below the 83p share price. Overall though, this share is nicely asset backed, so everything’s fine.
Diary date - 5 April 2023, for FY 12/2022 results.
New brands - has signed up as a franchise partner for ORA, a Chinese electric vehicle maker entering the UK market. I suspect we’ll see more of these Chinese brands coming here. ORA’s website shows that you can buy through a retailer (Lookers is listed), or buy online (direct presumably?). AutoExpress review the ORA Funky Cat here, giving it ⅘. Personally I think it’s ugly, and for similar money, I’d go for a Mini Electric. It might take the UK public some time to embrace unknown Chinese brands instead of well-known European ones.
Also a Lotus showroom is opening shortly in Belfast.
Broker forecasts - thanks to Zeus for an update. It raises FY 12/2022 PBT by 9.1% to £82.5m. This equates to 17.0 EPS. The PER is now only 4.8!
Obviously the market thinks earnings are not sustainable at this level, but that’s what everyone said this time last year, and 2022 actual out-turn was only a little below 2021’s bumper earnings.
Eventually vehicle supply will get back to normal, and margins probably normalise at a lower level, but who know when? Meanwhile the car dealers are coining it in still.
Zeus has a big drop to 11.4p pencilled in for FY 12/2023, which is going all the way back down to 2016 & 2017 profits, which seems very conservative to me. Hence I’m comfortable that even if market conditions worsen a lot, LOOK should be able to still say it’s trading in line, or even above, the current very soft forecasts for 2023. That’s a nice setup, and should mean profit warnings are unlikely even in a down market.
People tend to lease new cars now, so they’re not really particularly big ticket items any more - e.g. I got a new Audi A4 recently on a personal lease, and it’s only £275 per month. Insurance is dirt cheap, and repairs won’t cost anything, so it makes a lot more sense than buying a car outright, or buying secondhand, in my view. But there’s a wait on new cars, as production problems are still limiting supply.
Bottom line, is that even on soft 2023 forecast of 11.4p, the PER is still only 7.1 - which I think is very cheap.
My opinion - I remain a fan of the car dealers, because they’re classic value shares - substantially asset backed (freeholds), combined with low PERs and quite good yields (plus buybacks in LOOK’s case).
We know they’re enjoying a boom at the moment, due to restricted supply (hence high margins), but a full return to normal is already priced-into the shares.
Sector consolidation is a big theme, so bids could come in at any time. Plus we might see the demise of the numerous online-only startups, as they run out of VC/PE cash piles, which should benefit the traditional dealers as there's less competition for stock and customers.
There’s lots to like with this sector generally, and LOOK seems one of the best. A thumbs up from me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Warpaint London (LON:W7L) I’m circling back to this week’s results so apologies for being tardy
I was happy with this weeks TU & in particular the mention of sales growth in the US as this looks to be a key growth opportunity for them
Their US based NED resigned earlier this month so hopefully they’ll soon announce a new suitably experienced one & given their Board is currently 100% male I rather hope it’s a woman (it is a make up company after all & as a female investor I do like to see women on the Board of companies I’m a shareholder in)
Great to see that Paul is shortly to record an interview with Sam too- I shall look forward to that
Cambridge Cognition Holdings (LON:COG) - I really don’t like this acquisition. I could complain that the addition of another loss-maker to the portfolio clouds the financial picture and delays the achievement of positive earnings by another couple of years. But what really pisses me off is the thought that a business earning a paltry £10m in revenues feels the need to spend another £7m to take that number to £11m. And acquire 28 staff generating less than £40k each per employee at a loss of £75k per head.
Just sell some more of your own flipping tests! Or are we finding out that COG has already exhausted the TAM for its in-house capabilities?
Of course I know even less about cognitive assessments than I do about value investing so it could be a masterstroke - but I perceive better risk/reward, and far more liquidity, elsewhere in the life sciences field.
The Direct Line Insurance (LON:DLG) RNS highlights a point I have made previously. I occasionally see comments that companies have strong balance sheets which are underpinned by freehold properties. Direct Line say, '..our investment property portfolio has experienced a c.15% reduction in values, equivalent to £45 million.' What worries me is that a lot of companies will find that freehold properties are worth less each year, particularly those like car showrooms and large pubs because of continuously increasing energy efficiency targets. The government has proposed an interim target of a C rating by April 2027 but a bigger risk is that it pushes ahead with a requirement for B by 2030 - only 7 years away and an impossible target for a huge part of the UK's commercial property estate. 7 years may seem a long time but if the B target becomes a reality valuers will start discounting it straight away.
https://assets.publishing.serv...
Re Cambridge Cognition Holdings (LON:COG) - I think looking for acquisitive growth at their stage of development and growth with their in-house products (ie early and much to do to prove out very high valuation) hints that that they have a growth problem or blockage somewhere (a statement that needs to be assessed relative to high valuation).
IMO the company is likely to de-rate further unless acquisitions provide lots of growth...in which case it still leaves the question as to why give it such a high multiple...
Undoubtedly its a company that has performed much better under CEO Stark, nevertheless price and growth matter.
Paul writes: "The media have previously reported that Aldi/Lidl were winning market share, as people traded down. So J Sainsbury (LON:SBRY) also doing well is interesting. It does beg the question over whether the consumer downturn is actually as bad as we fear?"
I think this has to be put in the context of food price inflation. Before Christmas 2021 I was paying 109p for 4 pints of milk and 99p for a sliced Hovis 800g. Now they are 165p and 145p. That is +51% and +46% suggesting that with the big 3 revenues up 6% there is reduced volume.
Here's the complete picture with Aldi and Lidl gaining market share:
I shop at Aldi and Morrisons, although hardly buy anything in Morrisons now, their prices have gone up too much, in my opinion and also many others, the large store is very quiet now compared to 2 years ago, whilst Aldi is busier than ever. Morrisons need to do a lot cost cutting to get their customers back. You are right about prices going up, some items have nearly doubled, even in Aldi.
How interesting, thanks sharw! Very good point re prices & volumes.
My partner and I live in different parts of the South-east England and I was keeping an eye on footfall just before and after Christmas and it does feel like there's a split occurring within the consumer base. It appears to me that, despite talk of recession and cost of living crisis, there are groups of shoppers that are still able to splash out and appear comfortable with their spending.
Her son and his girlfriend both work in clothes shops selling clothes with high price points and they both reported back that they were very busy both, before and after Christmas.
i made the point of speaking to a few retailer cashiers in the run up to and through christmas, asking if people were cutting back, in a few cases I was told they wre 'seeing a lot of credit cards being used' people seem to have put this year onto debt, and I did anticipate a decent christmas reporting, and Marks and Spencer (LON:MKS) are updating imminently too
I'm wondering if today's RNS from Direct Line Insurance (LON:DLG) is specific to that company, or if there's a read across to other insures including Saga (LON:SAGA) .
It's hard to say from the RNS. Seems odd that a snap of bad weather in the UK can have an impact such that the divi needs to be cancelled. Periodic floods, freezes etc are not rare - they're bread and butter events for insurers. Ditto the stated rising costs of car repairs. Surely a competent insurer would see these costs steadily rising and steadily adjust quoted premiums accordingly.
Also it is alarming that Direct Line Insurance (LON:DLG) can suffer a £45m write down in property assets in one quarter alone. I never knew insurers held such illiquid assets, at least in amounts that could wipe out 20% of a year's typical profits in a single quarter.
So is Direct Line's balance sheet weaker than appeared, has there been sloppy underwriting practice perhaps? Or is general UK insurance been so competitive that all general insurers have been underpricing and will also suffer immenent losses?
I have been a long term holder of Direct Line Insurance (LON:DLG) . Summary: great dividend income but NAV per share as flat as the Norfolk broads. So the entire investment case has been the dividend income, and this has now gone. (Share price performance is distinctly underwhelming.)
Right now I've no idea if insurers might be a bargain (temporary blip) or if this is the start of something worse. Reading Direct Line's statement suggests a one-off problem, The only thing is how much confidence can be put in directors' views? Shouldn't management which was on top of its business (e.g. like the superbly run Next (LON:NXT) ) have seen this coming?
Car insurers have no doubt faced a few headwinds recently , but Direct Line seem particularly incompetent recently. Wouldn't necessarily read across too much to the other car insurers, who have hopefully managed risk a bit better. I am also very surprised they hold such large amount of commercial property on their balance sheet - this makes sense for the life insurers who have longer liabilities, but doesn't make sense for Direct Line whose liabilities are short dated. Definitely one to avoid until they sort things out.
I think we can expect a bounce in premium costs if nothing else in the coming months. I hod Admiral (LON:ADM) Aviva (LON:AV.) and Sabre Insurance (LON:SBRE) with Direct Line Insurance (LON:DLG) never being contemplated.
Silver Moon - May I ask why you never contemplated Direct Line? Obviously that company under its current management must be close to uninvestable but I wasn't aware they were as bad as they have turned out to be.
I did hold Sabre Insurance (LON:SBRE) but have sold today after reading the Direct Line update and re-reading Sabre's updates from July 22 (when the share price collapsed) and October.
I think there will very definitely be a read across to other motor insurers, and Direct Line is better than average in the sector.
As to longer duration or illiquid assets, these are often very reasonable investments for motor insurers.
First, they will have a material amount of long duration liabilities relating to third party bodily injury losses, for which individual claim reserves can be over £10m. Much of this will be reinsured out, but Direct Line Insurance (LON:DLG) carries a fairly large retention that they have increased since 2021.
Second, motor insurer cash flows are not volatile, with a reliable cash inflow from premiums and a fairly stable cash outflow on accidental damage claims. It is safe to put, say, 10% of the portfolio in illiquid assets, comfortable in the knowledge that cash flows are never likely to be such that these assets need to be realised unexpectedly.
Hi Paul - re Boohoo (LON:BOO) - I spoke to a former senior Boohoo employee last year, who indicated that they badly needed to begin to rationalise the acquired Arcadia brands, and that having each brand running independently was causing significant operational issues, as each brand was effectively competing for internal resources with other brands, and work was being duplicated unnecessarily.
So, I wouldn't necessarily take this as a sign of anything to do with trading, and long term, as horrible as redundancies are, it's probably a good sign.
MJ
The Debenhams website is still a very poor shopping experience. I fully expected Boohoo to apply their digital expertise and improve the site when they bought it.
Maybe Boohoo (LON:BOO) oversold their tech prowess?
To be honest THG (LON:THG) shouod be the ones buying up failed brands, given they have ecommerce-as-a-service in their Ingenuity unit.
this make more concerned , refund will be given only 21 days after return
https://www.thesun.co.uk/money...
THG (LON:THG) 's Ingenuity is merely a repackaging of internal IT and slapping a label as independent business unit with high margin growth potential...I might be wrong and maybe it makes it to be what they claim...but on looking into company soon after ipo that was my conclusion...a way to pump up the valuation
Any comments on the trading update from Nightcap (LON:NGHT) will be much appreciated.. given the share price now is it a good time to invest?
Nightcap (LON:NGHT)
On a very quick look - this looks very stretched.
If they are opening new bars and only making £1.2 mil profit and have sizeable debt how are they going to fund new openings. Thats not to say its not worth investing - just seems a highly risky "binary" bet where you could lose a large % of your investment if they need to raise lots of cash and that comes at time when price is lower (or raising is at a discount) to current shareprice. With any share on downward trend and low market cap - the need to raise capital should be a huge red flag unless you are happy to lose a big cunk of your investment if capital raise is needed at say 80% discount or more. Are youy happy they do not need to issue more shares?
Nightcap (LON:NGHT) This might help you decide: https://shareprophets.com/EPIC...
The site needs a subscription but you can read the headlines of the articles.
disclosure: I've never owned this. [I read bits of the Admission Document.]
Thanks for that link Laurie.
I see you have subscribed to shareprophets. What's the service like? Seems like it might be mostly about negative commentary / shorting from my brief (and ill informed) look.
Appreciate any feedback from you (or any other subscribers to the service.
Snazzy
Hi Paul, thanks for sharing the list of GARP shares. I picked up Macfarlane (LON:MACF) after further research. In the back of the interim report it transpires that the pension scheme is fully funded (£8m surplus or 112% funding level). Current deficit payments of £1.4m p.a. are being made, which they clearly don't need to. Surely the company would go to buyout soon. A similar theme across other companies must be happening (I noticed this on MS International (LON:MSI) as well). I wonder if anyone knows companies with large DB pension schemes that they are still funding? Although, TT electronics (LON:TTG) hasn't gone up much since they announced the buy-in of their scheme, I feel the market underestimates the impact of removing pension schemes from the books...
JD Sports Fashion (LON:JD.) put out an upbeat trading update today, it is not just the value retailers that are doing quite well, Next (LON:NXT) also had a good Christmas.
Did anyone notice the enormous drop in reservations at Barratt Developments (LON:BDEV) ? This must have a read across into MJ GLEESON (LON:GLE) . It looks like youngsters are struggling to find the money.
I think it's more people holding off rather than because they're can't afford - why would you want to buy a house right now when mortgage rates so high and house prices likely to fall over next few months? Better to sit and wait.
Certainly houses are not selling very quickly around my area, many have been on the market for 6 months, even with price reductions, they are not selling. 18 months ago, many were going within days of going on the market, some even before they were advertised.
Has anyone other than Mr Contrairian noticed Lookers full year trading update? PBT raised to £80 million and Q4 PBT 2022 above Q4 boomtime 2021. I thought there'd be a stronger read across to Vertu but hey ho, slow but sure?
Cambridge Cognition (LON:COG).
Management stated they were looking for additional growth opportunities a little while ago and they seem to be executing this plan and all from existing resources which is exactly what you want from a small high growth company with a gross margin of 80%.
1. The small acquisition of eClinicalHealth.
2. The partnership with Luca ( who also partner with AstraZeneca) providing an opportunity to capitalise on the second largest market for clinical trials, China. I noted understandable scepticism here regarding the safety of IP in China and I also had concerns. I wrote to Matthew Stork asking about this. Matthew has worked in the industry for his whole career and aware of the danger. He says the company takes steps to protect its IP in all cases and already obtained a small amount of rev in China. He directed me to the section in their IPO application regarding Copywright and registered trade mark. But importantly he also added that there is a more recent additional level of protection provided by APIs (doorways). This means that the source code is not provided but a response is sent when a partner sends a request via an API to a service. I looked into this. APIs are the modern way companies share knowledge. They are as safe as the software and the people operating them, like your front door. Obviously in this age of cyber security worry, there is the chance of an attack, just as in any industry.
3. Today's Winterlight acquisition which COG hopes will give it a leading position in the vocal cognitive impairment market which seems to be growing at 66% per annum, some clip. COG say that by 2026 earnings could be $30m. This is by far the largest of the 3 prongs of growth costing £7m (£3m cash and £4m shares) but comfortably affordable from over £8m cash of balance sheet.
I hope this information is helpful and remind all that I am biased as invested.
Michael
Interesting to see that Questor has chosen an AIM stock ,Premier Miton (LON:PMI) ,as their tip of the year.
Our tip of the year is ‘very cheap, very unloved and highly profitable’ (telegraph.co.uk)
I have been buying Premier Miton (LON:PMI) recently and would agree with what Richard Evans has to say.
The time to buy wealth managers is at the bottom of the cycle, which I am hoping we are somewhere near.
Premier Miton (LON:PMI) goes ev-div tomorrow . 6.3p for anyone that is interested.
Oh no.Hate it when one of my stocks start appearing as tips . Last ex divi is now almost a freebie
Yes a bit of love wont go amiss :-)
Has the market turned ?
Very different feel to the market the past weeks as opposed to the Armageddon of 3 months ago.
Lots of the upward pressures on inflation have evaporated in the past months especially on imported goods
- Gbp to usd received to over 1.20 and probably heading higher , that’s 10% lower buy price
- freight rates are back to normal and even below, we booked a 40 foot container 2800 usd now versus 13000 6 months ago, , that’s another 10% lower buy price than last couple years
These costs will filter through pretty quickly so importers look better placed although demand is still soft if your not in a good spot
Is all about stock selection right now and really looking closely but the general uptide is starting to lift a few sinking ships too so be careful which boat you get on (sorry got carried away with the rising tide analogy )
Thanks for these thoughts planetx.
Sentiment has moved significantly from the relentless gloom and lost confidence observable at points during 2022 - most recently a period in late June/early July and early to mid October.
Most would also agree with the factors/headwinds you call out.
However, there remain many risks which might badly spook the market (a sudden bad turn or escalation in Ukraine, political risk at home with the Government loosing control of the domestic agenda, strikes etc., or more broadly becoming visibly debilitated or divided, and the ever present unknown unknowns or wild cards). On this basis think its very possible the market could easily have a 20% or more set back is quite easy to see - think Paul Scott shares this view.
For these reasons I'm 15% liquid across portfolios and continue to re-circulate income received in established shares showing material weakness. I will buy strongly on a serious market set-back, but if that doesn't materialise in 2023 there will be new companies and situations which emerge which might make promising investments.
Not sure if other subscribers are adopting this approach or are more confident/invested?
Hi Jayman
On this basis think its very possible the market could easily have a 20% or more set back is quite easy to see
This type of figure would take us back to below the October (that budget!) lows which I do find hard to believe will happen, with more tail winds since then, but of course is not impossible.
I bought heavily during the lows of 2022 and were doing what you were and top slicing and recirculating, however I have found that more difficult to justify as sentiment improves, as these shares even at 20% and 30% up still look historically very cheap at current prices, and continue to rise...
I'm pretty much fully invested but have started to apply a FTSE100 hedge, which I could very well regret, and am prepared to ride down a leg and cut shares that go 10% below buying price. My gut feeling is I would lose maybe 25% of my portfolio (if its a violent leg down) but the decent shares would remain.
I agree with your general sentiment, it does feel a little like a bubble and have been preoccupied trying to have a plan in place, but the bottom line is the FTSE 250 and below (which is where I mainly trade) has seen a very small rally since October, with perhaps sentiment in them improving only in the last week or two, where as the FTSE100 defies the general trend, and I would expect to see a divergence from the lower indices, with the AIM etc performing better if the general sentiment continues.
Good luck, this next six months will be interesting!
Certainly appears to be a more positive tone, especially among UK small caps and better quality AIM shares, which is the area where I tend to invest. Some very attractive opportunities available a few weeks ago at depressed prices. I was fortunate enough to buy Ten Entertainment (LON:TEG) Centaur Media (LON:CAU) and TT electronics (LON:TTG) close to their lows, all of which have picked up tailwinds. They may not be in the same league as Games Workshop (LON:GAW) or Bioventix (LON:BVXP) but they didn't in my view merit the then overly depressed share prices. I still consider all three to represent decent value.
I have been buying Portmeirion (LON:PMP) which is completely unloved. If it gets close to market expectations and failing an outlook that translates into Armageddon the share price will I believe move significantly higher.
As with Smiths News (LON:SNWS), a share that I first started buying in November 2020 and is now in demand, much patience is required. Talking of which my patience has eventually come to an end with ITV (LON:ITV), a company that in my view continues to trade below its intrinsic value. Unfortunately in the absence of a catalyst, either the sale/IPO of ITV Studios or a bid, it will I believe continue to drift lower given the economic headwinds. I have therefore exited but would be prepared buy back, if the share price got really silly.
Just my thoughts, each to their own.
Good luck for the New Year
My view is this is a relief (suckers) rally.
FED will continue to raise rates (albeit at a slower rate) AND QT- everyone else will follow. Bank credit will tighten. $ will weaken. Bond yields will increase as a consequence. This will result in renewed downward pressure on equities.
There will be a recession as a consequence of rate rises/QT/bank credit tightening/ Dollar weakness.
Likely recession deeper and longer than experts anticipating (recession lasts until Q2 2024).
Capital preservation will be tricky. Although there will always be trading opportunities (eg if Ukraine peace talks etc) although these will be a sideshow from broader picture above.
IMO etc
A thoughtful set of observations and a sentiment which I share. I also welcome Jayman's commentary below as its always good to get the counter view. A couple of things I would like to add on the potential upside.
1. The Ukraine - there is a possibility that the end will be quicker than we think, maybe late summer - Russia is losing the logistics war big time - risk is that post defeat Russia falls apart.
2. China (aka Chi?) is showing signs of being much more rational of late. This is reflected in hawks being moved sideways, Covid restrictions being eased and the stock market rebounding - I hold HUYA, BABA & DOYU which are all up between 50-100% in the last few weeks. Before anyone thinks I'm clever I am still well under water on these holdings.
Either of the above proving true/sustainable could result in a significant bounce in the markets.
Thanks Berksbee.
You're right to call out the upsides and the extent to which the downsides are removed (e.g. peace settlement in Ukraine instead of anxiety about escalation, inflation actually falling consistently and faster than expected) then these might be powerful drivers.
1H, 23 will be interesting.
I know there wasn't time/interest yesterday.
SIG (LON:SHI) - Sell insulation a HOT product...
Appears to have delivered a very Good Update IMO
Doubled profits to £80M profit (though this was a bit under the radar as reported "in line"
£375M Mcap PER 4.68
According to Shorttracker - Ennismore short 1.5% or 27Million shares ( I reckon at about SP 37p ish)
They look wrong side of this now don't they????
Surely they've got to be buying to close their position????
Any thoughts.
I HOLD
DYOH
Someone bought a chunk (4.1M shares)
Be interesting to see if Ennismore short position decreases.
Hi Asset-Stripper,
The "£80m profit" quoted on the update is actually underlying operating profit, not profit after tax, so I'm afraid the PER is likely to be closer to 10.
Hope that helps
"* SIG PLC - SEES FY22 UNDERLYING OPERATING PROFIT TO C£80M,
UP
FROM £41.4M REPORTED IN 2021."
So 2021 £41m U. Op. Profit turned into a net £28m loss.
Are they even making a profit?
Debts are very high.
Yes - helpful thx. I saw the broker adjusted EPS 3.148p so a fraction over 10 x.
Interested to see if short position closed.
Ten Entertainment (LON:TEG) as mentioned below, a very positive full year update. Three new centres to open in Q1 with work starting on a fourth. Net cash of £10m with no outstanding debt obligations, Full year profit expected to be at the top end of expectations, so £26m or thereabouts.
Importantly the company acknowledges the effort of its employees and states
"Costs have been carefully managed, with operational efficiencies extracted to minimise the impact of cost inflation without the need to raise prices to our customers. We have ensured that we reward our colleagues for this excellent performance through a performance-related bonus scheme and by bringing forward wage increases for 87% of our teams to help our people manage the inflationary impact on their personal finances."
I hold and would welcome views/observations from other Stocko members and off course Paul or Graham.
Ten Entertainment (LON:TEG) - thanks. Net Cash, I had been going off the Stockopedia summary of net debt circa 200mn. May be very rudimental, but do you know how this was cleared / where the mis-match is between the net cash report today and the 200mn net debt on the Stocko report is?
I have held previously but sold out on the early covid chatter!
I think you will find that the debt to which you refer relates to lease liabilities courtesy of IFRS 16. See the narrative below from Paul's review of the interims in September
"Balance sheet - looks fine to me. I wish TEG would split out bank borrowings, and lease liabilities into separate lines. It’s such a bad presentational own goal, combining them. Nearly all the “debt” is actually lease liabilities, which of course are actually just future operating costs, which will be paid from future revenues & profit, so really shouldn’t be on the balance sheet at all. Net bank debt is negligible, at just £0.7m - so this is a very securely funded"
Thanks Jonno. Missed that text previously, I appreciate the follow up.
seems an odd reaction to Ten Entertainment (LON:TEG) results. £10m net cash means an EV of £180m but PBT of £26m and thus £21m PAT so you can now buy them on a PE of 9 versus Hollywood Bowl (LON:BOWL) on 15*
Not sure why such a disparity - both are very good well run companies with a good and relatively inexpensive product offering. Seems odd
Ten Entertainment (LON:TEG) the sp had risen around 20% very recently on anticipation of these pretty well 'known' numbers. This morning was a classic 'sell the news' situation.
Maybe holders were not so sure that the good news would keep flowing.
Hi David,
Short termers banking profits after the run up this past week. Rather than selling i am looking to add!
Regards,
Ten Entertainment (LON:TEG) - Hollywood Bowl (LON:BOWL)
Traditionally hollywood did trade at a premium -to Ten , certainly when i fisrt added Hollywood Bowl seem to have better metrics which suggested at the time it was slightly more quality business than Ten Entertainment (i invested in Ten being the cheaper of the two)
The above reasons may not apply now though - i suspect there may still be some advantages that Bowl has perhaps some informed posters may provide some further detail. I am a happy holder of Ten at present and i suspect they will currently look better than ever on a metrics basis (with current execllent trading) so not sure why there would be such a disparity comparing pe's. Sometimes basic/adjusted reported pe's don't tell the whole story though. Unfortuantely i dont have time to do any further digging - would be an excellent deep dive comparison (or perhaps billy basic one may do) of the two loking at the main important factors - margins/free cashflow - levels of capitalisation - etc
26M PBT, 200M mcap. Cheap! And with cash in the bank.
Ten Entertainment (LON:TEG)
To me the main plus point here is that they are a self funded "frachise type" rollout - its great when you can add extra profits each year by just "repeating what you already do" in new location. Obviously they have been shooting the lights out the last 12 months with all the tailwinds imaginable so the one caveat would be - "could these be peak earnings - on a per outlet basis>"? In that regard i am happy to carry on holding - they seem to be investing enough in the exeprience that that should keep the punters rolling in. Companies like this tend to go wrong when they dont invest to keep stuff shiny new and up to date and "pimp short term cashflow instead that exits teh door or is wasted (too much divis short term?) " - in that regard this to me seems a very well run outfit investing for the long term.
True - I just look at this and think it should trade around 13* for fair value. If Market cap is £195m and cash is £10m and PAT is £21m then £275m market cap seems about right = 420p a share.
So looks like still good upside from here and projected dividends look decent as well circa 4.5%
I agree that without price increases there is probably not a huge amount of LFL growth in the existing base but with a conservative rollout profile you'd imagine this level of profitability can be maintained and grown a few % each year.
I get it is up 15% on the week but I still don't get why it trades on a 30% comparative discount to Hollywood Bowl anymore.
interesting acquisition by Cambridge Cognition Holdings (LON:COG) - highlights:
· Acquisition of Winterlight, a leader in monitoring cognitive impairment through free-speech analysis
· Significantly enhances Cambridge Cognition's expertise and position in voice-based assessments
· The market for speech-based biomarkers for all conditions is reported to be growing at 66% per annum and, is predicted to be around US$220 million by 20261
· Total consideration for the Acquisition is £7.0 million, comprising a cash payment of £3.0 million and £4.0 million in Cambridge Cognition shares
· Limited overlap with Cambridge Cognition's existing customer base, potential to cross-sell and generate further revenue growth
· Potential to add more than £2.0 million to Cambridge Cognition's revenue in 2023 with considerable further growth in 2024
https://www.investegate.co.uk/...
See that John Authors makes a reasonably convincing case for investing in Emerging Markets, assuming dollar weakness will continue.
I have been in the emerging markets since November seeing some decent gains. I feel the key now is how quickly China can get on top of this COVID (unless you go ex-China). I could see the Covid situation getting worse in China forcing some mini lockdowns which would perhaps cause a pullback and a buying chance in many shares including the EMI.
I'm not sure I would average up in the EMI at this very moment, but I have been known to miss the boat.
Any credible sign that China are winning the battle on COVID would be a great buying cue IMHO.
My morning smallcap tweet: Have I Got Views For You
Surface Transforms (LON:SCE) Reach (LON:RCH) Argo Blockchain (LON:ARB) Cornerstone FS (LON:CSFS) Nichols (LON:NICL) WANdisco (LON:WAND) Warpaint London (LON:W7L) Lookers (LON:LOOK) Ten Entertainment (LON:TEG) Physiomics (LON:PYC) M Winkworth (LON:WINK), Johnson Service (LON:JSG), Creo Medical (LON:CREO), Nightcap (LON:NGHT), Quartix Technologies (LON:QTX), Hostelworld (LON:HSW), Ab Dynamics (LON:ABDP), Topps Tiles (LON:TPT)
◄Surface Transforms (SCE)► dabs the brakes as it warns FY-Dec rev up 113%, less than previously guided. Blames production probs in Nov and Dec as volumes were ramped up. "The problem furnaces are now operational but management wish to see several weeks of consistent output before being comfortable to confirm that the issue has been permanently resolved." FY23 production guidance unchanged. [SP=38 Cap=91m]. I hold.
◄Reach (RCH)► warns Q4 rev miss at 4.2% down due to weak ad rev: "significantly lower than anticipated benefit from traditionally stronger programmatic yields and campaign spend around Black Friday and Christmas, which has affected the whole sector." Guides FY-Dec op profit below market consensus (£112.8m) by mid-single digits %. [SP=109.51 Cap=347m]
◄Argo Blockchain (ARB)► more bad news as Dec mining only 147 Bitcoin equiv (Nov:198) dur to electricity rationing in Texas during storms. [SP=10.65 Cap=61m]
◄Cornerstone FS (CSFS)► guides FY-Dec rev up 109%, 12% ahead of market expectations. Gross margin c.61% (52%). [SP=5.76 Cap=3m]
◄Nichols (NICL)► guides FY-Dec rev up 14%. Adj pretax in line with market expectations. Guides FY23 FY23 adj pretax broadly in line with FY22 "but remains confident of significant progress in FY24 as inflationary pressures abate". [SP=1100 Cap=401m]
◄WANdisco (WAND)► giodes FY-Dec rev up 229%. In line? Loss? Outlook: "As the Group progressed through 2022, the breadth and depth of the pipeline continued to strengthen. This combined with the expectation of a significant ramp-up of consumption under the agreements signed in 2022 places the Group in a strong position as we enter 2023". [SP=902 Cap=600m]
◄Warpaint London (W7L)► guides FY-Dec c.£64m vs guided £61m+. Adj pretax c. £10m, ahead of market expectations and mgmt guidance of £9m+. [SP=188 Cap=144m]
◄Lookers (LOOK)► guides FY-Dec U/L pretax £80m+, ahead of mgmt exp. FY23 exp remain unchanged. [SP=77.9 Cap=301m]
◄Ten Entertainment (TEG)► guides FY-Jan rev up 88% and adj pretax at upper end of market expectations of £25-26.1m. [SP=290 Cap=199m]
◄Physiomics (PYC)► further contract with Cancer Research, expected to be completed during Q1 2023. [SP=4.68 Cap=5m]
◄M Winkworth (WINK)► guides FY-Dec pretax modestly ahead of market forecast of £2.3m. "We are very pleased with our sales results for last year and are less downbeat than the consensus on the outlook for prices in the current one. Lettings market activity abated towards the end of 2022, but we expect it to be strong again in 2023." [SP=155 Cap=20m]
In line: JSG, CREO, NGHT, QTX, HSW, ABDP, TPT
Surface Transforms (LON:SCE) "dabs the brakes" - love it! Actually I don't - it's about time they found out what the right hand pedal is for!
Paul or Graham. If you get a chance to look at Warpaint London (LON:W7L) that would be good. Results above expectations and adjusted PBT of circa 10mn. Having read Terry Smith's letter yesterday on adjustments versus full accruals accounting I will have a good look at adjustments when full P&L is published.
Greyster
Morning All,
Ten Entertainment (LON:TEG) excellent update this morning, good numbers and net cash position for the first time!
I'm just over 50% up on this - my thoughts are that I should probably slim down or exit totally; however, this is just an outstanding update that it reads that it can only get better...
However, I've just looked at my local centre and for a game of bowling at over £40, it certainly isn't 'cheap'. That said, they are planning to open new sites, including Crewe which is close to me, I know lots of Cheshire mums who can't wait for another party venue who have plenty of disposable cash.
Given the net cash position, I personally would like to see some further info on dividend growth. I may have talked myself into selling today.
Why would you sell? Topslice maybe, yes. 25M PBT this year against a market cap of 200M. That's cheap! At least 50% upside from here in my view.
Hi
WANdisco (LON:WAND) trading update quite encouraging.
But some caution still required as this comment is a point to note, profitability still some time in a future. ......
The Company ended the period with a strong balance sheet, with cash of
approximately $19m and $44m in trade receivables as at 31 December 2022. Taken
together with an RPO of $110m this should see the Company through to
profitability.
Other points made ....
FY22 Trading Update
Record bookings of $127m
Preliminary unaudited revenues of at least $24m
Strong Balance Sheet with $19m in net cash, $44m in Accounts Receivable
Accelerating commercial momentum with multiple multi-million-dollar contract wins
(can't post link to RNS as cannot access Investegate site for some reason, sorry).
I hold baby position.
Regards
Howard
Also unable to access Investigate site
Re Howard and Nathan, access easy enough through the LSE website.
Morning all,
Reading the daily comments on this feed provides me with detailed insight into a huge range of stocks. The work of Paul and Graham is fantastic, assisted so many of you in the community too. Like many others I'd love to contribute with more to the discussion, I'd like to feel I had an impact within the community, but the reality is, as a novice investor, I simply don't have the skillset yet and rely on the work of others.
I would love to learn to move beyond my current quite surface level analysis, which consists of reading stockreports and watching videos of CEOs being interviewed. I'd be really interested if anyone (doesn't have to be Paul or Graham) would be happy to do a recording of them doing their own more detaled research on an individual stock, talking through their process.
Not sure if this may already exist and if so please share!
Thanks again to everybody who's doing the hard work on behalf of the rest of us!
BenHazz
Hi Ben,
Not sure you have seen this but if not it's worth a watch (worth watching again after a few months of using the stock reports) and it will help you drill in to the reports and pick up some tail wind signs.
It's an interesting point you make on more detail as some would say less is more to avoid conformation bias, others like to pick at the bones. It depends on many factors including the time you have, your investment style, your thirst for knowledge on a particular company, your ability to not become sucked into a company the more you read, research and watch.
For me I like the numbers to do the talking, so carry out the above forensics, check historical RNS's on a company that pass the screen test, check broker notes through research tree, execute buys from my watch list avoiding FOMO using level 2, basic charting, and where we are in the economic cycle. Then carry out tight portfolio management cutting losing shares early, and running winning shares. Sounds so easy when you write it down....not so easy in practice.
Remember stock picking is only half of the equation, as plenty of well researched shares simply go down. I find that when to buy, when not to buy, and when to sell are really the key drivers for a successful investor (making money!).
Best of Luck
Paul
Paul & Graham do a great job of skimming through the trading statements and highlighting where the financials could do with further investigation.
Stocko is also good at summarising the historic financials at a high level, but that is just a starting point.
If you were to sit down with an analyst at a fund management firm or a brokerage firm/investment bank you would observe a much more detailed process. At a minimum they would restate the accounts, adjusting for leases, assets held at cost, exceptionals that aren't exceptional, the "polishing" of inventory/cash levels for period end, depreciation policy, share based compensation and then rebuild the P&L and balance sheet so they can observe relative valuation on a "clean" basis - apples vs apples. Look at the latest Fundsmith letter for an example of how this changed their view on Intuit vs Microsoft.
The accounts however are the easy bit. Much more difficult is trying to get a handle on the competitive position, the sustainability of margins, the likely future growth in revenues etc. Even the best analysts can't forecast out more than a year or two before it all becomes a guesstimate - which is a big problem because a large part of the value in any share resides in the terminal growth assumption (look into DCF valuation for more on this)
An analyst will easily spend a week on a single stock, if not longer. Some firms will even do their own primary research - measuring footfall etc. Meeting the company in person is a two-edged sword, in that you gain insight, but their enthusiasm/bias rubs off on you.....
There are more companies than any individual can ever cover in sufficient depth - investment outfits that are just one fund manager will be highly dependent on sell-side research, which their rivals also see.
There are plenty of books on this, but stick to recent publications simply because accounting standards are constantly changing, and can differ by region.
Hi Ben,
As the Floating Investor has already suggested Stockopedia does have learning modules that can help to improve your knowledge. They also have some e-books you can work your way through. Always willing to learn, I would personally second your suggestion for further detailed research by someone on the Stocko team.
In the meantime I recall Jack Brumby answering a similar question to your own as below
Jack BrumbyNov 6, 2020
Hi Casino_Winner,
Paul is very much champion of the balance sheet and you can perform very detailed analysis here. There are three main sections to a balance sheet: assets, liabilities, and equity. Assets are what the company owns and include cash and property. Liabilities. are what the company owes and include debt. Equity is what's left over when you subtract L from A.
Assets = liabilities + equity.
You want high quality assets comfortably above liabilities. If assets are largely made up of intangibles or goodwill that can itself be a warning sign.
You can get quite far quite quickly. I'm a big believer in the 80/20 rule and there are some easy checks that can quickly flag up any warning signs:
This is just a quick start - entire books are written on Balance Sheet analysis - but you'd be amazed at how far these few steps can get you. Also a stock with a high Quality Rank is likely to have a strong Balance Sheet.
I always recommend this video by Ed as well, it's a fantastic crash course.
Hope this helps.
Mark
Paul, Monty and Mark,
Thank you all for taking the time to write such detailed posts. I have watched the StockReport video again last night after first watching it about a year ago - it was actually what encouraged me to write the comment this morning.
I will have a proper read through your responses properly and look at the links after work today.
I must say I know I am a bit of a sucker for confirmation bias and its an excellent point you make about being careful to avoid that as you research more. Also, self reflection and recognition that whilst working full time (in education not finance) with a family at home I'm never going to be able to get close to the detail of those who analyse companies at a professional level. Fortunately, I am comfortable relying on the expertise of others (the writers and some of the regulars on the SCVR) and slowly but surely accumulating my knowledge over time.
Thanks again,
BenHazz