Small Cap Value Report (Wed 11 March 2020) - DTG, SOM, DTY, COST, KCT, LOOK

Good morning, it's Paul here with the SCVR for Weds.
This post is initially a "placeholder" - i.e. just an introduction, put up at 7am, so that readers can add your comments below, whilst I spend the rest of the morning & early afternoon writing up the main sections.
It's Budget Day today in the UK, which starts at around 12:30.
Estimated timings - I'll need to get the main report done by 12:30, so that we can then focus on what the Chancellor, Rishi Sunak, has been told to say by Dominic Cummings!
Update at 12:30 - today's report is now finished.
Volatility continues, with another huge rally in the US markets last night, which has almost completely dissipated in the futures overnight.
I went on a shopping spree yesterday, buying smallish new long positions in small caps, and increasing my existing small cap positions, but then got cold feet last night and decided to re-open my short on the Dow, as a hedge. Probably like everyone else, I really haven't got the foggiest idea where markets are heading. It seems to me that the headlines now are far worse than I'd been expecting - e.g. talk of Italy needing a large-scale financial bailout. Also the trajectory of new coronavirus cases in Europe, and USA, means this looks like the start of a wide-scale outbreak here. I just cannot imagine markets are likely to shrug off a wave of imminent terrible newsflow. Hence I'm now worried about another possible lurch downwards. Bottom line is - I have no idea what's going to happen next.
Breaking news - the Bank of England has cut base rate from 0.75% to 0.25%. It's also announced a package of measures to support SMEs. It looks like policy-makers want to be seen to be doing something to combat the economic impact of coronavirus, and of course trying to further prop up asset prices with ultra-cheap money.
Trying to prevent the banks from pulling essential credit lines to SMEs seems very sensible to me, given that this is a temporary factor - the last thing I would want to see is fundamentally sound businesses being put into administration due to short term cashflow problems.
As for interest rates, it seems increasingly likely that ultra-cheap money is now a permanent thing - markets are addicted to it, and it can't be withdrawn without crashing asset prices, it seems. Governments can borrow long-term, incredibly cheaply, so to my mind this is the perfect time to be undertaking major infrastructure projects, provided the cost:benefit calculations are genuinely favourable. Surely the obvious thing to do, is to build huge numbers of new affordable houses, and rent them out with a right to buy attached, thus giving younger people a decent way to look forwards.
Dart (LON:DTG)
Share price: 1028p (up c.6% today, at 08:41)
No. shares: 148.9m
Market cap: 1,530.7m
Dart Group PLC, the Leisure Travel and Distribution & Logistics group, today issues the following update on trading. Year ending 31 March 2020 (FY20)
Its main business is the Jet2.com airline, and its relatively new package holidays business. Plus there's a freight division too.
Why am I covering DTG in a small caps report? Because it's on my watchlist of possible purchases, once the coronavirus problem subsides. For anyone not aware, I'm first & foremost an investor, with report-writing being a secondary role, where I share my thoughts & research notes with subscribers here. It's recycling the same information & views basically, which makes sense all round. Hence if I think a company looks interesting as a possible purchase, then I'll cover it here, regardless of market cap size.
Today's update - looks surprisingly strong for y/e 31 Mar 2020 -
Due to the continued success of our growing Leisure Travel business, the Board expects Group profit before foreign exchange revaluation & taxation (excluding any impact of hedge ineffectiveness) for the financial year ending 31 March 2020 to be significantly ahead of current market expectations...
Normally that would have put a rocket under the share price, and it's the latest in a long line of forecast beats. This is a tremendously impressive company, which I admire very much, and want to part-own at some point.
Look at how the share price was exploding upwards on positive trading updates, and then see what happened recently when coronavirus struck;
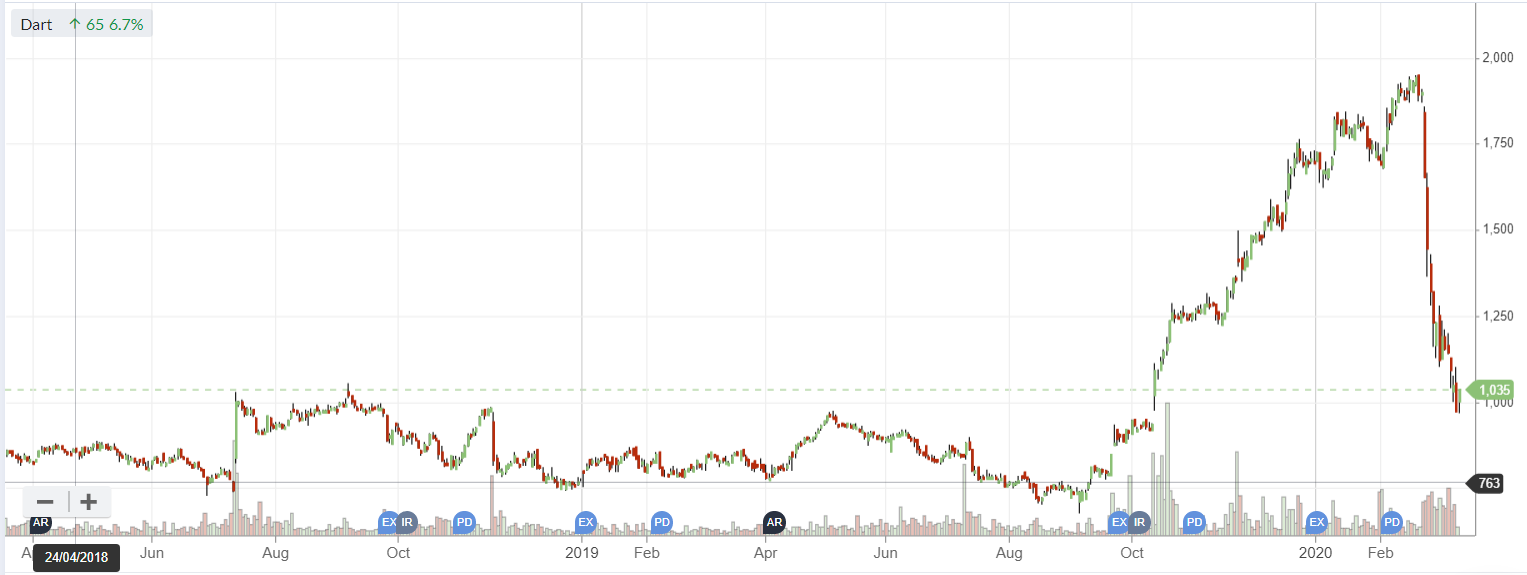
.
Without coronavirus, we would probably be over 2000p per share by now. Therefore, the current level of 1028p is looking very tempting.
Hedging losses - unfortunately, profits will be hit with what looks like a one-off exceptional charge for hedging contracts that have gone wrong. The way I interpret that, is that, because fewer flights will be using fuel, and fuel has also fallen a lot in price recently, then the company is probably committed to buying too much fuel, and at too high a price, with now loss-making forward hedging fuel purchasing contracts. I imagine this might be a problem for many airlines and cruise ship operators. Hedging contracts basically just defer price changes, therefore airline and cruise ships that undertake fuel cost hedging are not going to benefit from the lower fuel price until their hedges expire.
... However, future reductions of FY21 flying capacity will result in a proportion of the Company's existing hedging contracts becoming ineffective, thereby impacting those profits.
It would have been helpful for the company to have given an indication of the size of this problem, but they haven't done that.
Coronavirus impact - obviously this is the big problem right now, as it's likely to seriously impact revenues and profits from now on, for an unknown length of time;
Until very recently, Customer demand for our very popular Package Holidays and Flight-Only Leisure Travel products has remained consistently strong, with the important January and February booking performance resulting in our Summer 2020 bookings tracking well ahead of our 16% summer seat capacity increase...
That sounds great, but I wonder about cancellations? How many customers are cancelling bookings, or refusing to pay the balance if they've only paid a deposit? Who is legally liable I wonder? With cheap operators, often the customer can choose between a cheaper, non-refundable ticket, or a higher priced ticket that can be changed. All this information is missing from today's update.
I'm very surprised that forward bookings have not fallen a lot more than this - maybe there are further falls in the pipeline, once flights that were booked before coronavirus have washed through the system?
Understandably, however, momentum has weakened over recent weeks with the increased reporting of Covid-19 cases in Europe. Nevertheless, our current cumulative Summer 2020 bookings remain above those at this time last year.
Maybe DTG customers are more stoical, and are pressing ahead with their holiday plans regardless? Given the spread of coronavirus in the UK is now happening fast, albeit from a low base, I can't see demand remaining this robust for much longer. Short haul destinations in Europe are also seeing coronavirus rising rapidly, e.g. Spain, France, Germany. This is bound to hit DTG and other airlines. So I think the situation could probably get a lot worse than the company is letting on today. This sounds like a rose-tinted glasses type of update to me.
It says here that they don't know what the impact will be, but we can safely assume it's likely to be very bad in the short term, in my view;
The continuing success of our Package Holidays, including our newly launched ''Vibe'' brand, together with our strong and prudent balance sheet gives us long term confidence for the future. However, given the limited visibility on the impact of Covid-19, the Board is currently unable to determine how this will effect Group profit before foreign exchange revaluation and taxation for the financial year ending 31 March 2021.
Balance sheet - is indeed strong. Although it's complicated, as with almost all travel companies, that customers pay up-front. Hence cash is often offset by deferred income (the creditor side of the double-entry). The risk being that if an act of God causes operations to cease, or be sharply reduced, then the deferred income unwinds quickly, leaving weaker players insolvent. Remember the volcanic dust cloud a few years ago? There was a lot of concern then, that weaker balance sheets could blow up as the cash is pouring out, with little to no new cashflow coming in from forward ticket sales.
Later this year, I think travel companies are likely to be offering amazing discount deals, just to get cash flowing in again, and bums on seats. Therefore, I suspect readers would be well advised to hold back on holiday plans, and snap up the bargains later this year. Also, make sure we pay for holidays using a credit card that has refund protection if the travel company goes bust.
Fowler & Welch - is trading OK;
We are also pleased to report that our Distribution and Logistics business, Fowler Welch, is trading in line with expectations and continues to develop its revenue pipeline with existing and new business opportunities.
My opinion - I definitely want to own shares in DTG at some point, ready for a recovery. It's a fundamentally excellent business, with a great long-term track record.
Anyone buying this share now is likely to do very well long-term, I reckon. However, there's also a distinct chance that there could be another violent lurch down, if the next update (as seems probable) discloses a large drop in bookings, and even heavy temporary losses & cash outflows. How much of that is already in the price though? Nobody knows! This could be one where it might make sense to start off with a small long position, and then add more if coronavirus begins to subside. I might do that at some stage, but it feels a bit early right now.
.
Somero Enterprises Inc (LON:SOM)
Share price: 237.5p (up 12% today, at 09:52)
No. shares: 56.3m
Market cap: £133.7m
(at the time of writing, I hold a long position in this share)
This is a US-based maker of laser-guided concrete laying machines. We've covered it a lot here in the SCVRs, as it's a high quality, reasonably priced company, that generates loads of cashflow which it pays out in divis. The downside risk is that it's highly cyclical - so demand drops away considerably in recessions.
The company had a poor H1, blamed on bad weather in the USA. This was true, because performance recovered in H2, so kudos to management and advisers for telling it how it is.
Today's figures look fine to me, I won't go through all the detail, just a few bullet points;
Revenue & profits are as expected, down a bit, raising the question as to whether we're at the top of the cycle?
Adj EPS is 37 cents (the company reports in US dollars), down 3% on prior year. Converting into sterling gives us 28.7p = PER of 8.3 - very cheap, so clearly the market is assuming future earnings are likely to fall.
Balance sheet - fantastic, with plenty of surplus cash. The company is in great shape to withstand any downturn.
Dividends - a strong feature of this share. For 2019 it paid a regular divi of 18.75c, and a supplemental divi of 7.7c. Obviously the bumper divis could be curtailed if the world goes into a recession in 2020, a distinct possibility I'd say. But that's already factored into the lowly valuation.
Coronavirus - this is reassuring;
Whilst we have not seen an impact to date on our business, we are closely monitoring the evolving Coronavirus situation. Our supply chain has been unaffected as we do not source components from China and while we have yet to see delays in projects outside of China, we remain in the early stages of understanding the impact of the virus. We will provide updates in due course if we anticipate our full-year 2020 results will be impacted.
I think it's safe to assume that there might be some disruption to 2020 revenues/profits from the economic damage we're starting to see from coronavirus.
Outlook -
The Board is confident in the outlook for 2020 with the solid momentum in the US carrying forward from 2019 supported by the strength of the US customer project backlogs that span well into 2020. Outside of the US, while market conditions and activity levels remain generally positive, the Board continues to recognize factors impacting each market that slightly temper underlying growth expectations for 2020.
Clear guidance is given, from a management team that we can rely on, because they've always been honest in the past;
With this comprehensive view, the Board expects 2020 will be a profitable year with healthy cash generation.
Revenues are expected to be comparable to 2019 with EBITDA broadly in line with 2019 and in line with current market expectations.
Also note that additional expenditure is planned, to drive sales of the new product, SkyScreed. Shareholders should be happy with that, as it will drive future growth.
My opinion - I really like everything about this share, apart from the cyclicality of earnings.
For this reason, I'm keeping my personal shareholding in the company, bought quite recently, on the small side. Very small actually. The reason is that we're in a period of uncertainty, and I imagine that trading updates later this year could well talk about delays from customers, due to coronavirus. That might take the share price back down again. Or it might not, I don't know.
I think the litmus test is this - would I want to own this share once coronavirus is out of the way? Also, does the company have strong enough finances to survive any downturn this year? In both cases, the answer is a strong yes.
Quick comments now, as time is running short;
Dignity (LON:DTY)
Down 19% to 404p today.
Highly indebted chain of funeral directors.
2019 results look poor. Underlying EPS down 29% to 60.6p - although this only looks slightly below consensus of 60.6p
Some negative factors flagged;
· Changing competitive landscape has lowered average income per funeral as expected
· Further downward pressure on average income per funeral and cremation expected
· The CMA investigation could materially impact the industry and the Group
CMA sounds like a big deal, and aspects of turnaround plan have been paused until its findings are known.
Balance sheet - is one of the worst I've ever seen. Huge net liabilities - once we deduct intangibles, then NTAV is negative at -£510.3m!
My opinion - the way I look at things, it's insolvent. Therefore I think the equity is probably worth nothing.
This balance sheet has all the hallmarks of private equity having wrecked it, thinking they were being clever by gearing up annuity-like revenues at inflated profit margins (preying on vulnerable people by over-charging).
Anyone buying it recently, hoping to cash in on coronavirus deaths, richly deserves the 19% share price fall today!
Costain (LON:COST)
This infrastructure contracting services group has halved in price in the last month.
It's raising £100m in an underwritten placing. Looks like the bank & pension trustees likely to have pushed the company into this, as extending bank facilities is said to be dependent on it completing.
This bit caught my eye, and looks to have read-across to other contracting companies, and maybe other sectors too?
The introduction of the Prompt Payment Code whereby contractors are required to pay their suppliers earlier has also resulted in higher working capital requirements - in response, Costain has implemented revised processes to ensure that suppliers are paid promptly, with the average time taken to pay invoices reduced to 34 days from 58 days.
That's a really good thing for all the little companies that all too often have been exploited in the past. But it clearly means that the bigger companies need stronger balance sheets to finance quicker payments. If you invest in this sector, this strikes me as a key point to check out.
2019 results also out today, look like the company is very busy, but only scraped just over 1% operating profit from its many activities.
My opinion - this situation further reinforces my aversion to this sector. Shares in infrastructure companies seem to be time-bombs waiting to go off - large, complex projects with numerous risks, on wafer thin margins. Why on earth would anyone want to invest in this sector, hoping to pick a company that doesn't blow up?
Kin And Carta (LON:KCT)
A very quick note to flag the weak balance sheet here. NTAV is negative, at -£33.6m
There's a fair bit of bank debt, which could become a problem in a slowing economy. Also note the deferred consideration payments, and pension fund, which could be further drains on cashflow.
I wouldn't want to be holding this type of share in a slowing economy.
Lookers (LON:LOOK)
I've only just spotted this - shares down 30% to 26p.
A bombshell announcement last night is the reason;
Delay to announcement of results
In the final stages of preparing its results for the financial year ended 31 December 2019, the Company has identified potentially fraudulent transactions in one of its operating divisions.
As a result the Board has decided to postpone the announcement of its results until the second half of April.
Whilst the initial findings are not material in the context of the Group, the Board is appointing an external adviser to lead a full investigation into the matter.
Uh oh, I don't like the sound of that. Recent history tells us that it's best to sell immediately when accounting problems emerge.
That's it for today!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

92 comments
Dart (LON:DTG)
Paul - a couple of comments on Dart
Hedging - you are correct in your interpretation of hedging losses.
The annual report and accounts to March 19 (p22) say that at Mar 19 DTG had hedged 90% of its fuel requirements (in line with formal hedging policy) for the next 12 months. 2019 accounts also tell us that fuel costs were £305m.
Per IATA (https://www.iata.org/en/publications/economics/fuel-monitor/) jet fuel price at 6 Mar 20 was down in price 32.4% versus a year ago and 18.1% versus a month ago.
We also know from this weeks trading update that summer capacity was increased year on year by 16%.
So, all other things being equal, fuel cost for this year would be £353m (£305m * 1.16 to reflect 16% capacity increase). The question is how much of the circa £353m fuel cost is excess to requirements and what’s the hit on excess hedges - difficult to put an exact figure on it but if capacity is cut back by say 15% and there is a 25% hit on fuel price then we are looking at circa £13m - imprecise I know but I think we could be looking at low double digit £m
Cancellations
Re your questions on cancellation I think this is a two part answer - for those people who have booked a flight only then I believe these are paid for at time of booking in full with no refunds if customer decides not to travel for their own reasons.
More importantly for those people booking package holidays (flight and hotel) there is a deposit payable at time of booking which seems to be £60 per person. Cancelling 70 or more days before departure incurs a loss of deposit only, so a relatively low cost at that point for those inclined to cancel. Cancelling at 70 days or less incurs a loss of between 30% and 100% of holiday price. So at this point in time anyone who has already booked for Jun onwards could cancel for £60 per person and then wait and see how the virus situation goes and rebook at potentially lower price.
Clearly If Dart cancel the flight/holiday then there would be an alternative or a full refund.
Another point to bear in mind is that there is likely to be an excess of fx hedges in place as well as fuel. 2019 accounts stated that accommodation costs were £1.1bn so dependent on rates hedged at there could be a hit on these as well depending on degree of capacity cutbacks.
I like the culture of this company and its product is good too. Long term I think it will continue to do well and like you I am looking for a good entry point. However I think there are a lot of unknowns at the current point in time and it is highly geared to the virus situation so will wait for some clearer information on summer bookings as there is, as you say, a chance of another lurch down.
Old site loads fine; new - not so much. If you have the option switch back for now.
I never use the new site, too many issues for me, too slow being one of them.
I never use the new site, too many issues for me, too slow being one of them.
Yes, it's pretty embarrassing how slow it is. I tried my best to use the new site but gave up earlier today because I had the same problem with the comments not loading and the page updates are positively glacial. It's a shame because I'm sure that behind the scenes there's a lot of effort being put in, but this is not being reflected in the user experience.
All the best, SI
Yes, it's pretty embarrassing how slow it is. I tried my best to use the new site but gave up earlier today because I had the same problem with the comments not loading and the page updates are positively glacial.
I imagine the new site is getting its first proper stress test at the moment by people repeatedly hitting "refresh" in the hope that something will have changed :-/
timarr
I imagine the new site is getting its first proper stress test at the moment by people repeatedly hitting "refresh" in the hope that something will have changed :-/
Yes, I can understand that, but as an engineer it doesn't matter what you're designing, you have to stress test it yourself before calling it a product and selling it to someone else. In my experience, paying customers do not like being the Beta testers for your product.
I'm no expert on building websites, but if a teenager can build a bot network in his bedroom to stress test the Pentagon, I'm sure a half decent web designer can do the same to check the performance of the website he's just built when under a high load of page requests. If I'm sounding a little cheesed off by being caught in purgatory between two different sites, it's because I am.
All the best, Si
Thanks for the info but I have only been a member for about three months and so I am not aware of an old site and cannot see how to access it on my screen. This is the one of those days I really wanted to see what others were thinking and possibly doing as it would have given me a feel for the market from some very experienced investors. Hopefully tomorrow it will be back to normal.
Best wishes.
I see, yes I have heard new subscribers can't access the old site which I think is a pity as some things on there are not available on the new one.
If investing since the 90s counts as experienced (not sure it is long enough) then it is likely that people will identify with several behavioural types and be a blend of many of them. Here is a tongue in cheek range of possibilities until you can get access to those wiser than me.
Everyone. Amazed and confused.
This sort of event will roll around every 10-20 years. They are great learning experiences. Volatility is likely to persist for a while, as in itself, it forces quant institutions to rebalance portfolios, contributing to more volatility. There will be opportunity. The recovery will either be prolonged, v-shaped or steady, rapid or prolonged! No one knows, however, the consensus is probably wrong.
My objective is to buy quality/yield, cheaply - but I need to see signs of strength as capital preservation is key. I'll revert to quality-momentum when absolute strength returns. If screaming bargains are presented I'll treat them with suspicion, before approaching with caution and investigating.
This is the one of those days I really wanted to see what others were thinking and possibly doing as it would have given me a feel for the market from some very experienced investors.
You'd have to be very experienced to have witnessed a day like today ... it was Black Monday, 33 years ago. Ahem ... well, of course, I was around, wet behind the ears and sure I could cope. Michael Fish proved himself as adept at weather forecasting as all the financial pundits were at market predictions and I wobbled about like a drunk on a skateboard.
What everyone forgets is that the following day was worse ...
You have to go through this to understand what investing is really about. It's easy - too easy - to make money when everything's going up - and equally easy to lose it when it goes down. That's why Graham talks about needing a plan and Paul warns against leverage - when the markets turn they do so savagely.
Two things destroy returns - leverage and panic. Leverage in a downturn is horrible. If it's personal you're a forced seller at stupid prices - and many prices quoted today will prove to be stupid. If it's corporate then you're holding a company that is living on the edge, a single misstep can see them go bust. You can't recover a total loss of capital (I've had four, all horrible).
Panic is the result of not having a plan - it's selling good companies because their price has fallen or buying crap companies for the same reason. It's buying on the rallies and selling on the dips. It's about lack of emotional control. If you are going to panic - do it early. But you'll panic more often than there are crises, you'd be lucky to win playing that game.
History tells us markets recover - but it can take a year to eighteen months so you need to make sure you can survive that long without needing the cash. And it's all so much easier if you buy good companies at fair prices and otherwise sit on your hands.
Today I sold some bond funds to free up cash, placed a load of limit orders and missed all but one of them by a whisker. I did end up with some Schroders (LON:SDRC) which I'm sure will be a constant companion for me in the long self-isolating nights ahead.
Be lucky but - better - be prepared.
timarr
Thank you HumourMe and Timarr for your replies I much appreciate them. I have a plan but this volatility is quite something . I have hesitated as a couple of shares that I had earmarked to purchase have overshot to the downside making me question the validity of my decision, although I still believe in them long term they may go down further as the USA is having another bad day. On the other hand two others are doing the opposite and are holding up really well so perhaps these may be the better choice. I will see what tomorrow brings, just hope I can access the comments section because so far no luck.
Best wishes.
Off topic, but is it just me that can't view any comments on today's (Thurs 12 March) thread? All I get is a revolving circle saying "Loading comments". Other threads (eg this one) seem OK still. Thanks.
I am having the exact same problem and it’s driving me nuts, like I don’t have enough stress already.
I don't have any problem.
same for me now (16:49)
Discovered you might be able to see some comments if you go to the old site (stockopedia.com with no 'app.' prefix) and don't login, ie appear as a non-registered user. You can't read the articles but the comments may be viewable.
Dignity. Saw the word insolvent and that was enough for me, sold all of it as there would be more sellers tomorrow and true enough there are down 15% today versus a market of -6%. So many thanks Paul
I would not be touching Dart (LON:DTG) or other tourism related businesses at this stage. There is a lot more pain to come. I suspect that UK France and Germany amongst others will take the same action as Italy within 4 to 6 weeks and that we may see an end towards mid-June. But maybe this is already in the price of the likes Dart (LON:DTG) but I would not be sure.
Re NMC Health (LON:NMC) (first I've heard of it). My initial reaction looking at Stockopedia: revenues quadrupled over 5 years, raising concerns if company expansion had been too rapid. Debt is high. The board is stuffed-full of foreigners. So, plenty of red flags there. Now we find out there are accounting irregularities. The auditors were Ernst & Young. It would have been funnier if it were Grant Thornton.
The website address indicates that they're from the United Arab Emirates.
The company was incorporated in 2011, and made public in 2012. The company passes my 7-year test for investability, but only just. Maybe 10 years would be a better benchmark. No test is infallible, of course.
In hindisght, it's easy to see where this was all heading. The company was made public less than a year since its incorporation. So clearly not a battle-hardened business, but one spat out with financial engineering in mind.
I remain unavowed in this at the risk of being downvoted and called a rascist: heavy board representation by non-UK nationals is a massive red flag. I would make only the rarest of exceptions, like Standard Chartered (LON:STAN) for example.
PS The stock market is down again? We do seem to be seeing a pattern where the market is unable to sustain any gains its makes. I regard that as definitely bearish. I am taken aback by the rapidity of the fall, so where this all ends up is a mystery to me. My predictions of a short-term bounce have been completely wrong.
It's not racist at all to say that some foreign based Aim cos in particular have lost punters a lot recently !
I think because this an illiquid stock market makers will often use tree shaking tactics to try and get some stock on their books. I assume the price drop reflects that?
I am a Tracsis holder
You will all think me a bit contrarian. This could turn out to be a good thing for the world. People are being forced to think outside of the box which is "oh I will just jump on an aeroplane, or boat or car and go" be a nice holiday under the guise of working". People will be forced to use technology. There are so many options in todays society to communicate without being there in person. I note MIT have sent all students home and told their lecturers they have 2 weeks to prepare lectures online. What brilliant management, act before the issue hits. Every investor here should be asking what are the opportunities for us as investors in this different world? Probably less Ryanair and more Alphabet (I only use that one because of Graham's piece earlier this week!
Frontier Developments (LON:FDEV) announcement of licence agreement with Formula One sounds positive.
With so much talk of self-isolation and people not going out, I can think of crazier sectors of the market to be invested in than computer games developers and retailers.
Paul, I know you are principled and dislike pawnbroking and payday loans and I understand why. My concern is that Morses Club (LON:MCL) still has a stock rank of 89 and most indicators are good. I feel I did my own research as far as I could. I am still haunted by Conviviality that had a lofty stock rank and collapsed in a day (more or less). Your thoughts might ease my frustration. I tend not to chase stocks down and might well right it off.
I'm with you on this. I have held this for quite a while and have done a good bit of research on it and it was generally sound but has been falling for a while, before COVID-19. I'm also concerned and would like to get Paul's thoughts!
No, sorry, I won't look at things like Morses Club.
Entrepreneur relief on gains cut to £1m (from £10m). Personally consider this another kick in the whatsits for entrepreneurs, but probably will not produce any tears from the public at large.
Claims other reliefs will ameliorate its loss.
I had to pay 40% tax when I sold my business in 1972. It gives a different perspective.
Wow! Roughly how old are you, if I may be so bold?
Well I think that breakfast, or at least brunch, should be on you! ;-)
Will the VAT cut to all forms of reading, mean a price cut on our Stockopedia subsciptions? ;)
Not if you want my incisive wit & wisdom! 20% less, and I'll stay in bed LOL!
Split the difference. 10% for us, rest to you and Graham for your wit and wisdom... and new Twitter account ;)
I can't find the budget speech. It's usually published immediately after he sits down. I've tried the official .go.uk sites for HM Treasury and HMRC, the BBC, all the National dailies.... nothing. Just highlights and guff. Where is the actual speech?
https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/871799/Budget_2020_Web_Accessible_Complete.pdf
Now published, here: https://www.gov.uk/government/...
Anyone invested in £bmn understand the reason for today's 10% drop? Now thinking this is due to more than just covid-19 and for some reason the market doesn't like the agreement with £red (where shares are suspended) Currently looking at at 50% loss but thinking I might as well stay long, unless someone knows of a significant reason that might change my thinking :)
I assume you meant £BMN. It's probably a reaction to the Vanadium price falling which is a reaction to reduced economic activity. Most Vanadium goes into steel or titanium alloys as I understand it so I doubt if the RedT situation is significant.
"so to my mind this is the perfect time to be undertaking major infrastructure projects, provided the cost:benefit calculations are genuinely favourable". Agreed Paul but the word "genuinely" is important here. How many infrastructure projects generate the returns expected or come in within budgeted costs? Business tends to be poor at making these calculations and governments (of all hues) even worse. In the end, many of these projects provide a short term boost to the economy by providing work for construction workers and lots of dosh for the owners of big contracting businesses. Do we really have any idea of the final costs for the HS2 project or the benefits (if any) to the economy?
Tracsis (LON:TRCS)
Have made a further acquisition today. They have acquired iBlocks, which seems to offer an integrated back office software & consultancy solution to Railway Companies.
This appears a small (Rev circa £3m) but highly profitable company (NP circa £1.1m) and cash generative company.
Looks like a very nice bolt on to Tracsis (LON:TRCS) developing as a rather unique all round player in the tech/transport sector
I agree, and don't understand the market reaction
Paul - just a comment on Somero Enterprises Inc (LON:SOM) that management flagged much earlier in the year that H2 wouldn't make up the shortfall in revenue for the full year.
Therefore I wouldn't read the slightly lower revenue as "top of the cycle" - it was a function of the weather pattern in Q1. If that hadn't happened they would be well up on the year.
Of course that doesn't mean we aren't at the top of the cycle of course.
I am also long this share and have been for a while. I like management and the business and the cash it throws off a lot.
On the Chinese case stats, the NT Times gives a good view as the the reasons why the numbers might be subject to propaganda control. Time will tell.
https://www.nytimes.com/2020/0...
The NHS is often framed as being in a 'perilous state', maybe its just extremely good at keeping people alive with modern medicine and drugs - extrapolate the rate of success & it will never have enough beds & staff, maybe. I don't want to open a debate on the NHS :) Like all complex systems they are too complex to really analyse, like Coronavirus, negative rates & all that jaz.
Ok too much non shares chat from me today.
Back to shares.
NMC Health (LON:NMC)
the news yesteday seems to have sneaked under the radar somewhat.
Paul I would be interested on your thoughts on NMC
I know its a large cap but for a very recent FTSE 100 company its a bit of a disgrace that yet again companies can report gibberish financial information with the main audit bodies and the FRC simply and the board of directors not being interested in the whole state of affairs.
Perhaps for all listed companies not knowingly not keeping a correct updated ledger of all compay loans and guarantees taken out (with periodic balance verification) - should be treated as an automatic crime similar to money laundering offences. Make any lending insitution equally reponsible for getting confirmation that the finance given has been updated in this ledger. Then there should be a reasonably clear cut route to prison for anyone who chooses to committ such fraud. Backed up by only board members being able to approve borrowing for a listed company.
I am guesing NMC has been one huge fraud in this regard and no doubt the board members left (are there any?) / the auditors and the FRC will also sit on the sidelines and blame others for the situation that has arisen. When they have all allowed the situation to arise by burying their head in the sand.
Per nmc yesterday
The Board of NMC received an update on 10 March 2020 that the Group's debt position was materially above the last reported number as at 30 June 2019, and is currently estimated to be around $5 billion. The work on verifying this figure is ongoing.
In addition to $2.1 billion Group debt reported at 30 June 2019, the Company has identified over $2.7 billion in facilities that had previously not been disclosed to or approved by the Board.
This situation does beggar belief other than its exactly what was speculated was happening by muddy waters. The board though must take responsibility for stating that they thought everything was a ok when things were not and this was pointed out to them. Ok they did an independent review quite quickly but practicably speaking they proved they had no idea what was going on in the company they were looking after - very scary.
Do you know who the auditors were?.....hopefully not Grant Thornton the UK's favourite spiv audit company.
"They are extremely worried about what will happen if the Government's containment policies don't work."
"Looking at a very recent article on Statisa.com comparing which countries are best prepared for a pandemic and the UK come out number 2 well ahead of the third place country. "
I must be checking in all the wrong places - what exactly are the UK's containment policies and preparations?
Hi Paul,
Pretty new to Stockopedia but I have to say I am very impressed with the quality of commentary all round.
Thought I would share a piece of wisdom given to me back in 2000. "a share that has gone down 90% is a share that has gone down 80% and then halved!"
Think this may apply to a few highly leveraged travel and oil companies and serve as a note of caution to others . On the other-hand those that survive will come back stronger. And I have I been an exemplar of following this advice? ..... sorry need to take this call!
Interesting comment by one Chinese doctor on Newnight last night.
Apparently a feature of the infected can be that they show no respiratory distress, but actually their blood/oxygen levels are quite low, and they are quite tolerant of this, and therefore despite appearing at a less advanced stage of the illness, they can quickly succumb to the worst outcome if this element is not monitored or treated early.
Testing is going to be ramped up in the UK, to show where hotspots are developing, but it would be useful it seems if blood/oxygen levels was part of the checklist.
Paul, What are your thoughts on the BUYING that seems to be going on in RBG? Despite the price getting crushed further someone is buying just at or above the 20 period average. Does someone know something? Thx
Paul,
Admire your stance in picking up new small caps yesterday.
I have been trying to work how long to sit on my hands and so far have resisted the temptation to go back into the market. I am looking for the point (or approx point) of maximum financial contagion which should occur at or near peak Covid19 infection rates. Therefore a model that can predict this is of particular interest for me. With new infections having a doubling time of around 7 days, we are going to see an exponential increase in cases, until (for whatever reasons) the upward curve starts to flatten. At the such time we should be better able to assess the Covid19 economic impact too.
In the UK I think we are some weeks away from from a significant reduction in new cases so I will continue to wait and see.
The parlous state of the NHS means that there are hardly enough beds, doctors or nurses to handle normal day to day demands. Even without Covid-19, the system is beyond stretching point. The fact is that the NHS does not have the resources to handle a mass outbreak of Covid-19.
Within the developed world, the UK is probably only second behind the USA in having a health service that is not equipped to handle a mass outbreak of Covid-19.
That is not a political statement. It is what I hear privately from doctors who specialise in respiratory illnesses within our NHS. They are extremely worried about what will happen if the Government's containment policies don't work. The good news is that if you are young or youngish, are in good health or have no underlying health conditions, you should probably survive it.
Meldrew
Within the developed world, the UK is probably only second behind the USA in having a health service that is not equipped to handle a mass outbreak of Covid-19.
I think we have to concede that speaking to a doctor may give you a slightly one sided slant on the story - factually i would agree we are way short of most contries when it comes to bais items like spare bed capacity so i am not arguing that we are not poorly prepared in some areas - however that's not the only thing that matters if there is an pandemic - its about ones ability to respond if one needs to - basically the best prepared countries will equally be struggling capacity wise so its what you can of on top of that - that matters.
Looking at a very recent article on Statisa.com comparing which countries are best prepared for a pandemic and the UK come out number 2 well ahead of the third place country.
Rather strangely the best two ranked countries are the two counties that you feel are least able to cope !! i am kinda guessing that in a real strife the army and other emergency services volunteers and retired medical bods from uk and us can be drafted in and will be at a very high standard when it comes to helping.
https://www.statista.com/chart/20629/ability-to-respond-to-an-epidemic-or-pandemic/
I think we have to concede that speaking to a doctor may give you a slightly one sided slant on the story.
You might be right. I am not a doctor so I have to rely on my sources and my personal experiences. I could have added that I have more than one source. My sources think that the UK could soon be in an Italian style situation because, along with most other European countries, the UK ignored WHO advice on the most effective early actions it could and should have taken to combat the virus. Their belief is that, because of Government inaction in the early days, the Covid-19 genie is already out of the bottle, that present actions do not go far enough to protect us and there are not enough resources available anyway.
It is why I am not currently in shares. If I were confident in my knowledge and ability to short I might be doing a lot of shorting at the moment. I might well dip my toe in.
A bit of good news is that there are two strains of the virus. The most lethal one is less common, mainly because it tends to kill off its hosts so does not transmit so easily. The more common, less lethal strain is what most people get. It is not transmitted as efficiently as flu viruses but it can still kill the vulnerable.
The most effective way of protecting yourself is to wash your hands often and not touch your face with unwashed hands.
I read the link but I am dubious about the findings. The USA health system is notorious for the enormous gaps in its services and the large number of people who go untreated. It is the only country in the developed world where poor people are treated by Medicines Sans Frontieres. I know from my own personal experiences of the UK NHS that it has deteriorated dramatically in recent years.
As the old saying goes: There are lies, damned lies and statistics.
Which WHO advice did the UK ignore?
The UK Government dragged their feet and allowed people travelling from, eg. China, to enter the UK without any medical tests or any serious attempt to isolate them until they were sure they were not infected. EU countries did the same. It is one of the reasons why we are now in the situation we are in.
That's all I have to say about Covid-19. I'll get back to talking about shares. I've got a list of companies on my watch lists to consider investing in when the time is right. SOM is among them.
It is too easy for people to criticize the size and resources of the NHS. Partly because it is in the interests of everyone in the NHS to constantly cry that all the problems are down to a lack of resources, by which they really mean 'government give us more money'. Like all public sector organisations there is a lack of incentive for innovation and improvement. I say that as someone who has provided consulting services to many public and private sector organisations.
Eventually we are going to have to be admission that the NHS as currently structured can't be funded the way it is, as the costs of drugs and new treatments continually rise faster than government resources. At the moment it is still a political sacred cow that all political parties have to say is brilliant, and all blame the other parties for the lack of funding in the past.
john652
I feel cynical, and someone else here keeps saying the same, but are the chinese numbers believable? I hope so but to virtually eradicate the virus seems unlikely.
Being honest the stats in China are so low that it should be easy to prove them as liars - so on the basis that there is almost no new cases in most locals areas excluding people who have been abroad - i would expect if this is lie it would show up on the internet if there are new cases not being reported. As soon as the stats start improving too the need for the lie kinda goes away - do they really have a need to exagerate the drop in new cases being reported whats the motive in that regard? If anything i think as the rest of us its been more a case of burying ones head in the sand than anything else here
More encouraging from a transparency point of view is the stat mad south koreans who have done more testing than anyone i think - they are showing numbers that are trending way down too so that sort of backs up the fact that control measures do work once you allow for the natural time lag.
Presumably there is a point at which the virus has no where to go to stay alive and therefore once all infected are isolated the theory is that after that the spread should stop and the virus then vanishes from the local population.
I would say though that i would expect that a permanent drop to zero once people start moving en mass again is unlikely.
Thats all speculation on my part though so i could be completely wrong in my assumptions. Italy should give us very good signs over the next 21 days though as to how possible this is to nip in the bud (new cases by day stat) - hopefully after the next 3-4 days this may start to show a daily decline if my theory that individual people will start to take additional self preservation measures once the virus hits their locality hard - Watch that space i guess.
The VIX has remained extremely elevated at 53 ... that this hasn't declined suggest that protection isn't being sold and by extrapolation, the bottom is not yet in. The VIX is a forward looking options based volatility measure
at VIX 53 give an implied volatility for the S&P 500 of 3.3% daily or 15.6% monthly : that's pretty bumpy!
I collate and publish a set of market sentiment readings daily and publish as a dashboard: it is rarely this red . I've also started to track the coronvirus data drawn from WHO and visualised by country
From below most of the gauges are on red with increasing numbers of UK share on 52 week lows and all of the indices in the red on 200MA metrics
What is interesting ( alarming?) is that the American Association of Individual Investors (AAII) survey of last week shown below indicates a fair degree of complacency among individual investors with a high degree of bullishness. The survey will be updated this Friday so it will be interesting to see the delta. It would appear that years' of bullishness have conditioned a "buy the dip" response. Conversely, an opposing narrative is this correction is overdone and the individual investors have it. That was last week though so maybe it is a case of a slow boiled frog.
As part of that counter argument, typically when the Fear & Greed Index is in low single figures then the indicator become contrarian on a reversion-to-mean basis.
However, given that every rally gets snuffed out (even a 50bps based one this am looks weak) - I'd go with the sentiment as directly correlative to price movement for now.
Thanks for your detailed analysis. I agree that the US markets may fall a lot more. On a purely amateur reading of the situation if one or two leading politicians in the USA are tested positive and have to self-isolate I could see their markets dropping substantially.
So the cash portion of my portfolio, held for a situation like this, is not going to be invested yet. In a couple of months we may be able to see how the economic situation develops.
I feel cynical, and someone else here keeps saying the same, but are the chinese numbers believable? I hope so but to virtually eradicate the virus seems unlikely.
I can't vouch for the virus numbers but there are things that cant be hidden.. The satellite pictures of pollution starting up again are compelling. China is heading back to work. Devro (LON:DVO) had just reported its Chinese Plant is back and running as normal. The questions are virus spread and economic impact - it may be the economic impact whilst huge may be temporary for many.
I feel cynical, and someone else here keeps saying the same, but are the chinese numbers believable? I hope so but to virtually eradicate the virus seems unlikely.
No, I'm not cynical about the numbers, I suspect they are accurate, and they demonstrate the impact of major action to limit spread.
But, what remains unanswered is what happens when restrictions are relaxed or removed. By seriously limiting spread you limit the numbers infected quickly, but you also leave a large % of the population who have not been exposed and hence have built up no immunity. It will be no surprise to see future rises in infections, or at least a long tail of them. That's certainly a much better outcome than letting it rip and services being competely swamped, but I think it's much too early to say it's over.
I note that the Chinese appear to have introduced an app which assesses your level of being a likely risk, and which they are using to limit access to those who rank high. That's probably a very effective way of controlling ongoing infection rates - but it's unlikely to catch on here!
Hi Paul - I think this was mentioned by someone else in a comment on yesterday's SCVR, however would you be able to provide a bit of colour as to the mechanics for shorting indexes (as you have been doing), any pitfalls to avoid? I only have experience on long investments and feel now (more than ever) the need to start considering shorts as a hedge!
Best, SB
Hi Sammybates (and others),
I don't feel qualified to write an article about shorting/options, etc. Whilst I understand the basics, it's not my specialist area, hence not something I'd want to write about. There will be plenty of articles already out there on the internet, so it's probably best to just google it, and home in on good quality sources.
Generally speaking, I think hedging, and shorting, are far too risky for most investors. The best hedging is just to diversify, with a mix of asset classes, and if you're nervous, then a pot of cash on the sidelines.
People need to take regulated advice I think, that's not what we do here, this is just a discussion forum. I really wouldn't want to get into writing articles that might draw people into potentially disastrous losses, which experimenting with shorting, options, etc, can produce.
Regards, Paul.
Thanks Paul, completely understand. Appreciate the response!
Best, SB
Obvs a bit silly to draw conclusions from short term moves but....rates down 0.5% and chancellor about to announce fairly major investment from extra borrowing....and GBP up on USD. The market likes active govt now....and will like more of it...expect much more...feed me please
In the last 24 hrs I feel clearer that COVID19 is not the economic disaster many fear. Undoubtedly severe short term supply and demand shocks + a shock to health infrastructure. But we are being given the tools to see through the passing shock. It will leave permanent traces (inc some businesses gone) but death and destruction are part of the economic process and as long as we believe in the future we look through. We are going to be given everything we need to look through once we start glancing up.
COVID19 has made us very myopic. Plus there are many clever people that have been telling us (first quietly and now shouting) that this exogenous shock was coming. And as it was a shock they layered in all our other economic, political and social weaknesses (debt, low growth, Trump, health systems, etc) on top of the virus shock to create negatively cascading visions of the future. These other angsts had been stirring around particularly with many of the more interesting and high profile commentator sorts.
Today Lagarde of the ECB warns that this is a major economic shock a la 2008. This is already what we fear and so the ECB acting like this is the case will be good news. And it is nothing like 2008. 2008 was a genuine and, to most, inexplicable heart attack emanating from deep within a chaotic financial system virtually no one understood and officialdom had very little control or leverage over. I wouldn't claim they particularly understand it today but they have created some medicines to treat and control financial disease (wrong ones often but that is for another time) and they crudely work...today there is financial system stress but no systemic toxicity....UK banks are offering assistance and forbearance to people to help them thro hard times not margin calling them.
Now clearly COVID19 may armageddon-ify into something much more black plague ish but without trying to be callous this is looking like a nasty storm but in a teacup. In Italy the average death is >80 yrs old....not that our elder citizens are worthless and most will be someones parents/grandparents etc....but simply irrespective of how healthy one feels at that age mortality always lurks. Of course there are others with vulnerability not based on age and for those people as well as the elderly we need to do what we can to protect them. Partly as others are impacted by the excessive stress on healthcare systems if vulnerable groups topple too quick.
BUT the crisis roles towards us and we know its coming and escalating. The market fast forwards this as always. As it arrives more fully our coping systems will not be perfect but they will be developed with high and increasing economic safety valves opened (expect more to come from govt etc...whatever it takes...). In the US Trump has proposed 0% payroll tax as a stimulus/firebreak....that's a $1.2tr stimulus (and double current deficit too by the way!). It truly is yuge. Trump's idea hasn't been accepted at the moment and there is a danger that partisanship in US stalls action a bit like it did in 2008/9....however, the acute health fears this presents will not let them stall for long.
The virus brings damage for sure but change is always a stimulus to action and some growth too (most growth is not innovation but mundane change)...add on large stimulus and as the real virus wave and impact arrives and short term circumstances are more dire we perversely will be able to look through.
In the last 2 weeks we have been on acute hypermedia angst acceleration cycle. This angst acceleration must slow even as the reality accelerates negatively and we move to what is rather than what we fear.
I'm not suggesting that the market is going to snap back....and it may still move down more say as particular stresses arrive. The oil shock was dramatic frays nerves but its a distraction. Overall US market levels remain vulnerable as valuations and expectations relatively high there. In addition, more downside may come out of US until the politicians can agree on something partisanship aside. And, of course, China getting fully up to speed in next month or so is essential.
I am suggesting that at this point looking at the overall market is not the thing for stock pickers to do....if you pick stocks (not just trade them) then now is the time to pick some
I seriously think you should start a blog.
Hee hee. I'm probably too lazy and not enough to say to do a blog...but if I did I'd call it 'Sh1tfaced beta'...I thought about it but seems the space is crowded and lots of people doing them and most of them with more detail and dedication than I would bring. I did think about writing a book re our current economic, political and social times....but it would need to be a work of fiction as writing a straight one would be dull and is done by many others (just think of all those post 2008 books!). Plus I actually think a decent fiction would be much more powerful and successful in conveying our situation and potential changes as factual is too constraining and very quickly would seem wingnut. I follow and read many macro guys some of them would be viewed as extreme or wingnuts...but IMO the future is usually foretold by a nutter so got to look through a hundred to find the one...or look at many to get a sense for what's going unfold as it does rather than the dull ex post explanation (straight book!)
I do write some things for an alt economics mag....I'm not an economist and my role for the mag is write a bit of a non-consensus trouble making lead opinion piece. I put them on medium if I think they are more broadly palatable
Eg re hypermedia and mad thinking - https://medium.com/@mojomogoz/live-tonight-hypermedia-un-enlightment-11e93cc02ef3
Or this one re the 'unbearable lightness of western hegemony' https://medium.com/@mojomogoz/the-unbearable-lightness-of-western-hegemony-8860c413c52c (this one is a bit messy and embarrassing as I blew up a shorter tighter piece to get broader thoughts down and its a bit messy and I can't be bothered going back to edit and make tighter)
Ciao
Re Morses Club (LON:MCL) - another non-standard finance share I hold! Now down 30% today on 18-23% profit warning vs unstated consensus. This has 2 parts. Delays to newly acquired from administration Digital lending/banking companies. This might be expected and actually I am reasonably sanguine about this as trouble often occurs in such re-wiring exercises. I think they are right to get it right before motoring ahead.
More concerning is the continued drop in Home Credit customer base of 5%. This now looks to be an established trend with Non-standard Finance (LON:NSF) and Provident Financial (LON:PFG) broadly saying the same thing - that Home Credit is in slow steady decline.
Really surprised they did not talk to the C-virus since collecting cash door to door from low income/casual workers is not going to be easy in a lock down!
Fortunately, and unlike Non-standard Finance (LON:NSF), the balance sheet is strong at Morses Club (LON:MCL) and so it should it has time to weather the storm in Home Collect (extra volume/rates offsets more impairments) and re-invents itself to serve its consumer base in a new age.
Hi Zipmanpeter - I think on Morses Club (LON:MCL) you may be mis-reading the Home Credit drop. What has happened is that the company has both tightened its credit criteria over the last year or so and moved its customer base more towards digital lending. This has resulted in a drop in customer base in the HC division. That, however, is countered by a lower impairment charge.
The drop in this years forecasts of circa 20% is temporary and related to higher start up costs in the digital division so I think forecasts for next year will stay broadly the similar. On that basis after todays 30% fall puts it on a PE of 5 with yields of 11%.
Feels well overdone to me. The divi remains covered as reduced EPS for this year will be 10p (divi 8p). Next year EPS is estimated at 15p
Hi Davidjhill - Thanks for response. I agree that LT picture for Morses Club (LON:MCL) is good - I intend to hold despite the profit drop this year. But I do think the evidence is that the underlying Home Credit market is contracting is solid now.
PFG/NSF and MCL numbers have all gone down in recent years, as they all priorise quality. This has helped lower impairment rates but reduced customers numbers. I had hoped that MCL adding Digital services would have reduced churn enough to compensate. That it has not when the other big players are shedding customers suggests the overall market is shrinking, especially as the expectation is that smaller Home Credit players are also shrinking as regulatory costs rise and digital investment by the big 3 is hard to copy.
However, I don't think Morses move is squeezing any of its Home Credit customers over to digital. Indeed I think what Morses have done by providing digital services to the core Home Credit model will aid customer retention.
MCL's true (Shelby) Digital business is separate (completely new contacts) and complementary (offers extra services) - which is why I like it despite the short term losses and (my belief) that Home Collect numbers are well down on the 1.7Mn number quoted by the FCA study from 2017 and heading South.
Next 6 months will tell, as a lot of 'new' customers will need short term credit to cover missed wages etc due to the C-virus. Normally, this would lift Home Credit customer numbers. Interesting to see where they go to get that credit : Home Credit or other. My bet is Other.
Hoping for community comments on non-standard finance stocks since Paul normally shuns this area (and Budget / Coronavirus / Russia vs Saudi standoff may be diverting some attention from this important part of UK small cap world !)
Non-standard Finance (LON:NSF) finally announced a 6yr £200Mn securitisation deal today, expected since Aug 19. This is expected to save £1mn pa in interest by replacing some of a more expensive earlier loan . Much more important to me, it will also enable further growth in the EveryDay Loans F2F bank branches and Guarantor Loans division. These have a great market opportunity but have a high chance of bumps along the way. 'Forbearance' ie allowing customers to delay re-payments is a normal part of the business and likely to be called upon heavily in next 6 months.
Impairments will almost certainly still jump in next 6months and equity balance is paper thin - every drop of free cash is going to be critical until operational leverage kicks in. I therefore expect (hope?) the dividend is going to be cut as well. Notably excluded was the Home Credit division. Is this going to be sold off to raise cash?
With the share offering over 15% forecast dividend (!!), something clearly needs to happen - either the share now recovers big time or existing equity is going to get mashed - either through it going bust or via massive equity dilution (by a placing to PE that small investors are excluded from?) .
I continue to hold a big slug as I think the medium term picture is excellent for both EveryDay Loans and Guarantor Lending (as Amigo stutters under self inflicted wounds) . You probably cant find many more hated segments than non-standard finance at present and I think even more competitors will go bust even as rates rocket.
However, I recognise this is a businesses cornering on 2 wheels and super high risk.
Essity listed in Stockhom is an interesting play on all the nutters frantically buying toilet rolls :)
Ref Coronavirus
One slight bit of good news with reference to the Coronavirus is that i have seen the first decent analysis of how temperature may affect the Coronavirus spread. The data is very bitty and not firm enough to give any concrete answers at present but the anlysis linked below does suggest that the virus does seem to spread more easily at low tempratures, which gives some hope that all other things being equal we may be soon leaving the "peak" season where conditions worldwide are better for spread overall. Note this isn't to say that the virus will be as seasonal as something like the flu (simply not enough data at present in that regard) but it does seem that at least there is some slowdown of transmission with hotter conditions.
https://www.benzinga.com/pressreleases/20/03/a15521538/further-analyzing-coronavirus-cases-against-average-temperatures
The other slight positive i am taking is that China (daily cases grinding to a halt) and South Korea (daily cases well down) have shown that firm action taken can nip in the bud ongoing spread to minimall ongoing level (if we belive the stats) - ok it may jump back up when quarantines end but at least there is a plan of attack that appears to avoid the worst case scenario of 40%-70% being infected in the fisrt 3-6 months. Hopefully in this regard Italy over the next 7-10 days will see their new case count drop too once the delay in getting the diesease filters through after their new measures have taken effect.
Note news wise i expect the general news to be much worse over the next 7 days as i am pretty sure case count will continue to rise quickly in US/UK/Spain and France - thats a given from where we are and the lack of procative action taken to date in these countries (well us and uk for sure)
Kudos to whoever pointed me in the direction Of Dr John Campbell on youtube as his analysis has been spot on now for the last month with his excellent daily progres updates as to how this nightmare is unfolding.
Re peak season, aren't the opposite in the North and South hemispheres?
Have you checked the proportion of the World's population that lives in the Northern hemisphere?
Re peak season, aren't the opposite in the North and South hemispheres?
Yes but as DWit199 has pointed out population sizes are skewed to favour on the North - a quick google check suggests its 88% which would have been higher than my guess but there ya go.
Also the issue for those living in the south is specifically addresses in the linked article if you read it - those that do live in the southern hemisphere are more concentrated in areas that have milder winters than the world average.
On closer examination however we see that Southern Hemisphere winters are milder than many places in the Northern Hemisphere. For example, Hobart is Australia's coldest city and has an average temperature of 8.2 degrees celsius in July which would be classified as "middle" temperature
ezlifeme
Southern Hemisphere winter is still relatively warm in most places. Most Southern Hemisphere Countries are so far north of the Antarctic that even southerly winds don’t bring genuine cold weather, except on high ground and very far south of South America and, occasionally, South Island of New Zealand.
Problem with this theory is that tropical Countries like Singapore also have Coronavirus cases.
Have a hunch that it’s FAR more widespread elsewhere than being recognised simply because in so many cases it seems to be so mild people don’t even realise they’ve got It’s the more severe cases and especially the already unwell elderly, where it’s a big problem, along with fear of mutation into something much more severe generally that’s a big concern.
Investment wise I was like Paul and kept changing my mind about market effects. I cleared out everything I had any doubts about, and all shares obviously affected like travel companies, and raised far more cash than normal. Have now decided while this pans out to nibble add ons to existing holdings on big down days, sell as usual if any issue profits warnings, and do nothing on up days.
you are a brave man Paul. The only add ons I am making are to my high yield section of my portfolio. A yield in excess of 15% is not to be sneezed at (excuse the topical pun) which is what Diversified Gas & Oil (LON:DGOC) is currently offering. They have already confirmed that they will be joining the senior market this year so will increase the demand for the stock. I have a modest holding now and watching it like a hawk for any further price reduction which would enable further averaging down and further increase in the yield.
Ref £Dog
Lets hope that investment doesn't live up to its name.
The key phrase here may be "is currently offering". The dividend is only just covered, and oil prices have slipped since. (I am off to take rmillaree's DGOC for a walk!!!!!)
These heavily indebted oilers frighten me !
My morning smallcap tweet: Morses SOS
Global Ports Holding (LON:GPH) Morses Club (LON:MCL) Immotion (LON:IMMO) Tiziana Life Sciences (LON:TILS) Somero Enterprises Inc (LON:SOM) Medica (LON:MGP) Costain (LON:COST), Duke Royalty (LON:DUKE), Mattioli Woods (LON:MTW), Dignity (LON:DTY)
Global Ports Holding (GPH) is 'the world's largest independent cruise port operator. Oh dear. Has commercial ports as well. No meaningful impact from the Covid-19 virus yet but suspends dividend until the situation becomes clearer.
Morses Club (MCL) sounds pretty positive then boom - guides adj pretax 18%-23% below mkt forecasts. Re-engineering of acquired digital businesses has taken longer than expected.
Immotion (IMMO) covir-19: co has sufficient VR headsets and motion platform seats to deploy all current and forthcoming installations. Plant in China back at work.
Tiziana Life Sciences (TILS) expediting development of TZLS-501 monoclonal antibody) for treatment of patients with lung damage from coronavirus due to a cytokine storm. There are exisiting treatments.
Somero Enterprises (SOM) FY in line but smaller special div than last year. Covir-19: "supply chain has been unaffected as we do not source components from China and while we have yet to see delays in projects outside of China." Outlook confident. I hold.
Medica Group (MGP) FD resigns. He is thanked.
Costain Group (COST) FY in line. Plans £100m raise (rights/placing?) in coming weeks. Div cover rebased to 3x.
In line: Duke Royalty (LON:DUKE) Mattioli Woods (LON:MTW) Dignity (LON:DTY)
Your views on FDM would be much appreciated Paul.
Somero Enterprises Inc (LON:SOM) Hi, I wanted to discuss the Dividend from Somero ($0.13), which is meant to be paid at the end of April and will cost $7m out of Somero's cash pile of $24m. Surely the company should have a delayed dividend in current circumstances with a pay date of say 30th Sept with a caveat depending on circumstances at the time. With capital equipment demand likely to suffer a very sharp slowdown, if the Coronavirus epidemic turns out nearly as badly as looks likely, I would have thought SOM would need to save its cash just in case. (On that front I CANNOT BELIEVE our Government's softly softly approach - it looks ridiculously complacent).
The headline figures are of total cases is complete fiction. If a government health minister has the virus (which one does!) then you can bet its already rife in the population.
PeterW
Hi, I wanted to discuss the Dividend from Somero ($0.13), which is meant to be paid at the end of April and will cost $7m out of Somero's cash pile of $24m. Surely the company should have a delayed dividend in current circumstances
My thoughts are that they have updated today and trading is still on track - as you have pointed out they have the huge cashpile that covers the next dividend twice over. They have decent downside protection in that at present they expect decent profits on an ongoing basis that will keep topping up the kitty. So until such time as circumstances actually worsen thats the time i would worry about voting future dividends. If i held Somero Enterprises Inc (LON:SOM) i would be 100% happy for dividend to be paid with zilch worries - not something i would say of many companies i am invested. Note Somero have zlich debt and a $10 mill debt facility if they need it - so i would say a low point of $10-$15 mill cash directly after dividend paid is still a very strong financial position to be in.
Note Somero have zlich debt and a $10 mill debt facility if they need it - so i would say a low point of $10-$15 mill cash directly after dividend paid is still a very strong financial position to be in.
Please remember, that as always, the cash reported was just a snapshot at the end of 2019. At the point the dividend is paid the amount could be quite different depending on working capital flows.
All the best, Si
Somero Enterprises Inc (LON:SOM) results not sparkling but more than enough to support (and hopefully boost) the current price. One of the cheapest things out there IMO (unless there's a massive US recession coming)
BOE Announces Emergency interest rate cut of 0.5% to 0.25% together with support measures. Budget effects already Paul?
Another unsettled day?
I really appreciate your comments on how current conditions are affecting you psychologically. I am finding the ongoing tug of war in my own head quite exhausting!
For me the central issue is whether the Covid19 crisis is something that will fade away in a couple of months or whether it is something that will be with us for a lot longer, perhaps indefinitely. Some experts are saying that it could become endemic, which it means that it will be like seasonal flu, - constantly circulating and mutating but at least 10 times more deadly. If so, things will not just revert to normal - there will be some kind of "new normal".
In the short term, the focus will be on whether and how the virus can be contained, But even if it can be contained, we do not know the economic cost of doing so. In particular, we don't know what happens if and when restrictions start to be lifted.
There could be some very difficult policy choices ahead. Are we as a society ready to contemplate a choice between protecting our vulnerable populations and protecting our economic system? But perhaps it is too late? Just look at what is happening in the Itay where doctors are already having to decide who gets treatment and who misses out.
In the longer term we can be fairly confident that there will be vaccine but that is at least 18-24 months away. This should at least allow things to return to some kind of normality.
Of course, I don't know what is around the corner but my best guess is that things will get quite a lot worse before they get better. For that reason, I think another downward lurch is likely and I will be keeping by finger off the buy button.
If I am wrong and the crisis fades away and I miss out on a bounce, then at least I can console myself with the fact that the world is a safer place!