Small Cap Value Report (Wed 12 April 2023) - SED, SOS, SYS1, EMAN,DLAR

Good morning from Paul & Graham!
Signing off for today at 13:08
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Summaries of main sections
(more detail below)
Sosandar (LON:SOS) - FY 3/2023 TU - unch at 23.5p - (market cap £59m) - Paul - GREEN
Revenue in line with expectations, but PBT is c.£1.6m, a shortfall from £1.9m forecasts. Blamed on accelerated growth spending (eg. some key new hires). Now pushing ahead with international expansion via partner(s), which I think is more important than a slight profit miss. Plenty of cash, following another fundraise recently. Ambitious, capable management. I think risk:reward is now better than it's ever been, with the company now profitable & international expansion starting.
System1 (LON:SYS1) - ahead of expectations TU - up 14% to 185p - (market cap £23m) - Graham - AMBER
Profitable in H2 and for the year. Shareholders must now decide on a proposed management shakeup. As usual, SYS1 looks frustratingly close to long-promised success.
Saietta (LON:SED) - 70.5p (market cap £73m) - Paul - RED
A very strong share price rebound in recent weeks has caught my eye. Unfortunately, I think this looks like a speculative bubble at this stage.Negligible revenue and gross profit to date. Very heavy cash burn means I suspect another fundraise is highly likely, despite the company's denials. A key customer looks very small & weak. High risk & entirely jam tomorrow. Speculative upside could come if it lands some more significant deals with large manufacturers. No sign of that yet, but it says 11 projects are in the pipeline. Just a risky punt at this stage. Thumbs down.
Everyman Media (LON:EMAN) - Results in line - up 0.8% to 66p (market cap £60m) - Graham - RED
This cinema chain is pleased with an improvement over the Covid-impacted 2021. However, the 2022 results are still poor and choosing to expand rather than consolidate looks risky.
De La Rue (LON:DLAR) - Profit warning - down 23% to 38.4p (market cap £75m) - Paul - RED
More problems reported, with a slowdown in the larger bank note printing division, and low order book. This looks seriously risky now - discussions with bank to amend covenants, request to defer nearly £19m in pension deficit contributions. Another equity fundraise looks a high probability I think now, and could be on horribly dilutive terms, if it can be done at all. The outcome here could range from multibagger, to going bust, so it's impossible to value. Too risky at this stage, I think.
Paul’s Section:
De La Rue (LON:DLAR)
38.4p (down 23% at 11:01)
Market cap £75m
DLAR’s share price is volatile this morning, after yet another bad news release from this bank note printer & security authentication products group.
The turnaround plan, which looked promising a while ago, clearly hasn’t worked, and the share price is now back down to where it had to do an emergency fundraise when covid first struck in spring 2020.
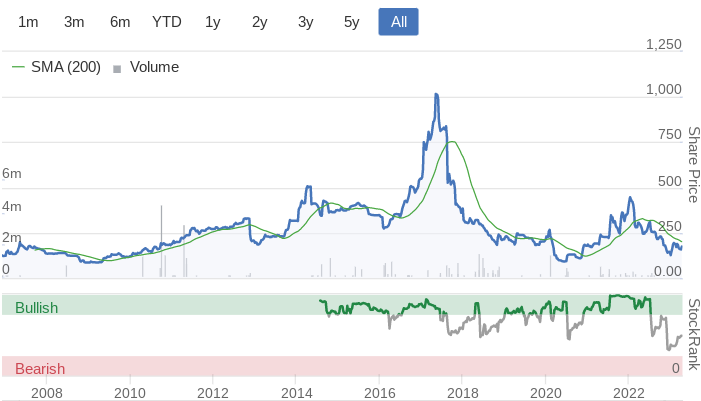
As you can see below, this used to be a solid, blue chip company, now it’s a penny share -

Dilution hasn’t helped, but nor has it been ruinous - the share count was 112m in 2017, and is now 195m. But will it need to do another dilutive fundraising, I wonder? The share price is telling me that the market must consider more dilution to be a serious risk.
Brokers have been steadily, and substantially lowering expectations before today’s update -

Here’s today’s news -
De La Rue plc (LSE: DLAR) ("De La Rue", the "Group" or the "Company") today announces a trading update on the financial year ended 25 March 2023 (FY23).
The Group is also updating guidance for the financial year ending 30 March 2024 (FY24).
FY 3/2023 - if I’m reading this correctly, it seems to be saying adj operating profit will be about 5% (“mid-single digit percentage”) below market expectations - but then refers us to Numis & Investec research notes, which of course private investors don’t get access to. Great.
Adj operating profit was £9.3m in H1, if that’s any help. There were large adjustments - costs relating to restructuring in H1, so the H1 statutory loss before tax was £(23.8)m. The accounts are quite complicated to understand, I find, especially without sight of broker forecasts. But it looks like a modest profit miss for FY 3/2023.
Net debt at 25 March is expected to be in line with market expectations, whatever that is?
Looking back through old RNSs, the last reference I can find to net debt guidance was provided with the interim results, on 23 Nov 2022, indicating expected net debt of £88-92m as at year end (Mar 2023). This is net bank debt, and excludes lease liabilities.
Checking back, I don’t seem to have reviewed DLAR’s interims in Nov 2022, as they were so complicated, and it got kicked into the long grass.
I note there’s a “material uncertainty” going concern statement though, which is obviously a worry, more so today, given that performance appears to have again deteriorated below expectations.
Combined with hefty bank debt, I think we clearly need to treat this as a higher risk, special situation - which could be a great recovery share, or could turn into a complete disaster (it’s most of the way there already for existing shareholders).
So far, the announcement doesn’t sound too bad for FY 3/2023.
Moving on to:
Guidance for FY 3/2024 - this is where it gets uglier - mentioning a “downturn in currency”, affecting the “wider industry” not just DLAR, is “causing a significant degree of uncertainty”.
Demand for banknotes is lowest in 20 years, and DLAR’s order book low - no figures given. I suppose that does make sense, given that so many of us are now using cards to pay for everything, not cash.
It sees signs of a recovery, and “a significant number of new tenders actively underway”. Great, but tenders are not orders. And timing is said to be uncertain.
Authentication division sounds mixed, but no figures on profitability are provided for either division.
We do get guidance on total group profitability at the adj operating profit level, which is “in the low £20m range”. That’s a single number not a range, but I presume they mean low twenties of millions of pounds.
I don’t recognise adj operating profit as a valid metric - because it ignores the finance charges, which will be quite substantial given the level of bank debt & higher interest rates, which it mentions as an issue.
Bank covenants - in discussions with banks, seeking amendment of the covenants. Oh dear, this is getting worse with each paragraph.
Pension deficit recovery payments are huge, as we’ve reported here before. The company has requested deferral of the next £18.75m payment (it doesn’t say when this is due). It’s a big number. Pension trustees are normally pragmatic on this, but it can’t be guaranteed that they'll cooperate.
Put all that lot together, and I think another equity raise is now looking a big risk. In the circumstances, equity holders should be prepared to stump up more funding. Banks are not there to provide risk capital, and nor should the pension scheme have to compromise itself just because the company is having cashflow problems. Although if bank & pension trustees don't compromise, they might kill off the formerly golden goose.
Not mentioned in today’s update is the shareholder revolt underway, and legal problems that have recently arisen re Kenya and India.
Paul’s opinion - DLAR is obviously a can of worms, and has been for a while.
It could be a multibagger, if it manages to avoid dilution from an equity raise, and trading improves from new orders.
Worst case? It could go bust. Or next worst case might be heavy dilution from a deeply discounted placing, greatly diluting existing holders. Private investors may or may not get access to such a fundraise, if it were to happen. So why get involved at this stage?
Banks have previously been happy to give time to companies to recover, when interest rates were zero. That’s not the case any more, so I don’t think we can assume banks will necessarily play ball. With interest costs accumulating, they might insist on a placing as the price for continued, reduced support maybe? It would be good to talk to someone senior in banking, and get a handle on what the sector is likely to do, generally.
Does DLAR have any assets tucked away that it could sell to reduce debt? That might be worth looking into.
It’s a lot of business for a modest market cap, especially when you look back on previous levels of profitability in its heyday.
For me though, it’s just too uncertain, and too high risk. Hence I don’t have any choice but to report on it with a thumbs down. RED on our traffic lights system.
Risk takers might get lucky though, so only time will tell how this pans out.
Sosandar (LON:SOS)
23.75p (pre market open)
Market cap £59m
Trading Update & Progress on Growth Strategy
Sosandar PLC (AIM: SOS), one of the fastest growing fashion brands in the UK, creating quality, trend-led products for women of all ages, provides the following trading update for its financial year ended 31 March 2023.
Sosandar’s headline is -
A milestone year, delivering revenue up 44% YoY and first full year of profitability
Quite a detailed update for FY 3/2023, so I’ll just draw out the main points as I see them-
Revenue hit target of £42.5m
Profit before tax looks to be a c.£0.3m shortfall, with “at least” £1.6m PBT actual, versus market consensus (per Sosandar’s helpful footnote) of £1.9m.
Reason for the profit shortfall is said to be bringing forward some “investment” (ie. expenses) into FY 3/2023 that had been planned for the following year.
3 big hires of senior management roles.
Mobile app to be developed & launched in Q2 of FY 3/2024 (quite surprising they haven’t had an app before, which I did ask them about a couple of years ago).
UK wholesale partnerships going well - “extremely strong” trading via M&S, Next, John Lewis, Very, and JD Williams websites.
Sainsburys online launched March 2023. Going into stores (first time) in Aug 2023.
Cash - net cash of £10.5m end March 2023. Raised £5.5m net of expenses in Feb 2023.
Gross margin - strong at 56.1% (up marginally from 56.0% LY), despite increasing mix of lower margin wholesaling. This is a very good overall margin in my view, and with high-ish average order value up to £97, this looks a decent business model, I think - as evidenced by the move into profit for the first time, now it has achieved sufficient scale.
International opportunities - this is the best bit, and could trigger a significant re-rating of the shares once market conditions for small caps are more bullish. I can remember the move from UK-only to international, put a rocket under Asos shares early in its growth phase, and took the share price up to previously unthinkable highs. If SOS gets even part of that effect, the results could be exciting, I think. Although there's a lot less excitement (to put it mildly!) these days about eCommerce businesses & hence valuations.
A deal has been signed with Global-e, for worldwide sales. I’d want to focus on this for further questions with management, as the key area. This goes live in the current quarter ending June 2023.
“Active discussions” are underway with other international partners.
Paul’s opinion - some people might be disappointed with the £0.3m profit miss for FY 3/2023. However, I’m more focused on the longer-term picture, and we have good news today that international expansion seems to be actively starting. To my mind, that’s worth more than the disappointment over a modest PBT miss.
Let’s see what the market thinks!
I wish I held Sosandar shares, and really do want to get back in, when funds allow.
There's an analyst presentation online shortly, I might try to dial in to that.
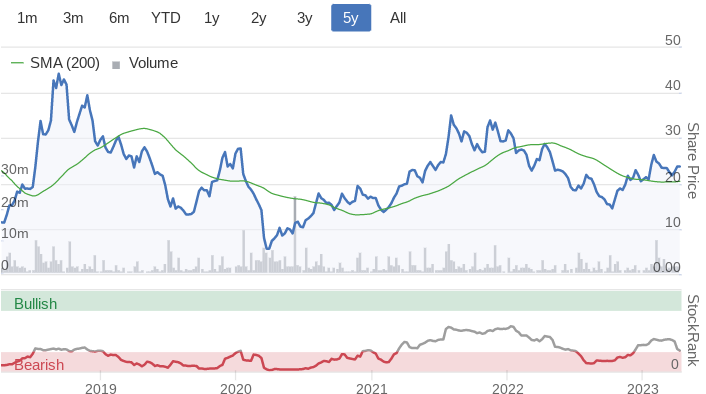
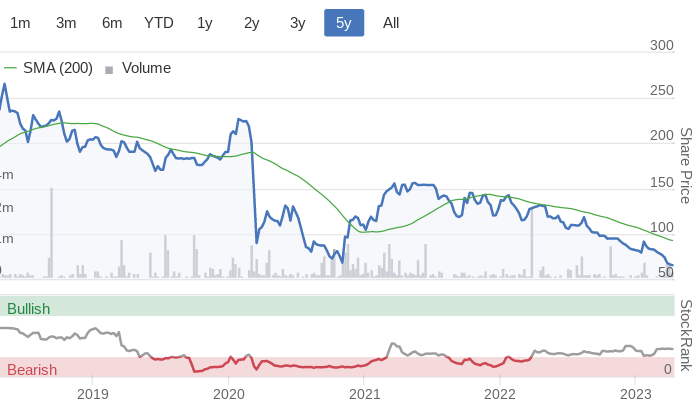
Looking at the 5-year share price chart below, we can see that it's hardly gone anywhere. How come, since the business a startup, which has since grown exponentially and moved into profit? It's due to large dilution unfortunately - when Sosandar listed (by reversing into a cash shell, which worked well, as it meant there was good liquidity from day one) it had 106.8m shares in issue, and the float price was 15.1p. Today there are 248.2m shares in issue, and the share price is about 23.0p. That said, I think investors today are getting vastly better risk:reward than people (like me!) who participated in the original float, when it was just a tiny speculative startup.
Saietta (LON:SED)
70.5p (yesterday’s close)
Market cap £73m
This share keeps cropping up on the top % risers list, so thought I’d take a look.
Saietta floated in July 2021. It makes electric drives for EVs, where it claims patented IP making its motors perform better & more efficiently than competitors.
Production (little so far) is in Sunderland, with a supply chain in India also being set up with partners (see recent announcements).
So make no mistake, this is a jam tomorrow project, which is highly speculative, and heavily cash burning at the moment.
Graham reviewed it here in Oct 2022 when weak interim results came out (negligible revenues, and tiny gross margin, plus a £10.1m H1 loss before tax). The only saving grace was a £22.7m cash pile at Sept 2022, following a fundraise (£23m at 138p/share) shortly before in Aug 2022.
Sorry, it was the interim results which Graham reviewed in Dec 2022 here. The previous announcement was lowering forecasts, with claims that it was chasing bigger, longer term revenues, instead of maximising short term sales.
Why has the share price taken off recently? It’s bounced from a low of c.20p to be a 3.5 bagger at the time of writing, so well done to anyone who bought near the recent lows -

.
As you can see, it’s still a long way below the c.292p share price peak in Nov 2021.
Looking through the latest announcements, the excitement seems to be due to talking up the Indian supply chain, and a recent £5m follow on order from existing customer in the USA, AYRO, which makes electric delivery trucks.
If we attribute value to contract wins, we have to think about who the counter-party is. Looking into AYRO, it’s a tiny company, listed on NASDAQ, but with a market cap of only $19m! So what we have here, is one tiny, heavily loss-making company, placing an order with another tiny, heavily loss-making company. Hence I wouldn’t attribute any value at all to the £5m contract win announcement. It could easily end up being a loss-making project, is AYRO runs out of cash. In any case, each unit is only being sold for £1.7k (£5m divided by 3,000 units), so I don’t suppose there’s much of a profit margin in there, manufacturing on a small scale in the UK.
Cash burn - the £22.7m cash pile at Sept 2022 has dropped alarmingly to £11m by Feb 2023. Despite this, the company says in recent updates that it has enough cash to reach breakeven. Pull the other one! I don’t believe that for a second, based on its historic cash burn. Hence be prepared for the possibility of another fundraise, probably at a much lower price than the last one.
Paul’s opinion - I have to throw an ice cold bucket of value investing over the hot heads buying this share! So far, it’s only achieved tiny revenues, negligible gross margin on product, and is very rapidly burning through its Aug 2022 cash raise from shareholders.
The company is worth nothing as it stands, to a value investor.
So the valuation is based entirely on hopes for future potential. Hence punters need to properly investigate the product, the competition, the strength of the IP, etc. If this really is a market-leading product, and the IP is properly protected with watertight patents, then the company could be valuable.
Jam tomorrow companies like this rarely succeed on AIM. Even when they do, it’s years late, and after numerous highly dilutive fundraises. So the optimists who get in early, end up nursing heavy losses usually.
I could be wrong, but the recent surge in share price just looks a speculative bubble to me, with little substance. Although it says there are 11 live projects in the pipeline, so more contract news could excite the bulls. If a really major contract with a big vehicle manufacturer is announced, or a big licensing deal, then that could change things for the better, at which point I'd reassess things, and change my mind if appropriate, based on the new facts, as is only logical.
I’m just reviewing the numbers here, not the potential, and based on the figures so far, I’ve got no option than the rate this RED, with a thumbs down.
After more than tripling in price recently, top-slicing the profit might be a good way to de-risk things maybe? But it’s your money, so your decision, as always.
Graham’s Section:
System1 (LON:SYS1)
Share price: 185p (+14%)
Market cap: £23m
This marketing research company provides a trading update in some unusual circumstances. Certain shareholders (who also happen to be former company executives) are attempting to change the makeup of the Board.
Before I get into that drama, let’s take a look at today’s Q4 update for the period January to March 2023.
The company has increased the level of detail it provides when breaking down its sources of revenues. I’ll try to summarise the key points:
Data revenue rose to £4.1m in Q4, so that data revenue for FY March 2023 was £13.7m (previous year: £9.7m).
Consultancy revenue is now classified either as “data-led consultancy”, or as “Other consultancy”.
“Data-led consultancy” grew in Q3 and again in Q4, and contributed £3.5m of revenue for the year.
“Other consultancy” was more variable but still contributed £6.2m of revenue for the year (down by about 50% compared to the prior year).
Total revenues for FY March 2023 are £23.3m (previous year: £24.1m).
The company sees this financial performance as a strategic win:
During Q4, the Company made substantial and measurable progress towards the strategic objectives that the board set out following the strategic review, specifically growing our standard Predict Your and Improve Your products (platform-based data and consultancy) to a point where they represented 80% of revenue in Q4.
They note that aggregate revenues from “data” services and “data-led consultancy” were up 38% year-on-year, and contributed 73% of total revenues for the year.
Their strategy is to target the world’s biggest advertisers, who are mostly based in the United States:
Excellent progress was made in the US in Q4 where we won new mandates from 3 of the country's 25 biggest advertising spenders, including the largest. The US delivered its highest half year of revenue since FY21, and standard product revenue increased by 23% for the year as a whole.
Profitability - one of the sticking points for this stock has been the lack of profitability in recent years. It’s all very well running a new strategy, but the stock market is impatient. People want to see profits sooner or later (preferably sooner).
Some good news on this front: management believes that the company was profitable both at the adjusted and the statutory levels in H2 and for the year as a whole.
“the Board now anticipates that profit for the year ended 31 March 2023 will slightly exceed its previous expectations”
It’s true that these were modest expectations to begin with; according to the StockReport, only £0.1m of net income was expected. But hopefully this is a good sign of things to come.
General meeting
As I noted at the top, a general meeting is happening on 21st April. It has been called by Stefan Barden who is a former CEO and Board Adviser to the company, and James Geddes who is a former CFO of the company.
They want the following changes:
The existing Chairman to retire.
One of the existing NEDs to retire.
Stefan Barden to become Executive Chairman.
The Founder and President John Kearon, who has been working in the US “to build the fame of our company and our products alongside the US sales team”, to step back to an NED role.
Private investor and commentator Maynard Paton has been in touch with Stefan Barden and helpfully published Barden’s thoughts on the changes needed at System1.
According to Barden, System1 is still “selling advertising creativity”, when it should be selling an automated platform whose results are “the best, the cheapest and the quickest”, and it should be selling these solutions equally to everyone, not just to the biggest brands.
Graham’s view
Personally, I must say that I like the sound of Barden’s approach. It fully focuses on an automated tech product that has general appeal and aims to sell this product generally to everyone in the advertising business. Under this approach, System1 would no longer provide and sell any particular method of ad creation to its clients.
But this is not to say that System1’s existing strategy is without merit. Focusing its sales efforts on the world’s biggest advertisers is a strategy that appears to be bearing fruit, even if profits are still very limited at this stage. But I do think Barden’s approach is more ambitious.
Which one will shareholders vote for? I don’t know.
As for System1 stock today, the price to sales multiple is 1x and the balance sheet also includes year-end net cash of nearly £6m. The cash burn has stopped for now. So this is by no means an expensive stock, relative to its potential.
I’d love to come up with a more definitive conclusion, but I have to remain stubbornly on the fence with this one. I’ve been following this company ever since the days when it was called Brainjuicer, and always been intrigued by it. Perhaps it is about to come good at last, but there are still so many unknowns.
Everyman Media (LON:EMAN)
Share price: 66p (+0.8%)
Market cap: £60m
This independent cinema company publishes results for FY December 2022.
It previously raised expectations for these results - covered by Paul here.
I don’t think the 2021 numbers are too relevant in the circumstances, and so I won’t bother reprinting them.
2022 numbers are as follows, which they describe as a “strong operational and financial performance”:
Admissions 3.4 million
Revenue £79m
Avg. ticket price £11.29, food and beverage spend £9.34.
Market share unchanged at 4.5%
Operating profit £0.4m.
Note the very low conversion of revenues to operating profit.
Operating profit in H1 was £0.8m, so there must have been an operating loss in H2.
Furthermore, in a post-IFRS 16 world, operating profit does not include the interest imputed on the company’s lease liabilities. These are significant - and they are a real cost, because they are an important component of the lease expense.
In addition to the significant amount of interest charged on lease liabilities, I also note the increase in the interest charged on bank debt:
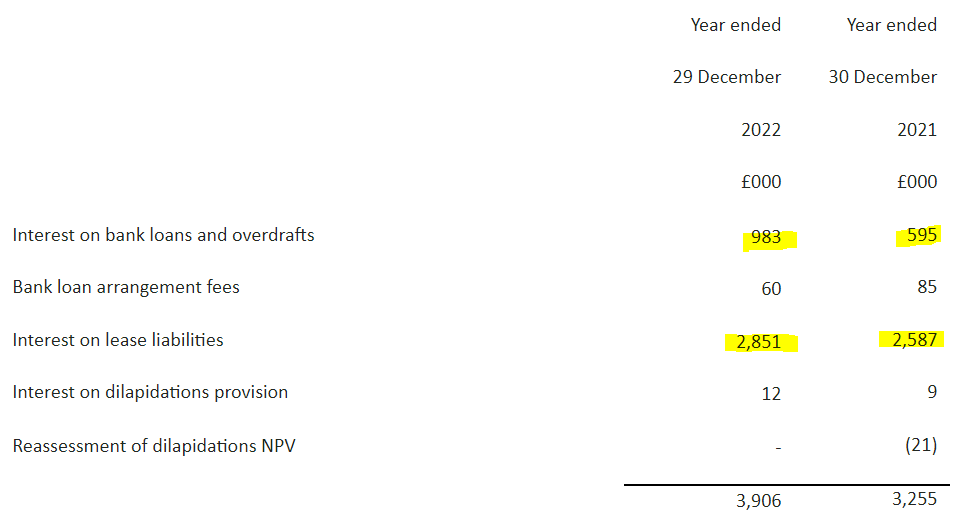
As a general reminder, it’s very important to check the pre-tax result, rather than the operating result, for companies with heavy leases. You could miss out on a crucial component of the bigger picture - in this case, nearly £3m of lease-related expenses!
Everyman’s pre-tax loss winds up at £3.5m for the year. It’s an improvement on the Covid-impacted 2021 result, but still rather underwhelming to me.
Outlook
Trading in the new financial year has been in line with expectations:
“Admissions in 2023 are expected to benefit from an increased number of wide releases, commitment to the theatrical window from distributors and new investment from streamers.”
“We anticipate continued financial improvement from higher admissions, strong management of costs and new site openings, despite the current difficult macroeconomic environment and its impact on consumer spends.”
“Management is confident of another year of strong operational and financial progress.”
It’s a bullish statement but for me, the tone doesn’t match the numbers I’ve just witnessed on the income statement and in the footnotes. Perhaps management are overly enthused by their adjusted EBITDA performance (£14.5m), which is a nonsense number?
Net debt finished the year at £18.5m.
Two new cinemas were opened, so the estate now stands at 38 venues with 130 screens.
Six new venues will open in the coming months and the company says it is “actively returning to an agenda of managed organic expansion”.
Graham’s view
The company apparently thinks that 2022’s performance was good enough to justify an active expansion strategy.
With that line of thinking, they remind me of the misguided retailer, selling items below cost, who said “we lose money on every trade, but we make it up on volume”.
Balance sheet net assets are £46m, including some intangible assets, so the balance sheet does not provide support at the current market cap.
More worryingly, I feel there is a mismatch between the quality of this latest financial performance and management’s perception of the performance.
If they think that a loss-making, capital-intensive company that is significantly indebted with bank loans and with leases should be expanding, then I have to worry about how this is ultimately going to wind up for shareholders. I don’t think that economies of scale are going to bail them out. So I have to give this stock the thumbs down now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
LON: SED I am posting with the benefit of some hindsight (August 2023). I think you are being a little harsh in your dismissal of this company. Seems to me they are achieving a massive amount in a short time in terms of new contracts and all the management work required to support that i.e. new production lines, staff recruitment, commercial contracts with partners etc., I am impressed by the management (Tony Gott in particular). It remains to be seen though how all the activity will actually convert into profits. Time will tell.
Sosandar (LON:SOS)
In relation to Sosander, Paul, you were asking in your excellent podcast about Global-e Online and whether any contributors could add comment. The company is one of my holdings, an Israel-founded facilitator of cross border e-commerce. They provide a local experience to consumers around the world, regardless of the abode of the selling company. Growing like a weed, with a massive runway, the easiest way to think about it is as an international Shopify. In fact Shopify is the biggest external shareholder in the business. The service is extremely good and the association with Sosander could greatly support the latter’s international expansion.
Hope that helps.
Georgia Capital (CGEO)
Bizarre little 5% drop today .
Bank of Georgia underpins it and that’s rock solid today and has been the past week so struggling to see the reason .(is it ex dividend ?)
Anyway took the opportunity to ditch a big chunk of the David Montgomery personal behefit company that is the gravy train that is National World and moved it into Georgia Capital in the 730-740 range which just looks the wrong price (slow burn doesn’t move quickly ).
Also moved some more into J Smart co which is a deep value play bit a long slow burn one .
Plus increased on Titon Holdings again following the news Rockwood have bought out the 10% holder putting them on 20%, 8 million market cap for this looks silly as that’s about the value of the freehold .(not in accounts at current market value)
Georgia Capital drop ? Anyone any ideas ?
Georgia Capital (LON:CGEO) drop ? Anyone any ideas ?
Perhaps the civil unrest in the country is having an impact?
https://www.theguardian.com/wo...
timarr
quite a lot of unrest in the UK and US too...................
Tongue in cheek aside - most other Georgian stocks went up today so not sure that's anything to do with it. Announced a buyback though - market seems to hate those at the moment.
doubt a primary to standard listing had any effect. Shareholder register not really sensitive to listing segment changes.
In particular, the proposed Standard Listing will mean that the Company will not be required to comply with the
super-equivalent provisions of the Listing Rules that apply to companies with
securities admitted to the Premium Listing segment. The Board considers that
certain of these super-equivalent provisions impose onerous obligations on the
Company that are affecting its ability to efficiently pursue its strategy.
In particular, the requirement pursuant to Listing Rule 10 to obtain prior
shareholder approval for significant transactions (acquisitions and
disposals), creates material impediments to the Company's pursuit of its goal
to monetise its investments. The delay and uncertainty associated with the
need for GCAP to obtain shareholder approval for significant transactions
discourages potential buyers and reduces their willingness to engage in the
sales process, including familiarizing themselves with the targeted portfolio
company and the Georgian economy, performing due diligence and the like.
During the sale of 80% equity stake of the water utility business, we observed
that international buyers were especially surprised to learn of a shareholder
approval requirement given the relatively modest size of the transactions in
absolute terms in relation to any number of larger transactions in the
international markets where no shareholder approval is required.
move from primary listing to standard one?!
Everyman Media (LON:EMAN)
Thanks Graham for your thoughts on Everyman Media (LON:EMAN)
I don't hold a position, but I do like to keep an eye on this one. I have a few additional thoughts:
---
If we exclude the £16m of expansionary capex (I am assuming this is all noted as "Assets Under Construction") then the group was actually cashflow positive in 2022. I calculate this as +c£3.2m for 2022.
It's not enough to fund the expansion, but certainly better than I was expecting.
---
Admissions/seat back in the old days of 2019 was 393/year i.e. every seat was sat in 393 times on average in the year - this is an estimate as new venues opened at various times during the year.
In H2 2022, this number was 314, so quite a drop and nowhere near back to previous highs.
The 2023 film slate looks quite good, commercially speaking (eg. Mission Impossible, yet another Fast movie, etc...) so I wouldn't be surprised if admissions crept up to their old levels. The expansion policy makes sense when I view the company and industry like this.
In addition to this:
There's a lot to like here and if the growth continues I personally think the business will rapidly approach an inflection point. It will be interesting to see how things progress in the coming 12-18 months.
A
I have avoided SOS and will continue to do so though I accept that they have a lively management, widening sales outlets and probably good products, though I don't approve of cheap, disposable textiles. At a market cap of £60mn a positive investor must be expecting £5mn net in the next five years at the very least and the share count has continued to climb dramatically. They may make it but it still seems pretty high risk to me, and when I did a simple comparison this morning - with Quiz, Boohoo and Asos - SOS didn't show up very well though they are (hopefully for holders) at a take-off stage.
Given Sosandar (LON:SOS) are expecting to do £3.6m net this coming year WDWombat then an additional £1.4m in profitability over 4 years is a pretty low bar. If that's all they do from here I'd say they've failed miserably but no signs of that so far.
With £10m+ net cash and profitable there should be zero need to raise funds. Given the macro environment and number of black swan events they've had to adjust to in a very short space of time I find the level of sales and revenue growth they have achieved is quite remarkable and they really should be given a great deal of credit for that. In a benign operating environment you'd expect them to do even better. It is super clear that the brand they have generated resonates extremely well with the demographic they have targeted and I think that is further borne out by the clamour of marketplace operators (Next, John Lewis, Very, Sainsbury's) falling over themselves to get access to the Sosander product.
International is next and rather than go a capital intensive route they have opted to do this via a 3rd party which appears very sensible. That opens up a huge market but allows management to focus on what they do best - manage the brand and range.
I have no issue with your wish to avoid, not every stock is for every investor, but I think you're rather late to the party with "high risk" view on it. I'd have accepted that a year or so back when they were on the cusp but the brand is no longer at the very early prospective stage. It has a strong balance sheet, is profitable and expanding with a strong industry reputation.
Brilliant reply, thank you David!
I would like to clarify one other point from WDWombat, who said -
though I don't approve of cheap, disposable textiles.
That's not at all accurate for Sosandar (LON:SOS) - it sounds like you're getting muddled up with Boohoo (LON:BOO) or Shein (who seem to be eating the lunch of the fast fashion UK companies).
Sosandar product is better compared with mid-market brands. It's fashionable, but definitely not wear once & throw away fast fashion.
I think what we're seeing with Sosandar, is the success of a powerful new brand. It's now moved into profit, and with international growth through partners, the sky's the limit for future growth, with no need to tap shareholders again, given it's profitable and has £10m cash in the bank.
Full disclosure: I've been saying for ages here that I want to buy back in, and finally took the plunge on Friday. Painful, as I had to top-slice other things that I didn't want to sell, to raise some cash. But such is life.
Regards, Paul.
Paul, glad you are having a rest.
We had a little chat on Crimson Tide (LON:TIDE) a few days ago.
A few back of the envelope sums.
Turnover growth has accelerated from 17% in year to Dec 2021 to 31% to year of 2022 following investment in marketing etc post the cash raise in April 2021.
FinnCap have t/o growing at 31%again to Dec2023 and then accelerating to 47% to Dec 24.
The gross margin is 84% and looking at Finncaps forecasts it seems that all other expenses were about £5.9m
As they have already built up the infrastructure for increased sales, Finncap have expenses staying at about £6m for the next two years. This leads to a pbt of £2.3m in 2004 and earnings of £1.7m. On a mkt cap of £20m that is a p/e of just under 12x.
But consider what MIGHT happen to Dec 2025. Assume a drop down in sales growth rate to 30%, same gross margin. and a 10% rise in other expenses.
That is t/o of £13.6m, gross of £11.6m, PBT of £5m. Tax at 25% gives earnings of £4.0m
Thus a p/e of £20m/£4.0m = 5x.
All very rough, with a lot of assumptions, but why would that company, given the growth rate, the margin structure etc, not be on a p/e of say 20x to 30x. After all, Eagle Eye with a lower growth rate is on a p/e of 5ox for 2023 and 40x for 2024.
A possibility then, that at the end of 2024, 20 months away, a prospective p/e of 20x gives a 4 bagger, 30x a 6 bagger.
All supposition of course, things have gotta go well. But doesn't seem a bad bet to me. I give it a GREEN!!!
Obvs, i hold.
A postscript. William Currie sold a chunk of Eagle Eye a couple of months ago and in Feb, appeared on the Crimson Tide register as a 5% holder.
To quote "As they have already built up the infrastructure for increased sales, Finncap have expenses staying at about £6m for the next two years". Never knew a company growing revenue rapidly to freeze their costs. Does not happen in reality. Uninspiring historic record of aCrimson Tide (LON:TIDE) will also put of share buyers.
While it is going too far to call Crimson Tide (LON:TIDE) performance inspiring it is worth noting that they have increased their sales revenue for every year since 2016 and, if they meet the projections will, by end of 2023 have more than doubled their sales in three years which is acceptable even on small numbers, especially useful on a climbing ARR. Given its size it will be a great while before institutions take an interest but seems to me squarely in the area where the private investor can help spread the word.
There is a wider problem. I hold both Crimson Tide (LON:TIDE) and Argentex (LON:AGFX) another of today’s discussions. In both cases the companies appear to be reinvesting their cash in investments in people and products such that net profits are held down. They both appear to be doing this only to the extent that they do not imperil their companies with excessive gains in debt and are positioned so that the normal upsets of business do not threaten their future. So I applaud them (and hold both) and believe that we should recognise the reasonable acceptance of risk for the promise of return is something we should recognise as desirable (and unavoidably more tricky for the smaller company). I hope that the managements are not dissuaded by short-sighted investor moans.
Cohort plc (LON:CHRT) no news out today, but there has been a nice recent run of contract extensions so ED research update published with fair value kept at 650p/share. Note is here https://www.equitydevelopment....
Portmeirion (LON:PMP) is up 8% today on no news. Has it been tipped somewhere?
Treatt (LON:TET)
Normally covered by the guys and with a positive TU this morning that addressed previous hedging deficiencies, showed a big drop in debt and more cost efficiencies from the new HQ, as well as resilience in their core beverages segment. I liked the update very much and it seems the market agrees. Expensive by standard SCVR metrics but very reasonably priced compared to competitors and a tasty morsel for one of the big 4 ingredients cartel.
If it’s a quiet day tomorrow, guys, I’m sure there are others who would appreciate you taking a look. Many thanks.
Hi BnB,
Thanks for the synopsis on Treatt (LON:TET) - yes I will come back to this one, ran out of time today unfortunately, but I agree it's a potentially interesting company that intrigues me.
Leave it with me, I'll try to surprise you in the morning!
Regards, Paul.
Thanks Paul
Don’t let it get in the way of a lovely rest on Gozo :-)
Slightly off topic but I wonder if anyone else has noted that whilst share buybacks appear to remain relatively popular the impact on the share price appears to actually be inverse to the intention.
Noticed that the likes of Tremor International (LON:TRMR) were continually falling whilst buy backs were occurring and yet have risen since they stopped. Similarly today Georgia Capital (LON:CGEO) announced a buy back of £10m and the share price fell a bit. There are a few other examples too.
Makes me wonder whether investors don't want buybacks which have the impact of increasing EPS for future years and would rather dividends? or maybe a level of arbitrage with short selling into strength absorbing any benefit anticipating a drop back once the buybacks finish?
irrespective - impact of buybacks seems almost negative which is completely the opposite of the intention of course.
I’m sure you’ve put the horse before the cart but could it just be a case that small cap BoDs don’t see the need to execute buybacks when shares are trending higher?
The point of buybacks is when that use of capital is better than investing it elsewhere. ie you create more shareholder value than reinvesting it in the business. So most BoD will sanction it if, in their view, there is a big disconnect between the fundamental value of the business and the share price.
However, that also creates a large demand for shares that should absorb any weak holder selling and thus push the price up or narrow the discount to NAV but this effect seems extraordinarily weak at the moment.
Thus my comment is that buybacks appear to be a waste of time in todays market. Better to retain the cash or pay actual dividends.
The point of buy backs is that reinvesting in the shares will give a greater return than reinvesting in the business. Whether this has been achieved or not can only be said many years in the future, when we can see if shares have been bought cheaply and what investing opportunities have been over the last few years.
Next (LON:NXT) has probably been the poster boy for doing buybacks. And it is difficult to argue that capital would have been better spent on the business (rolling out more UK stores, undertaking a risky international expansion, or being more aggressive on its online expansion).
The point of a share buy back is not (or probably more accurately should not) be to cause a short-term pop in the share price. Therefore this is probably not a good metric to judge whether the buy back announcement is a good idea.
I am no expert on Tremor International (LON:TRMR) nor Georgia Capital (LON:CGEO) - but I would note the market seems sceptical on Tremor and the buyback quantum announced by Georgia Cap seems somewhat token.
Agree with all of that but the point I am making is that historically share buybacks have been seen as generally good for the share price.
However, in a number of instances in the current market buybacks have actually resulted in continued share price slides BUT when stopped have resulted in quite big bumps up.
Tremor International (LON:TRMR) is an example of stopping. Up 15% since they stopped buying back shares
Georgia Capital (LON:CGEO) was an example of an announced share buyback today resulting in quite a large comparative fall (despite its main asset going up).
There are other examples - just these two highlight it.
Not sure David you might just be picking up two aberrations.
I held Tremor International (LON:TRMR) until 7/3/23 and after looking at the final results sold on the bell in complete exasperation/disgust - luckily I got out at just over £3/share - they then fell down to the £2 level. The end of the buyback program and the SP rise since I think has more to do with the fact that people think the SP can't go lower - I'm not sure.
I hold Georgia Capital (LON:CGEO) and was very surprised by the SP reaction today. It is classic logic for investment trusts, that when the discount to NAV becomes too much and you have spare funds then buybacks are a good idea to reduce the discount. I know Georgia Capital (LON:CGEO) is not exactly an investment trust but as of tonight £273m of its market value of £332m is supported by its shareholding in Bank of Georgia (LON:BGEO) and given that, overall, its now trading at a discount to 31/12/22 NAV of 63%, a buyback seems totally logical. There has never been any talk of a dividend as far as I'm aware.
So perhaps there's something else at work here . Did the market expect a bigger buyback, especially after the hotel disposals netting $28m.
Anyway I topped-up. Could be right, could be wrong (especially in this market).
I have held Tremor International (LON:TRMR) on and off since December 2017 (why you may ask). There share count now is more than double what it was then though they did buy back 6.5% of outstanding shares last year. But TBH it is all over the place. Management get huge share awards (which they normally almost always immediately sell but the company does tend to buy in the market to compensate for the shares issued to management.
Why do I still hold? Mainly because I still think it hugely under valued, cash is 70% of mkt cap but also the decline has made the holding so small that I basically see it as an option.
Regards
Michael
The price of Georgia is outrageously cheap. Net Asset Value is now 2103p so to buy them in at around 745p, they are getting them at close to a third NAV. They have a portfolio of defensive businesses like pharmacies, hospitals, medical insurance, schools and renewables as well as the 20.6% stake in quoted Bank of Georgia. I have bought 5,000 shares today taking my holding up to 86,000 shares. The buy backs will mop up loose sellers which should help to reduce the discount to NAV. Buying back shares at such a vast discount will increase the NAV even more for the remaining holders. Fair enough, Georgia is close to Russia but the risks are already built into Bank of Georgia who are on a prospective p/e of 3.5 and yield of nearly 10%.
why has georgia capital moved from a primary listing to a standard listing?
Argentex (LON:AGFX) – 9 months to 31 December 2022 versus 12 month 31 March 2022
Dividing by 9 and multiplying by 12, revenue and, to a much less extent, pro rata profits have increased.
This is partially on the back of additional expensive staff (staff costs 9 mth Dec22 £12.7m, 12mth Mar 22 £8.4m) selling more complex structured FX products (Revenue £3.8m Dec 22 versus £0.8m Mar22).
I always find it slightly worrying how smaller businesses (typical AGFX clients) prefer these complex FX products (compared to the largest FTSE treasurers who, rightly, wont give them the time of day). It can be profitable hunting ground for more sophisticated sales people but with adjusted operating profit margins falling from 31% (Mar 22) to 22% (Dec 22) perhaps the scale is not there yet.
I think it makes sense for AGFX to focus on financial services clients where banking service fees/margins can be higher than for corporates (though this is changing). Importantly, it gives exposure to the still rapidly growing fintech segment where large banks are often wary of offering services for regulatory and credit reasons and are forced to try to cherry pick the potential winners. This leaves opportunity for the likes of AGFX.
The Netherlands and Australia are hotbeds for fintechs so it makes sense to expand into those regions too. Not yet live in Australia so more set up costs to come in FY23.
I think clients will like the proposed new multi currency account solutions.
As you were going to ask, the key benefits of multi currency accounts to AGFX clients include eliminating the need for local currency bank accounts, process rationalisation and automation and better control of currency balances with resulting lower costs.
All that said I find this sector too much of a black box to invest in.
For AGFX (as for Equals (LON:EQLS) and Alpha International (LON:ALPH) I struggle to get comfortable with the offset of derivative assets, liabilities, client money, collateral held at trading counterparties and own cash held on the balance sheet. The risk being that assets and liabilities dont match off and after FX volatility there is a large write off. So, you need to have faith in the IT systems, treasury function and governance structure in what are small companies with limited resources.
Outside of this, I’m finding it difficult to get comfortable with what drove free cash flow of negative £7.4m Dec23 (Mar23: +£14.2m) and a fall in operating cash flow before working capital movements from Mar23: £13.6m to Dec23: £5.3m. Having read the explanatory disclosures and the notes to the accounts, I still don’t understand the working capital movements Dec22 -£7.4m (Mar23: £5.8m).
An added complexity is the £4.2m ‘LLP members renumeration’ and what this means for shareholder returns going forward.
Finally, as the size and complexity of deals get increases, I think it’s also worth keeping an eye on the credit evaluation provision movements Dec 22 £1.1m (Sept 22 £0.9m) a 22% increase in 3 months.
Much to learn at 1630 today at https://www.investormeetcompan...
Just an FYI but your quote "I always find it slightly worrying how smaller businesses (typical AGFX clients) prefer these complex FX products (compared to the largest FTSE treasurers who, rightly, wont give them the time of day)" is a bit misleading.
There really isn't anything complex in the FX products that Argentex (LON:AGFX) are doing for clients. It is just helping smaller businesses manage their FX exposure using simple instruments. It is in fact exactly what FTSE treasurers are doing for their larger businesses (and actually often a lot less complex).
Investors often assume the term structured products means complexity but in reality the term can range from something very simple to something horrendously complex. Argentex (LON:AGFX) are at the very simple end of this spectrum.
The other thing about collateral is that it is marked to market daily. ie the customer pays the difference each day. However, there is an initial margin which takes a stressed VaR of 2-5 days as well. This means that if a customer fails to pay any collateral the FX provider can close the position at zero loss even several days after default in stressed financial market conditions. As the product set they use is simple the calculation is equally simple, so whilst you do need good operational controls (reconciliations) to monitor it you don't need complex risk or IT systems.
Yesterday Belvoir (LON:BLV) published its annual report. According to Property Week, this indicates
"The board of estate agency group Belvoir awarded itself a 40% pay rise last year, despite a fall in annual profit.
According to the group’s annual report, its seven directors were paid a combined total of £1.2m in the year to the end of December, compared to £873,000 in 2021, even though the company posted a 2% drop in pre-tax profit to £9.1m."
It's not the worst compensation I've seen, but it always does stink a bit when company bosses give themselves healthy pay rises even though performance got worse and a lot of the benefit in 2021 (which might have influenced pay in 2022) in any case was also from wider economic tailwinds.
System 1 (SYS1)
Sounds like fun and games.
I know of Stefan Barden from his days as Wiggle CEO and he is very very good.
Sounds like he has a very strong plan and he is well worth backing based on the relatively limited interactions I had with him.
I held System 1 for a while then came to my senses when realised it was well outside my circle of competence and I dont really like marketing companies.
Much prefer companies that make nice things like Avingtrans and Somero that I can understand .
Anyway Barden is sharp.
planetx,
As an investor in SYS1, I'd love to pick your brains regards Stefan before I have to vote at the GM. I did a little digging at Companies House during the Wiggle/CRC period when he was the CEO but it's not completely conclusive. Turnover rose strongly (due to CRC being acquired) whilst profitability headed South.
I believe our mutual friend 'the boy Marsden' may have given you my number ;-) Would love to have a chat.
I also have long term holdings in a few other companies you appear to have been interested in including AVG & SOM & MSI.
Cheers
Patrick
System1 (LON:SYS1 is another of my sob stories, held since December 2019. A ray of sunshine a month later persuaded me to sell my SSE (LON:SSE) to buy more of this dog and have watched its volatility ever since. It'll be interesting to see how the vote goes.
De La Rue management needs a shake-up!
Spectra Systems market cap 83.72M
De La Rue a pitiful 69.18M
they need to focus a lot more on authentication. It can be a money stream if handled right - for governments authentication is the key to taxes.
i think the fall is overdone though
I wonder who will be buying in the background
https://uk.finance.yahoo.com/quote/DLAR.L/history?p=DLAR.L
Odey is my bet.
Also am I mistaken or currency notes in the UK will still need to be changed in the coming years now that the queen is deceased?
Https://www.euronews.com/2023/04/08/watch-the-uk-starts-production-of-new-king-charles-banknotes
Https://www.printweek.com/news/article/bank-of-england-reveals-king-charles-banknote-design
'The existing contract saw De La Rue take over the operation of the BoE’s Debden banknote facility in April 2015, and was set to expire in 2025. But it will continue to run until 2028 after the BoE opted to take up its option of a three-year extension that was part of the original deal.'
most of what Crystal Amber Asset Management complained about has resulted true.
They have about 10%.
Brandes also have about 10%.
ODEY ASSET MANAGEMENT LLP is probably adding in the background - notification on 24 March 2023 was for 6.89%
Other holders must be unhappy with the performance too.
If they join they can easily force DLAR to do big changes.
True. Crystal Amber (which is liquidating) is probably not in a position to buy more shares. It will rely on others that support its stance to buy more.
On Sosandar (LON:SOS) I think the update is a bit mixed but I lean towards positive.
Negative:
Positives:
I've decided to re-buy this morning because of the international growth prospects plus end of the quarter revenue being stronger than my low expectations.
Flowtech Fluidpower (LON:FLO) Trying to interpret this morning results. The curates egg it appears. A significant write off of goodwill. Thoughts anyone?
Jonno
I had a quick look as it’s at the bottom of my watch list .
Didn’t like it , not clear and that write off high .
As I don’t hold got bored trying to work it out and skipped off of my watch list into the I’m not interested list .
It’s basically a distributor albeit a good one but it’s going to get squeezed on margins with wage inflation and doesn’t seem to have any great game changing products or technology
Nice enough business but doesn’t really rock my boat or interest me (any more)
They never ever make any meaningful cash flow so are always stuck in a cycle of debt and interest payments. Dividends are never covered by cash flow, its the same story every time. They're just my thoughts of course !
If you search the discussion tab for Flowtech Fluidpower (LON:FLO) you'll see two interesting interviews with large holders (Richard Staveley of Rockwood and Stuart Widdowson of Odyssean) who discuss the rationale for their holding and explore the company's business model and upside bull arguments.
Worth a listen.
I am a (small, initial toe in the water etc.) holder.
Flowtech Fluidpower (LON:FLO)
Yes, "Trying to interpret" where trying is the right word. On ADVFN this morning 'edmundshaw' wrote:
"Bloody hell, that has to be some of the worst presented and most difficult to read (unaudited) results I have seen in 25 years of investing.
No proper formatting, long and winding sentences, lack of straightforward comparisons with earlier years, lack of clear and simple underlying results, and the notes are dreadful".
I replied "Agreed - the worst bit is that I can see the consensus forecast eps elsewhere but these are adjusted and the FLO report does not give adjusted. All I can find is the basic figure which is negative because of the massive £10m write-off of goodwill. We do get a detailed account of the changes of discount rate causing that!"
The elsewhere was here where adj. eps is forecast at 10.1p. All the report gives is (10.2)p.
In a separate RNS the CEO is leaving. He was previously CFO of this company. At least his replacement was not a CFO! (Mr C did not pick this one up so I should add 'He was thanked')
Argentex (LON:AGFX) anyone, can't work out if it's good or bad.
Revenue up 34%, but EPS appears slightly down, and can't work out what to make of the profit, ahead of increased expectations but it seems lower than last year.
Yours, confused of Gloucester
Nine month period
Argentex (LON:AGFX) results seem reasonably good to me. It would be good if this one was covered. There is a video on the results at 4.30pm today. Comparisons are difficult because you are comparing a 9m period with a 12m comparative period. As ever, management here are a tad more bullish than the actual results in terms of their commentary, but strong sales progress is definitely being made. £20m of the £41m revenues is paid out in staff costs and so management are definitely incentivised!
Argentex
Got a bit frothy for my liking recently with a lot of people talking about it and has a good rise .
It does seem to me to be nothing more than a currency broker taking a cut , competing against moneycorp etc
Run by FX dealers who are traders ducking and diving .
I’ve been dealing with the currency traders for 30 years and can’t understand how they are nothing more than money market middle men shaving off a few %.
I think they are doing well because the banks are so dismal , uninterested and basically still after all these years ripping off static people with non competitive currency rates .
This is the reason I’m happier in Equals than argentex , They are crossing the gap better and building long term value as offer much better than bank rates but with scale .
Having said that Moneycorp / Argentex are normally a tick below equals when you call for rates .
We generally call up all three to get a live rate and just use the lowest
You generally save circa 0.5% over a bank rate , on a 10 million a year soend that’s a 50k saving .
Now most companies might make 10% profit after costs so saving 50k is the equivalent of “not having to do” 500k turnover .
So anyone importing and purchasing currency should be serious about making sure these guys get wafer thin margins !
But thats financial broking for you plantex. It has existed for hundreds of years and will continue to exist and evolve, just as the FX broking market is doing now, through platform tech and product mix.
The margins the big banks used to take were just robbery but the margins now made by the new players like Argentex (LON:AGFX) , Equals (LON:EQLS) are sustainable and unlikely to go much lower at the corporate end. So whilst customers like you will shop around there is a staggering amount of untapped business around UK and Europe in the corporate space, particularly where businesses want to use multi-ccy accounts.
I like both businesses I have to say though and both look pretty cheap with high net cash piles (of own money - not clients) and trading not much above 10* free cashflow generation.
How long before we see them getting taken out by bigger fish though if we continue to persist with lowly valuations given the strong cash gen.?
Hello Bob,
Think because it's a 9 month reporting period, not 12. Hence lower numbers, but in actuality numbers have increased pro rata. If that makes sense?!
I don't know why Argentex (LON:AGFX) couldn't give us EPS figures for the full year (something to ask on the investormeet conference call later) but I make it out to probably be around 9p.
The most recent quarter revenue growth does look good given the very strong comparatives with last year - so I am surprised the market has sold off so far today.
Not knowing much about the sector, I am interested in understanding the level of risk of individual clients to Argentex - I'll probably try and ask it on the call if I can logon but would be interested in other readers' views here. (I hold).
They have presented the results really badly by comparing 9 month and 12 month periods and also not just putting it in a table (as opposed to confusing text). I am working this morning so haven't had a chance to do any proper analysis but on the face of it the revenues are up a lot and profits somewhat (6.8p for 3 quarters v 7p for 4 quarters looks good?). I think the second paragraph "Financial Highlights for the 12 month period ending 31 December 2022" is labelled incorrectly I think - I haven't checked properly but I think they are comparing to FY21 and it is mislabelled as FY22. Would be good to get a correction if true.
So I am optimistic on first reading but don't have time to validate any further so if anyone here can confirm this would appreciate it!
Argentex (LON:AGFX) looked absolutely fine to me. I care more about outlook than history and current quarter is 34% ahead at £12.7m of revenues.
Analysts are expecting EPS of 9p this coming year and circa 12p next. That puts it on a PER of just 13 and 10 respectively, but given the net "own" cash pile will be around 25p p/share this year it's really trading on cash adjusted PER of 10 & 8.
That looks too cheap for a growing, strongly cash generating business that is expanding in Europe and Australia. They have been investing for growth so as this investment tails off so the operating leverage kicks in.
Marks Electrical (LON:MRK) - Sales advance by 21.5% to £97.8m in FY2023 (new note and audio summary here: https://www.equitydevelopment....)
A better than-expected 21.5% increase in sales revenue to £97.8m, higher EBITDA margins and strong cash conversion were the key features of today’s Marks Electrical Group (MRK) FY2023 trading update. In addition, a positive start to April augurs well for FY2024, a year in which we expect to see further market share gains and expansion of the product and service offering.
The central investment case for the shares remains firmly in place, in our view. The company is well invested to meet demand growth in its business operationally as well as enjoying significant scope to generate this demand growth through increased brand awareness. Furthermore, market share is comparatively small at around 3% despite three consecutive years of exponential progress in sales.
With a trailing EV/sales ratio of only 0.8x we continue to argue that the shares appear undervalued and reiterate our fair value of 150p for the shares.
My morning smallcap tweet: De La Rue in Shit Street
Sosandar (LON:SOS) Narf Industries (LON:NARF) Invinity Energy Systems (LON:IES) Windar Photonics (LON:WPHO) Oxford Cannabinoid Technologies Holdings (LON:OCTP) De La Rue (LON:DLAR) Georgia Capital (LON:CGEO) Enteq Technologies (LON:NTQ) System1 (LON:SYS1) Marks Electrical (LON:MRK) Petrofac (LON:PFC) Cambridge Cognition Holdings (LON:COG) Smiths News (LON:SNWS), iomart (LON:IOM), Treatt (LON:TET)
◄Sosandar (SOS)► guides FY-Mar rev up 44%, in line. Pretax £1.6m+, a miss on f/c of £1.9m though you wouldn't know it from the headlines. [SP=24 Cap=60m]
◄Narf Industrie (NARF)► $2m invoice Financing Facility Agreement with the CEO! Interest 4.86%, fixed to FED rate. Formalises existing undocumented $1.3m non-interest bearing loans from CEO to the Operating Subsidiaries. Undocumented! [SP=0.93 Cap=16m]
◄Invinity Energy Systems (IES)► awarded £11m matched-funding gov't grant to deploy a 30 MWh vanadium flow battery. Conditional on executing a sales contract with a project partner. [SP=33 Cap=63m]
◄Windar Photonics (WPHO)► €0.87m order from an existing Chinese customer for delivery in 2023. [SP=22.15 Cap=15m]
◄Oxford Cannabinoid Technologies (OCTP)► regulatory license renewed. Programme update. [SP=1.1 Cap=11m]
◄De La Rue (DLAR)► warns FY-Mar adj op profit mid-single digit percentage below market expectations and in the low £20m range. "The demand for banknotes has been at the lowest levels for over 20 years, resulting in a low order book going into FY24. However there are encouraging signs that the market is recovering." Has requested a deferral of the next £18.75m of pension deficit repair contributions. [SP=50 Cap=98m]. I hold.
◄Georgia Capital (CGEO)► $10m share buyback over 3 months. [SP=770 Cap=347m]
◄Enteq Technologies (NTQ)► sells XXT MWD (measurement while drilling) intellectual property and the associated assets for c.$1.89m. Also selected customer account receivables and inventory have also been sold for up to c.$1.27m. Guides FY-Mar rev c.$6.1m with olny $1.9m n H2. Blames "move away from sales of lower margin products and a loss-making business to manage working capital more efficiently". Adj EBITDA loss $0.8m. [SP=11.5 Cap=8m]
◄System1 (SYS1)► guides FY rev £23.4m down 3%. Up 26% in Q4. Profit slightly above mgmt exp. [SP=163.9 Cap=21m]
◄Marks Electrical (MRK)► guides FY-Mar rev up 21.5%. Q4 up 20%. Beat mgmt exp on profit and cash conversion. Outlook: "strong exit in March and a positive start to April". [SP=83.5 Cap=88m]
◄Petrofac (PFC)► FY-Dec additional EBIT reduction of $140-160m due to "incremental project costs and a cautious view of the quantum and timing of recognition of certain revenue claims that would have partly offset those costs". Total EBIT loss $150-170m. Approximately 50% of these additional costs are expected to be paid over the remainder of 2023. "Agreement in principle with its lenders to extend borrowing facilities by 12 months." [SP=74.01 Cap=387m]
◄Cambridge Cognition (COG)► wins two 5 yr contracts worth £2.1m [SP=95.25 Cap=33m]
◄Smiths News (SNWS)► News UK contract renewed. Represents 19% of current newspaper and magazine revenues. [SP=48.7 Cap=119m]. I hold.
In line: IOM, TET
The update from Sosandar (LON:SOS) looks very positive. I’m looking forward to Paul’s review and the market reaction.
Think nbrown is a stronger business personally...
Long term hold share for me. This will either go great guns in UK and internationally or eventually be bought out. No too early I hope.
That was a well hidden profit warning.
They explicitly said it was below market expectations so not sure what was 'well hidden'?
I thought that you thought that the update was a bit mixed :)