Small Cap Value Report (Wed 13 Dec 2023) - SMRT, HVO, FAN, CHRT, SPR

Good morning from Paul & Graham!
Get ready for the renowned Stockopedia multibagger series of webinars - the next one is 11:00 today - details here. I think many of us have really been inspired by the insights from this research. And the next batch of 10-baggers will be somewhere buried in these Small Cap Value Reports, as multibaggers start off as small, and good value!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries -
Smartspace Software (LON:SMRT) - up 113% y’day to 71.5p (£21m) - Possible offer - Paul - PINK (takeover)
Shares more than doubled yesterday, when a potential bidder (rebuffed by the company) announced its approach to the market. SMRT now says it is consulting major shareholders. It looks a generous offer to me, it's difficult to imagine shareholders turning this down, but who knows!
hVIVO (LON:HVO) - 20p (pre-market) £136m - £16.8m RSV contract & Trading ahead of guidance - Paul - GREEN
Large contract win, and trading is ahead of expectations. 2 brokers update their numbers. Looks a very impressive growth company to me, and valuation still seems reasonable, so a continuing thumbs up!
Volution (LON:FAN) - up 5% to 417p (£825m) - AGM Trading Update - Graham - GREEN
A positive update from this designer and manufacturer of ventilation systems. Despite weakness in new builds, refurbishment demand remains strong. No change to revenue forecasts but EPS estimates get a small boost. Strong indications of a quality business.
Cohort (LON:CHRT) (Paul holds) - unch 532p (£222m) - Half Year Results - Paul - GREEN
Solid H1 results, with the usual H2 weighting to profit expected, hence trading in line with expectations. A very large multi-year order book gives nice visibility. Strong balance sheet with net cash. Not the most exciting of shares, but if you want a decent quality business at a reasonable price, Cohort looks worthy of consideration.
Springfield Properties (LON:SPR) - down 2% to 72.8p (£86m) - Trading Update - Graham - GREEN
Staying positive on this Scottish housebuilder after a confident, in-line trading update. Debt has risen but the company insists that land sales and normal seasonality will reduce this as planned by year-end (May 2024). Valuation is tempting at a 40% discount to tangible book.
Paul's Section:
Smartspace Software (LON:SMRT)
Up 113% y’day to 71.5p (£21m) - Possible offer - Paul - PINK (takeover)
An announcement was made to the market by Skedda Inc. yesterday, saying it had made a series of proposals to possibly acquire Smartspace, most recently at 82p per share, a large 144% premium, but not such a large premium if you zoom out the chart onto a longer timeframe.
SMRT management has not been supportive of this possible offer, but an 8.3% shareholder JO Hambro has been supportive.
Response to possible offer - out this morning from SMRT.
Says that it rejected a previous possible offer from Skedda Holdings Inc. (the market was not informed at the time), but is now consulting major shareholders about the 82p possible offer.
The Takeover Panel rules have kicked in.
Paul’s opinion - I’m probably not the best person to ask, as I never really saw much attraction to this share, with it being tiny and persistently loss-making. Hence I was amber on it in May 2023, when I looked at its last results, which did show strong ARR growth and reduced losses, but very small numbers (in particular revenue per client looked tiny).
Clearly there must be more to it than that, otherwise it wouldn’t have a bidder sniffing around trying to buy it!
Its track record as a listed company has been poor, but losses are now forecast to be largely eliminated, thanks to increasing revenues.
This situation once again brings up the question of when companies should inform the market about bid approaches. My view is that if a material premium is being offered by a credible potential buyer, then it should be required to be announced. That is not the case currently, so we’ve had a false market in SMRT shares, which were worth materially more than the stock market price, due to undisclosed price sensitive information being withheld by the company. Totally wrong.
Such a large premium is bound to appeal to many shareholders, so it will be interesting to see what level of support there is. Or people can sell immediately in the market (although for well under the 82p bid price).
Skedda is a trade buyer, being a workplace software company headquartered in Australia.
It will certainly be interesting to see how this situation pans out! I imagine many shareholders will be very happy to walk away with a 144% premium - it’s a sensible offer.
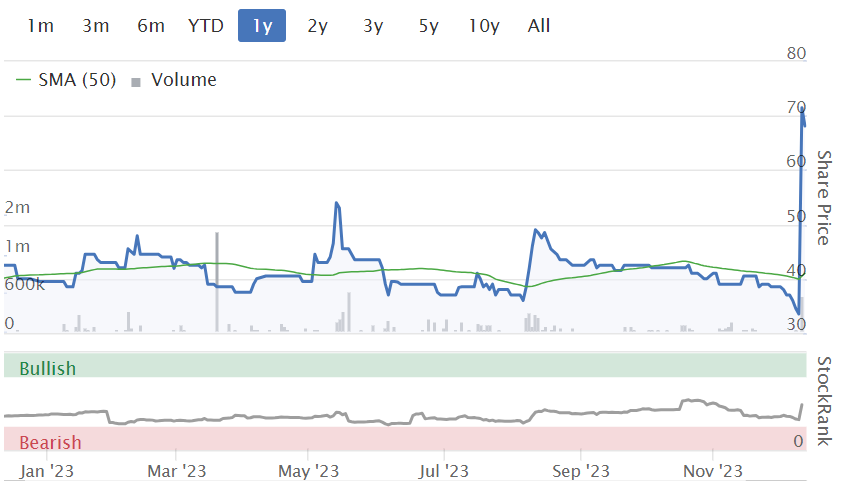
A generous offer of 82p in the short term -
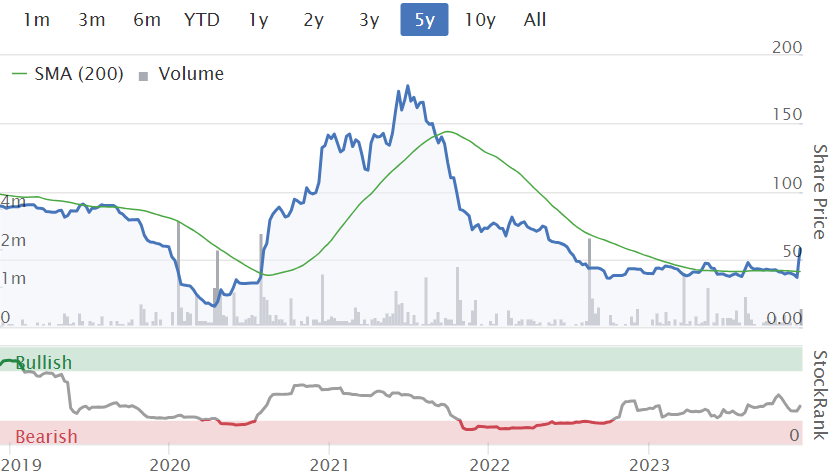
Less generous when you zoom out to 5-years -
hVIVO (LON:HVO)
20p (pre-market) £136m - £16.8m RSV contract & Trading ahead of guidance - Paul - GREEN
It’s useful when companies title the RNS with the key point(s), as above, it’s certainly attention grabbing.
Things really seem to be powering ahead at HVO - figures in recent years have shown highly impressive top line growth, and a move into profit, hence why we’ve been reporting positively on it this year (most recently green on 12 Sept).
hVIVO plc (AIM & Euronext: HVO), the world leader in testing infectious and respiratory disease products using human challenge clinical trials, announces that it has signed a £16.8m full-service contract with an existing top five global pharmaceutical client to test its respiratory syncytial virus ("RSV") antiviral drug candidate using the hVIVO RSV Human Challenge Study Model.
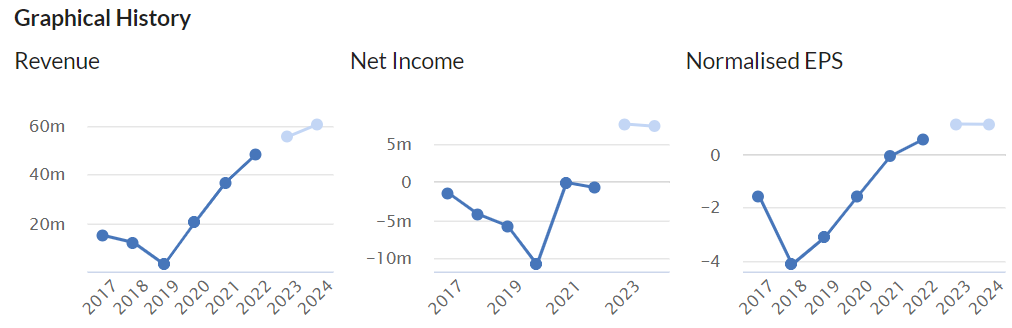
This is a big contract, in the context of £55-60m forecast revenues pa -
It says the majority of revenues will be booked in FY 12/2024, with some also in both 2023 and 2025.
Trading update - most of the announcement is rather technical, but this bit covers overall trading, pity they only mention EBITDA, as most of us prefer real profits, not EBITDA, but this is the fashion unfortunately -
The Company is pleased to report that trading has continued to be strong across the Group, with revenue slightly ahead of previous market expectations. The Group has continued to improve operational efficiencies which, coupled with the facilities funding that will benefit both FY23 and FY24, has resulted in EBITDA margins exceeding 20% for the year ending 31 December 2023. Consequently, the Group now expects EBITDA to be ahead of previous market expectations. With the addition of today's contract, the Company has clear revenue visibility into 2024. Further details will be shared as part of the Company's FY23 Trading Update in late January 2024.
Visibility is a good point - this is one of the things I like about HVO, its large forward order book. This also benefits cash, as contracts seem to have a large element of cash paid up-front, a very nice position to be in for HVO.
Broker forecasts - both Cavendish and Liberum post updates on Research Tree, thanks to all. Liberum has upped FY 12/2023 by 6% at EBITDA level, but +35% at EPS, from 1.0p to 1.3p. So maybe they’ve tweaked the model to include higher interest received on cash balances?
Next year’s forecast falling to 1.2p seems anomalous, given the growth trajectory, so I imagine HVO is probably set up to issue ahead of expectations updates throughout 2024.
Paul’s opinion - excellent news today, and this share is really gaining momentum, looking to be a very credible growth company in a large market. Valuation still looks reasonable too.
Hence I’m more than happy to remain at GREEN.
Cohort (LON:CHRT) (Paul holds)
Unch 532p (£222m) - Half Year Results - Paul - GREEN
Cohort plc, the independent technology group, today announces its half year results for the six months ended 31 October 2023.
To expand on that, Cohort is a collection of 6 companies, which operate largely independently of each other, mainly focused on the defence sector.
The financial highlights start off well, but the extra gross profit gradually disappears, consumed by c.£1m in extra finance charges and higher corporation tax -
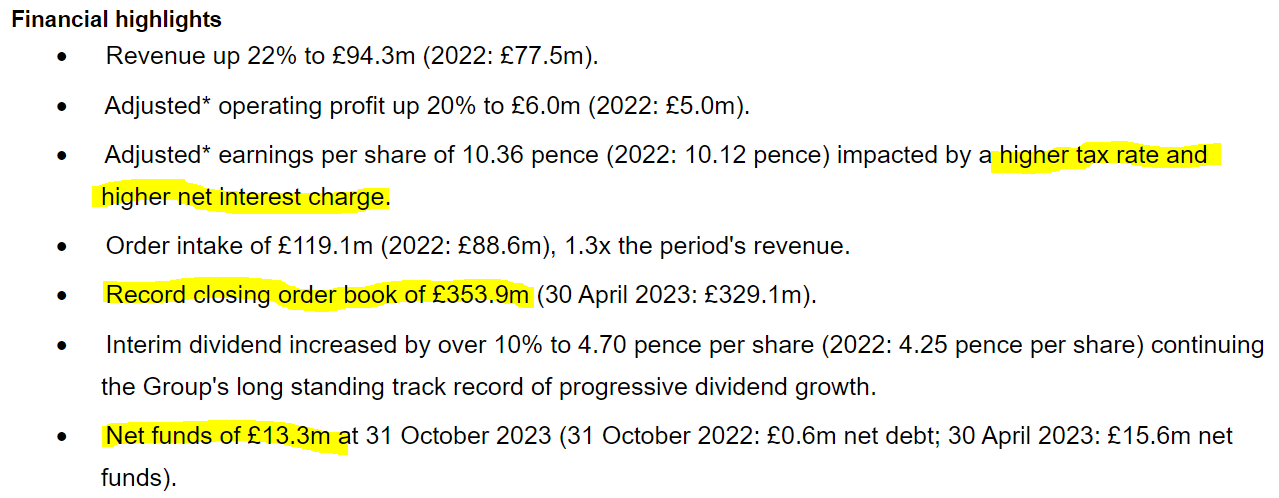
Note the very large multi-year order book, and a return to a healthy net cash position.
There was a heavy H2 bias to profits last year.
Balance sheet - NAV is £98m, including £54.5m intangibles (mostly goodwill), so NTAV is healthy at £43.5m.
Receivables strike me as excessive at £61m, which seems out of kilter with £94m H1 revenues. I would normally expect receivables (unpaid invoices to customers) to be less than half H1 revenues. So that’s a query point.
There’s a cash pile of £36.1m, in combination with £22.8m long-term bank loan. I think I queried why this is once before, but can’t remember the answer.
There’s also a £5.3m pension deficit.
Cashflow statement - cash generation is roughly used to fund capex (quite hefty at £2.7m in H1, similar to last year H1), dividends and share buybacks.
Outlook - reassuring I’d say -
The Group's order book at 31 October 2023 stood at £353.9m (30 April 2023: £329.1m), underpinning most of the second half of this financial year. In line with previous experience, we anticipate a stronger Group performance in the second half and thus remain on track to achieve our expectations for the full year.
The continued expansion of the Group's order book is a strong indicator that we are offering competitive products in a growing market. On-order revenue is now deliverable out to 2033. The pipeline of order opportunities for the remainder of the year also looks strong. Demand for our solutions and services continues to be driven by international tensions in the Asia-Pacific region and Europe. This backdrop is driving increased spending on defence and security in Europe, including the UK, other NATO countries and the Asia-Pacific region. Overall, we continue to see a positive outlook for organic growth in the years ahead.
Paul’s opinion - I continue to view Cohort as a decent group of quality businesses. Shares have had a good recovery of late, but still strike me as reasonably priced.
It’s been a reasonable safe haven in the last 2 years’ small caps bear market.
We have to disclose if we hold any share we write about, I am currently holding a small position here. I think it’s well-managed, and has a good long-term track record, and a positive outlook. So it’s another thumbs up from me.
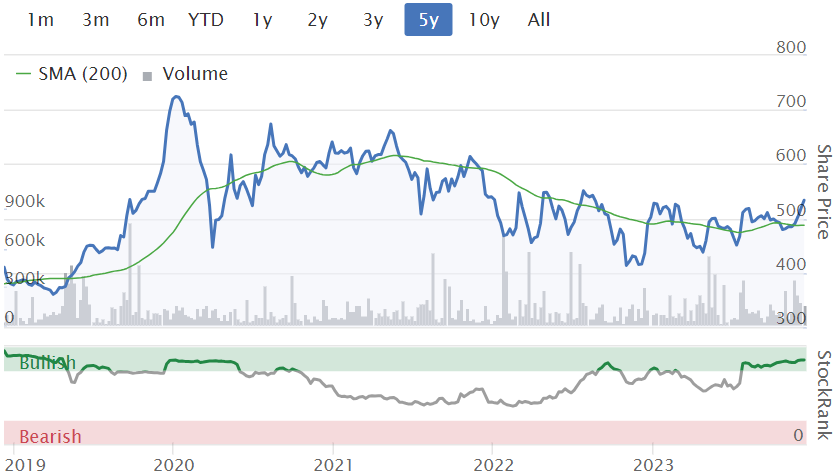
It looks as if the trend might be starting to turn upwards, perhaps? -
Graham’s Section:
Volution (LON:FAN)
- Share price: 417p (+5%)
- Market cap: £825m
Volution Group plc ("Volution" or "the Group" or "the Company", LSE: FAN), a leading international designer and manufacturer of energy efficient indoor air quality solutions, today announces an update on trading covering the four months which ended 30 November 2023.
This is an excellent update, that’s ahead of expectations.
The company’s year-end is in July, so the update covers the first four months of the new financial year.
Key points:
Revenues +8% year-on-year to £121m
The growth is primarily from acquisitions: 7.7% inorganic growth, combined with 2.9% like-for-like organic growth, minus 2.6% negative currency impact.
Recent acquisitions “are progressing well”.
Two-thirds of revenues are from the refurbishment of existing properties rather than new-builds, shielding Volution to some extent from a weak construction sector. UK residential is currently the company’s best-performing sector:
Despite the significant reduction in new build completions, this market benefits from regulatory drivers moving demand towards higher value energy efficient ventilation solutions.
Energy efficiency trends are also helping Volution in other markets such as Australia and the Netherlands.
Profitability is up, too:
Gross and operating profit margins have improved compared to FY23 due to strong pricing discipline, an ongoing focus on our operational excellence programme, including material value engineering initiatives, and the introduction of new products.
Outlook:
Whilst new build market conditions remain challenging, our refurbishment activities continue to benefit from strong regulatory drivers and consumer focus on eliminating the damaging health impacts of mould and condensation in buildings. Our strong start to the financial year, together with the tailwind from the three acquisitions completed in the calendar year, gives the Board confidence in delivering earnings ahead of the current range of market expectations for the financial year.
The existing range of earnings expectations was for EPS of 25.3p to 26.3p.
Analysts at Liberum are suggesting that there is no change to full-year revenue expectations, but that earnings upgrades are coming from margins. They boost their full-year EPS estimate to 26.5p.
Graham’s view
Paul and I have both been positive on this one - see my comments in July and Paul’s more recent comments in October.
The main weakness from my perspective is organic revenue growth, which appears to have reduced again from the c. 5% level achieved last year.
However, the company is making up for that with acquisitions that are performing well, and with improved margins, which seems the best possible outcome in struggling property and construction markets.
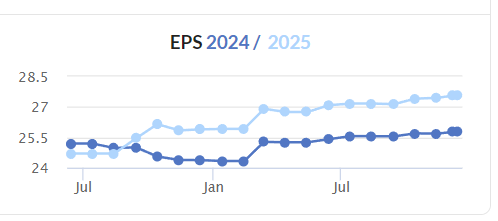
EPS forecasts out to FY 2025 suggest that growth will be limited in the short and medium term, and a case could be made that this has reached fair value at current levels:
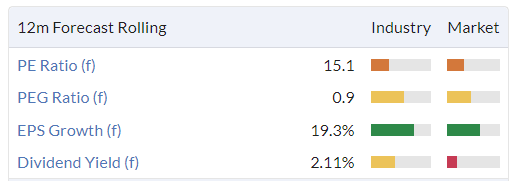
However, I will maintain my positive stance on this one. I continue to appreciate the company’s communication style (very clear). But more importantly, long-term momentum in favour of more advanced and effective ventilation products to reduce mould and condensation appears to be working in Volution’s favour. The company has been under-promising and over-delivering, as you can see from the EPS momentum chart:
Springfield Properties (LON:SPR)
- Share price: 72.8p (-2%)
- Market cap: £86m
This H1 update is in line with expectations, with some fresh information on the state of the housing market:
Springfield Properties plc (AIM: SPR), a leading housebuilder in Scotland focused on delivering private and affordable housing, provides the following update on trading for the six months ended 30 November 2023.
Demand in private housing is “stable but subdued”. Selling prices are stable but demand has been affected by “high interest rates, mortgage affordability and reduced homebuyer confidence”.
Affordable housing: the company has restarted signing affordable housing contracts - this was a key discussion point earlier in the year, when rising costs made these fixed-price contracts unprofitable. With affordable housing now back in play, we have a clear catalyst for performance to start to pick up again.
Build cost inflation is now running at around 4%, with “greater availability of materials and labour”. If inflation stays low, then the issue with affordable housing contracts and inflationary cost increases has solved itself for now - but builders will need to be extra careful in future when signing these deals. Springfield is only signing contracts with a 12-18 month delivery timeframe, which reduces the risk of getting caught out by inflation again.
Net debt has risen to £94m, but the company insists that it is on track to get this down to £55m by the end of the current financial year. It plans to do this by sales from its large land bank (6,500 plots and a further 3,255 acres), which it can achieve “without impacting the Group’s development pipeline”.
The recent rise in net debt is explained by £11m of defcon for acquisitions, land purchases, and “the usual working capital cycle” as work-in-progress builds in H1 for delivery in H2.
Last year, net debt finished H1 (Nov 2022) at £74m before falling to £68m by the end of the year (May 2023).
Outlook - in line with expectations for the current year. Beyond that, the outlook is optimistic:
…the Board is encouraged by the early indications of a return in homebuyer confidence, with inflation reducing and the Bank of England holding interest rates for two consecutive months. Build cost inflation continues to moderate and there is greater availability of materials and subcontractors. The interest that the Group is receiving in its land bank - and at attractive valuations - reflects the market preparing for an upturn in trading conditions.
In Scotland, three local authorities have declared “housing emergencies”, underlining the lack of supply.
Estimates: Equity Development have published a note suggesting EPS for the current year of 6.2p, rising to 8p next year.
Graham’s view: I’m going to stay positive on this one, as I did in July. My concerns over limited headroom - the company using a temporary overdraft - had previously kept me neutral on this share.
However, with the company outlining a clear plan to keep its borrowings under control, and with more certainty now around its performance in a higher interest rate environment, I’m happy to stay positive.
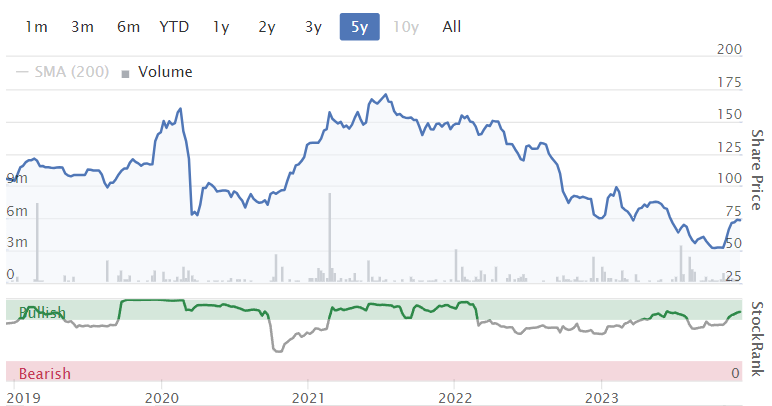
As previously mentioned, Springfield is trading a discount to tangible book value (c. £144m as of May 2023). One of the benefits of all this tangible value is the flexibility to sell assets to pay down debt, as required. My own calculations and those of the analysts suggest that price to tangible book value is around 0.6x, providing plenty of upside if the market is inclined to value this at book value at some point in the future. The shares previously traded at up to double their current level at the start of this interest rate tightening cycle:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
Cohort (LON:CHRT) *** Investor Presentation video recording now available (Half Year Results) - 13 December 2023 ***
?si=KmWpKGnp-hb6d_YSAndy Thomis (Chief Executive) and Simon Walther (Finance Director) of Cohort plc (AIM:CHRT) took investors through highlights of their interim results, and gave views on geopolitical tensions around the globe, as well as explaining why Cohort's order book is so large. The full video has been divided into chapters:
Is there anyone who still holds NB Global Monthly Income Fund (LON:NBMI) ?
Appreciate that the holding after the recent dividend and buy back is now underwater from purchase, but I had been reinvesting the buyback at the lower prices, and starting to look like a reasonable risk rate return for a close down fund, with 66p purchase against a 75p NAV.
Any thoughts by cleverer folks than me would be appreciated.
I hold, but now 1%, but happy to take a smaller return for what seems like a simple trade, or am I missing something?
Cheers
Tommy
We hold a tiny remnant of NB Global Monthly Income Fund (LON:NBMI) and plan to keep it until the imminent wind-up as that seems certain to yield higher returns with no charges.
Just a word to say thanks to Ed and Megan for their webinar earlier today.
One thing I learned is that you can see the major shareholders by clicking the Accounts: major shareholder. So it's a good place to look for heavy insider ownership. Yes, of course, the feature has been there for a long time, but it's something that I wasn't aware of until today.
I've had some good luck with a couple of contrarian purchases the last couple of years (Shell (LON:SHEL) has done really well, and my recent purchase of British Land (LON:BLND) is really motoring).
Ed mentioned "bowls" in terms of turnarounds. One idea that I did have is to look for companies on 52-week lows and then add them to a watch list until they reach 52-week highs. There's no good way to do this, though. So if the good folks at Stockopedia could be persuaded to add criteria to look for highs and lows, that would be a useful addition. There is a 52-week high screen on Stocko, but you do have to go through the candidates manually to find candidates that fit.
It would be nice to see the Fantasy Fund feature reintroduced from the old-style website, too.
The webinar has definitely influenced my way of approaching investing. I'm steering away from QVM and more towards things like good returns on capital and more growthy shares. So far, doing almost no trading and thinking more long term has improved my performance. At least it seems that way.
Another thing I'm doing is compiling a list of shares that I'm interested in for ISA top-up season. SCVRs are an important part of that.
So, a big "thank you" to everyone at Stockopedia for the services they provide.
You could probably do some screening rules around 52 week high and lows. Maybe some moving averages? So you want a stock that is rising from it's low but not reached it's 52 week high? Could work. It is a bit tricky screening for that but why stop when it hits 52week high? Some continue on upwards, see Rolls-Royce Holdings (LON:RR.) Warpaint London (LON:W7L) Associated British Foods (LON:ABF) Marks and Spencer (LON:MKS)
My logic is that you want a stock that has rebounded off its low (having reached its 52-w low) and then buy at the 52-w high. You want to buy into this momentum. This is a strategy for recovery and turnaround plays, not growth shares. For growth shares you ideally want to buy and hold indefinitely. It's a different dynamic.
I see what you mean. Can you not screen stocks just below the 52 week high, then check the mini charts on the screen?
I would be inclined to buy before the 52week high. That guru screen has performed poorly in the last 2 years, if the figures are correct: https://www.stockopedia.com/sc...
Although momentum has picked up since end of October.
"I would be inclined to buy before the 52week high. That guru screen has performed poorly in the last 2 years"
Yes, that's why I'd want to start with 52-w low. When it reaches the 52-w high you know that you're near the beginning of the recovery period. The theory is that momentum tends to reverse; say after a 3-year period. So the 52-w highs screen will have a lot of shares near the end of their momentum run, which is what you want to avoid.
The alternative is to look at all the charts on the 52-w high list on a regular basis, and see if anything matches something bowl-like that has just reached its 52-w high. I did this just now, and none of them had that kind of pattern. I think I did do it a couple of weeks ago and identified one that looked promising, but I don't remember the name of the company.
One would have to do a couple of sanity checks. Very illiquid shares aren't suitable for this exercise, not are those being subject to takeovers.
This is why it would be helpful to be able to screen for stocks near their lows and set alerts when they reach 52-w highs.
Not reached 52WH yet but maybe one to watch is On Beach group (LON:OTB), you could set an alert. I'm sure there are some others.
2 more: Clarkson (LON:CKN) and Spectris (LON:SXS).
Ultimate Products (LON:ULTP) and IG group (LON:IGG)
TP Icap (LON:TCAP) is only 6% below 52WH.
Yes, good charts. That's the kind of thing I had in mind.
Bloomsbury Publishing (LON:BMY) SSE (LON:SSE)
Silver Moon thanks for your post about todays Webinar on Multi Baggers. I registered late at 11am but I was not sent the link to my inbox.
Hopefully a recording will be issued in due course.
portugull, ask Oliver on the green chat button as I'm sure he'll send you a link to the recording when it comes out. I did pick up some fresh ideas thanks to Megan and Ed's enthusiasm, could have listened all day.
Anyone any views on the yield curve - the inversion is deepening again, which is not a good sign. This is due to 10-yr rates dropping off very rapidly and more so than 2-yr rates. By early in the New Year the yield curve inversion will be 18m old. Its still making me very nervous about markets in 2024, particularly with US markets so overvalued at c70% of the MSCI World Index.
Running some analysis on the last 16 central bank pivots: 6 caused a bear market crash averaging -39% (examples, Covid-19, GFC, Dot-com and early 70s) - all hard landings; and 10 pivots caused an average increase in share prices of +36% (examples 1980’s and 1990’s) - soft landings.
Market is betting on a soft landing, but are they correct? Could be a double-dip bear market and the market rally may be sucking people in ahead of the final unravelling.
No right or wrong answer at this stage - my analysis just underlines how very difficult it is to correctly time the market!
I'd really welcome some experienced or expert insight into gilt trading.
I hold some SPDR Bloomberg 15+ Year Gilt UCITS ETF Dist (LON:GLTL) because I expected gilt yields to fall and gilt prices to rise commensurately. I expected the effect to be greatest at the long duration end of the gilt market.
GLTL started rising strongly only in October this year, much later than I expected. It's still half the price that it was in mid 2020. It looks like an obvious buy if long gilt yields are expected to fall back much further. Does that seem right?
Hi FREng - its not really my specialism other than monitoring the yield inversion and 10-yr rates, as this impacts equity valuations. Personally, I just hold short-dated gilts for 5% tax free returns on "cash" (TN24 and TN25) in my Interactive Investor account. Longer term gilts may well be good value, but its not something I play around with particularly after some poor early experiences on index linked gilts a few years back. I would suggest maybe following Capital Gearing Trust (LON:CGT) as they are pretty competent in this area. They have regular investor presentations at CGAM and are worth watching. I hold shares in this investment trust as a defensive position.
ooft, bad one for Tandem (LON:TND) today
down 22%% as i type this
Tandem (LON:TND) - kudos to planetx - he has warned on this several times with the benefit of industry knowledge
I have bought some Eurocell (LON:ECEL) today.
Paul wrote on 8 Sep 2023:
“Recent comments from the Bank of England, that it sees inflation falling, and interest rates now being at or near the peak, suggests to me that buyers might be starting to nibble at cyclical companies like this again. When the bull market starts, it can surprise everyone at its speed, and often anticipates improved fundamentals - if we sit and wait for confirmation of an economic recovery, we’ll probably miss a good part of the next bull market. Hence I’m definitely warming to the idea of putting some money to work on shares like this, and Eurocell (LON:ECEL) (£100k Director buy there this week too), even though the figures look rather poor at the moment. They both have nice strong balance sheets, which means short term share price falls are not a concern.”
The last IC recommendation on Eurocell PLC shares was Hold at 155.00 on 01 Sep 2022.
A recent report of Surveyors has forecasted a gloomy assessment of UK housebuilding and the price of Polyvinyl Chloride (PVC) having been high are two factors that have impacted Eurocell in recent times. The company Half-Year report (5 Sep 20230 states
· Challenging market backdrop, with particularly severe decline in new build housing
· First half profits down as expected
· Further deterioration in market conditions since July Trading Update means full year performance now anticipated to be below our previous expectations
· Early and decisive action on cost taken in response to lower volumes and to position the business well for when markets recover
· Efficient inventory management driving good cash flow performance, maintaining strong balance sheet and liquidity
In the report, Darren Waters, Chief Executive of Eurocell plc said:,
"Looking further ahead, the UK construction market continues to have attractive medium and long-term growth prospects, driven by the structural deficit in new build housing and an ageing housing stock that requires increased repair and maintenance. Overall, I believe the actions we are now taking leave the business well positioned to benefit from a recovery in our markets which will, over the medium-term, drive sustainable growth in shareholder value."
Planning to hold this for the medium to longer term, and hopefully will do better than my foray into Frontier Developments (LON:FDEV) recently.
Consternation from some Stocko members this morning re Megan and Ed's webinar on Multi-bagging due to their being at work! Work-From -Homers shared the enjoyment with retirees, still, you can't please them all. Good Energy (LON:GOOD) was covered, don't know if it was through a question I asked, but there is so much more to consider than during in a few moments of inspection. There's a lot happening behind the scenes in GOOD which I think could slow its progress, so the next question is, should I ratchet? ( That is, having identified a candidate as a multibagger, sell high and buy it low?
So long as your crystal ball is in full working order, go for it!!
If I wanted to get some sort of short/inverse exposure to the "Magnificent 7" (or part of them)...
I do follow the logic that a rotation out of these into the other 493 is possible next year, but I'd be very wary. Prospects and valuations for these are not as high as those with a UK lens believe. Shorting MSFT is madness to my mind, and all three of AMZN META and GOOG look undervalued. Apple and Tesla - yes I get it, but these are the most cyclical of the consumer facing names so might benefit from a pro-cyclical rebound soon after the short case plays out. And Nvidia really isn't expensive next to many semiconductor stocks. It's on 24x CY2024 earnings for a company growing revenues at 100% per year in the hottest part of the market! Is that really an excessive valuation?
That said - it could happen. They are stalling a little right now as investors sell them to fund the next level of AI "winners" and growth stocks in general. But can you time the trade profitably? Aren't you better off spotting the best placed growth stocks and owning them in a coming year when revenue and earnings growth could be challenging for the market overall? That's what a soft landing means and is the view being taken by the market since October, and the Mag 7 are already falling behind the charge today. Perhaps they just tread water.
Mainly been treading water since July... no strong view.... but I do concur that a better use of time is working out future positive trends rather than trying to predict the end of stuff... leave that to the 2 & 20 crew.
I think a rotation is already underway as the next tier of growth names is surging forwards, funded by Mag7, which are taking a breather. If Mag 7 were primed for shorting, I'd expect to see more volatility in them already. Strong stocks consolidate by remaining rangebound. And these are clearly powerful names.
Off topic but think amongst this knowledgeable base, the answer is there somewhere!
If I wanted to get some sort of short/inverse exposure to the "Magnificent 7" (or part of them)...
But want it via an ETF for ease...
Also not able to buy the inverse ETFs for individual shares (eg MSFT, AAPL, etc). Need to buy an ETF that is a basket of names.....
Any recommendations?
Obviously could just get a vanilla S&P500 short like Xtrackers S&P 500 Inverse Daily Swap UCITS ETF 1C (LON:XSPS) , which is anyways highly leveraged to the 7 already. But wanted to see if there were any options for something more targeted.... inverse ETF wise...
Direxion Shares Etf (PCQ:TECS) is 3x short tech so likely does the job.... subject to obvious drawback re leverage ETF.... could be fun for start of the year
The 3x levered ETFs are designed to be held for very short periods only - almost certainly likely to lose value if held for for more than a few months (even if prices are flat or down!). You're probably better shorting them via spread bets in something like IG. Another option is put options which act like insurance contracts - they expire worthless if the share pieces don't fall by a specified amount (thus limiting downside) but can do very well if the share prices fall a lot.
Not exactly what you are looking for in terms of shorting the "magnificent 7", but have you considered an S&P 500 Equal Weight ETF? For example, iShares S&P 500 Equal Weight UCITS ETF USD A (LON:EWSP)
I'd be interested to hear the bear case against the shares - they do seem to have very high valuations, but I think a lot of people have been caught out trying to short them...
Indeed, betting against the Mag7 over the past year or two has been a widowmaker.
I don't have one strong, simple case. That would be too simple. Rather, I can see a series of different scenarios, some individual to a company, some broadly amongst several of the 7. And in my mind, there are enough of these scenarios and enough probabilities amongst them, that on balance I think the weighted index of the 7 is likely to go down rather than up.
I know I'm being very vague here! But its midnight and I don't have the mental strength to write out descriptions of each of the scenarios now.
Personally I wouldn't use a short ETF unless short term, but even then a simple spread bet is a better option imo.
You could short FANG+ index, I'm sure IG have this. Alternatively find an ETF with the highest weighting to mag7 and short this.
Sosandar (LON:SOS) interim results yesterday and a trading update presentation with Q&A video & podcast.
Smartspace Software (LON:SMRT) I hold. At 82p I would realise a loss a bit under 50% so the premium is not that attractive to me. Now the operation is fully a software house and the software is being (gradually consolidated) I can see the ARR steaming ahead. Or rather there will be no major operational barrier to it steaming ahead. They have proved themselves able to operate internationally, including Asian language countries - in other words they have the whole world as their market. It feels like its reaching a tipping point where business growth will accelerate.
That, together with it approaching profitability, and possibly already there with cash flow, means it is not an expensive one to hold and wait. An operation like that can grow rapidly, produce great ROCE. It should not be too hard to grow the operation from today's market cap of £20M.
Most likely outcome? IMO the ongoing realisations in the investment community will force the institutional holders to lean on the board to accept the offer. Possibly another bidder will push the price to around 100p. For me it is a disappointment because I recon it has a very good opportunity to become a multi-bagger over the next few years. I think Skedda have the same view.
Yes Paul is incorrect that this is a “generous” offer for Smartspace Software (LON:SMRT) as it is missing the point that all the groundwork has been done, profitability achieved. businesses like this command much higher premiums.
Being taken out for a song at the point the business hits profitability and has significant upside means current investors have shouldered all the risk and get none of the upside. That’s not generous it is predatory. Understandable from the acquirers perspective and certainly a sign of markets behaving inefficiently but not generous!
I don’t have much but will vote against at this price.
Yes so will I
B&M European Value Retail SA (LON:BME) - Definitely not a smallcap but what has happened here today just shows how things are stacked against the small punter. Major shareholder wants to sell down their holding - 'places' circa 3% at a 3% discount - then as a result - shares plummet by 5.6% - Amazed they got away with this..but thats what we are up against.
I don’t see how this discriminates against the small shareholder , who could have sold their shares in the market without a discount
Not who has got away with what to be honest?
hi bohenie
B&M European Value Retail SA (LON:BME)
I'm interested to know where you found the information about the large share sale at 3% discount?
Snazzy
hi Snazzy - just lookup the NEWS section under the stocko report - and responding to Jesseowens - Yes anyone can indeed sell in the Market but the SP is now down more than 6% as a direct result of the Institutional placing......
hVIVO (LON:HVO) Mo doing the rounds this morning
https://www.proactiveinvestors...
https://www.voxmarkets.co.uk/a...
Just for fun, a brief report on my Christmas Shopping trip yesterday! I don't generally like trudging round the shops, so I thought I'd keep a mental note of how the shops looked like they were doing while the wife & daughters dragged me round Bluewater.
The large Superdry (LON:SDRY) looked empty, but the same could be said for most of the other clothing stores.
PROCOOK (LON:PROC) looked quiet.
Works co uk (LON:WRKS) actually looked quite busy, as did Hotel Chocolat (LON:HOTC) , one of the few stores that actually had queues at the tills.
But the busiest shops of all were John Lewis, which appeared way busier than Marks and Spencer (LON:MKS) , and Card Factory (LON:CARD) which had by far the longest queues of the day.
Of course, it's just a small snapshot on one particular day. Could all be different today...
thanks af20001 - interesting - in a similar vein my 18 year old daughter says Revolution Bars (LON:RBG) in Cambridge was rammed at the weekend - "on all floors". I hold.
All city center bars will be though.
I don't hold Revolution Bars (LON:RBG) but noted an announcement today that the CFO is standing down at end of month.
Sorry, can't seem to delete my message, too many Revolutions, it was the CFO of Revolution Beauty (LON:REVB) who is leaving.
Triple Point Energy Transition (LON:TENT)
TENT investment trust is throwing the towel in over its persistent 40% discount. They have announced an orderly disposal of the assets and return of shareholders funds. The shares jumped 13% today, but they are still on a 30% discount.
After Arix Bioscience (LON:ARIX) comments re realising Assets at NAV I guess this is whyTriple Point Energy Transition (LON:TENT) is still at a large discount. Hipgnosis Songs Fund (LON:SONG) just sold a small song portfolio for 14% below NAV. No wonder many funds in the Trust sector has wide discounts.
This is all very frustrating, in that I want these ITs to re-rate, but not dissolve. The NAVs of the energy ITs like Triple Point Energy Transition (LON:TENT) went down a bit, because of interest rate increases increasing their discount rates. What do you think will happen in a year's time, when interest rates start to descend and discount rates with them. Won't this send the NAVs of the like of Triple Point Energy Transition (LON:TENT) , Gore Street Energy Storage Fund (LON:GSF) and GCP Infrastructure Investments (LON:GCP) back up? I like ITs for some stable income to live off, and I like spreading the risk, but I already have VPC Specialty Lending Investments (LON:VSL) in run-off. Victory Park Capital, the managers, will have seen their little UK-listed adventure as a complete waste of time.
Triple Point Energy Transition (LON:TENT)
I have a suspicion that all hydro generators are currently being undervalued by a DCF method (the usual method of valuing renewable energy generators). The reason I say this is that as more and more wind and solar are added to the grid, generators that can produce when the wind and sun are not blowing/shinning become more valuable. Hydro can be viewed as a cheap form of energy storage, ready to generate at a premium when required. I would not be surprised if TENT's hydro assets raise more than NAV.
I know that quite a few readers here follow Bioventix (LON:BVXP) and wondered if anybody has any idea what could be behind the sudden tear that it's gone on this week after a very lengthy period of trading within a pretty tight range? Has it been tipped somewhere or are there takeover rumours around?
Blimey - Been a holder for a few years - was getting worried about bumps earlier this year but had not noticed price movement of the last few days - so many shares now seem to be yo-yoing up and down. thanks for the mention
From what I've heard, Investors Chronicle tipped it recently.
Bioventix (LON:BVXP)
I saw your post about the sp rise before I went out this morning and returned thinking you had no replies but I see there were. bohenie and Mark Carter - it would be helpful if you could follow the request to mention which share you are talking about otherwise those who read following one of the three options that are not threaded do not know what you are talking about.
Was it a tip? - unlikely as it has been a steady climb over a week and tips tend to be more concentrated. https://www.investorschronicle... suggests that the last comment there was the day after the 30/10 results.
There are a number of possibilities including, but not limited to:
Small cap Santa rally - every day there seems to be a "Why has abc gone up x%" here and that, coupled with poor liquidity is usually the answer.
K A-L's Buffettology fund has been unloading from 19% before 5/4/23 to 12.8% on 15/11. I do not know why - maybe a rebalancing of the portfolio - at the end of November it was still their 5th largest holding. That will have had kept the sp down and if they have stopped now...
Another institution buying in (in the cessation of Buffettology selling any more) would move the sp.
Information from the company. This is somewhat confined to RNS results and if this year is the same as last there will be no trading statement between the prelims (30/11) and the interims at the end of March. However did someone attending the AGM pick up something? This discussion, posted here before, shows that is possible:
I have one more theory but need time to do more research. I will start that at some stage on a separate post - things get lost on the SCVR after the day.
Just reading the Warpaint London (LON:W7L) annual report and researching their different brands. I find it very confusing that Warpaint for Men is not one of theirs. Maybe at some point they should buy this private company - must be a common source of confusion.
hVIVO (LON:HVO)
I’d say quite a muted reaction to a strong update. This is a global leader in its field working with a lot of blue chip companies with high barriers to entry (moat), a large pile of net cash and high future year visibility. It can even get its customers to fund building its facilities it has that strong a position.
Its offering significantly improves the economics for Pharma/biotech which is why it is in demand and it is effectively the only operator of its type in the world.
Bizarre that the market doesn’t give it a better premium - it still trades at a discount to CRO valuations!
hVIVO (LON:HVO)
I’d say quite a muted reaction to a strong update
Perhaps the moderate valuation and reaction reflect the bear market in life science names that has prevailed throughout‘23 and is forecast to continue until H2 24 in a note issued by BAML yesterday. Who knows how well connected the average HVO investor is to proprietary research, but the caution around the sector is evident in valuations across the board. There is very little discount in the HVO price for its smaller scale and uneven trading history. Against that, it has a better balance sheet than big beast IQVIA! Looks good but I wouldn’t say cheap.
I wavered on this one at £15 and decided I needed the cash more for something else. Fortunately I can’t remember what as I’d probably be kicking myself.
Yeah - but think if you strip net cash out it’s sub 14* and CROs generally trade in the 20s
This is not a life science company it is a CRO (clinical research). The two trade valuations differently
This is not a life science company it is a CRO (clinical research). The two trade valuations differently
I know. That's why I compared it to IQVIA the biggest CRO of them all (I think). But both sectors are sensitive to the same fluctuations in biotech activity.
Springfield Properties (LON:SPR) - "Increasing confidence, debt reduction on track" - new note & audio summary here: https://www.equitydevelopment....
Springfield’s half year trading update (six months to Nov ’23) confirms an in-line performance for H1 and reiterates full year expectations. After a challenging period for the sector, it is a reassuring update, pointing to subdued but stable conditions in Private housing, increasing activity within Affordable housing and clear progress with the Board’s debt reduction strategy.
Recent indicators suggest that the market may be stabilising (notably mortgage approvals ticking up in October as interest rates appear to have peaked) giving us confidence to introduce FY25 forecasts within this note.
Springfield’s shares have recovered somewhat over recent weeks, alongside sector peers, but still trade on just 9x P/E and 0.5x P/Book for FY25. With increasing visibility of profit recovery and cash generation, we increase our ED Fair Value to 130p (from 110p) based on a sector average Price/ Book multiple of 1.0x.
hVIVO (LON:HVO) Pleasing comments from Paul above (I hold and hoping for multi-bagger status here in the long term)
With regards to Paul's comments (and general view on this forum and elsewhere) regarding EBITDA "pity they only mention EBITDA, as most of us prefer real profits, not EBITDA, but this is the fashion unfortunately" perhaps we should start a campaign of raising this matter with companies at every chance we get e.g. Investor Meet Company etc.
hVIVO (LON:HVO) given the level of net cash the company has and the large interest that should be building ebitda probably underestimates their earnings. The measure actually translates quite well to profits so not a particular problem I. This instance.
I am a fan (and holder) but not expecting a multi bagger from here Peter. I have a 35-40p target for them and suspect that will be a sale to another CRO in the next 2 years (or maybe a Nasdaq float as mgmt seem quite keen on that).
Hi davidjhill, big fan of your posts. Sorry, yes, I wasn't clear. Multi-bagger from my entry point after taking a punt here a couple of years ago (more luck than judgement but sometimes it works out) 35-40p would be OK and yes I'd would not be surprised at a buy out here or Nasdaq listing. All on the cards.
Let’s hope so Peter :)
I think this is very undervalued. Generally I want stocks that can go up 50% in 1-2 years and I think this is one. I can’t quite fathom why it doesn’t trade at 20* plus cash or about 30p currently but I know the directors take the same view and are working on that. We probably just need a slightly more conducive market but let’s see.
The bond market volatility fell 8% to 118 yesterday....still high but less worrying. The ten year yield did not budge. Equity volatility measured by Vix also fell....and at 12, suggests equity managers are really rather relaxed. And why not, equities have rallied and indices finding themselves in positive ground for the year. The Ruffer Investment (LON:RICA) update this morning is unusually sanguine. There are so many different inflation rates being watched it's possible to form any view you want ...if you are a talking head on TV that is. They seem to want to argue that the numbers were not really weak and the fed will remain tough.
The non seasonally adjusted all in CPI will most likely fall below target next year.... I "think" this is why the bond market is improving, despite the fiscal position. Just looking at the spread between the 10 year yield and the base rate suggests plenty of room to cut now. So the market expectation of a 100bp cut doesn't look out of kilter. In Europe Bonds also trade below base rates.
So it seems we should expect rate cuts now. The bond market is far from suggesting outright recession however, although yields curves are inverted, this could unwind rather quickly. I can't see that much changing on the back of tonights Fed meeting....famous last words!
My own positioning remains the same... a little firepower to deploy...as markets continue to strengthen I will look to increase this (ie raise cash) .... but overall Im happy to be invested. Tomorrow its Capita (LON:CPI) update which I hope isn't going to slap me in the face.. I have a starter position for a turnaround, improving margins, improve rating...fingers crossed....happy hunting everyone.
Need to wait for the Actual figures, not the Gestimate.
Which stock are you referring to?
I'm not referring to a company, I'm referring to BenHazz's comment on the economic figures out today. They always get revised at a later date, when they have all the data.
Cohort (LON:CHRT) - just a reminder post Half Year results this morning that we are hosting a webinar this afternoon at 4.15pm with the CEO & CFO - the link to register is here for anyone interested: https://www.equitydevelopment....
Complex bid for Impellam (LON:IPEL) announced at a roughly two thirds premium. Part cash, part loan notes with a 3 yr term and bearing a coupon of 17%. Will be interesting to see how the market unravels this into a SP this morning
Deleted - duplicate
My morning smallcap tweet: Tandem fails to find brakes for downward cycle
Impellam (LON:IPEL) Smartspace Software (LON:SMRT) Tandem (LON:TND) Oxford BioMedica (LON:OXB) Westminster (LON:WSG) hVIVO (LON:HVO) PROCOOK (LON:PROC), NWF (LON:NWF), Cohort (LON:CHRT)
◄Impellam (IPEL)► agreement reached on offer of 557.2p cash + 392.8 loan note + divs. Total 1084.4p, a 67% premium. [SP=659 Cap=294m]
◄Smartspace Software (SMRT)► is considering and consulting on the 82p mooted offer. [SP=71.5 Cap=21m]
◄Tandem (TND)► warns FY-Dec rev only £22-23m and pretax loss £0.9-1.3m, dependent on expected FOB orders being shipped in December. Blames weak toy and FOB sales. Bicycle sales, including electric bikes, remain significantly ahead YoY. Brave face: "While the Board is disappointed by the recent adverse change in current trading and the outlook for the remainder of FY2023, the Group retains a strong balance sheet, a well-managed current stock position, and we expect to see a positive impact on pension fund valuations as at 31 Dec". [SP=131.21 Cap=7m]
◄Oxford Biomedica (OXB)► cuts LTIP sizes and previous bonus in one case after 20% vote against remuneration at AGM. [SP=191.4 Cap=185m]
◄Westminster (WSG)► extends FY by 6 month to June to "better align the Group's reporting periods with the financial dynamics of the long-term contracts signed blah blah blah". Also has now received US$500k in settlement of its dispute with Scanport. [SP=1.27 Cap=4m]
◄hVIVO (HVO)► wins £16.8m full-service respiratory syncytial virus. contract. Majority will be booked in 2024. Guides FY23 rev slightly ahead of market expectations and EBITDA ahead due to improved operational efficiencies. [SP=20 Cap=136m]
◄ProCook (PROC)► H1-Oct rev down 4%, U/L pretax -1.7m (-£2.8m). Recent 8 weeks rev up 1.5%. "Having solved the majority of the new website teething issues by the beginning of the Black Friday period, we delivered a robust Black Friday campaign with revenue growth of 3.5% YoY." [SP=27.65 Cap=29m]
In line: NWF, CHRT
Cohort (LON:CHRT) - "Strong H1 24 results backed by a record order book" - link to our new report & audio summary: https://www.equitydevelopment....
For the six months to 31 October 2023 Cohort reported revenue of £94.3m, +22%YoY, EBIT (adj.) of £6.0m, +20%YoY and (adj.) EPS of 10.36p (adj. dil., 10.33p). The closing order book further increased to £353.9m (FY23, £329.1m). With £90m of orders deliverable in H2 the Group reports that 95% of market consensus revenue outlook is covered, whilst the order book has longevity to 2033.
The net cash position was £13.3m compared to £15.6m at year-end FY23 and H1 23 net debt of £0.6m boosted by operating cashflow of £10.3m (H1 23: £7.7m). The Group raised the Interim dividend by 10% to 4.70p/share, maintaining the track record of progressive returns.
Cohort noted revenue growth in each division underpinned by UK MOD demand. Revenue in the Communications & Intelligence (C&I) division (EID, MASS and MCL) increased 32.3%YoY to £43.9m (46.3% of total). Revenue in the Sensors & Effectors (S&E) division (Chess Dynamics, ELAC Sonar and SEA) grew 14.7%YoY to £51.0m (53.7% of total).
Overall, these results confirm the all-important upward trend in orders and contract awards which in turn underpin revenue growth and visibility from operations which span the major theatres of defence operations. These interim results continue the pattern of order-led demand for Cohort’s expertise and services, linking the bigger picture issues that focus on defence to Group prospects.
Our Fair Value remains at 650p/share.
So, unsurprisingly, the UK economy is showing it isn't quite as resilient as our friends across the pond. Hopefully Andrew Bailey has the strength of character to make cuts irrespective of what Jerome Powell is doing. If we stick to the current plan of simply copying the US strategy it could leave us in a real mess. We have to cut before the US in my opinion, fail to do so could leave us in a very deep hole.
For 18 months the government have blathered about inflation being the result of “Putin’s war”. Now oil is cheap again, yet energy costs remain ruinously expensive and the BOE are weirdly hawkish. When the economy is weak you support it, and that means big cuts. Bailey is totally out of his depth. If he does change his mind there are a lot of UK yield trusts (GCP Infrastructure Investments (LON:GCP) Sequoia Economic Infrastructure Income Fund (LON:SEQI) Real Estate Credit Investments (LON:RECI) etc) that should prosper.
They seem to be looking at out of date data all the time, as Paul said on one of his podcasts, as everything gets more expensive we cut back, look for discounts, shop Aldi, shop around petrol prices etc.
I went out for a Christmas party on Friday, nearly had a heart attack when I opened my banking app the next day, shots were a bad idea!
I think a small cut on interest rates would really make a strong statement that UK is open for business
Couldn't agree less BenHazz. Not a supporter of Bailey but it makes no sense for UK to cut interest rates before US when they will reach target inflation rates much sooner than we will.
Going earlier we will only weaken value of the pound and import more inflation. Would be counterproductive IMO.
Personally I expect all countries to hold til early summer at least. Historically I believe the US reduce rates no sooner than 11 months after last rise. UK unlikely to go sooner as inflation will take some time yet to drop below 3%. Can you really see our interest rates coming down before that happens?
If we want to do something to fire up our economy I'd suggest it needs to be through Fiscal Policy and that is unlikely to happen til after the next Election. Now where's your money on when that will be? The outcome is easier to predict!
Chapel Down (OFEX:CDGP)
Interesting development at Chapel Down Wines. Ex CEO and Founder Frazer Thompson now holds 4.34% . The purchase was on 8th December but it’s not clear if he held any before this.. This would seem an interesting purchase from someone who must know the business inside out. He was replaced by current CEO Andrew Carter.
I've been catching up on subscriber comments in the last few days.
Is there something in the water producing so many comments removed due to perceived violations of Content guidelines/Moderation rules? Somehow feel I've missed out on what was said.
You didn't miss anything! Better to have a clear-out and start again fresh,
Good, ahead of expectations, outlooks from hVIVO (LON:HVO) and Volution (LON:FAN, as we’ve become accustomed to throughout 2023, without the latter’s SP seeing much recognition.
Thankfully for every Eneraqua Technologies (LON:ETP) there is a hVIVO (LON:HVO)
I think the trick is learning to tell the difference between good and bad management.
There is a video with Eneraqua Technologies (LON:ETP) fairly recently, on here. Worth watching if you are considering investing. The disguised profit warning was not a good move.
Good update from Volution (LON:FAN) and always good to read "Full year outlook ahead of expectations". As someone who has installed a PIV unit, I cannot express how great they are at dealing with condensation, not a single droplet of water to be seen all year round,