Small Cap Value Report (Wed 13 July 2022) - ECEL, WINK

Good morning! It's just Paul today, Graham's busy.
I'm running a bit late, sorry about that, the first section should be up by 10am.
Agenda -
Paul's Section:
Eurocell (LON:ECEL) - a surprisingly upbeat, in line with expectations update from this seller of building products. It looks a nice value share, with sound finances, a low PER, and lovely 6% dividend yield. Worth considering as a long-term investment, depending on your macro view of course.
M Winkworth (LON:WINK) - a micro cap estate agents. It's not clear why its shares are listed. Too small to interest me, and not good value either. Although H1 performance seems good, and is in line with expectations. No sign of a housing market downturn yet.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Eurocell (LON:ECEL)
175p (up 2% at 09:30)
Market cap £196m
Eurocell plc, the market leading, vertically integrated UK manufacturer, recycler and distributor of innovative window, door and roofline PVC products, provides the following update for the six months ended 30 June 2022.
Company’s summary -
Good First Half and Trading in Line with Expectations
A decent update today, the key bit says -
… we continue to trade in line with expectations.
Given that forecasts look quite ambitious, and have been going up, I’m pleasantly surprised that the company continues to trade well.

.
Other points in today’s update -
Revenues up 13% vs H1 LY, and up an impressive 40% vs pre-pandemic.
Inflation -
We continue to take effective action to offset input cost inflation, with a dynamic approach to selling price increases and surcharges. Price therefore remains a key driver of sales growth, but we believe resin costs have now plateaued.
Gaining market share, and extending product ranges.
Operating efficiencies are improving.
Net bank debt has gone up £4m in H1, to £15m - that's fine, as it's less than 1 year's profit, so quite modest debt, and there's a big overall surplus in working capital, so using a bit of debt is OK.
Higher inflation has increased working capital substantially (hence net debt rising).
Valuation - as you can see, the forward PER is modest, and there’s a cracking dividend yield, also good asset backing, with a healthy Price:Tangible Book of 2.19 (the lower, the better) -

.
Balance sheet - NTAV last reported at 12/2021 was £87m. The balance sheet looks robust, so I don’t have any concerns about dilution or solvency risk.
A strong balance sheet also means it can afford to keep paying big dividends, which are about twice covered by earnings.
My opinion - this looks really good to me - a steadily profitable company, as you can see from the graphs below (with the expected pandemic blip).

The valuation looks attractive, because I suppose markets are anticipating a downturn in business, although there’s no sign of that downturn so far.
I think investors need to be reminded that we’re not just buying this year’s earnings. We tend to fixate on PERs, but actually we’re buying all the future earnings, which tend to recover from recessions.
Therefore, I feel that being able to buy a well-financed, low PER share, with a 6% dividend yield, twice covered, look attractive on a long-term basis.
Obviously it’s anybody’s guess what happens shorter term, so I’ve no idea what the short term share price is likely to do.
This is one to add to my list of possible buys.

.
There’s a good StockRank too -

.
M Winkworth (LON:WINK)
183p (flat today)
Market cap £23m
Micro cap franchised estate agents.
Today’s H1 update sounds reassuring, with a good performance in H1 vs pre-pandemic. Last year’s comparative was exceptional, due to buyers rushing to meet the stamp duty deadline, so it's down vs that exceptional period.
Lettings income is doing well - worth remembering that even when the property market slows, estate agents with a lettings division, tend to continue doing well, with rents rising.
Overall performance seems decent, and it’s good to see specific profit guidance provided -
While the UK economic outlook and confidence in the housing market remain in question, the Directors are pleased with the Company's performance in H1 2022 and expect that full year pre-tax profits will be in line with the market forecast of £2.1m, marking a substantial increase on the outcome for 2019.
My opinion - a market cap of £23m seems punchy for a business that’s only making £2m pre-tax profits. Stockopedia has the forward PER as 13.6, which doesn’t appeal to me, I would want it at about half that price to start to get interested, in current tough markets.
Why pick something this tiny? If I wanted exposure to estate agents, I’d prefer something larger & hence more liquid.
My sector pick would be Belvoir (LON:BLV) which has impressed with a strong track record of growth, and looks reasonably priced at the moment on a PER of about 12, for a very defensive business, that should benefit from higher inflation, as rents rise. So I cannot understand why Winkworth is on a higher rating? Maybe it's the generous 6.3% dividend yield, although note that is only just covered by earnings.
Winkworth shares have been a safe haven in the current storm -
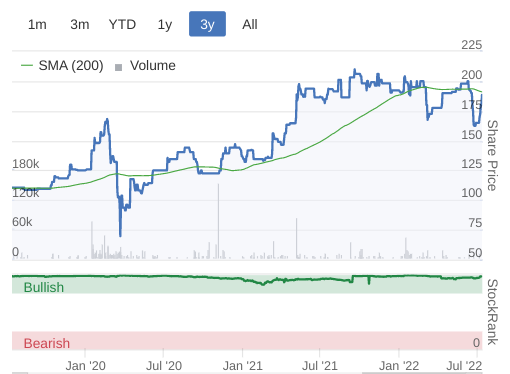
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Volex (LON:VLX) crossed 50D MA recently, PEG=0.6, £ weakness against $ should also help fcst numbers. valuation looks cheap to me.
Volex (LON:VLX) - support at 250p since 02/2022. 300p upside but with 150p a risk - I like round numbers (prove me wrong?).
Underwater but holding as the mercurial fundamentals still hold out long.
But patience has a price :)
Hi Paul, agree LON:WINK is small but its a dividend king - and is prone to sharing excess profits as special dividends. (6.4p in the last year). I've held it for some time and have nearly tripled my money by reinvesting. It also has an excellent stocko score.
The issue with M Winkworth (LON:WINK) is the spread is very wide, around 11% and that when there is no bad news. It is a problem investing in uk small caps.
M Winkworth (LON:WINK) ownership heavily in the Agace family (c50% in total) and the dividends not inconsequential as an income stream for them therefore. They don't trade them so we start with half the stock 'in play' effectively £11m of the market cap only for the rest of the world.
This outfit are more sales and London orientated than Belvoir (LON:BLV) and £TPFG. I know Paul favours Belvoir (LON:BLV) but I've always thought Property Franchise (LON:TPFG) was the best play in this sector and the acquisition of Hunters last year reinforced their leading franchise position. Will be interested to see the updates from both over the coming weeks. They usually report fairly close together.
Belvoir (LON:BLV) have dropped from 320p last August to 211p now. Property Franchise (LON:TPFG) from 365p in April to 272p today. Both look good value at current prices but market sentiment not supportive. With rental inflation running at 8% nationally, I think this was in their last commentaries, I'll be watching for that number in the half year updates.
A pal currently renting a property out recently checked the market and apparently could increase his rental by 20%, according to local agents and tenants expectations. He's doing the decent thing though as he wants them to be long term residents.
Let's see.
I too have held this share for over 5 years and it pays a good quarterly dividend and the odd special dividend. It seems very reliable and will be staying in my sipp for the long term.
Getbusy (LON:GETB) -> 29% YoY rev growth at interim with fy22 guidance lifted by at least 8.5% (estimate about 1.25% USD +ve impact in half). Strategy is to invest excess op cash for growth (both client acq and R&D). Price down 25% this year and 50% from peak. 1.5x rev for niche saas highly developed product to target and retain its target customer base (accountants, insolvency, specialist finance) making defence against more generic solutions robust at c.£245 pa user cost. Doubled revenue in 5 years and targeting the same going forward.
Mr Mkt’s wisdom is acute…
I don't own J D Wetherspoon (LON:JDW) but whatever comes this will be a winner. I'm a sometimes customer and struck by how busy they are (with very diverse customer often across age, ethnicity and often families eating). As cost of living bites they will remain an attractive destination...and spending time in a warm pub with friends is likely to be an attractive simple entertainment. Debt from covid is a pain but interest costs are well managed.
I hope it keeps falling (sorry) as a superb opp will appear
Have to concur, re LON:JDW, I believe it is very defensive and in my experinece offers excellent value and adapts to the demographic of its surroundings. I was mulling it over only yesterday - the problem is there are so many great opportunities out there.
Agree J D Wetherspoon (LON:JDW) is a great business, the food is also excellent and great value!
J D Wetherspoon (LON:JDW)
I believe it is very defensive
In theory that makes sense but reality at present is that they expect to lose £30 mill this year and have chunky debt (they have been buying back freeholds) - so its not so defensive short term if they needs to go back cap in hand to the market "again". I am in for the long haul though as like "greggs" they have a nice simple busines model that should work well in "normal" times
Fair comment on debt and like you I had drawn the Gags parallel. What they do not need is another lockdown (-which I can not see happening*) *Says the person that said even Putin wasn't stupid enough to invade the Ukraine!
J D Wetherspoon (LON:JDW) has some of the greatest pubs in the UK, irreplaceable, conservation area etc, a long hold.
But real ale aficionados CAMRA are niche.
Plenty of hipster lager brews with fruit etc have gained the traction maybe with Treatt (LON:TET) flavourings etc or their American big brother and other moat destroyers.
In my day new entrants were 'wine bars' - but accept with our cultural changes going on the old pub is like an old castle - a part of history. Discuss.
Hello Paul. Im a bit surprised given your deep interest in the sector, that you havent even mentioned Loungers (LON:LGRS) yet, never mind an intention to cover it.
It really seems to be going against the grain yet has been dragged down by the sector, Their detailed comments on how they got through the 2008 situation, how they were positioned then with a value for money offering and how that took them through in a positive way versus the rest of the sector, I found very interesting.
Good performance on orders on the app too.
I'm suspicious of the sector going forward but believe that this one may touch my fancy and at a reasonable price. The market hasnt taken it out of my reach yet either. Equally surprised at the low Stocko rating. What am I missing? Lots probably.
Please add it to your list if possible.
According to the Mail Boohoo (LON:BOO) is going to start charging for returns. This will be fascinating to watch for the retail sector as a whole. It might boost margins and/or cause a significant drop in customers.
Looking at the Boohoo (LON:BOO) website it looks like this has been implemented immediately and the cost will just be subtracted from the refund (so no upfront cost) which might limit the downside risk of putting off customers - at least initially "Please note a returns charge of £1.99 per parcel will be deducted from your refund amount. Returns are FREE for premier customers.."
https://www.dailymail.co.uk/ne...
That’s a good decision. I hear of many people who order 2 of the same thing at different sizes and send one back.
Who will now go elsewhere to order two sizes and send one back. IMO Boohoo (LON:BOO) products aren't special, and their customer base are poor and count the pennies.
Think about this; their customer base are willing to buy Shein, where delivery takes far longer. Just to save a few pounds here and there. That's the type of customer they are dealing with.
Getbusy (LON:GETB) ( I hold)
Getbusy appear to have put out a good set of numbers today and a second decent upgrade to 2022 expectations ( 17m up to 18.4m).
I haven't had a chance to go through them yet. They appear to be reporting certain numbers in a different way. Still looks very cheap for such a high recurring high margin business. Whilst they continue to invest for growth, it means they remain unprofitable.
They are on Investor Meets Company at 1pm. I'd be very appreciative if you had a look Paul or Graham. Many thanks.
Vianet (LON:VNET) (I hold) AGM Statement
MCap £20m SP 72p - up a couple this morning but down quite a lot more all the same.
As its an AGM statement its light on numbers but at first glance it seems to be positive. I'll try to be brief
FY to end of March so its effectively a Q1 update. Gross margin maintained whilst revenue growth continues and recurring revenues stable at 85%
On second sight - at least its not a profit warning. And even the obligatory warning on the cost of semiconductors and energy are muted and balanced by the maintained gross margins. Though the unstated corollarary is that gross margin improvement is likely being held back by these costs - particularly as they choose to grow their installations balancing off current cost increases against future recurring revenue.
Vianet has a long history of sustained growth being around the next corner so scepticism is sensible. It's in transition from being an installer of electronic modules to a SaaS based provider of data insight, management and payment services via its cloud-based portal. The heavy impact of lockdowns across its customer base have complicated the transition - but there are good reasons to believe that the products Vianet has developed over many years and launched during the pandemic will be increasingly valued by operators of hospitality estates and unattended retail (vending) estates as trading conditions seems to becoming more volatile and less stable over time. With opportunities in future unattended retail (EV charging) and remote data monitoring growing.
The update is reassuring that revenue growth continues - it needs to - and as always the company is excited about its prospects. But its a very different company and products from the old Vianet. One of those rare beasts where a significant technology growth opportunity exists effectively for little or no premium on top of an existing profitable business. Of course the growth may prove to be more mundane than expected. That would not be unusal for Vianet. I think there are reasons to be cheerful - and wary in equal measure.
Like most of us - I am watching and waiting in expectation of lower share prices to come so won't be topping up today even though I'd like to,
cheers
Mark
Thanks Mark, your review of Vianet (LON:VNET) has saved me a job!
It strikes me as a perpetual disappointer. The cash cow Brulines business seems to be in slow decline, and the growth stuff (vending machines-related) doesn't really grow much.
All in all, very dull. But it has been a generous dividend payer in the past.
I can't see the point in it being listed. Last time I met the CEO & prickly CFO (who seemed to have an attitude problem not at all appropriate for a micro cap!), I wasn't at all impressed. I think the CEO has been replaced now?
VNET listed almost 16 years ago, and the shares have roughly halved in that time. Adjust for inflation, that would be a lot worse. Although it has paid decent divis along the way, so it would be interesting to add those up, and see what the overall shareholder return has been.
It would take something significant, and genuine (not more jam tomorrow) to make we want to own this share, when there are so many better companies out there at attractively low prices right now.
Regards, Paul.
The new non exec appointment is interesting. Perhaps Vianet (LON:VNET) is looking for an exit route.
Zoo Digital (LON:ZOO) Full Year 2022 presentation given by management yesterday, (results published last week). They delivered very strong results and outlook. Video & podcast.
Saying that they're making significant progress towards the medium term $100m rev goal. A big beneficiary of the digitalised distribution of TV and films.
Separately, here is Part 1&2 of presentation by members of Listed Private Capital. Largely Private Equity funds who outline their fund but also give us a flavour of the temperature in Private Equity. Valuations have dropped but not as much as the public markets. I wonder if this will mean that PE starts to bid for public companies.
LPeC: Exploring listed private capital - resilience and opportunity.
Part 1 of 2: NB Private Equity, Columbia Threadneedle Investments and Gimv. Video & podcast.
Part 2 of 2: Oakley Capital Investments (LON:OCI) CVC Credit Partners, CapMan. Video & podcast.
Finally, 3 webinars over the next 10 days:
DSW Capital (LON:DSW) tomorrow 14 July, 1pm. Register here.
DSW IPOd in December, they are an IFA advising on corporate finance and due diligence to tax and corporate recovery. They are bsed in Manchester, Leeds, London and Aberdeen. This is the opportunity to learn more about this newcomer, and the broader macro picture.
Tpximpact Holdings (LON:TPX) on Tuesday 19th July, 12 noon. Register here.
TPX (formerly The Panoply) had a storming year in 2021. In March 2022, they said revenue was at the top end of market expectations (£78.8m), which is 54% up on 2021, and in FY23 they'll hit £100m revenue. The share price has sold off 38% over the last 6 months, in line with the tech sell off. We will learn more next Tuesday.
Creightons (LON:CRL) on Wednesday 20 July, 11am. Register here.
Full Year 2022 results yesterday disappointed, with EPS down 32%. Granted they've done well to make up the £14m of sanitiser sales with revenue only -0.7%. They are normally generous with their time on the webinar and answer all questions. I'm interested to hear how they are managing inflation and more on progress with Emma Hardie and Brodie and Stone.
Note, the registration links take you to the PIWORLD events page. Scroll down to the webinar you are looking for.
I'm looking forward to catching up on the Creightons (LON:CRL) webinar Tamzin (sadly I am never free to watch them live). It would be interesting to know whether their energy prices are hedged at all as it doesn't sound like it from the most recent update which makes me worry they are very vulnerable to further expected energy prices rises in the autumn.
Strong udpate from Gresham House (LON:GHE) which continues to see solid inflows despite the market turmoil. A few fund managers have been featured here recently such as Liontrust Asset Management (LON:LIO) although feel Gresham are much better positioned than most given their focus on sustainable, alternative assets (forestry, renewable energy, etc) - not only are these areas seeing strong demand, but they are also less correlated to wider market movements. Clients are also a lot stickier, so less risk of outflows.
It won't take much more of a decline for TP Icap (LON:TCAP) to fall within the £700m market cap limit for the SCVR! Anyone fancy a 10% yield?
H1 interims due 10 August
I've heard a few commentators mention the huge unlocked value in TP Icap (LON:TCAP) and this is on my list to have a closer look at. Looks a complicated beast so will need to wait until I have a bit of time. Would be interested if anyone has any thoughts on this one.
Hi Michael C,
Your mention of a 10% yield made me have a quick look at the StockReport for TP Icap (LON:TCAP)
It looks very interesting. I see profits dropped significantly in 2021, and broker forecasts seem to be continuously falling. But even so, a forward PER of just 4.3 seems astonishingly low - the market must be assuming that profits are likely to fall a long way short of forecasts then?
Forward divi yield is almost 11%, and it looks well-covered, if forecasts are met.
It has a large & complicated balance sheet, but once intangible assets are removed, the NTAV isn't great, at just over £100m.
I'd say this one looks worthy of a closer look, as those value metrics are astonishing but could be signalling that something's wrong.
Thanks for flagging, I'll look at the H1 numbers when they're published.
Regards, Paul.
I had a little look at TCAP yesterday, I came away thinking there is value there but they arent generating the profits their adjusted numbers indicate as they are making alot of exceptional charges and are forecast to continue to do so, I dont mind the amortisation of acquired intangibles but when they are including 'costs to achieve cost savings' and incurring these costs year on year I don't think you can seriously accept the adjusted numbers as representative of the true business performance.
See below for the forecast numbers for 2022 from their 2021 accounts:
The main significant items for 2022 are expected to be approximately:
§ c.£50m of amortisation of intangible assets from acquisitions with the increase due to a full-year impact of the Liquidnet acquisition.
§ c.£40m of costs to achieve the cost savings programs initiated in 2021 (see Incremental P&L savings and costs to achieve table in the previous section).
§ c.£20m of costs to achieve new savings initiatives currently being planned.
§ c.£10m relating to the unwind of the discount of deferred consideration relating to acquisitions.
§ c.£6m of Brexit related staff relocation costs following the EU stating it is unlikely to grant UK-based firms automatic market access equivalence.
We expect significant items to reduce further in 2023.
Be very careful with TP ICAP. They are embroiled in a complex and long running legal case involving one of the biggest tax frauds in history. It could take years to play out and the settlement could be collossal, not to mention the terrible press it will generate. Besides that, they are an extremely low margin business and they could see a significant decline if the financial markets stay subdued.
I heard one fund manager say that despite their problems, one part of the business is doing well and worth more than the entire market cap (forgive me, I haven't looked into this yet and didn't catch which part of the business this was, but would imagine you might know more about this)
Just to flesh out my earlier comment on TP Icap (LON:TCAP) - the fund manager was Christopher Mills, and he said the data analytics part of the business was itself worth significantly more than the entire market cap. That certainly made me take notice and intend to take a closer look at company when time permits.
If anyone wants to hear Christopher Mills' comments which Bouden54 referred to, I think the relevant podcast is here, at 37:45
When I was listening to this I got a little irritated that whenever he discussed valuations of anything his only interest was in EBITDA, and I couldn't make up my mind whether I was listening to pearls of wisdom or someone talking their book. And when I looked at his funds there seemed to be some cross-holdings which I abhor. But I noted he said that his fund bought TP Icap (LON:TCAP) recently at about £7 and there are signs of an activist investor getting involved.
Thanks to Paul for taking an interest. I do not know how you fit it all in.
When I was listening to this I got a little irritated that whenever he discussed valuations of anything his only interest was in EBITDA, and I couldn't make up my mind whether I was listening to pearls of wisdom or someone talking their book.
Reminds me of that pearl of wisdom from Charlie Munger that whenever you hear or read EBITDA replace it with "Bullshit earnings". I have no idea why anyone would use it to value a company, it makes no sense. Is that maybe what Private Equity do?
All the best, Si
Would be interested to hear the SCVR team’s view on the M&A news from £SOLI. £25m acquisition announcement to be funded by share placement so shares rise 5.5% yesterday. When the share issue success announced (oversubscribed) at a significant discount to yesterday’s closing price the price falls back 12%! Be interested to hear any views on Solid State (LON:SOLI) which looks a good solid business.
re Solid State (LON:SOLI) (I hold), seems to be an incremental type acquisition, rationale seems to be primarily to build presence in the US. Makes sense, one of my concerns about Solid State (LON:SOLI) has been that it is too UK-centric.
Solid State (LON:SOLI) looks like a good business (I do not hold) but I'm not surprised that the price has fallen towards the discounted placing price today. If the institutions wouldn't fund it without this discount, the fall looks reasonable.
Solid State (LON:SOLI) Been close to pulling the trigger, but its still a pretty punchy P.E. for the current market conditions I.M.O, backed up by Paul's excellent recent coverage, I'm on the fence.
Clearly plenty of good RNS news coming out from them, with contract wins etc. Just the P.E. puts me off for now, even after the fall.
any thoughts on Tharisa after yesterday’s production update Paul?
I don't think generally Paul will comment on mining stocks.
But my take was that the Tharisa (LON:THS) Q3 production update was clearly a negative as the chrome production guidance has been moved down by 10% for the year - this is quite a large fall as there is only one quarter to go until the end of FY22. I would have definitely wanted more detail on the reasoning behind this as the "slower Vulcan ramp up" was a surprise to me as most of the recent commentary on Vulcan has been positive. In addition, no reason was given on why the chrome feed grade was lower.
The Tharisa story has clearly become more risky in recent months, with:
1). Global recession on the horizon, there is clear uncertainty around metal prices. Tharisa seems to be saying it expects the recent rally in chrome prices (which will have boosted current year earnings considerably) is likely to reverse in the coming quarter. Rhodium (the most important PGM to THS) is holding up surprisingly well in recent weeks but platinum is falling relentlessly.
2). The political situation in South Africa and how it affects the mining companies has been a source of concern for a while. Security of distribution of bulk materials (particularly coal) to the South African ports has been back in the news the last few days.
3) The development in Zimbabwe (Karo) - while it might be a long term major positive - clearly introduces new risk into the Tharisa story and it will have to deal with managing a major investment project in the current inflationary/ supply shortages environment.
4). Tharisa has targeted but so far failed to get its production to increase. It had in its "Vision 2020" programme (originated in 2018 I believe) a target to get to 200,000 oz of PGMs and 2m tonnes of chrome a year by 2020. While Covid and delays to Vulcan affected the plan, we are in FY2022 and the guidance is now still only 165k to 175k oz of PGMs and 1.55 - 1.65 million tonnes of chrome.
So I can understand why the stock has fallen a long way from its highs earlier in the year and I believe that some of this fall is justified. But with the company now trading below tangible book value and current earnings being strong, I think this is a reasonable buying opportunity and I have been adding modestly, even after the production update.
Very positive report from Loungers (LON:LGRS) which indicates that it is well placed in the market, offering what the market wants and perhaps can afford going forward. Very positive statement regarding further openings. I dont know much about the group but it seems well positioned. Would you have a look at it Paul S please?
Loungers (LON:LGRS)
Yes huge contrast between loungers update and wetherspoons updated today (i hold JDW for my sins and not this). Without really doing much research (i have visted one of the outlets that seemed fine). I do get the impression they have a decent niche - it is such a tough sector though that what is flavour of the day now (shiny and new?) may not be in 5-7 years. With such a tough sector do we need the risk at all ? I would perhaps be minded to say quality was always out so they can't do much more than do what they are doing here right now so its hard to faulty what they are doing. Price seems to have droped of nicely for anyone looking to ypick these up. Note its expected that profits will materially worsen this year - that should not realy be a massive shock - per stoicky doesnt look like there has been any materials downgrades here so loks like there is nowt new in the news.
Its hard to say why loungers are doing better than wetherspoons - i suspect it may be the fact they are "not a wetherspoons" so can attract the peeps who wouldnt be seen dead in wetherspoons (is that a growing list?). I do wander though if their sites might be in slightly more "city central" type locations than your average wetherspoons - wetherspoons themselves said the folowing in their update today.
Contrary to expectations, sales in major city centres, apart from London have been stronger than suburban locations or smaller towns. For example, sales in the latest quarter in central Cardiff were plus 14.9%, plus 13.8% in Newcastle, plus 9.5% in Nottingham, plus 8.6% in Glasgow, plus 8.5% in Bristol, plus 8.3% in Coventry, and plus 7.0% in Manchester.
I read both RNS's this morning Loungers (LON:LGRS) and J D Wetherspoon (LON:JDW) .
I have thought for some time that Covid Lockdowns have ruined J D Wetherspoon (LON:JDW) business model, the majority of their customer base having realised that as cheap as ' Spoons' is it cant compete with buying Special offer wine and beer in the supermarket and drinking at home . The drop in beer sales and increase in cocktail sales would probably prove this .
Richard
On J D Wetherspoon (LON:JDW)
The chart shows a long and sustained downward trend (momentum rank 23) - not a good sign.
On the other hand, discretionary income will come under pressure over the next year, and when they can sell beer for £2 a pint, I think they will benefit.
The JDW comment on sales in city centres reflects (to some extent) increases in travelling costs and decreasing discretionary income. If you have to travel (bus/car) to a surburban spoons, you wont as often as a city centre, where you are there for work anyway. The ranking of those cities may also be aligned with the quality of the public transport available in that city (Cardiff's is much better than Bristol's, which is not just pretty bad, but the last bus from bristol to my satellite town (clevedon) leaves bristol at 9 on weekdays)
Renold final results look very encouraging. No dividend payment, but I'm happy for that at the moment. Good reduction in debt and pension liabilities too. I'd be interested in your thoughts Paul.
Many thanks,
DH2.
Does anyone who better understands this sector have a view about the extent to which Renold (LON:RNO) might have benefited from the recent commodities boom?
Public service announce: US CPI report for June is announced today, could cause some volatility in the markets this afternoon.
*announcement
Inflation data worse than expected
Ilika (LON:IKA) looks like it will take a pounding - their revenue has dropped to £500k from £2.3m . I've watched with interest but that really isn't good news - unless I'm missing something
I agree the share price will fall but the figures are not unexpected. I think the previous revenue was mainly from research grants. They are in a strange hinterland between having done the initial product development and bringing it to production. They have failed to find production partners which was their initial plan and are developing their own production facilities. Unfortunately the main market for Stereax tiny batteries is for medical implant devices which have to go through tortuous safety qualification. The Goliath batteries for cars, etc, seem to be further behind and although they may bring it to market for small volumes they need a partner to make it on superfactory scale. I hold a few shares and my problem with the company is simply that I don't know if it truly is ground braking technology or whether it will lose out to the numerous other batteries technologies in development. We wont really know until end 2023.
Concurrent Technologies (LON:CNC) has a decent sized contract win ($2.2 million) detailed in an RNS this morning. New CEO and CFO recently both ex £QQ, with lots of experience.
A lot to like about this company and may be worth a look, the contract is significant by my quick calculations.
(I hold)
I agree that the Concurrent Technologies (LON:CNC) contract announcement looks significant, as it is said to repeat annually and is an extra ~10% "wholly accretive" to their current revenue. CNC has an operating margin of 17% (per Stocko) and net cash. I'll be surprised if it doesn't lead to broker upgrades. It has been a long term Lord Lee investment. Maybe this contract will be the trigger for a further takeover in his portfolio. No institution holds a blocking shareholding.
I hold.