Small Cap Value Report (Wed 13 Mar 2024) - SDRY, SHOE, BBY, MMAG, CPX, IXI, GYM, KWS, VCP

Good morning from Paul & Graham!
Masterclass reminder!
The latest in this series is today at noon - I wrongly assumed it would be this evening, so apologies for not flagging this earlier. The topic is investing strategies. These series of masterclasses are terrific, and I know that a lot of work goes on behind the scenes to prepare them, so I shall be trying to multi-task from 12:00, writing more sections here whilst listening in to the masterclass!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
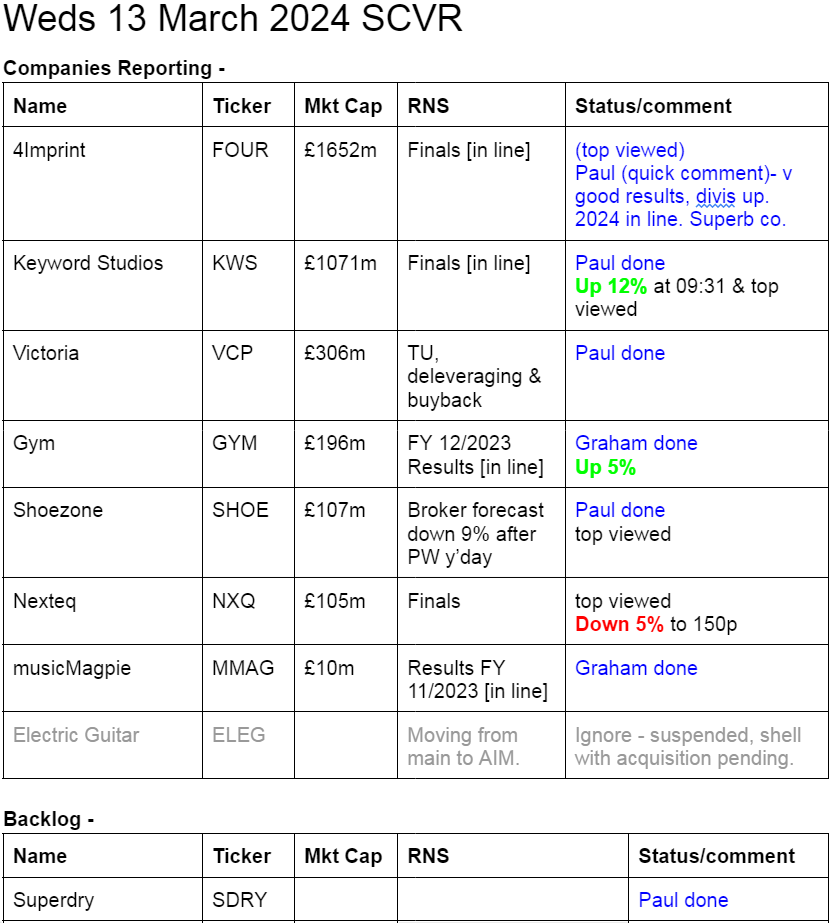
Other morning movers (with news) -
Balfour Beatty (LON:BBY) - up 9% to 370p (£1.98bn) - positive market reaction to increased share buyback (£50m existing, upped to £100m) and to FY 12/2023 Results with underlying EPS down 21% to 37.3p, in line with expectations. Massive £16.5bn order book. Large complex business, low margins, negligible NTAV. Outlook sounds good, with growth expected in 2024 & 2025. Paul’s view - none, it’s not one I’ve looked at in detail. Shares have gone in a sideways range for 15 years, so it’s navigated lots of potholes better than most industry peers. Could infrastructure/contracting shares be coming back into fashion now maybe? The devil’s in the detail of all their contracts, info that we probably won’t know about. But I can see that the lowish PER, and encouraging outlook, make this something that sector experts might want to look into further.
CAP XX (LON:CPX) - down 81% to 0.076p (£negligible) - Corporate update - we haven’t covered this since 2017 (apart from here on 1/2/2024 when I flagged it was almost bust), as it looked so bad - serial loss-maker, cash burner, and equity issuer - typical of many AIM shares unfortunately! - which is why we usually ignore this type of thing, but they’re coming up constantly on my new morning movers section - have I created a monster?!
Anyway today’s update is saying things have only got worse, and cash now “highly constrained”, and it needs fresh funding by the end of this month. No debt options available, and efforts to raise equity taking longer than expected. Paul’s view - existing equity looks worthless, as mentioned last time. Time to call it a day as a listed company. RED obviously.
IXICO (LON:IXI) - down 22% to 6.8p (£3m) - Profit-warning, with FY 9/2024 now expected to show another decline in revenues. I’ve done a 10-minute review, and it’s not a complete basket-case (yet). It did make small profits in the past, but more recently reported a loss for FY 9/2023, and revenues have since continued falling. It had £2.8m cash remaining at 29/2024, down from £4.0m at 30/9/2023. It says sales pipeline is growing though. Providing management can conserve the cash, and not come back to an unreceptive market for more equity, then this could be a survival/turnaround story, possibly. Delisting risk is considerable though. So one for gamblers only, but as a fun money punt, I can see some attraction, if they don’t run out of cash.
Victoria (LON:VCP) - down 6% to 229p (£265m) - Trading Update, De-Leveraging & Buyback (profit warning possibly? Unclear) - Paul - AMBER/RED
Trading - near-term conditions remain tough, but forward indicators improving. Market demand down 20%, interesting as this is what Headlam (LON:HEAD) also said recently. FY 3/2024 - underlying EBITDA now expected to be c.£160m, but nothing said about what it was previously expected to be - infuriating, and no broker updates available to us proles! Mentions “pressure on earnings” from higher labour costs, and restructuring, so I assume this must be a profit warning, but we need more information to be sure. “substantial permanent” reductions in overheads, and improved efficiency (not quantified).
Says margins will be 250-350 bps higher, when demand returns.
Asset sales - non-core & surplus land has been sold for E31m already, with E50m more expected. Quite hefty numbers.
Working capital - says it can squeeze £30m out of inventories in FY 3/2025.
Share buyback - a strange thing for a very heavily over-indebted company to decide, but it says there is an “intention” for a “potential” £25m share buyback.
Bond repurchases - has bought back E11.1m of its own 2026 Bonds, at a 21% discount vs par value. Target is E25m total but there isn’t enough market liquidity to do this, they say. The coupon on these bonds is only 3.625%, but buying back at well below par produces a good overall return to maturity.
Paul’s view - the problem here is not market “noise” as the Chairman seems to think, it’s that mgt at VIC have greatly over-geared the balance sheet, with last reported NTAV of £(371)m. So I didn’t respond well to their rather dismissive commentary today - the share price has crashed precisely because of their high gearing strategy, combined with poor market demand. Mind you, borrowing through fixed interest bonds rather than a regular bank, is looking an inspired decision now that interest rates are higher. Overall, I could see this share multibagging in a flooring market recovery, aided paradoxically by its precarious balance sheet - we’ve seen this play out before, if you look at the long-term chart. So it could be an interesting share for risk-takers who can live with its hideous balance sheet & high debt. I’ve got to flag the higher risk, so will go with AMBER/RED. It’s likely to move big in one direction, I just don’t know if that will be up or down! Not much use to you then really!
Summaries of main sections
Superdry (LON:SDRY) - down 13% to 27p (£27m) - Response to media speculation - Paul - RED
Super-high risk now, given increasingly alarming press reports over various advisers being called in, and a (company confirmed) need for a further £20m of borrowings from lender of last resort Hilco.
Shoe Zone (LON:SHOE) - 232p (pre-market) £107m - Zeus update note - Paul - GREEN
Zeus drops forecasts EPS by 9%, which is more than I was expecting from the mild profit warning issued yesterday. It still looks a good quality (high scores) business, and good value too. Although [trigger warning!] Chinese direct to consumer Shein/Temu (and other?) aggressive competition worries me.
Musicmagpie (LON:MMAG) - down 1% to 8.9p (£10m) - Full Year Results - Graham - RED
Not much cheer for MMAG shareholders this morning as revenues fall, net debt grows, and the pre-tax loss expands. Recent trading is in line with expectations but I don’t see how investors can have faith in this company becoming sustainably profitable.
GYM (LON:GYM) - up 5% to 115.6p (£207m) - Full Year Results - Graham - RED
2023 results from this low-cost gym operator are in line with guidance and the company reports a good start to trading in 2024. It remains ambitious for growth despite already having over 200 sites and carrying substantial debts. Too risky for me.
Keywords Studios (LON:KWS) - Up 12% to 1544p (£1.21bn) - FY 12/2023 Results. - Paul - AMBER/GREEN
Overall I'm pleasantly surprised with these 2023 results, which look pretty good, if you're happy to accept the large adjustments. A major acquisition spree leaves it with net debt (although not excessive, providing it remains decently profitable). Worth a closer look I think.
Paul’s Section:
Superdry (LON:SDRY)
Down 13% to 27p (£27m) - Response to media speculation - Paul - RED
It’s strange how news from Superdry typically first comes out via Sky News, and then the company responds. The latest news is that SDRY confirmed on Mon evening that it was seeking an additional £20m lending facilities (£10m for restructuring, and £10m for seasonal peak trading in the autumn). “No certainty that such changes will be agreed”.
Paul’s view - SDRY is looking increasingly financially distressed, and doing all the things I would expect from a company that’s at considerable risk of going bust. There have also been press reports that it was considering its debt options (of which there are very few, in my view), and has called in various advisers, again often a precursor to some form of insolvency in my experience. Maybe it can pull another rabbit out of the hat in IP sales, but I think that would only be postponing the inevitable.
We've been warning here for a long time that SDRY is looking increasingly risky, and I confirm that I’m treating this share as super-high risk now, with the most likely outcome being a 0p outcome for shareholders. Although who knows what might happen? Remember that the brand will survive, but maybe with a different owner. Be very careful, this one is only for gamblers now, hoping for a miracle. Remember also that Hilco are experts at dealing with insolvencies, and as the main (secured) creditor, they will legally rank higher up than trade creditors, let alone shareholders who are at the bottom of the heap and usually end up with nothing in financially distressed situations.
Why would anyone bid for the existing equity, and take on all those onerous leases for the many loss-making shops? Doing a pre-pack administration is the obvious route to take, which of course would almost certainly wipe out existing equity. Similar to what happened at Joules (where I lost a packet, so am not making the same mistake twice).
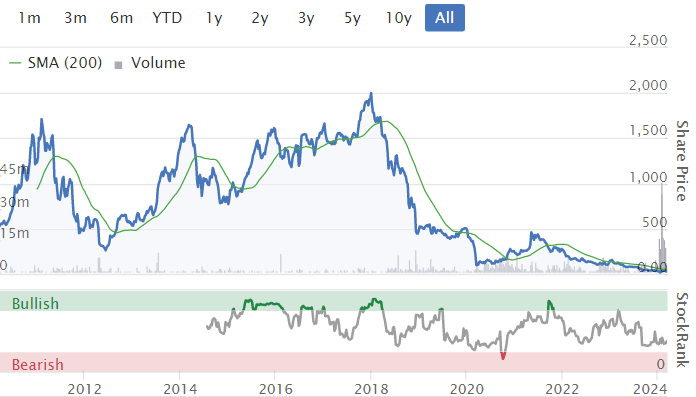
An outdated, failing brand? Down over 98% from the Jan 2018 peak, with the bulk of the collapse in share price happening before the pandemic began in early 2000. It's a reminder that mid-market brands come and go - what's fashionable for one generation may become cringe-worthy for the next -
Shoe Zone (LON:SHOE)
232p (pre-market) £107m - Zeus update note - Paul - GREEN
Yesterday we had a mild profit warning from SHOE which I covered here, blamed on NLW, Suez, property costs, and slower A/W trading. SHOE told us trading was “marginally below expectations”. Shares sold off sharply, giving back all of a recent surge seemingly triggered by a couple of media buy tips.
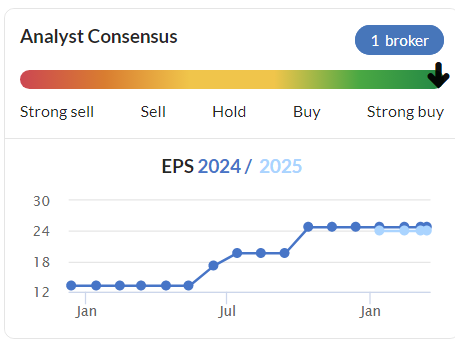
This morning broker Zeus updates us (many thanks), and it seems worse than the announcement yesterday seemed to suggest. Zeus has lopped £1.4m off its adj PBT forecast for FY 9/2024, reducing from £15.2m to £13.8m. Forecast adj EPS comes down from 24.7p to 22.4p - a c.9% reduction, which doesn’t fit the description from SHOE of “marginally below expectations”. Zeus says it’s being prudent, but even so, this has not been handled very well by the company. It should have said “below”, not “marginally below” in yesterday's RNS. I’ll make a mental note of that for future reference when interpreting announcements from SHOE - that they might be reluctant to accurately divulge bad news.
In the short term then, I feel SHOE has blotted its copybook somewhat. However, once the dust has settled, people may take into account that it’s only giving back a bit of a previously very positive forecast earnings trend (not yet updated for today's forecast revision to 22.4p) -
The numbers are still very good, and the valuation modest still, especially after this recent pullback, so I’m sticking at GREEN.
I do still have background worry about potential erosion of sales from the aggressive direct-to-consumer Chinese companies, eg Shein and Temu. This seems to trigger some readers, who think it’s a preposterous idea. However it’s real - I’ve bought shoes from Temu, they squash them down in a bag, with no box, and they don’t seem to worry about making profits - they’re more interested in killing the competition, and apparently have no qualms about working conditions at the factories to achieve lowest cost price. That’s a big worry, when SHOE is also sourcing its products from China and making a fat gross margin on them - an open goal for Shein/Temu I would say, and they only need to erode a small % of SHOE’s sales, to dent its profits badly, due to the operational gearing. Returns rates are low on shoes, as you just buy the size that you are, and it usually fits. That said, most customers will probably still want physical shoe shops to try on the fit.
Anyway, for now I remain positive on SHOE, but am starting to have some doubts, given that it seems to have lost short term trading momentum.
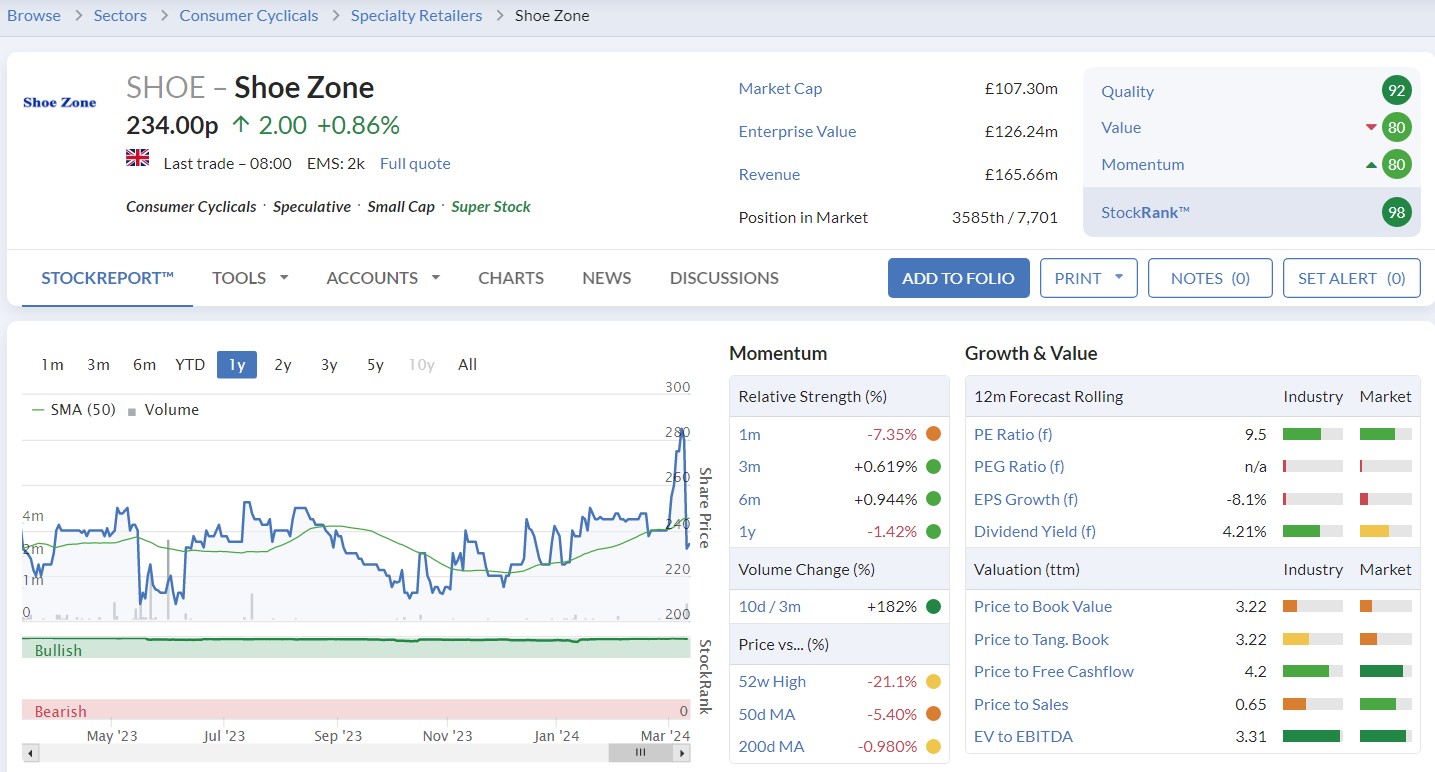
There’s lots of green on the StockReport, and a terrific StockRank of 98, so maybe I’m needlessly worrying? I’d be interested to hear all opinions from readers, whether you’re bull, bear, or somewhere in between. As always, don't let bulls shout you down, we want to hear a range of well-argued opinions.
Lots of green here (the longer bars, or higher numbers, for the colour-challenged) -
Keywords Studios (LON:KWS)
Up 12% to 1544p (£1.21bn) - FY 12/2023 Results. - Paul - AMBER/GREEN
We’ve covered this share very little here in the SCVRs as its market cap was too big, but after recent falls, and us spreading upwards into mid-caps, here it is! Graham did review KWS here in Dec 2023, taking an amber view, and saying it had grown into a more reasonable valuation.
Quite good results today I think, given the carnage elsewhere in video games sector. KWS seems to provide services to bigger computer games companies, including 24 of 25 of the largest it says - impressive.
Reporting in Euros, main numbers are -
Revenue up 13% (5.6% organic) to E780m
Adj EPS flat at 112.9c (Euros)
Statutory EPS much lower at 25.3c, so very large adjs
Adj operating profit up 7% to E122m.
Statutory PBT is down 49% to E35m, so you have to be comfortable with the large adjustments here -
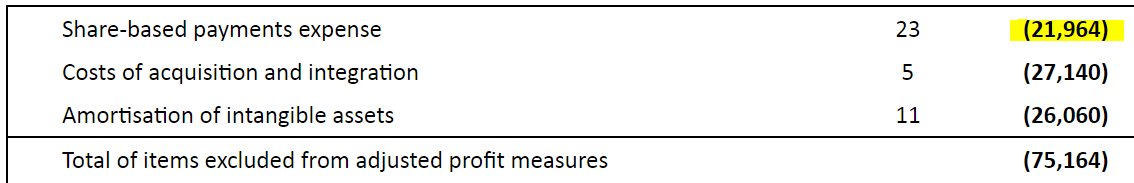
Moved from net cash of E81.8m to net debt of E67.5m due to heavy spending on 5 acquisitions.
Total divis of 2.61p (up 10%), but insignificant yield of c.0.17%
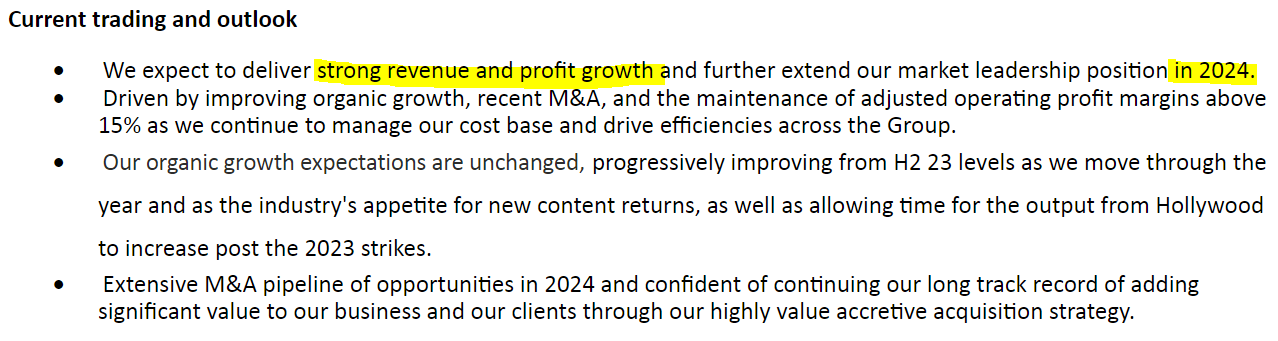
Outlook - I’m impressed with all this -
Share-based expense - is way too high, excessive even, at E22m in 2023, and E18.7m in 2022. How can that be justified? But I suppose the market cap is £1.2bn, even so mgt nabbing 1-2% of the company for themselves each year, on top of other forms of remuneration, puts me off somewhat.
Finance costs have shot up, and finance income dropped by two thirds, as it moves from net cash to net debt.
Balance sheet - has been strikingly geared up, to pay for the acquisitions. NAV of E599m contains E632m intangible assets, so NTAV is now negative at E(33)m, which might put off some value investors.
Paul’s opinion - KWS does look interesting, if you’re OK with all the accounting adjustments, and the rapid & expensive acquisitions spree. Given all the turmoil in this sector, and Hollywood strikes, these results do strike me as “resilient”.
Outlook comments sounds upbeat too, helped by the 2023 acquisitions contributing a full year in 2024.
I’ve only done a quick review, and it’s not a company I’m familiar with, so take my view with a pinch of salt. Based on what I’ve seen, I quite like this, and will go with AMBER/GREEN, it’s something that seems worth a closer look by readers maybe. Pity there are no broker updates out since last summer available to plebs like us!
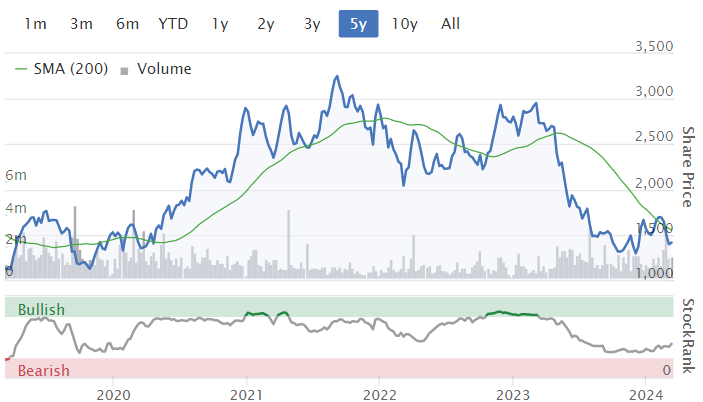
I’m drawn to this chart too, as possibly a good entry point, combined with today’s resilient results, who knows? -
Graham’s Section:
Musicmagpie (LON:MMAG)
Share price: 8.9p (-1%)
Market cap: £10m
musicMagpie, a circular economy pioneer specialising in refurbished consumer technology, disc media and books in both the UK and US, announces its audited full year results for the year ended 30 November 2023 ("FY23").
The company has put a brave face on when it comes to presenting these results, and in some ways they aren’t too bad. But then you get down to the bottom two lines of the highlights table:
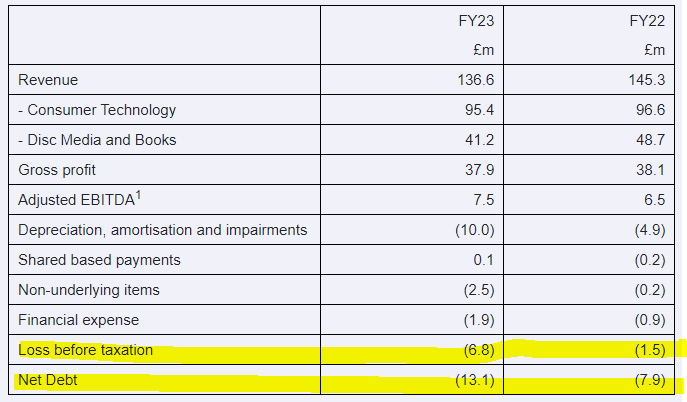
The company has two major categories: Consumer Technology, and Disc Media and Books.
Disc Media and Books - the sale of new and second hand games and DVDs in disc format - is an activity that is inevitably going to continue to decline in my view, as there is simply no reason for games and movies to be stored on a disc instead of downloaded.
My opinion on this has evolved; a few years ago, I still liked having the physical disc of a game and thought there was value in owning that disc (e.g. being able to share the disc with your friends after you’re finished with it). But I don’t believe these arguments are very strong these days.
These days, if you install a game from a disc onto your games console, you will most likely be prompted to download the latest updates to the game. These updates can be very large. So why not simply download the entire game?
I agree with this article which says that the real point of game discs these days is as a proof of purchase that enables the user to download the game, not as a format that actually stores the game. This makes it a legacy format that in many ways doesn’t need to exist any more.
Music Magpie’s Disc Media and Books division saw revenues fall from £48.7m to £41.2m:
…declining as expected, mainly owing to the continued reduction in the sale of both new and second-hand physical media as consumers increasingly consume content in different ways, for example online streaming.
We are starting to see a deceleration in this sales decline as the more rapidly declining DVD and gaming segments become much less significant and books, which are more resilient therefore generate an increasing share of overall sales.
The trend suggests that this will eventually become a Books division, as Disc Media will not be a thing.
The larger Technology division also saw declining revenues, from £96.6m in 2022 to £95.4m in 2023:
Within this segment, the Rental business grew from £5.3m to £8.25m as active renters increased from 30,500 to 37,100…
The second component of Consumer Technology, outright sales, saw revenue decline by £4.0m to £87.2m (2022: £91.2m), but gross profit was static at £16.0m. The Group has focused on expanding its margin on outright sales via a number of initiatives as well as managing the sale of stock across the various sales platforms in a more sophisticated manner in order to achieve minimum expected gross margin targets.
Profitability
Let’s see how large EBITDA becomes a large loss:
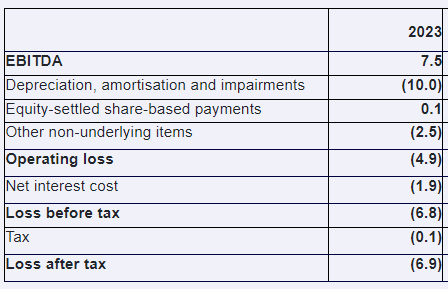
Is there anything here that doesn’t represent a real cost? Not much, I’m afraid. The depreciation charge (on devices out on rent) seems fair to me, as does the amortisation charge.
Within “other non-underlying items” (£2.5m), you could maybe argue that the impairment of goodwill (£1.1m) is not a real cost. There is also a loss relating to electricity prices - the company hedged its electricity costs at prices above current market rates - and investors might choose to ignore this.
Therefore, in my view, only the “other non-underlying items” can potentially be adjusted out and ignored by investors.
Balance sheet has notional net assets of £12m but if you exclude intangibles this falls to zero.
Bank loans: the company has a £30m RCF with HSBC and Natwest. £20.5m was outstanding at the end of 2023, vs. £14.7m at the end of 2022. Rates charged are reasonable but the banks have security over nearly all of the company’s assets.
Q1 Trading and Outlook
Q1 FY24 has recently closed and trading was in line with management's expectations. This positive start to the new financial year, combined with the recent changes made in the US to the Group's Consumer Technology buying strategy and operations, cost reduction exercises in the UK and lower investment levels into our Rental offering, give the Board confidence in the Group's FY24 and medium-term prospects.
CEO comment excerpt:
We expect second-use markets to continue to grow which will complement our strategy of unlocking a 'world of inventory' from consumers homes and providing them with a solution that is 'smart for you, smart for the planet' across of our existing product categories and potential new product categories. As such we remain confident in musicMagpie's future prospects.
Graham’s view
Unfortunately I don’t see an easy route to profitability for this one. And given that it’s in a net debt position, without any proper asset backing, I’m not sure if the equity is ultimately going to be worth anything at all.
In that sense I’m relieved to see that the market cap is only £10m; if it was something more substantial I’d be extremely worried for shareholders! At £10m, it might still be worthless but there is at least the chance of a reasonable outcome for shareholders if performance miraculously improves.
The StockReport warns us that this stock is involved in a “takeover situation”; the reason is that on 27th November 2023, Music Magpie said that it “continues to seek potential buyers” for it, after two potential buyers ruled themselves out.
Stranger things have happened, but I would be shocked to see a buyer paying a big premium here. Why bother taking that risk, when it might be possible to do a deal with the bank at some stage?
These shares are already priced as options and do have multi-bagging potential if the company pulls a rabbit out of the habit. On the basis of the poor figures, however, I’m giving this one the thumbs down.
GYM (LON:GYM)
Share price: 115.6p (+5%)
Market cap: £207m
Let’s take a look at this low-cost gym operator’s full year results for 2023.
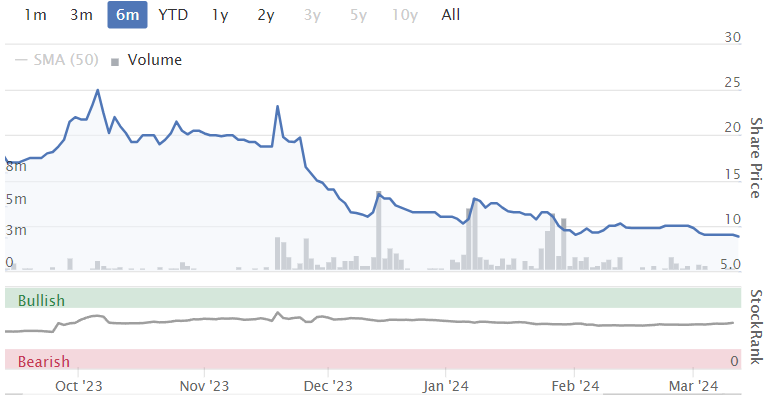
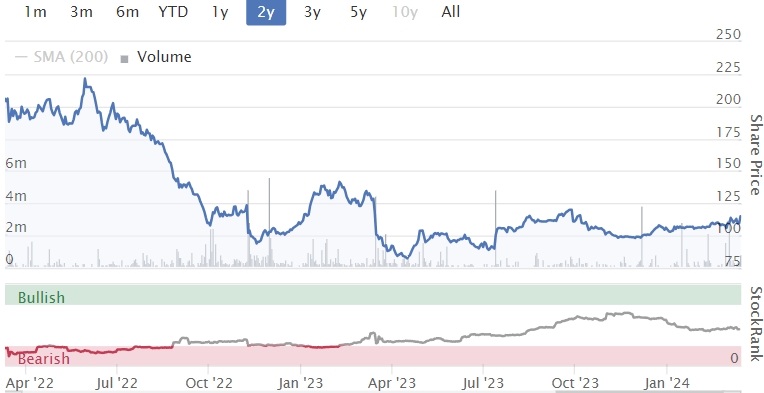
From a technical point of view, perhaps the shares have found a base?
Here are the highlights:
Revenue +18%; like-for-like revenue +8%
“Group Adjusted EBITDA Less Normalised Rent” is up 1% to £38.5m but this strikes me as a totally meaningless number.
Adjusted pre-tax loss £5.5m, same as the previous year.
Statutory pre-tax loss £8.4m, an improvement from a £19.4m loss in the previous year.
Net debt (excluding leases) improves from £76m to £66m.
Management - during 2023 the company recruited a new CEO and will have a new CCO this month.
Current trading and outlook sounds quite good:
Good start to trading in 2024; revenue after two months has grown by 16% year on year, reflecting a 3% increase in average members and 13% growth in yield, benefitting from price taken earlier in the year. Like-for-like revenue up 12%
Like-for-like revenue in 2024 to increase by 4-5% overall as the impact of the early price increases normalises later in the year
Plan to open 10-12 new sites in FY24; leverage expected to remain within the range of 1.5 to 2.0x. Next Chapter growth plan aims to deliver c.50 site openings with average ROIC of 30% over three years, funded from free cashflow.
The forecast of 4-5% like-for-like revenue growth for 2024 implies that there will be some real revenue growth, assuming that inflation falls from the current 4%.
However, the leverage multiple of up to 2.0x still makes me feel uneasy. GYM has struggled to show a profit ever since Covid, and pre-Covid profits weren’t particularly high to begin with.
They already have over 200 sites, which presumably includes all of the areas they might have considered low hanging fruit. Increased rates of working from home in recent years may have changed their calculations to some extent, but the question remains: what is going to change to make this company profitable?
Cash flow: the company presents “free cash flow” (excluding expansionary capex) of £27m. Therefore the bullish argument for this stock is that if you ignore expansionary capex, then you can get a cash flow number like this which is actually quite good. So I’ve answered my own question: the argument for this stock is that its financial performance could improve when it stops expanding.
However, it’s unlikely to stop expanding in the short-term. The CEO comment argues that the market can sustain the creation of more low cost gyms:
We have maintained positive momentum in revenue through the second half to deliver results that have offset cost inflation, in line with our guidance. With a strong start to 2024, and clear signs that demand for health and fitness has never been stronger, these are solid foundations on which to build our Next Chapter growth plan… There continues to be substantial headroom for low cost gyms in the UK and we are fully focused on our aim of making high value, low cost fitness even more accessible for all."
Graham’s view
There is a bullish argument to be made for GYM, but I’m afraid I’m not sold on it yet.
On the positive side, it has managed to push through price rises that have enabled revenues to keep pace with inflation and it plans to do so again this year.
Its cash flow performance is also not bad, if you exclude expansionary capex.
On the negative side, it is carrying significant financial debt, on top of enormous property leases. And its statutory numbers are poor, to say the least.
I’m therefore inclined to keep my negative stance on this stock for the time being. Maybe it can surprise me and prove me wrong, but I see substantial risk here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
Volex (LON:VLX) and Avingtrans (LON:AVG)
Many thanks for the feedback.
Some good points regarding Volex (LON:VLX) with reference to near-shoring, Mexico being a case in point to serve the American market and Downing Strategic Micro-Cap Investment Trust (LON:DSM) slowly selling down its position as it winds down.
Apologies to 'sharw' for the irritation caused by the use of the dreaded 'd' word!
As for Avingtrans (LON:AVG) my views I believe are fairly well known and I am more than happy to side with planetX. On which point I thought that I ran a fairly concentrated portfolio with my top 6 holdings accounting for 40% or thereabouts, but planetX takes the prize by some margin.
I am off course biased so hopefully my views on both are correct.
"The governor of the Bank of England says the UK jobs market is near full employment.
The country is experiencing an "unusual" pattern of falling inflation without significant unemployment, Andrew Bailey said, adding: "This is tentatively good news."
Usually, higher interest rates result in companies cutting jobs because borrowing and investing become more expensive."
It's scary isn't it. The Bank of England doesn't seem to understand basic stuff - that inflation is falling because of supply shocks now washing through as they annualise. They seem to think their decisions on interest rates are somehow fine-tuning the economy and causing these effects. It's totally delusional. Interest rates have to rise to slow down overheating economies, not ones that are flat-lining as we've had for ages now.
Volex (LON:VLX) and Avingtrans (LON:AVG) are my two largest holdings in what is a relatively concentrated portfolio of 27 UK small caps.
Volex (LON:VLX): from Feb 9 to today's close, the shares have given up 13%. It would appear that Mr Market takes the view that the company is likely to be impacted by the dreaded destocking and will not achieve market expectations. I have no insight into trading but I would suggest that the current share price and resulting investment metrics go some way discounting the impact should such an outcome materialise. My view is that robust demand for cabling in data centres and to a lesser extent medical equipment is likely to offset a softening in electric vehicles and power cords for white goods, PCs etc.
Avingtrans (LON:AVG) I added to my holding on recent share price weakness and was pleased to see that the shares rose today in excess of 6%. I suspect that there is no specific reason for this, although the possibility of a disposal of one of the engineering businesses did come to mind. Again this is just musing on my behalf.
Fortunately good share price performance from the likes of Bloomsbury Publishing (LON:BMY) Galliford Try Holdings (LON:GFRD) and Sigmaroc (LON:SRC) has offset the recent softness in Volex (LON:VLX) and Avingtrans (LON:AVG)
The above post helps me to clarify my thoughts, although observations and views are welcome.
are you concerned about the rising net debt levels for volex?
Jonno
With you on Avingtrans , I doubled down hard when it briefly hit the 330s.
This was on the basis I was a happpy buyer at 420 so why would I not be super happy at 330 .
I’m even more concentrated than you and Avingtrans alongside Georgia capital and Bloomsbury are the three I’m super comfortable with 10/10 on my confidence chart
Hargreaves next 9/10
Equals and Filtronic down to 7:10 would like a bit of news .
These 6 account for 70% of my investments (Filtronic was only a half holding till it went and doubled !)
Actually clipped a few Filtronic today as I needed to pay for the replanting of a load of trees after the weevils ate the ones we planted last year .
Bloody weevils .
Avingtrans (LON:AVG) on brief inspection looks unappealing. EPS estimated shrink to 6p with share price 400p. What's the special feature that has you impressed?
The EPS decline is due to the funding of the nascent medical division comprising Adaptix (portable 3D X-ray scanner) and Magnetica (portable helium free MRI scanner). Both have significant potential. The Adaptix 3D X-ray device has FDA approval and is in the process of being marketed. The Magnetica MRI Scanner is to be submitted for FDA approval later this year
There is a very good interview on Vox Markets with management discussing the recent H1 results; link below.
Q&A with Avingtrans CEO, Steve McQuillan & CFO Stephen King - Vox Markets
"Destocking" is a word that really irritates me as it is now used as a cover for so much. Originally in the first two years of the pandemic supplies, particularly from China, were so erratic, not just from origin but with places like Tilbury clogged up, that it was sensible to increase stock if you could to deal with fluctuations. Then when freight transport moved back towards normal there was destocking and balance sheets looked better with less working capital tied up in stock. But now? - with the Houthis attacking a main trade route, sending a lot round the Cape of Good Hope, the original reason has gone. A company should only be destocking now if it looks likely that it will not be selling as much as it anticipated.
You mention Volex (LON:VLX) (I hold) and this is where Mr. Market has really got it wrong if it thinks this company has been hit by destocking. It has been riding the wave of "nearshoring" that has been taking place by increasing operations in places like Turkey and Mexico, and often talks about it - e.g. in the 2023 annual report one of the bullet points for delivering excellent performance on medical revenues is "Momentum expected to be sustained over the medium term with near-shoring benefit".
Volex - Downing Strategic Micro Cap Investment Trust has reduced its holding of shares from 9.7% to 8.35% over the month of Feb as it begins its slow wind down. It wsa 10.06% end of November. Probably doesn't help the share price as well.
Another nice surge upwards from Warpaint London (LON:W7L) today. I need to stop top slicing this one, it’s a rare gem in this market where the fundamentals of a quality GARP business are matched with the momentum in the chart.
Warpaint London (LON:W7L) price rose on good volume too. A wonderfully scalable business, lots of growth opportunity and co-owner managed. I added last week after top slicing a couple of times myself. EPS forecasts keep rising too.
Why firms are bringing their manufacturing back home - the flip side to cheap Chinese imports, good to see!
"More than half of UK manufacturers are now reshoring, according to one study at the start of this year.
Other firms are "near shoring", which means that while they are still getting their manufacturing done overseas, they are moving it to a nearer country.
And then there is so-called "friend shoring", whereby you keep your manufacturing abroad, but move it to a country that has friendlier relationships with your own. Apple is said to be doing this, as it increasingly moves production from China to India."
Source: BBC https://www.bbc.co.uk/news/bus...
The Magic Matgin
Not sure this is “friend shoring”
Apple is said to be doing this, as it increasingly moves production from China to India."
You will find most of the monstrous corporates are totally full of BS hiding the very hard cold fact that they somy chase the cheapest labour in the world . Chinese tech labour rates probably higher than India .
I know that Nike and the other global sportswear brands are going to be moving away from Bandung / Java after the imposition of a min wage by the Indonesian president .
Few years ago I remember all the low cost Chinese production suddenly wasn’t the lowest cost so the Chinese factory owners jumped ship and set up in military ruled Myannamar . You couldn’t ship from Myanmar directiy so they trans ship .
Same with production from China to Vietnam .
Let’s not kid ourselves that corporate America and corporate uk do nothing more than chase the lowest cost labour round the world in an effort to get the lowest factiory gate prices for the trainers they then sell for 200 usd .
This is our world .
My friend makes his jeans in the UK with European fabric and has to sell them for 150 quid .
If Nike sold a pair of jeans for 150 Quid they would still be made in India with “the magic margin”
The magic margin is beloved of the big brands .
It’s 10 times the cost price .
That’s what they look for if they have worldwide distribution channels to consider .
And in perfume it’s probably 100 times .
Nothing more annoying than global brands who pontificate and lecture and twist the themes of the day to suit their narrative .
Auto. Friend shoring to countries like Vietnam can be invested in through Investment Trusts-I hold VietNam Holding (LON:VNH) and Vietnam Enterprise Investments (LON:VEIL) . Latin America should benefit from both Europe and the USA near shoring- particularly Mexico. Blackrock Latin American Investment Trust (LON:BRLA) is the only listed Latin American Trust. Mexico has an ETF-iShares MSCI Mexico ETF (LON:0JF4) -I hold both of these. Turkey would be a logical choice for Europe- I recently bought an ETF to cover Turkey-iShares MSCI Turkey UCITS ETF USD (Dist) (LON:ITKY) . Trusts are good vehicles for Country and sector exposure as they will not suffer from redemptions- though the discount widening is a risk if they fall out of favour.
You have some very interesting selections there especially iShares MSCI Mexico ETF (LON:0JF4).
Argentina looks promising as well.
Banco Bilbao Vizcaya Argentaria SA (NYQ:BBVA) is extremely cheap even after a 60% rise in the last two months (I hold).
Oxford Biodynamics (LON:OBD) just announced a placing at 9p after market closed. Another example of a cash strapped company with promising technology having to heavily dilute to raise funds. Looks like market anticipated after it hit 47p less than 6 months ago after promising news around its prostate cancer test and since retraced to around 11p - the writing was on the wall, in the chart and on the balance sheet! Hope the placing goes well and they use the money to help mankind.
Boohoo v Shein v Shoe zone
Bottom line is online fashion is at best stagnant and at worst a falling tide .
The move is very much away from fast fashion and firmly into recycled fashion .
I know of one retailer (route 51) who have totally ditched their own brands and are now buying containers of vintage clothing from USA such as Carrhart and only selling that .
I can’t for the life of me see how that adds up online as each item requires a sepetate listing / size chart etc .
I also see a boatload of teenagers buying and selling on eBay / Vinted etc .
My old designer / partner popped in today and he has a very strong online brand (Hebtro co) they are doing very nicely, high end , 100% made in the UK, and they are holding their own but they have a strong customer base .
Shoe zone will be less affected but I don’t see anything remotely special apart from a nice business buying and selling cheap shoes. If they were buying up old brands like Mike Ashley think they would be in a better position then at least they had a bit of heritage brand power (maybe they do own a few brands ?)
They could even have picked up that dog Hotter shoes for next to nothing .
Mike Ashley is smart he has picked up sone good brands over the years like Dunlop, No Fear, Lonsdale (I think these) and he just rotates them through .
Why do t we mention Mike Ashley being under attach by Shein ? I think he’s a step ahead of them or at least a worthy combatant not scared to put his kahunas on the line against the Chinese invaders .(even though he makes most stuff in China !)
I heard a story about a “rebate tax” that all Chinese companies got from their government for export meaning they could trade at breakeven / a loss then claw it back in rebate tax , apparently when Ashley and co got wind of this they went to China and insisted it was paid to a special account . All total rumours based on Dog and Duck due dilligence .
My point is this market is very much one on the move so agility is going to very key .
Victoria (LON:VCP)
Paul,
Would you consider changing your opinion of VCP to RED?
I vaguely remember that the auditors had resigned because the company refused to give them access to the accounts of a subsidiary. (Edit—I can’t find an RNS stating that they have resigned. Grant Thornton are still listed as auditors on VCP's website.)
Here is what a short-seller has published: https://iceberg-research.com/2022/08/03/victoria-plc-vcp-ln-mites-under-the-rug/
If a fraction of this is true, it would be a brave person who held the shares.
This is from the HY24 report. It is the only mention of the auditors: Shareholders can be assured that the Board immediately moved to comprehensively address the items set out in the audit report and have allocated additional experienced finance resources to the small (1.25% of Group revenue) subsidiary that has been the focus of all the attention and audit qualification.
From AN (Alliance News) 29.ix.23: Auditor Grant Thornton UK LLP identified "risk factors of fraud" as it handed its qualified opinion.
I would say a lot of the stories are around the company are sensational journalism at best especially from the and Financial Times that just seemed to correspond with the shorting attacks.
All the explanations given by the company in defence sounded perfectly reasonable to me.https://www.londonstockexchang... The bones were that "inadequate accounting records associated with no more than £400,000 of customer receipts." This was referring to a very small private company purchase. As i am led to believe many private companies have poor accounts and are not suitable for PLC audit and need a fair bit of bashing into shape.
I am just trying to get a bit of perspective here but the auditor Grant Thornton can be excused for being a bit twitchy after the fine work of auditing Patisserie Vallerie.
Don't get me wrong VCP is struggling with an immense amount of debt and I disagree with the share buy back which I hope is more a threat to shorters. But they are doing a good few things right.
Debt issued in bonds not up until 2026 was a clever move.
Very good consolidation of uk manufacturers of carpet/underlay and the Balta Group NV(Belgium factory sold off and now manufactured from existing plant in uk) that now integrates with their own purpose built distribution centre and transport.
Wholesale and online distribution in America has opened up a good market for Spanish and Italian ceramic businesses.
Hi Laurie,
To be fair, we've been highly sceptical about Victoria (LON:VCP) here for a long while, due to excessive debt, huge adjustments to the accounts, awful bal sheet.
I wish people would read all our articles carefully, and look for the detail & nuance. We don't make simplistic judgements, we cover all angles I think.
Thanks, Paul.
Sorry, not a small stock but Aviva (LON:AV.) Can you help?
So in the statement at the finals, they said "We know the importance of a sustainable dividend for shareholders, and in recognition of the group's strong prospects, we have also upgraded our dividend guidance to mid-single digit growth in the cash cost (from low-to-mid single digit previously)"
Mid-single digit, say 5%.
So if the number of shares in issue stayed the same the dividend would rise by say, 5%. From 33.4p to 35.07p.
But they are buying back £300m of shares and expect to complete by the end of June 2024. A share reduction of about 2%. So the 5% increase in the cash dividend, will be paid to 2% fewer shares. So roughly a 7% increase per share. About 35.7p
The current forecasts on Stocko are for 34.5p of dividend for 2024 and seem to have gone down over the last month.
But I think that this, at todays price, is yielding just short of 7.5%.
Am i wrong?
Chris
Wouldn't it be just a 2% increase to the 5% i.e. about 5.1% ?
Chris
The promise of future dividend increases in mid single % digits, applies whether or not they are buying back shares. The dividend data site is excellent for dividends. Here’s the link for Aviva (LON:AV.)
https://www.dividenddata.co.uk....
Indeed Ken, so 5% more cash on 2% less shares... 7% per share increase, n'est pas?
They explicitly did NOT say a per share increase but a total cash payment.
No; it does not mean therefore a 7% increase in the Aviva (LON:AV.) dividend.
This is the relevant bit from their Results update:-
“We know the importance of a sustainable dividend for shareholders, and in recognition of the group's strong prospects, we have also upgraded our dividend guidance to mid-single digit growth in the cash cost (from low-to-mid single digit previously)9.”
Aviva will decide just how much when deciding the level of the next dividend. “Mid single digit” provides a bit of flexibility when AVIVA are deciding the exact amount of the next dividend.
Far more important is the promise itself! I.e further dividend increases on top of an already very generous dividend.
GYM (LON:GYM) (I just bought)
I know Paul & Graham don't like this company but i'm impressed by these results and have subsequently this morning been relocating Shoe Zone (LON:SHOE) funds into GYM (LON:GYM)
Headline eps numbers are a distraction here, it's the free cash flow of £27m pa that attracts me. This is a self funded roll out with targeted ROCE of 30%. Debt has been paid down down to a manageable 1.7 times and I think that's ok. If debt is paid down further even better, if interest rates are cut in the next 18 months better still.
But they are a growth business and between them and Pure Gym they have the budget gym market sewn up, a nice oligopoly.
And budget gym revenues are sticky, young people prioritise gym membership over and above other discretionary spending, it's very much a way of life. Also it's cheap, we are talking circa £20 a month, that leaves plenty of headroom for price increases down the line.
Eventually the roll out slows down and these 'sunk cost' automated businesses can turn that cash flow into chunky dividends. I had a similar experience with Ten Entertainment & MEGP and now think Gym can do the same thing.
Any other Gym fans out there? As a new shareholder i would welcome your opinions, thanks.
Great to hear a polite and well-explained different take on things from you Burnt Onions, thanks for posting your views on GYM (LON:GYM)
GYM (LON:GYM)
Any other Gym fans out there? As a new shareholder i would welcome your opinions, thanks.
I think this is a tricky one to value - i used to own back in the day well before the company hit the rocks , i sold as it wasnt really hitting te targets they had set themselves for one rerason or another (growing pains?) - i did always think it would probably come good one day. If they have now passed the point of peak investment so that cash profits are greater than real profits then perhaps te point at which the market will sit up and take notice. Note they still kinda need to be delivering real profit too long term - albeit i would expect ongoing capital expenditure to be reasonably manageable.
ref your quoted £27 mill metric of cashflow - note it does like there may be some one off windfalls in here - the working capital positive number is £5 mill this year but was £5 mill negative prior year - so perhaps £22 mill is a more realistic figure perhaps if you ignore the working capital postive swing this year ?
Free cash flow generated in the year was £27.0m (2022: £16.7m). The increase year on year is largely driven by improved working capital, including an increased uptake of pay-up-front and student products and the normalisation of rent payments.
if we take market cap of £195 mill - its under 10 times £22 mill pa - so i can see the attraction here if i have missed nothing.
Call me slightly old school though but i do prefer companeis to be returning profits - albeit with the depreciation amortisation charges being so chunky perhaps thast ignoring the real world that the ongoing cash costs should be less than what is hitting te profit and loss.
One annoyance is that this company like some others mixes up lease adjustments in fianace costs - for my sanity i always preume i might be mising something on these companies when i take quick dive. Is the reality that some of the rent paid shows up as finance costs here ?
GYM (LON:GYM)
I also think free cash flow was actually lower than the published figure after accounting for maintenance capex and working capital movements - c£17m by my reckoning.
---
I did also wonder if Maintenance Capex was kept low in FY23 as in H2 it was only £1.7m vs £7.0m in H1 - that's quite a difference and I would expect it to be relatively constant.
This amounted to 4.3% of FY23 revenues, which is below the 5-6% the company is forecasting for FY24.
---
I think it's also important to factor in the non-lease net debt of £66.4m. This gives me a current EV of £276m, and a resultant EV/FCF multiple of x16.
This is too high for me sadly as I'm wary of the future cash generation if Maintenance Capex is indeed expected to be materially higher going forward.
A
Hi Abtan, no it's definitely £27m of free cash flow after maintenance capex of circa £10m. Going forward maintenance capex is 6% of revenues, which seems about right. Debt of £66m expected to be modestly lower by year end as all the cash is going into new sites.
GYM (LON:GYM) Thanks rmillaree, yes your point regarding cash flow and one off working capital improvement was addressed in the webinar (just watched).
They said that because of that fact free cash flow is likely to remain flat year on year at £27m but then continue to grow from that base level for future years.
It was a really good webinar, they clearly have a plan and plenty of runway.
One interesting takeaway is their memberships are on average £2 a month cheaper than Pure Gym's and they want to carefully close this gap and thus improve their yield. A £1 pcm increase per member increases revenues by approximately £10m and that all falls to the bottom line. Nice!
Very interesting presentation by IP Group on Investor Meet this morning. Well worth a look if not seen already. A UK Company investing in early stage companies across three sectors. Not all UK companies, presentation given by Hysata Oz co. IP has a big discount to asset value could offer some investors a way to this part of the market. Do your own research. I am NOT an owner at this stage but intend to buy in after the flux from todays results and presentation has disappeared.
ReShoe Zone (LON:SHOE) I suspect that many on here who were badly burnt by Boohoo (LON:BOO) will be very reluctant to invest in yet another company trying to compete with the damn cutthroat Chinese
We should be making the Chinese worry about stamping out their illegal, unfair competition with us instead of us worrying about what their DTC sales will do to our companies, such as Shoe Zone (LON:SHOE) . When are govts going to wake up & realise that the Chinese Communist Party is our strategic enemy & China is trying to weaken & undermine the West. They don't play by the rules. Govt needs to protect our industries now, and we as consumers need to stop buying from companies like Shein, and stop investing in China. Do you think the CCP would allow any Western co an unfair competitive advantage in China ? Of course not. Govts are finally slowly waking up to threat, eg. tentative steps to put up trade barriers against deluge of cheap Chinese EV's that are on their way to flood our markets. Our naivety baffles me.
Re BOOHOO v SHOEZONE
I thought that the strategy of Boohoo was to manufacture in the UK using fast turnarounds to match changes in fashion. The selling point was that containers of clothes coming from China didn’t have this responsiveness. It would appear that this didn’t work as planned.
The difference is that Shoezone apparently manufacture in China and import. The threat here is that the China imports come via a different route other than Shoezone.
Do Shoezone sell a lot of slippers in the Autumn/Winter season? Thats one product I can definitely see people buying from Temu etc as size isnt quite so important.
RE Shoezone
I guess the question that you are asking is will customers buy non casual fit online or would they want to try on the product beforehand? I personally would want to try a pair of regular shoes on and suspect that many people are the same.
However, I was struck by an industry report back in October 2023 which stated that Shoezones digital revenue now accounted for 18.7% of group revenue. I would doubt that these are all slippers.
https://fashionunited.uk/news/...
I would agree with Paul Scott’s analysis of the threat here. This 18.7% could easily be eroded by much bigger competition from China
Any tax on Chinese imports would probably hurt Shoezone as much as a direct supplier. It also worth noting that any such import levy would also probably damage the likes of B&M European Value Retail SA (LON:BME) and many more. Not going to happen in my view.
Model 1 : Design in the UK, place bulk order from China. Months of lead time, huge quantities. This is the traditional fashion retailer model. Primark for example.
Model 2: Design in the UK, small batch production in the UK. Days/weeks to shelf. Repeat if demand is strong. This was the early Boohoo model.
Model 2a: Same as above, except the last step, to then place a big order from China or elsewhere, long leadtime. Need to make a big order.
Model 3: Design in China, manufactured in China. Sold DTC to UK customers. Shipped via airpost. No 20% VAT to pay for consumer. Medium lead time, but still shorter than Model 2a. This is the Shein and Temu model.
Model 3's big downside is that the quality is very variable, and likely very poor governance on chemicals and provenance of raw materials. There is also no easy returns. However, the UK value consumer is lapping it up, as long as its cheap.
Now, there will be an equilibrium. Not everyone in the UK wants Shein or Temu. Boohoo (LON:BOO) will just need to find their niche. They will not be able to cater to the "cheap as chips" value end of the market anymore.
Model 3, returns are very easy, you don't need to return, they just give you a refund. Many products you see on ebay or FB or some Amazon sellers, are from Temu, but the prices are much higher.
Hi Caper4,
You're absolutely spot-on, re Boohoo (LON:BOO) bull case being destroyed by Chinese direct to consumer competition. Practically everyone missed that, including me. All the other bear points on BOO were just background noise, it's Shein that wiped out BOO's profit margin. I can only recall one investor warning me about that, and like a fool I ignored him!
Hence why I'm very alert to this danger for other UK retailers that basically just import cheap Chinese products and sell it on at juicy gross margins. You could argue they're unnecessary intermediaries, and Chinese competitors don't seem to worry about making any profits whilst they destroy the competition.
Also have you seen how much advertising Temu are doing? OK they've probably embedded a cookie on my computer, saying I've bought things from them before, so I get Temu ads on everything now where I have ad blocker disabled - eg this one today - shoes!
Temu offers low prices for a variety of reasons. Firstly, it makes a loss because it is playing a long game in order to destroy the competition. Secondly, a lot of its products are knock off copies, Thirdly, the quality of products is often low because they are cheaply made, sometimes made by slave labour according to observers.. They also exploit a tax loophole which means they pay no import duty as items are sold in small value orders. Lastly, China subsidises its businesses either directly or by paying employers to increase wages in response to worker demands so the employer avoids having to increase prices.
The West is under economic attack from China, which is intent on capturing markets by outcompeting incumbent businesses. Every item we buy from Shein, TEMU et al is another death by a thousand cuts for good businesses in the West.
This article is one of many which explains how TEMU keeps prices so low.
https://www.zdnet.com/article/...
"Practically everyone missed that, including me. All the other bear points on BOO were just background noise, it's Shein that wiped out BOO's profit margin"
I don't think it's a stretch to describe Boohoo (LON:BOO) as a low margin, over valued e-commerce retailer (PE 70ish June 20), with no discernible moat.
It was for these reasons that it was so vulnerable. If it wasn't Shein it would have been someone else imo. Other clothing retailers with more robust business models (Next, M&S, Shoezone etc) have thrived over the same period.
Many argued at the time in this forum (shout out to Mojo) that as an investment it was an accident waiting to happen which proved to be the case.
Hi Kouremenous,
Re Boohoo (LON:BOO) a few years ago, you said -
"Many argued at the time in this forum (shout out to Mojo) that as an investment it was an accident waiting to happen which proved to be the case."
That's true, but my point is that the bears here on BOO a few years ago all got the reasons completely wrong, which makes them lucky, not correct!
BOO went wrong for reasons that I don't recall anybody here spotting - erosion of margins from Shein being the main one. All the other reasons people were bearish turned out to be complete red herrings - eg corporate governance, poor standards in UK factories, etc.
I recall posting many times, showing that BOO was on a PER of 20x, and had sector-leading margins, and revenue/profit graphs that were 45o upward sloping from left to right. So it wasn't overpriced at all, the valuation was attractive, and the bull case made complete sense at the time a couple of years ago.
What also went wrong is that many people (including me) assumed the growth in 2021 was structural, when actually it was a pandemic online sales boom when people had nothing else to spend their money on. Sounds so obvious now, but of course none of the companies themselves said this.
It's important to draw the right conclusions from share ideas that go badly wrong. What went wrong with BOO, and the whole sector, is that Shein killed it. Nobody here saw that coming.
What it's taught me in particular, is that I don't know enough about the fashion sector any more, as my retail experience is now 25+ years out of date. Everything has changed, and brands come and go much faster than in the past, and the Chinese direct to consumer issue really, really worries me. Hence why I'm just not interested in buying any shares in this sector any more. Asos could easily end up bust, and BOO is likely to survive, but I don't think it will ever regain previous profit margins. Many smaller me-too competitors have disappeared.
We could be about to see the impact of Chinese competition in electric cars, with apparently 21 new brands about to hit UK & European markets. I noticed one Ora I think it's called, with a goofy looking, but cheap, EV are sponsoring a big ITV show. Could be a nice fillip for ITV and other advertising sector companies, as they make money from China destroying European industry over the next few years.
Regards, Paul.
RE BOOHOO
That's true, but my point is that the bears here on BOO a few years ago all got the reasons completely wrong, which makes them lucky, not correct!
I would agree with Kouremeneous, the investment case for Boohoo had been damaged long before the arrival of Shein.
If anyone wishes to determine this for themselves all they need to do is click on the Boohoo stock report and look at the historical discussions. The arguments against are well reasoned but tended to be dwarfed by the exuberance of holders.
I personally thought that the very heavy director selling in 2019 was a good cue for holders to exit. This would have been a logical (not lucky) bear reason to sell.
Investors posting a bearish view on Stockopedia tend to be polite and respectful to holders. They make the bear point and then leave the argument. It is easy to overlook their contribution but it does not make it less relevant.
Very valid points in your post on Boohoo (LON:BOO)
Many many logical points at the time nothing to do with Shein. Unfortunately the holders did not want to accept them.
Sad to read though that even now they don’t!
Hi Paul,
The psychology of investment decisions fascinates me - what really drives us to buy, hold or sell a stock at a particular time. I think most of us like to think that we are our rational and our ability to analyse companies, crunch the numbers etc will optimise returns.
Conversely, I feel my most significant realisation on my investment 'journey' was when I realised how irrational I actually was, and understand (some of the time!) how I would oscillate between fear and greed when making decisions (both equally bad in my experience).
You believe the Boo bears were "lucky, not correct" as their reasoning was wrong. I completely disagree with that view. 2 opposing views is what makes a market after all :-)
If in doubt, lets consultant the Oracle (Warren Buffett 1995);
"We're trying to find a business with a wide and long-lasting moat around it, surround -- protecting a terrific economic castle with an honest lord in charge of the castle."
IMO BooHoo failed on both these counts.
Their low margin model; making cheap, poor quality clothes in the UK, selling them over the internet and shipping them around the world was fundamentally floored - where's the moat?
UK production costs are higher - so the threat from a competitor in China, Vietnam etc was always there. All the 'red herrings' as you describe them around corporate governance, poor standards in UK factories, poor US distribution facilities etc. were Red flags.
Boo were making these short cuts in a desperate attempt to sustain a higher cost floored business model.
As for "an honest lord in charge of the castle" - does that sound like Mahmud Kamani? My personal favourite was a £200m share raise to buy PLT from his son in May 2020 for £269.8m - no conflict or vested interest there surely? ;-)
On a personal level I called this right, and and I don't believe I was lucky, as there were numerous red flags long before Shein really kicked in. Just for balance I came completely unstuck / irrational at a similar time with Reach (LON:RCH. Having bought at the lows in 2020, it 6 bagged and then I gave a huge chunk of the profits back irrationally believing the UK google story (I recall that at the time you were, correctly, a bear on Reach)
What an idiot! :-)
Very well explained the fall of Boohoo (LON:BOO) . Obviously nothing to do with what Paul is saying. Just an overpriced bad business!
All the best
The question now is whether there is a pathway for Boohoo (LON:BOO) , and also by extension ASOS (LON:ASC) the other big online fashion retailer.... whether they can both find a way back a stable share of the market and sustained profits.
I wrote a longer article on my Substack, but the TD;LR version of it is that I think they are too challenged on four fronts, to be able to find a pathway:
I think had a think of what the successful online players are doing well - and think it is down to having a good Brand, and selling higher quality products. Think the likes of Next (LON:NXT) and maybe Marks and Spencer (LON:MKS) and Sosandar (LON:SOS) .
You then look at Matches Fashion, which Frasers gave up after a few short months; because it doesn't have a strong Brand.
Sosandar is interesting, if only because if they pull off and create a strong Brand (with high awareness and consideration) then it can be an online "winner" and flourish. However, this is an unknown as Sosandar doesn't talk much about its Brand marketing investments, or marketing investments in general. At least not in the last HY reports.
So this is where I have a problem - comparing two different business models and drawing the same conclusion. Shoe Zone (LON:SHOE) and Boohoo (LON:BOO) are very different beasts and the woes of the latter cannot be triangulated across to Shoe Zone (LON:SHOE) in glib fashion.
Shoe Zone (LON:SHOE) basically rely on stores with an omnichannel online offering. That online offering is designed for two things (1) people who have bought from Shoe Zone (LON:SHOE) before can order new shoes online without visiting a shop because they already know the fit that comes with the shoe supplier. This is important because almost every shoe manufacturer has a different fit. (2) Allows for online buyers to purchase online and click/collect or return. That drives traffic to the shops.
The Boohoo (LON:BOO) model was the complete reverse of this. Temu and Shein are also the reverse of this. So Whilst Shein directly competed against Boohoo (LON:BOO) on business model only offering cheaper, unprofitable clothes made with zero regard to ESG or working conditions they don;t directly compete with Shoe Zone (LON:SHOE) because they don’t have shops of franchises.
So the question around competition is very different. The question that should be asked is whether the public can be persuaded to buy their cheaper shoes online in future or whether physical presence is important. Shoe Zone (LON:SHOE) take the view that the latter is vital - people want to shop but in a slightly different format (hence the big box strategy with an online omnichannel offering). Shein & Temu think they can persuade people to buy some of their shoes online……but how many?
I hold Shoe Zone (LON:SHOE) and I’m mulling over my position. Gives a 15p divi tomorrow and looks cheap now on 23p reduced eps. I suspect broker has deliberately overplayed on a 9% reduction to give wiggle room for no more warnings and leave room for an upgrade later in the year (but that is just my suspicion). On the other hand it has lost some of its momentum and I need to see where the new growth is planned to come from. Again I suspect that of the 4 reasons given for reduction I only really buy a lower than expected demand in late autumn season. Now, given that I think consumers are likely to have more money in their pockets later this year and increasing confidence I wonder whether that may provide an opportunity for better sales but that’s uncertain. Holding for a strong divi alone isn’t worth it. I’d buy Liontrust Asset Management (LON:LIO) for that in an ISA. So on balance I’m minded to hold but not entirely sure,
Shoe Zone (LON:SHOE) Hi David, your last paragraph here on Shoe is spot on. I have held since 2021 and its been a fabulous ride but I fear momentum has been lost and have subsequently sold most of them.
Analysts have historically always been steered lower by management here, so again I think you're right re future upgrades and I also think of all the reasons given for the warnings only 'lower demand' holds and that is why I have sold.
But the 15p dividend would have been nice.....
Not a word we should be using here in reply to other well-reasoned views.
Not meant rudely Paul - rather in the context of easy to throw out as a direct read across when it’s really not. Probably the wrong word - not intended as inflammatory, more a pun on the word fashion, which you might well say was rather glib of me in its own right!!! Apols………
Anyway, I understand the competition concern from Shein & Temu but I think the relevance of that competition is one of whether consumer behaviour switches increasingly online or not. If you believe it will then undoubtedly that competition becomes real. If not then it’s largely an irrelevance. I’m more in the latter camp as I think omnichannel with strong physical presence is where the consumer is going and is particularly relevant to the likes of harder to fit items like shoes. That doesn’t mean I’m right ofc and maybe that behaviour does shift but I don’t think we should be comparing two very different business models and applying the same logic to both.
"I’d buy Liontrust Asset Management (LON:LIO) for that in an ISA"
Thanks for your many insights on many companies, always interesting and good to read, and much appreciated. I have read your well reasoned arguments which have helped me decide to sell Boohoo (LON:BOO) today at a 83% loss. The funds released have gone into buying Liontrust Asset Management (LON:LIO)
Edit: Should have added that Liontrust was already on my watchlist, and yes, fully agree on not investing based on recommendations on this forum.
Remember always do your own research. Everyone’s portfolio and risk appetite is different, so what’s good for one isn’t necessarily good for another. We all share insights on here in a closed forum, which I find valuable whether I agree with them or not as it helps me with my own logic, but anything anyone says should always be treated with caution. I know there is a disclaimer that nothing on here should be treated as a recommendation but it really is true.
I still hold a few Boohoo (LON:BOO) to remind me of the slap I should take for having bought them in the first place and failed to let go further up when the competition became obvious :-)
Keywords Studios (LON:KWS) Youd think with the share price hanging around the lows there would be some nasties in the outlook statement but looks OK to me, be interesting to see what Paul makes of the numbers. Sounding pretty bullish, maybe H2 weighted?
"We expect to deliver strong revenue and profit growth and further extend our market leadership position in 2024."
Good long term performer. EPS growth isnt the fantastic 40%+ previously so it doesnt deserve such a high rating but could argue its overshot to the downside.
Keywords Studios (LON:KWS)
even after todays jump shares are still only half of their peak price - perhaps that peak price was slightly over enthusiastic at the time? but the revenue growth of this company has been pretty impressive over the years i must say (ok not all organic!) . Plenty of adjustments in accounts that leave it to the reader to work out what they think the real underlying level of profitability is here , must admit i have taken an initial holding here today as the outlook looks sufficiently confident , although i suspect they now have tailwinds rather than headwinds with the holywood strikes being in the rear view mirror.
Macfarlane (LON:MACF) Acquisition and ‘stealth profit upgrade’ (I hold)
Macfarlane management continues their long record of exceptional(ly good) acquisitions, buying Bury St Edmunds based Allpack protective packaging distributor for £2.5m (before cash adjustment of around £1.8m).
In 2023 Allpack turned over £3m and pre-tax profits of £0.6m, Macfarlane is paying around 4.2x pre-tax profits.
Allpack’s pre-tax margin is 20% (triple Macfarlane) Looks to be another good buy?
Allpack has 10 employees, including 3 directors, all of whom will stay with the company. Another hallmark of Macfarlane acquisitions is that the management stay with the company ( something that Charlie Munger focused upon) and have agreed an earn-out of £0.75m on further agreed growth targets in 2024.
The RNS says nothing about management expectations for 2024. Management has a track record of caution, under-promising and over-delivering. Current consensus forecasts for Macfarlane (LON:MACF) fell on the recent results and expectations look to be essentially flat, or slightly down YoY, taking into account full year contributions from the 3 acquisitions in 2023, let alone the stop on pension payments. Assumes that there is no sales recovery in 2024 in the market sectors that the company serves.
On top of that there looks to be nothing in the forecasts for acquisitions in 2024 and the company makes 2 or 3 acquisitions on average. I’d expect consensus forecasts to rise on today’s quality acquisition? Very helpfully Shore Capital (house broker) has already released a note and upgrades profits in a stealth profit upgrade (note is free on Research Tree) which upgrades management expectations by the backdoor?
Shore Capital has raised FY24 (adj) profit to 12.5p which puts the shares on 10.3x this mornings 129p. Which doesn’t look cheap compared with other bargains around today? And the Stocko algorithms have signficantly demoted the share on both quality and stockrank to 84.
Macfarlane (LON:MACF) is not going to be exciting nor an over-night multi-bagger, it's more of a quality compounder? Profits have steadily increased profits YoY despite the events of the last few years, and with likely further bolt-on acquisitions in H2 even a slight economic recovery in its markets will create significant tailwinds. Of course I don't know when that will happen but I expect further progress in 2024.
Cheers
Mark ( held MACF for 20 years, though I hold a lot more now, and expect the best is yet to come).
Thanks Mark, smashing write-up on Macfarlane (LON:MACF)
I agree with you, that MACF is a good quality buy & build group, that is not getting credit from the market for its successful growth strategy. Although 2024 YTD it seems to be gaining some traction, and is still reasonably priced I think -
[expand image by right-clicking and view in new tab, if you wish]
I liked the update on 29/2/2024, which I've summarised on my SCVR spreadsheet as "in line results. Confident in outlook. Very reasonable valuation, cheap".
It will be interesting to see if the current positive share price holds, or if it fizzles out as people bank the gains?
Today's acquisition news looks nice, but was too small for it to get onto our agenda, so I appreciate you posting a nice detailed refresher on MACF, we love it when readers post this kind of comment - high quality, detailed, well-researched stuff, thank you! :-)
Best wishes, Paul.
Thank you Paul, very kind words and much appreciated. You're very welcome! Very happy to contribute where I have knowledge and I remain in awe of the amount, quality and knowledge that Graham, Roland and yourself contribute daily!
cheers
Mark
Hi Mark, thanks for the excellent write-up on Macfarlane (LON:MACF) . I've had this on my watchlist for over five years and hovvered over the Buy button a couple of times when the shares were 85p. I regret not buying, especially when I look at a few companies in my portfolio which have gone South in the past few years, though the dividends are a small comfort!
The main thing holding me back about buying Macfarlane shares is the Net Debt figure on the Stockreport. It almost tripled between 2018/19 and has remained fairly stable since then. I'm not capable enough when reading the Accounts to know whether this is anything to be concerned about. As a successful long-term holder, do you have a view on this please? I've been following Jim Slater's Zulu Principle criteria for years and I normally try to avoid companies with large amounts of debt.
Regards,
Martin
Hi Martin,
You need to be very careful with net debt on the Stockreport. This figure includes lease liabilities (effectively future rent that will be payable over the outstanding terms of leased properties). Whilst this is consistent with current - stupid - accounting rules, it results in a nonsensical net debt figure for any company like Macfarlane, with a substantial leased property portfolio.
In reality, Macfarlane (LON:MACF) do not have net debt at their latest year-end, they have £7.2m of bank borrowings and £7.7m of cash, giving net cash of £0.5m. They periodically dip into net debt as they use borrowings to fund bolt-on acquisitions, but they are good cash generators and these net debt positions quickly reverse.
Although the Stockreports are useful as a quick, one-stop summary of a share, their contents need to be treated with suspicion, and there is no substitute to going back to the source material to get a proper understanding of the numbers.
Hi Effortless Cool. Many thanks for your reply. I must learn how to read the accounts properly and not take the simple approach of merely looking at the Stockreports and making decisions based on the bare figures. I have just been listening to Macfarlane's (LON:MACF) Full Year results presentation on the Investor Meet Company website (5th March) and was very impressed.
Thanks again.
Any holders of Advanced Medical Solutions (LON:AMS) ?
I know next to nothing about it but looks an interesting acquisition of Peters Surgical, and outlook comments sound positive. Q1 started strongly.
Never mind British ISAs, If there's one thing Id change for private investors it would be for every listed company to provide broker coverage to everyone. Absolute pain not being able to see updates.
Advanced Medical Solutions (LON:AMS) acquisition doesn't seem like stunning value on the surface. 14x EBITDA, just 4% organic growth forecast. Driven a truck through their perfect balance sheet for a high single digit boost to 2025 EPS. Agreed about broker coverage
Possibly, but it is the commercial synergies they are buying, not the growth. But I feel there may have been a defensive motivation as well; if Peters was for sale they might have not wanted someone else buying it. Advanced Medical Solutions (LON:AMS) has a good track record on acquisitions. I hold.
Metro Bank Holdings (LON:MTRO) have released results.
They have made a statutory profit yet a underlying loss, albeit reduced.
Regarding Shoe Zone (LON:SHOE) , plenty of people (including my kids) order trainers online without ever having tried them on, so I don't see why that couldn't extend to regular shoes being ordered online from the likes of Temu.
I would suspect though it's more likely to come down to brand reputation/hype.
If the management were genuinely shocked by the increase in minimum wage (which is positive for many customers, I hope), then they probably haven't heard of Shein/Temu either! I hold SHOE but I sold down a third yesterday, There is something we are not being told?
Centaur Media (LON:CAU)
I hold.
Lots of flowery language in the prelims, but as far as I can tell the overall results look positive. I need to look at the adjustments, but adjusted and statutory operating profits are not a million miles apart. Adjusted diluted eps of 4.2p gives a PE of around 9.5. The dividend is around 4%, plus there is £9.5m of cash, which I assume belongs to the company and not clients, something else to check.
Outlook statement a little cautious and waffles somewhat.
There is value in the business that looks more valuable that the sum of its parts in my view. The Lawyer in particular would I suspect go for a tidy sum to the right buyer. As always time will tell.
Thoughts and observations welcome
Financial highlights
2023 trading:
£m
2023
2022
Statutory revenue
37.3
38.4
Adjusted1 EBITDA margin
26%
21%
Adjusted1 EBITDA
9.7
8.1
Adjusted1 operating profit
7.6
4.9
Statutory operating profit
6.1
3.6
Group statutory profit after taxation
4.9
2.8
Net cash2
9.5
16.0
Ordinary dividend (pence per share)
1.8
1.1
Adjusted1 diluted earnings per share (pence)
4.2
2.6
Jonno
Agree looks ok but I got so bored and annoyed reading the wiffle waffle I’ve ended up jusr selling 1/3 of my holding at 40.8 and 41 .
Was never really intending to hold centaur but at 36p it was very over sold .
Plus any company producing something to encourage “influencers” really needs to get a grip of itself and be slapped with a wet fish .
Thing is with these illiquid shares sometimes the only way to clear shares is on results days so I’ve chopped a few out today .
Held most in my Trading account and not a big fan of having decent yielding shares in there as tax payable on dividend .
Also held in my ISA which I will hold .
Centaur Media (LON:CAU) is a thinly traded £58m market cap FTSE fledging, marketing/media business, 29.8% owned by Harwood Capital. It’s often touted as a break up candidate given its two main businesses, the Lawyer magazine and the 'marketing department support' business have little overlap.
Today it celebrated the successful completion of its MAP23 strategy which has seen adj EBITDA margins double to 25.9%, Revenue from continuing grow 27% and £14.2m of free cash flow generated since 2020.
Centaur Media (LON:CAU) is now a robust, cash generative marketing support and media business focussed on shareholder returns with special dividends and a target pay out ratio of 40% of ‘adjusted retained earnings’.
I think management are justified in celebrating the huge improvements and business turn around during a period when client advertising spend has reduced or been under significant pressure.
Not surprising, Centaur Media (LON:CAU) has had to close the worst affected and least profitable businesses during the period to realise their ‘adj’ based targets. Marketing/media companies are often a patchwork of acquired small businesses with specific capabilities that often come and go out of fashion. So ‘weeding out the weaklings’, especially during a cyclical downturn, is a sign of good stewardship by management.
All that said it does beg the question what next? Singer has trimmed its FY24 revenue and profit forecasts but maintained its target price.
On the one hand cycles pass and there is definitely a case for upside as this cycle passes.
On the other hand, cutting costs and improving margins is an easier task than growing new business.
Across the marketing/advertising sector we’ve seen a range of winners (eg Silver Bullet Data Services (LON:SBDS), System1 (LON:SYS1)) and losers (eg S4 Capital (LON:SFOR), Mirriad Advertising (LON:MIRI)) as the strongest have used AI and new digital offerings to thrive during the sector downturn.
Centaur Media (LON:CAU) will set out their new strategic targets at a capital markets day in late April. It’s not clear what camp they’ll fall into but my concern is that if they had ‘the next great thing’ to hand they’d already be telling us about it. Or do they need to invest in a digital catch up to ensure their courses and events remain relevant?
All in, I suspect this is one for the very patient ‘coffee can holders’ and/or followers of Christopher Mills.
(I do not hold)
"Growth returned in the UK economy in January, according to official figures.
The measure of everything produced in the UK - a metric called gross domestic product (GDP) - rose 0.2%, the Office for National Statistics (ONS) said.
It's the first official economic growth announcement since a recession was declared last month as there were two successive three-month periods of negative economic growth.
When looked at over a three month period, GDP fell 0.1% up to January, compared to the three months to October."
https://news.sky.com/story/uk-...
Nexteq (LON:NXQ) Final results
Revenue down 5%
PBT up 45%
Gross margin 36.3 up 410bps
Net cash $27.9m up 116%
Generating a lot of cash at the moment
"Healthy demand tempered by customer de-stocking, with volume growth in strategic Gaming and Broadcast sectors."
EDIT: EPS only up 2%
Two brokers notes out on Research Tree.
Nexteq (LON:NXQ) - note that adj dil EPS is only up 2%! The PR only sent me the headline that PBT was up 47%, so selective reporting LOL! Net cash up healthily I see. I'll aim to do a section on this company later, if there's time.
Nexteq (LON:NXQ) (I hold, big shout out to Wolfie).
They still look very good value to me.
It's the upward momentum in gross margins, operating margins and ROCE that impressed. The flat top line numbers not so much.
But by FY25 they will have net cash of 1/3 of the current mkt cap so again the free cash flow is impressive.
I think what they decide to do with the cash will determine direction from here but this cash flow generation must offer excellent downside protection.
Just my opinion.
The difference between EPS and PBT is all down to tax (there has been no meaningful increase in the share count in 2023 - nor indeed since the company IPOed in 2013, when the share count was 64.6m. ) In 2022, Nexteq had an unusual positive tax contribution of $2.2m. In 2023, tax returned to its usual negative contribution of $2.0m (implying a 16% tax rate on PBT.)
I hold Nexteq (LON:NXQ) because of the strong cash flow and its history of funding growth out of cash. The Densitron acquisition in 2015 (which finally in 2023 seems to be paying off with strong operating margins) was all for cash and I would expect the current cash pile to be used for another sizeable acquisition in 2024 - this seemed the way management was pointing in the September ImC call.
The main negatives for me are: (1) the lack of topline growth in 2023 (and none forecast for 2024 and today's outlook comment is a bit uninspiring) - although management believe they are in structurally growing markets and (2) even though exposure (customer concentration) to Ainsworth has declined massively since the IPO, still in 2023 the two largest customer’s for the Quixant division accounted for half of that division’s revenues.
My morning smallcap tweet: It's a cash and burn
CAP XX (LON:CPX) Victoria (LON:VCP) Netscientific (LON:NSCI) Electric Guitar (LON:ELEG) Woodbois (LON:WBI) Symphony Environmental Technologies (LON:SYM) IXICO (LON:IXI) OptiBiotix Health (LON:OPTI) Quantum Blockchain Technologies (LON:QBT), GYM (LON:GYM), Musicmagpie (LON:MMAG), Nexteq (LON:NXQ)
◄CAP-XX (CPX)► co requires additional financing by the end of this month. Trying to arrange a fundraise. No wonder the CFO scarpered yesterday. Did co really not have this dire info yesterday? [SP=0.38 Cap=3m]
◄Victoria (VCP)► guides FY-Mar rev broadly in line with market expectations and down YoY. U/L EBITDA nw only c.£160m. De-leveraging update. £25m buyback because SP "materially below the intrinsic value". Chmn says "There has been a lot of noise around Victoria in the last six months". [SP=244 Cap=282m]
◄NetScientific (NSCI)► portfolio update. Strategic objectives for 2024 and beyond. Will implement a "carried interest scheme to incentivise and compensate key Group employees and fund management teams in line with VC industry standards". [SP=67.78 Cap=16m]
◄Electric Guitar (ELEG)► to move from standard listing to AIM in conjunction with the acquisition of 3radical. [SP=2 Cap=1m]
◄Woodbois (WBI)► to sell Mozambique ops because they "have not and cannot contribute meaningfully to Woodbois' profitability." No sum mentioned. [SP=0.74 Cap=29m]
◄Symphony Environmental Technologies (SYM)► wishes to highlight 2021 report from US Environmental Protection Agency on biodegradable plastics. So 3 yr old news is RNSable now! [SP=2.48 Cap=5m]
◄IXICO (IXI)► warns FY-Sept likely to be only £5.2m - £5.9m due to "longer contracting cycles and postponements of certain new contracts". FY25 will be hit too. However overall opportunities pipeline value up ove 50% since Sept 2023. [SP=8.4 Cap=4m]
◄OptiBiotix Health (OPTI)► India's Morepen to sell SlimBiome containing products in India under the Dr Morepen brand. Could boost rev by £6-7m PA in next 4-5 years. [SP=24.2 Cap=22m]
◄Quantum Blockchain Technologies (QBT)► has developed a new method ('C') that uses AI to boost Bitcoin mining. To develop a custom IC using this and other methods. Also "early-stage exploratory discussions with Bitcoin rig manufacturers and US Bitcoin mining companies". [SP=1.5 Cap=22m]
In line: GYM, MMAG, NXQ
Back in 2019, Terry Smith wrote an interesting article in Money Observer. Below are the points I found the most interesting.
Bull markets do not broaden with age: they narrow. The current bull market began in 2009, when shares rose indiscriminately. After 2014 emerging markets stopped rising. Then the US took the lead. Then the technology sector in the US. Then just the big-hitting FAANGs. The idea that in the late stages of a bull market investors can make gains or protect themselves by switching into the stocks that have lagged flies in the face of history.
As for buying so-called value stocks, this is best done after the bear market has struck, not before. If you approached any of the famous value investors and suggested they buy some of the assorted stocks in the FTSE 100 index on a p/e of 15 times as a value play, they would laugh at you. Real value plays, when they emerge in a bear market, involve buying stocks with a yield almost as high as the PE. For example, at the end of 2000 Imperial Tobacco was on a p/e ratio of 8.1 times and had a yield of 6.25%.
https://www.smithson.co.uk/new...
The curious thing is the UK US divide. For example you can buy BAT with a yield over 10%, and many other solid outfits are giving 6% plus in th UK.
Now Imperial Brands (LON:IMB) is on a PE of 5,6 and a yield over 9%
After yesterday's slightly hotter than expected US inflation print (re 3.2%), here's the latest global CPI rankings.
Indeed, China (re property market collapse) is apparently NOT now in deflation.
Also, projected interest rate cuts by central banks continue to be pushed to the right, with bond markets currently forecasting three (or 0.75%) by the end of 2024 for the UK/US, and five over the next 12 months. Ultimately settling down at a neutral level of around 3.5% in 2025.
For those scratching their heads at a bond market shrug and an equity rally ... J Authers as usual has all the good spin... why hot wasn't so hot this time and why the market took it so badly in January. Bloomberg points of return for those who don't know where to find it.
It seems to me inflation isn't quite licked ...and economy is hanging in there... but the longer rates remain high, the problems will emerge. What to do? Well nothings changing really.... Sterling despite all is showing a little life... not much to say yet but a stronger domestic currency will depress overseas returns at a time allocations are at an all time high relative to UK equities. The decoupling hope may still emerge as a valid investment case.