Small Cap Value Report (Wed 13 Nov 2019) - ACSO, IDEA

Good morning, it's Paul here.
Estimated time of completion - about 3pm. Update at 14:28 - I can't find anything interesting to write about, and want to give some support to Ed & the Stockopedia team on the their stand at Mello, so will sign off early for today. Therefore this report is now finished, sorry it's a bit half-arsed.
It was great to chat to many subscribers at yesterday's Mello Investor Show. I'm walking wounded today, so probably won't be going back for seconds today (OK - some time later - retrospectively that didn't work out quite as planned)
accesso Technology (LON:ACSO)
Share price: 590p (up 13% today, at 11:40)
No. shares: 27.6m
Market cap: £162.8m
Further update on the formal sale process
accesso Technology Group plc (AIM: ASCO), the premier technology solutions provider to leisure, entertainment, hospitality, attractions and cultural markets, provides the following update on its announced formal sale process (the "Formal Sale Process") under the City Code on Takeovers and Mergers (the "Code") which remains ongoing.
There's been a 13% bounce in share price today, alleviating some of the suffering for beleaguered shareholders, who've seen their investment drop by about 80% from the peak. Amazingly, in the last year, it's scrubbed off all the previous gains since 2013. Which begs the question, was the surge to almost 3000p share largely a speculative momentum-driven bubble? It looks that way to me.
The sale process seems to still be active, so today's announcement is being seen as having increased the chances of a takeover bid;
Following receipt of a certain number of refreshed indications of interest over the last several months, the Company and its advisers are continuing to engage in discussions with several parties to determine whether a potential offer for the Company can be delivered at a value that the Board considers attractive to shareholders.
The interested parties remain engaged in financial and operational due diligence.
Due diligence normally only occurs when there is serious bid interest. That's because it's expensive to send in teams of accountants & lawyers. Or sometimes, it can be a good excuse for a competitor to run their eyes over the detailed figures that they wouldn't otherwise be able to see.
My opinion - Accesso is extremely difficult (impossible?) to value, because the accounting is unusual. Large amounts of expenditure are capitalised, therefore the EBITDA and arguably profit numbers seem meaningless.
The balance sheet is weak, with NTAV negative, at about -$15m. I don't understand why (mentioned here at the time) when the company had a market cap close to £1bn, that it didn't do a relatively small placing of say £20-40m, to eliminate debt, and make its balance sheet bulletproof. That was a big missed opportunity.
On the positive side, this company does seem to be the market leader globally, in an interesting niche. With a more reasonable market cap of £163m, this could perhaps be a buying opportunity? Why is the company up for sale though? I don't really understand why management is pursuing a sale process at all.
The problem in this situation, is that we are in the dark about what level the expressions of interest are at? I don't like that, because rumours start to swirl, and insider dealing probably occurs. Is this a distressed sale, maybe if the bank is getting jittery? We just don't know. There's always the chance of a bid occurring at a decent premium. Or it may not.
In conclusion then, I just haven't got enough information to form a view on this share. It's tempting to have a little punt on it, in case a bid does happen.
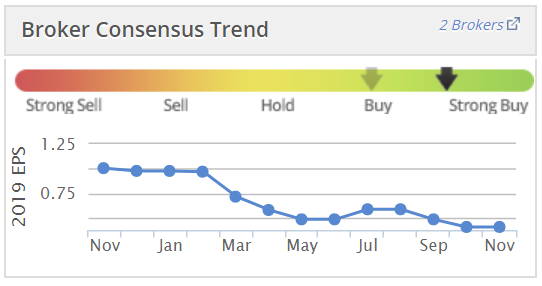
Earnings forecasts have been coming down, so it looks as if underlying trading has not been great;
Another point is that Accesso's former CEO, Tom Burnet, has just been promoted from NED to Chairman at Kainos (LON:KNOS) - which makes me wonder if maybe his interest in ACSO might be waning?
Ideagen (LON:IDEA)
Share price: 153.5p (up c.2% today, at 13:17)
No. shares: 223.6m
Market cap: £343.2m
Ideagen PLC (AIM: IDEA), a leading supplier of Information Management Software to highly regulated industries, today provides an update on trading for the six months ended 31 October 2019.
This company is appearing at Mello today, I understand.
There's a reassuring, upbeat-sounding trading update today;
The Board is pleased to report that trading has remained strong in the first half of the financial year and that revenue and EBITDA are both expected to be significantly ahead of the same period last year and in line with management's expectations.
This has been achieved through both organic revenue growth and the acquisitions of Redland Business Solutions Ltd (acquired in June 2019) and Optima Diagnostics Ltd (acquired in Oct 2019).
The Company has a clear strategy to grow revenues organically and maintain high EBITDA margins whilst transitioning from a perpetual licence to a SaaS based subscription model. The successful execution of this strategy will provide an even more robust business model and a higher quality of earnings over the medium term without impacting on the short-term profitability of the business.
More detail is given, including;
- High level of recurring revenues
- Organic revenue growth of 7% [looks good]
- 240 new customers won
- Net debt risen from £1.3m to £18.2m in last 6 months, due to a £19.8m acquisition
- Operating cashflows "robust"
Outlook comments are upbeat;
Cash generation has been good which coupled with further growth in new SaaS recurring revenues and an increase in repeat business from our growing customer base provides a strong platform for the second half.
The market opportunity remains large and long term and given the Group's position as a leader in the Governance, Risk and Compliance market, the Board is optimistic about the Group's continued growth prospects."
I would have preferred a specific reference to market expectations for the full year.
Valuation - the price reflects good performance, over multiple years. So the forward PER of 23.8 is not cheap, but I think it's justified by strong historic performance.
I had lunch with the Chairman earlier this year, and one thing in particular has stuck in my mind. He said, "We've never missed our forecasts. We always meet or beat market expectations". That is an important point, as it builds confidence amongst investors, and shows that management are properly in control, running the business well, plus forecasting the future accurately.
Bear in mind that the Thompson Reuters data used by Stockopedia reports the statutory figures, not adjusted figures, in order to be consistent in presentation of figures across many companies. Therefore this data format punishes acquisitive groups, because the goodwill amortisation is not adjusted out of the Stockopedia data.
My opinion - this seems to be one of a select group of acquisitive companies that make that strategy work well. Another stand-out performer is Judges Scientific (LON:JDG) which has created huge shareholder value through multiple, low-priced acquisitions.
I'm not keen on the balance sheet, which looks a bit stretched to me. I prefer to see NTAV positive, whereas it's negative at -£17.0m here (as at 30 Apr 2019). Given the high valuation, I think a placing of about £20m would make sense, to eliminate the negative balance sheet, and pay off debt. That would only be about 6% dilution, which is a small price to pay, to correct a stretched balance sheet, and completely eliminate financial risk.
In all other respects though, this share looks good to me.
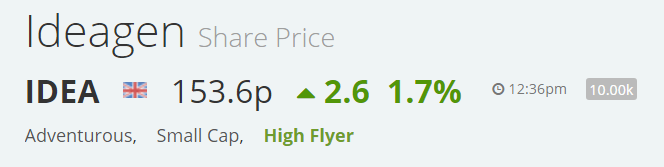
Stockopedia likes it on the "Styles" section, with a High Flyer classification;
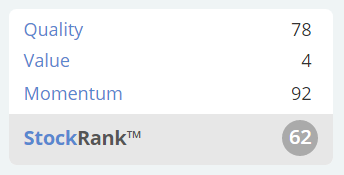
As usual, the StockRank system summarises it well;
That's it for today. See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Ref brewdog (not listed last time i looked) - i always regret never investing in this business back in the day as i think their valuation has since skyrocketed.
anyway they have an a most excellent bond offering for those that like a tipple and a return on their money. Their bond is paying 3% cash and 3% beer returns not bad if you spend your bucks with them- this was a company going places last time i looked so i would guess risk is reasonably low albeit one would need to do further research.
Each BrewDog Bond will cost £500 and the brewery promises “each BrewDog bondholder will receive £20 BrewBucks to spend in the company’s 90+ bars and venues worldwide, a free copy of BrewDog’s book ”Craft Beer for the People”, as well as a free beer on their birthday for every year they are a bondholder”, on top of the interest rate.
Portmeirion (LON:PMP)
Further deterioration for current year with a very late new “material miss” with only 6 weeks of the year left.
They have tried to mitigate the bad news by being optimistic with regard to 2020 - without any firm numbers I am not sure I believe that 2020 numbers will not be downgraded - from here if they can get back to 2018 numbers in 2020 I think that would be best I can hope for with 2019 being a complete w/off. Seems very late in year to be saying what they are saying now seeing as it’s a continuation of issues they knew about. I am sure price will open down - the damage will likely dependent on what 2020 expectednumbers look like with updated broker forecasts.
Process of appointing and waiting for new CEO in September may have caused this late in day notification . I think in profit warning terms it is fixable. But probably as you say more likely in long rather than short term and the broker forecasts will be key
This is a continuation of the South Korean problem first identified by the company 6 months ago (May).
The Portmeirion (LON:PMP) share price is down 42% since this original announcement.
Surprising that investors are still selling on a repeat/continuation of old news.
deleted duplicate
Portmeirion (LON:PMP)
Howard Marx
Surprising that investors are still selling on a repeat/continuation of old news.
I am not surprised at all - this is a further material miss on top of the previously announced bad news. I think the shareprice rebound will only happen when the market knows that 2020 (or later) number forecasts are decent and there is some evidence this is not just wishful thinking from the bods running the company. When sales are lost its always tricky to try and regain ones mojo - sometimes they are simply gone for good. I think if we say £7 mill profit 2020 (thats glass mostly full) 12 times multiple thats 77 mill market cap - thats pretty much where we are. I think the company will need to deliver something above that to see the sharerprice get back to its prior higher levels. I have held onto these against my better judgement i had a sell order in that never got filled when the share price stabilised in the mid 900's silly boy - if it doesnt feel right sell and move on - hopefully the company will regain its mojo quicker that i think may be the case :).
The Portmeirion (LON:PMP) share price has fallen 42% in the last 6 months since the issues in South Korea were first reported.
In 2018 Portmeirion (LON:PMP) achieved £8.2million of revenue in South Korea - this equated to just 9% of group turnover.
Investors have hence arguably over-discounted this trading difficulty.
Surprising that investors are still selling on a repeat/continuation of old news.
I imagine people invested / held on the basis of the brand and the problem being fixable short-term. At least the update today explains the underlying issue - distributors in countries outside South Korea re-selling into SK in competition with the company.
There's an upside and a downside to this. The downside is that sales and demand outside SK may be exaggerated, so prior earnings are probably at least partially overstated. The upside is the demand in SK is still strong, it's just that resellers are taking market share. On balance this isn't too bad - either sales ex-SK are lower margin, so the outside distributors are arbitraging the difference or SK demand is sufficiently strong to warrant higher prices.
The steps being taken - delivering SK only product and better tracking of where distributors are selling to - will turn this round, but it'll take a year, I'd expect. Distribution problems are fixable, with decent management, as long the brand is undamaged.
I remain a holder, will consider adding more when the immediate sell-off has run its course. At these prices it's got to be looking attractive to would-be acquirers.
timarrOk I think it’s thursday now
Norcros (LON:NXR) interims out.
Everything seems a ok here. Pension deficit down again now under £30 mill and capitalised expenditure nicely under control. This company needs to nothing other than tick over and meet expectations for the balance sheet to materially strengthen and de risk the business. I guess we should continue to expect more acquisitions when the time is right let’s hope anything in that direction is not over ambitious.
Talk about revolving boardroom doors triggered by Tim Martin reminds me of a saying of Peter Lynch along the lines of it being best to buy shares in companies that could be run by monkeys because sooner or later they will be!
Ideagen (LON:IDEA) please - the trading update is very positive, with significant growth seen (partly due to acquisition), increased recurring revenue, etc.
£dmjram
The flip side of course is that the board becomes a cosy club dominated by group think. Which is what the governance rules are trying to prevent.
I would 100% agree with these comments too - to me there is the middle ground that can be had in this regard so that a company can be run by experienced bods doing their jobs as long as shareholders are happy with that situation - rather than having forced change just for a tick box. Note J D Wetherspoon (LON:JDW) do have Harry Morley on the board and he i chair of the audit committee and a member of the nomination and remuneration committee he seems fairly independent based on his other board appointments and he has only been on the board since 2016 so it's not the fact that the entire board have been around forever. Perhaps they could do with one extra spot on the board being a spot that would have a fixed term period so that there is a little more real independence.
To me i look at the board and how they are acting and vote accordingly by either staying as shareholder and leaving (my vote will rarely matter in any other respects) - there have been plenty of companies with long term appointments i have shied away from - just look at the joke that is Stobarts and what used to go on there - to me its more about the actions of the board and how they deliver that i want to judge the company by rather than a tickbox dictating to me i must have shiny new bods running the company when i was perfectly happy with what i had.
Surely the essential point of Tim Martin's comments is that the rules specifying maximum length of term for executive board members are not sensible. As an investor, whether wisely or not, I try to look at length of service of the executive directors - if they have been there a long time and the company has been doing well, it suggests good management. What is wrong with cosiness if they are demonstrably running the company well? The time you want to see fresh management is if you are looking at a turnaround situation, or a business stuck in a rut. But there is always an extra risk with new management - there have been some major corporate disasters - take GEC for example.
I tend to agree with this - also cosiness might actually make management more willing to try things - if they know chairman is not going to get rid of them for a mistake (for example)
Would love to have a pint with TM - he comes across as a very interesting fellow and a good egg
Appreciate a view on Renold (LON:RNO) which has been harshly judged (again) this morning, down a further 10% to 19p and now on a downtrend for over 2 years. Personally, I thought the results perhaps showed some longer term company positives in a short term toughening macro-environment?
Topline revenue was down 2.8% and mood music for the near term was cautious/negative (esp in US/Europe) and reported debt was up.
The big issue of pension was much worse with the reported deficit increasing to £111Mn (despite a reported helpful spike in deaths of retirees - its odd what helps !). However, cash cost of payment to pensions gap seems manageable over the timescale involved. The issue of misstatement of accounts (fraud?) in a subsidiary seems to have been fully dealt with.
Positively, cash from from continuing operations (excluding pension costs) was sharply up and non pension debt is only 1.4X EBITDA towards the end of an investment cycle that has consolidated, built or updated factories and a loss making SA business exited (to mgt). Stockranks is 98 on value and Quality should improve going forward as self help plans build and embed.
I hold a scrap to keep abreast of a potential turnaround that sadly remains a losing contrarian bet so far.
Ocean Wilsons Holdings (LON:OCN) please, they have just released their quarterly update. Group revenue is down 7% compared to last year.
J D Wetherspoon (LON:JDW)
IMHO I think there is a difference between using two quotes from someones comments as examples of how this company has a similar ethos of the quoted text and reading the comments as being some Eulogy of the entire business practices of that person being quoted. It is the quoted text Martin is talking about not the man who quoted it. Should we also say he is Eulogising Enid Blyton and Noddy as Noddy also gets a nodding mention in todays comments?
There is a lot of sense and logic in what Tim Martin writes but I totally disagree with his eulogising of Sam Walton:
Sam Walton's number one was always Sam Walton, which is one of the reasons he died so rich. He is a "folk hero" to some but not to many on the receiving end of Walmart's business practices. His legacy lives on: How Retail Employment Is Defined in Courtrooms by Walmart's Ethics
Bonitabeach
My morning smallcap tweet: Bonhill downhill
Bonhill (LON:BONH), accesso Technology (LON:ACSO), Eddie Stobart Logistics (LON:ESL), Integumen (LON:SKIN), Renold (LON:RNO), Ocean Outdoor (LON:OOUT), Velocity Composites (LON:VEL), Ideagen (LON:IDEA)
Bonhill (BONH) guides FY EBITDA £2.5m, materially below market expectations. Blames continued challenging conditions experienced by Last Word Media in the UK and Hong Kong and significant investment to transform its offering. "However the new technology platform and the calibre of the people we have recruited combined with the underlying work in improving our offering puts the Group in a stronger position...£1.5m of cost savings already identified."
Accesso Technology (ACSO) offer talks not dead, continuing to engage in discussions with several parties. I hold.
Eddie Stobart (ESL) offer from proposal from DouglasBay Capital III Fund for 51%. Would form JV with existing holders in exchange for making £55m loan. No consideration menationed. Wincanton still pondering an offer.
Integumen (SKIN) multi-year Framework Agreement with Parity for s/w across Parity's NHS, Central Government and Private Institutional clients. Now guides FY20 rev $4m "excluding developments that may arise from Integumen entering into the agreement with Parity Group". No F/C to compare.
Renold (RNO) H1 weak due to reduction in demand in traditional markets. This trend expected to continue into H2. Cost cutting mean it expects FY 'overall result' in line.
In line: Ocean Outdoor (LON:OOUT), Velocity Composites (LON:VEL), Ideagen (LON:IDEA)
Ienergizer (LON:IBPO) ?
Hi Paul
Not a Small Cap, but this morning's trading update from J D Wetherspoon (LON:JDW) makes very interesting, and entertaining, reading......
Andy
Tim sounds like the kind of guy you could go out for a pint with and not have to say a word all evening, unless you disagree of course.........
Talks a lot of sense on the CG front whilst being entertaining and informative
Steve
Talks a lot of sense on the CG front whilst being entertaining and informative
Yes, he maybe an entertaining old windbag but in his diatribe on Corporate Governance he mentions his best buddy NEDs, himself, his employees, his customers, but not once does he really mention other shareholders in J D Wetherspoon (LON:JDW) - It's like they don't exist, and that's quite telling. But then the Corporate Governance code is their to protect them so it wouldn't really help his argument.
All the best, Si
Luke Johnson is another who enjoys whining about corporate governance, didn't follow it at CAKE and went further than Martin by leaving his shareholders non existent.
J D Wetherspoon (LON:JDW)
simoan
That's not how i read the comments today , to me the whole point about the comments today was talking directly at the main shareholders (who voted neds off the board) and explaining reasonably clearly his view on things and why it is the way it is (governance possibly not strictly speaking being by the book on all measures) - he is obviously upset that the rules that are in place dictate that someone who knows the business well is forced to leave simply due to their having been there x years - and he is saying the rational of why what they do in theory goes against good governance - whilst also pointing out the shareholders voting don't follow the ethos they are voting against. It is plainly ridiculous that Tim Martin should not be Chairman as he has been there over 9 years. I would say having a strong questioning independent NED presence on any board is of preference to me, however i just don't want the board in the company i own to be a revolving door of bods booking a fixed period of easy money then leaving. He mentioned that at the many shareholding meetings he has had corporate governance has never really a problem flagged up by shareholders. Note J D Wetherspoon (LON:JDW) are a fairly investor friendly company - simply fill in the Investor contact form on their website if you have a question and i would be gobsmacked if they didn't respond in full as appropriate.
"he is obviously upset that the rules that are in place dictate that someone who knows the business well is forced to leave simply due to their having been there x years - and he is saying the rational of why what they do in theory goes against good governance"
The flip side of course is that the board becomes a cosy club dominated by group think. Which is what the governance rules are trying to prevent.
None of the NED's seem to have challenged Martin on his political advertising on beer mats which is likely to have influenced the shareholders in removing them.
Hi garbetklb,
Thanks for flagging J D Wetherspoon (LON:JDW) results. I always enjoy his commentary!
Will print that off and read it on the train later, no doubt chuckling away to myself.
Regards, Paul.
Following up on J D Wetherspoon (LON:JDW) trading update.
One sentence mentioned trading.
The rest of it was common-sense commentary from an owner-managed, brilliant, entrepreneurial business. Anyone who can't see that, is crazy, and almost certainly hasn't run a business themselves.
Regards, Paul.