Small Cap Value Report (Wed 13 Sept 2023) - OTB, SUP, EQLS, FDEV, DUKE

Good morning from Paul & Graham!
We have to leave it there for today.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
On Beach group (LON:OTB) - 104p (£173m) - FY 9/2023 Trading Update - Paul - GREEN
A positive sounding update - traded in line for FY 9/2023, but better finance income means PBT at top end of analyst range (but not stated what that range is!). Bookings for winter 2023 and summer 2024 sound well up. Overall, I'm guessing that a 10-20% share price rise could be on the cards here, as the existing forward PER looks much too low at only 7.1 (written before the market opens, so let's hope I don't look an idiot if it goes down!!!)
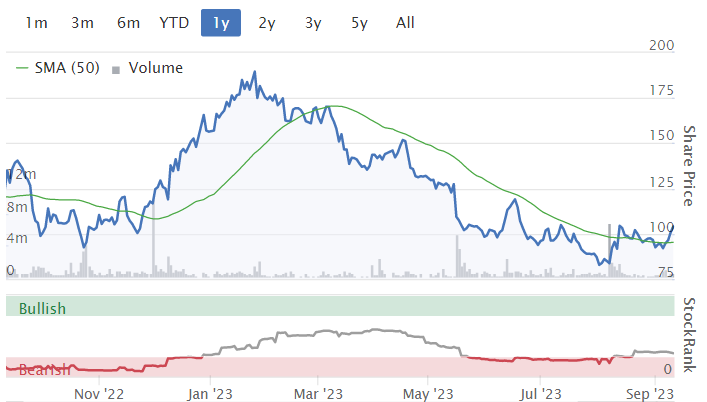
Supreme (LON:SUP) - up 2% to 96p (£112m) - Response to media speculation - Paul - AMBER
This concerns media reports of a possible ban on disposable vaping products. SUP's update doesn't really say a lot, and looks like PR to me, emphasising that vapes can be used as a smoking cessation product. Usefully though, it does confirm current trading remains in line with expectations. Will update on possible impact of disposables ban, when more information is available. I'm sitting on the fence overall, keeping my amber view, as there seems merit in both bull and bear cases.
Equals (LON:EQLS) - up 6% to 113p (£210m) - Interim Results (upgraded estimates) - Graham - AMBER
This fintech company providing services primarily to B2B customers issued strong results and had its full-year estimates upgraded. It also signalled an intention to pay a maiden dividend. I remain neutral but the financials are interesting and it may be worth a closer look.
Frontier Developments (LON:FDEV) - down 1% to 304p (£120m) - FY 5/2023 Results - Paul - AMBER
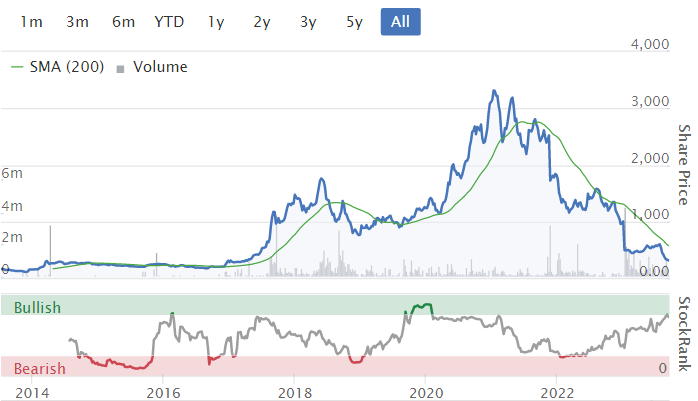
Poor results, but the loss is all due to a non-cash impairment. Just above breakeven excluding that. Balance sheet looks adequate, with a cash buffer that may be adequate. I really dislike this sector - horrible visibility, with large up-front development spend for unknown returns. On the upside, if it can return to former profitability levels, then there might be nice upside from a share price that's down 90% from the early 2021 highs. Probably just for sector experts, and complete punters only!
Duke Royalty (LON:DUKE) - up 3% to 33p (£139m) - Trading Update - Graham - GREEN
Another solid update from Duke, confirming £6m of recurring cash revenues in Q1 and guiding for £6.2m of recurring cash revenues in Q2. I continue to view this one most likely being undervalued at the current level, although it’s still early in its evolution.
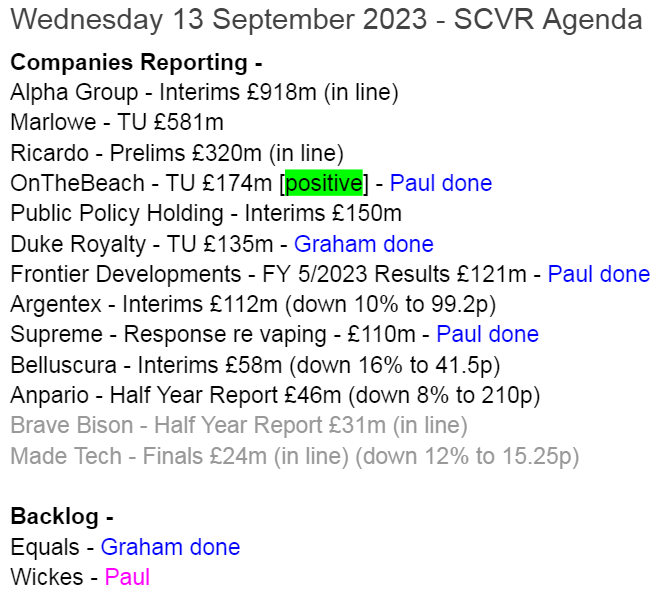
Here's today's list. As usual we'll prioritise ahead/behind updates, so won't cover the in lines unless there's something particularly interesting about them & enough time -
Paul’s Section:
On Beach group (LON:OTB)
104p (£173m) - FY 9/2023 Trading Update - Paul - GREEN
This one caught our eye at 95p on 14 August, when the founder (now a NED) bought £2.5m of shares in the market, which triggered us going GREEN here - Director buys of that size usually happen for a good reason!
On the Beach Group plc (LSE: OTB.L) today provides an update on trading for its financial year ending 30 September 2023 ("FY23"), in advance of announcing its preliminary results on 5 December 2023.
This summary below sounds OK, it’s basically traded in line with expectations, but had a boost from higher than expected interest income on cash balances -

The StockReport shows a forward PER of just 7.1, so to be slightly ahead of that is very pleasing, and could trigger a re-rating from this bombed out PER, I imagine (writing this before the market opens).
Outlook comments - forward bookings (this sounds like passenger numbers, so revenues could benefit beyond these numbers due to price rises, possibly? It’s not entirely clear -
The Group expects Summer 23 passenger numbers to be 11% ahead of Summer 22, with Winter 23 currently 26% ahead of the prior year. Notwithstanding that it remains in its early stages, bookings for Summer 24 are also significantly ahead of the prior year…
Following our strong second half performance we will exit FY23 with the momentum of a record forward order book and demonstrable progress in strategic expansion areas, which we are excited to build upon in FY24."
Paul’s opinion - rushing this out just before 8am, I think this share is likely to put in a nice increase today.
I can’t find any broker notes unfortunately, so it will be interesting to see how much brokers increase forecasts for FY 9/2024? It sounds as if the numbers are likely to be increased, but currently a jump in EPS from forecast 11.5p in FY 9/2023, to 14.8p in FY 9/2024 is already anticipating a considerable improvement.
We’re in the dark re forecasts, but with a positive-sounding update today, I suspect this share is likely to attract buyers. It’s fun to guess! I reckon a 10-20% share price rise today could be on the cards, so a good candidate for an opening bell purchase, possibly?
We also got a good update from midcap Jet2 (LON:JET2) recently. Could this sector be a nice area to find oversold shares? I think it might be. Although given what happened in the pandemic, some investors might want to permanently avoid the travel sector, as we now know it could get completely shut down again at any point if another virus appears. So possibly PERs should be lower than they were historically, given this increased risk?
Supreme (LON:SUP)
Up 2% to 96p (£112m) - Response to media speculation - Paul - AMBER
Supreme comments this morning on media reports of a possible ban on disposable vapes.
My summary of key points -
- Emphasises that its vaping products help people stop smoking.
- Govt formal consultation still taking place.
- Supreme believes that, if banned, users of disposable vapes would switch to other vaping products (which Supreme makes/sells).
- Rechargeable “pod system” set to be launched - better for environment vs disposables.
- Trading in line with market expectations (aEBITDA of £25.6m), FY 3/2024.
- Will do comprehensive review “to measure the impact” of any legislation changes, once clarified.
Paul’s view - it’s difficult to say, but the last point seems to imply there might be some possible downside impact on Supreme from a ban on disposables? Why else use the word “impact”? As mentioned yesterday, the trouble is that the more Supreme is known as a vaping company (it does other things too though), then the more likelihood there is that many investors won’t want to get involved at all. So all this publicity on vaping is probably not helping. Hence a low PER on an ongoing basis seems likely to me, regardless of the financial outcome of the possible ban on disposables. The rest of today’s response from Supreme strikes me as a PR release.
I can see merit in both bull and bear cases, so will remain at AMBER.
Thin end of the wedge, or a buying opportunity?
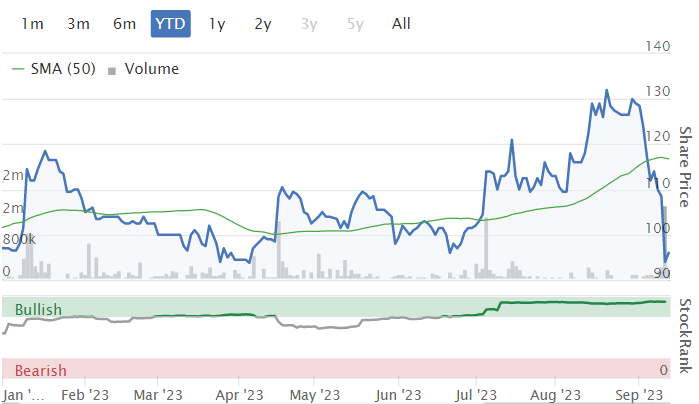
A sea of green for SUP on most of the Stockopedia metrics. That 6% dividend yield looks tempting, now that inflation is coming down, and interest on cash may not be so generous next year, if/when interest rates come down. So locking in 6%+ yields could be a good strategy, possibly? (if they're sustainable) -
Frontier Developments (LON:FDEV)
Down 1% to 304p (£120m) - FY 5/2023 Results - Paul - AMBER
This share came up at Mello Monday this week, as something potentially interesting for us to look at.
Frontier Developments plc (AIM: FDEV, 'Frontier', the 'Company', or the 'Group'), a leading developer and publisher of video games based in Cambridge, UK, publishes its full-year results for the 12 months ended 31 May 2023 ('FY23').
Revenue down 8% to £104.6m
Hefty operating loss of £26.6m, but that includes a £28.7m non-cash impairment charge.
Cash of £24.8m recently, end August 2023, down from £28.3m at May year end.
Outlook -
The Board continues to be comfortable with market expectations for FY24, with consensus revenue at £108 million and consensus Adjusted EBITDA* loss of £9 million.
The Board is confident that the Company can return to attractive levels of financial performance over the medium-term, based on the strength of its existing portfolio and planned new releases, underpinned by the refocusing of its strategy.
* Adjusted EBITDA is earnings before interest, tax, depreciation, and amortisation charges related to game developments and Frontier's game technology, less investments in game developments and Frontier's game technology, and excluding impairment charges, share-based payment charges and other non-cash items.
Balance sheet - seems OK with c.£32m NTAV, including net cash of £28.3m at May 2023.
Strong balance sheets are particularly important with games development companies, because they incur the heavy spending up-front to develop games, then the success/failure of the game has a dramatic impact on the future returns. Hence they need a big cash buffer I think, to tide them over if games flop.
Paul’s opinion - lots of listed games developers floated at high valuations, and have since disappointed, including this one. Is FDEV a bargain now, having fallen c.90% from its peak in early 2021? It might be, but I can’t tell, because it all depends on whether its new releases of games in development are successful or not.
Although I see from its track record, that FDEV has been decently profitable in the past. So it might just be going through a bad patch perhaps? There might be an issue with profitability - eg. tinyBuild (LON:TBLD) flagged that online platforms are being less generous with their payments to games developers.
Anyway, it’s not something I would want to gamble on, because I don’t have any insights into the games, and there’s so little forward visibility that me punting on it would just be complete guesswork.
That said, if FDEV is able to return to prior levels of profitability, then the upside on the shares from this level would probably be considerable.
There was also takeover interest in the sector during the last boom. David Braben has 33%, so effectively controls it. I see Tencent Holdings is the next biggest holder, at 8.6%.
Unless you’re a sector expert, then surely there are better sectors to look at?
I’ll put this in the “don’t know” tray, so AMBER for me. I don’t see anything particularly bad in the numbers though - i.e. insolvency/dilution risk looks quite low at this stage.
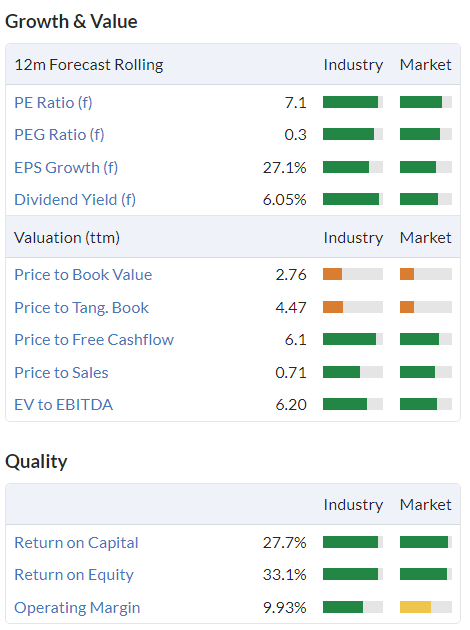
Quite a rollercoaster ride here. Note that the share count has only gone up a little, so theoretically former glories might be achievable, if profitability were to soar again -
Graham's Section:
Equals (LON:EQLS)
Share price: 113p (up 6% yesterday)
Market cap: £210m
This is “the fintech payments group focused on the Enterprise and SME marketplaces”. Its vision is “the simplification of global money movement for business customers”.

It announced interim results (to June) and a trading update yesterday.
Paul Hill also released a Vox interview with the company, which is very helpful.
Here are the interim highlights:
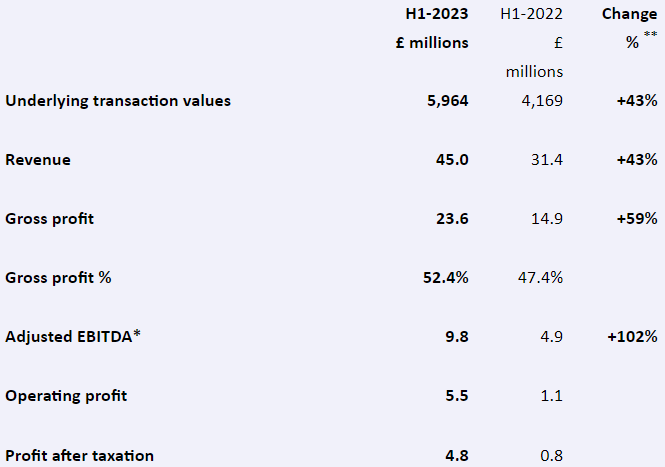
The impressive growth is explained by the CEO in the interview as simply the result of “winning new business all the time… our addressable market is growing… it boils down to winning new new business [sic], particularly the larger end of new new business”.
As we discussed in this report in July, Equals made a small Belgian acquisition which gave it regulatory licences and banking relationships across Europe. The integration of Oonex (“Equals Money Europe”) is “proceeding according to plan”.
CEO comment in the RNS:
"This is an outstanding set of results with record revenues combining with improved gross profit retention to yield enhanced profitability. These results, coupled with our continued cash generation, enable us to announce our intention, conditional, inter alia, upon the completion of the proposed capital reduction, to pay our maiden dividend of 1.5 pence per share in respect of the financial year 2023, while continuing our growth strategy.
Current trading and outlook
This sounds positive:
In Q3 2023 to date, revenues continued to perform strongly reaching £63.6 million on a year-to-date basis as of 8 September 2023. This is 39% ahead of the same period in 2022 and represents revenues per working day of £370k compared to £265k per day in the prior year.
Year-to-date revenue growth (39%) is therefore slightly lower than H1 growth (43%), but hardly a reason for concern.
CFO review breaks down the cost base and illustrates how higher revenues and gross profits were achieved with a cost base that was fixed in many respects, thereby leading to significantly higher profits. The major change in operating costs was staff costs, up from £6.6m to £9.2m.
One other figure in particular stands out to me, in cost of sales: affiliate commissions. Equals finds B2B businesses who will refer their own customers to become Equals customers, paying out large commissions in return.
Note how affiliate commissions dwarf the commissions paid to staff at Equals itself and also the transaction costs associated with providing the services:
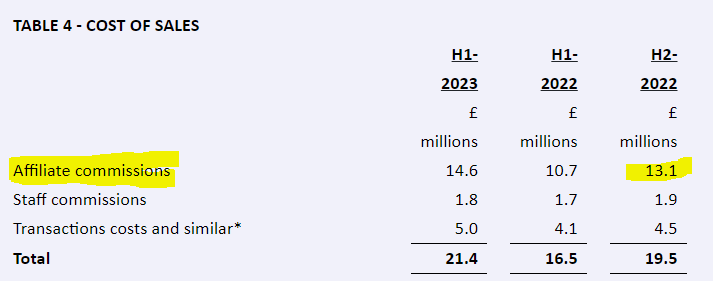
I’m not suggesting that there is anything wrong with this, but it does tell us something important about the business model.
Graham’s view
I’m impressed by the clarity with which the company lays out its amortisation of intangibles, which seems unusually transparent.
Combine that with a quick look at the cash flow statement, where spending on intangibles is not excessive, and the cash performance looks good in the most recent period.
Upgraded estimates at Canaccord see revenues in the current year of £95.5m (previously £88.1m) and PBT of £10.8m (previously £8.1m). As we said back in July, it was sensible for investors to start pricing in upgrades back then, as momentum was clearly very strong and the existing forecasts appeared too conservative at the time.
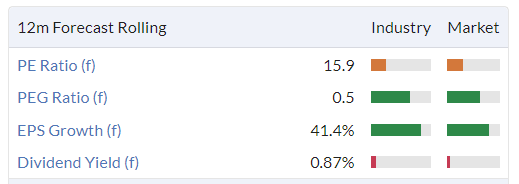
I’m pleased to see that the company has made it through to achieving substantial profits:
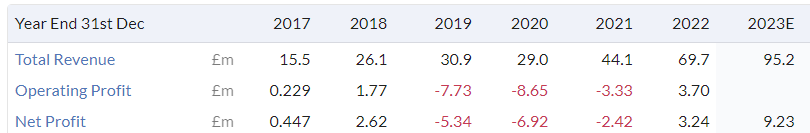
Given that it’s now crossed over into making substantial profits, with continuing high levels of revenue growth, there is plenty of cause for optimism.
However (and this is my own fault, not the company’s), I don’t feel that I understand the competitive advantage here - why do businesses choose Equals over the multitude of other products they could choose when it comes to payments? Is it all about the product itself or has it got a lot to do with the route to market, i.e. the way the company finds its affiliate partners?
I’m going to stay neutral on the stock for this reason but that might be unfair - this could still be an underpriced growth stock even after it has multi-bagged since its Covid low.
Paul adds: Excellent review of EQLS, thanks Graham! Personally, I'm a bit more positive, and would go with AMBER/GREEN, as opposed to Graham's more cautious AMBER. I'm a bit wary of companies that start producing bumper profits out of nowhere (vs prior years), especially in a highly competitive sector. But the figures and broker upgrades have impressed me, and providing nothing goes wrong, then valuation still looks reasonable. Could be good.
Duke Royalty (LON:DUKE)
Share price: 33p (+3%)
Market cap: £139m
This is “a provider of alternative capital solutions to a diversified range of profitable and long-established businesses in Europe and North America”. I’m a former shareholder in the company.
Today brings a Q1 update (April to June) and guidance for Q2.
Key points:
Q1 recurring revenues £6m (as previously discussed).
Total Q1 cash revenues, including one-off transactions, of £7.8m.
Investment income has grown well:

Q1 saw one successful exit from an investment, and two small follow-on investments into its existing portfolio.
In Q2 (July to September), we have already had one large investment into a Texas-based company (discussed here).
The forecast for Q2 is £6.2m of recurring cash revenues, up 17% year-on-year and up by a few percentage points vs. Q2.
CEO comment:
"We are pleased to report another quarter marked by record-breaking cash performance, underpinned by solid growth. This underscores the resilience of Duke's business model, especially in the face of ongoing economic challenges. Looking ahead, we remain confident that the consistent quarterly growth we have generated in recurring revenue will continue, and Duke is committed to working with our partners for their long-term growth."
Graham’s view
I laid out a detailed rationale for my positive view on this stock in early July, so I would refer readers back there for my detailed comments.
At the current level I do view it as offering good value. It is still not back at its pre-Covid valuation, despite not really putting a foot wrong through all of this time:
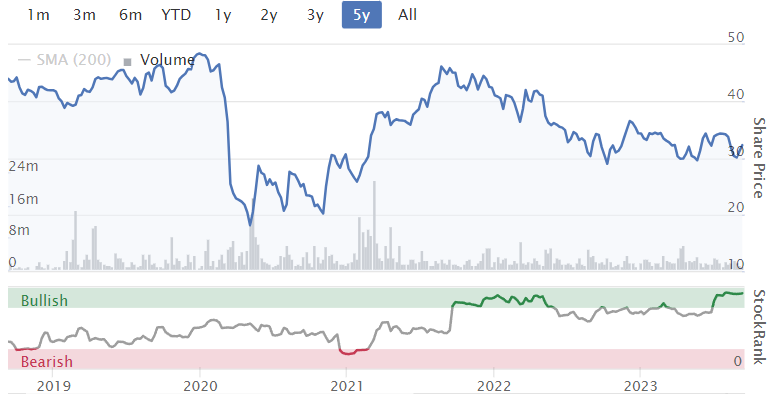
The yield as calculated by Stockopedia is 9% and it passes the “Ben Graham Deep Value Checklist”.
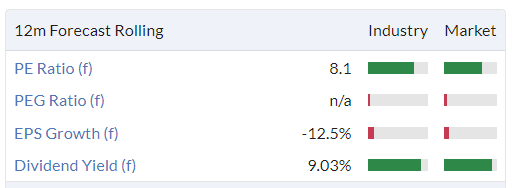
I’d probably be a seller over c. 45p, but at 33p it seems too cheap to me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Really enjoy these articles. My suspicion is ON THE BEACH is currently benefiting from stored pandemic cash but I fear this may run out shortly due to the cost of living crisis. Much will depend on the demographic it caters for,
Good news for Eneraqua Technologies (LON:ETP) this evening, the house of lords blocked Gove's bill.
Now let's see if that was the real reason for the recent profit warning
Jet2 (LON:JET2)
Thanks for the feedback on customer service planetX and Northender. I have looked at the 'Which' reviews on package holiday companies and Jet2 (LON:JET2) was voted joint number one provider, alongside Kuoni, "with five-star customer service at a very reasonable price."
This also seems to be reflected in its employees views on the company on Glassdoor.
Feisty talk from mid-cap Hunting (LON:HTG) in their market day - revenue nearly doubling to $1.3 billion by 2025, pivoting away from providing products and tools for just oil and gas resources to aerospace, space, power generation, defence and medical businesses, keeping friends with China while chatting up India, 10% dividend growth per year.
Mark Simpson covered it in April as part of his article on Net Nets, saying 'Hunting is finally expected to be profitable again in 2023'.
(I hold.)
Sharp eyed stock picker Simon Thompson at Investors Chronicle reiterates his BUY rating for Equals.
https://www.investorschronicle...
Finally fraud charges against ex bosses of Patisserie Valerie ; but why it took so long?
Anything dragged out over time becomes less important and receives more leniency. PPE scandal? Michelle who? Oh gawd, that was aaaaaggges ago…
Predictably hopeless results from Made Tech (LON:MTEC)
This was floated as a high growth baby Kainos (LON:KNOS) but is more of a no growth waste of time. Singers cut revenue forecast today 7% , they forecast net cash dropping from £12.3m last year > £8.5m this year > £6m 2024. There's a load of adjusted numbers forecast with eps 1.1p.
Did have a good trade on it at the start of the year when it almost doubled, but it's been downhill since for the company.
The only person who's come up smelling of roses is the CEO who pulled off a masterstroke floating this at 122p
Nice movement with the On Beach group (LON:OTB) share price today - good soothsaying from Paul!
Yes indeed! My tealeaves were speakin' to me at 07:59, saying OTB will be goin' up soooooon! About ten to twenty percent. Oooooh
Supreme (LON:SUP) Thanks for the commentary Paul, much appreciated. I personally suspect vapes use won't go away, after all tobacco use hasn't. However the sentiment toward Supreme [I hold] isn't helped. Politically a new Government might take an alternate view. Devolved parliament's already can and may look to outdo Westminster in their own fiefdoms.
More broadly I expect that Supreme will intensify plans to increase other business areas as a share of overall mix. They've indicated this intention already in their last investor presentation, so management already recognised that their success with vaping increases risk as it becomes a more dominant part of Supreme's offer.
Supreme (LON:SUP)
More broadly I expect that Supreme will intensify plans to increase other business areas as a share of overall mix They've indicated this intention already in their last investor presentation
I would presume they have consciously previously tried to avoid being over reliant on any one segment (particualrly if vaping) anyway. If they have been always trying to maximise other stuff previously whats the difference now ? - if other areas havent worked previously whats to make us think they will ramp them up now when they havent ben able to do so previously !!!
Its easy to trot out plans of we will do x but the questions i would ask is have they not already been doing that ?and if not why not? Specifically if cashflow has been great for last 2-3 years from vaping they have had the perfect opportunity to address other areas time wise and cash wise so that the fruiote would be arriving now.
The reality is "easy money" is hard to come by so more the fools them if they have taken their ball of other categories that could be diversify profits - particulalry if the vaping easy money will be throttled harder than a scotman taking the micky out of Harry Macguire.
In fairness to them they have always in the past eeked out profits - but how much profit do they make at present ignoring vaping ? is it anything ?
Circa £16m gross profit in other categories
When they talk about other categories they mean acquisitions.
Historically operate fast moving goods business relatively balanced. Were not expecting the speed of success in vaping. They will look to deploy new acquisitions into other fast moving goods to continue to diversify, leveraging their extensive distribution.
Wanted to deleverage the balance sheet before undertaking new acquisitions which was sensible. Have now done this and are net cash again.
None of this is new or off the hoof because of the current vaping bashing. It was all clearly articulated in the last results presentation by management as part of their ongoing business strategy. Todays statement just reiterates what they said back then.
hVIVO (LON:HVO) Simon Thompson in the IC bullish on them after results, even highlighting them as a takeover target.
I think with hVIVO (LON:HVO) the stated aim is either to be taken out or to merge with another CRO and list in the US at some point, so unsurprising that ST highlights that.
Based on recent CRO deals a takeover should value them at 30p+ in my view but of course there is never any guarantee of that and I never invest in something solely as a takeover play. But I am happy to hold, particularly now regular dividends are commencing, for the next couple of years as I think they will rerate materially. Fundamentally they can be doing cash profit of £12m+ so share price just looks cheap in my view.
Hi Guys,
Any chance you could look into - (CABP) Cab Payments Holdings Plc.
Thanks.
Morning John,
I don't think we'll have time to look at Cab Payments Holdings (LON:CABP) (a recent float, so I don't know anything about it) today. Looks like it's another forex/payments group, with £667m mkt cap -
CAB Payments, a market leader in business-to-business cross-border payments and foreign exchange, specialising in hard-to-reach markets, announces the Company's results for the six months ended 30 June 2023.
Very impressive profit growth reported today, mostly from forex - a booming area, as we've seen from Equals (LON:EQLS) and others in the sector.
I see another forex co, Argentex (LON:AGFX) is down 13% this morning, so it seems to be missing out.
How do we sort the wheat from the chaff in this sector? They seem to all claim to have the best platforms & customer service! I think it needs specialised sector knowledge and experience to asses the various companies in this sector.
CABP seems to have made money mainly from interest income, and forex gains. Are those sustainable I wonder? Could it be a race to the bottom (with margins) eventually in this sector, as customers shop around? I don't know.
Regards, Paul.
Read somewhere that an activist investor has taken a stake in IG group (LON:IGG) although currently I understand this seems to be below the 3% declarable for RNS purposes.
They feel apparently that the Group is undervalued even allowing for its pretty active share buyback programme, good dividends and healthy profitability and associated cash. Feels that its cost base could be reduced after a strong take-on during and after Covid and its acquisition in the States.
Its CEO stood down recently for health reasons recently, and they are looking for a replacement.
I recently bought back into IG group (LON:IGG) followed promptly by the CEO leaving - needless to say, an unusually short distance between my usual investing gamble taking place and something unforeseen happening to the company!!
However, overall the Company looks in good shape, and its good nonetheless to see someone sees the company is undervalued.
The CEO of their US option play acquisition is a real character and 'disruptor' (although i don't like the term)They had a livestream show for a decade it seems now.And now all of the big players seem to including Charles Schwab.They're all viewable for free on youtube but probably elsewhere too including their own platforms (i haven't checked).He sold ThinkOrSwim to TD Ameritrade before starting Tastytrade and was previously a optiuons marketmaker on the CBOE.
I think he is wanting to shake it up and pushing to continue to do so, introducing new products and features etc.. and continuing to focus on really engaging with customers and what they want.He's a shareholder in IG still too.Not sure how much of a stake but i'd be surprised if it's under 3%.
He's a shareholder in IG still too.Not sure how much of a stake but i'd be surprised if it's under 3%.
RE: IG group (LON:IGG)
Tom Sosnoff, holds just under 4%.
timarr
thanks for your update on hVIVO (LON:HVO) Paul, I've held for a long time, nice to see them growing into what looks like a good long term business.
Worth a listen to their Interim results presentation from yesterday, puts some meat on the bones.
Paul, excuse me extolling the virtues of Jet2 (LON:JET2) which is far from a small cap.
I don't know On Beach group (LON:OTB) very well, but the valuation of Jet2 (LON:JET2) seems crackers to me. It reported cash (excluding customer deposits) of £1,127 million at the recent prelims and has just taken delivery of 98 new Airbus A321/A320neo aircraft. Given the demand for new aircraft and full order books at Airbus and Boeing, which I understand extend out 5 years or more this is an important consideration.
It has just released a very positive AGM update upgrading prospects the year to end March 2024.
"We are on track to exceed current market expectations for Group profit before foreign exchange revaluations and taxation for the year ending 31 March 2024(1), with the outcome presently expected to be in the range of £480m to £520m. This guidance remains dependent on avoiding any material extraneous events in the balance of the year."
While acknowledging the cyclicality of airlines/travel industry, Jet2 (LON:JET2) trades on a forward PE of less than 7 which as I said seem crackers. Needless to say I hold and am biased but the facts speak for themselves.
I wish holders of On Beach group (LON:OTB) well but my preference is very much for Jet2 (LON:JET2)
Might need to research maintenance issues with the RTX engines. Engine out downtime across a fleet could be material or even some failure outside recall plans.
RTX is one of two manufacturers of engines for the popular narrowbody Airbus A320neo, the other being CFM International, a joint venture between GE GE.N and Safran SAF.PA
As tech steps up to improve efficiency and new fuels then there are risks. Looking forward to my first long haul autopiloted electric plane flight :)
Reading across whether this would be good news for Rolls-Royce Holdings (LON:RR.) - sorry out so no time to research.
when time would like to know ref RR. please
Re: Whether RTX Engine Grounding is Good for Rolls-Royce Holdings (LON:RR.)
RR left the narrow-body airliner market and is yet to return. Regardless, it isn't as simple as swapping out a RTX engine for a rival, even if RR had an alternative to offer, which it doesn't. The costly investment and long delivery lead time aside, a different engine maker means a different maintenance and spares supply chain and training. The engine control computer (FADEC system) is different too, which requires flight-crew training. Once in on a particular airframe, an incumbent engine-maker has considerable barriers to entry by a competitor, even in the event of in-service problem so serious it grounds the fleet.
Hi Ed. No industry knowledge just interest in defence, nuclear and airplanes since a lad, as many I suspect.
Clearly engines aren't being swopped out, but if the next order of engines is being considered then the pros and cons are weighed up and maybe RR in with a shout.
Fundamentals I leave to Stocko but I seem to have missed the boat on the 150 breakout (weekly kumo).
Hi Alison.
My interest in RR. (Sorry small cappers).
Supplying engines for the B52 upgrade for next 30 years lifecycle.
Small Modular Nuclear Reactors (look up Old Royal Naval College, they had one back in the 60's for training and a replica there today I believe (nukes in the heart of London, not many knew of course). But I think we've lost the initiative to Asia and Westinghouse etc - so sad.
RR also into Aussie subs so has lots of things going on.
Air India order for 68 XWB97 engines - again no industry expert just pick up snippets as find them and stick them into Stocko Notes.
And then watch the chart, which failed to do here - should have set an 'alert' but was a 'non flying duck' not so long ago.
Apologies to SCVR - I know - set up a separate Discussion, but not enough input to go that route, apologies again.
Re: Can RR. benefit from RTX Engine Grounding? Hi Harry, As I mentioned briefly in my 1st reply, RR currently does not have an offering for narrow-body airliners, only wide-body, so the problem grounding the Airbus A320neo won't benefit RR. It's been thinking about re-entering that market according to something I read buried in its annual report (I left my job as a metallurgist for RR in 2015 so no longer have an insider's view), but aero-engines often take longer to develop than does the airframe (engine development can't really get going till airframe specification is quite advanced, which is why airframers sometimes launch new airframes with concrete blocks where the engines should be). In order to win new orders due to the grounding of a competitor's engine, an engine maker needs to already have an alternative engine that has passed airworthiness certification and, ideally, is already in production.
Jonno
As a further bullish point on jet2 from a customer persiective it is actually delivering a great service .
My missus flies to Ireland a lot to see her family and loves flying Jet2.
I couldn't agree more about customer service. My 20 yo niece and her friends were abandoned on Majorca by Ryanair a couple of weeks ago when their flight was cancelled. Ryanair offered a replacement flight in 4 days time and no assistance. They had to sleep in the airport the first night as all hotels were full.
Jet2 were fantastic, finding them flights in 2 days, sorting ferries out to Menorca, and a hotel. She won't be flying with Ryanair again even though they may be cheaper than Jet2.
That's one of the advantages of looking at investing in public facing companies - visiting retailers branches or a pub chains bars or using a service can often give as much info as you need to confirm an investment decision.
On that note, I'm staying well clear of Wickes due to the uninspiring experience of my local branch!
On that note, I'm staying well clear of Wickes due to the uninspiring experience of my local branch!
Two third of Wickes (LON:WIX) sales are generated online. 98% "touch" the stores, presumably via click and collect. But there are clearly opportunities to reduce the retail store cost base.
timarr
Thank you Paul for your early morning work with On Beach Group (LSE:OTB). Some investors might want to take profits from Jet2 and pick up some OTB at a discount price (I hold).
There are few profits to take in Jet2 (LON:JET2) at the moment, and as Jonno eloquently points out above, this is a ridiculously undervalued share for such a well managed company. (I hold)
Jet2 (LON:JET2) may have just turned the corner.
I've picked up a few at this level, looks like its re-tested a previous supply/demand level which (barring poor results or macro factors), could put a floor in the sp.
Quite a few bullish comments on the fundamentals of this share and technically its looking promising imo.
Belluscura (LON:BELL) ..not a pretty set of results to my eye. However Paul Hill was very positive on the company's prospects earlier this month (Vox markets 7th September). Is it a sucker stock or a genuine jam tomorrow deliverer?
I am following. That royalty contract is juicy. Cash runway enough?
Looking for additions to my list of bargain shares
Rules
Trading on a PE of under 10 in 2024, adjusting for net cash/debt/pension deficits but not lease liabilities
Reasonable quality, growing business
Not be overly cyclical
Macfarlane (LON:MACF)
Nexteq (LON:NXQ)
Science (LON:SAG)
Card Factory (LON:CARD)
RWS Holdings (LON:RWS)
Hargreaves Lansdown (LON:HL.)
Journeo (LON:JNEO)
Pennant International (LON:PEN)
Inspiration Healthcare (LON:IHC)
Close misses for the likes of Liontrust Asset Management (LON:LIO) Jet2 (LON:JET2) IG group (LON:IGG) OnTheMarket (LON:OTMP) for being too cyclical....
Slightly over 10 with Volex (PE 11) and ME Group (PE12). High quality companies
Duplicated
Supreme (LON:SUP) have just put out a trading update in with a statement regarding the media storm around vaping:
Supreme remains on track to deliver Adjusted EBITDA(1) for the year ending 31 March 2024 in line with market expectations(2) and will undertake a comprehensive review to measure the impact of any proposed changes across the medium to long term once further clarity is provided.
also contrary to media reports:
At this stage, it is important to clarify that no new legislation will be implemented before the formal government consultation takes place.
They also suggest that if a ban was in place, it would cause a shift towards their recyclable products.
The Market Makers are playing with investors in Burford Capital (LON:BUR) this morning.On low volume the spread is jumping around between 13p and 37p in seconds.
My largest position and as a long term patient holder any comments from those wiser than me would be appreciated.
As Donald Pond rightly flagged on twitter with Burford Capital (LON:BUR) as the example, this just shows the disparity between the state of UK vs US markets. (He compares spread of 2.5% in London vs less than 0.25% across the pond). It is one both of appreciation of the story/companies and of liquidity.
When it jumps around like that, it's usually because a Bot is at work.
Agree with mighunter on Burford Capital (LON:BUR) . I wouldn't trade before the US opens and also slightly ignore price movements before that. UK listing a bit pointless as I think most investors are US now. Results very soon!
Re Burford Capital (LON:BUR) said today on their 3pm BST webinar that when last they checked, US shareholders accounted for just under half ("high 40s"%) of all shares. They will check again next year (mid year, I think), but said regardless they have no intention currently to delist from AIM.
Cab Payments Holdings (LON:CABP) new float, went straight into ftse250
Results actually look OK. Seems to have been a slowdown in Q2 but now normalised, leaving Q4 as the usual big quarter. 40/60 split with H1/H2 is the norm, which from the limited info I have seen seems like theyre aead on revenue at least
Anyone have any views on this?
Cab Payments Holdings (LON:CABP)
Crown Agents Bank (as was) - cross border payment specialist with long history of managing currency corridors with Commonwealth countries.
The moat is the depth of relationships with counterparties in those countries and the deep integration with domestic payment systems, along with the fact that most mainstream banks have withdrawn from cross-border transactions in "exotic" countries.
The downside is the reason they've withdrawn which is the increased risks around anti-money laundering and sanctions checking, and the huge regulatory costs of getting that wrong. There's also a lot of work around new methods of cross-border payments but other than the work central banks are doing on CBDCs, which will take most of the decade to come to fruition at earliest, most of that is unlikely to touch CAB's business.
Looking at their alternative eps figures and their 40/60 H1/H2 split the forward PE looks to be about 19. I'd say that's about right until we see other figures.
I'll spend more time digging into the numbers when I get a chance, but generally I regard these types of businesses carrying the potential of huge regulatory sanction as uninvestable.
timarr
Cab Payments Holdings (LON:CABP) Sharepad has a forward PE of 12.2 and that should fall further in future years if company delivers on expectations. It looks so cheap for about 40% growth. It looks another bodged UK IPO (335p in July) where holders start selling below IPO price almost immediately. I think market has decided there is a lack of visibility / scepticism on future numbers so if CABP can deliver on what they are promising it should do very well. I bought some as a trade recently but I'll sell to the index buyers on Friday as it goes into the FTSE 250.
Cab Payments Holdings (LON:CABP) (no position)
Hi WOSS
Here are my notes from one month ago after reading the IPO document, which you might find of interest:
A hugely important territory for the company.
----
And my thoughts today:
(NB: staff costs are slightly different in the P&L vs in the P&L notes - not sure why, don't like that they don't just match, but I only glanced through so there might be an obvious reason for the discrepancy.)
Nigeria revenue was only £3m back in 2020 (FY) and only £2m in H1-FY21.
Very volatile - hard to sense direction of travel here.
After today's results I don't plan on taking up a position, though I remain intrigued by the possible opportunity. I would probably reconsider if I saw signs of cash generation in H2, even if (when?) Nigeria-related revenues fall.
As a side note my favourite FX players at the moment are Wise (LON:WISE) , which I own, and Remitly Global (NSQ:RELY) , which I do not own.
Cheers
A
Fantastic. Thanks abtan, feta and timaar, what a smart bunch of people hang around here!! With your brains and my looks we could go far :)
I bought some as a trade in August for it entering the ftse250. In profit so probably put a stop around break even and see what the brokers make of it in the next couple of days.
I almost bought Wise (LON:WISE) as it setup perfectly on the chart 4 days ago but didn't want another FX player.
Could the lack of NGN FX services from other FX players be because of the NGN challenges in the past few years, where its been very tightly controlled by the central bank? if I have it right, only a very few players in the market had access to the official NGN foreign exchange market.
I know that earlier this year there has been a devaluation, and also a signal to allow the NGN to trade and float more freely.
This might then encourage some of the big FX players (like Wise) to re-enter?
A cynical view is that this could be why Cab Payments Holdings (LON:CABP) IPO'ed.... the loosening of the NGN exchange regime has been on the cards since the election of the current president back in Feb23....
Hi Boon
The Wise decision appears to be because the central bank banned the receipt of remittances in naira and instead insisted on receiving dollars instead. Wise's problem would be how to get dollars into Nigeria, since there's a scarcity of foreign currency in the country. Sending a fleet of armoured trucks overland really isn't their core business.
Cab Payments Holdings (LON:CABP) have probably benefited from this as they'll likely have deep relationships formed over decades with local banks. So - at a guess - they've IPO'd at a very opportunistic point. But they'd hardly be the first company to do that. I certainly wouldn't want to project current growth forward indefinitely.
I'd also note that Wise and CAB are quite different companies - Wise tend to serve individuals and small businesses while CAB can support large corporate transactions. The main difference there is liquidity - CAB need access third-parties to transfer billions, while Wise can often rely on local deposits in major remittance corridors, so can use their own cash.
Note that neither Wise nor CAB are FX traders, their business is moving currency cross-border.
I hold Wise (LON:WISE) .
timarrLots for me to think about there! Thanks abtan. Excellent stuff.
Frontier Developments (LON:FDEV) FY results out this morning. Another disappointment in a long line of miss steps. An operating loss of £26.6m, worse than the projections they gave in June of around £11m loss. Though revenues have held up reasonably well at £104.6m due to a strong back catalogue of games and continued DLC content.
Poor results due to closing of Frontier Foundry, their third party publishing label, which lost money on all seven of the games it published. And lower than expected returns from their new F1 Manager series of games. F1 Manager 23 has been received fairly well with a Metacritic score of 79, though sales have been lower than the first game. All in all not a great time.
“The financial year that ended 31 May 2023 was a challenging one. In January 2023 we announced a reset of our revenue expectations following a lower-than-expected sales contribution from F1® Manager 2022, the general sales underperformance across the portfolio during the Christmas holiday period, and the poorer than expected performance of the Foundry games. Subsequently, we took the difficult decision to cease all activity relating to acquiring new third-party titles within Foundry. We took this opportunity to refocus and reset, with all of the Group's efforts on Frontier's own internally developed portfolio of titles.”
They have an upcoming release, "Warhammer Age of Sigmar: Realms of Ruin", a real time strategy game. A game that offers single player and multiplayer options. Though for longevity will certainly rely on the multiplayer aspect. I've watched a few videos of early access gameplay and reviews and the results have been mixed, though there does seem promise there. It will very much depend on community adoption though, so I'm not holding out a lot of hope.
Aside from this release they have two new creative management sim games coming in FY25 & FY26, which I assume will be along-side future F1 Management instalments. They also have their new studio working on a turn based strategy game. So games in the pipeline, but certainly concentrated and if they miss the mark with sales numbers on those games.
Any other thoughts would be greatly appreciated, especially on the finances, thanks.
(I hold)
Unfortunately I think I'm just stating the obvious but it's very clear that the performance of the Warhammer game will be absolutely critical to their financial performance (at least this financial year.)
F1 Manager 2023 has disappointed (despite the somewhat positive metacritic score). They will likely have forecast against sales/usage compared to last year. A quick look at SteamDB (only a partial view as it is for Steam sales only but perhaps indicative of the wider trend) F1 Manager 2022 peak users of 25k and avg. users dipping below 3k in Dec 2022. F1 Manager 2023 shows peak users of 6.5k (-75%) with average users dipping below 3k in the second week of August... That's poor and shows the development team aren't in touch with what the community wanted from the next instalment. They now have another 12 months to work out what that is and produce a better game, but it doesn't reflected positively on the strategic decision-making by management.
This is the well known issue compared with companies which produce a portfolio of games which offsets the risk of titles underperforming (e.g. Team17 (LON:TM17) though Devolver Digital and TinyBuild show even that approach is not without risks!
So eggs are in the Warhammer basket. It's worth watching Youtube videos of content creators having early access to the game to see how they react. Keep an eye on 'wishlist/followers' on Steam, watch to see how sales go on platforms like SteamDB and hope mgmt's forecasts are prudent with room for outperformance!
Dreadful FY23 Results as expected for Frontier Developments (LON:FDEV) with an operating loss of £26.6m but luckily the board are "comfortable" with expectations of an adjusted EBITDA* loss of £9 million for FY24. Judging by the precipitous fall in share price (19 straight losing days apparently), shareholders are not feeling quite so comfortable.
It's said that the first step in recovery is to admit that you have a problem and the new CEO does manage the delicate act of slagging off the poor decision making of the company over recent years whilst celebrating his predecessor's achievements (founder David Braben):
"We are conscious that our financial performance over the last two years has not been good enough"... "the majority of our financial challenges have been driven by some of the decisions that we collectively made over the last five to six years, which did not always result in the expected financial outcomes for the Company."... "we'll be celebrating 30 years since David Braben founded Frontier in 1994. That has provided the perfect context in which to look back at our games, and re-evaluate what makes a 'Frontier' game when it comes to our project selection decisions. Analysing our successes, and also where we have had our greatest challenges, we have defined four project selection pillars: Strategic, Experience, Gameplay, and Longevity."
So the good news is that they have identified the problems and have a plan to address them.
Terminal death spiral or deep value buying opportunity anyone?
I'm leaning towards the latter but wonder if I should wait a while for more concrete evidence of positive change before dipping my toe in.
Yes it does sound like they've realised their mistakes and have now re-focussed on what made them successful un the first place. I did like the commentary you've mentioned from the CEO. I'm torn on your final question. It could be a very good deep value opportunity, although they are still going to be heavily reliant on one or two games a year and their recent results haven't been great. I hold a small position but won't be adding until we see how their next game lands, and maybe the one after that as well.
Brave Bison (LON:BBSN) (I hold) have come in in-line, with a new Cavendish note this morning introducing slight tweaks to FY '23 forecasts (same bottom line) as well as a FY '24 estimate showing modest growth, which seems sensible given the outlook comments.
I first encountered Brave Bison (LON:BBSN) at one if the in person Mello's in Chiswick and came away impressed with the Green Bros, who came across as competent and entrepreneurial.
Share register now has Lord Ashcroft owning 19%.
IMO, this is one to watch, especially as we emerge from today's subdued advertising market. Outlook for '23 is still in-line. Net cash gives some confidence. Share count up with latest acquisition of Social chain, which they say has real potential.
Views (and a comment by the team) most welcome!
BBSN I listened to most of the Investormeet presentation, looked at the the interim results release and the previous releases in February on the relatively large Social Chain ‘SC’ acquisition. And I have just glanced at a (presumably paid-for ) note from Cavendish.
My conclusion was that the outcome was somewhat better than i had expected but the jury is still out. I had sold half my position at around the current price fearing that the slowdown in ad/pr revenues, and in particular jitters on the role of the influencer, might spoil the party.
My tentative conclusion now is that all depends on making SC profitable. It has merged that business into its own, much smaller, social media and marketing agencies group. It paid c£8mn and a hefty £800k brokerage fee foe the £4.8mn equity fundraise. But at the time of the purchase it stated that there would be up to a further £9.5mn payable over three years depending on achieving EBITDA targets. They today stated that this contingency fee would no longer be relevant as the (German) seller had ceased trading. That was a major plus for me.
It was also obvious, however, that there was a major slowdown in the existing businesses. Cavendish had previously indicated probable revenues this year of £40mn but has dramatically revised that downward to £35mn against £32mn last year. Given that a standalone SC had revenues of £14mn in 2022 it looks like a fairly sharp decline in the existing revenue streams. However as stated above the broker has not materially changed their adjusted profit figures for f23, the company is indicating both that most of the restructuring costs at SC have been implemented (inc a 28%) staffing reduction, suggests the trading and net cash position in H2 will improve. The massive tax losses might also make this an attractive add-on to a larger ad company and as my friend states Michael Ashcroft has become a very significant shareholder and is not in it for the fun.
My guess is that the space is still growing reasonably well but may be much more competitive now. I hope that succeed but times are and will stay much trickier.
Argentex (LON:AGFX)
Thoughts on Argentex, currency management and payment services company please. 28% revenue increase, strong cash generation and £3M net increase in cash.
Argentex (LON:AGFX)
Thoughts on Argentex, currency management and payment services company please. 28% revenue increase, strong cash generation and £3M net increase in cash.
You only have to compare with two key competitors who released TUs in the past 24 hours. AGFX today is clearly a weaker player in a crowded field, constantly chasing the innovations of its better run competitors. One for traders, not investors in my opinion.
Re Argentex (LON:AGFX) Depends on your investment timescale I guess. I always go straight to the outlook statement as the market should be looking 6 months ahead, was immediately drawn to talk of challenging trading post period end.
"Whilst the core UK corporate currency management business remained resilient, our Institutional and European divisions have more recently experienced a greater season reduction in market activity."
I don't really follow the company tho so I could be well off the mark.
Oddly worded as they are also saying they are in-line as at mid Sep for full year.
Broker forecasts haven’t moved either so no hidden changes.
Seems to me that institutions were doing lower volume over summer but this has been offset by significant uplifts in their new Transaction banking products.
Ie my suspicion is that they hoped they’d beat expectations but are in-line due to lower institutional trading volumes.
Argentex (LON:AGFX) interims today worth a comment. Growing revenue at about 20% (to 5 Sep), but costs growing faster at about double that. Results OK, I think and growing the top line steadily.
I should own up to having sold my position a few weeks back: I had lost conviction in management, and the CEO in particular, on the back of how they update holders, fast growing headcount and the continued large LLP profit skim payments.
The large LLP costs are payments to the original founders of Argentex LLP who take a percentage (around a 1/3rd I think) of the main trading company profits - something that has been disclosed since IPO and is effectively a "bonus staff cost".
I had missed the LLP payments before. Do you know if that is a fixed percentage or gets negotiated each year?
Argentex (LON:AGFX) - re. LLP payments - it was £4.2m in the 9 months ended 31 Dec 2022 out of £14.7m in the LLP accounts so 28.5% or so. Effectively, the LLP is not wholly owned.
Excludes Directors of Argentex Group PLC who are/were also members of Argentex LLP.
Prior to IPO, profits from Argentex LLP were distributed according to individual equity holdings in the LLP. Following Admission, the self-employed LLP members who are members of the LLP Executive Committee will be remunerated under the Amended and Restated LLP Agreement by a combination of (i) fixed annual remuneration (ii) participation in revenue
commission schemes (iii) annual bonuses and (iv) other variable compensation based on the LLPs performance.
Argentex (LON:AGFX)
disclosure- I am not an accountant. I own a few shares in AGFX.
I traced the LLP members' costs through the last FY accounts. These costs are accounted for as staff costs (members do not appear to be salaried) and are included as costs in deriving stated operating profits. Members also have an interest in the LLP's capital. I could not trace the extent of this. N.B. The LLP is AGFX's operating subsidiary.
I would appreciate any comments by those more knowledgable.
Argentex v Equals
Interesting (and finally) change of sentiment
As a user of both and knowing the Argentex CEO from buying currency off him many years ago .
Have to say it was frustrating watching the Argentex share price outperform equals in the past year or so .
Argentex not much more than a currency broker and Harry Adams back in the day came across as a proverbial cheeky crappy salesman along the lines “oi oi geezer “
Equals looked a whole different proposition adding value to its customers and enabling them to manage their currency better .
It has taken a long time for the market to grasp on and Equals share price has stubbornly refused to stay above the pound barrier .
Argentex is only as good as it’s last trade
Equals is building a brand and system with scale that now looks to have momentum and looks a probably 3 bagger if it delivers over next 2 years .
I wouldn’t touch Argentex as a long term proposition .
I own both though admittedly I am much more weighted towards Equals (LON:EQLS) which I prefer.
However, in my view Argentex (LON:AGFX) is too cheap. Strip out own cash and you have a company growing at 20% p/a on a PER of 8 or less.
yes it was behind the curve on tech but has been investing in this and some areas of its business are now outperforming. Interesting that they are about to launch a mass payments functionality (so think HR etc) which is something Equals (LON:EQLS) are also in the process of doing so they are not a follower in everything.
Growth prospects look pretty good for the business once you factor Europe, Australia and new functionality in and I think a cash adjusted PER of 8 is the wrong price for that growth.
Nonetheless I concur that if I had to hold only one it would br Equals (LON:EQLS) but I disagree that Argentex (LON:AGFX) isn’t a good business.
Didn’t say Argentex is a bad business .
But is is definitely not got a “durable competitive advantage”
That’s the issue, sane business as Moneycorp and the other currency traders out there .
And definitely has a senior team that prioritise making themselves very rich in the process .
So there are clear red flags .
Redrow (LON:RDW) results for those who keep an eye on housebuilders. Some snippets from the RNS:
"As expected, the sales market over the summer has been
challenging. This has resulted in sales per outlet per week for the
first 10 weeks of the new financial year of 0.34 (2023: 0.61)."
"Reflecting the macro-economic picture and the tougher sales
market, our average private reservation rate per week for the year was
0.46 compared to 0.68 in 2022."
They've also locked in their pension surplus (I'm being simplistic):
"On 27 January 2023, the Trustees of the Redrow Staff Pension
Scheme entered into a bulk annuity buy-in contract with Standard Life."
Redrow (LON:RDW) The pension "surplus" has reduced from £39 million to £5 million as result of the bulk annuity buy-in. The £34 million write off has gone through Total Comprehensive Income instead of P&L and therefore has not hit eps. This treatment is allowed by some auditors but not others. It is just another example of the complete idiocy of current pension accounting rules.
Being a cynic, I never believe pension "assets" are real until the company has received the cash on wind up of a scheme...
On Beach group (LON:OTB)
Record TTV of £1.1bn, significantly ahead on summer 2024 bookings, debt free, cash generative. On a fcst p/e of 7.1 and peg of 0.3( as of cob yesterday) On Beach group (LON:OTB)
Jeremy Naylor on IG early morning call predicted a rise in share prices. Target is 140
Apologies it’s lost my post which was:
The suspense is killing me AstonGirl :-)
A positive trading update from Duke Royalty (LON:DUKE) this morning (Q1 24, June 2023). Recurring cash revenue reached a new record of £6.0m, up 17%.
Company guidance for Q2 is now £6.2m
I hold.
My morning smallcap tweet: Hot Beach
On Beach group (LON:OTB) Kinovo (LON:KINO) Versarien (LON:VRS) EnSilica (LON:ENSI), Hornby (LON:HRN), Brave Bison (LON:BBSN), Argentex (LON:AGFX), Made Tech (LON:MTEC)
◄On The Beach (OTB)► guides FY-Sep adj pretax at the top end of market expectations. [SP=101.59 Cap=169m]
◄Kinovo (KINO)► award worth an expected c. £4.8m over 19 months through The Greener Futures Partnership's Decarbonisation Framework. [SP=57 Cap=36m]
◄Versarien (VRS)► 62% owned subs. Gnanomat awarded a grant of c.€415k to design conductive inks based on nanomaterials for flexible and printed electronics. [SP=1.25 Cap=4m]
◄EnSilica (ENSI)► wins sensor ASIC supply contract for the e-mobility market worth over $7m over first 5 yrs. [SP=70 Cap=55m]
In line: HRN, BBSN, AGFX, MTEC
On Beach group (LON:OTB) - Looks like a positive trading update.