Small Cap Value Report (Wed 14 Feb 2024) - BMY, WRKS, CCH, DNLM

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
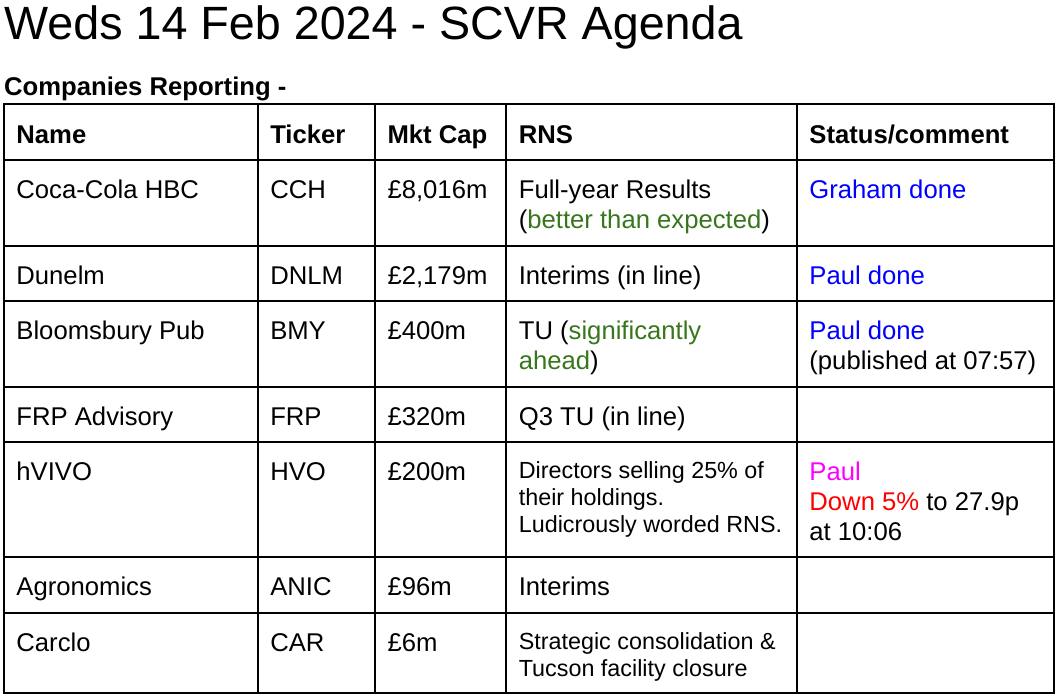
As it's quiet again today for small caps, we've reviewed a couple of mid caps that interest us too -
Other mid-morning movers (with news) -
Works co uk (LON:WRKS) - up 9% to 24.25p (£15m) - appoints 2 new NEDs, unusually these are non-independent, being the CEO & CFO of active, but tiny investment company Kelso group (LON:KLSO) (mkt cap £11m), which owns 5.1% of WRKS (paid 33p). Speculation of some kind of corporate deal maybe? KLSO is pushing WRKS to do buybacks, see here. WRKS looks a very marginal business to me, with little (if any) equity value, but might benefit from higher consumer spending as 2024 progresses? Although April 2024 sees big wage cost hike.
Summaries
Bloomsbury Publishing (LON:BMY) - 492p (£401m) - Trading Update [ahead] - Paul - GREEN
This book publisher delights us with another out-performance update. Pity they don't explain how much they're ahead, and only the privileged have access to broker notes that will tell them how much ahead the company is. That's wrong, but it doesn't dampen my continuing enthusiasm for this excellent company - still priced reasonably, even after a (justified) good run upwards. One of my top 20 share ideas for 2024, and I remain very positive on BMY shares.
Coca Cola HBC AG (LON:CCH) - up 6% to £23.31 (£8.5 billion) - Full year results (ahead) - Graham - GREEN
Strong numbers from Coke HBC which it reports as being stronger-than-expected. Volume growth (1.7%) is minimal but price increases help to insulate shareholders from inflation. I view this as one of the most impressive big-caps in the market and the PER is only c. 12x.
Dunelm (LON:DNLM) - down 1% to 1077p (£2.17bn) - Interim Results - Paul - GREEN
Decent enough H1 figures, considering the tough macro backdrop. Cost increases have been recouped through higher gross margins. Outlook in line for FY 6/2024. No concerns over balance sheet or cashflow. A key feature are generous divis (incl. specials), due to plentiful cash generation. I like it, as a decent quality, long-term investment with a nice income too for shareholders.
Paul’s Section:
Bloomsbury Publishing (LON:BMY)
492p (£401m) - Trading Update [ahead] - Paul - GREEN
Bloomsbury Publishing Plc (LSE: BMY), the leading independent publisher, is pleased to announce the following update on trading.
This looks like an unscheduled good news update, for the almost finished FY 2/2024 - overview -
Revenue and profit significantly ahead of upgraded expectations.
As you can see from my favourite graph below, forecasts for FY 2/2024 had previously been substantially increased, so to be “significantly ahead” of these higher estimates is really impressive -

How much ahead is “significantly ahead”? It doesn’t say, but does tell us what the existing forecasts are -
The Board considers that the consensus market expectation for the year ending 29 February 2024 is currently revenue of £291.4 million and profit before taxation and highlighted items of £37.2 million.
Broker updates - nothing has landed on Research Tree yet, nor my inbox. BMY doesn’t seem to arrange for any broker notes to get through to pond life like us, I just cannot understand why some companies have this silly blindspot in their investor (lack of!) communications.
So we’re forced just to guess. It was 36p before today, so significantly ahead could mean say 40p? Maybe more, who knows? Well the company knows, they’ve just declined to tell us. Also the company probably wants to keep it vague to allow for any audit adjustments. Only people who pay for access to the top broker notes will now have the unfair advantage of getting this inside information of the likely outcome for FY 2/2024 profits.
Author Sarah J Maas (mentioned in the past by BMY trading updates) seems to be the star performer, with fantasy fiction being a strong selling genre -
The Consumer division has delivered exceptional growth driven in part by the publication on 30th January of Sarah J. Maas novel House of Flame and Shadow which reached Number 1 in the US, UK, Australia and many markets around the world.
The publication of her latest novel has also driven demand for her previous 15 books which Bloomsbury has published throughout the world in the English language. Bloomsbury has a further 6 titles under contract with Sarah J. Maas.
Nigel Newton, Chief Executive, commented: "I am overjoyed to report an exceptionally strong period of trading, principally driven by the increasing demand for fantasy fiction. Sarah J. Maas is a publishing phenomenon and we are very fortunate to have signed her up with her first book 13 years ago. Her books have a huge audience which continues to grow backed by major Bloomsbury promotional campaigns, driving strong word of mouth recommendation, particularly through TikTok and Instagram channels."
Valuation - with a terrific track record, and repeated out-performing updates in the last year, I think BMY is a growth company priced like a value share.
If it’s heading for say 40p (my guess) EPS in FY 2/2024 then the PER is only 12.3x
Providing you think this higher level of earnings in sustainable, and growth can continue, then surely a higher PER makes sense? Maybe 15-20x ? That would suggest a price of potentially 600-800p could be justified, nice upside from the current 492p. We should see a nice gain today, at a guess something like maybe 520-530p? (writing this at 07:42, it’s just for fun guessing!)
Downside risks? Nothing with the balance sheet, which is bulletproof with £100m NTAV and plenty of cash within that. The only risk I can foresee is if fantasy fiction goes off the boil, and strong growth this year cannot be replicated in future years. Although as we’ve seen with J K Rowling, once an author becomes highly popular, that popularity seems permanent rather than fleeting. BMY seems to have a knack of finding such authors early, and that in itself is a good reason for paying a higher multiple for this share.
Paul’s opinion - BMY was already one of my favourite GARP (growth at reasonable price) shares, and is on my top 20 ideas list for 2024. With another ahead of expectations update out today, the bull case has just been refreshed again.
So it’s a wholehearted GREEN from me again today.
There’s a very good earnings trend, which has been reflected in a lovely uptrend in share price too -

The forecasts (lighter blobs) below are pre-today’s upgrade, so are likely to rise. Note the FY 2/2025 forecasts are very modestly set, anticipating a drop in earnings. That doesn’t seem likely to me, given the trend has been so positive to date - so more upgrades to come, is more than 50% probability in my view. Hence overall I see nice risk:reward here, but nobody can reliably predict the future, so as with all shares, it’s educated guesswork!

Dunelm (LON:DNLM) - down 1% to 1077p (£2.17bn) - Interim Results - Paul - GREEN
Dunelm Group plc ("Dunelm" or "the Group"), the UK's leading homewares retailer, today announces its interim results for the 26 weeks to 30 December 2023.
I’ve long admired this mid-cap household goods retailer from sheds in retail parks - it makes decent margins, and has an excellent long-term track record of growth and decent shareholder returns (note the frequency of special divis, on top of regular divis). So given that there’s little small cap news of interest today, I’m grabbing the opportunity to give these H1 results a quick review.
As an aside, I recently mystery shopped (online) for curtain rails & curtains (called “Berlin”) and was very pleased with the reasonable quality, and low prices. It’s not top end stuff, but affordable homewares, with a very wide range. I imagine almost everything would be cheaply manufactured in the Far East, so it will be interesting to hear what they say about freight cost/delays.
On to the numbers -
Interim Results for the 26 weeks ended 30 December 2023
Strong performance and increasing our broad appeal
Revenue up 4.5% to £873m - not great, as it’s below inflation over H2 of calendar 2023.
Digital sales are 36% of the total it claims, but footnote 1 reveals this is nonsense, as it includes “tablet-based sales in store”! If a customer is physically present in the store, then nothing they buy can credibly be called “digital sales”.
Four new stores opened, total now 183. I make that annualised sales per store (ex VAT) of almost £10m, so these are big sheds, much more efficient than lots of smaller High St stores.
Gross margin is up a useful 160bps to 52.7%, but
Operating costs have offset this margin gain, with a rise of 150bps.
Profit before tax is up 4.8% to £123m (no adjustments is good)
Diluted H1 EPS is 44.6p, down 2.6% probably due to higher corporation tax, which is rarely commented on, but the rise from 19% to 25% has taken a hefty chunk out of most companies earnings.
Overall, I think the above H1 figures are pretty respectable, considering the backdrop of a sharp squeeze in household disposable incomes in 2023 (likely to reverse from April 2024).
Outlook - sounds OK to me -

Helpful footnote, many thanks -
8 Company compiled average of analysts' expectations for FY24 PBT is £202m, with a range of £199m to £207m.
Note that this suggests an H1 bias to profits, as it includes the busy Christmas period.
Freight comments - doesn’t sound any reason for concern here -
There was a net benefit in the half from lower freight rates and adverse foreign exchange movements. For the full year, we reiterate our guidance for gross margin to increase by 100bps. The rate of improvement is expected to slow in the second half due to the combined headwinds of foreign exchange movements and lower freight benefits. We are managing the impact of ships taking longer, more costly routes as they avoid the Red Sea area.
Balance sheet - looks fine to me. NTAV is about £170m.
There’s a bank loan of £48m, but that was offset on 30 Dec 2023 by gross cash of £56m.
I expect there would probably be quite large intra-month swings in cash/debt, depending on when suppliers, landlords, and payroll are paid out. Being a retailer though, the cash flows in on a daily basis, in a highly predictable manner.
Given the strong profits and cashflows, I don’t think it needs a strong balance sheet, and could even take on more debt if necessary. Everything looks fine, so no concerns here.
It looks to be clean, re no pension deficit. The word “pension” doesn’t appear at all in the results statement (doing a CTRL+F to search for it).
Cashflow statement - very clean, although as always IFRS 16 has messed up the numbers by putting rent costs in the wrong place.
Overall, DNLM is consistently cash generative, and this is mainly used to pay generous divis. It looks as if they’re deliberately flexing the divis in order to keep net debt roughly static at a small net cash position (of £6.2m at 30 Dec 2023).
I’d like them to disclose average daily net cash/debt, which would be much more useful than a year end snapshot.
Broker updates - nothing available. Going on broker consensus data from the StockReport, we have 74.6p for FY 6/2024, and 79.7p for FY 6/2025. Personally I imagine there could be upside on the 6/2025 number, given the big rises in real household incomes kicking in from April 2025. So it wouldn’t surprise me if EPS might be on a rising trend to maybe nearer 100p with some patience? Hence the share price of 1077p could have some upside on it. Plus shareholders receive the bulk of earnings in divis whilst you wait.
Paul’s opinion - I think this looks a really decent income share, with built-in inflation protection, and long-term earnings growth likely.
Thumbs up from me. GREEN.
Graham’s Section:
Coca Cola HBC AG (LON:CCH)
Share price: £21.84
Market cap: £8.0 billion
Coca-Cola HBC AG, a growth-focused Consumer Packaged Goods business and strategic bottling partner of The Coca-Cola Company, reports its financial results for the twelve months ended 31 December 2023.
This is far above the market cap limits for a small-cap report, but as news is quiet this morning I thought I would take a look.
Coke HBC is the bottler/distributor of Coke’s drinks in many European markets. It should not be confused with Coca-Cola Europacific Partners (LON:CCEP) which has a different portfolio. Coke HBC has Austria, Greece, Italy, Switzerland and many other developing and emerging markets in or near Europe (see here).

The company says that 2023 performance was “stronger than expected”.
Headline growth numbers are very impressive, although they are driven by inflation:
16.9% organic revenue growth
1.7% organic volume growth, i.e. the revenue growth has been driven by price increases (15%), not by volume.
FX is a headwind due to weakness in emerging markets, so reported revenue growth ends up being lower at 10.7%.
Profitability: the EBIT margin improves slightly to 10.6%.
Gross profit margin is up 80 basis points, a movement in the right direction after the high inflation of recent years. Last year, gross margin fell by 200 basis points.
ROIC (as calculated by the company) increases to 16.4% - a very good number. I’d be happy to achieve that on average across my portfolio.
Cash flow & net debt: free cash flow (again as calculated by the company) rises 10% to €712m.
This hasn’t led to any major reduction in net debt (€1.6 billion); it seems that the company feels its debt is already low enough. The dividend is being increased by nearly 20% year-on-year, and the company has already launched a €400m share buyback.
It has been buying back shares at a modest earnings multiple:

The company’s confidence in buying back shares is probably justified; the leverage multiple is only 1.1x (net debt to adjusted EBITDA) and most of the debt isn’t due for repayment until 2027 - 2031. S&P and Moody’s both give the company stable investment-grade credit ratings (see here).
CEO comment:
"2023 was another year of consistent execution of our growth strategy. We delivered volume growth, share gains, improved margins and record levels of free cash flow. As a result, we were able to increase shareholder returns, including the launch of a share buyback programme.”
Outlook
Guidance for the current year includes:
Organic revenue growth within the 6-7% medium-term target range.
COGS per unit to increase “low to mid-single digits” due to inflation and FX.
Organic EBIT growth of +3% to +9%.
It’s a wide range of potential outcomes but as I said yesterday, I much prefer to see a wide range of estimates rather than false precision.
No company can be reasonably expected to predict inflation over the course of the next year, and it won’t be possible (or desirable) to fix so many costs as to insulate the company’s performance from it. So we are left with a wide range of possibilities.
Graham’s view
As readers may know, I often find myself attracted to high-quality big-caps and Coke HBC is a typical example of the sort of thing that I’d be comfortable owning.
The numbers are clean: net profits of €636m, up 50% with no adjustments needed.
The business is well-funded with easy access to finance and can afford to buy back shares while also paying out nearly half of earnings to shareholders in the form of the dividend.
Governance is reassuring with the two cornerstone shareholders of Coke HBC being the Coca-Cola Company itself and a private company which previously owned Hellenic Bottling Company (Coke HBC’s predecessor).
I’m inclined to agree with the StockRanks and give this stock the thumbs up at the current level:

Any reasons for concern?
I do think the Deposit Return Schemes could be an issue. The company mentions six countries where these are now active: Croatia, Estonia, Latvia, Lithuania, Romania and Slovakia. Ireland has joined the list. Could this have a noticeable impact on consumer demand? I’ve been wondering the same about the UK soft drinks companies with the prospect of a DRS in the UK over the next few years.
Inflation is the more obvious and straightforward worry. Although I continue to maintain that prices will eventually feed through to consumers sooner or later (It’s one of the most important advantages of equity investing vs. fixed income investing, that you get this inflation protection.) Coke HBC doesn’t seem to have had much difficulty raising prices, with only a modest reduction in gross margin over the past two years.
It’s unlikely that we’ll cover this stock again soon in the SCVR. But for what it’s worth, I’m going to give it the thumbs up. A high quality business at a reasonable price, in my book.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

188 comments
hVIVO (LON:HVO) Two and half years ago Cathal Friel was a buyer at 26.5p. Today he cashed out a quarter at 28p. This had grown into my biggest position and I've taken the opportunity to follow his lead and reduced my position. If he thinks there are better uses for his money, I'm not going to argue. Mind you he bought before it went to 10p, so it could just be his timing is lousy. Will continue to hold some but not willing to let the position get outsized.
Looking at the RNS Cathal Friel has cashed out over half their holding for 28p/share. Remaining holding is just over 3% of the company so a decent amount of skin in the game still.
Presumably today's insider sale means their can be no significant recent information that has not been released to the market.
Thanks Paul for the brilliant and surprise update on larger Company Dunelm (LON:DNLM. I bought at 690p on the John Lee and Warren Buffett tactic of buy when most are selling during the Trump/Kwarteng chaos, but now that the share is back down from over £14 to £10 was wondering whether to raise cash for other bargains. There are SO many at present, both small companies and large. But using your update as a guide on top of all the info from Dunelm today I’ll definitely hold now. The dividend with those specials added is very useful.
Dunelm (LON:DNLM) is in my wife’s ISA portfolio and she has just read your update and disagrees with your comment below about digital sales.
“Digital sales are 36% of the total it claims, but footnote 1 reveals this is nonsense, as it includes “tablet-based sales in store”! If a customer is physically present in the store, then nothing they buy while in store can credibly be called “digital sales.”
Why not she asks? A lot of their offerings are heavy or big or both and won’t fit in a car. So people go to the store to see the choices available and having decided then buy on line while in the shop. Why isn’t that a digital sale? AND it’s a chance as she does, to alert friends to bargains in store, that they might have missed seeing online. So sometimes they go to the store too, and end up buying online in the store. Arguably it leads to higher dividend sales.
Our nearest Dunelm up here in the North East is often very busy and with big queues at the checkout, despite the checkouts being well manned. Buying online while in store avoids the queuing.
Finally while chatting in the Dunelm PAUSA cafe with staff there, they told us Dunelm was a great Company to work for, and at their store, no staff were laid off during covid. There is a buzz about their stores. Share still looks good value though notbsure what the rigger woukd be for a significant short term boost to it, , and certainly one to check out.
Another dip if there is one could prove to be another good buy opportunity…..as long as China doesn’t take a shine to the sector and hammer prices charged and margins and prove as ruinous for stores like Dunelm as SHEIN was for Boohoo (LON:BOO) and ASOS (LON:ASC) . No sign of that happening yet…..is there?
I don't see an issue here, Cathal has taken hVIVO (LON:HVO) from about 5p to 30p, plus span out Poolbeg Pharma (LON:POLB) giving shareholders a dividend in species. Now he is cashing some chips in with the least amount of disruption to the share price. No drip selling for months
He couldn't really put that in an RNS
Fair play I say.
One thing with hVIVO (LON:HVO) I think the plan was always to flip it in the end but I don't know who would buy it. They work with lots of big pharma so if one of them bought it they would lose the custom of the rest of them.
That is probably another reason Cathal is cashing out, fed up waiting for an offer. The man can't live on shares alone, one needs actual money.
The exit plan is not to pharma - it is either a Nasdaq listing (aka a repeat of Amryt Pharma) or a sale / merger with another CRO
So this tells me that a Nasdaq listing is not on the cards in the foreseeable future. I suspected it was but have now changed my opinion after today. Fundamentally Cathal is a trader of businesses - so he’s lightening the load and will find something else to play with. He’s not really operationally involved in hVIVO (LON:HVO) since Mo took the reigns. So best guess is he’s taken money out to reinvest in new shiny toys but will keep the rest of his shares after he freely admits he was bitten selling Amryt far too early.
Is it coincidence that Poolbeg Pharma (LON:POLB) is on the rise……I suspect not!
Anyone following Arrow Exploration (LON:AXL)? Looks like it's on the move today in advance of Q1 drilling. Small oil company in Columbia with sp approaching the 20p mark. This feels like an early stage Petrotal (LON:PTAL) .
I'm keen to hold oilers that are not in the North Sea and have hopefully decent upside potential. Oil price is very strong unlike Gas which just seems to get cheaper and cheaper. Hence avoiding I3 Energy (LON:I3E) even though it is getting interesting below 9p.
Edmund's contrarian play article on oil at the weekend encouraged a further look.
I have followed Arrow Exploration (LON:AXL) in the past. They seem to be drilling everywhere in Columbia. They have missed production and capex estimates very recently on a couple of occasions. If estimates are correct in 2025 and 2026 it will go much higher. Are they? I don’t know. Good thing is that huge capex needed is and will be funded from existing production and earnings. Looks good on paper.
Jeez its only Wednesday, at this rate we'll be comparing the UK markets to the Amman stock exchange by early next week.
Renold (LON:RNO) was a stocko darling at the turn of the year and has fortunately held its gains over the past month. There was a big buy of £600k yesterday and number of other decent sized buys going through today, nothing crazy but 50k here, 20k there. Looked back and saw there was a trading update around this time last year (8th Feb). Hoping someone knows something I don't and we might hear some positive news tomorrow. Just speculation on my part but thought I'd share. (I hold, M)
Renold (LON:RNO) is one of my top 5. There has been a continuous stream of good turnaround news since Paul highlighted them a year or 2 ago. I've noticed the large volumes although some of them appear to have been their own pension fund buying chunks of the company. I like to think they might have a reason for increasing their holding?
Hmm good and bad on hVIVO (LON:HVO) result of placing announcement in my view.
1) Cathal and the other director actually sold 50% of their holdings (not 25%) so that’s less aligned as they’ve taken quite a bit off the table (bad)
2) The fact they did that suggests significant institutional demand (good) - you would imagine they will add in market to build stake
3) There is a now a 12 month lock up (good) no more of these secondary placings
4) They both still have significant interests in the price going higher (good - but not as good as the 75% I thought).
On balance I’m now wondering why they’ve sold quite so much but Cathal does have a bit of form here, selling previous stakes in businesses much too early. I wonder if, as a serial entrepreneur investor, whether his patience window is long enough to maximise his returns but we’ll see.
Given the year lock up and the 90%+ revenue visibility and current trading momentum I’m not particularly concerned, particularly given the demand for stock, but the sale is now giving me food for thought.
hVIVO (LON:HVO) I’ve got four letters for you. BOTB
Definitely written tongue in cheek. But I really took fright at the size of the disposal. What does Cathal know that we don’t? He’s hedging his bets at the least and I’d be thinking of doing the same if I was a holder. I’d hate to be the person to encourage you to quit the name when it could go onto much greater things, but I do find the disposal gives serious pause for thought. At the very least, I’d expect it to signal the end of the upgrade cycle, and a period of consolidation in the company’s progress.
Good luck, whatever you choose to do
Hi BnB : Bit of a different scenario to BOTB where they took most off after a lockdown boom. These guys are retaining 50%.
With hVIVO (LON:HVO) the next years visibility is in the bag as is much of the following year. The CEO & CFO have set a medium term target of £100m revenue at mid 20’s margins. They are both quite cautious - under promise, over deliver is the mantra so they will have thought long and hard about that.
My suspicion is that Cathal likes to recycle investments. I think he moves on to the next thing and I’m not sure he is actively involved much in hVIVO (LON:HVO) now on a day to day level. What I don’t like is the nonsense about creating liquidity - thats just an excuse to say “an opportunity came up to sell some stock and I took it”. But then he is pretty promotional so the spin doesn’t surprise me. He did the same with Amryt Pharma which sold for a huge amount more than he sold out at.
Irrespective hVIVO (LON:HVO) is a strong company with a good moat, a world leader and as a CRO is undervalued against peers despite my assertion that global leaders should really be on a premium. I had expected a corporate event in the next year or so but the timing of the sale makes me question that. If that was on the cards Cathal would be holding on so that tells me it isn’t in the mix. Fundamentally he is not a long term holder of businesses - his track record tells us that.
hVIVO (LON:HVO) Surprised this has not brought about more comment / analysis here today - According to Stocko only 20.7% of the shares are held by major holders - so near 80% already available in the Market -so what's the real story ?
As I say the real story in my view is that Cathal is not a long term holder of businesses and he has seized an opportunity - this is not unusual for him. The RNS rationale is b*****t though.
Cathal has acknowledged in the past at hVIVO (LON:HVO) that he 'has the attention span of a gnat', so this isn't a surprise.
'Steady as she goes' IMO
CCH The dividends are denominated in EUR, so how does that work with a GBP-denominated account?
Interesting that Paul does not comment on Temu potentially eating some of Dunelms lunch. But does think that is possible for Shoe Zone. Personally I think it is equally likely that Temu will affect Dunelm having successfully bought a bunch of home items from Temu recently. I think Dunelm is a very well run business but I am more likely to buy homeware from Temu than shoes.
Hi Fegger,
Yes I was thinking about potential downsides for Dunelm (LON:DNLM) and the competitive threat from Chinese direct to consumer company TEMU did cross my mind, but it seems to focus mainly on smaller items that can be squashed into a plastic bag. Whereas a fair bit of the things DNLM sells might be too bulky/heavy to air freight into the UK possibly? That was my line of thinking, hence why I didn't expand on that point in the report.
If you think TEMU might be more of a threat to DNLM, then you're right to flag it for us all to ponder, many thanks, Paul.
PDD Holdings (NSQ:PDD) aka Temu were one of the biggest spenders during the recent Super Bowl too, with record viewer numbers '123.7 million U.S. viewers, according to Nielsen estimates on Tuesday.'
Perhaps due to Miss Swift now dating hunky football star Travis.Or that's how her pr team like to spin it nonetheless.
'A 30-second spot in Sunday's game cost companies a whopping $7 million. Temu's advertisement featured animated characters using the app to transform their lives to the tune of a catchy jingle.2 days ago'.'Temu dropped $21 million on 3 Superbowl ads'.They do seem very US focused right now.. I donno.I'm sure they do want some UK sales too!
Thanks for the coverage of Coca Cola HBC AG (LON:CCH) - great company and looks like growth at a reasonable price, with very limited risks.
Bloomsbury Publishing (LON:BMY)
Can anyone shed any light on why Stockopedia currently has Bloomsbury Publishing as negative EPS growth, -9.1% ?
Sharepad is forecasting a positive 17.2% EPS growth !!
stockopedia figures are quite often out-dated, that is why!
That is disappointingly poor to be honest. Especially as it is covered this morning in the SCVR and no mention is made of the misleading numbers.
Bloomsbury Publishing (LON:BMY)
The reason why the EPS Growth is shown as negative is because of the time frame it is referencing. The figure in the top right of the StockReport you are referencing is the forward rolling forecasts, comparing 2025 and 2024 estimates on a rolling basis. Given the 2025 eps figure is below 2024, this is negative. If you look at the growth based on TTM or comparing 2024 vs 2023, you will notice a positive growth figure.
From the Times today, what a difference a 0 makes...
LYFT took Wall Street on a bumpy ride overnight thanks to a typo in the ride-hailing firm’s earnings release. Shares spiked more than 60 per cent after Uber’s wannabe rival said margins would improve by 500 basis points in 2024. Those gains fell away dramatically after chief finance officer Erin Brewer, who took up the job in June, admitted on a call with investors that this would actually be 50 basis points. Katie Prescott has more here.
And here’s a brief analytical synopsis for all you AI jockeys in here…
Margin v volume
Do you know where that is going and why?
(I don’t as I’m not playing as I ain’t that smart)
As Bloomsbury Publishing (LON:BMY) is in the news today I felt I must pass on a Harry Potter story I was told this morning by an Author friend who frequents the Coffee Shop my wife and go to most days.
When J K Rowling was trying to find a publisher she went to Bloomsbury with her first Harry Potter Book. The guy read the book and tossed it in the Waste Paper Basket. During the day his school age Daughter came to the Office and said "what can I do for the rest of the day"
He gave her the Harry Potter Book and she just could not put it down. She told him it was utterly brilliant. Luckily he listened to her and changed his mind. A historic change of mind.
Now I have no way of knowing if this is true and as far as i know it may be a well known story but if it is apologies but it was the first time I heard what appears to have happened.
According to Nigel Newton, the Bloomsbury chairman, it wasn't quite like that. He did give it to his daughter Alice to read, but not after he had binned it. He just wanted her opinion.
Here is the report https://www.independent.co.uk/... and the actual interview https://www.independent.co.uk/... from 2005. I must say he comes across as very engaging and explains Bloomsbury's unique approach.
Sounds like Sir Hugh Facey didn't know much about cricket. The umpires don't keep the scores....!
This is from the Mail about 10 years ago.
And then there’s the Hugh Facey doctrine on accountancy: ‘If you’re running a cricket team, you send in a batsman to bat and a bowler to bowl. You don’t send in the bloody scorer. Accountants are great at keeping the books. But don’t let them run the bloody business.’
He is even more withering about personnel directors. ‘They haven’t a clue about anything.’ He says that in the 23 years since he started Gripple, he has only had to make one redundancy — in 1996 (and that same man rejoined the company last week as a senior executive).
Transense
Just lightened my position by 25% guess Yiannos getting to me .
What is disturbing me is no CEO and the two senior figures seem to be CFO and an chairman who comes from an accountancy background who isn’t in the business day to Day .
Sir Hugh Facey once said to me “accountants are umpires they keep the scores they don’t make the runs”
Also asked for a quick light tough scoot round the factory to see the operation and getting fobbed off to the advisor . Doesn’t feel quite right .
Mmmmm , still a good position and share price pretty strong and unusual liquidity so think Better to play safe .
Also quite a nice feeling to actually see cash in the bank and my business partner in Java wants to buy a beach on Sumba Island which sounds more fun though there are big mosquitos .
Do not blame me though later!
I always found in my business it was very important to be able play the blame game
It’s still a big enough position don’t worry for a micro cap
Planetx - I've been a Chartered Accountant of 25 years working in commercial roles in SME and AIM listed companies I can assure you Sir Hugh Facey is talking balls!!!!!!
Re dead markets. Until approx 2012 Japan was truly a dead market in eyes of world....however professionally I invested there and travelled there a lot. It was great for alpha! Volatility and unpredictability over short time frames as macro stuff could wash over hard and shake things up...but if you could find a good stock picker the opportunity for good cumulative returns was exceptional. Japan is bigger than UK....but today UK doesn't feel dissimilar narratively speaking (and Europe too)
So I'm quite bemused about all the UK v US (and other places) conversations. I was (professionally) a global investor ('macro' and allocation not stocks...so my views on small cap stocks are defo not expert in anyway tbc!) and have looked at and travelled to huge number of markets looking for opportunity. They all blow hot and cold (UK and Europe have done so for a long time mainly as they embraced the illogicality of austerity since 2008 IMO).
A myriad of local factors and sentiments move each market and components within it in different ways. If a market like US is beating everything else on average...then that story is in the price to a significant degree. The beat may continue (for momentum reasons - price, narrative, economic, fundamentals) but it happens for new reasons not what you can easily see....and if you think its obvious at that macro sort of level then imo you are a sucker.
Stick to what you know a bit about unless you truly are a trader or systematic investor of some sort that explicitly plays probabilistic edges without necessarily needing to know too much about stocks. I live in UK so I've decided to focus mainly on UK stocks (and particularly 'inefficient' small caps) for most of my personal selections. I go overseas when I have a thematic perspective to pursue that I understand something about (usually something capital cycle related - so uranium is my recent). I want to 'time' my selections decently but if a place is truly 'inefficient' then timing it well is a contradiction.
Being an outsider to a market tends to put you at a disadvantage, acutely so when it comes to any attempts at timeliness in positioning or perceptions.
As for NVIDIA (NSQ:NVDA) - great stock and call if you did it - AI was definitely and exploitable theme...but I think there may be a handful of investors in the world who understand how to value this. Dumb balance of probabilities is it goes significantly under its current level. When something is that hot I think you've got to know when you're going to get off and be wary of over belief...
IMO a lot of people are chasing yesterday's news at the moment....doldrums ex US and hotness in bit of US makes people want to chase (and the narratives are beautifully formed)
PS the best professional investors with long term records are nearly always deep fundamental guys and usually slow moving ones at that who have a niche/identity and plough away at that. Traders in stocks rarely sustain (they can in macro)...for moments they can be hot as hell when things all fire for them but the acute heuristics tend to die (or they get too much capital). More possible to be small and sustain trading (I don't doubt that)
This is a really excellent post. Thanks for sharing .
Hi
A few days ago a few lamented that they could not buy Arm Holdings (NSQ:ARM) on their platforms, HL explicitly. I think one noted they could on A J Bell.
This LinkedIn poster (Richard Holway MBE) however, sheds additional light on the problem. One paragraph states ....
'However, today an even more serious issue has arisen affecting all trading platforms in that you cannot hold ARM shares in a Stocks and Shares ISA. ARM shares are only available via the American Depository Share (ADS) mechanism. You cannot hold ADS shares in an ISA. Both Hargreaves Lansdown and AJBell have publicly confirmed this.'
If interested this is the posting on LinkeIn.
https://www.linkedin.com/posts...https://www.linkedin.com/posts...
Regards
Howard
Arm Holdings (NSQ:ARM)
I had a similar problem with a holding in Abcam (LON:ABC^L22) when it moved from the London listing to the US where it was only available via the American Depository Share (ADS) mechanism. So it had to be sold within the ISA and repurchased outside the ISA wrapper, only for it to be taken private not very long after.
Hi shopping365
Oh that's not a good outcome
Regards
Howard
Bloomsbury Publishing (LON:BMY)
Great company no doubt.
I do not hold although I have in the past.
My problem and that relates to the whole UK market (small caps under £700m cap):
This has been trading around 500p previously and after 4 beating estimates the company trades roughly around 570p (dividends included).
If this was listed in the US and with their cash generation all investment analysts and advisers will be crying for share buybacks and reduce the share count. If this mentality does not change in the UK small market cap sector I believe there is no future.
Somero Enterprises (LON:SOM) another cash machine buying back a ridiculous small amount of shares where they could have reduced the share count by about half of its market cap!
The difference between the two stock markets. Over the pond they are reducing the share count year after year creating liquidity day after day after day………..
yiannos1
If this was listed in the US and with their cash generation all investment analysts and advisers will be crying for share buybacks and reduce the share count. If this mentality does not change in the UK small market cap sector I believe there is no future.
here here - its great to see someone that actually agrees with regard to the obvious benefits of share buybacks. Being frank i think the majority of uk investors wrongly seem to think sharebuybacks suck - i can understand why they are suckered into this thinking faulty/over simplistic thinking - if their experience of buybacks is a crapola company going nowhere spending money on sharebuybacks doesnt alter the fact you shouldnt be invested here end of - if companies future propsects are going into reverse. I love simple companies that manage to buy back shares and continue to move the business forward (eg Next)- perhaps usa managers are savvy enough to realise do what you do well better is better and buy your own stock is way forward rather than risking your entire future on acquisition that may or may not work out and may destroy shareyholder value if it doesnt (brickability last 6 months) - i suspect americans have it much easier with far larger market that its easier for them to grow to biegger size organically without market sauturation whereas uk companies need the dreaded move abroad or into areas they are probably not expert at and one shouldnt presume they are sooner than similart us company.
Heyho ho - simple solution for anyone that thinks buybacks arent good value - if you are saying they are not good value for company you own who is buying back shares why on earth do you not consider selling up . surely if there is no value for them to buy there is no value for you to continue holding ?
I would say companies do need to have spare cashflow or decent outlook ref profits to be going down the buyback route - so i wont disagree there may be the odd uk case where managers are doing somehwat risky buybacks for reasons that may suit them when sits not obvious that shares are cheap or value compared to historic norms.
Uber Technologies (NYQ:UBER)
Just announced an inaugural buyback of $7B.
Some buybacks Brickability (LON:BRCK) for example or Speedy Hire (LON:SDY) were just desperate measures by their board. I am talking about cash machines the likes of Bloomsbury Publishing (LON:BMY) that have no debt. Important feature in the US that most of these big companies have no debt!
I am talking about cash machines the likes of Bloomsbury Publishing (LON:BMY) that have no debt. Important feature in the US that most of these big companies have no debt!
100% agree and no one is better placed to know prospects have been good for the last 18 months _ than the company mangers - if everyone here is screaming value and doing great surely management should know buybacks are no brainer - deffo missed opportunity for buybacks at levels significantly below where we are.
Factually incorrect. Most have debt. Some at levels that are significant relative to profit or even turnover (eg NVIDIA (NSQ:NVDA) since its so topical)…
Does anyone even look at the accounts of these US stocks or just spout hot bs endlessly in a U.K. small cap forum?
I’m not up to speed with Uber Technologies (NYQ:UBER) but if it’s buying back $7.5bn stock then it’s probably issuing debt to do so.
I’m sceptical that most (any!?) people talking up big US stocks here have done anything other than narrative surf.
I hope this will not be another DAX vs FTSE performance and admit late in the evening that DAX has outperformed (after of course researching it).
Most big companies have no debt (perhaps no net debt is the right phrase) and you have to adapt on their reporting and accounting standards whether you like it or not. That’s what all analysts do when they deal with US companies.
I have in front of me UBS AG (NYQ:UBS) research on NVIDIA (NSQ:NVDA) forward cash estimates.
2024E=£18B
2025E=£53B
2026E=£90B
If you think you can analyse accounts or US companies better than UBS that’s ok by me. I do the opposite and tend to look at these reports and follow them.
No need to answer to you again as I feel that it’s just personal attacks without no proper research behind your comments. This has started with the Cornerstone FS (LON:CSFS) debate and you just keep going on about everything.
All the best
Does anyone even look at the accounts of these US stocks
i do - happy to discuss the merits of dropbox - paypal - corsair or any other any other us company.
Some at levels that are significant relative to profit or even turnover (eg NVIDIA (NSQ:NVDA) since its so topical)…
You picked a really poor example here mojomogoz - nvidia per latest release 30/09/2023 had chomping "net cash position" in the region of $9 billion - the debt they have is more than dwarved by their cash (and equivalent) balances. I am sure you would agree its not real debt if they hold more than enough (double) the cash to cover the modest debt they have !!!!
I’m sceptical that most (any!?) people talking up big US stocks here have done anything other than narrative surf.
perhaps those talking down the stocks are doing the same based on your poorly picked nvidia example ?
Note i do somewhat agree with your overall point - so apologies for my nit picking (we all know i cant help myself in that regard)
I’m out of date maybe. I just looked at annuals on other data service and at end of last financial there was mix of cash, investments and debt…ie there is debt. I made no mention of net amounts. Most big tech (from memory) have some mix of the 3. By no means did I say there was either net or stressed debt…specifically, Uber I said likely issues debt to buy back $7.5bn stock…maybe I’m wrong….but hey so what as this is A SMALL CAP UK FORUM…
And I stick by most people touting hot US stocks don’t know what their talking about from a fundamental perspective and ability to carry valuation or growth…someone can moan about my unreasonableness here…but this is a historic area of expertise for me and I don’t need to acquiesce to some emotionally unstable ego (not directed at you tbc)
Can we refrain from using offensive langauge such as "emotionally unstable ego". I presume you are not medically trained and qualified to make such an evaluation. In fact, one could say this about you, based on some of the things you have written. I just laugh at times, when "experts" who haven't made dime or at least kept a dime, are claiming superior intellect.
no worries - my point was the yiannos was on the the ball with the figures they quoted. Its a matter of fact they (nvidia) have double the liquid cash that they have in debt so stong net cash position of approx $9 bill - so imho you picked exactly the wrong company to highlight your point as they have strong "net cash" - no biggie i agree they do have debt but think the text you posted that i highligthed was highly misleading by absence.
surely you have to agree if they have $9 bill of debt and $18 bill of liquid cash its misleading to focus on the debt as being an issue without highlighting the more than compensating cash that exists - its the net sum that really does matters most in the real world and it was you that tried to suggest this company has debt issues whilst not highlighting cash thats clearly not telling the real truth
ePerhaps you could be kind enough to agree that the $18 bill quoted by yiannos in that regard is likely to be real and accurate figure rather than nonsense as i think you might have suggested and also that this company has no debt worries due to excess cash then hopefully we can all move on.
Just reminding again that these are UBS figures/estimates and not mine.
Have worked in the industry for so many years-I have experience and knowledge but I do not claim to be an expert and I certainly do not claim to know everything. Buffett and Lynch are experts. Porter Colins is an expert.
Nothing more to add-Guybrush was spot on!
I checked the latest 3 monthly filing to 29/10/2023 and there was $18 bill cash (also $9.6 bill debt) - so that kinda evidences that strong cash figure you quoted is real.
rmillaree
A brief final reply. We can’t try and find excuses for each buyback that was followed by the share price never again reaching the buyback price! The 3 examples I gave were just that:I.e 3 of dozens of similar examples I know of . There are many more I won’t know about.
e.g your covid excuse for Whitbread shares. The Costa sale was in 2018 and the buyback supposedly rewarding Whitbread shareholders was also in 2018 and long before covid.
There are some plus points for buybacks but the claim made SO often by commentators that they “reward” shareholders or “return cash to shareholders,” is nonsense. They DON’T.
e.g your covid excuse for Whitbread shares. The Costa sale was in 2018 and the buyback supposedly rewarding Whitbread shareholders was also in 2018 and long before covid.
that was my point - Whitbread would have not expected covid would come along in advance when they did share buyback - obviously the shareprice was crucified by covid. they cant have seen that later event coming along so its harsh to say sharebuybacks were bad choice at the time - they were just plain unlucky they huge profits were replaced by huge losses temporarily not so long after buybacks.
anyway i dont think we are massively disagreeing i was simply against the default argument that "sharebuybacks are bad news" - they probably will be for poor quality companies but shouldnt be for good quality companies most of the time where price paid for buybacks is reasonable.
I would certainly agree they are not really a reward to shareholders or a return of cash to shareholders - clearly its a calculated gamble by the managers that the company funds spent will hopefully generate good value for continuing holders on the basis that future prospects will be bright. In some respects its somewhat doubling down that company will perform well in near future.
The Whitbread Costa sale buyback was 2 years before covid! Covid is irrelevant.
ok i will give this one final last attempt as my point is clearly getting lost in translation here
you said
Another wasWhitbread (LON:WTB) . They “rewarded “ their shareholders by spending the huge sum they got when selling their Costa business to CocaCola, on buybacks. The shares then fell heavily and are still well below that supposed reward.
yes its a fact shares fell heavily and in hindsight now that buyback looks bad judgment as the price hasnt recovered to buyback levels - the reality is though the shares only crashed when covid came along and that crash was due to covid - so imho the reasons for the buyback failing are entirely covid related - this is evidenced by the fact the shareprice just before covid was performing fine and dandy (compared to most of 2018 to start of 2020) - one would expected that price now would have been above buyback price without covid imho - we cant be sure of that fact but its pretty sensible conclusion to me.
ref current buybacks on the basis that premier inns and associated brands are a decent business with good outlook i suspect that current buybacks might work out well - i wouldnt say the price they are paying is stonkingly cheap here but if ignoring leases they have little debt and are confident of the future buybacks are imho a fair shout - the true test will be future trading though thats for sure. I would agree they probably should have an upper price they are happy to pay ref buybacks (i suspect that is probably the case) - note price has reached a post covid high after buybacks started - so for those that really think its the wrong choice at least they have had the option to exit their position at near 4 year high if they dont like this cunning or not so cunning plan.
Hi Ken,
They do and they don’t and it is a subject that investors many times disagree on. I am a shareholder as I said earlier of Nanoco (LON:NANO) and I prefer a huge buyback or a tender offer. Every company is different and each situation is different and I can give examples as well that buybacks worked better than dividends.
They do enhance EPS and by that way the next dividend amount paid (say the same as the previous year) obviously gives more to shareholders as there are less shares. They do return money to shareholders the buybacks.
Come on fella, respect and value all opinions even if they don't match your own - please disagree in the right manner.
rmillaree you're perfectly entitled to your own view on buybacks but please don't have a go at those that disagree. We are allowed to disagree.
I disagree as these are usually presented as Returns to Shareholders - which they are patently not. They are buying the shares so those selling and receiving the cash are no longer shareholders. As a shareholder if you want to return money to me either get the sp up (and I can then decide if I want to sell) or give me a divi (which I can then reinvest in you or elsewhere). Buybacks remove that option for me. You are in effect making the decision for me. I may not wish to sell the company as a result as I may still believe it will generate me a good return. It's a bit like tax - I'd rather pay less and decide how I spend my money than have someone else do it for me. Just my point of view.
Providing the company has not had to pay interest on the money used to buy the shares back or even worse taken on additional debt to do so then I accept the inherent value of the business remains the same. How often though do Directors get the timing of buybacks right and how often wrong?
If they want to reduce the number of shares in issue and get the EPS up then why not pay a special divi and then run a consolidation? Now that most shares, if not all, are held electronically it's an easy exercise. Would have been much more logistically difficult when we all held paper certificates.
We are allowed to disagree.
If I understand correctly your last paragraph refers to tender offers?
Example Nanoco (LON:NANO)
This company has been trading for many days about 25% below 2024 cash when the SP was 16p.
(I have bought a reasonable position with an average of 17p).
In addition they have announced that they will be returning about £40m (60% of current market cap) back to shareholders.
For example if the announcement about this return to shareholders is a special dividend then we will waist 12p and make no value for shareholders. But if they decide to make a buyback and cancel the shares or a tender offer at about 37p for 1/3 of shares then they will create value for the shareholders and this basically what they would have chosen if listed in the US. It’s on these basis that all these tools should be used to create value.
Imagine all these Somero Enterprises (LON:SOM) dividends were buybacks and cancellations and thus enhancing EPS.
This is basically our disagreement and the benefits of share buybacks and/or tender offers to shareholders.
I don’t think that rmillaree is stating that debt should be used for buybacks.
just to add my tuppence on buybacks, I think they can be both good and bad for owners.. if a business is fundamentally undervalued and has cash in the bank then surely it's beneficial. i.e if there are less of us, there is more to go around.
if it's used as PR or when they have debt , used to raise a price to hit management incentives or when the future is unsure.. I'm not sure they are better.
So as is so often in investing (or more specifically are buy backs a good thing?) the answers is usually ... it depends...
I'm only adding this rather simplistic point to highlight that it's possible for both advocates and critics to be right. I'm a strong believer that a 'tense' opinion doesn't help anyone, especially in investing. one could be 100% Genius correct but if the rest of the dullards out there don't see it..... the price would never go up ;-)
You are correct and basically we are all saying the same thing in a different way.
i think most peeps who are pro buybacks would agree 100% with your comments Patrickmylnetrade - the fact that buybacks may be a no brainer or a good idea certainly doesnt mean that they are always a good idea . They often cover over cracks when a business in lacking direction or as you say are being done for motives other than "business is going great" and has great cashflow and shareprice is somewhat under appreciated or not obviously expensive in the market - thats good time for buyback imho.
On the flip side those that dont like buybacks seem to take the viewpoint they are nearly always bad , when that can be far from the truth. The real positive long term impact that can be had when share count reduces long term is pretty simple to understand if we get more of a growing pie. To be fair to those that dont like buybacks there are plenty of companies that have performed very poorly after buybacks - with the benfit of hindsight though its normally the case that future earnings did not meet earlier expectations anyway in which case if companies prospects worsened materially best thing to do is exit the share altogether as soon as companies prospects go down hill - at least buybacks can add some liquidity for that those that dont like em and may choose to sell.
one could be 100% Genius correct but if the rest of the dullards out there don't see it..... the price would never go up ;-)
for situations like this buybacks are fantastic - if you grow earnings by inflation and are on constant pe of 7 and use all spare profits to buyback shares - its only a matter of time before shareholders are rewarded - run that on spreadsheet and see what investor returns are compared to paying out profits as divis over 10 year - 15 year period !!
As a shareholder if you want to return money to me either get the sp up (and I can then decide if I want to sell) or give me a divi (which I can then reinvest in you or elsewhere). Buybacks remove that option for me.
Here you want something that suits you - divis dont suit everyone so its pretty obvious that there can be advantages to buybacks that you are ignoring here - presumably you are lucky enough not to be paying the top rate tax of 39.35% on your divis - for peps paying tax on divis share buybacks may make more sense . One can flip it round and say if you own more of the company then you can sell some shares and have same % ownership if you dont like buybacks - albeit i would concede that for samll amounst that isnt practical.
What is abundantly clear though is the the i hate share buyback brigae often have a very biased narrative.
Hopefully what you wont doubt is that we the owners and shareholders know the company is doing well and the shareprice is on the cheap side and future prsopects fine then surely you arent agruing that outcome long term is fine.
but please don't have a go at those that disagree.
My viewpoint is just mine its fine for you to have yours and see mine as illogical as i see your anti buybacks stance - i am certainly not saying you cant have your opinion or that my opinion is right and your wrong (i am more than happy for you to say my thoughts are nonsense) - in some resepcst your post comes across that i shouldnt have my opinion that some peeps against sharebuybacks simply dont see the overall picture or are comigg from biased viewpoint - in that regard thats my opinion whether you like it being said or not - its not menat to be there to wind anyone up.
Sorry to nit pick rmillaree (a reference to your earlier comment that you also find it hard to resist nit picking) but your posts are often difficult to read due to a multitude of typos being a regular feature.
I do find your contributions most helpful but I've simply reached the point where I felt I should say something.
Perhaps you could type a bit slower and proof read before sending? Or maybe use a spell checker?
Apologies and sympathy if you suffer from dyslexia.
For your information I suffer from degenerating vision.
Snazzy
cheers snazzy will try harder
rmillaree.
A few Compsnies use buyback’s effectively. E.g Next (LON:NXT) who will only buyback when believing the share price is cheap.
Far too many Companies buyback at inflated prices and continue buying back all the way dow.
Abrdn (LON:ABDN) started their multi million buybacks at £5 about 6 years ago. They’ve bought back consistently ever since and the share is now £1.65 and has never again been back to £5. There are so so many similar examples.
Marks and Spencer (LON:MKS) Stuart Rose infuriated me as a long term Marks shareholder by insisting that he had rewarded investors with a £2 billion buyback, all around £4. That was SO many years ago and even now after more than doubling Marks and Spencer (LON:MKS) is nowhere near that supposed reward?
Another wasWhitbread (LON:WTB) . They “rewarded “ their shareholders by spending the huge sum they got when selling their Costa business to CocaCola, on buybacks. The shares then fell heavily and are still well below that supposed reward.
Mining sector Companies that used to spend multiple £billions on buybacks have realised AT LAST hat they were a waste of money as their share prices subsequently fell to extreme lows in 2015 Mining bear market. e.g Anglo American (LON:AAL) fell to just £2.20 and Rio Tinto (LON:RIO) to £18.
So now Mining Companies do what sevenccc has advocated, They now pay huge special dividends in the good years. E.g RIO paid nearly £8 in dividends in 2022. Not bad even at the current £5 or so share price and over 30% for any who bought the dip in 2015. I hold RIO and other Miners and have really appreciated their REAL money from those big dividends.
Buyback theory is fine. Few who advocate buybacks seem to check out the subsequent share prices. I often use the share price gain on the day a big buyback is announced to sell. That’s because buybacks reward those selling (who have the Company buying back as a willing buyer if the shares they are offloading). It’s often a fictional reward for those who stay invested.
Few who advocate buybacks seem to check out the subsequent share prices.
I would advocate for exactly then opposite one should check - i 100% agree that company that doesnt trade well in the future will have pi ssed money up the wall on buybacks - the whole point is if company prospects arent what they used to be , and they are using buybacks when prospects are not good thats probably an easy choice to sell up sooner rather than later particularly if you get the impression that buybacks are not done for the right reason. In summary buybacks didnt make the business crapola you have simply highlighted poor businesses and businesses that have perhaps been unlucky with covid (whitbread?)
Marks obviously isnt the consistent money making machine it used to be (although thinsg seem to be loking up) i think we would all agree its tougher for them now than it was in the good old days.
Ref whitbread - it looks like they sold costa just pre covid - i think the reasons for poor shareprice perfomance are much more covid related than buyback related - i for one would not blame them for not seeing covid coming.
Abrdn (LON:ABDN) - i supect thats similar to aviva i held aviva for quite a while (that was bottom fishing in hope rather than sensibility hopiung some value would out ) but sold out when they sold units for big wonga and were buying back shares left right and centre - prospects werent terrible but i did get the impression that share buybacks were in the absence of a good plan to improve profits - so i sold out. the reality is i was not convinced aviva was company going places - i suspect arbdn is similar so not sure why peeps would keep holding.
better example are companies who one would want to own shares in like next , if whitbread keep delivering there is hope
anyway this argument is probably now going round in circles somewhat - its always about the future company prospects that matter - in that regard buybacks can make a bad egg taste even worse.
I try and invest decent companies that have both dividend distributions, and share buybacks (which look sensible on current market pricing, cash generation etc,) I tend to do this within an ISA, for a further tax free boost, and I also nominate a DRIP reinvestment programme for them.
I am trying to have more of them in my ISA portfolio, but confess there are a few impulsive buys still in there from when I didn't follow my own Captain Sensible perameters which have cratered. I am fighting that other devil on my shoulder regarding these, namely staying in and looking for an upside, rather than selling and looking for better opportunities.
i dont think any of us have the answer as to whether share is going through temporary bad patch or whether that company has had its day medium term . The reality is most companies have bad patches and pull through so its never an easy decision to sell. I would say when managers have spent the crown jewels on buybacks and then soon after trading worsens and there is little good news in sight - that would make me think why were managers doing buybacks at that time - the fools Unless pe is ridiculously low in think buybacks are for times when its clear the financials are progressing nicely Bloomsbury being a perfect example of then time being right for the last 12 months or so.
Anyone know how the share buybacks at Supreme (LON:SUP) work? Price has been creeping up lately but only 75k bought so far. Tia
I believe £1m in capital is being used to buy back.
Yes but there are Market Abuse Rules they need to follow. So not simple as buying whenever they like. What are these rules? Supreme (LON:SUP)
Usually for buy backs they give an irrevocable undertaking to their broker based on certain price criteria…..eg average VWAP. That means the broker buys the stock back and MAR rules don’t apply to the company. Ie they get on with the day job and the broker buys back based on price/volume and not timed from a news perspective.
Supreme (LON:SUP) buyback is ceremonial rather than fundamental. It is there to signal that the business is in strong shape irrespective of some of the nonsense and rhetoric published about the vaping division. It will mop up a little stock but unlikely to make any diff to the share price.
I think the movement up we are starting to see is because investors are starting to realise that the business has much stronger long term fundamentals than the hysteria in the mainstream media might imply. This is not unusual - we’ve seen it many times across other companies and the share price trends are generally very similar.
Michael Taylor of IC and past writer here analysed Supreme's charts recently. It's one of his favorite shares for 2024 I believe. I've added it to my watchlist and wait eagerly for a breakout, which looks close . I have to learn to be more disciplined with my timings though, I often jump in far too early and pay the price with a lighter pocket shortly afterwards. Fudamentalists need not wait though, can buy in at any time it seems.
Guybrush - do you not take a small position then increase, or do you put it all on the table in one go? I've been building a position in Supreme (LON:SUP) from £1ish - £1.10 and feel fairlly comfortable adding more, although admittedly I'm not a chartist.
Viz, I scale in. Generally, I take a quarter/half a position on a first breakout and half on a 2nd breakout. I don't like adding on higher breakouts than this as the risk/reward then becomes less favorable. Each full position is no more than 25 percent of my total equity and I always use stop losses of maximum 10 percent.
At least that's the theory. I find that on days when I haven't sleep well, and that is quite often(noisy neigbours), I get brain fog and stressed, and then its open season on the position size.
For those who don't care for breakouts, at least Supreme is comfortably out of a long term downtrend. It's now in a stage 1 phase (moving sideways) and has been for about a year now;the Quality rank, which I love now, is excellant(green and 89), so it all looks good really for buy and hold investors right now as the start of a long term uptrend looks possibly on the cards, IMHO.
As a trader though, I'm trying to grow my funds as quickly as possible so I'm trying to skip the phase 1 which can last years, and wait just for phase 2. Easier said then done though, as fear of missing out can dominate the emotions quite frequently.
Guybrush - great insight into another avenue of how people look at things, thank you. Whilst I don't know your individual trade situation, looking at Supreme (LON:SUP) it would be interesting to hear the trading position that makes you take a rational/emotional position on? Charts, valuation, future prospects?
*edit to add, as I've said previously, I believe in management, the market and the current valuation.
HI Viz,
Trader/investors can fall in to 3 camps: pure fundamentals, pure technicals, or both; within the "both" camp the mix can favour one side more than the other, or equally(other camps are more esoteric such as astrology- appararently the pull of the moon affects harvest so it may not seem so ridiculous). I belong to the "both" camp, but leaning more towards the technical side. The reason is, while anything fundamental will always show up on the charts, the charts of shares can often rise/fall with no fundamental reason whatsoever, but plenty of technical reasons . Also, I find it interesting how someone firmly in the fundamental camp can argue that their side is best, without having any knowledge of the other camps.
In Schwager's market wizard books, which contain interviews of best trader/investors on the planet, these masters belonged to every camp, so it really is a case that there are many ways to be successful in this game.
I focus on charts firstly to quickly find shares with the right setup, then I dig in to the fundamentals: rising revenue, rising profits, decent ROCE, low net gearing, stable average number of shares , etc... basically the data in the Stockreports is perfect for this analysis, then I go back to charts for timing, and apply risk managment on the buying and selling of my trades. I also check the latest RNS for updated financials, as Stockreports will always be behind due to the lag of releasing the latest full financial reports.
This has taken me a good decade and a half to get here but I feel I have finally discovered the Big Whoop, or not. :) Plenty of ways to skin a cat though, so your way could work just as well if not better.
Hey Guybrush how do you screen for rising revenue? I can only find Sales but not comparative sales....thanks. Dave
Hi doctor dave, on the screen : add rule->growth->sales CAGR(3 years) or net profit 5 year CAGR(no option for 3 years) and set them both to greater than 10 percent, or whatever figure you desire. Or you can use Sales growth, Q on Q, for a shorter time frame to catch them early. And for earnings there is EPS growth Q on Q etc...
Then there is that nifty micro bar chart that appears if you move the mouse over the financial data on the Stockreports, to see the trend visually.
You will see stocks such as Bloomsbury Publishing (LON:BMY) on the list.
Great thanks Guybrush hadnt seen the Sales Growth option (though on my phone it is 2 yr rolling !?). Have added it to my BESTEST screen which screens for stocks with a collection of good fundamentals.
Great thanks Guybrush hadnt seen the Sales Growth option (though on my phone it is 2 yr rolling !?). Have added it to my BESTEST screen which screens for stocks with a collection of good fundamentals.
It's my pleasure doctor dave. On my phone, the default setting for sales Growth is "TTM", but in the drop down menu(have to scroll right to see it) there are other time frames, "2 year rolling" being the last one.
If you go to discuss->see all blogs -> screens and stockranks, there is a treasure trove of articles on the subject of screens. That's how I discovered the Sales Growth and Earnings CAGR screens. It was about a year ago, I think, the article in question.
All the best.
Anyone following Petrotal (LON:PTAL) - I see RNS this morning of quarterly dividend at 2c
Looks like that should equate to an annual 15% dividend and a reducing share count from buy backs - so maybe closer to 20% total return and thats before any capital gain improvement. (Similar return last year)
Has a production profile that has in excess of a decade already built in and a very strong replacement reserve ratio too.
As a dull and boring oil stock an annual return in dividend/buy back alone of 20% meets my criteria - happy to bank and reinvest that annually but looks significantly undervalued from a market cap perspective too, so good upside imo. (Brokers targets vary between 85p and 145p but both are considerably higher than current 44p.)
Remember regarding Petrotal (LON:PTAL) that the US$ may have an impact and that 15% minimum withholding tax is taken off. Get your W8BEN into action
You comments re reserves are well said especially after the company said that that more emphasis has been put upon transportation given the vagaries of the dry season constrictions.
I hold
A reminder to everyone, get those tables booked!
We all appreciate Mr Contrarian’s witty takes on the RNS but this one on “X” is one of his best!
The man's knocking it out the park even on holiday LOL.
My kids ISA performance .
I have 2 kids, and they both have ISA the Bloomsbury update got me thinking about investing in what you like and believe in
When I was choosing their shares (with them) we decided to invest in the companies and things they like and are interested in .
The result has been that my daughter is up around 40% and son down about 5% .
My daughter is sensible and super bright with a love of science and education etc, So she has the likes of Astra Zenoica , big slug of Bloomsbury as she is huge Harry Potter fan and a few others. Investment wise everything related to her personality has turned to gold .
My son on the other hand is shall we say somewhat less enthralled by education excellence and it has to be said can be a bit of a twat .
His sectors involved a few gaming shares and restaurants and Sone big win big lose high risk “all or nothing “. Punts .
Not sure why I’m sharing this but it’s got to the point if my daughter buys something in her ISA. I follow suit .
Just an observation on family portfolio but maybe thinking and investing conservatively Is a good lesson here of maybe she was lucky to live Harry Potter and chemistry .
But your son’s strategy may blow her performance away when the market finally turns.
My son also made all or nothing picks when he started investing. He outperformed in a bull market but massively underperformed in the bear phase.
He’s out of the market now because he’s investing in a house, family and a start up business.
This really made me laugh, cheers.
I think we all need to take a lesson from your daughter. You look at the really successful fund managers and their main stocks are always pretty dull, pretty stable, and / or the "obvious" ones, while we're here searching through a load of horsesh1t trying to find the next massive multi bagger that no one's heard of, and generally not succeeding.
No surprise that most people on here are (or come across as) men.
Cheers
Chris
I have stated this to you on many occasions and this is why I love your posts. I have done so much research on Good Energy (LON:GOOD) and still I am down about 40%! (At the moment).
But I have made my US largest holding and I have shared this here at the time iShares Bitcoin Trust (NMQ:IBIT) sitting on a big profit. On something that I do not understand or believe there is any use at the moment. I just followed some well known successful investors (not waisting time on research as well!).
I've tried to get the kids involved (and the wife) but given that the kids are 11 and 9, they aren't bothered. However, my son keeps on telling people that he 'owns part of Shoe Zone', which bodes well for how he views things.
I did open an ISA each when they were born, initially I did want to go all or nothing and see how much return could be made, but with my sensible head I've got a plan to hopefully have a pot worth 50k each, which then they could use as some sort of pension pot and just drip small amounts into each month to secure them a decent pension.
Therefore, high yielders, cyclical unloved businesses and investment trusts are where I anchor their investments. However, I do speak to them about it and I reversed a massive position in Boohoo (LON:BOO) when I spoke to my daughter and she told me all about how Boohoo were old news and SHEIN were the best.
Equally, I tried to get her to do a kids analysis of Centaur Media (LON:CAU) vs Bloomsbury Publishing (LON:BMY) and all I got was shrugged shoulders. One day Rodney...
hi planetx
My son on the other hand is shall we say somewhat less enthralled by
education excellence and it has to be said can be a bit of a twat .
Love the honest commentary - pure gold.
Snazzy
Hope your son can't access your Stocko !!
I was certainly driven by my daughter's interest in books to buy Bloomsbury for her JISA.
Similarly with Impax Asset Management (LON:IPX) and thinking about what will matter to her.
I for one am glad you shared ... best post here today. It is not a bad idea investing in what you like and are interested in. You really don't have to own everything. For those that don't know Chris, his blog on this subject is well worth a read:
https://www.woodlockhousefamil...
Chris manages a small family office with over £100 m under his wing. He only owns 12 shares but knows each company inside out. Your daughter would enjoy his philosophy I suspect.
Have a nice day.
Planet great post really had me chuckling (as a dad of 3).. in our house when the teens do something "twatty" .. The missus and I are immediatly explaining to each other... "they get that from you!"...
Just a quick thank you to Paul for his weekly pod catch ups. Been listening for the last year, looking for any small fun trades of shares I would not normally buy.
Another one up 15% Plexus Holdings (LON:POS) since the weekend, every little helps.
BMY - fair point Paul re investor communication to the pond life that is the PI. Time for the recently appointed Head of Investor Relations, Tamsin Garrity, to spring into action. I suspect she will be more likely to respond to you than me!
Bloomsbury Publishing (LON:BMY) - Paul the previous ahead statement suggested revenues at 274.2mil which have raised to £291.4mil today (6.3% increase) and profits £32.9mil increased to £37.2mil (13.1% increase). Previous EPS was 36p, so the increase in profit put you at 40.7p.
I had a look back at Bloomsbury Publishing (LON:BMY) numbers and it has a 5Y average PE of 16. Over 5 years the Average Stocko Quality Score is a respectable 89Q. However BMY now sits with a Q score 99 (+10 points), so it should attract a higher than 5Y average PE multiple. Using Pauls mid-range PE of 17.5 (15-20x) and assuming 40p EPS (this year) that’s a share price of 700p.
So I think we are seeing a 52 Wk High momentum behaviour situation whereby there is an investor under reaction to good news, particularly with companies at or near their 52 Wk High. This underreaction is known to be particularly prevalent in high quality companies i.e. Bloomsbury Publishing (LON:BMY) which is in the Top 1% of UK companies by Q ranking. This morning’s price of 535p shows significant potential upside. I Hold.
BMY "The only risk I can foresee is if fantasy fiction goes off the boil, and strong growth this year cannot be replicated in future years."
It's a fair point, and one never knows, of course. BMY do have a digital division, so if things go well that's an extra string to their bow. So far, so good. They made encouraging comments in their last presentation.
I guess it's a bit like Greggs (LON:GRG) the bakers, how many more bakers does Britain need? Or Games Workshop (LON:GAW, surely there's only so many plastic orcs could they could sell? The answer turns out to be surprisingly more than one might imagine.
As ever, we shall see. I think the trick is not to go overboard on any one share, but diversify. If one can find a dozen companies of such quality and value, the odds are heavily in favour of one beating the market over the long term.
BMY I'm going to express the contrarian view that I'm laid back about the company not giving detailed guidance. I'm taking the view that BMY will be a good long-term holding. The minutiae of what to expect next year ought not to affect the long-term performance. I would much rather directors play a little coy, get on with the job of running the company, and surprise us on the upside than directors who tell us what they had for breakfast that morning.
I think one must accept the fact that one will make mistakes in investing. It's all part of the game. Smarter people than me will do better, but as long as I can get a decent return and beat the market over the long term, I'll be happy enough.
Listening to Ed Croft's webinar on multi-baggers made me realise that one can't nip in-and-out of good shares. I recently read "What I learned about investing from Darwin", which has further influenced my thinking. I've recognised over the last year that I need to be much longer-term in my thinking of quality shares. (Contrarian plays like oil prices have a much shorter time-frame). I recommend the book, BTW. The author does talk a lot about the natural world, but it is an interesting read.
I've also recently bought Algy Hall's book, which is proving to be a good read so far.
I project that my portfolio turnover to be about 7% this tax year, equating to an average holding period of 14 years. Let's see if I can extend that period next year.
Another great update and beat from Bloomsbury Publishing (LON:BMY) , and was an absolute steal when it slipped back to £4 or so late last year.
Paul, I agree it’s incredibly frustrating for a company to say they are significantly ahead without noting at what level we should be adjusting our forecasts to. Only select brokers will get to see this, and a negative mark for the new Head of Investor Relations who was appointed to this new role in early-January…
“Bloomsbury, the leading independent publisher, is pleased to announce the appointment of Tamsin Garrity as Head of Investor Relations, effective from 8 January 2024.
In the newly created role, Tamsin will report to Chief Executive Nigel Newton and Group Finance Director Penny Scott-Bayfield.
Tamsin forged her career over two decades as an Equity Research Analyst focusing on European Media, working at investment banks including Jefferies and UBS. Tamsin has extensive experience in analysing media companies, financial models, writing research, M&A and communicating with fund managers, analysts and equity sales forces.
Nigel Newton, Chief Executive of Bloomsbury Publishing Plc, commented: "I'm delighted to welcome Tamsin to Bloomsbury as our first Head of Investor Relations. Tamsin's appointment underlines Bloomsbury's long-term growth aspirations and commitment to deepening communication with analysts and both existing and potential investors. I'm confident her significant experience will add real value to our team."
Bloomsbury Publishing (LON:BMY)
non holders here should perhaps be kicking themselves (me included) we have had great posts slapping us in the face ref current great trading probably ahead of official news . My only niggle would be that if one authoress/author is generating a short term abnormal level of sales - is there scope for poullback - or later bad news if they leave at the end of their current deal. I did think about that issue a while back and satisfied myself that if Ms Rowling is happy "partner" then thats a pretty good advert and enough for me but still didnt buy for one reason or another. Hey ho one cant get em all right.
Bloomsbury Publishing (LON:BMY) With 6 books left in the contract that is like virtually all of Harry Potter potentially. Maas also adds to the network effect of enticing the most exciting authors to think of Bloomsbury first as a vehicle for their work.
On Bloomsbury Publishing (LON:BMY) it's important to recognise that the publisher does not hold the Harry Potter rights in the US nor digital versions of the books.
With SJM I believe that they hold the worldwide rights (and definitely rights in the US) and Print + Digital versions.
It's also worth pointing out that I imagine Bloomsbury's contribution margins will be lower for future SJM books after the latest 6-book deal was signed.
Hi Paul
Re Bloomsbury Publishing (LON:BMY), what please is your lower bound thought in percentage terms re the meaning of "significantly ahead" re revenue? Clearly the percentage increase in EPS forecast will be (say) 2-3 times greater than that of revenue. Does sound incredibly positive especially given how careful the CE is with his words.
Hopefully we will get some views from readers on this. I am certain Paul added his own interpretation of these a long time ago but I cannot find it.
Broadly in-line +- 1 - 2 % either way
Moderately ahead = ~ 3%
Materially ahead = ~ 5%
Substantially ahead = ~ 10%
Significantly ahead = more than 10%
I am just having a guess?
"Broadly in line" is pretty much always down, probably not by too much but you never know.
Zotefoams (LON:ZTF) (I hold) have issued an RNS which annoys me. They have joined a sort of trade body, Recoup, which deals with plastic recycling. I looked it up. There are some big names but pretty much anyone can join. Paying a membership sub to a trade body doesn't justify an RNS and I've come to regard pointless RNS announcements as a red flag. As usual the company reminds us about its flagship new product:-
'ReZorce® Circular Packaging, is the subject of a Joint Development Agreement with a major global player in beverage packaging and trials with a major European retailer, replacing Liquid Packaging Board (LPB) for juice cartons, are planned for early this year.'
But they've been saying that for ages. I'm not selling today, but I repeat for me this is a red flag.
Michael, I agree on Zotefoams (LON:ZTF). I fear the project may be running behind schedule and these little reminders are to keep private investors from getting bored. In many ways the opposite of a company like Somero Enterprises (LON:SOM) who only update when absolutely necessary. Beeks Financial Cloud (LON:BKS) was one Paul discussed only this week about selling due to stagnated sp and bordem. I must admit, I did the same. The upside however is that if they felt the project was doomed to failure, they wouldn't keep shoving it down our throats. Like you I am happy to hold, but expecting a delay or extension of trials RNS at some point.
Zotefoams (LON:ZTF)
this update is clearly labelled as being
Non Regulatory Reach Announcement
On that basis are you not being harsh giving it a red flag based on the fact it does what it says on the tin - i am with you here that its not "necessary" to have these coming out but i think most peeps know the difference between Non Regulatory Reach Announcements and official rns releases surely stuff like this isnt totally uncommon for companies that like to promote new deals and the like. I tend to ignore these rather than give them red flag.
Being honest i tend to get wound up more by companies that keep announcing new material contracts that never affect existing broker forecasts !
Bloomsbury Publishing (LON:BMY)
Although i was expecting a trading update from Bloomsbury, there wasnt one scheduled but the sales of SJM's books have obviously beeen so strong, the numbers have rather surprised me.
Pre TU the expectations were rev of £291m and PBT of £37.2m, considering that they did £137m rev in H1 2024 this would suggest they are expecting £183m for H2, that is a huge beat (20%)unless I have my wires crossed somewhere!!
Help anyone?
Bloomsbury Publishing (LON:BMY)
At the risk of hubris it is nice to call it right occasionally, it makes up for the more frequent times when my calls have been less than accurate. Bloomsbury Publishing (LON:BMY) is my second largest holding, the only slight irritation is that I should have backed myself more fully by adding a few more, after recently adding at 476p a month or so ago.
If Bloomsbury digital can continue to grow and Nigel Newton and his team spend the £39m cash on the balance sheet wisely the future looks bright indeed, but as ever in investing there are no guarantees.
All the best
Jonno
It’s a sleep well at night share too .
Lot to be said for a good nights sleep .
In terms of “no guarantees” it’s as close as I have seen in the past years .
Bloomsbury Publishing (LON:BMY)
Indeed jonno. I always make a note of the reason when I first buy a share. In this case I was a firm believer (at the time - not now) that a high StockRank guaranteed success. This was BMY:
..and how did BMY come to my attention?
Paul:
and among others:
So thanks! The full version can be read here.
The good thing, as others have said, is that it has not given me a sleepless night since.
Bloomsbury Publishing (LON:BMY)
Thank you shawr. Very gracious.
All the best
Excellent UK CPI data this morning. -0.6 mom vs -0.3 expected. Furniture -5.2% for its biggest decline since Jan 2020. Food -0.4% for its first decline since Sep 2021. Electricity was one of the upward pressures (+4%) but that was due to the price cap increase and the price cap is due to come down quite a bit in April. This is in contrast to the US CPI which was a little hot yesterday, causing widespread declines in stocks and bonds. FTSE 100 futures +0.5%.
Spot Gas and Electricity rates have reduced c.40% in the past 3 months. - https://www.cliffordtalbot.co....
Within the next two weeks OFGEM will be updating the energy price cap. Looking at the recent news, the suggestion is of a 15% reduction, it could be a higher %, but if not come the summer the price cap will be further reduced (as long as pricing stabilises at the recent spot rates).
Further reductions in all of our energy bills will once again give the consumer more money back in their pockets - hopefully to spend on more books Bloomsbury Publishing (LON:BMY)
https://www.voxmarkets.co.uk/r...
Bloomsbury Publishing (LON:BMY) issued an unscheduled but probably not surprising trading update this morning. Revenue and PBT expected to be significantly ahead of expectations. Sarah J Maas books and to a lesser extent some other popular publications being responsible.
Blooomebury
If Heineken did shares this would do it .
Don’t know why I bother with a portfolio should just whack it all on Blloomsbury and leave it there .
Significantly ahead update , has cash , makes loads , good sector , great management and also s great company to want to support doing good in the world
Didn’t top up few days ago as it spiked up , don’t think we will see the 400s again .
You can guarantee that Bloomsbury Publishing (LON:BMY) will be a winner as I sold out at 382,5p when hit my stop loss back in September 2022. Failed to get back in as it continued to climb. Some consolation that I bought at 240p I guess but another opportunity missed and find stop losses very frustrating. Ignore and share continues to fall. Implement and share goes back up!!
I think stop losses in this market with big price swings on no volume are pretty much “not fit for purpose”
Prices are jumping up and down for no real reason and on no liquidity so don’t actually bear any correlation to company performance .
Best to wait for actual news and decide if your investment case theory has changed then just take the pain .
That’s my thoughts on stop losses I guess if you have a lot of shares then might work .
Big drops for no reason other than sentiment are surely more of an opportunity than a reason to sell .
Bloomsbury haven’t put a foot wrong for several years so I can’t think of a reason to have sold for a long time .
ACounsell
Doesn’t your regret at selling Bloomsbury Publishing (LON:BMY) last September only because it fell to some arbitrary stop loss figure back up what we both discussed on the Investment Trust thread here, that we should sell for investment reasons? Isn’t it folly selling at the very point a Company with a good record of in line or better than expected updates, falls to a price that looks a VERY good BUY opportunity.
Just look at the following:-
July 18th. In line update and share price up on the day to 440p. Paul Scott rated it a “green” and wrote “excellent steady growth company, nice balance sheet. Lots to like. So why sell just 2 months later on no evidence that trading had worsened? Shares and markets are volatile. It’s when a share price falls between updates when others in the sector are not falling or going up that there’s a strong case for selling. But otherwise wait for the next update as it might again surprise on the upside.
Was that what went on to happen with Bloomsbury Publishing (LON:BMY)?
YES.
October 26th. Solid Results.Share price up to 440p after a low on 381p a week earlier ahead of that update,
December 7th. “MATERIALLY AHEAD” update. Again a GREEN rating from Paul.
And now today. Another positive update and share price up 54p to 546p!!!
Isn’t at least a brief checking back of updates and news when we make our sell decisions far more likely to bring consistent success than selling without doing that just because the share has hit some arbitrary price,? And that price possibly in a bad week generally where it should be patently obvious that the share price weakness is more likely to be for market reasons than because of bad news specific to that share?
And the same points apply even more when quality Investment Trusts trading at unusually high discounts to NAV suffer illogical share price falls. They are SO often BUY opportunities!
Can't dispute your facts on Bloomsbury Publishing (LON:BMY) but there are probably as many examples of shares that rose on repeated bouts of positive news only to slump dramatically or worse turn out to be a fraud like Patisserie Valerie. Without perfect hindsight it is very difficult even for expert analysts like Paul Scott to get it right all the time. Consequently for what is a portion of my portfolio that I consider 'fun money' (less than 3% of my total portfolio) I feel that a systematic stop loss is important for a relatively risk averse investor like myself. In retirement my goal is generate a reasonable return from core holdings and get the occasional bonus from a successful small cap investment. Some pay off - many do not.
My strategy for Investment Trusts is completely different as provided they continue to pay dividend income, have good dividend cover and a solid balance sheet I am prepared to live with unusually high discounts to NAV. Supermarket Income REIT (LON:SUPR), Impact Healthcare REIT (LON:IHR) and Renewables Infrastructure (LON:TRIG) are some that I think fall into this category though the market doesn't appear to like the latters recent purchase of a battery storage facility which is seen as increasing the volatility of revenue streams going forward. This has probably also had a negative knock-on effect to Gore Street Energy Storage Fund (LON:GSF) but as they have reiterated their intention to maintain the dividend I won't be selling that holding. We will see if it goes the way of Digital 9 Infrastructure (LON:DGI9) which you have already pointed out I should have exited some time ago!
ACounsell.
My fault probably but again you’ve missed the point.
It’s simply that it’s a MUST to check out Results and trading updates. Then use additional information like the brilliant balance sheet analysis provided by Graham and Paul here. It’s NOT to base our investment decisions on the opinions of other people.
You cite the fraudulent Patiserrie Valerie. That only happens very rarely and if we base our investment decisions on such remote likelihood we might as well not risk investing in anything! Bloomsbury Publishing (LON:BMY)recent updates have all been good, so why sell on some arbitrary stop loss figure.
Fact is that Companies (e.g NEXT) that under promise and over deliver time and again, far far far more often than not, prove to be superb shares to invest in. if buying when likely good news isn’t already priced in. Next (LON:NXT) has risen from 6p in 1990 to £83.
It’s uncanny really but based on your reported Investment Trust losers (and credit to you for so freely admitting to that) it seems you buy when I would more likely be selling.
e.g You mentioned that you still hold Digital 9 Infrastructure (LON:DGI9) now at 17p but that I sold (at a small loss) at 44p.
Why did I sell then? Simple. A diabolical update on that day. That’s what I mean about selling for INVESTMENT reasons.
But right now I’m tempted to buy a modest stake again. WHY?
Have a look at the post today from Donald Pond on this Digital 9 Infrastructure (LON:DGI9) thread.
https://www.stockopedia.com/co...
DG19 was an obvious sell at 44p.Is it now at 18p a tempting punt?
Finally! Next (LON:NXT) has gone up 1384 fold from 6p to £83. So just £100 invested then (all those years ago admittedly) and held ever as NEXT repeatedly under promised and then beat expectations, is now worth well over £100,000!! AND NEXT now pay a dividend of £2 a year. So the dividend now is 33 times more than the share price was then.
NEXT is an extreme example and it would have been essential to top slice over the years to prevent the holding becoming far too big. But I’ve used this example to back up the “sell for investment reasons”case and not some top loss figure that sees us too often out of a subsequent BIG winning investment.
No further comment to make on your views of my investment approach - only that I hold Next (LON:NXT) and admire the trading and results statement that CEO Simon Wolfson publishes which I read avidly. Without doubt the best corporate communication in retail or any other sector probably. Sadly I haven't been in the investing game for long enough to amass the £100K from one stock! However, a family holding in Coloplast A/S (CPH:COLO B) of c.£400 back in 1988 proved a very valuable investment - top sliced many times in the intervening period leaving a current holding in excess of £10K (and that is after a significant decline in the last couple of years)
ACounsell
If only!! I DIDN’T get £100,000 profit from Next (LON:NXT! I decided I had missed the boat when Next quintupled in no time from that 6p to 30p.
The turning point was the sale of their Grattan catalogue business and Next has rarely looked back since then. I agree with your comment about their updates being the best in the sector and probably all sectors.
hVIVO (LON:HVO)
("hVIVO", or the "Company")
Proposed Secondary Placing of not less than 14 million Existing Ordinary Shares in the Company
hVIVO plc (AIM & Euronext: HVO), the world leader in testing infectious and respiratory disease products using human challenge clinical trials, announces that it has been informed by certain Directors of the Company of their intention to sell, in aggregate, not less than 14,000,000 ordinary shares of 0.1 pence each ("Ordinary Shares") in the capital of Company (the "Placing Shares"), representing approximately 25% of their current shareholding, at a price of 28 pence per Placing Share (the "Placing") in order to satisfy strong institutional demand.
Each of Raglan Road Capital Limited and Raglan Securities Limited (two investment vehicles of Cathal Friel, Co-Founder and Chairman), Pamela Iyer (Cathal Friel's spouse), Horizon Medical Technologies Limited (an investment vehicle controlled by Cathal Friel but of which neither he nor his spouse has any beneficial ownership) and Brendan Buckley (Co-Founder and Non-Executive Director) (together, the "Selling Shareholders"), intend to participate in the Placing as the selling shareholders.
Following a series of meetings with both new and existing institutional investors, it became apparent that demand for Ordinary Shares was in excess of those readily available for sale. The Selling Shareholders recognise the strategic importance to hVIVO of a strong and supportive institutional shareholder base, and have therefore decided to release a portion of their own holdings in order to help satisfy this demand.
hVIVO (LON:HVO) featured in the Investors Chronicle with a 35p target
https://www.investorschronicle.co.uk/ideas/2024/02/12/business-is-booming-at-hvivo/
Do think it would be better for folks to just post a link to a source of the RNS rather than cut and paste a verbatim copy.
https://www.investegate.co.uk/...
Saves those who've already read it elsewhere from wasting their time scrolling through it.
And if you have a constructive comment or some insight do add it.
I think that we're all slightly over thinking this cluttering of the board... it takes less than 0.1 of a second to scroll through eParo's message... and because this RNS link didn't mention hVIVO (LON:HVO) , I had to click on the link to see what is was about ... as long as the share name is posted it takes fractions of a second to move to the next post... or maybe I need to value my time more highly haha..
It’s always very generous and magnanimous of Directors/Founder shareholders to provide ample liquidity for the stampede of buyers….
Excellent way to dispose a part stake without creating a massive overhang or mullering the price. No issues with me hVIVO (LON:HVO)
Agree Cathal deserves to cash out a few chips, great way to do it. hVIVO (LON:HVO)
It's a pity that he didn't think the same way previously when he talked up the share to 40p
Bryaz
Cathal is promotional and exuberant so you have to take what he says with a. Pinch of salt, but he doesn’t really run hVIVO (LON:HVO) anymore, Mo Khan does and he is not promotional, rather believing in under promising and over delivering. The last few updates have evidenced that. Look at the fundamentals of the company and a peer group analysis and make up your own mind. What Cathal does or says is irrelevant. What matters is the fundamentals.
For what it is worth if Cathal is buying a new business I’d personally be an early follower into that trade as he will only buy value and has a history of making money. What he says or does after that I generally ignore as he is just talking his own book.
I would add that maybe the IIs want their extra shares at 28p now before new contracts are announced and the price shoots up! Why are some investors so sceptical? Have a look at what hVIVO (LON:HVO) is doing in the CRO space.
Haha - I hate the term “to satisfy liquidity” which hVIVO (LON:HVO) used this morning so that annoyed me!
However, having vented about fluffy language I’m not really concerned. Firstly a 3% discount is basically at the market so clearly strong demand is actually there and it would be good to have some institutional support/interest. Secondly it is a 25% stake sale so they still retain 75% of holdings which ensures they are well aligned to shareholders. Thirdly Cathal is fundamentally a trader/entrepreneur so no surprise he wants to take a few chips off as chairman, but worth pointing out that he also exited on Amryt pharma early and that went on to achieve a $1bn+ trade sale, so I wouldn’t necessarily use his sale timing as a particularly good indicator of the future.
Fundamentally for me nothing has changed. I anticipate EPS up towards 2p next 18 months and a good CRO should trade at between 20-30* plus net cash - so I am still of the opinion these are well undervalued, particularly given their global leader status in the field and the barriers to anyone else coming in. I’d imagine there will be some sort of corporate event in the next year or so - either a listing on Nasdaq (they’ve been banging on about that for a while) or if they continue being lowly rated it wouldn’t surprise me if a predator picks them off.
US CPI data came in hot yesterday...and therefore falls in inflation showed less momentum than expected....never the less, it remains "likely" that we will see further falls this year until September. That is assuming that the Month on Month numbers slow to 0.2% and the January number proves an outlier. The market reaction reflects a view that the Fed will have less room to cut whilst data remains strong. I wouldn't get too carried away yet since its only one months number.... but obviously Goldilocks can't last forever and disappointedly the Russell 2000 got hammered and not a positive for small cap investing. I personally thought the market was somewhat primed for a bad number so am a little surprised it reacted so badly but maybe things even out a little over the next day or two. We are def biased towards bad data being good for now...and vice versa. Data that is hot will hit the rate victims further unfortunately.
PS UK data just out, which provides a little relief since it did not get worse! Might help reverse some of yesterdays weakness which reflected above...lets hope so...
When more than half of all US investor 'Buy/Sell' decisions are driven solely by price/momentum (ie passives)
Then its pretty easy to see why markets can irrationally overshoot (eg Nvidia & Eli Lilly) both to the upside and downside.
Sure ETFs are low cost trackers. Yet equally what about the hidden opportunity cost of passives for investors in terms of 'loss of price discovery'?
Personally what I TRY (albeit not always successfully) to do is the opposite.
Indeed as the 'momentum herd' rotates into the latest hot sectors (eg AI, GPL-1s), they often have to sell in another areas fund these purchases. Sometimes creating attractive buying opportunities for active investors in much cheaper quality stocks which are simply deemed not flavours of the month.
What concerns me most, as someone who is underweight the US ( absolutely nowhere near the 71% global weighting )... aren't those passive flows incredibly sticky, as they're likely to be pound cost monthly averaging? Directionality that is more likely to have a bullish bias, but more importantly will surely have an outsized effect on volatility in bull or bear markets.... there may be the moral hazard of a ' Fed put ' on the downside, but if the dip of bad data / earnings are bought, what constrains the upside ...
At some point I'll have to increase US exposure, but 1 poor US CPI and 1 good UK print isn't enough of a catalyst...
I think the old adage about a stock market being a voting machine in the short term and a weighing machine in the long term is at least dulled by the rise in passive investments. The driver of share prices is supply and demand.
Americans are very insular, and believe, not unreasonably, that their stock market is the only game in town.
That means every day, retirement savings from the biggest economy on earth pile into the US market, regardless of valuations.
US demographics are pretty good until 2034 (see Ciovacco Capital's Youtube on this).
Meanwhile a lot of US companies are buying back shares: Meta Platforms (NSQ:META) announced a $50bn (!) buyback in its last earning report.
So unless the US has a recession and people become net sellers of US stock, then I can't see how the market doesn't continue going up.
One caveat: an awful lot of US investing seems to be through options. I saw one guy bought a call option on ARM at $103 when the SP was $70, sold it when the SP was $160 briefly and made 100x his initial investment. I have no idea how these options are covered, but there is a lot of leverage in the system. And while it might be driving prices higher for now, that never ends well.
Re. Paul Hill's thread and the US market, what interests me is the amplification of a crowded trade by passive investing. I was reminded in this morning's general reading that the current mania (eg: NVIDIA (NSQ:NVDA) at 95 P/E) in a small number of shares is a bit like the 1971/2 "Nifty Fifty" phenomenon, which pre-dated automated trading but where there was almost identical crowd-following behaviour into a small number of shares. But it's worse this time, because a lot of the index advance is coming from the "Magnificent 7" - just 7 shares. And as (the perma-bear) Albert Edwards says, “I never thought we would get back to the point where the value of the US tech sector once again comprised an incredible one third of the US equity market. This just pips the previous all-time peak seen on 17 July 2000 at the height of the Nasdaq tech bubble.'
What might pop the bubble? Those businesses which are valued highly because of AI are going to face competition. The capabilities of the technology are truly astonishing, and I agree they are going to destroy huge numbers of jobs at a faster rate than we saw in the industrial revolution, but nobody has a single blockbuster patent on Generative Pre-trained Transformer models and the hardware guys like Nvidia are going to face competition - Sam Altman has been in the Middle East trying to raise 5-7 trillion dollars to build a foundry (or foundries).
Heaven only knows how PIs should respond to this. I know how we should have responded, we should have done what Nadeem Walayat has been telling us for ages. Too late now.
I do not hold NVIDIA (NSQ:NVDA) but it is my opinion that looking at the current PE of such a fast growing company is the biggest mistake an investor can make. What will this PE be in 4/5 years time?
The US market trades at a 20x earnings rather then its average 16x earnings and on that basis the DOW should be trading about 31000. But all these great companies (magnificent 6 Tesla (NSQ:TSLA) is out for me) are growing so fast that any prediction on their SP is very very difficult.
All the best
I do not hold NVIDIA (NSQ:NVDA) but it is my opinion that looking at the current PE of such a fast growing company is the biggest mistake an investor can make
Absolutely. I hold and, only six weeks ago, Nvidia was on a retrospective PER near 100x, but a CY24 PER below 25x. I couldn’t understand how the market had allowed it to stay so cheap given it had trebled already. Needless to say it’s up 50% since then, but it’s still only rated on a similar multiple to many less celebrated semiconductor stocks – many of which I also own.
Indeed, I’m coming to the conclusion that becoming a specialist semiconductor investor (I’m not) is the key to huge stock market outperformance. You don’t even need to distinguish between the individual companies as you can simply own the SOX ETF. But you do need to be able to read not only the feast or famine semiconductor cycle, but also the extent to which the stock market will anticipate it. At the moment we are in the trough of demand for analogue chips and the peak of demand for high end graphics processors. If you can accurately read the cycle, then you can exit stocks before they halve and re-enter before they triple - which is the typical pattern of progress of semi stocks. Imagine the performance that would deliver! Easier said than done!
NVDA is on a forward PE of 34. It's hardly a bubble yet. Cisco at 200PE in 1999 more so.
Minervini is full of examples of PE ratios and the havoc they cause. There are many examples of very best companies having very high PE ratios before the share price advances, and the PE ratio declining to reasonable levels before the SP collapses. CKE Restaurants is one example he gives, had a PE ratio of 80 before the stock rose 740%, then the PE fell to about 30 before the price dropped 80%.
He emphasises that a focus on PE leads to investors missing companies during the period of explosive growth and then buying "broken leaders" when the growth has stopped.
Super Micro Computer (NSQ:SMCI) has gone up around 7x, in the last year, but forward PE is only 30 and PEG is only 1. I no longer hold, sold out too early. Real growth in some the US technology companies. I sold NVIDIA (NSQ:NVDA) recently, probably too soon.
Real momentum.It'll come back to UK small caps sometime.
My own thoughts on NVDA and chips in general ... Covid caused widespread supply disruption and the West is worried about China choking off supply should it so choose.
The US, wisely I figure, decided that it was in their strategic interest to increase capacity in friendly places.
It seems that everybody is gearing up heavily for chip fabrication. Intel will spend billions. Amazon, Google, Microsoft etc. are developing their own chips. AMD and ARM want in on the action, too.
The need for datacentres is heavily involved in all this.
I think we should sound a note of caution, though. Chip manufacturing is a capital-intensive highly cyclical business, no joke.It was like that in the past, and I don't think the nature of the beast has changed.
My fear is that we are pumping a lot of capital into the high point of the cycle. That's going to end badly.
I think that chip consumption is still likely to increase over time. As a tinkerer in microcontrollers I think hobbyists (and proper industries, of course) have hugely benefited from the increased capability and reduced cost. So I think that the trend in volume likely to continue.
Contrariwise, AI is in hype mode at the moment. I view it in the same vein as 3D printing (actually less useful than 3D printing). 3D printing was all the rage, set to transform manufacturing. Sober minds would have shaken their head, realising that it was no solution for mass production. For niche small-volume items it's great.
Paul. I think that the bulk of my recent gains have been due to this behaviour! And thanks for talking about Sondrel (which has done me proud)...will a contract win come before a funding announcement?
Really well done Chumba.
I'm absolutely hopeless at trading stocks - so never try to do it.
Is there anywhere options can be traded within the ISA wrapper or do you need a special trading account? If not, and in the fortunate situation that you make some profits, what's the tax situation?
Conistons
You can't hold Options in ISAs
Ah thank you
I recommend Tasty Trade owned by IG group (LON:IGG) if you want to trade options.They recommend selling them primarily according to their research based strategy of probability of profit.They have a daily show available on Youtube.They have a great platfrom too as Tom created Think or Swim, owned by TD Ameritrade and now sold to Charles Schwab (NYQ:SCHW) , before creating Tasty.
Thanks, much appreciated, I will follow up
According to Mr. Market, Nvidia is now worth the whole Chinese stock market cap, pretty telling
That’s because most of the big Chinese companies are not listed or they are listed in other major stock markets (Alibaba Holding (NYQ:BABA) ).
However, UBS upgrading NVIDIA (NSQ:NVDA) last night a week before their results makes me sceptical too at the moment. Still a fast growing company with lots of upside.
I'm pretty sure Baba is a dual listing. It is listed as 9988 in the Hong Kong market. The US listing is an ADR as far as I'm aware, so the main listing is Hong Kong.
Hong Kong stock market and Chinese stock market are two different things.
The comparison you are trying to make is wrong as most companies in China and the biggest are SOE.
Apple (NSQ:AAPL) and Microsoft (NSQ:MSFT) market cap together is bigger that the GDP of every country in the world except US and China. That i understand and it is frightening for many different reasons.
I believe that you are completely wrong here. Investors and in general the financial industry in the US are more advanced than here (in another level).
Perhaps though the market need a 7-10% correction something that happens in the US almost frequently and then pushes higher (yet again). Politics is the major risk for me this year and not the economy.
Passive investing offers higher returns for long term investors.
You are also discounting the $7 T parked in money market funds. Where will all these funds go after the US starts cutting rates?
Just some personal opinions.
I believe that you are completely wrong here (To Paul Hill)
Well Paul is just talking his own book, using Stocko for exposure in return for videos of varying quality. And there is simply no evidence that he is right. Passive US investing beats all-comers and I don’t see that changing over any timescales other than very brief episodes.
Markets reflect the quality of the companies that comprise the indices. And that is the most important lesson a fundamental investor needs to learn when allocating geographically.
I agree, 3-5% pullbacks on the S&P are frequent, maybe 10% once a year and the occasional 20-30% bear market.
I've 20% of my portfolio in S&P trackers,the rest is mine to trade with in mostly UK shares. Personally this is the only holding Id ever average down on.
I've been lucky enough to beat the S&P since 2009 (was out the market 2018+19) even with at times lackluster UK shares. There's always something to trade. Tho I do admit Im odd as I like the challenge of difficult markets.
Why mess around with fund managers, 95% can't beat the S&P, when anyone can buy a low cost tracker which automatically holds/weights the best companies. If I ever lost my love for trading Id bung almost all in a global or US tracker
Hi WoSS: On the subject of S&P trackers what are yours and others thoughts on using an equal weighted tracker? In theory it will provide balance to the tech heavy index but will it underperform the weighted index?
Politics indeed Yiannos1 and specifically the only serious threat to the Mag 6 is anti-trust regulation ... as mentioned, I'm unfortunately underweight, but that might provide an opportunity for reweighting ....
Not necessarily, Apple’s growth in earnings have been running out of steam. It has not been buying so much of its own shares. And a certain older guy has started to sell.
I'm not a genius but Fang Friday on you tube is a nice short weekly review from a TA mixed with fundy analysis.
Still this is the US market and it feels like it wants to continue pushing forward so if some of the fangs blunt we must expect others to take up some of the slack.
With regard to the prevalence of passive investing, this degree of "thoughtless" buying should surely create opportunities for the discerning?
If something manages to drop out of the Index, the share price ought to drop like a stone and vice versa. Is this true in reality?
Yes there is well established research that shares do well in the month before and after promotion to the FTSE100 and shares do poorly in the month before and after demotion from the FTSE100. Although it can be a little difficult to untangle because promotion / demotion is connected to prior price changes. Essentially investing in a tracker is partly a play on size and momentum, it is not purely passive in this sense.
"If something manages to drop out of the Index, the share price ought to
drop like a stone and vice versa. Is this true in reality?"
I hold a US share @JXN (Jackson Financial) that popped on the day it entered the S&P 600 (29th August), and had very high volume on the day and for a few days afterwards. It was around £2.2bn market cap at the time it entered (before the rise).
Interesting! Surely an opportunity in both directions....
I read your posts with interest. BTW the pie chart in your profile is a little hard to read, sorry but a table would be easier to follow!