Small Cap Value Report (Wed 15 April 2020) - OBR report, BKS, CTP, SOLI

Good morning, it's Paul here, with the placeholder for today's SCVR. Please add your comments in the usual way, and the main report should be finished by 1pm today, depending on how much news there is. Edit: predictably, I'm running late, so will finish at 3pm. Today's report is now finished.
In case you haven't seen it, Jack has published an interesting article here:
Multi-bag or bust? RTN, MAB, RBG, and OTB
.
OBR coronavirus reference scenario
This document published by the Office for Budget Responsibility has understandably caused a furore. It's a forecast of what impact coronavirus might have on the economy. Being sensible people, they are not calling it a forecast, but instead a "reference scenario".
Economic forecasting is widely discredited, because people repeatedly try to forecast, repeatedly get it (often wildly) wrong, but continue pretending that they actually can forecast the future with any accuracy, when they cannot. Former Bank of England Governor, Mervyn King, has written persuasively about this, urging economists and pundits to stop pretending that they can forecast the economy, because they can't.
There's a terrific book on this called "Super-forecasting: the art and science of prediction". This makes the same point. Dominic Cummings (Boris's brilliant adviser) spat out the name of this book to journalists doorstepping him, obliquely calling them "useless political pundits", and suggesting they read this book. It's a fascinating read, highly recommended if you haven't already seen it. The core theme in it, is that a long-running study showed that many experts & pundits are useless at forecasting, but nobody ever pulls them up on their serial failure.
The same useless forecasters repeatedly appear in the media, despite getting things mostly wrong. It also identified (through a scientific process) an unusual type of person, who presented with facts & figures and allowed to research economic or political issues independently, were proven to be amazingly good forecasters. Not experts, but smart laypeople. Yet these super-forecasters rarely had any influence or involvement in policy, or even media commentary.
The conclusion being that we need to measure the accuracy of pundits forecasts, and jettison the ones who are no good. Then recruit the unusually good super-forecasters to give us predictions instead. Very sensible, but it won't happen. Apparently, an engaging & confident manner is enough to convince media outlets that you talk sense.
Going back to the OBR report, I printed it off & skim read it last night. The numbers are so horrific, it's is clear that ending the lockdown is not desirable, it's essential. The economic cost is so vast, it cannot possibly continue for much longer. This changes risk:reward for shares. If the ending of lockdown has to happen quite soon, then more companies survive, and can begin to rebuild their operations & earnings. I think this is why the stock market has been rallying so strongly of late - recovery is being priced-in.
Other positive factors include hopes for some kind of drug therapy to lesson the impact of Covid-19, with maybe a vaccine at some later date. Above all though, the Fed in the USA, and the UK Govt here, are throwing so much money at the problem, so much economic stimulus, that recovery is more-or-less inevitable. They can keep borrowing at unthinkably high levels, because they have a guaranteed buyer for newly issued debt - themselves! (round the houses, but that's what QE is).
Anyway, here are a few key numbers from the UK's OBR report, which assumes a 3-month lockdown;
- Q2 GDP down 35% on Q1, but bounces back quickly when lockdown is lifted
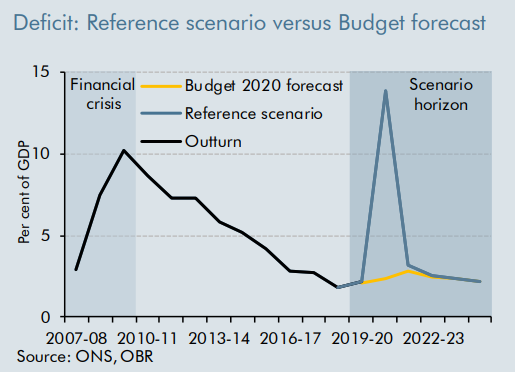
- Govt net borrowing soars to £273bn, or 14% of GDP - far higher than at the worst of the 2008-9 crisis, which peaked at roughly 10% of GDP
- Public sector net debt soars above 100% of GDP during the downturn, settling back at a still high 95% (far worse figures are being forecast in the EU, which in my opinion makes another sovereign debt crisis in the EU inevitable. Possible collapse of the Eurozone is on the cards in worst case scenarios - I see that as a very big risk, and quite likely)
- I've seen estimates that the Govt's payroll scheme alone is likely to cost £14bn per month. It's probably wide open to fraud, and there are concerns the money won't get to companies in time to save jobs
- GDP falling 13% in 2020 would be worse than not only the financial crisis in 2008, but also worse than both world wars (per the OBR report, I'm not making this up!)
.
The above chart shows the forecast explosion of the Govt's spending deficit, due to the current lockdown & the recession it is creating. Historically, large deficits usually take years to reduce - as shown above after the 2008 crisis. I'd be very surprised if this time it can be brought down almost vertically, that doesn't look realistic to me.
My view - these figures are so bad, that lockdown has to end by early summer, or there won't be anything to come back to, in the commercial world.
The aftermath of coronavirus is going to leave many countries with unsustainably high debt to GDP ratios. That doesn't matter so much if you can print your own currency (e.g. USA & UK), but where does it leave the Eurozone? In a much worse mess than the 2010-12 crisis. Italy could be looking at debt:GDP not far off 200%, by some estimates. There's just no way Germany is going to backstop that. Therefore, I think the next financial crisis could well be a disintegration of the Euro, into 20 separate Euros, with an instant & gigantic correction of all the Euros to the levels that they should be at, were they not artificially pegged at parity. I could be wrong, but it's a huge emerging risk that I want to start planning for.
Given the severity of the economic cost of lockdown, then it's difficult to see why many UK shares could remain at current levels. Are investors really going to just look through the worst economic downturn in living memory? I don't see that happening, because it's not happened before. Markets may rally strongly, but when faced with the actual figures, then I see individual share prices being bashed down again.
Will the economy really rebound in a V-shape, as the OBR report suggests? Again, I can't see that happening, because it's generally not what happens. When previous (smaller) economic shocks have happened, there's a partial V rebound, then growth settles down, and the lost GDP can take several years to recoup. But the bottom line is, nobody knows what's actually going to happen.
We all need to think about this, and have at least some idea what scenario we're basing our investing on. Personally, I don't want to own the market overall, as I feel bearish about the terrible short term economic outlook. But I am happy owning individual shares that look too cheap, and hedging that against index shorts after each rebound.
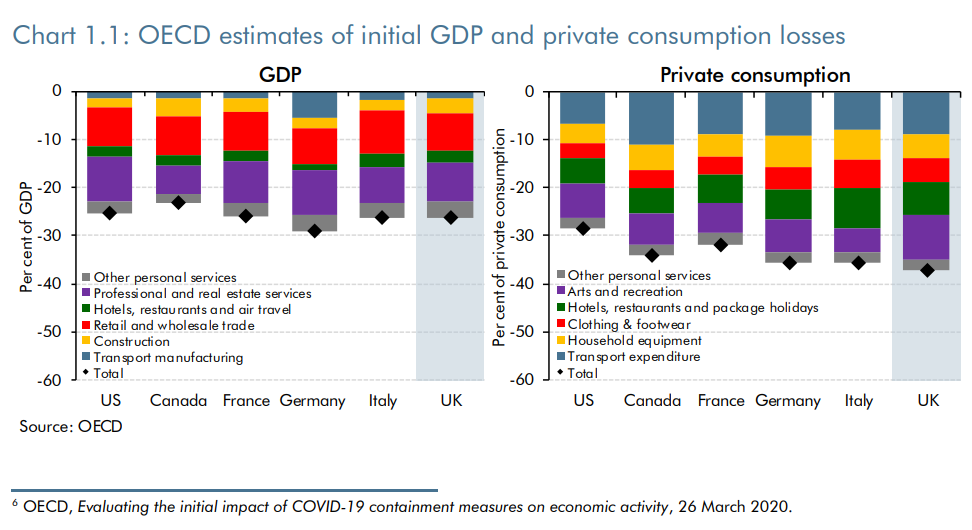
It's not just the UK that is suffering;
.
I think when investors actually see the company H1 numbers, and the reality of how this crisis must be wrecking many companies' balance sheets, then optimism about recovery could be dented. Particularly with small caps, where it only takes one determined seller to smash the share price down - recent examples of that being Keith Ashworth-Lord's clumsy exit from Revolution Bars (LON:RBG) and a similar situation with a big seller at French Connection (LON:FCCN) (I'm long of both) . In both cases they presumably decided the equity was worth nothing, so dumped in the open market at whatever prices they could get. Which will look smart if those companies do go bust, but not so smart if they survive & recover. Time will tell. It's all just educated guesswork at this moment in time in particular.
It's an evolving situation, so nobody knows how this all ends. The above is just my personal opinion, which is subject to change as the facts change.
Beeks Financial Cloud (LON:BKS)
Share price: 92p (up 2% today, at 12:02)
No. shares: 50.9m
Market cap: £46.8m
(at the time of writing, I hold a long position in this share)
Beeks Financial Cloud Group Plc (AIM: BKS), a cloud computing and connectivity provider for financial markets....
This is a small acquisition, which broadens Beeks' product offerings (or I should say, services), and brings cross-selling opportunities. It's interesting to note that RBS has provided a £1.5m borrowing facility to make the acquisition. More evidence that taxpayer-backed RBS is the best bank to be dealing with right now.
More importantly, there's a Covid-19 update as follows;
· Minimal impact on current trading from measures implemented due to COVID-19, with continued operational cash generation, increased Annualised Contracted Monthly Recurring Revenue ("ACMRR") and recurring revenues of c.95%
· Continued growth in new business, however new customer implementations may be delayed
That's encouraging. I increased my personal holding in BKS a few weeks ago, on the basis that the company has strong recurring revenues, that should hold up well in this crisis. The spread betting companies have been doing well in recent volatility, hence it stands to reason that Beeks, being a provider of cloud-based trading connectivity would probably also be seeing demand hold up.
Outlook - despite the reassurances, it sounds like there is going to be some impact;
... therefore while we are unlikely to be entirely unimpacted, we believe we are in a strong position to withstand the current challenges."
I'm not madly keen on the double-negative there.
Broker update - there's a note on Research Tree today, which lowers forecast EPS for FY 06/2020 by 16% to 1.9p which is well down on last year's 2.6p. Forecast is for strong growth to 3.1p the following year.
Therefore, in reality, this looks like a nicely disguised profit warning. There again, why would anyone be surprised by forecasts being lowered, since we're in the middle of an unprecedented (in living memory) health & economic crisis.
My opinion - I like the business model, and exceptional management. Recurring revenues are proving very valuable at the moment - in cushioning the blow to financial performance & share price.
The share price looks about right to me, I don't see it as one to chase higher from this level.
I'm happy to hold BKS for the next c.5 years (providing nothing changes). It's the sort of niche company that is highly likely to be considerably bigger, and more profitable over that timescale. Hence I see it as something to tuck away & largely forget about.
Castleton Technology (LON:CTP)
This used to be called Redstone, and it provides software & services to the social housing sector mainly.
There's a 95p cash, agreed takeover bid, so congratulations to holders.
This is a respectable 43% premium to last night's share price. With 47.3% support already, then this looks a done deal.
It seems an unusual time for a takeover bid, hence why I'm flagging it. I wonder if there will be other takeover bids, with cash-rich buyers taking advantage of lower valuations maybe?
This comment from the bidder is interesting, and should give us pause for thought as to whether many smaller companies should be listed at all?
Finally, MRI also believes that in order to maximise its future potential, Castleton would be better suited to a private company environment, where initiatives to improve the performance of the business can be implemented effectively, with appropriate support, capital and assistance from MRI, free from the requirement to meet the public equity market's shorter-term reporting requirements and expectations, and the costs, constraints and distractions associated with being a publicly traded company.
Solid State (LON:SOLI)
Share price: 458p (up 2% today, at 13:04)
No. shares: 8.54m
Market cap: £39.1m
Solid State plc (AIM: SOLI), the AIM listed manufacturer of computing, power and communications products, and value added distributor of electronic components, announces a trading update for the 12 months to 31 March 2020 and a further update on the impact of COVID-19 on the business.
There's a strong update for the FY 03/2020, but of course that's only really of passing interest now that we have an economic crisis underway;
The Board expects to announce revenue close to the consensus forecast of £68m and adjusted profit before tax is expected to be approximately 10% ahead of current consensus forecast of £4.2m, which is a record year for the Group.
Net cash - is £3.0m, benefiting from good cashflows, including some customers paying £2.5m up-front.
Has unused, renewed bank facility of £7.5m, so headroom looks OK.
Order book - up 11% on a year earlier, at £39.9m. Although the company says it expects some orders to be deferred.
COVID-19 -
- All 4 UK sites are operating, and some staff working from home.
- SOLI has been designated a critical supplier by some customers, a good thing.
- Softness in demand for some products (e.g. batteries for aircraft & oil/gas sector).
- Inventories increased to 2.5 months to smooth over any supply chain problems.
- Cash conservation measures similar to what everyone is doing.
- Acquisitions & capex both suspended.
Outlook - uncertain visibility, guidance can't be given at the moment.
My opinion - it sounds like the business should survive, and that management has taken sensible steps to conserve cash.
With no guidance, and an uncertain outlook, I cannot see any reason why this share should be any higher than it currently is. The rebound has probably run its course for now, in my view.
Why would I want to buy now it has almost doubled from recent lows, and is back to the level of last summer/autumn? Yet we have no visibility on earnings now. Risk:reward doesn't look great to me at the moment. Longer term, it should be OK, I imagine.

.
All done for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

92 comments
Thanks for your latest views on coronavirus Paul and for the book recommendation, which I intend to read. Further to my post of 9th April, your hope for lockdown to ease by early summer is possible, but almost certainly some degree of lockdown will extend beyond this. Almost certainly there will be addiitional waves of infection before an effective vaccine is developed, trialled, bulked up and administered, so lockdown will need to be re-introduced, though not necessarily to the same degree. Although I have a Ph.D in microbiology, this knowledge is not needed to make these predictions, you just need to read about the 1918/19 pandemic to understand how respiratory viruses behave. However my final fear is pure speculation. With 3 deadly coronaviruses emerging in the last 13 years (SARS, MERS & COVID-19), I wonder if the virus has undergone a mutation which encourages pathogenic variants to emerge - I sincerely hope not.
Paul you say "Recurring revenues are proving very valuable at the moment". I always thought the same but Stephen English in his excellent piworld webinar made it clear this is not necessarily the case at the moment. He cites a leading American dental software company with recurring SAAS revenues that is receiving calls from clients refusing to pay for 3 months with the threat of switching to another vendor. I suppose in the case of Beeks Financial Cloud (LON:BKS) it depends how unique their offering is.
https://www.piworld.co.uk/2020...
(42:55 minutes in).
Hi Henry,
Good point. I've got the Stephen English video in an open tab, just haven't had time to listen to it. One of my shrewdest friends says that recurring revenues are not all they're cracked up to be. It's certainly worth asking some questions.
As regards Beeks, one of the things I like about the company is that it's service is incredibly cheap, and there doesn't seem to be much competition. Hence its recurring revenues are likely to be quite solid, although I reckon some traders may have blown up in recent market volatility. That's only likely to be small beer for BKS though, I remember them talking about £15, or possibly £50 per month for traders, depending on what feeds they want.
Above all, I think we're backing brilliant management at BKS. PIWorld have some outstanding videos of presentations. The thing that really stuck in my mind, was that the CEO set up the business for his own algorithmic trading. The story is that traders & brokers then started coming to him, referred by the exchanges, asking to pay for his service. i.e. he says he had no outbound sales operation at all! If that's true, then it's extraordinary, and a business worth backing.
Thanks for the excelled OBR report view Paul, and the comments today have been excellent as well and reminded me of Howard Marks, whose notes are always worth a read. Very distracting whilst I am meant to be working from home...
You mention that the next big crisis will likely be a breakup of the Eurozone and I would agree the chances of that happening have increased dramatically in the last month but I guess the next question we would have to ask is how to profit from it as private investors if this were to occur?
Is it possible to short the weaker 10 year EU government bonds; Italy (1.87% yield), Greece (2.06%), and Spain (0.89%) are all on extremely low yields currently for example but I have no idea how to short such assets? I have heard of inverse ETF's but the high volatility would make me lose money even if it plays out exactly how you suggest due to the volatility loss making them terrible instruments to hold for any great length of time.
Would it do to simply short the Italian, Greek, & Spanish indexes, but if you do you also run the risk (with a decent chance of happening) of being killed by a recovery in these beaten down indexes. If you are able to short a 10 year gov't bond you are paying a low percentage so your max loss is not high.
Alternatively such a view is also useful as having such an expectation would influence what you buy in terms of future share purchases, so owning Italian & Greek shares becomes less tempting if their "euros" are about to heavily devalue upon breakup. Profiting from the knowledge by reducing losses rather than actually profiting directly.
Definitely made me look a little further out than I had previously, so thank you Paul.
Hi pgs501,
Do be careful, because I tried to make money from EU Govt bonds, etc, and it was a real rollercoaster. I made an absurd profit one week, then lost it all the following. The trouble is, if we're not familiar with risk:reward, and venture outside the scope of our expertise, then it could open up disastrous losses.
I'll never forget how a suicidal spread better contacted me a few years ago, after the Swiss currency peg broke. He incurred ruinous losses. Hopefully he's still alive, and managed to negotiate a way out of his losses.
The general rule therefore is, to stick to what you know.
Regards, Paul.
Hi Paul
I can see Costain on your daily report but can't see any comments.
Hi nervous2,
Yes, sorry about that, I ran out of energy, had a funny turn, and had to spend the afternoon in bed. Had intended to look at Costain (LON:COST) but it was not to be. Sorry about that.
Regards, Paul.
I sense the markets are getting very nervy today and indeed the figures coming out of the US are very bad. We have had a fantastic rally over the last few weeks in many stocks...a good time to cash in a few? I am sure many will be lower at some stage.
I'm wondering the same. By sheer blind luck I could exit to 100% cash and be 0.5% up on the start of the year. Very seriously considering selling everything.
When lockdown starts to ease and the wheels start turning the market will rise albeit for a short time
I expect a price explosion early May and there are some serious big companies out there with low share prices!!!
Fill your boots
Paul,
ref the big sellers of £RGB and French Connection (LON:FCCN) you mention, I think that if I were on a broken-down service bus I would be expecting a relief bus to come along for me to jump on. Achieving the destination is the most important thing.
Crap comment. Maybe keep your counsel until you have something intelligent to say in future?
Hi Paul
Excellent comments as always
I would appreciate if you can provide any comments on Lloyds Banking Group currently trading at around 30 pence, I am not sure whether is good value now or not
I have had a good nibble on Lloyd’s could see a good spike soon but not to last very long!!
30p is cheap imo
Hi Ramesh (and apologies to Paul for answering on his behalf). Paul does not really do financials, and even with current events, Lloyds Banking (LON:LLOY) is not yet a small cap. Also the company has not put out any news today. (For what it is worth, I think it looks good value, but then I thought it looked a bargain at 48p!!!)
I never buy shares in banks, usually.
The figures are impossible to fathom, and hugely leveraged to downturns. So this seems amongst the worst possible time to be buying bank shares.
I came across the NYSE FANG+ index which tracks the US tech giants such as Facebook, Amazon, Google, etc.
This index stands today at the same level as it was around mid-December 2019.
IMO, either these tech companies are detached from reality and their valuations do not reflect the reality of a post C-virus world... or they do in a perverse way. In a neo-Darwinian way, the market reflects the view that they will grow bigger and stronger at the expense of weaker and smaller companies which will be decimated.
Hi Paul
Thank you for the brilliant preamble today.
I am like many (including yourself) but not all, extremely bearish. Some think that this is because having sold at the current bottom I want my sale to be justified. It is not.
I agree with you when you say:
“My view - these figures are so bad, that lockdown has to end by early summer, or there won't be anything to come back to, in the commercial world.”
I would change one word though “has” to “should”. I just cannot see that happening without a vaccine or a treatment that is 100% successful. Both of which are highly unlikely. Governments are too tuned into public opinion rather than pragmatic realism.
Phil Oakley made the excellent point a while back in an IC podcast that the economy of the world is really about the flow of money. Currently there is little flow of money (except to food and mortgage/utilities payments) and that flow is going to take a long time to come back; years? We are simply in a denial stage propped up by markets belief that the Fed can solve all stock market declines by QE.
However on the plus side we had a debt to GDP ratio at a much higher level (230%) so if this (corona crisis) is a war (Though TBH I dislike the metaphor) on the scale of WWII (and I would argue its on a greater scale in terms of the economic impact) we have a lot of headroom in terms of Government borrowing. The 1950’s was the greatest bull market in history.
The US has less headroom as after WWII debt to GDP was at 112%. It now stands at 107% but as the world’s reserve currency perhaps this is less of a problem for them?
On the downside when Chamberlin declared war on 3rd September 1939 condemning millions of mainly young people to death, he did not shut down the economy. Quite the contrary it went to the full productive swing that “Total War” requires and the consequent consumption (even if it was for tanks, guns and bullets, UK GDP in fact grew). There is no way that the “Total War” we are engaged in now will not last in some form for a least a couple of years (can anybody see cruises coming back before then or even possibly large group gatherings (football, race meetings, conferences) coming back before the end of 2022? It will then take several years to get back to where we were at the end of 2019.
Even if the lockdown (and I am not saying it should be) was lifted tomorrow it would not solve the problem, as most people would still act as though they were still in lockdown; would you risk it?
We are one hedge fund blow up or large company going into Chapter 11/administration from a significant leg down. I suspect the news coming out of the US as I type might be the start.
Still 60% cash, 11% gold and 17% £AAZ.
Kind regards
Michael
Paul.
I commend you on a brilliant piece of writing..you make so many good points and everyone on this site and others should read it...Your article clearly, in plain simple English puts the current perspective we find ourselves in , in clear focus
No one reading your article will then have any doubts , that we are quickly reaching the point , where our government and those in every country will simply have no choice but to begin the process of ending lockdown....I speak with a mother of 87 in a care home, who has only been able to move her eyes and be fed pulped up food by hand very slowly for about 6 years..she literally is in another world....and I am resigned to the fact that if she were to get CV19, it would , if she passed, be in a better place then her current predicament..she is totally incapable of anything ...anything .
The lockdown has to be gradually reduced ...quite soon, because we will end up leaving our children with a legacy so enormous it will blight their lives and those of their children.’.
There will be a future and the younger generation will be the first to celebrate once lockdown ends but for people like me at the wrong age , care and self preservation will be more important.
We will find different ways for travelling, different ways for working and different ways to invest and the future for us investors will be bright, provided we carefully do our homework.’
Currently, I am about 35% cash at the moment but I am getting to the point where I believe I have no choice but to sell into these rallies to get to 70% cash.....but I am still investing small amounts into various shares where the risk reward ratio is compelling.
I hate losing money as much as anyone but my fear of losing money is less than my desire to invest in companies who I am convinced will survive.. and thrive ...Revolution Bars Revolution Bars (LON:RBG)(unconvinced until I read the RSN and your article yesterday ) and Tekcapital Tekcapital (LON:TEK), who appear to have a portfolio of products that could be revolutionary...I have small holdings in both companies...( incidentally, I stumbled across Tekcapital (LON:TEK) after looking at the tips given in 2020 Share Challenge...in 4th was Perkys Picks ..and is ever the case , it’s what’s written between the lines that is often more valuable than what is actually written...Thank you Perky and congratulations .
The ultimate short term view is that once the real figures emerge and businesses emerge from their coma, some businesses will not get the cash through their doors they were expecting ..and despite cutting expenses and saving cash it will not be enough to save them.
Stockopedia and writers like you , are brilliant and the subscribers in their writings daily provide invaluable insights to how others interested in investing are thinking .
Keep up your brilliant work and insights , your effort is so very much appreciated and very very valuable in formulating our thought processes.
Finally, I urge everyone to read the March 2020 fund review by Keith Ashworth -Lord ..his Buffetology fund did lose over 26% in March but when he stated he did not see the lockdown coming ..and other comments and observations , it illustrates to me that many professional fund managers should not be managing their clients money.....
Keep up the good work Paul and thank you .
Great comment.
Do you have a link to the “March 2020 fund review by Keith Ashworth -Lord ..his Buffetology fund”. As I am struggling to find it.
Thx
https://www.trustnet.com/facts...
Sorry just realised that this takes you to the April fact sheet. I can send you the March one if you let me know your email.
Thx but rather not publicise my email.
Hello Puepleski/ Michael,
I struggled to find also but the link was from a stockopedia subscriber last week..I will see if I can relocate for you ..Thanks. Tony
https://basethree.s3.eu-west-1...
purpleski - I posted the link here:
https://www.stockopedia.com/content/small-cap-value-report-thu-9-april-2020-eck-otb-589448/?comment=6#6 .
Thanks Tonysaparito for calling out KAL's Buffetology Fund Commentary which I was shocked to read. It beggars belief that somebody in charge of managing £1bn+ of other people's money should be so brazenly complacent. To state that "I never saw that one coming" is bizarre. Does he not read newspapers or listen to the radio? I'm a complete amateur with no financial training and a full time job and I saw it coming. I posted here on February 7th (https://www.stockopedia.com/co...) that "...nobody can predict the course of this or the eventual impact but given the recent appreciation of most markets and the potential risks if sentiment surrounding the outbreak worsens, with more companies reporting material impacts from it, I've taken the decision to reduce all of my holdings across the board."
This was the same day that Burberry (LON:BRBY) reported significant material impacts on their Asian business. It's patent nonsense to say that this crisis came out of nowhere. I didn't foresee the severity of the crisis but the potential hit to sentiment was clear. I recognise that a billion pound fund cannot necessarily go to 70% cash overnight which is a huge advantage of being an individual investor, but nonetheless to have not seen this coming strikes me as being asleep at the wheel.
This is the 3 month performance of the Buffetology fund managed by someone with "30 years of equity market experience":
This is the 3 month performance of my own SIPP managed by me with around 6 or 7 years of investing experience:
The old adage that if you want a job doing properly, you best do it yourself certainly seems to hold true when the job is looking after your own money.
Hello Johnsmith68.
I agree with what you have written and KAL s Buffetology Commentary is I think one that should be used by educators to educate people of all ages in the world of investing.
For far too long, children have been taught to pass exams and achieve excellent grades to go to study at University...or get a good job..whatever that is.
However, those dimwits who run the FCA should be forced by the government, to help fund Schools and Universities, with cash they received from the fines paid...use that money to educate our children about the world of investing and money.
This would help stop the general public falling prey to our banks, insurance companies and so-called investments funds ,from conning hard-working people out of their hard-earned money.
We have to accept that many people of all ages are scared to talk about money...we have as a nation to start talking, as this crisis is where we have found out that too many people are financially illiterate..and need educating.
Personally, I would volunteer to help with this in schools and Universities but I fear there is no appetite amongst the young in investing for their very financially dimished future.
Finally, well done with your Sipp..congratulations and wishing you continued success.
tony
Can we see your five year audited track record? Feels a bit harsh to take a fund which has smashed the market over years and stick a knife in when it has a rough few months, no?
Really the only point I was trying to make (and I'll concede that I made it hastily and without sufficient humility) was that someone whose job is to manage client's money absolutely could have foreseen this by simply staying abreast of the news. I manage my own portfolio in my spare time and I foresaw it in February and took action. You could say that I got lucky and that may be true but I feel that there was plenty of mounting evidence in early February that risk:reward was getting dangerously out of balance. To say that it came out of nowhere is disingenuous in my humble opinion. I certainly wouldn't claim to be a great or even a good investor or to have even a fraction of the analytical and financial skills that KAL and most of the contributors here have. I just believe that this was signposted from Wuhan long before the market took notice.
Good Evening ExpectingValue.
Thanks for your reply and it is fair question to ask, so tomorrow I will reply to you at length.
Good Afternoon Expecting Value.
I hope you will not take offence at anything I write below and if you find what I write brutal so be it, because if you are investing in small companies, as many of us are on these pages , you must realise we are prepared to accept greater risk.
Having said that I manage my own pension fund through a Sipp and a Sass and in addition I have residual income from a portfolio of properties..
However, all the money I have made from my businesses in my life have been hard won...and the area of business where I accumulated the most profits was horse racing and betting...so when it comes to evaluating risk, I understand that equation as I have been involved with both property, betting and investing for a very long time ..and through my betting understand risk and reward more than most.’.
I have lost count of the number of operators who made mind boggling profits only to lose them and very often because they are complete gamblers.
From my experience, the most successful bookmakers , some of which have and are clients have mine will tell you , ‘“ the most successful bookmakers do not just lay the horse but lay the punter”.
In addition, the most successful punters are those that accept all the risks involved and that the simplest way to success, is to limit your losses...the less you lose the more you win, it’s as simple as that..
However, many of my clients , are successful businessmen and women who have been clients of mine for over 25 years...they remain clients of mine because I proved over a long period what I can achieve for them.
So before I started the process of investing for my pension, I deposited my money into my Sipp and Sass banks accounts ..then completed several years of research, into every investment manager, fund manager , share tipster, etc etc.
At the end of that defining process, I decided that about 90% of my money would be invested with what I considered one of the best investment managers...his performance, his history , his track record could be traced back a very long time....you can do the same .
I read letters from him , I watched videos about him and I took third party opinion about him ..but in the end my decision for my money was to be made by me...I wanted the man who looked after 90% of my pension money to give me complete confidence, so I could go to bed at night and sleep.’.
This man had to have an investment philosophy like mine...which is to invest in world class companies, whose businesses had a moat and whose previous track record was there for all to see...no exploration companies, no banks, no insurance companies, no airlines , no businesses based on the “ fair weather principle” .
And ...and a man whose company had a philosophy which was to buy right, hold and do nothing ...a company that would run with its winners , as multi-baggers can be had from trading , investing for the long term or a bit of both.
In a nutshell, buy and forget....I want as many 10 or 100 baggers as I could get
Now the final 10% of my pension is totally my betting bank , for buying and selling shares in companies , I may trade or I may hold ...I am prepared to accept far greater risk here , as I know if I want high rewards I have to accept high risk but I am happy to accept the equation .
In my research or due diligence I came across Keith Ashworth -Lord.... KAL Sanford DeLand UK Buffetology Fund —-The length of the name of the fund was off putting I have to admit but nevertheless, I looked at the fund and watched it for several years , as my money sat and earned diddly squat in my pension bank accounts.’.
I looked at countless funds and monitored their performance , I looked at their good months, their bad months over many years...I wanted transparency and I needed liquidity , so if the proverbial was to hit the fan, I could liquidate my holdings...I did not want to find my money with a guy like Neil Woodford and be trapped...I avoided by the way , the funds in the Hargreaves Lansdown wealth 50 and similar bullshit traps that snare ordinary men and women.
If you are not bored to death by now ExpectingValue , you might suggest I was asking for the impossible...but in addition , I looked for a man who could get close to delivering an annual growth rate over a few years.of 20% noting I would accept a year of poor performance in return for years of over performance..
KAL over 5 years looking back from today, with figures provided by Hargreaves Lansdown as are follows...they are there in black and white.
DeLand UK .
12 months ending -15-4-16 = £ 16.42% .
12 months ending -15-4-17 = £ 20.69%.
12 months ending -15-4-18= £ 17.94% .
12 months ending -15-4-19 = £11.25% .
12 months ending -15-4-20= £10.17 minus.
Remember, 5 years ago the DeLand Fund was a bit different to what it is today and the fund was established in March 2011.
KAL professes to be a disciple of Warren Buffet ..what a load of tosh...I cannot imagine Warren Buffet investing in Revolution Bars Revolution Bars (LON:RBG), Restaurant Group Restaurant (LON:RTN), Craneware Craneware (LON:CRW), Dart Dart (LON:DTG) and Provident Financial £PFG.
However, to give KAL credit he did hold stakes in some Buffet style companies that perhaps Buffet would admire, such as Games Workshop Games Workshop (LON:GAW), London Stock Exchange London Stock Exchange (LON:LSE) and Relx Relx (LON:REL) and others .
Now compare the figures below to the performance where 90% of my pension money is invested...I made the choice , I made the decision and if I mess it up I will blame myself ...but of course I can also blame the man with whom I have entrusted my pension fund.....because I chose the wrong guy ...and we are not talking about insignificant sums here...this is money that will allow me, my wife and our children to have a comfortable retirement when that day comes.
12 months ending -15-4-16 =£17.44%.
12 months ending 15-4-17= £27.45% .
12 months ending 15-4-18=£ 8.18% ..
12 months ending 15-4-19 =£24.24% .
12 months ending 15-4-20 =£4.36%
Over 5 years as you can see KAL has attained a satisfactory total return of 56.13 % and to date has recovered about 15% since its 26% loss I spoke about previously ..
My pension fund is invested with a man who has returned 81.67% over the same identical period as KAL....the difference is an additional 25.55% of performance over 5 years.’
You , ExpectingValue , do not need to be a brain surgeon to recognise this outer performance compared to KAL ..and hopefully accept my evaluation all those years ago has proved to be a good investment.
Remember also. when I did my research 5 or more years ago I was looking backwards in the hope I could see good results going forward and on the face of it the above figures from KAL are reasonable...provided you are prepared to forget that 26% Monster loss detailed in March , when KAL stated “ did not see that coming“ ....I personally, see a loss of 26% in 3 months , as a “ canary in the coal mine moment to any investor in the Buffetology fund run by KAL...many will disagree but frankly I do not care about that .
I love Tesla but the shares trading at over $1000 in mid February was a clear sign to me that the bull market had reached its summit ...and soon after sold a big chunk of my holdings to give me 35% cash.....interestingly , since I sold a big chunk of my holdings, I like most people have been amazed at the recent sharp recovery.’.
At this point you probably are wondering where I have invested 90% of my pension fund......so I am going to tell you.
However, before I tell you, please tell me more about you...are you invested with KAL..do you control your own investments ..not because I am nosey but because I am eager to learn from everyone on Stockopedia .
Go and check out Terry Smith and `Fundsmith Equity and as that bread advert used to say..” Enough Said” .
I sincerely wish you prosperity but I know one thing for sure, many men and women do not learn from their mistakes ..whatever you believe.
Finally, one of the other enquirers asked if I had invested in the FANGS ..Terry Smith in his February 2020 Shareholder meeting which you can view on Fundsmith website..gives a most interesting view on why he is no about anytime soon going to be buying either Amazon or Google Alphabet.
My view as to the best way of summarising Fundsmith ..is straightforward ..it is a GOW Fund....a fund for Grannies, Orphans and Widows .
Apologies for any typos and note I hold shares in Revolution Bars £RBG...I frankly do not care if the company goes bust..I do not believe it will as Paul has outlined all the risks elsewhere..but it’s going to a fun ride along the way and that’s why I have a 10 % fun fund which may go pop or may allow me to replace my Mercedes which has just completed 290,000miles ..why put money into a new car when you can speculate in a new share ..that just might turn into a 10 bagger.
My back of the envelope returns for the Buffetology fund and Fundsmith for calendar years 2013 to 2019 are average annualised returns of 18% and 20% respectively.
Their outcomes over 7 years aren't that much different.
Looking at that performance in the current climate you should be managing your own investment fund! As this is from a Stockopedia folio I assume you must be invested in shares, Investment trusts and possibly ETFs plus the cash that has accrued from transactions (and that thing of the past , dividends). To achieve this performance I would have thought you are probably heavily exposed to FAANG+ stocks and/or a very good trader who bought at the last major dip in March and benefited from the recent rally. Today’s market tremors may be a sign that you can repeat the process - if so would love to know your strategy as I suspect like many investors on Stockopedia I am sitting on losses despite having a SIPP with a large cash % even before the COVID-19 crisis . A very risk averse strategy offset by a slightly more racy strategy for my ISA which of course is down 25%+!
Hi Acounsell. Thanks for that but as I say in reply to another poster here, I wouldn't claim to be a good investor. I'm a novice and I frequently worry that I don't know what I'm doing but when I see an experienced fund manager claiming that this current crisis was totally unexpected, it makes me think that I may be better off managing my own affairs. I believe there was plenty of evidence in early February that this was getting very bad. The trading update from Burberry (LON:BRBY) on February 7th was a clear signal that anybody could have interpreted. All I did was to move into cash and stand aside whist the crisis evolved. I was lucky but I made some of that luck I believe. I repurchased some positions at better prices so I have seen some of the recent rally but I am still mostly on the sidelines for now. What happens next is way more difficult to gauge and arguably this is where KAL and other professionals will earn their money going forward. I wouldn't bet against his fund doing considerably better than my portfolio in 5 years time and that really is what I should have made clear in my original post.
Well his fund is benchmarked and promoted as a UK Small Company fund. By inference his "job" is to be invested in that manner. If investors in such a fund want to reduce their exposure to that asset class it is down to them to do so by selling and exiting, not the fund itself.
Thank you everybody for your efforts on the link to KAL’s note.
Having now read it, I realise I had read it and commented at the time here or on Twitter that I was surprised that:
I hold a minute amount of his fund in my son’s JISA. It is up 54% since Nov 2016 when I bought, which is more than can be said for my holdings, so I am not saying I would not invest in a KAL fund.
"Finally, I urge everyone to read the March 2020 fund review by Keith Ashworth -Lord ..his Buffetology fund did lose over 26% in March but when he stated he did not see the lockdown coming ..and other comments and observations , it illustrates to me that many professional fund managers should not be managing their clients money....."
I read KAL's commentary. I thought it was fairly straightforward at least. Not many fund managers talk about their losers so openly.
As a professional fund manager, should he have seen the fall coming and sold in advance? I think it depends on his investment remit, which is to buy good companies, valued on a DCF basis, and hold for the long term. I would not want a fund like this to become a trader, trying to front-run dips. If I want that from a fund, better to invest in a long-short, absolute return or all-weather style fund.
Otherwise the hedging is up to us.... short the FTSE during downturns.
As an investor, I always compare buying a managed fund with simply buying an index tracker fund. The fees are far lower so less leakage in the long run, more compounded growth, which really adds up. A fund manager has to have 'alpha' to pay back their fees and more. As a result, I usually avoid funds, many are really closet index trackers with no edge.
KAL may or may not have an edge. At least he seems to have some sort of process, using DCF. But his holdings appear to lack concentration. In comparison, his guru Buffett's (Berkshire Hathaway) top five stocks account for 69% of holdings, somewhat driven by his huge Apple holding. KAL's top five is 21%. Buffett did maintain it's better to hold a small number of great stocks. One of Buffett's quotes went something along the lines of "why would you invest in many stocks, why not put more money into your best three ideas". It was also Buffett's point here "diversification is protection against ignorance".
So I avoid funds, prefer trackers in this instance.
There is a good quote from Mr Black Swan, Nasir Nicholas Taleb on a similar theme which is “don’t tell me what you ‘think’, tell me what you have in your portfolio”. Vast majority of so-called experts we see commenting on markets are not prepared to put their money where their mouth is. If they aren’t, why should anyone else? Paul - we like your comments as you also tell us where you are trading. You are eating your own cooking, good for you.
Very good point Nebraska,
I'd advise anyone to check a fund managers holding in his own fund before you invest. 'I put my isa allowance in each year' is very common, oh wow 20k well done, keep on going with my money.
On the other hand RIT Capital Partners (LON:RCP) has £300 of Lord rothchilds cash, Ruffer, Troy, Lindsell train & fundsmith big allocations. Probably lots of other funds, but maybe no surprise, they have all done proportionally well with Ruffer in particular up, as they have a very Taleb approach using derivative protection. Worth a look if you need a fund to have some hope of capital protection (the safe barbell in Talebs approach) & allowing you to concentrate on small caps.
https://www.ruffer.co.uk/-/media/Ruffer-Website/Files/Fund-reports/RTRF/C-class/2020/2020-03-RTRF-C-class-fund-report-Mar2020.pdf
Hi Paul,
Excellent comments as always & if you look at the IMF report the figures are phenomenally bad everywhere (ignoring the ability to predict of course). The papers are finally starting to raise the question about this being a mass , group think, overreaction.
https://www.telegraph.co.uk/bu...
No mainstream politician dare say it outright, but it is what many people are thinking. Are we not engaged in a huge and destructive over-reaction to the coronavirus pandemic that threatens lasting harm to the economy and society at large?
Complete shambles, start to finish, all the nightingale hospitals are empty, London critical care never at more than 80% & the whole marketing message 'stay in, the virus can get anyone, kill anyone' ....and in a few weeks time 'forget all that, erm, come out, er, its still there but, well just forget the bombardment we gave you, just erm, go out, if you have any money or job of course.'
''The latest World Economic Outlook by the IMF predicts a fall in Spanish GDP of 8%.
To put the projected contraction in perspective, it is useful to look at the global financial crisis of 2009, when the Spanish economy shrank by 3.6%. During the sovereign debt crisis of 2012, activity fell 2.9%.In the context of Europe, the slump in the Spanish economy this year, according to the IMF, will only be comparable to that of Portugal, also 8%, and Latvia and Lithuania, both in excess of 8%. In Italy and Greece, the IMF predicts, the fall will be even greater: 9.1% and 10%, respectively.
The damage will be somewhat lower in the two main euro economies, however, with France to lose 7.2% and Germany 7%. The eurozone as a whole will lose 7.5%, but with very different intensities.''
I agree with your sentiments that we at least need a plan on how to exit lockdown, sooner rather than later, but on the other hand; those complaining that the death rate is lower than expected* so 'why did we even bother with lockdown?' are a bit like Eurostar passengers complaining that they didn't even get a bit wet while travelling London to Paris, so 'why did we bother building the Channel Tunnel?'
All that said, Corona is the new normal, we will have to accept the new risk:reward profile sooner rather than later.
*likely higher than expected as for whatever reason we have not been counting care home deaths.
“Complete shambles, start to finish, all the nightingale hospitals are empty, London critical care never at more than 80% & the whole marketing message 'stay in, the virus can get anyone, kill anyone' ....and in a few weeks time 'forget all that, erm, come out, er, its still there but, well just forget the bombardment we gave you, just erm, go out, if you have any money or job of course.'”
John, I really think you’ve gone way over the top here.
The nightingale in London took in its first patients a week ago. The NHS also increased ICU by temporarily converting operating theatres. A very logical plan to avoid running out of capacity. If they had run out of capacity by not doing this everyone would be complaining that they had done too little. The requirements for staying at home to reduce the spread are easy to understand. The government/NHS/PHE have done a good job of explaining what’s being done and why and the compliance levels clearly indicate the public accept that. There is no reason to believe that when they end the lockdown the message will be anything other than similarly clearly explained.
The NIghtinggale has been built so that the NHS can cope. Not cope today, no. Cope tomorrow when the lock-down is lifted. The current flat curve UK will stay flat for many, many months. The job of the government now is to figure out how to open up of the economy without overflowing the Nightingales. It's not easy. The risk/reward for them is not evenly spread. If the hospitals overflow they'll get lynched. If they remain empty, they'll be lauded and will be able to keep their government backed pensions. But the rest of us live in poverty. So their job is to keep the curve flat (at some rate). What that rate should be (ethically) is the big question. As a society we need to get to grips with this reality. Technology (Medical or tracing) is probably not going to arrive to save the day.
Hi Graham F,
Over the top, maybe a little, but that all depends really on if you think the response is in proportion or not.
If you have a look at this site it raises questions that cannot be ignored and at last are being raised by the media.
http://inproportion2.talkigy.com
And this is the key question, as it's core to the opening of the lockdown, and trying to limit the damage. After all the NHS can cope, that was the objective I believe.
Those figures are just hospital reported ones, they don't include any outside such as care homes or at home. The ONS figures for the week up to 3rd April show excess deaths were around 6,000 this is by far the highest ever recorded and in London is over 60% higher than the previous record. THat is just one week which is before the virus has peaked, so I think the deaths are much higher than those figures indicate, if you doubled them you would be closer to the real numbers. By now it could be over 20,000 already. I can't see this lockdown being lifted for at least 3 weeks.
would you know roughly how many died with only Covid 19 and nothing else?
You've posted the inproportion link before and I, for one, am not having any of it. He does not compare like with like, and then commits a series of logical fallacies that don't stand up. For example, starting his death counter from Jan 1st 2020, as opposed to end of of Feb when we started detecting COVID-19:
From inproportion.com:
As of 3rd April, the total number of deaths so far this year is around 6% less than for the equivalent period in 2018
(164,444 vs 175,419).
Whereas we actually know from the ONS that deaths when COVID-19 has a foothold are much higher
From the Financial Times via the ONS:
In the week ending April 3, the Office for National Statistics received registrations of 16,387 deaths, a figure that was 6,082 higher than the average for that seven-day period over the past five years.
And again, he fails to compare like with like:
From Inproportion,com:
By 2020-04-10 in England and Wales, around 8,429 people have died "with" COVID-19. If 2020 follows the pattern of 2018, a bad year for respiratory disease, then in the same time period...
So what he's basically saying is that more people died from repsiratory virus in the period before COVID-19 really got a foothold so therefore COVID-19 isn't a problem.
Also, the ONS is pretty clear...
From the Beeb:
Covid-19 is way above flu and pneumonia deaths when the disease begins to take hold.
Some more examples of cherry-picking from inproportion.com:
England (not Wales) is currently unique in Europe in there being a projected increase in mortality beyond earlier waves of respiratory disease. The question remains open as to whether the partially increased mortality is due to the coronavirus alone or also due to the sometimes drastic measures taken (e.g. isolation, stress, cancelled operations, etc.)
Except we can do a natural experiment, whereby if 'isolation' is the root of all this death as opposed to a voracious respiratory disease, we would expect the countries with the tightest lockdowns to have spiking death rates due to isolation, stress, and cancelled operations. Except they don't, they have falling mortality.
More biased cherrypicking:
Overall deaths in Europe are represented by the green line. Notice that Europe remains in a better position than it was at the worst of the 2016/17 flu season. This raises the question: why are we taking such unprecedented measures with quarantines and shutdowns when this was not necessary then?
His argument appears to be that we are experiencing a death rate comparable (and increasing) to a bad flu season despite the most draconian lockdown in modern European history, so why the lockdown guys?
He is a biased, cherry-picking, crank who is pretending the lockdown isn't happening to argue for the removal of ... the lockdown.
Hi John
Sorry, but I’m not going to spend any time reading that website. It is by someone who chooses remains anonymous, and also admits he is not qualified to provide a detailed analysis. You seem to believe that the authorities are an incompetent shambles. If that is the case they surely do not have the competency to coordinate a campaign of misinformation across government, NHS, PHE, Imperial College and so on.
Hi Graham & IncredibleMosesLeroy
Some good points but my point still stands.
Is a total lockdown , the shutting of the economy, on a global scale in proportion & the correct playbook.
I am not suggesting there should be no restrictions, but this is not eradicating the disease, just slowing it.
There are alternatives, A partial lockdown , isolate all over 60, all with serious illnesses, social distancing, more restrictions in areas with large number of cases. Let the rest carry on.
Is that more in proportion? Even if this is considered an approach that now stands with hindsight, what can't be argued with is that the NHS can cope, the curve has been flattened. So today, right now, is continued lockdown a proportionate response given what we now about the disease compared to the economic destruction & all the other implications that follow?
There's a terrific book on this called "Super-forecasting: the art and science of prediction".
It's by Philip Tetlock, I spent the Easter weekend reading it. Essentially the pundits who are most confident are the ones we tend to believe even though almost never make testable forecasts. Really good forecasters tend to be cautious and regularly update their predictions, although usually only by small amounts. Their caution and willingess to change their minds means that most people don't regard them as experts. Only problem is that teams of these people completely wipe the floor with "experts" from other domains,
On the OBR report - I think we should always remember that they have to write a report because that's their job. But they don't have any special insight into how this will pan out and their baseline is most definitely not a prediction - they're very clear about that. Basically I don't think we can view the OBR report as any kind of forecast - it's more a kind of doomsday warning to the government that they need to figure out how to lift the lockdown sooner rather than later.
They do, however, suggest that there will be quite a rapid bounceback in economic activity when the lockdown is lifted. I agree with Paul - I'm not convinced that that you can turn the economy back on like that. For instance, I understand that in China online fashion companies are seeing a very slow recovery now that everything's reopened.
Skimming through the RNS's this morning I was also struck by the fact that a number of companies were announcing redundancies even though they could presumably furlough people. Contractors and temporary staff are being laid off across the board.
It's no predicton at all to say that picking our way through this will be quite tricky.
timarr
Essentially the pundits who are most confident are the ones we tend to believe even though almost never make testable forecasts. Really good forecasters tend to be cautious and regularly update their predictions, although usually only by small amounts. Their caution and willingness to change their minds means that most people don't regard them as experts.
This reminds me of an anecdote that stuck with me from one of the well-known BE books (one of Dan Ariely's?) where you go to the doctor with a problem. What would you prefer? A very confident doctor who quickly pronounces your ailment is not really a problem, or a doctor who seems unsure about it and so references a book, then takes a minute to think things over before giving his prognosis? Most people would naturally prefer the former but in reality it's irrational to give too much credence to such an overconfident expert.
All the best, Si
Paul, could you please explain what you meant when you wrote:
"Therefore, I think the next financial crisis could well be a disintegration of the Euro, into 20 separate Euros, with an instant & gigantic correction of all the Euros to the levels that they should be at, were they not artificially pegged at parity."
Are you referring to the individual national currencies in the Eurozone that existed prior to the introduction of the Euro?
Newriver Reit (LON:NRR) has appointed a joint broker, which could indicate an imminent fundraising. Has anyone seen or done an analysis of the share price performance of companies following placings, where these are done for prudent or positive reasons rather than in desperation and distress?
Nobody has so far noted the good news at Castleton Technology (LON:CTP) where a takeover has given a 40% boost to the stock.
I have two regrets:
- I don't have any (I liked it but procrastinated)
- it marks the disappearance of another AIM stock to foreign parts. We just do not seem to have the necessary cojones to build to global scale
Whilst not arguing with your basic point I suspect that Housing Associations, which are the focus of Castleton Technology (LON:CTP) are not an international market except perhaps in Australia so I'm not sure that this is an example of a company with potential to build globally.
Edit: I've now read the RNS - clearly the bidder disagrees with me!
If you missed the Stephen English webinar hosted by piworld last week, is worth a listen. Stephen outlines some of his thoughts on investing in CV19 times. Here are a few snippets:
“Don’t obsess over bottom fishing, keeping the wrong score. Prepare for shares to fall more after buying mentally. No bell rung, won’t know for weeks or more correctly months bottom in place. Most profitable investments need to hold nose when you buy.”
“We're in the discerning stage. More interested in individual companies that offer value, than focused on ‘the market’. Stocks can rise in a bear market and fall in bull market, the wider stock market is secondary.”
“Right issue stocks tend to outperform. Buy where have clearer visibility on their prospects. But if company was already weak before CV19, w falling revenues, move on, target those with unblemished earnings power but wrong capital structure going into it.”
“At this stage only buy high quality companies, where you can forecast future earnings, and their price has disproportionally cratered. Low quality could end up a value trap.”
"Beware some quality stocks, especially where op margins have as risen strongly as sales. Gearing makes a good co look great but op gearing works against you in a downturn. Esp if end markets permanently impaired or added costs."
"Central banks are on a path of least resistance. Like Nero reducing silver content in denarius the numbers just get bigger & bigger until some ultimate denouement. It won’t be immediate. Could be a blow off top in inflation ultimately, but we’re probably at least a decade from really high inflation. It’s interesting that inflation expectations are rising despite oil falling."
Tomorrow, Thursday 16th April, 1pm, we have another piworld Thursday webinar with Jamie Streeter aka @CompoundIncome who talks through his strategy of Investing, Compouding & Surviving. Jamie's an ex Fun Manager for a number of top institutions, and has developed his own metrics called Compound Income Scores to aid his investing decisions. Pre-register here.
I advise anyone to read Samuel Pepys's diary just for context of current events and for an interesting read in these lockdown times. The man lived through the English Civil war, the execution of Charles I, various wars with the Dutch, the Plague, the Great Fire of London, and he had to have a death defying operation as a young man for a kidney stone (without anaesthetic) ... to name but a few of the events that occurred during his life.
I advise anyone to read Samuel Pepys's diary just for context of current events and for an interesting read in these lockdown times
Absolutely - but he didn't just live through those great events, he was right at the heart of them.
From a humble background he ended up as Naval Secretary and laid down the foundations of the Royal Navy, he was at the execution of Charles I, he was on the ship that brought Charles II back to England, he was the man that informed the King of the Great Fire of London ... and somehow, by outrageous good fortune he wrote the best diary of all time in the middle of this and it survived to be read by us.
Do read it.timarr
Trident - Thanks for the reminder. I read it many years ago when I was stuck in a hotel for a week. Will re-read it during this lockdown.
BTW you can download it as a Kindle ebook *for free* from the Amazon UK website!
Agree but unlikely it will take the whole of the lockdown period.
If you have not all read it I suggest the Hilary Mantel trilogy of the life and times of Thomas Cromwell. Wolf Hall, Bring up the bodies and The Mirror and the Light.
I found the first two imppossible to put down. The third I am finding heavey going so it could take a long time plus it is nearly 900 pages longou can buy it from amazon. I have the print copies because I keep needing to re-read bits. I buy such books second hand on amazon They are usually relatively cheap.
Personally I found the Mantel effort poorly written and unreadable. Pepys is a far better, and more informative, read.
Anyone looking for a long read might try Edward Gibbon 'History of the Decline and fall of the Roman Empire' A superlative writer and chronicler.
Picking up an earlier point....in business and finance the confident bullshitter type often trumps the more diffident commentator who is more accurate in his comments. Perhaps an example is D Trump where supreme self confidence in his own utterances has taken him a long way. He also has a TV background which seems to be a pre-requisite for a politician today.
An interesting tender offer spat seems to have broken out over Fulcrum Utility Services (LON:FCRM) in the last few days. I'd be really interested if readers hear (or Paul if you feel inclined) had any views or background to share?
It's obviously perked up the SP and an activist or critic prepared to invest can IMO sometimes focus the minds of the board and SMT. FCRM are painting it as an opportunistic undervaluation.
I hold Fulcrum Utility Services (LON:FCRM), and am tempted to sell at a small loss!
The good part for me is that the final quarter of 2019 was a record high for sales, and that the first quarter of 2020 would have been even higher but for the delay of two contracts due to covid. £71m order book for when things recover, no debt, and special divs promised for the next 2/3 years from the sale of domestic connections. £FCRM has been through the wars but now seems sorted. I hold, and hope not to have to sell at what looks a tricksy offer.
His final paragraph sums it up, but the rest is very worth a read
Actually, there is so much common sense and logic in Howard's memos I'd say it's essential reading, particularly for those that have not been investing for long. I personally liked the start of the memo; pretty much what I was saying last week but it doesn't matter how many times you hear it. I need to be reminded on a constant basis that I'm kidding myself if I think I am informed enough to extrapolate out to the future from what happened in the past.
All the best, Si
Hi Simoan,
All 5 of his most recent articles are excellent & give a great overview of how this unfolded, this is like years of trading and investing experience & phycological pain in just 4 weeks! A few friends and family members have asked me about investing now - I've pointed them to these memos...who the f knows!
One thing that is strikingly obvious though is how the past was almost quaint.
The 2008/9 global bailout packages have caused 10 years of constant commentary and hand wringing about the imbalances in the system, asset prices inflation, budget deficits, government debt etc.
Today, those concerns are almost comical given we already now have $10 trillion of stimulus and counting & all the 'crazy' things the fed is doing. So what next, given the impact the financial engineering had in 2009.
As a sobering thought, only 20 years ago, Long Term Capital Management collapsed, this was the headline:
''Federal Reserve Intervention
To save the U.S. banking system, the Federal Reserve Bank of New York President William McDonough convinced 14 banks to bail out LTCM.7 They spent $3.5 billion in return for a 90% ownership of the fund.
The Fed started lowering the fed funds rate. It reassured investors that the Fed would do whatever was needed to support the U.S. economy. Without such direct intervention, the entire financial system was threatened with collapse.''
$3.5bn to $10+ trillion , in 20 years, struth!
I was at one of the banks asked to bid on the LTCM portfolio. They were simply overlevered in their trades, they were not a risk to the system. There was nothing particularly clever or insightful about their trades.
The Fed/ regulators have continued to allow excess leverage in the system and that is still the problem. Overlevered business either raise money or get wiped out and replaced by a better business model-that’s what capitalism should look like. The system has been completely corrupted by financial engineers (pretending they’re capitalists).
This is not a black swan event. I started trading just before the crash in 1987. I have seen so many instances of markets or sectors losing 50-90% of their value. Most people simply choose to game the system. Even the VAR (value at risk ) models inside the bank are gamed continuously. In what way is covid 19 unforeseen? A history of pandemics, SARS,Mers, Ebola, Bird flu-we’ve had enough warning signs in the last 15 or so years.
The Fed is now totally complicit in the games being played. Most of the beneficiaries so far will be amongst the financial community. Inflation has been rampant in asset prices for some time now even though we don’t see it as clearly in our everyday existence.
These are exceptionally dangerous investing conditions. The world and government are addicted to debt and terrified of letting the edifice come crashing down.
I have no idea how it ends but a lot of the sentiments on here are spot on. Balance sheet strength, sustainable business model, clear addressable markets. You might not make as much in a market normalised rally but risk adjusted return will be significantly superior in my view.
Anyway rant over!
Morning all,
Investors friend and good egg Howard Marks has his latest, and long, memo:
https://www.oaktreecapital.com/docs/default-source/memos/knowledge-of-the-future.pdf
His final paragraph sums it up, but the rest is very worth a read
"But Justin Beal, my artist son-in-law, is mystified. “I don’t get it,” he told me on Saturday. “The virus is rampant, business is frozen, and the government’s throwing money all over the place, even though tax revenues have to be down. How can the market be rising so strongly?” We’ll find out as the future unfolds."
S&P up another 3%, Mr C small cap tweet, another tale of woe, I cant help thinking US is two-is weeks away from the cascade of bad news.
That is a really good article. What interests me is how, under these unique, unprecedented circumstances, many philosophies that have been rejected under normal conditions seem feasible and others, ludicrous. There is a "money tree" if we say there is. When you can't use the labour that creates wealth, you realise how you need it, as much as the capital to float the business. Is life ultimately really only about food? Do footballers and other entertainers really have to be paid so much? If we save above our daily needs, is that to cope with future trouble? If so, how much trouble do we need before we use it?
I think the reason why the markets are up is because Coronavirus cases have levelled off and seem to have peaked, also deaths. Also many countries are coming out of lockdown, even worst hit ones such as Italy and Spain have lifted some restrictions this week. So they can see an end to this. But I don't think they have factored in yet the economic fallout for some reason, maybe they think everything will be back to normal in a few months?
...supported by a wall of QE, bailouts, loads, helicopter cash (in some countries). But is the Fed put strong enough to cope with an effective write off for 2020 earnings?
we’re are markets up?
Probably means markets are up from the recent lows.
"I think the reason why the markets are up is because Coronavirus cases have levelled off and seem to have peaked, also deaths. Also many countries are coming out of lockdown, even worst hit ones such as Italy and Spain have lifted some restrictions this week. So they can see an end to this."
The problem with this reasoning is that, until a vaccine is developed and is readily available (which might be a year from now or never), as soon as lockdown restrictions are lifted, the Coronavirus cases and deaths will start growing again and restrictions will probably eventually have to be reintroduced.
"The problem with this reasoning is that, until a vaccine is developed and is readily available (which might be a year from now or never), as soon as lockdown restrictions are lifted, the Coronavirus cases and deaths will start growing again and restrictions will probably eventually have to be reintroduced."
There's actually no hard evidence for the lifting of lockdowns causing deaths to increase or of the efficacy of lockdowns at all. See Sweden and Japan for example.
Not so sure.
https://www.npr.org/sections/c...
Thanks for the article, a very interesting read...
There is a lot of debate about whether we should try and predict where this is going, and a lot of wise people are warning us against it. This is exactly what they should be saying, we are all guessing. But we can still make educated guesses, we just need to remember they are still guesses. I've always felt people are far too confident in their opinions, and we all need to be aware of our limitations.
There is a quote from Tinker, Tailor, Soldier, Spy that goes something like this: "Never trust a fanatic, they are always hiding some hidden doubt".
My way of looking at it is that a lot of us buy companies based on the managers. This is a different type of guesswork that relies of the principle of cause and effect. It believes that good decisions lead to good outcomes, and good outcomes lead to further good decisions. This is also a central idea in momentum investing.
If we were to apply the same principle to the current market, we only need to look at what is happening to make an assessment on whether this is a market we can believe in, or choose to ignore. These points are taken from Howard Marks memo:
- one of the greatest pandemics to reach us since the Spanish Flu of 102 years ago,
• the greatest economic contraction since the Great Depression, which ended 80 years ago,
• the greatest oil-price decline in the OPEC era (and, probably, ever), and
• the greatest central bank/government intervention of all time.
With these facts in mind can we have any confidence in this market at current levels? Personally I don't think so. We don't need to come up with detailed analysis to make an educated guess based on the information we already have available.
Sorry for the rambling post, I just really like discussing investment principles.
Ref connect again. I recall Real Estate investment bought a number of Tufnell sites and Connect guaranteed the rent. Not sure what happens to these but I would not see it as positive for REI given must be long odds some of these will be closed
I agree it is worth looking at Connect. I like the cash flow from Smith News but was dismayed by the purchase of Tuffnells. The new management have taken a long time to bite the bullet on this. Can be certain this will take some time to complete but it is a nasty hole that needs to be addressed. There is the ashes of a decent Business here.
Morning Paul: I hope you are feeling better? I was sorry to read about everything that you've been through in the last few months.
I second MassimoJack with a request for a look at Connect (LON:CNCT) The disposal of the Tuffnell's biz looks anything other than straightforward but if they can complete it and rid themselves of it then they are left with Smiths which is ripping costs out of what is a decent-ish (albeit a slowly decaying) business. This is a decent size business for a market cap of £45m as a I write this with the share price up around 10%. At the least I would've thought that this is an interesting turnaround situation involving a company which operates in a duopoly backed by some large contracts with suppliers.
DYOR. I am long.
Cheers
Andrew
Hi Andrew,
Sorry I didn't get round to looking at Tuffnells. The logistics sector doesn't interest me, so it's not something I would want to invest time into.
Regards, Paul.
Kromek (LON:KMK) RNS today saying that they are entering the race to manufacture ventilators under licence from a major Japanese company.
No doubt the sp will shoot up as this sector is now turning into a bubble.
Highly speculative. DYOR.
Why? There is surely going to be a huge glut of this equipment 12 months down the line. Even now, it doesn't seem to be the most critical shortage the NHS faces.
We are going some pretty big procurement overspends, and misalloacation of resources as a result of the panic to stampede to produce ventilators etc.
These will sit in Govt warehouses for years, rather like the TamiFlu vaccines.
The facts seems to be that unless you spend and plan in advance judiciously, you are cursed to buy at the top of the market, and plan in panic.
That being said I do have sympathy with the Govt, and would like to see some sharper put downs of journalist questions.
As Stanley Baldwin once said of the then press, but equally could be said of media and punditry today in general today:
'Power without responsibility, the prerogative of the harlot throughout the ages'
I bet that the share price spikes won't last, from tiny, irrelevant companies which seem to be jumping on the Covid-19 bandwagon. Quite sick actually, the way I look at it.
My morning smallcap tweet:
Driver (LON:DRV) Tissue Regenix (LON:TRX) Solid State (LON:SOLI) U and I (LON:UAI) UDG Healthcare (LON:UDG) Live (LON:LVCG) Diurnal (LON:DNL) Prime People (LON:PRP) Ceps (LON:CEPS) QUIZ (LON:QUIZ) Georgia Healthcare (LON:GHG)
Driver Group (DRV) guides H1(March) pretax broadly in line with internal forecasts with no material covid hit. Covid will soon impact customer behaviours and activity levels, perhaps materially so. Net cash £3.3m. Cutting costs, passing div.
Tissue Regenix (TRX) has secured a US Government backed covid loan of $629k so expects cash to last until at least the second week of July 2020. No covid no disruption in its supply chain. Q1 rev up 18%. "The Board continues to be encouraged by discussions with potential investors"
Solid State (SOLI) Guides FY(March) rev near F/C of £68m and adj pretax ~10% ahead of forecast of £4.2m. Net cash £3m and unused credit £7.5m. Co designated a critical supplier. Soft demand for batteries for the commercial aerospace market and in computing products for certain niche applications. No guidance.
U and I (UAI) Guides FY(March) gross development and trading gains c.£16m against its target of £35-45m. As previously stated, Brexit, and then the General Election delayed several key projects. Cutting costs. Passing div. "Delays in third party decision-making, coupled with restricted site working practices, will impact on the rate of development expenditure on our projects." £70m of free and restricted cash available imminently plus £11m of undrawn facilities. No FY21 guidance.
UDG Healthcare (UDG) Strong H1 FY20, well ahead of prior year. Covid will hit H2 so FY financial guidance withdrawn. Dv passed. Net debt to EBITDA ratio ~0.3x.
Live Company Group (LVCG) £500k loan from chmn at 16.2% monthly in advance and £25k fee and legals of up to £25k. No events have been cancelled, though a number have been postponed. Revised agreements with RiverFort and YA. Are these death spiral lenders?
Diurnal Group (DNL) receive the initial non-refundable payment of $3.5m for Alkindi Sprinkle license. Co has enough cash to take it through to profitability based upon current plans and assumptions.
Prime People (PRP) significant reduction in demand. Cutting costs, passing div.
CEPS (CEPS) says cash resources are sufficient, Board has either cut or deferred all or part of their remuneration as a precaution. Long-term impact on the Group's performance will not be known for some time.
Quiz (QUIZ) website now fully functional.
Georgia Healthcare Group (GHG) possible offer from Georgia Capital of 1 share in GCAP for every 5.22 shares. Conditional on independet dirs' unanimous rec. That's 94p/sh, a 5% discount. "The Independent Directors consider GHG to be undervalued by the market, but...blah blah blah will roll over."
Morning Paul, wondered if you have any views on the announcement by Connect (LON:CNCT) this morning? They are finally ridding themselves of the troublesome Tuffnell’s business, and there is also some further colour on trading since the Government lockdown was implemented. Thanks
Good Morning,
Beeks Financial Cloud (LON:BKS) : Acquisition and COVID-19 Update
https://www.investegate.co.uk/beeks-fin-cloud-grp--bks-/rns/acquisition-and-covid-19-update/202004150700066517J/
Would very much appreciate your comments around "earn outs" in this specific case and maybe more generally too if possible?
many thanks,
Hi welwichia (good user name!)
The earn out provisions are explained in the RNS - I've copied it below.
Earn outs are additional payments made to the vendors, in a takeover, if (and only if) agreed targets (usually on profitability) are achieved. The purpose of this is to incentivise management of the business to work as hard as possible once the takeover bid has happened. Without earn outs, there's a big risk that the vendors would then just sit in their offices drinking gin, and not bother doing any work, with bulging pockets from the takeover bid.
Earn outs are most important when acquiring a small business, that relies on key Directors to continue working, and be incentivised post-acquisition by another company.
Earn out consideration may be payable by Beeks depending on the Group achieving certain challenging gross revenue targets during the financial years ending 30 June 2020 and 31 June 2021. The maximum amount of earn out consideration payable in respect of the financial year ending 30 June 2020 is £500,000 payable in cash and the issue and allotment of such number of Ordinary Shares as equals £350,000. The maximum amount of earn out consideration payable in respect of the financial year ending 30 June 2021 is £1,600,000 payable in cash and the issue and allotment of such number of Ordinary Shares as equals £800,000. The maximum aggregate consideration payable (including the base consideration) is £4.55 million, capped at 2x the revenue earned by Velocimetrics during the financial year ending 30 June 2021.
thanks very much Paul - I am really learning a lot from your deep experience and generous sharing ... also the many thoughtful comments from the user community here every day. Helps so much to hear a voice of calm and reason in these difficult times!
Thanks welwichia, I appreciate your reply.
I don't say it often enough, but my articles here are just one person's opinion. Sometimes I'm right, and I'm often wrong. It's interesting to discuss things.