Small Cap Value Report (Wed 15 Feb 2023) - GATC, PIER

Good morning, Graham here. The RNS feed is light on news so I'll leave it there for today. See you tomorrow!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Graham's Section
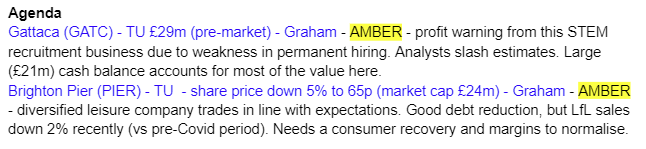
Gattaca (LON:GATC)
- Share price: 90.5p (pre-market)
- Market cap: £29m
Paul normally covers this one but I’ll take a quick look at it this morning.
Gattaca is a STEM recruitment business with an uninspiring financial track record:

The main attraction with these shares seems to be the strong balance sheet, rather than its financial performance.
Here are the key points from today’s trading update, which relates to the six months ended January 2023.
Although it doesn’t explicitly say so, this is a profit warning, and analysts have downgraded forecasts
H1 net fee income +5% year-on-year to £22.7m
“Core sectors” seeing double digit growth, weakness elsewhere.
Permanent hiring shows “signs of weakness since the turn of the year”.
Net cash rises to £21m as of January 2023, vs. £12m in July 2022, thanks to the collection of receivables (N.B. this is not a measurement of profitability).
CEO comment highlights the weakness in permanent hiring:
As we enter the second half, we are conscious of softening in some external sectors, and perm is likely to be impacted by a level of restraint around hiring, shifting candidate sentiment and, as such, slightly longer hiring cycles. Despite this we continue to see demand for STEM skills in our core sectors and the shortage of candidates plays to our key strength of deep knowledge and understanding of our sectors and niche skills."
Estimates - thanks to Equity Development for sharing their forecasts.
Their adj. PBT estimate for FY 2023 falls from £2.5m to £1.8m.
Their adj. PBT estimate for FY 2024 falls from £5.9m to £4.25m.
The analysts at Liberum do likewise, getting the same number for FY 2023 and a slightly lower number for FY 2024.
My view
I can think of few examples of recruitment companies that turned out to be high-quality investments, and it would surprise me greatly if Gattaca turned out to be one.
The track record isn’t there, and the “new” management team isn't really new: the CEO has been with the company for 20 years, and was previously Group Business Development Director.
The CFO was previously (since 2018) Gattaca’s Group Director of Financial Planning.
Today’s profit warning is probably not their fault, but it doesn’t really matter: either way, it goes to show how unpredictable the company’s profits are.
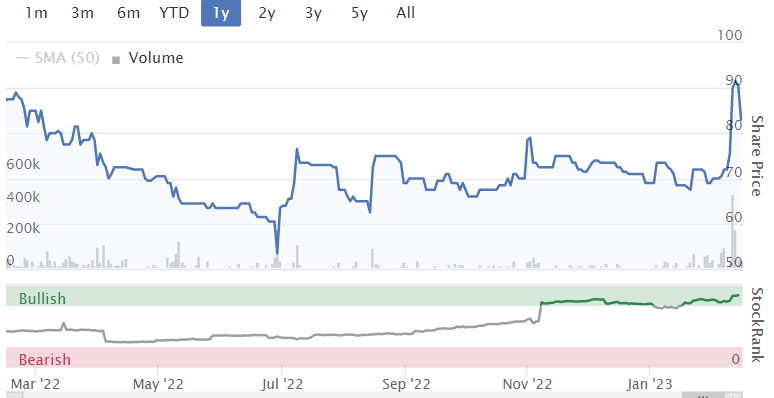
Given the lack of a track record, it doesn’t surprise me that the shares trade at only a small premium to the company’s cash balance.
I can’t take a negative view on the shares since the lack of quality should already be priced in at this level, i.e. any turnaround in performance could result in a valuation uplift. But neither can I take a positive view on a company that appears to lack any attractive investment characteristics, beyond its cash balance.
Brighton Pier (LON:PIER)
- Share price 65p (-5%)
- Market cap: £24m
Brighton Pier today gives us a most unusual trading update, which refers to the 78-week period ending 25th December 2022. In other words, it’s an 18-month trading update.
Changes to the accounting reference date nearly always bother me. Part of that stems from laziness - they make my job harder.
But they also make me wonder why the company didn’t have the right accounting date in the first place. For example, Brighton Pier argues that moving the accounting date from June to December will help to avoid splitting the peak summer season in two, and it will also result in the audit process being less of a distraction to staff during summer.
This explanation makes perfect sense and I can’t argue with it. But then why did the company put up with a June accounting date for so long?
In any case, here is the key point from today’s trading update:
Overall, the Group performed well, and continues to trade in line with market expectations having ended the 18 month period with a stronger balance sheet. In the first 12 months, the Group benefited from COVID-19 related government assistance and pent up demand as the UK emerged from lockdown, while the final 6 months witnessed a decline in consumer confidence and increased costs across the sector.
Compared to the equivalent 18-month pre-Covid period ending December 2019, like-for-like sales are up 9%.
However, compared to the equivalent 6-month pre-Covid period, like-for-like sales are down 2%. This helps to demonstrate that after the initial expression of pent-up demand, sales have softened in recent months.
We also need to keep inflation in mind, when comparing against performance three years ago.
Balance sheet - net debt has reduced from £13m to £7m over the past 18 months.
CEO comment
"Like many in our industry, we have had to absorb higher costs relating to wages, energy prices and other inputs. However, going into 2023, our businesses remain profitable, well managed and backed by a strong balance sheet and asset base.
We are confident in the ability of our management teams to operate well in our markets, but we remain mindful of the continuing pressures from the wider economic environment in which we trade."
Estimates
We have new estimates for FY December 2023 from Cenkos, suggesting revenues will rise 16% to £38.8m and adj. net income will fall from £1.7m to £1.4m.
Inflation is set to cause higher prices for customers, but PIER will have to take some of the hit themselves. There will also be higher interest rates paid on the reduced debt load, and higher corporation tax.
My view
I find myself agreeing with some of the bullish arguments here. PIER has impressively reduced its debt load, reducing its financial risk.
I am curious to see the unadjusted numbers when they are eventually published, but the adjusted numbers (and the debt reduction) suggest there has been decent profitability during the volatile 18-month period that just passed.
And then, looking forward, there are similar arguments as we’ve seen elsewhere. Will margins “normalise” when real wages start to rise again and the cost-of-living crisis is over? Perhaps. That’s a bet I’m willing to make with other stocks whose profitability is currently depressed.
Pre-Covid, annual net income here was often around the £2m mark,
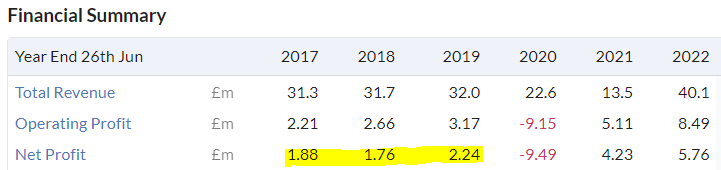
PIER’s enterprise value (market cap plus net debt) is currently c. £30m. That strikes me as a fair price, given the risks involved. Future capex requirements could be expensive and I would completely ignore the use of EBITDA by this company and its sell-side analysts.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Hargreaves Lansdown (LON:HL.) , not sure what is happening, the shares were up 8% this morning but are now down 9% on the day. I can't really see anything in the RNS.
The RNS looks positive to me. I don't understand why price fell.
I've only done a quick skim on Hargreaves Lansdown (LON:HL.), but it looks like the long term metrics of the company (AUM, customer numbers, etc) were all mediocre? I'd love to hear Abtan's view on this, as I know he has been tracking HL for a while!
On a 16x PE and 15-20x FCF it doesn't strike me as particularly good value unless the growth continues.
"Hargreaves reports a 31% jump in HY profit before tax as
an increase in the number of its active clients overshadowed a
drop in the assets managed by the company
** Co reports HY 2022 profit before tax of 197.6 million
pounds($238.92 million) compared to 151.2 million pounds a year
ago.
** Says revenue for the period also rose 20% to 350 million
pounds ($422.70 million)"
Well clients were up, assets though were down, not surprising, as many PIs moved money out of shares.
They are also set to gain from higher interest rates, which they get on clients cash balances.
I can see why the shares were up 8% initially, then they fell around 16% which seemed quite surprising, now have recovered somewhat to -5%.
This is an interesting one. There are solid bull and bear points to made. In the former camp you obviously have their market leading position, the relative stickiness of their customer base, their balance sheet strength and solid FCF generation. But in the latter you have:
1. The fact that their Net Customer growth is now pedestrian. They seem to be solidly in the 'cash cow' rather than 'growth' stage of the BCG matrix
2. The fact that their cost Inflation depending on your point of you and to steal a line from founder Peter Hargreaves is completely out of control. We "now expect FY23 Underlying Cost Growth at top end of the guidance range (c.11.5%)". Note further that even though their revenue will be up almost 40% from '19 to '23 their Operating Profit is essentially flat over the same period owing to ballooning costs. No wonder the margin has dropped double digits
3. A completely different competitive environment from when HL originally disrupted the market. You have the likes of AJ Bell, Interactive Investor, etc, offering much cheaper dealing and custody, for what is essentially a relatively similar product
4. The fact that their bacon has been almost completely saved in H1 by the rise in interest rates and the consequent massive boost to revenue from the higher interest on cash deposits. But on p.9 of the Investor Pres they imply that the most recent increases in base rate have been entirely passed through to depositors. So presumably this one-off step change is now done. And indeed on p.12 they seem to imply a lower revenue margin from Cash deposits than originally forecast
All in all I must admit that I find myself in the sceptic camp. I buy the relative stickiness of their AUM and customer base. But I struggle to see what the massive increase in cost over recent years has achieved. Charitably you could argue that it has been necessary to defend their market position. But if that is the case then it's not as good a business as it was before owing to the competitive environment. Less charitably and to build on Peter Hargreaves' recent press comments the spending has been wasted. I certainly think that their ambition to become a hybrid wealth management provider will be a very difficult trick to pull off. It's notoriously difficult to provide bespoke or even semi-bespoke advice at a reasonable price and in an automated way. And then if you look at their near term revenue lines I struggle to see where any growth is expected to come from. Share dealing volumes look like they peaked during the pandemic and are unlikely to return any time soon. Custody / fund fees are largely flat. Interest on cash is the one-saving grace but this is self-limited from here as touched on above, presumably owing to competitive pressure and the risk of regulatory interference. The risks to the downside are obvious then: continued competition forcing a further step down in custody and trading fees. More investment in marketing required just to stand still. And further squeezed margins as costs continue to grow double digit. I see the only potential catalyst as A. a bid from a (foreign) rival looking at establishing a leading, turn key UK retail brokerage. Possible of course but obviously a totally exogenous event and impossible to predict B. the new CEO taking Peter Hargreaves' advice and taking an axe to costs in the pursuit of a leaner strategy. And yet I believe he is committed (at least for now) to following the original strategy. All in all then is it any wonder that Mr Market is not happy. Perhaps it's a prime opportunity for an Activist Investor to shake thinks up?
Hello Phil, thanks for your very detailed response.
I don't hold any Hargreaves Lansdown (LON:HL.) shares but I do use their platform. I agree there is a lot of competition now and I use IG group (LON:IGG) most of the time, HL are too expensive especially on US shares. I will be moving most of my account to other platforms this year. HL I will only use for funds and other investments that are not available on my other platforms.
Re the cash deposits, this is cash in accounts such as ISAs, SIPPs and Share accounts, they have now increased the rates by about 1%, top rate I think is 1.70%, but you only get that on the top tier, not on all your cash. I would have thought they earn higher rates than that, so don't really understand about it has all been passed onto the depositors already, the higher rate was only paid on 9th February, 2023. I can get instant access rates of around 3%. I think what they mean the recent rises have now been passed on, as they have increased the rates, and it looks like rates won't be rising much more.
The increase in rates is welcome but won't stop me moving, the cash is for buying shares but did build up last year, but I will be looking to invest more this year, probably mostly in the US markets.
Hargreaves Lansdown (LON:HL.) service is a lot better than some of the cheaper competition though.
Hargreaves Lansdown (LON:HL.)
Hi Boon
I have indeed had quite a thorough look at today's results, though I missed the earnings call and am waiting for the recording before coming to a final conclusion.
Overall though, I was quite impressed:
(Note that Assets Under Management have gone up every year since 2004...until FY22 - a remarkable record.)
There's lots to like.
Having said all that I sadly do not hold at the moment because:
On point 2. above, I actually think that the company is doing the right thing and as a customer I look forward to being able to participate in IPOs, fund raises, etc... over the next few years...but I fear that the share price might stagnate for a while as a result.
It's such a remarkable business that I'd probably be quite content to buy and forget; I can't see how it won't do well in the long run.
A
RE: Hargreaves Lansdown (LON:HL.)
It's such a remarkable business that I'd probably be quite content to buy and forget; I can't see how it won't do well in the long run.
Yeah. What he said.
Clearly there are challenges ahead, and the excess investment in the platform now required is a direct failure of past and current management. Still, it's being addressed.
Going forward it will be harder to grow, no doubt, but it's going to be hard to shift all of those lovely fee paying customers who are very happy with the service they're getting. Meanwhile we can see that the shift between low interest rate and high interest rate environments can be smoothed out due to interest payments, something I'd always doubted.
Others here have put forward decent bear points so I won't reiterate them, there's no magic bullet to making money, but it's hard to see how they can't continue to be successful and profitable going forward. What it isn't going to do is shoot the lights out, the days of rapid growth are behind it.
timarr
Corero Network Security (LON:CNS) (Ihold) today announces that Lionel Chmilewsky, the Company's Chief Executive Officer, has resigned to pursue other opportunities! Any thoughts?
Large Cap Value,
Hello all,
I thought I'd post an investment idea here in case anyone is interested.
US coal producer Peabody £BTU released Q4 results yesterday showing it had finally paid off debt and removed the obstacle to shareholder returns, which they indicated they intend to do through both share buybacks and dividends. At 3.5Bn Mkt cap they have about half that in cash and business is booming since sales that had been hedged at much lower prices are now going through close to much higher spot prices. Theres an account on twitter, 8750Capital, which has some long threads going though the financials in detail that might be of interest.
Best wishes,
J
Hi John. Can i ask if you own any shares in Peabody (BTU) ?
I was short on Peabody Energy (NYQ:BTU) and got stopped out yesterday and was wondering why so thanks for explanation!
Hello Paul
Wondered what your thoughts are on Babcock Int (BAB) today being awarded a MOD contract worth an initial £ 400 million starting in March 23. to operate the MOD Skynet 6 program. As its market cap is in excess of £1.5 Billion, I know it's outside your general remit. I am surprised that the share price has only gone up less than 1%.
The question with Babcock International (LON:BAB) is whether you can get comfortable with the debt level and the pension deficit, plus the liabilities they may incur when they mis-price a long-term contract with pretty tight margins.
There are ongoing disposals to further reduce the debt & you would hope the pricing environment for assets they need to dispose of would be firmer than in recent years?
S&P upgraded them from BBB- to BBB, stable back in December. They survived the LDI debacle, but the pensons scheme(s) reduced their inflation hedges to avoid selling risk assets.
If you can get a handle on their liabilities (some are lease related), then it is cheap relative to BAE Systems (LON:BA.) and Qinetiq (LON:QQ.)
However, it really would help if some of their brain-dead employees didn't glue back on the heads of plastic screws they over-tightened on a nuclear sub recently. Talk about shooting yourself in the foot.
Any thoughts on Jubilee Metals (LON:JLP) trading update today
Lots of fixes being put in place to prevent future issues but lower PGM basket price has taken its toll alongside increased countrywide power outages affecting their copper production
Kicking the can down the road yet again. Another ‘jam tomorrow’ update. This is a perennial disappointment. Will they ever make a decent profit? I am beginning to think that I might not live long enough to see one.
Yes the TU from Jubilee Metals (LON:JLP) is not looking good. The PGM & Copper production is down in H1 FY23 vs H2 FY22, only Chrome is up 5%. Likewise the net cost of production of copper has increased (notwithstanding the additional costs noted of $300/t at Sable to secure the integrity of the power supply). Comparing H1 FY23 vs H2 FY22 again the commodity prices are down although they do state in the TU that chrome metal prices were recovering sharply post the reporting period.
So we have production down, costs up and prices down - not a comforting scenario to say the least. The FY23 guidance for copper production has been "prudently" updated in S.Africa. To finish on a positive note the copper price has increased 10% since the start of the year.
Do you think there is a read across to Sylvania Platinum (LON:SLP) here as their share price fallen nearly 15% in the last month with the bulk of the fall in the last week. Does tend to be volatile but Stock Rank remains good though 2Q results for revenues & EBITDA at Jan 30th were both down on comparable quarter. Are they running out of steam?
Sylvania Platinum (LON:SLP) (I hold). Share price tends to track very closely the platinum Spot price.
Leon positive as usual, despite the setbacks. https://www.directorstalkinterviews.com/jubilee-metals-group-plc-results-on-target,-despite-south-african-power-situation-video/4121105773 Jubilee Metals (LON:JLP)
I hold and well down agree jam tomorrow update totally agree but look out a couple of years and things may be quite different, shortages are well forecast and according to some we are sleep walking into an era of significant metals price rises or at least I hope so.
Gattaca (LON:GATC) Has a stock rank of 87.
It's stock rank was above 80 between April 2019 and November 2021. For 9 months in that period it had a stock rank of 100.
It has been back above 80 since November 2022.
What has been driving these great rankings? I've never bought this share but I've followed it as it's constantly been showing up in loads of positive screens for years.
Gattaca (LON:GATC) Has a stock rank of 87
It’s mostly to do with the balance sheet representing a high proportion of the market cap. It’s certainly not representative of where it ranks in the industry.
I concur that the ranks can sometimes throw up strange results. LON:BOR - no sales since 2012, burnt through $40m cash, ~$1.5m left - score of 60 and the best bankruptcy score I've seen yet. Think the scoring formula could do with a couple of tweaks.
as per the tip in Investor Chronicle last week it was just that. i dont rate this company and the sector is struggling.i know as i am an IT contractor myself and there isnt much work out there for this time of year.glad i wasnt tempted to buy
What company? This comment doesn't seem nested to the original comment - bug?
Gattaca (LON:GATC), it was an IC tip and Robbie Burns mentioned it, lets hope he got out before today.
Gattaca (LON:GATC), it was an IC tip and Robbie Burns mentioned it, lets hope he got out before today.
Well I did warn him - although ultimately this dog will probably reward traders in an indiscriminate bull market.
Robbie isn't in it and hasn't been for some time, I actually did a better job of trading it than he did at the time lol
Robbie isn't in it and hasn't been for some time, I actually did a better job of trading it than he did at the time lol
Well, he was in it when I warned him last Friday!
Gattaca (LON:GATC) - Strong cashflow coupled with solid top line growth (new note here from Equity Development following Trading Update: https://www.equitydevelopment....)
The UK recruitment industry is being buffeted by a number of macro crosswinds, but for the right skills, there is still robust demand. Particularly across Gattaca’s core verticals (65% of NFI) of Infrastructure (eg Lower Thames Barrier, HS2, etc), Defence, Energy (off shore wind & nuclear) and Mobility (aero, auto & marine). Indeed, the company reiterated today that it was well on track to achieve its medium & long term goals after posting solid H1’23 LFL NFI growth of 5.1% to £22.7m (£21.6m LY). And encouragingly cashflow was strong too with statutory net funds climbing £8.7m to £21.0m (65p/share) as at the end of Jan’23 vs £12.3m in Jul’22 - reflecting lower debtor days and tight working capital management.
Consequently, we think the turn-around plan is making real headway, despite being slightly slower out the blocks than we’d previously modelled due to the tougher macro environment. Given the ‘blustery’ economic conditions, we’ve prudently trimmed our FY’23 and FY’24 PBT forecasts to £1.8m (£256k LY) and £4.25m respectively on NFI up 5.3% & 8.9%, alongside adjusting the valuation to 130p/share vs 160p before.
Gattaca (LON:GATC) looks like a profit warning disguised as a positive statement. Improvement in cash is attributed to better capital management but it’s just as likely to be because of waning contractor numbers. How can a business with 45% staff churn have “deep knowledge and understanding of our sectors and niche skills”?
Anyone who loaded up on Thompson’s Bargain Shares recommendation is learning that hope isn’t a strategy.
Ultimately a rising tide might float the share. A lot of sh!t floats, after all. But the other listed recruiters, all of them superior in quality except maybe Impellam (LON:IPEL), whose valuation makes no sense to me, and hapless Norman Broadbent (LON:NBB) can be relied upon to do so.
Morning all, not sure if this has an importance.. Eneraqua Technologies (LON:ETP)
Notification of major holdings for Hayley Louise Peters, who has a dormant company under the name "control flow technologies"
https://find-and-update.compan...maybe looking to spin out that part of the business?
I don't understand the notification about the holding in Eneraqua Technologies (LON:ETP) by Hayley Loiuise Peters. It shows no previous holding by her but the Stockopedia Institutional shareholders tab shows that she had a higher holding last April. As it's a slow news day, I looked further.
On Oct 11 last year, ETP issued an RCS announcing (in part) what seem like magical results from some kit they sell:
Eneraqua Technologies plc, a specialist provider of energy and water
efficiency solutions, is pleased to announce that, following the success of
net water neutrality pilot programmes with two English local authorities, the
Board has confirmed the decision to invest in a direct B2C offering.
The water neutrality pilots were to demonstrate how Control Flow HL2024
installed in existing homes can save water to offset the demand of new homes
in the area. This would allow Control Flow HL2024 to be used in unlocking
some of the estimated 120,000 new build homes across the UK currently stuck in
planning due to water and nitrate concerns.
By eliminating water flow fluctuations, Control Flow HL2024 reduces water
wastage and improves the performance of hot water systems. The pilots
involved 100 homes and found that the Control Flow HL2024 system reduced the
household daily energy and water bills equivalent to an average saving of
c.£360 a year. The analysis, which was carried out jointly by Eneraqua and
local authority staff, was based on actual gas and water meter data, taking
before and after meter readings to determine the change in daily consumption,
which is then multiplied by the current energy and water prices.
Customer satisfaction surveys were carried out post installation to monitor
householder experience, which showed over 99% user satisfaction with the
product and supply of water.
As a result of the success of the pilots, from both a saving and customer
satisfaction perspective, the Company will shortly commence the launch of the
product direct to consumers, with pre-launch costs of approximately £0.5m in
H2 FYJan23 to cover marketing and operational delivery teams.
The Board strongly believes the B2C offering has the potential to create a new
and exciting revenue stream for the business in FY24.
I don't hold, and I'd welcome others' views on ETP.
Hayley Louise Peters was a director of Cenergist Group, a precursor to Eneraqua prior to it listing on AIM. She had a large holding on listing which was sold down. I'm dont know why she sold down or why she now appears to have increased her holding.
ETP's solutions are based on the owned IP of 'flow' technology for water and heat solutions, deployed primarily in large buildings (e.g. blocks of flats, hotels). The acquisition of the IP was a key part of transactions around the float. See Admissions document page 120 for example.
https://wp-eneraqua-technologi...
I hold (LON:ETP). It's a thinly traded share with a wide spread and is therefore quite volatile.
I believe long term contracts with local authorities and others support its valuation. It addresses a secular need to improve both water management and to support the green energy transition for large buildings e.g. hotels, tower blocks, flats that need to replace legacy heating systems.
With a 31 January year end, FY23 and FY24 are underpinned by a contracted back log (85% of FY24 revenue by Oct 22). ETP has its own manufacturing facilities to produce its flow devices and last year acquired a drilling business to ensure access to equipment needed to deliver the back log.
Gross and net margins (40% and 15% plus respectively) look good to me but the strong operating cash generation is being used up for small acquisitions and Capex.
India and the UK retail opportunity you describe above provide potential upside but are yet to be shown to be scalable businesses of substance.
My investment thesis is based on growing the core water/heating system business. So I'd like to see the order book continue to grow alongside continued profitable delivery.
I've found management to be very transparent and capable, answering all the questions asked during presentations. Interested folks can learn a lot from their website and PIWorld presentations.
https://www.piworld.co.uk/?s=e...
Good info on Eneraqua Technologies (LON:ETP)
I also hold based on its patented and proven technology and profitable market position within an important subsector of the energy transition. A segment growing very rapidly under regulatory pressure and with significant government support. I agree that management are reassuringly dull yet professional in their presentations .
I would caution that with cash/debt around breakeven level any of the promised M&A activity could trigger a share dilution, although the (hopefully) earnings enhancing nature of a quality acquisition might mitigate that risk. I also perceive a risk in trying to run too fast across too many jurisdictions.
On the encouraging side, there are much bigger and acquisitive players in the sector, like Engie or Veolia, who might be eyeing up the company’s IP and its market position. Additionally, despite strong growth! the company is currently valued in line with (or even below) mature contracting/engineering businesses at an almost single digit multiple, but if its IP becomes recognised as the source of a moat, the multiple could rise towards elevated levels enjoyed by firms such as Daikin or Trane Technologies.
My morning smallcap tweet: Business qualities and frivolities
Mercantile Ports & Logistics (LON:MPL) Gattaca (LON:GATC) Sondrel (Holdings) (LON:SND) LPA (LON:LPA), Brighton Pier (LON:PIER)
◄Mercantile Ports & Logistics (MPL)► dredges up another bucket of hope. Handles its first container freight albeit with small initial volumes. Also MoU with another port on "collaboration on the movement of shipping containers and vehicles by coastal waterways". Latter will have no material impact this FY. [SP=6 Cap=2m]
◄Gattaca (GATC)► guides H1-Jan net fee income up 5%. In line? Outlook - "softening in some external sectors, and perm is likely to be impacted by a level of restraint around hiring, shifting candidate sentiment and, as such, slightly longer hiring cycles." [SP=88.2 Cap=28m]
◄Sondrel (SND)► guides FY-Dec rev up 116%. In line? Design wins in line with expectations. Warns of project delays this FY. [SP=60 Cap=53m]
◄LPA Group (LPA)► wins £5.3m order for the supply of electro-mechanical products to the UK rail industry. Sales expected to commence towards the end of current FY. Guides FY23 in line with mgmt expectations. [SP=75.21 Cap=10m]
In line: PIER