Small Cap Value Report (Wed 15 Nov 2023) - RNO, KNOS, SCE, FSTA

Good morning, it's Paul & Graham here again today!
We'll leave it there for today.
As I expected, Richard Staveley of Rockwood Strategic (LON:RKW) (part of the Harwood Capital stable) was absolutely brilliant on the Mello Funds & Trusts show yesterday afternoon. I took detailed notes, it really was a masterclass in how to create & manage a small caps portfolio. It's a tiny fund, only £46m, but it's established a fantastic performance track record, no.1 in small caps funds. You can see why when Staveley explains Rockwood's approach. He'll be appearing in person at Mello Chiswick too, along with loads of other superb speakers, so I'm looking forward to that.
Multibagger webinar is tonight at 18:00 - all subscribers should have been sent emails about this event, but you can register here if not. The boffins at Stocko HQ have come up with a data-driven way to spot multibaggers - that is certainly more than enough to grab my attention! I've set an alarm on my phone so I don't miss it.
Big drop in UK consumer inflation - this is as expected, but the ONS report today confirms that there has been a huge drop in CPI inflation from 6.7% in Sept, to 4.6% in Oct 2023, mainly due to a big jump in Oct 2022 inflation dropping out of the numbers as it annualises. What it describes as "core" inflation (which excludes volatile food/drink/energy prices) dropped from 5.9% in Sept, to 5.6% in Oct 2023.
Still some way to go before things have normalised, but it's clearly moving in the right direction. How long before investors start anticipating lower interest rates, and all that cash on the sidelines starts surging back into small caps?! Your guess is as good as mine!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
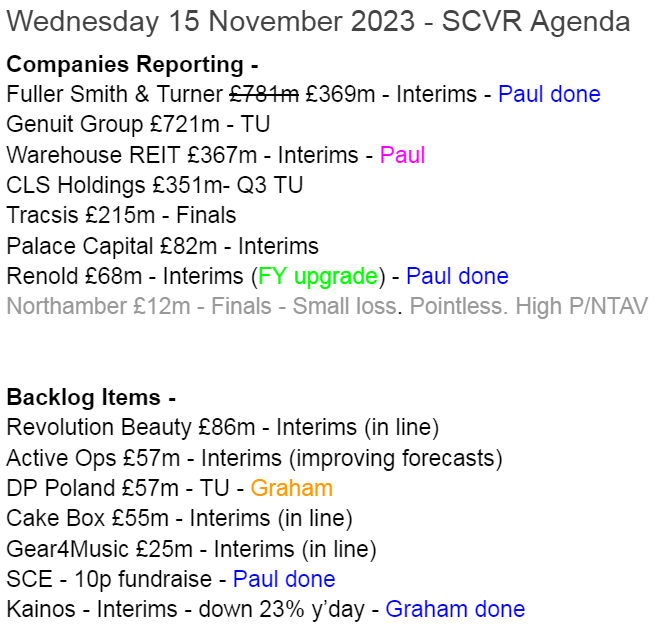
Here's today's list, as usual we'll cherry-pick the most interesting companies, and over/under expectations updates primarily. If it's just in line, then it probably won't be covered -
Summaries
Renold (LON:RNO) (Paul holds) - 30p (pre-market) £68m - Interim Results - Paul - GREEN
Excellent interim results. Cavendish raises FY 3/2024 forecast by 9%, but even then it seems modest, so I'd anticipate another beat. This share looks far too cheap, even allowing for the cash-hungry pension scheme. I see continued upside here, providing nothing goes wrong. Although it's using cashflow to fuel the pension scheme, and make acquisitions, so no divis for now.
Kainos (LON:KNOS) - down 15% this week to £10.01 (£1.25bn) - Interim Results - Graham - AMBER
This IT provider published decent results, but the market took fright at some weaknesses in the commentary and pushed the stock down by c. 25% at one point. Kainos has cash of over £100m and is probably a fine company in its field, but the valuation seems hard to justify.
Surface Transforms (LON:SCE) - 10.75p (£26m pre dilution) - Fundraise - Paul - RED
As expected, SCE has come back for more cash, but it looks nowhere near enough (again), so I doubt this fundraise will be the last. A vitally important point is that most of this 10p equity raise is conditional on securing a £13m capex loan from an unknown lender. Therefore, I think this share remains very high risk unless & until the loan has been agreed (on what terms though?). Hence I'm not giving it the green light yet, as so much risk remains. Fingers crossed the funding is secured, as this looks such a promising company with a huge order book. What a pity to see it struggling like this.
Fuller Smith & Turner (LON:FSTA) - up 6% to 608p (market cap £369m - see below) - Interim Results - Paul - GREEN
This pubs group is much cheaper than it looks on the StockReport. I've been guided by a previous analysis of the complicated 3-class shares structure, by our Graham, and confirmed it with a Liberum note. Strong asset backing (above the market cap) and decent profit growth, with sector-leading LFL revenue growth, make this share appeal to the value investor in me. Although I'm more of a 'Spoons man in terms of value for money, as a customer!
Paul’s Section:
Renold (LON:RNO) (Paul holds)
30p (pre-market) £68m - Interim Results - Paul - GREEN
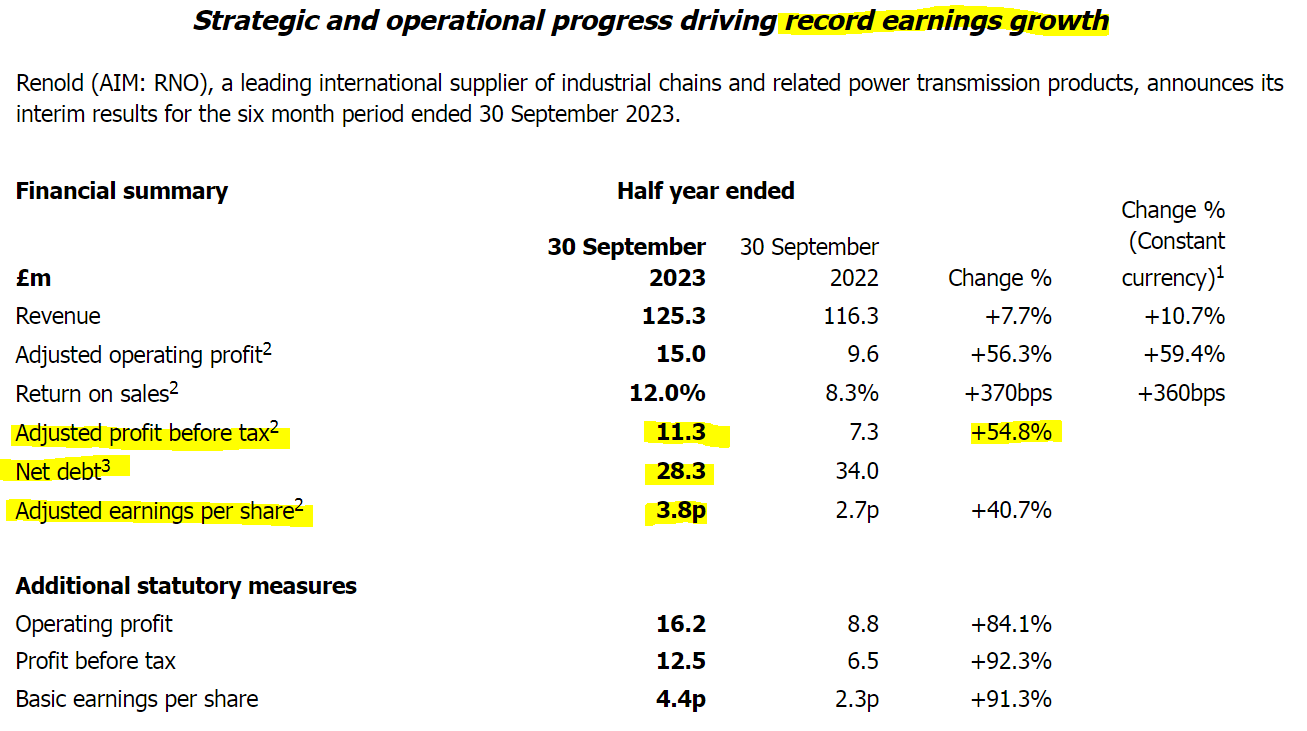
Renold (AIM: RNO), a leading international supplier of industrial chains and related power transmission products, announces its interim results for the six month period ended 30 September 2023.
A long-standing favourite of mine, this has been an under the radar, but convincing turnaround in recent years. Problems of the past are now behind it, and Renold is now on the front foot, with debt under control, bolt-on acquisitions being done, and it sailed through the pandemic and energy crisis with aplomb (no dilution necessary, share count has remained at 225m since 2018).
The main negative is a large pension fund, which is cash hungry, which is cash that could otherwise have been used to pay divis, hence why the PER will be a fair bit lower than companies without pension deficits.
Considering tough macro, I find these interim highlights very impressive! (assisted by acquisitions)
Note that profit adjustments are fairly small (about 10% of profit), and this year go in the opposite direction - ie lowering adj profit vs statutory profit (thanks to a one-off property disposal gain).
Very good figures, and note that net debt is less than 3 half years’ profit, or 0.7x rolling adj EBITDA, generally considered low -
Pension deficit - has reduced under IAS 19 from £62.2m 6 months ago, to £52.7m at 30 Sept 2023. Still substantial of course. The cash contributions from Renold were a whopping £6.0m in H1, but that includes an accelerated payment of £2.6m that was originally planned for H2. Pensions are important to valuing the share, so make sure to read all the information on that in today’s results. Note the additional £1m cash contributions (if adj operating profit over £16m) has kicked in this year. That’s fine, it’s affordable, and a well known factor. This is why the PER is so low.
Outlook - order book has fallen, but I think that’s OK as the explanation is that supply chains are normalising, so customers don’t feel the need to order further in advance, as they were doing last year.
CEO comments below start off sounding cautious, but then surprise and delight us with an ahead of expectations conclusion (for FY 3/2024) -
"I'm pleased to report continued progress which builds on the momentum the Group has enjoyed in recent periods, delivering a record half year result. Sales, margins, profits and cash generation have all progressed well. Global markets continue to be uncertain and we remain vigilant for changes in patterns of demand beyond the current order book shortening. We are delighted with the purchase of Davidson in Australia, which further builds our inorganic growth strategy and we remain well positioned to continue developing through acquisition. There remains uncertainty over the implication of global economic pressures in the medium term, however the Board is increasingly confident in delivering a result for the current year ahead of previous market expectations."
Cashflow statement - excellent cash generation in H1 of £17.1m (that’s after capex, and working capital movements).
The pension scheme payments used £6.0m of that, but the more normal £3m half-yearly payment would have been about 18% of cash generation. So this pension issue is being nicely diluted into a bigger, more cash generative group. Becoming less of an issue, in other words.
It’s also self-funding the acquisition payments of £4.9m in H1, without borrowing more.
The big gap is obviously there are no dividend payments, but that is the company’s stated strategy - it is making acquisitions, as a better use of its cash generation, at this stage. The capacity to pay future dividends is clearly there, however.
Balance sheet - dominated by £42m of intangible assets, and the £52.7m pension deficit.
NAV is £51.8m (up from £38.2m a year earlier), and NTAV is c.£10m. So not the greatest balance sheet, but the pension deficit is a manageable, long-term liability, which is being managed fine.
Broker update - thanks to Cavendish for crunching the numbers.
It ups FY 3/2024 forecast by 9.3% to 6.0p.
However, the company has just reported 3.8p achieved in H1, so the forecast looks light, and hence I’d expect another upgrade probably after Christmas.
We like it that way around - under-promise, and over-deliver!
It’s difficult to see if there is any H1/H2 seasonality from the historic numbers, due to the multi-year covid disruption. It looks as there’s some variability in seasonal profitability, but if anything, H2 seems the stronger half most years. Another reason to imagine the 6.0p current year forecast might be beatable.
Paul’s opinion - remains highly positive. This is an excellent quality business, that investors still seem to be prejudiced against due to its lacklustre historic track record. But we're not buying the past, we're buying the future!
These numbers clearly show a very much improved business, that has decent margins, is strongly cash generative, making good bolt-on acquisitions in the same sector (so they know exactly what they’re buying, hence not likely to make any expensive mistakes).
The shares are strikingly cheap, at a PER of only 5x the new (prudent) forecast.
I think the discount for the pension deficit is now far too large, which gives considerable upside to equity.
In my opinion, this share could be double the current level in the next bull market, so patient holders should be increasingly confident that you’re onto a winner here. Providing nothing goes wrong of course, as with everything.
It’s another thumbs up from me, I’m very pleased with how Renold is working out. GREEN.
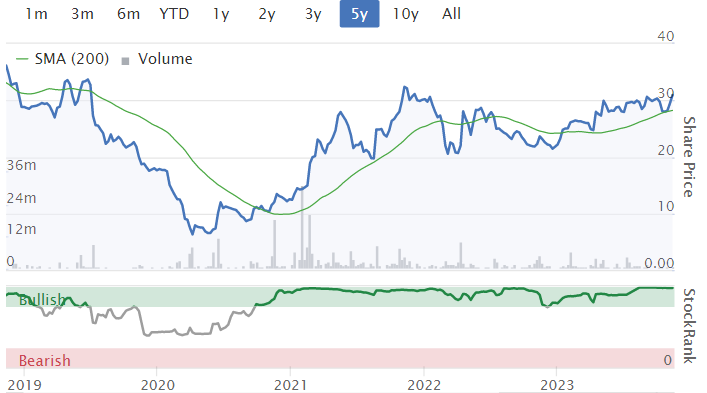
Stockopedia awards an unbiased, top-class StockRank of 97.
Considering the last 2 years have been a savage bear market for small caps, RNO has been a safe port -
Surface Transforms (LON:SCE)
10.75p (£26m pre dilution) - Fundraise - Paul - RED
As expected, this accident-prone maker of high end ceramic brake discs has had to come back to the market for more equity, yet again. No surprises there, as it’s been obvious for some time that another fundraise would be required.
The longer it takes to refinance, the more it leads to small shareholders selling in the market (very sensible, and a key advantage we have), hence big destruction of existing shareholder value, with the eventual fundraise being done on distressed terms and heavy dilution. We see this huge error from management over & over again in UK small caps, and SCE is only one of the latest examples.
That’s why I think it’s usually best to just not invest in any cash burning shares, but instead watch and wait for them to reach a tipping point where they’re close to breakeven, and have ample funding. The valuation is often on the floor by then as well, so risk:reward favours the cautious, later investors. The early optimists take all the risk, and often end up with very little at the end of it. Plus they’re almost forced to keep averaging down, in the hope of the eventual gains. I’m speaking from experience here! Lots and lots of it, doing it the wrong way around, backing cash burners way too early, and losing my shirt. They nearly all fail, requiring much longer, and costing multiples of what the initial business plan suggested. Early valuations built on hope/hype are almost always way too high.
Look at SCE as an example - it floated originally in 2002, so it’s taken over 20 years to begin to commercialise its ceramic brake discs.
On the upside though, its huge order book demonstrates there’s very strong demand, so for that reason, despite all the problems, I do think this company looks potentially interesting, hence why we’re covering it here. If it was just another no-hoper, we wouldn’t be wasting ours or your time on it.
This Proposed Placing announcement came out after hours on Monday this week (13 Nov 2023). Key points -
New equity being raised at 10.0p per share (15% discount on an already bombed out share price).
£2.0m firm placing
£6.0m conditional placing
Key point - “conditional” in this case is more important. Usually in placings that just means subject to the rubber stamping at a shareholder vote (18 Dec 2023). However, in this case it’s absolutely key that SCE secures a loan facility of £13m for its required capex. If that loan facility is not agreed, then the conditional placing (and open offer) could fail, and result in a potentially disastrous outcome of a larger, even more deeply discounted fundraising being required, or potential insolvency even, if it wasn’t possible to raise more equity. So this share remains high risk I’d say.
£2.0m Open Offer to existing holders (with scope to increase it to £3.0m if there is excess demand)
Zeus & Cavendish are the joint brokers.
Directors are only stumping up £135k between 5 of them.
Proposed Loan Facility
To finance its capital expenditure plans, the Company is in advanced discussions on a £13 million capital expenditure loan facility that would be released if new capital expenditure is incurred in 2024 and 2025. The proposed Loan Facility has a five-year term and can only be used to finance capital expenditure and not for working capital purposes. The outcome of these discussions is not certain but is expected to conclude before the end of 2023. Success in securing the Loan Facility (or alternate debt funding) will enable the Company to finish installing the current capacity build to £75 million9 p.a. (Part 2 of Phase 2), as well as commencing the next stage of the capacity build towards £150 million9 p.a. revenue capacity (Phase 3); however there remains the need to finance working capital required to support the significant production increases during 2023 and 2024.
The following day, 14 Nov, SCE announced this - Result of the Placing & Subscription
The placings have succeeded, conditionally raising £8.3m through the future issue of 82.9m shares (existing equity is 241.7m, so this is c.34% increase in the share count.
In addition, there could be 20-30m new shares issued in the open offer, taking the total to between 102.9m to 112.9m new shares (dilution of c.43% to 47% of the existing shares). It could be less than that of course, if the Open Offer bombs. Although Open Offer applications are also conditional on the loan facility being agreed, so applicants are not taking any additional risk, as if the loan agreement fails, then they wouldn’t have to pay up for the open offer shares. That’s my understanding anyway, correct me if I’m wrong. Hence I think it does make sense for existing holders to apply for open offer shares, as they're not taking any additional risk.
Paul’s opinion - this situation actually makes me feel quite sad. Such a promising UK company, with massive demand for its products, that is struggling to raise a relatively small amount of money to push through to full commercialisation.
Mind you, I can also see why investors are reluctant to fund something that has disappointed so many times.
This is not a normal fundraise, it hinges on securing a £13m loan for capex, which in itself looks a stretch - few lenders will normally extend such a loan to a still loss-making venture. So I wonder what the cost would be, even if it is possible to secure it?
If the loan negotiations fall through, then we’re into potentially very choppy water. For this reason, I see it as far too risky for me to want to get involved at this stage.
It could all turn out fine, which would be great. I’m only flagging risk, not predicting what will happen, as I have no idea what negotiations are going on behind the scenes, so I couldn't even guess at the likely outcome, and wouldn't want to guess, as I don't have enough information.
This share highlights yet again that the UK stock market is simply not the right place for speculative startups requiring repeated rounds of funding. SCE should have never been floated in the first place, this type of business should be funded by venture capitalists or private equity, not retail investors on AIM.
Maybe someone with deep pockets might come along and buy SCE in its entirety? That would probably be the best thing for the business, but leave AIM investors nursing losses.
I can say with considerable confidence, that this latest placing won’t be the last!
SCE clearly, very obviously actually, needs a lot more investment. Investors need to hope that it can turn the corner with the various technical problems, so that the next fundraise (almost certainly necessary in 2024 I think) could be at a higher price, and hence less dilution.
Overall then, for me the risk is too high, so I’ll stick at RED until the £13m loan has been agreed (on sensible terms), triggering the equity fundraise going ahead. Subject to all that happening, then I’d consider having a small punt on this share myself, but not until that immediate funding risk has been removed. There could possibly be a decent short-term bounce if the funding deal all goes ahead, and focus returns to the upside potential from the large order book... until the next operational & funding problems emerge.
Right back to where it started, but with about 3 times as many shares in issue (compared with 5 years ago), once this latest placing goes through -
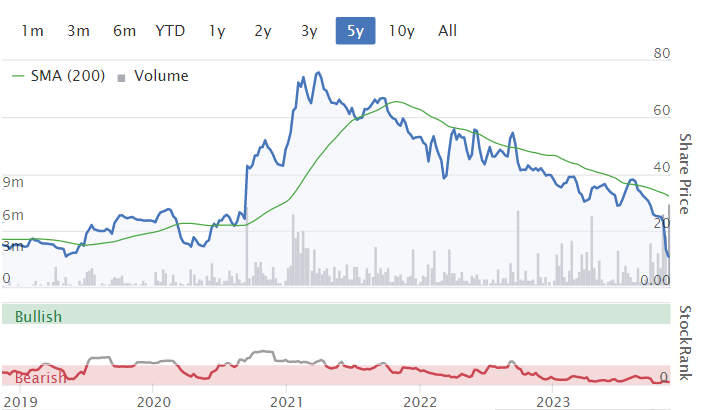
Stockopedia hates this type of thing, so gives SCE a scornful StockRank of just 3.
EDIT: I didn't intend spending so much time on SCE, but it's super-interesting! Could go either way I think.
Fuller Smith & Turner (LON:FSTA)
Up 6% to 608p (market cap £369m - see below) - Interim Results - Paul - GREEN
This is a “premium pubs and hotels business”, with 376 sites, mostly in London and the South of England.
The next key point is that there are 3 classes of shares, with different voting rights (to ensure founder family control) and dividend rights. Graham summarised it really well here in the SCVR dated 20 July 2023 - essential reading, as the market cap shown by the StockReport at £781m is calculated using 136m total shares in issue. But the 85m B shares within that only have rights over one-tenth of the dividends. Hence Graham’s view is that the share count should be adjusted to a notional 61m (valuing B shares at one tenth of A and C shares). That sounds convincing to me.
Therefore we think the market cap should be adjusted from £827m (using 136m total share count) to £371m (using the 61m notional share count). That’s clearly a massive difference, so this issue needs very careful checking before anyone buys the shares.
Ah silly me, I’ve just realised I can check it from a broker note! Many thanks to Liberum, which published an excellent sector note (via Research Tree) on 27 Oct 2023, which shows FSTA’s market cap as £345m at 568p per share back then, which implies 60.7m shares in issue, the same as Graham calculated above, allowing for rounding). Therefore we’re definitely correct on this. I’ve flagged the incorrect StockReport market cap (or rather, technically correct, but not actually correct!) to the HQ team at Stocko, with an explanation, so hopefully they can get the data adjusted. They’ve acknowledged my message, and the data team are now investigating.
Key points from today’s Interims from FSTA -
H1 revenue up 11.8% to £188.8m
Impressive LFL sales growth +12.7% in H1
Adj PBT up 48% to £14.5m
Adj EPS 17.2p (but calculated only on A & C shares, per footnote 3 - confusing!)
H1 divi up 42% to 6.63p
Doing more buybacks of A shares.
Net bank debt flat at £129m.
Current trading has slowed down a little, masked by quoting +11.7% for the 32 weeks to 11 Nov 2023 (down from +12.7% in the first 26 weeks). My estimate suggests the last 6 weeks is +7.4% - sneaky reporting, I’m not impressed.
Balance sheet is wonderful, with mostly freehold property. NAV is £443m, less £29m intangible assets gives NTAV of £414m, or 12% above the market cap. When were freeholds last revalued I wonder? There could be upside there (or maybe even some downside, as I’m not convinced pub valuations generally are realistic at the moment, given the poor returns often made on capital values. Alternative use value can underpin some sites though, especially in London where FSTA has a lot of sites).
There’s a pension scheme, so that would need scrutiny.
Potential upside is mentioned from hopefully cessation of rail strikes, and a return of inbound tourism (still below pre-covid, it says).
Paul’s opinion - FSTA looks really interesting, once I got to the correct market cap!
Graham explained very well why he was GREEN on 20 July 2023, and the share price is almost the same now, despite today’s uplift on good results.
With the lovely asset-backing, and a confusing shareholder structure that might put off lots of investors, I agree with Graham that this share might be undervalued.
The hospitality sector is back in focus, after the bid for Restaurant (LON:RTN) and sector dynamics are now looking positive to me, with the squeeze on consumers easing somewhat (wage growth now above inflation), and probably an appetite for people to let their hair down a bit.
So I think this could be a good time to take a fresh look at the whole sector.
The family shareholdings might block a takeover bid for FSTA though. OR, ensure that any bid had to be a knockout price to succeed?
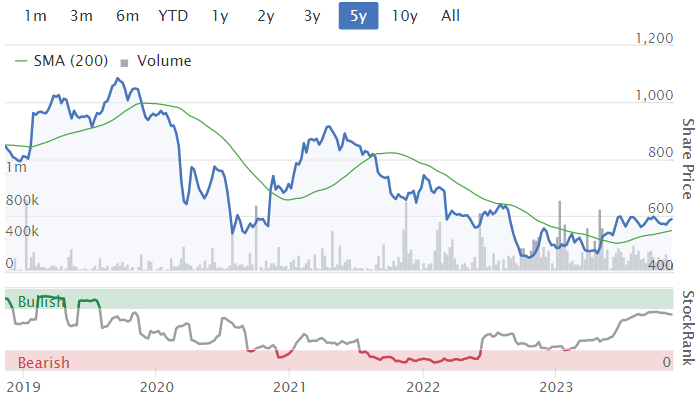
Even I can see there's a breakout on this chart, for traders maybe?!
Graham’s Section:
Kainos (LON:KNOS)
Share price: £10.01 (down 15% this week)
Market cap: £1.25 billion
Kainos Group plc (KNOS), a UK-headquartered IT provider with expertise across three divisions - Digital Services, Workday Services, and Workday Products, is pleased to announce its results for the six months ended 30 September 2023 (H1 24).
I’ve been promising to cover these results since Monday - so let’s take a look at them now!
The shares fell by over 20% on Monday but have since recovered some of the fall.
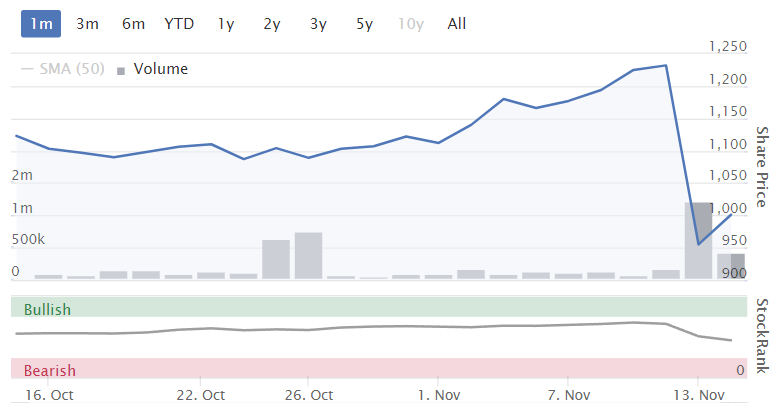
The IT provider’s results were pretty good by all accounts, despite the market reaction.
Here is the highlights table. I’ve yellowed some of the items that stand out to me:
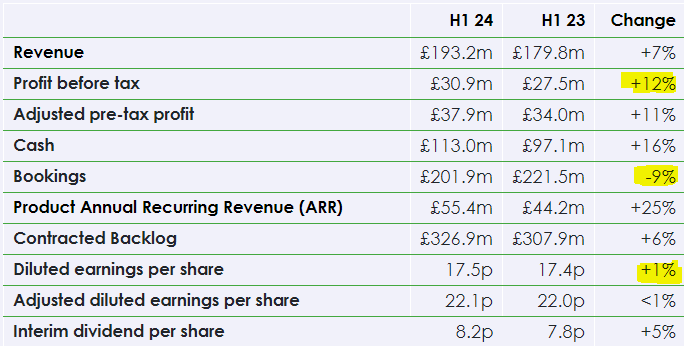
As you can see, I’ve highlighted 12% growth in PBT - a strong, inflation-beating result, and faster than revenue growth of 7% (I always like to see profits growing faster than revenues).
Note also that the revenue growth in H1 is fully organic and at constant currencies it’s a little higher at 8%.
The company has three divisions: Digital Services, Workday Services and Workday Products. The last two recorded strong revenue growth but Digital Services, the largest division, saw a small (c. 1%) revenue decline.
So why were the shares so disappointed?
Let’s start with bookings down 9%. The company observes that “the comparative period included a 125% increase in Workday Services bookings”.
Then at the Digital Services division, there are references to “reductions in scope”:
Within Digital Services, strong public sector revenue growth of 17% was offset by the anticipated decrease in healthcare and project scope reductions in some commercial sector engagements, with overall revenues at £109.2 million (H1 23: £110.5 million).
This division also saw much lower revenues from public sector healthcare: £20.4m in H1 this year vs. £29.5m in H1 last year. The company describes this as a continuation of post-pandemic decline, i.e. these revenues are still falling after getting a temporary boost from Covid.
Now let’s turn to the outlook: overall it’s a very positive outlook statement, with the company only referring to “significant funding challenges facing the NHS” as a cause for weaker sentiment for Digital Sentiment.
Financial performance: nothing very strange to report here. However as I highlighted in the table above, EPS growth looks very small at 1% - this seems entirely due to taxation. The company’s tax rate jumped sharply from 21% to 28% in the period, as the company saw its UK rate increase and also saw a higher proportion of its profits being taxed at higher rates overseas.
Graham’s view
We rarely cover this one in the report and I’m not inclined to make a habit out of covering it.
For IT providers/consultancies (not software owners), I like to see modest valuations. But this one remains at the racier end of the valuation spectrum, even after recent share price weakness:
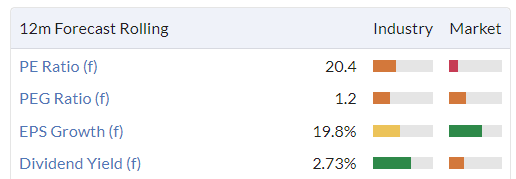
But remember that Kainos helps companies to deploy Workday, and this is how Workday ($WDAY) is valued:
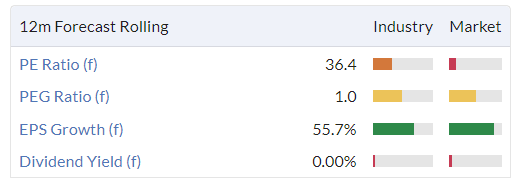
Personally, I’d rather take my chances with the absurd Workday valuation than to pay over the odds for a Workday partner.
If I was choosing a stance purely on valuation I would give Kainos the thumbs down. However, I don’t believe that Kainos is actually a bad business, but I would say it is probably overpriced. So I can take a neutral stance on the stock.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Warpaint London (LON:W7L)
https://s3.eu-west-1.amazonaws...
It looks like there has been a reasonable upgrade to Warpaint's EPS for '23 and '24 recently .
The attachment is from 5/11/23 .
Stockopedia | Warpaint London Share Price - W7L Share Price Quotes, Charts, RNS & Stock Market News
and this is from today.
Guess where I am, Paul. Malta for four days. I 've hired a bicycle (electric) for a few days to see the Islands. Hopefully I will pop over to Gozo tomorrow from Bugibba.
Lucky you slopsjon!
I very nearly popped over to Malta myself this week, as the weather is beautiful out there at the moment, totally unlike a usual November, my sources on the ground tell me! Have fun :-)
Regards, Paul.
Ocean Wilsons (LON:OCN) very interesting quarterly update today. NAV £22.70/share v share price £11.25/share, ie 50% discount. NAV includes £15.74/share for its stake in Wilsons Sons ports and towage business, and the Board has received a number of “indicative non-binding offers” for its stake, following the initiation of a strategic review. Wilsons Sons has also just disclosed decent trading results.
Other asset is a portfolio of funds.
WRT looking at Funds and Investment Trusts and cherry picking their ideas it is worth being wary of the top 1 or 2 in position size are usually there because they have already grown a lot and although they may still look attractive may not offer great upside, maybe best to concentrate on more recent/smaller positions.
Thanks to Graham for the report on Kainos (KNOS). I shall be interested to see if this company is mentioned in the multibagger webinar tonight as the company has a relatively steady record of organic growth supplemented by the occasional acquisitions, has a very high ROCE, operates in quite a fragmented industry and, bearing in mind the need for digitisation in many areas, has an apparently endless runway for growth. I don't think the reasons for the recent share price setback raise any fundamental concerns about the company which always seems to be highly rated.
RM, Trifast, Saatchi, Flowtech, Centaur, Galliford, Finsbury Food, City Pub, Van Elle, Titon.
I can spot a couple that will probably double but none of these are multi baggers.
Nice big volume spike on Focusrite (LON:TUNE)
Richard Staveley was excellent yesterday on the Trusts and Funds show and I will share a link later when the recording is available.
Meanwhile a reminder that Richard, Ed Croft, Cockney Rebel Richard Crow, Andy Brough, Christopher Mills and so many more are live at MelloLondon at the end of this month….
Mello are hosting their second in-person event of the year, MelloLondon. The event will take place on Wednesday 29th and Thursday 30th November 2023 at the Clayton Hotel and Conference Centre in Chiswick, West London.
You can expect the usual mix of fantastic Keynote Speakers, 50 quality growth companies, Investment Trusts & Funds, Fund Managers, panel sessions and much more! To find out more information, click here: https://melloevents.com/mltickets/
The ticket options are as follows:
One day: £99 (Either Wednesday or Thursday)
Both days: £159
However for all Stockopedia subscribers we offer everyone the early bird opportunity to get half price tickets if you apply before the 10th November by applying the code; Stocko50
The early registrations help us to book extra speakers and to ensure we allocate sufficient presentation rooms so that everyone gets to see the companies they want. As ever all companies will do two presentations so that if you miss one you can catch up later in the day.
Loyalty Discount:
Have you attended three or more in-person Mello events?
If so, you are entitled to our loyalty two-day ticket at just £37.50!
Use code LoveML2023
Do not miss our 'Ask the Fund Manager' session with five well known fund managers on stage answering questions from the audience.... plus Richard Crow aka Cockney Rebel and Andy Brough on stage together too....one supports Arsenal and the other is a Spurs fan so there will be plenty of banter ! https://melloevents.com/mltickets/
We hope you can join us at this educational and engaging networking event
David
'However for all Stockopedia subscribers we offer everyone the early bird opportunity to get half price tickets if you apply before the 10th November by applying the code; Stocko50'
It has been extended for all Stockopedia users until the event.
Early bird date was 5 days ago..............................
This presentation was released today by Twenty Four Select IT - people may find the first slides an interesting overview of the macro economic environment and the current trends....
https://mb.cision.com/Public/2...
Paul, you asked about the Sosandar (LON:SOS) webinar from Monday. It was an overview of the recent results webinar with a Q+A tagged on. Looks like a measured roll out of a retail footprint in targeted towns. It’s happening and I think it will add value.
Ikea buying shopping centres in the UK. Avon opening shops.
SCS (LON:SCS) goes 10p ex-divi on 17th:
"In its audited financial results for the year ended 29 July 2023, which ScS expects to announce on 25 October 2023, the ScS Directors intend to declare the Permitted Dividend of 10 pence per ScS Share. ScS Shareholders on the register of members of ScS at the relevant record date will be entitled to receive the Permitted Dividend regardless of whether the Acquisition becomes effective and without any reduction in the Cash Consideration if the Acquisition becomes effective. The Permitted Dividend, if approved by ScS Shareholders at ScS's 2023 Annual General Meeting, will be paid on 15 December 2023 to ScS Shareholders on the register of members of ScS on 17 November 2023."
The ex-divi date is actually tomorrow the 16th as per the link https://www.dividenddata.co.uk...
The 17th November you refer to in the statement above is probably the record date
Pick up the dividend in time for Christmas and then comes the long wait. This is why I cashed in my SCS (LON:SCS) chips a month ago and reinvested elsewhere.
Hi Silver moon, I also did this and cashed out..... however I'm thinking of buying back in today just for the divi and then selling again.... I can't see the price dropping much as £2.70 seems to be free money (well an extra 3.7%). is anyone else seeing this as a win win, and what is the flaw in my otherwise cunning plan....
The flaw is that the current 2.70 factors in the risk the deal doesn't complete. So 2.60 would be a perfectly logical price on that basis, post ex div. It may not drop that much, but no guarantees. You could pocket 20p if you held till the deal completes, but you would be accepting the risk is doesn't.
thanks Peterg. makes sense. We shall see how much the price drops on Friday 17th
Rockwood Strategic (LON:RKW)
Paul says it was a really good presentation yesterday. For those who, like myself, missed it I see there is another chance - they are presenting on IMC on the 27th. -
https://www.investormeetcompan...
Renold (LON:RNO) thanks Paul for the analysis and it is also my view that equity offers good risk / reward.
i think the share count has REDUCED in recent years from 225m to 208m. They bought back shares 2 years ago i think. i took this to be a massive to spend money this way which must have been approved by banks and pension trustees etc..
re the pension its interesting that the actuarial deficit in 2022 (i.e. should be better now) was only c.4m. this is because the actuaries recognise the l.tail repayment plan which is actually a fixed loan for 3.5m for UK scheme. for me i just deduction the 6m p.a. as an expense. thus you have a global no.2, making record profits, with low debt on with pension adj eps of >5p, i.e. p/e c.6.
disc i hold
https://travelweekly.co.uk/new...
Interesting piece from Travel Weekly on an upbeat report from the independent Hays Travel. A good read across for Jet2 (LON:JET2) 2 and On Beach group (LON:OTB)
Not sure I am getting to the same conclusion...?
Obviously the boss of Hays Travel is optimistic of further growth for her company into 2024. But she doesn't explicitly say that current trading has been doing well.
All she says is citing a third party study that suggests consumers are likely to keep spending on travel into 2024, ahead of other areas of spend.
This is not the same as confirming that Hays Travel current trading is healthy, nor that their forward bookings order book for next year looks strong...
In fact, because she didn't say any of that, you could imply that Hays are not really seeing strong current trading nor strong forward books for 2024. Otherwise she would have stated that.
Morning. Is the Multi-bagger webinar being recorded this evening perchance? ?
Hi there - it is, yes. I send the replay to everyone who registers!
I don't seem to have had the email about this?
Found the email in my spam, but here's the registration Link MattH
https://why.stockopedia.com/mu...
Nor have I
Apologies - please use this link.
Hi Lawrence. I've registered for the seminar but no email has come through (checked junk mail). Are you able to post the link
Lawrence it is clear that many subscribers are not receiving the emails. I have messaged Ed.
Matt, I think a number of subscribers have been omitted from the email list used to notify us of presentations.
please send the replay to me Lawrence as yet again I didn't get an email informing me of the preso. I have raised this issue with you before but no action was taken. barryadd@btinternet.com
Fuller Smith & Turner (LON:FSTA)
Due to time constraints I have only managed to read the CEO commentary which is very upbeat. Hopefully this will read across to its contemporary Young & Co's Brewery (LON:YNGN) which is expected to release interims tomorrow. I hold the non-voting shares. Fingers crossed!
Palace Capital (LON:PCA)
Is to all intent and purpose winding itself up and distributing the proceeds back to shareholders. In addition to the mooted tender offer early in the new year, it has announced, subject to shareholder approval a further buy back programme for up to 15% of its shares.
It has continued to successfully deleverage and achieve property sales at a premium to book value. As a result of the share buy backs it continues to trade at a significant discount to NAV of 294p, current LTV IS 6.5% and it yields around 6.5%.
What's not to like? I hold and am obviously biased, so as always make your own investment decisions.
Totally agree Jonno. With Peter Gyllenhammar AB holding 11.55% I am sure the strategy will stay on track for Palace Capital (LON:PCA)
Palace Capital (LON:PCA) Peter Gyllenhammar increases stake RNS to-day https://newsfile.refinitiv.com...
What's not to like you ask? The NAV discount versus other property companies with good dividends (my favourite is Tritax EuroBox (LON:EBOX)) is not that exciting basically!
Rockwood Strategic (LON:RKW) Couldn't agree more with Paul's comments. Rockwood Strategic (LON:RKW) has a clear strategy and Richard Staveley supported by Rockwood's advisory board is prepared to do the hard yards to make it work. Although no one gets it right all the time his success rate in an awful market for small caps is impressive. Rockwood Strategic (LON:RKW) is unfortunately not available on all platforms, but it is held in my wife's ISA on the ii platform and I have added a few more at this morning at a 5% discount to NAV, or thereabouts.
Also a word for Rockwood's stable mate Odyssean Investment Trust (LON:OIT) another well run and differentiated Trust managed by Stuart Widdowson and Ed Wielechoski. A succesful Trust using a PE approach to invest in listed small caps. This is held in family ISAs where the platform for some spurious reason doesn't allow investment in Rockwood Strategic (LON:RKW).
Both Trusts trade at or close to par.
Thanks jonno.
What I like, is that as PIs we don't have any of the massive liquidity problems that funds have, getting in and out of their positions. So as Staveley said yesterday, they have to think about potential exit routes before they buy any share - and it's only a tiny fund, at about £50m. Whereas we can just look at Rockwood's top 20 positions, and cherry-pick the ones we like, knowing that the best performing small caps fund has done the due diligence for us. That strikes me as a very good strategy. We can buy & sell them with relative ease, so why buy the fund?!
Regards, Paul.
Hi Paul,
Yes, I hold several stocks owned by Rockwood Strategic (LON:RKW) and Odyssean Investment Trust (LON:OIT) . Pressure Technologies (LON:PRES) , Flowtech Fluidpower (LON:FLO) M&C Saatchi (LON:SAA) Elementis (LON:ELM) to name some, but never any guarantees and patience is required. A little good fortune also helps.
All the best
Well yes....provided you are prepared for the following when they take a company private (bearing in mind Rockwood Strategic (LON:RKW) can act alongside alongside the rest of the Harwood stable which includes a private equity capability):
1. Your platform may demand the shares are transferred out of your ISA/SIPP (with ISAs it is the rules, with SIPPs it is platform capabilities)
2. You've checked the articles of association to ensure there is no wording that permits a clean-up operation under "drag along" to eject small minority shareholders at "fair value"
3. You are prepared to fight for your minority shareholder rights in court if the majority shareholders persuade the board to amend their Articles of Association?
I've just checked the factsheet, and Rockwood Strategic (LON:RKW)have the ability to hold 15% in private shares.
Credit where it is due - I think I recall you/Graham/Roland at some point when reviewing a Harwood-owned company highlighting that there were scenarios where the risk of investing via the manager could be very different to investing alongside....
Hi Monty
I accept what you say regarding Harwood taking listed companies private and they have close to 30% of Pressure Technologies (LON:PRES) and Flowtech Fluidpower (LON:FLO) , but I would make a few observations.
It depends on the price one paid. For example Rockwood Strategic (LON:RKW) and Peter Gyllenhammer supported a placing in December 2022 in Pressure Technologies (LON:PRES) at 30p. My recent top up was sub 26p. Messrs Mills and Gyllenhammer have also stepped in to provide a £1.5m loan to the company, although I wouldn't call the terms generous.
To paraphrase Howard Marks as I often do, success in the stock market is about buying well. Hopefully I have done so. Time will tell.
Regarding Flowtech Fluidpower (LON:FLO) which is held by other small company managers such as Gresham House and Downing who collectively own 14%, I can't conceive of them accepting a low ball offer. Why should they? You then have to consider Roger McDowell, a close associate of Chris Mills who sits on the Rockwood Strategic (LON:RKW) advisory board and is a director of Flowtech Fluidpower (LON:FLO). He owns 1.7% of the company plus there are other significant shareholders such as Close Brothers with over 7%.
Both Pressure Technologies (LON:PRES) and Flowtech Fluidpower (LON:FLO) are currently priced at a significant discount to NAV, so in the absence of a 'black swan' event at either company why would the other 71% of holders accept an unfair offer.
Never say never, but I am happy to sit tight as I did with Crestchic.
All the best
How do you go about finding out Rockwoods positions?
I have looked on their website and cannot find that info anywhere
Thanks
Andrew (long term lurker)
A quick way is to add it to a Hargreaves Lansdown watchlist, then click on the fund factsheet
Hi Paul,
With respect to Rockwood Strategic (LON:RKW) I would agree that cherry-picking their holdings is a good alternative to buying the fund and I use this approach. However, as I understand it, they do not have to declare any holding if it is below a 3% stake so if they build a stake over a period, by the time it goes over 3% (and needs to be declared), the share price might already have moved significantly. Of course, by the time the fund discusses the new stake in one of its excellent presentations, the share price might have moved even further. In addition, if they reduce a stake, perhaps because of an adverse development, the share price in that company would likely fall before the public declaration was made, although this is admittedly a rare event. I also keep a lookout in case Rockwood trades at a discount to net asset value as that might be another reason to consider buying the fund rather than its individual holdings, but this has not happened lately as far as I am aware.
I recall that that some time ago Ed Croft & Ben Hobson contributed to an e-book 'The Smart Money Playbook' https://www.stockopedia.com/bo... . This looked at using this approach in detail along with with various other approaches. Some of the analysis was quite 'data heavy' and at the time I think there was a plan to incorporate it into a Stockopedia feature but I guess it proved too difficult in terms of getting hold of consistent quality data. Nevertheless as you say the concept is a very good strategy and it would be nice to see it on the Stockopedia new features plan at some stage in the future.
RKW Why buy the fund? I guess the answer with any fund is that buys and sells are not always immediately announced and corporates might get offers to join in placings that PIs might not receive, Also some PI's (not here lol) might not follow the markets avidly and smal lcaps can as we know move very quickly.
However yes one could most likely follow along if inclined.
Yes but do you? Did you hold Load? From memory you were not that keen on Load. You don't know when they buy and at what price. The information on holdings not up to date. They can buy at discounts sometimes. They have access to more information. The performance has been good, around 120% over 5 years and 88% over 3 years.
Actually I'm thinking of investing in more funds, small caps are taking too much time and effort, why not let someone else do all the work? If they make 120% over 5 years that is fine.
I hold Rockwood Strategic (LON:RKW) and obviously bought it as I believed in the manager. However since I paid the equivalent of £2.02( there was a stock split) shows that even good managers can struggle to perform in difficult markets.
I had a look at Rockwood Strategic (LON:RKW) recent Factsheet and noticed their largest holding is RM (LON:RM.) - nearly 10% of Rockwood's portfolio.
Seems very strange to me. As RM (LON:RM.) looks a pretty unappetising investment proposition with high debt, flat sales growth and little by way of recent cashflow. Just curiosity on my part really.
Have Rockwood got stuck in a duff position or could they have spotted an opportunity in RM (LON:RM.) that others have missed?
Did you see Steveley's comment? 'The Fund’s best-in-class performance was driven by gains at RM Group (+23%), following non-core disposals and management change. I think he may have been referring to RM's stash of IP addresses which is very valuable and they sold some recently. for £2.7mm.
Thanks - I hadnt noticed the comment about the value from selling those IP addresses.
No they bought most of their holding in RM at very low prices; below 35p.
True - but Harwood Capital / Rockwood are still buying and they went from 11% to over 12% earlier this week.
Indeed they did. My take on it, is that Rockwood are banking on a Labour Govt investing significantly more in education and companies like RM will surely benifit. Certainly worth a small punt and a hold for a couple of years to see what eventuates.
With respect to Rockwood Strategic or any other UK fund , if I had to choose that type of investment I would definitely go for Warren&Charlie (not UK small cap investors but definitely better and much more experienced than Rockwood management).
Also, If I am not mistaken Paul’s picks at the beginning of the year have by far outperformed Rockwood!
Cake Box Holdings (LON:CBOX) snapshot seemed to be received well yesterday, thanks for the feedback. No companies reporting on my watchlist today, but here's Kainos (LON:KNOS) interim results from Monday. I did hold this but got stopped out below 950p, typically biggest rally of the year the day after :).
For a bit of background if I'm going to start uploading a few of these. I am certainly no expert, so please don't rely on any info I provide. I started investing in individual stocks in 2020 & investment trusts a couple of years prior to that. It's been a rollercoaster first few years with some major highs & lows. I love it though and am now putting a large amount of time into improving my investing skills and building my portfolio. I've been absorbing as much education as I can and am just starting to feel as though I have some idea of what I'm doing. Though I have made so so many mistakes! I guess that's just the price of entry & I'm sure I will make many more.
I've been a lurker on here for the past few years as I didn't feel I had the knowledge to contribute. Though it's probably time I start :). I have to say it's incredibly useful and a massive thanks to Paul, Graham, Roland, Stockopedia and all the other regular contributors.
Great post Phil.
I like Renold (LON:RNO) as a business but their recent RNS’s have been consistently unclear on the impact of the YUK acquisition. Buried inside this one is a comment that it added £7.2m of sales. Other comments imply there’s a chunk of price increase to offset inflation, suggesting organic sales volumes are probably declining quite a lot. I can’t really get my head around why profits are up so much, there seem to be some chunky fx effects and my hunch is product mix is important somehow. Anyone want to have a go? Setting the pension issue to one side, it’s a hard business to understand relative to its size.
Will be interesting to listen to the call this evening and see whether that offers any further clarity
On Renold (LON:RNO) (I hold) we need to probe why profit has spiked up so much on a revenue increase which, as you say, may be driven by as much by price increases than volume. The Cavendish broker note suggests margins have improved across both torque and chains but I note in particular 'Returns continue to benefit from greater automation driving efficiencies. TT division saw strong revenue growth of 25.2% to £28.8m, driven by the increasing production at Cardiff for the large-scale military contracts. Operating profit increased 206% to £4.6m, with margins improving from 6.5% to 16.0%.' That's a fab margin improvement. I think this is the contract referred to? Luckily it lasts for a while yet so that margin might not drop off anytime soon unless some of the revenue has arrived early in the contract with costs higher later on maybe? That might be something to ask about at any investor call.
I am more worried that at their AGM trading update (about four months into the year) they said that revenue had increased 16.6% at reported rates and 18.7% at constant exchange rates but today, just two months later, we find that revenue is up 7.7% (10.7% at constant exchange rates. That suggests quite a lot of softening in the last two months?
This might explain why Cavendish has revenue actually falling by the year end despite that the recent acquisition will bump up the numbers in H2. It also explains why broker has EPS falling next year. So perhaps we are at peak-performance for Renold (LON:RNO) - although offsetting this risk is that more acquisitions are likely.
On the pension, would anyone expect contributions to decline anytime soon? I'm less across the situation there.
Hi M48,
I also did a CTRL+F search for "YUK" in the Renold (LON:RNO) interims today, and agree with you that there was hardly anything about how it is performing. Whereas the smaller Australian acquisition gets some positive comment.
Although checking again, I see that it says, "The integration of the YUK business has proceeded as planned...", and £1.7m of deferred acquisition was paid. Which probably points towards the acquisition being OK maybe? It also mentions a benefit from substituting product internally, replacing bought-in external products.
I also searched for "organic" as I wanted the split between organic & acquisitive growth, but it doesn't seem to show this. The regional section in the commentary shows Europe (chains) revenues down 5.8%, but up 7.6% including YUK. Americas is up 6.9%, and Australasia up 6.7%. India down, but China up 50%.
There looks to be a good margin improvement, with the chains division increasing its "return on sales" considerably to 15.8% (LY H1: 13.1%). So yes, it looks like a big improvement in margin, rather than sales, has driven the profit rise (and acquisitions helped too).
I've also just spotted that the Torque Transmission division had a big improvement in H1 profit, from £1.5m LY H1, to £4.7m this time. That's adj operating profit. That £3.2m improvement from TT is more than half the total £5.4m improvement in H1 adj operating profit.
Regards, Paul.
Renold (LON:RNO) is my largest portfolio holding, at 9% so I am deeply involved in this share. Yes it's dirt cheap on all metrics but I was left unsettled by this stellar update and will sell a portion into any further rally! Because, on reading the accounts carefully 1) Europe sales are slowing 2) the pension fund deficit reduction is purely due to higher interest rates, and it will rise with falling yields again 3) Competition is increasing in China and India, two key future markets 4) Renold communicates nothing about its strategy for segments which should allow it to re-rate, such as robotics - does it have one? 5) And overall, I find progress very..slow. Small acquisitions, a poor balance sheet with very high intangibles and a pension fund which could come back and devour 30%+ of its cashflow if there is any kind of slowdown, and the deficit increases again. I have a very good track record on spotting UK engineering takeover situations and that is the last factor which never happens. With increasing sales, this becomes more likely and Renold needs more critical mass and clear exposure to high growth industries for a foreign group to buy it. It feels like it will almost certainly tick up from here to mid-30s and then try to establish the floor for a new, higher trading range of 35-40p.
Good prelims from Tracsis (LON:TRCS) this morning with inline outlook. Management summary here:
https://plcwebcast.uk/trcsfy23
Net cash and balance sheet now free of material deferred consideration obligations.
Particularly good progress with N America acquisition and now moving to cross-sell UK Remote Condition Monitoring product there.
Yes, very good to see. A good play given the context of investment in transport other than planes, ships and automobiles. Personally I am more weighted to JOURNEO - great value and trending nicely.
Yes £TRCS rather more of a steady Eddie these days than the early days rating, which was largely based on expanding the US growth element.
Ironically the US is now growing albeit steadily but encouragingly, but it has taken a lot longer than the early bulls anticipated. Their order books are strong, but they don't really say what growth they have in order books which is a bit disappointing. But perhaps I would be a bit cautious on outlining order books myself, and they do say there will be more weighting to H2 in 24/25.
4.6%... release the bulls
"BUT inflation in the largest part of the economy, services, is still 6.6% and core CPI (excluding energy, food, alcohol and tobacco) rose by 5.7%."
https://twitter.com/Peston/sta...
True, but how long are those in cash willing to wait. Surely the fomo starts to kick in around about now...
I don't know. I've got coupons paying over 8% which means I don't fear I'm missing out. Waiting for a pullback in the housing market too to deploy some funds for the long term. Adding to my portfolio is the last thing on my mind currently.
Surely the fomo starts to kick in around about now...
Why should there be any fomo here ?- surely we are roughly speaking at a place we expect to be so this news aint unexpected overall (sadly too slow in coming probably) . If base rates are stuck where they are now for another 9 months then a boatload of peeps will still be materially worse off as they come of cheaper fixed rates.
Is your avrerage punter going to invest in stocks if thye can get 5%-6% return risk free -? probably not.
Headline CPI 4.6% vs consensus 4.8%. Core CPI 5.7% from 6.1% last month.
Shock horror - government delivers on promise of halving inflation!
Possibility of a soft landing?
Time to go LONG
The Government hasn't actually done anything that I can see - the independent Bank of England has set the monetary policy that has supposedly brought inflation down. The real driver in the fall of inflation is that energy prices have stopped increasing, so the knock oon effects from that have stopped.
I suspect the Govt would say in its defence that its Fiscal prudence in not lowering taxes further reduced the potential effects of inflation (assuming there was too much money in the system).
Input costs certainly were a factor, but probably the BOE thought by taking money out of the system (savings increasing as a proportion rather than spending, and discouraging debt take-on) they would cool demand, putting the pressure back on suppliers to limit their scope to increase prices without damaging their businesses.
Now the BOE wants to restrain wage growth and demands, but it is nip and tuck whether current rates help encourage that or deter it. However, I think we will see Unions starting to settle strikes, as they see inflation coming down-hopefully and the PR boost that may have helped sympathy about high inflation cooling.
I think the government would point to several factors
1) a relatively hardline on public sector pay increases despite strike action so as to not fuel demand led inflation
2) a targeted support on energy / cost of living crisis, again reducing the level of cash in people’s pockets and restricting demand
3) restricted spending
4) relief on tax and in a number of cases tax rises again absorbing money.
They might say that this type of fiscal prudence combined with BoE rate policy is why inflation is now at and below committed targets. The fact that inflation was supply shock driven has not been exacerbated by a much uglier problem of wage growth cycles leading to demand led inflation.
whether one agrees with that will depend on their macro, policy and political views (I make no comment either way) but the above are 4 ways the government would likely claim their policy has helped the inflation picture.
"The fact that inflation was supply shock driven has not been exacerbated by a much uglier problem of wage growth cycles leading to demand led inflation."
Is wage growth such a bad thing ? - i think the main upside from brexit (i didnt vote to leave) is that it has brought some obvious pricing power back to skilled workers which was lacking when europeans could come in enne masse charge cheap rates take the tax credits and leave with all the cash building nice new home at home.
With wage growth that will boost taxes and boost spending power of peeps in the shops - whats the problem with wage growth ? it should also be incentive for us to be more efficient. Seems that the more stable countries actually have higher wages.
And not fuelling that by increasing interest rates - surely rising base rates had peeps hounding employers for pay rises. WATP
Yes, too much wage growth is seen as very bad from an inflation perspective rmillaree. It leads to excess demand for services and products, which means companies have pricing power to push up and hold prices, leading to increased inflation. That in turn encourages employees to demand even higher wages and you quickly get an out of control wage growth cycle. That is precisely what the BoE and Govt are concerned about. The supply shock led inflation component is pretty irrelevant as that fades very quickly as supply is restored and monetary policy has zero impact on supply led inflation.
What you are looking for is a sweet spot of GDP growth, low but positive inflation and wages increasing in real terms but not far ahead of inflation. That keeps economy growing, money in peoples pockets but businesses hungry and price competitive.
It is important to distinguish between causality and coincidence. What did the government do to reduce inflation? Interest rate rises were put in place by the Bank of England. And we don't know whether or by how much inflation would have fallen anyway. As Paul has said (many, many times) this inflation has been caused by an increase in the cost of inputs rather than by excess demand. Wouldn't it have fallen anyway as energy prices stop rising and supply chains unblock themselves (see also af20001 below).
No doubt government and the Bank of England will claim the credit. That is what governments (of all hues) always do
"As Paul has said (many, many times) this inflation has been caused by an increase in the cost of inputs rather than by excess demand. Wouldn't it have fallen anyway as energy prices stop rising and supply chains unblock themselves (see also af20001 below)."
I certainly agree with this statement - from my novice viewpoint seems like all increasing base rates has done is fuel inflation as peeps seek out (rightly) higher income and companies charge higher prices to service their debts. I wont disagree base rates were stupid low for too long but seems like they have over reated on the upside and still continue to over react if there is no hope of slight drops for another 9 months.
Hi Wol,
My view (maybe not clearly enough expressed) is based on what former Governor of the Bank of England has said - that the burst of inflation we've had recently was caused by a combination of -
1. Much too loose policy on both interest rates (for 14 years at or near zero) and excessive Govt spending (fuelled by QE during the pandemic), so too much money in the economy, and
2. Supply constraints caused by lockdowns on global supply chains, throwing almost everything into some degree of chaos.
So as King explained in some interviews he did recently, it really has been a classic case of too much money (from QE & Govt deficits), chasing too few goods (from pandemic-related supply chain disruption).
Those factors are clearly now getting resolved naturally, so arguably the central banks are pushing too hard on interest rates and QT, when it's not necessary.
Only time will tell!
I wonder how much effect interest rates have actually had? I don't buy into this view that central banks are somehow fine-tuning the economy with interest rates. History shows that they're hopelessly inept, mis-time pretty much every cycle, and have little to no forecasting ability. So why do we take their utterances so seriously?
Mervyn King goes further, and says there is an intellectual vacuum at central banks, due to groupthink, as the economists all studied the same duff principles & beliefs at the same universities, which just assumed that inflation would permanently stay at 2% regardless of whatever they did with interest rates. They realised with a collective shock that this wasn't true, hence have now over-reacted with interest rate hikes. Just his view, which I find compelling, obviously he knows infinitely more than I do on the topic.
Regards, Paul.
Not sure the govt can claim much credit for the reductions - after all, they were blaming Ukraine, Covid etc., for the increases.