Small Cap Value Report (Wed 15 Sept 2021) - CCT, RCDO, TPX, CAML, ELCO, HRN, DVRG, PDG, SUN, SIS, RBGP, TWD, ANP

Good morning, it's Paul & Jack here with the SCVR for Wednesday. Today's report is now finished.
It's my last day in Malta unfortunately. Although with so many RNSs to report on here, it's been more work than holiday! Mind you, waking up to this view (below), who's complaining?! (not me). And of course the weather this morning is already "scorchio!"

Agenda -
It's ludicrously busy again for updates/results today - we've already listed 14 companies on our GoogleDoc where Jack & I draft sections. So we're not going to be able to cover everything. We'll try to pick the more interesting updates (e.g. above & below expectations). If you're going to request us to look at a company in the comments below, then it helps if you explain why you think a company is worth looking at, as there's lots of other stuff competing for our attention today! By all means post your own reviews of results/updates too, we welcome that.
Paul's Section:
Ricardo (LON:RCDO) (I hold) - results for FY 06/2021 look OK, but nothing special. Balance sheet seems fine, after an equity fundraising last year. Modest divis. Overall, I'm neutral. Probably priced about right?
Panoply Holdings (LON:TPX) - a strong trading update, ahead of expectations. This share is expensive, on a high PER, but that seems justified by strong performance. Very strong order intake in particular.
Hornby (LON:HRN) - bit of a mixed trading update - strong order book (no figures provided), but as I would expect it also mentions potential supply chain problems. Overall, it's been turned around from basket case into generating a modest profit, but it's difficult to see much upside for shareholders, especially as the top 2 own 91% of the company, so minority shareholders are completely at their mercy - inherently risky.
Deepverge (LON:DVRG) - a very quick review of loss-making interims. Too speculative for me.
Pendragon (LON:PDG) - as with other car dealers, business is booming (for now). Strong full year guidance. Looks cheap.
Surgical Innovations (LON:SUN) - greatly reduced losses, due to cost-cutting. Trading around breakeven now. Balance sheet looks solid. I can't see anything to interest me here.
Science In Sport (LON:SIS) - interim results show a move into a small (adjusted) profit. Balance sheet looks OK. I think this company looks potentially interesting, but I baulk at the £106m market cap, which seems a long way ahead of events.
Rbg Holdings (LON:RBGP) (I hold) - a very quick look at impressive interim results. Upbeat outlook too. Seems quite good.
Trackwise Designs (LON:TWD) - poor interims. Clearly a jam tomorrow share, as these figures don't justify a valuation anywhere near £70m.
Anpario (LON:ANP) - interim figures don't impress. Why is this share on such a high PER, when there's little to no growth?
Jack's Section:
Character (LON:CCT) - sales continue to be strong at this toy distributor, but freight costs, port delays, and rising raw material and labour costs are impacting profitability. Management guides to at most 10% lower FY PBT, which suggests £10.8m. The balance sheet is strong and the group is well positioned to survive but near term pressures will likely weigh on the share price, which is at near all-time highs.
Central Asia Metals (LON:CAML) - copper, zinc, and lead producer with operations in Kazakhstan and North Macedonia. Results are strong and impressive levels of free cash flow are being used to pay down debt and pay out dividends. Management is now focusing on potential acquisitions. The company is doing a good job with what it can control, but commodity prices remain the key driver of performance.
Eleco (LON:ELCO) - revenue up 13% and recurring revenue up 8%. Product development continues, all funded from internal cash flows, but the company guides towards a temporary reduction in profitability over the next 18 months as the transition to SaaS progresses.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Ricardo (LON:RCDO) (I hold)
420p (last night’s close) - mkt cap £261m
I dipped my toe in here a little while ago, with a starter sized position, so will be interested to see if the figures today provide confidence to expand my position, or whether it should be chalked up as a mistake and ditched.
Ricardo shares caught my eye originally because it looks a decent quality company, on a cheap-looking valuation. Obviously the automotive sector (one of its segments) is having a tough time at the moment with component shortages, so that might be having some impact on Ricardo maybe. Let’s have a look.
''Over the last eight years we have significantly diversified our portfolio and, by so doing, Ricardo is now positioned as a world-class environmental, engineering and strategic consultancy offering expertise that is supporting global green agendas.
Preliminary Results (for the 12 months to 06/2021)
The main highlights seem quite encouraging -
· The business continues to grow and we are well positioned as markets recover post COVID-19.
· Positive momentum, with H2 underlying profit before tax of £13.0m, compared to £5.0m in H1.
· All segments, except Automotive & Industrial, increased profitability on the prior year
Revenues flat at £351.8m
Underlying profit before tax (PBT) £18.0m, but large adjustments there, as statutory PBT is much lower at £3.9m
Order intake down 4.5%
Order book at year end is down 6.5% but still substantial at £293.5m. Order book data can be tricky though, as we’re not usually told over what length of time this is spread over. Companies should really provide a table, showing the order book split out for each future year.
Dividends - looking at the Stockopedia divi summary page here, Ricardo seems to have skipped the final divi last year, and reintroduced a small interim divi (at a much lower level than pre-pandemic) in early 2021.
A final divi is declared today - again at a much lower level than pre-pandemic -
Final dividend of 5.11p per share (total dividend of 6.86p per share) declared.
The divi yield works out at 1.6%, and I would expect the divis to rise in future years.
So worth having, but income is not the main reason to buy this share.
Net debt - looks OK -
Equity fund raise, together with a strong working capital performance, enabled the Group to reduce net debt by 36% to £46.9m.
Outlook - sounds OK -
As we enter FY 2021/22, we do so with a robust order book and pipeline. This is a business with a positive outlook and as a Group we continue to push the boundaries, strengthening our business for a sustainable future.
Being a services business, investors don’t have to worry too much about supply chain problems, although that is bound to be impacting Ricardo’s customers, which might have knock-on problems possibly?
Balance sheet - looks OK to me, and has benefited from an equity placing last year.
Note the pension scheme has moved into a small accounting surplus, but is still a drain on cash, with a £4.6m cash outflow to fund the actuarial deficit.
I continue to bash my head against an imaginary wall, when I have to look at pension scheme accounting, which is just so ridiculous - having two sets of figures, yet the accounting treatment requires the use of less prudent numbers, which under-state the real world deficit, and cash outflows.
The investment community is not being well served by the people who dream up accounting standards, I’m sorry to say.
Valuation - a share price of 420p is 18.8 times fully diluted EPS for FY 06/2021 - probably priced about right?
The latest forecast from Liberum (accessed via Research Tree, with thanks) is a significant rise to 31.5p, then 39.4p for FY 06/2022 & FY 06/2023 - quite punchy numbers. If forecasts are achieved, then this share would be very good value. I don’t know whether the forecasts are achievable or not.
My opinion - I can’t get excited about this, and am thinking about whether or not I should sell my small position here, as it’s a bit of a distraction, and I don’t have high conviction on this share.
The business is nicely diversified now, with good performance from other sectors, as the table of performance by division shows.
The balance sheet looks fine, with the risk of further dilution now looking low.
With economies recovering, maybe performance is likely to improve further?
Overall, I can’t decide, so will just say I’m neutral.
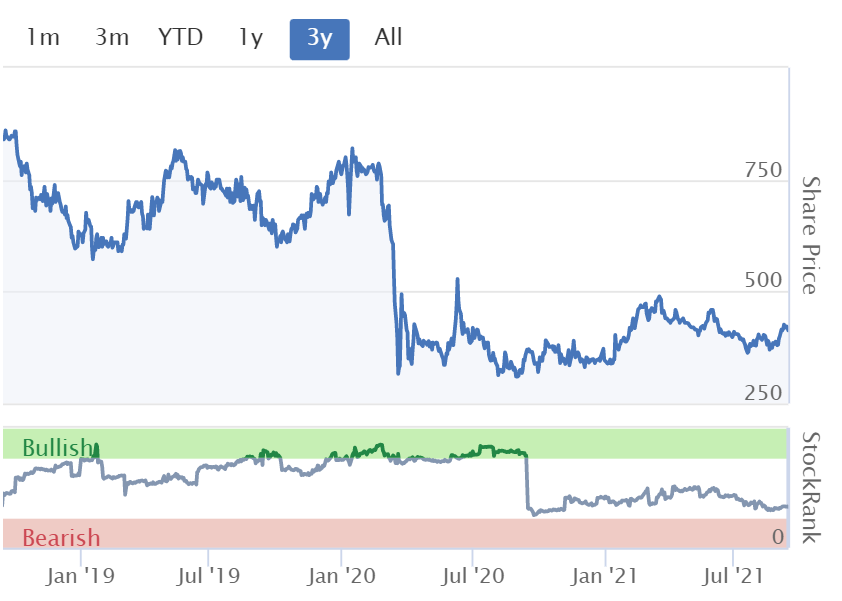
The chart below is quite unusual, in that Ricardo has not seen much of a rebound from the pandemic lows, whereas most other shares have recovered much better. Could there be an opportunity there to catch up maybe?
Note that the share count has risen from about 53m to 62m shares, due to the equity fundraise last year.
.
Panoply Holdings (LON:TPX)
270p (up 7% at 08:51) - mkt cap £226m
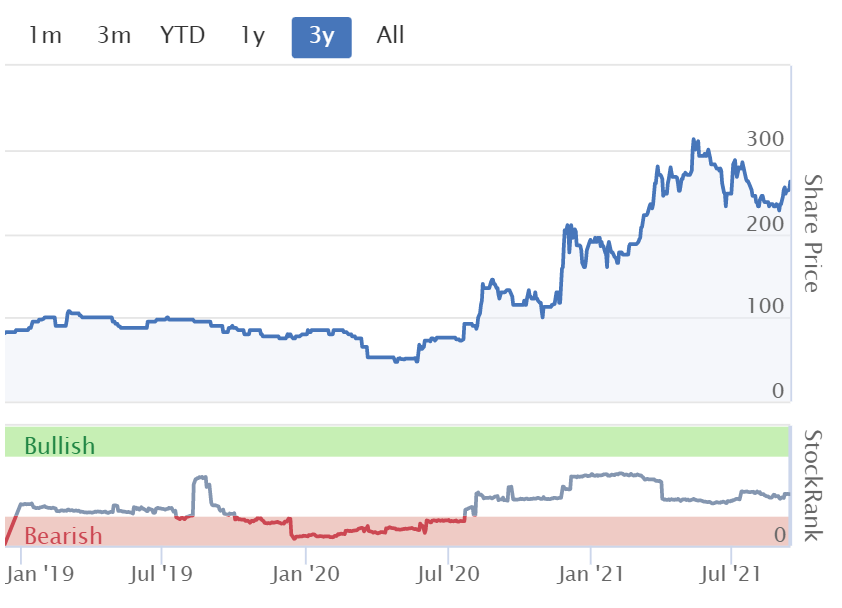
I last looked at this software group here in July, when I reviewed its results for FY 03/2021, and came away with a much more positive impression than in the past - strong trading, good growth, and my previous concerns over dilution & balance sheet weakness had mostly been sorted out. Although the share did look very expensive at the time time at a very high PER, I felt the premium was probably justified.
There’s more good news today -
The Panoply Holdings PLC (AIM: TPX), the technology-enabled services group focused on digital transformation, announces an update on trading for the five month period from 1 April 2021 to 1 September 2021.
Trading significantly ahead of expectations
Guidance is raised -
As a result of this strong trading, the Board is raising guidance for organic like-for-like revenue growth for the full year ended 31 March 2022 to between 15-20% (from the original commercial vision target of 10-15%). The Board now expects to report revenue for the full year in excess of £77m.
In light of the growing market opportunity, and in order to execute on the substantial pipeline that has been built, the Company is investing in human capital and a single brand, but still expects to see Adjusted EBITDA margin expansion in the year.
Other points -
- £50m contracts won so far this year, +177% order intake
- Larger contracts being won, e.g. £10m 5-year deal with a utility company
- High demand
Valuation - many thanks to Dowgate for crunching the numbers for us. It forecasts 10.0p EPS For FY 03/2022, although note that this drops to 8.7p on a more prudent basis which takes into account maximum potential dilution relating to previous acquisitions. So it’s probably best to value the business on 8.7p forecast EPS, giving a PER of 31 times - a punchy rating, but that’s because the business is performing well.
My opinion - another positive update, which is reflected in a high PER.
.
.
Hornby (LON:HRN)
41p (down 8%, at 12:09) - mkt cap £68m
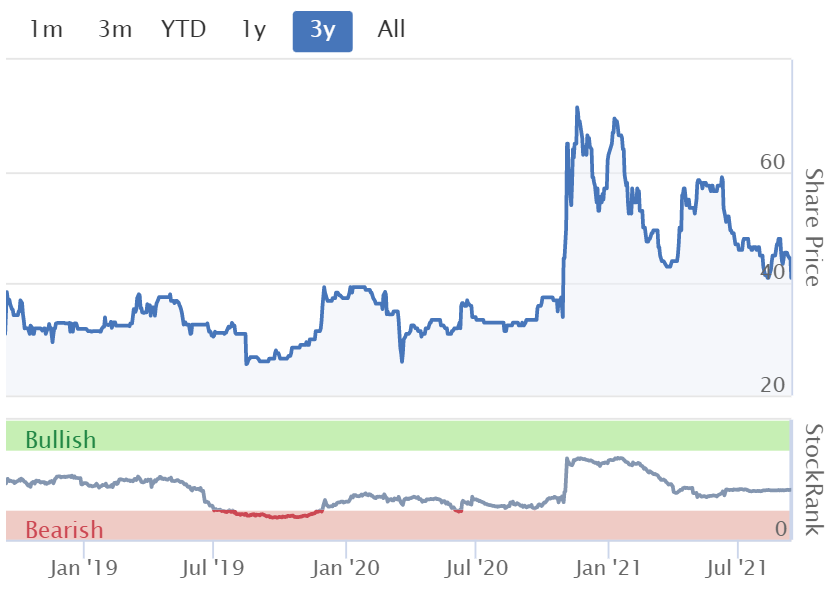
To get up to speed, I’ve just read Jack’s excellent review of the FY 03/2021 results, which is here. After years of losses, this models & collectibles group scraped into a small profit for FY 03/2021. I would have expected a big boost from lockdowns, so those numbers don’t particularly impress. The share price has gradually drifted back down to where it was before the everything rally began in Oct 2020.
For the period from the 1st April to the 31st August 2021, sales and margins have been slightly lower than the previous year but in line with internal budgets. Trading patterns have begun to return to those experienced in pre-covid times.
On 30 July 2021, the Group completed the acquisition of the remaining 51% of LCD Enterprises Limited for a cash consideration of £1.3m.
As is usually the case in our industry; the outcome for the full year is subject to the sales rate over the key Christmas trading period. Our outstanding order book is very strong and substantially higher than a year ago, however timing is everything when it comes to Christmas and we are mindful of the potential supply disruption at the ports continuing.
That’s a mixed bag, but I think the most important point is that the order book is very strong, and substantially higher than last year. That indicates strong demand, which is the most important thing any business needs.
Supply difficulties is par for the course at the moment, and shouldn’t surprise anyway. These are temporary issues, and really shouldn’t be impacting share prices that much, because temporary problems get ironed out, and don’t matter in the long run. Unfortunately, we’re in a market where many traders/investors have the attention span of a fruit fly, and instantly react to every piece of news, often irrationally. Stock markets are meant to be for long-term share ownership, but seem these days to be more like a giant casino, with many people trying to get rich quick, and all the distortions that introduces.
For that reason, I think this is a good time to have some cash on the sidelines, so that we can pounce on heavily discounted shares in great companies, when they announce supply chain problems, as loads of companies are, and will be doing in the coming months.
My opinion - with Hornby, it doesn’t really interest me at any price. I just don’t see a particularly viable business here. Management has done well to make it modestly profitable again, from the basket case it was previously. But where’s the growth going to come from? Why is it valued at £68m, given that the last dividend seems to have been paid in 2012?
Note that the top 2 shareholders own c.91% of the shares, an unhealthy ownership structure, so small shareholders are completely at their mercy. De-listing is therefore possible in my opinion, a risk I wouldn’t want to take on.
So definitely not for me, but I wish the company well, as it’s nice to see heritage brands like Hornby, Scalextric, Airfix, Corgi, still going.
.
.
There are loads more companies reporting, so I might just do very quick review sections now, to cover as much ground as possible, so less detail, just a general overview. Here goes!
Deepverge (LON:DVRG)
28.5p (down 6%, at 12:52) - mkt cap £61m
Interim results show revenues up, but losses increased to £(2.3)m in H1, worse than LY.
EBITDA is not so bad, as the amortisation charges are high.
Balance sheet has been strengthened with a £10m placing, so looks fine for now.
Overall, this looks highly speculative, so not the sort of thing I would be interested in. Positive commentary, as you always get with speculative shares.
Pendragon (LON:PDG)
18.8p (up 2% at 12:55) - mkt cap £262m
Strong interim results, as we’re seeing from all the car dealership chains at the moment - they’re basking in soaring prices of used vehicles, giving them a spectacular (but temporary) boost to profit margins.
Underlying H1 profit before tax is £35.1m, and guidance for the full year is £55-60m. That’s surprising, because my sector pick Vertu Motors (LON:VTU) (I hold) guided for H2 barely above breakeven. They can’t both be right, hence I see read-across here for another profit upgrade at VTU potentially.
Balance sheet looks OK, but note there’s a pension deficit. Pendragon is unusual in that it also includes a profitable software business.
The valuation looks attractive to me.
Pendragon says it is aiming for profits of £85-90m by 2025, which seems ambitious given that this year’s bumper profits are likely to turn into next year’s tough comps.
Surgical Innovations (LON:SUN)
2.88p (up 7% at 13:11) - mkt cap £27m
A tiny company, with only £4.2m revenues in H1. The most notable aspect of these interim results is how much costs have been reduced. Hence it ekes out a small EBITDA profit, but a small loss after tax of £(94)k. That’s much better than the heavy losses of the past.
The gross margin is low, so whilst there is some operational gearing, it’s not great.
Balance sheet looks OK, with £2.7m net cash.
Overall, the company seems to be recovering from pandemic-related reduced demand, but unless it’s able to achieve a step change in revenues & profit, then I can’t see much of interest here. Not sure why it’s valued at £27m, I wouldn’t pay a third of that price personally. It needs to develop a blockbuster product, as current size & performance doesn’t justify SUN being a listed company.
.
Science In Sport (LON:SIS)
78p (up 1% at 13:23) - mkt cap £106m
This is a potentially interesting company, although a lot of upside is already priced-in. It sells sports nutrition products.
Interim results show some revenue growth, although against a soft comp, and not much growth on H2 last year.
Loss before tax of £(2.6)m in H1, but if goodwill amortisation and share options are reversed out, then it scraped into a small profit. Share options seem excessive at £1.4m charge in H1, very generous given the company isn’t yet properly profitable.
Balance sheet looks fine.
Outlook comments seem upbeat -
After record monthly sales in June, sales in July and August have performed very strongly, supported by our investment in technology and brand. Online sales have accelerated and retail sales have continued to recover. We are continuing to manage input cost inflation. While there are still challenges and uncertainties in the current environment, the Group remains very well-positioned to exceed revenue targets for the financial year. We remain very optimistic about growth prospects over the medium and long-term.
My opinion - this company looks promising, but £106m market cap seems a long way ahead of events. For the same price I could buy cash machine Scs (LON:SCS) (I hold) on a single digit PER, and with an embarrassingly huge cash pile. Why would I buy a breakeven sports nutrition business in preference to that? There again, we are in a bull market, and people cheerfully over-pay for growth in bull markets. The pain comes later.
.
Rbg Holdings (LON:RBGP)
139p (up 8% at 13:37) - mkt cap £133m
On a quick whizz through, these interim numbers look impressive. It’s a legal services business, with a particularly impressive lady CEO. I took a small position a while ago, mainly on being so impressed with her presentation in a webinar, and the figures looked OK too, obviously.
Numbers today look strong, and the company’s summary/outlook is also encouraging -
"The Group has had an excellent first six months which is reflected in our revenue and profit growth. With strong demand for all Group services, we are on track to meet our recently upgraded market expectations for the full year.
While acknowledging the economic conditions continue to be volatile, we look forward to the coming months with optimism and are excited about the long-term prospects for the Group."
My opinion - I’ve not really done much work on this lately, but the figures & commentary today are enough to make me happy to continue holding a small position. I’m generally not a fan of professional services listed company, due to the inevitable conflict between remunerating the big fee earners, and outside shareholders. A lot of the legal work RBGP does is very high margin though, so there’s enough to go around. Stockopedia shows a low forward PER, and a decent divi yield.
.
Trackwise Designs (LON:TWD)
245p (down 6% at 13:48) - mkt cap £70m
Looking at these figures, I see a tiny, loss-making company. If I didn’t know the market cap, I would have valued it in single digit millions, so how the market gets to a £70m market cap, is beyond me. Clearly there must be some jam tomorrow excitement baked in to the valuation. I see from the chart that the share price went vertical in Sept 2020, usually a sign of some news considered to be game-changing. It’s certainly not fed through into the figures yet, a year later.
Last year’s profit came from a negative goodwill credit, it was loss-making on an underlying basis, as it also the case for H1 this year.
It seems quite capital-intensive, with unusually large property, plant & equipment on the balance sheet, for the small size of the revenues. Also note receivables looks extremely high, I’m not sure why.
Overall, I’m not interested in jam tomorrow shares.
.
Anpario (LON:ANP)
610p (down 7%, at 13:59) - mkt cap £141m
Healthy animal feeds sounds like a good area to operate in, given the damage being done with the over-use of antibiotics. The trouble with Anpario, is that it’s priced as a growth company, with all the valuation metrics on Stockopedia flashing red, but as these figures today confirm, the company isn’t really growing much, if at all.
Adj diluted EPS is down 7% to 10.88p for H1.
Strong balance sheet.
As you can see below, it’s taken 5 years just to grow revenues from £23m to £30m. Although note from graph 2 that the profit margin is excellent. It’s been a reliable dividend payer.
Unless something dramatic is going to change for the better, then it’s difficult to justify the PER of almost 30, for a company that’s not growing very much. Animal feeds markets must be huge globally, so Anpario is clearly a tiny, niche player.

.
Jack’s section
Character (LON:CCT)
Share price: 600p (-13.36%)
Shares in issue: 21,379,781
Market cap: £128.3m
Character Group was founded in 1991 and designs, develops and distributes toys, games and giftware. This is a cash generative company with a strong balance sheet, a history of buying back shares, and shareholder management.
But it has also had its fair share of issues - first concerns over keeping its important Peppa Pig licence led to some volatility, followed by a sales vacuum in the Scandinavian market in 2019 caused by the failure of the region’s largest toy retailer. These events led to a huge drop in price, but the group has since rebounded.

Character sources product from China, like many companies, and so there are several well known dynamics that management must currently be facing including supply chain disruption, elevated freight costs, and wider input cost inflation.
Given the recent rise, Character’s share price is arguably as expensive as it’s ever been. While this reflects a good recovery job and returning confidence, it also means the market might be less forgiving if these pressures throw the company off course.
The re-opening of the bricks and mortar retail sector in many markets has had a positive impact on sales and the group is seeing many of its brands outperform management expectations.
However, Character goes on to say, ‘the outcome for the full year has been affected by several factors… which have since deteriorated further.’ These factors are:
- Global logistical challenges (delays at ports, shipping and container shortages, exponential increases in freight rates, and increased costs of inland transportation in China and the UK), and
- Pressure on costs of production in China due to raw material and labour costs.
Together these have impacted profitability, and it’s uncertain when supply chain conditions will improve. After a lot of work from its teams in the UK, Scandinavia, Hong Kong, and China, Character believes it has limited the downside but full year underlying profit before tax for the year will come in at up to 10% less than market expectations.
The group reminds us that these expectations are for revenue of c.£140m and underlying profit before tax of c.£12.0m. If we subtract the maximum 10% to get £10.8m and apply a notional 20% tax rate, that comes out at about 40.4p of earnings per share and an FY21 PER of about 17.1x.
Aside from this, business continues. Development of the product portfolio for the new calendar year is well advanced and the reception from customers has so far been ‘very positive’. Order levels are strong and the prospects for a good sell through remain favourable.
Conclusion
It might not be news that shareholders will want to hear but we know many companies are trying to meet increased demand via a heavily disrupted supply chain. Tricky conditions.
Given the rough calculations above the shares look expensive by their own historical standards on a PE basis, especially after accounting for the increasing costs impacting on profits.
But there is a well-run business here, one prone to shocks, but with a relatively strong balance sheet (at the last reporting date, cash and equivalents of £35m covered all liabilities of £28.4m), that generates healthy levels of cash, and uses that cash to invest in the business, buy back stock, and pay out dividends. There’s very little debt, so all in all the group is well placed to ride out volatility. Communication to the market is clear as well.
Character expects to update the market regarding the launch of its tender offer later this month, so we might see further buybacks on share price weakness.
The group does say that conditions have deteriorated further though, so how these trends progress and just how far into profits they eat remains to be seen. So far, management has limited the impact and the team will presumably be doing everything it can in the months ahead.
Given the group’s prudent financial position I imagine it will survive the current pressures but as a neutral here, it makes far more sense to me right now to sit back and wait for further updates than to go fishing for shares.
Central Asia Metals (LON:CAML)
Share price: 247.5p (+6.68%)
Shares in issue: 176,026,619
Market cap: 435.7m
CAML has two key operating assets, both in the lowest cost quartile, one copper operation (Kounrad, in Kazakhstan) and one zinc and lead operation (Sasa, North Macedonia). As ever with miners, your view on the company depends on your view of the underlying commodity. The outlook for copper is certainly buoyant, given the global need for wiring.
Share prices across a number of copper miners look cheap, but their earnings forecasts are underpinned by a historically high copper price. As above, there are good reasons for a strong price, but it can’t be stressed enough that should that level come down, earnings will go down with it. It reliably catches investors out.

Nevertheless, CAML has proven itself over the years as a solid small/mid cap copper producer, expanding into zinc and lead in 2017. Sasa was quite a big acquisition which saw the group take on a decent level of debt. Strong cash flows have allowed the company to pay this right down though.

With a c5.5% forecast dividend yield almost matching its forecast PER, it’s certainly worth taking a look at.

Financial highlights:
- Net revenue +42.4% to $100.8m,
- EBITDA +51.5% to $64.4m, EBITDA margin up from 56% to 61%,
- Free cash flow +130.7% to $48.9m,
- Cash in bank up from $47.9m last December to $54.3m and net debt down from $36.2m to $10.1m, with $19.9m of debt repayments in the period,
- Early repayment of $10m corporate debt facility post period end,
- Interim dividend of 8p, up from 6p and representing 40% of group free cash flow.
A bumper period for free cash flow generation - if the group could repeat that figure for H2 then that would be a shade north of £70m in free cash flow (assuming a static exchange rate) and a price to free cash flow of just 6.2x.
Debt levels are also rapidly reducing so at some point soon the group will become net cash and the enterprise value will fall. The cash figure does include $3.6m of restricted cash.
Kounrad produced 6,214 tonnes of copper, down from 6,607 in the same period 2020. CAML says there is 140,000 tonnes remaining in this operation, so about 23 years remaining at current rates. Costs can start to rise once the low-hanging fruit has been harvested, but the group’s current position along the cost curve is reassuring.
Kounrad produced 6,214 tonnes of copper cathode during the period and sold 6,241 tonnes, generating gross revenue of $57.3m (H1 2020: $37.0m) from an average copper price received of $9,183 per tonne, 64% higher than that received in H1 2020 ($5,605 per tonne). Underlying cost inflation sees cost of sales up by 20% to $11.5m (H1 2020: $9.6m), although almost half of this increase was a consequence of increased Kazakh Mineral Extraction Tax ('MET') due to higher copper prices. H1 2021 EBITDA was $45.8m (H1 2020: $27.1m).
Sasa produced 13,807 tonnes of lead concentrate (compared to H1 2020 of 15,140 tonnes) and the River Remediation Project has been completed. The Cut and Fill project is on track and on budget for commissioning in Q4 2022.
H1 2021 gross revenue from these metal concentrates was $49.0m (H1 2020: $38.4m), up 28% on H1 2020 due to significantly higher commodity prices during the recent period. The zinc price received was on average 44% higher than the previous period at $2,829 per tonne (H1 2020: $1,964 per tonne) and the lead price 26% higher at $2,114 per tonne (H1 2020: $1,676 per tonne).
Sasa's cost of sales was up 11% to $27.8m (H1 2020: $25.1m), although 41% of this increase was currency related, resulting in EBITDA of $26.5m (H1 2020: $19.5m).
Three group lost time injuries (LTIs), no further detail given, all at the Sasa mine. CAML calls this ‘disappointing’ and says ‘lessons have been learnt from each of these incidents’.
Outlook - On course to achieve upper end of 2021 Kounrad production guidance and lower end of Sasa production guidance (which is between 23,000 tonnes and 25,000 tonnes for zinc and between 30,000 tonnes and 32,000 tonnes for lead).
Business development - this is interesting.
Management's focus on business development has accelerated during the first six months of 2021, with 18 opportunities reviewed and three discussed at length at Board level, as well as one site visit undertaken. Although there are no advanced discussions with third parties currently underway, management will continue to investigate opportunities of potential interest.
These opportunities have been in geographies including Kazakhstan, Europe, Africa and the Americas.
Conclusion
With strong demand for the metals that CAML produces, the company is in a strong position. The balance sheet is improving and some $135m of the funds borrowed to acquire Sasa less than four years ago have now been repaid. Now the group turns towards potential acquisition opportunities. As a low cost producer, it’s better placed than most to ride out cost inflation.
But so much depends on the commodity price, and continuing elevated levels are not a certainty. Management indirectly touches on this point when discussing its business development work:
Strong base metal prices have generated interest from other parties in terms of mergers and acquisitions ('M&A'). However, diverging views on long term metal outlook, that typically arise in periods of elevated near-term metal prices, have in some cases emerged and these can create differing expectations on asset valuations, making completing transactions more challenging.
So even miners have fairly divergent outlooks on commodity prices and asset valuations right now.
Putting commodity price considerations to one side, CAML does look to be in a strong position. Debt is coming down at pace, life of mines is long, free cash flow is strong, dividends are up, capital investment is ongoing, and the group is scouting out potential acquisitions.
Eleco (LON:ELCO)
Share price: 137.9p (-5.2%)
Shares in issue: 83,104,650
Market cap: £114.6m
We last looked at Eleco here, and my famous last words were ‘I’ll probably do some more work into it’. Needless to say that hasn’t happened but my general feeling at the time was of a situation worth looking at more closely.
This group was founded way back in 1895, previously a family business, and has evolved much more recently into today’s SaaS (‘software as a service’) provider with clients in the architectural, engineering, construction, and interior furnishing industries.
Eleco is transforming at pace, from a product-led company to a customer-centric business focused on higher quality recurring revenues, strong free cash flows, healthy internally funded product development, and greater customer lifetime value (LTV).
The company's ‘market leading’ Elecosoft software solutions are developed by teams in the UK, Sweden, and Germany. They cover a range of activities including project management, timber engineering, asset and facility management, and cloud-based digital marketing solutions.
The Quality Rank of 98 is an intriguing figure but the valuation is pricey: a trailing twelve month PER of 39.4x and a forecast rolling PER of 29.5 suggests strong future growth is expected at these levels. SaaS companies have recurring revenues and good earnings visibility, so it’s not unusual to encounter high relative valuations, but not all SaaS businesses deserve them.
With Eleco, it is worth noting that free cash flow is often actually higher than reported earnings. Note the more palatable trailing twelve month P/FCF metric below.

The de-rating of non-growth SaaS businesses is a risk, but if you pick the right ones then they could grow to become very big indeed, so I see the attraction. Transitioning to a SaaS model does tend to temporarily depress profitability though.
Financial highlights:
- Revenue +13% to £13.831m (+12% at constant currencies),
- Recurring revenue +8% to £7.543m (55% of total, down from 57%),
- Adjusted EBITDA +11% to £3.649m,
- Operating profit +14% to £2.366m, adjusted operating profit +15% to £2.73m,
- Basic EPS +16% to 2.2p, adjusted EPS +20% to 2.6p,
- Free cash flow -23% to £2.855m,
- Cash flow conversion down from 157% to a still strong 105%,
- Net cash up from £4.435m to £8.478m.
Adjustments exclude amortisation of intangible assets, depreciation charge and former directors' payments.
The strong revenue growth in new licence sales from Eleco’s Building Lifecycle businesses and the increase in services revenue means recurring revenue is slightly lower as a percentage of total revenue. This revenue growth should lead to a further increase in recurring revenues going forward, however.
Software - The group continues to invest in its software. Total software development spend (including both capitalised and expensed elements) amounted to £1.628m (2020: £1.623m). That’s equivalent of 12% of revenue. Software development expenditure capitalised in the period totalled £790,000 (2020: £760,000).
Transformation is now being overseen by Brigit Lenton, the incoming Transformation Director who has 20 years’ of experience. Steps include:
- The merger of Eleco's two German visualisation businesses, to be rebranded Veeuze and relaunched to its customer base by the end of the year,
- The merger of three UK Building Lifecycle businesses, due for completion in Q1 2022,
- Creation of the Northern Europe Building Lifecycle operation, which includes all building lifecycle businesses in Germany and the Netherlands,
- Expanded the focus of our Swedish Building Lifecycle operation to the Nordics region,
- Group-wide implementation of a new finance system to enable more efficient financial reporting,
- Identification of Arcon and Staircon products as stand-alone niche business areas, delivering focus and agile decision making.
Fredrik Pantze was appointed as Chief Product Officer in April to spearhead the group’s move to create software solutions based on the future needs of Eleco’s clients and to enable them to ‘make better real-time decisions’. Eleco is also searching for a Chief Technology Officer. So quite a few senior hires slated.
Software is now being sold on a subscription basis in the UK, Germany, Netherlands, Sweden and the US. The latter is a key growth territory for Eleco and the group launched Elecosoft into the Texas market as a direct sales organisation in July. The uptake in orders is expected to take time as the market presence and recognition of the brand grows. The maintenance management portfolio has also been taken into the German market.
Outlook - These projects will take time to seed but ultimately are about growth, so investors are paying a premium today for growth down the line.
The group says its transition towards a SaaS subscription model will ‘inevitably... soften revenues and profits in the short term as revenues are spread over a longer period of time and costs are added to drive growth… We therefore expect a temporary reduction in our level of profitability over the next 18 months.’
The group says ‘inevitably’ but it looks to have taken FinnCap at least by surprise. The broker has just reduced its FY22E and FY23E adjusted EBITDA forecasts by 32% and 37% respectively. They will presumably have had some guidance from management on these figures.
The broker’s earnings per share estimates now show 4.4p in FY21E falling to 2.8p and then 2.9p in the following years. While this should translate into higher customer lifetime value, lower acquisition costs, and greater revenue and earnings visibility in following years, it does raise questions over the present valuation. That’s an FY22E PE ratio in the 50s.
The company is also undergoing some major transformation projects including the digitisation of its back office systems. This should ultimately be a benefit.
Conclusion
I don’t believe a reduction in profitability was properly factored in. This is strange, as it’s known that shifting to a SaaS model depresses near-term profits while (hopefully) increasing the overall lifetime value of customers. Eleco is only part-way through this transition so it follows that near term profits might be lower.
Easy to say in hindsight I suppose, but FinnCap is paid by Eleco to produce this research so I wonder if it has taken them by surprise as well?
I’m interested in the proposition here but put off by the price and not familiar enough with the products and market to have confidence that the growth rates in c3 years’ time will be worth paying up for today.
The company is potentially attractive still, with a long heritage in its industries and a developing product suite of software services funded internally. The Quality Rank is high and the group’s cash conversion is impressive, while the net cash balance sheet is useful (although net tangible asset value appears to be negative after accounting for c£17m of goodwill and intangibles).
Revenue is forecast to continue growing. And it’s worth noting that presumably over the past year the group’s clients have faced extensive Covid-related disruption. It could be that the earnings downgrades are a red herring, with Eleco rightfully focusing on longer-term growth at the expense of shorter term profitability. The group does call it a ‘temporary’ reduction.
I remain undecided here. For now, I would either want a lower earnings multiple or higher growth rates. Reading between the lines, Eleco is asking its shareholders to be patient as it invests for future growth. The analyst consensus figures for FY21 and FY22 are presumably going to have to come down again.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

81 comments
117 thumbs ups, from 6,700 reads! Paltry. I could have gone sightseeing instead today.
7759 reads now Paul! The lack of thumbs up doesn't at all mean a lack of appreciation. The number of reads is the measure of popularity.
Trackwise Designs (LON:TWD) (I hold)
receivables looks extremely high, I’m not sure why.
This is high as it reflects some of the capex spend, here is the key section from the interim results
Capital expenditure in H1 was £8.7m including £2.7m which relates to deposits on new equipment, which is disclosed in the balance sheet as Other Receivables.
"so how the market gets to a £70m market cap, is beyond me."
The high market price reflects the potential of the companies Improved Harness Technology (IHT), (the investor meet company presentation provide good information on IHT 6.07mins onwards)
The shareprice for Trackwise Designs (LON:TWD) also reflects the recently signed contract with an UK EV OEM (which everyone knows is Arrival) to provide IHT products to it's electric vehicles - this will be worth a minimum £16m next year (and if I remember correctly over £30m over the next 4 years).
I would agree that this is a jam tomorrow company, I have invested due to the potential market size of IHT which is unknown but could be huge if they are able to sign a few more contract with EV suppliers.
Thanks smegster,
It's really helpful when people post additional info & views like that, which may not be obvious from the published accounts. Much appreciated, thanks.
Regards, Paul.
Many thanks Jack for covering Central Asia Metals (LON:CAML): the work rate effort from the two of you at the moment is phenomenal both in terms of quality and sheer content/number of companies covered daily.
Regards Andy
12 companies and over 6,600 words of analysis and insight - Subscription VFM or what
Many thanks again Paul and Jack for your quality input, I'm still working my way through it!
Nearly, it's actually 13 companies! I've ruined my holiday in Malta due to my dedication to you all!!! LOL. It's fine actually, a lovely rib-eye steak, and copious red wine has more than compensated tonight! :-)
Nobody ever seems to mention Journeo (LON:JNEO) (formally C21) (as an investor I like that there is no noise!) - They are a circa £10m transport management system provider (information systems and technical services)
They have been quietly winning contracts and today announced a 5 year software and support contract with Transdev Airport Services - a real time information system and vehicle hardware on public and staff shuttle services. This is their third airport win after Gatwick and Stanstead.
They also recently won a small contract to provide real time passenger information services for Aberdeenshire County Council and Abellio London Buses.
Seems like they are in a sweet spot at the moment and the management are doing a good job winning contracts. Anyone else holding or have a view?
Hi ben,
C21 was a dead loss for the many years I followed it - it never went anywhere - the occasional big contract, which always turned out to be lumpy contract wins. They didn't have any unique tech. Good luck with it, but I'd say you're wasting your time & energy, and better to bank the profit in this everything rally.
Happy to be proven wrong though.
Regards, Paul.
Journeo (LON:JNEO) (no position)
Hi Bsharman
From the last notes I made (March 2021), it seemed like underlying cash generation was quite paltry - c.£200k vs a £5m market capitalisation at the time (NB: today it is £10m).
Like you though I've noticed the large number of contract wins coming in, so I do like to keep an eye on this one in the hope that cash generation improves.
For now though, it's only on my watchlist.
Cheers
A
Some interesting points on wage inflation and immigration and its impact on wages I find it hard to believe that anyone can seriously think mass immigration on the scale the Uk has received over the last 25 years has not had an impact on wages it went from 20,000 net migrants in 1990 to over 400,000 in 2010 and the population increased by over 10 million from 58 million in 95 to 68 million now which seems to have been kicked off by the election of Tony Blair
https://www.worldometers.info/...
We can’t carry on trying to grow the country’s GDP by mass immigration of low skilled labour and although it may cause short term pain longer term we will have a better balanced economy if wages go up for sectors that have lagged such as HGV drivers
Timarr made some interesting points about automation and a reduction in the need for employees and that may well happen
Personally I hope that as happened with the agricultural revolution where we went from 90% living and working on farms to 1% today that new jobs will be created remember Warren Buffet talking about this
Nice results from Central Asia Metals (LON:CAML) and a good right up on them thank you Jack Central Asia Metals (LON:CAML) are the share I have held longer than any other that I still own while I have looked at Antofagasta (LON:ANTO) and Atalaya Mining (LON:ATYM) and they both are well for my copper expire I am happy to stick with £CAML
I sold some back in 2018 when it was over £3 but now own more than I ever have after topping up in 2020 and will be happy to carry on owning what I do now for the foreseeable future I think they are run in a conservative manner and have a very good management team who made a very good acquisition when it came to SASA and when they make another acquisition in the future I am sure it will be after similar due diligence
Like some other posters on here I think ESG strategy is little more than virtue signalling I do like the way Central Asia Metals (LON:CAML) supports the local community where a lot of its workers live it makes sense on every level
Just announced is a fairly substantial acquisition for Eenergy (LON:EAAS)
It is earning enhancing but there is dilution for existing shareholders.
I like this business and given the team they have in place. I think acquisitions like this will be common place.
I'm a tad surprised that no one's mentioned the Restaurant (LON:RTN) interims:
https://www.investegate.co.uk/...
Obviously dependent on no further restrictions for further growth and their concession business - airports and the like - is still badly affected.
And a nice ESG strategy review which I'm sure all posters will read avidly.
timarr
Hi timarr,
Spurred on by your comment, I've had a look at interim results from Restaurant (LON:RTN) (c.£830m market cap, after today's 10% drop).
Poor figures, but as I would expect given enforced site closures. So I think we should be largely ignoring the P&L.
Recent LFL sales look great and (like everyone else!) they claim to be out-performing the market, e.g. Wagamama +21% since re-opening.
It is pointed out that the temporary VAT cut is flattering LFL revenues. When that ends (not sure when), these big LFLs likely to abate I reckon. Also, will people be so willing to dine out in winter, with doors & windows shut? Who knows?
As mentioned many times before here, my main problem with Restaurant (LON:RTN) is its awful balance sheet. Today this is confirmed by the numbers. NAV is £424m, including intangibles of £599m! So NTAV is horribly negative at £(175)m. Oh why does that matter Paul, you old fossil, I hear you ask? Because companies with stretched balance sheets often get forced into equity fundraisings at the worst possible time, in a crisis, which is exactly what happened here - management were imprudent, and ended up having to dilute shareholders in the crisis. That would probably not have happened, if this business was run by an owner/manager.
On the plus side, current trading is good, and EBITDA expectations have been increased, but I can't find any hard numbers on that, even in the RNS or broker updates - so if you have any figures, or I've missed anything, please do leave a comment below.
Net debt is £200.3m (excl leases). There's £235m cash headroom, from large debt facilities.
Overall - as I've been saying for a while here, RTN shares looked to have overshot on the upside considerably.
If you look at Electra Private Equity (LON:ELTA) then TGIs provides a much better value way to play the recovery in restaurants, in my opinion.
Just my view, form your own, because I'm often wrong!
Regards, Paul.
Restaurant (LON:RTN) - I have said this before but the original restaurants did well being Frankie & Benny's and Chiquito. I held them from quite low down to over 600 because I was impressed with the Brunning & Price restaurants which we visit frequently, Not cheap but in the wealthy areas of Cheshire and usually very busy. I started to realise that the consensus on Trip Advisor was that the original chains were getting bad reviews so I sold all but 250 each for myself and my wife to continue to qualify for the 25% shareholder vouchers. So at that stage we had 500 shares between us worth £3,000 and now worth £500, but not to worry we have had a lot of discounts!
It seems to me that if a company can run Brunning & Price successfully and I believe also Wagamama although we don't go there, they should be able to provide decent food in the rest of the chain.
We used to go in Friday's year's ago and we preferred Brunning & Price although that may just be us, so I would say check out the food.
i am a day behind with regard to discussions ref made.com - thought i would copy my comments into todays thread - feel free to call out my made up numbers if they are fanciful or croc.
Made.com (LON:MADE)
for fun i have done back of the envelope calcs here to see the possibilities
Say they get to £1 bilion "revenue" reasonably soon (mid term)
say gross profit % after distribution costs as per interims ( interims 28.8% used)
= 280 million bgross profit before admin expenses and the rest
admin costs are tricky and is probably the key number - the latest interims had 34% and prior year was 40% - of sales.
Lets have full glass here and say they can hit 20% by the time they ramp up to 1 billion.
There is hope here in that marketing is very high - thats doing great job if its ramping up revenue and brand name - hopefully when mature % of sales spent on marketing can materially drop.
That would give us £80 mill of profit - deduct 20% tax (to generous lets preume tax cut on the way in time for the next election) thats 64 mill net profit - say pe of 25 = £1.6 billion.
current market cap = £565 million
That seems very promising IF they admin costs can trend down to 20%.
So the follow up/key question is what % of sales can they get admin costs (and the rest) down to when they hit £1 billion turnover - are they of the boohoo variety where stuff startd to nicely drop through to bottom line or more along the AO world (just noticed they actually now make profits) where all the extra sales will get eaten up in costs.
Certainly has also piqued my interest to do some further research here. Looking at price to sales Made.com does seem to be similar to boohoo (slightly more value) so if they can get a lid on admin costs and keep growth at 25-30% plus rates this one could be interesting depsite looking "expensive" on todays numbers. Lets just hope the majority of their followers on social media are real people and not bots or dopplegangers!!
hi rmillaree
The results presentation was interesting. They are obviously a pan European business so lots of scope for the growth they are targeting. It's not just a UK play. Very agile so are capable of managing the supply chain disruptions. For every stock line they have moved to a major and minor supplier, each in different locations so a lock down in one country does not scupper that line of stock which, gave me some comfort they have a well enough diversified supply to manage the volatility over the next year or so. EBITDA this year expected to move positive and remember they have £175m of net cash. Their aim is to get to £1.5bn of sales by 2025 and should achieve at least 10% at a PBT level so your back of envelope calcs probably aren't a million miles off with some conservatism built in. In my view the key is whether you think the brand and management is strong enough to continue to execute at the sales growth rates they need. In my case I looked at it recently and decided I thought the risk/reward profile looked favourable so I bought some on a 2-3 year view.
Made.com (LON:MADE)
davidjhill
Their aim is to get to £1.5bn of sales by 2025 and should achieve at least 10% at a PBT level
Cheers David thats exactly the kind of numbers i was hoping may be available - in some respects attach a p/e of 25 to £100 mill+ and thats above what i would have hoped for - practicably speaking 2025 isn't that far off so if they can get anywhere like there without having to dilute shareholders unduly this is looking a very interesting play.
I joined the analyst call yesterday and was impressed. can't find a link to a recording but the abbreviated version is on PI world as John mentions. Was surprised to see it drop but agree it does look like an interesting 3 year play
Yesterday's Made.com (LON:MADE) presentation is on PI World. It is just a presentation, no Q&A unfortunately but that does mean it's under 13 minutes.
Cheers for that John- i didn't realise Rene from Allo Allo is alive and kicking doing the Made.com presentations - thankfully i shall say zis only once.
Hi Paul, I agree with your take on Ricardo (LON:RCDO) . Investors could do well if the automotive side recovers as historically this share has traded on a high p/e, has a small moat in terms of niche expertise, and is also working in some fashionable areas like its energy and environment work.
On the other hand even before the pandemic revenue growth had ground due to a halt, primarily due to automotive issues. I note the outlook statement, despite being 3 months into the new financial year, doesn't say very much. I also feel I need more knowledge about the automotive issues in terms of what's driving lower consultancy spend - do any readers have any sense of what's happening there and what would be the drivers to recovery for Ricardo (LON:RCDO)? I don't think it is just a symptom of the current semiconductor shortage as revenue from automotive was falling in 2019.
Hi Patrick,
I pondered some more on Ricardo (LON:RCDO) after thinking out loud in the section above. In the end, I decided to do what I often do when unsure - I sold half my position. That's usually a precursor to selling all of them as it breaks the emotional link you have with a share, I find. It's not all science, buy/sell decisions definitely involve emotions as well, especially selling, which they shouldn't do, but they do.
Best wishes, Paul.
Emotional link with a share..........heresy!
Paul
In light of your comment on the ESG section of the Somero Enterprises Inc (LON:SOM) presentation I thought you might find Aswath Damodaran’s comments on ESG in today’s Musings on Markets on ESG of interest where he writes:
“More than ever, I believe that ESG is not just a mistake that will cost companies and investors money, while making the world worse off, but that it create more harm than good for society.”
http://aswathdamodaran.blogspot.com/2021/09/the-esg-movement-goodness-gravy-train.html
Regards
Michael
I thought you might find Aswath Damodaran’s comments on ESG in today’s Musings on Markets on ESG of interest
Damodaran isn't saying ESG in the general sense is a bad thing, he's saying the way it's being implemented is bad and is being driven by actors operating in bad faith:
Telling companies that being good will always make them more valuable, investors that they can add morality constraints to their investments and earn higher returns at the same time, and young job seekers that they can be paid like bankers, while doing peace corps work, is delusional.
The bottom line is that if we want to make the world a safer place we're all going to have to accept lower returns. Whether that happens because companies are forced into it by bizarre ESG accounting rules, through government dictats or because the world is going up in flames around us is yet to be decided.
timarr
Tim
I take your point. But thinking about this slightly differently, (and hopefully you'll get my drift here even if I don't manage to express it very well).......
Economic growth in the West didn't come at the expense of lower long term environmental standards. (Short term yes but long term no). So, I'm not sure that there is a strong correlation between a better world in environmental terms and lower investing returns. I.E. since the age of the industrial revolution we have managed to achieve both.
I note that the likes of James Anderson are looking towards the way in which the cost of electricity from renewables is coming down rapidly and forsee a world with cheap clean electricity. (I know that we were promised the same with nuclear and it never happened but the costs of solar and wind have dropped considerably).
So, yes short term returns may be somewhat lower until technology overcomes this challenge but longer term I don't think lower returns are inevitable.
Graham
Economic growth in the West didn't come at the expense of lower long term environmental standards.
Hi Graham
I do take your point. And longer term I'm quite hopeful, we're an incredibly resourceful and adaptive species.
However, I think we can also reasonably say that economic growth in the West has definitely come at the expense of the environment. Standards may be higher, but the costs of a carbon based economy are increasingly clear. Does anyone really believe that climate change isn't real any more?
Nonetheless, we are where we are. Without coal, oil and gas we wouldn't have been able to build out the world's infrastructure to the point where we can reasonably hope to survive and grow without those as sources of energy. We'd probably still be stuck in the pre-industrial age, eking out a subsistance lifestyle. And most of us wouldn't be here to discuss these matters.
But going forward there will be a cost in terms of economic growth in transitioning from a carbon based economy. That will fall unevenly across countries and companies. As investors we'll need to be nimble to avoid being caught on the wrong side of the game. I think the general scoffing and ill-informed 'woke' comments that usually accompany discussions around ESG on these boards show a profound lack of understanding about what's at stake here.
Personally I don't think the current approach to ESG will deliver what society needs. But it is what it is and adopting these standards carries real costs for companies and investors. So we should take it seriously while hoping for something better.
timarr
I hear what you’re saying.
I suppose that my thinking is along the lines of global warming due to greenhouse gas emissions is another environmental issue that we must overcome in the same way as we have overcome others and probably we will manage that through technology and innovation and thus economic growth will continue.
You might be interested to see this discussion on the downward trends in the cost of utility scale solar energy.
https://rameznaam.com/2020/05/...
It’s a pity that the author hasn’t got round to writing the subsequent parts and hopefully that’s not because the most recent data shows a change in the trend.
But if solar can really become that cheap it does give me hope that the living standards in some of the poor areas of Africa for example can be improved dramatically and so the burden of transitioning to a low carbon future actually might be spread quite differently to what we might think.
Its a load of old WOKE
Time will tell !
I confess to not reading the whole article. But it sounds very much to me like he's just pointing out some inconsistencies and trying to be a bit controversial.
Frankly, someone who takes the time to try and undermine ESG the way he does on the grounds of there being differences of opinion by age group or differences of performance by size of company (which he thinks smacks of large companies gaming the system) needs to to look in the mirror and ask himself what kind of a defeatist approach that is.
He concludes with this "The ESG movement’s biggest disservice is the message that it has given those who are torn between morality and money, that they can have it all"
ESG is not a movement. (Is he trying to conflate ESG with XR, Greta etc.?)
ESG is just another set of factors that may or may not be important to a company or investor but has sprung from the fact that a significant number of investors are keen to try and steer their investments towards companies that are trying to improve their environmental performance. And on the other side of the equation, companies that are concerned about reputational damage if they don't take action and much more acute damage if the factory shuts down due to lack of water for example.
And he seems to have fundamentally misunderstood the returns aspect. It's not a case of "morality and money, that they can have it all". It's a case of you can still make a nice amount of money without investing in the most polluting industries and companies.
Michael,
Everyone has their own view on ESG, so I don't want to get boxed into a corner on this.
I see many positives from pushing companies and people into being better behaved & kinder.
But also it can often be box-ticking & meaningless.
Everyone can form their own view. From my view (being reluctantly gay), things seem a bit kinder, and I'm very thankful to everyone now for making my life a bit easier than it used to be. Thank you from the bottom of my heart to everyone. My inner angst gets a little less each year.
Best wishes, Paul.
Kounrad produced 6,214 tonnes of copper, down from 6,607 in the same period 2020. CAML says there is 140,000 tonnes remaining in this operation, so about 23 years remaining at current rates.
Jack, please note these are interims for Central Asia Metals (LON:CAML) , so you may wish to revise the above calculation and note for full year production.
Thank you for the Central Asia Metals (LON:CAML) analysis. I'm not sure but I think the price was dented in this period by the war which the Kazakhs won convincingly giving a stable ? foundation for the future. They are expanding and it looks like more acquisitions will come.
Then it's buoyed by the copper price. It seems to me that this is a function of supply and demand. Supply is probably fixed short term, so what will demand be over the next couple of years ? My guess as the World recovers, is up.
So it's a punt, but it looks a lot better than a lot of punts we see, especially if you want some commodity exposure
I'm not sure what war you are referring to Shrubby re Kazakhstan. I think you must be thinking of the fairly recent Azeri-Armenia dispute that impacted companies such as Anglo Asian Mining (LON:AAZ) for a bit, but had nothing to do with £CAML.
Thanks for the write-up Jack on £CAML. I'm at a bit of a loss regarding its valuation mismatch, but that is the wonders of the market. Now its debt free it makes little sense for it to be trading at less than when it made the SASA acquisition and took on US$140m debt. Copper prices are also 40% up from that time period as well, and entering a likely period of extended favourable headwinds.
you're right...oops. AAZ
Central Asia Metals (LON:CAML) is a good little earner and Anglo Asian Mining (LON:AAZ) didn't stop paying dividends during its country's war.
I hold both, also Pan African Resources (LON:PAF) as all three are getting good stuff out of the ground and putting cash in my pocket unlike physical gold. Sure, they are subject to the whim of the PI and too small for the Institutions to much bother with so I just don't have all my savings in them.
Silver
I guess Paul you’ll have too much on your plate again to cover the Electra Private Equity (LON:ELTA) update issued this morning ahead of the Capital Markets event later today.
https://www.stockopedia.com/sh...
If so I hope you will be able to comment on a quieter day. It reads well but I found it a bit confusing which is why I’m hoping you can explain, along with your latest thoughts on whether the potential share price upside still looks as good. Seems it will be in the 4th quarter and not by the end of this one as in the original announcement but that’s no big deal.
Maybe others here holding Electra Private Equity (LON:ELTA) will post their thoughts too.
I hadn't seen this as for some reason investment trusts do not show up on the Stocko feed - would someone on the technical side be able to look into this? I missed an important announcement from Harbourvest Global Private Equity (LON:HVPE) this morning showing a 7% increase in NAV.
The announcement Ken links to is from August but the capital markets day it references is today
Apologies for posting the wrong ELTA news link earlier today. I posted in haste ahead of going out and wrongly assumed that that link was to their update today. It wasn’t because the update today is still not available on Stockopedia.
So here’s the correct link from ADVFN.
https://uk.advfn.com/stock-mar...
Thought the capital markets day was interesting and looks like Hotter Shoes is well positioned to grow substantially both here and abroad. Strong digital retail strategy - eg I liked the augmented reality on the App that allows a shopper to wave their bare feet at their smartphone camera and see what the shoes look like on; coupled with a smaller physical store footprint (sorry!!) that is focused on 3D scanning of feet and interactive shopping. Feels like they have created a high quality business capable of growth both here and abroad well into the future.
Fag packet calcs I did was around £5-6m of EBITDA this year growing at 15% for the medium term. What do you value that at? maybe £100m doesn't seem far fetched given the mid teen growth projection. Then TGIF if they are doing £40m EBIT could be another £300-400m+ market cap. Combined it does feel as though the two businesses on standalone listings should perhaps be worth a combined £400m or maybe more so I am happy to hold here looking for 1000p + equivalent across the two holdings (all things being equal of course).
David ,
Thanks for that. Although i hold £ELTA when I looked at their website a little while ago I was rather underwhelmed but i just tried the App and it's Virtual Try On gadget and it works very well . I am always amazed that every retailer doesnt have their own dedicated App.
Richard
Hi ken,
I did actually listen to the Electra Private Equity (LON:ELTA) Capital Markets Day for Hotter shoes, which will become Unbound, as a separately listed company, once TGIs is spun out shortly.
I thought it was OK. Nothing special. Unbound looks set to make £5-7m EBITDA pa, and mgt have sensible plans to expand in low risk ways into the over 55 demographic.
I think Unbound could be worth £50m+ as a separately listed company.
Mgt - generally seem OK. There was a bit too much MBA management speak for my liking. I prefer hands-on entrepreneurs. Also, the Q&A was not handled well. They clammed up & refused to answer many questions, saying it was too commercially sensitive. I think that displayed inexperience as listed company Directors. There is always a way to talk around a question, and give a sensible answer, rather than clamming up & upsetting the audience. But it's a tiny company, so I don't expect miracles from mgt, they're learning on the job, when it comes to managing a listed company, which is fine.? We'll see
TGIs is the star. Anything we get from Hotter (Unbound) is a bonus. I like the strategy, and intend running with it for maybe 2 years or so? This could become a mini SAGA, and I love the focus on over 55s, so let's see what happens. Timings dont matter.
Regards, Paul
Electra Private Equity (LON:ELTA) capital markets day today (09:30). Probable nothing new to be revealed but the RNS suggests a lot of ground will be covered regarding the name change, prospects for Hotter etc.
Placing for Jubilee Metals (LON:JLP) this morning. Disappointing that it is not available to retail shareholders but at least the discount is relatively small and the deal looks worthwhile. I like this position a lot with the significant expansion into copper and the comments this morning on developing the Cobalt opportunities although no real indication of how material that might be. The next couple of years look interesting. I hold.
What do people think about Inflation ?? I can't see an alternative to the return of inflation, during the thatcher years, pay increases were held down by fear of unemployment, before that they had tried and failed with incomes policies. Since then, there's been lots of deflation from high tech goods, but the big one, is that there was the EU, providing virtually limitless cheap labour, supressing wage increases and thus inflation. Now I'm not interested in debating the rights and wrongs of brexit et al, but to my mind the idea that unlimited supply of cheap labour, wasn't holding down peoples wages always was a lie, and has proven so in the last few months. on top of that we have the inflation caused by increases in demand in some areas, while drops in supply, and disruption of supply channels etc. Now I know some of this is temporary, and will sort itself out, but how much will prices fall back ? or will they just stablise at these higher levels ? And once people get used to this, and see how hard it is to recruit staff, what will happen then ? they'll want bigger payrises, and they'll start discussing it with their friends etc, etc, Once this expectation gets baked into the economy, it's very hard to get it out. This is all in my opinion, and I'd be interested in hearing reasons why I'm wrong, however, I'm more interested in hearing, which companies/ investments win, if I'm right ?? Any thoughts ? Surely anyone with pricing power, who can raise prices and maintain margins, is in a better position than those that can't ? What effect will high inflation have on interest rates ??? The last time that happened, there was a battle to produce returns for investors, involving property bond and some magic that made them aaa investments by slicing and dicing, we all recall how that turned out. what will happen this time ? will rates have to go up to control inflation ? and if so what happens to those with huge mortgages taken when they were so affordable (including all that help to buy debt, which the government itself has a financial interest in ????). To my mind it's absolutely crazy not to have some managed plan for immigration to cater for this demand, although obviously we need to retrain people who are unemployed to fill roles too. But where's the harm in allowing 2 year visas for 10,000 european lorry drivers while we train up more here (HGV) ???? Not sure the government is thinking this through logically.
Re. Inflation, I think the U.K. in 2021 is a very different place to the U.K. in 1979 and the prospects for wage inflation are very different. For me, the big structural change is that we’ve moved from a post-war heavily public sector focused economy where there were a number of huge employers owned by the state with monopolies in their respective markets and a political desire (from both major parties) to enforce a social contract between unions, management and the government of responsible, collective cooperation to get a fair society for all of its stakeholders. Now we have a far more atomised (and international) economy with few big public sectors (NHS and local government services aside) and for better or worse individuals being left to get the best deal for themselves in a market rather than via widespread industrial action via powerful trades unions.
Against this structural change, I don’t think the impact of Brexit on the supply of cheap labour is a major driver other than in occasional short term blips (e.g. current issues over availability of sufficient HGV drivers) and that over time supply and demand for labour are able to balance each other out. I think rising inflation rates may well be an issue but feel it is other macro factors such as rising global food/ commodities prices and the impact of years of massive monetary stimulus that will be the primary drivers.
Gus.
My local Sainsbury's has a mannequin driver dressed in hi viz tabard in its entry lobby next to a board advertising for drivers.
I suspect the Govt. doesn't want to give early on European driver visas, as this currently advantages local drivers and wages, and it doesn't want to be seen as undermining that until it absolutely has to. They will want to say Brexit has provided local jobs for local people on decent wages, if they say anything.
There has been invisible food price inflation for a while, as during the height of the pandemic it was noticeable that many food providers subtly starting altering the weight/size/price ratio of their offerings.
The jury is out on whether overall inflation will persistently increase. There are many pressures on it to do so, including taxation inputs from Govt., minimum wage etc.
I suspect the Govt. doesn't want to give early on European driver visas, as this currently advantages local drivers and wages, and it doesn't want to be seen as undermining that until it absolutely has to. They will want to say Brexit has provided local jobs for local people on decent wages, if they say anything.
It won't make any difference if they do. There are HGV driver shortages across Europe so European drivers have their choice of jobs. They'll pick ones where they have more job security than they can get with a one year temporary UK visa. The UK will have to fix its labour shortages itself, which will probably mean a couple of years of disruption. But it'll rebalance eventually.
No one really has a clue whether inflation will be persistent or not, but if it is the most likely result will be massive investment in automation. John Deere have a satellite network that directly controls farm equipment remotely, Amazon warehouses are populated by self-driving shelves that come to the packers, etc.
As the price of automation falls then the value of labour will also fall. The world is now connected, it's a very different place from the last time we had serious wage inflation.
timarr
One estimate says there are 90,000 vacancies in the UK. Since the start of the pandemic 15,000 EU workers left while 50,000 UK workers left the profession. Last year there were only 25,000 people taking the test vs 70,000 on a normal year. There are 120,000 vacancies in Poland. Brexit and COVID have complicated recruitment in this sector. There is competition for drivers in the form of courier driver jobs.
Apparently it only takes 8-10 weeks to obtain a HGV license:- https://www.hgvt.co.uk/how-to-... (it is interesting to note that this website references a newspaper article from 2018 indicating shortages of 45,000 drivers)
Anecdote: my friends younger brother is being offered £20k while training on a HGV and £50k when qualified.
Anecdote: my friends younger brother is being offered £20k while training on a HGV and £50k when qualified.
All of which, of course, increases the price point at which an autonomous vehicle would be economic. Obviously we're still years from having driverless HGVs on our roads, but it will happen at some point.
In the meantime trained drivers are quids in. And good luck to them.
timarr
I think I've found the missing HGV drivers - they are all nose to tail on the M62 between Manchester and Leeds in both directions !!
I would think that the government will want to see what the unemployment level is after the furlough scheme ends on 30th September. It would be odd to bring more people in from the EU while paying people here to do nothing. That will mean shortages on the shelves for some time I expect.
I did see a story about a former EasyJet pilot who is earning more now as a HGV driver so there is some scope for people to retrain but lots of delays in training and getting licenses.
I think jobs that have to be done here will be better paid than before. Wherever that labour can be substituted by imports that will tend to keep costs down. Thinking of Easy Jet I saw they recently turned down an approach from Wizz Air. I'm pretty sure Wizz will be able to recruit pilots at lower cost in Eastern Europe than Easy Jet will be able to do here as an example.
But even with 20% pay rises companies are not getting any applicants for drivers jobs, according to the news. Also farmers are wasting loads of food because they don't have enough staff to pick it. Most of these jobs were done by eastern Europeans.
It is the same in hospitality sector, companies can't get any staff .
This may change when furlough ends.
As for inflation it could get worse, have you seen how much your energy costs have increased, my 1 year contract finishes in January, looking at alternative I was shocked how much they have gone up, cheapest quote is up 56% on my current plan.
Oil prices have increased which will cause inflation due to transport costs.
From the latest numbers I can find there are still about 1.6 million people on furlough. I have no idea how many of those will be looking for new jobs when the scheme ends. I don't even know how many are still in the country as it was perfectly legal for people to collect furlough pay and head back to their home countries.
Will central bankers raise rates?
They might…. already they’re getting more hawkish than recent times, they need to start appearing like they are tightening monetary policy fairly soon in the face of rising inflation - is it transitory? I have some doubts, so we need to focus on the inflation adjusted ‘real’ interest rate which is currently very negative. If inflation continues to rise more quickly banks could raise rates and the real interest rate remains constant or even more negative depending on speed of both increasing!
If the central banks stay ‘behind the curve’ does the party in equities and commodities just continue in the face of rising rates?
Interesting that as wages are now rising more steeply in the U.K. so is taxation; in the current environment it seems like taxes will be used as a ‘wage control’ tool while the debt is inflated down somewhat.
I see what you mean about invisible food inflation, packs of tomatoes in Tesco which used to 6 are now only 4 in a pack, same price, they are larger but the quality is very poor, shipped from Spain.
Also remember that individual households adjust our own inflation rate. E.g. these days I am moderately affluent, but because I was desperately poor from 1992-5, and 2008-2012, I learned money-saving habits which have changed my behaviour forever. For example, if a bag of veg is over 99p. I refuse to buy it. I'll cycle to Aldi, and fill a rucksack with fruit, veg, and noodles, for about £12. Even if I've just made £50k on my portfolio that day. It's mad. Maybe it's the fear of losing everything again? also I dont want to let down the next generation, who Ive promised things to.
P.
My local Asda is the same, I guess the government are betting that wages will go up, and at some point the supermarkets will recuit drivers, and send some of their more experienced drivers off to hgv training, to resolve the problem. I think it would help if they did something to incentivise this or make it easier. Lets be honest, driving is a skill, but most people can do it, driving a van is not so skillful, obviously hgvs are much harder, but still a learnt skill. There are many unemployed people who could be trained to do this, I spoke to a chap who has an hgv licence but doesn't use it, and has friends in a similar situation as they dropped out when they could get better paid jobs elsewhere. Now considering a return. of course all of this is short term, self driving is coming, how long will it be ? I don't know 10 years ? 20 years ? a
Jack - you are completely missing the net cash position of Character (LON:CCT) in your analysis.
it trades on a cash adjusted PE of 8 !
Would be weary when doing your cash-adj calc that c.£17m of the net cash increase at interims were due to falling inventories and receivables which are now well below historic averages
Hi Paul , have a good final day in Malta. I flew out there from UK when i was 17 to join HMS Eastbourne . I can remember cheap wine and bad hangovers. I can imagine its much changed now.
Hi Pete,
Hi Paul , have a good final day in Malta. I flew out there from UK when i was 17 to join HMS Eastbourne . I can remember cheap wine and bad hangovers. I can imagine its much changed now.
How marvellous! The red wine is fantastic here in Malta, and nothing that 2 siestas cannot resolve the next day!
I feel almost turbocharged! WFA (working from airbnb) is the way forward, I think!
Incidentally, I wandered into what I thought was a gay pride demo. but then saw a "health apartheid" banner, and realised I'd wandered into some anti-vaxx numpties! Dear oh dear. There are complete fools everywhere, sadly! Natural selection will sort that out, but it's the problems it causes for everyone else that bothers me.
best wishes, Paul.
A most bizarre reaction to Character (LON:CCT) very mild profit warning. Profits will be no more than 10% below expectations despite all the headwind we already knew about in the supply chain and raw material inflation. Thus EPS is expected to still be 40p. But what people miss is the Cash..... 40% of the market cap is net cash so the fair value impact on the share price should be only around 6% ! This trades on a cash adjusted PE of 8 already with a tender offer to come.
Outlook generally looks positive for this years portfolio of products.
Only 20,000 shares traded mind so also looks like this is all an illiquidity discount rather than a rational reaction.
Hello David, I'm struggling to get your figure of 40% of market cap? What is the cash position now?
Many shares are being marked down even after better than expected results so I'm not surprised the shares are down.
market cap is £120m now and cash should be around £40m so it's about 33% now. Mkt cap was a bit lower earlier but nonetheless is about 175p of the share price. Character (LON:CCT) are highly cash generative.
The point really is not what others are doing but relative value. You can't say they are on a PE of 15 and look fully valued without taking into account the cash position. Once you strip that out it sits on sub 10 PE. I'm not surprised to see the shares down but not by 20% for what is a 6% downgrade, that's leveraged by 3* the actual position. Many shares being marked down after good results is because their valuations were ahead of themselves, it's not the same comparison.
A tender offer is coming next month as a use of the big cash pile so it is being returned. Presumably the tender will be at a significantly higher price than this otherwise they wouldn't do it, which makes the 20% fall a more bizarre overreaction in my view.
Tinybuild Inc (LON:TBLD) - has bought another, more violent than the past, title and half dozen software engineers, highly acquisitive and works with them for a couple of years before stumping up so know what they are getting.
Eleco (LON:ELCO) - powerproject and construction visualisation products seems a nice 'coffee can' with growing revenues.
Trustpilot (LON:TRST) - seems to be stable after IPO. Still making a loss but market does not seem bothered but lets see today. Not sure a coffee can yet but do see it everywhere so the brand is strong.
What put me off Trustpilot (LON:TRST) was that it has been around for ages (14 years) and is still not turning a profit. Makes me question if it ever will.
Private companies don't like to pay tax. Revenues are rising so maybe profits will come around when they feel the needed to attract investors - like flies to the honeypot.
Talking of Malta, De La Rue (LON:DLAR) has announced a significant expansion of its operations in conjunction with the Maltese government at no additional cost to the company's turnaround plan. Clive Vacher, the CEO sounds brimming with optimism in the announcement.
De La Rue (LON:DLAR)
jonno
"Talking of Malta, De La Rue (LON:DLAR) has announced a significant expansion of its operations in conjunction with the Maltese government at no additional cost to the company's turnaround plan. Clive Vacher, the CEO sounds brimming with optimism in the announcement."
Thanks for that jonno , i have shied away from this company in recent times as it temporarily seemed to turn into a bit of a basket case. I wander now if all the issues they had are firmly in the past now ? does anyone know if they still have any specific legacy issues left or material contracts that may end soon or any other nasties in the cupboard? - - oh dear it looks like the pension scheme here may rule me out - scheme assets and scheme liability of £1 billion apiece is too much for this to be investable for me "probably" (why take the risk with plenty of shares to choose from) - thats a shame as the pe of only 10 does look cheap - now i understand why its cheap.
Note i do have large holding in norcross which also has has "the pension noose" around its neck. As a quick comariosn - it looks like De La Rue makes slightly more profit that norcross (looking into the future not dodgy recent past) - however the size of the scheme assets and liabilities at De La Rue is nearly 3 times the size of what Norcross have - Clearly different level stuff potentially . I am also happy that Norcross pension liabilities have peaked too as its a mature scheme compared to most - their "scheme liabilities" have reduced from £467 mill in 2017 to £417 mill in 2021. Having quick look at De La Rue it looks like scheme liabilities have also decreased but not sure if they may have been forced to pump a wad of cash in to make that happen?.
If anyone thinks that De LA Rue pension scheme is less of an issue than it looks at my intitial fisrt glance i would be interested to know.
Ah, Paul, tell me about it, there is no peace to be found.
Rbg Holdings (LON:RBGP) group unaudited results -
o Group EBITDA margin up to 28.1% (2020: 22.0%)
· Group profit before tax up 279% to £3.9 million (2020: £1.4 million)
· Group profit after tax of £3.1 million (2020: £1.2 million)
· Group earnings per share up 157.0% to 3.47 pence (2020: 1.35 pence)
Yes Interims from Rbg Holdings (LON:RBGP) look good and I thought better than in line although it is a bit difficult to work out exactly with Memery only included since May. I'm hoping the presentation on Investor Meet Company at 11 this morning will clarify that. Convex seems to be doing well and perhaps we will get a bit more colour on the Litigation side then as well.
The SP reaction has been good. I hold.
And a couple more:
Epwin (LON:EPWN)
Solid set of interims this morning , nothing really jumps out solid trading , supply chain issues and price inflation - just look at the price of resin ! Up 80% strewth.
Happy holder here at present not exactly a bargain but they strike me as being well run company with solid enough niche that their customers simply come to them. One issue is how they would do in a recession - probably very poorly but as a retailer they should be able to pull through in that regard.
Debt coming down very nicely and they seem to be self funding for future growth from existing finances - so new outlets and small bolt on acquisitions etc should keep turnover ticking up even if existing stuff only tracks inflation. They seem to be investing well to ensure their production is done efficiently as possible.
Character (LON:CCT) trading update (I hold): we expect the Group's underlying profit before tax for the year ended 31 August 2021 to decrease by no more than 10% of market expectations
Sell on profit warning, or buying opportunity? Be glad to hear Paul/Jack comment on the situation.
I know its not Paul's bag but if Jack is around any chance of a ramble on Central Asia Metals (LON:CAML): divi up 33%, early repayment of corp debt facility, free cash flow more than doubled, net debt reduced from £36 million to £10 million.