Small Cap Value Report (Wed 16 Mar 2022) - RTN, EYE, SAG, ANP

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
Agenda -
Paul's Section:
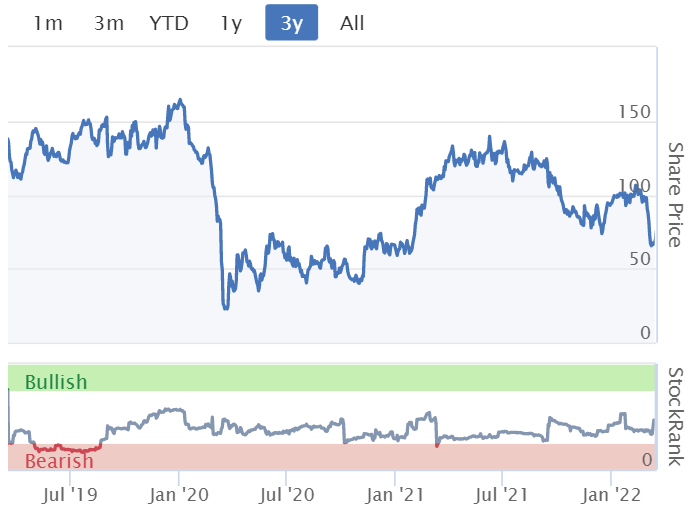
Restaurant (LON:RTN) shares are up 10% on FY 12/2021 results. Current trading in 2022 looks strong. I'm not happy with the balance sheet, despite a big equity fundraise. Shares look to be a forecast PER of about 20 for 2022, which to my mind seems too high, given all the macro uncertainty & squeeze on household incomes.
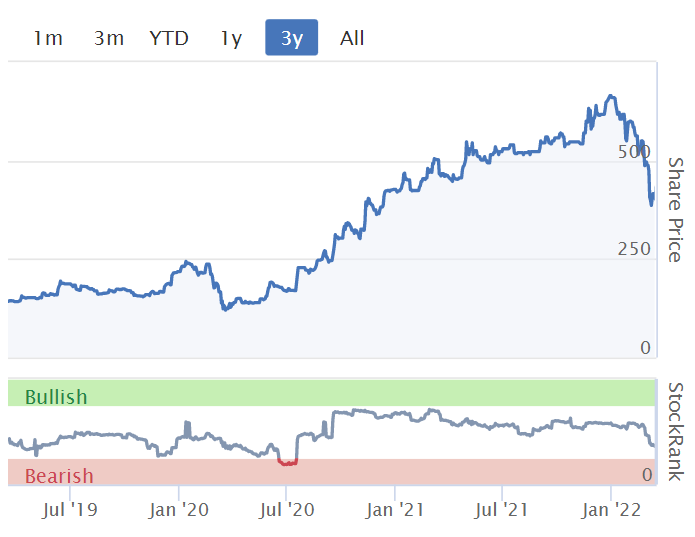
Eagle Eye Solutions (LON:EYE) - decent interim results show a move into a small maiden profit. Despite correcting in value by about a third, it's still expensive. However, there's nothing wrong with the company, so I'm inclined to look at the sharp price drop as a potential long-term opportunity for growth investors.
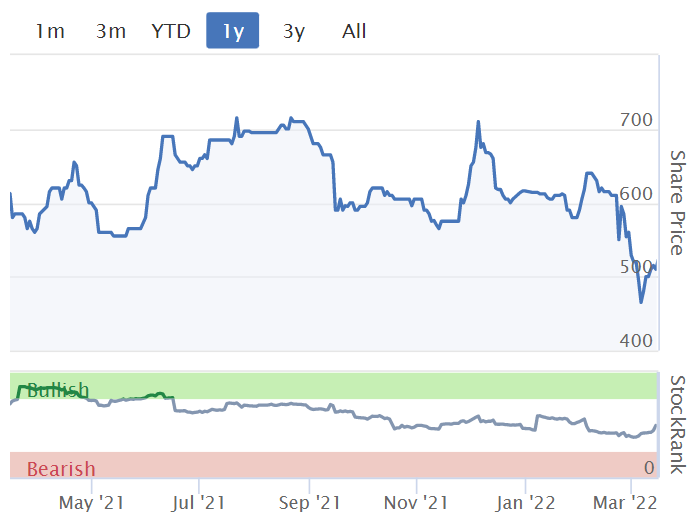
Anpario (LON:ANP) - 2021 results are out today, and look reasonable. The way I see it, the share price has corrected from excessive, to just about reasonable now.
Jack's section:
Science (LON:SAG) - record FY results following multiple upgrades, with funds for organic and acquisitive growth. The valuation is not overly expensive, particularly when coupled with the positive trading momentum and underlying profit margins, so worth a closer look.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Restaurant (LON:RTN)
70p (pre market open) - market cap £533m
As at 2 January 2022, The Restaurant Group plc operated approximately 400 restaurants and pub restaurants throughout the UK. Its principal trading brands are Wagamama, Frankie & Benny's and Brunning & Price. It also operates a multi-brand Concessions business which trades principally in UK airports. In addition the Wagamama business has a 20% stake in a JV operating five Wagamama restaurants in the US and over 50 franchise restaurants across a number of territories. The Group employs approximately 16,000 people in the UK.
Results are for the 53 weeks ended 2 Jan 2022 (which I’ll call FY 12/2021)
As with Hostmore (LON:MORE) (I hold) which we covered here recently, FY 12/2021 was a year that was badly disrupted by the pandemic, with trading largely shut down until May 2021, but with generous Govt support measures offsetting some of the losses. Hence it’s difficult to draw much in the way of conclusions from these numbers.
Revenues £636.6m (up 38% on LY) - but still impacted by enforced closures in the early part of 2021
Adj operating profit of £42.8m, but there’s a large finance charge, so adj Profit Before Tax is only £16.6m, which doesn’t seem much.
Current trading - RTN's LFL revenue growth in 2022 (see table below) look way ahead of the disappointing -3% recently reported over the same period by MORE.
However, I’m wondering if the reporting basis is different? I’m told that MORE seems to normalise VAT over this recent period, but it’s not clear if RTN is doing the same, or letting it boost the numbers? I suspect the latter.
Revenue is always stated ex-VAT. However the 12.5% reduced rate now, against comparatives that had 20.0% VAT deducted, will significantly boost the current period's ex-VAT numbers. For example, gross sales of £100 would be revenue of £83.33 when VAT was 20%, but the same sale of £100 would b e £88.89 if VAT is 12.5% (the current rate until 31 March 2022). That's a 6.7% boost to ex-VAT revenues, for the same gross sales value. Hence to get a true LFL performance, we should be normalising VAT, by reducing the figures below by 6.7%, which for example would reduce Wagamama's LFL sales growth this year from +21% to about +14% - still excellent, it has to be said.

.
Outlook -
c.95% of electricity and gas volume hedged for 2022
o c.75% of electricity and gas volume hedged for 2023 and 2024
· Management's current expectations for FY22 remain unchanged, although we are mindful about the consequential inflationary impacts arising from the conflict in Ukraine
Balance Sheet - has always been my main gripe with RTN.
It’s still negative, once you strip out £600m intangibles, which takes NAV of £439.7m down to NTAV of £(160.3)m - which means the business is heavily reliant on debt funding, which I very much do not like.
IFRS 16 lease liabilities are showing a deficit of almost £121m. These numbers should improve over time. I’ve noticed that, at the moment, with uncertainty over site profitability, lots of multi-site operators seem to be publishing gloomy IFRS 16 numbers - i.e. a low asset figure, with much larger liabilities figures. Hence why I tend to remove the IFRS 16 numbers from the balance sheet. The old system was so much better, where an onerous lease provision was required for loss-making sites, which gave us the key information needed.
Net debt of £171.6m doesn’t sound too bad, but the gross long-term debt of £318.1m stands out as being too high. The cash pile of £146.5m could be a seasonal high, who knows?
Overall then, this is certainly not a strong balance sheet, but doesn’t look alarmingly weak either. Given our experience with covid, I think it’s better overall if companies pay down debt, so that they’re not reliant on the vagaries of Govt support measures, and the lenience of the bank manager, if something similar happens again.
Note that RTN raised £175m in fresh share capital during the year, so the balance sheet would have looked terrible without that cash injection. More shares means lower EPS of course, in future.
My opinion - current trading looks impressive, much better than Hostmore (LON:MORE) (I hold) recently reported, although it’s not clear if the figures are comparable due to VAT concessions. This is the trouble with LFL (like for like) figures - there’s no standardised definition, so different companies calculate the figures their own way, and don’t always make it clear how the calculations have been done. The glossary definition of LFL here doesn’t mention VAT treatment, which is a significant boost to ex-VAT revenues, if not adjusted for the current reduced rate. Hopefully we might get some clarification on this.
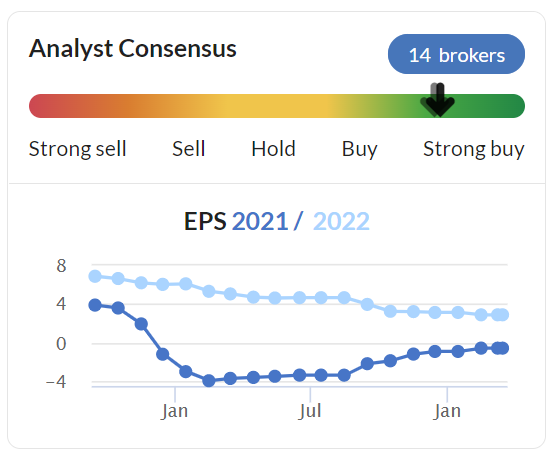
I can’t find any broker research on RTN, so that impedes any assessment of value in the shares. However, the Stockopedia consensus figures show a considerable reduction in FY 12/2022 forecasts, as you can see below. With all the additional cost pressures coming through, it’s difficult to see much value in this share.
Hostmore (LON:MORE) (I hold) is on a much cheaper rating, but its current trading figures were poor, so that puts a question mark over whether it can achieve forecasts for this year.
The whole sector has been savaged, due to the current pressure on consumer disposable income, due to higher inflation, and especially higher household energy bills. That should all come out in the wash, so it’s always worth looking at this sector when valuations are depressed, because in recent years we’ve seen how inflationary pressures tend to abate once they annualise, and incomes rise again. I’d rather buy when the sector is out of fashion, and valuations are low, rather than paying top whack when everyone’s comfortable and applying a high PER.
With consensus EPS below 4p for FY 12/2022, and a share price currently up 10% at 77p, that looks a PER of 20. How does that make sense, given that we know household discretionary spending is coming under pressure? It looks too expensive to me. You need to be very confident RTN can beat expectations, if you hold this share. I wouldn’t want to bet on that, given macro conditions at the moment.
.
.
.
Eagle Eye Solutions (LON:EYE)
434p (up 8% at 08:30) - market cap £113m
Eagle Eye, a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing through coupons, loyalty, apps, subscriptions and gift services, is pleased to announce its unaudited interim results for the six months ended 31 December 2021 (the "Period").
Strong financial performance and record new business pipeline
This is a decent little growth company, generating strong organic growth, and a high level of recurring/repeating revenues. The client list is very impressive too, with big supermarkets and other retailers using EYE software.
It’s just broken into a maiden, small profit (ignore EBITDA, as it’s meaningless for companies that are capitalising some of the payroll).
So there’s no doubt the company is doing well, as always the question is what’s it worth? Historically the valuation got way ahead of itself, like pretty much all growth shares. After a large correction, is it now a bargain at £113m market cap?
.

.
Outlook - sounds good -
· Entered the second half of the year in a strong position, as shown by the considerable increase in ARR
· Positive trading in Q3 to date, in line with the Board's expectations
· New business pipeline continues to grow at record levels, both in the UK and internationally
Forecasts - many thanks for Shore Capital for an update note today, available on Research Tree. It pencils in 4.8p EPS FY 6/2022, rising to 8.2p and 10.4p in subsequent years. Therefore on a conventional PER valuation metric, at 434p per share, you’re being asked to pay a heroic multiple of possible future earnings. The hope must therefore be that it beats these numbers.
My only thought on that, is I’ve noticed habitually loss-making small caps, when they do finally break into profit (as EYE has just done), have often been operating on a shoestring, and tend to have multiple pent up demands on expenditure - e.g. deferred pay rises, staff having to multitask to save money, outdated equipment needing replacement, etc. Also management often like to “invest” the proceeds of growth in higher sales & marketing spend, etc. Therefore the much vaunted operational gearing can prove to be somewhat elusive, in my experience, with costs often rising almost as fast as revenues.
For that reason, it wouldn’t surprise me if EYE out-performs at the top line in future, but might not become as profitable as investors imagine. That’s just a guess of course, outside investors don’t have a clue what’s really going on at any of the companies we invest in. You need to be an insider to really understand any company properly, there’s so much hidden below the surface.
My opinion - even after a market-wide correction in growth company valuations, EYE still doesn’t look good value, let alone cheap.
However, I think it’s an unusually impressive organic growth story. Therefore, if you like the business, which is performing well, then it makes a lot more sense to buy now at 434p, than the optimists who paid as much as 660p in the excessive bull run in 2021. The story hasn’t changed, but it just got a third cheaper.
Overall then, for growth investors I do think this share is worth considering. Although in a bear market, it might get cheaper again, if there's another panic market-wide sell-off. So buyers now have to be be steely-nerved. I like the idea of buying in 3 tranches over time, so that there's some dry powder to deploy when other people are irrationally panic selling.
.
.
Anpario (LON:ANP)
537p (up 5% at 09:43) - market cap £124m
Anpario plc (AIM:ANP), the independent manufacturer of natural sustainable feed additives for animal health, nutrition and biosecurity is pleased to announce its full year results for the twelve months to 31 December 2021.
These numbers look respectable -

Note that the gross margin fell, with the company not able to fully pass on cost increases -
...however gross margins were lower at 48.7% (2020: 51.9%) compared to the same period last year impacted by increased logistics costs and significant raw material price inflation, which was partially mitigated with sales price increases during the year.
Profit rose mainly because Anpario was able to hold administration costs level with last year.
Overall it looks a beat against expectations, with consensus showing 21.5p, and actual coming out at 23.0p. I can’t see any updated broker notes today.
Ukraine - sales to Russia/Belarus/Ukraine have ceased (insignificant, at <1% of total).
“No dependency” of supplies from these countries.
Outlook - some interesting points in this, and overall strikes me as reassuring -
The Company is maintaining the progress of last year and the priority is to pass on raw material price inflation through planned sales price increases. We are seeing some encouraging signs that cost price inflation has begun to stabilise but given the very live events in Ukraine there could be further challenges in global supply chains and energy markets which may affect raw material prices. The significant increases in grain prices will also present difficulties for our customers, however, Anpario's products improve animal feed conversion rates through natural gut health improvement making the animal more efficient in nutrient utilisation.
We look forward to delivering profitable growth for the year, capitalising on the investments made in new products and significant market opportunities such as aquaculture. Investment and development in our sales and marketing channels will continue with the recruitment of local sales teams which will be helped by the improving international travel situation enabling our sales teams to drive business development initiatives in person.
Our geographic and product diversity does help the Group smooth out these disruptions and our strong balance sheet enables us to invest not only in innovative natural product solutions but also support our delivery service levels with good local stockholding. We remain confident in capturing the opportunities to grow the business both organically and by acquisition, should the opportunity arise, for the long-term benefit of all stakeholders.
Balance sheet - is superb, very strong for the size of company. It includes a cash pile of £15.5m, with no interest-bearing debt, just small trade creditors.
There’s scope for the company to do something with its cash pile, even take on a bit of debt, given its reliable profits & cash generation.
So hidden value here.
Note that inventories rose substantially in the year, which seems to be linked to ensuring continuity of supply.
My opinion - in the past I’ve questioned why Anpario was rated so highly by the market, despite profits having been essentially flat around the £4m level since 2015. The price has come down in the recent general small caps sell-off, which is encouraging for anyone considering a purchase. Not so nice for existing holders though.
Its products seem very niche (revenues must be a negligible proportion of a huge global market), but high margin.
If we assume modest earnings growth to say 25p in 2022, then the PER is about 21.5 - and we can knock off say 10% for the surplus cash pile, so a n adj PER of about 19.5 - not exactly a bargain, now that we’re in more bearish market conditions.
That said, I’ve always quite liked the potential at Anpario. Imagine if one of its products really starts to grow rapidly. Then it could hit that golden patch, where earnings start to rise rapidly, and the PER expands as it’s perceived as a growth company. In that upside scenario, the share price could conceivably double, or more. Yet the downside looks reasonably well protected by solid performance. So risk:reward looks reasonably good, providing nothing goes wrong.
Overall then if you understand the sector, it might be an interesting one to investigate in more detail.
.
.
Jack’s section
Science (LON:SAG)
Share price: 396p (+4.21%)
Shares in issue: 45,615,876
Market cap: £180.6m
Results for the year to 31 December 2021
- Revenue up 10% to a record £81.2m,
- Adjusted operating profit +49% to £16.3m (another record),
- Adjusted basic EPS +47% to 28.5p,
- Recommended dividend increased by 25% to 5p,
- Cash of £34.3m and net funds of £19.0m.
Science Group is an international science, technology and consulting organisation. The Group comprises three divisions: R&D Consultancy; Regulatory & Compliance; and Frontier Smart Technologies ('Frontier'), together with significant freehold property assets and a strategic shareholding in TP Group plc.
R&D Consultancy - provides science-led advisory and product/technology development services, applying science and engineering capabilities to the medical, consumer, food & beverage, and Industrial, Chemicals & Energy markets. Revenue here grew from £32.2m to £34.3m and the new, unified brand approach (‘Sagentia Innovation’) should bring additional cross-selling opportunities.
Regulatory & Compliance - provides scientific and regulatory advice together with registration and compliance services for the Chemicals and Food & Beverage sectors. This division generated revenue of £21.4m (2020: £20.1m), of which around 25% is recurring. Management says increasing scale and reputation is attracting larger opportunities.
Frontier Smart Technologies - the market leader in DAB/DAB+/SmartRadio technology chips and modules (formerly listed on AIM and acquired in 2019).
The Frontier division had a strong year in 2021 reporting 21% growth in revenue to £24.9 million (2020: £20.5 million) and an adjusted operating profit margin of 21% (2020: 16%), producing a 59% increase in adjusted operating profit. This success was achieved despite the global semiconductor and other supply chain constraints.
Conclusion
Another record performance, the company is clearly doing well at the minute which makes the recent share price pullback more interesting.
The balance sheet is strong, with cash resources and an undrawn new debt facility providing the potential for further acquisitions. This positive update follows several upgrades made over the past year, with strength reported across all parts of the business.

The forecast PER multiple of 14.1x isn’t overly demanding given the operational momentum and good profitability metrics.

I’ve not spent much time on SAG in the past and so am not too familiar with the business model. Things are clearly going well though, with healthy margins, and an undemanding valuation, so it’s putting itself forward as a strong candidate for further research, I think.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
I own shares in both Luceco (LUCE) and Volex (VLX).
Both have been absolutely hammered by the market over the last six months - with share prices trading 40% worse than their market ( mid caps). Even at these levels the shares are very volatile - eg today have risen 10% and 7% respectively , presumably on positive ukraine peace talks ? To my knowledge, neither have issued profit warnings over that period and both appear to be well run businesses.
Can anyone shed any light on what is driving the harsh market sentiment ? Many thanks
Where to start :) .......
I don't hold either stock but like both. If I recycle any money in the near future I will likely buy some of one, probably £VLX or maybe both.
Markets rallied today mainly because China have hinted at a big stimulus package. The market likes this. It also went up because whilst war in Ukraine is ongoing the signs are that a deal inches closer but I don't think that was the overriding factor today. Finally rates rose in the US by 25bps. As expected, signals FED believes they can get inflation under control with 6 progressive rises or another 1.5%.
Luceco (LON:LUCE) and Volex (LON:VLX) have been hammered for several reasons in my view.
Started with worries over supply chains and warnings that this was causing a few problems. Then came inflation and expectations rates would rise, thus discounting future profits particularly where they supply future markets like EVs. Then came war in Ukraine where the worries were around spill over to rest of Europe or WW3! Finally China started locking people down again on covid threatening supply chains/production.
It was a bit of a perfect storm. Small caps get hammered with uncertainties like this and that's what has happened to many stocks irrespective of earnings. It is primarily retail investors selling into very little buying so prices just keep going down. Particularly as the MMs have turned from liquidity providers to matched brokers, ie holding no stock. Any hot money was buying oil and commodity stocks so others were unloved.
Hope that helps.
Thank you DH, I really appreciate you time and thoughts
A couple of comments :
David,
I agree with your comments but would add that SP’s had definitely got ahead of themselves in a lot of Small Caps , priced for perfection and not inflation.
Richsrd
Continued strong growth and improved margins at Eenergy (LON:EAAS)
This is small and speculative but what they provide is becoming more relevant and important by the day.
Continued strong growth and improved margins at Eenergy (LON:EAAS)
This is small and speculative but what they provide is becoming more relevant and important by the day.
For the same reasons I bought Inspired (LON:INSE) recently.
Having taken a quick glance at eEnergy's investor relations page I was surprised at the heft of the BoD. An impressive bunch. I'm not really convinced that "light as a service" is a better solution than hiring a specialist to specify the relevant capital expenditures before installing oneself - thereby owning all the savings instead of handing over a high proportion of them to eEnergy - but I can see the appeal for certain businesses.
SP is not daunting but liquidity is very thin. And this innovation cannot be compared with software as an asset-light, high margin proposition. Nor is there any IP to form a moat so the business is extremely vulnerable to copycat competition. All that said, looks an interesting little business that should be able to grow profitably.
It's too illiquid for my portfolio rules but I enjoyed the browse - thanks for the tip
Hello BnB, all very well re Inspired (LON:INSE) but where is it going? The SP pattern looks like a range of severe constipation to even more severe diarrhea and back again......and all for a measly 2.5% divi. Cant we all find better? Stick some money into a company like Somero Enterprises Inc (LON:SOM), or a thousand more (many of which I have missed over time!) and watch the divi and the SP gains pour in, then buy some more on the dip. Just an observation, having looked at Inspired (LON:INSE) many times and read their endless RNSs on reorganizations, changer of directions etc.
Hello BnB, all very well re Inspired (LON:INSE) but where is it going?
Inspired looks to me to be a stock that was seriously overvalued at times - thereby distorting the relationship between SP and earnings - but whose revenues and profits finally meet a depressed valuation just as they potentially start to get a shift on. Anticipated margins meanwhile suggest a business with a PER around 20x, nearly double its current level - provided execution builds confidence - and that's the big unknown.
As to what role it plays in my portfolio, I already hold Somero (and Volex and Luceco and Calnex and Halma, not to mention tons of high growth tech stuff) so I'm happy to have a steady plodder in the mix, particularly when, thematically, it fills a hole in my allocation.
Continued strong growth and improved margins at Eenergy (LON:EAAS)
This is small and speculative but what they provide is becoming more relevant and important by the day.
Paul Scott wrote today "I spotted large buys of that size in £VLX".
Paul Messrs Molloy and Rothschild bought 740k and 340k of Shares in £VLX on 14 Feb but did you see what they paid? 25 pence per share!!!
I think I would spend £85k if I could buy them at that price.
Molloy’s wife purchased 95000 shares at £2.62 on 14 March in Volex VLX - publicly available information here on Stocko.
As the saying goes DYOR !!!
If that is the case is indeed as we say in Yorkshire “a right royal piss take”
Rothschild for sure with his vast wealth does not to be part of a share scheme that enriches himself purely at the benefit of the shareholders he should be proudly building wealth for .
There is a gravy train at the station but he already is in the first class wagon so should not be rubbing it in .
If he is writing cheques out at market price , or putting in incentive plans to reward hard working employees that don’t have funds to deploy fair enough but when already seriously rich directors award themselves freebies it really is just , well it’s basic theft .
planetx,
If that is the case is indeed as we say in Yorkshire “a right royal piss take”
Re Volex (LON:VLX) - would you mind checking the facts before you spout incorrect nonsense like this please in future. That's what I do. Always check the facts first. Then form an informed view. Then have a think about it. Only then publish your view. Oh, and admit it & withdraw it, when you've got it wrong.
Thanks, Paul.
P.S. Invoking Yorkshire doesn't help either, apart from if you're making me a cup of tea ;-) (GOLD, if you can stretch to it, but Red label is fine for a less formal occasion)
Hello Portugull, and Paul, I got caught on one of these some months ago when, without doing sufficient research, I noticed that the founder of Joules (LON:JOUL) had 'bought' 100,000 an extra shares. I was quite positive at the time and topped up my holding, then soon after they fell through the floor. The 'purchase' was in fact either at no cost or 1p or something similar!!! Caveat emptor!
Well read the RNSs more carefully then, ridavies! You've been around for long enough here to avoid daft mistakes, surely?
Are you on a wind -up ? 25p is PAR value
Hi portugull,
Paul Messrs Molloy and Rothschild bought 740k and 340k of Shares in Volex (LON:VLX) on 14 Feb but did you see what they paid? 25 pence per share!!!
I think the 25 pence refers to the nominal value of the shares.
We need to read RNSs quite carefully. The one I was referring to was this - where 25p nominal value shares were bought recently by a Director in the market at 261.98p per share.
I do check things before posting anything about it, you know!
https://www.stockopedia.com/sh...
Paul.
No they got them for 25p, in February 2022.
For Paul (since he has mentioned this) and others,
There is a really good recent full access interview by Grant Williams with Luke Gromen about recent events and their long term effects. Worth a careful listen. I'm just copying over here:
My guest in the latest episode of The Grant Williams Podcast is my good friend, Luke Gromen, publisher of Forest For The Trees.
With events in Ukraine happening at breakneck speed, the moves by Western nations to isolate Russia through a series of escalating sanctions have revealed weaknesses in the global financial system that bring into sharp focus a set of dominos Luke has been lining up for a number of years.
The dollar's place at the heart of the financial system is now under serious threat after the sanctions placed on Russia's central bank have fired a warning shot across the bow of every other central bank in the world.
What does this mean for gold? Oil? Bond markets? Currencies? Luke lays it all out in brilliant fashion as he explains why the moves of the last two weeks have changed the financial world as we know it forever.
Alpha Fx (LON:AFX) some excellent results today, PBT is up around 94%, I see that is is now a small cap, maybe worth a look.
In bear markets, I find it pays to follow decent sized Director buying - i.e. £6-figure purchases in small caps are usually meaningful, and not done for show.
I spotted large buys of that size recently in Volex (LON:VLX) (I hold) and Purplebricks (LON:PURP) (I hold - small, speculative position only).
Another thing struck me this week, when skimming through the RNS - there are so many companies buying back their own shares right now. I see that as a generally positive thing.
Regards, Paul.
On the topic of strong director buys, one of the interesting ones is Itv (LON:ITV) ...
Their share price tanked after they announced results. The results were good, but their guidance on their key focus over the next 1-2 years, to invest in launching a new streaming service (to compete against the likes of Netflix, Disney+, etc) completely tanked the share during the market turmoil.
However, as you can see, some widespread and strong director buying, at quite decent levels. Of course, ITV directors are paid well, given the size of the company, so their purchases are not big compared to their annual renumeration.... but some of the purchases are still quite sizeable, and collectively quite a decent sum.
(I hold)
Dear Mr Scott,
What does PER mean?I know it's not a intelligent question.Do you feel we should invest in energy as recommended by some.I feel this is one variable in the entire equation that needs to come down as inflation can be controlled by it.Low energy cost plays an important role in controlling inflation along with interest rate.
Thank you
PER = Price Earnings Ratio or PE ratio
sadly,
You did the intelligent thing and asked rather than remain ignorant.
If you go to the Stockreport page of any company share and click on the 'blue text' of the PE Ratio, PEG Ratio, EPS Growth etc for example, a window will open that is full of information that explains exactly what it is.
Hope that helps, regards Neville
If you click on the click on the blue "title" of figures in Stocko. (any of them :) ), it gives you the definition. When you click on PE(ttm). you should be taken to this page...
https://www.stockopedia.com/ratios/price-to-earnings-ratio-ttm-723
Hi sady,
Dear Mr Scott,
What does PER mean?I know it's not a intelligent question.Do you feel we should invest in energy as recommended by some.I feel this is one variable in the entire equation that needs to come down as inflation can be controlled by it.Low energy cost plays an important role in controlling inflation along with interest rate.
Thank you
I always worry when anyone calls me "Mr Scott" - often a sign of trouble ahead ;-)
As regards abbreviations, several readers have asked me to avoid or reduce using them, but it's so difficult to get the balance right. Please do feel free to ask - or just google the abbreviation (which I have to do frequently in RNSs) - a good example today was Hostmore (LON:MORE) (I hold) referring to "QSRs" - industry jargon for "quick service restaurants". But I didn't know what it meant, as I have to look at dozens of sectors, so find it really thoughtless when people in any industry use abbreviations which generalists like me don't necessarily know.
As regards the other part of your question, about investing in energy, that's beyond my remit here. It's up to you to decide what sectors to invest in, etc. All we do at the SCVR is try to dissect company trading updates & results. I've got no idea what sectors might do best in the next year or two, I don't possess a time-travelling space capsule, and hence can't report back from the future!
Regards, Paul.
Inchcape (LON:INCH) yesterday belatedly announced their strategy regarding their remaining Russian operation (which nonetheless comprises 10% of group sales and 5% plus of group op profit). But they failed to use English to descrie their moves. They are going to "transition" it - which could mean a variety of measures. If I held it, I would be cross. But like many UK plcs with Russian operations it is difficult to see them extracting some hard currency out of any closure or sale.
£HL.
Centralnic (LON:CNIC) open offer
Rant alert !!
In the above open offer i applied for my entitlement plus a modest number of extra shares in my HL ISA account. By return i received an email telling me I did not have enough cash to cover the cost! After wasting loads of my valuable time trying to get through to HL. I eventually get a reply very calmly telling me that they dont know why they sent that email to me. Just a word of warning to anyone thinking of opening an account with Hargreaves Lansdown (LON:HL.) . . . . . . DONT .
Richard
Make a formal complaint to their compliance dept. I had issue with IG but ended up with a good result in the end. They should rectify the issue - it will take months though.
Wolf,
I have lost count of the time i have wasted doing that with HL, they take the 8 weeks that the FOS allow them to reply to a complaint and then write to you saying ' it wasnt our fault guv' .
Hopeless.
Yet HL are far better than IG are generally. It has taken IG nearly 4 months to resolve a simple matter of converting over shares in one ETF to another one, because of the delay I have lost about 20% of my money. It took over 20 emails before they did anything.
If it helps, mMy experience of YouInvest has been much better than both of the above. On the few occasions over the last 5 years when things have gone wrong, they have taken ownership and fixed quickly.
I sent AJBell an email about a week ago about opening a SIPP and they still have not replied, not very encouraging.
I have been holding back on updating the Stockopedia community on the outcome of my complaints to the Financial Ombudsman about similar poor service from platform providers until the compensation was safely in my bank account. I'm not quite at that point yet but I will post at much greater length as soon as I am. However, what I will say at this point is that the Ombudsman found in my favour in all of my claims for consequential loss against platform-providers and that they have accepted the Ombudsman's verdicts and the mechanism for calculating that compensation. The quantum runs into tens of thousands of pounds.
However much we take it for granted, we are, indeed lucky in this country, to have the type of checks and balances that the Ombudsman services represent to hold businesses to account. I would urge people who believe that they have suffered material financial loss as a consequence of incompetence by platform-providers to raise a complaint with the Financial Ombudsman's service. While it took some time for me to reach the point where a case handler was assigned to look at my complaints, I have found their service subsequently to be knowledgeable, considerate and communicative.
I suspect that platform-providers make a calculation that takes into account a very low level of pay-outs from cases taken to the Ombudsman when deciding how much to invest in their administrative resources. If that calculation were to change as a consequence of losing many more cases that are taken against them, they might make the decision to allocate more resources to administration leading, ultimately, to a better service for all.
Taking a complaint to the Ombudsman is simple and free and merely requires good record-keeping and some simple calculation skills. I am happy to be contacted by anybody who would like further information in advance of me posting at length about the detail of the cases.
good news, well persevered ( if that's a word :-)) )
I have a feeling it is all to do with WFH.
High Dicktrade. I do sympathise. Had a problem with IWEB a couple of years back. Dreadful customer service. Took about 9 months to get all the money and shares out and a pathetic amount of compensation. I complained to Lloyds the parent company and they hadn't even heard of IWEB. About sums up both organisations.
I pay a bit more in trading with Jarvis (I dont hold their shares!) I nearly always get to speak to a human being quickly if needed. I applied for all excess in (CNIC.L). They even advised me that I could have my entitlement in the ISA transferred to my nominee account as I did'nt have any free cash left in the ISA . Not really worth loosing sleep over. As always you can usually buy below the placing at some stage, and indeed you could have done a couple of weeks ago. They are only a few pence above now. Compared to where they could be this time next year not significant for one of the fastest growing tech companies in Europe. Change your broker. Its small hassle but worth it in the long run.
I had the same email from HL. Sounds like someone there put the decimal point in the wrong place.
They sent me a similar message and wasted my time too
Anpario (LON:ANP) Decent results from a long term holding. Hefty increase in dividend a sign of confidence, also £25k going to Ukraine relief. Sales growth has been a struggle last few years, but they do seem to be gathering momentum and balance sheet looks bullet proof to me. Any observations from Paul/Jack welcomed
Nice company Anpario. Lots of good things to say about them. But worry if with inflation rising they can drive profits from where they are. In normal times under recent valuations they justify a pe over 20 times but not so sure going forward.......
RTN - outperforming restaurant chain - they own Wagamama
here's one huge advantage over the competition
- 95% of electricity and gas volume hedged for 2022
- c.75% of electricity and gas volume hedged for 2023 and 2024
how many restaurants can say that?
Hello Darren23, Hostmore (LON:MORE) can I believe though their recent sales have been sluggish. Products too expensive?
Upbeat statement from Gym (LON:GYM) (I no longer hold but used to)
Membership numbers growing well and end to Covid restrictions should keep that going in my view. They operate at the low cost end of the gym market so it will be interesting to see how a squeeze on disposable incomes due to inflation will hit them. On the downside, the customers are not locked into a contract but on the upside gym membership is seen as almost a necessity by many and they should pick up new members trading down from more expensive competitors.
However, my spider-sense is tingling, and not in a good way, over this
“New technology platform launching in April 2022 to drive website traffic, engagement and conversion”
and
“Brand transformation commencing Spring2022 to support membership recovery and future growth”
They already prided themselves on their use of technology so why is there a need to spend money on a new tech platform with the associated risks of implementation?
Brand transformation sounds like a substantial commitment in time and money with a very uncertain outcome. Large bills can quickly accumulate with this kind of thing and achieve very little. Admittedly, I have always felt that the name ‘The Gym’ just doesn’t pass some of the basics that a brand name should such as being distinctive, although I can see that they might have been trying to imply that it was a gym that does all the core activities well and doesn’t bother with peripheral stuff.
However, they have built The Gym as a brand over the years and to change it now is going to be very expensive. So, I really question whether a brand transformation is needed and is going to be financially worthwhile.
Gym (LON:GYM)
So, I really question whether a brand transformation is needed and is going to be financially worthwhile.
Well it does kinda suggest all the effort building up the brand as they have wanted is wasted if they need to tranform it , so i would agree slightly strange and somewhat worrying/perplexing comments. Perhaps a bit to frank if i am being honest. To me every decent brand should be continuously evolving rather than needing 5 yearly reset in ideas - unless its broke of course ! . I know nowt about branding - perhaps it does work like a basic pub refurb in that maybe peeps do like shiny new stuff ?
I have held Gym in the past and could buy back in but it has certainly been knocked for 6 with covid. The main issue with Gym is that the brighter future is always in the future rather than now with this company. Sales projections trends are always positive (covid ignored) but the reality of the delivered numbers has not as of yet been great - cant blame them for covid though thats for sure.
Spiders can detect danger coming their way with an early-warning system called eyes. But that's not all: their most important source of information about the world and its hazards comes from highly sensitive hairs that cover the bodies of most spiders.
I've not got much hair, so will rely on Stocko and the SCVR and the meat pies.
Hi
Bit above SCVR level, but might to useful to some to look at. Ip (LON:IPO) strong results today. Also, I do not see why many of the headwinds in the markets would be too detrimental to £IPO. Its reported NAV for its year end 167.0p is around 80% higher than current share price.
Some might be interested (I hold).
Regards
Howard
Morning Howard
Thanks for the alert. Ip (LON:IPO) results not showing on
www.investegate.co.uk
I have had to go to the corporate website to find them. I hold and added recently.
Hi jonno
Glad that was useful.
I picked it up from the Stocko Newsfeed which I scan first thing as it often has several snippets not on www.investegate.co.uk
I call it up in each of my portfolios and therefore see items related to any of my holdings. I find it really helpful to alert me to things of interest.
For any newbies interested, open your portfolio, click the 'News' selector just above the chart and any items related to your holdings will come up. I usually ensure my portfolio is only showing live holdings to keep it focused. But if you have closed holdings if you have those also showing then their newsfeed items also appear.
Regards
Howard
Re the Ip (LON:IPO) RNS not showing on Investegate, I have noticed this a few times recently with companies I either own or follow. I have no idea why.
Just be aware that NAV was 31 Dec. A lot of rerating in tech since then.
Any idea what the current NAV would be?
Hi wolfspirit
Yes that is true.
But I am slightly encouraged that several other similar PE/VC type companies share prices seem to be rising from recent lows as well. Suggesting that sell offs in these particular types of companies were in part market sentiment and now investors are returning to them for their underlying growth potentials.
In addition to £IPO I hold Harbourvest Global Private Equity (LON:HVPE) Hgcapital Trust (LON:HGT) Molten Ventures (LON:GROW) Halma (LON:HLMA) £MNTN and all have had improvements against recent lows.
Could be dead cat bounce of course, so I'm being cautious. We shall see.
Regards
Howard
Hi Howard and Wolfspirit,
I did hold IP Group, but sold two months ago on account of the price seeming to perform in-line with, or worse than, the Oxford Nanopore price. At my last check, IP Group still held 10% of ONT, and my interpretation was the market price of IP Group tended to follow ONT's price.
ONT has fallen 40% since 31 December, and IP Group's share of that fall they say is GBP 233m - which comes out at about 13.4 % of NAV, which would still equal a very healthy 145p or so of NAV. This is without taking anything else into account such as change in senior mgt. (an unknown, could be good or bad), completion of GBP35m share buy back at prices below reported NAV (good), and the valuations and funding achievable in the private equity market (no idea).
However, it looks like they have a decent amount of cash that needs a home so they could potentially pick up some bargains in the private market now, who knows. A genuine science-led company might be less likely to suffer from the issues caused by the Ukraine war (apart from valuation), and could potentially help solve any problems that have arisen because of it (food, materials, energy etc.).
Thanks
Chris
Hi Chrisfarrell21
Those are useful points about £IPO many thanks for posting them.
I too think Ip (LON:IPO) and other investing companies who invest in both the private and public markets might have good conditions to pick up some interesting and future valuable companies. I am quire cautious about Ip (LON:IPO) though as it has lagged alternatives such as Harbourvest Global Private Equity (LON:HVPE) Hgcapital Trust (LON:HGT) for example, quite considerably over past years.
Regards
Howard
I calculated the fall in value of Oxford Nanopore Technologies (LON:ONT) for Ip (LON:IPO) . IPO owns 82m shares in ONT. At 31/12 ONT worth £572m @697p a share and now worth 428p today so a fall in value of £221m worth 21p to IPO's NAV.
Yeah, I think we have 1p difference in our calcs., I had a 22p fall. I took the GBP 233m straight from today's IP Group results which I'm assuming would have used yesterday's ONT closing price to calculate the difference.
Cheers
Chris
[duplicate deleted]
£SAG Excellent results as anticpated I still can't understand why Stockopedia has held estimated profit figures well below the anticipated figures per trading statements, perhaps now they can be adjusted to reflect the true position.
It’s not Stockopedia (they just grab market data via Refinitiv) but rather, it is the broker(s) who need to upgrade forecasts which in turn will be reflected in the market data.
Stockopedia my outsource provision of the data but they do not outsource their responsibility for the data they present to be accurate and up to date. That is the service we pay them for, is it not?
Have they failed to capture broker upgrades for Science (LON:SAG) then? (As per the OP)
Science (LON:SAG) (I hold)
I'm generally very happy to have a pop at broker figures - as except for passing through managment expectations I don't place much faith in them. In this case I'm not sure.
The year end trading update in January upgraded to
revenue in excess of £80 million and adjusted operating profit anticipated to be in the order of £16 million,
The consensus of two brokers figures (still) on the stockreport are for 80.3m revenue, 28.3p adj eps, dividend of 5p and net profit of 7.7m with upgrade history clearing showing upgrades through the year including January.
The broker figures agree - surprisingly to me - with the results today except the net profit which came in at 9.56m - and to be fair the company did not guide on net profit in the trading update. I'm not surprised at that - as the current tax charge of 4.2m (including the 1.8m tax on the property transfer I assume) was reduced to around 1.4m primarily through a deferred tax credit. I'm guessing that the brokers assumed that the 1.8m might have to be paid. I did as the company warned on a likely charge. The new CFO seems to be earning his keep?
Given that I don't have much faith in broker figures - I'm struggling to find much to complain about here? Maybe I've missed something?
cheers
Mark
PS - happy with the results today. But for me this is all about how they manage to scale the operation - scaling consultancies can be very hard to do. You have to keep finding ever more brilliant above average staff without scraping the barrel from a limited talent pool, If you don't have better consultants than your competition where is your edge? So its all about how they execute with Frontier and whatever the diabolical* plan for TP Group turns out to be (* 'diabolical' according to some upset shareholders in TP Group that is). Promises to be an interesting ride.
Science (LON:SAG)
Hi Mark
Many thanks for providing explanation above okay it does make more sense to me now with regards to draft figures.
My guess is that Science (LON:SAG) will tempt any worthwhile consultants away from Tp (LON:TPG), and leave the potentially profitable engineering part to stand alone
EC,
you beat me to that comment. True.
EC
Are you saying that Stocko is incorrectly reporting brokers estimates (which would be a fair complaint) or that Stocko is reporting poor quality brokers forecasts, which end up being proved wrong , - which is clearly a ridiculous complaint to make at Stocko.
peterg,
I think it is quite clear that my comment is about Stockopedia being responsible for the accuracy and timeliness of the data, rather than the accuracy of the broker forecasts represented in the data.
Hi EC,
I know you like to be quite sweeping with your statements, but please bear in mind that a lot of brokers actively hide their forecasts, and try to stop their forecasts getting into consensus numbers.
There's a lot more behind the broker consensus numbers than might meet the eye.
It'a a very frustrating area, one which I frequently chase up with Stocko HQ, but perhaps you could have a discussion with the green blob, to ask why figures might look wrong (often because a broker is withholding info) before blasting the team who are trying their best here.
Bottom line is this - the smaller the company, the more difficult it can be to find broker forecasts. Even then, they're often wildly wrong. So don't shoot the messenger maybe, who are trying their best, and rely on third party data sources which are not perfect, due to many key brokers concealing their forecasts and only giving them to paying clients.
This issue drives me mad. Maybe we should just ignore broker forecasts, and do our own, which is sometimes what we have to. But if profit is (say) 5% of revenues, and revenues drop significantly, or costs go up significantly, then profit could go all over the place. It could even turn into a loss, when operational gearing is taken into account. Very difficult to forecast numbers without knowing the ins & outs of a business.
P.
Hi Paul,
I'm not sure why you think I am "blasting the team"; I don't think that my posts do that at all. I do actually use the green blob to follow up on specific issues that I know about and have found the guys to be responsive in getting them fixed. However, I only know about issues in cases where I own (or am considering owning) shares and have managed to source the broker forecasts myself. That is a tiny proportion of the whole. Since errors in this small population have been quite frequent, I worry about the wider accuracy. Incidentally, none of the issues I have reported have been due to brokers withholding info - if I can get hold of their research, Refinitiv certainly can!
More generally, however, I have been disappointed with Ed's contributions to discussions in this issue, which I interpret as blaming the service provider. I do not believe this is appropriate.
You suggest that "maybe we should just ignore broker forecasts and do our own". That is broadly my approach. However, I value the broker forecasts for two reasons:
All the best.
Fevertree Drinks (LON:FEVR)
Year end results with trading update today ref 2022 , whilst they are doing a decent job todays announcement contains downgrade for current year (ye 31/12/22) estimates for EBITDA
expected ebitda 2022 now 63-66 mill compared to late jan update expected 69-72 mill - with sales guidance unchanged. Due to input cost pressures no shocks here.
So thats nearly 10% of the bottom line (fake one) - in the 6 weeks since the end of january.
Looks like the near term updates may separate those companies that can pass on cost inflation and keep margins in check and those that can't. These numbers which is quite rapid worsening in 6 weeks do kinda back up recent stockmarket price weakness does have some logic to it rather than being bargains galore - unless these headwinds turn out to be short term. I am much less hopeful in that regard than i was 6 months ago. Short term if i am adding i think i want to buying quality (ref margins-busines model) from here on in temporarily rather than something that seems to be cheap.
Fair play to fevertree ref clarity they simply give us a range of numbers so at least we don't have to mind read directors waffle on top. Simple method that should be employed by every company every time they update in year. sales ann ebita or underlying profit range please - thank you very much.