Small Cap Value Report (Wed 17 August 2022) - BOO, PURP, COG, MOON, CINE, GHH, GATC, CFX, MYSL

Good morning from Paul & Graham! Today's report is now finished.
Agenda -
Paul's Section:
See the reader comments section below, where I put up brief comments first thing, covering (as I hold these shares, I see their news first, from email alerts) -
Boohoo (LON:BOO) (I hold) - acquires 7.1% strategic stake in Revolution Beauty (LON:REVB) a few days ago.
Cambridge Cognition Holdings (LON:COG) (I hold) - announces involvement in a drugs trial with Oxford University, in which it says take up of a new voice-based testing service has been good.
Purplebricks (LON:PURP) (I hold) - another big Director buy from the Chairman, might be significant, who knows?
Moonpig (LON:MOON) - I got an email telling customers to order early, due to Royal Mail strikes. Could this damage its business, if strikes remain unresolved?
Mysale (LON:MYSL) - breaking news! Mike Ashley's Frasers (LON:FRAS) has announced a 2.0p cash bid for the company (an Australian flash sale eCommerce business). This is a 25% discount to yesterday's closing price. Although as FRAS points out, the price spiked up from 1.25p when FRAS popped up with a new 28.5% stake in MYSL on 1 July 2022, which I covered here. MYSL is a serial disappointer, so I'll be really glad to see the back of it, and not to have to waste time covering its future updates. As an entry into Australian markets, it makes much more sense for MYSL to be consumed within FRAS's vast empire, than try to operate on a standalone basis, which has tried, but failed.
Bigger sections:
Cineworld (LON:CINE) - finally concedes that it needs to restructure its technically insolvent balance sheet. The only surprise is it's taken so long. Looks like a debt for equity swap is being considered, which "will likely result in very significant dilution of existing equity interests in Cineworld". We've been warning here for a long time about this high risk share, which is a good example of why highly indebted companies are best avoided. Especially in an economic downturn.
Gattaca (LON:GATC) - an in line trading update, but forecasts had previously been slashed to only breakeven. Clearly something is wrong with this business, as it operates in the staffing space for STEM skills, which is a lucrative area for competitors. New CEO & CFO were appointed in April 2022, so I look forward to hearing their turnaround plans. Finances are secure, and there hasn't been any dilution, so this could be a promising platform to start a turnaround. I'll monitor it more closely in future, as I can see speculative potential here.
Colefax (LON:CFX) - stellar results for FY 4/2022, but the outlook comments make clear this was a one-off bumper year, with a variety of factors meaning profits are likely to fall this new year. Although it could surprise on the upside, who knows? Lovely balance sheet, and it seems to collect in cash on delivery, rather than offering credit to customers - so trade receivables are small, and result in CFX sitting on a big cash pile, that it's been using to buy back a lot of its own shares. Very nice company, but share price probably now up with events, in my view, after a great run up.
Graham's Section:
Gooch & Housego (LON:GHH) (£165m) - a profit warning for G&H after the promised H2 recovery fails to materialise. If management’s narrative is to be believed, the order backlog provides for excellent prospects next year and beyond. I’m inclined to believe that the problems being encountered are indeed of a temporary nature. Indeed, given the size of the backlog, my instincts are to treat G&H’s current problems as growing pains: if they can rise to meet these challenges (especially their challenges in recruitment and retention), they will have a larger and more successful business. The market cap is now only around 11x the broker estimate for next year’s adjusted PBT. So if you can give the company the benefit of the doubt for next year, these shares are starting to look a lot more interesting from a value perspective.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
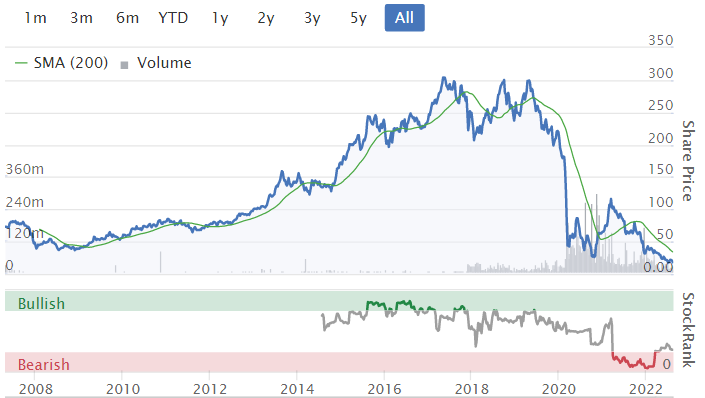
Cineworld (LON:CINE)
13.2p (down 37% at 08:18)
Market cap £180m
Update regarding current trading, liquidity position and capital structure
Key points are -
“Gradual recovery of demand” since re-opening in April 2021.
Recent admissions have been below expectations, due to limited new film releases (expected to continue until Nov 2022)
Trading & liquidity impacted “in the near term”
Taking “proactive steps” to cut costs & save cash.
“Evaluating various strategic options” to obtain more liquidity, and restructure balance sheet debt “through a comprehensive deleveraging transaction” - i.e. a debt to equity swap - “likely result in very significant dilution of existing equity…”
Day-to-day operations should not be affected.
My opinion - none of this should come as a surprise, because CINE has been operating with a ridiculous, over-leveraged (that’s putting it mildly) balance sheet for some time. We’ve been ringing the alarm bells about it here for a long time.
For example, as at 31 Dec 2021, NAV was $345m, but that included $5.3bn of arguably worthless goodwill and other intangible assets. Write those off, and NTAV was negative at $(5.0)bn! How is that even possible?!
Net debt at Dec 2021 was $4.8bn - when a company owes its creditors this amount, then it’s the creditors who are in charge effectively, not equity holders. When control slips away from equity to debt, it usually ends in a near, or complete wipe out for equity, unless they’re prepared to stump up fresh cash in a meaningful way.
Hence being long of this share was just idiotic. Or based on pure hope that lenders would continue rolling over the debt, and the company could trade its way out of trouble. Although that was never likely, given the huge scale of finance charges, as lenders tend to increase the cost of debt as it becomes riskier.
All that remains to be seen now, is how brutal the debt holders are in the negotiations to swap debt for equity. I would argue the equity is likely to be worthless as things stand now, so the only reason debt holders would be kind, is if existing shareholders stump up a significant amount in a refinancing. For existing holders, it probably makes more sense to just ditch whatever is left, and move on, and maybe take a refresher course in understanding balance sheets, because there was nothing subtle about the risk here, it was obvious.
To be fair, the pandemic didn’t exactly help, but CINE was set up for failure before that, due to a reckless acquisition strategy that involved taking on ruinous debt.
Well done to shorters here, that was a logical trade, and required patience too. I don’t do shorting any more, because it’s so difficult, and share prices of distressed companies can behave in a completely irrational way - I remember both Thomas Cook, and McColls roughly doubling in price, shortly before they went bust. Hence shorters can be stretchered off just due to the irrational volatility. And what if you’re wrong? Then you could face being on the wrong side of a multibagger.
Another reason to avoid shorting, is that you can’t guarantee that the position would stay open. Shorts are often closed out, because the lender of the stock calls it in, at a time & price of their choosing. It’s very specialised, and high risk, so for most people I think shorting is definitely best avoided. Leave it to the experts, and even they get burned badly every now and then.
.
.
Gattaca (LON:GATC)
75p (up 3% at 10:11)
Market cap £24m
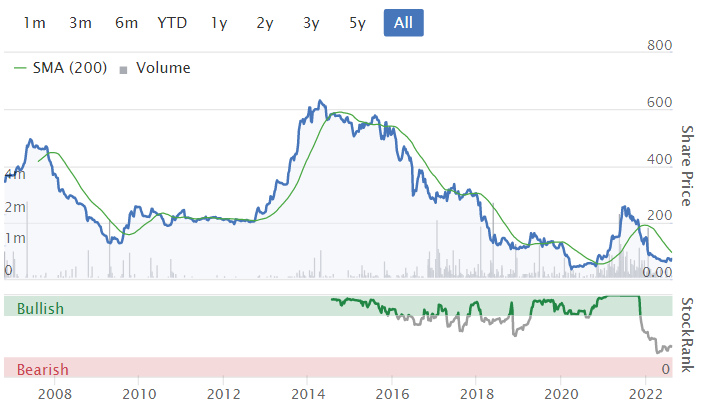
A dire long-term share price performance from this serial disappointer staffing group.
Forecasts have crashed this year, as you can see from the brokers consensus graph -
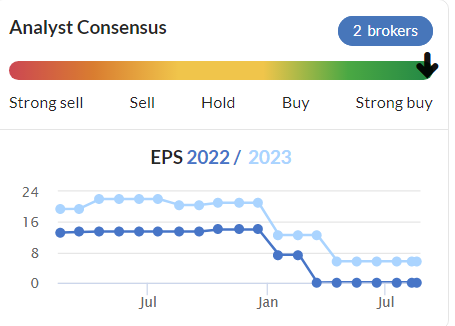
This is despite the staffing sector generally performing well, and other (better) companies performing ahead of expectations, so GATC’s problems are obviously internal, and have been for several years - profitability crashed before the pandemic.
On the upside, the share count has remained static at 32m over the last 6 years, so that means in theory, were the business performance to turn around, then the share price could recover well, back to previous highs since there's been no dilution.
Another positive is its strong balance sheet. Price to tangible book is actually below 1, not something you see very often in this sector.
.
.
Gattaca plc ("Gattaca" or the "Group"), the specialist Engineering and Technology staffing solutions business, today provides the following trading update for the 12 months ended 31 July 2022.
Company’s summary -
Trading in line
We expect our continuing underlying PBT for the full year to be in line with market consensus of break even
More detail is provided, but it seems irrelevant to me. The only question, is why this group is not making any profit, given tight labour markets, when competitors are doing well?
Looking back to its H1 results,the “continuing underlying” PBT was a £(0.3)m loss. So achieving breakeven for FY 7/2022 implies that H2 was a slight improvement, to a £0.3m u/l profit. Not madly exciting, but at least the trend is moving a little in the right direction.
Net cash position - looking good, at £12m at end July 2022. That’s down £2m on a year earlier, but includes payment of VAT arrears of £5.6m. That means net cash is half the market cap. The low finance charge on the P&L (last interim accounts) suggests that the net cash position is probably maintained most of the time throughout the year.
I see from note 9 (interim results) there’s a huge £75m invoice financing facility with HSBC. So plenty of headroom there to cope with intra-month working capital movements.
Balance sheet - Writing off £4m intangible assets take NAV of £31.4m down to £27.4m NTAV, a healthy position. The structure of the balance sheet is good - with a decent working capital surplus (current ratio was 1.47 - comfortable), and no long-term debt.
Outlook - sounds quite encouraging - although I wonder why management is pleased with performance that is only breakeven? They shouldn’t be! -
Matthew Wragg, Chief Executive Officer said:
"We are pleased with the performance of the Group through the second half of the year and importantly the speed in which the business is embracing our four strategic pillars; increased external focus, improved culture, operational performance, and cost rebalancing. We have established a solid foundation from which we can grow, leaving us well placed as we enter our new financial year, which has started well.
"We are mindful of the current macro-economic conditions as we continue to see robust demand in our key markets. There remains a shortage of candidates which plays to our key strength of deep knowledge and understanding of our sectors and niche STEM skills. We remain confident that the long-term fundamentals in our core STEM markets provide an exciting future for the business as it returns to growth."
My opinion - management sound a bit complacent to me. Being pleased with breakeven, doesn’t impress. GATC focuses on STEM skills (science, technology, engineering and mathematics) which is a booming area. Much larger competitor SThree (LON:STEM) makes a decent enough profit margin in this sector, where GATC makes nothing.
If GATC managed to increase its profit margin to a similar level as STEM, then this share would be a multibagger.
It’s adequately financed, so waiting for a turnaround doesn’t carry dilution risk.
I see that Matthew Wragg became CEO in April 2022, being an internal candidate. The CFO was also replaced at the same time with another internal candidate.
It’s too early to judge whether the new management are any good. Let’s hope they get some webinars going for us, so we can hear their plans, and ask Q&A.
Overall, I think GATC shares look quite appealingly cheap, for a potential turnaround. Although there’s not yet any evidence that a turnaround is actually happening, as it’s early days for the new CEO/CFO. Let’s see what they can do.
.
Colefax (LON:CFX)
808p (up 3% at 12:12)
Market cap £64m
(for the year ended 30 April 2022)
Colefax is an international designer and distributor of furnishing fabrics & wallpapers and owns a leading interior decorating business. The Group trades under five brand names, serving different segments of the soft furnishings marketplace; these are Colefax and Fowler, Cowtan & Tout, Jane Churchill, Manuel Canovas and Larsen.
My notes here in April on the “ahead of expectations” trading update are a useful quick refresher.
I guessed that EPS for FY 4/2022 might come out at 75-90p, when market consensus was 68.6p. The actual out-turn revealed today has blown the doors off, at 102.5p (up 127% on LY). That’s a cracking result.
Revenues up 31% to £102m
Pre-tax profit up 100% to £10.8m (helped by operational gearing, and a one-off big contract)
Share count - very unusual, in that Colefax has significantly reduced its share count with buybacks & tender offers (11m in 2016, now down to 8m shares in issue). That’s worked out tremendously well, and really shows the value when a decent business that’s on a low rating, uses that cash to buy back shares, thus enhancing EPS in future.
Modest divis though, only 5.2p for the full year (0.6% yield)
CEO owns 19% of the company, lots of skin in the game, which we very much like here at the SCVR.
Outlook comments - I like the measured tone here, clearly guiding us towards not expecting a repeat of the stellar FY 4/2022 results -
"Over the past year we have benefitted from the very strong housing market conditions which emerged after the first lockdowns in 2020 and this is the main reason for the Group's record results for the year ended April 30 2022.
"Rising interest rates and high levels of inflation have already started to slow housing market activity and we are therefore cautious about prospects for the coming year especially as we tend to lag changes in the housing market.
We are also experiencing high levels of cost inflation especially from our fabric suppliers whose manufacturing operations are being impacted by large increases in energy and raw materials costs.
Against this backdrop we believe it is unrealistic to expect continued sales growth in the current year especially against such strong prior year comparatives.
The fact that the Group operates at the premium end of the market should provide some protection from high levels of inflation.
In addition we are benefitting from the recent strengthening of the US Dollar as over 60% of our Fabric Division revenues are in the US.
The Group has a very strong balance sheet including cash in excess of £21 million and is well placed to deal with more challenging trading conditions"
Balance sheet - looks strong. NAV is £33.1m, with no intangible assets, to NTAV looks excellent also at £33.1m.
Stripping out the IFRS 16 lease entries gets rid of the £25.6m RoU asset, and £4.2 + £23.8m = £28.0m liabilities, so a £2.4m deficit. That adjusts NTAV up to £35.5m, which is very comfortable for the size of business, and means that the £64m market cap is about 55% asset-backed, giving great downside protection, and clearly more scope for continued share buybacks, given the £21.8m net cash pile.
One query I have, is why receivables are so low? Only £7.0m in April 2022, and £8.6m a year earlier. That’s extremely low for a £100m revenues business. This suggests that most customers must be paying pro forma - i.e. cash on delivery. If paying on more usual 60-day terms, then I would have expected receivables to be £20m+
I just raised a query through an adviser, and the answer is yes, the fabrics business sells cash on delivery to customers, no credit. The furnishings business operates differently, but has stage payments from customers during its work to revamp high end residential property. What a fantastic business model! That shows considerable strength, and means that CFX gets to keep the cash in its bank account, rather than offering free credit to most of its customers. That’s not something I see very often, but I like it a lot!
My opinion - lovely numbers, but the commentary is making it very clear that this was a one-off bumper year. Therefore, for valuation purposes, I wouldn’t use the 102.5p EPS achieved in FY 4/2022. Indeed, broker consensus is a halving to 50.7p EPS for FY 4/2023, which makes more sense as the figure to use for valuing the shares. At 808p that means a PER of 16.0x which looks if anything a bit too high.
Although if we adjust for the fact that about a quarter of the market cap is surplus cash, then that would adjust the PER down to about 12x.
Taking everything into account, the share price looks about right to me.
EDIT: a new broker note out this morning pencils in 57.4p for this year FY 4/2023, so that reinforces the point that we need to treat FY 4/2022 at 102.5p EPS as a one-off. End of edit.
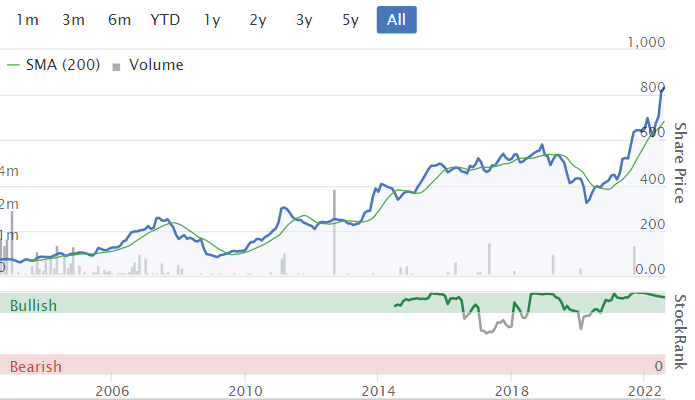
This share has had an amazing run, but I don’t think it makes sense to chase it any higher right now.
Very nice business though.
.
.
Graham's Section:
Gooch & Housego (LON:GHH)
Share price: 662p (-20%)
Market cap: £165m
This is a photonics group with a long history of profitable operations. However, bottom-line growth has been somewhat limited in recent years and this explains the lacklustre five-year chart:
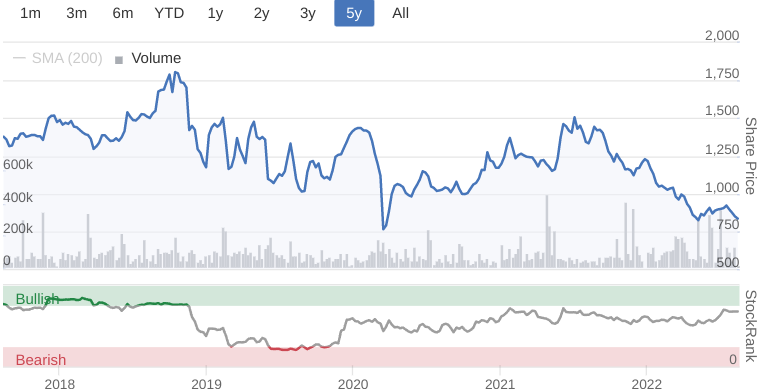
Today brings a trading update with a profit warning, let’s dig in:
Strong order book - the order book reaches a new record high thanks to strength “across all principal areas of the business, namely industrial lasers, telecoms, A&D and life sciences”.
Lasers are used in a wide variety of sectors and one of the most important is in semiconductor manufacturing. But there are also applications for undersea cables, satellites, and defence and medical purposes.
The order book has increased to £140.6m, up 32.6% over a 12-month period at constant FX (but actually up by 43.9%, if you don’t make any FX adjustments!)
Current trading - the ability to meet the order backlog is hampered - or “gated” in the words of the company - by supply chain shortages, Covid-related absences, competitive labour markets, and higher workforce attrition. I wonder are all of these factors external to the company, or do they need to try harder to engage employees to stay for longer?
On Glassdoor (the employee review website), the company gets a rating of 3.4 out 5.
54% of those who left a review would recommend the company to a friend, and there are some who left scathing reviews of management. Many companies do worse than this on Glassdoor, but still it suggests to me that there is a lot of room for improvement.
Profit warning - if you can trust what management are saying here, I’m not sure that this is such bad news:
Second half trading levels are expected to be better than the first half of the financial year due to the actions taken to improve recruitment and ameliorate supply chain shortages with higher inventory, but the longer ramp up and the higher level of investment to meet the increased order book mean that adjusted profit before tax is now forecast to be around £3.5 million lower than management's previous expectations.
The bad points are:
- We are promised both an H2 weighting and an improvement next year, which often fails to materialise. G&H already promised that H2 would be better than this.
- The company has recruitment issues and this may hint at deeper problems such as management who are out of touch with the job market and with the expectations of employees and candidates.
- Supply chain shortages continue to fester. These are outside the company’s control and there’s no clarity on when they’ll be resolved.
- Customers may be disappointed if their orders are fulfilled much slower than they expected (but again, this may be an industry-wide issue and not specific to G&H).
Against all of that, there might be positive elements to this profit warning. After all, the company is being forced to invest in staff, in order to meet high customer demand. It is being forced to outsource manufacturing that it would have preferred to do itself.
This sort of thing occasionally happens to a growing company and it doesn’t mean that the company is failing: it’s better thought of as growing pains. In future years, the investments and the decisions made now should benefit both the company and its customers.
Impairments? Management will “review intangible asset carrying values” - I wouldn’t worry about this. These will be non-cash adjustments to carrying values which are usually wrong, anyway!
FY 2023 Outlook - G&H expects “double-digit volume growth” in the financial year that begins at the end of next month (FY Sep 2023). Price increases are being passed onto customers, and revenue growth will be positive for the EBIT margin.
The FY 2023 outlook sounds ok, which helps to bolster my suspicions that the problems in FY 2022 should not be of huge concern to long-term investors. G&H itself tries to prove this with a progresive dividend declaration: the full-year dividend for the current year will be higher than last year’s.
New CEO - the long-standing CEO is stepping down after eight years in the role, and his successor has been selected. I don’t see any major red flag here - eight years is a reasonable tenure. There will be a handover period, and hopefully an orderly transition.
Estimates - the new FY Sep 2022 estimates from finncap are for adjusted PBT of £7.5m (previously £11m).
The adjusted PBT estimate for FY 2023 is now £12.1m (previously £15.1m).
It’s unfortunate to see that the FY 2023 estimate is cut by almost as much as the FY 2022 estimate: the profit figures are highly dependent on small changes to revenues and margins, and the FY 2023 revenue estimate has been reduced slightly. But you can see that there’s still a big improvement expected in FY 2023.
My view - I’ve hopefully made my view clear during the course of this report. G&H does have issues, of that there is no doubt. But many of these issues are industry-wide and found in other companies. But on the basis of this update, some of the issues simply stem from high customer demand and the challenges posed by trying to meet it. There’s an interesting contrarian thesis which says that these shares should have a nice recovery over the next 1-2 years, as the backlog is fulfilled.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
Boohoo (LON:BOO) Increase stake to 12.85%
So that's why I got a 40% off cinema tickets email from Cineworld (LON:CINE) last week!
The soft film release schedule must also be an impact on Everyman Media (LON:EMAN) too, for any holders out there...
Wynnstay (LON:WYN)
Placing for Instos only just announce, min price 550. Closed today at 610/630
Heads they win, tails we PIs lose.
https://www.londonstockexchang...
That’s quite a discount and no chance for the small PI to participate.
Focusrite (LON:TUNE) is tanking (-20%) this last fortnight on no news and against the more recent trend for calm. I like a lot about this business except for the advanced age of the founder. Anyone any thoughts?
A fund manager, who still likes the stock, has been a forced seller due to redemptions in his open ended fund. It is not to do with concerns over the company's fundamentals. Unfortunately, it does not take much trading volume to have a significant impact on some of these illiquid holdings.
Very helpful thank you.
Apologies on being late with this one Paul and Graham. Braemar's statement today has been received well (we hold) but I wondered how you would view the reason for the delayed results. I'm convinced by the explanation and we might add to our holding or perhaps I should wait till the 30th.
Gooch & Housego (LON:GHH) - as share that I've looked at a few times over the years, but has always looked too expensive. So the recent drop has brought it back into focus. Without knowing the company in detail, the first thing that jumps out is the steady drop in operating margin over the last 5+ years. Wonder if anyone with bettter knowledge of the company has any thoughts?
RE: Gooch & Housego (LON:GHH)
Without knowing the company in detail, the first thing that jumps out is the steady drop in operating margin over the last 5+ years. Wonder if anyone with bettter knowledge of the company has any thoughts?
I was wondering exactly the same thing. The company makes great play of its adjusted numbers, where the operating margin doesn't look too bad. Those adjustments involve amortisation of intangibles and restructuring costs. Generally I ignore the former but the latter is dependent on how rare restructuring is. Looking at their last few annual results the restructuring costs have been:
2018: £864,000
2019: £1,355,000
2020: £2,609,000
2021: £5,860,000
(I note these change a bit from year to year).
Broadly the restructuring costs look valid - but are they valid adjustments when they keep recurring - and getting larger?
On balance I'm likely to take a stake here. Most of the issues look temporary and there's a decent chance the restructuring will actually lead to margin improvements once the gating factors are resolved. But I don't have much confidence in the management's forecasting capacity - it feels like there's at least another warning in here unless the economy moves in their favour, and that's more wishful thinking than anything else.
But Gooch & Housego (LON:GHH) is another decent company, like Treatt (LON:TET) where the share price has been discounted due to management's inability or bad luck in dealing with rapidly changing economic conditions. We can allow managements a certain amount of latitude around this (let's face it, the "experts" at the BoE and the Treasury haven't demonstrated any forecasting ability either) but from here on in the bad news is in, they need to start to perform.
timarr
Re Gattaca (LON:GATC)
I made several observations six months ago here on post 36 of Nov 5 and here on Nov 4 post 38.
My initial thought concerns the new CEO. If ever a recruitment business needed someone to come in from the outside and introduce best practice and operational targets gleaned from experience at a combination of boutiques (focus, high margins, higher recurring revenues, better relationships) and large operators (branding, resource management, scale) then Gattaca is it. Yet they've appointed a (no doubt thoroughly deserving) candidate who is a Gattaca lifer. I respect his CV, I just don't think, based on his experience, he is best placed to execute a turnaround.
On the other hand, the company is such a shitshow that it won't be hard for him to look better than his predecessor.
Paul, another observation. I know you see value here, but you're looking at the business as an investor with an accounting background. Debt, balance sheet etc. Important stuff and you are doubtless correct to see potential for a profitable recovery. But we are both shooting in the dark when it comes to assessing what's going on in the business. My reading is that the problem facing the company is that it has gone into a decline that may be irreversible. And, since we know that the market is good, then what has gone wrong is almost certainly related to the loss of key fee earners. Successful recruiters, even the largest, thrive on the reputations and fees of a surprisingly small cohort of rain-makers. Once those leave, you are in big trouble - often terminal. With no superstars to inspire and educate the next cohort, no matter how much you add to headcount, productivity evaporates along with revenues. The competition is brutal and vast. The much discussed SThree (LON:STEM) don't have 1% of the UK market. In fact I'd be surprised if they have 0.1% of the market. There are literally thousands of competitors. So junior hires without guidance and leadership simply wither and die.
I think we see the effect of that in what, based on the assumptions in my posts from last November, is a move down-market in their niche. IT recruitment is effing difficult. Top consultants earn very high incomes, £250-£500k (possibly more today), not because it is money for old rope, as outsiders believe, but because it is so damned hard to be successful. Gattaca's staffing issues leave the company chasing roles of the lowest technical complexity while persuading the market of "our key strength of deep knowledge and understanding of our sectors and niche STEM skills" . Haha. While a top boutique will find you a security architect and SThree (LON:STEM) will find you the programmer to work under them, Gattaca will find you someone who can say "have you tried switching it on and off"
Hi BnB,
Good points, very interesting, thanks for posting.
Although as I stated in the article, the fact that Gattaca (LON:GATC) is only operating at breakeven, when competitors make good profits, is the key question - the figures are clearly telling us that something is wrong. So I think your explanation makes complete sense.
For me it's only a potential turnaround. There would need to be evidence in the numbers, and from the strategy, that things are improving in future, to make it worth backing in my view. But a sound balance sheet, and little to no dilution risk, is a good starting point for a turnaround.
As you say, maybe it would have been better to bring in a high flyer in the sector to really shake up GATC, rather than making internal promotions, that point occurred to me too.
Also I wholeheartedly agree with you that outside shareholders don't have a clue what's really going on internally. I made that point in another report earlier this week, it applies to all listed companies.
Regards, Paul.
Hi Paul. I was careful to use your wording “potential for a recovery” in my post so I wasn’t suggesting you were leading forum members down a dangerous path. I found your analysis of the balance sheet very interesting.
As for hiring an outsider, it’s entirely possible that Gattaca (LON:GATC) tried to do so. The problem is that the majority of the most capable leaders in the industry are also owners of their own businesses, and earning £millions. So taking over an ailing dinosaur like Gattaca (LON:GATC) makes no sense - lots of work for far less money. It is telling that SThree themselves were unable recently to find a candidate to stand up against the company lifer interim CEO. And, looking at the remuneration package this is no surprise.
My criticism of the firm is therefore a little harsh. After all, the appointment of an outsider would probably have put the noses of either of these two internal candidates so far out of joint that each company would have lost their services. But I think the criticism is valid from an operational point of view and Gattaca will need to bring in outside knowledge to help the new man deliver his objectives. I have no such concerns about SThree where Timo is the continuity candidate having built their most successful division.
Paul
Can you look at Colefax please maybe even with a quick SDG comparison .
Both look solid and undervalued (unloved )
Colefax fag packet numbers
10 million profit
62 million market cap
22 million cash
I’m not convinced this years profits are a one off, I think both SDG and Colefax are in sectors that are actually rising tide not falling tide (middle class home improvements ) and I don’t see the middle classes reigning it in .
Colefax don’t seem to pay much dividend , they also did a very clever (I think) tender offer last year and bought back 12% of the company at a cost of 6.7 million . Interestingly management partook in this and circa 30% of the tendered shares were from management , seems a nice clean way for management to sell down and bank some cash.
I’m going to have a closer look later but I am coming round to the point of view that SDG and Colefax are mature well run businesses in good sectors with good management that are simply going to be spitting out cash in the years to come .
Sure, I'll take a look at Colefax (LON:CFX) next - section should be up before 14:00 I hope.
Revolution Beauty and Boohoo collaboration is a show stopping announcement but does not change some worrying fundamentals .
It is also maybe a touch of clever high level back scratching market manipulation. By definition the share buy creates an RNS which creates a share bounce as small PI get sucked back in to a frothy share that jumps around .
The bear points remain
- firstly Boohoo was already a customer so not necessary that sales are going to improve (unless they only listed a few of the products )
- secondly sales may indeed suffer, a buyer of cosmetics at a competitor to Boohoo will view this negatively and buy less from Revolution.
- The CEO was full of sh1t with his claims to build a 1 billion pound company but couldn’t back it up, a strategy which saw the crazy stock build and resignation of CFO . He hasn’t changed .
I just think there is a trend here, this is a share price “in play” so it’s a trading opportunity for those with balls of steel and good market timing, probably money to be made (by Boohoo) and a lot of people who get it right especially if this market bounce gains momentum .
But it remains very clearly a company floated at the peak of the bull market at a very inflated price on big promises and hype , and that’s the point really that is the modus operandi .
It is a punt, Boohoo have taken a punt and if you do the same no problem but accept it as that as it cannot in any way be considered a strong investment opportunity based on established fundamentals .
Gambling on the stock market is ok but the stats are not so good for traders in bear markets .
Just being a touch provocative and putting an opposing view as I think everyone will pile in like lemmings again on this announcement and the whole pantomime starts again .
Are you shorting?
No I I don’t do shorting or trading .
I invest in companies with solid finances, great honest management that work for shareholders that I think are worth owning .
If I want to gamble I go meet my friend William Hill who is always glad to empty my pockets .
I just got this email from Moonpig (LON:MOON) which I thought was interesting, and worth sharing -
Royal Mail Strikes
Hi Paul,
Due to Royal Mail strikes in the coming weeks, there will be delays to First Class card deliveries which will vary depending on when you place your order. The strikes are planned for the following dates:
Unfortunately these delays caused by the Royal Mail strikes are beyond our control so all we can do is advise you to order early where you can. Please note that our gifts and flowers use different delivery services so will be unaffected by the strikes.
To find out more about your options and cut-off times, head to our delivery page.
Thank you for understanding and have a great day,
Moonpig
This worries me a bit, as a prolonged dispute could harm MOON's business. It could also harm Royal Mail (LON:RMG) business, as customers might switch to alternative delivery services, although I don't think there's anything comparable for greetings cards only.
Industrial action & big pay rises is something we tend not to think about re our investments, but it's becoming a much more pertinent issue now. You can't blame anyone for wanting their pay to keep pace with inflation. But strikes do so much damage to the business, leaving lasting effects. I've never invested in any company that used to be a public sector service, because the mindset of the staff never changes, making them riskier investments.
Regards, Paul.
Good Morning Paul,
I have subscribed to Money Week and Investors Chronicle for years, I have recently cancelled both subs because for the last 3 months i either do not get the mags or they are 4 or more days late, I appreciate that the RM service is dependent on the local Sorting Office situation but discussing the problem with the mags distribution it seems to be fairly common place. RM's Parcel Delivery seems to be unaffected. Draw your own conclusions.
R
I had the same issue with delivery of Money Week, cancelling after they increased their subscription and discovering that you can access an electronic version on the day of publication via Readly for less than the cost of MW with a few thousand other publications thrown in
I access Money Week for free via my local Library & their on line app for Magazines - they have the Economist too, but not Investors Chronicle - loads of other general interest stuff to from Cars to IT depending on your interests.
I have had occasional issues with Money Week too and am away a lot sailing so I download it onto my iPad in the Newstand app and it’s usually available on Thursday afternoons so you can get it a day earlier than the mailed out magazine.
I asked IC for a digital only version recently as I live in Amsterdam. Called loads of times to the number they gave me. No one answers.
they are hopeless. I’ve called them numerous times to get the digital version and each time they say they will report it to IT and someone will get back to me. They never have yet. I’ve given up with them.
Do not get either moneyweek or inv cron but do get the Spectator and a TV Guide delivered every week and only rarely are either late.Both are also very good at anticipating problems in December with Xmas. Inv Cron and Moneyweek should be able to sort out the problem if the management step up
What a great piece of business by Sanderson Design (LON:SDG), collaboration with Disney. Fabulous kudos for the Sanderson brand, notwithstanding the absence of any figures. I hold.
'Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, is pleased to announce an exciting collaboration with Disney.
Under the terms of the licensing agreement, the Group's Sanderson brand will be able to create wallpapers and fabrics based on a wide range of Disney Classic franchises.
The Group's Sanderson archive has a unique collection of original wallpapers and fabrics based on classic Disney characters including Mickey Mouse and Minnie Mouse and Snow White and the Seven Dwarfs, dating back to the 1930's.
Products developed under the new agreement will be distributed internationally, including North America, EMEA, APAC and South-East Asia, through the Group's existing sales and distribution network.'
Sanderson has been on a downward trajectory share price wise and is hovering on what must be a key support level around £1
Does look unloved at the moment and they seem to just cracking on with the day job .
Colefax their main competitor have reported what looks a good update this morning with significant increase in profits albeit tempered with the now compulsory “it can’t go on” message
SDG looks outstanding at £1 share level especially if you believe that the disposable income of the middle cases is going to remain high
I would also add that Sanderson Design (LON:SDG) is trading at around the value of its irreplaceable archives, William Morris and Sanderson in particular. These were valued at around 92p per share a number of years ago.
Where I can see value in the assets of a company that is not reflected in the share price, I am happy to hold and even add, providing the balance sheet is supportive, notwithstanding a challenging trading environment. Another good example is in my opinion ITV (LON:ITV), where the share price significantly fails to reflect the value of ITV studios and its back catalogue. Patience is a virtue in such cases and it often takes a long period of time, but eventually value is recognised.
On the basis of the above I was lucky enough to add to Sanderson Design (LON:SDG), then Walker Greenbank I think, at 39p during the pandemic. I could have bought at 29p had I been brave enough and have recently added at 108p having previously top sliced at 195p. Similarly I have added to ITV (LON:ITV) recently at around 65p and 70p.
How successful these purchases will be, remains to be seen, as I have made a myriad of mistakes in my time as a retail investor. Just my approach and I am sure that there are more successful investing strategies.
Sanderson has been on a downward trajectory share price wise and is hovering on what must be a key support level around £1
Does look unloved at the moment and they seem to just cracking on with the day job .
Colefax their main competitor have reported what looks a good update this morning with significant increase in profits albeit tempered with the now compulsory “it can’t go on” message
SDG looks outstanding at £1 share level especially if you believe that the disposable income of the middle cases is going to remain high
Kenmare Resources (LON:KMR) have released an excellent set of HY numbers with record revenues announced. Profits, cash generation and the dividend all grew impressively. A few highlights
- Record H1 revenues of $182.1m, an increase of 9%, Average price received up52% to $429, EBITDA of $105.5m up 28%, net debt reduced to $65.6m.
The dividend was increased 51% to USc10.98
Strong market demand for Kenmare products continuing into Q3 suggesting prospects for H2 are encouraging as production and shipments improve.
Mgmt present 18/8 at 12.30 Register here
Purplebricks (LON:PURP) (I hold) the Chairman has just bought again - £261k-worth, announced this morning. I know there are lots of negatives about this share, but this follows a previous purchase this month worth £370k by this Director, Paul Pindar. Plus the CEO recently bought £100k-worth. These are not trivial amounts, so I take this as a potentially good signal. With the caveat that, as discussed here the other day, Director buying is not necessarily a positive signal.
(by the way, I'm not trying to pump my own holdings, it's just that I get email alerts for shares that I hold personally, so I see them first)
Purplebricks have dire customer service. Best to avoid.
Purplebricks (LON:PURP)
Patrick L posted this interesting item yesterday:
https://thenegotiator.co.uk/pu...
Purplebricks (LON:PURP)
What ridiculous comment from the company (copied below) - they are hiking their fees - still making losses and from the sounds of that article losing market share tro teir nmearest rival. I really think they would have better saying nowt rather than congratulating their nearest compietitor who has directly replaced them as top "low cost online" dog if my reading of that article is correct.
A Purplebricks spokesperson told The Neg: “We are pleased to see one of our hybrid peers doing well – it only goes to underpin the growing demand from sellers to move away from the huge cost of the high street agents. We’re absolutely focussed on implementing our own plans to improve performance and grow instructions and we’re confident of reclaiming our number one position.”
Could you tell me which estate agent has good customer service ;) ?
At least they're cheap!
Paul Pindar was previously CEO at Capita, he was instrumental in building the business from listing onwards for 20+ years and left long before things went pear shaped. Not sure I understand the full picture here but I know from direct experience he is a tough minded and driven individual who was the prime mover in making Capita a FTSE 100 company along with then Chair Rod Aldridge. Not sure if this is a good or worrying sign for retail investors!
Another point I just remembered, is that Purplebricks (LON:PURP) (I hold) Chairman recently came under public attack for the poor track record. So I wonder if buying shares in the market is designed to strengthen his position at the company?
For the avoidance of doubt, I don't see my PURP position as a great investment, it's a lousy company. But I think the shares could be an interesting special situation, at this bombed out level. So more speculative than my usual value type stuff.
Probably not worthy of a section in the main report, but I like the update from Cambridge Cognition Holdings (LON:COG) (I hold) today. Its cognitive testing is being used on a study by Oxford University. No financial details are given, so I'm assuming it's not material, but it does seem to be saying that a new product recently launched by COG is doing well. I also like that an investment I hold could potentially make a real world difference to combating dementia. Probably not a price sensitive announcement, but it makes me feel more comfortable holding this long-term position -
"Matthew Stork, Chief Executive Officer of Cambridge Cognition, said:
"We are delighted to be partnering with the University of Oxford to develop better treatments for Alzheimer's disease. We are particularly pleased to be including our voice solution, NeuroVocalix(TM), as we believe it could help track the earliest cognitive indicators of dementia and this study is an important step as we gather further validation data. We have seen strong early uptake of NeuroVocalix(TM) following launch to the academic community last year and more than 20 institutions are using it."
Ivan Koychev, Chief Investigator of ISAP, said:
"The ISAP study paves the way for novel and much needed therapies for Alzheimer's disease. Glucagon-like peptide-1 receptor agonist medications such as semaglutide are particularly promising given the emerging evidence of reduced dementia incidence in patients who take them as part of their diabetes treatment. We are grateful to our commercial partners Novo Nordisk and Cambridge Cognition for their support of this study."
I see from the RNS this morning that Boohoo (LON:BOO) (I hold) has turned up with a new 7.1% shareholding in Revolution Beauty (LON:REVB) with the purchase (or enough to take them over 3% anyway) dated 12 August. The price range for that day was about 13-17p. An interesting development. Share price of REVB is now 24p, having tripled from the 8p low the other day, amazingly.
EDIT: a separate RNS has been issued by BOO, saying this -
Strategic Investment in Revolution Beauty Group plc
boohoo is pleased to announce that it has recently made a strategic investment into Revolution Beauty Group plc ("Revolution Beauty"), amounting to a direct interest as at the close on 12 August 2022 of 7.1% of Revolution Beauty's issued share capital. The investment builds upon the existing relationship between boohoo and Revolution Beauty, under which Revolution Beauty products are sold through several of the Group's direct to consumer brand websites and its online digital department store, Debenhams. The investment reflects boohoo's belief in the growth potential of Revolution Beauty and it intends to be a supportive stakeholder and long-term partner.
Damn. Bought at 8 but took profits as concerned about auditor’s report. Today will be interesting.
2 more RNSs this evening, saying Boohoo (LON:BOO) (I hold) has increased further to 12.85% of Revolution Beauty (LON:REVB)
These transactions happened on 15th & 16th August 2022.
Hi Paul ,
Have you got any idea what was the interest of Boohoo’s Chairman Mr. Mahmud Kamani in Revolution Beauty in the IPO , and if this should have been announced prior to these big purchases.
Revolution Beauty will need between 25%-30% of today’s market cap in the next year or so in new finance i.e. placing.
These purchases , together with the fundamentals and accounting issues , make no sense at all.
Boohoo could have got this from the administrators for nothing if they wanted to and the fall in today’s (Boohoo) share price agrees with my assumption.
I'm wondering if that's the plan by Boohoo to buy Revolution Beauty when it goes into administration. By having nearly 13% of Revolution Beauty shares already, does that put Boohoo as frontrunner to buy all of it when it enters administration?