Small Cap Value Report (Wed 17 Jan 2024) - SPT, SDRY, BOOM, KLR, OBD, 888, CRPR, CHH

Good morning from Paul & Graham!
Today's report is now finished. I'll do some more sections tonight, ready for first thing tomorrow morning again.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Agenda
A crazily busy list today. We might need some help from readers, so do flag up any particularly interesting ones (above or below expectations), or strong value/GARP characteristics, for us to prioritise! Thanks.
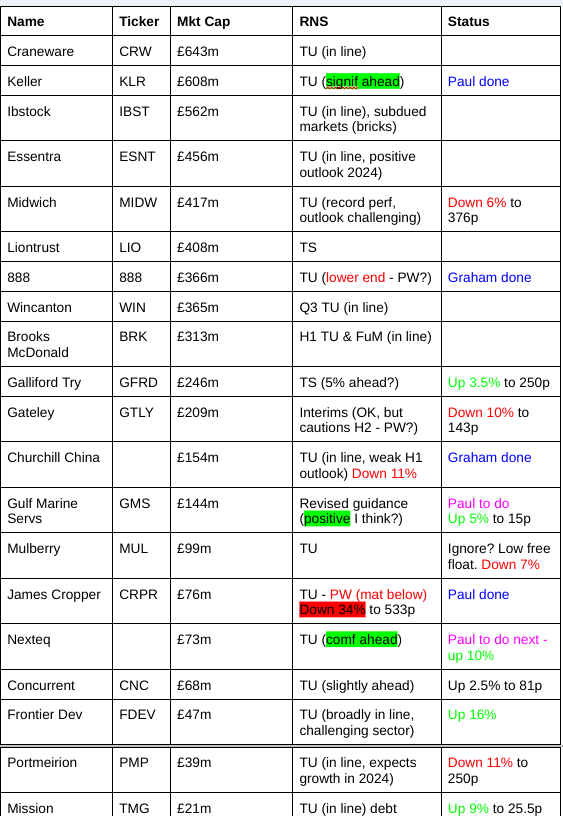
Backlog Items -
- Spirent - Paul done
- Audioboom - Paul done
- SuperDry - Paul done
Other mid-morning movers (with news) -
Oxford Biodynamics (LON:OBD) - down 23% to 26.3p - results - negligible revs, £10.2m op loss. £5.3m cash left at 30/9/2023, after raising £15m in year. Looks like it will need to do yet another placing soon, but on what terms? Its products sound interesting, but that's of no interest to me until it has enough cash to reach breakeven.
Summaries
Spirent Communications (LON:SPT) - up 11% y’day to 128p (£741m) - Trading Update - Paul - AMBER
An 11% rise yesterday caught my attention. It had a terrible 2023, when years of profit growth collapsed. However, upbeat outlook comments in the latest update make me wonder if a turnaround might be starting? Plenty of cash, and it's used some to reduce the share count with buybacks. Could be worth a look, I know very little about the company.
Superdry (LON:SDRY) - down 15% y’day to 25p (£25m) - Sky News report - Paul - RED
Shares clobbered again with a report from Sky saying that it has called in accountants PwC to "review debt options", following a disastrous profit warning in Dec 2023. Given that it's already using non-standard, higher cost lenders, it's difficult to see what more debt options are available, that wouldn't involve some form of insolvency procedure, and probably heavily dilute or wipe out existing shareholders. Existing equity could easily end up worth nothing. Super high risk.
Audioboom (LON:BOOM) - down 18% this week to 270p (£44m) - FY 12/2023 Trading Update - Paul - RED
This week's trading update is more of a PR release, talking up what positives they can find. Q4 an improvement on Q3 though. Reality is that it's burning cash, not helped by a major mistake with a loss-making contract that runs until 2025. I think it's a weak business model, although mkt cap is now low, and we've seen mad speculative frenzies in this share before, so it might appeal to traders/punters in the next bull market? Profit-takers are sensible, given recent 100% rise I think.
Keller (LON:KLR) - up 3% to 853p (£622m) - Trading Update - Paul - AMBER/GREEN
Ahead expectations trading update. Very low PER, and 5% yield. Balance sheet just about OK, although a fair bit of debt. Looks interesting!
888 Holdings (LON:888) - down 9% to 73.6p (£330m) - Trading Update (profit warning) - Graham holds 888 - AMBER/RED
A mild profit warning from 888 as 2024 EBITDA is expected at low end of range. Net debt/EBITDA remains too high but they do have a few years to improve before the debt will need to be refinanced. I’m neutral on the outlook for the stock but it’s certainly very high-risk.
James Cropper (LON:CRPR) - down 34% to 530p (£50m) - Trading Update (profit warning) - Paul - BLACK for spreadsheet, AMBER on fundamentals
This is a bad profit warning, with FY 3/2024 anticipated profit almost entirely vanishing, due to project delays and customer de-stocking. Surely this should have been flagged earlier, rather than a bombshell huge drop in forecasts? I can't muster any enthusiasm for this share, but seeing as it's probably got adequate funding (although it would be worth checking the bank covenants to be certain), then I'll reluctantly go with amber. Long delays mean little chance of a rapid bounceback in profits, which calls into question the company's strategy.
Churchill China (LON:CHH) - down 6% to 85p (£136m) - Trading Update (poor outlook) - Graham - AMBER/RED
Churchill China confirms that 2023 profit is in line, as efficiency gains offsets flat revenue. Looking ahead, the company sees continued weak demand in H1 2024. I remain neutral on this stock: it’s highly rated but performance doesn’t seem to be going anywhere fast.
Paul’s Section:
Spirent Communications (LON:SPT)
Up 11% y’day to 128p (£741m) - Trading Update - Paul - AMBER
Spirent Communications plc ("Spirent", the "Company" or the "Group") (LSE: SPT), the leading provider of automated test and assurance solutions for next-generation devices and networks, today issues the following Trading Update for the financial year ended 31 December 2023, noting all financial results are subject to external audit.
Interesting to see this share rise 11% yesterday. I know very little about it, but Roland covered its nasty profit warning here on 4/10/2023, concluding that it might be a decent recovery candidate, but wasn’t sure, so sat on the fence with amber. Remember that in these reports we’re mainly reviewing what’s actually happened, and flagging up the range of possibilities of what might happen next, then giving an overall opinion. So when things are uncertain, sitting on the fence makes sense, until a clearer picture emerges.
Previously Spirent made big profits but it’s run into a lean patch in 2023, OR something bigger might have gone wrong, we don’t really know yet.
2023 was a seriously painful year for Spirent shareholders -
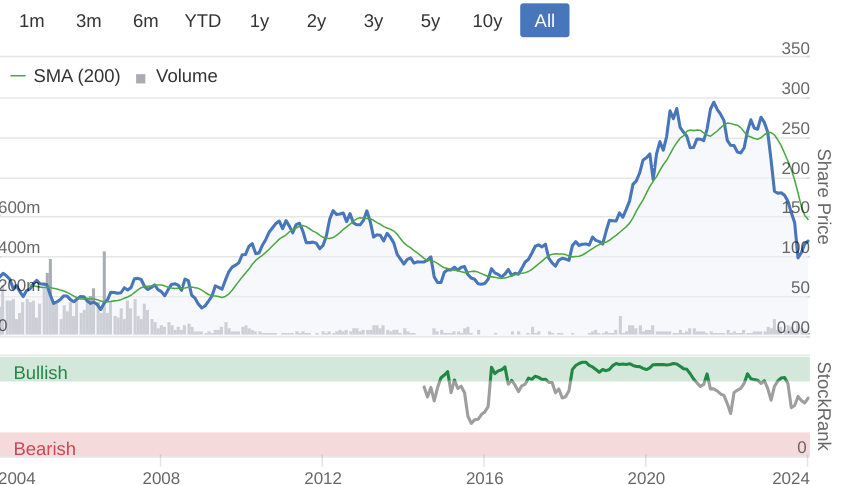
About 5 years growth unravelled in one fell swoop last year -
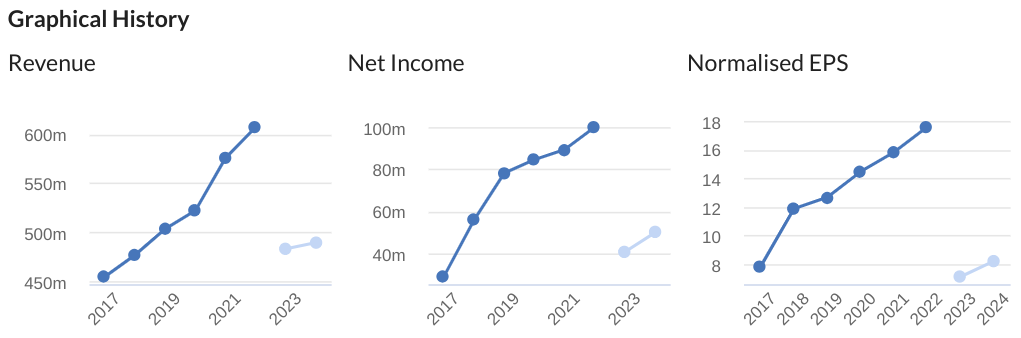
The latest update is in line with expectations - so good to see things have not deteriorated further -
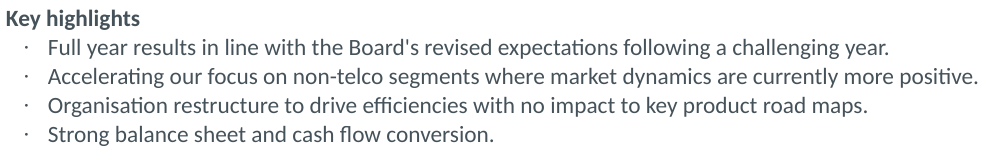
Outlook comments sound quite encouraging -
Whilst we continue to see softness and customer spending delays in the telecommunications sector, we are accelerating our focus on non-telco end markets, and we have seen good growth in order intake for our Positioning business and from Hyperscalers. We also closed a strategic, and significant sized deal with a world leading Financial Services organisation representing a new end market for us. We are building an order pipeline for these end customers…
We are pleased to have started the new financial year with a growing orderbook. We are well positioned to deliver strategic and operational progress, with growth opportunities in our non-telco end customer markets whilst we continue to invest in our leading technology solutions across our portfolio which will position us well in these markets as and when they recover. Overall, the Group remains well-placed for the year ahead.
Cost-cutting has been done, with an 8% headcount reduction, avoiding cuts to core activities.
Cash - sounds healthy still, a key point Roland mentioned in his Oct 2023 review -
We maintained our strong balance sheet and disciplined investment policy. The Group's cash position closed at $103 million supported by our effective working capital management. $72 million of shares were repurchased during the year. We remain well placed to take advantage of investment opportunities as they arise.
Paul’s opinion - not a company I know at all, so I’m just looking at the numbers only. The forward PER is hardly cheap, at 18x, but that’s based on forecasts which have unwound all the growth and gone back to 2017 levels.
So the investment case seems fairly simple - bulls imagining that earnings could recover in future. Given the upbeat outlook comments, that strikes me as a reasonable probability event, so it might pay to carefully watch the trend of broker forecasts in the coming year, or anticipate increased forecasts, if you feel that's likely.
It’s always good to have a nice balance sheet (as this does, I’ve just checked), so management are clear to focus on a turnaround (H1 results were poor), without having to worry about funding or solvency.
Looking at the average share count, share buybacks have been accelerated in 2023, with the total in issue falling from 606m to 579m now.
For turnaround hunters, this looks worthy of further research, based on just a cursory review from me. So I’m happy to retain Roland’s AMBER view.
Superdry (LON:SDRY)
Down 15% y’day to 25p (£25m) - Sky News report - Paul - RED
This news from Sky clobbered the shares yesterday afternoon -
“The fashion retailer, which has a market value of just £30m, has drafted in advisers to examine further debt-raising options following a pre-Christmas profit warning, Sky News learns.”
As regulars will know, we’ve been ringing alarm bells (at various volume levels) for a long time, over the deteriorating position of this struggling brand. It offered some hope after the IP sale in 2023, and various refinancings (debt and a little equity), but all that seems to have been overtaken by greatly deteriorating trading.
The last profit warning on 19/12/2023 was horrendous, with one broker now forecasting a £45m loss. It looks like the broker consensus (2 brokers) is diluting this with an unrealistic figure from the other broker.
As a sector expert friend has said to me, what debt restructuring options are left to SDRY, given that it’s already been ditched by conventional lenders, and is now financed by Hilco and Bantry Bay? Convertible loans that dilute existing holders maybe? Debt for equity swap - these are not usually on favourable terms for existing equity. A dilutive equity raise, or a combination of these? Who knows. Founder Julian Dunkerton might take it private, but why do that when it's in such a mess? A pre-pack administration seems more likely to me, similar to what Next did with the founder at Joules, leaving outside shareholders with nothing.
Paul’s opinion - it gives me no pleasure to say this, but I cannot see any value in the equity. Anything could happen next, but trading now seems to be so bad, that SDRY must be burning through cash, and as mentioned before, I doubt it gets to the end of 2024 in its current form. Just for gamblers, because one way or another, debt providers look likely to end up owning the business. It needs to ditch the onerous leases, so that needs some form of insolvency, eg CVA, which should have been done a long time ago, but wasn’t. Also the collapsing sales from wholesaling is telling us that customers don't like the product/value proposition. It's obvious why, when you look at the prices in their shops - expensive, for unremarkable products. That said, the IP sale shows that the brand does still have value.
A pre-pack administration would likely leave small shareholders with nothing, so one way or another, a zero outcome now looks a high probability.
Audioboom (LON:BOOM)
Down 18% this week to 270p (£44m) - FY 12/2023 Trading Update - Paul - RED
My initial skim of the update on Monday morning seemed quite positive, but shares fell 10% by Monday’s close, and again on Tuesday. Maybe some profit taking after a >100% rally from Oct 2023 lows of c.133p? We’re seeing a lot of profit-taking in big risers at the moment.
Long-term BOOM has been a disappointment, punctuated by two large speculative frenzies, as you can see -
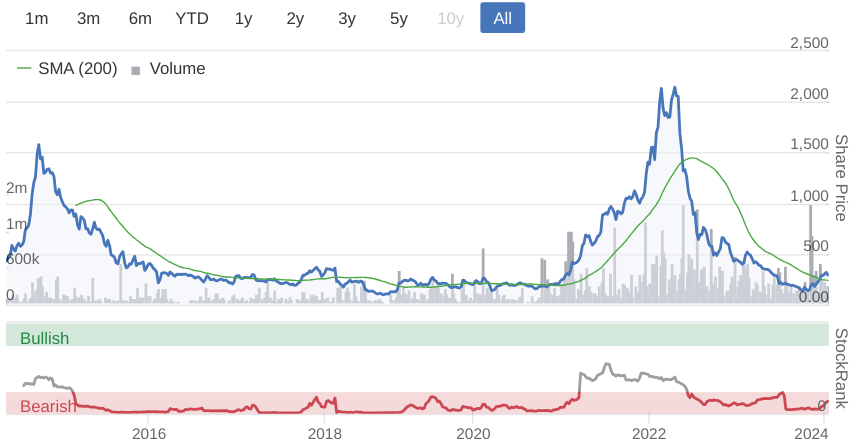
To be fair though, current management did take a basket-case a few years ago, then achieved big revenue growth, resulting in around breakeven trading now (in a depressed market for advertising, so it might recover in better conditions maybe?) -
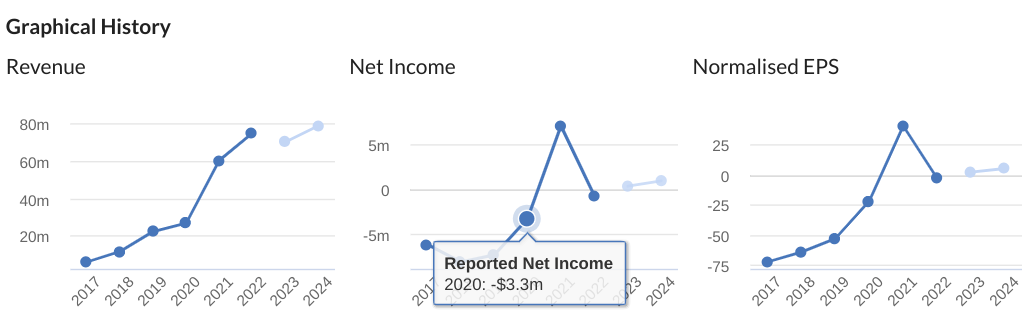
Is it a good business model? No, in a word. It does podcasting, and the trouble is that financially successful podcasters then shop around for the best deal. So it seems to me that BOOM has poor sustainability of profits, which can easily disappear (as they have done).
It’s not a tech business, it’s an advertising business which operates through the digital output of podcasts. There are still a load of costs associated with that, and lots of competition, so it’s nothing special in my view.
Management seem greedy too, with excessive share options awards that snatched all the profit away when it did make some profit - see the P&L in previous accounts.
Latest news -
Audioboom (AIM: BOOM), the leading global podcast company, is pleased to provide a trading update for the year ended 31 December 2023.
Q4 return to revenue growth, EBITDA profitability and cash generation
Q4 revenue $19.2m moving in the right direction, up 5% on last year Q4, and up 37% on Q3 2023.
Q4 scraped a small adj EBITDA “profit” (so not really profitable) of $0.2m
Cash is up by $0.7m in Q4, to $3.7m, plus $1.8m undrawn bank facility. Adequate? It doesn’t mention that cash was higher at $5.3m at the interims in June 2023. So cash has actually fallen in H2.
It also doesn’t mention that a huge $8.9m loss was booked in the H1 results, for onerous contracts. That’s going to drain cash in future, running to July 2025. See note 9 of the interim results for more detail.
Full year 12/2023 numbers aren’t good - revenue $65.0m, down 13% on LY.
Worse, it’s loss-making for the year at $(1.5)m - this is adj EBITDA. So the real loss will be larger. That’s a big deterioration from 2022, which saw a positive $3.6m adj EBITDA.
I’m rapidly losing interest, and didn't have much interest to lose in the first place. We’ve established that it’s not very good. Is there are brighter future ahead?
Outlook - $47m contracted ad revenue already booked for 2024 - which is good.
I like this too -
The Company anticipates record revenue in 2024, with operational improvements (including the significant reduction in minimum guarantee obligations) and a return to adjusted EBITDA profitability
Although this won’t include the heavy losses on the onerous contract, as that’s already been booked to a balance sheet provision. However, it’s still cash going out of the door, so in the real world, I think it’s likely that BOOM continues burning through the little cash it’s got left. Or it might not, if there’s a big pick-up in advertising revenues, if its markets improve.
Paul’s opinion - I’d forgotten about the onerous contracts, which was a disastrous misjudgement by management. It’s not really profitable, and the FY 12/2023 results are likely to look grim, as the interims were.
Is there upside though, given that it might see a cyclical recovery in ad revenues? Possibly, I don’t know. Also the market cap is only £44m now, so you could argue it’s very cheap compared with previous speculative bubbles in the valuation.
Overall, I have no idea what the share price is likely to do, but I can see that the fundamentals are weak at this point in time. So it has to be a continued RED from me, I’m afraid, despite management’s best efforts to put a good spin on things in this week’s PR release (sorry, trading update). I don’t blame people for banking their profits this week.
Keller (LON:KLR)
Up 3% to 853p (£622m) - Trading Update - Paul - AMBER/GREEN
Keller Group plc ('Keller' or 'the Group'), the world's largest geotechnical specialist contractor, issues a post close trading update for the year ended 31 December 2023.
Checking our previous notes for background;
17/5/2023 - 653p (Paul - GREEN) - Good TU, confident FY 12/2023. Good order book. Decent value.
23/10/2023 - 771p (Graham - AMBER) - Mat ahead TU. Low quality, but cheap.
As you can see, I tend to view KLR more positively than Graham.
The StockReport is showing a very low PER, and decent yield. Normally for a PER this low, there’s something wrong, usually high debt, pension deficit, or declining sector.
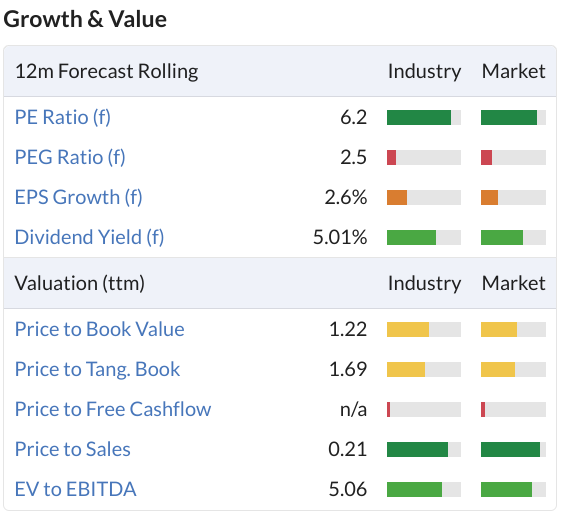
The long-term, 20-year trend has been sideways, within a wide range -
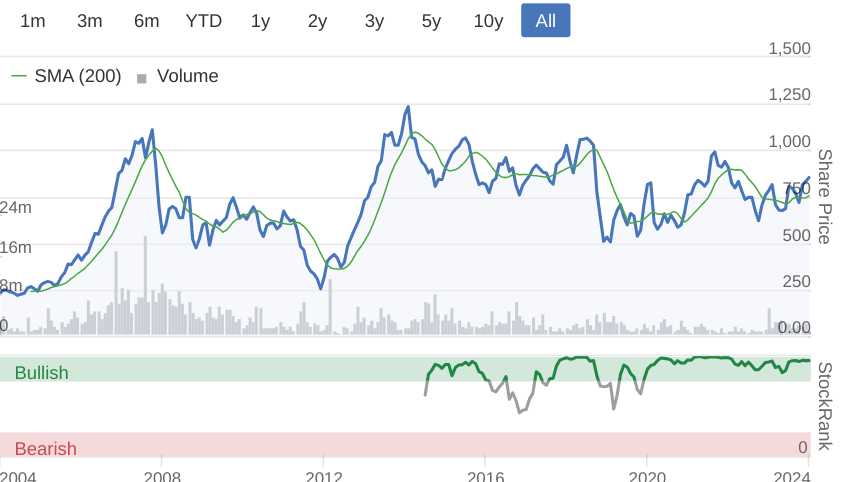
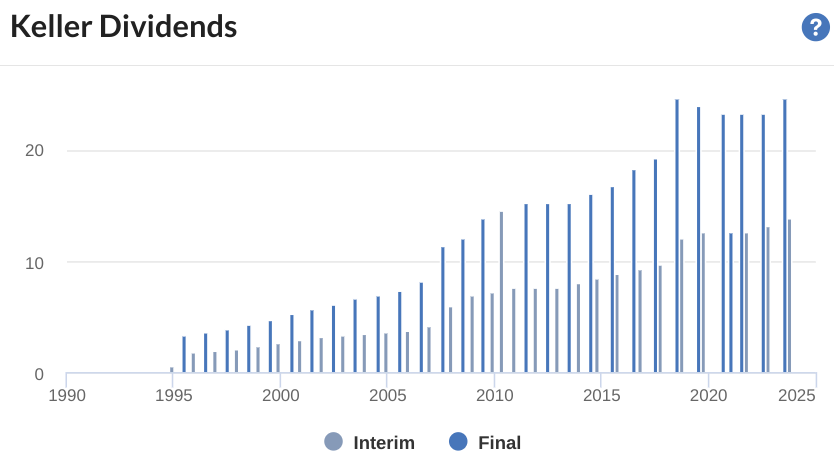
However, the main attraction is the divis - a lovely track record below -
The story is explained well in the 5 graphs -
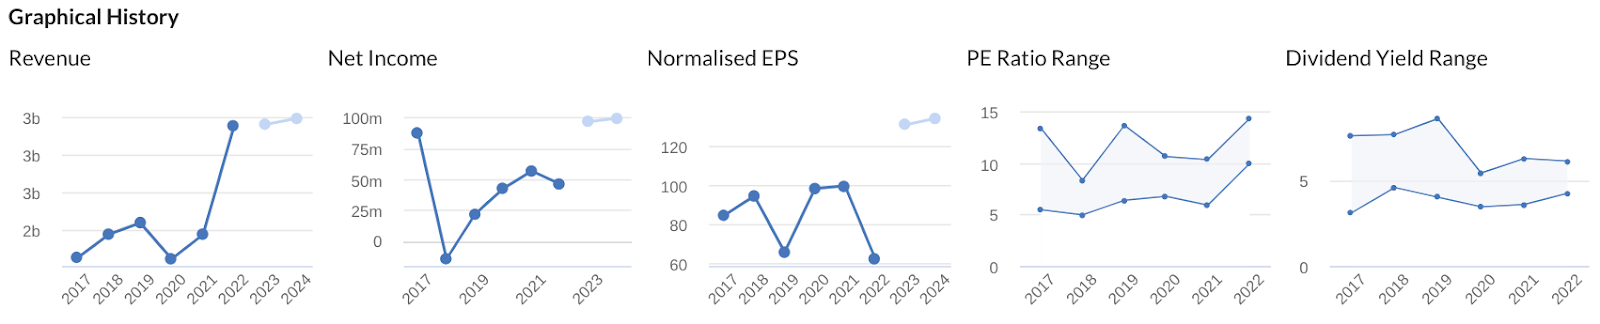
Low margin, but improving, on very large revenues. Something went wrong in 2018, but profit has been recovering since. Strong performance in the current year, and tends to be rated on a low PER, with divi yield c.5% most years.
Today’s update - sounds very good to me -
The positive trading momentum and strong operational performance seen in the first nine of months of the year continued in the fourth quarter, with a particularly strong end to the year.
Accordingly, we now expect to report an underlying operating profit for the year significantly ahead of current market expectations1. The underlying operating profit margin for the year is expected to be significantly ahead of recent years.
1 Analyst consensus underlying operating profit for 2023: £150m.
Broker updates - nothing available as yet. Liberum have published notes in the past, so hopefully something might filter down to us pond life! "significantly ahead" suggests that forecasts will be obviously be going up. So the PER might get even cheaper than 6.2x.
Companies often report operating profit, if they have heavy finance charges, so let me check the debt/finance cost situation at the last interims.
This looks OK - in H1, operating profit was £37.7m, and net finance costs £5.0m, so PBT was £32.7m.
Bank debt is high, at £245m June 2023 interims, although this is mainly for funding fixed assets, as it’s a capital-intensive business. Also working capital is large, with enormous receivables - the company needs to be sure it’s not acting like a bank for its customers, extending them too much credit. I would like to see the average daily net debt, rather than just period end snapshots, as with all companies.
Overall the balance sheet looks just about OK to me, although I would like to see it reduce bank debt by tightening up on receivables collection.
Looking through the interims, 2023 looks like being an exceptionally good year in its large US business, which is mopping up weakness in other geographies. So the risk is that 2023 is a one-off good year, which could be why the market is giving it such a low PER?
Outlook - this sounds slightly contradictory to me, mentioning “one-off” profits in 2023, yet still being confidence about 2024 -
"We are very encouraged by the Group's strong progress in 2023. The combination of management actions to improve operational performance in project execution, commercial agility in the face of a dynamic market, and the one-off benefits in North America will result in Keller delivering a record performance in 2023 that has significantly exceeded our original expectations. The fundamental strengths of the business, together with the continued positive outlook and our strong order book, give us confidence in further progress in 2024."
Paul’s opinion - I don’t really understand the business, but the numbers look attractive to me. Maybe Graham and I should compromise at AMBER/GREEN.
I like situations like this, where you have huge revenues, and low but improving operating margins. That can give big upside to profits, if it’s an establishing trend, not just one-off.
It could be worth readers taking a closer look at Keller, and doing some proper research, based on my positive initial review.
Looks like it could be a bid target from USA too, given that it’s cheap, and much of its operations are in the USA.
James Cropper (LON:CRPR)
Down 34% to 530p (£50m) - Trading Update (profit warning) - Paul - AMBER
James Cropper is a market leader in Advanced Materials and Paper Products, centred around four market audiences: Future Energy, Technical Fibres, Luxury Packaging and Creative Papers.
A purpose-led business, built upon six generations of the Cropper family, James Cropper has a 600+ international workforce and an operational reach in over 50 countries.
Established in 1845, the Group manufactures creative papers, luxury packaging and advanced materials incorporating pioneering non-wovens and electrochemical coatings.
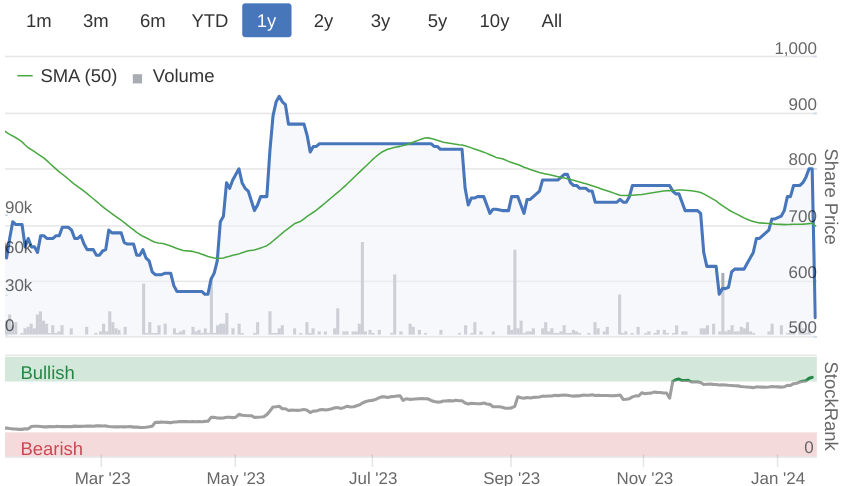
Coincidentally, CRPR came up on one of my screens the other day, and I noticed how peculiar the recent chart looked - with repeat buys seemingly walking the share price up a little every day. That’s all reversed in one fell swoop today though, so bad luck to any holders here, we can all commiserate with the sinking feeling of profit warnings, which is just part of small caps investing, and cannot be avoided altogether, however hard we try - hence why we should probably diversify, to spread the risk -
What’s gone wrong then? Financial year is FY 3/2024. It’s project delays -
… the Advanced Materials business has seen expected projects in hydrogen being delayed, partly as a result of inflation and higher interest rates feeding through to higher project costs. In addition, funding decisions by governments have impacted end customer project plans and scheduling. As a result, customer expansion plans saw a noticeable change with major market growth now expected to be pushed back to calendar years 2026 to 2028.
Oh dear, the timescales there are much longer, so this is not just a temporary, fixable problem, it seems.
The Advanced Materials divisions' revenue trajectory will be impacted in FY2024 as a result and the Board now anticipates a slower ramp-up in demand than previously expected across calendar years 2024 and 2025. Nevertheless, the longer-term outlook for the hydrogen business remains strong…
I can’t see the market quickly forgiving this.
Although -
Pricing across the business has been resilient, underpinned by strong customer relationships which has protected margins.
Paper products division is also suffering -
As a direct result of ongoing high inflation impacting consumer confidence, compounded by supply chain destocking, demand in the Paper Products business continued to soften to an even greater extent during Q3.
Recovery sounds on the cards (haha!) for this part of the business though -
Whilst near-term revenues have been affected, the future project pipeline remains strong and in the meantime the Group will aim to keep efficiency high through tactical use of free capacity.
The final quarter of the year is expected to show some recovery in volumes in Paper & Packaging and demand is expected to further recover throughout FY2025.
Revised guidance -
As a result of the above trends, the Group now expects full year FY2024 revenues to be not lower than £103m. FY2024 adjusted PBT is expected to be materially below prior management expectations, with the Board now expecting to report a small adjusted profit before tax for the year.
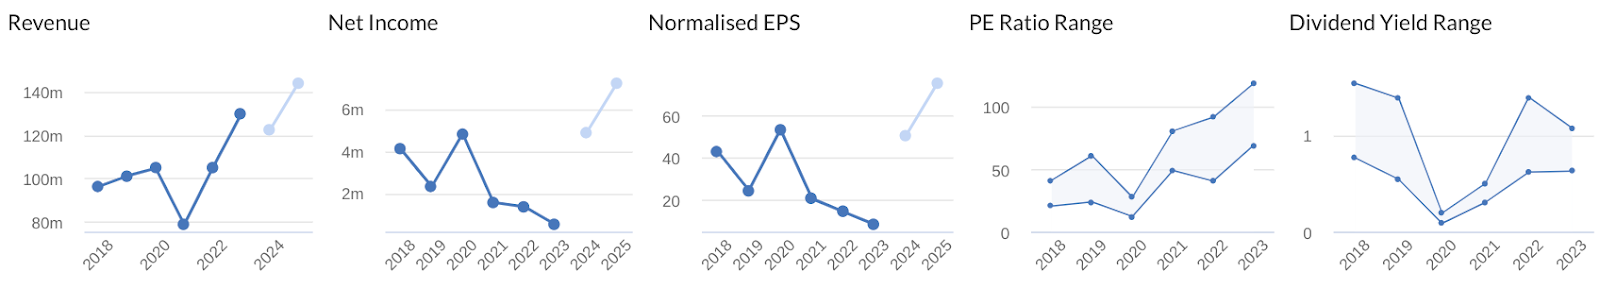
Shore Capital (many thanks) gives us more precise guidance, and it’s grim - revenue forecast dropped from £122m to £103m. Adj PBT crashes from £5.9m previous forecast, to just £0.5m now! EPS is now only 4.1p - giving a PER of 129x
So clearly the share price now factors in a major recovery of profits from this pretty disastrous performance in FY 3/2024.
That’s not an unreasonable assumption, given the historic profits pre-pandemic of £2-5m post-tax -
Balance sheet - there was about £30m NTAV when last reported. Although note long-term borrowings of £24m, although about half offset by cash. So bank covenants might need to be considered. It mentions slower capex in today’s profit warning.
Someone mentioned it has freehold property, so I’ve checked the 3/2023 annual report, which shows £7m freehold property at cost, so there’s a chance that might be worth above cost maybe, given that it’s an old, family-controlled company? Does anyone know if there’s upside on property value? If so, that could mean we don’t have to worry about the bank debt.
Paul’s opinion - we didn’t review CRPR in 2023, so we’re overdue a fresh look, unfortunately after a very nasty profit warning, almost wiping out all profit this year. That naturally raises quite big questions about the direction the business is going in.
I’d need a lot of convincing to want to bottom fish at the current price.
It’s difficult to decide whether to go with amber, or amber/red. Since I don’t have any worries over solvency, then I think AMBER is best. Although this is a big profit warning, and I’m not seeing value in this share, so amber is probably generous.
Graham’s Section:
888 Holdings (LON:888)
Share price: 73.6p (-9%)
Market cap: £330m
(Graham has a long position in 888)
888 (LSE: 888), one of the world's leading betting and gaming companies with internationally renowned brands including William Hill, 888 and Mr Green, today announces a post-close trading update for the three and 12 months ending 31 December 2023…
The revenue figures for 2023 aren’t very good, but this had already been pencilled in. The consensus revenue forecast according to Stockopedia was £1,712 million, and the actual number coming through is £1,711 million (down 8% year-on-year).
So this is no surprise:
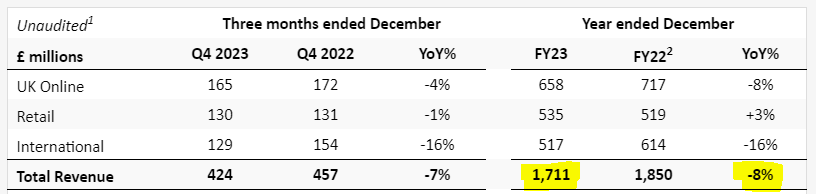
Mitigating, the company points to 5% year-on-year growth in the number of active customers.
The main reason given for the revenue decline is “a proactive mix shift away from dotcom markets, which impacted revenues by approximately £80m during FY23”.
That would indeed account for the majority of the decline, and then there are also “customer mix changes in the UK as a result of additional safer gambling measures, alongside the change in the Group's marketing approach to focus more on sustainable revenue and profitability”.
So in a nutshell, the company now has more customers than it did before, but they have a different profile than before and they generate less revenue on average.
A noteworthy change is that while international revenues fell 16%, retail revenues (i.e. William Hill store revenues) were up 3%. So there are far fewer customers from international unregulated markets, but there are more customers making small bets in physical UK shops.
2023 EBITDA margin will be “approximately 18%” (previously indicated range: 18-19%).
Cost savings/synergies:the disastrous - for shareholders - William Hill takeover required lots of cost synergies to have any chance of working out; the company says that the full £150m synergy target will be delivered this year.
Cash: available liquidity £275m. Remember that net debt is c. £1.8 billion.
Management team: the company hired a new CEO as of October 2023. The company also has a new CFO joining next month, and has a range of other new appointments - Chief IT Officer, Chief Product Officer.
As we have previously discussed, 888 had some regulatory problems in the Middle East, leading to the departure of the previous long-standing CEO.
Outlook for 2024 - this contains a mild profit warning.
888 reports a positive outlook for revenue growth from current levels, along with a new £30m cost savings programme.
Cost savings will be allocated to marketing:
Cost savings to support an increase in marketing spend in 2024, with superior returns supported by a more effective customer and product lifecycle management plan.
The above initiatives will enhance long-term profitability, but the additional investment means the Group currently expects 2024 Adjusted EBITDA to be at the low end of consensus range.
The consensus range is given as £340 - £397m, quite a wide range and it’s unfortunate that we’re going to be at the lower end of this.
Graham’s view
As a long-suffering shareholder, I am fine with the strategy to focus more on taxed and regulated markets (now responsible for 95% of revenues), instead of exotic unregulated markets where the outcomes are less predictable.
I am also happy with the strategy to focus on customers who will bet smaller amounts but hopefully stay with the company for longer - this is more or less required by regulations anyway. Hopefully the company will still attract high rollers in cases where the individuals can afford to be high rollers. I am a strong believer in the principles behind Safer Gambling.
(As an aside, I was only reading the other day about Keith Gillespie, a footballer I used to follow, who was declared bankrupt in 2010 despite earning over £7m during his playing career. He threw it all away on the bookies - a sorry reminder that sometimes even those who bet big can’t really afford it.)
Getting back to 888, I remain deeply concerned about the situation here, but I still haven’t sold my small stake in the business.
Net debt/EBITDA, using figures suggested today for 2024, is c. 5x. It’s still too high and so it appears that shareholders are still at least two years away from seeing the leverage approach a reasonable level.
It is tempting to sell here - I will have to give it more consideration as to whether I’m willing to wait even longer for the company to fix its balance sheet. I would be gutted if the company agreed to a takeover soon, and I had already sold out (we discussed the possibility of a takeover in December).
Most of the debt matures in 2027 and 2028, so there are still a few years to sort things out.
Investors in the 2028 bond don’t seem to be panicking yet:
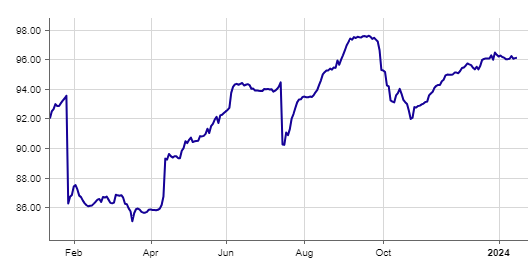
I have a neutral stance on this stock, although for the purposes of our colour system a RED warning might be justified.
Churchill China (LON:CHH)
Share price: 1185p (-6%)
Market cap: £136m
Churchill China plc (AIM: CHH), the manufacturer of innovative performance ceramic products serving hospitality markets worldwide provides an update on trading for the year ended 31 December 2023.
This is a much-loved Stoke-based business, but today’s announcement is a little cautious.
Firstly, the good news:
The Company is pleased to announce that margins have continued to improve throughout the year and as a result profitability for the year is expected to be in line with analyst forecasts. This is particularly pleasing given a more challenging sales backdrop in H2 of 2023.
Revenues of £82.1m are below last year and significantly below the forecast suggested on the StockReport (£89m).
Fortunately, the profit result was saved by “improving manufacturing yields” and “a further reduction in agency staff in Q4”.
Now here is the weak outlook:
The macro-economic situation in UK and Europe remains challenging and we expect demand to remain weak for at least the first half of the year. Cost increases, including the national living wage will have an impact on margins in 2024 which will in part be mitigated by further efficiency improvements and increased prices.
It’s the second time this week I’ve seen a company mention the national living wage, and I guess we’ll be hearing a lot more of this. The increases are significant and start from 1st April 2024.
Chairman Comment:
"We are pleased that we have delivered a good result in 2023 and have continued to improve profitability and levels of efficiency despite the difficult trading conditions. Churchill China is a resilient business and whilst the outlook for 2024 remains challenging, we are confident that our long-term strategy positions the Company well to benefit when demand improves."
Graham’s view:
Paul and I have both been neutral on this one, due to concerns around costs and also due to its high earnings multiple:
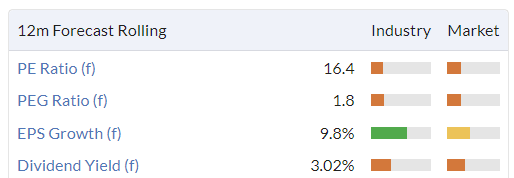
The stock has a below-average ValueRank, and an above-average QualityRank, which makes perfect sense to me. It does earn good ROCE/ROE and has an admirable track record of profitability and dividends over very many years.
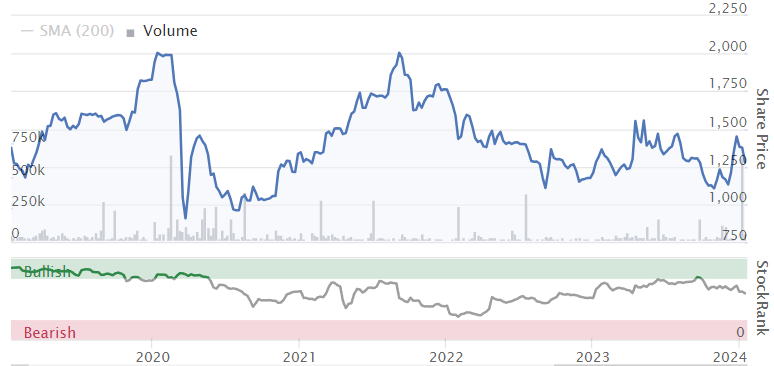
However, I do struggle to get excited about it at the current level. Where is growth going to come from? European hospitality customers aren’t exactly booming, and energy/staff costs continue to drag on performance despite the company’s best efforts to be as efficient as possible. Energy hedges have expired so maybe there is a chance for the company to benefit from falling prices in 2024?
I do admire the company’s long record of success, and I note the continued presence of the Roper family on the shareholder register. But I wouldn’t be in any rush to get involved at this valuation. So far, the market agrees:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

144 comments
On a generally down day for me the highlights were Nexteq (LON:NXQ) comfortably ahead and Renold (LON:RNO) closing at a multi year high on a huge volume spike. Anyone know of any reason for the volume?
Renold (LON:RNO) , as well as 16m today, most days in last few weeks have seen 600k traded. that volume with an unchanging price in a volatile market indicates to me a stake as being built in background for a few weeks.
maybe its the precursor to a bid?
but even a new institutional holding taking a c.5% stake at 38p would be a huge vote of confidence in the mgt team and their continuing self-help turnaround and growth plan.
think we 'll know more by next week.
all imho, dyor + bol. disc: RNO is in my top 5 hldgs.
Huge volume in SCVR favourite Renold (LON:RNO) traded today - 16m, avg daily volume 450k or so.
I do despair at UK markets. They collapse at the merest hint of trouble whilst the US sails merrily on : Dow now positive after all the headlines of FTSE wipes out £40bn in biggest rout since July……. All based on 0.1% inflation data which is fundamentally a rounding error. I mean really WTAF - talk about skittish. We have absolutely no resilience in the UK markets anymore. That’s more depressing than the falls.
Markets are only reflecting the general air of despondency in the U.K. We have been so poorly managed politically in the last ten years and there is little confidence that a Labour government will do anything that will help the country, economically. Brexit as we all know has been a disaster , especially because any perceived benefits from it were frittered away.
One may question our sanity for continuing to have faith that investing in U.K. plc will be profitable . Let’s face it, pension companies and most fund managers certainly don’t .
Personally, I now have only about 10% of my free assets in the U.K. market , down from about 40% over ten years ago.
Good post- I am with you 100%.
.
Wolf, nice post. Interesting to see JD Sports Fashion (LON:JD.) with such high profit per employee. Companies like J Sainsbury (LON:SBRY) are going to feel the pinch! On an inverse, did you flag any low PE companies with very high profits per employee who won't feel any pain at all?
Dont say Im not good to you Ben!
Sorted by Forecast P/E. Minimum profit per employee 15k
Id rather buy from this list than the one below
Sorry, that list was scanned only from my watchlist. I thought I recognised all the names :)
This is whole of market (profitable only)
Amazing Wolf many thanks for taking the time. I agree - a much better hunting ground this list! Interestingly (and reassuringly) from your watchlist version I hold 7, which is a lot considering I only hold 18 stocks total and two are US. Good to see Brickability (LON:BRCK) atop the list, that was the one you put me onto a few weeks back. Let's hope it can crack on in the next few months, I have been tempted to top up there as the SP has come off a bit with recent macro but I'll give it a few more days to try and add under 50p.
J Sainsbury (LON:SBRY) prices already risen since xmas asda and morrision are no competition to them due to their debt
Regarding the rise in minimum wage coming in April heres a list of the top employers (under 10k profit per employee cutoff)
I wonder if brokers have forecast this into their current numbers or maybe a few nasty surprises waiting down the line?
How did VietNam Holding (LON:VNH) get on that list? It’s an Investment Trust investing in Vietnamese Companies.
lol I had a laugh at that one too. Ive often wondered what all these fund managers do all day. 42,000 of them staring out the window is quite a picture.
They all need double checked from the annual report, so dont rely on it being accurate
It appears to be from FPT Corporation, one of their holdings I think?
"As of 31 December 2022, FPT employees 42,408 employees,
including 28,533 engineers and technology experts, across its eight
subsidiaries."
J Sainsbury (LON:SBRY) minmium wage goes up in march new financial year.
Cheers wolf interesting list
I wonder if brokers have forecast this into their current numbers or maybe a few nasty surprises waiting down the line?
good question - i did notice that both Churchill China and Portmerion both hit ye targets and both have had instant downgrades from brokers for the new year - not sure if the brokers have said its clearly tough should you not be setting low expectations - seems somewhat coincidental that the companies would be saying almsot the exact same thing at the same time without some external nudge? . So perhaps the brokers are doing their job here and ensuring the forecasts are "realistic".
To me tough times like differentiates the well run from the not so well run - for example i would have 100% confidence wetherspoons can weather the storm despite being very low profit per employee on that list - in some respects as a regular checker of what i own with them i often think wethspoons sells some of their stuff too cheap.
Anglo-Eastern Plantations (LON:AEP) employees are all overseas so won't be impacted
Eldose Babu from UAE has crossed 7% holding in Saga (LON:SAGA) this week. Anyone know what his Modus Operandi is? Can't find much on Google searches.
He also holds a large chunk of Revolution Bars (LON:RBG)
Agreed - Stockopedia does not appear to have a lot of resources for development.
All the more perplexing as to why Stockopedia decided to commit significant resources on replacing the website a couple of years ago. Was it really a priority. In my view the boards are less functional on the new site.
James Cropper has completely broadsided me. I wasn't expecting
"The final two months of 2023 have, however, presented trading challenges in the Paper and Packaging business and a slowdown in the pace at which customers expect their revenues to increase in the Future Energy hydrogen sector of the Advanced Material business."
So the advanced materials division has seen delayed orders as Hydrogen projects have been put back. Why? They blame inflation and higher interest rates leading to higher project costs. Also Govt funding decisions have muddied the waters (I would like to understand more about that) and most worryingly customer expansion plans changing (perhaps higher interest rates are now starting to impact). Anyway in conclusion this pushes major market growth forward to 2026 to 2028!! The revenue trajectory will of course be impacted but the longer term prospects for the hydrogen business remain strong. Reverting to the longer term always slightly bothers me.
Paper products division continues to soften due to falling customer confidence as a result of inflation, compounded by supply chain destocking. Costs appear to have stabilised which is good news in a low margin business.
They now expect to report a small pbt with revenues not below £103m. Net debt will fall a bit.
The key factors clearly Hydrogen being put on a back burner. I wonder if that is related to Trump winning Iowa. Inflation which coincides with what we know and todays numbers won't help. My purchases around £7 are going to be dead in the water for a while. If it wasn't such an illiquid stock I would probably trade out for a while. But for a long term play I still like it and I will add a few thoughtfully over the next few weeks to keep building my holding.
I'm also disappointed by this profit warning from James Cropper (LON:CRPR) . It seemed promising earlier in 2023. Things are not going well for sure. Paper needs to turn-around back to healthy profitability, and Advanced Materials has just fallen off the rails. One-hit wonder with hydrogen projects, or able to diversify and get more sustainable earnings?
Covenants on the debt is a problem IMO. I've done a bit of my own analysis, written quite a bit about it on my Substack, and my conclusion is that they are likely to have to renegotiate terms with the bank / seek waivers, or do an equity fundraising. A 20% dilution (circa £6m) would probably suffice to get them healthily back well within covenants.
Motorpoint (LON:MOTR) down 15%(!) over the past two days for....reasons? no news, no RNS etc
also, got to love the freak-out in the indices because inflation was 4.0% vs the 'predicted' 3.9%!
Indices down all across Europe and Asia so don't really think the CPI numbers are the main factor.
Big falls in Asia apparently due to China's GDP figures coming in at 0.1 percentage point less than expected!
Considering all these figures always end up getting revised, I'm surprised the market takes so much notice of them.
Holding Rio Tinto (LON:RIO) has really made me notice the China updates... its ridiculous.
One day I'll see a headline "Miners down on weaker than expected china data", then two days later "Miners rise on stronger than expected China data"... repeat ad infinitum.
The whole thing just seems like a pantomime for the sake of explaining every 1% or 2% move up or down.
There were significant director sales in Rio Tinto (LON:RIO) recently.
FCA crawling over car buyers being charged too much interest while finance houses and dealers have benefited, Cinch just declared losses of 181 million and Cazoo are near extinction. Perhaps those three are filtering through to Motorpoint holders RJS89?
possibly, but: Motorpoint (LON:MOTR) last year made the very deliberate choice NOT to pass on the increased cost of financing to their customers
e.g hiking APR like all their rivals did. this impacted their profits ofc which the market hated, completely oblivious to the underlying reason why they chose not to pass on the costs in the first place
As previously commented, I emailed Vertu last week to query the possible impact on their business. I have not had a reply. I was a holder but sold this week.
I have done the same on Vertu Motors (LON:VTU) and no reply as well. I have only sold shares equivalent to my initial investment.
Interesting on a down day to see Quartix Technologies (LON:QTX) looking a little perkier. Big volume on Monday. I wonder if we're at trough earnings now, price rises going though February 1st on 80% of subscription base should boost profits. Founder Andy Walters back. Its not cheap at 17x
Seller recently looks to be Buffettology fund, who seem to be selling things across the board to raise cash. Must be seeing outflows? Last increased holding on any company I could find from them was way back in 2021.
yes, buffettology has been selling things down for a year+ at this point
Bioventix (LON:BVXP) is another noticeable one, very illiquid that stock. their buys (at least going from their filings) is Next (LON:NXT) (after they swore they'd never buy another retailer ever again, and Spirent Communications (LON:SPT)
they've also been hit by their man holdings in Focusrite (LON:TUNE)) and Liontrust Asset Management (LON:LIO) being hammered
Am sure you are right - Buffetology has had dreadful results for the last 3 years or more and Bioventix has for years been a top holding - too much for such a large Fund and as a result, depressing the SP for others (I hold Bioventix (LON:BVXP)) as they struggle to sell out to meet redemptions. Another star of the past - Slater Growth have just issued their Dec factsheet - another disaster .
Just confirmed it was Buffettology fund reducing Quartix Technologies (LON:QTX) , from 14.5% to 10.33%
They had a webinar on December 12th where he said "Andy Walters and team are now back in control at Quartix, something we regard as very positive"
3 days later they sold 1.5%, then another 4.14% this week. Just as well he didnt see it as a negative!!!
buffettology fund really has suffered from several things:
a) the OEIC rules e.g limiting top holdings to 10%, so effectively capping their returns on Games Workshop (LON:GAW) which they've held since 2010! when it was £3 a share...
this is alongside the rule that holdings that are more than 5% must not make up more than 40% of the fund etc. terry smith at fundsmith has been very vocal about this, also
IMO it's a complete meme that successful funds MUST sell their best performing holdings down to stay within regulatory limits (that are - i will add - defined by people & groups that have never ran money or invested others' money in their lives!) nothing to see here, just Big Paternalism running wild in the UK regulator(s), as per usual
and secondly, b) due to being an OEIC, buffettology has ofc been hit by the redemptions due to people selling their fund holdings as you've mentioned related to this: they did open the FreeSpirit fund as an Investment Trust (IT) IIRC, but unsure that it's done much
thirdly and lastly, c) their obvious UK bias, particularly their shopping around the small cap & AIM areas. they have had some investments here work out very well but ofc when people are selling, that is when the lack of liquidity and ridiculous price movements downwards occur, which then becomes a self-reinforcing spiral!
I agree RJ the rules are absolutely stupid.
If im paying someone I want him to beat the market, so he has to be able to do something different to the market. That may mean having 30% in one company or moving to 50% cash if thats what he thinks is best.
This is what Id pay for, not some crappy sub par tracker forced to sell at the lows.
heh, I feel obligated at this point to mention that Apple (NSQ:AAPL) is actually not ~50% of berkshire; it's closer to ~18% due to their privately owned insurance subsidiaries, the railroad, berkshire hathaway energy etc! but that is pedantic nitpicking from me ;)
but yes, buffett is the very obvious case here, seeing as he manages the largest actively managed equity portfolio in history! he has the vast majority (~90%+) of berkshire's $300B+ public equity portfolio in 10 stocks, but really it's mostly in 5 stocks as your infographic demonstrates
another example would joel greenblatt in his first 20 years of running gotham; quite often he only held 6-8 stocks, sometimes less than 5. michael burry would be yet another example following graham's & buffet's approach, holding very, very few securities and being extremely patient and selective
there have been individuals who have had success(es) running a large(r) amount of securities (30, 50, 75, 100 etc.), mostly notably ben graham himself! as well as one of his proteges and buffett's fellow student i.e walter schloss. but it should be stressed that their approach was not remotely the same as the one being followed by the vast, vast majority of fund managers who are, as you correctly put it, holding 60, 80, 100+ stocks and are closet index followers!
a more modern example would be rich pzena who holds 70-80 stocks because he is running billions (~$30B IIRC) and has done very well in spite of the handcuffs that running that giant amount of money places on you, from an investment choice standpoint.
rich pzena was coincidentally (hint: not coincidentally at all!) the research partner of....joel greenblatt, when they wrote a paper together (pre greenblatt's gotham days) shouting about ben graham's approach to stock-picking, and by extension, buffett's early days. they were right ofc, not that anyone seemed to notice
but yes, the short version is: you want outstanding results, you have to do something different. and holding 100+ stocks mostly from the FTSE 100, or holding making your top 5 holdings identical to the S&P 500...that is not going to do it!
Things which are obvious in hindsight- episode 381
888 Holdings (LON:888) 9 Sept 2021. William Hill Acquisition (red arrow on the chart) added huge debt risk. This statement on raising funds at "an appropriate time" in particular should have alerted me to potential downward pressure on the shareprice and maybe looked to go short. Wasnt smart enough at the time unfortunately. We live and learn.
"To create a more beneficial long-term capital structure, 888 expects to raise approximately £500 million of gross proceeds by issuing new equity via a capital raise ("Capital Raise") to be undertaken at an appropriate time, such that pro forma net leverage ratio is under 4x."
Pennant International (LON:PEN) - price has crossed 50d SMA. It was discussed a few days ago - fcst p/e of 7.6 and peg of 0.5 with a couple of astute IIs on board. Getting noticed now. Last year a trading update was issued on 8th Feb.
New contract on the way:
The Flight Simulation and Synthetic Training Team, part of the United Kingdom Ministry of Defence ("the Authority") intends to place a new contract with Pennant PLC ("Pennant") for the repair and software maintenance of an updated Virtual Reality Parachute Trainer (VRPT 3) at RAF Brize Norton. The Authority intends to place a new contract with Pennant for a value of £670,000 for a period of up to 5 years, plus 5-year option.
https://www.contractsfinder.se...
Great find!
Thanks for highlighting Pennant International (LON:PEN) eParo, I hadn't seen that, a small win which is why not reported but further endorsement of them being in the right sector.
According to broker notes they are on a prospective FY24 EV/EBITDA of just 3.5 so they are cheap, which is a good starting point.
However they have been stuck in a 40p-25p trading range for about 3 years so I think it will take some more significant news flow to move this one back up to where it once was.
I hold and am feeling good about the company I am keeping here (young guns in Rockwood, Dowgate & Crux) all recent buy ins so let's wait and see. Lots of upside potential and I think limited downside, roll on Feb's trading update..
Pennant
I’ve been building an ok stake in past 3 months buying on all the dips to 30p level . Takes a long time to build a decent stake in such in illiquid company and even longer to get out in the event of a negative so be careful it comes with value trap risks .
I think Rockwood have sone M&A ideas to push onto the board here which could be interesting .
Sector is red hot and they have good technology that is on the money, I heard they are tendering for lots of projects and they take a bit of time to land so expect a lot more news flow in 2024 .
There were a lot of buys day before yesterday .
Think this is about to punch out of its 30-32 range and head up to a new level .
I’ve posted about this before. This is an excellent bulletin board with an ever widening range of investment comment. Thing is though that it’s increasingly becoming the case that the small companies that Paul and Graham cover in such depth here that involves them in masses of work and time are getting ignored.
This is THE Stockopedia thread to go to partly because of the high quality analysis from Paul and Graham, but also because this is the one that often sees 100 or more mainly good quality posts every day.
But there are so many other very good threads on Stockopedia with a wide range of topics covered on them that unfortunately see very few follow up posts. That even applies to threads started by Stockopedia’s own writers. Why don’t more of the readers of and the posters here look at those threads too?
There’s far more to investing than just Uk small companies. That’s getting covered on other threads, and with a bit of success after hard work from the likes of Charles Mitchell,Donald Pond , ShoeShineBoy and a few others, on Investment Trusts,but a lot of threads just die.
An example of a great article with near zero follow up was the one from Roland Head yesterday on Harbour Energy (LON:HBR)
I’ve done posts on Bargain and Investment Trust threads that got single figure up ticks and little or no follow up, but when I decided to post a couple of them here there were a lot of ticks (over 100 once) and some excellent follow up posts too. But they were off topic for this thread.
One idea might be a “catch all” thread for a wide range of topics.
Nobody else seems bothered about this and if everyone is happy with the status quo and if Paul and Graham aren’t bothered if the majority of posts on their thread become even more not on the shares they cover, then there’s no reason to change anything. But it seemed worth posting this in case there is more widespread disappointment at the lack of subscriber interest in threads beyond this one.
Graham's post yesterday was excellent, but often those articles are about an individual stock and the number of comments on the article reflects that. I agree that a general thread could be of use to discuss companies not reporting that day, but I think we would need to see a big uptick in comments and subscribers to make that a necessary requirement. I find 100 comments manageable and do like the one stop shop, although I do explore the other threads often. I would enjoy a US and/or FTSE100 daily thread to complement the SCVR, but that would require additional writers!
The Stockopedia board has become a bit unstructured so that all sorts of conversations appear on one thread. Its becoming difficult to navigate and any good ideas from contributors have to be jotted down or lost forever due to the lack of in-thread search facility.
It would also help considerably if all contributors put the name of the stock they are referring to at the top of their post so that anyone on unthreaded default can quickly determine what the comment is about.
Stockopedia dont answer emails or seem to want to improve the situation so I dont expect any change soon.
hi intuitive6191
any good ideas from contributors have to be jotted down or lost forever due to the lack of in-thread search facility
Agree this is a shortcoming on the daily SCVR comments.
In the absence of a fix, when I read an interesting comment on SCVR and think I might want/need to refer back to it in future I copy and paste it as a note on the relevant company Stock Report.
Very easy to do and I often find myself referring back so I do find it helpful.
Snazzy
Thank you Snazzy
You can try the following to search the Stockopedia site for a keyword.
Stokopedia site search
Click that link and it should open another search window. You can change the Filtroinc part to any word you like to search the overall site - I then tweek the dates etc on google chrome to narrow my search results
Does not work for me. Many of those are Stockreports, some not even Filtronic (LON:FTC).
You can use this if it has been tagged: https://www.stockopedia.com/sh...
The problem is there is so much buried in the SCVRs and elsewhere on here, it is a job to find it, even if you know which day it was.
Hi Rusty2, this is what comes up for me when I did that search. It does needs us all to remember the put the stock symbol in though. It is not perfect I agree and a proper search function would be great.
Also the only thing with the stock search you suggested and I also use is I find is that it will only bring up results if the author has put in the symbol in the title - so on your example the SCVR from Monday 15th where Filtronic was discussed by readers but not in the main title by Paul & Graham means it is not picked up by that particular type of stock search but is by my example.
Hopefully Stocko team are working on a proper search feature otherwise lots of good input gets lost...
That is strange because that is not what I got from your link. Maybe it depends on your device or internet interface you use? I'm using an iPad.
Yes that is strange, the link was from my laptop (using chrome) but I’ve just tried from my iPad (safari) which is where I’m typing now and I get the same result… I do have it filtered for just the past week if that makes a difference ? Another reason why a proper search function within Stocko is needed!
I think the problem is the way Stockopedia has set up the discussion side of the website.
The SCVR is the first port of call for most regular users for 3 reasons. First. the quality of the analysis by professional writers who are very good at what they do. Second, it's highlighted on the landing page. But a really important reason is that it isn't a thread, which is what has been created for Investment Trusts. It's a Blog, and therefore it is a new thread every day based on news.
Ed Croft and the team need to think about this because I know I'm not the only member who is reviewing their investment strategy. I have lost confidence in the UK investment marketplace. It's too small and it's going to get smaller. It's desperately illiquid and the institutions can't provide liquidity - an extreme case is Downing Strategic Micro-Cap Investment Trust (LON:DSM) winding up. Their commentary on this decision begins: 'The decline and demise of the smaller companies’ markets in the UK are now part of the daily narrative of the ecosystem. The facts are stark' The IPO model seems broken and therefore the UK doesn't offer sufficient exposure to the businesses of the future. Yiannos' quote from BnB speaks volumes: ' The US is on to the next big innovation (AI) and we are still discussing the prospects of a teapot maker!' (Portmeirion (LON:PMP)).
I suggest that Stockopedia needs Blogs like the SCVR for USA and European markets, and ideally for collective investment opportunities like Investment Trusts. On the Investment Trust thread I suggested such Blogs could be started by members rather than staff writers at no cost, to see if they work, but it would have to be possible for several people to have equal access to a Blog in the same way as Paul, Graham, Roland etc. have access to the SCVR. An easy way to test this would be for Charles and Ken Mitchell (unrelated!) to be able to start an Investment Trust blog where they share the task of keeping it alive and hopefully can recruit (and vet) others to help.
Hi Michael C,
Some very interesting ideas in your post but on a brief look at Stockopedia’s financial accounts then one can easily assume that the resources are not there ; and it is indeed the subscribers that will have to take the initiative and perhaps take this forum to a more diversified level.
Thanks
I tried to do this with Filtronic (LON:FTC) yesterday. I think most companies should have their own thread where they can be discussed and a sort of narrative maintained outside of the SCVR
I agree, I was already aware of the financial position, the resources probably aren't there.
I think having the ability to search the threads for key words would be a great help, I raised this as a request with Stockopedia a while back, but it doesn't seem to be a prioirty for them. Like many on here I find as much value in the discusion threads as I do in th stock analysis tools. Perhaps they should ask as us the subscribers to contribute ideas on what we would like as enhancements and then allow us to vote on what we would like to see ?
Hello Snavira. If you are on Windows, and all the text is on the same page, then you can search for any words by pressing " Control" & "F" keys together. It also works for things like company annual reports and saves a lot of time. I would really like to vote on Stockpedia improvements as per your suggestion.
More outflows for Liontrust Asset Management (LON:LIO).
I wonder what their chances are of picking up any of the inevitable outflows from Jupiter Fund Management (LON:JUP), from the funds managed by the soon to be departing star fund manager? In my experience, institutional investors don't hang around waiting for the manager to leave before moving their money - they and their consultants will already be looking around for alternatives.
So there's potential for any of the UK based fund managers to pick up a few billion from Jupiter, but it's anyone's guess as to who will be successful! But in my opinion, expect to see larger outflows from Jupiter than their competitors in the next few months.
The problem is there are dozens of fund managers all offering very similar funds so no reason why Liontrust would get them. One of the reasons that I'm cautious on the sector as it's very difficult to stand out, unless you have a particular niche.
Decent 20,000 share purchase by CFO today Liontrust Asset Management (LON:LIO)
I bought Spirent Communications (LON:SPT) high and sold low last year, and lost faith in management along the way.
While their commentary through the year did flag possible weakness ahead they were buying back substantial numbers of shares which implied to me that they at least believed it couldn't be that significant.
Then they dropped a PW which knocked about 30% off the share price. So far at least it seems to be recovering rather than following the 'normal' PW pattern, which just rubs salt in the wounds!
I just feel in terms of capital allocation and communication management played things really badly last year.
Well a pretty grim start to the year after the excitement of the Santa rally. Reading through all the investment commentaries on Bloomberg, the general view now seems to be that the market got well ahead of itself in pricing-in how quickly inflation and (hence) interest rates would fall. On top of that you've got all the uncertainty over the situation in the Red Sea and (further ahead) the distinct possibility of a Trump presidency. Feels like things might remain volatile for a while, although I guess gives the opportunity to pick up yet more bargains! Staying largely fully invested, but with a little cash on the side lines to take advantage of further weakness.
I suspect that a Trump return is more likely than a ' distinct possibility ' Bouden54... unbelievably he's come in from 20 -1 to the favourite at 1.32 - 1
The bigger problem unfortunately is liquidity. Share prices are being marked down heavily on very light volume, suggesting once again that no liquidity is returning to the market alas. That means we are at the whim of wildly exaggerating macro news. A tiny rise in inflation over Xmas causes woe and gnashing of teeth, it will probably fall more than expected in Jan as promotions take effect…..but actually it is all very marginal.
Ironically though this might be good for corporate earnings. If you look at PPI it is zero to negative so if consumer inflation is 4% that suggests the companies we are looking at may be seeing increasing margins that have not yet been passed on to the consumer.That’s good for earnings.
At the moment though UK stocks are way too volatile against what is very marginal changes in macro conditions……. Sigh
is a trump presidency a bad thing ? i thought he was pro business? would the markets not prefer him to sleepy joe? i was looking on oddshcecker last night and bookies say trump has way more chance of getting in than sleepy joe - albeit if you look at democrats v republicans its not far of being 50/50 call.
I would have guessed 12/18 months ago Trump had zero chance of winning there ya go - seems like the working class peeps are suffering the same problems as the uk with immigration causing issues for local services eg cities like Chicago with then poor now have boat load (not actual boat) of immigrants to deal with. Note i am not saying trump will actually sort out here.
I think markets are more concerned about the geopolitical implications of a Trump presidency (eg potential trade wars with China) rather than his domestic business policies.
Imo rmillaree a Trump presidency would be a very bad thing. He showed disdain for NATO, close to praise for Putin and generally left political situations worse every time he got involved. The 96 criminal charges are not fabricated. Did you read Christine Lagarde's warning a day or two ago on his attitude to allies and the EU?
Apropos of nothing in particular, I have been digging through an old notebook of mine. I came across an entry from 9 Jun 2015 which I thought would be interesting to share ...
It concerns a fund manager by the name of Hugh Yarrow, who was billed as "Woodford's heir". In retrospect, that's not such a great accolade. He gave picks for 10 top dividend growth stocks. I'll list the stocks below, along with their performance over the last decade in percentage terms:
RKT 23.7, BRBY -15.2, SGE 177.2, SXS 44.9, PZC -63.4, ERM ??, ATKW ??. ROR 15.1, DPLM 384.4%, PAY -52.4.
RKT used to have the symbol RB. I don't know who ERM or ATKW are or what happened to them. Perhaps someone could enlighten us.
If I exclude ERM and ATKW from the calculations, then the mean return was 64.3%. If I assume that they both went bankrupt (which seems less than likely), the return drops to 31.4%. I suspect that they may have been taken over or renamed.
Even on a pessimistic basis, it still beats the return of the ASX (All-share) which returned 13.9%.
All of that is on a capital basis. Neither has been stellar, although Yarrow has certainly outperformed. On an annualised basis, 64.3% works out at about 5.1% compounded. The ASX works out at 1.3%, giving his portfolio an annual outperformance of about 3.8% By pro manager standards, that's really good.
To bring things up-to-date, Yarrow runs the Evenlode Income Fund, and his returns since inception have been impressive against the index.
Here are his latest reported top 20 holdings, which make up 74% of the portfolio, from highest holding to least: RELX, Unilever, Diageo, Reckitt, Bunzl, Experian, Sage, Spectris, Intertek, Compass, Howden, GSK, London Stock Exch, SGS, Hays, Page Group, Savills, Roche.
Readers will notice a lot of crossover with Nick Train. No Burberry, which is interesting.
So, those are my thoughts for the day.
Thanks, Mark. There are some remarkable yields available today with high StockRank companies. We hold Smiths News (LON:SNWS) Y9% twice covered. SR99. Taylor Wimpey (LON:TW.) Y6.6% 1.6 covered, SR 97. Bank of Georgia (LON:BGEO) Y6.69, four times covered, SR99. Redde Northgate (LON:REDD) &7.2, 2.3 covered, SR 93. International Personal Finance (LON:IPF) 8%, twice covered SR 98. There are many more.
IMO there's good, lower-risk value here.
I also hold almost all of the stocks you mentioned. Apart from WH Smith (LON:SMWH) and Bank of Georgia (LON:BGEO) .
Whs because in 2004 i sat in a meeting and couldn't work out what it was for (oh for time travel)
Bgeo because I always felt it was too cheap or too expensive.
Bottom line: my subjective opinions are less useful than the SR.
Andrewdb. Thanks for the reply. It was Smiths News (LON:SNWS) in my list of high yield, high SR shares, not WH Smith (LON:SMWH) .
Agreed. There is a lot of value available at the minute. Eventually translates into rising prices but when that occurs who knows.
I don’t think there is a lot of value available at the moment based on growth and future earnings. Maybe there are some companies that they should be trading +50% of their current prices but value as in growth is very very limited.
Please share with us companies that you think they offer value and growth.
Thanks
"Please share with us companies that you think they offer value and growth"
Great question - here are 5 that I hold and think merit that description:
Volex (LON:VLX) Renold (LON:RNO) Bloomsbury Publishing (LON:BMY) [OK maybe I am pushing it on 'value'] Severfield (LON:SFR) Norcros (LON:NXR)
Also a happy holder of Redde Northgate (LON:REDD) but agree it is not forecast to grow significantly next year - it will in time, I believe.
FWIW I own some REDD and BMY.
I listened to REDD's online presentation late last year (https://www.investormeetcompan...) and liked what I heard. Maybe I'm too easily swayed by management, though. They seem happy with leverage position, with interest rates fixed for 10 years. They noted a structural trend to outsource, which they can take advantage of. They also said that the customers like the integrated services that REDD provides. In other words, rather than fiddling around with several suppliers, customers can choose to use one simple platform.
BMY also seems to be doing really well. They seem excited about the Sarah J Maas books, so expect to hear good news about how it's going when they next report. There's a Netflix Series of the "Three Body Problem" coming out this year (?), and well as Harry Potter TV series. Their digital services also seems to be progressing well, and they're increasingly producing audio books. The shares are reasonably priced, and it all seems quite bullish to me, at least.
Also on Redde Northgate (LON:REDD) I like the way the share count is steadily going down year by year, at the same time as the book value is going up. I know the SP has gone sideways for over two years, but those factors will eventually have an impact. Like you, I rate the management highly.
Bloomsbury, I hold and would add for what it is worth that:
Impossible Creatures by Katherine Rundell was Waterstones book of the year. This is the first book in the trilogy. Also there is £39m of cash on the balance sheet looking for acquisitions.
It wouldn't surprise me if there is a second 'ahead of expectations' announcement prior to the final results in May.
I hold Renold (LON:RNO) from these and one that probably will be acquired this year.
I did hold Bloomsbury Publishing (LON:BMY) but I found it a bit boring.
Volex (LON:VLX) I have never got involved in it for personal reasons.
Severfield (LON:SFR) hasn’t gone anywhere for years and Norcros (LON:NXR) I have never researched it in detail.
Redde Northgate (LON:REDD) I will not personally touch it.
Thanks
I bought Redde Northgate (LON:REDD) about three years ago and with reinvestment it's yielding me now an incredible 16.5% on original cost
is it skill or luck if two out of 10 picks have massively over delivered ref gains - to me it looks like 8 out of 10 picks (or 6 out of 8)overall delivered negative returns - that sound pretty poor stock picking to me saved by 2 lucky ones.
Fair enough, but it's difficult to say. It's not uncommon for the outsizing to be concentrated in a couple of positions. So on the one hand, yes he was lucky to pick a couple that went to the moon, but on the other hand, no, that's how the market works.
The latest factsheet for Evenlode Income is available here:
https://evenlodeinvestment.com...
The performance since launch has been impressive compared with the index, so I don't think it's just luck.
There is also a case for style investing. Can outperformance be merely a function of style? In Terry Smiths case, it seems that he may have been able to add about 3 percentage points pa.
10-year annualised total return for Funsdmisth has been 14.96% (https://www.morningstar.co.uk/...) whilst that for the iShares MSCI USA Quality Factor ETF has been 11.88% (https://www.ishares.com/us/pro...)
Hi Mark - I was into Evenlode / Yarrow but got out some time ago. I could not accept his steadfast faith in Unilever and Diagio which even today are at the top of his holdings The fund is definitely below par over the past 12 or so months. Just look at the Cumulative perf over 3 years.
Fair enough, but it's difficult to say. It's not uncommon for the outsizing to be concentrated in a couple of positions. So on the one hand, yes he was lucky to pick a couple that went to the moon, but on the other hand, no, that's how the market works.
I would agree but statistically speaking the variance can be that big that it can almost be as much chance of having only 1 big winner as 2 and there is fair chance it could have been be zero if they got 2 - ok it might be he was unlucky and could have expected to have had 3 or 4 big winners. Its probably somewhat unfair to throw stones though if the reality is the portfolio would have been trimmed perhaps to get rid of the bad uns before they went super bad - my comments were somewhat throwaway in nature its always good to take a look at stuff like this. As you say if teh overall numbers stack up we probably shoudlnt get petty in our criticism.
What is does evidence though is that if these were seen as very safe steady picks for the long term over half of em turned sour so thats not great advert - albeit no surpise with how much stuff has moved on in the last 8 years - i think any portfolio needs monitoring at least once a year unless its invested in greggs and wetherspoons (that is a joke comment)
Note ref commending Fundsmiths there is the danger they have been the lucky ones the last 10 years - starting with a sample of 50 good fund managers the one at the top that is probably most likely to be "benchmarked" with regard to how it can be done right - the reality can be they may have been the luckiest one of the bunch if we are being honest . From what i have seen of fundsmisths though they do seem to be a cut above with regard to quality of picks so again i wont knock em.
ERM was Euromoney which was 70% owned by Daily Mail for years and I think got bought
Portmeirion (LON:PMP) Why cant the CEO say what the broker is saying. I dont like the company, they sugar coat things then use the broker to push through the downgraded numbers
"FY24 Outlook
Following a positive Christmas performance, we expect sales to return to growth in 2024 YOY alongside a healthy operating margin improvement compared to 2023. However, we expect 2024 to be a challenging year due to ongoing macro uncertainty with customers remaining cautious in relation to H1 order flow, in particular in the US and Korean markets. In addition, we expect to continue to incur higher interest costs during the year given current rates."
Broker view
"Outlook - Following the positive Christmas trading performance, we have maintained our sales forecast at £105m for FY24F, but noting a challenging year is expected and the combination of the expectation of tougher trading in the important US and S. Korea markets and higher interest costs has led us to reduce our adj. PBT forecast to £4.5m from £6.0m. .........Similarly, we have maintained our FY25F sales forecast at £110m but with cautiously no or little recovery expected in the US and S. Korea we have conservatively reduced our adj. PBT forecast to £7.0m from £9.5m."
Completely agree. Believe that's the 3rd time Portmeirion (LON:PMP) have done that in the past year or so....likely we might bump into the CEO next week, on a Tuesday!
Portmeirion (LON:PMP)
Why cant the CEO say what the broker is saying
Agree 100% communication from this company has always been below par - they skirt around the simple task of saying how it is by using mumbo jumbo or simply not advising. I will sort of be fair to them today - i do appreciate honesty so if they expect to make less this year at start of year at least they are getting that fact out into the open even if its bad news for holders (i am stupid enough to still be holding having not exited when i should have done). Note i would say when they use the term "challenging" its pretty clear that that should be taken as indication that this is likely to be a downgrade - absolutley ridiculous that they cant say it. I have to presume they have had words with broker ref broker update ? - or its it possible broker has been given sight of today release with no info and said this is worse than useles and taken it upon themselves to do hatchet job (very unliely i would have thought)
Ps love the early updates of new broker forecasts before the opening fantastically useful to get that info out. Your prior flagging of downgrade did exactly what the company should have done themselves in the rns but didnt.
I think it was BnB that said that the US is on to the next big innovation (AI) and we are still discussing the prospects of a teapot maker!
Haha very true Yiannos - I think UK companies who have started to utilise AI to produce something tangible (rather than just name dropping AI into their RNS) could see a good year. My two holds with this in mind are Poolbeg Pharma (LON:POLB) who are utilising AI to speed up drug discovery and Eagle Eye Solutions (LON:EYE) with their new EagleAI service. Poolbeg is very dependent on the old Amryt team coming in and making some acquisitions to make the company profitable and get the NASDAQ listing sorted out, I recognise it's higher risk, higher reward because of this.
Card Factory
Really does look to be a case of Mr Market having a meltdown .
Online down doesn’t bother me as everyone knows online is down, when online is down in store is picking up .
Started buying at these levels .
Looks the wrong price
I once met Dean Hoyle the original founder who went on to buy Huddersfield football club .
I am of the impression that the reason will be down to Teleios selling down their stake. They’ve sold after the past few updates and have roughly halved their position in the last 6months or so from c.20% down to c.10%. I’m expecting another holdings RNS in the coming days and weeks.
re Card Factory (LON:CARD)
Just be aware some prominent X promoters of this stock have cut and moved on now.....
And in a very shifty fashion, having been pumping it until the last minute!
Yes - Cockney Rebel has been talking about it persistently for a long time and cut most of his position though it still makes up 3% of his portfolio apparently and he’s saying it is very cheap here. Make of that what you will…….
What I would say is that unless you are trading in and out of stocks it is best to ignore promotors.
Personally I think Card Factory (LON:CARD) valuation is bonkers at this level irrespective of what Cockney rebel and his pals do. It is on a PER of sub 7* will start paying a dividend again in May and net debt should be right down and is no longer a concern. That’s a bit of a virtuous circle as interest costs decrease which also helps the bottom line. If you think about the update they were at the top end of the most bullish analysts, so whilst not a beat as such it was a beat against almost all analysts. Notwithstanding that they reaffirm the medium term capital markets objectives which are worth watching imo.
Personally I am beginning to wonder whether Telios really are selling down their position or if they were just trimming previously. There have been no RNS’s since last results so am watching next few days.
I actually think it's reached a point where there is only good news left to factor in with regards to Tellios. An RNS gives a reason for the fall and evidences their decreasing share, investors like this as once they are fully cleared you expect a bounce up. A lack of RNS over the next few days would show Tellios aren't actually selling and there isn't a barrier that needs to be broken through, so nothing actually stopping the SP climbing. Maybe I'm just looking through rose tinted glasses after a couple of days of big losses!
I think he sold Card Factory (LON:CARD) because it was not going up, got to 115p then drifted down again, he saw Watches of Switzerland (LON:WOSG) taking off and bought them. They have since fallen back, maybe he sold? He is also in Avon Protection (LON:AVON) which is soaring and CMC Markets (LON:CMCX).
Lots of alerts going off but some are misleading. Email from Stocko saying Mortgage Advice Bureau (Holdings) (LON:MAB1) buy is under 740p, it is not, it is around 794p. Spoken to Stocko about this in the past but they insist the alerts are correct. I want to know when the buy price is below a certain price not the sell price. It does highlight how wide some spreads are.
What are you talking about? Mortgage Advice Bureau (Holdings) (LON:MAB1) price is 738.67.
Rusty2 is correct. If you look at the trading under ‘Full Quote’ on the SR it shows (only) 1 trade of 988 shares at 738.67, the ‘price’ you refer to. However, the quoted bid – offer spread is 752 – 798.
Mortgage Advice Bureau (Holdings) (LON:MAB1) No it was not, that was a sell that went through, the live price to buy was 394p. Stocko prices are very misleading. According to my broker price had not changed.
"Stocko prices are very misleading"
Totally agree. It annoys me when a small cap share with a 98/102 share quote all day goes from +2% to -2% every time a buy is replaced by a sell or the reverse.
I always go elsewhere for prices and LSE is good for trades. In this case:
https://www.lse.co.uk/ShareTra...
You will notice that the 738.666 trade was within the spread at 16 seconds after open and that the next trade was at 09 37 so would not show up on Stocko until 09 52 at the earliest.
It is now showing the 13.13 trade at 788.
Galliford Try Holdings (LON:GFRD)
I hold.
My preferred share in the infrastructure arena, despite being more highly rayed than Costain (LON:COST), but it has no bank debt or pension obligations and continues to run with a significant net cash position, albeit most is likely to be customer advances.
It operates predominantly in regulated sectors and carries out significant amount of work with the water industry, where it continues to build its specialism through bolt on acquisitions. It also has a collection of PPI investments, valued at around £40m that make a useful cash contribution.
It has just completed a £15m share buy back programme and pays a good dividend of around 5%. The company has some very good Glassdoor employee reviews that support the view of a good management culture.
Bill Hocking, CEO has done an excellent job since his appointment.
that's a very risky choice - in the past galliford had been prone to disasters. Its profit markets were too tight like 2% so very risky?
Galliford is a completely different proposition under the current management . They have been very clear that they won't pursue the open ended contracts which resulted in previous disasters (Queensferry crossing and Aberdeen ring road ) . CEO is excellent and backed up by an equally impressive Fd .
Post the demerger the balance sheet has been rock solid with net cash often close to market cap and the pension liabilities all went to the housebuilding side of the business . They are also very choosy in only entering into contracts where they have the geographical coverage in place . Kicking myself for having sold too early !
Hi Ben
I take your point about low margins, but it was ever thus in construction related companies. As for Galliford Try Holdings (LON:GFRD) one needs to get underneath the bonnet to fully understand the transition from its former guise as a basket case under previous management to a credible turnaround since Bill Hocking's arrival as CEO. The sale of Linden Homes effectively eliminated debt and current management is very risk conscious and now generally only takes on contracts on a cost plus basis as opposed to fixed price.
As I mentioned previously they have no bank debt or pension liability unlike Costain (LON:COST) or Kier (LON:KIE) and from memory the maximum contract size is £25m, anything larger needs to be agreed by the Board. I particularly like the exposure to the water sector where it has built up a specialism. You only need to look at the share price appreciation in the last year to see that management's strategy is working. This is the second upgrade in the last year.
Regarding margins and revenues, the company's current growth strategy is for £1.6 billion of revenue and 3% margins by 2026 for which it is on track to achieve..
No one gets it right all the time but you may want to watch Paul Hill's interviews with Richard Staveley, manager of Rockwood Strategic (LON:RKW) , Sid Lall of Canaccord Genuity and Chris McVey of Ocotopus Investments to get a better understanding of the investment thesis. All of these interviews are available via the discussion button on Stockopedia.
All the best
Any idea why stockopedia says they are a company in financial distress?
No idea Smig78 they have a load of net cash on the balance sheet and no debt.
Not a lot of positives to take away from Frontier Developments (LON:FDEV) interim results. Though it is as I was expecting. Sales of their new release Warhammer Age of Sigmar: Realms of Ruin have been lower than expected. F1 Manager sales declines 34% YOY, even with the release of the new 2023 version. However the back catalogue continues to deliver, providing 72% of revenue.
They have a plan to go back to what they are good at, CMS (construction & management simulation) games, which I think is definitely the right move. Though they are now in a transition period to get back to that, which, along with underperforming new releases (not in the CMS genre) is hurting their results.
This new push in CMS games isn't going to arrive until FY25 & that first release has to be a success. They have proven they can make market leading games in this genre though, so there's nothing to suggest they can't do it. But for now its looking quite ugly. (I hold)
Thanks for the cheat sheet!So simple to understand.I hold too.Not understanding the sector it was a punt and a mistake in that respect, as i guess they're like movies some being hits and some not.I was hoping for some of the Games Workshop Warhammer effect.
Some consolation that I have been ferverishly reading online gaming rags since re how many other game dev companies have been having a rough time ,( like Paul's mentioned before perhaps more of an indutry issue currently too?) with restructurings and raising money like much bigger Embracer this July.
I decided to hold through results and still hoping they can turn things around!It'd be lovely if they manage to get the company back to the good old times and pull a future multibagger out of the hat.Hopefully the market is assured they are fine for now for cash.
No worries. Yes the game industry is very dependant on continued high quality releases, which unfortunately Frontier have failed to do recently. I believe that as long as they get back to releasing high quality games it will be a multi bagger from this point. They have a proven pedigree in the Construction & Management Simulation genre so I don't see why they can't continue to make great games in that space.
As you say the whole game industry has been struggling recently, with even the biggest developers having to cut costs with huge amounts of lay-offs industry wide. It's just amplified with Frontier because of the underperformance of their recent games.
With the share price reaction today I have to believe all the bad news is priced in at this point. Of course more could go wrong, but maybe we're at or near the bottom now? I also think they look like a great takeover target. They have a strong portfolio of proven IP, strong fan base & a very talented team of developers. It would probably be a great pick up for one of the larger players like Microsoft (who are buying tons of developers to bulk out their exclusive offerings), EA, Tencent etc
GFRD - please. Ahead of statement although Stockopedia says company is in distress.
Couple of broker upgrades this morning.
Concurrent Technologies (LON:CNC) PBT '2023 +6%
Nexteq (LON:NXQ) Cannacord 2023 EPS + 13% 2024 +10%
Portmeirion (LON:PMP) PBT cut 36%
James Cropper (LON:CRPR) looks like 2024 EPS cut by 95% Ouch!
Thanks again Wolf for the Nexteq (LON:NXQ) tip, great entry point when you highlighted it.
FY24 EV/EBITDA of just 3.5 times, less than half its peers.
Projected cash of 37% of its mkt cap and a free cash flow yield of 11.5%
Broker target prices raised across the board, some as high as £3
At £1.20 still very cheap and very good value, have to find something to sell in order to top up!
Would be interested to hear views on Concurrent Technologies (LON:CNC) - it's small and has been highlighted elsewhere (Inv Chron I think) - I would expect directors to have a decent holding but No. What thoughts please ?
Concurrent Technologies (LON:CNC) I like it a lot but for me the price is up with events, would look to buy on any decent fall backs
Id agree with that Mr O. Im looking for 90-100p this year as a target on Concurrent Technologies (LON:CNC) So far things looking pretty good. Forecasts for 2024 set for possible beats Id say, but im just guessing like everyone else.
Miles Adcock knows how to play the game, maybe a little too much. But rather that than no updates for 6 months. So far things going in the right direction, just have to let it play out.
UK CPI will attract attention but 0.4% whilst a little high is not a game changer. Jan data was weak last year but was then followed by nos approaching 1.0% MoM for feb, Mar, Apl, May.... so prospects remain for data to weaken this year and a relatively small miss can be ignored IMO. Sterling has hardly moved.
Thanks very much RDHOWARTH. The voice of reason on a 'red' day!
I keep an eye on the truflation web site, who obviously use a different methodology to the official statistics, but the trend there is clearly down. That gets updated every day. You can also see the impact of different categories - according to them alcohol & tobacco has barely moved!
Sadly the market doesn’t seem to agree. Most indices down close to 1.5% this morning. . My portfolio value which doesn’t even hold many more speculative small caps is heading back to where it was end October 2023 before the pre Xmas rally. Very dispiriting- a trip to warmer climes would help and I note from today’s SCVR that Paul Scott has upgraded his accommodation in sunny Gozo. The digital age equivalent of the ‘wish you were here’ postcard
Just FYI Paul/Graham, Concurrent Technologies (LON:CNC) trading update is actually ahead of previously upgraded forecasts (twice) for FY23. Worth a closer watch now as last year was the heavy investment year doing the lifting for more stronger FY24 and 25 IMO. I hold
Gulf Marine Service Gulf Marine Services (LON:GMS) produced a positive trading update, dangling the prospect of a return to the dividend list. Debt is extensive but coming down. I hold for a change.
My morning smallcap tweet: The double-sausage full smallcap breakfast
Mulberry (LON:MUL) Corero Network Security (LON:CNS) James Cropper (LON:CRPR) Portmeirion (LON:PMP) Concurrent Technologies (LON:CNC) Nexteq (LON:NXQ) Churchill China (LON:CHH) Tialis Essential IT (LON:TIA) Galliford Try Holdings (LON:GFRD) Hornby (LON:HRN) Gulf Marine Services (LON:GMS), Brooks Macdonald (LON:BRK), Mission (LON:TMG), Wincanton (LON:WIN)
◄Mulberry (MUL)► Q ending Dec rev down 8.4%. Co maintained its full price sales approach. Blames macro and and decline in luxury consumer spending. No FY guidance. [SP=160 Cap=96m]
◄Corero Network Security (CNS)► guides FY-Dec rev up 11% and ARR up 17%. In line? "This strong performance continues to improve earnings visibility...well positioned for revenue growth in 2024." [SP=8 Cap=40m]
◄James Cropper (CRPR)► warns FY-Mar rev c. £103m+ and only a small adj pretax, materially below management expectations. Blames weak Paper and Packaging sales and slowdown in the pace at which customers expect their rev to increase in the Future Energy hydrogen sector of the Advanced Material business. [SP=793.2 Cap=76m]
◄Portmeirion (PMP)► guides FY-Dec rev at least £102m, marginally ahead of consensus and pretax in line. Outlook - expect sales to return to growth in 2024 with a "healthy operating margin improvement" but still challenging due to macro uncertainty and higher int rates. [SP=270 Cap=38m]
◄Concurrent Technologies (CNC)► guides FY-Dec rev c.5% ahead of market expectations of £29.5m and adj pretax slightly ahead of exp of £3.5m. [SP=79.7 Cap=68m]
◄Nexteq (NXQ)► guides FY-Dec rev only $114.8m down 4% but adj pretax comfortably ahead of market expectations which are $119.6m and $12.7m resp. Outlook - "market conditions continue to lead to a more normalised purchasing environment following exceptional demand in 2022, the quality of the pipeline remains strong across the Group's focused industrial applications". [SP=107.39 Cap=72m]
◄Churchill China (CHH)► guides FY-Dec rev down 0.5% but profit in line due to improving manufacturing yields and a further reduction in agency staff. Outlook - expects demand to remain weak for at least H1. [SP=1317 Cap=145m]
◄Tialis Essential IT (TIA)► warns FY-Dec rev £22m+ and adj EBITDA £2m+. "Results were affected by additional contractual delays on signing new business and the mix of revenues was less favourable than expected." Outlook - "expect further improvement in 2024 across revenue, profit and cash generation". [SP=60 Cap=15m]
◄Galliford Try (GFRD)► guides FY-June rev c.5% ahead of mkt exp. with an equivalent increase in pretax. F/C are rev £1,435m to £1,490m and adj pretax £25.2m to £28.1m. Outlook - "order book of £3.7bn (£3.5bn) remains predominantly in long term frameworks and provides good visibility of future workload". [SP=241 Cap=247m]. I hold.
◄Hornby (HRN)► Q3 rev up 5% and margin 46%, up from 43.8% in H1. Outlook - "current forecast to year end March 2024 remains on track for year on year growth". Er, is than in line? [SP=16 Cap=27m]
◄Gulf Marine Services (GMS)► guides FY-Dec adj EBITDA c. $86m at the top end of guidance. Maintains $87m to US$95m range for FY24. [SP=14.18 Cap=144m]. I hold.
In line: BRK, TMG, WIN
Tin hats on today, what a dreadful start to the year. Might be one or two opportunities presenting themselves though...
Corero Network Security (LON:CNS) - "Confirmed double digit growth in ARR" (link to report: https://www.equitydevelopment....)
Corero’s trading update points to double digit ARR growth and a significant beat to our FY23E EBITDA forecast. We have upgraded our full year numbers to reflect this strong bottom line performance. The new Akamai partnership has already brought two new customers to the Group and we expect to see continued momentum from this route to market.
We have left our FY24E forecasts unchanged for now. but, with a new CEO, Carl Herberger, onboard and an excellent pipeline of new business, we see plenty of capacity for upside risk to our FY24E forecasts. The business is self-sustaining and, in our view, undervalued on an EV/sales ratio of 1.8x this year. We continue to see fair value at 14p, with the potential to rise.
Corero Network Security (LON:CNS)
Surprised at the underwhelmed response today, bad day all round.
Here we have a tech company that's had its up and downs over the last 10 years but really seem to have turned a corner, not having issued tons of shares to stay afloat and are cash positive having paid off loans. They also generate real eps rather than pnoney ebitda earnings, not great yet but next year Rodney they will have a more attractive PE.
Reasonable trading update this morning from Nexteq (LON:NXQ) announcing full year adjusted PBT "comfortably ahead of market expectations" although revenue looks like a miss - $114.8m versus consensus of $119.6m.
Some other positives:
Net cash increased substantially to $27.9m from $18.5m at 30 June 2023, with the increased profitability enhanced by improved cash from operations and positive working capital movements as the Group reduced overall stock levels.
Order book at c.5 months of revenues, consistent with historic levels.. good visibility for FY24
I hold.
Nexteq (LON:NXQ) almost halved on no news , and today announced it was comfortably ahead of expectations with a strong improvement in margins.Now trades on just 8 times next year's modest forecasts with net cash forecast to be a 1/3 of the market cap. It's clearly the wrong price, even without recovering the premium rating it once held
Brooks Macdonald (LON:BRK) - FUM rose by 4.3% in Q2-FY24 from £16.9bn on 30 Sep 23 to £17.6bn on 31 Dec 23. This is on track to meet our end-FY24 (30 Jun 24) FUM target of £18.4bn (+9% y-o-y growth). Investment performance was strong, contributing £821m to FUM or +4.9% of opening FUM. Net flows remained subdued at -£98m (Q1: -£70m).
We remind readers that in Oct 23, BM announced a programme to reduce costs by around £4m per year, with one-off FY24 restructuring costs of up to £3.0m. This followed extensive technology and digitalisation investment over the last few years, enabling the group to manage the same or even higher business volumes with a reduced workforce. BM has now confirmed that the one-off restructuring cost is in line with the £3m estimate, and that some cost savings will be seen in FY24. As such, we reduce our FY24 cost estimate and increase our profit estimate as per the table below.
With net flows slightly weaker than forecast, but costs also lower, our fundamental valuation remains 3,050p per share. We also see BM’s PER of 16.5 as too low.
Link to report: https://www.equitydevelopment.co.uk/research/fum-up-4.3-in-quarter-profit-forecast-upgraded-a-touch
Hold onto your hats today. The reaction from the inflation numbers are unlikely to be pretty
Plus all Asian indexes are in dark red (Hongkong -4%), every commodities are down. It might be a bloody Wednesday...
I'm surprised tobacco has that much effect on inflation. So fuel prices fall but inflation is up because of tobacco and alcohol, so the newspapers report.
This isn't over yet. Watch for supply side inflation as the Houthis interrupt trade in the Red Sea. Lots of companies now taking a much longer route for shipping goods
Bizarre really, and probably shows how outdated the weighting’s to tobacco really are. In my circle, people who inhale that crap have moved to vaping, with only one or two still on the hard stuff.
Electronic cigarette refills/liquid are included in the tobacco category.
Headlines a bit misleading there. Tobacco only contributed 0.1% so not really a big factor, but I guess just enough to push it above expectations.
Sounds quite a lot actually. Fuel prices were down about 4%. I think the weightings need to be adjusted.
The weightings are adjusted every year by the ONS and take account of consumer expenditure.
No doubt Feb inflation numbers will undershoot forecasts..
Has been the pattern for the last few months. Overshoots one month, undershoots the next
I would not bank on it, next figures are for January. Gas and electric have gone up around 5%, so I expect that to have more impact than smokers.