Small Cap Value Report (Wed 17 May 2023) - AFRN, SMRT, ANG, RBGP, PURP, ATG, KLR

Good morning from Paul and Graham!
We're off to a flying start this morning, with some comments I prepared last night on less important micro caps, nothing madly exciting, but there wasn't much on tele so thought I'd use some time productively!
Thanks very much for the excellent reader comments yesterday too. I was a bit worried that it had all gone rather quiet out there, but it's great to see some very interesting comments from subscribers.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Agenda
This all looks pretty boring today, so I'm focusing on backlog items mostly -

Summaries of main sections
Aferian (LON:AFRN) - down 23% y'day to 28p (£24m) - FY 10/2022 Results - Paul - RED
A series of profit warnings has crashed this share. Finances are also looking wobbly, with a "material uncertainty" going concern statement, and says it might need to raise fresh equity. In negotiations with bank over covenants. All looks rather risky at present, hence why the shares are at a near-20 year low.
Auction Technology (LON:ATG) - +5% to 708p (£853m) - Interims - Graham - AMBER
This collection of auction websites is on track for EBITDA/EPS this year. But statutory H1 profit is very low after high finance costs. An interesting “marketplace” type of stock.
Angling Direct (LON:ANG) - up 15% to 30p y'day (£23m) - FY 1/2023 Results - Paul - AMBER
Poor results, not much above breakeven, but as expected. The balance sheet however is very strong, with £31m NTAV (mostly inventories & cash). Can they develop it into a worthwhile business, or is it just inefficiently tying up a lot of capital?
RBG Holdings (LON:RBGP) - down 13% to 33p y'day (£32m) - no news - Paul - AMBER/RED
The plummeting share price - is it a concern, or a buying opportunity? Paul reckons there's not enough information to decide.
Smartspace Software (LON:SMRT) - down 14% to 45.5p y'day (£13m) - FY 1/2023 Results - Paul - AMBER
Very small software company. Good growth in recurring revenues, but still making (reduced) losses, and cash position getting tight-ish. Tiny revenues per site, so I question whether it will be economic to scale up this business?
Keller (LON:KLR) -
Paul's Section
Aferian (LON:AFRN)
Down 23% to 28p y’day
Market cap £24m
Final Results - Paul - RED
I last looked at this set-top TV box company here on 10 March, when it dropped 36% to 38p, on a profit warning, saying FY 10/2023 trading was “substantially below” expectations. Also problems with bank covenants was delaying publication of FY 10/2022 results.
Yesterday, Aferian published those rather late FY 10/2022 results, strangely to no initial market reaction, but then yesterday afternoon the share price fell sharply, down 23% to 28p.
Going concern note is worrying, saying there is a material uncertainty over its ability to remain trading within its bank covenants, so it's negotiating a relaxation of these. An equity fundraise could be required. It is not in breach of bank covenants at this stage.
An adjusted operating profit of $7.5m becomes a statutory operating loss of $(16.6)m, after hefty goodwill write-off, and exceptional costs, for FY 10/2022.
Balance sheet looks a bit weak, with NTAV negative at about $(2)m at Oct 2022, and that’s probably worse by now, in the new financial year.
Outlook comments sound like a fresh profit warning, but it’s difficult to know, without any broker updates being available to us -
Following the investment made in inventory within the Amino business, the Group currently has a net debt position, and expects this to continue throughout the current financial year. As previously announced on 10 March 2023, we expect Group revenue and adjusted EBITDA for FY23 to be significantly below FY22, albeit that the Group is expected to generate a material positive EBITDA.
There’s a problem with that - EBITDA is not reality here, because Amino capitalises $7-8m pa in development spending, spending which of course is ignored by EBITDA.
Paul’s opinion - this looks worse than I expected when I last reviewed it about 2 months ago. I’m surprised at how quickly trading, and the financial position, have deteriorated at Amino (the old name for Aferian). It had a long, and good track record of decent profitability, and paying divis. The wheels seem to have come off in the last year, leaving it financially distressed now, with a high risk of dilution or insolvency.
Kestrel, Premier Miton, and Investec, together own over 50%, so they (and the bank) are calling the shots now, over a possible fundraise, and maybe even de-listing it, to remove an embarrassing mistake from public scrutiny, possibly?
The risk is therefore high to small investors here, who are along for the ride, and could get badly diluted if the big holders decide to refinance Amino with a discounted placing. It could all turn out to be fine though, I’m just flagging the risks, for you to make your own decision over what course of action to take, armed with the facts.
If it gets back on track, with no dilution, then the shares could be a multibagger.
I don’t have any firm view either way, as it’s not a sector I have any insights on. But for me, the high risk of dilution/insolvency means it’s just a punt at this stage, so not something I would want to get involved in. Hence I have to give a RED opinion on it, whilst there remains significant financial uncertainty.
We can revisit it once it’s lower risk, with bank facilities amended hopefully, and more clarity on the outlook.
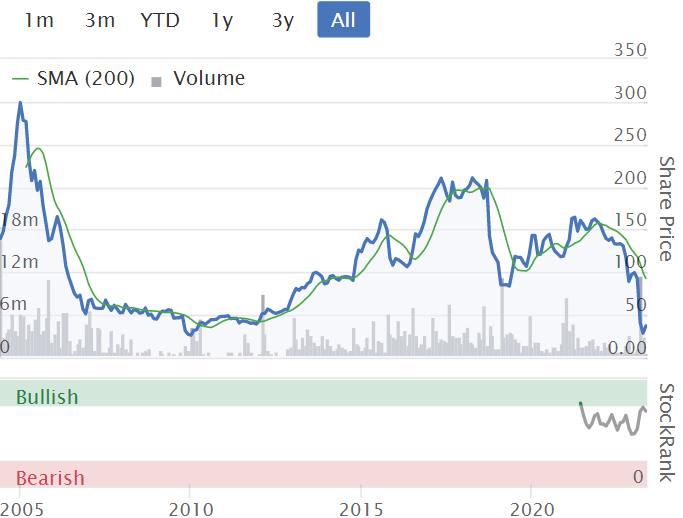
This share listed 19 years ago, and is pretty much back down to its all-time low again - is it a bargain, or has the company had its day? We don't know yet.
Angling Direct (LON:ANG)
Up 15% to 30p y’day (£23m) - Paul - AMBER
A Board re-jig is happening, which looks planned, with the CFO stepping up to CEO, and the CEO becoming Chairman.
ANG calls itself -
…the leading omni-channel specialist fishing tackle and equipment retailer..
Operating from shops, and online, mostly in the UK, but also with a European operation.
It’s not a very good business, and bumps along just around breakeven, but the main attraction is the net cash pile, which management has carefully preserved. This was 80% of the market cap at end 2022, hence why I added this share to my top 20 value/GARP shares watchlist, which is doing quite well so far this year (with the portfolio up 12% YTD, not bad in a depressed small caps market).
Final Results - FY 1/2023
Profit fell from £4.0m last year, to only £0.7m this year. This is mainly as a result of the pandemic boom unwinding, but also impact from higher costs, supply chain, and a drought impacting fishing in 2022. Also, expectations were lowered previously with profit warnings, so the disappointing trading performance was already factored into the bombed out share price. So that’s all OK.
Balance sheet is the main attraction. NAV is £37.3m, containing £6.1m of intangible assets, which becomes £31.2m of NTAV. This is mostly working capital, containing £17.8m inventories, and £14.1m cash. These dwarf trade payables of only £6.8m. Other creditors are small, or can safely be ignored (lease liabilities). Therefore this is a remarkably strong, over-capitalised balance sheet - which makes this share very safe, but does raise the question as to why the company is tying up so much capital for little to no return?
What’s the point in expanding the business, when all it means is tying up more capital in unproductive assets? Hoping that competitors will fall by the wayside seems to be the main strategy, so a last man standing type of strategy - which strikes me as somewhat lacking in excitement.
Paul’s opinion - there doesn’t seem much appeal here, other than the superb asset backing.
Let’s see what the new CEO comes up with, in terms of strategy. The main risk is that a more aggressive expansion strategy ends up squandering the cash pile.
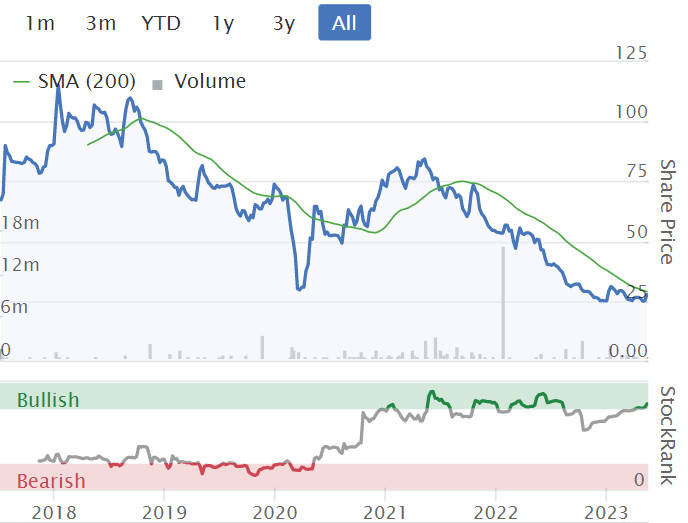
Not the most inspiring chart below, but plenty of eCommerce shares are down a larger % than this!
RBG Holdings (LON:RBGP)
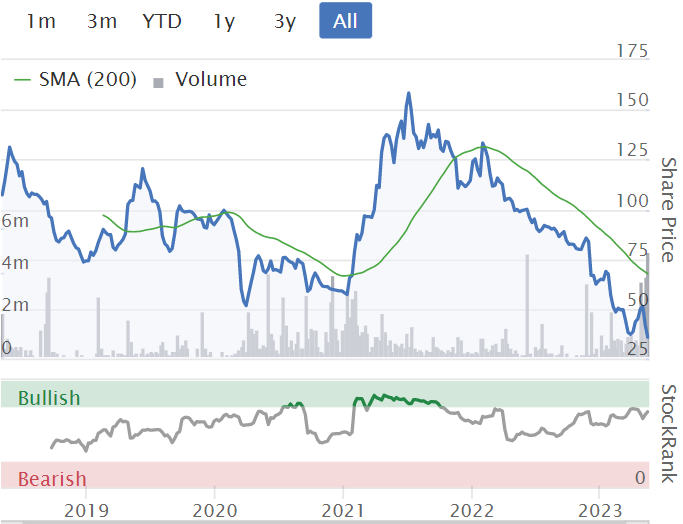
Down 13% to 33p on big volume (£32m) - Paul - AMBER/RED
Something funny seems to be going on here, at this legal services group (Rosenblat and Memery Crystal). I’m not keen on listed lawyers, or accountants, and tend to avoid them due to the inherent conflict of interest between fee earners, and outside shareholders.
The former CEO Nicola Foulston was sacked after she made a mess of the Lionfish litigation finance startup, and press reports suggested that she used unacceptable language at some industry dinner. Since then, the senior partners of Rosenblat and Memery Crystal have taken back control of the group.
Are the shares a bargain now? It’s impossible to tell. There hasn’t been any more news since the FY 12/2022 accounts were published on 22 April 2023. The figures show a healthy performance from the ongoing business, with nice profits more than offsetting losses at discontinued Lionfish.
Although the balance sheet does concern me, as it’s weak - with £61m NAV mainly comprising £55m of intangible assets. Also we don’t know how the assets & liabilities of Lionfish will unwind. Bank debt is significant, with a £20m non-current loan.
Paul’s opinion - not enough information to make an informed judgement on this share, so I’ll watch from the sidelines. I’m wary, given what the share price is doing, so AMBER at this stage, but with some signs of distress, so maybe I should be RED until the facts become clearer?
Smartspace Software (LON:SMRT)
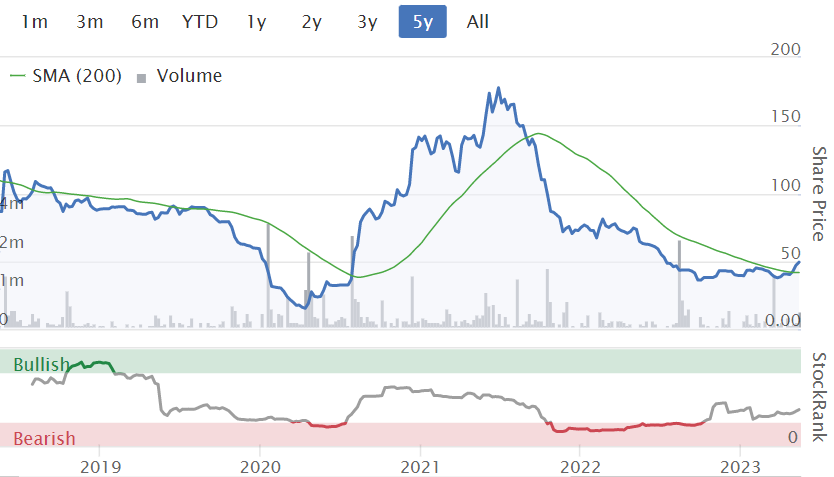
Down 14% to 45.5p (£13m) -
FY 1/2023 Results - Paul - AMBER
I’ve had a quick look through the numbers, and watched a recording of a previous IMC webinar (there’s a new one due today). This is a very small software company, with nicely growing recurring revenues, which helps manage access & control over buildings. The main product seems to be SwipedOn, which looks low value, starting at £29 per month for a single site with up to 50 staff. Customer churn is low, which implies the product works well, in the simplistic way I look at things!
It’s trying to sell a small hardware subsidiary called A+K, which makes sense, since it’s lumpy sales (and no profits) were obscuring the growth in the software business.
SMRT is still loss-making, and burning cash, although performance is improving, and I think it might be able to manage without another fundraise, although it could get tight.
Paul’s opinion - it’s just too small, in my view. Also generating only £5.0m revenues from over 8k locations, means this product is only generating peanuts per location. So is the sales & marketing cost to generate new sites actually worth it? Are the listing costs/hassle worth it? I have my doubts. For this reason, I’m struggling to see how this could scale up into a significant business, making big profits. That said, a £13m market cap isn’t bad, if you think it could accelerate growth, and keep building that recurring revenue stream to a tipping point where it starts to generate cash instead of burning through it.
I can see some attractions, so I’m happy to view it as AMBER (neutral).
Purplebricks (LON:PURP)
** Breaking News at 08:55 **
Announces it has agreed to sell “substantially all” of its trading business, assets and liabilities, to Strike. The price agreed is … drum roll please … £1
PURP seems to be retaining the cash pile “up to a maximum of £5.5m”, some of which will be needed to pay costs, and “excluded liabilities” that Strike is not taking on.
The remaining cash is to be returned to shareholders, and the cash shell liquidated. This is described as a “small return” to shareholders.
The AIM listing will be cancelled.
That’s that then.
Keller (LON:KLR)
Up 2% to 653p
Market cap £472m
This is a large, low margin specialist contractor, calling itself -
the world's largest geotechnical specialist contractor
I last looked at it here on 16 Jan 2023 and concluded (on a quick review only) that the shares looked good value. It was knocked about 10% on that day by revealing a fraud at its Australian operations, but the size didn’t look too serious relative to the whole group.
What’s the latest news?
Today it updates us for the 4 months so far of FY 12/2023. This sounds promising -
AGM Trading Update - Strong start to the year, confident in achieving full year expectations
First 4 months “strong and better than expected” - for both profit and cash.
Various operational details are given, which I won’t repeat here.
Outlook -
The increased momentum across our business cited at our full year results in March 2023 has continued in the period. This, combined with a strong order book and recent contract wins, gives us good visibility and confidence through the remainder of the year and we continue to anticipate a full year performance at least in line with the Board's expectations.
It’s hard to fault any of that!
Balance sheet - I’ve checked the end 2022 figures, and it’s a large balance sheet, carrying a fair bit of bank debt. With debt now costing a lot more, this would probably be the area to focus on when doing your research.
Paul’s opinion - KLR shares tend to oscillate sideways over the long-term, so not a very exciting share. The main benefit is the decent dividend yield of over 6%, which would have interested me in a 0% interest rate environment, but a lot less so, now that we can earn 4-5% on cash deposits. So why take on all the risk of an equity position, to chase a 6% dividend yield here? That’s a much broader question.
The value metrics do look nice at KLR though -
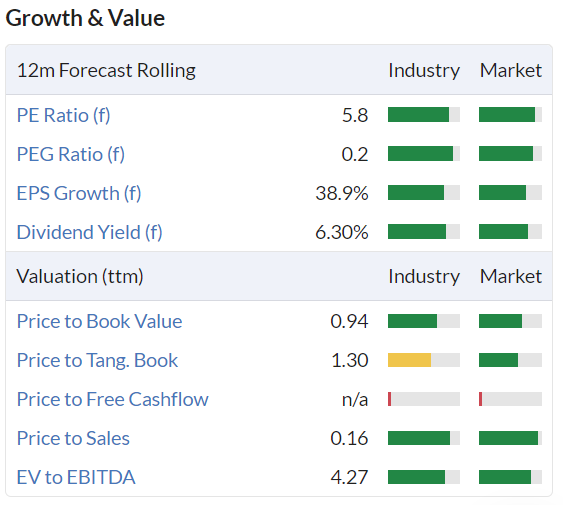
Given that it has also issued an upbeat-sounding trading update today, I can’t see any other option than to view this share positively, as GREEN.
Another point is that if you expect interest rates to go down again in 2024 and onwards, then locking in some big yields now on shares and fixed interest stuff, could be a good idea.
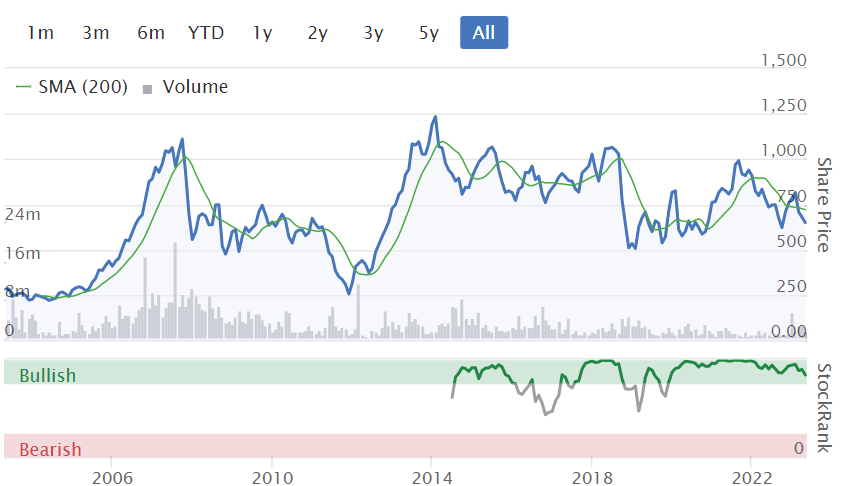
The StockRank system likes it too - as you can below the StockRank score is in the green area (near the top actually) most of the time -
Graham's Section:
Auction Technology (LON:ATG)
Share price: 708p (+5%)
Market cap: £853m
This share has never been previously discussed on Stockopedia, but I’m happy to kick off the coverage this morning!
One of the first things I’ve noticed about it is that it’s an IPO from 2021. This is already a red flag of sorts, since we were treated to so many overpriced, poor-quality IPOs that year! Hopefully this was one of the exceptions.
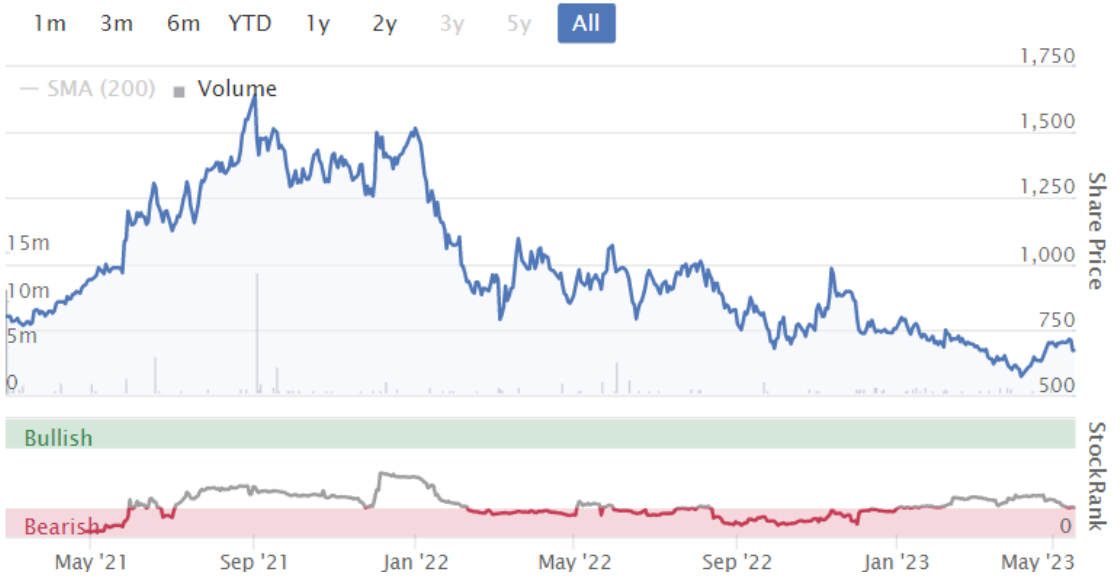
The share price began its journey on the stock market strongly, but it has drifted lower since the beginning of 2022 and is now within reach of the 600p IPO price again:
It describes itself as an “operator of world-leading marketplaces for curated online auctions”.
These marketplaces include:
https://www.the-saleroom.com/ (European marketplace for art, antiques, collectables).
https://www.liveauctioneers.com/ (North American auctions)
https://www.lot-tissimo.com/ (German art and antiques)
https://www.bidspotter.com/ (industrial auctions)
They have eight websites in total. The majority of revenues are generated in North America, with the largest product categories being “art and antiques” and “industrial and commercial”.
With that brief overview behind us, here are the interim results for the period to March 2023:
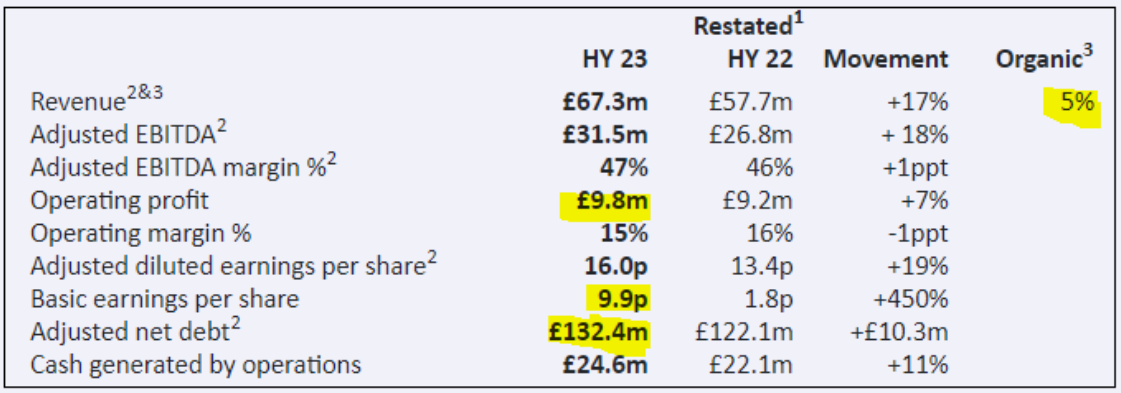
5% organic revenue growth is shown on a constant currency basis, so I believe that is the best indicator of real underlying growth.
It’s not a bad figure by any means but I have noticed that “good” companies are frequently generating revenue growth of 8%+ purely from the effects of inflation, so that’s the context in which I’d interpret it.
Revenue here is largely a function of “Gross Merchandise Value” (the value of the products sold on the company’s websites) and the “Take Rate” (the percentage commission earned). GMV is up by 5% organically to £1.9 billion, and the Take Rate commission is flat at 3.2%. The company sells a variety of “valued-added” services in addition to its core services.
Leverage: thanks to ATG’s acquisitions, its net debt / adjusted EBITDA multiple is 2.3x over the last twelve months. This is typically considered to be on the higher end of the spectrum.
CEO comment excerpt:
We have made great progress against each of our six strategic growth drivers…
As expected, organic revenue growth accelerated across the half and this rate of growth has continued into the start of the second half. This momentum, combined with strong traction against our key strategic initiatives, leaves us confident that we will deliver a higher rate of organic revenue growth in the second half of the year and into FY 24.
The outlook is in line with expectations for EBITDA and EPS. However, despite what the CEO says regarding higher organic growth in H2, this growth will be at “the lower to mid end of the range”.
Finance costs: I’m drawn to one particular entry in the income statement. Finance costs have moved from £5.5m in H1 last year to £9.1m in H1 this year, and they wipe out most of the company’s operating profits.
I’ve found the explanation. The key points are that the company is paying a floating rate on a loan and it is denominated in US dollars. This caused the interest charge over the six-month period to increase by £2m to £5m. There was also a nearly £4m non-cash loss relating to the translation of loan values.
Graham’s view
I think that investors generally are wise to the value of successful marketplaces. People understand the value of network effects in these types of business - think of the likes of Rightmove (LON:RMV) (in which I have a long position).
However, one of the key elements of a successful marketplace investment is that it should have or develop a high market share. Remember that Peter Lynch said “in business, competition is never as healthy as total domination”!
However, the markets in which ATG operates are by their nature highly fragmented and it’s not obvious to me that high market share is possible for them. But maybe they can do it?
Here is how they explain the value of what they do:
For auctioneers and sellers of secondary items, we massively extend their reach by giving access to our diverse and highly fragmented global bidder base, specialised technology, and operational efficiencies that arise from working with us. Critically, we help ensure they achieve the highest asset sale price possible for their consignors.
For bidders, we provide access to millions of unique, specialised, and curated second-hand items through our eight online marketplaces and listing sites.
The combination of the widest array of inventory and the largest bidder base has enabled us to create a virtuous circle that benefits both buyers and sellers, with more buyers participating in online auctions and estate sales resulting in higher realised prices for second-hand items, which in turn attracts more secondary assets to be listed and sold online, and thus more bidders.
They say they are on “the well-trodden path of online marketplace development”.
I must admit that I’m intrigued. Could this be the next successful marketplace stock, to be mentioned in the same breath as Auto Trader (LON:AUTO) and Rightmove (LON:RMV) ? I wouldn’t rule it out yet.
The balance sheet is a slight concern, as borrowing at floating rates in US dollars is not ideal right now. The leverage multiple needs to come down. And I do not view the H1 performance as being particularly profitable, since the company’s operating profit got eaten up by those finance costs.
For now, therefore, I’ll stay neutral. But I think this could be a nice stock to own someday, at the right price, depending on how they develop over time. With a current ValueRank of only 27, there is a good chance that this one is still in that period of post-IPO overvaluation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Tags still missing.
Kinovo (LON:KINO) - Paul could you do a review of Kinovo. I though their figures announced last week were excellent and although the shares went up they still look very cheap.
Good notes on Aferian AFRN and Keller KLR as some have discussed elsewhere. I used to own Amino, AFR's predecessor, and did very well looking back to early 2020 when I finally exited. But I was very lucky. Investing in companies where one really doesn't understand the technology, the competition etc is always high risk, especially if they are smaller companies in a large market. Streaming is now a huge market. What is happening here is that there are two divisions, the newer, pure software streaming business - doing well but high R&D cost - and the older Amino business which distributes set box tops for streaming. This is dire, there is a large inventory position (£2mn to £9mn in a year) and this needs the US market to recover. Kestrel, the largest 26% shareholder, has a man on the board now (i.c. remuneration!) and if worse comes to worse I suspect their backing or backing away from a further financing may dictate AFR's fate.
Keller KLR had record profits in 2017 since when its US business has marked time, Europe seems (they have changed geographical split) pretty weak but they are making great headway in the ME led by a huge Saudi contract. This seems to be the main reason for much higher year end borrowings, presumably along with the hiccup creating much higher inventory in the US, but overall I am pretty impressed. It looks solid but the biggest market, easily, is the US where I believe housing starts are under pressure. This might just be a fly in the ointment.
Bouden54 your post this afternoon on Card Factory (LON:CARD) made I laugh!
Off topic but for investors here in car dealers shares, there's a very interesting piece in Car Dealer Magazine which has picked up on Cazoo's latest update to Companies House. It's a very grim read for Cazoo investors and possibly good news for established franchise dealers. Full disclosure ,we hold Vertu.
Card Factory and Vertu two biggest holdings at moment in UK stocks . Quite sad that seems the best potential investments personally in Country at moment.
I suggest some sound investment advice - do the exact opposite of what I do! Yesterday after Sylvania Platinum (LON:SLP) continued to fall and hit my latest stop loss (-25% from 1st January 2022) and the chart didn’t look great I decided to sell albeit at 100% profit. Today it is up nearly 7% - I despair at this small caps game and should probably give it up altogether!!
I wouldnt beat yourself up about it. 100% may be less than you were hoping for but you could do a lot worse. Id have sold too. Horrible looking chart and falling forecasts. Lots of momentum, just in the wrong direction.
Its a pretty awful market right now for most small caps. People are much more short term thinking and unwilling to hold without a recent positive update or upcoming news. If its any consolation the Dot Com bubble bust seemed to go on forever and 2008 was absolutely brutal, this is nowhere as bad. Have to either grit your teeth and hold or be very precise with stock picking/trading.
We all do things we regret. Mine include buying just before a profit-warning, and selling just before a take-over bid.
I have a position in Sylvania Platinum (LON:SLP, which I bought in 2008. I sold half in Jul 2021 at 98p, shortly after the share fell 10% to 103p. In hindsight, this turned out to be the right move.
SLP seems heavily dependent on the price of rhodium. Current price is 7100 (https://tradingeconomics.com/c...). It spiked to nearly 30000 in May 2021. There's no reason why the price can't go lower, though, as 1200 seems to have been an average price from 2013-2017.
It's all tricky. I resolved not to sell anything for the rest of the tax year unless forced, so I'm more holding out of stubbornness. I'm somewhat persuaded by arguments that commodities will go higher. So, meh, make of that what you will.
You wouldn't be wrong to say that the chart looks ropey. So, despite the 7% rise (actually now around 5.5%) you may yet be proved right.
You're too hard on yourself ACounsel, I would have been delighted to have taken 100% profit on any of our portfolio over the last three years. I sometimes wonder if paralysis by analysis applies to more than golf, common sense matters too.
Always give a little bit back ACounsell!! Everybody has to eat.
Thanks for your thoughts on Keller (LON:KLR) Paul, very useful.
Not one Id looked at before but the update today sounded positive and theres a possibility of a beat in future I think. 1 or 2 nice potential catalysts before the the August interims?....... "management is in advanced discussions on NEOM about the award of a second works order, which could be more than 3x larger than the first works order of £40m." Obviously theres negatives of fraud investigation, US housing and largish debt.
I like companies who've been in a downtrend, but announce positive updates, taking the markets by surprise eg. Volex (LON:VLX) Can make a nice low risk trade or longer term hold.
Took a chunk for a trade early this morning. If it doesnt work out theres a tight stop in place so pretty good risk/reward here I reckon.
Re £ANG - contrary to Paul's descriptor of it as an e-commerce, it is only a 44% e-commerce business; it is a nicely balanced mix of online and offline stores. The online store is the clear market leader in the UK and its offline stores sell some stuff you really need to go to collect (not everyone wants bait through the post even where possible and it is often the market leader in its store catchment (geddit) area. No other fishing specialist matches its range and often size of store and it has a history of buying up the well located/good independents when they come for sale. It has a decent own brand business established for many years and good grip on knowledgeable staff and consumers in a sector where being able to tell fishy strories is a requirement
So far, so good.
The 3 key Qs to me are
1. Will ANY retail ever before profitable (or a favourite of share buyers) again - my view is yes, in time
2. Will its model work in the big omni channel markets of near Europe - yes, why not?
3. Will its online ever recover/be profitable - yes, scale really helps here, it has the range already
4. Will fishing remain a mass activity - yes, at worst it will slow decline and last man standing
5. Can it deploy its capital quickly and well? Hmmm
My guess to Q5 is "no" so its either v slow burn or takeover/injection by someone who thinks it can or it squanders it or it has been patient and will be rewarded once its careful European expansion gets going.
I hope it gently but steadily grows and this ultimately delivers sustainable profits. On that basis I hold without expectation of much short term excitement.
If you hold Card Factory (LON:CARD) you might be interested in my wife's experience at the Teignmouth Branch this morning.
One staff member on the till with 7 customers queuing. One customer buying 2 balloons told to come back in 30 minutes to have them inflated. Manager upstairs but Staff Member did not want to call him for assistance. Very poor service being offered but on the positive side Branch was busy. Nonetheless on my watch list.
Perhaps that explains the recent weakness - market not impressed with the poor customer service in the Teignmouth branch.
Where else can you get a big balloon though!
Frasers Group just upped his holdings in ASOS from 5.10 to 7.40%
this is a confirmation that he'll keep upping his stake. ASOS at 429.27M market cap is outrageous
How come Zalando has a market cap of 8.08 billion!?
Outrageous as in way too expensive?
something doesn't tally. Either ASOS is outrageously cheap or Zalando is outragerously expensive. However ASOS seems very cheap at those levels and I've been adding - the fact that Frasers Group been adding seems to tally with that perspective. For me ASOS at those levels is easy prey for the likes of Primark/NEXT/MKS/Apollo/JD Sports/Other Hedge Funds/USA Retailers...etc
ASOS is definitely expensive heading south, might recover for a couple of months and then we will see new lows. The reason is just too simple : massive debt and loss making.
Frasers Group were the largest holder in a listed company that went to a big zero last year and delisted.
Thanks
Any thoughts on Watches of Switzerland (LON:WOSG) ? Confusing update: they have started strongly for 2024 but expect to be in line with 2023....why??
I don't follow this company closely nor have read their results. But suggest you have a quick look on YouTube for videos re. the luxury watch market. It seems that the speculative luxury watch bubble has well and truly burst. Prices are roughly down 30% from peak. (Most) Rolex prices are back to MSRP or below. This will surely not have gone unnoticed by those who were queuing up at WoS stores, hoping for a quick flip on the grey market. Just off the top my head some questions I would be asking and, again, some of the answers may be in the results, which I have not read:
1. What is their revenue split between watches and jewellery
2. What % of the former are Rolexes - by volume and brand recognition the brand that dominates the luxury watch market (annual global production 1m watches plus (factory expansion in progress) vs. say, Patek, <0.075m)
3. How many customers are first time buyers vs. repeat customers. How has the latter's buying behaviour changed - I assume this is not disclosed
4. What is there geographic presence? How exposed are they to the duty free travel trade? Return of Asian travel buyers? UK VAT refund issue for foreign buyers vs. Europe?
As I have said on here before WoS benefitted from a huge Covid tailwind, which is likely to have been partially cyclical / one off rather than structural. As this abates it is coming through in their forecast results. Far better ways to play the luxury space IMHO. Go to where the IP is and not to a mere (local) distributor
My view is that Watches of Switzerland (LON:WOSG) was wrongly classed as a high growth company, when in fact much of the growth of recent years was due to the bubble in the luxury watch market. As markets have cottoned on to this it has derated quite significantly. Not sure where it goes from here, but personally still not tempted.
The cure for high prices (watches bubble) is high prices. What you do is own a Rolex, lock it away, and wear the fake one - some apparently are very good and supposedly tell the proper time.
Re Smartspace Software (LON:SMRT) - I liked sound of story and product when it was being ramped by the usual crowd (and a nice covid fit too...so ideal for the rampers to pump)...but was never going to chase a ramp for such a speculative pre-proof stock. Catnip for PIs so no doubt many got burned. I too am perplexed by 8500 customers and £5m revenue. Something doesn't add up. Maybe there's something about reporting whereby they are reporting per user of systems rather than at aggregate company user? If its truly representative stats then it means problems re acquisition, growth and servicing of customers....and that they lack an effective enterprise level engagement capability (that means they are likely a cheap option that picks up the scraps rather than a Rolls-Royce for corporates)
Hi Paul, is @OTB still on the radar? Market was not impressed with results yesterday, perhaps a little unfairly as H2 may be pretty good. Cash makes up a good % of current cap.
Hi Paul,
I also would be very interested in your thoughts on On Beach group (LON:OTB) if you have the opportunity. It was a tricky update to unpick yesterday and not investor friendly. I sold at the open and was fortunate to get 124p, I am now looking at the potential of buying back in at a lower price. I notice it has continued to fall further today to 105p, which seems good value. I note that Boon, who's investment style of picking unloved contrarian stocks (I agree with his approach, particularly in the current market), rated it's recovery chances moving into H2 in his well written writeup yesterday.
Cheers,
Ben
Unloved indeed
Paul, Graham: Auction Technology (LON:ATG) is the last of the 2021 IPOs for which there's nothing in the archive. Perhaps you might consider it as a few moving parts where you might add value, especially balance sheet. Thanks
A slightly weak outlook yesterday from Tharisa (LON:THS) combined with disappointing China data sent the shares, which had been weak recently, down further. I note today a certain small cap specialist from the Chronicle is pushing Sylvania Platinum (LON:SLP) , another South African Platinum Group metals producer, more expensive than Tharisa - but still a very attractive entry point. These companies both have net cash on respective balance sheets, low single figure PEs and terrific dividend yields. Yes there is some S Africa risk, but EM relative risk in general appears to be moderating - so these stocks may be worthy of consideration.
I'm watching Sylvania Platinum (LON:SLP) While revenues and cash position is up, profits are down due to the current depressed price of Rhodium and Palladium. Palladium looks to have bottomed out and has broken out of it's downward channel while Rhodium is still in a downward trend but having hit an all time low last month, it may well start to turn soon.
As for Sylvania Platinum (LON:SLP) there is strong support at 70p and this is my target for an entry. Note that there is possible a Death Cross (200 and 50 Ma crossing) about to happen.
It does give a good dividend, but with profits much lower will it continue to or not? Though it can afford to as it's cash pile will be about £112m.
I wouldn't say Simon Thomson is pushing it, as he has it down as a hold.
Purplebricks (LON:PURP) biz sold for £1! "Proposed Sale results in the Company's cash balance on Completion (up to a maximum of £5.5 million) being retained by the Company with the intention that the net cash proceeds after the deduction of certain costs and expenses to meet the excluded liabilities (the "Net Cash Proceeds"*) are distributed to Shareholders."
Business model flawed at launch with non-refundable upfront fee. Agents not incentivised to actually sell the homes. It was corrected too late.
Purplebricks, Capita (and offshoot Link, of Woodford fame) and Eve Sleep all had a common board member - a Mr. Paul Pindar.
Perhaps, with the internatonal situation being what is, he could redirect his efforts to recruiting for the army again:
https://www.forceswatch.net/ne...
Thank you for your comments Paul on RBG Holdings (LON:RBGP) which I hold. I bought in Sept 2021 after the SP had risen from 68p to 145p in 8 months.
I am very tempted to average down at this price currently 32p which is the year low.The firm has grown revenue and profits over the last 5 years and if the sale of Lionfish goes through debt should fall.
Very tempting but risky. My biggest concern is how is Nicola Foulston going to sell her very large holding. Big overhang.
The comments of other subscribers would be very much welcomed on this one.
I held RBG Holdings (LON:RBGP) over a period of time but sold out as the share price declined and Nicola Foulston popped up everywhere promoting the business. I assumed it couldn’t be doing that well, otherwise she wouldn’t have needed to appear on almost every other Mello. I bought back in again after her dismissal and before the recent results, as the board twice stated there was no change in expectations. I thought the results were fine, as was the corporate presentation, the shares went up a fair bit, which is when I should have sold…I am now sitting on a sizeable loss as the SP seems to have dropped roughly 5% every day for a week or so and a huge amount yesterday. Today is down yet again. My assumption had been that Nicola Foulston is already selling down her holding. Would she need to declare that? The CEO stated a ‘substantial’ amount would accrue to RBG from the Lionfish sale. The shares seem oversold at the moment
Thanks Paul and others for comments on RBG Holdings (LON:RBGP), the volume of late and particularly yesterday suggests Ms. Foulston's trust is selling down her holding. The only thing I would add to Paul's comments re the industry dinner is to suggest a quick skim of para 9 of the attached employment tribunal decision which makes interesting reading.
https://assets.publishing.serv...
I have just re listened to the year end RBG results video
https://www.investormeetcompan...
On the positive side they are still trying to offload the Lionfish part of the business and state they have 4 bids and one is going through due diligence. No news since then but, despite being loss making, the sale of Lionfish could bring in some cash to reduce the debt.
Also the remaining parts of the business (legal services) seem to be doing well with a good outlook for cash generation.
I have just averaged down for the dividend payments. It is risky though with the Nicola Foulston overhang.
Solid results from Renew Holdings (LON:RNWH) yesterday. The price spiked 4% into the close, but much of that is being undone this morning. I'm considering buying in, as something to tuck away for a few years.
During my review, I noticed the three executive directors appear to be paid quite well and they don't have a lot of skin in the game, in terms of stock.
I wondered - does anyone have any general rules that they follow for director remuneration? In terms of deciding whether it's reasonable or excessive, either on an absolute basis or relative to the size of the business.
Breedon (LON:BREE) FYI
As at close of business on 16 May 2023, there were 1,694,509,871 Old Breedon
Shares in issue with a closing share price of 69.0 pence, representing a
market capitalisation of approximately £1,169 million. Based on the Company's
issued ordinary share capital at Admission of 338,901,668 New Breedon Shares,
the implied price for each New Breedon share is approximately 345 pence (based
on an equivalent market capitalisation).
Am I correct in assuming there will be on inheritance tax relief on this share now
I meant NO inheritance tax relief
Your assumption is correct. It explains a lot of selling over the last couple of weeks. Some punters have been using this excess supply to buy looking for a quick trade. Decent business so there was a lot of IHT money in it (not many decent AIM stocks these days!)
YouGov (LON:YOU) CMD today might be worth a look at the webcast when available as they have announced punchy mid term targets of £500m Rev and 25% operating margins. That's a doubling.....
This "may" justify the 20x PE and would almost certainly pave the way from FTSE250 to FTSE100 ...never a bad thing. Looks like it's worthy of some work - shares done nothing for 18 months. On the "to do" list.
My morning smallcap tweet: A whine of information
Newmark Security (LON:NWT) Xeros Technology (LON:XSG) Silver Bullet Data Services (LON:SBDS) 4Global (LON:4GBL) MPAC (LON:MPAC) Kinovo (LON:KINO) Fix Price (LON:FIXP), Aptitude Software (LON:APTD), DSW Capital (LON:DSW), EKF Diagnostics Holdings (LON:EKF)
◄Newmark Security (NWT)► FY-Apr rev 'growth'. Not even a number! Human Capital Management ARR £2.1m up 133%. Return to profitability and cash flow generation. Good start to FY24. Why is this £6m tinpot even listed? [SP=58.9 Cap=6m]
◄Xeros Technology (XSG)► 10-year, worldwide non-exclusive license for its denim finishing tech to KRM Tekstil Boya San. [SP=3.15 Cap=5m]
◄Silverbullet Data Services (SBDS)► partnership with Silverpush, a global leader in cookieless advertising solutions. CEO 'thrilled'. [SP=46.5 Cap=7m]
◄4GLOBAL (4GBL)► partnership with Jonas Fitness, extends relationship with Jonas brands into North America and their 10k+ customer sites. [SP=48 Cap=13m]
◄Mpac (MPAC)► AGM stmt - sounds in line. [SP=230 Cap=47m]
◄Kinovo (KINO)► guides FY-Mar marginally above expectations with rev-cont up 18% and EBITDA up 29%. [SP=46 Cap=29m]
◄Fix Price (FIXP)► Russian shop chain open in Armenia, its ninth market. [SP=NA Cap=NA]
In line: APTD, DSW, EKF
MPAC (LON:MPAC) - new note here: https://www.equitydevelopment....
In a statement accompanying the AGM, Mpac Group reports that the positive momentum of Q4 22 has been maintained, with order intake and quotation activity significantly ahead year-on-year. As expected, pressure on working capital has eased - the completion of orders and shipment of equipment means that Q1 23 closed with a positive net cash position, which is expected to be maintained in H1.
This is a clear validation of the steps undertaken in the latter part of FY22 and a strong positive indicator for the current year. We note that Mpac expects trading to be second-half weighted, with the order book sufficient to meet revenue expectations. The positive momentum reported should continue.
The core message of this AGM statement is that Mpac continues to focus on its key markets, notably Healthcare and Food & Beverage, where the shortage of key components in FY22 constrained the ability to deliver, and where there is now evidence of healthy demand.
Our fair value for Mpac remains 485p/share, indicative of a FY24 EV/EBITDA multiple of 7.9x.
Morning Paul. Thanks for your comments on RBG Holdings (LON:RBGP) l hold. I am hoping that big drop is related to Nicola foulston shedding stock and this may be a good buying opportunity.
RBG Holdings (LON:RBGP) I held for a while, impresed by Nicola's vision. But got cold feet and sold late last year - using 2020 as base year and seeing turnover increase significantly, share count increase significantly, debt increase significantly, operating profit increase and EPS flat. I started to lose faith once institutions bought in at £1 from legacy holders who were supposed to be tied in, and sold out on first bad news from Lionfish, fortunatley missed more recent turbulance in the share price. I will avoid, of course I could be wrong, I often am!
All good point’s especially the lion fish warning, perhaps they were out of their comfort zone and were being greedy. In my view lawyers should stick to what they know not speculate. At this price a good yield.