Small Cap Value Report (Wed 18 Jan 2023) - W7L, ITM, SMD, BOKU, MIDW, HAT, TM17, ALPH, EYE

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda
Warpaint London (LON:W7L) - I've been impressed with performance last year, reporting on it here positively several times. So I approached the company about interviewing their CEO. This is booked in for 2pm today, so the audio will hopefully be up on my website late afternoon, I'll add a link here once it's published. EDIT: Now published, my audio interview with Warpaint's CEO.
Here's today's to do list. We're going to try something new, and gradually change these to one sentence summaries, once we've done each section below:
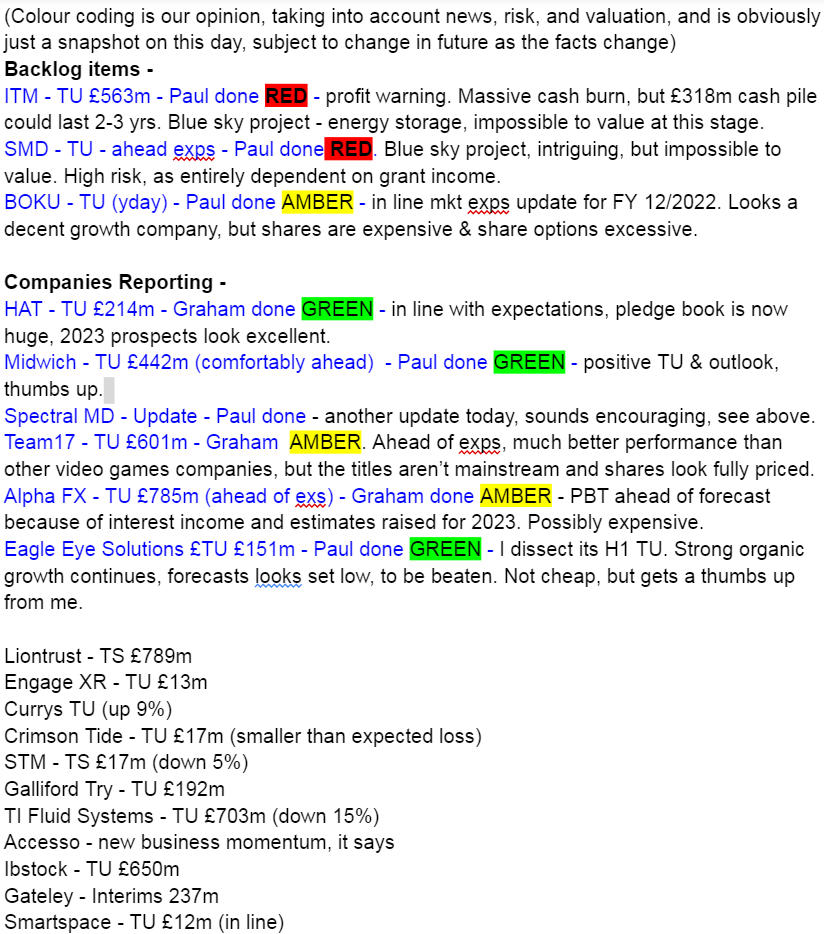
There are lots at the bottom that we didn't get round to looking at, sorry about that. I might check out a few later, for tomorrow're report.
Paul’s Section:
Firstly I did 3 backlog items last night -
ITM Power (LON:ITM)
89p - mkt cap £563m
I have to mention this update, published earlier this week, as there are some staggering numbers in it! It’s a profit warning for FY 4/2023, from the new CEO.
… it has become clear that the outcome for the financial year ending 30 April 2023 will be materially different from the current guidance, with lower revenue and a higher EBITDA loss.
Various problems have arisen, which is says are “surmountable”.
Net cash is staggering (for a blue sky, AIM company) £318m, but that’s as of 30 Oct 2022. It’s burning cash prodigiously, so a more recent number should surely be provided too? Otherwise it looks like they're trying to mislead us.
Guidance provided in Sept 2022 for FY 4/2023 was -
- Revenue of £23-28m
- Adj EBITDA loss of £(45)m to £(50)m
- Capex £30-40m
- Cash burn of £110-135m for the year!
So presumably with a profit warning this week, these figures are likely to be even worse?
My opinion - none, as I’ve not researched it. This looks an incredibly ambitious project, for a UK AIM-listed company. The one saving grace is the massive cash pile, which should last 2-3 years if the current pace of cash burn continues.
It seems to do energy storage, which is a key theme globally, to allow renewable energy to be stored, and not reliant on intermittent generation from solar or wind. Whoever cracks that market is likely to make squillions, if they can defend their IP. That’s probably the attraction with this share.
If you’re going to do something blue sky, I like the concept of going big! Although ITM is probably small fry compared with other (especially USA-based) organisations that are bound to be tackling this same area. In my experience, very few blue-sky projects that list on AIM reach commercial success at all, and the ones that do - it usually happens years late, and after lots of ruinously dilutive placings. The early investors hardly ever make any money. Let's hope ITM is different, as the UK badly needs some ambitious, big technology breakthroughs, particularly in energy.
Spectral MD Holdings (LON:SMD)
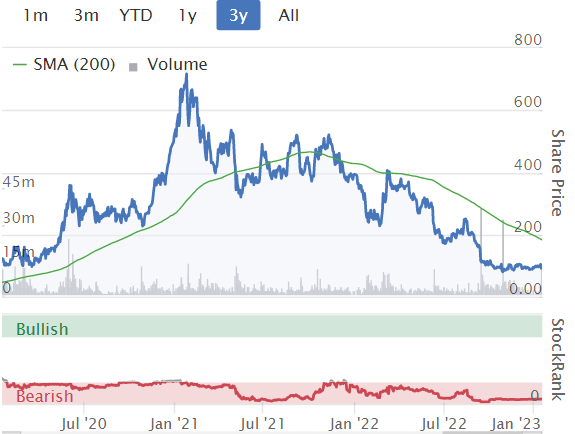
31.5p - mkt cap £43m
A new share for the SCVR. It floated in June 2021 (uh-oh!)
A positive update this Monday said -
Unaudited cash, revenue and loss for the year expected to be ahead of expectations
I started doing some digging, and it’s very unusual, in that all the revenue of c.$25m pa seems to come from grants in the USA, from BARDA.
So it looks as if this share is a binary outcome research organisation. It’s developing a machine to investigate diabetic foot ulcers.
There’s about $11m cash in the business, and of course the whole thing seems to completely rely on the grant funding continuing, which looks high risk.
Two individuals seem to own 59% of the company.
My opinion - neutral obviously, but it might be something interesting to look into. I don’t recall ever seeing something quite like this before. Which begs the question why was it floated, so the Admission Document would be the first port of call for further research.
It’s not the type of thing where I can add any value, or opinion. I just wanted to take a quick initial view, so we’ve got some facts & figures in our archive, for future reference.
EDIT: There's another update today, which seems to be saying that its diabetic foot ulcer device works well. It's too technical for me to understand, but the comments seem to make it sound positive. The trouble with this type of share, is that your average investor (you and me) can't really judge whether it's going to be a commercial success or not, it's pure guesswork. As a punt though, I do think this share looks potentially interesting. That the whole thing is being funded by grants (not tapping shareholders) does appeal to me. But I would only ever treat this type of share as a gamble, with money I can afford to lose.
Boku (LON:BOKU)
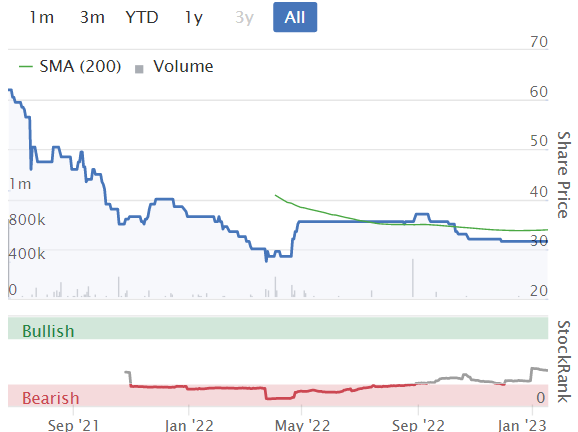
156p (up 6% y’day) - mkt cap £465m
Trading Update - FY 12/2022
It talks about “strong underlying growth”, but actual revenues are only up marginally at $63.3m, although it says this is due to adverse forex, with constant currency revenues up 14% on 2021. So I’m assuming it must generate revenues mainly outside the US, in weaker currencies, but reports in US dollars.
I last looked at this mobile payments IT company about 3 years ago, and filed it in the too difficult tray. Its shares have doubled since then - impressive considering there’s been a tech market crash in the last year.
Adj EBITDA is at least $20m ("in line with market expectations"), which I wrongly assumed we could take with a pinch of salt. But a note from Edison shows that adj EBITDA does largely turn into real profits (adj PBT anyway!) of $17.8m.
Share based payments stand out as repeatedly excessive over the years, whilst divis have been nil. So it’s abundantly clear for whose benefit this company is run! (the Directors). Take a look at the Director dealings page, where you can see that Directors are using this as a personal cash machine.
Balance sheet - the last one looks OK, with a healthy cash pile. This has since gone up to $116m, but only $50m of this is Boku’s own cash, the rest being customer cash in transit. Still, it seems to have ample liquidity.
My opinion - overall, this company has come on greatly in the 3 years since I last looked at it, when it was speculative. Now it’s grown into a proper, profitable business, with solid finances. Growth looks to have slowed down a lot, although maybe that could accelerate this year due to forex movements (at least partially) reversing? Also, it’s close to 100% gross margin, so there’s operational gearing from additional revenues, which could get exciting if serious growth is achieved.
Valuation looks aggressive, on a fwd PER of 44.3, and note that broker forecasts have been coming down - not a good combination (high valuation & reducing forecasts).
So it’s not for me, at this stage, but it could be worth a look if you do tech/growth shares.
On to today's news, and starting with a positive update -
Midwich (LON:MIDW)
492p (pre market) - mkt cap £437m
Midwich Group plc (AIM: MIDW), a global specialist audio visual distributor to the trade market, is today providing a trading update for the year ended 31 December 2022.
There’s an attractive headline -
Record revenue of £1.2 billion, with profit before tax ahead of expectations and the Group well placed for the year ahead
Revenue growth is impressive, up 40% (half is organic) to £1.2bn
Gross margin “broadly in line” (so slightly below, why can’t they just say so?) with 2021. (note that gross margins are low, as it's only a distributor)
Adj PBT “comfortably ahead of market expectations” , with a lovely footnote to assist us -
*Market consensus based on an average of £40.8m and a range of £40.1m to £41.2m, as at 17 January 2023
I haven’t seen any revised broker notes yet, and looking on Research Tree, there don’t seem to be any proper ones at all, because MIDW uses two brokers who ignore private investors altogether - Investec, and Berenberg. How does the company expect to attract private investors, if they don’t let us see any research? Bit of a schoolboy error for a small cap - which need the liquidity that comes from an active private shareholder base.
Valuation - the StockReport shows broker consensus of 33.2p for FY 12/2022, which is well above pre-pandemic levels. If they’re “comfortably ahead”, then this might mean say 36p actual, at a guess? The 492p share price gives us a PER of 13.7 - which looks reasonable. A nice trend here with forecasts -
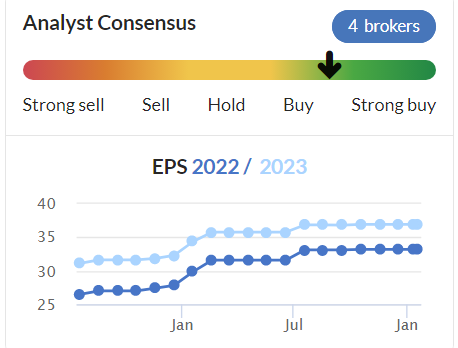
Although bear in mind that the group carries a fair bit of debt, on a weakish balance sheet (only modest NTAV), and of course debt is becoming more expensive these days.
My opinion - this has historically been awarded a high earnings multiple, so maybe this is an opportunity to buy it on a reasonable PER of 13.7? It sounds confident about its markets for 2023 too, although recessionary risk needs to be taken into account. Overall, with rising forecasts, a beat today, sunny outlook, and reasonable valuation, I’ve got to give Midwich a thumbs up.
Eagle Eye Solutions (LON:EYE)
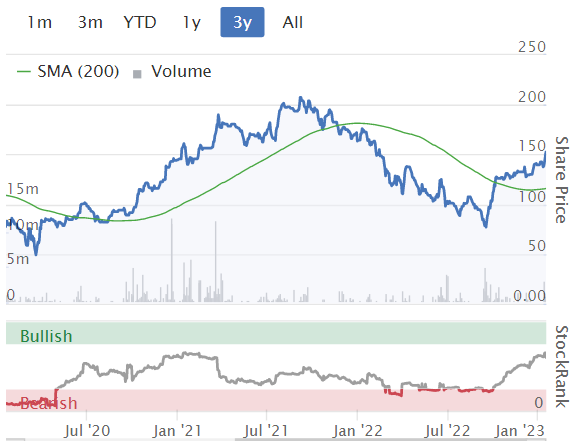
540p (up 3% at 10:15) - mkt cap £155m
We didn’t cover the last full year accounts here, for FY 6/2022 published on 21 Sept 2022, probably because there were no surprises in the numbers (as you know, we prioritise the most price-sensitive updates, good and bad). Looking at those numbers now, the key points for me are -
Very impressive revenue growth, up 39%, and 76% is recurring.
Adj EBITDA up 54% to £6.5m
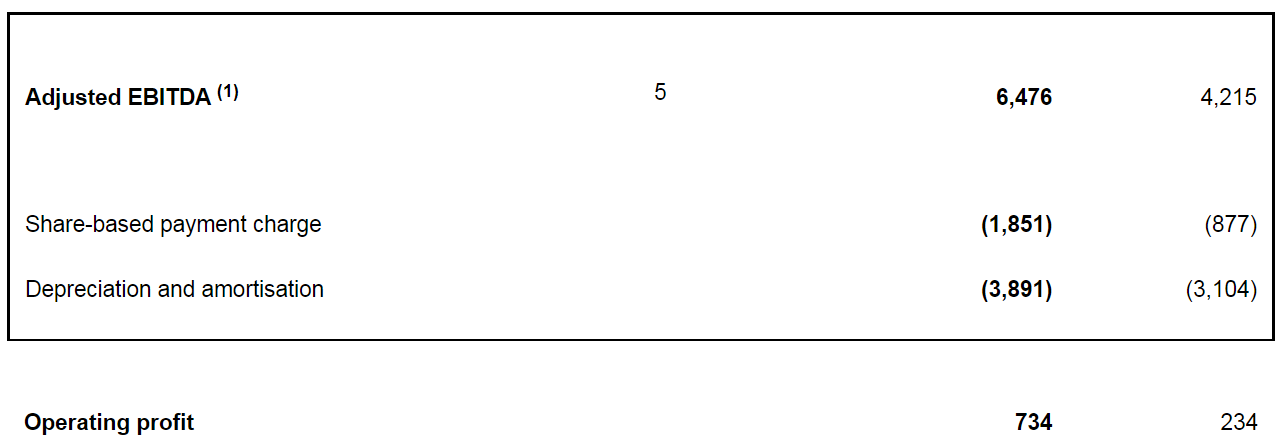
BUT, as I always point out with EYE, it hardly makes any real profit, because the EBITDA numbers are inflated through capitalising a ton of its internal costs onto the balance sheet (almost £5m, per the cashflow statement).
This table from the FY 6/2022 results (LH column) and 6/2021 (RH column) demonstrates the point that after rewarding Directors, and paying for development spend, it’s barely making any genuine profit at this stage (the hope is that in future, rapid growth would create operationally geared high profits) -
.
On to today’s news -
Eagle Eye (LSE: "EYE"), a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing, is pleased to provide an update on the Group's trading for the six months ended 31 December 2022 (the "Period").
The headline says -
Continued strong trading and confident outlook reflecting the growing global demand for personalised loyalty and promotional programmes
Key points -
H1 revenue growth looks good at +32% to £20.0m
Recurring element is higher, at 78%
Adj EBITDA (just for a half year remember) is up 50% to £4.7m
Net cash of £5.7m (up from £3.6m 6 months earlier) - after paying for recent acquisition.
Managed inflation pressures within budget - good.
Pipeline strong
Outlook - FY 6/2023 trading in line with expectations.
Acquisition of Untie Nots has recently completed, going as planned.
Broker update from Shore (many thanks, very helpful) - seems to have set the FY 6/2023 forecasts very low, with £7.6m adj EBITDA, despite it having already achieved 62% of this at £4.7m in H1. So it looks set up nicely to produce a series of ahead of expectations updates over the next 6 months - great, I like it that way around!
Shore seems to be adjusting out the excessive share options cost, which I’m sceptical about, so its £2.5m actual for FY 6/2022 needs to be seen in the context that the real profit (including share option costs) was only about £700k!
Shore’s FY 6/2023 forecast is adj PBT of £3.4m, but I reckon there’s good upside on that figure, so £4m+ looks more likely, less what management decide to help themselves to in share options.
My opinion - I’ve followed this company since it listed, with the concept always looking interesting, but the valuation seeming too stretched to interest me.
However, the fundamentals are improving considerably now, and it’s clearly got a great product, proven by winning & retaining contracts with major retailers, globally.
I’m adding EYE to my potential buys watchlist, as the sort of share that I’d be happy to buy on any general market panic sell-off. It seems to me a share to tuck away and forget for a few years, and try to avoid being shaken out by market volatility.
Overall then, not a value share, but I can see the potential, and am happy to give it a thumbs up.
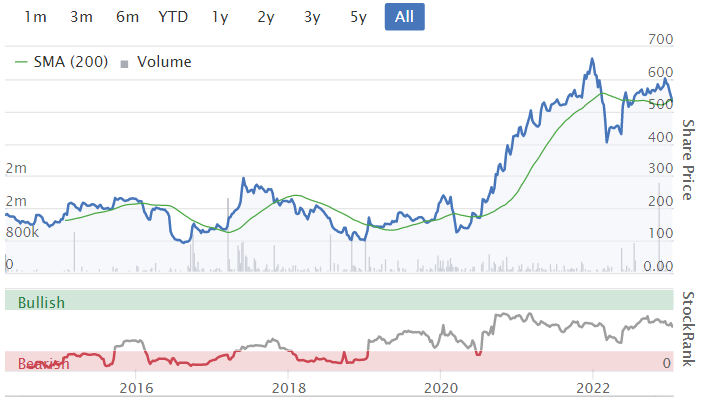
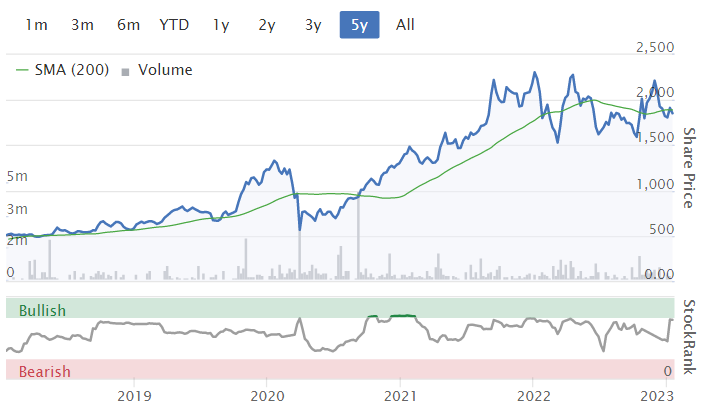
As you can see from the long-term chart below, EYE promised jam tomorrow for years, but we're actually now able to taste the jam, and put a dollop of cream on top too (or the other way around, depending on how you like your scones!)
Graham’s Section:
H & T (LON:HAT)
Share price: 493p (pre-market)
Market cap: £216m
Following on from the update we got from Ramsdens Holdings (LON:RFX) yesterday, today brings an update from larger pawnbroking rival H&T. It’s in line with expectations.
H&T has a much larger pawnbroking operation than Ramsdens, but it doesn’t have the level of diversification into other services that Ramsdens does, particularly foreign exchange.
And H&T stores are spread out nationally, while Ramsdens is only just moving into the South-East (I wonder if there will be much head-on competition between them?).
Anyway, let’s catch up with this trading update for H&T’s performance in FY December 2022:
Trading performance remained strong through the fourth quarter of the year, continuing the momentum seen across the business throughout the year. Demand for pawnbroking loans, in particular, was buoyant. This performance resulted in the pawnbroking pledge book growing to c.£99m as at the end of December 2022 (December 2021: £66.9m). Demand for pledge lending in early January 2023 has remained strong.
Note that H&T’s pledge book is huge compared to Ramsdens - about 10x the size!
And we can see that in these difficult circumstances for many households, the need for pawnbroking loans is higher than ever. But at the same time, H&T’s retail sales are holding up:
December was a record sales month after a slightly quieter than anticipated November, with watch sales being a particular December highlight. Full year retail sales rose over 30% to c.£48m (2021: £36.2m)
The store network has grown by ten in 2022, and there are another nine in the pipeline for 2023. Over-ambitious growth would scare me, but those numbers doesn’t strike me as overly aggressive.
My view
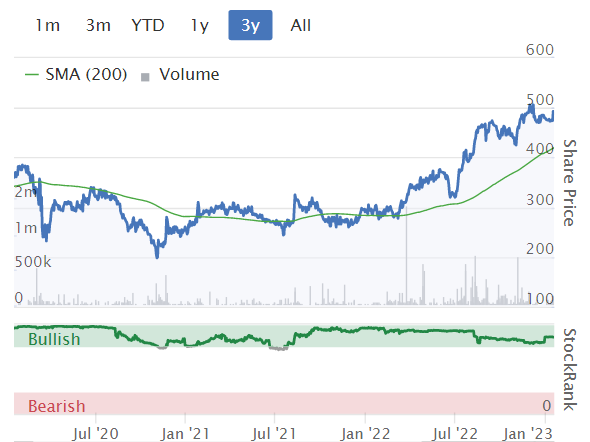
I’ll wrap this up here, as at the end of the day it’s an in-line update. The estimates are unchanged for adjusted EPS of 36p in 2022, rising to 58p in 2023. The pledge book is much larger now, and I do expect a fantastic result in 2023.
Like any lender, H&T is subject to some economic forces beyond its control. If inflation subsides, for example, then perhaps the current extraordinary levels of demand for short-term credit might soften.
Similarly, the level of competition it faces in the short-term credit space is not something that H&T can control - but I personally think the prospects there remain excellent, as the regulatory environment is unfriendly to new entrants.
Overall, I remain a huge fan of this business. My only criticism is that its return on equity could be higher - but hopefully 2023 will see a return to it earning high ROE.
Team17 (LON:TM17)
Share price: 440p (+7%)
Market cap: £640m
We covered two profit warnings from video games companies recently. These warnings resulted in pressure on the Team17 share price, who responded that same day with their own reassuring RNS (see here).
That RNS promised only that FY 2022 was “at least in line with market expectations”.
Today we get the full reveal: it turns out that revenues and profits for FY 2022 are significantly ahead of market expectations!
As I keep saying, video games companies should try not to use the economic big picture as an excuse for poor performance. Good video games will be purchased regardless of the economic environment, because they provide hundreds of hours of entertainment (and are therefore much cheaper than most other forms of paid-for entertainment).
Perhaps one of the few exceptions to this rule relates to the Covid era, when lockdowns artificially boosted demand for home entertainment, and the ending of lockdowns took away that temporary demand.
But Team17 has not needed any excuses: it has continued firing on all cylinders each year. Here’s the explanation of its strong performance in H2 2022:
We are pleased to report that the Group traded strongly in H2 2022, with multiple new first and third-party games released, extended games distribution to wider platforms and strong support across the portfolios with additional new content updates. Careful lifecycle management of the diverse portfolio of growing games and apps across the Group combined to complete a strong FY 2022 performance for the Group.
Debbie Bestwick MBE (CEO) says:
"We look forward to 2023 with an exciting pipeline of releases and updates as well as ongoing ROI from the investments we have made in people and products."
Estimates
According to Stockopedia, the existing forecasts for 2022 were for revenues of £127m, and net income of £33m.
The forecasts for 2023 were for revenues of £138m, and net income of £36.8m. Based on the current market cap, that puts the shares on a 2023 P/E multiple of 17x.
My view
While I have to admire Team17’s financial performance and growth, I must admit that I do find it a little surprising. It's difficult to find any mainstream blockbusters in its catalogue of games. The long-standing Worms franchise is still, after all these years, the only title that really stands out to me.
But it’s hard to argue with the company’s numbers and the leadership is also very impressive when you read about how the CEO was involved in creating the company (and she is still a 21% shareholder, so there’s very good alignment with other shareholders).
Overall, I’m a fan of this company, but I’m inclined to think that it could be fully priced at this market cap.
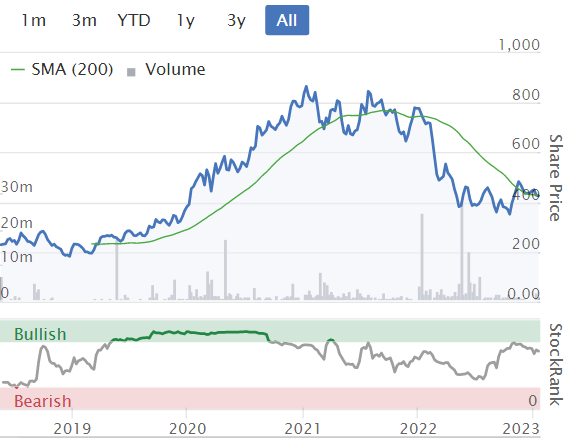
Alpha International (LON:ALPH)
Share price: 1820p (unch.)
Market cap: £767m
This company’s market cap has reached tremendous heights in just a few years. I last covered it in March 2020, on the day when a disastrous RNS saw its value fall to just £142 million!
But here we are, after a slight change of name from Alpha FX to Alpha Group, and with much better results.
Today brings a trading update for FY 2022:
…trading has remained strong: we expect revenue for the full year to increase 27% to approximately £98m (2021: £77.5m), operating profit to be in-line with expectations and profit before tax (including interest) to be ahead…
Moving into 2023, we find ourselves in the fortunate position of expecting exceptional growth in absolute earnings and cash generation, driven by a combination of expected strong revenue growth and interest income.
The point about current-year performance is that it is in line with expectations, except when it comes to “other operating income” - this is interest earned, mostly on client money, and it’s coming in at £9m instead of the £6m forecast.
In a period of higher interest rates, we’ve got to remember to look out for companies that are able to earn a yield on cash balances! And so do the analysts.
So Alpha’s PBT for 2022 is ahead of expectations, purely because of this higher interest income.
2023 estimates - the revenue forecast increases 5% to £120m, and the interest income forecast increases from £18m to £24m. The PBT forecast is now £71m (previously £65m).
Let’s go back to today’s update, and see what the company plans to do with the windfall of unexpectedly high profits it is generating:
…it would be a missed opportunity to not bring forward investment in our operations (in particular in our Alternative Banking Solutions division), originally planned for 2024/25 and beyond. This investment is already underway and is focused on accelerating future revenue growth and strengthening the long-term scalability and sustainability of our business.
Additionally, if operating profit exceeds expectations in 2023, the company will spend those gains on “discretionary initiatives (e.g. marketing campaigns)”, in order to push growth even faster.
My view
After reviewing my notes from 2020, I’m keen to see some evidence that the mishaps which occurred back then will not repeat. Alpha does reassure that its FX Risk Management division has seen “a reduction in overall client concentration”. So there is some reassurance on that front.
This FX division is expanding to Madrid - it’s nice to see international growth, and they already have Spanish-speaking clients which reduces the risk of this expansion failing.
The “Alternative Banking Solutions” division, on the other hand, is still young, and has a long way to develop. But it’s an interesting project and I can see why an FX specialist might have the expertise to build this type of business (opening bank accounts and processing international payments for corporations and institutions).
In summary: I think this is an impressive company. Again, it’s led by a founder-CEO who is also the largest shareholder with 16% stake. So there’s a lot to like. Is it possibly too expensive at this level? That’s for you to decide; I’m neutral at this valuation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
ITM Power (LON:ITM) are the leaders in their field and areb a bloody good company, but hydrogen is a long way away from being even remotely comparable to battery only solutions in terms of efficiency. ITM's main value prop is the adoption of 'green hydrogen', and thereby the mass purchase of their main product: water electrolysers (you make hydrogen from just water and electricity with them). "Green" hydrogen is also dependent a renewable or nuclear energy supply. A dirty energy supply can still power an electrolyser but kind of misses the point.
Hydrogen is, basically, and unfortunately, an extremely cost inefficient way of storing energy for future use. Albeit with good "green" credentials.
Ashtead Technology Holdings (LON:AT.) - buying opportunity coming in the morning with 14% of the shares being offered in an accelerated bookbuild. Main seller is Buckthorn Partners selling down a third of their very large (35%) holding. But CEO is offloading GBP 1m worth so avoid if that's a red flag. Personally I would be adding if I didn't have a full position already.
I know the market can be a strange beast but can anyone explain how H & T (LON:HAT) share price has fallen by nearly 7% after reporting excellent results in line with expectations. Also Paul's analysis and Stockopedia metrics all seem very positive. In the current economic climate in line with strong expectations must be a more than reasonable result given that if you report a slight miss the share price gets hammered! Did investors think they should have been even better than expectations after the results reported by Ramsdens Holdings (LON:RFX)?
I have seen a fair bit on 'selling on the news' coming back into the market again (Knights group (LON:KGH) and Ashtead Technology Holdings (LON:AT.) ) , which is much better than just 'selling' which was the theme of last year.
I think Robbie Burns wrote an article on it on stocko somewhere.....worth a look. That would be my guess as H & T (LON:HAT) does look fully priced, where as Ramsdens Holdings (LON:RFX) perhaps is still not.
Yes I have noticed that quite a bit lately, "buy the rumour sell the news", is the expression. I think a good opportunity to buy or top up, if you are looking to buy, I did buy some Knights group (LON:KGH.
Warpaint London (LON:W7L) is another one that fell back after good news.
I guess what people forget quickly is Knights group (LON:KGH) was down in the 67p range in November 2022, in two months it is up to £1.20... so yes if you bought at £1.20 it hurts to be at a £1 if you bought at 75p, you think I should have sold at £1.20, but still £1 feels good
Though if you bought back in 2020 at £4.80 you are still going OUCH!
On my watch list, I do not hold.
Tommy
Alpha International (LON:ALPH)
Graham,
ALPHA has several growth share schemes, SAYE schemes, etc., etc., which I feel need to be considered when valuing the company.
Here is a flavour of what is happening, taken from 16.iii.22 RNS for FY21. Opaque-masquerading-as-clear explications of the schemes are included elsewhere in the RNS.
13. Events after the reporting period
Following the vesting of the B Growth Share Scheme for the year ended 31 December 2020, the Company will be issuing 630,279 shares in March 2022. Following the revenue growth target for the year ended 31 December 2021 being met for the B Growth Share Scheme the Company will issue 675,419 shares in March 2023.
Following the vesting of the C Growth Share Scheme for the year ended 31 December 2021, the Company will be issuing 219,494 shares in March 2022.
Following the vesting of the E Growth Share Scheme for the year ended 31 December 2021, the Company will be issuing 174,345 shares in March 2022.
Following the first year of vesting of the Alpha FX Institutional Limited share scheme for the year ended 31 December 2021, the Company will be issuing 99,828 shares in March 2022.
Following the vesting of the SAYE scheme, the Company will be issuing a total of 108,671 shares over the next few months starting on 25 March 2022, with the date of allotment dependent upon when employees elect to exercise their option during the prescribed window.
All of this is in addition to shares issued during the year and does not list shares issued in partially owned subsidiaries. The FY report makes it clear that the schemes issue shares every year and that further schemes are being created.
Furthermore, B Growth shares (+C, +E, etc.) don’t show up as part of the share count until they are exchanged for ordinary shares @ 1:1. For some reason, they don’t appear as share-based payments, either.
The total shares above = 1,908,036
Price of the company’s shares in March 22 c. £13.40 x 1908036 = £25,567,682
I treat payment in shares as compensation, so in calculating the earnings of a company I subtract the value of shares issued to employees from profit:
£25,567,682 in shares subtracted from underlying full-year profit before tax c. £33.2mil = £7.6 mil minus tax of £7.14 mil= c. half a million for the owners of the company.
I haven’t worked out the likely number of shares to be issued this year. It is unlikely to be fewer. It might be possible to get an idea by looking at the details of the various growth schemes.
Disclosure: I don’t own any.
Hi Graham,
Thanks for your review of Alpha International (LON:ALPH) May I ask for the source of the £71m PBT figure? Assuming tax at 20% that would mean PAT c£56m so a PE of 13.5. Given their high growth rate (27% all organic) I'm surprised you're not more positive than 'neutral'
Thanks very much
Alpha International (LON:ALPH)
Hi Kouremenous, you're welcome - Liberum's estimate of 2023 reported PBT is £70.9m. This is after £24m of estimated interest income. The revenue growth is indeed very impressive! G
Thanks Graham
Alpha International (LON:ALPH) - I don’t indulge in much technical analysis but one thing I’ve learned - the highest quality stocks consolidate by moving sideways. Compare the long term chart to the likes of Equals (LON:EQLS) Argentex (LON:AGFX) and Wise (LON:WISE. This is the cream of the FX crop.
The update had everything I look for: outperformance, bullish outlook, commitment to reinvest excess profits for growth (no I don’t want a dividend - grow baby, grow). A repeat of the large customer blip of 2020 is far less likely following a restructure of contracts and widespread diversification. And it’s not even particularly expensive any more at 16x FY23 reported earnings (per Liberum).
Team17 (LON:TM17) Fortunately I bought in to Team17 shortly after they went public in 2018 and since then they have been as high as 800 pps per share during the lockdown years and I was lucky enough (or wise enough ) to trim my holdings at that kind of price . I recall meeting Graham at an investment do in Leeds ( I think it was probably 2019 ) when I asked him to take a look at Team 17 but at the time I believe he felt that they were possibly too small and also fully valued at the time. It's good that he is now a fan of the company but I think thet his opinion about valuations has not changed . At the time I looked at Keywords , Frontier Developments , Suma (since been acquired ) and I think there was one other that I can't recall . Team 17 stood out as an outstanding value share in a growing market - I think the business model developed by Debbie Borthwick is clever ( a mix of in house games development and independent ( "indie") ) is very defensive in a competitive market and they have slowly through aqusition and in house developement increased their in house share and hence increased their margins at the same time. The move into educational entertainment ("edutainment") apps for children with the acquisition of Story Toys in July 2021 in my view was clever and has helped to insulate the company from the woes suffered by Frontier Developments . All in all a very well manged company in a sectotr that will continue to grow . Like Mark B I would regard this as a buying oppurtunity.
This really isn't good. All this talk of how good the company is could have the undesired effect of pushing up the price! I need a dose of irrationality - similar to the events of a few days ago. Lets get that share price down.
Two edged sword of course and I prefer the edge where the direction of travel is north not south but pleased that you endorse my views on the company .
The direction of travel will always relate to the fundamentals of the company, eventually. I like it when it is disconnected - that's where the opportunity is. My ideal would to be buy for the next year or two and then sit on it for the next 20. :-) Obviously, the future is never that clear cut - but that should signal my intentions.
I remember that! Well done Fred (edit: but maybe it was the Manchester Investor Show?)
Could have been -is it more than 10 minutes ago !
Boku / Bango.
Paul, you are correct. Boku accounts in USD but most revenue is in other currencies. Japan and South Korea have traditionally been the centres for direct carrier billing but DCB is now spreading world-wide and this explains the recent foreign currency headwind, however, this may well now become a tailwind in the US stops increasing interest rates. Indeed the USD has already weakened somewhat from its strongest point.
I do not have a position in BOKU. They made a terrible acquisition a few years ago and I am not confident in their strategy.
I do have a position in Bango (LON;BGO). I do like their strategy, directors, and recent acquisition end Ausust. This acquisition of the data processing arm from their largest competitor in Japan, coupled with a long term plan for all their DCB billing will almost double Bango's EUS from $4B to $7.5B and also bring many more clients to Bango creating a halo effect, more transactions, more data etc.
Bango have also recently announced contract wins including Verizon, T-Mobile USA and also a contract with a global tech leader which is most likely Apple, all of which are only just starting to produce revenue.
Bango also has very high margins of over 90% so every bit of revenue in mostly profit.
I hold so biased.
Hi Guys, Newbie poster here. Any chance of a review of Belvoir BLV ? Asking for a friend !!! Great daily updates BTW
Hi Colin! Welcome to the SCVRs!!
Yes, I always cover Belvoir (LON:BLV) when it reports, and it's one of my watchlist ideas for 2023. I last looked at BLV here in late Oct 2022.
These reports are driven by the day's announcements, and I don't see any news from BLV today. So when BLV next updates us on trading, I'll definitely be covering it here.
Regards, Paul.
Thanks Paul, that link to Oct 22 on BLV only mentions BLV in passing (bottom of PURP comment) with no sectional comment. Unless Im missing it ?
Hi Colin, if you click on the 'Discussions' button on Belvoir (LON:BLV) page, it will show all the previous times Belvoir (LON:BLV) have been discussed in previous posts.
BLV management regularly present to private investors. If you search on YouTube you'll be able to find their Investor Meet Company presentations.
hi Paul
Following Team17 (LON:TM17) being reported on and tagged all the tagging for the other previously reported companies have dropped off.
Snazzy
Oh I know, the tags all vanished a little while ago, but I spotted it & put them all back in manually.
Must drive you mad!
Cerillion (LON:CER) down 10% past couple of days, no news I can see? Hoping just a shake out!
Team17 (LON:TM17) - the comment about how it's surprising that the company does so well even though it doesn't have any block busters - that for me has always been a silver lining. Debbie - my CEO - has a very good history of organizing developers (cats) and so it's no mistake that she is able to aggregate this into substantial value. One day, these bunch of developers could come up with a block buster which will be icing on the cake. Given it's past growth performance, I think the future growth performance will be similar, considering the market and how small they are in that market. Nothing is certain obviously, but I have owned this for circa 3 years and expect to own it for many more - but that's not really applicable to the majority here. The short term performance of the shares is beyond me, I hope it goes down, but in the long term - and I think I will own it for at least the next 5 years, maybe forever, I see this company compounding for many years to come. The current price, on my valuation work is currently undervalued, so I keep buying - I just hope that you disagree and sell me your shares. :-)
Last time people here talked of holding shares forever the market tanked for 18 months, including Team17 (LON:TM17)
And I almost doubled my holding. I call this a buying opportunity. I don't know when these happen, but I do know what I do when these happen. And the majority of people start talking of holding forever when the market is red hot, more buyers than sellers for a prolonged period. The same majority then exit by following most everyone else. Happy to buy in those times as long as the business operations are executing well and not too concerned about factors beyond their control when I view them as short term events and not life threatening events. But, if trading and speculating are your game, then by all means, sell those shares. I'm happy to keep accumulating and hope the price stays below my valuation for as long as possible.
Don't get me wrong I like Team17 (LON:TM17) and have bought back in again this morning but I wouldn't consider any share a hold forever especially if they don't pay a dividend. Selling is as much of a skill as buying in my opinion.
No broker notes for us plebs but if it's of interest to anyone-
"Numis increased its 2022 sales forecast by 7% to £137 million and adjusted EBITDA (earnings before interest, tax, depreciation, and amortisation) by 7% to £47.6 million which is around 9% ahead of consensus.
Analysts at Peel Hunt made similar upgrades to their forecasts saying, ‘Team 17’s thesis of careful life cycle management alongside thoroughly researched M&A has stood the test of time and once again produced strong results, especially in the context of competitors struggling"
Just because it doesn't pay a dividend now, doesn't mean forever. The company does state that if it cannot find opportunities to re-invest, it will start paying a dividend. That, hopefully, is a long way off as they can continue to find great places to re-invest - better than I can with a dividend. All this information is on their web-site and in the annual reports - you just have to read them. Surprisingly, and I am genuinely surprised, there seems to be a distinct lack of reading the reports that our managers (as owners) give us. I cannot fathom not reading them. I want to know as much as I can about my businesses otherwise I would liken the shares to currency in a casino.
Mark, as you consider yourself a part owner could you maybe give your CEO a call and ask them to use a Private investor friendly broker, instead of giving a large advantage to a select few?
I have no problem with my broker Interactive Investor
I thought compounding only referred to a company that pays a dividend (now) ?
Have a look at Berkshire Hathaway for an example of how a company compounds internally and has never paid a dividend. If a company can re-invest its free cash flow at a greater rate of return than I can typically get, that's my sort of company.
hmmm I see your rationale but not sure I agree Berkshire a lot more successful then Team17 at it that we can agree on
my apologies Mark B -after doing some research I now see what you are saying and what a quality compounder refers to - I'd always thought it referred to the effect re-investing dividends had... thanks !!
Eagle Eye Solutions (LON:EYE) with organic growth of 32% to £20m and £2m net cash inflow (in the most recent half year) is looking very strong and might be worth a closer look, Paul. Shore Capital hints at future upgrade. This kind of rapid profitable SAAS growth is (still!) valued highly in the US at 6x revenues (according to Shore) or 7-8x revenues (see PublicComps use 42% for rule of 40) -- so at least with American eyes this one looks a bargain given its £40m revenue runrate.
Been quite a bit of director selling selling recently. Which puts me off.
Where did you see that? It looks like William Currie (non-exec) reduced his stake by a third but the other 6 directors all bought in the placing at 555p.
Eagle Eye Solutions (LON:EYE) Im looking on Stockopedia. Currie sells nearly £6m, some of the other directors do buy some. Seem to be a lot share options, buy shares for 1p.
Nice positive update from £GFRD Admittedly a low margin business but trading well, good staff engagement, credible approach to revenue and margin growth with some savvy acquisitions, such as the water business of North Midlands Construction from the administrators. Has initiated a £15m share buy back, reintroduced dividend 5% plus.
Contracts now generally have inflation adjustment clauses built in. Shares trade below cash on the balance sheet.
Recently bought an opening position.
Hi jonno, forget the £ key, use the @ to prefix your ticker! (and choose the ticker in the pop-up).
Thank you Silver Moon.
Galliford Try Holdings (LON:GFRD)
Contracts now generally have inflation adjustment clauses built in. Shares trade below cash on the balance sheet.
Do you have any idea how it will work in 9 months time when inflation is in negative territory ?
Will they potentially have to reduce prices or does the linkage stop at zero or a minimum specified figure above zero?
Don't think anyone is forecasting prices falling. Just the rate of increase in prices falling.
Well energy prices have fallen considerably since last March and that is the main cause of inflation.
Hi rmillaree
Regarding inflation you may well be right, but personally I have no idea where inflation will be in 9 months time, hopefully it will have fallen significantly.
My approach when investing is as best I can to focus on the facts and avoid predictions.
Insofar as Galliford Try Holdings (LON:GFRD) is concerned Andrew Duxbury said during his Mello presentation that inflation protection is built into contracts. He added that inflation has become more stable of late which has made this process easier and has enabled the company to lock in prices with suppliers. They pay suppliers promptly, my recollection is within 25 days
Your particular point was put to him by David Stredder who asked if the company might benefit if inflation decreased during the contract period. Andrew Duxbury replied that this was potentially possible, although he didn't expect inflation to disappear anytime soon.
GFRD
looks copper bottomed to me
3.5 billion of orders is a a decent order book
Share buybacks very good , 15 million I seem to remember
10 million pa payout is good
175-195 million cash is good
They are looking to increase margins to 3%
Looks easy to understand and I think it’s just looks too cheap given the order book .
Building myself too .
Galliford Try Holdings (LON:GFRD) Very much agree planetx, but I am biased. My purchase deviates somewhat from my usual criteria in that I tend to shy away from low margin businesses, but after some research the upside looks very positive, given patience.
If you are signed up to Mello Mondays, there is an excellent presentation from the CFO of the last interims to 30 June 2022. See Mello Monday 24th October 2022. It covers the company's approach to risk management, employee engagement, finances, plan for revenue/margin growth and recent acquisitions.
All three acquisitions have been bought out of administration and focus on the regulated water industry.
My morning smallcap tweet: Game of Moans
Omega Diagnostics (LON:ODX) STM (LON:STM) Fix Price (LON:FIXP) Triad (LON:TRD) Alpha International (LON:ALPH) Mercia Asset Management (LON:MERC) Team17 (LON:TM17) Crimson Tide (LON:TIDE) ENGAGE XR Holdings (LON:EXR) Tissue Regenix (LON:TRX) Midwich (LON:MIDW) Burning Rock Biotech (LON:BNR), Eagle Eye Solutions (LON:EYE), S4 Capital (LON:SFOR), H & T (LON:HAT), Galliford Try Holdings (LON:GFRD), Smartspace Software (LON:SMRT)
◄Omega Diagnostics (ODX)► warns FY-Mar lower than expected revenue, Rev at Health and Nutrition business £7.5-£8m. EBITDA loss (cont) c. £1m. "With the later than anticipated receipt of customer orders, Company has insufficient manufacturing capacity to meet anticipated demand." Stronger than expected order book for FY24. [SP=3.82 Cap=9m]
◄STM (STM)► guides FY-Dec rev £24.1m and pretax £1.7m. H2 "albeit slower than anticipated, particularly within the personal pensions and life assurance business". [SP=28.02 Cap=17m]
◄Fix Price (FIXP)► opens two stores in Mongolia. [SP=NA Cap=NA]
◄Triad (TRD)► H2 has seen "a strong upturn in levels of new business wins and bidding activity". In line? [SP=95 Cap=16m]
◄Alpha Group (ALPH)► guides FY-Dec rev up 27% and pretax ahead of expectations. [SP=1863.88 Cap=798m]
◄Mercia Asset Management (MERC)► sold Intechnica for £14.5m (EV) = £3.7m cash, 70% above book. [SP=33.45 Cap=147m]
◄Team17 (TM17)► guides FY-Dec rev and adj EBITDA significantly ahead of market expectations. [SP=410 Cap=597m]
◄Crimson Tide (TIDE)► guides FY-Dec rev >£5.3m up 30%, smaller than expected pretax loss due to high rev and cautious H2 marketing spend. [SP=2.51 Cap=17m]
◄Engage XR (EXR)► guides FY-Dec rev up 63% and EBITDA loss €5.8m. In line? [SP=4.8 Cap=14m]
◄Tissue Regenix (TRX)► distribution agreement for OrthoPure® XT in China. Distributor must purchase a minimum unit volume each year to maintain its exclusive status. [SP=0.63 Cap=44m]
◄Midwich (MIDW)► guides FY-Dec rev up 40% and pretax comfortably ahead of market consensus of £40.8m. [SP=490 Cap=436m]
◄Burning Rock Biotech (BNR)► hikes FY22 rev growth guidance to 10% from 5%. [SP=NA Cap=NA]
In line: EYE, SFOR, HAT, GFRD, SMRT
Team17 (LON:TM17)
After rushing out an "at least in-line" TU after being caught up in the Frontier Developments (LON:FDEV) profit warning, today's TU says the result for the year "will be significantly ahead of market expectations and show strong growth compared with FY 2021, benefitting from the performance of a stronger, broader portfolio supported by the acquisitions and investment in people made over the last two years."
Lets see what the market makes of that after writing-down the SP over the last few days.
Phil
(I hold)
A pity that it has gone up - around 6% at time of writing. I was hoping it would stay depressed at least until the end of February which would give me time to accumulate more. Maybe I will get lucky and one of the other companies in the sector will report some bad news and everyone will start running for the hills again. Bonkers market followers.