Small Cap Value Report (Wed 18 May 2022) - SAG, KLR, REDD, BWNG, POLX

Good morning, it's Paul & Jack here with you today. I'm (Paul) conscious that there's a big backlog from yesterday's results, so will try to make inroads into that. Today's report is now finished.
Agenda -
Paul's Section:
Science (LON:SAG) - impressed us last year, with a series of upgrades. It issues another positive update today, with H1 20% ahead of last year's impressive H1. Looks good value to me, although with so much macro uncertainty, nobody knows what might happen. Dollar strength is helping.
Redde Northgate (LON:REDD) - one of our favourite value shares, so I'll continue reporting on it, despite the growth in market cap. It's a very nice update today. There are some risks, but this share remains a SCVR favourite, with a low PER, robust outlook, divis over 5%, and strong net asset backing too.
N Brown (LON:BWNG) - I explain in the reader comments section why I've dropped coverage of BWNG. Basically because I'm worried about its large/complex legal action. But mainly due to the collapse of similar business model Studio Retail - selling stuff online, to generate business for a high risk/high cost consumer lending business. After a close shave with STU, I wouldn't go near any similar business ever again. That said, if you're prepared to accept the risks, then today's trading update does come across well. [No section below]
Polarean Imaging (LON:POLX) - a quick look at this blue sky medical company, to see if it has enough cash to reach regulatory approval? It seems funded into 2023, but risk:reward now looks a lot worse, given that if regulatory approval is denied for a second time, then another future fundraising could be very difficult.
Jack's section:
Keller (LON:KLR) - mixed results so far but management expects full year results to be in line with a customary H2 weighting. The group is low margin though, and it faces pressures in a number of markets, so I’m ruling myself out. But there’s a good dividend track record and the yield is nearly 5% (covered more than 2x), potentially something to consider for income investors.
Mello Chiswick update - it’s next week!
I know how hard David Stredder & the Mello team have been working behind the scenes, it’s been incredibly difficult for them to persuade companies and fund managers to come to a physical event, as they prefer online webinars now. I can understand that, but there’s no substitute for face-to-face interaction, and I’m really keen to see investors support these physical events, otherwise the danger is we’ll lose them forever. Obviously only if you feel comfortable attending a physical event, not everyone is, I understand that. David says the seating will be much more socially distanced than in the past.
Provisional schedules have now been published - do click on the links below, to see what's on, as they're very strong in my view -
Tues 24 May - day one schedule - focused on investment trusts & funds. This looks a really good opportunity to meet, and question many fund managers, in different sectors.
Weds 25 May - day two schedule - Andy Brough, Gervais Williams, and Lord Lee are the headline speakers, it should be fascinating to hear their perspectives on this horrible bear market. There are some excellent companies presenting too, that I’m looking forward to meeting in person, having written lots of stuff about them here! Will I need a bodyguard? Looking at the list, probably not, as I don’t recall being particularly rude about any of them!
Thu 26 May - day three schedule - highlights for me are my friend Leon Boros, who is always full of investing wisdom & insights, plus Ken Ford, Chairman of SDI (LON:SDI) which has a superb track record of acquisition-driven growth. If you’ve not heard Clarke Carlisle speak before, then his session is a must - I won’t spoil it for you, just hear him speak, a very moving, and inspirational man.
There are still available slots for companies that would like to get in front of & interact with hundreds of serious investors. Contact David here.
Discount code - get 50% off tickets, using: M2250
I’m looking forward to seeing Stockopedia subscribers there, to say hello, have a beer, and this will also give me an opportunity to apologise in person for Boohoo (LON:BOO) performing so badly, which I know has cost many of us an arm & a leg unfortunately.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Science (LON:SAG)
380p (pre market open)
Market cap £173m
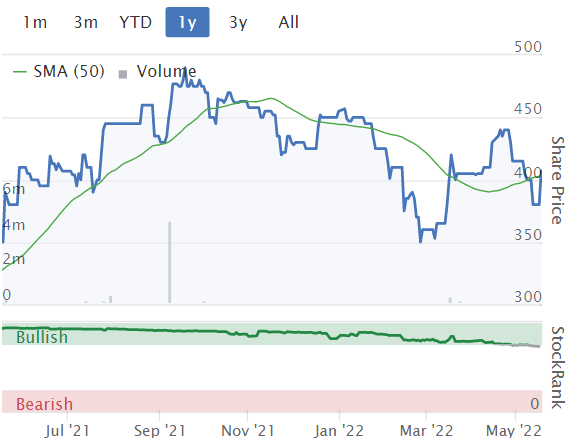
This share peaked at around 490p last autumn, and like almost all small caps, has slipped back (22% down from the peak) this year, largely irrespective of fundamental performance. I recall reporting on a series of positive updates from SAG last year, so it’s a company we like here at the SCVR - performing well, and now reasonably priced again.
What’s the latest?
Relating to FY 12/2022.
The person who wrote/approved the RNS seems to have forgotten to put in a description of the business. Here is the description which it did include in the last full results published on 16 March 2022. Management need to remember that investors have well over a thousand listed companies in the UK to look at, and some investors are new, so people won’t necessarily know what (particularly smaller companies) actually do! So a brief description should appear at the top of every trading update/results statement please.
Science Group is an international science, technology and consulting organisation. The Group comprises three divisions: R&D Consultancy; Regulatory & Compliance; and Frontier Smart Technologies ('Frontier'), together with significant freehold property assets and a strategic shareholding in TP Group plc.
This sounds positive to me -
The Group has had a good start to the year, with performance through April slightly ahead of the Board's expectations.
It is therefore anticipated that the Group will report adjusted operating profit ("AOP") for the first half of 2022 around 20% higher than in the same period of the prior year.
The Board is closely monitoring the impact of materials, energy and wage inflation but is benefitting from a broadly offsetting effect due to the strengthening of the US Dollar relative to Sterling.
That’s a really good point, which we haven’t mentioned yet here at the SCVR - that there’s been a significant strengthening of the US dollar recently, which makes inflation even worse in the UK of course. So if it sticks, then that adverse exchange rate move is more bad news for many UK companies. However, it’s good news for companies that generate sales in dollars, but report in sterling. So it’s worth having a think about which companies in our portfolios might benefit from, or be damaged by, this change in exchange rates. Or, we can just ride it out, if we’re longer term investors, as swings & roundabouts. That’s up to you, depending on your investing timescale with individual shares.
Looking back to last year’s interim results, they were very good - adj EPS up 51% to 13.3p in H1, then 15.2p in H2, giving 28.5p for FY 12/2022.
So being 20% ahead in H1 this year, looks impressive.
Outlook - nothing much is said about the outlook for the full year, which is a bit disappointing. I think in these unstable macro times, companies need to give clearer guidance, especially of the downside risks.
Liquidity - sounds fine -
Gross cash at 30 April 2022 was £38.4 million with net funds of £23.4 million. The Group's strong balance sheet, enhanced by the undrawn facility of £25 million arranged in December 2021, enables the Board to continue to evaluate corporate opportunities to increase the scale and/or development of the Group.
The balance sheet is pretty good, I’ve just checked the last one as at 31 Dec 2021. Although note 11 shows that trade creditors are high at £30.0m, including “contract liabilities” of £17.1m, which usually relates to situations where the customer has paid up-front (the double entry being DR cash, CR trade creditors), hence flattering the cash position.
Why does that matter? Because it could unwind possibly, reducing the cash pile if/when it does so. Hence best not to spend that cash, in case the favourable working capital position does unwind, or at least partially unwind. These things can also be set up so that they look good at year end, which is why I much prefer reporting average daily net cash, rather than a year end snapshot.
New Director - only a NED, Susan Clement Davies, but she has an impressive CV. I know some people roll their eyes at diversity, ESG, etc., but personally I think it’s great to have more diverse boards (providing people are suitably qualified for the roles). In my personal experience, the dynamic definitely changes when there are more women on a Board. Although there is a risk that the women change their behaviour, and try to out-macho the men, which is not good, which I have witnessed myself, thinking about one former colleague in particular!
My opinion - I don’t have an up-to-date note, but looking back to a Liberum note from March 2022, it was forecasting 2022 EBIT (i.e. operating profit) up only 2% on 2021. Hence the company telling us today that it’s now expecting H1 profit to be 20% up on 2021 looks like a considerable beat. Or at least, it seems to provide some leeway for H2 to be softer, and the group still achieves its full year forecasts.
It’s always better to be ahead of expectations, rather than scrambling to try to catch up.
The beneficial dollar effect is lucky! That could reverse of course, so caution is needed there.
Stockopedia is showing the forward PER as 13.9, which looks cheap for a group which has a strong track record.
There’s also the issue of its holding in TP (LON:TPG) where SAG’s shareholding has flopped in value, and its attempted takeover bid didn’t succeed. There could be an exceptional write-off there, perhaps? Or will SAG come back for another attempt at a bid, now the share price has crashed? The timing might be ideal for that now - shareholders would probably be more receptive to an exit at a decent % premium, now the share price is bombed out.
All in all, I do like SAG. As with everything though, we don’t know how current macro problems will play out, so there’s short term risk with practically all shares. Longer term though, equities (and property) are the best places to be when inflation is high. Whilst bonds & cash are the worst. So all those investors holding cash piles, you’re losing 10% p.a., so that cash needs to be put to work at some point!
I see SAG has opened up, so that's good news for holders.
.
.
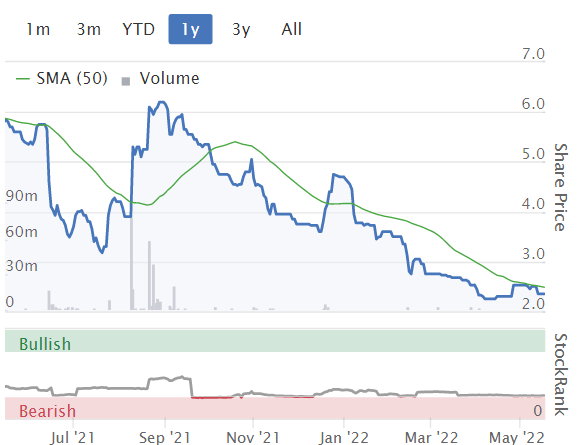
Also note that SAG owns 27% of listed TP (LON:TPG) (current market cap £18m) whose share price is not looking so robust, to put it mildly, hence a loss of value for SAG -
.
Redde Northgate (LON:REDD)
379p (up 3% at 08:45)
Market cap £932m
Prompted by readers nagging me to look at REDD when it was dirt-cheap during the pandemic, we’ve done very well on this share. So it would seem a pity to drop it, just because the market cap has risen above our arbitrary £700m usual cut-off, hence I’m going to continue covering Redde.
Redde Northgate (LSE:REDD), the leading integrated mobility solutions platform providing services across the vehicle lifecycle, today announces its pre-close trading update for the year ended 30 April 2022, ahead of its results for the full year scheduled for Wednesday 6 July 2022.
My scorecard awards an “E” for the company’s own self-description above, which is meaningless.
Let me rectify that with my own description -
About half of REDD is a white van rental business in UK & Spain. The other half is credit hire & other legal services business - mainly providing courtesy cars for the not-at-fault party in car crashes, charging insurance companies the fees.
Isn't that better?!
Credit hire businesses in this sector tend to trade on very low PERs, because they’re often quite flaky business models - running up massive receivables, and sometimes going bust. I looked at something like this recently, but can’t remember the company name. I think it begins with A? It looked awful, with receivables well over 1 years' revenues! Big profits (and lots of tax to pay), but no cashflow. That looks an accident waiting to happen, Quindell v.2?! I've remembered, it's called Anexo (LON:ANX) - very much one to avoid I think, for the reasons given. If it starts to generate proper cashflows, then it might be worth a fresh look in future, but for now it's uninvestable for me.
REDD is better, because it moved to a collaborative model years ago now, whereby fees are pre-agreed with insurance company clients, and paid promptly. So it’s more of an outsourcer. Margins and cashflow are very good, and divis remain generous. Insurers probably don't care too much about REDD making nice margins, as it's all passed on to motorists through premiums. That's why false whiplash claims remain an obvious, and ongoing debacle - the cost is passed on to us.
REDD has also been lucky, in that the restricted supply of new vehicles means it’s been sitting on a goldmine, in terms of its large vehicle fleet appreciating in value. Although that may not persist, so let’s hope the company does move over to a leasing model, as planned, and they get the timing right to dispose of the owned vehicles whilst values are high. The clock is ticking on that, as in a recent webinar, the CEO of Vertu Motors (LON:VTU) (I hold) said residual values are now falling by c.2% per month, which is normal market conditions (although that’s from an inflated starting point).
PR heading -
Strong FY2022 performance across the Group
My summary of today’s update -
FY 4/2022 in line with expectations (raised in Mar 2022)
Underlying revenues up 24% on LY
Strong residual values for used vehicles due to restricted supply
New vehicle supply expected to remain constrained in FY 4/2023
Expecting “some moderation of used vehicle pricing”
Credit hire volumes at c.90% of pre-covid level
Longer credit hire lengths (good for REDD) due to parts supply constraints for damaged vehicles
Cost inflation - is being “carefully managed”, and margins in line with expectations - sounds encouraging
Cashflow - “underlying”, “remains strong”
Liquidity - “significant headroom” on bank facilities, renewed in Nov 2021.
Outlook - a bit vague, but sounds positive -
The ongoing macro challenges in the global automotive supply chains look set to continue in the short term, albeit expectations for a recovery next calendar year are growing. On this basis we expect to retain more of our van fleet this year and limit disposals in order to meet customer demand, and to grow our car fleet in line with our strategy.
With strong performance in all areas of the business and supplemented by previously announced new business wins, the Board expects to see another year of progress in FY2023.
Valuation- for value investors, how could you not like these numbers below - low fwd PER, great divi yield, and a price to tangible book value of only 1.38 - in other words, this share is also strongly asset backed, as well as being cheap on earnings & yield. Very attractively priced, for a fairly decent business I think -

.
Downside risks might include -
- Regulatory/Govt action of some kind that could hurt the credit hire side of the business
- Loss of a major client on the credit hire side is something that previously triggered a nasty profit warning, a few years ago, from memory I think the share price roughly halved on that news - looking at the chart maybe it was 2015? Although note that the business is now more diversified, following the merger with Northgate’s van hire business more recently.
- For more risks, it’s always worth reading the risk disclosures that come with results statements, and are in Annual Reports. Many people ignore these notes, but they’re a mine of useful information.
- This sector tends to only attract modest PERs, and current profitability may not be fully sustainable, given the unusual shortage of supply.
My opinion - I used to hold REDD, but don’t currently. It’s tempting to buy back in, given the really attractive valuation, asset backing, and dividend yield. For existing holders, as always it's your decision. Although REDD looks well protected from current macro conditions, and you get lovely divis to offset some of the impact of higher inflation. After today's update, I can't imagine why anyone would be selling.
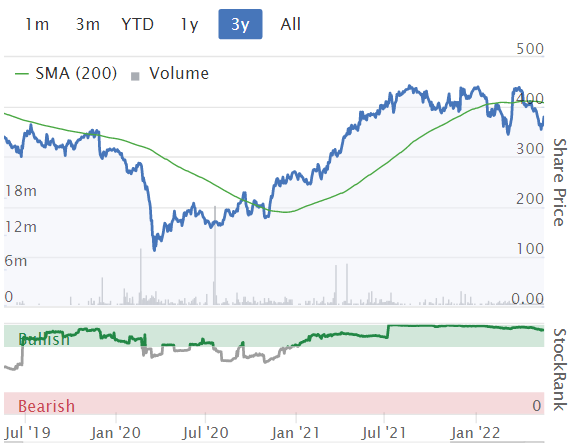
As you can see below, from the 3-year chart, it's proven resilient, and I cannot see any reason why that would change, given the strong fundamentals and low valuation -
.
Polarean Imaging (LON:POLX)
50p (down 1% at 11:24)
Market cap £105m
Polarean Imaging plc (AIM: POLX), the medical‑imaging technology company with an investigational drug‑device combination product using hyperpolarised 129xenon gas to enhance magnetic resonance imaging (MRI) in pulmonary medicine announces its audited final results for the year ended 31 December 2021.
What a wonderful company description! At least it says what the company does, not that many investors will understand it!
We don’t normally cover blue sky companies, but some shrewd friends pointed me towards this one, so I did some work on it a while ago. To my untrained (in medical matters) eye, Polarean looks credible for a number of reasons, including having a heavyweight Italian medical company as a major shareholder.
It had a major setback recently, when regulatory approval was not granted, and POLX was sent away with a to do list, to reapply in due course. Many investors thought regulatory approval was a formality, which turned out to be wrong.
Hence the outcome here is binary - if approval is granted, then the share is likely to spike up instantly, and could go on to be successful if the product sells well.
The downside scenario is that it runs out of cash, and can’t get regulatory approval.
Polarean is largely pre-revenue (just a small $1.2m in revenues for FY 12/2021 for research purposes - but quite interesting that research customers obviously think the product has potential, or they wouldn't be buying pre-regulatory approval, one imagines).
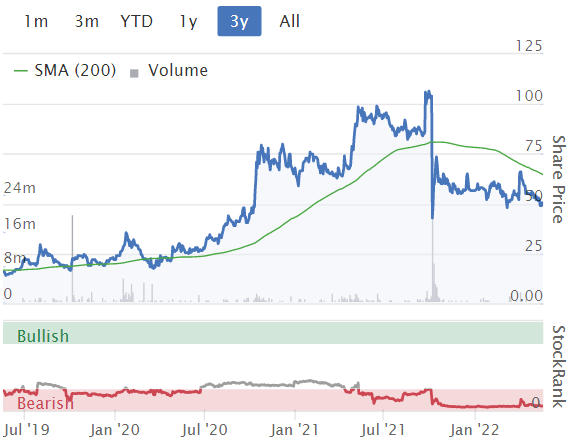
Cash - is it going to run out of cash, is the main question with 2021 accounts? Probably not, I’d say, at least for now. There was a $28.9m cash pile at end 2021. However, costs doubled in 2021 vs 2020, resulting in a hefty $14.0m loss before tax. So if costs remain at that level, then the cash pile would last about 2 years, requiring another fundraise before it runs out, so in H2 2023 perhaps? This is confirmed by the company, which says -
The financing we completed in the first half of 2021 has put the Company in a solid financial position with the ability to fund the Company well into 2023.
The clock is ticking then.
How does that compare with the timescale for possible regulatory approval? This seems to suggest late 2022 -
We spent the first quarter of 2022 finalising our NDA resubmission focusing on execution of near-term objectives. We announced on 20 April 2022 that the FDA had accepted the resubmission of the NDA as a complete response and has established a user fee goal date of 30 September 2022.
My opinion - none, as it’s way outside my area of expertise, even to guess at! Readers who know more about POLX are welcome to add more detail in the comments section, as always with all companies. My stuff is just a quick overview, so we like it when readers add to it.
I just wanted to inspect and report on the cash position more than anything.
Good luck to holders, I know a lot of shrewd investors who hold POLX shares, hence why I’m keeping an eye on it.
Obviously the stock market is now in bear mode for speculative, blue sky shares like this, so market risk:reward has dramatically deteriorated compared with this time last year, for example, when we were at peak euphoria for speculative shares. Although as mentioned above, POLX strikes me as one of the few credible blue sky companies, out of the many junk shares that get listed on AIM to gullible punters.
So maybe investors need to ponder whether the upside now justifies the increased risk of something else going wrong - e.g. being unable to refinance in 2023, possibly? So this is very much a binary bet! Good luck to holders, I hope it pays off for you.
.
.
Jack’s section
Keller (LON:KLR)
Share price: 785p (-1.38%)
Shares in issue: 72,770,781
Market cap: £571.3m
the world's largest geotechnical specialist contractor
A ‘mixed’ start to the year although expectations for the full year remain unchanged, despite a challenging environment, supported by a record order book of £1.4bn, and a foreign exchange tailwind.
Revenues are in line with expectations and Keller has passed on a ‘significant portion’ of cost increases in the form of higher prices, but performance has been affected by materials shortages and the residual effect of inflation.
We expect our full year performance to have the customary second half weighting, and to reflect our usual increase in trading momentum as the year progresses.
This H2 weighting does come across in previous interim results.

In North America, performance in the Foundations businesses has been hit by materials shortages, inflation, and ‘other operational challenges’ but all the other business units have performed well. A small bolt-on acquisition has been completed, GKM Consultants Inc, a geo-structural measurements and monitoring business based in Quebec, Canada. This goes into the Speciality Services business in the North America Division.
In Europe, the division is trading in line but there have been several deferred project starts, residual COVID-19 effects, supply shortages, and increased macroeconomic uncertainty. Keller has exited two peripheral geographies.
AMEA was the most impacted by COVID-19 in 2021 and has had a much stronger start to the current year, in line with expectations. Australia is recovering but the ASEAN business is still seeing lower market demand. The business environment in the Middle East and Africa remains challenging.
Diary date: interim results for the half year ending 26 June 2022 will be announced on 2 August 2022.
Conclusion
Keller may well compare favourably to its peers, but this is still a low margin, sprawling business, facing challenges in multiple markets.

It strikes me as well run and the valuation might be superficially attractive, but I’m also concerned about the group’s ability to handle the pressures it faces. The share price hasn’t done much over time and there’s not too much detail in this AGM statement, so not enough to convince me.

A good dividend track record though, with the forecast yield currently at just under 5%, so there’s something here for income seekers. Not to mention the strong StockRank of 95 of course.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
Please comment about Shoe Zone (LON:SHOE) results and return of dividends
Mello 2022 in Chiswick next Tuesday..... I have 17 FREE TICKETS to our Mello2022 Trusts and Funds event! We have great speakers & 23 Fund managers presenting
I've been looking at the situation with River and Mercantile (LON:RIV) and wondering if I'm missing anything.
They're due to return £2.20 to shareholders when Schroders complete the purchase of the solutions business. The rump of the business will then be acquired by Assetco (LON:ASTO) in an all share deal - 0.07392 AssetCo shares for 1 RIV share.
At the current AssetCo price that equates to £3.18 per RIV share compared to the current price of £2.59.
Obviously there's execution risk, but this is all expected to happen in the next month or so and a discount of 25% seems quite high for what looks like relatively low risk. Basically buy a RIV share for £2.59, get £2.20 back in a month or so and receive 0.07392 of an AssetCo share for 39p, as opposed to paying 99p in the market right now.
Unless I'm missing something?
Similar thing with RQIH where there's a 175p bid on the table and the shares are trading at 125p. More risk there of the buyer walking away, though, I think.
timarr
The market seems to think you're missing something, but I can't see what it is. I think there's money to be made there, but it's always worth estimating the potential downside. How would things look if the deal fell through? Fwiw, I think a fair price for River and Mercantile (LON:RIV) without the bid would be 200-250p, call it 225. But in the aftermath of the deal collapsing in the current environment, I can see the market price going to the 52w lows of 150p. If it did that though, that would present an opportunity to pick up a bargain, so it wouldn't be all bad news (e.g. a buyer now could use that opportunity to average their buy price to 225p, giving them a solid, albeit unplanned investment). So that's my guess at the downside. Put that together with odds of the deal completing at >=80% and I would agree with your assessment.
But in the aftermath of the deal collapsing in the current environment, I can see the market price going to the 52w lows of 150p
Granted, but the Schroders bid for the solutions business is done and dusted:
https://www.londonstockexchang...
So that was £230 million in the bank in February while the market cap of River and Mercantile (LON:RIV) right now is £222 million ...
timarr
Redde Northgate (LON:REDD) looking forward the key thig that concerns me about this share is that they made the decision to swap to Contract Hire for their fleet of vans. So any profit (or loss) on van sales going forwards will go to the leasing company. With used values being sky high at the moment, what percentage of their current profits are from the disposal of their owned fleet. I just think, once they have offloaded their fleet profits will drop considerably.
Paul,
If you have time, I'd welcome your views on the interims yesterday from Shoe Zone (LON:SHOE) as there may be read across to other low-price retailers in the current inflationary environment (Card Factory (LON:CARD) and Works co uk (LON:WRKS) for example). The figures looked pretty good to me and to other commentators in yesterday's SCVR but the market was unimpressed.
Thanks, Jack, for the Keller (LON:KLR) write up - glad to know the mixed impressions weren't hiding anything that greater experience than mine would find. I hold, and will continue to do so as I think that there is a need for their expertise. It's not a strong conviction, though, and your comments about low margins are useful. Fingers crossed that the challenges recede.
Science (LON:SAG) (I hold)
Thanks for the excellent overview Paul. I've been building a longterm stake in SAG for a couple of years now - I'd like to have bought more recently, but so many bargains and so little money to spend right now,
Good point on the cash position and trade creditors - might explain why they have been so keen to raise cash and take on the loan facility. I seem to remember that SAG's food and chemicals consultancy (their acquisition of the old Leatherhead food research centre) is a largely regulatory business with a lot of lab testing - from memory I think that long term customers tend to book and pay for lab time in advance - rather than miss their slot for mandatory testing. On a quick look I can't find any evidence for this (other than the mention of passing through regulatory payments in the US- but the cash for this is separately accounted not revenue) in the last accounts and don't have the time to go further back right now. - Anyway thats a long winded way of saying I don't think there is a high risk of this sudden;y unwinding completely - it's probably the business model - but never say never and thanks for the warning.
The TP Group takeover fascinates me. SAG has form on this. Not so much hostile but certinaly aggressive where it disagrees with shareholders opinions of value. Though that perception probably differs depending upon where you are looking from? Looks like TP Group is shaping up the same way.
f I remember rightly SAG bought in the open market at around 6 to 6.5p the level of their indicative offer. TP Group board refused to open the books and SAG had to walk away under the 'put up or shut up' 28 day rule which prevents buying above 30% or a lower offer within 6months (rather simplified). I do suspect that walking away might have been a part of the plan all along. suckered in the TP Group board and it's certainly turned over a lot of stones and exposed what was under them to the light.
SAG have not been quiet - they continued buying upto 28% at which point they had enough shares in concert with some of the large institutional holders to force the issue and requisition an EGM. That they stopped buying at this point - indicates that they did not want to buy more than they had to force the EGM. The old board totally underestimated SAG and walked or were fired. The SAG executive chairman and a SAG NED are now the executive chairman and director at TPGroup along with the original FD on a short leash and the CEO brought in to turn around TPGroup by the old board has now stepped down to become an NED - which indicates that this phase of his job is done and the SAG directors are keen to work with those who can deliver value..
Less of a failure than a work in progress I think. They are doing the same work that they would have had to do once TP Group had been acquired - might have been a bigger mess on their books at 100% of the company? It's conceivable that this is still going to plan as TP Group gets straightened out as an associate at 28% without being consolidated - kind of depends what the end game is I suppose.
Current state of play at TPGroup looks like a kitchen sink job, flogging off loss-making businesses and non-core businesses. Taking writedowns on old projects. I think it will be a shame if the European space and defence consultancy Sapienza goes - but needs must I suppose. The core will most likely turn out to be the UK software and consultancy businesses and the marine manufacturing business.
What happens then? I can't pretend to know what they plan - but I do think that they have a plan. I would not bet against SAG getting whats left (and what they want) for well below the 6.5p they originally paid - and I believe that they have done this before. Continuing to run it as a 28% associate company might work - but it looks like a holding position to me and won't really deliver the best outcome for SAG which would be to integrate the consultancy and software businesses. Acquiring will depend upon what value is left after the kitchen sink - and how quickly the institutions want to exit - or receive SAG shares?
In the meantime TP Group is short of cash and the short term future has been assured by a stand-by facility from.......yes you guessed it SAG (edit - just seen Roger's detail on this, sorry I missed it whilst I was writing this)
In the last accounts SAG wrote down their their original 12.7m to £10.3m then converted it to an associate once the SAG directors took over the board - and further wrote it down to around 9.3m if I remember rightly. Wuth TP Group trading around 2.5p right now SAG would have to right down another 4 or 5m. Which is not too large as to cause a problem? and will set them up well for the future? Whatever that turns out to be?
Should be an interesting next few months.
cheers
Mark
Another significant contract for Open Orphan Open Orphan (LON:ORPH) (I hold) this morning and the price is currently...... down slightly. How much does the market hate this stock? A quick tally of RNS figures suggests contract worth over £40m have been announced in the past year, never mind the smaller ones that don't warrant a release. Much too much puff and blow from their rather gassy chairman last year and the year before, but now they seem to have shut up a bit and are getting on with the job. Projected revenues of around £50m, (not including covid work from memory) enterprise value of £83m and moving into profit. Bread and butter today, and even a smear of jam. I guess every time the price rises a bit there is a wall of selling from folk well underwater who want to be in cash or value.
Thanks for highlighting this share. I agree it is an attractive price for a business with a lot of potential. I used to hold (usually for me, I sold at the right time) and what made me sell was that it seemed to have 3 businesses - Challenge studies, hVIVO and VENN - and I didn't see a lot of synergy between them. I like to see small companies more focused. I see they have a new CEO and they seem to be concentrating on Challenge studies. Could be time to buy back in, but I am wondering whether to wait for the 2021 results.
Thanks for the update on Science (LON:SAG) Paul. I hold, having bought at 85p 8 or 9 years ago using one of my most successful investment strategies (i.e. my daughter worked for them for her uni sandwich year and they seemed to know what they were doing)!
I note the TP offer was 6.5p only last Summer. Suspect they could get it a lot cheaper now, if they still want it.
I just spotted that TP (LON:TPG) has a credit facility, so far unused, from Science (LON:SAG)
The Facility is for up to £5 million for the period from the date of signing until 30 September 2023. The Facility, which is unsecured, includes an arrangement fee of 3%, interest rate on drawn amounts of 1% per month and a rate of 0.4% per month of any undrawn amount, both subject to Sterling Overnight Index Average (SONIA) remaining below 1%.
Paul,
' and this will also give me an opportunity to apologise in person for Boohoo (LON:BOO) performing so badly, which I know has cost many of us an arm & a leg unfortunately.'
I don't believe you should need to apologise for any shares performance, you have no crystal ball and only gave your opinion at the time, there were plenty of negative opinions at the time also. Any losses anyone incurred have to be owned by them alone.
Who knows Boohoo (LON:BOO) many provide a positive return over the long run.
BSV
Fully agree with that, I don't see anything to apologise about. It is imperative we do our own research and can't imagine anyone would invest in something simply because you liked it. From my own perspective, I was never keen on Boohoo (LON:BOO) for a variety of reasons and always stayed clear. On the other hand, you have highlighted many fantastic companies that I would otherwise never had heard of, and (after further research) have invested in several of these and done very well Vertu Motors (LON:VTU) and Redde Northgate (LON:REDD) being good examples from last year.
I remember Paul covering it at 32p and it has returned a lot since then.
There's too much self pity and entitlement around investing. The risk we all take take when we invest in anything is a luxury that many people in the world don't have.
Blimey! Thanks BV, appreciated :-)
Hear hear!!
Totally agree, no apology needed..ever.
Advice is just that, its my money and my risk alone.
Paul,
Your links to the Mello schedules are wrong. The Day Two link is OK but the Day One link is broken and the Day Three link dowloads the Day 2 link again.
Thanks FREng.
Mello days 1 & 2 links are fine, but day 3 was wrong, so I've corrected that now.
Thanks v much for flagging, most helpful! :-)
Best wishes, Paul.
Good Morning Paul / Jack, Will either of you be looking at Premier Foods (LON:PFD) (Premier Foods) , although guess it may fall outside the your Mkt Cap limit size. Would be interesting to hear your thoughts as Premier has been a serial underperformer for a number of years but seems to have finally turned the corner although how they are impacted by the current inflationary environment remains to be seen.
Hi COYS61,
Yes, Premier Foods (LON:PFD) is above our upper limit now, and we've got such a long list of backlog small cap companies to look at, I doubt we'll find time to cover PFD. But by all means post some more thoughts on it, and it might get me interested!
Regards, Paul.
Morning Paul and Jack, any thoughts on Brown (N), BWNG? I think you may have looked at it in the past. Thanks.
Hi Galois
N Brown (LON:BWNG) Looks like a very interesting valuation see graph below.
I've taken a small position hoping for a £1 share price by year-end.
As always DYOR
BSV
Sales growth and potential valuation.
Cheers BSV - i do like your graphs.
Morning galois,
Re N Brown (LON:BWNG) - I've very much gone off this share, following the collapse of Studio Retail, which had a similar model - selling stuff online in order to generate profitable business for its high risk/high cost credit finance offerings.
STU turned out to be a can of worms, and was allowed to go bust by major shareholders who refused to refinance it and then bought it for £1. It seems obvious now that there must have been false accounting going on at STU. That's the trouble with a huge consumer receivables book - all sorts of horrors can be easily hidden in it.
For that reason, and a large/complex legal claim ongoing with BWNG, personally I wouldn't want to go near BWNG, at any price really. It also has a controlling shareholder, who might take it private maybe? If that can be done for £1 in a pre-pack administration, then why not do that? It might also extinguish legacy liabilities with the legal case, and wipe out minority shareholders.
So BWNG looks far too high risk for me, given my very close shave with STU - thankfully I spotted the warning signs there, and explained here why I had lost confidence in STU mgt and had decided to sell. It went bust just 2 weeks later - way too close for comfort, so I would never invest again in this hybrid business model of retail/high cost credit. That excludes BWNG too.
Sorry about that.
Regards, Paul.
Relieved N Brown (LON:BWNG) is not a conviction hold for you.
regards,
BSV
Mean reversion!
This response has tickled me :)
Sorry Rev8, I meant Amazon. Not enough coffee this morning. Should not have gone to Paul's watering hole last night
Hi Goronwy. Yes I had heard this report and I can understand why it might be a while before shares hit 600p again.
I personally can't see construction grinding to a halt and demand for higher tolerance floors should become the norm which will drive contractors towards Somero Enterprises (LON:SOM) equipment. Somero Enterprises (LON:SOM) might not be able to continue its stellar growth but the shares are already priced at a PE of less than 8. Somero Enterprises (LON:SOM) have a good order book and no debt so I'm working on the basis they have been oversold. It will be interesting to hear their next update.
I should have added: They sell in Dollars so their profits will be boosted when quoted in pounds sterling. A hedge against the falling pound.
Hi Revs 8 I have a large interest in Somero. The only problem I see is that Amerson ? have too much floor space and if a recession come, it could hit Som hard
I am also a Somero Enterprises (LON:SOM) shareholder. The one counterpoint would be that the company is still buying back shares. I believe that if they had seen a downturn in their business they would have paused the buyback. Admittedly this is assuming they have the ability and the nouse to do so!
Marston's (LON:MARS)
I am long suffering holder here , todays update seems to be more than half full (in tone) which is a slight surprise with current cost inflation worries and their eelephant in the room. I note Mitchell and Butlers update not so great based on brief headlin esummary i have read for that company so i wouldnt really see any read across here that things are on the up due to the fact they are more chipper than not at martsons. When i say chipper thats really from a level of very low expectations so probably more a brave smiling face - with current tough times + the £1billion plus of debt (the elephant) aligned with reduced profits aligned with fact they sold half their brewing buisness over covid aligned with increasing interest rates means the outlook here is somewhat bleak. Behind the scenes though this company has a decent business however with huge debt + rising interest rates and cost worries its probably not a share anyone should have much enthusiasm for at present.
rmillaree - Re Marston's (LON:MARS) - I too was surprised by the 'chipper' tone in the face of a coming cost-of-living storm.
Given that storm, I note also their plan to row away from 2-for-1 deals and the price driven 'value' sector. Great if they can do it, perhaps using the historic pull of the pub ( esp. vs restaurants/delivery) to attract more older consumers who mostly are still in good financial shape. But clearly a risk.
(The younger set who are more diverse, drink less and do not have such a pub-social culture are being absolutely clobbered by NI/energy/rent/graduate loan repayments (=9% marginal tax on income over £26K/yr). They won't have much money for the next couple of years; the very poorest, of course, never had much money for a Marstons style food & drink pub anyway. )
I also noted Marstons statent intent to 'refresh' pubs more frequently - so more CAPEX, but supportive of a slight trading up and 'better than the rest' strategy ie it seems to hang together as a plan. Let's hope it works.
On the positive side, Marstons are also still getting property away for above book value - re-assuring when the price :TNAV is only 1.07 on Stocko ie the business is almost for free, with the debt manageable.
The worry of course is that interest rates climb, property prices fall.....and then they are in trouble. Absent this, with a correct continued focus on debt reduction (so no dividends), I think Marstons will be a surprisingly solid performer this year. (I hold - wearily.)
I was fortunate enough to buy in April 2020 as a recovery play (one of the very few so far decent decisions I have made) and so I can afford to be a little more patient here.
At the time my thinking was that the panic sell-off was overdone, and although I expected the industry to take a massive battering during Covid, I expected larger operators to be able to weather the storm a bit more easily and then potentially pick up under valued pub chains or individual pub businesses that were forced to sell.
To an extent this started to play out when the bought SA Brain, so I was pleased with that.
I still think that long term this is a likely scenario but that long term will be during a period of reduced discretionary spend in the economy in general.
Currently it's one of my few green numbers, hoping for it to stay that way.
Hi Paul. Good point about the dollar strength.
However, it’s good news for companies that generate sales in dollars, but report in sterling. So it’s worth having a think about which companies in our portfolios might benefit from, or be damaged by, this change in exchange rates.
Somero Enterprises (LON:SOM) I noticed my dividend payment was boosted by the good exchange rate. I assume that all of Somero Enterprises (LON:SOM) sales are in dollars. Makes the recent SP drop even more puzzling. I have been buying the dip as I don’t believe Somero Enterprises (LON:SOM) sales are about to drop off a cliff. If they can maintain their dividend then I don’t really care what the share price does.
Looking through my portfolio, some interesting non GBP plays could be:
Rio Tinto (LON:RIO)
Spectra Systems (LON:SPSY)
Intercede (LON:IGP)
Where predominantly the revenues are in non-GBP. And in the case of Intercede, the costs are GBP so the full benefit of a weak pound will come through.
I sold a few months ago worrying that the potential for a US recession would be seriously bad news for a supplier of capital goods to the building industry.
Its a great company I hope to repurchase at some point.
Redde Northgate (LON:REDD)
Very solid year end trading update confirming trading is still strong. Numbers in line with mid March upgraded expectations for year just finished.
Ref year just started they expect further progress , so that seems positive when you factor in that the numbers per stocky were flagging up expected very minor dip in earnings. It’s reasonably clear they have massively benefited from tight vehicle supply issues - so the unknown here is when and how much we should expect these tailwinds to vanish and what the result will be ref earnings when normality returns - jury still seems firmly out as to how sustainable current profits are , in the meantime I am just enjoying the strong numbers knowing that valuation would still be reasonable if profits dipped 25% - management seem to be running nice tight ship here too - so seem safe pair of hands to me.
As well as the value on offer here, another potential share price catalyst for Redde Northgate (LON:REDD) is in their last update they said they were interested in mergers and acquisitions. Last year there were also rumours in the Daily Mail that a company had shown interest in Redde Northgate (LON:REDD) as a potential takeover - maybe interest will resurface at the current share price levels?
The company helpfully publishes analyst consensus figures on their website, which are available here: https://reddenorthgate.co.uk/i...
This page was last updated in March when they noted the mean consensus for FY23 is 46.8p underlying EPS putting these shares on a lowly 8x price-earnings.
Good morning Paul and Jack, I'd appreciate comments on Ninety One's results if you get chance today (we hold). Apart from the warning about investment conditions worsening (tell us about it!) the results look good to me on EPS, profits and dividend so as with several others I'm tempted to top up.
Morning JASVFS! Sorry Ninety One (LON:N91) is way too big, at £2.3bn market cap. We normally stop at around £700m, unless it's something interesting that we know well - e.g. retailers & eCommerce, is a sector I usually have something to say about.
The idea generally with these small caps reports, is to shine a light on smaller companies where coverage from the City is so limited. Mid & larger caps usually get plenty of coverage elsewhere.
Sorry about that.
Regards, Paul.