Small Cap Value Report (Wed 19 June 2024) - SFR, AVG. Brief: BKG, GAW, RQIH, AFM

Good morning from Paul (now back in the UK after a wonderful trip to Washington DC - a fantastic place to visit, highly recommended!). Graham's having a well deserved holiday.
I've added some extra links below, at the bottom of the explanatory notes (that nobody ever reads lol!), as I noticed that there were several requests for those links. This way they're available in every report from now on.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
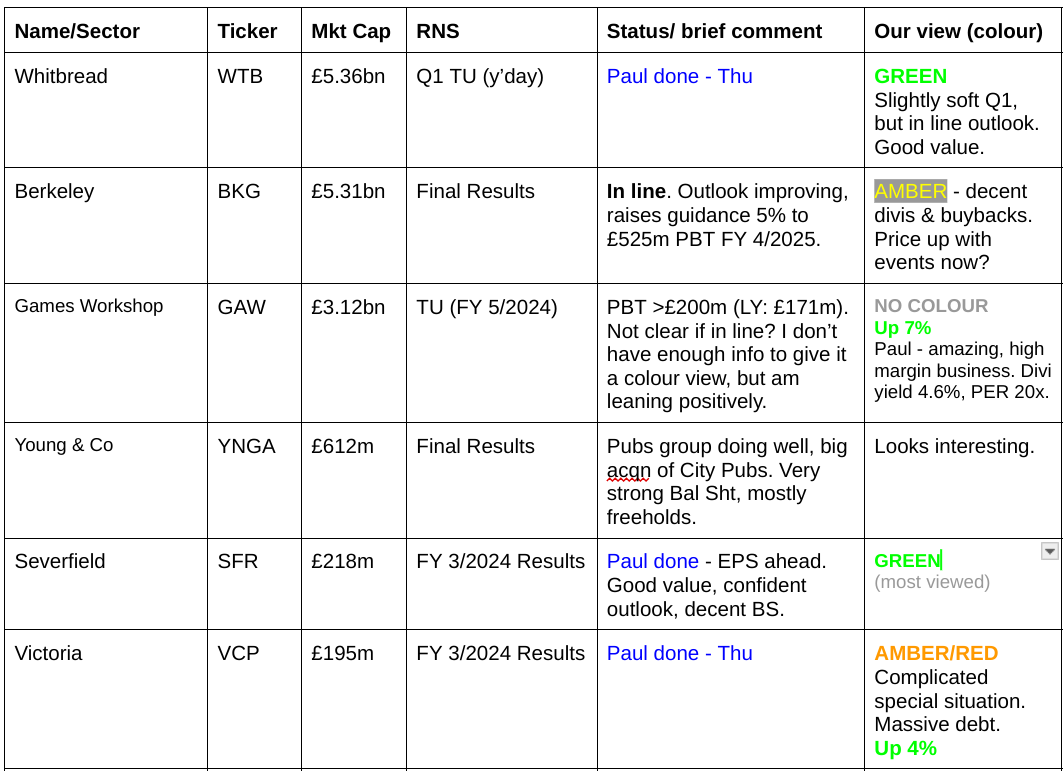
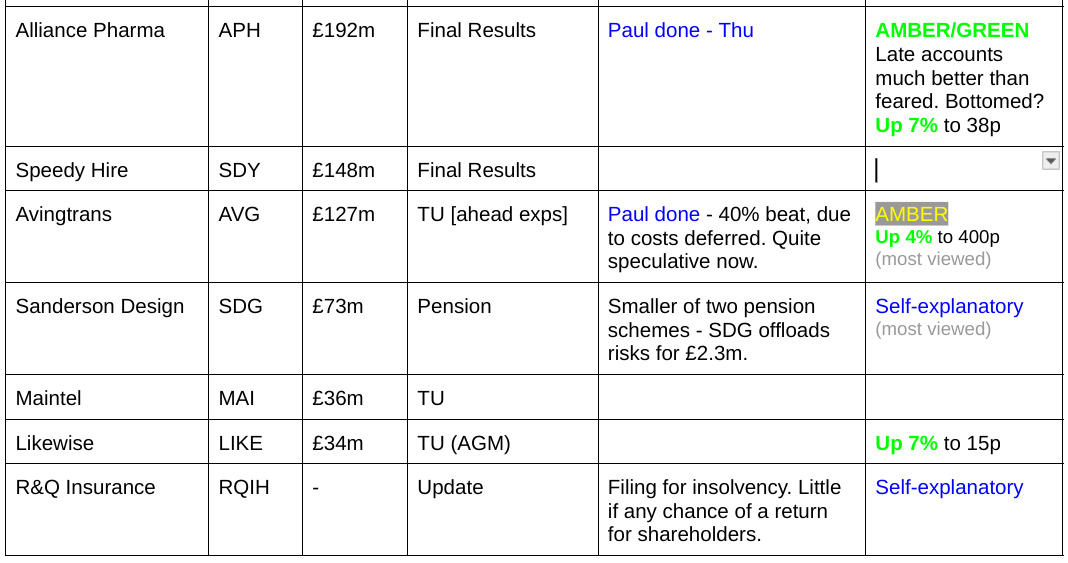
Companies Reporting
Other mid-morning movers (with news)
Alpha Financial Markets Consulting (LON:AFM) - up 21% to 475p (£541m) - Indicative Offer - Paul - PINK (takeover)
AFM is a specialist consulting/staffing company. It previously announced on 1/5/2024 that private equity giants Bridgepoint and Cinven were both considering making offers for AFM. This caused a vertical move up in share price, which had been withering away somewhat in May & June. Today we get another vertical move up to 475p, on fresh news that Bridgepoint has tabled an indicative bid (ie not yet a formal bid) as follows -
Type - indicative bid (not yet a formal proposal, but nearly there)
Bidder - Bridgepoint (private equity)
Price - 505p cash
Premium - 29% to last night’s close. 51% to the undisturbed price before 1/5/2024.
Recommended? - AFM says its independent Directors would unanimously recommend this bid if it becomes formal.
Status? - “advanced” stage of finalising discussions and documentation.
Shareholders support? - not known at this stage.
Paul’s view - this price looks fair to me. By my calculations the 505p bid is a PER of 21.9x forecast FY 3/2024 earnings, and 20.0x forecast FY 3/2025. That seems a decent exit valuation. There’s little in the way of tangible asset backing in AFM’s accounts. The bid is just above previous highs for AFM shares.
Overall AFM has been a successful investment for shareholders, floating in late 2017, with an exit now at about 3x the original price, plus a stream of divis received in between. It’s a pity to see another decent quality growth company leave the London market, but I can’t argue with the price being offered, which is 50% higher than the stock market was valuing it at before 1/5/2024 announcement of bid talks.
Summaries
Severfield (LON:SFR) - down 1% to 71.5p (£219m) - Results FY 3/2024 - Paul - GREEN
I'm surprised at how positively the FY 3/2024 results come across. I think there could be quite nice upside on this, which is looking a decent GARP share. The PER of 8 looks too low, and you get a c.5% yield, which is easily affordable, plus buybacks on top. Well worth considering, for value/GARP investors to research in more depth.
Avingtrans (LON:AVG) - Up 4% to 400p (£132m) - Trading Update FY 5/2024 [ahead exps] - Paul - AMBER
EBITDA guidance for FY 5/2024 is significantly raised (c.40%), but due to deferring some costs into next year. Despite this I'm perturbed by the strongly downward trend in forecast earnings, which makes AVG difficult to value. It's more speculative than I realised, with the valuation hinging considerably on the outcome for 2 new medical products in development. Might be suited to a sum of the parts type of valuation. Too difficult for me to assess, so I moved down to don't know, AMBER.
Paul’s Section:
Severfield (LON:SFR)
Down 1% to 71.5p (£219m) - Results FY 3/2024 - Paul - GREEN
Severfield plc, the market leading structural steel group, announces its results for the year ended 30 March 2024.
A strong headline, but so far (at 08:36) it hasn’t done anything for the share price -
Profits ahead of expectations, strong order books, further strategic progress in Europe
Revenue down, but profit measures up, so this is a case of margin improvement, which I find impressive given tough macro -
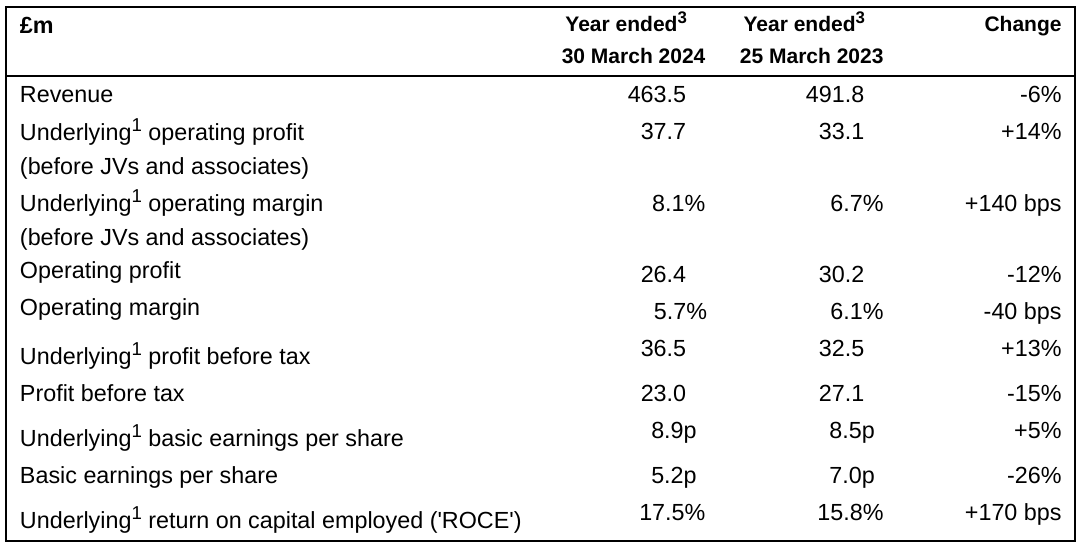
The 8.9p EPS is a PER of 8.0x at 71.5p/share.
Dividends are good, with a strong statement here -
Total dividend increased by 9% to 3.7p per share (2023: 3.4p per share), includes proposed final dividend of 2.3p per share (2023: 2.1p per share) - ten consecutive years of progressive dividends
That gives us a (now historic) yield of a healthy 5.2%.
Note also a £10m share buyback began in April 2024, which is about 5% of the market cap.
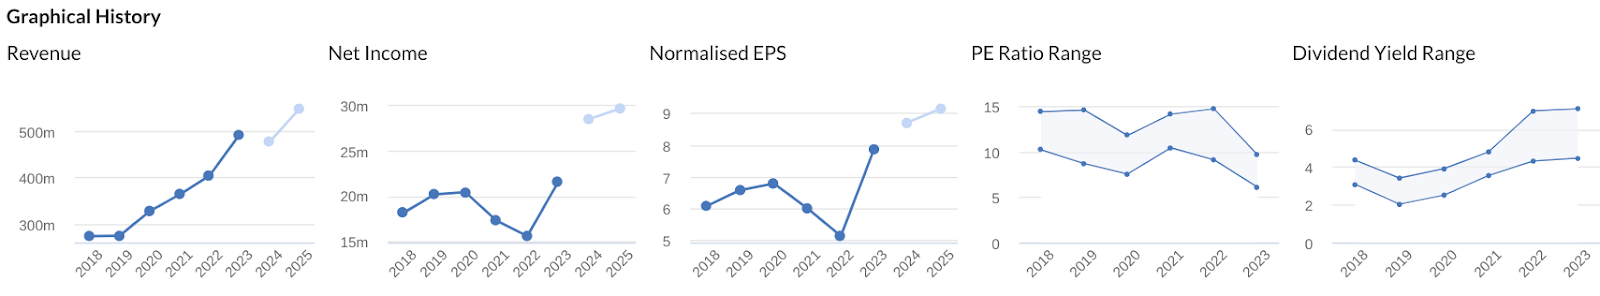
Graph 5 below shows that the dividend yield has been rising, and is a good reason to buy this share, alongside good trends in all the graphs - performance improving, but PER going down, is a good combination -
Order book - hasn’t changed much, and is c.1 years revenues - so decent visibility -
High-quality, diversified UK and Europe order book of £478m at 1 June 2024 (1 November 2023: £482m), includes higher proportion of European orders
Encouraging points above. The key line says -
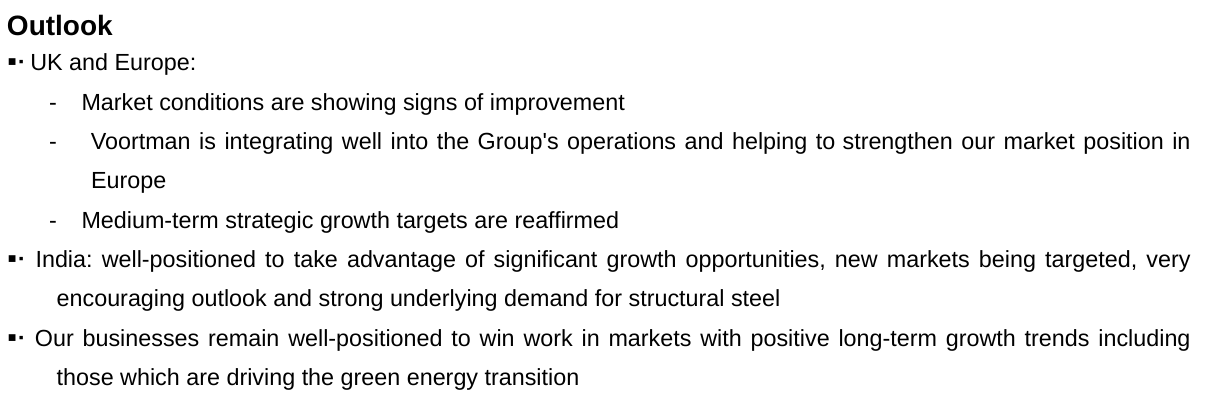
“On track to deliver a result for 2025 which is in line with our expectations”
CEO comments are also positive, including -
“Looking ahead, we have strong order books in the UK, Europe and India which are providing us with good earnings visibility through 2025 and beyond. With market conditions showing signs of improvement and with our businesses well-placed in markets that are expected to benefit from positive long term growth trends, which are unlikely to be impacted by the result of the upcoming UK general election, we are confident in the outlook for the business."
A new note from Progressive shows a slight increase to 9.2p EPS for FY 3/2025. A combination of modestly set forecasts, an upbeat outlook commentary, improving macro, plus an acquisition, suggests to me there’s a good chance it might beat forecasts in FY 3/2025.
Balance sheet - looks healthy to me. NAV £221m, less intangible assets of £104m (mainly goodwill on previous acquisitions), gives NTAV of £117m. That’s just over half the market cap, so there’s reasonably good asset backing here.
Note there’s a small pension deficit of £11.5m. There’s little in net debt, at only £9.4m (excl leases). For a business that’s reporting adj EPS of nearly £37m, that bank debt is insignificant, and there’s scope to take on a little more, eg for acquisitions, in my view.
The Indian JV is accounted for like an associate, with its net assets shown as a single line on the balance sheet, of £37m. On the P&L, SFR’s share of the profits of £2m is shown as a single line. The Indian operation looks quite interesting actually, with good growth, and upbeat outlook. It has bought some land to expand, but note it seems highly geared, with half the operating profit being consumed in finance charges.
Overall, it gets a thumbs up from me for a healthy balance sheet.
Cashflow statement - healthy cash generation of £45m was mostly spent on capex of £11m, and acquisitions & investment in the JV totalling £25m.
Dividends and share buybacks total £14m, which arguably have been financed through increased debt (up by £11m). But that’s fine, as debt is negligible.
Overall, it looks a healthy, cash generative business to me, both this year and last.
Paul’s opinion - on a quick review, I’ve seen enough to be comfortable giving SFR a thumbs up, continuing Graham’s positive view last time, so we’re both GREEN.
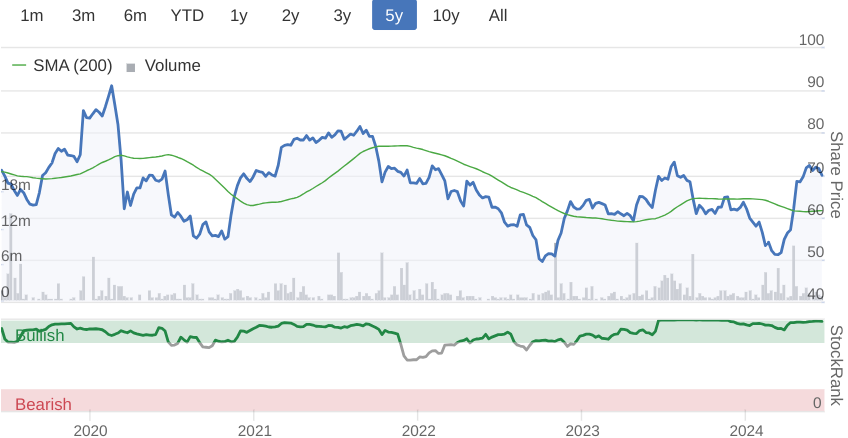
Previously we’ve been worried about macro risks, but I don’t see that as a problem any more, given the positive outlook comments and slowly improving macro in the UK and elsewhere. India could grow into a decent part of the business too.
You get this for a PER of 8x, and whilst you wait you’ll get paid a dividend yield of just over 5%. Plus it’s buying back shares too, thus enhancing EPS and the yield. I like buybacks in situations like this - when the shares are cheap, and the balance sheet robust enough to make it easily affordable.
This share probably won’t be a multibagger, but I think it’s a good business, with a decent operating margin, at a very reasonable price. Yes, I’m keen on this share actually, it ticks all my value investor boxes, and it could be seen as a GARP share. There should be decent long-term upside, and maybe even a short-medium term profit of say 25% if it re-rates from a PER of 8 to something more appropriate of 10. Even that would still be quite cheap. So I reckon with a bit of patience, and providing nothing goes wrong, you could see 100p+ out of this share.
Avingtrans (LON:AVG)
Up 4% to 400p (£132m) - Trading Update FY 5/2024 [ahead exps] - Paul - AMBER
Avingtrans PLC (AIM: AVG), which designs, manufactures and supplies critical components, modules, systems and associated services to the energy, medical and industrial sectors, announces a positive trading update in respect of the financial year ended 31 May 2024.
I’ve loosely followed Avingtrans for many years, and my impression is that management are active in buying & selling companies, trying to add value in between. Management seem highly regarded.
Shares have done well over the last 20 years, as you can see below, tending to do good bull runs, then trade sideways for several years after each one -
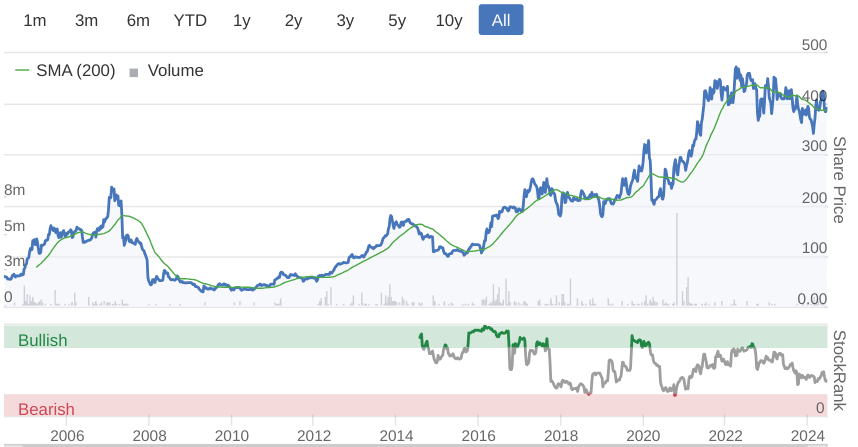
We’re due a fresh look, as last time I reviewed it here was 13/7/2023, on an in line trading update for FY 5/2023, and news of an acquisition, strong order book and confident outlook. I concluded that it wasn’t a bargain at 425p, but a high valuation was justified given the decent long-term track record. Almost a year later, the share price is about 6% lower at 400p. The published spread looks wide, 390/410p, although as I’m sure you know, the actual trades are usually within the quoted spread, but it’s fairly thinly traded most days, hence more a share to buy & hold, rather than trade in & out of.
Today it says for FY 5/2024 -
Revenue in line exps (no figure given).
EBITDA - note that this is not a reliable profit measure, being way higher than adj PBT -
“Adjusted EBITDA from continuing operations is materially ahead of market expectations* and is expected to be in the range of £13-14m
*Prior to today's announcement, the Company understands that market expectations were: Adjusted EBITDA of £10.0m and Net Debt (exc. IFRS 16) of £7.1m”
That’s a 30-40% beat at EBITDA level. Shares have not reacted much to this beat, perhaps because some (not stated how much) costs have just been deferred into the following year, which is obviously not a very good reason for beating profit expectations.
Net debt is £1m below expectations, at £6.1m, which is neither here nor there really.
Engineering division commentary sounds positive, with acquisitions doing well.
Imaging division - mixed comments, including FDA delay and slower sales build up for new products. This bit has interesting positive read-across for cybersecurity companies -
“the increased cyber security scrutiny required by the FDA in the USA has required additional time and effort.”
Outlook - vague, but says they’re confident.
The trouble is, deferring costs from FY 5/2024 into FY 5/2025 flatters the results for FY 5/2024, but now means a growth headwind trying to beat those increased profits in FY 5/2025.
Broker updates - thanks to both Cavendish and Singer for putting out helpful updates today. Looking at Cavendish, it raised adj EBITDA to nearly the top of the new guided range, at £13.9m. This becomes a lot lower figure, adj PBT of £7.0m, well below the last 3 years’ despite a big forecast increase today. That’s forecast to halve to only £3.5m adj PBT next year, FY 5/2025, making the £132m mkt cap look considerably stretched on a conventional valuation basis.
In EPS terms, we have 15.4p almost actual for FY 5/2024, and only 6.0p forecast for FY 5/2025. Hence at 400p the share price is showing a sky-high PER, and on earnings trending significantly downwards. So bulls have to be very comfortable that these forecasts are significantly too cautious, otherwise you’re heading for trouble.
Reading through more of the commentary, this share seems to mainly hinge on new product launches, so it’s a lot more speculative than I previously thought. Forming an informed view on the prospects for new products looks to be the key thing to research further here.
Balance sheet - I’ve had a quick look at the last reported balance sheet at 30 Nov 2023, and it looks strong. My only reservation is that receivables seem much too high, so I suggest that needs to be part of your deeper research to find out why. If anyone already knows why, please do leave a comment below.
Paul’s opinion - this share is more speculative than I realised. I think the best way to value it would be on a sum of the parts basis, assessing each subsidiary as a separate entity, as it sounds like there could be parts of the business that are profitable, and other bits that are not, or are spending a lot on development projects anyway. If those work, they could be valuable, but it’s beyond the scope of these reports to delve into the new products and try to assess (or rather guess) how they might work out.
Overall then, I’m moving down from green to AMBER, as I don’t like the way profitability is set to drop sharply according to broker forecasts, and I have no way of knowing if the new products will be good or not. Maybe it’s best to see AVG as a combination of some existing profitable companies, with some blue sky stuff added on, and value those two parts of the group separately, rather than on a PER basis for the combination? Cavendish flags its MRI and 3D X-ray new products as having potential upside, if they sell well.
It doesn’t interest me at this stage, but good luck to holders. Management have done a good job in the past, so that’s always a good starting point.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
Argentex (LON:AGFX) I'd watch the presentation first David, cash looks like a red herring. The body language when talking about debt/cash was pretty awful I thought.
Wolfie
100% with you on comments regarding Argentex (LON:AGFX)
This will end up in tears imo unless a much bigger fundraise (around £20m) is successfully completed ASAP ; something that I find very difficult to be achieved.
I believe that current shareholdings will end up worthless and is something that can easily be spotted. Cash headroom has fallen from £30m to just £2m
in 3 years! This figure has fallen £5m only in a couple of months and this was the reason
for the sudden fundraise.
All the best
Agree Yiannos the cash headroom deteriorating so quickly is a major red flag. They say Alternative Transaction Banking will require significant investment over the next two years, so I think like you they'll be back with the begging bowl.
Hi Wolf without hopefully coming over as thick any way one can spot this easily on a stocko stock report ?
Argentex (LON:AGFX) still being punished after yesterday's investmeet presentation.Shorts firmly in control.They've now commited to more regular market updates.Here's hoping they can turn things around more like Frontier Developments (LON:FDEV) now in terms of more regular market updates/communiation and demonstrating that the updated strategy is graudally starting to work out, even if the figures might take a little longer to come through.A previous joke about Argentex (LON:AGFX) 's mcap meeting Finseta (LON:FIN) 's on the way down could still potentially play out!All to play for!
Intriguing on Argentex (LON:AGFX) - trading not much higher than its own net cash
Given new management might end up a multi bagger from here - need to have a look properly and watch the IMC and see if I want to buy some for the longer term.
The majority of balance sheet cash is needed for regulatory liquidty/margin call reasons!Worth a watch still possibly!To be honest i wasn't too impressed but went against my own ideas and 'averaged down' from 50p too soon.I didn't realise their website looks, from a brief view, similar to stocko's (which i assume is a template).No offense to stocko.I think they have the clients and history and it seems including some bigger names but they really need to up the tech.Low volatililty in the US markets due to Nasdaq seems to have destroyed their forward hedging business, which has the larger margin over spot. Finseta (LON:FIN) i'm not too sure where their main business comes from, but i think it's less hedging and more private, high net worth clients.Although could be totally wrong!I sold out of there (and only bought due to ahead of trading RNS s) and kept the Argentex (LON:AGFX) hedge on foolishly, as i believed them as the more established player..
Neobanks are a risk still to business and margins, but large banks which own the majority of the business still.. i can't see any reason for them competing on price soon, unless they start worrying about the neobanks too much like Monzo and Revolut.
No idea how much the whole tech reboot will end up costing the be honest......Overall not too surprised it sold off at the moment.
There was a late RNS from my favourite share Resolute Mining (LON:RSG) stating they had received AUD 30m from a previous mine sold in 2020 with another AUS20m in September. Then up to another AUD 150m to come in the next two years. This is really good news for RSG as it increases it's cash position and makes it's EV even more positive. The lightly hood of dividends re-instated soon has increased too. I can see the cash position of RSG at the end of the year being a third of the current company market cap of £600m.
Technically it is looking good too, with a recent pull back from the last highs, bouncing off support and the 50MA.
As a client of Hargreaves Lansdown (LON:HL.) for over 20 years it looks like the increased bid has got the approval of the major founding shareholders.
I seem to recall it was floated at 160p around 2006 and for many years was one of my best performers.Deadline extended to 19 July.
The co-founder was interviewed on this morning's Today program (about 7.10 am). He wasn't very forthcoming when asked if the bidders had addressed concerns that he had raised earlier in the process.
Hargreaves Lansdown is currently refunding upto £100 of trading fees this and last month up to June 21 too.Strategy change somewhat as they never used to do 'discounts'?Shame i'm not trading much at the mo.Good luck to shareholders.I watched an interesting Paul Hill interview with Leon Boros who had invested in Hargreaves at the lows.Wonder what he's going to do with the profits now?
Hargreaves Lansdown (LON:HL.) I see this as another opportunistic bid for a good quality company, which again simply lowers the number of long-term investment opportunities on the UK market. Even with the bid premium, the price is at 2015 levels and not much more than 50% of the 2020 highs. It's an absolute cash cow with very high margins and it's a shame the vultures at CVC have got their hooks into it. As a client of HL I won't expect to see much in the way of product development under their ownership.
Alpha Financial Markets Consulting (LON:AFM) announcement out bid at 505p. Some peeps at Sky insider dealing this morning?. And the seller of those 20k chunks down nearly 100k as a consequence
Alpha Financial Markets Consulting (LON:AFM) a very leaky ship. Now trading up at 473
Alpha Financial Markets Consulting (LON:AFM) some weird price movements here. Seller of chunks at below the stated market bid price half an hour ago. I was offered 20,000 shares at 379 when the bid price was 380 and couldn't even sell 500 shares. Now bid 460 for the same 20,000 shares.
Someone knows something about tomorrow's results and PUSU deadline
Thanks for all your efforts and it would be great if you find the time to cover Speedy Hire today.
I also took a copy of Philip's analysis of the colour coding system - I thought it was interesting how many were ranked and the current percentage positive:
There's always a few forgotten...
Once again, I have to refer you to our Explanatory Notes - especially this section, which you don't seem to have read or understood -
"We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! ..."
Just ignore him Paul. Some people are always looking for reasons to be dissatisfied. The rest of us feel really lucky to have you providing so much great analysis on a daily basis.
Ignore him Paul.
He's just a broken record. Not worth giving him the oxygen of publicity.
You say you can't cover everything but I must say, you give it a bloody good go! I've only been investing for a few years but your small cap reports have been a massively helpful entry point.
A very interesting table. Can you give some more details about this.
Severfield (LON:SFR) Thanks Paul for your write up today - Agree with your anaylsis - a GARP share indeed! Just so frustrating that for the many years Ive held this share - have not actually made anything to talk about - yet the company ticks all the boxes and with so much infrastructure work on the horizon will hopefully loose its GARP status and become the Super Stock that stocko already has marked in green!
Sanderson Design (LON:SDG) not an expert on pension liabilities but £2.3 million seem an awful lot given their total pension deficit was last reported as £0.9m. Important to note that they are only transferring out the smaller of their schemes so this implies a payment several multiples of their accounting deficit - worth bearing this in mind when weighing up the cost of transferring these out. To make matters worse they still seem to be on the hook for £700k pa to cover admin expenses - this is a not insignificant portion of their overall profits (and to repeat we still have the other larger scheme in place).
Perhaps we should invest in insurance companies instead, as they will surely be making very good returns on these sort of numbers. Legal & General (LON:LGEN) looking tempting after recent sell-off.
Morning - as Rhodie Jonners notes in a reply further down, the £700k admin expenses is a total amount (to be paid over the life of the scheme) rather than an annual payment.
Hi Bouden54,
As RJ mentioned earlier I believe the £700k is the total payment for the life of the scheme not an annual payment.
SDG
That does look a staggeringly bad deal
Mmmmm
Must either be missing something , not clever enough to understand , or actually a staggeringly bad deal .
confused.com
Not sure if helpful, but this document published by the Pensions Regulator may help explain some of the differences in how scheme liabilities can be valued for different purposes. https://www.thepensionsregulat... see page 6 for a quick overview.
Effectively buying-out with an insurer is likely to require additional funding even if 100% funded on an accounting valuation and the basis contributions are valued at. This document looks to be a few years old and I know there’s been some talk about the differences in assumptions used converging between the different valuation methods - but it might at least shed some light on why additional funding was required from Sanderson Design (LON:SDG)
I think it’s worth noting that the calculation to arrive at the deficit figure of £0.9 million, is based on the very high interest rates and gilt yield that currently existing. I think the transfer of risk is probably very well timed because as interest rates and gilt yields reduce significantly over the next year or two, the actuarial consequence will result in a higher deficit, perhaps significantly so. I’m not saying it’s a bargain, but I don’t see it as expensive either and it provides certainty that the company cannot be forced to lob in huge sums into this scheme in future. All in all, probably a good deal. (I hold)
I am thinking macro over the last month which I know isn't as interesting as stock selection but it can have a significant impact on ones wealth. I posted in early June "we have missed our chance to sell in May and go away" or something similar. It received a response along the lines that is an anachronistic rule, which initially I didn't disagree with. It existed because City guys would go on holiday for 3 months over summer and therefore volumes would drop. Technology has of course diminished this effect. However this year is year politic and I know we don't like to talk politics. But with so many elections taking place including the key to Capitalism in the US I have decided to take an unusually liquid position. Yet another cliche "the market doesn't like uncertainty" must surely come home to roost at some point. If anyone has read Project 2025 it does represent an inflexion point in the West. Coupled with Trumps meeting with a group of CEOs last week and them leaving saying he hadn't got a clue. I think there is in the West a meeting of two very different political views and I am not clever enough to identify who is going to win, but I can tell you Project 2025 is not good for the US and ergo Western Capitalism. If that doesn't represent uncertainty I don't what does. As always make up your own mind. https://www.heritage.org/conse...
As expected the Government claims the credit for the fall in inflation; somewhat disingenuous to say the least, in my opinion.
In terms of financial acumen, the two Steves at Avingtrans (LON:AVG) or Simon Wolfson at Next (LON:NXT) would get my vote to run the treasury
thanks Paul for the broker upgrades video
Games Workshop (LON:GAW)
Core revenue to be not less than £490 million (2022/23: £445 million) and licensing income of £30 million (2022/23: £25 million).
PBT estimated to be not less than £200 million (2022/23: £171 million).
Looks like a decent beat according to Stocko figures. Revenue is now double pre-Covid levels.
My fear used to be that they would reach saturation point but I believe this continued growth is due to expansion into foreign markets, especially the focus on US sales. The runway therefore could be much longer than people think.
Also looking to expand production according to the Nottingham Post https://www.nottinghampost.com...
Summer job cuts as minimum wage bites
Hiring for seasonal summer jobs has fallen sharply as employers grapple with rising wage costs
"Data from the Recruitment and Employment Confederation, an industry body, shows job postings for temporary summer jobs have fallen sharply in the hotel, restaurant, tourism and construction sectors in April and May, compared with the same months last year after a climb in the minimum wage."
https://archive.ph/Fku6T
Avingtrans (LON:AVG)
I am with planetX.
The two Steves , McQuillan (CEO) and King (CFO) are a first class management team and and excellent at identifying acquisitions and buying well, Slack & Parr being the latest example. Sooner or later, when the time and price are right they will sell one of the companies, Booths Industries being the that which is touted as most likely.
The medical division, comprising Adaptix and Magnetica is the cherry on the cake and is currently not profit making. There will always be bumps in the road with new technology, but progress is being made and the management team would not have invested in the business if they did not believe they could bring it to commercialisation.
Young & Co's Brewery (LON:YNGA) and Young & Co's Brewery (LON:YNGN)
I hold the non-voting shares, it is my smallest position and I am happy to remain invested.
In my view Youngs and Fullers are the pick of the pub operators. Youngs has splashed the cash with the recent acquisition of the City Pub Group, the benefits of which are still to come through, hence the apparently disconcerting net debt to adjusted EBITDA figure. This is expected to to normalise as the integration of the City Pub Group progresses.
"It is also expected that the net debt to adjusted EBITDA ratio will fall back to more historical levels by the end of FY25 once a full year of the additional EBITDA from the City Pub Group acquisition is included."
Also the company has had to contend with a higher tax charge.
"A tax charge of £9.6 million (2023: £6.5 million) was recognised for the year. The effective tax rate was 46.6% (2023: 18.0%) compared to the statutory rate of 25%, with the difference primarily driven by adjusting items not deductible for tax purposes. Further detail can be found in note 6."
Any thoughts from Paul/Graham, time permitting would be appreciated.
All the best
I noted that Berkeley group (LON:BKG) also made reference to the increase in the tax rate in today's accounts
The industry has absorbed many regulatory changes over recent years and, while all well-intended, when taken together they have stifled investment, housing delivery and growth. In terms of corporation tax alone, the industry's rate has increased by 10% (from 19% to 29%) over the last two years, including the 4% RPDT. [Residential Property Developer Tax]
They also announced a move into Build to Rent sector
UK CPI data is out this morning with PPI... PPI weak, could be described as bumping along the bottom, no fillip for the industrial sector. CPI will be reported as good, with an archived annual rate of 2%. Alas there is a but .... YTD monthly numbers of -0.6%, 0.6%, 0.6%, 0.3% and 0.3%....so it's fairly clear to me that we are running a little hotter than the headlines suggest. The somewhat random Jan number is having a big effect....which I guess is the whole energy situation normalising. Never-the-less if we continue to trot along at the current pace we won't be staying as low as 2%....and wage growth running at 6% certainly isn't helping. It's reasonable to suggest lags in CPI don't reflect weakness in PPI and maybe it's yet to show itself.... and on that note we will be watching the US again next month to see if this months number was the outlier or the beginning of a weaker trend. On a positive note whilst the UK number might be a little high it doesn't look as though it's runaway or anything.
Overall these numbers are ok and likely to be taken to be soft landing consistent but with only limited scope to cut rates so far.
It is a surprise that the high interest/ mortgage rates haven't had a bigger impact on spending and the economy.
Take a look at the OOH (Owner Occupiers Housing Costs) element of the CPIH index
It's not spelt out but I presume this is the impact of higher mortgage rates.
https://www.ons.gov.uk/economy...
Yes one of the quirks. Higher interest rates increase Owner Occupier Housing Costs and therefore increase inflation. Which means that raising interest rates raises inflation, instead of reducing it.
Discretionary spending / prices have to fall even more to compensate.
When it comes to raising rates I thought the Bank of England's target was CPI, rather than CPIH, in recognition of that feedback loop?
I'm puzzled...
The graph shows that OOH inflation is rising.
I am also guessing rental inflation is also rising, given what I've been reading in the news.
so how can CPIH be tracking CPI so closely? I would have thought it would start to diverge and be meaningfully higher.
NextEnergy Solar Fund (LON:NESF) - Be interesting to see market reaction to the overnight raft of announcements. Sale £27m asset. New £20m sharebuyback Annual results showing lower valuations yet a slightly increased dividend. All these renewable energy companies have suffered - maybe this one finds a way forward and up?
This sector seems out of favour hence 30% discount? Good investment opportunity?
It looks to me like it's a punt on future power prices and hence gas prices. Power prices are trending downwards long into the future, which can't be good for NESF revenue, bringing some uncertainty into the sustainability of the 11% dividend. If power prices continue to slide, revenue will drop and the dividend will have to be cut.
Are the contracts not agreed years in advance hence not dependent on energy price? The risk is in underestimating the cost of construction, which can hit yields.
Not really, they are hedged a couple of years ahead but very much exposed to longer term power price assumptions - see the most recent annual report;
"As at 6 June 2024, the Company had secured fixed price agreements covering 92% of its electricity generation for the 2024/25 financial year and 75% for the 2025/26 financial year. "
"NESF’s NAV over the year decreased by 9.6p per ordinary
share to 104.7p per ordinary share (31 March 2023: 114.3p), driven largely by a reduction in the external power price forecasts that the Company uses (-7.8p per ordinary share)."
The major risk is that the average useful life of their solar assets is 25+ years, so if renewables do take over and drive down long term prices then their NAV will get eroded. There is also technology risk as their assets may become somewhat obsolete if newer models are substantially more efficient.
All in all, I think almost all of these renewables funds are cheap for a reason & are potential value traps.
Are the contracts not agreed years in advance hence not dependent on energy price? The risk is in underestimating the cost of construction, which can hit yields.
Thanks for the comments so far. This issue of the forward contracts and the declining energy pricing also has to be considered along with the rate of interest they are paying on their debt - which is significant - So mix them all together and (I'm no expert) I suspect the result is positive for the company and shareholders. Hence the modest increase is SP this morning
From today's NextEnergy Solar Fund (LON:NESF) results:
NextEnergy Solar Fund continues to lock in PPAs over a rolling 36-month period. This proactive risk mitigation helps secure and underpin both dividend commitments and dividend cover, whilst reducing volatility and increasing the visibility of cash flows.
Forecasted Total Revenue Breakdown 8,9,10,11:
And don't forget they can add plenty of batteries onto the existing sites over the coming years. I am very comfortable with our position here. They have increased discount rates: I don't believe actual interest rates will increase from here, and 28% price discount to this reduced NAV? I think a 20% recovery with 22% div over the next 2 years is good enough...
I have had solar panels for 10 years but my sister has just put some up and half the number produce as much power so surely these solar companies could produce more power from the same fields
Inflation down to 2 per cent, now cut those rates and get the house market moving, but not holding my breath.
I agree Bob.
The ECB has already cut it's rates with its CPI at 2.6% and its rate was already lower than ours.
The BOE has repeatedly said that we were not close enough to 2% to cut rates, however we have now reached the target. The US Fed has indicated that it will cut rates before the 2% target is reached whilst its CPI is currently 3.3%. One important difference is that the UK's fiscal policy does seem to have operated in tandem with monetary policy unlike in the US where fiscal policy seems to be out of control.
On this basis I think we should have a rate cut at the BOE's meeting tomorrow. If it doesn't happen I will suspect a political decision.
I think they will defer to August claiming it might influence the election.
If the BOE thinks they should raise rates but doesn't because they think it might influence the election; they will probably influence the election. In my view they should only think about the economy.
From an article in the Telegraph:
Traders reduce bets on August interest rate cut
Traders are cutting back their bets on the Bank of England cutting interest rates in August after the services inflation proved more persistent than hoped.
Money markets are pricing in about a 35pc chance that policymakers will lower borrowing costs for the first time in four years when they meet in August, having all but ruled out a rate cut at tomorrow’s meeting.
Traders had placed a 45pc chance on an August rate cut before the latest inflation figures, which showed prices in the services sector - covering things like education, hospitality and culture - rose at 5.7pc, which was higher than the 5.5pc predicted.
A full quarter of a percentage point reduction in interest rates is priced in by November, with a second reduction by the end of the year given a 60pc chance, down from 80pc earlier.
The view seems to be a cut tomorrow is very unlikely, since core and services inflation (the ones that really matter) are still quite high and sticky.
So why be autonomous from the government if political considerations still enters the decision making process?
Spectris (LON:SXS) a rather scruffy trading update blaming an ERP roll out and weakness in china.... industrial bellwether not doing what is says on the tin.... bottom end is no disaster and the shares suggest the market wasn't expecting much. Not quite sure what to make of it but H1 statements from China plays look less likely to shine ...
I'm not overly concerned with Spectris (LON:SXS) given this TU says very little that wasn't already announced in the May trading update:
While conditions in some of our end markets were softer than expected in the first quarter, notably China, we continue to expect to deliver progress this year as markets improve, with progress weighted towards the second half.
Then you also had one of the NEDs, Alison Henwood, picking up £35k of stock (announced May 28). Not a huge amount perhaps, but half her annual fee. Spectris NEDs are not required to own any stock at all.
Stocko runs very hot & cold on this stock, regularly flipping between high and low Rank scores over the years.
For anyone unsure, GAW's licensing revenue needs to be added to core revenue in order to get total revenue. Look at last year's financial report and this is how they've laid it out. Figures look good to me.
Avimgtrans
Lovely jubbly Rodney .
Have to say despite share price going sideways (though it held its ground in the bear market ) this alongside Bloomsbury is the company I hold and never causes me any thoughts of selling .
All divisions firing nicely , the recently acquire one out of administration also contributing and the medical / imaging thing ticking along slightly behind plan (so not using the forecasted cash )
Rinse and repeat .
Proven strategists in turnarounds buying out of admin and sorting companies out saving jobs and rescuing businesses .
Good to support a company doing good things and running good businesses
Strangely no mention of AI and a distinct lack of stupidly named initiatives and no management nonsense waffle .
Remains core holding .
On Avingtrans (LON:AVG), the main news in my view is in Cavendish's note rather than the TU itself.
The TU says the Advanced Engineering Systems Division traded well, with two of the businesses recording record sales and the recent purchase of Slack & Parr from administrators getting to EBIT positive; but there were delays in medical imaging (slower uptake of sales for Adaptix in veterinary and non destructive imaging) and a delay to H1 of calendar 25 in Magnetica approval in the US because of increased cyber security requirements. The delays in medical have reduced spend on that division, boosting EPS (on Cavendish's forecasts) for FY24 from 2.8p to 15.4p and resulting in a better than forecast net bank debt position of £6.1m (vs £6.9m forecast). So far, so so, because AVG has clearly signposted plans to invest in medical (with costs expensed into the P&L) so higher profits caused by delays in those investments are not, in themselves, good news because, logically, those costs just get pushed out into later periods.
However, Cavendish has kept the FY25 forecasts unchanged saying that this "illustrates management confidence" (i.e. they've not just left the old forecasts in place to be updated later in the year). So the combination of the uplift to FY24 forecasts with feedback from management resulting in their holding FY25 numbers seems positive.
(There's a supplementary question about why the most interesting information is in the broker's note rather than the TU itself. And a supplementary, supplementary question about what happens to equality of access to information when the company releasing the most interesting information does so through a house broker whose notes are not available to private investors. This last one is easy, but I digress...)
Alistair, your mention of Slack and Parr took me back nearly 50 years to when they were a customer of the IT support company I worked for. A nice little bespoke engineering company back when we had industry that made stuff in every back street of every town in this country and the use of the word Industry by the media meant exactly that. Pleased to see they are being rescued by Avingtrans (LON:AVG), if they were cheaper I'd certainly have some in my income PF.
There is also a Singer note on Avingtrans (LON:AVG) which is not identical. Worth reading both. It's good to see that the 2 Steve's were able to stop the outflow of cash into the Medical companies as there are some (I think expected) delays. Not all companies would have managed cash so well in such a situation. Hat's off. EPS forecast 2.8p, actual 15.6p
I have a few.
In my view a great British engineering company, the kind of company that makes real things.
Any chance of covering Young & Co's Brewery (LON:YNGA)? Thanks
My morning smallcap tweet: Winners and binners
Likewise (LON:LIKE) Games Workshop (LON:GAW) Sanderson Design (LON:SDG) Avingtrans (LON:AVG) H C Slingsby (LON:SLNG) Light Science Technologies Holdings (LON:LST) IXICO (LON:IXI) Microsaic Systems (LON:MSYS) Victoria (LON:VCP), Maintel Holdings (LON:MAI), Brave Bison (LON:BBSN), LPA (LON:LPA), Speedy Hire (LON:SDY), Alliance Pharma (LON:APH)
◄Likewise (LIKE)► AGM stmt - H1-June rev up 8.5%. "Whilst market conditions remain challenging, the Group is confident in further overall Sales increases in the traditionally busier H2." [SP=14 Cap=34m]
◄Games Workshop (GAW)► guides FY-June core rev up 10% and pretax £200m+, up 17%+. [SP=9435 Cap=3109m]
◄Sanderson Design (SDG)► hives off its smaller (Abaris) pension scheme for a £2.3m payment. CO will still pay £700k PA admin and advisory costs. The scheme has 119 members so that's £6k PA each in overheads! [SP=102.75 Cap=74m]
◄Avingtrans (AVG)► guides FY-Mar rev in line and adj EBITDA £13-14m, materially ahead of market expectations of £10m. This is partly due to some costs being delayed into FY25. [SP=385 Cap=127m]
◄HC Slingsby (SLNG)► AGM stmt - Jan-May rev down 4%, better than Q1's 5% but April 2023 was a weak comparative. May rev down 12%. Pretax loss £0.22m. Blames customers reducing or deferring spending following cost increases and uncertainty caused by the General Election. Outlook cautious. [SP=300 Cap=3m]
◄Light Science Technologies (LST)► wins £750k+ order to be book this FY. [SP=2.58 Cap=9m]
◄IXICO (IXI)► wins £1m+ five year trial contract. [SP=6.45 Cap=3m]
◄Microsaic Systems (MSYS)► FY accounts delayed to as late as end July Shares will be suspended on 1 July. [SP=1.15 Cap=2m]
◄Victoria (VCP)► FY-Mar in line. Outlook cautious. [SP=172 Cap=195m]
In line: MAI, BBSN, LPA, SDY, APH
Mr C. On Sanderson, the report says that £700K advisory and admin fees are the total expected to be paid over the life of the scheme. Its not an annual payment as your note suggests
Speedy Jire
Results look as expected but pity about the waffle and nonsense and stupidly named initiatives .
It’s like something a millennial snowflake would write .
And to top it all they have to cap it off with a ridiculous
”We continue to improve our customer proposition, investing in technology and AI capabilities”
And here’s me thinking they hired our machinery to builders and infrastructure companies .
No need for the waffle , just hire some stuff out and make a few quid please .
I read it that maybe they were planning on renting out some of their AI, brickies and builders probably could do with extra I, artificial or not..
“No need for the waffle , just hire some stuff out and make a few quid please .”
Shoukd have added
“And don’t lose millions pounds worth of scaffolding due to poor stock management “(that was a year or so ago with huge writefuen whej they realised they had “lost” millions of pounds of scaffolding
From The Times:
Shareholders have rewarded CMC Markets (LON:CMCX) as it continues its expansion away from its traditional business of spread-betting and contracts-for-difference trading.
The FTSE 250 trading platform business founded by Lord Cruddas, the Conservative peer, which has diversified into areas such as traditional stockbroking in recent years, on Tuesday announced a deal with the challenger bank Revolut.
As part of the deal, Revolut will offer some of CMC’s trading services through its app, with the under-the-bonnet infrastructure supplied by Cruddas’s company.
CMC’s share price rose by 15p, or 5.9 per cent, to 269p, with Cruddas saying that he expected Revolut would launch the new products “imminently”. CMC’s full-year results are due on Thursday.
Surprised this hasn’t been RNS?
Meanwhile Cannacord saying the CMC Markets (LON:CMCX) valuation is too generous https://www.sharecast.com/news...