Small Cap Value Report (Wed 2 Mar 2022) - VTU, RBG, HOTC, MMAG, FOXT

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
Agenda - (also known as, what fresh nightmares will be visited upon us today?)
Paul's Section:
Vertu Motors (LON:VTU) (I hold) - adj PBT guidance is raised again, from £70m to £75m, for FY 2/2022. As the outlook comments make clear, this year is a one-off bonanza, due to a shortage of supply pushing up used car margins. Next year profit is set to more than halve, but the shares look very cheap, even on future reduced profits. Great value.
Revolution Bars (LON:RBG) (I hold) - interim results from yesterday look encouraging. RBG has moved back into profit, holds net cash, and is in expansion mode again. 2 new concepts have been successfully trialled. Shares have not yet reacted to the turnaround, and are barely above the placing price of 20p which refinanced the business during the pandemic. Stronger reasons than ever to be bullish here. I see 50%+ upside.
Musicmagpie (LON:MMAG) - share price is down 27% today, on wobbly outlook comments accompanying in line results for FY 11/2021. I can't see anything interesting here, and like many recent IPOs, it still looks expensive, even after plunging on a profit warning.
Jack's section:
Hotel Chocolat (LON:HOTC) - good H1 performance, with profit and EPS up c50%. Management is certainly ambitious here, targeting £500m of revenue by FY25E and investing to grow into a £525bn global addressable market. So there is a long term opportunity. But the stock remains expensive and I’m not that comfortable with the valuation at present.
Foxtons (LON:FOXT) - revenue and profits up, while cash inflows have increased. The company is returning to dividend payments and has been buying back shares. It has also been winning market share and is positive on the outlook. Things did go wrong here, and shares remain well down on IPO levels, but this update is more positive than the languishing share price might suggest.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Vertu Motors (LON:VTU) (I hold)
57.6p (pre market open) - mkt cap £207m
Vertu Motors, the UK automotive retailer with a network of 159 sales and aftersales outlets, announces the following update with regards to the five-month period to 31 January 2022 (the "Period") ahead of its preliminary results for the year ended 28 February 2022 to be announced on 11 May 2022.
It’s yet another upgrade -
Trading Update: Further Upgrade of Expected Trading Performance for FY22
"I am pleased to report that the Board now expects the trading result for the year ended 28 February 2022, at an adjusted1 profit before tax level, to be not less than £75m…
The trading results have been aided by sector tailwinds and limited vehicle supply leading to augmented margins. In addition, recent acquisitions have contributed at a higher level than initially envisaged due in part to a swift and successful integration process."
This is a £5m upgrade to £75m profit for FY 2/2022, guidance was previously £70m.
There’s lots more detail in the announcement, which I won’t regurgitate here.
Outlook - stressing that FY 2/2022 is a one-off bonanza year, as we already know -
FUTURE PROSPECTS
The strong balance sheet, experienced leadership team and strong systems capability of the Group ensures it is well placed to capitalise on the significant opportunities for growth that exist within the UK automotive retail sector. The Board considers that scale is a vital success factor in the sector given the need for strong brands and investment in digital developments and continues to have ambitious growth aspirations for the Group in the next few years.
Without doubt, FY22 has seen extraordinary trading conditions which have driven the exceptional financial performance. Whilst the outlook remains uncertain for FY23, it is clear that these highly favourable trading conditions are unlikely to recur. The FY23 financial outcome is likely to be some way below FY22, although we certainly expect performance to be well ahead of periods prior to FY22. As the year progresses, we will update the market accordingly. Significant increases in operating expenses such as payroll, energy and investment in digitalisation and related marketing are evident. In addition, rates and vehicle expenses are expected to normalise. The enhanced vehicle sales margins seen in FY22 are anticipated to continue but at a reduced augmented rate as supply in new and used cars normalises in the year ahead. Considerable uncertainties remain over new vehicle supply and the timing of market normalisation. In addition, consumer confidence will be critical in the months ahead as cost-of-living inflationary rises become apparent and geopolitical uncertainty arises. These matters could impact vehicle sales.
The Group is now in a better position to maximise aftersales revenues due to higher resource levels following pay reviews and a recruitment drive. Aftersales margins are likely to reduce, as seen in the latest Period, with a potential offset with revenue growth. The last two-year decline in new vehicle sales will lead to a softening in the market for service and repair work in the UK for vehicles under three years old, the traditional core market for franchised retailers servicing. Increasing market share in the older vehicle service and repair market will be a critical objective to seek to offset this softness.
Valuation - many thanks to Zeus for publishing an update note this morning, on Research Tree. It has pencilled in 15.8p for FY 2/2022 - a PER of 3.6! This is best ignored though, because it’s a one-off.
Next year, Zeus has profit more than halving, to £35.4m, anticipating sales conditions normalising, and higher overheads. This is the more relevant figure to value the shares on, in my view. So at 7.5p, this is a forward PER of 7.7 - which looks highly attractive to me.
Particularly when you also factor in that the balance sheet has net cash, and is full of freehold property.
My opinion - as shown above, even if we adjust out current extremely positive market conditions, VTU shares still look very cheap.
The current share price is at a discount to NTAV, which doesn’t make any sense to me. That implies that the company is making unproductive use of its assets, which is clearly not the case. So I think the market price for Vertu shares just looks wrong (ie. too low).
The dividend yield is about 3%, plus VTU is buying back its own shares, thereby enhancing EPS, with another £3m buyback announced today.
There has also been takeover activity in this sector, so further upside could come from that.
There’s so much to like here, so I remain a firm holder.
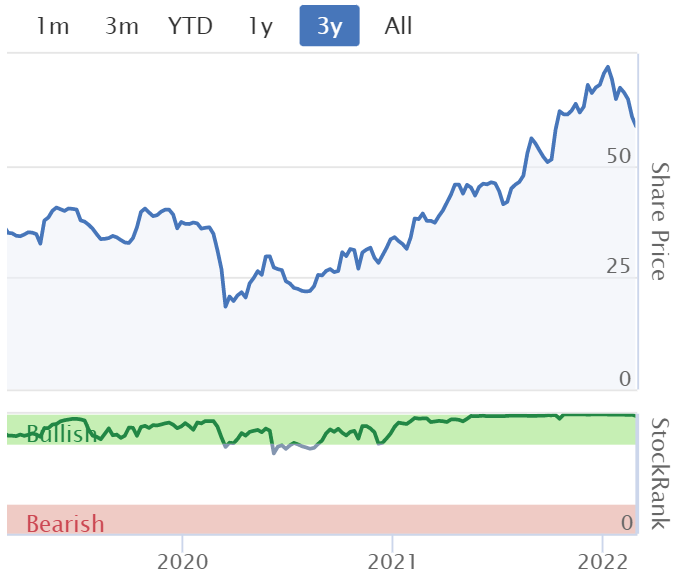
Looking at the chart below, I might usually consider banking some profits. However, the fundamentals are so good, that it doesn't make sense to sell a share which is this cheap.
.
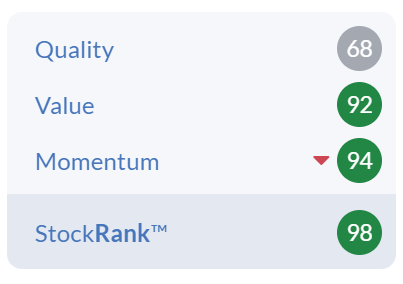
Stockopedia's algorithms love VTU too -
.
Revolution Bars (LON:RBG) (I hold)
21p (yesterday’s close) - mkt cap £48m
Interim Results (published yesterday)
Revolution Bars Group plc ("the Group"), a leading UK operator of 67 premium bars, trading predominantly under the Revolution and Revolución de Cuba brands
Dramatically improved performance is now evident, for the 26 weeks ended 1 Jan 2022.
The 6 months was still affected by covid, at the start, with restrictions only being lifted on 19 July 2021, and then towards the end, when omicron hit the peak seasonal trading hard. In between there was a strong recovery though. LFL sales were up +14% for most of the period, but omicron reversed most of this, with LFLs being +1.4% from re-opening to H1 period end.
Therefore, we should see further upside on these numbers, if no further covid restrictions occur.
Offsetting that, H1 benefited from £1.3m in business rates relief.
H1 revenues £74.1m, adj EBITDA £7.6m, Profit Before Tax £4.3m - I think this is a good performance in the circumstances.
Full year FY 6/2022 profit guidance for FY 6/2022 - top end of market expectations, of £8-10m adj EBITDA (on IAS 17 basis)
Net cash of £4.2m, so the company has plenty of firepower for expansion into new sites. 2 placings at 20p generated £34m of fresh cash, which has transformed the financial position, but also heavily diluted - there are now 230m shares in issue, compared with 50m pre-pandemic. Therefore to get the same upside, we have to buy a lot more shares than before, and realistically the share price is unlikely to return to anywhere near the previous highs.
New sites - 2 for this year, and 6 planned for next year. There’s scope to do more though, and I think the ending of the rent moratorium could throw up additional opportunities on attractive rents.
Refurbishments - now underway in earnest, with 19 planned for this year. Excellent 2-year payback. This should be a big driver for sales growth, and hence allow the company to absorb cost increases in other areas (e.g. wages, energy, ingredients).
Exited poor sites during the pandemic, and got rent reductions, so this is a better business now, compared with pre-pandemic.
Dividends - for technical reasons, probably won’t be until Nov 2023.
Going concern note says material uncertainty due to covid. This has nothing to do with the company’s financial position, which is now strong, with net cash, very strong actually compared with a lot of highly geared competitors (some of which are likely to go under when rent moratorium ends shortly).
Balance sheet - NAV is negative at £(20.9)m, but this is due to the big deficit on IFRS 16 lease liabilities. That doesn’t make sense to me, because the problem leases have been ditched. So we should expect this deficit to reverse in future, as the Right of Use Asset figure rises to reflect improved trading post-covid. So not a concern.
New formats - two have been trialled, with strong performance so far. An old site in Northampton has been rebranded as Playhouse with arcade style games combined with cocktails & pizza. Looks good, and it has positive reviews online. Also a site in Swansea is trialling another new format called Founders & Co, which I also like.
My opinion - this is now looking very good, and the shares are cheap, in my opinion.
All the historic issues have now been solved, and I think market perception of RBG could radically improve once investors twig that this is now a well-funded, well managed, expanding, multi-brand speciality bars group.
Despite industry-wide cost pressures, RBG has some good growth potential, from the refurbs, and new sites.
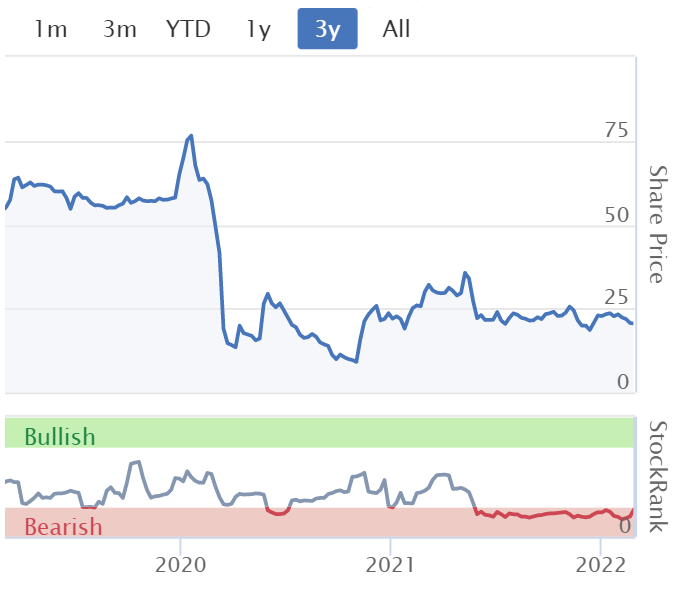
Yet the share price is only 5% above the placing price, which I think provides an attractive opportunity to possibly bank a c.50% profit over the next year or two. The facts have changed very much for the better, but investor sentiment has not. That's a buying opportunity in my book.
.
.
Musicmagpie (LON:MMAG)
119p (down 27%, at 10:13) - mkt cap £128m
This has cropped up on the top fallers list for today, so I’ve taken a quick look.
This company floated on AIM in April 2021, and is joining the long list of over-priced, underwhelming IPOs, many of which were online businesses that floated on the back of an unsustainable profit boost from the pandemic. As that growth stalls now, share prices tank. Often IPOs are mainly done as a lucrative exit route for selling shareholders.
It’s my first comment here on MMAG, but I do recall skimming through its Admission Document last year, and thinking the business looked a bit old hat (especially its “legacy” CD/DVD reselling, and books businesses). The more modern part of the business refurbishes & resells (or rents) consumer electronics. Again, not an interesting business model to me.
Full year results - for FY 11/2021 are out today.
In line with expectations, the company says.
Revenues £145.5m (down 5.1% on LY)
Adj PBT £7.9m (down from £9.2m LY) - as pandemic boost receded.
Why are the shares down 27% today then? It’s got to be the wobbly-sounding current trading comments -
· FY21 ended strongly with record sales in the UK and US during the Black Friday period across the business. This sales momentum continued as we entered the current year, however, as the first quarter of FY22 has progressed, volumes and trade-in activity levels have moderated in line with consumer trends
· Consumer Tech revenues for the first quarter of the year have been in line with management expectations, but a trend towards lower sales volume at a higher average selling price and an increase in the proportion of products sourced from intermediary wholesale partners, is currently expected to compress the gross margin on outright sales in the category in the current year by c.4.0 percentage points compared to FY21
· The rental subscription service is continuing to grow, with c.19,000 active subscribers at the end of Q1, with a forward contracted order book of £2.2m (2021: £0.4m). 15 per cent. of outbound Consumer Tech volumes on musicMagpie store are now rental sales versus 4 per cent. in 2021. The introduction and success of rentals to our business model is expected to have a short-term compression on the Group's headline revenue growth as we move from upfront to monthly revenue recognition. This area of the business is expected to earn higher revenue and EBITDA over the life of a device, as opposed to a one-off sale, underpinned by a contracted recurring income and cash flow stream and will become more visible in the Group's performance in the medium-term
Dividends - none.
Share-based payments - there’s an astonishing £17.4m charge to the P&L, which makes the company heavily loss-making at the statutory level, at a £(14.8)m loss before tax. I don’t like the look of that one bit!
Balance sheet - looks OK.
Cashflow statement - some concerns here. Cash generation fell considerably compared with last year. Also, it capitalised £2.8m in development spending, and had a further £4.4m in traditional capex, which seems quite a lot.
The IPO proceeds of £15.0m was mainly used to pay down debt.
My opinion - MMAG doesn’t appeal to me at all.
It still looks over-valued to me, even after today’s sharp fall.
.
Jack's section
Hotel Chocolat (LON:HOTC)
Share price: 454p (+0.89%)
Shares in issue: 137,278,264
Market cap: £623.2m
Interim results for the 26 weeks to 26 December 2021
Hotel Chocolat is a stock that has always looked expensive. That’s no different this morning.

It has staged an impressive post-Covid rally, however, briefly touching all-time highs of 520p at the start of the year before falling back to today’s price of 454p. That still results in a £618m market cap, so the group has grown substantially since listing back in 2016 at 167p, for a market cap of £167m.
- Revenue +40% to £142.9m,
- Underlying EBITDA +35% to £33.8m,
- Profit before tax +56% to £24.1m,
- Diluted EPS +49.7% to 14.2p
50% of placing (c£40m total from a little over 11m shares priced at 355p back in June 2021) proceeds have been deployed into growth investment.
The group reports a growing brand appeal in the UK, US, and Japan.
The active customer database in the UK has grown by 38% to 2.3m, active numbers are up 119% in the US thanks to digital, and the Japanese joint venture’s sales to consumers have grown by 131%.
Management action on inflationary pressures means profit has grown faster than revenue, although the gross margin has slipped slightly, from 61% to 59.8%.
Net cash flow from operations was £29m (down from £33m in H1 FY21, but up before changes in working capital) and net cash is up from £45.6m to £53.8m.
£13.6m spent on plant, property and equipment, another $4.2m lent to its joint venture, and £1.9m spent on purchase of intangibles make up a £19.7m cash from investing outflow. Then the £40m placing ensured that net cash grew from £10m six months ago to £53.8m today.
If you ignored the placing, there would have been an inflow of £3.5m.
Seems fairly routine. BDO has been in place since 2012 so is being replaced by RSM. Best practice is to replace after ten years or so.
Conclusion
For all the stock’s priciness, I do think there is potential in the brand here. Here’s what the CEO and founder says on that:
Our brand purpose is to make people happy through chocolate. This means bringing happiness to all the groups we connect with, including customers, team-members, growers, suppliers, and local communities. This remains our 'North Star' and by continuing to follow it we will achieve our business goal of becoming the leading global direct-to-consumer premium chocolate brand.
That’s a big prize to aim for, and broker Liberum touts a £525bn global addressable market, but a lot has to go right for it to happen. Hotel Chocolat has paused its dividend programme in order to invest more into this strategy, as well as raising cash from shareholders.
In order to fund an acceleration in growth, the Group raised a total of £60m equity via placings in 2020 and 2021 and paused its progressive dividend policy. The Board are mindful of the potential growth opportunities in the USA and Japan, and the Board will continue to review potential reinstatement of any dividend relative to the potential opportunities for re-investment in service of profitability and growth.
One thing about an extremely expensive share price though, is that share dilution so far has not been that bad. The group IPOd with about 113m shares in issue and today, nearly six years later it has 137m.
In terms of outlook, the group comments:
Since the end of the financial reporting period, trading has continued to be in line with the Board's expectations. The multi-channel performance of the UK remains encouraging, and the new markets continue to show promising potential for growth and profitability.
That sounds fine, but I still struggle with the valuation here. There could be something really valuable at Hotel Chocolat, but a fair amount of this is priced in and so I don’t think the risk:reward is particularly attractive at these levels.
It’s a growing business with an intriguing brand proposition and business model. The group is targeting £500m in sales by FY25E. That would be impressive and implies that management is ambitious, with a good vision of where it wants to get to. So I’m not dismissing the prospects, but I would want a lower entry price.
Foxtons (LON:FOXT)
Share price: 35.02p (+1.06%)
Shares in issue: 318,972,062
Market cap: £111.7m
Final results for the year to 31 December 2021
The share price has collapsed here again, giving back all of the gains made as the nation came out of lockdowns.

The London property market certainly seems far more buoyant now, and rents are going up, so I’m curious to see what’s driven that poor relative strength.
Revenue of £126.5m is up on both FY20 (£93.5m) and FY19 (£106.9m). Adjusted operating profit is up to £8.9m, from £1.9m in FY20 and a £0.7m loss in FY19. Reported PBT is up from a loss of £8.8m in FY19 to £5.6m. Adjusted EPS is up to 1.9p from losses in both prior years, although reported EPS remains negative at -0.4p.
Foxtons has also returned to dividend payments, returned £5.7m to shareholders via buybacks, and net cash inflow has increased from -£2.5m in FY19 to £6.6m.
The group also says it has increased its market share in the London sales and lettings market, with the current under-offer sales commission pipeline marginally ahead of 2021.
Outlook
In sales, 2022 began with our under-offer sales pipeline marginally ahead of 2021 levels, and significantly up on the pre-pandemic levels, giving us confidence in a more sustained market recovery. In lettings, London average rental prices are in line with 2019 levels which we expect to be underpinned by strong tenant demand as pre-pandemic behaviour returns, including continued growth in Build to Rent in 2022. We have a good pipeline of further lettings portfolio acquisitions and expect to invest £8m in 2022 to generate attractive returns for investors. In mortgage broking, we expect there to be similar levels of market activity to 2021.
Subject to the geopolitical situation, we expect the trading environment to remain positive, and will take steps to control costs, despite inflationary headwinds, and improve productivity. Overall, we have a clear plan for growth and expect to build on the strong progress made in 2021.
Conclusion
I understand Foxtons has had its issues but I’m struggling to justify the recent share price fall. Perhaps it was just a poor AIM market compounded more recently by Russia’s invasion? And maybe the market remains sceptical as to the duration of the positive sales and lettings environment.
It sounds like the group is doing a decent job of rebuilding momentum.
Growing market share is a priority and it is encouraging that we improved market share in both sales and lettings for a second consecutive year after a period of decline.
If Foxtons can maintain that market share performance and the wider market holds up, then there is potential to grow from today’s modest levels via acquisition of lettings books. I feel as though the market’s been a little harsh on the share price here but clearly there are some significant macro risks to consider.
Additionally, private investors also have access to a number of higher quality sales and lettings operators with franchised business models. The operating track records of the likes of Belvoir are extremely good, so they are probably safer bets. But this update reads more positively than the recent share price performance might suggest.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Hotel Chocolat (LON:HOTC) look at my comment when this was trading in mid-high 400s. I know the chocolate industry. Hotel Chocolat is WAY overvalued, even now. Thinly traded, not great quality product, entirely dependent on marketing spend, and entering a recession when mid-priced chocolate will suffer. Yes, it's the only pure-play chocolate retailer on the market but Japanese and US expansion plans are at too early a stage to justify its current multiples.
Not a small cap but ...
Interesting comments from Asos (LON:ASC) re withdrawal from selling in Russia/Ukraine. Surprisingly large hit to profits -
ASOS Plc
Update on impact of the Russian invasion of Ukraine
ASOS is providing an update on the impact of the Russian invasion of Ukraine on its business. ASOS' priority is the safety of its colleagues and partners in the region. Immediately following the invasion, ASOS suspended sales in Ukraine as it became impossible to serve customers there. Against the backdrop of the continuing war, ASOS decided to suspend sales to Russia earlier today. In FY21 Russia and Ukraine represented c.4% of Group revenue and contributed approximately GBP20m to Group profit.
Wow, that was more than I was expecting too.
Do they have any infrastructure in Ukraine? Warehousing, logistics, etc?
Asos (LON:ASC)
Hi Boon
ASOS has no infrastructure in Russia/Ukraine as far as I am aware.
A
When I go to the stockreport page of any company, and press the discussions tab I get nothing!
Are other users experiencing the same problem ?
When I go to the stockreport page of any company, and press the discussions tab I get nothing!
Yes, the same even though I know there are threads. I have reported through green button.
Hi guys,
Thanks sharw and others for alerting the team via support. A bug card was written up yesterday and a developer continues to look into it, so we're on the case!
I'm interested to see that Ab Dynamics (LON:ABDP) has fallen to its pandemic lows. I know there are a few fans of the name amongst the Stocko crew yet the name has never been covered in any discussion - if the search function is to be believed.
At a market cap of £250m this name ought perhaps to be more widely discussed.
I can imagine why it has sold off recently as car production is being disrupted by the situation in Ukraine at a time when the business is looking for a new identity with products branching into defence and mining technologies. And what was once a business with excellent operating numbers has fallen away of late in terms of operating efficiencies. But revenues continue to rise even during the pandemic.
Any thoughts on the opportunity here everyone, especially from holders with a better handle on the name than I have?
Ab Dynamics (LON:ABDP) used to be discussed quite a bit a few years ago, looks like the search is only on the new site?
Actually looks like another system problem as Vertu Motors (LON:VTU) does not have any discussions on the search. I will report it.
Foxtons (LON:FOXT)
Thanks for the write-up Jack.
Like you I am struggling to understand the rationale for the current depressed share price.
There's lots to like in today's update:
I am expecting this to continue rising in the short term.
---
If there was one niggling concern it would be on the company's outlook that 2022 Sales Operating Profits will breakeven.
I personally think the company is being too bullish in light of reduced housing supplies.
For reference I think the last time Sales made a full year profit was around 2015/2016. It was in fact what has put me off investing in recent months.
However, I've come around to the belief that I should be looking at Sales and Lettings Operating Profits together as a lot of the costs here are simply apportioned based on headcount. One can't simply close the Sales business as the branch rents - a material cost - will still need to be paid.
For reference one can see the progression of the lettings business over the last 3 years below (+ my guestimates for 2022.)
Note the big jump in Lettings OP from H1 to H2 in 2021 (£1.5m ---> £7.5m) as demand in London increased, rents rose to pre-covid levels and operating leverage kicked in.
I hope that I am being conservative enough in my modelling to show a very cash generative 2022 (£6m-10m) for a company with a market cap of £110m and net cash on its balance sheet (excluding lease debt) of c£20m.
I haven't bought a position yet, but I probably will. I would be interested to hear thoughts from others.
Am I missing something obvious?
Cheers
A
Vertu Motors - interesting business, very tight margins with a huge tangible asset base due to owned commercial premises.
My interest in the tangible asset growth might suggest that this is my kind of business. Not necessarily, I am not that interested in the asset base, although I am very interested in the growth of the net tangible asset base as this is usually a more reliable indicator of wealth creation within the business than the declared earnings of the business.
By comparison, if, for example, ScS, which has a sizeable asset base due to its cash build up, were, hypothetically, to be selling for around book value, the shareholders would rightly demand that the money be distributed to them. Vertu's tangible assets are largely in buildings, which is fine, but it is the rate of tangible equity growth relative to MCap that interests me.
Over the past 4 years, Vertu's tangible equity has built up at an average annual rate of c3.0% per annum, I estimate the forward dividend to be c2.75% and the average share buy backs over the past 4 years are c1.5% pa. Put it all together and the average tangible surplus generated by the business is c7.3% of MCap.
A moderate bargain at this price, but I prefer to see tangible wealth generation up at 10% pa relative to MCap and Vertu's margins tend to be very tight, which does make me a little uncomfortable.
Re Vertu Motors (LON:VTU) , it is mathematically very difficult for a tangible asset rich business with 11% gross margins & 2% operating margins to create any growth at all in tangible equity.
The size of Vertu’s existing asset base is not relevant, as the growth in net tangibles (plus dividend and factoring in buy backs) is calculated as a % of the MCap not the existing asset base.
As for the margin, I agree, the turnover would have to be enormous relative to MCap to create a higher acceptable return. I have been into the sales office of our local Bristol Street Motors, it did seem very chaotic and does, I believe, have a high turnover of sales staff. I don't want to put too much weight on this impression as sales offices can often appear more chaotic than they actually are. But, car sales persons can be very turnover driven, even if sales were reduced by 20% but margins were up nearer 2%, that would be a dramatically better outcome, accept 20% less sales for a 1% increase in the sales price. If you give a car sales person a tiny profit bottom line price that they must not go below, then that is what they will sell for most of the time, i suspec that this is what is happening here.
Vertu's margins are in line with or better than other franchised dealer groups. Historically tight margins have sadly been the case which is why Vertu in particular run a tight ship and acquire on strict criteria. Cazoo claims a new dawn in used car margins -- I know which share I'm happy to be in and it isn't one making ridiculous claims.
No RNS from 888 Holdings (LON:888) yet on yesterday's £9m fine and final warning for allowing players deposit up to £40k without a source of funds check, and many other failings. Letting an NHS worker gamble more than 90% of his earnings each month was just one of the many ways it enriched itself.
In 2017 it paid a £7.8m penalty package for failing vulnerable customers.
It boasts "Over recent years, we have increasingly recognised that being uncompromising on safer gambling lies at the heart of this.”
Lies at the heart of it indeed.
https://www.independent.co.uk/...
Scum.
Great post Mr C - i wander if uk facing gambling shares will be the next big thing in a similar manner to the the payday lending companies ,being actively targetted by regulators on increased scale. Makes one wander where this regulation will stop? - are other simialar ethical areas eg spreadbet companies likely to face similar issued - i was also slightly uncomfortable next was making over 1/3 of its profits approx (from memory may not be accurate) from "finance income" selling clothes on expensive credit , culd pawnbrokers be targetted ? . As someone who invests in shares and who may lose out with "unexpected penal regulation" tunring up i am actually not against tight regulation in this area - i am all for proper reasonable reponsibilty being put on providers - i would suspect most betting companies are well delinquent in this regard and see fines as lesser evil. Seems sensible to me someone earning 30k a year should not be able to to spend 10-15k a year on a gambling site without providing some reasonable evidence they don't have a problem - which they clearlky do if they dont have serious wads of net liquid cash. I have done a lot of gambling in my time and i have always found the gambling companies are super happy to take your money at any stakes if you are a known "loser" or "big net spender" - they are very quick to limit stakes of winners - so they IMHO must mostly have the tools to target big losers too - sadly its obviously not really in their interests to be asking "losers" why they are losing so much as the reponse may be something that ends that particular cash cow. At present i am happy having very little expposure to any of these areas- i do have Ig Group (LON:IGG) on my watchlist though - little snippets like this do make me wander where the next "ppi" lies and is it hear?
Ref £888 itself i did hold and did very well - i sold out very early on the runup as i thought covid related boost was not likely to last (share price continued on the up and up as happens when i sell ) - surprised somewhat to see the shareprice where it is today if trading has continued to be "robust" post covid - looking at current forecasts they still seem to be doing very well operationally speaking . Perhaps the regulatoy issues might be something potentially serious with regard to ability to make "easy money" ?
Hostmore (LON:MORE) (I hold) dropping to new lows this morning. Trivial volume so I am guessing it is panic selling unless anyone can enlighten me on why?
I actually went to one in Birmingham on Sunday afternoon with the family. Firstly we had to go in at 12:30 as afterwards it was fully booked until late evening. Food was good, service was a bit on the slow side and it was apparent the staff were running around trying to manage too many tables, however they did try to hide it when dealing with the customers.
130 pound for the 7 of us so no complaints at all.
I had a similar experience in Gloucester. Providing they can train and retain staff then they should be making money as they appear busy.
ELTA and the two spin-offs has been such a disaster. Hospitality and retail will not be for me in the future I think
Discretionary spending stocks are being hit - inflation means less spending - hence sentiment has changed.
Vertu motors very cheap for sure but I wonder how hard headwinds are going to become.
Inflation rising, lord knows where energy prices are going to end up, its pretty easy to see people not buying that new car or used car when they need to feed the kids, pay the mortgage and keep the house warm.
I know the bicycle market is absolutely brutal right now (not the same as car admittedly) , toughest it has been for years yet manufacturers are committed to big orders, on long leadtimes, with deposits paid and cash committed, couple this with a sudden drop in "pull" with demand then the "push" of the avalanche of stock arriving is going to cause a perfect storm of carnage in about 8-12 months time.
On the plus side for car market shortages will probably continue so demand may remain tight keeping prices high but if / when supply catches up and the exceeds demand then I fear the industry will not "return to pre pandemic levels" but face a much worse bigger and more perfect storm than the bicycle market is going to get first.
Doom and gloom scenario for sure and Vertu is still my third biggest holding .
"Agenda - (also known as, what fresh nightmares will be visited upon us today?)"
This made me chuckle Paul. It's relentless at the moment.
Reminder: Ukrainians have it worse.
(End of war commentary.)
Morning Paul, any chance of giving us your thoughts on yesterday's Revolution Bars (LON:RBG) update? Regards
On Revolution Bars (LON:RBG) I really like their top-line numbers and momentum there, but wonder how much margins will be squeezed.
I remember from a Langton email earlier in Feb, the Night Time Industries Association published a survey that said total operating costs for their night-time businesses has increased 26% in the past year (unclear whether incurred in H1, or H2).
Due to stock and workforce increases, utility increases, and insurance prices (interesting).
First two factors have seen further inflationary momentum in recent months.
On top of that, RBG target audience (20-30 year olds) will be squeezed in terms of disposable incomes at some point, and I wouldn't be surprised by headlines later this year of "partying behaviour has changed with house parties becoming more common".
I think structurally they're set up well and the economics of RBG is now very very strong, but sitting on the sidelines still due to the macro pressures.
If the under 30s that live at home start contributing to household costs then there might be a downturn in the going out trade, but chances of that being widespread with this generation?
Interesting comments. Certainly the 18-30 year olds have missed out on a serious amount of socialising and partying over the last two years which should be good for £RBG. (No position - but held in the past).
I was thinking about the roaring twenties a few days ago and pondering whether there were some similarities now to that period. In other words much more a prolonged period of high activity rather than a one-off partying like it’s 1999.
However, the roaring twenties was followed by the Great Depression. So, I’m asking myself how soon might a depression come after the post Covid partying?
My conclusion is this. Rampant inflation is a clear negative. The Ukraine crisis may keep energy prices high and we have no idea how long that will last - and high energy prices are a huge negative for disposable income. Furthermore, how will graduate debt affect this as the debt compounds at RPI+3? Will that affect the spending power of that demographic even more?
Seems like prospects for £RGB could be strong short term but we may find that is a much shorter length of time than expected.
I agree with Paul's comments on Vertu, I'm a long term holder with some motor trade experience. Thank you Paul for covering today's statement.
re Norman Broadbent (LON:NBB)
How a professional recruiter with a well established brand can fail to make a profit year after year after year must be a mystery to many. The costs of a pointless listing must be weighing on margin and that central London office isn’t cheap, but mostly it’s because their consultants are overpaid relative to their output, ie with one or two exceptions, they’re not very productive. Avoid.
Vertu Motors (LON:VTU) (I hold) - positive trading update this morning. Solidly profitable, net cash, on a single figure PE and standing below NAV. Why so cheap? What am I missing?
With Vertu Motors (LON:VTU), the operating margin is very low, which has put me off investing before. Although the other metrics and value look great. Is the operating margin a concern for the investors?
Hi richwilko8796,
With Vertu Motors (LON:VTU), the operating margin is very low...
That's true, but most of the revenue is pass-through, i.e. the value of the cars being sold. So I tend to view gross profit as being more akin to revenue. The profit margin then looks a lot better.
Same thing with staffing companies, where revenues are huge because it includes pass through wages of the workers.
Regards, Paul.
And perhaps for construction companies which sub outa lot of the work.
It is true for main contractors who are essentially project management companies co-ordinating the work of specialist subcontractors. IF things work out well, they make a decent ROCE, but on wafer-thin profit. However, if they do - and it only needs a few projects not to - then those margins can be obliterated. This suggests either invest in those companies which:
- have a niche as they tightly control and manage what they know ... and charge a decent margin for it, which in turn ...
- actually do the physical work, ideally having some defensible IP which implies
- they are also responsible for some elements of manufacturing rather than just installing (which is know-how).
Today at 5pm there is a webinar with Mirriad Advertising (LON:MIRI) CEO Stephan Beringer, CEO and Mark Melvin, EVP of Sales and Brand Partnerships with responsibility for North & South America, They will introduce the digital advertising platform, talk about the progress made over the last year and the exciting opportunities ahead.
Last week the company released an RNS Reach announcement which highlighted the first major partnership signed in Canada as well as reporting very strong campaign metrics from recent in-content advertising campaigns in North America. Nielsen data showed audience reach using the Mirriad in-content format was up to 39% higher than in the equivalent TV spot breaks in the same content.
CEO Stephan Beringer also reported that Mirriad in-content advertising was in use around Super Bowl in the US, one of the biggest advertising opportunities in the US, which would suggest 2022 revenues are off to a good start.
Earlier this week the company announced they had signed their first contract in Japan, the worlds third largest advertising market. CEO Stephan Beringer said “Momentum is building for Mirriad, rolling out its transformative advertising solution to new markets across the globe and establishing in-content advertising as a new standard in the industry.”
Come along to the webinar today and hear for yourself why Mirriad is confident they are pioneering an advertising solution that will become a standard in the industry.
Register: https://us02web.zoom.us/webinar/register/7016461630416/WN_ax173xrKRvyeQkoUBXAjxA
Morning peeps. Quick morning question plz... does the uk have any neon gas making companies?
No. Up to half of the worlds neon gas supply comes from the Ukraine. Another challenge for the semiconductor industry.
https://www.wired.co.uk/articl...
Does anyone think it is odd that we have the problem in the Ukraine and that just happens to make our economic woes so much bigger, from oil and gas and corn and wheat to now neon. Could not have picked a better country if you want to cause more chaos than there already is.
The puppet masters of the world tweaking the strings again!
Our world has become very interconnected. Another example is the pointless destruction of the Antonov AN-225 Mriya, the world's largest aircraft and the only one of it's kind. That will impact all manner of projects including space launches.
We are back in the dark ages it seems, when the Vandals swept through Europe post Roman Empire.
You don't make Neon or helium or xenon etc. It is inert and exists in small quantities in the air and natural gas. The Steel industry uses a great deal of oxygen in refining blast furnace iron. This is produced by liqifying air and separating its constituent parts in a similar way to oil refining. The neon and other gases will be one of those constituents which are further processed imho. 8 years in the steel industry before it collapsed from foreign competition.
Apologies buddy, when I said 'make' I was referring to the collection/processing, storage and sale of neon gas as this is used for chip manufacturing.
No need to apologise Lee, from reading the link to Wired it isn't a consumable as such for chip production. Just used to manufacture the lasers, used in etching the semiconductor wafers, which presumably have a long life.