Small Cap Value Report (Wed 20 April 2022) - VLX, CARR, WINE, SFR

Good morning, it's Paul & Roland on SCVR duty today.
Agenda -
Paul's Section:
Volex (LON:VLX) (I hold) - a reassuring update for FY 3/2022 year end. Ahead of expectations (only slightly for profits). Lots of other positive remarks, including continued ability to pass on higher costs. Supply chain disruption could even be a positive, with customers increasing forward orders for certainty of supply. Even after a 14% rise this morning, this share still looks a bargain to me.
Naked Wines (LON:WINE) - trading update is in line. I'm wary of this business model.
Roland's Section:
Carr's (LON:CARR) - this agricultural feed and engineering business has underperformed the market in recent years but has a strong long-term record. Commodity market conditions put pressure on margins in H1, but this should unwind in H2. A strategic review could result in improved focus and growth potential. I can see decent value potential here.
Severfield (LON:SFR) - the structural steel group appears to be trading well with a strong order book. Full-year results are said to be in line with expectations, although I can’t entirely dismiss concerns about cyclical risks here. Even so, the shares do look decent value to me at current levels.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to
Paul’s Section
Volex (LON:VLX) (I hold)
247p (pre market open)
Market cap £390m
Volex plc (AIM:VLX), the global supplier of integrated manufacturing services and power products, provides the following update on trading ahead of the announcement of the Group's full year results for the 52 weeks ended 3 April 2022 ("the year").
The share price has been relentlessly falling, which of course makes us all worry that things might be going badly. The reason I’ve been fairly comfortable holding Volex, is because the company recently agreed substantially increased bank facilities. That matters, because banks are all over the management accounts, and would not be expected to increase lending if things were going badly. So that was an important sign, that the market seemed to ignore.
Sure enough, things are going well. Today we’re told -
Results ahead of expectations
Volex is pleased to confirm that the Group's revenues and underlying operating profits are expected to be ahead of consensus market expectations1 for the year.
The Group expects, subject to finalisation of the accounts and audit, revenues to be in excess of $605 million (FY2021: $443 million) and underlying operating profit2 to be in excess of $55.0 million (FY2021: $42.9 million).
1. The Company has compiled forecasts from four analysts with current market forecasts for the 52 weeks ending 3 April 2022 for revenue to be in the range of $575.0m to $586.3m, with a consensus of $581.2m, and for underlying operating profit to be in the range of $53.8m to $54.6m, with a consensus of $54.2m.
So before we get too excited, profit is only slightly above expectations. Still, to have achieved that in a time of supply chain turmoil, and heightened inflation, is impressive.
Strong demand -
Volex has continued to trade strongly, delivering robust organic revenue growth, including a significant contribution from the Electric Vehicles sector, where revenue has almost doubled. Demand has increased during the year with greater visibility of forward orders as customers look to secure manufacturing capacity.
That last bit that I’ve bolded sounds highly significant. It sounds as if Volex could be a beneficiary of supply chain problems, in that customers are committing more forward orders. This probably also means Volex has improved pricing power, since customers presumably are more likely to accept price rises, in return for certainty of supply, in a disrupted world.
Inflation - once again, Volex has confirmed that it is successfully passing on cost rises to customers. Management has been telling us this for a while, but again for some bizarre reason, some investors have ignored this, and made the incorrect assumption that Volex must be suffering from higher copper & plastic prices.
Acquisitions - four have been done this year. Volex seems to have a disciplined approach to making acquisitions (not over-paying, and only buying companies that are a good strategic fit).
This should have led to a re-rating for the shares, but in this small caps bear market, the valuation has actually been falling, which doesn’t make sense at all to me.
Directorspeak - sounds upbeat -
Nat Rothschild, Executive Chairman said, "We have delivered an excellent performance in a challenging environment and are now well ahead of the five year plan we set out in October 2019. This is a validation of an effective strategy which has created a resilient and diversified business. We continue to pursue a number of exciting organic growth opportunities, while successfully acquiring and integrating compelling acquisitions, leaving us well placed for the future."
Valuation - many thanks to Singers for crunching the numbers.
I find EPS easiest, which are (converted by me at £1 = $1.30)
FY 3/2021 actual: 23.1p (boosted by an unusually low tax charge)
FY 3/2022 forecast: 20.3p (this should be close to actual, as guidance given today)
FY 3/2023 forecast: 22.2p
FY 3/2024 forecast: 23.8p
Remember that Volex is acquisitive, so these numbers could be boosted with further acquisitions.
Whilst I’ve been typing the above, the market has opened, and Volex has shot up c.14% to 280p, so it makes sense to use 280p as my valuation share price. This gives us a PER of only 13.8 times for the year just finished, FY 3/2022. Dropping to 12.6 for the new year. This is obviously bargain basement territory, and makes this share a clearly attractive buy, even after this morning’s 14% rise. Obviously just my personal opinion.
My opinion - it’s a bargain! That’s assuming you think performance can be maintained. I don’t think we need to worry about cost inflation, or supply chain - Volex seems firmly on top of those issues, and might even benefit from competitors struggling, allowing Volex to expand its margins possibly?
I’m so glad I held the line on this one, and didn’t let fear of further losses induce me to panic sell. We’re in a very difficult market right now. Everything (almost) has dropped a lot, and we simply don’t know if that’s due to deteriorating fundamentals, or just the background noise of nervous holders selling through fear.
Decision-making is particularly difficult for all of us right now.
.
Naked Wines (LON:WINE)
374p (up 13% at 08:31)
Market cap £274m
This is an update for FY 3/2022, from this online wine retailer.
Company headline is -
Performance in-line with expectations driven by Repeat Customer sales, strong retention and demand from existing members
Revenues are only up 3% on LY (5% at constant currency). The suggestion is that demand was pulled forward by the pandemic, hence the 2 year growth rate is much higher, at +72%. I think that’s a fair point, as we’ve heard similar from many other online businesses. The interesting question is what level (if any) growth settles at longer term? Are these online businesses still in structural growth, or have they gone ex-growth? There might be an opportunity in this sector, as valuations of online companies are really bombed out at the moment, yet some might be demonstrating stronger growth next year, against softer comparatives maybe?
Various KPIs are mentioned, but these tend to distract me from matters - is this a viable, scalable business model? The growth potential from the USA looks interesting - obviously a huge market compared with the UK.
Profitability - the story in the past is that WINE has a highly profitable, long-term user base, which is uses to fund expansionary marketing spend. With growth now stalled to a snail’s pace, the jury’s out on that.
Today, it refers to “positive EBIT”, but only in “low single digits”
Balance sheet - a very large increase in inventories, to £143m, up £66m. Cash of c.£40m, presumably some or all of that might relate to customer deposits under the monthly prepayments programme (also used by Virgin Wines Uk (LON:VINO) )
My opinion - I’d need to see the full accounts, to see how it all fits together.
It’s difficult to see why today’s, in line with expectations update would trigger a 13% share price rise today. Maybe it just coincided with people being ready to buy, after a typical big fall which so many smaller companies have seen.
I’m mindful that Netflix dropped 20% after hours yesterday, as subscriber numbers fell. We have to watch out for subscription type businesses that are discretionary spending for their customers. Higher utility bills might make at least a few of WINE’s customers decide to cancel their subscriptions maybe?
Another point to beware of, is that it’s a lot more expensive to recruit new customers now, due to the internet giants grabbing the profits for themselves. Hence I would not be looking to buy into any online, subscription-based business right now.
.
Roland’s section
Carr's (LON:CARR)
Share price: 141p (-5% at 08.21)
Shares in issue: 94.0m
Market cap: £144m
“A robust performance in the period with full year expectations unchanged”
This agricultural supplies and engineering group has been a ten bagger over the last 20 years, outperforming the market by a country mile.
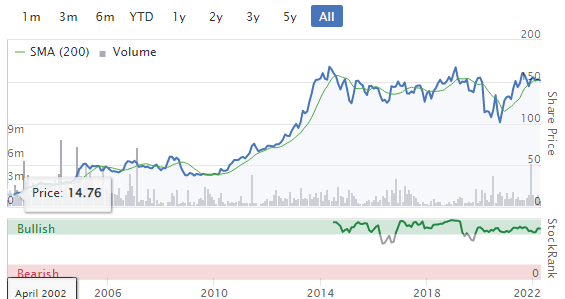
However, the stock has gone nowhere since 2014, while profits have also been fairly flat.

Carr’s has some attractive characteristics, in my view. But I see the lack of consistent growth as a potential risk. To consider buying the stock I’d want to see some signs of improvement. Do today’s half-year numbers provide fresh hope?
Note: Rather like Tate & Lyle (LON:TATE) - the former sugar producer - the supermarket bags of flour which bear Carr’s name are not produced by the company. The group sold its food division to Whitworths in 2016, “enabling Carr’s Group plc to focus on high value markets within Agriculture and Engineering”.
Financial highlights
Today’s half-year results cover the six months to 26 February 2022.
Carr’s numbers show strong revenue growth, but flat or falling profits, depending on your preferred measure of profits. This suggests to me that margins have come under pressure, presumably in the agricultural business.
- Revenue +10.6% to £222.7m
- Adjusted pre-tax profit -2.3% to £10.3m
- Statutory pre-tax profit -0.1% to £9.5m
- Adjusted earnings per share -8.4% to 7.6p
- Interim dividend unchanged at 1.175p per share
- Net debt up from £10.6m to £29.9m - a significant increase
Specialty Agriculture: Sure enough, the commentary flags up a “strong performance in Agricultural supplies despite significant raw material cost increases” (my bold).
A combination of volatile market prices and forward sale agreements meant that increases to sale prices lagged behind rising input costs during the first half. However, “cost and prices have since been brought into line” and the situation has stabilised.
Higher raw material costs are also said to have accounted for the majority of the increase in net debt, as more cash was needed to fund inventory purchases. Carr’s expects this increase to unwind during the second half.
Profits and margins from this business were hit hard in H1, but if the situation does reverse in H2 then this might not be a big concern.
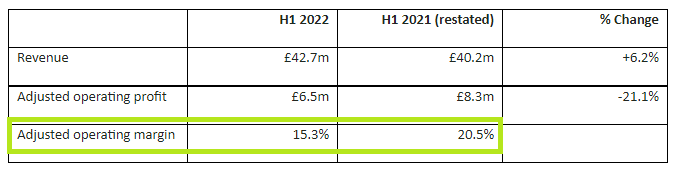
However, the company does warn that there’s some risk to volumes in H2 due to higher prices and drought in some parts of the USA (reducing livestock numbers).
Agricultural supplies: This business generated 71% of revenue, but only 36% of profit during the first half of the year. It’s a low-margin operation, but appears to have traded well during the period
Like-for-like retail sales rose by 4.1%, with total revenue up 15% to £158.7m. This included a new machinery branch opening.
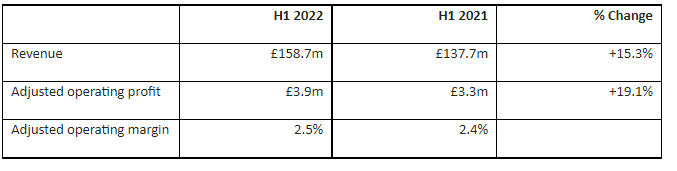
Solid, but unexciting. However, I can see opportunities for incremental growth through bolt-on acquisitions and new branch openings.
Engineering: Carr’s engineering businesses are focused on specialist steel fabrication, robotics and other engineering solutions for the oil, gas and nuclear energy sectors. They delivered an improved result compared to the pandemic-hit comparative period, but management say performance remained behind expectations.
Note the improved margins:
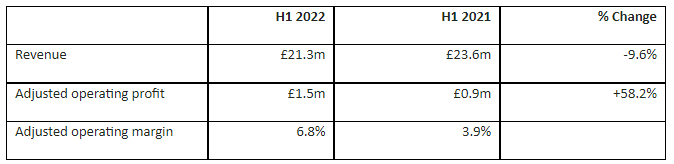
Checking back to H1 2020, revenue was £24.9m and adjusted operating profit was £1.2m. So the H1 2022 profit performance seems to be an improvement on pre-pandemic levels, too.
Stronger conditions in the oil and gas market are benefiting Carr’s and the company also won a new robotics contract in the USA.
The problem area seems to be the engineering solutions business, which is suffering delays and cost overruns on a defence project.
The order book rose to £44.2m at the end of February, an increase of 13.8% from the year end.
The numbers seem reasonably positive to me, albeit with limited visibility.
Strategic review: In January, Carr’s announced a strategic review of its three divisions to evaluate their growth potential. This is said to be nearing completion.
Balance sheet & profitability: As Paul has noted previously, this is quite a complex and capital-intensive business. Profitability varies widely between the group’s divisions and the balance sheet shows net tangible assets of £104m.
At a statutory level, profitability is low:
- TTM operating margin: 3.0%
- TTM ROCE: 7.3%
The sharp increase in net debt is also a risk, although I think the explanation (working capital linked to higher input prices) is reasonable.
These numbers don’t look too exciting to me. But as a long-term investment, Carr’s has proved a safe home for shareholders’ cash.
There’s also a useful forecast yield of 3.6%, backed by a very solid dividend record:
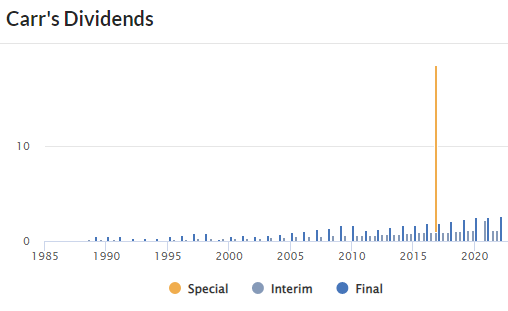
Valuation: Carr’s has left full-year guidance unchanged today. Based on Stockopedia’s consensus forecasts for earnings of 13.2p per share, that prices the stock on a modest 10.7x forecast earnings.
My view: Carr’s valuation looks very undemanding to me. The shares also offer a useful dividend yield.
Today’s results do flag up some risk factors relating to commodity market conditions and perhaps climate change.
However, Carr’s has been in business for over a century and has been listed on the London market for more than 50 years. It’s survived a variety of difficult conditions and appears to have some attractive operations in engineering and agriculture.
The ongoing strategic review could see the group reshaped to focus on higher growth/more profitable lines of business.
I’d consider Carr’s as a potential long-term value play, for a true buy-and-hold portfolio.
Severfield (LON:SFR)
Share price: 67p (+5% at 09.13)
Shares in issue: 309.5m
Market cap: £199m
“The group expects to deliver a full year result in line with management’s previous expectations.”
Today’s update from this structural steel group covers the year to 31 March and strikes a confident note. I’d guess it should be reassuring for shareholders, who’ve seen the stock fall by more than 15% over the last year.

Severfield’s operations are divided into two geographic divisions, UK/Europe and a joint venture in India. Conditions appear to remain positive in both the group’s main markets, despite some cost pressures relating to Russia’s invasion of Ukraine.
Full-year results are expected to be in line with expectations. According to Stockopedia’s consensus forecasts, this leaves Severfield shares looking potentially good value:

Let’s take a brief look at the commentary from each division.
UK/Europe: Back in November, Jack noted “some signs of customers delaying projects”. There’s no mention of delays in today’s update.
Severfield says that the company secured “a significant value of new work” in H2, resulting in a record UK/Europe order book of £479m at 1 April 2022 (1 November 2021: £393m). £382m is due for delivery over the next 12 months.
The order book is said to be well diversified across the group’s markets, with 96% for projects within the UK.
Management say they’re encouraged by levels of tending activity and are well positioned to take advantage of “some significant opportunities” in markets such as data centres, industrial and distribution.
Cost inflation and higher steel prices are said to be being managed effectively, with steel remaining “largely a pass-through cost for the group”. Although this statement is reassuring, it also makes me wonder whether Severfield’s increased order book may be due in part to higher steel prices, rather than organic growth.
India: Severfield’s Indian joint venture reports big order book numbers, but has not been very profitable historically (2021 share of loss £0.7m, 2020 share of profit £2.2m).
However, today’s update says that the JV is performing profitably and in line with expectations, after a difficult start to the year.
The order book has risen to £166m, from £140m at the start of November. 40% of this total is said to represent higher margin commercial work, with the remainder representing industrial projects.
Balance sheet: Severfield expects to report year-end net debt of £19m, excluding lease liabilities. The group recently refinanced its revolving credit facility, increasing it from £25m to £50m.
My view: Severfield shares look decent value on around eight times rolling forecast earnings, and the forecast yield of c.5% seems safe enough to me at present.
The main risk, in my view, is that we’ll see a cyclical slowdown in some construction markets as rising inflation and higher interest rates dampen growth. However, by targeting a diverse range of projects Severfield may be able to mitigate this risk.
Severfield is still a fairly capital-intensive business, but the long-term average ROCE of 10% seems reasonable to me and the balance sheet looks fine, following a refinancing a few years ago. If market conditions remain stable, then I think Severfield shares could offer decent value at current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
this is opinion. You have a choice. Statistically you will make the wrong one. It's close to crazy what I am about to say because the general consensus will be against me. And yet, you are wrong. If you understand this, you will see the opportunity ahead. If you don't, your world is probably going to be very negative for a lot longer than mine, but you will be comfortable that most people agreed with you.
I have no idea what you're saying. Sorry.
Thank you Paul for the write up on Volex (LON:VLX) (I hold).
I managed to not sell anything in my portfolio by dint of simply not looking at it! In size I hold Anglo Asian Mining (LON:AAZ) Sylvania Platinum (LON:SLP) Tremor International (LON:TRMR) Ergomed (LON:ERGO) Mpac (LON:MPAC) Bioventix (LON:BVXP) Volex (LON:VLX) Games Workshop (LON:GAW) Reach (LON:RCH) Somero Enterprises Inc (LON:SOM) and Boohoo (LON:BOO). All have had excruiating falls from their one year highs of between 74.4% and 17.8%.
The questions I have asked myself quite often over the past months are:
Are these good companies? - Yes IMO (and I include Boohoo (LON:BOO))
Is the market irrational? - Yes IMO
Is it frit? Yes IMO
Will these companies beat the market over the next five to ten years? I have no idea
Are these companies likely to perform satisfactorily to meet my goals over the next 10 years? I believe so.
I keep reminding myself of Ben Grahams phrase: “In the short run, the market is a voting machine but in the long run, it is a weighing machine.”
and
"Mr. Market is there
to serve you, not to guide you."
https://static1.squarespace.co...
Worth a read. And this phrase from the last paragraph:
"Indeed,
if you aren't certain that you understand and can value your business
far better than Mr. Market, you don't belong in the game."
Makes me ask myself another question!
With all that said it has not been easy but I learnt a lot from my total meltdown in March 2020. I just wish I had learnt the lesson a lot earlier.
Regards
Michael
I think every investor should read the intelligent investor by Benjamin Graham. This is not a book for traders, speculators or gamblers unless they want to change as they will most likely be offended.
Absolutely. And if you can't get through the whole thing Buffett says that chapters 8 & 20 are must reads. Personally I loved the book and will re-read after reading Security Analysis, which I am finding very hard going but I think it is warming up as I get into it!
I would disagree tough as I think it is very much a book for "traders, speculators or gambler" as it may stop themselves on what is, for MOST, a futile path -
"The Financial Conduct Authority has studied a sample of spread-betting customers and found that 82% lost money on products offered by the industry..."
https://www.theguardian.com/bu...
Regards
Michael
"Will these companies beat the market over the next five to ten years? I have no idea"
Then why not own the market instead? By owning a small number of stocks, you are taking a huge risk that you don't need to. Studies of long term returns in the most successful stock market in the world (the US) showed that between 1926 and 2016, more than 50% of stocks had negative lifetime returns. Just 4% of stocks accounted for 100% of the wealth created by the market. Just imagine what the results are for some of the less successful markets e.g. AIM.
The majority of professional stock pickers underperform the market. The average amateur probably does worse. If you rely on stock picking, your success depends on finding a few needles in the haystack and you start with the odds against you.
You have objectives, so why not think through whether an investment in the market index can meet those objectives. If it can't then maybe it's wise to re-think the objectives. If it can, then why not do it?
90% of Male swedish drivers think they are better than the average. This fact, Charlie Munger describes in his almanac, is very relatable to the private investor. To get yourself into the 10% you have to have an edge. Your circle of competence and your knowledge of it so you don't go outside that, gives you your edge.
90% of Male swedish drivers think they are better than the average. This fact, Charlie Munger describes in his almanac, is very relatable to the private investor. To get yourself into the 10% you have to have an edge
I really don't want to be in the 10%. I would imagine that the 10% who think they are worse than the average are probably quite bad (or they're depressed, but that's a different piece of research).
The point that Munger was making is that most people - especially men - tend to be overconfident about their abilities. Hence people trade too much - remembering that every trade is an opportunity to make a mistake.
Munger's edge, of course, is to be brilliant and not make too many mistakes. The rest of us need to spend more time with the Highway Code:
https://fs.blog/great-talks/ps...
timarr
buy the book. It's a great read. Expensive for a book, invaluable as a tool.
buy the book. It's a great read. Expensive for a book, invaluable as a tool
To quote from my copy:
"How many of you have fifty-six brilliant insights in which you have equal confidence? Raise your hands please. How many of you have two or three insights that you have some confidence in? I rest my case".
timarr
men? I only see men here. We are in an echo chamber
Thx cmpeckham. Firstly, it is impossible to say whether a company will beat the market over the next x years, so it was a statement of fact but one works with probabilities. I believe they will be otherwise I wouldn’t be in them.
Your comment in your second paragraph is interesting because that is precisely what I am doing. I am pivoting the portfolio so that will own:
BRK.B - 25%
VUSG - 25%
Large Tech - 12%
Balance small caps
The timing is flexible but the aim is to have the portfolio structured like this over the next couple of years.
As to my own returns I am reasonably content with them but it has been a tough two years of Covid for various reasons but the full picture is:
31/12/2008 -7.10%
31/12/2009 27.40%
31/12/2010 9.10%
31/12/2011 -16.40%
31/12/2012 4.50%
31/12/2013 76.00%
31/12/2014 -24.20%
31/12/2015 16.00%
31/12/2016 30.70%
31/12/2017 36.40%
31/12/2018 -11.60%
31/12/2019 27.00%
31/12/2020 0.00%
31/12/2021 -15.30%
This is give or take an 8% return (the long term rate on the S&P) but achieved at much higher risk. Up until 2019 it was closer to 11.2%.
Very volatile, which is what I would like to reduce.
Regards
Michael
Hi Michael,
I learnt a lesson in 2021 (the hard way) regarding cutting my losses, and one of the stocks I learnt the hard way was Volex (LON:VLX) when I was left with a small profit after watching a large profit disappear.
I try now to cut losses a bit sooner and try to maintain some winners once they drop a certain amount from their highs, but I still get too attached to some stocks and watch them slowly shrivel up and lose their flowers. For example, I am still holding Hostmore (LON:MORE) despite it being 44% down on my average price.
Another is Gear4music Holdings (LON:G4M) which I probably should never have bought but was tempted in by the story. Also I hold onto a small holding in Baillie Gifford Shin Nippon (LON:BGS) but I class this one as more of a "hang on and use it as a reminder to watch it and buy more once it turns".
It's a constant debate in my mind as to whether to get out of falling stocks or just wait for the good times to return. I remind myself I am a longer term investor so shouldn't worry, but its difficult to watch your investments keep falling day after day - I am trying to be more ruthless, but its a constant battle.
Good luck with your holdings. I seem to get the feeling that there maybe a bit pore positivity around at the moment and things may not be all gloom and doom. Results are frequently good, and the inflation threat looks like it might peak in the next 12 months - wishful thinking maybe, but I try to remain optimistic.
Best. K
Thanks Kevin.
I sold out of almost everything on March 19th 2020 when I was down from the portfolio ATH by about 45% and I clawed my way back to break even for the year. (If I had done nothing all year the portfolio would have been up 36%, so a very expensive mistake)
Yes I should have top sliced (as I have done with Ergomed (LON:ERGO)) but I am as convinced as I can be that this is not the time to sell. I think these are good companies that I am happy to be invested in.
Regards
Michael
Thanks for your settling report on Volex Paul, we're in after reading one of your earlier reports on the company and Nat Rothchild is a mover and shaker adding excitement.
I appreciate your comments on Carr's today Roland, it's one we've held for a long time and after reading your report will continue to do so.
There seems to be lots of fear out there at the moment. Only have to see the declining number of comments here or the scaling back of private investor interest in presentations, twitter comments, retail short positions, cash levels or investment fund outflows. Majority is very bearish.
If you're of the contrarian persuasion tho this should all be music to your ears.
I like to think of it as a buyers market, which is good for me as I am a net buyer of stocks and a dedicated follower of the principals set down by Benjamin Graham and adopted and refined by Warren Buffet and Charlie Munger. As I have over a decade before I need to sell anything, this is my time to buy and the general sentiment is overly pessimistic, which is great for me. History favours the optimists in the long term whenever this has happened. That or we are all doomed. I have nothing I want to sell, and lots I want to buy. I sometimes wonder how long this pessimism will last, but mostly I try to envisage what the companies I own and want to own will be doing in ten years and this makes me very optimistic. It has been a revelation in human behaviour watching how the meme stocks have shaped and how everything comes back to fundamentals in the end. As the great Wazza once said, the markets are a voting machine in the short term and a weighing machine in the long term.
Just to add - in case people are wondering what I am buying - Team 17, Alibaba, Prosus & Boohoo. Holding Berkshire Hathaway, Arista technologies, Facebook, Beazley & B&M supermarkets. Wanting Google to go down by circa 10% and then I will also be a buyer. Happy researching everyone and wishing you make the right decisions so you all sleep well.
Interesting Mark and thanks for sharing. It would be interesting to get your views on Team17. They have had some awful PR this year which has brought into question both the ability and behaviour of senior management. This triggered me to sell as I lost confidence in them. Perhaps I was wrong ?
Does this business fall within your circle of competence? I have been in IT for the last 23 years professionally and an engineer before this. I think I have an edge in this business. Do you have an edge can give you conviction when things go wrong? For me it's an opportunity as this unfortunate management decision will pass and be corrected. If you trust management, which is integral to my buying process, they are correcting and I am a big fan of Debbie and believe she has learnt from past mistakes and will probably make more in future but the aggregate of good and bad decisions will be far in away on the positive side.
are you a business owner or just an owner of a ticker symbol in the market. Investor, trader, speculator, gambler. If you don't know, you are a gambler. I'm going to get hate from this but if spend time researching you will change.
To echo Paul’s comments. I have been a long term holder in Volex and with the recent decimation of the SP have been close to banking waver thin profits. Experience has finally taught me not to overreact and stay invested. Quality counts.
The market seems to be looking at a wall of fear at the moment.
Noted the reaction to £RNO when its recent TU came out . Big recovery from a SP drift caused by fears which the TU pointed out were more or less unfounded.
Decided to add starter stakes in:-
Volex (LON:VLX)
Severfield (LON:SFR)
Brickability (LON:BRCK)
Centralnic (LON:CNIC)
The first two are working at the moment - so I'm probably tempting fate here - I'll have to see what happens to the updates arrive.
I'm not saying these are the best - they were just ones I selected from my watch list as fitting the bill.
Phil
I’m mindful that Netflix dropped 20% after hours yesterday, as subscriber numbers fell.
Not very relevant to the SCVR but interesting to note that later today the Netflix share price will be below that at the outset of the pandemic while the quarterly EPS just announced is only a bit less than that of the entirety of 2019.
timarr
When a share is on a PE of over 50 it has to keep growing at a fantastic rate. Looks like the market thinks Netflix has had its day and Im inclined to agree.
Probably a good time to buy the likes of Netflix and Meta soon. Meta is on a P/E of 15 according to a quick Google search.
Meta - possibly a buy given its very dominant market position. Not sure about Netflix though as getting extremely competitive in that sector and streamers having to spend ever more on creating new content.
I read a report recently that many people were stopping one or more streaming service due the rise in cost of living, so I think all of them will take a hit this year, believe Amazon has report a drop in their streaming services.
Dominant? You haven't seen the numbers showing that Tiktok is #1 last year in global traffic....
There are many of us looking at shares and wondering why they appear to be such a "bargain". Of course not all of them are. Just because a share has fallen dramatically does not make it a "bargain".
For me the share that looks a bargain to me is Unbound (LON:UBG) (I am building a stake)
If they hit their forecasts for 2023 and 2024 the price is a "bargain"
Analyst price target is almost 3x current price
Price to Tang is 0.59; Market cap £13.6M, NAV £23.1M
More than one director has been buying recently
New partnerships with M&S, Next and others.
Flagship product is shoes which are not really a discretionary spend (or at least you would forego a meal out rather than a pair of shoes).
Share price qualifies for 3 respected value screens
I do question whether the Stockopedia information properly reflects the recent changes to the group otherwise I cant see what I am missing?
Revs8 agree it does look interesting. The only negative I can see is the market cap at £14m. Cannot believe it is easy to build a stake.
I agree Revs8 Their detailed financial report released on 7th April makes for good reading.
https://unboundgroupplc.com/fi...
I wonder if Paul Scott has cast his eyes over this report yet.
I also understand that they have other brands in the pipeline and will be announcing a new website this summer.
The price rise today is promising, but the market is so illiquid that even my small purchase moved the needle this morning :)
Keeping a close eye on Unbound (LON:UBG) And I am hoping to make back some of the losses from the ELTA mess!
It will be interesting to see if there is any profit taking after todays price rise. If not then it could indicate that the sellers are done for now.
several of my small caps testing resistance today. Signs that buyers are returning?
Paul, thank you for the update on Volex (LON:VLX), which I have held for 3 years or so and have added to recently. Some rare good news in terms of share price movement in the field of UK small caps. On the topic of increased bank facilities, which you mention in respect of Volex (LON:VLX) I wonder if the same might apply to Supreme (LON:SUP) the share price of which was battered by the recent trading update.
I also hold Supreme (LON:SUP) and added after the update as I considered that the share price fall was an over-reaction. Anyway the following is the final paragraph from the outlook statement of the update. The investor presentation this Friday hosted by Equity Development should hopefully help shed further light on current trading and strategy.
"The Group remains fully focused on driving organic growth, closely balanced with strategic acquisitions, having agreed a new £25 million RCF facility with HSBC in March 2022".
All the best
We spend a lot or a little as time allows on deciding. I hold Volex (LON:VLX) and Supreme (LON:SUP) and appreciate Paul's comment "held the line". Did the fundamentals change enough to make the business something else or just macro 'noise'.
If I'm taking pain then always take some (saddo) comfort in that the institutions are hurting far more than me.
"Decision-making is particularly difficult for all of us right now." Totally agree with that!! Are we still in an environment for stock picking? Surely the macro issues, Ukraine, Interest Rates, Exchange Rates (John Authors this morning), Bonds all point to a major upheaval? I am going to make a cup of tea and try again today.
It's always a difficult time to pick shares! At least we appear to have valuations on our side at the moment.
Severfield (LON:SFR)
Reassuring in-line TU after SP has been taken down a lot - along with most small caps.
Big expansion in order books (already have orders for delivery in the current year in excess of forecast sales) and the Indian JV back to profitability after a couple of difficult covid impacted years.
Has a very safe 5% yield on this basis.
Phil
(I hold)
Volex (LON:VLX) Singer have a note out today. "We have revised our PT to 325p (390p) reflecting the change in sector multiples and maintain our buy recommendation."
Canaccord have given Volex a 510p PT this morning
From what to 510p Josh?
Paul.S "From what to 510p Josh?" I had to find a previous post of joshwood976 to find it was a TP for .Volex (LON:VLX) - please remember half the ways of reading this are not threaded.
Anyway, I have found the answer and hardly earth shattering. I laugh quite often when brokers change these by insgnificant amounts, in this case 10p, as if the market is such an exact science!
Thanks sharw...great info. As you say the figures are much less important than the amount of change...in this case....nowt.
Thanks again
Paul
Tatton Asset Management (LON:TAM) AUM ended FY22 (31 Mar 22) on £11.3bn, +26% y-o-y (31 Mar 21: £9.0bn), in line with our previous forecasts. But more impressive, from a longer-term strategic perspective, is the fact that ‘organic’ net inflows of +£1.28bn exceeded our forecasts to make up for an investment performance which was hit by the market turbulence of Q4 (Jan-Mar 22). In fact, net inflows in H2 almost matched H1 (£625m vs £652m).
Tatton has also entered into an agreement to acquire 50% of 8AM Global Limited (8AM), for c£7.0m (£3.5m payable on completion, funded through the issue of new shares, plus two performance-adjusted payments after 12 & 24m). Tatton will have an option to acquire a further 50%. This appears to be a solid strategic fit and in line with Tatton’s acquisition strategy.
Our bullish view on Tatton’s fundamentals remains unchanged, as do our forecasts, other than a small adjustment to FY22 AUM to match the actual closing value. We maintain our fundamental value of 560p per share1 which is around 30% above the TAM share price following its recent fall, although we highlight the fall is not unique to TAM, with ‘growth shares’ generally hard-hit in 2022.
https://www.equitydevelopment....
A great trading update from Coral Products (LON:CRU) this morning. Sales and PTP “materially above market expectations”. A second interim dividend of 0.4p, and an extra £500k cash in the bank.
A positive update from Naked Wines (LON:WINE)
Group sales increased 5% YoY on a constant currency basis (3%
reported)
●
On a two-year basis, group sales increased 77% constant currency
vs continuing operations in FY20 (72% reported)
●
Sales retention was 80% (vs mid 70s guidance)
●
Repeat Customer sales increased 13% YoY on a constant currency
basis (11% reported)
●
Active Angel base increased 9% YoY to 964k in FY22
●
Adjusted EBIT was low-single digits
●
Year-end cash was approximately £40M
●
Year-end inventory approximately £143M, up £66M vs FY21
Why is Inland Homes (LON:INL) buying back shares when the whole purpose of the company for many years has been to reduce debt to manageable levels?
To hit Directors bonus targets? WFH and finding little else to do? Truthfully, I just don't know but can't help being ever so slightly cynical.
I hold Inland Homes (LON:INL)
despite being tipped by Simon Thompson since time immemorial Inland Homes (LON:INL) has failed its shareholders. For a long time. Big salaries at the top despite debt. They massacred the dividend and now are trying the buyback. I sold out years ago but still follow. ‘One day’ management.
Re Inland Homes (LON:INL) Was there any explanation given of Gary Skinner's termination?
Good update from Volex (LON:VLX) (I hold), ahead of expectations, on an 18 month low SP. Is it time for this recent disappointer to shine? Its a great chance to have exposure to the coming age of the electric car, if they stop issuing shares and focus on what they do, they could well fly,
Hi Paul.S
I think it's a red herring to assume that share issuance is automatically a bad thing. It can be, true, but in the case of Volex, there were 2 things relating to dilution -
1) The original turnaround a few years ago (it had previously been very badly managed), and
2) More recently, making a series of sensible, disciplined acquisitions, which all seem to have gone very well.
The Exec Chairman owns about 25% of the company, so is not going to dilute himself without good reason.
The key figure to ascertain if dilution is good or bad, is surely EPS? In the case of Volex it's impressive, going from about 10c to almost 30c in the last 4 years.
Regards, Paul.
Thanks for the write-up Paul. Renold (LON:RNO) and Volex (LON:VLX) are good examples of the market over-selling on abstract fears - maybe there are good trades to be had right now in buying just before news if you have the confidence in the company?
Interesting you say that Patrick as I did exactly that with Volex which according to a couple of sources had results out on the 4th April, and from me buying in on the 1st April to yesterday managed to go down a further 12% ;-0. Cant win them all I guess.
Thanks Paul, your points are well made. I recently added Volex to my portfolio and the share issue stood out to me as a potential red flag, thanks for the clarity.
I would like to long term hold this, as I do see the growth potential large, but like many am worried about the raw material price squeeze. They certainly give the impression of being able to dictate pricing which is again reassuring.
It looks very cheap to me even after the hike today, but like many manufacturing small caps they are out of favour...am thinking Tyman, Morgan Advanced, Bodycote, Somero...I just don't get the current valuations.
Remember that manufacturers aare very prone to inflation risks.
Hi Paul.s
On Volex (LON:VLX) (I hold) I read a similar comment as yours somewhere else:
"if they stop issuing shares and focus on what they do, they could well fly."
But I am perplexed by it. Can you explain?
According to Sharepad they have issued the following:
2014 - 27.9m shares issued
2015 to 2018 no new shares issued
2019 - 46.7m shares issued
2020 to 2021 no new shares issued
The big placing was to facilitate the purchase of Silcotec announced in May 2018.
I first bought January 2021.
Am I missing something?
Regards
Michael
Hi Michael
Am simply going of Stocko's figures TBH, which could be wrong perhaps?
They have gone from 89 million in 2016 to 164 million as of today, which Stocko averages out at 11% per annum.
TBH that is fairly high for a long established (value) business IMO, and fair enough if the money is being used on acquisitions, but is (or perhaps was) the revenue, profit and SP reflecting that?
Could some of that growth been achieved organically?
Absorbing companies into your business is not always easy as am sure you know, and i have always been a great believer in wringing every last ounce out of your own assets, your own clients, as well as growing organically. (Maybe i was a slave driver).
I just felt in the six months i have been following them that that was a part of the problem, (stretching management by absorbing these companies) but TBF I am no expert in any of this...I am just not a big fan of dilution, but TBH I tend to stick to value stocks so my eyes go out on stalks when I see more than 5% on Stocko!
I hope that makes some sense, as I said its just my thoughts and am really happy Volex as put the money to good use!
BTW I have held them for a few weeks now, so my rules are more a set of guidelines clearly ;-)
Volex (LON:VLX)
To be honest volex was probably a bit of a basket case share back in 2018 - i really think any comparison of where the business was then compared to where the business is now is meaningless - obviously things needed to change back then and the raising of £36.00 million pounds by issing 48 mill new shares at that time was a really material event.
If you judge the company on what it has done since raising that cash and diluting shareholders at the time then the proof of the pudding is a most tasty feast. They raised funds when shares were at probably under 80p a share and 4 years on the shareprice is not far of trebling. I doubt you will find any long term shareholders who see that large dilution as generating anything other than fantastic results for shareholders. in summary that was a material event and should be judged on its own merits from that bygone era the end results being fantastic - anyone who didnt want to be diluted could have stumped up more cash and been well rewarded with the investment that was made at that price.
If we look at the last 3 years the increase in shareprice has been very non material - that being the case i would say giving the impression that they are issuing new shares at 11% a year is highly misleading -with regard to recent past Note as the shareprice is that much higher now a similar raise would create a fraction of the dilution that that "material event created"
Could they have succeeded without that capital raise and acquisition in 2018 - who knows they always had decent "turnover" - but facts of the matter they were going nowhere did that big raise and their fortune turned for the better soon after so one has to say their plan of attack has certainly worked very well and they have kept later dilution to vey manageable levels.
I used to post on here that this company was complete basket case (nearly £2 bill of sales over approx 6 years making nil profit !) - i kinda guessed at first they may have got lucky when trading started to pick up but i must say management had hardly put a foot wrong since 2018.
Someone really needs to research their moat - how difficult to replicate a 'cable'. Ok a nice reliable cable and none of that cheapo copy cat stuff which melts when we turn on the bitcoin mine. Bit like ceramic brake disks - just not so sure can defend the castle. Thanks to Paul.S flagging up the share issues for growth as a contrarian view. Volex (LON:VLX) look a safe hold but not buying more. Sorry don't have time for DYOR - momentum follower.
Thanks for the info rmillaree, I appreciate it...you have been around this game much longer than me, and yes I agree seems the share issue was required, and winding the clock back as been good value.
If they have as much pricing power as they suggest in the resent RNS then they indeed seem to have some kind of moat, but would like to see a little better operation margins, although i guess it keeps the competition out!
Thanks
Paul