Small Cap Value Report (Wed 20 Dec 2023) - DPEU, GDWN, MEX, TMG

Good morning! Graham here. We have several interesting updates to look at today.
That will do it for today (1.20pm). Thanks for dropping by!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Thanks to everyone for your helpful comments yesterday, especially on Cavendish Financial (LON:CAV). Since I've been positive on this one for a while, I wasn't unhappy to see that the shares were up by c. 20% by midday!
DP Eurasia NV (LON:DPEU)
- Share price: 95p pre-market (+8.5% yesterday)
- Market cap: £139m
We've had further developments in the attempt by DPEU's major Indian shareholder to take it private.
See our coverage earlier this month, when we reckoned that the surprise 85p bid was "the bare minimum".
Jubilant Foodworks, up until recently a 49% shareholder, has increased its stake further to 54.67%.
Even if it had not already signalled its intention to bid for the company, its further purchases would have triggered a mandatory bid anyway.
Let's get up to speed on the latest state of play.
Dec 5th: DPEU's management reiterate that they are "extremely disappointed" that Jubilant went public with a bid instead of approaching them first. They go on to say:
The Board has evaluated the Jubilant Proposal with its advisors and believes the financial terms fundamentally undervalue the Company and its prospects.
The Board has received feedback from a significant proportion of the Company's shareholders, indicating that they are also overwhelmingly of the opinion that the Jubilant Proposal fundamentally undervalues the Company.
I agree! Each DPEU store was being valued at only around £180k (roughly speaking, the 85p bid is an attempt to buy c. 700 stores for £125m). That compares to a market value of £1.2m per store in the UK and Ireland (we'll speak more about relative valuations in a minute).
Dec 19th: Jubilant goes public with a higher 95p bid, "following consultation with DP Eurasia's shareholders" (I note that they say shareholders, not management!)
Other major DPEU shareholders include an individual investor based in the Cayman Islands, and a US-based hedge fund.
The new 95p bid raises the valuation to £139m although Jubilant is already a majority shareholder, so it would only have to pay a fraction of this.
The new bid is a 38.7% premium to the share price just before the original bid announcement. This strikes me as being a more normally sized premium to pay over a prevailing share price.
Dec 19th: DPEU management respond to the new bid as follows:
...the non-conflicted members of the board of the Company (the "Board") have determined that [the 95p bid] is significantly below what they consider to be the fair value of the DP Eurasia business and its prospects, particularly considering its continued strong performance as detailed below.
I imagine that the atmosphere is a bit prickly on the board now, as the DPEU board members who are not affiliated with Jubilant are taking the opposite stance to the "conflicted" Jubilant representatives!
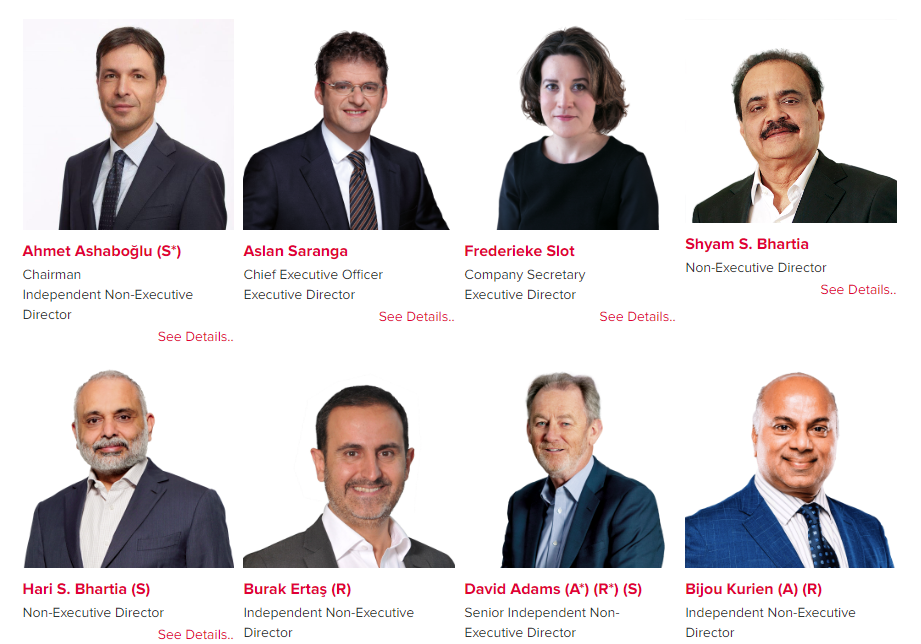
The entire DPEU board is shown below. On the top right and the bottom left are the co-Chairmen of Jubilant:
The Dec 19th announcement by DPEU also raises profit guidance:
- now expects to marginally exceed EBITDA guidance of 696 million Turkish lira (this guidance given recently, on 28th November).
- FY 2023 EBITDA now expected at 713m Turkish lira (c. £24.1m).
- FY 2024 EBITDA expectation is 1,245m Turkish lira (c. £30.7m).
- FY 2023 year-end net debt expected at 653m Turkish lira (c. £17.8m).
Based on the above, they provide valuation multiples for their international peers:
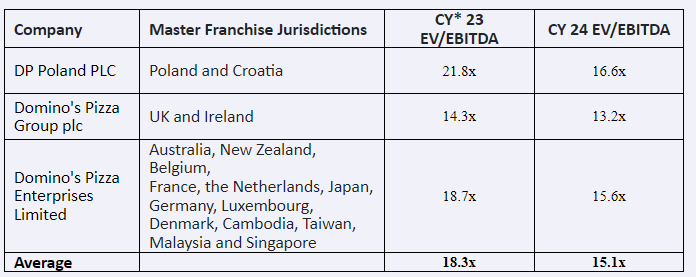
They then compare this to the valuation at the 95p bid:

And also to the valuation of Jubilant Foodwords:

As you can see from the above, DPEU is rated much more cheaply than its European peers, even at the higher 95p bid, and despite the very high expectations for EBITDA growth next year.
Jubilant's StockReport can be found here, if you're interested.
DPEU's board acknowledges that the hyperinflation in Turkey does complicate this analysis, and that the economic situation in Turkey could justify a lower valuation for DPEU compared to its European peers. But they still argue that they are being undervalued at this level.
By doing a store count, I came to similar conclusions earlier this month in the SCVR, noting that a DPEU store was being valued at one sixth of the value of a store in the UK & Ireland.
In EBITDA terms rather than in terms of store count, the valuation discrepancy is less extreme, but DPEU is still only being valued at around half of the UK & Ireland (based on current year earnings).
And given the growth prospects for next year outlined above, the discrepancy doesn't seem to be fair. But then there are additional risks in Turkey (especially political risks) that are more difficult to analyse from abroad.
Wrapping up, the DPEU board has this to say:
The Company suffers from extremely limited minority protection rights in takeover situations due to the fact that it is neither subject to the United Kingdom's Takeover Code nor to any EU takeover provisions despite its listing in the United Kingdom and being incorporated in the Netherlands. In addition, despite being a good commercial partner, Jubilant has sought to exploit this to its advantage by seeking to take full control and de-list the Company without offering fair value, to the detriment of minority shareholders. Furthermore, by virtue of its representation on the board of the Company, the Board believes that Jubilant is well aware of just how much growth potential exists.
20th December: Jubilant have hit back today, defending their offer as fair based on "historic share price performance, DP Eurasia share liquidity, a peer group of comparable quick service restaurant companies, the wider macroeconomic environment and intensifying competition in Turkey".
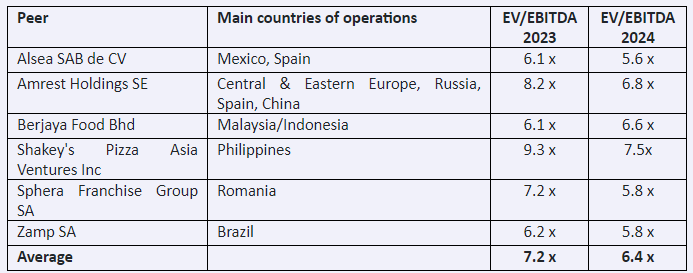
They also point to the valuations of emerging market peer companies:
Graham's view
Jubilant have made a strong argument that emerging market fast-food stocks tend to trade at cheaper multiples. However, I imagine that most DPEU minority shareholders (I used to be one myself) are involved for the potential re-rating that would occur when DPEU becomes solidly profitable, reduces its leverage, and the economic situation in Turkey stabilises.
DPEU shareholders are also more likely to think of Domino's as a premium brand that is worth more than, for example, Burger King (one of the brands operated by companies in the table published by Jubilant).
And for whatever it's worth, the DPEU IPO was at 200p all the way back in 2017:
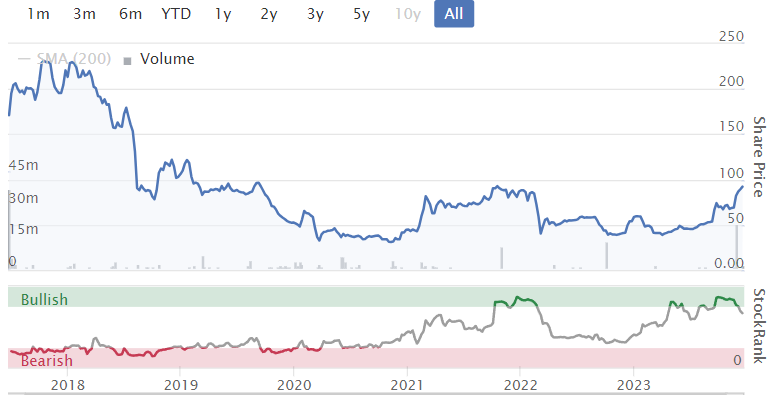
Since then, despite all the struggles that the company has experienced, it hasn't diluted its shareholders and the share count is virtually unchanged.
Russia turned out to be a disaster but growth has been seen in Turkey and recent positive updates suggest that it might be about to generate some genuinely strong financial numbers, with excellent short-term growth prospects.
There are some risks that concern me, however. In particular, there is the risk of a delisting. Jubilant could attempt to cancel the listing even if they don't succeed in a full takeover. If they had 75% of the votes, it is something they could achieve, leaving minority shareholders without any liquidity and perhaps in a precarious situation, holding shares in a private Dutch company.
Therefore I'm going to stick with a neutral stance here, for the simple reason that the majority shareholder doesn't want to keep the listing. For investors who don't care about liquidity at all and don't mind the possibility that they could find themselves holding shares in a private company, maybe holding on here would make sense. Personally, I would learn the lessons from the experience and get out at 95p, even though I think this price probably does undervalue the business and its prospects.
Goodwin (LON:GDWN)
- Share price: £54.24p (-8%)
- Market cap: £407m
Paul look at this engineering group's full year results in August.
Today we have interims. Key points:
- Revenue £97.6m (H1 last year: £89.3m)
- Pre-tax trading profit £11.2m (H1 last year: £9.1m)
Note that Goodwins has two divisions - "Mechanical" and "Refractory". Within these, there are a large number of capabilities and operating subsidiaries. Feel free to explore them here.
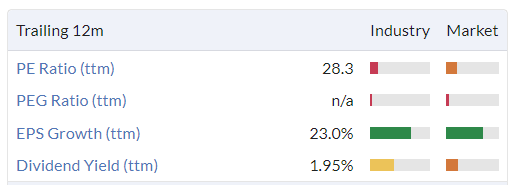
As mentioned by Paul in August, Goodwin's large order book seems to be a key reason for the punchy valuation:
On that point, the outlook for the rest of the year sounds good, the company saying:
...we anticipate a continuation of this increased performance for the rest of the financial year, with a current forward order book of £266 million.
The order book was last reported at £271m, so perhaps it is stabilising a little? Although it's hard to read much into a six-month movement. Also, revenues could keep growing for a while even if the order book stabilises, as orders are fulfilled.
On orders currently being received, the company says: the slow pace of third party decision making has been a source of frustration. Nevertheless, we are well prepared to capitalise on these opportunities as they arise.
As the company works through its orders, it has seen a temporary drain of cash. Net debt rises to £54.6m (a year ago: £46.1m), which is said to be in line with expectations. The gearing ratio is therefore 47.8%, but this is expected to fall back to 30% within 18 months.
One key product owned by Goodwins is AVD, which has been designed specifically to extinguish fires caused by lithium-ion batteries. In a world of mass adoption of electric vehicles, this is a useful invention! Here's the latest exciting news on this product:
There is ever-growing interest and adoption that extends way beyond the automotive sector, encompassing a diverse range of applications worldwide. To support this demand, proactive measures have been taken to expand AVD manufacturing capacity. The Group has acquired a 2.5-acre site with a 5,000 square metre industrial building, conveniently located close to Dupré Minerals Limited's primary manufacturing facility in Staffordshire. The site is ready for immediate use with the planned commissioning date of the new, higher-capacity AVD manufacturing line set for April 2024.
Shareholder relations: Goodwins strikes me as having the culture of a private, family-owned business (as previously highlighted by Paul, most shares are held by insiders and their relatives). However, as its valuation has increased, it perhaps needs to start acting a bit more like a conventional, publicly-listed company. This means longer and more frequent reports for shareholders. The Chairman says:
After due consideration, from listening to shareholder enquiries at the AGM, we recognise the importance of providing more frequent updates. Considering our Group's diverse and complex operations, we have decided to introduce quarterly trading updates to keep our investors more informed.
I'm sure many US companies would be amazed to learn that there were UK companies who had to be persuaded to published quarterly updates for their shareholders!
Outlook
Here's an excerpt from the outlook statement:
The Group's increased levels of activity that have occurred in the first half of the year are expected to continue throughout the second half of the year, generating a similar level of profitability as was achieved in the first six months...
If a few of the notable contracts that are expected to arrive over the coming months do not get delayed again for the Mechanical Engineering Division, the forward workload will be further increased by the year end.
Graham's view
The main point for me going into today's results is that Goodwin was already on a hefty PER, so any shakiness in the outlook could have a negative impact on the share price. That's the context in which we have an 8% fall today.
The order book should increase again by the end of the year, but it's clearly possible that it won't, if there are further delays from Goodwin's customers. So if we end up with an order book that hasn't grown for a year, it might be more difficult to justify a PER of nearly 30x.
The net debt position also makes for a share price that is more sensitive to any doubts on trading performance. In isolation, today's cash flow statement isn't very good - there is negative net cash from operations, due to large increases in receivables and "contract assets" (economically similar to receivables). On top of that outflow, there was modest capex. Hopefully the cash performance will improve very soon, as indicated by the company.
Goodwin moved up the risk spectrum in H1 by borrowing an additional £12.5m and paying out more than that amount to shareholders in the form of buybacks and dividends.
Therefore, while I don't doubt that this is a company with excellent culture and heritage (going all the way back to the year 1883!), and it has a tremendous track record of profitability, I think the valuation and the risk profile might be in territory where the shares will be vulnerable to any trading setbacks and where new investors at the current price might need to have a great deal of patience.
In general, I expect to see engineering companies trading at modest or even below-average multiples. With Goodwin, I do see mention of intellectural property and interesting patents. Along with the track record and the positive culture, I'm inclined to think that it's worth a considerably more expensive rating than the average engineering stock. But I would be neutral at the current level.
Please note that there is still no proper analyst coverage of this stock, so it is left to us to come up with our own forecasts of future performance.
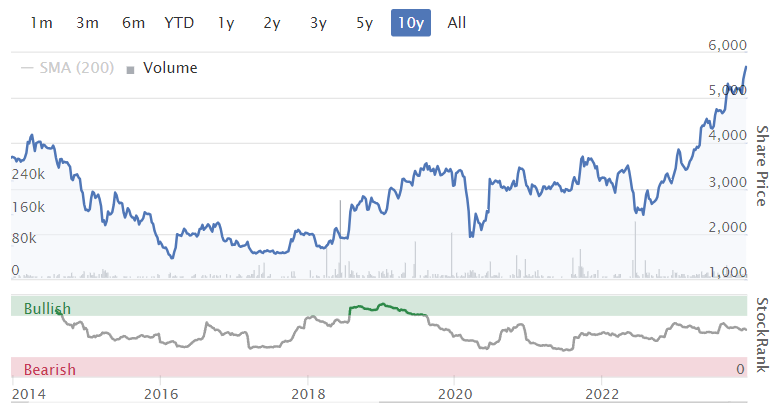
Tortilla Mexican Grill (LON:MEX)
- Share price: 49.05p (-11%)
- Market cap: £19m
Tortilla Mexican Grill PLC, the largest and most successful fast-casual Mexican restaurant group in the UK, provides a Trading Update for the financial year ended 31 December 2023 to date ("FY23" or the "Period").
This is a 2021 IPO, a restaurant chain with 87 sites.
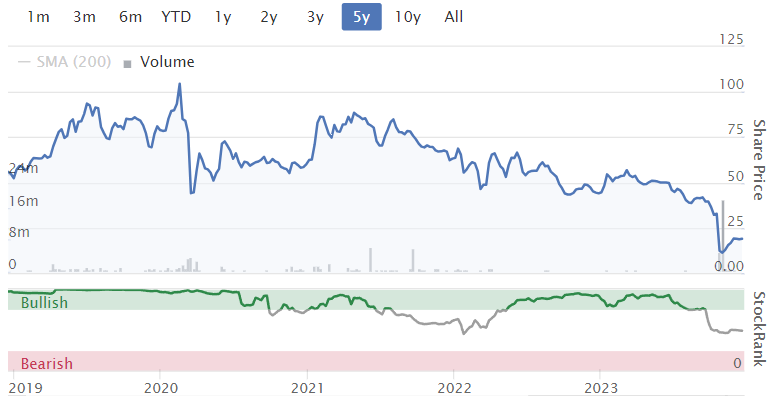
Its share price performance is predictable enough:
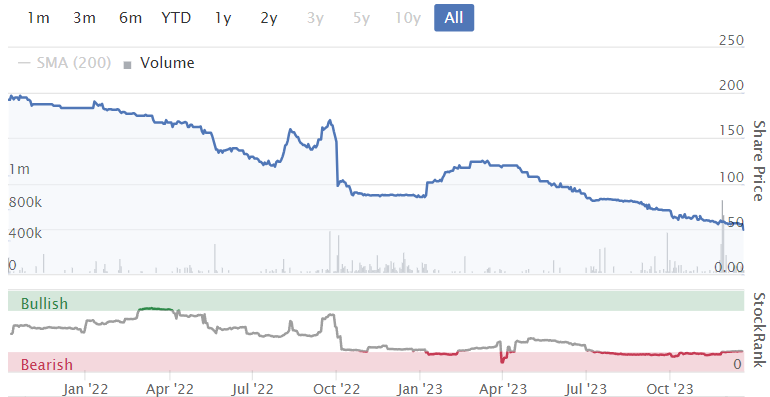
Paul last covered it in July. Today brings a trading update for FY Dec 2023.
Key points:
- Revenue +13.8% to £65.7m, but UK life-for-like growth is more modest at +3.7% (or +5.0% adjusting for VAT).
- Performance is slightly behind previous expectations due to subdued consumer confidence, particularly in Q4.
- Underperformed on high streets (lower footfall) and in smaller tertiary towns and cities where brand awareness is lower.
Deliveries are stable at 31% of total revenue. Margins were impacted by partnering with multiple delivery companies. This strategy is under review.
Overall, the adjusted EBITDA margin improved in H2 vs. H1, in line with guidance. Paul has previously criticised this company for promoting EBITDA, when real profits get eaten up by lease payments and depreciation.
(Note: we need to be extremely careful with EBITDA these days, as the accounting rules put the cost of renting sites into interest and depreciation which are excluded from EBITDA.)
Estimates: the new adjusted EBITDA forecast for 2023 is £4.5-£4.6m. According to the broker Liberum, the previous forecast was £5m.
Next year's EBITDA forecast also gets downgraded from £7m to £5.6m.
Importantly, these EBITDA forecasts do include the cost of rent payments.
However, statutory profits, if any, are likely to be minimal. The adj. PBT forecast for next year is cut by 50% to £1.2m.
2024 outlook: negative on the market outlook, due to cost-of-living pressures, especially outside London. Marketing costs will increase to drive brand awareness and offset the weak consumer (I'm not sure if this makes logical sense to me, but that is their plan!).
The living wage will further increase staff costs from April 2024.
More new sites in the pipeline.
Wrapping up:
Notwithstanding the challenging trading environment, the Group is targeting robust Adjusted EBITDA growth in FY24 on the back of the full year benefit of cost initiatives, the sales growth from the marketing investment and the Group's store rollout program.
CEO comment:
"As a management team we are taking proactive actions to adapt to the changing market environment. We know that in buoyant eating out markets where the Tortilla brand is well known, we outperform. We have a strong portfolio of new sites in high quality locations as well as additional franchise growth opportunities. In addition, we intend to increase marketing investment to improve broader consumer awareness of our brand and fresh, value for money proposition whilst also taking action to optimise the profitability and long-term potential of our delivery channel.
Graham's view
It might be better for Paul to cover this one, as he might be able to give a more balanced view.
Personally, I see few attractions here. A pub or restaurant share can generally grab my interest only if if falls into one of the following categories:
- If it owns its own properties, so there is no landlord. This way, if the restaurant business struggles, shareholders still own something of tangible value that can be put to different use. The most recent full-year results from MEX showed lease liabilities with a present value of £37m. I don't believe it has any freehold properties.
- If it has an extremely valuable brand and infrastructure so that restaurant operators are willing to sign up as franchisees, meaning that the brand owner doesn't have to take the risk of operating too many restaurants (McDonald's or Domino's, for example). MEX has some existing franchise partnerships and initiatives but my impression is that they are small-scale for now.
To maintain continuity, I will keep an AMBER rating on this share. It is forecast to have a small net debt position at the end of the current year (excluding leases), but is not in financial distress currently. Hopefully the roll-out is successful and the marketing spend pays off as intended. Though personally, this is not something I'd have any interest in betting on.
Mission (LON:TMG)
- Share price: 18.7p (unch.)
- Market cap: £17m
- Category: RED
Paul looked at this marketing group in October,
Today's brief update lets us know that FY 2023 is in line with the revised outlook after that October profit warning.
Value Restoration Plan - a grand name for "cost saving initiatives, margin improvements and selected possible business disposals".
£5m of cost savings have been identified. For context, last year this company made a "headline operating profit" of £8.7m on revenues of £79.8m. So it's quite believable to me that they would be able to find £5m of cost savings:
An initial £2m of annualised costs savings relating to headcount reduction in certain of the Group's business units have been delivered at a cost of £0.4m. A further £3m of annualised non-agency cost savings have been targeted and are being implemented at a cost of £0.3m.
Additionally, two non-core subsidiaries are progressing towards disposal.
Bank relationship - Natwest have agreed to waive the December covenant. It had already been flagged that a breach was likely, so the covenant waiver is good news. Although it's striking that it took two months to announce this - could it not have been announced sooner, or has the waiver only just been agreed at the last minute?
We remain in constructive dialogue with respect to covenants and maturity of facilities and are confident that through this ongoing support from our Bank, we will have the liquidity and headroom to deliver upon our medium-term strategy.
Net debt remains around £24m.
Graham's view - the net debt position is simply too large in relation to the company's recent (lack of) profitability.
The latest interim results showed revenues of £41.8m translating into a "headline operating profit" of just £2m and reported PBT of £0.1m. Marketing is labour-intensive work!
The share count here has been admirably stable over the years but an equity fundraising might be the best way out of this situation. Therefore I agree that this deserves to go in the RED category.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

120 comments
Anyone looked at Nexteq (LON:NXQ) recently? Named changed from Quixant previously. Appeared on Roland's Small cap screen - https://www.stockopedia.com/co...
12mth rolling fcst: P/E 7.2, PEG 0.8 yielding 4.02
Small director buy in September at 122p (current SP 95p)
Qualifies for Benjamin Graham's Deep Value screen. Mkt cap = £62.46m against an EV of £49.28
H1 2023 results presentation here - https://www.piworld.co.uk/comp...
A quick summary on Jupiter Fund Management (LON:JUP) based on Graham's write up in the Small Cap Value Report (Tue 17 Oct 2023, JUP price 77p at that time):
A recent bottom triangle (bottom wedge) chart formation suggests an intermediate-term target of 102-105p. I have bought today (now makes 10% of my portfolio) in a bid to balance my portfolio with some slow and steady less risky actors.
turbo, most of my portfolios are made up of rather volatile companies and as such, while not using stop losses, I have been underwater for some time. I notice that my AIM constituents are moving up faster than anything else now and wonder if this isn't the right time to seek 'slow and steady less risky actors'?
There is lots of dividend yield on offer for any dividend investors despite the recent market rally. I'm still being cautious, but have been steadily adding to infrastructure trusts like Renewables Infrastructure (LON:TRIG), BBGI Global Infrastructure SA (LON:BBGI) and Bluefield Solar Income Fund (LON:BSIF).
Given the dramatic movement in 10-year gilts to c3.5% (https://tradingeconomics.com/b...) these all seem to offer compelling value, if you are happy with a c8-10% annual return, with indexed starting yields of c7% and c15-20% discounts to the now possibly rising NAVs. Much better than long-term likely "return free risk" offered in the S&P500 (magnificent 7) given toppy valuations... all in my view!
On the smaller cap. side, I've also added Pollen Street (LON:POLN) a few days back as I like the investment manager which seems to be having continued success in raising new funds for private credit and equity in a difficult environment. Stonking dividend while you wait as well. Chesnara (LON:CSN) I've added to again ...... the 9% starting yield is excellent for 19 years of 3% dividend growth.
A 7-10% secure dividend yield is much more attractive when 10-yr gilt yields have moved down from 5% to 3.5%. Quite a big shift in a small amount of time! Anyone else been looking at similar things?
The yield on offer in various parts of the market has become tempting.
Bought some Greencoat UK Wind (LON:UKW) following their revised capital allocation policy resulting in increased dividends and a buy back. Their cash-flow is impressive and they aren't reliant on equity raises to increase their investments, which is causing problems for a few in the renewables sector.
Reinvested in Phoenix group (LON:PHNX) and Legal & General (LON:LGEN) as the market finally turned in their favor and both yield over 8%. Do think the new IFRS reporting structure here has confused the market and raised an opportunity.
(Totally tangentially I bought into Polar Capital Technology Trust (LON:PCT) recently as I speculate there might be a Santa rally in big US tech. The 10%+ discount to NAV on offer here looks very attractive given they invest in the most liquid shares on the planet.)
All look good with interest rates predicted to start coming down next year. Holding Legal & General (LON:LGEN) and Polar Capital Holdings (LON:POLR) at moment.
In a similar vein I have been slowly accumulating some prefs. Yields circa 7.5 % plus capital appreciation should hopefully give 10% pa for the next 3/4 years.
Just wondering if anyone is invested in or has a short term and longer term view on Lendinvest (LON:LINV)? They reported yesterday, however their business/report is too difficult for me to get to grips with.
I was wondering if they could be a interest rate/rebound play perhaps sometime?And if they manage to grow their loans book do even better over time.Anyone else invested or interested or am i way off and/or too early here?Surely buy to let isn't going away anytime soon, even with increased regulation, even if government totally get their boots on and start building more supply on steroids straight away sadly.
So...I see that the conversation from yesterday has continued re wisdom of following fund manager tips and I'm being obliquely gently teased for my cynicism with Filtronic (LON:FTC) being provided as the counter proof. I've got a few observations around this case...
I like FTC and spoke to mgt a couple of times in last couple of years (a meeting and an email exchange). They are good and a nice little biz. Share price has certainly attained at least low earth orbit ;)
Interesting time of launch. This occurred from Mello London onwards...ummm, interesting.
Now I missed the FTC presentation as I had other things to check out and I felt I'd DDed them enough to know I like but didn't want to invest. Perhaps an error of omission by me as I missed a clearly super presentation?
Well, interestingly, I know from others that they didn't blow their trumpet too hard and they certainly didn't tell anyone they were fulfilling orders for Mr Musk's Starlink (another potentially great biz)....but I came away from Mello knowing this would happen. Double interesting!...
How did I know. Well unsolicited after chatting to an attending and presenting fund manager (beloved in these pages) about a couple of cos they happened to drop into the chat some info on FTC....triple interesting!!...I wonder how many of us managed to pick up this info!
A 25% move off the back of Mello attendance for a company that's not gone anywhere fast for years (in sp terms) is quite remarkable...its unlikely to be driven off a general presentation at the best of times...and these ain't been the best of times where a company can create excitement/hype and ramp their price short term....AND that is not what the sober management of FTC do.
So, how do you credulous people explain these mysterious moves? I'd say the sp moved off back of new order info is a little meh...particularly given the (unstated by FTC tbc) Starlink order...
I don't have a view whether this is a buy the rumour sell the news moment. I would point out that valuation looks stretched short term and note the absence of longer term guidance. This probably isn't possible for FTC as its an engineering biz that relies on an ongoing flow of orders to make revenue....and that leads to some volatility in rev and earnings over time. Balance of probabilities I'd suggest this is a hard price level for FTC to sustain. I don't know...and the nature of biz they are currently transacting could keep excitement and price high. DYOR obvs.
Looking forward to a 3-5 year fundamental view on revenues, earnings and business development from someone...
They are meant to be making 24m revenues in 2024. I double that and round it to £50m and on operating margin of 6-7% (being extremely very generous in both of these figures) then I still do not come up anywhere near its 50m market cap.
But who knows it might go much higher; it’s just not for me with the figures I have in front of me at the moment.
I don’t believe any fund manager has “tipped” Filtronic as such not sure why this keeps getting raised, as a Stockopedia member I did a review of my time at Mello and mentioned it along with everything else .
I’m a fan
I was already a shareholder
I sat in the room at Mello and Did my own research
Sector is good
Technology and IP is a good moat
Customers for the satellite technology are the world leaders
Management are grounded
Shareholder base is good
Valuation has shot up on the back of two great orders with a combined value of circa 10 million .
As you say DYOR and draw your own conclusions and spend your own cash .
I now know how Ylannos felt last week .
I remember you were on Filtronic (LON:FTC) when it was still 12-14p do well done from me!
I personally did not see the opportunity although I did feel at the time that it was ready to take off-just the numbers were not there for me.
Maybe I will like this when its near 50p-sometimes on these growth stories it’s like this.
Always a pleasure to read your posts.
Have a good Christmas my friend.
Evidence provided by me and others to the contrary...you can disbelieve me on my exposure or not...in court I have a witness tho! :)
I like Filtronic (LON:FTC) and mgt. I looked back in the low double digits sp too and didn't bite as I need to believe in the duration of the opportunity and not just a short term value or newsflow angle. My problem is they have not shown the ability to gain new revenue and repeat and grow...they don't have repeat revenue nor a sell repeated small parts (relative to their revenue) business and that's what I tend to like in engineering (there are other good UK engineers that I like but wouldn't take a piece in public equity)
I like the fund manager who mentioned it (will likely allocate to his fund...family etc) and tbc there is no impropriety in him relaying what he discovers from his primary research and talking up his capabilities and position. BUT it most definitely is a tip and he is talking his book...and no doubt gave the same message I got to many others...well played!
I think Richard Staveley in his interview at end Nov said that Lockheed are setting up a new UK Space HQ in same industrial park in NE England as Filtronic. He was hinting that they'd be a natural takeover target for Lockeed because of some govt rules that a foreign firm has to have a certain percentage of UK based supply chain/labour etc. Maybe that's one of reasons why the share price is moving at moment ?
Marks and Spencer (LON:MKS)
From this morning's Retail Gazette. Well worth a read. Some turnaround happening at Marks and Spencer by the looks of things. I'm not sure all of this is in the price yet. There will probably be a Christmas trading update in the week beginning 08/01. That will be interesting.
M&S Clothing - how the retailer revamped its fashion arm (retailgazette.co.uk)
Not sure if one should read anything into this, but activist investor Ed Bramson Sherborne Investors (Guernsey) C (LON:SIGC) has just been appointed Vice Chairman at his 'target co' Navient (NSQ:NAVI) .
SEC Filings | Navient (gcs-web.com)
Item 8.01. Other Events.
On December 8, 2023, Mr. Bramson was appointed as Vice Chairman of the Board of Directors of the Company.
David Yowan (believed to be Bramson's man-or, at least- 'a man Bramson can do business with') was appointed Pres and CEO on 15th May 2023. He's been a NED on NAVI for abt 5 years.
Yowan appointment was based, inter alia - per the press release - on his "proven track record in transformational change.."
There is a solution if anyone is unlucky or unsuccessful with their smaller company investments. It’s so frustrating (and this happens even when we research them properly) ending up with the poor performers, and worse still if alternatives we dismissed rocket.
The solution is either to go for a couple of UK Smaller Company Investment Trusts or hold at least one of those and some smaller companies like the ones so well analysed here. There’s no point buying several as it’s just duplication and there are so many other Investment Trust sectors to consider that enable us to invest all round the world!
This link takes readers to all the UK Smaller Company Investment Trusts:-
https://www.theaic.co.uk/aic/f...
Then for loads of facts and figures on each individual Trust just click on the red Trust heading.
Key thing then is to check must know info (some not included in the Stockopedia stock pages unfortunately) like:-
1.NAV and the discount t to NAV.
2. Performance over 1, 5 and 10 years. AND compare the performance of that Trust with the average performance over the same periods for all the smaller company Trusts. That figure is the one at the very top. (That overall long term performance doesn’t look that impressive reflects the long term weakness of UK markets including too many small company shares AND the fact that Investment Trusts generally have underperformed with discounts to NAV unusually wide. So the future could be a LOT better with now the time perhaps to cash in).
3. Announcements obviously for RNS updates and often very good research from Kepler and Quoted Data. I’ve pasted a sample from Kepler at the end of this post.
4. PORTFOLIO. It’s a MUST to check this and their top 10 holdings and the percentage the Trust holds in that share.
5. Use Stockopedia for what it is also intended for. I.e the stock pages for each share the Trust holds in their top 10. And then for analysis from the likes of Paul and Graham as well as sometimes (today is not so good so far!) quality reader follow up. If the Trust holds shares we like that’s a plus.
Now for specific examples of possible UK Smaller Company Trusts to go for.
My preference with Investment Trusts generally is the ones with conviction portfolios with a high percentage in their top 10 holdings. Those Trusts (e.g Strategic Equity Capital (LON:SEC) and Rockwood Strategic (LON:RKW) often work closely with AND provide us with detailed info on each share they hold. I use this info to assist with my own share buying as it can reveal quality shares with great prospects that look too cheap.
Trusts with 100 or more holdings and no conviction buys can’t possibly do that.
So now to the Trusts that HAVE got conviction portfolios.
Rockwood Strategic (LON:RKW) 85% in top 10. High quality Trust and hence unfortunately at a small premium to NAV.
Strategic Equity Capital (LON:SEC) 72% in top 10 Rights and Issues Investment Trust (LON:RIII) 68% Athelney Trust (LON:ATY) 65% but note very small market cap around £4 million and poor performance. Odyssean Investment Trust (LON:OIT) 62%.
I like Strategic Equity Capital (LON:SEC)
Note performance. 1 year up 42% 5 years 72% and 10 years 137% against sector average of 12% 27% and 80%.
Check their top 10.
Medica 12.2% XPS Pensions (LON:XPS) 10.8% Tribal (LON:TRB) 8.2% etc.
I don’t hold any of these Trusts at present because I prefer to choose my own smaller company investments, but I DO hold a LOT of Investment Trusts that enable us to invest all round the world and in things like UK commercial property where I hold several of those very big dividend paying Trusts and until recently very bombed out too. Also Vietnam has proved a fabulous investment for so many years and I hold VinaCapital Vietnam Opportunity Fund (LON:VOF) and VietNam Holding (LON:VNH) and both are still well worth checking out.
Finally here is a section from the Kepler research on Rockwood Strategic (LON:RKW) which summarises it very well. Yea, it’s paid for research but it’s often very good and what’s so different between honest admission that research comment is paid for and House Broker comment?
Rockwood Strategic (RKW)
27/11/2023
Results analysis from Kepler Trust Intelligence
Rockwood Strategic (RKW) has released its results for the six month period ending 30/09/2023. The trust saw NAV and share price total returns of -5.5% and -2.5% respectively during the period, compared to equivalent returns of -10.3% in the FTSE AIM All Share Index and 2.9% in the FTSE Small Cap (Ex-ITs) Index.
That six month period captured a difficult period for UK small company shares which follows an exceptional fund track record over longer periods. In the 12 months to 30/09/2023, RKW delivered total returns for shareholders that were close to 30%. Since the period end and as at 22/11/2023, RKW was the top performer in the AIC's UK Small Cap sector over 1, 3, and 5 year periods. Annualised returns for that five year period were in excess of 20% on a share price total return basis.
This strong track record meant that RKW traded at a premium for much of the period, enabling the board to issue new equity to investors, expanding the shareholder base by 5.7%. We note that this is at a time when UK small caps and the wider investment trust sector have been massively out of favour, with average discounts for closed-ended funds at levels last seen during the financial crisis.
RKW Chairman Noel Lamb said: "The first half of our financial year has been a challenging one for UK small company stock market investors, with sustained outflows from the asset class amidst negative sentiment as interest rates continued to rise against a subdued economic backdrop. For those with sensible time horizons these are typically the conditions for positive future medium-term returns, not least due to the heavily depressed valuations of small company shares relative to history. Private Equity and Trade Buyers are clearly recognising the opportunities created by this environment with the drumbeat of takeovers within Rockwood's portfolio continuing throughout 2023."
Kepler View
Rockwood Strategic (RKW) takes a unique approach to the UK small cap sector, with manager Richard Staveley investing at the smallest end of the London Stock Exchange. He looks for companies that are undervalued and which have the potential to deliver a 15% IRR over a three to five year time frame. This process is helped by the fact that few other fund managers can invest in these companies, mainly due to size and liquidity constraints, and that they typically have little to no research coverage. RKW also takes an active approach with the firms it invests in, meaning members of the RKW team regularly taking up board positions with portfolio companies and push for change where needed. In the period Nick Mills from the investment team joined Trifast as a NED.
Three takeover bids in the RKW portfolio since the end of September are also a validation of the trust's investment process. These were all announced at substantial premiums to prior day closing prices, with Smoove acquired at a 69% premium, Onthemarket a 56% premium, and The Pub Group a 46% premium. We note that the prospective uplift for RKW was superior to each of these, given the entry point at which the managers invested.
RKW is also arguably well-positioned to continue its impressive track record moving forwards. The increasing level of M&A activity we are seeing in the portfolio and wider UK stock market is a sign that trade buyers and private equity firms clearly see the value these companies offer, even if other investors do not. At the same time, we think Richard's focus on valuations, cash flows, and strong balance sheets mean the RKW strategy can succeed, regardless of whether we are in a period in which rates have peaked or where they remain 'higher for longer'. Recent news that Downing Strategic Microcap (DSM) has plans to wind up means the trust is now one of the only closed-ended funds offering investors access to the UK's smallest companies.
I echo your thoughts on investment trusts as a vehicle for investing in overseas markets. I am also a holder of VietNam Holding (LON:VNH) and invest in the Indian market via Ashoka India Equity Investment Trust (LON:AIE) . Both investment managers are stock pickers and both countries have vibrant economies.
Thanks for replying Sharewalkah. I haven’t looked at Ashoka India Equity Investment Trust (LON:AIE) or other Indian Investment Trusts for a while as their market is expensive …but perhaps justifiably so. I bought India Capital Growth Fund (LON:IGC) by sheer luck right at the bottom for 40p at the depths of the covid lows in 2020. I sold around 110p……and that was a mistake as share price is now 170p!
Vietnam has proved equally successful via VinaCapital Vietnam Opportunity Fund (LON:VOF) and VietNam Holding (LON:VNH) which I ‘ve held apart from temporary sells for most of this Century. Vietnam is much cheaper than India and there could well be a lot more to come for VOF and VNH. The other Trust Vietnam Enterprise Investments (LON:VEIL) I don’t hold but it’s also well worth checking out.
Re Goodwin (LON:GDWN) I hold & it’s by far my largest position …it’s important to note that they are now at most 6 months away from the launch of a new polyimide range of products designed for extreme applications where it’s unparalleled thermal range & self lubricant characteristics will command a very high price…they’ve designed it to slot straight into use cases such as aero engine components, semi conductor manufacturing, & glass bottle manufacturing where a chemically identical competitor is now out of patent. They are already in communication with prospective customers & today we learnt that they’ve raw materials for 30 tonnes of output..if their aspirations are realistic this 30tonnes alone will in itself be by far the largest part of the business in valuation terms….the costs of developing this have largely been absorbed…the benefits will accrue over future years.
The rest of the business is varying degrees of awesome too…but I would say that wouldn’t I…
Thank you for the comment Mr. Rhomboid... I am very nervous writing about Stoke-based businesses in your presence! G
Chill Brands (LON:CHLL) £23m market cap and £83k turnover. My mate in his sixties does painting, and odd jobs has a higher turnover. I don't think he's worth £23m. I not saying you can't make money on a share like this on good news, but it's a punt, not a long time investment.
That made me laugh.
I don’t suppose your friend loses £3m a year and on top owes £5m as well , and that is after so many fundraisings.
I will leave it there and wish all holders of Chill Brands (LON:CHLL) good luck.
I know when I read 3-4 continuous trading updates from a plc with no material figures in them , that the company has no future.
Good luck to all holders
Is anyone looking at PFC?
Petrofac (LON:PFC) I don't hold. With those (9%) shorts in position it's well worth a look if they start to close, watching
It’s just my personal opinion but these short sellers will never close their position on Petrofac (LON:PFC)
They will wait till the company defaults on their bond payments and restructuring takes place and bond holders become the majority shareholders.
On today's ONS figures I think it's helpful to note that not only is inflation rising less fast (on a YoY basis) but actually prices are now falling (on a month-on-month basis). See below courtesy of Resolution Foundation. More helpful signals that 2024 should see a decent rise in share prices.
Thanks for highlighting - I always think the MoM figure is a lot more relevant than the12m figure. As you can see from the table, the 12m rise was nearly all driven by rises in the early months of 2023 - this is all history now and CPI has essentially been flat since May.
How's the core inflation index doing MoM?
I presume that one has greater weight for BoE decisions on rates?
Also, more good news this afternoon: energy prices are projected to come down significantly from April by £170 - £380 for customers at typical consumption: https://www.bfygroup.co.uk/blo...
Must be a bit humiliating when a stock as large as Entain (LON:ENT) moves up 25% over the days when the CEO resigns! I have been agitating for that change in management for about a year now as it was clear the market didn’t have faith in her strategy despite the stock (when you add in the value of the BetMGM 50% stake) being materially lower in valuation terms than peers.
If they get the right person in then no reason this can’t go on to be the global giant it really should be based on their tech offering but I suspect it gets taken out now - probably around the 1500-1800p mark. I suspect it is more that driving the change in share price than the CEO leaving in reality.
Feeling a bit disappointed this morning that I've sold my ME International (LON:MEGP) holding.
The sp has been on a steady decline, and I decided to take profits today. I've done well out of it, but I've allowed some emotion to cloud my judgment on this; should have sold a while ago.
Seems like the market has decided (for the time being) that there are better opportunities out there.
Feeling a bit disappointed this morning that I've sold my ME International (LON:MEGP) holding. Seems like the market has decided (for the time being) that there are better opportunities out there.
I think it had run up too high and needed some air taken out of the balloon. That put it in a downtrend while everything else has been rising - leading to weak hands flipping it for the next thing. Personally, I think the technicals suggest that the worst is over. The chart shows potential for support around these levels and a recent bullish divergence with lower lows in the SP accompanied by higher lows in the RSI add weight to that possibility. Meanwhile the valuation is the most attractive I've seen for the name, maybe ever. Over recent years, earnings have doubled and the multiple has halved.
If you're still a fan of the company and just bothered by the price action, I'd monitor to see if there's a good moment to buy back in. By contrast, I just opened a position today. Funny how two investors can have differing views - but that's what makes a market!
I hold ME International (LON:MEGP) , and while I obviously don't like the recent chart, just a few points.
YTD SP is up from 115p to 124p
Two dividends have been paid in 2023 bringing in 5.97p
Thus if you held ME International (LON:MEGP) at start of year, it has returned 13pc. Personally I am looking to make 20pc per annum, this is however one of my best performers of 2023.......
EPS estimates for both FY2023 and. FY2024 have increased since start of year, only 7pc, but given the amount of profit warnings small caps have had, that's reasonable.
I look every month at forward PE for current FY and next year. Up to NOV, average has been 11.0 with a high of 12.8 for FY23, and average of 10.4 with a high of 12.1 for FY24. Currently PE of 9.6 for FY23 and 9.1 for FY24. That's not a bargain rating at present, but I think it's a reasonable fair multiple.
The company has a lot of cash, and is buying back shares, has done every day this week. This is rarely a negative point.
So while the shares are on a downward trend, I am still holding. I will only sell if the forecasts deteriorate, always a possibility, but they have not this year. While I understand you selling out, I thinks it's one to watch closely, if SP falls any more and estimates remain static or are increased, it's one to buy back into. If forward PE goes to 8.0, I will be looking at adding.
Thanks both BnB and Orval - yes I've kept in on my watch list and will keep a close eye on it.
I am finding it very hard to pick up certain smaller stocks at the moment. Suggests there is no sellers which is quite a good sign.
Very surprised to see the reaction on Goodwin (LON:GDWN) this morning. The TU seems to me to show that Goodwin is trading well and the reduction in profit on the derivative is irrelevant. Having got a 30 year at 1% loan they are sitting pretty in my mind. The actual operations seem to be moving ahead on all fronts. I decided to add a few to my holding before the market realised that the mark down was way overdone. I have been in and out of the company over the years. This was a mistake, I should have stayed in and let the family get on with doing what that they have done well over several generations.
I agree and topped up this morning. I don't really understand the derivative profit.
They bought a swap or similar to guarantee they pay an effective 1% interest on their debt. When interest rates go up this becomes more valuable and when they goes down it becomes less valuable. Every six months they have to put this notional profit or less through the P&L.
You just have to take view on whether it was a sensible thing to do over the entire duration of the arrangement and ignore the noise. fwiw I don't know what fees were involved but locking in interest rates at 1% (at a time when base rates were low) feels pretty sensible to me.
[I hold]
I agree Aislabie. I read the RNS this morning and confidently expected them to rise today! I take the fall as an opportunity and have topped up.
Overall the news seems positive apart from an increase in debt which appears to have been due to capital investments in new plant and maybe the delays to the announcement of tender results which they are still positive to receive next year. The latter leaves me a little nervous having been involved in offers which we were sure to win but in the end were lost.
However, the other news of increased business in the states and in India as well as new products coming onto the market all sounds very good. So I have lso added.
Bank of Georgia v Georgia Capital
Bank of Georgia testing its highs around 3700 .
Interesting Georgia capital always lags .
For those that don’t know Georgia capital own circa 20% of bank of Georgia so they should move together .
If Bank of Georgia pops up to 4000 level and sets a new high Georgia capital should gap up to circa 1200 about a month later .
Worth keeping an eye on.
Geo political risk as always with Georgia but lots of geopolitical risk in many places at the moment .
Thanks Planetx- the chart of both does suggest Georgia Capital (LON:CGEO) is lagging.
Bank of Georgia (LON:BGEO) also pays an almost 10% dividend. Georgia Capital (LON:CGEO) doesn’t but benefits from the former as their 20% holding gets some decent annual income allowing them to invest in their other businesses where necessary. But I think the divi direct to shareholders is one reason for both the lag and discount. If they also start paying a divi I think they’d re-rate to more like a 30% discount to NAV which would be maybe £15-16
Morning all,
I know the writers at the SCVR do not tend to cover oil/gas stocks in their writeup, so I just wanted to draw attention to Seplat Energy (LON:SEPL) , a company that I know a few here invest in. The company is not one that is not regularly covered by analysists, and due to being based in Nigeria there is certainly geopolitical risk that puts off more cautious investors. I do believe the investment case here shows good risk reward and I attach a link to the most recent research note that came out this week: https://fromsmash.com/Seplat-Energy
Whilst I recognise this is paid research is does emphasise a few key points that in my opinion demonstrate the significant potential upside for both the share price and dividend. The figures used in the report do not account for the acquisition of MPNU from ExxonMobil which could significantly enhance the projections should it get the green light in the near future. Nigeria, partly due to decisions made by the new government, has seen its currency fall and its stock market reach new all time highs.
I would be interested to hear the thoughts of anyone who takes to time to read the report, I am not going to regurgitate the financial information from the report but I will draw readers to the overall headline:
"Seplat is on a discount rating to peers and on compelling forward valuation multiples with upside of 32%-91% to our initial NAV estimates, excluding the potential transformational value from
the MPNU and PIA uplifts."
As always DYOR (I hold a medium size position in Seplat Energy (LON:SEPL)
All rests on geopolitical risk. Cant remeber the name but didnt another oil company in Nigeria just dissolve overnight due to fraud?
Afren. Nigeria is a lot of risk.
I agree there is certainly geopolitical risk, however like many developing countries the government are actively trying to clean up their image and invite further international investment, Seplat Energy (LON:SEPL) will be a huge catalyst in that. Seplat is already the 5th largest company by market cap listed on their stock exchange and the largest oil/gas company. If a similar issue to Afren was to occur it would be awful for Seplat but also a very bad look for Nigeria. Fraud can happen anywhere as Wandisco showed us, but I understand there are greater risks in less regulated countries such as Nigeria. Fingers crossed the next few years runs smoothly, I know theft of oil was a huge issue until recently but with the governments support this has been reduced significantly this year.
Goodwin (LON:GDWN) HY is out today, market does not like it, shares are down 12%. The issue seems to the "Unrealised gain on 10 year interest rate swap derivative" only £0.9m down from £3.1m last year.
Has anyone been to or have children who have been to Revolution Bars (LON:RBG) or XP Factory (LON:XPF) recently and, if so, have they been busy? XPF shares have not moved at all in quite a while except to the downside, despite much talk of ‘experiential leisure’. RBG have gone up a bit. BenHazz did an interesting AI analysis of RBG earlier in the year. I got my son to ask Bard and it presented the occupancy ratio for RBG for 22-24 December already… AI into future-telling. I’ll stick with human observation for the time being.
My thoughts on XP Factory (LON:XPF) are its a really tough hold, I've been in a few years now and they have always delivered so I'll keep holding
It's stuck in a range and I guess the catalyst will be the trading update, probably at the end of Jan. If they have a good Christmas happy days! I think they will, train strikes are off and people are definitely still celebrating Christmas party season.
Personally I think there is still someone with stock to sell no buying volume. Previous bulls like Justin and Paul have gone cold on it, must be due to lack of anything happening as the story hasn't changed and the big elephant in the room is that we don't really know if BBB is profitable on a site level. I think Richard will deliver on plan, has done up to now and there has been lots of insider buying lately.
The concern is with some of these late-night bar companies that although footfall and bookings has recovered recently, we don't know how that maps to profitability. There was an article around a week ago, possibly in the FT, that spending per head (in nominal terms, let alone after inflation) at these bar companies was down, especially in those venues with younger customers. Revolution Bars was mentioned in the article as one of the companies with higher bookings but lower spending per head.
Have to agree Roger. My initial excitement over the potential for AI to provide easy access to information that could give retail investors a glimse into future earnings of companies has certainly waned. The more I experimented and was able to then check back and see the impact of the figures produced, the more I realised it was not reliable enough. Some companies like J D Wetherspoon (LON:JDW), Marks and Spencer (LON:MKS) and Next (LON:NXT) which showed great footfall statistics have jumped significantly, where as others like Revolution Bars (LON:RBG) and XP Factory (LON:XPF) have bombed. Based on the data JD Sports Fashion (LON:JD.) should have seen the biggest rises but that has had a mediocre year and has only jumped recently on outperformance by US peers. All in all, I agree, stick to human observation for the time being!
XP Factory (LON:XPF)
I was going to be dismissive and ask what their point is BUT went and had a look at the website.
Where you can see the level of future bookings and how much it costs (I must be getting old...)
There are limits to growth, they will always be in a popular part of a city and only one per popular area and looks like it needs a large area I.e. one in Bath maybe two in Cardiff
I think this will be very sensitive to young people's spending power, more so than a bar.
It looks like you need to book. I would suggest having normal bar as well so you can snag walkups.
Thanks. I am going to go away and look in more depth.
When XP Factory (LON:XPF) moves, it moves quickly, +13% today, at last!
Edit 11:32 , I spoke too quickly, the seller must have just woken up. Maybe had a Christmas party or something so had a bit of a lay in.
Well, since my post a couple of hours ago, XP Factory (LON:XPF) has gone up 11% to 16p and was even higher at 18p! If I hadn't been planting tulip bulbs in the garden, I could have sold out at a tidy profit...It seems like it could go either way. Experiential leisure is the current big thing. Corporate bookings are high, no train strikes, quite a pricey activity but cost of living pressures, increased wage costs, zero moat, etc. The January update will be interesting
Yep, by the time those tulips bloom XP Factory (LON:XPF) should be much higher.
You can just turn up, but you run the risk that all of the games are booked out. Usually some more mundane stuff will be available though even if the popular things like axe throwing are booked up. There's always the bar if you're happy to sit and wait for an open slot!
I must visit. Beer and axe throwing should be a great spectator sport.
As well as the sector not being popular, XP Factory (LON:XPF) changed its broker and its year end. Nothing too untoward there, although the resulting new updated forecasts implied a sizable decline in profitability for the period ended 31 Dec 2023. In addition, Paul pointed to write downs in lease assets suggesting that some sites were less profitable/loss making.
Management always come across well in interviews but I cant recall them being challenged on these points.
In summary, I think they have some very successful and profitable sites, but there are others sites doing less well and these will obviously, to some extent, offset the good ones. This could partly be a result of last year's accelerated roll out and some sites maybe 'fixed' by management. In the meantime the Group's limited cash generation and funding position restricts its ability to grow through further site openings.
All that said, it's a popular and growing concept and I still expect it to beat (reduced) forecasts. I hold.
Nice to see their progress with the Fire extinguishers, was sat in Dupre's offices (work related meeting not investment) in 2018 and remember their GM telling me how much time and effort they were going to put in to bringing it to market. Can imagine the testing and development will have taken a lot of time, and cost some considerable money, hopefully they can monetise it and create another income stream.
(I DONT HOLD)
Fantastic news for Chill Brands (LON:CHLL) - breakthrough into a major supermarket, not long after sales to WH Smiths. It's been a long road, but this seems to be coming good.
Chill Brands (LON:CHLL)
This is a serious and well respected forum by the investment community in general. It is my humble opinion that these kind of companies with NO FUTURE, one million RED FLAGS ; that will eventually end up to a big ZERO should not be mentioned here.
We will then disagree with each other. It's had a rough time - but £1.85m of revenue in the past quarter, distribution deals with two major retailers in UK, one in US, market place with 30+ brands now selling through. It may be down as a sucker stock, but it has potential.
It’s an open forum we all pay for where many people are looking for growth opportunities. I think Chill Brands (LON:CHLL) is building something special, or maybe it fails like many companies do. We are all our own independent judges on here.
I will explain to you later on after the market closes why Chill Brands (LON:CHLL) is a zero in the making.
My post will include figures not feelings!
You are supremely confident in your opinion of an unwritten future. I am happy you made a good choice with McBride. I am also happy if others in Chill make money. I didn’t ask for your explanation on Chill, but please feel free. It’s a forum.
I don’t hold. Don’t plan to hold. You appear to think I do, so no need to explain it to me unless you have the time.
I think some other people have already covered this and I have also added some more figures-85K revenues , £3m losses pa and debts mounting to £5m. Available cash from July’s balance sheet of £3m probably has gone by now as they are serial cash burners.
I remember this when it was 75p and I have stated at the at time exactly the same things I am now-it’s a big zero.
Perhaps Graham can help out on this and the colour he thinks is appropriate; it can be probably either RED , RED or RED.
Thanks
PS. I am only trying to help and I have never shorted a share in my life as I find the whole process and the leverage not investment but just simply gambling although I know many clever people that make good money from shorting shares.
Yiannos1
I think that you're being too backward looking. You are quoting numbers which are out of date - the revenue figure you quote is from the final results to March 2023.
9 months is a long time and as per an interview with the CEO released today, revenue of £1,85m has been achieved in the past 2-3 months following the launch of zero nicotine vapes into the UK and US. In Q1 2024, they will be stocked in 2100 stores in the UK, from small convenience stores, through WH Smiths and as announced today with one of the big 5 UK supermarkets. They are also available on Amazon in the UK. In the US, the vapes can be shipped to all 50 states and are being rolled out by Smoker Friendly to their 700+ stores.
In addition, Chill.com now has 25 brands in the UK and 22 in the US, with more being added on with a regular cadence. Chill gets a commission for each sale from the website.
For avoidance of doubt - Chill is not a CBD brand anymore (as was stated on here) and the CEO has publicly stated that that was a mistake.
Interims (for period to end of September) are due soon. Given the ramp up in revenue / new sales channels since then, you may still see low revenue - but you will hear more of the successes.
I'm not saying its not risky. Maybe it is a sucker stock and maybe it is RED, but unlike when it was 75p and trading on Hype and the investment of John Storey, there is more substance behind it's value than there has been in the past.
If you don't like the idea of Zero Nicotine Vapes - then definitely not the stock for you - but maybe keep an eye on where this goes.
"Chill ZERO products will enter these stores during Q1 2024. Following this
roll-out, Chill ZERO vape products will have been sold into more than 2,100
locations in the UK including independent and chain stores, receiving combined
gross sales and purchase orders in excess of £1.85 million (including VAT) in
the short time since their launch on 7 August 2023."
I'm not sure if they are saying £1.85m turnover already, as it includes purchase orders? is that the past 3 months and the next qtr revenue.
This is what he is missing obviously as probably he assumes that purchase orders are actual sales , and the mentioned figures includes VAT as well.
Thanks
You're right - and I meant to correct that last night. They are confirmed orders - but not yet recognised as revenue (and may well represent the sale price to the consumer), but my point is that it is much more than the £83k that was being bandied around. I'm glad that Yiannis is now starting to quote more current figures rather than those which are 9 months old - as I said above, we will need to disagree on whether this will be a success or not. To my mind there's a lot of momentum building, distribution agreements in place, it's a question of whether the products sell. Time will tell.
Last post on Chill Brands (LON:CHLL)
This is a company with no future and I am always looking forward at least 2-3 years.
On the 5th of December about 150m new shares were listed that caused 2p to the holders. These shares were paid in April and June 2022 and the FCA just approved them to be listed as it was the result of loan note conversions.
It’s one thing to get a product in a store or on Amazon and another thing to sell it and then another thing to make profit.
The company does not have the capacity to make any meaningful revenues nevermind turning these into profits and free cash flows.
In its September balance sheet the company admits that the cash is only £1.7m now therefore from March they lost another £2m (at least).
The company also agrees that it will need to raise more cash again and the most important issue is that the company does not inform or indicate that there is any improvement in its trading.
Now I am talking in numbers and you are just telling stories.
Good luck with your investments and have a wonderful Christmas and a happy healthy and prosperous new year.
Thanks
Chill Brands (LON:CHLL)
"For avoidance of doubt - Chill is not a CBD brand anymore"
Then why are they still selling these? -
https://uk.chill.com/products/...
Stocko. calls it a 'sucker stock', i agree.
They sell vapes, which confirms their "sucker stock" status.
Chill Brands (LON:CHLL)
CBD sales are well down, they manage to lose £5m every year, their website is awful, 67 trustpilot reviews, a market cap of £23m, and that's just scraping the surface.
Chill Brands (LON:CHLL) Stock Rank 0.
Cavendish Financial (LON:CAV) interesting descending channel breakout yesterday on the daily. Been in this downtrend for the whole of 2023 with some nice volume. Great summary from Graham which I'm sure helps support confidence, together with return to volume next year!
My morning smallcap tweet: BELL ends year with warning.
Directa Plus (LON:DCTA) Home Reit (LON:HOME) Chill Brands (LON:CHLL) Seeing Machines (LON:SEE) Belluscura (LON:BELL) Location Sciences (LON:LSAI) PCI- PAL (LON:PCIP) Tortilla Mexican Grill (LON:MEX) LBG Media (LON:LBG) K3 Business Technology (LON:KBT) Rua Life Sciences (LON:RUA) Filtronic (LON:FTC) t42 IoT Tracking Solutions (LON:TRAC) Petrofac (LON:PFC)
◄Directa Plus (DCTA)► to acquire 'groundbreaking' technology for G+ graphene compounds for application initially in Batteries and Polymers. "The acquisition marks a strategic leap for Directa Plus' positioning in the value chain." Did I mention the groundbreaking technology I recently acquired at Screwfix? A forge steel fork and spade set. Only £14.99. [SP=27.1 Cap=18m]
◄Home REIT (HOME)► Aug portfolio valuation £412.9m, 42% of acquisition cost. It's £10m down on Feb figure. [SP=38.05 Cap=301m]
◄Chill Brands (CHLL)► Chill ZERO nicotine-free vapour products to sell in a top five UK supermarket from Q1 2024. [SP=6.11 Cap=27m]
◄Seeing Machines (SEE)► wins $30m automotive program for new European OEM customer. Production starts 2026. [SP=5.2 Cap=217m]
◄Belluscura (BELL)► warns FY23 EBITDA marginally below management expectations. Chinese approval for X-PLOR Portable Oxygen Concentrator. [SP=20.19 Cap=28m]
◄Location Sciences (LSAI)► expects to publish an admission document for the acquisition of Sorted Holdings by the end of January 2024 at the latest. Remains suspended pending that. [SP=0.14 Cap=4m]
◄PCI-PAL (PCIP)► awarded £1.06m as an an interim payment of costs in patent trial. [SP=61.4 Cap=40m]
◄Tortilla Mexican Grill (MEX)► warns FY-Dec rev up 13.8%, slightly behind mgmt expectations. Adj EBITDA £4.5-4.6m, in line. [SP=55 Cap=21m]
◄LBG Media (LBG)► guides FY-Dec rev up 7% and adj EBITDA up 8%+. Profit in Oz down, which they plan to reverse with "a number of positive changes". They are the best kind. [SP=76 Cap=157m]
◄K3 Business Technology (KBT)► guides FY-Nov adj op profit at least in line with market expectations. Cash balance £8.3m, ahead of market expectations. [SP=111.02 Cap=50m]
◄RUA Life Sciences (RUA)► computer modelling of the RUA leaflet composite heart valve material suggests that its mechanical properties would be ideal. Seeking to commercialise the composite material as an alternative to animal tissue. [SP=10.2 Cap=2m]
◄Filtronic (FTC)► yet another order, for $6m initially to be booked in calendar 2024. [SP=22.64 Cap=49m]
◄t42 IoT Tracking Solutions (TRAC)► gets £925k 12 month convert at 8%. Strike 15p. Hopes to extend period. [SP=2.5 Cap=1m]
◄Petrofac (PFC)► gets second contract award under the Framework Agreement with TenneT. Worth $1.4bn to co. Net debt at year-end is expected to be modestly higher than at H1. "Near-term focus remains on strengthening the balance sheet with ongoing review of strategic and financial options." [SP=21.84 Cap=114m]. I'm short.
Puntastic!
Best one yet.
Like it!
Hi Graham, Paul never caught up with Xlmedia put was on his agenda, any chance you could take a look? Many thanks
Hi Chris, thanks for the suggestion. I don't think I'll get around to covering XLM today but let's see! G
Anyone invested in Shanta Gold (LON:SHG. Recommended cash offer of 13.5p a share. A whopping premium of under 7% (6.72%). Bidco is a new vehicle setup by connected parties. Looks fishy. Gold price near highs, company almost clear of debt with a promising future. Bids rejected November last year as being too low.
Agree - feels like a stich up. Maybe it will draw out other offers for the company?
If it looks like a stitch up and feels like a stitch up then it probably is. Sadly as I hold. Hopefully, a larger bid will materialise.
Almost certainly a stitch up. Note the SP has been sold everytime it has tried to breakout around 12p. With gold threatening a major breakout, the timing couldn't be worse for the average investor.
Yes, I hold Shanta Gold (LON:SHG) and think the Investor Meet Company's presentation of July 3rd is worth checking out.
Edit: Upon checking, Simply Wall St. says this;
making me wonder why there hasn't been a hostile bid.
That is pretty annoying! @SHG had grown to be my largest holding, and I thought it still had plenty of potential. Even if it's not a done deal yet, that they are recommending it has taken away my confidence in the management.
Thanks for the CAV tip...my gain yesterday paid for almost half of my subscription.
Good morning all,
This is not a tipping service-we are all expressing our personal views here (sometimes backed by financial analysis!) and everyone then should do their own extensive research before they commit their hard earned money.
What a pompous put down yiannos. Tip might not have been the right word but I have been grateful many times for the heads up on stocks mentioned in these reports.
I beg to differ Lord gnome, yiannos comment if fair and 100% factually correct
When I joined here 2 years ago I treated this board like a tipping service and went into
Joules (total wipeout), hostmore (considerable loss), revolution bars (considerable loss), saga (still holding at a considerable loss)
i dont blame anyone else, i made my choice and the loss is on me, i know i have learned from these mistakes and i think of it as the cost of the education
I find it very fair and correct to make it clear to readers of this board that all commentary and posts are a personal opinion and nothing more (we've all seen posts on here from silly people blaming Paul for their own shortcomings)
Callum
They should also state that they get paid to make their commentaries. I can't imagine that they do them for free!
Yes, must treat comments (tips?) on Stocko's SCVR with utmost care.
Yes, Yiannos is quite right - it is important to highlight it isn’t a tipping service. There are a number of people on here who do strong research and share ideas but people need to do their own research before investing in anything. Timing is important, a lot of people will ordinarily talk their own book so have a bias irrespective of analysis that may not suit someone else’s portfolio.
Another very big contract win for Filtronic (LON:FTC) . That’s 2 this week, for a combined value of around half last years turnover. And with 2 private individual families owning very big stakes, it is primed for a takeover imo.
Wow! Great progress at Filtronic (LON:FTC) this week and it looks like the SP is responding positively again today. Another one from the Rockwood stable.
Filtronic
Another order for he who cannot be named .
Maybe not a bid idea to follow the lead of a dodgy fund manager after all .
I've figured out that following a certain fund manager is an alpha generating opportunity because it leads me to the most undervalued stocks in the market. Given I am a selfless soul and the profit opportunity is so great, I proclaim my finding to the world. Everyone joins in causing the valuation anomaly to disappear. If only I had kept the secret to myself.
I think you will find the likes of Filtronic is rerating not because of any tips or fund manager but because the company is performing quite well .
Look at the company and DYOR but it’s a plus if what I perceive as “smart money” is already in there .
- check the company
- look at fundamentals
- look at sector
- look at shareholder register and who’s buying / selling
- looK at management
- check cash v debt
And ask if it’s something you can understand / believe in .
Rank those factors above in order of importance to you
Then make your own decision .
Blindly following anyone whether it’s Paul Scott, Warren Buffet , Christopher Mills or the bloke at the bar in the fat cat then you are indeed a total muppet .
I'm glad we agree. It is far more important to focus company fundamentals in our research process rather than if a certain fund manager is on the register. No-one wants to be a lemming (at least they shouldn't).
Didn’t realise I had ever said that .
I listened to Christopher Mills the other night .
Then reviewed everything discussed .
And only ended up with four investments that I considered interesting .
Animal care
TCICap
Assetco
Pendragon
Rest didn’t like so much, and none of the above except animalcare are likely to be big holdings in the future as they are non IHT Aim which is another big box I like to tick .
Normally would stick on a watch list and not buy straight away
However at the moment I take starter positions as I want money in the market as it looks like market is turning .
have to say I do have a very high “agreement” rate with Staveley / Rockwood though I don’t like Flowtech , pressure tech and a few others .
That's all fair enough. My comments were prompted by an observation that these managers get many highly positive mentions on these threads (not just by you) to the extent that critique of the related stocks almost becomes a secondary consideration. Just thought it was worth highlighting this imbalance, that's all.