Small Cap Value Report (Wed 20 May 2020) - macro, PMP, MCB, JDG, BMY, CLL

Good morning, it's Paul here. No silliness in today's preamble. Just to reassure readers who posted concerned comments yesterday about me naming & shaming a young lady in Bournemouth - relax, as I made up the name!
Please see the header for company announcements I'll be covering today.
Estimated finishing time - today's report should be largely done by 1pm. Edit at 12:57 - Today's report is now finished.
Here are a few interesting news items that have caught my eye, together with my comments;
CNBC reporting that 40% of S&P 500 companies have withdrawn profit guidance for 2020. (Paul: how can market be so buoyant, when so many large companies cannot predict their trading this year? Risk that markets may not be properly factoring in potentially very bad 2020 figures. We need to treat all UK broker forecasts as probably far too optimistic, unless a company has specifically confirmed it is trading in line. In fact, I'm basically ignoring broker forecasts right now, as they're largely defunct - a very unsatisfactory situation. Just because it's difficult to predict, doesn't mean you should stop trying, if that's your job!)
Walmart reported strong sales, but it's incurring higher costs, e.g. additional cleaning, and staffing costs. (Paul: so even businesses that are trading well during the crisis, could see a squeeze on profits)
Chancellor of Exchequer has made ill-advised comments in a committee hearing - does he not realise these are televised? He described the UK as facing, "a severe recession, the likes of which we haven't seen". (Paul: if that's what our top finance man in Govt thinks, then we should be very worried, and cautious, in my view)
Air travel - proposals being mooted for "air bridges" - i.e. reciprocal arrangements with other countries which are seeing low covid levels. (Paul: could be why Dart (LON:DTG) shares shot up yesterday?). Also, the UK 14-day quarantine period being introduced apparently will not have an exemption for France. I've no idea why it has taken so long to introduce this measure, when it was needed a couple of months ago.
Vaccine - news from $MRNS about its success in early stage covid vaccine trials, which is reckoned to have triggered the Dow's 900 point rise yesterday, is apparently not so exciting after all. US markets gave back about a third of yesterday's gains.
CLBILS (Coronavirus Large Business Interruption Loan Scheme) - Govt has raised limit from £50m to £200m, a very significant announcement. Large companies can borrow up to 25% of annual turnover. It's a loan guarantee scheme. Divis & cash bonuses banned when using this scheme (good!). Higher limit available from 26 May. Note that N Brown (LON:BWNG) told us yesterday that it had borrowed £50m using this scheme, so perhaps the increase to £200m would give it extra possible funding, which is positive for the shares.
Let's start with a few items left over from yesterday.
Portmeirion (LON:PMP)
Share price: 390p
No. shares: 10.64m
Market cap: £41.5m
Portmeirion Group PLC, the designer, manufacturer and worldwide distributor of high quality homewares under the Portmeirion, Spode, Royal Worcester, Pimpernel, Wax Lyrical and Nambé brands...
My notes from 16 Jan 2020 here are quite useful to bring us up to speed. 2019 results were in line with expectations, but broker forecasts had been heavily reduced during 2019. So the business wasn't really firing on all cylinders even before Covid-19 began.
2019 results - headline PBT fell 24% to £7.4m in 2019, or 56.3p adj EPS. Final divi cancelled. Balance sheet not as strong as previously, due to debt taken on for acquisitions. I imagine it must be struggling to collect in receivables from its retailer customers.
A new joint broker (Panmure Gordon) was appointed recently on 12 May, which can be an indication that a fundraising might be on the cards perhaps?
30 March update - extending usual 1 week Easter factory shutdown to 3 weeks. Reduced customer orders from UK & USA. Strong online sales growth in March. Far Eastern markets starting to return to normal. Significant order book for overseas markets. Wax Lyrical (candles) subsidiary has converted production lines into making hand sanitiser & spray. Cash conservation & cost-cutting gone well. Outlook uncertain, but group is well positioned.
19 May update - partially re-opened factory on 6 May, so shutdown was about 6-7 weeks, not the previously planned 3 weeks. Capacity will be increased further in coming weeks. Warehouses fulfilling eCommerce orders successfully. Wax Lyrical to ship more than 1m units of hand sanitiser in Q2. Here are its sanitiser products, which seem to retail at typically £3-5m, so wholesale price probably not much more than £1 per unit, hence this doesn't look material to the overall group results.
Business has been "significantly impacted" due to retailers being closed. Expected to continue in Q2. Export orders to Far East being shipped, as they are opening up again. Significant uplift in UK & USA online sales (up over 100% in April), expect this trend to continue. Cash burn in Q2 less than £1m. Sufficient bank facilities & headroom. Divis - will reinstate as soon as they can.
My opinion - this doesn't sound too bad, in that solvency sounds OK. Although cash burn was only £1m in Q2, remember that the P&L loss could be much worse, because companies are deferring many cash costs, e.g. delaying tax payments, etc.
Given there is so much uncertainty, and no profit guidance, I don't know how to value this share. As with so many companies, we cannot rely on the now defunct broker forecasts. Actual results are likely to be far worse, but no indication has been given of how much worse.
Overall then, I don't have enough information to form a view. There doesn't seem to be any risk of it going bust, so long-term holders should feel reasonably relaxed about sitting tight, I think.
.
Mcbride (LON:MCB)
Share price: 62p (up 8% yesterday)
No. shares: 182.8m
Market cap: £113.3m
McBride plc (the "Group"), the leading European manufacturer and supplier of Contract Manufactured and Private Label products for the domestic Household and professional cleaning and hygiene markets, today provides a trading update for the current financial year, ending 30 June 2020.
McBride seems to be making products which are very relevant to the current crisis, which sounds positive;
Further to our update on 25 March 2020, demand levels in our Household business have moderated from the surge seen in many markets as countries went into lockdown but encouragingly remain above the run-rate levels seen before March. These higher demand levels are evident in most of our major markets and apply mostly to surface cleaning and dishwashing products, with more limited impact in laundry products.
This is all self-explanatory;
Our teams have worked well to address the early challenges of staff shortages, material availability and distribution blockages and all factories are currently operating at more normal activity levels.
As anticipated in our March update, we have seen lower input pricing in this period although some of this benefit has been tempered by one off COVID-19 related operating costs.
This company has also jumped on the hand sanitiser bandwagon!
Profit guidance - a bit of a positive bombshell here, very impressive;
As a consequence the Board now expects full year adjusted profit before tax to be approximately 15% ahead of current market expectations (*) and for net debt at 30 June 2020 to be lower than expectations.
(*)Current market expectations refer to a Group compiled consensus for FY20 of adjusted PBT £18.6m.
Lovely to see the company include that footnote, giving market expectations, that's so helpful.
My opinion - this is clearly a positive update. Although if you check back, the company has been under-performing for several years, with EPS in steep decline.
I'm not madly keen on its balance sheet - this is quite a capital-intensive business, not generating much of return from a lot of fixed assets. Therefore it's not really a sector, or company that interests me. However, it's performing well in this crisis, and the valuation looks cheap. Therefore it might interest value investors at this level.
.
Judges Scientific (LON:JDG)
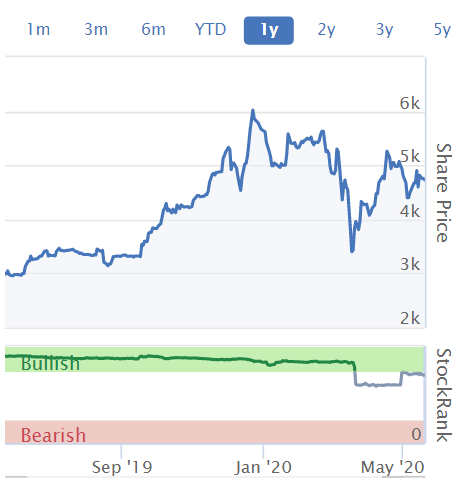
Share price: 4,750p (flat on the day, at 09:02)
No. shares: 6.25m
Market cap: £296.9m
It opened down 2%, but has since recovered, although only on tiny volumes printed so far. Hence the price could go anywhere over the next few days, being so illiquid.
Judges Scientific, the group focused on acquiring and developing companies in the scientific instrument sector...
Orders - there's been a sharp downturn in new orders;
Across the Group, organic order intake as of 15 May was down 18.5% compared to the same period in 2019, caused by the closure of universities, the cancellation of scientific conferences and our inability to travel. This reduction in order intake has not been evenly spread across our key geographies with China/Hong Kong and the UK each decreasing 4%, North America experiencing a reduction of 25%, the Rest of the World reducing by 22%, whilst Rest of Europe decreased 11%...
Clearly that's bad news, but the order book overall is still "comfortable", at 11.9 weeks. This is down from 13.2 weeks organic order book at end 2019.
Profitability -
The Group has operated profitably in each of the first four months of this year and has generated positive operating cash-flow for the period. As a result, the Group has maintained a robust balance sheet with solid liquidity.
More information is given about operations.
My opinion - this is all a bit vague. I think we can conclude that the company looks secure financially, and hence there's probably not any insolvency risk. That said, it's not possible to ascertain what level of profitability is likely this year.
Broker forecasts are now out of date, hence need to be ignored unless they are recent, and specifically adjust for covid.
This share has done brilliantly for investors in the long term, hence I certainly would not bet against it. That said, the current valuation seems very high, given the uncertainty over future earnings. It seems to be priced as if covid hadn't happened. That doesn't make sense to me. Nice group of companies, but it's over-valued right now, in my view. Why pay top whack, given the earnings are likely to fall considerably this year, and who knows when recovery will take place?
EDIT - an email has come through from WH Ireland, saying that it lowered FY 12/2020 forecast EPS by 30% in March, to 152.4p. It says today that this forecast is retained, but "arguably with more risk attached". I'd be surprised if JDG does hit that target this year, so why take the risk of buying/holding now? However, there could be recovery potential in 2021. End of edit.
.
.
Bloomsbury Publishing (LON:BMY)
Share price: 215p (up 2% today, at 10:02)
No. shares: 79.1m
Market cap: £170.1m
Bloomsbury, the leading independent publisher, today announces unaudited results for the year ended 29 February 2020, in line with expectations.
That's really useful, telling us that the figures are in line with expectations right at the top of the announcement.
Being pre-covid, these results are not terribly relevant, with outlook comments being more important right now.
FY 02/2020 - adjusted earnings up 12% to 16.8p - the PER is 12.8
Net cash of £31.3m at 29 Feb 2020. Why did it then do a placing, raising £8.4m in April 2020? How bad are FY 02/2021 results going to be?!
Covid/Guidance - this is rather waffly;
Since the year end, the coronavirus pandemic has led to significant disruption across all our key markets. The impact may be substantial.
Orders for print books, which comprised 79% of the Company's revenue for the year ended 29 February 2020, are being affected in all our markets. Our UK, US and Australia warehouses remain open and continue supply to customers.
Our strategy of expanding and leveraging our digital rights and products means that we are well placed to benefit from increased demand for our digital resources, audio and e-books.
There is no immediate certainty around the severity and duration of the impact on our business and therefore the Board is unable to provide guidance for the year ending 28 February 2021 at this time.
Current trading - much more useful, and this seems to show that the business is resilient. The closure of schools & Unis looks to be positive for BMY, as learning moves partially online. I like this;
April 2020 year-to-date revenue is 3% below last year, with print revenues at 87% of last year's sales and academic digital revenues up over 52% year-on-year.
Although this sounds a lot more positive than the tone of the comments further above, which sound much more bearish. Maybe the company is expecting demand to reduce as this year progresses? It's not very clear.
Plausible downside scenario - I'm really pleased to see the company joining others that are informing investors as to their stress-testing. This is vital information, that all companies need to publish. Here it is in full, as this is useful to flag up;
The Board has modelled a severe but plausible downside scenario, including the impact of coronavirus. This assumes:
· Print revenues are reduced by 60%-65% for the three months of expected global restrictions to July 2020 and gradual recovery through to March 2021;
· Downside assumptions about extended debtor days to the end of 2021;
· In this scenario, we extend the cost reduction measures already implemented, as set out above.
Under this pessimistic downside scenario, we expect our business model to be able to manage these downside assumptions and stay within the headroom of our current banking facilities.
Should a prolonged downside scenario not materialise the equity placing proceeds will be used for future growth opportunities. Bloomsbury has a successful track record of acquisitive growth via 26 strategic acquisitions and we continue to see opportunities in the Academic markets.
.
That's really useful information, well done Bloomsbury. Although modelling such a large drop in revenues does suggest that revenues must be getting a lot worse than the March to April downturn of only 3%.
Note also that receivables could be an issue - not only delays in receiving payment, but I imagine solvency of customers could also be a problem - hence expect potentially a big increase in the bad debt provision this year.
My opinion - it's financially secure, so insolvency should not be an issue.
However, I am a bit shocked by the potential downside outlined in the plausible downside case. It's good to see the worst case scenario, but if that did play out, then there would be plenty of scope for the share price to fall significantly.
The lack of earnings visibility puts me off. If the price were about half the current level, then risk:reward would look more appropriate for me personally. On the upside, the online growth looks good.
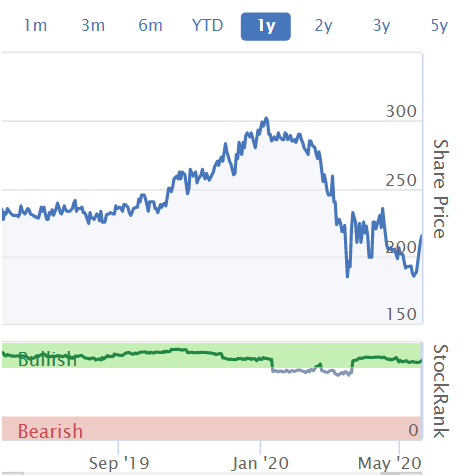
Looking at the chart, the current price is only slightly below where it was last summer. Yet the economic outlook was OK then, but is now dire. Can anyone explain to me how that make senses?
.
.
Cello Health (LON:CLL)
Share price: 119p (up 4% today, at 12:31)
No. shares: 106.2m
Market cap: £126.4m
Cello Health plc (AIM: CLL), the global healthcare-focused advisory group...
Updating for FY 12/2020.
- Good Q1 (but that was mostly pre-covid)
- Q2 also going well. especially in the US - hence confident about H1 results to come
- Supporting Covid-19 public health campaigns
- Cello Signal (16% of Q1 revenues) likely to be more impacted by covid-related delays & cancellations - so have reduced costs
- Solid net cash position, it says. Still paying 1p interim dividend shortly
- Cash generation good
My opinion - this sounds a reassuring update. The focus on healthcare is clearly good news. That said, I wouldn't want to be holding any shares in the marketing sector right now. It's the first thing customers cut, when going into a recession. Although the healthcare focus for Cello could be its saving grace. Not for me.
That's everything I wanted to cover today, so will leave it there.
Graham's putting away his trowel, dusting off the soil, to write tomorrow's SCVR for you!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
It doesn’t need the chancellor to make these comments to make everyone realise the situation the world is in. This will be a depression not a recession leading to the collapse of the dollar and a resetting of the financial system. Only plays in town are gold silver and gold/silver mining shares as leverage.
Usual stuff - speculation dressed up as undeniable fact. Really! D minus - must try harder!
Interesting after hours update from Dart (LON:DTG) Proposed placing for up to 20% dilution, raising a minimum of £100m to waive banking covenants for the summer but up to £170m. Trading update to end of March reads well but is kind of redundant for the time being. They give three different scenarios for being able to fly again in a phased way
Dart Proposed Placing
re Marks and Spencer (LON:MKS), I always thought that considering their market (for women's clothes) Sosandar (LON:SOS) seemed to be a very obvious purchase?
It's possible. Given that the stock market route hasn't really worked for Sosandar (LON:SOS) so far, and that it might need yet another funding round, then selling it to Next (LON:NXT) or £MKS could make a lot of sense.
SOS management have done a fantastic job compared with other online fashion startups in recent years. The mistake was seriously under-estimating the marketing costs. That said, they've created something valuable, and unique. It could well have value in excess of the current valuation, and probably does. Is it likely to be a 5-10 bagger now though? Probably not.
I don't see as much share price upside now, so have partially lost interest in it. Better fish to fry. We all only have a limited amount of time & energy after all.
The UK Govt (possibly supported by Cello Health (LON:CLL) ?!) keeps putting out this advert every few minutes on CNBC's audio feed. It says;
Stay alert. Control the virus. Save lives
This is utterly ridiculous, and if it has to be explained in depth, then it's rubbish. If we must be governed by slogans, let's at least get them right.
I've come up with a much better slogan;
Keep your distance. Protect the vulnerable. Lose some weight
There we go, sorted.
I've sent the above to my excellent MP, Tobias Ellwood, together with a suggestion that he furloughs Dominic Cummings, who has clearly peaked, and needs a good long rest. I've suggested he is reassigned to other duties.
Paul
I enjoy your commentaries & your retail focus.
But this now is redundant.
Now that the High Street, Pubs, Hospitality are mostly bust, why not study the Healthcare companies?
Testing is here to stay.
Thanks Paul, great write up as always.
Just a reminder, at tomorrow's piworld Thursday webinar, we welcome Reg Hoare: Investment Trusts - An Investing Panacea for Pandemics. Reg will discuss the attractions of Investment Trusts for the time poor retail investor and how they can be used to get concentrated exposure to sectors and themes - whilst getting some sleep at night.
Please join Reg and I, via this link.
Reg is a Managing Director of Engine MHP Communications, the leading Financial & Corporate PR firm where he specialises in advising mid-market companies, from FTSE 250 to AIM 100. He has over 35 years’ City experience including a decade in investment banking and securities. In his spare time he is an active private investor, managing his own SIPP and other investments.
Here's the recording of last week's webinar: Everything you've wanted to know about Market Making ... but never been able to ask! Spencer Crooks, ex Director of Market Making at Winterfloods, gives us his perspective on the other side of the trade.
Hi Paul. Interesting comments as always. I agree with you on M&S . Covid will be a catalyst for the business getting back on a growth track. Any thoughts on the release from Modern Water this morning?
Indeed, Covid might (!)be a catalyst for change at £MKS
Modern Water (LON:MWG) - it looks like a marketing type announcement (Reach) from it today, about winning an award. Its financial track record is terrible. Speculative, so not something I feel I can add any value on.
Worth a look. I bought MWG at 0.049p Took some profit today (not all) at 5x in just a few weeks. They have new management, new facilities, new A.I. tech coming. Systems in place are worth more than the market cap. World governments wanting to test water, the cruise industry will need this to get back. The link with SKIN is very good news to what was a poor run company. Real turn around happening there imo.
Paul I thought you would be interested in Avct announcement this morning? Kumani of Boohoo fame has set up a business called Medusa to distribute the Avacta antigen test. I am split on it. My first instinct is outrage at the way he and the wife of Zeus Capital guy invest £1m each at 18p days before an announcement that sees the shares rise 80%!! At the same time Zeus are appointed as a second broker. This is just the sort of behaviour that makes me sick to the craw, there will be some plausible PR people put up to represent them or an enquiry by the absent authorities but it will all be pushed under the carpet. Anyway on the other hand it is an interesting idea that we are just dealing with mass distribution here and Boohoo have the right pedigree for that.
Hi Camtab,
I've been following the Avacta (LON:AVCT) story with interest. Annoyingly, I participated in a previous placing, at a fraction of the current price, but sold out before the price went parabolic.
It's far too speculative for me to write about here. As you know, I don't cover blue sky pharma type companies, as I have no skills or knowledge to be able to add any value. Feel free to discuss it with other subscribers here if you like.
Best wishes, Paul.
Hi Cantab
Similar comments on the Avacta (LON:AVCT) announcement were made by someone I follow on twitter this morning but I struggle with the argument.
Of course we (shareholders) could be getting screwed but I like to look on the bright side.
Also:
So to summarise:
Yes I am biased as I hold (only since May 1st) and am aware that it could all come to nought but I think the risk reward is worth it.
Best wishes
Michael
Camtab
It stinks to high heaven but unfortunately (only in my opinion) this is how the world works.
Insiders are always going to profit - our job as investors and traders is to spot the insiders gaining (before the widespread market does) and then piggy back off it... it's all we can do and if one can do it correctly, there is money to be made out of the opportunity. (Only my opinion). So one can monetise this higgery jiggery.
My opinion is that Avacta (LON:AVCT) Avacta will see further share price growth.
I have been in and out since c46p and am firmly 'in' now. My observation is that the sp rises on news flow... (it is down today because, many, like you, can't stand the stench of insider incestuousness have bailed out)... but when the biggie news items hit*, the shares will soar. And from what I see, the chief exec, Mr. Smith is cunning in dealing with the market as well. He seems more of a business man than a scientist. I like that. Hopefully he knows how to make money.
Here is a non exhaustive list of news flow which will come down the tracks in the coming weeks.
* Cytiva produce prototype of lateral flow test
* Cytiva get approval for lateral flow test (BIG)
* Cytiva start selling lateral flow test (BIG)
same for Ademptrix
* Ademptrix produce prototype of their test kit using Avacta Affimers
*Ademptrix get approval (BIG)
*Ademptrix start selling kit (BIG)
Then you have
*Other partnerships/manufacturing agreements (BIG)
* Produce tests by themselves using a contract manufacturer (BIG)
Then you have the numbers that start to come in.... (HUGE)
(Disclaimer, I hold so have confirmation bias) DYOR etc.
* I forgot to mention potential therapeutic application of Affimer technology against covid Doh !
Doh! I forgot to mention the original oncology purpose that could be huge.
anyone following AO World (LON:AO.)? Up 100% this month and now +30% YTD. Reported results to March 20 in line - pre IFRS16 EBITDA breakeven and operating loss about £10m. Still never posted a profit. Post lockdown gaining market share in a reducing market. Given state of UK job market demand for new fridges and washing machines surely lower. Market cap now £550m. Disclosure (painfully) short.
Cash flow positive going forwards. Huge demand for online shopping as people get more used to buying staying home and buying online. Job market poor but lots of people not spending money going out on restaurants/ pubs or petrol so spend on household items instead. Still only 0.5 times sales and sales will grow a lot this year and next. Disclosure long.
Re AO World
I'm not an expert on this area of retail, but a couple of thoughts :
1. I think it is a mistake to think that everybody is worse off at the moment, a lot of people are still working, others are furloughed and yet others drawing the pension. Whilst opportunities to spend on the hospitality sector etc. are seriously curtailed. Don't get me wrong, I do know that some people are facing real hardship, but overall I suspect there is at least as much spending power out there as there ever was.
2. Maybe it is just me, but I don't think most spending on white goods is discretionary - I don't think there is much of an upgrade cycle for white goods - you use them until they go wrong and then replace them. Maybe the lack of house moves and kitchen upgrades will cause a bit of a slowdown, but not much I would have thought.
In fact when people were panic buying food at the beginning of all of this, I also found they were panic buying freezers!
With bricks and mortar competition shut-down it has got to be a good time for an online retailer like AO.
So I would expect them to be doing really "well" at the moment and they seem to think that much of the move to online will stick (not so sure myself).
However they are still along way from profitability and I would not want to pay a PE ratio of 60x 2021 earnings - especially when they have the habit of over-performing on the top line but underperforming on profit.
I had been short AO. in the past and may have another look when their results are out in mid-July.
Hi Paul, would be interested in your words of wisdom on Playtech (LON:PTEC) if you ave time.
Is playtech too big for this report? Graham has written a few words about it in his midcap report on his cube investments website.
Yes, I had a quick look, but decided Playtech (LON:PTEC) is not one that I want to cover. Its market cap is a bit higher than I usually cover here, plus it would up too much time for me, as I'm not familiar with the company. So maybe 2-3 hours work, when I'd rather focus on companies I already know, which take 30-90 minutes per section to write about.
Sorry about that.
Glancing at the PTEC Stock Report though, it looks a nice profitable business, and modestly priced. So could be quite good to take a look at on a quieter day possibly?
I think we are starting to see the torrent of unemployment bad news now. Such a sad business for many people.
I am associated with a business which is holding up quite well. It has moved to reduce hours and some furloughs to reduce some costs. Most staff accept the relatively small sacrifice of the reduced hours, but subject to what the landscape looks like after lockdown, its hard to imagine there won't be some reduction in numbers. However, there may also a mix of reducing hours on a more permanent basis for others. Maybe the Corbyn promotion of a 4 day week is not so far away!
If so I suspect this will mainly be on a voluntary basis rather than via State legislation. Maybe the State will encourage this mixed approach by some incentives to try and reduce overall the States benefits bill.
Yes, I agree. The furlough scheme is really just deferring a lot of unemployment. It's difficult to see what the Govt's exit strategy on this would be. I think it has little choice but to increase support for the hospitality sector, as it employs millions of voters,
I have little exposure to the hospitality sector - but I am not convinced by this logic. Rather than more money Government subsidy to the sector (much of it owned by private equity funds) surely there is a good case for letting existing businesses going bust at the expense of shareholders (and some lenders/ landlords) and let businesses be bought out in a pre-pack, where arguably there might be little adverse effect for employees. Admittedly, even pre-pack buyers of a then debt free business might still not be willing to come forward, until the sector is reopen, or there is a clear path to reopening.
Fair point, but remember that pre-pack admins only rescue the profitable units. Everything else is ditched - which can easily be 50%+ of the sites, and staff.
Another good trading update from Frontier Developments (LON:FDEV) today as they announce that operating profit will be materially ahead of £11-13m expectations as a result being ahead of £65-73m expectations. Second upgrade in a few months. Business looks very strong with the F1 and Warhammer IP's secured for games in the coming years and another major global IP still to be announced, plus their own games which also perform very well (Planet Zoo and Planet Coaster for example).
I hold but potentially valuation is starting to look a bit frothy. Expensive compared to Codemasters and Team17 for example but has a sector-beating ROCE, no debt and is held in high esteem for the quality of its games by its customers.
Justifiable premium IMHO due to the opportunity to distribute considerable volumes into China via Tencent, which is a shareholder. This may well be giving them an edge in signing up exciting new IP such as Games Workshop as this will also help Games Workshop (LON:GAW) to build brand awareness in the Chinese market. A virtuous circle in the making. Quite a powerful forward looking strategic opportunity which looking forward 5-6 years I feel should payoff considerably.
Is it true that Graham is ‘career-changing’ and becoming a gardener? Shame if it is.
He followed his tweet up, saying he was being satirical! It would certainly be a more relaxing career path than the markets anyway!
Could he compromise as a market gardener?
Marks And Spencer (LON:MKS), Im a holder, I bought badly! so for me its a Q of what can you learn from today? do I dump or just sit it out and average into a big rights issue.
Trading news is largely irrelevant unless you want to gorge on poor numbers. The one number that stood out to me was the free cash being £150m better than their Covid 19 scenario.
They budget for a return to normal by Feb 2021... which seems ambitious. However their new normal will be with £1bn less cost and a JV with Ocado. £500m to be achieved by 2021.
Peak drawdown on facilities is expected to be this Autumn... at £600m... with no covenant tests for a further year. They clearly need to bury as much as possible into the financial year 2021... so that in the calendar year 2021 metrics look better. For me better means less debt... which was ok today at £1.5bn. I don't think they have much room to take on more debt, and facilities are there to manage cash flow.
A 20% placing can bring in £340m but I'm not sure that's enough. £500m of stock being carried forward and £560m on order presents risk. Do not expect any bold fashion moves!
I think Marks And Spencer (LON:MKS) highlights what an interesting market we have here. Very difficult to analyse but some companies will emerge better from this. Marks And Spencer (LON:MKS) has had problems for many years but actually Covid 19 might provide the opportunity to completely rescale the business and emerge better. You just cant see it any numbers, not for 2 years I guess.
Im inclined to carry my position and average in around a fund raise. £500m may see them through but probably in feb next year... to support the balance sheet in full year numbers.
I think the £600m peak drawdown is in their scenario planning, but they later advised: "we consider the Group well positioned to exit the crisis with limited drawdown against its facilities in 2020/21" if current trading patterns continue. Also, Reuters is reporting "M&S CEO says sees no reason to raise more cash" but don't know where they got that from - especially as the analyst call hasn't happened yet. I'm holding, and waiting for the Ocado deal to kick in.
I'm a bit puzzled by your comments. The way I read it, today's RNS from Marks And Spencer (LON:MKS) makes it abundantly clear that it does not need to raise equity. It says drawdown on its debt facilities is only going to be £300-350m by March 2021. That gives it over £1bn headroom, so what's the problem?
The cashflow statement is revealing. Just look at cash generation at the top - reverse out the depreciation charge, and it's still throwing off tons of cash. With capex likely to be reduced considerably, and no divis for a while, then I see it as being financially secure.
It's strange the way it reports net debt including IFRS 16 adjustments, which seems crazy to me, as the market wants to see net debt reported without these lease adjustments. It should at least report both numbers side by side. A lot of the properties are freehold too, remember.
Very much a glass half full/empty share! I see it as a survivor, with a good opportunity - the food offering is superb, and gets affluent customers into the store, who could then be tempted to buy clothing/homewares, if they improve the product - why is this so difficult?! They've spent years trying to improve clothing, and getting it wrong time & time again.
Agreed. I was encouraged by the RNS and have increased my holdings .
Apologies, perhaps I wasn't being clear... they have facilities, and can use them, but IF they do...what next?
They do separate out net debt, excl IFRS 16... it is unchanged at £1.5bn in the opening summary. The facilities if drawn will increase this. So whilst they don't run out of cash .... the net debt will rise from £1.5bn at full year 2021... and I think this will be seen as too high. Q Do you think Marks And Spencer (LON:MKS) will emerge from the next twelve months as a business able to carry more financial debt, pay a dividend, invest in the business and manage working capital? A For me the answer is no...
Ofcourse the crux here will be guidance for their financial year 2022. Here taking a view on adjustments is the largest swing factor £336m this year, £427m last year... the problem being this coming year its likely to be high again. This affects borrowing levels the market is comfortable with.
Lets assume by Feb 2021 retail has not returned to a normal monthly run rate, its actually 10% behind... that Marks And Spencer (LON:MKS) has excess stock to clear ... and so has drawn on debt facilities £500m.... so net debt is £2bn for year ending March 2021. I think its reasonable to say this trend is unsustainable. I am not saying it goes bust...I would also never say it has zero chance of going bust. I am simply asking how much more money we think they might need. I think the answer is they will have to replace the rise in ent debt.
I would not take comments at face value re not needing to raise money... if the market wants them to raise money, they will. That is why Im trying to work out how much they may need..... and whether that is a stretch or not.
There appears to be confusion around the availability of liquidity and drawdown capability. Whilst many companies have the headroom in their committed facilities, as already noted below, it does not mean management should or could draw on these facilities. Not only would this increase the leverage (M&S is already way too high, hence the junk rating), finance service costs and refinance risk but they are usually drawing this against weaker trading meaning the EBITDA will be lower and, therefore, more likely to restrict or prevent future drawings due to covenant restraints. It may also be an announceable event should they do so intentionally which would worry the markets.
I note that M&S has already renegotiated with their lenders to amend their covenant test through until Sept 2021 which will provide some headroom (typically 15%) but this is not only concerning in itself it will have been at a cost... and what happens in Sept 21 particularly if they have needed to drawdown additional loans and leverage is higher against weaker trading?
As I mentioned a few days ago, M&S is basically shot to bits, both the operating model (which is not fit for purpose in retail today) and the balance sheet is weak and over-leveraged (net debt remains >£4bn). The results note that the impact of COVID in March alone was £83.7m and the base case forecasts show material trading issues during the FYE 3/21, including:
UK clothing and home - 70% decline in revenue for the four months to July - full year negative impact £1.5bn
UK food - 20% decline in revenues to July - full year negative impact £400m
On the basis that profit after tax was £37m for the FYE 3/20 (with the benefit of no final dividend) on annual revenues of c£10bn (margin 0.37%), the next year or two looks to be quite daunting.
It is also worth noting the FCF has reduced by £355.8m (61%) from £580m to £225m less dividends = FCF after shareholder returns of only £34m (87% reduction 3/19) - this would have been far worse if the company hadn't cancelled the dividend (£130m) and also deferred CT and VAT.
It is not clear why M&S actually exists as it remains a consistent economic value destroyer. Whilst there is not doubt the company does have some good products (this apparent strength is constantly highlighted as a saving grace, which it isn't) it is just not able to sell enough of these at a strong enough margin to cover its economic costs and deliver value-creating returns for equity providers. Equally concerning is capital structure with debt >2x the market cap and leverage in high risk territory.
Consequently, I see any investment into M&S as more of a gamble that may at times benefit from certain market trends or momentum particularly when lockdown is further eased but, as a value-creating investment, I will continue to leave well alone.
Completely agree. It has been moribund for ages in my view.
MKS....my view is that there is still a real business here and the food distribution deal could transform. I see it as a takeover target too; it would be buttons for a major US company interested in the brand name and the website potential. I hold and have a target of 130p by late summer as I think the lockdown will end by then.
I’m not sure how you arrive at a 45-50% increase in market cap in the next 3 months when trading is forecast by the company to be dire. The numbers to FYE 3/21 are likely to show a significant fall in revenue, further squeezed margins, losses, negative FCF and increase in leverage (again)... and a further 12 months of restructuring which has been going on for c25 years since the mid-1990s problems.
The food is a red herring as the revenues, margins, profits and cash flows do not deliver the requisite ROC - too much capital is needed in the business which is structurally flawed.
Re M&S: superb food, affluent customers; food hall usually very busy, most of those customers by my observations tend to be in the 40+ age group, yet look at the clothing on offer - the older shopper is largely forgotten about. My wife, who's quite tall, tries to buy work trousers there when she's in getting food but invariably finds that two pair off the same rail and marked the same size are actually different - quality control?
The Men's offering has improved greatly and it is nice to see them supporting British woollen mills - but why do they mix polyester into everything? Linen jackets with polyester lining seems a contradiction if one is looking for a summer jacket. The affluent customer tends to shy away from man-made fabrics and will pay a bit more for quality - or maybe that is just me. As for those two words that strike terror into many of the men in the Food Hall, "Slim Fit" - need I say any more?
Quite - if M&S have so many older customers , what the hell is this Slim fit all about !!!
If its to attract the younger hip / skinny ! shopper then pigs will fly before any youngest goes to sop at M&S.
Sop or shop !
I think you have to face up to it being a dead business. 1,000 stores? Warehouses full of merchandise? An impaired brand.
Agree, and many of the stores are subject to onerous leases, in the wrong place, the wrong size and selling too many of the wrong products that not enough customers are willing to pay for... hence why they are trying to exit so many.
A tortuous job...
I am quite interested in Newmark Security as an investment but worried by the small market cap?
Any views out there on Newmark or what the minimum size of market cap one should have?
My morning smallcap tweet: Water stops flowing uphill at Malvern
Newmark Security (LON:NWT) Aeorema Communications (LON:AEO) Judges Scientific (LON:JDG) Frenkel Topping (LON:FEN) Malvern International (LON:MLVN)
Newmark Security (NWT) guides FY(Apr) rev marginally lower, as previously anticipated, due to lockdown. Unable to give profit guidance. Some momentum in sales of new products at Safetell seen before covid. "The Group is also looking ahead to the "new normal" for its customers with expected market evolution towards 'contactless' methodologies being adopted in the HCM sector. Additionally, Safetell's advanced door portals would provide safer employee working conditions and/or customer interaction." One of Grosvenor's US customers, Ultimate Software, announced a merger with Kronos Inc. Expects that Grosvenor will switch Ultimate to using its own timeclock.
Aeorema Communications (AEO) guides FY(June) pretax loss at lower end of previous guidance of £150 - 250k. Still confident that rev and profit from postponed events will fall into FY21. Well, some might, I doubt all will.
Judges Scientific (JDG) AGM stmt: organic YTD order intake down 18.5% due to caused by the closure of universities, the cancellation of scientific conferences and inability to travel. Co has been profitable in each month. Co has only suffered minor supply chain issues, all of which have been mitigated and managed accordingly.
Frenkel Topping Group (FEN) activist shareholder Christopher Mills climbs aboard the board, no doubt eyeing the tiller.
Malvern(MLVN) the anticipated fundraise thumps down at 15p, a 61% discount to the astonishingly levitated recent SP (up to 55p) of this car-crash cash-bleeding education outfit. £1.17m to keep the lights on.
Hi Paul,
What is your opinion on £MKS. I have a long position here and thought I got in at the bottom. The food sales are going really well. I know the clothing side is not doing that great at the moment apart from maybe online retailers. However I thought this was already priced in. Since I have bought around maybe April, the price has fallen to 85 - why is that ? There results are out today which will probably just confirm the above. What do you think, is it still worth holding for the short term ? Long term I think it will be fine, I just don't know if I have the patience tho.
Thanks,
TA
I look at M&S and see bankruptcy looming. FTSE to much of a risk and the F-Score proves that. I also think about how COVID will continue to effect other businesses from the simple stat of 0.3% of the UK population has been infected when the population requires 60% of their genocidal herd immunity plan. If all of M&S stores had been foody type stores then maybe worth a punt but that element of that business is to small currently. Me personally I would get out if you can.
Re Marks And Spencer (LON:MKS) you see bankruptcy looming? Are we reading the same RNS?!
Maybe you didn't read the section about scenario planning, where it lays out the figures, and demonstrates how it will only be drawing down modestly on borrowing facilities by year end 03/2021. It has over £1bn in borrowing headroom, so there's clearly no question of insolvency at all.
Depends On the overall outlook really, I dont see drawing down more debt on the mountains it already has, in a critical situation, a long term positive.
Morning arshadte,
I've spent the last hour going through Marks And Spencer (LON:MKS) results.
The figures are historic now. I like they way it lays out scenario stress-testing for covid. There's tons of liquidity headroom, with it only drawing down modestly on borrowing facilities. Hence zero chance of it going bust.
Lots of positive stuff in the commentary. Looks like covid is forcing it to modernise, doing things that should have been done years ago.
I like the split of food & clothing into separate reporting. Food margin of 3.9%, clothing margin of 7.0% - bit of a surprise there, in that food isn't quite the star I thought it was, and clothing still decently profitable despite poor -6.2% LFL.
Lots of opportunity with Ocado JV launching in Sept.
It will be interesting to see any broker updates over next few days.
Not sure how the market will react, but personally I'm sitting tight on my long position. I think the business has a lot more potential than people seem to think, especially when its excellent food offering goes online.
Regards, Paul.
Marks And Spencer (LON:MKS) from the Investors Chronicle -"In particular it looks as though M&S has learnt just how important online is – so it’s making its Ocado venture more central to the business, introducing 1,600 Clothing & Home lines to be available online via Ocado. Much smaller store footprint, more focus on food, leverage the Ocado platform – there is at last a lot to be said for the MKS approach"
I think the Ocado link up is very exciting and can transform the business. My wife can hardly wait for Ocado (who we rate very, very highly) to start delivering M&S Foods on top of their existing branded products.
Paul its not liquidity. Its solvency that will be the issue. Sure they can add debt but if they continue to pile up losses there will be a solvency event. Think of the balance sheet that will emerge from this situation. The estate is too big.
Can you tell me what you mean by continue to pile up losses? When was the last year it reported a loss, or had a negative free cash flow.
In 2019 they had a cash flow of a whole £42m and in 2018 a negative £218m. This to sustain a company with £10bn sales and £6bn of assets.
https://corporate.marksandspencer.com/documents/reports-results-and-publications/annual-reports/annual-report-2018.pdf
Not according to the annual report!
Thanks Paul for you reply.
It looks like the market likes the news today.
I'm holding for now.
I will review once I see how the venture with Ocado goes in September. If the results are positive then I can see a big upside. Also it's good to know that they have enough money now so should not go bust.
TA
The SP jumped up to +98p on the open. The market is in highly oversold territory. Beware of a trend reversal too.
Hi Paul
I thoroughly enjoyed yesterday’s preamble. A little humour in times of trouble is always welcome.
My biggest surprise so far is how 7 weeks uncut hair can add a stone in weight. Who knew?
Best wishes from the Isle of Bute. Tennents Lager and no beach huts : -((
Douglas