Small Cap Value Report (Wed 21 Feb 2024) - GHH, HAT, EQLS, KEYS, CSSG, AQSG

Good morning, it's Paul & Graham here!
Reminder for this evening - Forensic stock analysis masterclass: How to get the most out of the StockReports in 2024.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
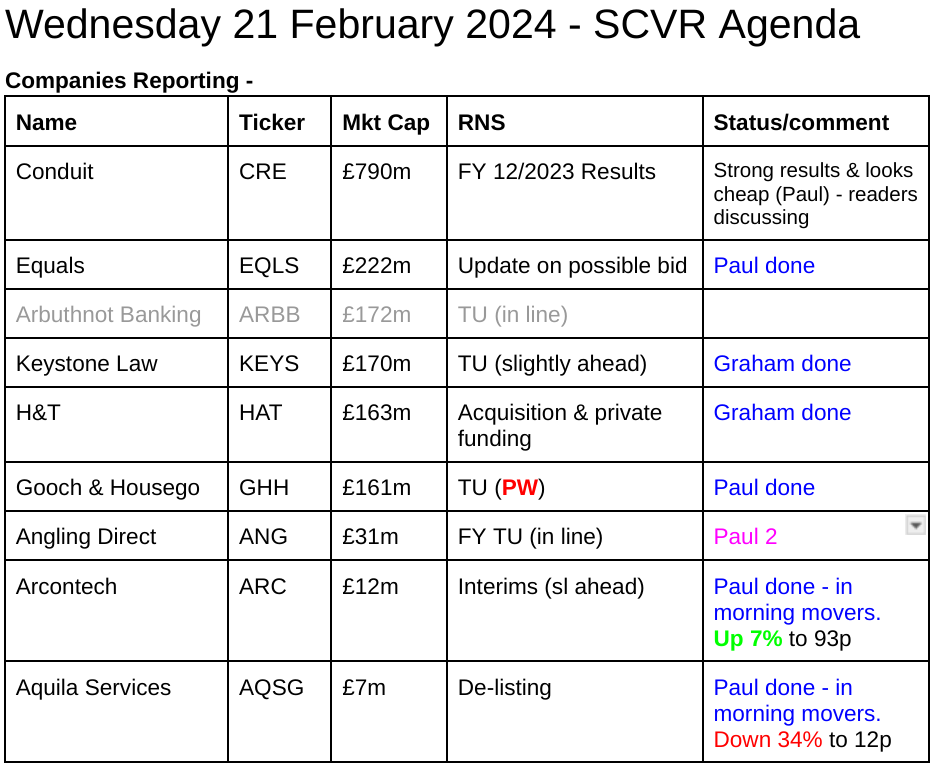
Other mid-morning movers (with news) -
Windward (LON:WNWD) - up 7% to 120p (£103m) - RNS Reach (ie marketing rather than regulatory) says INTERPOL started using WNWD’s services (AI for maritime) in H2 2023. Interesting company, and highly relevant given attacks on shipping. Jam tomorrow in terms of numbers, with heavy losses each year so far, so impossible to value at this stage. It’s been a nice punt so far, with shares in a strong up-trend. Good TU on 17/1/2024, ahead exps with losses reducing, and $17m net cash. Could be an interesting trade for the adventurous?!
Shield Therapeutics (LON:STX) - down 46% to 3.05p (£23m) - FY 12/2023 TU - reveals third party data errors that caused growth in prescriptions to be over-reported previously, esp in Q4. Also looks like it’s running out of cash - had $13.9m end 2023, but is cutting costs. Aiming to reach cashflow positive in H2 2025, which says to me it’s gonna need another placing before then. So I’m wary of this. Pity, as its key product (iron deficiency treatment) is being commercialised now. Might be worth a look once it’s raised more cash, but too risky for me before that - existing shareholders are often lambs to the slaughter.
Croma Security Solutions (LON:CSSG) - up 7% to 71.5p (£10m) - FY 6/2024 - H1 Results - in line, and “promising start” to H2. Disposal proceeds of £5.8m scheduled to be received instalments Mar 24 - Jun 26 - highly material risk if not received. NB the buyer, M&W Security (SC753198) was a newly created company, with no published accounts or track record. So there has to be some doubt over whether the instalments will be paid.
H1 figures very small, £362k PBT (a quarter came from interest received). Strong balance sheet with c.£10m NTAV, but about half is the dubious receivable for disposal. Too small to be listed. Maybe priced about right? See reader comments for more discussion.
Arcontech (LON:ARC) - up 7% to 93p (£12m) - Interims - tiny niche software company - H1 revs £1.45m, but very high margin (adj PBT £535k up 45% - most of the increased profit came from finance income earned on cash pile. NTAV: £6m, including net cash of £5.7m. Dividend yield of 4.4%.
Paul’s view - I can see the interest from value investors, due to excess cash pile, divis, and decent profits. Key question is whether the core business can scale up, then you would have a big winner on your hands maybe. In the meantime, mkt cap is strongly asset backed, so probably limited downside risk. Main risk is that its services might be legacy deals that gradually wither away? Worth a closer look though, I think.
Aquila Services (LON:AQSG) - down 34% to 12.1p (£5m) - Delisting - we’ve never looked at this share here. It reversed into a cash shell in 2015, and has really gone nowhere since. It’s a specialist consulting business, with most shares owned by individuals (management?) It says trading continues to go well, but that the listing isn’t delivering value for shareholders - fair point, I agree, it’s wasting probably hundreds of £k pa with a pointless stock market listing. Last H1 results were just above breakeven. Bal sht was fine, so this is not a distressed delisting. We need a mass clear out of tiny companies from the stock market, where having a listing provides no benefit, but lots of costs & hassle.
Summaries of main sections below
Gooch & Housego (LON:GHH) - 610p (pre-market) £157m - AGM Trading Update - Paul - BLACK (profit warning) - AMBER on fundamentals
Profit warning, with FY 9/2024 broker forecast EPS cut by 24%, so expect a similar % drop in share price today. Blamed mainly on customer de-stocking - why wasn't this anticipated? Also mentions some positives. I can't see any reason to get involved at this stage.
H & T (LON:HAT) - up 3% to 380.6p (£167m) - Acquisition and Additional Financing - Graham - GREEN
Interesting update from the country’s biggest pawnbroker as it buys a “posh” rival’s pledge book and takes over its Essex-based store. It also borrows £25m from a large international lender, not due for repayment until 2029-2031. Remarkably cheap if business stays strong.
Equals (LON:EQLS) - down 4% to 114p (£214m) - Strategic Review Update - Paul - AMBER
Today's strategic review update confirms discussions ongoing with Madison Dearborn, and the PUSU deadline is extended for the 4th time. It reassures that current trading continues to be in line with expectations. Shares look fairly valued to me, but I hope shareholders get lucky with a takeover bid, but after this length of time (since 1/11/2023) I wonder if the probability of a deal happening might be receding somewhat?
Keystone Law (LON:KEYS) - up 7% to 580p (£183m) - Trading Update - Graham - AMBER
This challenger law firm says that it has “slightly” beaten expectations for 2023, those expectations including adjusted PBT of £10.9m. It looks expensive for a law firm but the founder-CEO has achieved impressive growth without dilution in recent years.
Paul’s Section:
Gooch & Housego (LON:GHH)
610p (pre-market) £157m - AGM Trading Update - Paul - BLACK (profit warning), AMBER on fundamentals
Gooch & Housego PLC (AIM: GHH), the specialist manufacturer of photonic components & systems…
It’s another company blaming customer de-stocking for a downturn, this is becoming a widespread theme from many companies at the moment -
"Further order book growth but near-term demand impacted by destocking"...
… This period of inventory adjustment is proving to be deeper and more prolonged than previously anticipated.
Our semiconductor market customers have reduced near-term demand but still expect strong growth in the medium term. We have also received customer notification that certain US A&D programmes will no longer go ahead or have been deferred.
Impact on profit is about £3m - pity they don’t state what their previous (or revised) profit expectations actually are -
As a result, the Group's trading for FY2024 is expected to be more weighted to the second half and profit growth for the full year to be lower. Adjusted profit before tax is anticipated to be circa £3 million below management's previous expectations.
Broker update - Cavendish helps us by crunching the numbers, many thanks.
It puts through a 24% reduction in FY 9/2024 forecast EPS to 29.8p.
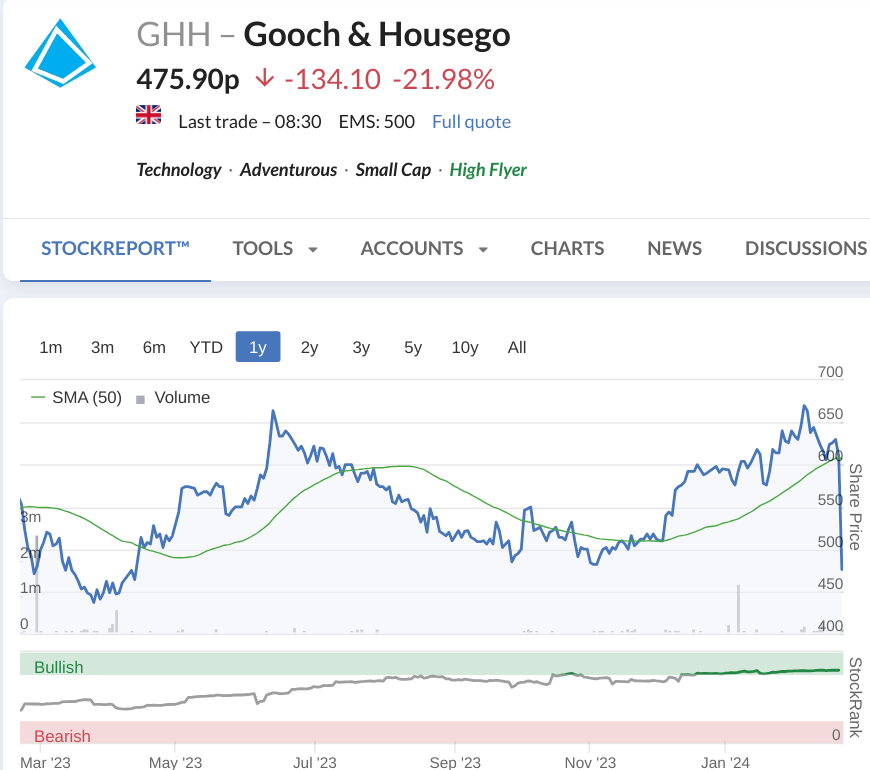
That makes the PER too high at 20.5x, so I would expect this share to take a tumble of 20-30% today (writing this at 07:46).
Outlook -
Given the strong medium term customer demand demonstrated by a growing order book, recent operational improvements and the Group's strategic focus, we believe we remain extremely well placed to respond quickly and benefit as several key end markets recover…
… Our review of the Group's product portfolio is well advanced and near-term actions in this area are expected to support the future profit margin improvement of the Group, especially in our A&D business.
Net debt is down slightly, but sounds quite substantial -
The Group's financial position remains strong. Working capital levels have been reduced in the first four months of the financial year and net debt at the end of January 2024 stood at £30.5m (Sept 2023: £31.7m).
EDIT: I've reviewed the last balance sheet at 30/9/2023, and it looks fine to me. NTAV is £60m. Strangely, the company scores an own goal by including lease liabilities in its net debt figure of £31.7m at 30/9/2023. Net bank debt was about a third lower, at £20.9m, and doesn't look stretched. I think inventories & receivables look a bit too high, so if I were the CFO my priorities would be to tighten up on cash collections from customers, and to get those inventories down. I reckon that could halve net debt, and hence save a fair bit on interest costs too. Anyway, I don't have any worries about solvency or dilution risk, so its balance sheet gets an overall clean bill of health from me.
Paul’s opinion - there are some positives in today’s update too, including strong order intake, with the order book having risen to £128.5m (9/2023: £124.1m). Operational improvements in its factories are mentioned, together with a review of product lines to improve future margins, and subcontracting out some products to lower cost producers (which does raise questions about GHH itself).
GHH shares have de-rated considerable in the last few years, and today’s update certainly won’t help.
I’m happy on the sidelines, waiting to see where the dust settles, but don’t feel particularly motivated to want to research this company further - why get involved?
Snapshot at 09:00 -
Equals (LON:EQLS)
Down 4% to 114p (£214m) - Strategic Review Update - Paul - AMBER
Today’s update provides little new information, but is a neat summary of the events so far. Here’s my summary of their summary! -
Strategic review announced 1/11/2023, triggering start of offer period under the takeover panel rules.
Deadline (“PUSU”) has now been extended for the 4th time (in 28-day periods) to 20/3/2024.
Ongoing discussions with Madison Dearborn Partners LLP.
It’s not clear if there are any other interested parties involved in discussions, none are mentioned as being currently involved, but we don't know for sure.
Current trading - continues to be in line with the Board’s expectations.
They say confident in long-term growth prospects of the business.
Paul’s opinion - I don’t have any data to support this view, but my inkling is that when takeover discussions drag on this long, the chances of a deal actually happening tend to reduce.
So smaller shareholders (who can get in & out whenever they want) are no doubt weighing up the pros and cons of selling in the market, or holding. Anyone selling now could miss out on a takeover bid premium. Or they could avoid a plunge in share price if deal talks fail.
I’m still not entirely comfortable with why management seem so keen to sell, if the business has such good prospects?
It looks fairly valued to me, on a fwd PER of 17.1x, and on about 16.7x tangible book value, so very little asset backing. I’m not sure why it should be valued any higher, either by the stock market, or a private buyer?
Payments/forex companies had a great run over the last few years, since the larger banks have allowed smaller competition to have some market share by being more competitive on price. Also, companies like EQLS seem to have innovated and built an interesting suite of services, and technology. So the bull case is persuasive, and the financial results speak for themself. Although ultimately customers are mainly driven by what forex rates are offered, so logically I imagine it would be a race to the bottom on price, hence erosion of margins seems inevitable, no matter what bells & whistles are offered on service, tech "platform", etc.
I think EQLS looks fairly priced at the moment, so it doesn’t interest me as something to open a new position in now. I will however be keeping my fingers crossed that shareholders get lucky with a bumper takeover bid hopefully! Meanwhile, the in line trading update today reassures.
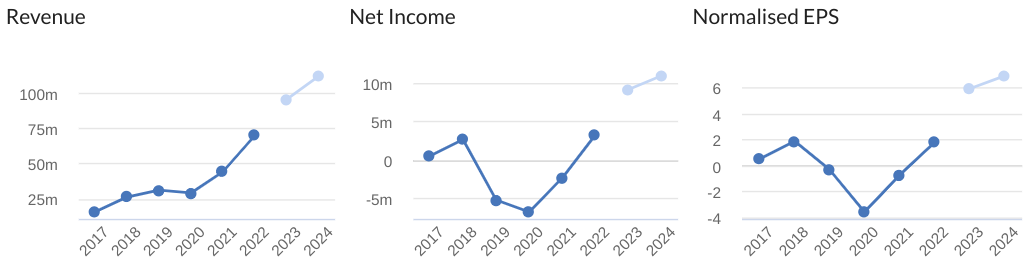
Very strong growth, but profitability is a recent phenomenon - flash in the pan (bear), or the start of a long-term bonanza (bull)? You decide! (I don't have a strong view either way).
Graham’s Section:
H & T (LON:HAT)
Share price: 380.6p (+3%)
Market cap: £167m
No trading update from HAT, but news of an acquisition and additional financing.
Acquisition: H&T is buying “certain assets of Maxcroft Securities Ltd” for £11.3m.
Maxcroft is an Ilford-based pawnbroking business; H&T is buying its £6.1m pledge book and will lease its existing Ilford store.
The value of the £6.1m pledge book is calculated by including accrued interest on the loans but also deducting expected credit losses (“after required IFRS 9 provisions”).
The Maxcroft book has a similar asset mix to H&T’s existing book: gold, jewellery, watches, etc.
However, the big difference is the average size of a Maxcroft loan. It’s over £4,000, about ten times bigger than the average H&T loan.
I did get “posh” vibes when browsing Maxcroft’s website this morning:
Customers are served comfortably in a private area allowing for privacy and a very discreet service.
It almost sounds like you could be served a champagne flute while discussing your pawn loan!
The reason for the large size of the loans is that Maxcroft customers include business owners who need to boost their working capital. This is not a segment that has traditionally been served by H&T.
Funding
H&T has picked up £25m of additional funding from Pricoa Private Capital, a subsidiary of Prudential Financial (not to be confused with Prudential (LON:PRU)).
£10m is due in early 2029, while £15m is due in early 2031. Rates are fixed at c. 8.4%.
H&T’s total net debt at the end of 2023 was £31.6m.
CEO comment:
"We are very pleased to be able to announce these two transactions, both of which underline the Group's focus on growing and broadening its core pawnbroking business and investment in the store estate. We are also delighted to have further diversified and enhanced the Group's funding arrangements through the relationship with Pricoa.
Graham’s view
This all looks like positive news to me, although perhaps taking H&T slightly higher up the risk spectrum.
For example, the addition of £6m of larger loans onto H&T’s existing £131m pledge book shouldn’t make a big difference to the risk profile. But with an average loan of £4000+, and probably including some £20,000+ loans (as advertised on the Maxcroft website), the performance of this pledge book could perhaps be vulnerable to greater volatility than H&T’s existing book.
But I’ve had a brief look at Maxcroft’s documents at Companies House and can’t find anything that troubles me.
As for the funding, I’ve said before that I like it when H&T borrows, because it’s usually a sign that business is strong and that it’s highly profitable.
However, it’s also important to me that H&T doesn’t over-expand. I don’t think it’s doing that yet, but I’m curious to see what it plans to do with this £25m of additional funding - presumably half of it will support the Maxcroft acquisition, but what about the rest?
The positive features of the new loans are that a) they don’t mature until 2029-2031; and b) rates are fixed at quite reasonable rates.
However, against that, they carry similar covenants to the existing Lloyds RCF.
It might be impossible for a company like H&T to borrow meaningful amounts at decent rates without agreeing to covenants such as these, but we all know that these covenants can often be a huge headache for shareholders.
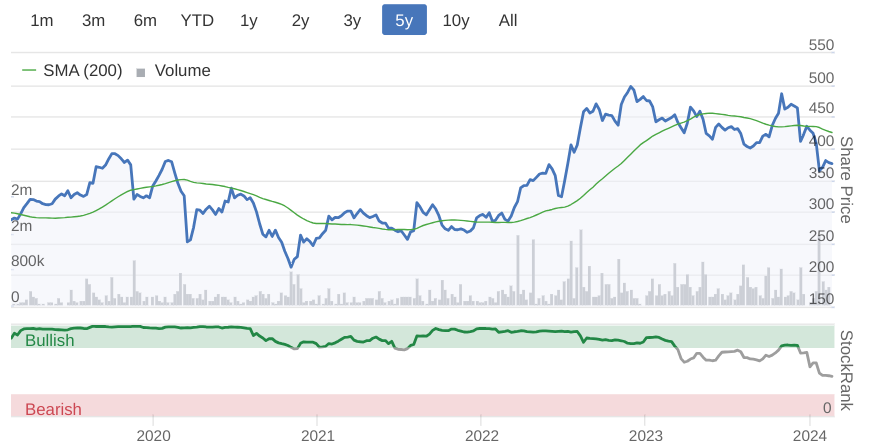
Overall I’m staying positive on H&T, but I do think shareholders need to keep a close eye on it, to watch out for an increase in management’s risk tolerance. If trading remains strong, however, then shareholders will benefit from acquired growth on top of the existing very strong organic growth in pawnbroking.
Value remains compelling:
Keystone Law (LON:KEYS)
Share price: 580p (+7%)
Market cap: £183m
We don’t regularly cover this “network and tech-enabled challenger law firm”. It has a full-year update for FY January 2024, and it’s good news:
Sustained client demand, as well as the impact of new joiners, has generated a better than anticipated revenue outturn. As a result of these factors, in combination with continuing high interest rates, the Board now expects the Group to deliver revenue and adjusted profit before tax for FY 2024 slightly ahead of current market expectations
Kudos to the company and its advisors for letting us know that the prevailing expectations were for revenues of £84.8m and adjusted PBT of £10.9m.
Hiring has been strong with 51 new Principals recruited during the year; the company finished the year with 432 Principals (last year: finished with 398).
Similarly, the total number of fee earners at the end of the year was 549 (last year: finished with 507). “Favourable market conditions” allowed this higher level of recruitment than the previous year.
CEO comment: I think this is the first time I’ve heard a labour market described as “fertile”, but it gets the point across:
"I am delighted to report that Keystone delivered a strong trading performance across the year, further leveraging our unique operating model and market position within the legal profession.
"Our ongoing financial and operational momentum has been accelerated by a more fertile recruitment environment following the challenges of the last couple of years, and we look forward to building on this performance in the year ahead."
Graham’s view
Not a sector I analyse regularly, but Keystone Law seems to be doing something right:
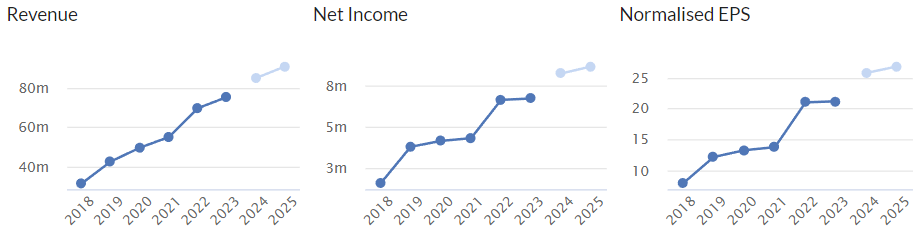
Growth has been achieved with minimal dilution - the share count has held steady since 2019.
Most recent interim results showed the company having net cash of £11m. Tangible balance sheet equity was about the same (~£13m).
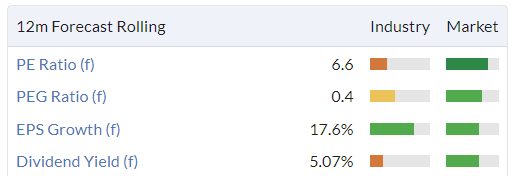
Against earnings, it’s highly rated:
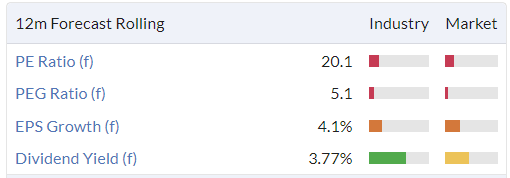
The founder-CEO owns c. 28%, which could help to explain the lack of dilution and the conservative balance sheet.
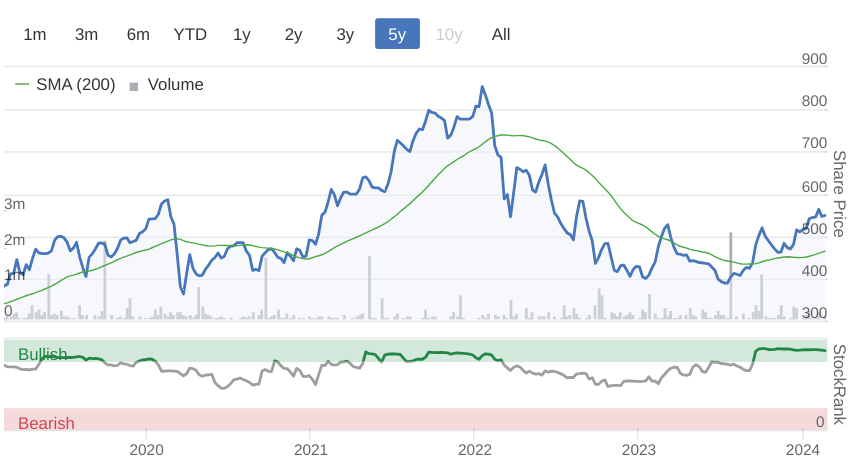
Overall, I have a positive impression of Keystone so far, but I’ll keep a neutral stance. Perhaps it’s fully valued here?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

93 comments
I'm travelling/busy so missed all the fun in here...
IMO the SCVR is eating itself as too many fragile prissy egos. Get a grip - its all future uncertainty. Getting one thing right or wrong in the past means nothing. Paul not liking your stock or being wrong on it is a nothing burger. He's dismissed many stocks I like in the past - often he's been wrong to do so. But hey, he's not here to puff my ego.
TBH I don't follow a lot of the comments so miss many things. The value is in what Paul, Graham, etc publish every day (I don't agree with them often...but they ain't here to fit my biases)
All the people looking for blood as their feelings got hurt are committing an act of self harm. You will not be happy with any change you enforce. If you succeed in ensuring only your type of people or comments then the SCVR will become so anodyne it will die and wither. A pyrrhic victory.
You don't know how good you got it! Fools!
PS its really tedious to read self congratulatory comments about how great you are evidenced by an unaudited "I said and did" this.
Not worthy of you, Paul.
I don't always agree with yiannos, in fact frequently don't, or sometimes the nature of some of his responses. But his views are often worth reading, and his loss as a subscriber is no benefit to these boards.
We all have different views and different opinions but to bully subscribers consistently using a foul language is unacceptable. In my opinion this is the management’s fault as they do not tackle this serious issue. Just imagine if stockopedia was a plc what would have happened.
This behaviour started a couple of years ago maybe three when I had the courage to say that Boohoo (LON:BOO) Saga (LON:SAGA) Joules (LON:JOUL^L22) were going to lose more of their values (some other stocks as well the likes of Purplebricks (LON:PURP^F23) ).
I have reported this bad behaviour this morning to the relevant authorities.
All the best to all subscribers.
Arcontech (LON:ARC) Interims to end Dec23
Thank you Paul for the quick comment on Arcontech. I hold a tiny sliver in my portfolio for the reasons you state, profitable, net cash, cash generative, high margin software to sticky customers - with upside potential and limited downside.
It's not much of a value play at 2x TNAV and at face value doesn't look cheap at 20x forecast earnings for the current FY24 to end June. The company has done nothing in terms of profit and sales for some years - so it's all about the future?
I have also heard the whispers of end-of-life products and de-listing risk. I've yet to find evidence of this. But then as its a niche supplier of financial market software to the banking industry I struggle to evaluate the products at all. It's easy to worry.
On the other hand the in-line interims add to the evidence that customers are not continuing to leave the ship*, together with two more pointers:
[1] Oct23 multi-year contract award to a new customer tier-1 bank with implementation starting in New York, and
[2] Statement today that the almost 100% recurring revenue is onto longer contract terms
Leaves me more interested. But still under-researched. Other views very welcome?
I'd like to add to my position - hoping the company will continue to be neglected and unloved for at least a few more months and the price will settle back down again whilst I am scrabbling down the back of the sofa for some funds to invest.
cheers
Mark
* I'm noticing a tendency for investors to overlook the environment that companies have had to navigate in the last few years. Just like the rest of society - we all want to be back to 'normal'. For many companies it's far from the way it used to be. Especially those B2B suppliers lower down the food chain where large customers turned off the investment taps - and are slow to turn them back on again ? A lot of old business models have gone bang or are just holding on and may not prosper in the future. Investors remain quick to judge when turnarounds and new business models are taking longer by at least a year or two. That yields good opportunities for the patient - but the art is in distinguishing the future successes from those clinging on to old models with a facelift? I'm not yet sure about Arcontech - but my sentiment is improving?
Sounds like H & T (LON:HAT) are feeling the pressure from Ramsdens Holdings (LON:RFX) who are growing in all the right ways while keeping costs down for customers. I agree with Graham that this looks like increasing risk for H & T (LON:HAT) .
I have been monitoring H & T (LON:HAT) and Ramsdens Holdings (LON:RFX) closely for a few years now and I have noticed that H & T (LON:HAT) trustpilot scores have been decreasing slightly. They're still pretty good but there is a clear drop. In contrast Ramsdens Holdings (LON:RFX) has remained higher and more consistent.
Ramsdensforcash = pawnbroking and travel money.
Ramdensjewellery = their retail division.
Volex (LON:VLX) and Sanderson Design (LON:SDG)
I hold both; Volex (LON:VLX) being my largest position. I have no insight on the share price action.
In the same way I had no insight on the 8% rise in Centaur Media (LON:CAU) yesterday or its 4.5% fall today or in Kitwave (LON:KITW) where it fell to 292p on Monday and bounced to 308p today. I also hold both.
My best guess with Volex (LON:VLX) is as suggested some skittishness given recent updates from the likes of XP Power (LON:XPP) and Gooch & Housego (LON:GHH) . I suspect that the diverse nature of Volex (LON:VLX) end markets will enable it to meet expectations. The tractor market is weak at present most farmers in the western world are disenchanted with the adverse impact of government policies on their livelihood, but agriculture is only on of the markets served Murat Ticaret, other include transport, construction and military. Medical and data centres should continue to trade well, especially the latter with the demand for AI. As for EV the move towards electrification, whatever ones views are, is inexorable.
As for Sanderson Design (LON:SDG) I added recently at 108p. The reason being that I believe that trading in brands and manufacturing is likely close to the nadir and the William Morris and Arthur Sanderson archives are irreplaceable and in my view worth more than the current market cap. Finally there is the £16m cash on the balance sheet, which represents 20% of the market cap.
To paraphrase Warren Buffet, the stock market is a mechanism for taking form the impatient and giving to the patient. Whether the above succumb to profits warnings I don't know, but I believe the shares prices of all of the above will be higher in the medium than they are today.
Wonder what is going on at Volex (LON:VLX) ?7% down on no news?
Volex (LON:VLX)
Perhaps an accumulation of less than inspiring updates from other companies are making peeps worry about next update from Volex.
Are they updating the market soon ? 10 * pe AND a positive update would be nice little incentive for me to pick up some shares here for the first time. i note their financial calendar on their website is out of date with November 2023 being in the future :(
not sure what chartists would say with that blip below the green line ? perhaps its just a blip for now?
hey ho lets hope its not market manipulation
Also holding Volex (LON:VLX) and was wondering about that sharp drop. Read across from XP Power (LON:XPP) comments citing broader industry concerns around destocking etc may be weighing although agree with above post that diversification may help cushion them. They also just dropped through 200day MA so there may be some traders selling on technicals. Cheap on fundamentals and a solid company IMHO so staying put for now. Expect FY trading update in April.
Me too? I am totally fed up with small caps now, rise and (usually falls) for no apparent reason. I sold today, I may regret it, but that's me done with small caps.end of!! Just look at the crazy and totally irrational behavior of the SP of OTB, and this is a cash rich company. Large caps, IT's for me from now...as I have been doing for the last 45 years, should stick to one's knitting I guess :-) I am just almost rueing the fact that I have just renewed my STOCK subscription, but will keep it as I value Paul's market commentary /outlook too much. Good luck all.
Hi JohnDoe2378,
Wonder what is going on at Volex (LON:VLX) ?7% down on no news?
I've also been wondering about this. It's guesswork, as nobody fills in a form to disclose why they're selling, but I think it might be due to all the companies reporting customer de-stocking? It stands to reason that VLX might be seeing something similar?
Is it a threat or an opportunity though? I see profit warnings from short-term, fixable factors, as being potential buying opps. But how do we know if these are short-term problems, or they might be more fundamental things going wrong at the company concerned?
Tricky isn't it!
Regards, Paul.
Halfords (LON:HFD) Up 10% in the last hour - I cannot see any news, anyone got any info re why the rise? Maybe renewed bid speculation.
(I don't want to feed the rumour mill) but any news on Betaville..?That's the question.Betaville are always involved.They were involved with the buyout rumour of US pharma Aurinia Pharmaceuticals (NMQ:AUPH), which never materialised.I'm not too sure of their track record...?They do get some correct.I always wonder how Sky News et al. are always the first to break bigger M&A acquisitions too... There are definitely some dodgy practices in some areas of the market which cause spill over worries into other areas imo.I probably should stop fuelling it myself now as it's all too easy to fall into the trap.
Nope, I have just had a look there. Volume of HFD traded didnt seem out of the ordinary, but appreciate we dont get to see the full picture on trades. Time will tell I guess.
Conduit Holdings (LON:CRE) Presentation was very good and no nonsense talking from Neil. Their single location and resulting very low cost ratio is an impressive differentiator, as is their lack of legacy issues and a simple business model. There is always black-box risk on re-insurance, but the management team appear well aligned and have deep experience. They have delivered what they set out to do at IPO and so I came away very impressed. With a hard insurance market continuing they could do very well in 2024. A 1:100 event knocks about 8% of NAV if, and when, it happens.
I had previously been a bit frustrated with this holding as it took 2-3 years to turn a profit, as they built scale from a standing start and then were hit with unrealised losses on their bond portfolio (which have now largely unwound). It just shows that patience is required - not something that the LSE stock market shows. Building a US$1bn reinsurance business is not a 1 year task!
Croma
I think that’s a poor analysis by stocko and if I’m honest a touch lazy .
Clearly taking cursory glances of companies that s writer doesn’t know much about can lead to these types of “analysis” .
Given the Saale was effectively a spin out to part of the previous management it’s not at all like that .
Anyway impossible for stocko to cover accurately all the listed companies but I don’t think that’s a good summation .
That's a poor comment PlanetX re Croma Security Solutions (LON:CSSG) - wrongly accusing me of lack of research.
I did read the RNSs, and saw that the spin out was to former Directors. The company they set up was a start up - I discovered this today by searching Companies House website before writing my review of it. So I actually did the necessary work, and there is nothing wrong in my analysis. You just don't like it, because you own the shares, we get that a lot!
Tell me what was factually wrong in my report please?
It may have displeased you as a holder, but my points are factually correct, and a fair opinion. Disappointed that you've made a false and dismissive accusation against me of lack of research. I always check the facts. You should know that by now! That's why there are hardly ever any factual errors in the SCVRs. We're careful, and do the work.
Fine to differ on opinion, but not fine to dismiss my view as uninformed, when I HAVE done my research. So yes, I'm pushing back on your comment.
Regarding Croma Security Solutions (LON:CSSG) , the business disposed of, Vigilant, has a long track record available at Companies house.
VIGILANT PROTECT UK LIMITED filing history - Find and update company information - GOV.UK (company-information.service.gov.uk)
It is a decent business, with potential
Whilst there is some risk that the new owners may not be able to finance the £5.8m payments still due, the deal is structured such that Croma effectively get Vigilant back if that happens. It is not like a normal unsecured receivable and that obviously limits the downside exposure.
True, it would be normal for this kind of deal, that if the buyer defaults on instalments to buy a business, they forfeit the business. But you have to ask, if that scenario plays out, what would be left?
It's a risk - deals where the acquirer is skint, and pays in instalments assumed from future earnings, are more likely to fail. So I did my job by flagging this RISK. You can decide if you find the risk acceptable or not.
That's an unnecessarily defensive response, Paul. I did not suggest that you did not do your job, I merely added some relevant additional information that was not included in your short write-up.
You pointed out info about the acquired company. I pointed out the acquirer was a newly created start up company. All factual. Nothing defensive about any of it.
Thank you rmillaree and sharw for your really helpful posts re Sanderson Design (LON:SDG) Your comments are why I love Stockopedia so many wise heads contributing.
Thank you also to DaviStoVest for your pithy comments. You are right I got my timing badly wrong no one to blame but myself. Must do better.
If it helps the investment case, my other half has just spent £3k on some curtains using a Sanderson fabric for our lounge. :)
For what it is worth, I have plenty of my own experience of bad timing. Others are probably right that it's best not to make big buy/sell decisions just ahead of an announcement. You're buying a lottery ticket. But, whenever I buy, it often just seems like bad luck (if it wasn't for which, I wouldn't have no luck ... ... ..., etc.).
Since I don't have any special trading skills or access to privileged information, I try to take a fairly strategic approach to investing ... basically buy, build and hold. OK, sometimes I'll suffer an early loss but over the long-term a few per cent up or down just after purchasing doesn't add up to much in the grand scheme of things.
Then, I try hard to sit on my hands.
Bytes Technology (LON:BYIT) bad news for Bytes Technology just out, the CEO has been trading without notifying the market. His resignation this afternoon has been accepted. I no longer hold.
Trading in line as stated per RNS.
And not to be flippant but it really depends on whether he was buying or selling…
Bytes Technology (LON:BYIT) - looks like he was only CEO for three years. Does this merit a 15% fat in the value of. the company?
IMO it does not, hence why I bought at 515p. The only issue is if investors are expecting the TU to be exceeding, which explains the rise of the SP. So not entirely sure if the inline TU hacks it. We'll find out tomorrow.
Not sure it makes much difference, either way it is dishonest
Why is Arbuthnot Banking (LON:ARBB) greyed out?
Sanderson Design (LON:SDG)
If you ask a question about a sudden drop then the best thing is to first check trades - usually thin for any company with MCap < £100m.
In this case there were 8 trades on Monday, 9 yesterday, and 45 so far today. The big one was at 09 46 when 0.42% of the shares in issue changed hands @ 110.5p.
I find these sites useful for trades:
Unlimited number for day: https://www.londonstockexchang...
Limited number depending on whether casual visitor/registered/subscriber but also shows spread at time of trade: https://www.lse.co.uk/ShareTra...
I bought Sanderson Design (LON:SDG) on 6th Feb for a 2 year hold and I am down 19% in 12 trading days. I am more and more wary of market manipulation. Am I right to be concerned?
In terms of the facts, what is it that leads you to conclude there is market manipulation here?
'Cock-up' is almost always a superior explanation to 'conspiracy'. You just got the timing wrong. Hard luck!
The usual excuse is "shorters"... yawn.
Sanderson Design (LON:SDG)
Am I right to be concerned? -
i would say not here NO - imho.
I think buying stocks is like betting on the horses - are you not as likely to benefit from market manipulation as you are be punished. I would say you are playing with fire if you buy stocks soon before trading upodates as allegedly those in the know can scrape data ref sales and the like that aint in the public domain.
The issue with sanderson is 100% innocent though and its as per Pauls excellent comments on the day of the update the 8th February. The market has rightly updated prospects for 2025 on the back of the latest update from the company (2 days after you bought) and the reality is we now expect profits to be 7% lower this year than we expected the day you bought. So downward revision tallies with shareprice drop. Note imho everything is 100% above board here - now is the time to be updating ref current year and the change is pretty minor in nature - i prefer minor tweeks rather than storing up troubles for later.
You should be aware if you buy 2 days before important trading update you are gambling - if future prospects are upped share will go up if future propsects are downgraded share will go down - all other things being equal.(imho the start of the new year is crucial with regard to setting tone for noew year and its new year that matters most imh)
Ref manipulation if there was any going on i would have expected the price to fall before the update on the 8th announced the lowering of expectations. The fact the drop mostly happened on the day suggests everything is right and proper. As ever with downgrades you may expect that price may drift afterwards on basis news is more bad than good. Your gamble would likely have paid off had current year expectations been upgraded.
finally at present i think i am much more likely to wait for news then buy rather than presume that next upcoming news will be neutral at worst - seems more bad than good news is creeping out at present - albeit overall markets should be factoring that in to some degree.
Funny day today in the markets after recent BoE statements and US is looking wobbly in general pre Nvidia earnings.Shouldn't affect Sanderson, but markets can be unusual/sensitive at times and small cap liquidity is still not great.Personally, I trade a few shares, but try to ignore the noise elsewhere.For example, i bought some Argentex recently, following Rockwood in and to hopefully complement my higher growth Cornerstone position, and its down over 10% today on no news.I definitely know which are my trading shares for interest (smaller proportion) and which longer term holds, and don't worry.Some will work out and some won't for a while or perhaps not at all.Personally I know it can be hard to take emotions out of the equation and just let the company's future play out though without overthinking and trading.
Market manipulation! Its stock which hasn't grown its revenue in 5 years, even when everyone was staying home during covid and going home improvement crazy.
Sanderson were analysed on the Mello BASH in the show on Monday evening
https://melloevents.com/mm-190...
Croma Security Solutions (LON:CSSG) - with regard to the mention above of the the lack of trading history for the purchaser of the guarding business, which has been offloaded - it was sold to two members of management and they have registered it as a new business. RNS announcements prior to the sale did include mention of a number of new contracts for that business (Vigilant). One has to hope that they know what they are doing and the business does not immediately fall on its face....
I hold a small amount.
Sanderson Design (LON:SDG) - Down 7-9% percent today. Have I missed something in the news on this one? Its a smaller-mid hold for me but one I was tempted to dip out of on the trading update as I couldn't see much upside in the short term, looking a bit late for that now as it appears a few others acted on that same mindset. Would 100p be a nice entry point now for any non-holders?
I have been trying to show restraint and not be so trigger happy having been a bit rash to move out of positions at times over the past few months, of course then missing buyouts or nice recoveries - as is always the way. Sanderson Design (LON:SDG) is doing its best to sway me today...
I hold this too and am happy to continue to do so. It is one of those stocks where market makers have big spreads on low volume, currently is about 350bps. Additionally, for no news, volume is high today at three times the average volume. I can’t imagine this is for no reason so I suspect we have missed something somewhere but I havent seen any broker notes or change in forecasts or an RNS? A bit of a mystery but stocks still highly rates on most metrics, including forecast share price well ahead of current levels. I’d be interested to know if other subscribers have seen something reported anywhere, too.
Sanderson Design (LON:SDG) my complete and utter guess is that it's a large holder selling down after the lacklustre trading statement on 8 Feb (portugull - this is why the price is down, not market manipulation), but I don't have level 2 so can't see any of the trades . Which means this could continue.
Must admit, I'm really on the fence with what to do. I would say though that the story hasn't changed in the last few years, and it should always have been clear (and Paul's pointed this out more than once) that a luxury furnishings company would struggle in the current economic circumstances.
Equally, it should pick up once things get better (assuming no radical changes in fashion), so just being patient longer term should be ok. I guess it times like this, and shares like this, that show us whether we are buy and hold investors, or not.
I think I've just talked myself into doing nothing.
Cheers
Chris
Sanderson Design (LON:SDG) I am always put off by the revenue numbers. Not sure why they can't grow their revenue - and I'm not sure why these numbers are almost identical every year - what am I missing here? Its as if they have a target and then they all go home early for the day.
Sanderson Design (LON:SDG)
I hold - i think its a fair criticism your points . similar Gooch and Housego one would look at this business and say its gone nowhere other than backwards since 2018. That is deffo true.
What they have done is pick themselves of the pre covid floor when trading was really bad in 2019 and the future outlook wasnt great in that it would be a long hard slog back to make anything like £10 mill pa profits. They have clearly morphed business away from making money on sales to making money via licensing - thats probably not for lack of trying ref physical sales i would say - presumably they have targeted investment in the licencedirection perhaps though .
Note they probably had a boost during covid with certain stuff selling well when peeps were stuck in the house and replacing their chintz - so the fact they have managed to carry on path upwards ref profits till now depsite covid tailwinds vanishing is probablly semi commendable.
They struck some good licencing deals in 2023 - so the main profit earner is up against very tough comparitives imho in 2024 . I perpahs wander if they had made less in 2023 and pushed that licence revenue into 2024 would the overall picture have looked better and shareprice been higher ?
What i dont have a decent handle on is if current forecasts are conserative ref licencing income in 2024 or not - they are kind of keeping that close to their chest. Normally i have an inkling of whether companies would epsexct to beat or not - at present i am probably just below half full in that regard simply due to decent 2023 numbers - i think others might be more positive perhaps ?
So thats my plausible explanation of why they have made zero progress since 2018 and why they expect to make zero progress in 2014. Wipe 2018 and before from the history books and starting from 2019 there is probably a reasonable trend of more of the static sales falling through to the bottom line as licencing income ""trends" upwards. So progress despite going backwards (ok shutup now your are talking nonsense)
It is no surprise that Gooch & Housego (LON:GHH) (I have a small holding) got taken to the woodshed after a profit warning this morning. But it is disappointing that the market does not take a longer view, and it is the way that the UK opens itself up to having its technology future stolen by opportunistic foreign purchases. As Paul notes there is nothing much wrong with GHH, it has a growing order book in world class high tech products supported by a serious research spending and a reasonable Balance Sheet. But it does not have the heft to get over being in businesses that lead to lumpy contracts with unpredictable government funding.
It is the danger point for UK companies, especially those in the tech/industrial space. We can get companies just so far that they are largely proved in Research but still are suffering the lack of Development cash of deep private capital or markets that are willing to be better informed. Companies in similar situations might include Velocity Composites (LON:VEL) , Pressure Technologies (LON:PRES) , Thruvision (LON:THRU) , Hardide (LON:HDD) , Surface Transforms (LON:SCE). Even companies that have a sound business and reputation get put on the naughty step for taking reasonable business risks , a current example being Avingtrans (LON:AVG.
I note that this morning Charlie Peppiatt the GHH CEO has bought 2000 shares to add to his small holding of 5000. This minimal purchases are always counter-productive and I am sorry that he has not been so advised. I am however noting that no Director sales of GHH have occurred since a former Director sold in March 2019.
Gooch & Housego (LON:GHH)
is the reality here not that this company has gone nowhere since 2018 - so has to face the reality that they probably havent delivered as expected or promised?
its sales have certainly grown since 2018 but if they are yet another company with growing sales but reducing margins/static profits should they expect anyone should give premium rating?
- thats where you may have an advantage if you know the the products and market and know they will come good the shares should re-rate then.
But facts are that in the now companies that dont deliver shouldnt really expect to be rewarded with premium rating. Note quicky sketchy research is very superficial here - 2017 they made £7 mill net profit and it looks like zero progress since then if we are saying stocky estimates will now not be hit. Probably £1 billion of sales and less than £35 mill net profit delivered back to sharholders over 6 years - does that deserve market cap more than £157 mill - not on the numbers alone - 6 years ago where did they expect to be now ?
One big issue here is that companies bubbling in the £5 mill to £10 mill profits bracket with high turnover is that they are doubled edged swords that you can easily fall on. 3% miss on margins and the earnings can half along with resultant "material" drop in company valuation . In theory on the flipside one would hope if they have the "overheads covered" - the extra sales on top would always push the company forward - that hasnt happened here despite the decent uplift in sales since 2018.
Equals (LON:EQLS) - I hold
I have held for just over 3 years, starting at 116p and averaging down to 29p. I don't normally do that but the underlying commercial business was growing in a straight line with margins maintained. Paul's comment on long term sustainability of that margin are a slight concern but I think EQLS investment in the platform as they grew will now stand them in good stead against the competition.
I suspect EQLS management are not that keen to sell at this point but rather hope to pull off plan A, a deal to boost earnings from the USA without taking undue risk. Having started talks, I guess they can't refuse to discuss the possibility of a full offer. In that scenario, Madison Dearborn may prefer a full purchase and EQLS are obliged to discuss it but no way will they let it go cheap. As the share price is reasonably (fully) valued at the moment the possibility of a huge premium is somewhat constrained. After three months I am inclined to agree a full takeover becomes less likely as they can only be dancing around the handbags on price at this point.
Personally I am happy to see a price slump if talks don't result in a transaction, their 'on-rails' line performance over the last three years gives me the confidence they will continue to grow profitably at a good rate for a few more years yet.
Unless you are trading the Equals (LON:EQLS) special situation it’s all just noise.
I’ve seen quite a few throwaway comments about the business from people that clearly haven’t looked behind the numbers or really understand the story. That’s fine as we can’t all look in detail at everything, but from a personal perspective I ignore those type of comments.
Zone out the noise, work out what’s relevant for your own risk, investment style and timeframe and base your decisions on that.
Not a small cap but does anyone have views on Burberry (LON:BRBY) - They have ambitions to increase revenue to £4 billion, but a slowdown in luxury demand resulted in a profit warning in January. I suppose that they are heavily geared to the Asian market and China in particular. Having browsed their website, I'd like to know who buys £1000 jumpers or £500 T-Shirts! They have some great quality metrics however and are starting to look cheap (PE 16) - but a lot depends on China:
I think Graham holds them.
Burberry (LON:BRBY)
, I'd like to know who buys £1000 jumpers or £500 T-Shirts!
with £20 billion of revenues in the last 7 years does it matter who ? all that matters is they do and they do deliver!
with price being close to 8 year lows - certainly sometime soon would look to be good time to add if one is confident that Brand name is still mostly what it was ?? (dont ask me if that is the case).
I guess the main negative here is that sales have grown well below the rate of inflation for past 7 years or so - that kind of suggests the brand may perhaps be slightly tired - maybe the reality is the youth are not so brand conscious (or have more choice). Should we be paying much more than 12 pe for something that clearly hasnt progressed in such a long time? - i think the answer for me is probably yes at the right price if there are no other obvious same sector competitors that are more compelling. I havent dug deep - but what i do like here is that they do churn out consistent base level of profits every year - so clearly they havent fallen into the trap of trying global domination or moving into areas that are not their core competence - having said that if they want to add an extra £1 billion of sales might they be trying to go down that route soon? hopefully they wont add extra sales at any cost if it involves moving outside core competence? - dont get me wrong plenty of options to move into new areas just do it on basis that you dont go big unless you are making decent margin.
The risk here is the long term in house designer left and the replacement is quite unproven from what I know. Fashion is fickle so if they don’t get right then you could be facing several periods of underperformance. I think that is one of the key risks here
Darktrace (LON:DARK) .The stock is weak this morning on the back ofPalo Alto Networks (NSQ:PANW). Watching Palo Alto's webcast the slowdown in revenue growth this year appears due to its customers consolidating their cyber products to a single platform and not being charged until the renewal date occurs. They talked about customer fatigue..I am sure customers would prefer not to have to spend on cyber security.
I noticed that and watched an interview with the ex Palo Alto Networks (NSQ:PANW) CEO, Lane Bess, on CNBC, who still holds stock (and used to work for Zscaler (NSQ:ZS) and now works for Deep Instinct )and is still bullish, especially on cyber companies with proper AI technologies.Not all apparently have real AI cybersec abilities.Cybersec surely has further to grow as tech and tech threats are constantly evolving and getting more complicated...... and they're will be clear bumps in the road, especially with the way wall street invests/trades on short term news and forward prices a lot of growth in the valuation.And i'm guessing the current big US players will continue winning.Darktrace (LON:DARK) say they have an AI offering and are still growing though.
Re Croma Security Solutions (LON:CSSG) - I'd really like the business prospects if I was the owner. Simple strategy of consolidating back office (purchasing, finance etc) and creating a national brand in a niche. Like Angling Direct (LON:ANG) lots of slow moving bulky/heavy stock (locks) that can be held purchased/held and sent out from one central store and/or sold online with a decent website operation - much more efficient than the single locksmiths it aims to roll up. Strategy also enables recruitment of retail salespeople instore to puush sales who don't need to worry about stocks/book-keeping plus national account type sales people to roll out to big key users (NHS, schools etc) which is where I see a moat can be created through service and scale. Ultimately, one off residential or small business security sales have to compete with online giants.
But it is so small (mid-teens stores) that meaningful growth will take years and it's probably got enough cash/cashflow to finance adding almost that many stores each year. Angling Direct (LON:ANG) has the same issue with a similar strategy which is why it has not grown as fast as the market will reward despite having a big cash pile.
If it doesn't do it quickly, will advances in swipe cards or similar not replace physical locks in a lot of places?
Finally, the CEO also has 42% of shares in the family and probably controls over 50% with some individual investors. However, having de-scaled and focused by splitting from the old manned security side to focus on retail security shops (locksmith + security equipment), if it succeeds will it not be taken private?
Any chance that Graham could take a look at Conduit Holdings (LON:CRE) -- no offence Paul but its probably not your thing.
Sparkling FY results this morning from this pure play reinsurer moving the profits from $44 loss to $190m profit as thus newly listed business scales up, aided by hard market conditions..This follows on from their excellent renewals announcement in January.
With a mkt cap of 760m this may be above the limit reported on but here's hoping
I hold
Yes, can I second this. Results look great but I find the insurance business hard to understand.
I third it (I hold) Conduit Holdings (LON:CRE)
Would also be keen for Graham (or Paul too if he thinks it's his thing!) to take a look at this Conduit Holdings (LON:CRE) - results looks very good - after a few years building up the business, strong profits now seem to be coming through with a ROTE of 22%. Looks like they are benefitting from a hard insurance market (as well as higher yields on their bond portfolio). A key attraction and differentiator for me is the clean balance sheet and lack of legacy issues.
Still trading at a discount to NAV and paying a c6% dividend yield. There's also been some sizeable director buys over the last year or so. I believe there is an Investor Meets Company presentation today where they usually give a good overview.
Would like to see cre move to premium listing for fste 250 entry.
Although never actually worked in the insurance in my days in accountancy firms I learned a lot about doing underwriting guys tax returns. This taught me about the 3 year tail risk etc and the different sectors (marine casualty D&O etc). Conduit Holdings (LON:CRE) had been on my radar but it was Neil Eckert presentation last October on IMC that told me so much about the experienced mananagement and their experience, lack of tail risk, and their story so far that got me to invest and topping up after the renewals RNS. That and the hard market at the moment!!
Morning Threepeat,
Any chance that Graham could take a look at Conduit Holdings (LON:CRE) -- no offence Paul but its probably not your thing.
Haha, none taken! I've just had a quick look, and it seems to be an insurance underwriter, which is not a sector I look at. The Stockopedia value metrics look great, some smashing numbers here -
The headlines with today's FY 12/2023 results sound strong, eg -
"Efficient business model, strong capital base, positioned for continued growth into favourable market conditions"
CEO comments sound upbeat -
" Trevor Carvey, Chief Executive Officer, commented: "2023 was an outstanding year for Conduit Re, delivering comprehensive income of $190.8 million and an RoE of 22.0%. Across all three divisions, the underwriting teams navigated the market well, being focused in choosing their preferred spaces to play and allocating our capacity to those where we saw the best opportunities and returns.
We continue to benefit from a lack of legacy issues and our clean balance sheet has given us tremendous freedom to deploy exactly where we wish to.
Strong investment performance, particularly in the last quarter of the year, supported our underwriting efforts.
Entering our fourth year, we continue to deliver on our plans and the market landscape out there is offering up plenty of good opportunities for continued growth."
Looks interesting to me too! I'll wait to hear Graham's view if he has time today, it might have to go on the backlog list, or he might decline to review it.
Regards, Paul.
Conduit Holdings (LON:CRE) - I have held this one since just after listing, so would be interested in Graham's thoughts. I'm really impressed with today's numbers. The share price has gone nowhere in 3 years apart from down and back again, but its now looking well placed. It still yields 6%.
This pure-play reinsurance business based in Bermuda, was always a play on the abilities of industry veteran, Neil Eckert. Nice to see patience finally being rewarded. 22% return on equity this year, and 2024 prospects look very good again.
There is an Investor Meets video at 3pm this afternoon that I will be watching.
Conduit Holdings (LON:CRE) - there's been sellers about, despite the excellent performance. Perplexing share price action.
Conduit Holdings (LON:CRE) . In my working life I was UK underwriting manager for a top 5 global reinsurer. I've been out of the market for 15 years, so things might have changed a fair bit.
I've not studied Conduit in detail - I've just skimmed through the RNS, Financial Statements & Presentation on their website. So there may well be lots more info available that I've not seen.
Big attraction is that they have no nasty skeletons in the cupboard from the past - BUT they may well be creating them. They are writing a surprising amount of casualty business and I've not spotted what - this is probably long tail. They appear to be taking $38m profit in 2023 - brave. Most casualty takes years to develop - our (prudent) policy was not to take any profit in early years, but to reserve any unexpected negative loss development. Theirs might be shorter tail casualty business - but I don't see any description.
Property is likely to contain a fair bit of catastrophe (cat) exposure - they give some PML (Probable Maximum Loss) figs in a presentation, but give no info as to how these are calculated, or where they are - think US hurricane, California quake, Japan quake, NW Europe windstorm.
In a year without huge cat losses, I'd expect their property account to make a decent profit.
No idea what's in their Specialty account as they don't tell us.
I suspect the plan is to run the co for a few years, then sell it. You might do very well following a similar plan - absent a decent cat. Any mention of adverse casualty development - run for the hills
It's of no interest to me. If you want a decently run insurer / reinsurer, Hiscox would be a good place to start.
Conduit Holdings (LON:CRE) I recall from an earlier presentation that they take relatively low levels of catastrophe risk but can't remember the exact figure. Will tune into the IMC presentations later on as that may give more detail.
Conduit Holdings (LON:CRE)
I'm struggling a bit with their results - this may well be 2 nations divided by a common (reporting) language.....
They show premiums written - policies incepting during the year. And revenue - premiums collected. But not premiums earned. To explain in simple terms (for calendar year reporting) :
For an annual policy incepting on Jan 1, 100% of the premium will be earned during that calendar year. For an annual policy incepting on 1 July, 50% will be earned in that calendar year, 50% in the subsequent one.
For company growing rapidly (Conduit Re 50% last year), the differences between written, revenue, earned will be huge.
But surely losses are easier? Well, no.
Losses are not always reported promptly - in the case of some classes of casualty, maybe not for years. It takes a while to sort out & pay claims - with property claims it's normally quicker & the claims less contentious; at the original policy level it's your insured who is claiming and, typically, they want the damage repaired. With casualty, it's normally someone else who is alleging that your insured caused them loss; your insured may well not agree. So lots of litigation. And injuries take ages to stabilise. and the original insurer may not agree that the issue is covered under the policy.
Simple casualty class - UK motor. It will take 5-10 years for a decent sized bodily injury claim to settle. For the original insurer (or quota share reinsurer), they won't have a clear idea of the outcome of their underwriting year account for 3-5 years, because they buy excess of loss (XL) reinsurance for the big claims. For the XL reinsurer, the period will be much more 6 - 10 years. And UK motor is a pretty straightforward casualty line.
Turning back to their property class. They report net premium revenue of $278m and "net reinsurance service expenses" of $162m, suggesting a profit of $116m. This pretty much tracks through on their consolidated statement.
This is a staggering level of supposed profit - the insurance / reinsurance market isn't (sustainably) like that......
So why?
- maybe the market is so hard (high rates) that it's true. Well, it certainly won't remain this hard - capital will pile in.
- their book is cat / quasi cat (think big industrial etc) and the cat / big loss hasn't happened. Quite likely.
- the figures are under reserving for eventual losses. I'd want to be v v sure this ain't the case before investing.
If they are genuinely writing low cat exposed sustainable property business at these ratios & highly profitable short tail or massively over-priced casualty, they have discovered something that has eluded generations
And, please, no comments of niche...........
I'd need a lot more info to dig around. But I'm currently on hols!
On Conduit Holdings (LON:CRE) I'm not sure I follow garbetklb - premiums earned are the revenue number of US$633m versus the larger US$967m premiums written.
It might be worth you looking at the annual report, when issued, as that is more comprehensive.
I agree with you that a 22% ROE is probably not sustainable through the cycle, but > 15% is their target. It depends where you are in the cycle and its probably been one of the best years in 2023.
Anyway, Neil Eckert founded Brit Insurance which was large and successful and sold for a good price. I am hoping that they know how to account for insurance liabilities, albeit there is always risk even on short-tail business!
In my view, it's all about the people and this is a high quality management team. I am hoping that they will do well for a few more years, pay good dividends and then probably sell the business to a larger player.
Conduit Holdings (LON:CRE)
Hi Topvest - maybe revenue & earned premiums are the same thing in Bermuda accounting terminology, I don't know.
But they most definitely are not in the sort of UK insurance / reinsurance accounting I was involved in in the UK.
Revenue = cash received
Earned = calculated allocation of a proportion of premiums written (at any time) to a calendar period. To match premiums to losses incurred during a particular period.
If you want a chat, drop me a line on the same screen name on ADVFN - as one of the useful features that Stocko dropped a few years back was direct messaging.....
Shield Therapeutics (LON:STX) oh dear, what a mess.
Comment on overstated prescription number guidance from todays update,
"…the projection methodology used by its third-party data provider resulted in an overstatement of total prescriptions in 2023”.
Range was forecasted between 100k - 130k prescriptions, actual 77k. That’s some variance,
Coupled with news from earlier in the year that average prescription sales price was lower than thought…..
Got to ask what the CEO is actually doing each day?
Shield Therapeutics (LON:STX) He was only paid £678k in 2022.
Corero Network Security (LON:CNS) "New partnership supporting growth" - research note here: https://www.equitydevelopment....
Corero has announced a new partnership agreement with TechEnabler, a Brazilian network solutions provider. Latin America is a relatively untapped market for Corero and this agreement should yield considerable upside as it develops. We continue to see fair value at 14p and upside risk to our current forecasts.
Kentik channel partner. TechEnabler is a Kentik channel partner and integrator headquartered in Sao Paulo, Brazil. Kentik is a US based network observability platform which visualises cloud and network traffic. Kentik enables the resolution of any troubleshooting problems many times faster than normal and helps mitigate cyber-attacks.
$1m+ booked. The partnership agreement has already generated bookings for Corero’s products and services in excess of $1m as part of its Scrubbing-as-a-Service offering.
Strong trading in FY24E. Corero recently highlighted that revenues for FY24E are to be in the region of approximately $22.3m, indicating YoY revenue growth of +11%. Corero closed last year with annualised recurring revenue (ARR) showing even stronger growth of +17% YoY to $16.9m.
Debt free. Corero is now debt free and, with a very experienced CEO Carl Herberger now onboard, it can focus on executing a growing pipeline of new business. We see plenty of capacity for upside risk to our FY24E forecasts. The business is self-sustaining and, in our view, undervalued on an EV/sales ratio of 1.8x this year.
Here's an interesting snippet I found in Algy Hall's latest book: "Research conducted by O'Shaughnessy Asset Management has shown that between 1964 and 2015, reconstructing the Russell 2000 to simply exclude the half of stocks that were ranked lowest in basic quality measures boosted annual returns from 11.6% to 15.0%"
Croma Security
To quite my old CEO looks “clean as a whistle”
Negatives are microcaps and quite illiquid and management I think a touch highly laid .
Can’t complain with the restructure and current stats
9 million market cap
1.7 million cash
5.7 8 million deferred payment for their division just spun out first payment May 24
Making profit say 0.5 to 1 million
Plus a balance sheet stuffed with freeholds
Sector Is ok
Strategy is good and makes sense
And they have sone nice IP and sticky customers
Also management were very shrewd buying back 400k of shares at 45p tight at the bottom
.If you are prepared to accept ghr 5.7 million is going to arrive then valuation is extremely attractive
EV allowing for deferred payment is 1.57 million
That’s an anomaly of a valuation
And to be fair even without the 5.73 million the valuation is not that far off
If that first cheque lands on their doormat in May happy days
Which reminds me I once had a dealer who owed me money and when I kept chasing his pat excuse “sorry Dave can’t pay right now the slugs are my chequebook “
Might have talked myself into adding a few .
management I think a touch highly laid .
It's a thought, Planetx - might be a good incentive...!!
Oops classic typo, I did once back in the day say to my sales team (all men) back in the day
“Whoever sells the most this month gets 1 hour unlimited at the Sabai rooms “
Don’t think that type of talking is allowed these days and it is of course highly inappropriate .
The Sabai rooms is not a curry house .
And it was a (shit) joke that bonus never occurred
(Might have dug a hole here )
A little Ralph Halpern - 1st to claim £1m+ pay and claimed 5 times a night
https://www.theguardian.com/bu...
Oo, matron.
If all the economists in the world were laid end to end, it wouldn't be a bad thing. -- Peter Lynch
As a customer it is my go to for anything lock related. I have a few classic cars and on one a key had worn out , the lock was taken apart re-keyed for £21!
another car had no keys again 2 locks taken apart and keys made to fit £30!
if anything they significantly undercharge for this service
if you need a lock in Bournemoth, Croma in Moordown highly recommended
My morning smallcap tweet: The pasting-table for smallcaps
Gooch & Housego (LON:GHH) Aquila Services (LON:AQSG) Shield Therapeutics (LON:STX) KRM22 (LON:KRM) Ondo InsurTech (LON:ONDO) Feedback (LON:FDBK) Keystone Law (LON:KEYS) Equals (LON:EQLS) Cambridge Cognition Holdings (LON:COG) H & T (LON:HAT) Arcontech (LON:ARC), Arbuthnot Banking (LON:ARBB), Angling Direct (LON:ANG), Croma Security Solutions (LON:CSSG)
◄Gooch & Housego (GHH)► warns FY24 adj pretax will be c.£3m below mgmt exp. Blames Industrial and Medical laser market customers cutting inventory and reporting weak demand. Also weak demand in semiconductor mkt. Some US A&D programmes will no longer go ahead or have been deferred. [SP=610 Cap=157m]
◄Aquila Services (AQSG)► to cancel listing. No vote needed since its on the Standard List. Claims it will "provide an improved return to shareholders, maximise the retention of key skilled staff and to attract the best new talent". Co continues to trade well. [SP=20 Cap=7m]
◄Shield Therapeutics (STX)► guides FY-Dec rev up 182%. Prescriptions c.77k, up 210%. Co "has recently identified that the projection methodology used by its third-party data provider resulted in an overstatement of total prescriptions in 2023. This development was partly responsible for the Group not achieving previously indicated guidance of total prescriptions in FY23 of 100k to 130k." Rev not affected by error. [SP=5.63 Cap=44m]
◄KRM22 (KRM)► FY-Dec rev £5.2m up 21%. ARR £5.8m (£4.6m). In line? Net debt £3.6m. To cut £2.1m PA from costs. Co "expects to operate within its existing available cash and facilities and anticipated new contract signings." [SP=29 Cap=10m]
◄Ondo InsurTech (ONDO)► adds another well-known US insurer to list of partners to offer LeakBot. [SP=25.9 Cap=22m]
◄Feedback (FDBK)► radiology specialist Medical Imaging Partnership has agreed to pilot Bleepa-CareLocker. Expect modest revs in the early stages, post the evaluation and planning phase. Also H1-Nov rev £473k down 18% "primarily due to the timing of revenue recognition of the QVH/Sussex ICS pilot contract during the previous period and legacy product contracts reaching end of term". Pretax -£2.1m (-£1.6m). [SP=62.8 Cap=8m]
◄Keystone Law (KEYS)► guides FY-Jan rev and adj pretax lightly ahead of market expectations of £84.8m and £10.9m. "Our ongoing financial and operational momentum has been accelerated by a more fertile recruitment environment." [SP=540 Cap=170m]
◄Equals (EQLS)► extends PUSU deadline again as offer talks with Madison Dearborn continue. [SP=117 Cap=220m]. I hold.
◄Cambridge Cognition (COG)► partnership with ActiGraph, a leading provider of wearable technologies for clinical trials to deliver a broad suite of assessments to "provide a fully rounded view of mental and physical capabilities". [SP=51.09 Cap=18m]
◄H&T (HAT)► buys certain assets of Essex pawnbroker Maxcroft Securities for £11.3m. A single store with a large pledge book of £6.1m. Also £25m of additional financing at c. 8.4%. [SP=370 Cap=163m]. I hold.
◄Arcontech (ARC)► H1-Dec rev up 7% and pretax up 45%. Guides FY rev in line and pretax slightly ahead of market expectations. [SP=86 Cap=12m]
In line: ARBB, ANG, CSSG