Small Cap Value Report (Wed 21 June 2023) - BOTB, LIO, SRT, CER, WATR, THG

Good morning! It's Paul & Graham with you today.
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
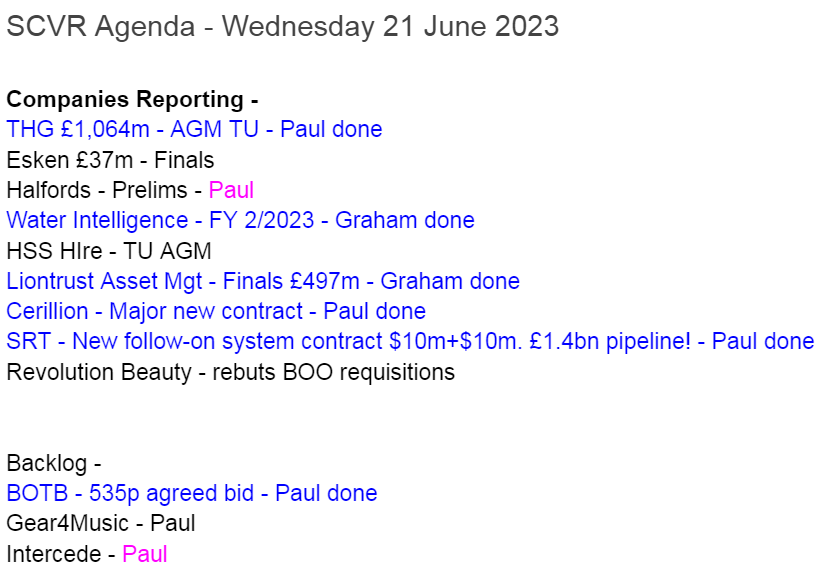
Here's today's to do list - as usual, we may not necessarily manage to do everything, but will do our best -
Summaries of main sections below
Best Of The Best (LON:BOTB) (Paul holds)
Down 6% to 520p y’day (£49m) - Recommended 535p cash takeover - Paul - AMBER
A shock announcement yesterday afternoon that founder management has agreed a cash bid of only 535p from 30% shareholder Tedi Sagi - known for his lowball bids, and strong-arm tactics. I ponder the situation in more detail below.
Liontrust Asset Management (LON:LIO)
Down 2% to 750p (£487m) - Finals - Graham - GREEN
This fund manager reports full-year results and reiterates its high hopes for the acquisition of GAM. I go on a treasure hunt to understand its high “amortisation” number. Normally I would not give this stock the thumbs up, but the value on offer here strikes me as unordinary.
SRT Marine Systems (LON:SRT)
Up 1% to 61p (£111m) - New Follow-on system Contract - Paul - AMBER/GREEN
It's not actually a signed contract yet, so this RNS seems premature. I discuss below how SRT has over-promised and under-delivered in the past, but news this year does seem game-changing. I'm still nervous, but maybe risk:reward is leaning towards the positive now? I discuss bull:bear points below, and am leaning slightly towards the bull case, but only as a speculative thing at this stage.
Cerillion (LON:CER)
Unch at 1465p (£432m) - Major new contract - Paul - GREEN
A useful 6-year contract, about £2.5m pa in subscription revenues. Doesn't move the forecasts though, so seems like it was already in the budget as an expected upgrade from an existing European customer. I recap on the share in more detail below, and remain very positive about it, although 34x fwd PER doesn't leave any room for disappointment.
Water Intelligence (LON:WATR)
Down 2% to 429.5p (£83m) - Finals - Graham - AMBER
I am tempted to give this US-based leak detection company the thumbs up, as it continues to grow and benefit from high-quality franchise royalty income. Valuation might be about right here but as it continues to invest for the future, it offers an interesting proposition.
THG (LON:THG)
Up 6% to 77p (£1.12bn) - AGM TU (in line) - Paul - RED
Some signs of life in this update, with better margins, and it hopes to reach free cashflow breakeven. Not exactly inspiring for a company valued at over £1bn! I explain below why I think it's still overvalued, despite some signs of life.
Paul’s Section:
Best Of The Best (LON:BOTB)
Down 6% to 520p y’day (£49m) - Recommended 535p cash takeover - Paul - AMBER
I had barely signed off yesterday’s report, and was relaxing in the sun on my lounger, listening to company webinars, and news came through for an agreed takeover bid at BOTB, which is my largest personal holding. Exciting!
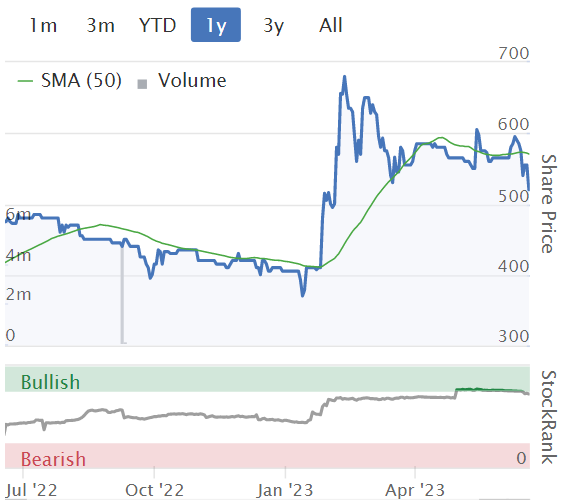
Except when I saw the price - only 535p, which is a discount to the previous share price, which had been settling around 550-600p, after a nice surge from 400p to up a peak of to 680p in Jan 2023, after a strong trading update.
It looks like 30% holder, the notorious Tedi Sagi, must have strong-armed founder management into submission somehow, as they’ve agreed it. Including in-the-money share options, management holds 20.5%.
So together with Sagi’s 29.9%, that’s just over 50% voting for the deal.
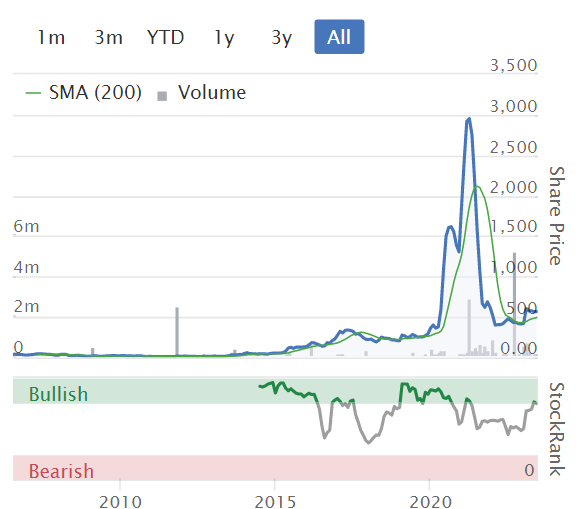
What we need to know now, is what the institutional holders think? Slater is the biggest outside shareholder, at 9.1%, and if you recall, the institutions were stitched up in April 2021, with a secondary placing that saw mgt bank c.£60m personally by selling about 2.5m shares at £24 each. A pandemic boom was passed off as structural growth (which the market believed at the time, as mgt was adamant that was the case, I can remember the conversations), hence the eye-wateringly high secondary placing price.
.
Mgt banked another £8.7m in Sept 2022 by selling 30% of the company at just 400p to Tedi Sagi, who owns many businesses, including online gambling companies. The low price did raise eyebrows at the time, but the thinking was that, a bit like Dragon's Den, a low entry price for Sagi would be offset by the value his team would add to BOTB via international expansion.
So the hope, and the stated aim, was that this partnership with Sagi’s company Globe Investments Ltd, would result in turbocharging BOTB’s performance via improved marketing skills, and international expansion. The existing business was trading well too, so the market share price recently looked great value, on about 10x PER. With BOTB also having a superb history of paying special divis, doing tender offers, etc, BOTB shares looked to me a terrific each-way bet, a highly cash generative value share, but with exciting growth thrown in for free with an expert partner.
Yesterday’s news that mgt have decided to throw in the towel, and hand over the company to Sagi, at just 535p is incredibly disappointing. They should have held firm, and negotiated a much better deal. It seems to me that Sagi has successfully walked all over them. He’s well known for that, and did something similar at KAPE. Still, hard negotiation is not a crime.
Why has BOTB management thrown in the towel? I don’t know, but the numbers suggest to me that having already essentially banked their profits at a price that might never be repeated (£24), with together with the more recent sale, has banked mgt c.£70m. So their remaining stakes pale into the background, at about £8m current value. It probably isn’t worth their time or the hassle, hanging on and trying to fight off Sagi, when they can retire very comfortably, and go off and do new projects.
Reading the offer document, it sounds like Sagi said he wanted full control in order to press ahead with the big expansion plans, which in any case would have probably resulted in dividends being stopped, and a move into losses to build up international operations - which AIM investors used to the nice shareholder returns might not have particularly liked anyway.
Is it a done deal? I don’t know. I can imagine institutions might want to stall this deal, and hold out for a better price. That’s my feeling too, so I won’t be selling at this level, unless forced to do so with an imminent delisting, which needs 75% I think. Although as always I reserve the right to change my mind at any time. If a more attractive investment idea comes up, then you have to sell something to get the money for new ideas, even if you're not happy with the price.
Apparently at KAPE, Sagi also tried to buy it on the cheap, but upped his offer slightly from 344 to 360, I am told (I’ve not checked those figures). Hence something similar might happen at BOTB - maybe an increased offer to 550-560p, if we hold out for more?
Paul’s opinion - I bought quite well here in Jan 2023 at 458p, so a 535p bid is a 17% profit in 5 months, in a bear market for small caps - I can think of worse outcomes!
There’s a buyer in the market, I did a dummy trade yesterday afternoon. At the time the published bid price was 510p, and you can usually only get a quote for 500-1000 shares in BOTB, but was bid 515p for 2k shares, or 512.5p for 10k shares. I’d rather sit and wait for the 535p bid (and possibly more).
Is there a chance of a higher competing bid? The document says management have given irrevocable undertakings to back the deal, so probably not. Although irrevocable undertakings are not always irrevocable, so who knows.
Disappointing for sure. Bids should be at a premium of at least 30%, so this deal is taking the proverbial I would say. But clearly mgt have already largely cashed out, so didn’t want to fight for a decent deal for their small shareholders. Or maybe the business is only worth 535p? They know it best, after all.
Also a mental note that when Tedi Sagi appears on any shareholder register, we should probably sell into any spike up, rather than buying!
I’ve read some of the offer document, but after a few pages had got the gist of it, so now I’ll just wait to see how the institutions react. There must be a good chance they’ll reject this lowball offer, and hopefully give mgt a good grilling too. Although I’ve got mixed feelings there - long-term shareholders did have an opportunity to bank a c.30-bagger in the pandemic, so if people didn’t sell, then that was your choice - people got too greedy. Plus mgt were very fair to outside shareholders with generous divis/buybacks, modest remuneration, and little dilution, etc.
EDIT: a hat tip to member Chris Brown, who posts additional detail in the comments below, pointing out (I had missed this) that Finncap says the terms of the offer are "not fair and reasonable". I cannot recall ever seeing a broker say that before, can anyone else remember a similar case? Usually brokers just rubber-stamp deals. I don't suppose this will change the outcome, but could it open the Directors to possible legal action? If Slater latches onto this, and threatens to sue, it could result in a higher priced bid maybe, in order to achieve Finncap's approval? Or management and Sagi could just tough it out. Who knows?
SRT Marine Systems (LON:SRT)
Up 1% to 61p (£111m) - New Follow-on system Contract - Paul - AMBER/GREEN
SRT Marine Systems plc ('SRT'), a global provider of maritime domain awareness systems and technologies for security, safety and environmental protection…
SRT says that an existing customer will be awarding SRT (i.e. hasn’t yet signed) a new contract, for the next phase of its maritime surveillance system.
Estimated value is $10m, delivered within 12 months of signing (expected in “the next few months”). So that sounds as if it might straddle FY 3/2024 and FY 3/2025 results.
So not material, in terms of existing forecast revenues of £71m for FY 3/2024.
There’s also a possible additional $10m for customised hardware mentioned.
CEO comments are, as always, super-bullish. As I've mentioned before, I do worry that announcing the staggering pipeline figures, that get bigger with every passing year, might be counter-productive, given the historically very poor visibility and conversion of pipeline into actual money.
Simon Tucker, CEO of SRT Marine Systems, commented:
"The accumulated investment of many years is now being reflected in the accelerating pace at which our new contract opportunity pipeline is growing and then transitioning into contract. Over the last year, our pipeline of new system contract opportunities, has grown to an approximate value of £1.4bn, of which £380m are at a mature stage in the sales cycle with increasing surety of timing. I am delighted to receive notification of another new contract sooner than expected from this long-standing customer, which will likely result in additional revenues for SRT in the current financial year. I expect to continue to see further conversions from our pipeline, along with more additions to the pipeline into the future."
Paul’s opinion - I’ve followed this company for 18 years, and have seen investor sentiment ebb & flow, along with performance - repeated false dawns, with surges in revenues (and brief spikes into profitability). For that reason, I’m deeply sceptical about SRT’s ability to become a consistently profitable company.
Checking our archive here, we were RED on 23 March 2023, due to a huge profit miss for FY 3/2023. Despite that, shares have risen, as the market placed more emphasis on the outlook & pipeline optimism.
Then on 18 May 2023 we changed up a gear to AMBER, as a major $180m contract win does look game-changing. Although things could still go wrong, the money’s not in the bank yet.
Today’s announcement looks premature, as the latest deal isn’t signed yet. But taken at face value, it sounds encouraging for an existing customer to be looking at awarding a follow-on deal.
Having said that, if we can believe all the announcements, then SRT is looking intriguing, and I can see the merit in dipping a toe in here with a small, speculative position, possibly. Just don’t be surprised if something goes wrong, because that’s what has happened repeatedly in the past. So I’m leaning towards AMBER/GREEN. To go fully bullish on it, I’d need to see audited evidence of profits, and cash in the bank.
Everyone can make up your own minds, balancing up risk:reward as you see fit, so there's no right or wrong on this - it's educated guesswork for all of us.
Cerillion (LON:CER)
Unch at 1465p (£432m) - Major new contract - Paul - GREEN
Cerillion, the billing, charging and customer relationship management software solutions provider…
Key points -
6-year contract
Existing customer, in Europe
Worth a total of £15.1m, so £2.5m pa, assuming evenly spread
(for context, FY 9/2023 forecast revenue is £38m)
Looks as if this was already in the budget, as an expected contract win -
All of the revenue is subscription income that will be recognised over the term of the contract, and will support current consensus market forecasts.
Management comments -
Louis Hall, Chief Executive Officer of Cerillion plc, commented:
"We are delighted to further extend and broaden our relationship with this customer. It is another demonstration of the clear operational and commercial benefits of our solutions. Telecommunications companies are looking for solutions that enable them to drive more revenue from their network infrastructure and improve their end-customers' experience. Our solutions efficiently and cost-effectively meet this need."
Paul’s opinion - CER remains one of my favourite GARP shares, although the forward PER of 34x is stretching the RP (reasonable price) part of GARP!
That said, when you find a company that’s in a sweet spot, with the right products, in demand, and generating superb growth in recurring revenues, then I think quibbling over valuation is often a mistake.
For that reason, I’m going to remain GREEN here. Although it's easy to be bullish on companies that are doing well, so it's important also to consider what could go wrong, and whether current strong performance is sustainable. I've not seen anything to make me doubt that at CER, although that's not saying much, as I'm no sector expert, and problems can be complete surprises to everyone when they do happen.
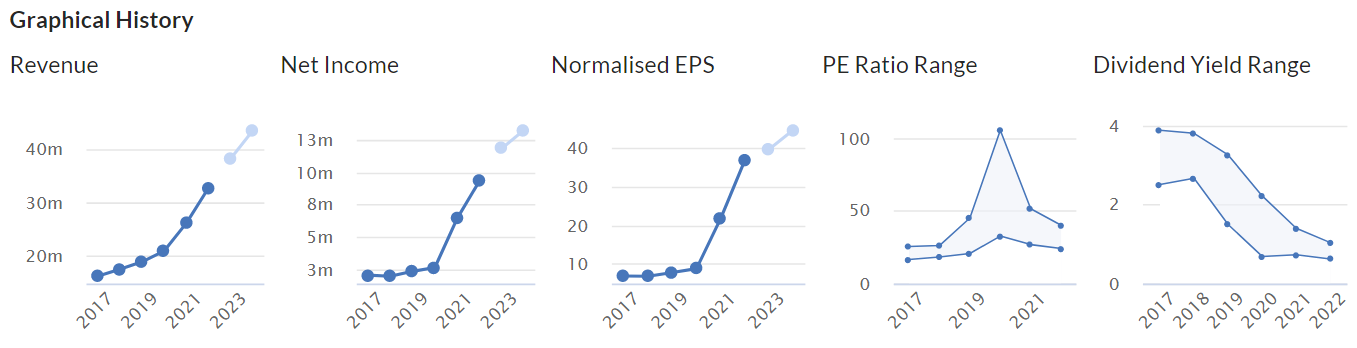
This is a stunning track record I think, and I’m pretty sure it’s all organic too -
By far the best interview with the CEO that I’ve heard is actually mine - I recorded it here in Nov 2022, which gets to the crux of why the company is doing so well. All still relevant, and a manageable listen at 32 minutes.
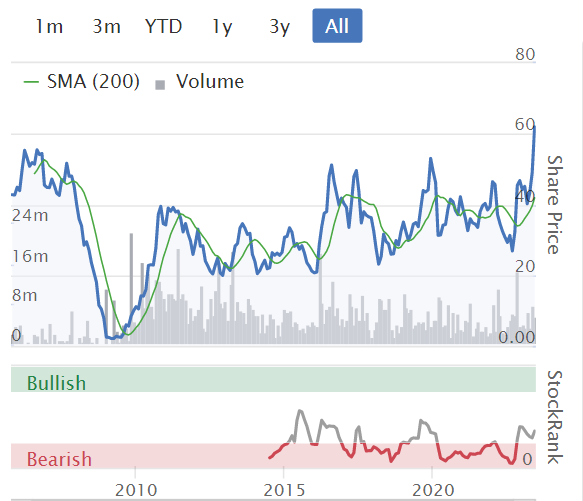
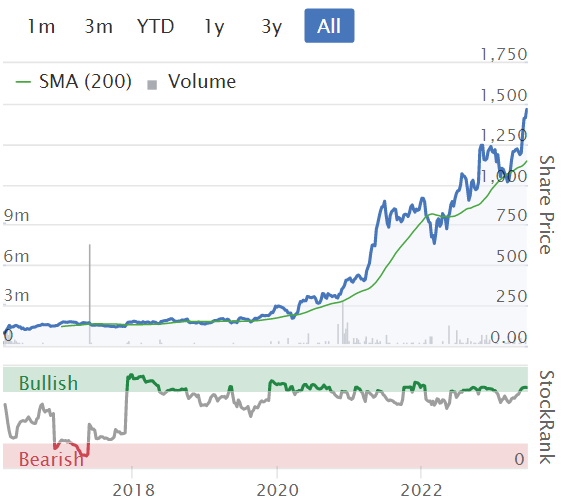
Hitting all-time highs in a weak market -
THG (LON:THG)
Up 6% to 77p (£1.12bn) - AGM TU (in line) - Paul - RED
See my notes from 12 May 2023 for details on why I think this share is so awful. Both management and shareholders seem delusional about what it’s worth, and don’t seem to have noticed that the irrational tech boom has ended (or has it?!) and that this isn’t actually a tech company anyway.
Today’s update says that guidance for FY 12/2023 is in line with broker consensus.
H1 adj EBITDA of £44-47m is up on £32m in H1 LY. However, EBITDA is nothing like real profit, or cashflow, at this company, so is best ignored.
Free cashflow is negative at -£(40)m in H1, and is ahead of (clearly not every ambitious!) expectations. Signs of life for the full year though - although this is lamentable for a company valued at over £1.1bn! -
The Group remains well on track to deliver free cash flow neutrality[3] for the full year, with adjusting items materially lower than the prior year.
[3] Group free cash flow is calculated after working capital, net capital expenditure, adjusting items, tax and financing (prior to debt capital repayments and deferred consideration on acquisitions).
I’d want to see the full accounts before relying on any of these snippets in trading updates, given the rampy presentation of numbers in the past.
Good news on margins though, to be fair -
THG Nutrition has had a particularly strong start to the year, with the pricing decision to support consumers through exceptional market-wide inflationary conditions in FY 2022 now paying dividends. Commodity prices continue to ease, with further margin benefits expected in H2 2023.
Outlook - also sounds more reassuring than what we’ve heard in the past -
For the Group, Adjusted EBITDA margin accretion into FY 2024 and beyond will be driven by annualised commodity pricing benefits, ongoing automation efficiencies and operating leverage, in addition to normalised capital expenditure, underpinning positive free cash flow guidance for FY 2024.
The founder’s “special share” has been cancelled.
Paul’s opinion - no broker notes are available, but I can see from the StockReport that consensus is for continued losses after tax of over £100m in each of FY 12/2023, and £FY 12/2024. So investors are being asked to continue valuing a massively loss-making cumulatively business at over £1bn, in the hope that it can eventually reach breakeven.
I can’t see the appeal to that, but maybe I’ve missed something?
At least today’s update shows some progress is being made towards the goal of turning this into a viable business. Although it seems likely that achieving free cashflow breakeven, but still heavy losses on the P&L, must involve favourable but unrepeatable working capital movements from reducing inventories, I reckon.
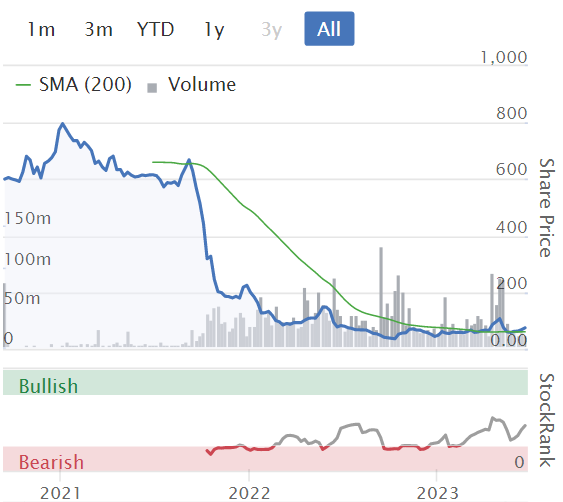
As you can see, this was another utterly ludicrous valuation, pandemic era float, and it remains too expensive, even after this collapse in share price -
Graham's Section:
Water Intelligence (LON:WATR)
Share price: 429.5p (-2%)
Market cap: £83m
Water Intelligence plc (AIM: WATR.L) ("Water Intelligence" or the "Group"), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water, is pleased to present its full, audited results for the year ended 31 December 2022.
This US-based share has been very highly rated in the past, commanding enormous P/E ratios:
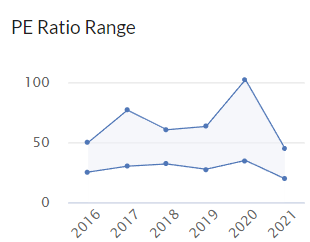
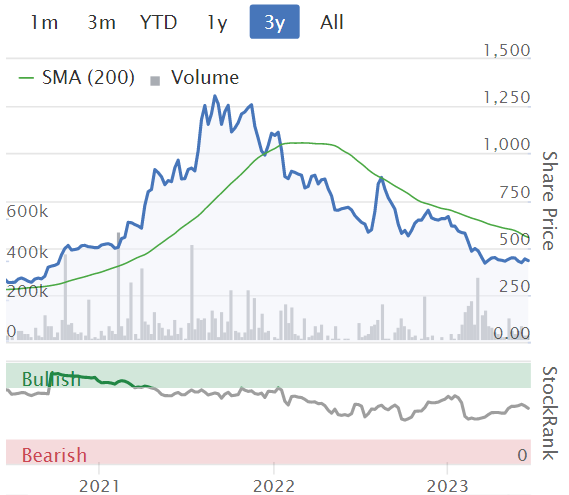
However, it has come off the boil over the last two years, and is now down over 50% from its peak.
Here are the key points from today’s release.
Overview:
Market demand for the Group's water leak detection and repair solutions remains strong reinforced by increased public sector spending forecast in US and EU for aging water and wastewater infrastructure.
2022 results:
Revenues +31% to $71.3m
Adjusted PBT +12% to $7.8m
Total network sales are the best indicator of the total size of the business, as they include both direct sales by WATR to end consumers, plus sales by franchisees. This metric grew by 11% to $165m.
And note that most of WATR’s profits are generated by high-quality royalty income from franchisees, rather than by the company’s own direct sales.
As we are already halfway through 2023, I won’t dwell on the results from last year. The company confirms again that there has been a “strong start” to 2023.
Net debt as of May 2023 is $8.4 million. This figure includes c. $12m of deferred acquisition payments, some of which aren’t due until 2027. So in reality the liquidity situation is a little stronger than this net debt figure suggests.
The company chooses to not yet pay any dividend. That’s probably the right decision, given the outstanding obligations and its growth ambitions.
Chairman - the chairman is crucial to the story here. He owns nearly 28% of WATR and is a shareholder of a company that owns another 14%.
In 2022, he was paid $590k plus stock options with a value of $80k. So total comp is over half a million pounds sterling. Is that perhaps a little high, given the size of the business?
Graham’s view
The company doesn’t provide much more information on the outlook for 2023, so it’s time for me to start wrapping this up.
Overall, I’m neutral on this one. I can see the attractions of a franchise-based business providing essential services. Profit margins are quite good and overall quality is above-average (QualityRank is 84).
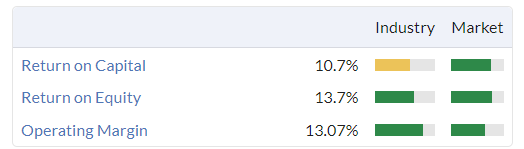
At the current valuation it may be worth considering - it’s not cheap in a traditional sense, but the track record of growth suggests that shareholders could do well from here. So I’m open to the idea of giving this one the thumbs up in a future report.
Graham’s Section:
Liontrust Asset Management (LON:LIO)
Share price: 750p (-2%)
Market cap: £487m
This fund manager publishes full-year results for FY March 2023.
It’s a stock which I have viewed as simply “too cheap”, along with several other fund managers who have seen their shares collapse due to the poor sentiment (and volatile performance) of equities.
Adjusted PBT for the year comes in at £87m. This is slightly ahead of the figure suggested by the company when it raised expectations in April. But it is still down 10% on the prior year.
Statutory PBT is a lot lower - only £49m, down 38% on the prior year.
Since the discrepancy between adjusted and statutory PBT is so large, let’s go straight to the reconciliation and see what is going on.
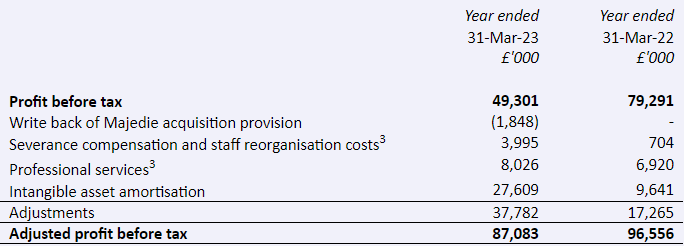
What jumps out at me is the “intangible asset amortisation” (third line from the bottom), which is up by £18 million (from £9.6m to £27.6m)..
Unable to find a satisfactory explanation for this in today’s RNS, I’ve had to go back to the interim report to look for clues there.
What I discover is that what Liontrust refers to as “intangible asset amortisation” is in fact amortisation and impairments, and the impairments are significant. But today’s RNS didn’t break out the impairment charges.
In the interim report, I find this table, showing the amortisation and impairment at two acquired businesses::

I could be missing something, but the £4m impairment figure for Majedie doesn’t make sense to me - add up the columns and rows and you’ll find that this table just doesn’t work. Does it include an error?
It’s not the first time that I’ve found Liontrust’s announcements to be less than entirely helpful.
Last year, in a trading statement, the company announced that AuMA (assets under management and advice) had fallen by 5.5%. It was left to investors to figure out that excluding acquisitions, AuMU was down by c. 20%.
It is a standard pattern for companies in general that when the effects of acquisitions are beneficial, they are likely to be included in the headlines. But when the effects of acquisitions are less beneficial, investors have to go searching for them!
Let’s move on and look at some other aspects of today’s full-year results:
AuMA £31.4 billion, down 6% (remember that this number has been boosted inorganically by the Majedie acquisition, which brought in £5.1 billion. The organic fall in AuMA is much larger).
Net outflows of £4.8 billion, with more outflows in H2 than H1.
The CEO comments on the planned purchase of GAM, a Swiss fund manager.
The proposed acquisition of GAM will help us achieve our strategic objectives through the global distribution footprint, expansion of asset classes, processes and investment capability, and the combined business infrastructure.
The collective scale of and expertise across the enlarged group will provide financial stability and certainty to GAM's clients and shareholders.
CEO comment
Many shares in Liontrust’s “sustainable” fund category have had very poor ValueRanks, i.e. they were quantitatively poor value and probably on the speculative end of the spectrum.
Today’s CEO comments touch on the performance of Liontrust’s “sustainable” investments::
…the rotation from quality growth to value stocks had started to impact the performance of many of our funds. While this has continued over the past year, I am proud of the proven long-term track record of our teams and their processes. This includes the Sustainable Investment team, who have delivered strong returns following previous periods of relative underperformance.
Outlook - gives little away, but talks up the GAM acquisition.
GAM buyout - this deal is being paid for in Liontrust shares. At the cost of some dilution, AuMA is set to significantly increase, if the deal goes ahead.
According to older estimates from Singers, the combined group would have a cash balance of c. £222m. Profitability would improve with the help of £56m in planned synergies, including the rationalisation of roles and various other cost synergies (offices, data, other administrative expenses).
Graham’s view
Again, I must reluctantly give this stock the thumbs up.
At the current share price, it offers investors £61 of AuMA for every £1 invested in the shares.
This figure should rise if the GAM deal goes ahead.
I don’t believe that either the Liontrust brand or the GAM brand are particularly strong right now - continued outflows speak to this - but I expect that fund investor inertia will enable these companies to continue to generate significant profits.
Here’s a reminder of the value characteristics of the share, with the typical sign of extreme cheapness being that the dividend yield is higher than the P/E ratio. The company is paying another 50p dividend, so the total payout for the year is 72p.

No company is perfect but nearly every company is too cheap at some price. I think Liontrust is now in that position.
It passes two of Stockopedia’s bullish stock screens: the Philip Fisher Growth Screen and the Free Cash Flow Cows Screen.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Anyone a holder of Hunting (LON:HTG)? Been knocked out of the FTSE 250 so suspect tracker funds selling?
Trading seems to be improving tho so may be an opportunity. Zeus upgraded EPS/PBT by 25% + 12% for 2023/24. 2023 doesn't seem to have filtered through to stocko.
PER around 10.5 +9 based on Zeus
Trading update in 2 weeks. It's below the price it gapped up on a contract win/revised guidance. Been watching for a while and it's the first afternoon for some time there's no seller knocking the price. Volume pretty low tho.
Hey Paul, is Gear4music (HOLDINGS) (LON:G4M) still on the agenda? Very interested to hear your thoughts, but also appreciate there has been a lot of work done already!
Yes, I'll try to catch up with backlog items, but might have to be on Friday, if it's busy tomorrow.
Thanks Paul, no worries at all.
Impressive mid morning update form Augmentum Fintech (LON:AUGM) which may have been missed - one of their positions has had a new funding round at almost 3 times its previous valuation. Not so long ago they sold one of their positions to Natwest at a 40% uplift. AUGM itself trades on a deep discount to NAV and has a good track record so looks to be a lot of value there.
They call themselves "Europe's leading pubicly listed fintech fund"...
They're buying back shares too. It's interesting to look through the 24 companies that they hold in their portfolio - all fintech - some very interesting ideas in there.
Yes it looks like an interesting portfolio and they seem to have natural buyers for their investments from the big financial institutions (Natwest and Abrdn being recent examples) who generally have a lot of cash and a need to innovate - doing it in house has had very mixed results so they increasingly just buy early stage fintechs.
They've done a couple of presentations on the Investor Meet Company platform and I thought they were very impressive. They have a fairly prudent, methodical approach and didn't splash the cash during the massive bubble in early stage tech companies in 2021. As a result they have a decent cash pile ready to be deployed.
I am getting very frustrated trying to sign into Stockopedia on my Ipad. What is going on?
No problem on my Desk Top Computer. Are other Subscribers having this problem?
Had a few problems yesterday on iPad, but not today, although the site is slow.
I have had the same problem since Monday afternoon so much so that I took the decision yesterday to give up and have consequently cancelled my subscription.
Paul said this on the SCVR yesterday:
Sorry for the logging in problems yesterday, should now be sorted. Apparently any remaining login problems can be resolved by clearing your cache (I just googled it last night, and it's very simple!)
Might be relevant?
Logging in is not my problem, it's logging out. I'm sure I'll sort it but this shouldn't happen, opening Chrome on my desktop and finding myself already logged into Stocko.
Thanks Indie but I have tried that but all to no avail I'm afraid bearing in mind I am nearly 80 and are not very tech savvy also tried to contact the support team by phone twice but on both occasions was instructed to try again later as their lines were full.
The problem with clearing the cache on an iPad is you lose all your passwords and tabs. It also often does not do any good. This site is the worst I use. It did improve when it went to cloud based but recently it is slow to log on and often I get connection warning messages, even though my internet connection is fine.
Apologies for posting today rather than yesterday when Paul provided commentary on Saga (LON:SAGA) but, as an older person, I thought that I would try their travel insurance. I was really surprised that I was ruled out on (what I thought would be minor) health grounds. Surely minor health conditions come with the territory - particularly if you are going for the older demographic. Other companies I approached offered cover - albeit at raised premiums. Perhaps this is indicative of why their insurance business seems to be struggling.
Saga gave me a good quote for a recent week's travel insurance. I'm 75 with lots of health problems.
I was refused by many other insurance companies before trying Saga
Daniel Thwaites (OFEX:THW) Figs out today. Seem quite good though they complain of difficult times. EPS 20.1p ..PER of less than 5, though half the profit due to increase in value of interest rate swaps. Debt slightly up. NAV of over £4 per share. Dividend has been increased ! Hopeful of better times and well positioned to benefit.
Interest rate swaps are finally helping them, though their debt is mostly long term at fixed interest rates. Market has ignored these numbers.
'Bank needs to create a recession'
Karen Ward, a member of Mr Hunt's economic advisory council and chief market strategist at JP Morgan Asset Management, said the Bank needed "create a recession" to curb soaring prices, arguing that it had "been too hesitant" in its interest rate rises so far. https://www.bbc.co.uk/news/bus...
The complacency is staggering. Would anyone really trust the same lot who ignored early signs of inflation, calling it transitory, to steer us through a very mild recession.
August 2021 Bailey warned inflation would hit 4% but decided to leave interest rates at 0.1%. at the same time BoE were on a £850b QE splurge.
They are just bound to overshoot to the upside and create a bad recession. Businesses are being hit on multiple fronts with higher corporation tax and very high energy costs. Add to that the uncertainty on ever increasing interest rate rises. One company on the news said they are still paying back the covid loans which they took out at 0.1%, which has now gone up to 5%? Not sure if these were linked to the BoE base rate.
Hindsight is easy. We’re supposed to be non-party political here. But when the government is claiming it will reduce inflation to 5% by the end of the year, they’re saying that they can control inflation and admitting it was their failure that it rose so much in the first place. Yes, the Bank bears responsibility but scapegoating the Bank and not holding the government accountable is sheer political bias.
A very encouraging (pending) contract announcement from SRT Marine Systems (LON:SRT) this morning.
https://www.londonstockexchang...
The country involved is Bahrain, which was the first national coast guard to adopt the SRT technology in 2016.
https://srt-marine.com/bahrain...
They have been an enthusiastic proponent of it since, and the fact that they are now investing to develop and expand it is, a strong endorsement of the value they see in it.
Whilst the numbers involved may be of limited materiality, this endorsement by an existing customer is, in my opinion, much more material to future prospects.
What are the thoughts of the community here w.r.t. investing in UK funds and companies? With inflation still high and BOE likely to hike 50bps, I am looking to reduce my UK exposure. Equities have to compete with higher cash yields. And of course high cost of debt hits margins and profitability
What are the thoughts of the community here w.r.t. investing in UK funds and companies?
My allocation to the UK is 20%, virtually all of which companies have significant international exposure. That sums up my view better than any explanation.
Yes - UK companies with Intl exposure makes sense but even here - buying these companies is expensive with the exchange rate at 1.27 - but of course means better dividends. In the UK companies such as Primary Health Properties (LON:PHP) which I would have classified as a 'widows and orphans' share suffering presumably because of its high debt on the balance sheet
Precisely the reason I'm investing in the UK. It's been deserted for a while (see pension funds moving money away). Generally I prefer to buy when others are fearful as I think this tilts the balance in my favour over the long term. I don't see a "ruin" event of the UK, but have some international shares and gold as a backup. I'm about 70% net worth invested in UK shares and probably about 40% exposed to purely UK revenue.
Been deserted for about 20 years now and will remain the same.
On balance my preference is for Polar Capital Holdings (LON:POLR) over Liontrust Asset Management (LON:LIO) . The former has grown without acquisition, but by introducing mew funds and hiring able fund managers. I acknowledge Polar Capital Holdings (LON:POLR) large weighting in technology, but it remains my preference. Unsurprising perhaps as I hold.
My view is the same, Polar Capital Holdings (LON:POLR) is much higher quality, and they seem to be quite deliberately trying to reduce the reliance on the technology stable to drive performance. My main concern there is the AIM listing rather than main market, I think this is a hindrance to them getting re rated upwards. But nevertheless I'm happy to collect the dividends and watch the business grow.
Agree too. Much prefer Polar's specialist approach (technology, healthcare, insurance, etc). Liontrust seem to have dozens of near identical funds which really don't stand out. That's what you get by constant acquisition. Performance has also been poor recently.
Well I own both and am very happy to hold for long term
Directors of Revolution Beauty (LON:REVB) issued a squealing response to Boohoo (LON:BOO) 's efforts to oust them. Certainly not bowing out quietly.
What else can they do?
With less than 15% of Revolution Beauty's shares held by small private investors, all they can do is squeal.
They deserve to go - overpaid for an acquisition. Lost the plot. Although frying pan to fire with Boohoo!
Personally, I've always liked Neil Catto as CFO. He's down to earth and says it as it is. Maybe Boohoo is exactly what Revolution Beauty needs.
A somewhat uncheering take on Liontrust Asset Management (LON:LIO) Graham but thanks. I have a feeling that too much profit is going in the direction of the Directors and not enough diligence coming from them. It was not always like this. I hold.
I should clarify that while not a particular fan of Liontrust Asset Management (LON:LIO) as a fund management business, it does look cheap and provide a highly geared exposure to an eventual recovery in UK equity markets, so should do well in long term.
For all the talk from Saga (LON:SAGA) of "Growth momentum continues" all I can see is momentum going in the wrong direction.
PBT looks to have been cut from 36.1m to 31.8m.
Share price is up but this is the danger of buying a company with no broker notes. The trading update spin and the reality seem to be getting wider recently in many companies.
Hi Wolfie!
Thanks for flagging the revised Saga (LON:SAGA) forecasts, which have come through nice and promptly after yesterday's update. It's much as expected, I mentioned in yesterday's SCVR that the wording of the update looked like a disguised profit warning.
26p (old) to 23.3p (new) forecast for FY 1/2024 isn't a disaster though.
Note that the big cruise operators have seen astonishing share price rises this year - Carnival & Royal Caribbean shares have almost doubled in the last 2 months. That's incredible given the heavy debt loads. So the market must be super-confident about the cruise sector, which might make sense given that all those rich pensioners are now getting a new income on their cash deposits.
Some of this should be rubbing off on SAGA shares, so I actually think people might be missing a trick by being bearish on SAGA when it's;
I think there's a danger that investors could miss a nice potential bull run, by clinging on to a overly-bearish view on SAGA.
That said, we all know there are downside risks, which we covered yesterday, so it's not out of the woods, and the insurance operations are not doing great at the moment.
But for £191m market cap, I think the risk:reward might be leaning towards the upside, for a trade at least. Not sure I'd want to hold long-term, as I don't rate management.
All up for discussion, alternative views are equally valid!
Regards, Paul.
Morning Paul. Yes very valid points, the risk reward looks OK
The market certainly likes it, up strongly in last 6 days. It's far too complicated for me, and with no broker notes not something I'd be interested in but can see it may make a decent trade for a few months.
Saga (LON:SAGA)
What really annoys here is that downgrades have ben so conssitent for so long now - and the downgrades are somewhat contradictory to the narrative being presented by the board. Thats sucks big time. I would accept it if they provided clear details - i would guess the reasons for continual downgrades are that the insurance side of things continues to get worse and is outweighing any positive trend ref cruising - who knows though based on current lowered estimates its not clear they are knocking the lights out ref cruising. Also whats teh score with insurance - its gone from highly profitible to bsomewhat sucking - what are expectations for next 24 months , in some respects thats the most important uknown. Could insurance be trending to nil profits or could it at soem stage bounce back to £80 mil plus profits pa - if mamangement had some plan to ensure margins are decent that would be great. I know all has changed recently ref the way insurance has ben doen but i would expect most companies to still be mkaing reasonable margins eventually under new rules for them to be viable - who knows.
One should be hpoeful that at least 2025 numbers are expected to be up on 2024 and we are still expecting profit so they still have some leeway ref the future. But if they continue the habbit of starting high and lowering during the year that really does suggest to me management are bordering on incompetent if other companies are starting to do what they said they would do on the tin.
The main thing any holder should be prepared for it almost total wipeout if market forces drive shareprice lower and force them to raise cash.Paul seems to think 2026 is sufficiently in the future - but really they need to be upping cash level every 3 months on top of paying down debt (ships will depreciate) - to show they can accumulate funds so that if tehy need to pay off 2026 financing they can do - or at least show the market there is whole life cycle viability without going cap in hand to shareholders again. So upside may be great but whilst shareprice is low the vicious circle ref dilution similar to revolution bars raises its ugly head. Its pretty obvious the market is cynical ref companies ability to propser and one cant blame em when management keep lowering expectations. I do share Paul's view ref the upside potential here that is not in dispute.
Re. Best Of The Best (LON:BOTB) - quite an unusual one here where the offer has no premium and is actually at a discount to fair value (as backed up by BOTB's financial advisers Finncap). There's potentially a small opportunity here for anyone who doesn't currently hold. Buying in at this morning's 520p price gives you a small profit if the deal goes through at the undervalued 535p bid price (with the potential to increase this if the shareholders hold out for a increased offer) and your main 'risk' is the bid collapsing / being withdrawn - which would then reset things to where we were before the bid - at a time at which the price was actually higher anyway. Potential flies in the ointment of course re. the management's position / continuity and Sagi seeking to cause further trouble if the bid fails, but seems more likely we will see a concluded bid either at 535p or a slightly higher price. It's an unusual case of being able to buy in after an offer without the usual risk in a bid scenario of a collapse in price due to bid premium evaporating. 15p profit is not much if there is no higher bid of course (it gives you 2.8% profit - still not bad if you assume say a 2 month wait for the deal - annualised that's equivalent to 16%pa return), but you could view this as buying yourself an option over a higher bid for a price that should give you a small profit in any event (an option you get paid for...) whether it's worth it depends on how likely you view a higher offer and how likely you think the downside case of no concluded deal might be.
BIACS
Best Of The Best (LON:BOTB). I think these are the most telling sections, deep within the offer announcement (apologies for the long quote):
"View of the Company's independent financial adviser with regard to the financial terms of the Offer
The Independent BOTB Directors accept the advice of finnCap who have advised as to the financial terms of the Offer. finnCap has on balance determined that, in their opinion, the financial terms of the Offer are not fair and reasonable. In providing this advice to the Independent BOTB Directors, finnCap has taken into account the commercial assessments of the BOTB Board.
finnCap has observed in this respect that the Offer Price represents (i) a discount to the volume-weighted average price of a BOTB Share over near-term time periods which it believes to be most typically reviewed (being thirty, sixty and ninety days) to assess the Offer price against; (ii) implies a lower range of multiples of revenue and earnings than that of companies and transactions identified as being broadly comparable to BOTB and the Offer (whilst recognising that there is a very limited pool of directly comparable and relevant companies and transactions); (iii) carries no conventional premium to the near term share price for obtaining control of a public company; and (iv) does not fully recognise the value that could potentially be generated should the Company's strategy (including the benefits of the GIL partnership) be successfully executed and delivered as currently anticipated.
Conclusion of the Independent BOTB Directors
The Independent BOTB Directors have considered the advice from finnCap carefully and acknowledge that the Offer may not fully recognise the potential shareholder value which may be generated in the longer term as a result of a deep and successfully executed partnership with GIL and that it also lacks a customary control premium based on the closing price of an Ordinary Share on 19 June 2023, such that the financial terms, taken in isolation, are not fair and reasonable.
The Independent BOTB Directors maintain confidence in the Company's current strategy and its ability to respond to the challenges that the Company will inevitably face in a challenging inflationary and consumer environment.
However, the Independent BOTB Directors acknowledge that there are execution risks to this strategy during the transition in leadership of the Company....."
This is where the Board then lays out some wishy-washy excuses for losing all backbone and capitulating to the bid. I'm afraid CEO William Hindmarsh will not be on my Christmas card list.... (I'll refrain from using stronger words)!
I also note the bid approach was made more than five weeks ago:
"On 11 May 2023, GIL and BOTB entered into a non-disclosure agreement in relation to the Offer"
As someone who topped up their (admittedly modest) holding on 12 June at 595p, that really rubs salt in the wound!
Some credit is due to finnCap, at least.
Fantastic additional detail, thanks Chris! I will refer people to your post in the main article, as an edit :-) As you say, bravo to Finncap, showing that they're not just rubber-stamping things.
Shocking looking inflation figures this morning. The BoE have been absolutely hopeless since M King left, Carney sowed the seeds and the current moron is finishing off the job.
I really do dispair at current politicians. Housing policy, energy security and general monetary competency are a joke and it isnt even political because they all follow the same path.
Looking at interest rates peaking around 6% now you can see why investors are avoiding the UK, inflation will eventually come down but they may have caused a recession getting there.
Rant over.
It's amazing how similar May 2023 inflation figures are to May 2022. CPIH exactly the same on an annualised and month-on-month basis, at 7.9% and 0.6% respectively. Hopefully we are now at least on a declining trend, if only slightly.
Shocking looking inflation figures this morning. The BoE have been absolutely hopeless since M King left, Carney sowed the seeds and the current moron is finishing off the job.
Central banks across the board used QE before and during the pandemic, but only the UK appears to have sticky core inflation - the US is at 4%, the Eurozone at 6%, both falling quite rapidly.
There appear to be a number of reasons for this but UK wage inflation is running at over 6% and being fuelled by a lack of workers, either because they've taken early retirement, can't work because they're ill or caring for people who are ill or have simply left the country. Mostly those are structural problems that will take years to fix.
And as people roll off two year fixed rate mortgages taken out at the end of the pandemic there's still a lot of pain ahead.
timarr
I just don't believe the Eurozone figures. They don't match up with what I see on the ground.
Also we import about 50% of our food. Energy prices for households has not fallen yet, but will do in July.
I'm seeing a few food prices fall for the first time, in the last year, but still some others are going up, such as potatoes, tomatoes, eggs, bread and yoghurt.
Interest rates increasing will cause inflation for many households and rented properties are up around 12% if you saw the news last night.
I don't agree with putting interest rates to reduce inflation, in the current situation. It could push us into a recession.
Good morning Rusty, I agree that there is so much more we could be doing other than raising interest rates. For instance growing more of our own food by using green field for market gardening instead of house building, householders turning their patio and patch of grass into a vegetable garden or working allotments. But I am biased, see my back garden of today!
Haha love the picture, Silver Moon!
I half expected to see Tom & Barbara lurking behind some runner beans, trying to get the pigs back into their pen! And Margot leaning over the fence with a look of horror on her face!
A wonderful comment Paul, I am going show it to my better half! I might even frame it between our two Polymetal International (LON:POLY) paper share certificates....
showing your age!
I'm also growing some vegetables and fruit, but my garden is a lot smaller than yours, so I only have lettuce, blueberries, onions, tomatoes, Pak Choi, Chard, Cauliflower and runner beans.
Only problem is they need watering, which is not good as we no rain for 5 weeks.
I'm not on a water meter but the can is best except on seedbeds. Had a proper rain shower yesterday for the first time in those 5 weeks, garden is happy now and so am I.
Two particular reasons, caused directly by the government, that account for high inflation and lack of workers, are
the increase of the minimum wage by 10%, so of course everyone else wants a 10% pay rise
the number of people employed by central government has increase by 400K since mid 2019 and still increasing thus reducing the workforce pool and increasing our taxes/borrowing.
And don't get me started on Andrew Bailey who is now going to employ consultants to tell him what he has done wrong!
In my opinion our high inflation is due to the fact that we import most of our food. The high energy prices are feeding into the increased cost of food, as well as our own energy bills. I was in Germany and food costs there are also very high although they produce a lot of their own fruit and veg. I blame the high energy costs which feed through to everything, from businesses to transport to heating etc. Cannot see this improving any time soon due to net zero.
The BoE has a tightrope to walk. I dont agree with higher interest costs as this does not address the underlying factors and in fact fuels inflation even more. All this independant BoE talk, they need to work with the government. They should also have a target for growth as well as a target for inflation.
Not to mention the impact of Brexit on reducing worker availability from the EU in key sectors such as agriculture, as well as acting as a further accelerant to wage inflation.
Aren’t we suppose to be increasing import checks/controls later this year also, further increasing costs of EU exporters to U.K. and likely fuelling further inflation?
Re; further checks this year
Can't remember when the BoE has performed this badly. Most commentators said that inflation would be sticky and not transitory. Spent a year raising rates gradually by 0.25% a pop, now inflation is embedded and will only be dislodged by a recession.
That’s always the case!
Re BOTB/Kape - Was a large Kape holder, got stitched up. The moral of the story is.... if Sagi is on the register don't get involved. He clearly gets the board/s onside early doors, they walk with their profit and then let let the company/s go for a song. Hey ho...nothing illegal, such is life!
My morning smallcap tweet: They're talkin' bout a revolution
Revolution Beauty (LON:REVB) Hydrogen Utopia International (LON:HUI) SIMEC Atlantis Energy (LON:SAE) Skinbiotherapeutics (LON:SBTX) Touchstar (LON:TST) Cerillion (LON:CER) SRT Marine Systems (LON:SRT) Haydale Graphene Industries (LON:HAYD) i-nexus Global (LON:INX), HSS Hire (LON:HSS)
◄Revolution Beauty (REVB)► says BooHoo's AGM requisitions to remove execs are "value-destructive, opportunistic and self-serving". Manoeuvres to postpone AGM so holders have time to think about it properly ie get some propaganda from the board sent to them. [SP=8.25 Cap=26m]
◄Hydrogen Utopia International (HUI)► plans to buy substantial minority stake in Carbon Capture and Sequestration Limited. There is a related-party transaction in the works involving a cannabis company. That smells a bit. [SP=5.95 Cap=23m]
◄SIMEC Atlantis Energy (SAE)► AOE17 debenture holders agree to extend maturity by a year but rate hiked to 10% PA. [SP=0.99 Cap=7m]
◄SkinBioTherapeutics (SBTX)► AxisBiotix-Ps receives health authority approval for launch in Italy, the second European country. [SP=12.7 Cap=22m]
◄Touchstar (TST)► will start divs, will be announced in Sept. £300k buy-back. [SP=104.5 Cap=9m]
◄Cerillion (CER)► wins six-year contract worth a total of £15m. [SP=1470 Cap=433m]
◄SRT Marine Systems (SRT)► existing Coast Guard customer to place follow-on contract worth c.£10m. [SP=60.54 Cap=110m]. I hold.
◄Haydale Graphene Industries (HAYD)► guides FY-June rev ahead of market expectations of £4.1m despite a number of projects expected to start during June slipping. LBITDA miss. Cutting costs. Directors "expect the commercial momentum from this Year to continue during the Year Ending 30 June 2024 although anticipates a slower than anticipated revenue build than previously signalled." [SP=1 Cap=8m]
◄i-Nexus (INX)► to issue £0.5m of convertibles (10p strike) and extend 2020 and 2021 convertibles. [SP=3.5 Cap=1m]
In line: HS
No mention of the one where you were short?
I didn't see the Chill Brands (LON:CHLL) RNS. Is that what you mean? I closed my short a while ago.
Avacta (LON:AVCT) is RNSs every single step in its trial. I don't think the fifth dose escalation result is material although the market clearly does. I'm still short.
Probably Avacta (LON:AVCT) (I hold) had some quite remarkable news this morning.
Edit: You've update your post - fair enough.
But still and will still be burning an enormous amount of cash.
From the figures: looks as if they'll probably need a raise mid next year (I believe thats why companies list on public markets), but for most holders they're not looking to Avacta (LON:AVCT) to take this to market, most likely they'll get bought out. That is how the Pharma industry seems to work. The data is quite remarkable, to see that several terminal cancer patients have had their cancer somewhat halted is fantastic news.
This is Phase1. Just saying……
Thanks for the listing and Pharma lesson though. Never knew all these. Much appreciated.
Yes, I was referring to Avacta (LON:AVCT) . I only commented because from your posts, it doesn't seem you hold or short that many shares (maybe I'm wrong on that (?), just my impression after a period of time reading your posts), despite the time you clearly put in to analysing what's going on - so it kind of stood out. Fair enough.
revolution - opportunistic and self serving - absolutely, the inverse would be moronic. Value destruction - I think about the incentive here, the execs get sacked and lose their ability to be self determining. The synergy between revolution and boohoo is self evident, so share holders in both benefit.
Inflation figures for May are not encouraging. Depressingly I suppose it will mean further interest rate rises and further downward pressure on FTSE 250 and smaller companies.
Notice though the PPI numbers both core and non core have come in much lower than expected and on a month on month basis have gone negative. I'm no economist but it seems in the UK lower prices are taking longer to filter through.
Someone seems to be selling alot of M Winkworth (LON:WINK) at the moment, down nearly 20% yesterday
Yes I noticed that too - anybody know if this is Odey related?
M Winkworth (LON:WINK) - no Odey shareholding on register.
Avacta (LON:AVCT) 5th cohort complete on P1a trial on to cohort 6 (max 7). From the RNS:
"Several patients remain on trial in different dose cohorts and continue to receive AVA6000 as their disease has not progressed".