Small Cap Value Report (Wed 22 April 2020) - ABDP, MOSB, XLM, BOO

Good morning, I'm back, it's Paul here with the SCVR for Weds.
It's quiet for news today - please see the header for the running order today.
Estimated timings - I'm running a bit late today, and have also just managed to hit the wrong key and delete everything written so far, so am having to re-do it. I should be finished c. 5pm. (extended, because it's going to take me a while to read through the BOO results & broker note)
Edit at 23:41 - OK that didn't work out as planned, but today's report is now finished.
Ab Dynamics (LON:ABDP)
Share price: 1487p (down 2% today)
No. shares: 22.5m
Market cap: £334.6m
AB Dynamics plc (AIM: ABDP, "ABD", "the Group"), the designer, manufacturer and supplier of advanced testing systems and measurement products to the global automotive market, is pleased to announce its Interim Results for the six-month period to 29 February 2020.
The announcement has been given one of those little titles that PR companies seem to like to insert, to steer us towards the conclusion they want, namely;
"Strong first half financial and operational performance across the Group"
Given that the half year end was 29 Feb 2020, then Covid-19 would not have had much, if any impact on these numbers. Hence they're not terribly significant. Outlook comments matter more at the moment.
Here are my notes on the H1 results-
- Revenue up 34% to £34.7m
- Underlying revenue growth is lower, at +11% (still good though). The difference is due to 2 acquisitions, rFpro, and DRI which added more revenues into these figures
- Adjusted operating profit of £8.6m, up 34% (same % increase as revenues). This is a strikingly high op profit margin of nearly 25% - which means this business has considerable pricing power - it must have good products, with little direct competition, to be able to generate a 25% profit margin
- Statutory op profit is much lower, at £3.6m. Adjustments look OK, apart from £1.86m inventory impairment, and £0.54m share based payment, both of which strike me as normal costs of doing business
- Net cash very high, at £35.1m - hence this business looks financially secure, even if Covid-19 hurts its performance in H2 and beyond. No need for a fundraising from shareholders, in my view
- Adj diluted EPS up 10% to 31.2p - this reflects the increased share count, after a big equity fundraising last year
- Recurring revenue has risen from 10% to 25%, which is good
- Interim divi suspended - surprising, and worrying, given how small the divis are, and how high the cash balance is. Trouble ahead?
- Outlook - some large orders deferred. H2 "highly uncertain". Withdrawing forward guidance.
- Balance sheet - very strong, despite cost of acquisitions.
.
My opinion - the outlook comments are very worrying, and suggest to me that
There's no doubt this is a great quality company. However, the automotive sector is a nightmare at the moment, it was struggling even before Covid-19 clobbered things further. Therefore it seems likely to me that ABDP's customers are bound to want to rein in capex, which is likely to harm ABDP's sales and profits, potentially seriously, at least in the shorter term. That's all quite obvious really.
Yes the share price has fallen back a fair bit, and as with most things, bounced considerably from the lows.
Personally, I wouldn't want to buy this share right now, because we can be fairly sure it's heading for horrible numbers in H2. The question is whether the market is likely to look through poor H2 figures? People often imagine it will, but then when lousy figures are published, reality for small caps tends to be that a few people sell, and smash the price down due to lack of liquidity.
Overall then, I can't see any reason to buy or hold this share, given that profits are likely to be poor in H2, and maybe beyond? It all depends on your overview. If you think that economies are likely to recover in a V-shape, as suggested by the OBR, then it could make sense to look through short term profit weakness (as seems likely in H2). If however, you suspect that economies could take several years to recover (as I do), then it's probably safest to sit on the sidelines in cash. If ABDP does unusually well in H2, then that could make it more appealing.
I don't know what the figures are likely to look like, therefore I cannot value this share, and have to say I'll steer clear of it for now. Historically though, it's been an excellent company & share. Therefore, long-term shareholders might stick with it, but need to be buckled in for a bumpy ride. Looking at the chart, I wonder if some investors might be "anchoring" to the previous very high valuation, and imagining that it's now cheap (when it really isn't)?

.
Moss Bros (LON:MOSB)
I see from today's update that the bidder is trying to wriggle out of its insane bid for Moss Bros. Why is anyone surprised about that? Who in their right mind would want to buy a chain of closed shops?
My take here on 12 Mar was: "I have to say, I think the bidder is crazy, and would be tempted to sell in the market at close to 22p, if possible, in case they change their mind!"
The share price has plummeted today to 14.5p (down 29% on the day). If the bidder doesn't want to proceed, then it strikes me as highly unlikely that the bid would go ahead, whatever the legal technicalities.
I see little to no value in MOSB shares, hence would be a seller at 14.5p now, if I'd been asleep at the wheel and not sold previously into the higher price.
Xlmedia (LON:XLM)
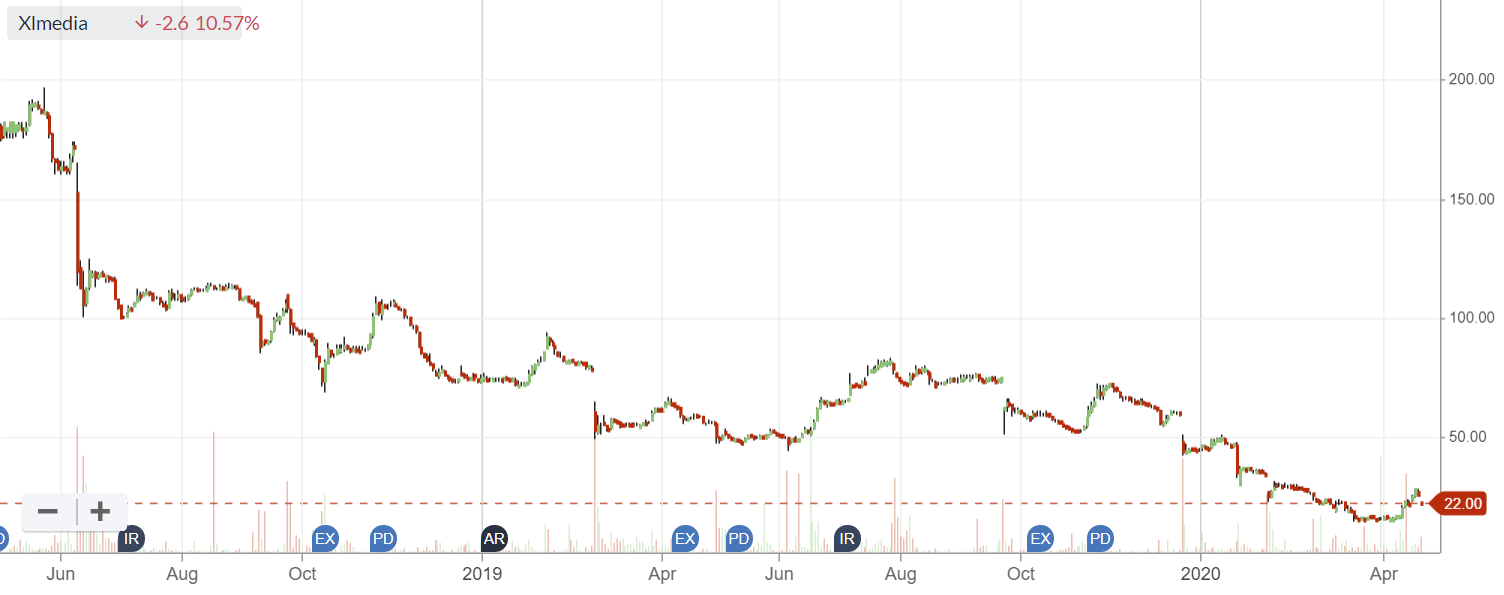
Share price: 22.5p (down 9% today)
No. shares: 187.1m
Market cap: £42.1m
XLMedia (AIM: XLM), a leading provider of digital performance marketing services, announces the Company's audited results for the year ended 31 December 2019.
Considering the market cap is now down to only £42.1m, the 2019 results make this share look a fantastic bargain. It made an adjusted profit of $25.3m (albeit down 30% on prior year).
The problem came after the year end, with google de-ranking some of its websites, and now Covid-19 having some impact.
For years now, I've been emphasising that the profits & cashflow at XLM are real, but questioned whether they are sustainable. That's the big unknown here. Unfortunately, I don't see enough visibility to be able to determine whether there's a likely turnaround here or not.
The only reason to hold the shares in the past really, was the divis. Hence this statement puts me off;
Board will not be recommending a dividend or share buyback programme for the foreseeable future
That suggests to me that management cannot be particularly confident about re-building profitability.
Balance sheet - not as good as I thought. Note there's a big income tax liability within creditors, of $11.9m, which if paid would make a large dent in the $27.1m cash pile. I've looked through note 15, and cannot work out why the balance sheet tax liability is so much larger than the P&L. I'm not interested in wasting any more time digging through the detail, so will leave it there on that point.
My opinion - this one has to go into my "too difficult, and too uncertain" tray.
The big issue with this share has always been whether its profits were sustainable. It turns out they are not. Sometimes companies like this can re-build profits somewhat, branching out into different areas. Therefore I think a partial share price recovery is possible.
The part of my brain that likes a punt, has begun sending me "go on, buy a few of these!" signals. I'm trying to resist it, because I don't have enough information to be able to make a rational decision.
.
Boohoo (LON:BOO)
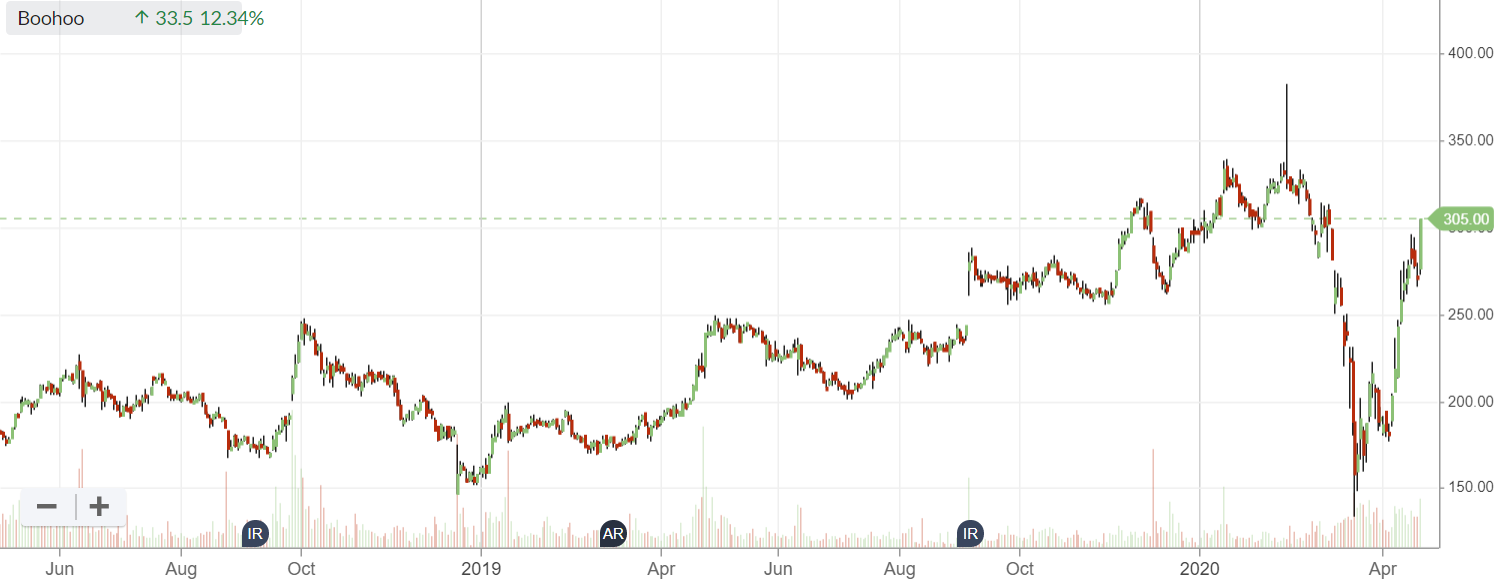
Share price: 293p (up 8% today)
No. shares: 1,160.2m
Market cap: £3,399.4m
Sparkling figures today, from this online fashion multi-brand group, for the year ended 29 Feb 2020.
It looks like an earnings beat, with adj diluted EPS of 5.88p (Stockopedia consensus: 5.66p).
I'm just printing off the results & an updated note from Zeus that is available on Research Tree. As it's sunny, I'll sit in the garden and read those, so please bear with me. Several hours later - I've ploughed through all the detail, as well as having a nap in the sun. I highly recommend the Zeus note - it summarises things very well in 4-5 pages of narrative.
Going through the numbers & commentary, it really hits me, what a fantastic business this is. Growth was again strong in FY 02/2020, and the business is generating prodigious cashflows now - something that Asos has never managed.
I won't go into the detail of the numbers, but take it as read that FY 02/2020 was a fantastic year for the group, and the balance sheet is laden with cash - net cash of £240.7m. Therefore, solvency is not an issue, even if Covid-19 worsens. This is where the superiority of BOO's business model really shines. Its cost base is largely variable, e.g. marketing, logistics, etc. Traditional retailers are facing serious tests of solvency, in dealing with the fixed costs of many physical stores, and the fact that those stores are currently shut, generating zero revenues. By contrast, BOO seems to be functioning as normal, being online only. That's an incredible advantage, especially that most of its competition is effectively shut down. So whilst (mainly) women may be buying far fewer clothes overall at the moment, BOO's market share must have gone through the roof.
Outlook/Covid-19 - The elephant in the room is obviously Covid-19, whose effects began to hit businesses hard after BOO's 29 Feb 2020 year end. As a couple of readers have commented, the wording in today's update does seem ambiguous. However, reading the Zeus note has helped clarify this. BOO says;
The group saw a strong end to the financial year ended 29 February 2020 and in the first two weeks of FY21 this trading momentum was maintained. Since the middle of March, trading has been mixed, as a result of the impact of the COVID-19 pandemic, initially with a marked decrease in year-on-year growth...
Taken in conjunction with what the broker says, I think this means that the group was still generating positive Y-on-Y sales growth, albeit at a lower level (not provided). Next it says;
Performance has improved in more recent weeks and we are now seeing improved year-on-year growth of group sales during April.
That suggests to me that sales growth is positive, and improving. In the current circumstances, that has to be seen as encouraging.
Forecasts - Zeus has very sensibly slashed forecasts. Revenue growth of +15% is pencilled in for FY 02/2021. Nobody knows how accurate that will be because it depends on what happens with Covid-19, and Govt policy, consumer confidence, etc.
In the positive scenario, if lockdown can be withdrawn in the next few weeks/months, then that should boost demand. However, once the High Street re-opens, then a lot more competition to BOO resumes trading, and will be highly price-competitive, since the High Street retailers will be desperate to clear their spring/summer stock at deep discounts. That could be a nasty headwind for BOO over the summer.
In the negative scenario, if lockdown continues, or is re-imposed after a second wave of Covid-19 later this year, then paradoxically that would probably be a boost for BOO as competitors are once again forced to cease trading from physical stores, in many cases probably for the last time - it's difficult to imagine how many clothing retailers could survive another extended lockdown.
Overall, Zeus is forecasting negligible change in EPS, to 5.9p in FY 02/2021. That's a PER of almost 50. Expensive? Not necessarily, as the earnings forecast is for a year when many companies will almost certainly suffer extreme losses. Therefore I think that has to be seen as the low point for earnings. Once recovery is underway, then it's really not a stretch to imagine BOO achieving EPS of 10p+ which would bring the PER down to below 30.
This is such an outstanding business, which has established the business model of buying up good, but failed brands, then applying the BOO treatment of better product sourcing, test & repeat online only selling, and marketing expertise, to name just a few of BOO's wide-ranging expertise & experience. Note that Nasty Gal brand is now making a meaningful contribution, at nearly £100m revenues, and a contribution of £33m towards central overheads. Coast, Karen Millen, and MissPap are in the pipeline, starting out to get the BooHoo treatment. Hence these are likely to be drivers of future growth. The up-front costs are easily absorbed by the profits made by the rest of the group. Same with capex & automating its warehouse. Cashflows are plenty to absorb these outlays, and acquisitions of more brands.
My opinion - this is a stunning business. I'm kicking myself for not buying any on the recent plunge. I was so close to buying, but just wanted it a little cheaper. That resulted in me missing the boat. Also, to be fair, we didn't know at the time that BOO was bucking the trend, so it would have been speculative to have bought in the March lows.
Personally, I'm not chasing the price any higher than it is now. But I'll definitely be a buyer if there is another market plunge.
If Covid-19 is something that we are just going to have to live with, until there's a vaccine, as some experts are saying, then it really does raise the question of whether it's worth investing in any physical retailers? There's a lot to be said for just buying the best online retailer, BOO, and holding it forever, safe in the knowledge that it seems largely impervious to pandemics. Plus, it was beating the competition before Covid-19 reared its ugly head. So BOO shareholders are likely to win whatever the future holds. The high valuation does arguably reflect that already though.
One final point, is that it's worth looking at how well international sales are progressing, especially USA and Europe. This is rapidly becoming a global stable of brands, hence I think the £3.4bn market cap has plenty of scope to go much higher, if you take a long-term view, and based on the global potential.
I could scarcely be more positive about a share on fundamentals & business model. Valuation is high now though, so for now, I'm going to sit on the sidelines and wait for a better entry price. This share is in top slot on my wish list though.
.
That's it for today.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
yes easy to miss this boat.
Paul has often said the he doesn't do Pharma and Mining..both require specialist background knowledge. Therefore no point in raising that here..If you want the main BBs will provide almost 24/7 comment ..most of it worthless though there are some very knowledgeable posters. I hold Avacta and Synergain. Made some good profits on Genedrive and took them.
Where I live in London my daily cycle takes me past literally hundreds of folk running/jogging.
Guess where Boohoo (LON:BOO) are reporting strong sales! The other area doing well for them is smart tops for ZOOM office interaction. Sometimes things are hiding in plain sight.
I think a fair analysis of Ab Dynamics (LON:ABDP) - a high ROCE, stellar historical performer but on an pacy rating.
I feel pretty conflicted with shares like this . Terry Smith of Fundsmith has seemingly been riding out the current crisis well, by targeting high return, robust companies and not over worrying about the PER. Yet if things go wrong, it is a long way down for a highly rated stock. Keith Ashworth Lord's UK focused, mid and small cap Buffetology fund uses the same principles and seems to have been battered.
Anyway, back to AB Dynamics. I agree with Paul in that any temptation to buy is negated by passing the tiny dividend. It signals that management aren't entirely confident -so why pay a high price for this share?
The Moss Bros (LON:MOSB) situation reminds me of the bid for Imperial Oil in 2008. When the bidder also seemed to want to walk away (as the deal price made no sense post Lehman Brothers). The Takeover Panel then stood up and refused to let the bidder walk which it was attempting to do on the basis that the deal had not received approval from the Indian Government (as the bidder was an Indian state owned enterprise). In the end the Imperial Oil bid was completed at the original price. But that was back in 2008....
https://www.theguardian.com/bu...
There was also a requirement for 90% acceptances - so there was a big attempt to make sure that all holders had tendered their shares. The Guardian article above refers more to this latter stage of the Imperial Oil saga.
I feel that Paul is unduly negative on Ab Dynamics (LON:ABDP). In particular, I think it is worth focusing on this extract from the interims:
The Group has sufficient inventory and work in progress to maintain production schedules for the foreseeable future and to date there are limited impacts from supplier constraints. The Group is constantly monitoring supplier performance and through proactive dialogue we will attempt to mitigate any risks to production. In many cases, for critical components, the Group has a dual sourcing strategy to ensure any impact relating to individual suppliers are minimised.
rFpro continues to operate effectively as the provision of software can easily be produced from a home environment. The DRI business in California is currently operating both manufacturing and track testing under an exemption to the Californian State shutdown.
The Group has implemented mitigating actions to ensure cash conservation for the duration of the crisis and has approximately £35m of cash available to support any potential emergent issues. It is critical that we maintain our new product development activities during this period to ensure new products and services are delivered on time to meet market demand. R&D activities are continuing as planned with engineering being completed remotely using collaborative online tools. The Group has also determined that it should continue to invest in the Company wide ERP system and has approved the contract to deliver the system in FY21. These actions should ensure AB Dynamics remains well-positioned post-COVID-19.
Discretionary spend has been tightly controlled and the nature of the pandemic is naturally reducing certain operating costs. If required, the Group will make use of government assistance programmes to furlough staff if deemed appropriate, but there are no current plans to utilise these schemes.
I believe that Ab Dynamics (LON:ABDP) are well-placed to weather this storm. I'm not remotely concerned about them suspending the dividend (Paul feels this is "surprising, and worrying"). Pretty much every company is doing this and I am sure that there is strong pressure to do so from non-execs worried about their own personal liability should something go wrong down the line.
I also don't think that a prolonged cut-back in R&D expenses is a feasible option for any motor manufacturer, given how competitive that industry is. That is especially true at present, in my view, due to the ongoing transition from ICE to EV. Those manufacturers that don't invest in new models and technology risk being permanently left behind.
Whilst I'm not necessarily a buyer of Ab Dynamics (LON:ABDP) at this price, given current uncertainties, I remain a reasonably comfortable holder.
I agree with your comments about the major auto manufacturers and their Capex. AB are working with the major quality auto companies and, for example, German manufacturers plan to start production again in Germany in the next week or two. And, VW, re-started manufacturing in virtually all of their many Chinese plants a few weeks ago.
No premium brand is going to want to fall back on developing the next EV models and they are re-building sales in China now.
Obviously we'll have to wait to see what European and US customers do, but the Chinese consumer is buying again.
I am looking forward to Paul’s take on £BOO. I held from November 2015 until selling in Feb and March 9th and 19th (the latter was a huge mistake - at the moment but hindsight is a wonderful thing) for a CARG of 44.2%.
I will almost certainly be buying back in at some point but I struggle with a PE of 46 and Price to FCF of 57 in the current climate (I hasten to add that it was an appropriate rating in a pre-Covid world).
Paul. Good morning. Is Avacta AIM: AVCT worth a look ? It has teamed up with a large US pharma to develop and distribute COVID19 test kits
I bought £AVCT. Can I reach out to Paul and the rest of the community here?
It looks likely that they along with Cyvita (formerly GE Health and now part of the massive Danaher Group ) are going to produce a rapid test for C-19 (ten minutes pregnancy type test).
Avacta (LON:AVCT) is relatively small, they produce the reagent which identifies protein in the 'crown' part of the virus (the bit that makes the virus uniquely identifiable).
Cyvita - have the tech to put the reagent into a 'strip' like a pregnancy test and Avacta (LON:AVCT) retain the IP in the reagent (which identifies the virus). . Cyvita will have the means to manufacture en masse and will also have global reach and probably, given the size of Danaher, connections to the White House etc.
Surely if we all want to be in a place to test, on site, pretty much instantly then Avacta (LON:AVCT) are on to a winner. The market is huge...
Surely if we all want to be in a place to test, on site, pretty much instantly then Avacta (LON:AVCT) are on to a winner. The market is huge...
There are at least 10 rapid antigen tests for COVID-19 already on the market. There are probably more. A lot of them haven't passed testing, there are issues with supply chains, etc, etc.
Basically - every company in this area in the world is working on this. Maybe this will be the best one, maybe Avacta (LON:AVCT) will make a ton of money out of it. Maybe.
timarr
Just to echo timarr's sentiments, it really is impossible to predict which of the many diagnostic tests, drugs and vaccines being developed in connection with the SARS-CoV-2 pandemic will be successful but believe me, this is a hugely competitive area and an area which I, as a biotech specialist, am generally avoiding apart from the exceptions below. Most companies working in this area are of course in the US and if you want to buy a lottery ticket then you could have a look at Regeneron Pharmaceuticals as they have a track record of getting things done quickly and sufficient cash which suggests that their drug has a decent chance of being successful, although they may offer it on a non-profit basis. Within the UK I would favour those companies, such as Tristel or Byotrol, with existing products likely to see longer term increased sales without needing any breakthroughs.
I don't disagree with you all re Covid but as I said in my earlier reply the product is affimers and covid, is a bit of a side story.
As someone who has an interest in molecular farming, I'd have a look at the lottery ticket that is BAT's Kentucky Bioprocessing facility. They could be producing 3m doses of vaccine a week inside 4 months. https://www.bat.com/group/sites/UK__9D9KCY.nsf/vwPagesWebLive/DOBN8QNL# Medicago in Montreal can do similar.
Gilead's Remdesivir is also indicating well as a potent potential cure.
1] https://clinicaltrials.gov/ct2/show/NCT04292899
This trial has just been expanded to 6000 patients, from an initial 2400. If there weren't positive initial results, I don't think this would happen.
2] https://www.statnews.com/2020/04/16/early-peek-at-data-on-gilead-coronavirus-drug-suggests-patients-are-responding-to-treatment/ A Chicago hospital treating severe Covid-19 patients with Gilead Sciences’ antiviral medicine remdesivir in a closely watched clinical trial is seeing rapid recoveries in fever and respiratory symptoms, with nearly all patients discharged in less than a week.
3] There is also earlier positive evidence from "compassionate use" in very severe cases. https://www.nejm.org/doi/full/10.1056/NEJMoa2007016
I was a seller of some AVCT at 75p this morning. I like the company and the news today....but it is up from just 20p since the start of the month and I took my cash back from buying these a couple of weeks ago. Still very positive about a move above £1 but some of these testing stocks are up a lot and the danger is many of them are now well overbought and the competition is not standing still. NCYT has a great test and even WHO approval but is up from 6p late last year. It hit over 500p last week before falling back to below 300p yesterday. That is still a 50 fold increase in six months. Many novices admit they are underwater on this and similar stocks now. I hold NCYT from 64p and 75p and it is exciting to watch as it races up and down.
I have a long list of Covid stocks....mainly involved in testing.....and many of them are now very volatile and very highly rated. So buyer beware is my strong advice. I would not put anyone off buying a testing stock at all....I am all over them....but this is punting not investment in my opinion. If you pick the right one it might make you a fortune.
If you want something a bit more solid in this area then BYOT is one worth looking into (I hold). This is a disinfectant / hand sanitiser company and they have already said that business is very good.
How is Paul meant to comment on (potentially) pie in the sky pharmas involved in developing Covid-19 tests and vaccines, with high hope-based Momentum ranks and minimal Value ranks ? Their eventual success or failure has little or no connection to any historic results and depends entirely on the quality of what they produce either individually or in partnership with other companies. For that you need sector expertise not a forensic ability to interpret TSs and past results.
He knows more than most of us Shanks... his opinion, if he had one, would certainly be valued but I take your point.
Grout I am not sure this is Paul's sort of stock. For what it is worth, my opinion is it looks very promising on two levels. First with regard to Coronovirus it has potential, and it seems to be progressing well. There are plenty of competitors claiming also to be in the mix, and Oxford Uni claim to be making quick progress on a vaccine. Second the testing on Doxorubicen this year which have huge potential to change cancer treatment. They also are doing work in stem cell areas. It really comes down to affimers and the benefits of an affimer over a antibody, smaller, quicker to produce and more consistent. The main issue I have with them is the way they allowed Kumani and his mate to buy shares at 18p two days before announcing they had something on Covid. But if deals come off their existing mkt cap is well short of possibilities.
Well at least it on everyones radar now. Good luck all.
Ab Dynamics (LON:ABDP)
Amortisation of acquired intangibles:
- The amortisation relates to the businesses acquired in the previous year, DRI and rFpro.
November 27, 2019 02:00 ET (07:00 GMT)
Following the Group's successful share placing in May 2019 which raised net proceeds of ca. GBP48m we were able to pursue our strategic objective to acquire value enhancing, attractive acquisitions. During 2019 total acquisition spend was GBP35.4m of which GBP18.1m was invested in the acquisition of rFpro, a leading developer of engineering grade simulation software and digital twins. Immediately prior to the end of the financial year we invested GBP17.3m in the acquisition of Dynamic Research Inc, a leading supplier of automotive engineering test products and services to the US automotive sector.
The Group continues to seek value enhancing acquisitions and the pipeline of potential opportunities remains positive.
Yougov (LON:YOU) mid-year results looks interesting:
· To date, we have not yet seen any material impact to our business from the COVID-19 pandemic
· Notwithstanding the current macro-economic situation, our pipeline of sales opportunities for our syndicated Data Products remains strong with more opportunities for growth in Custom Research
Fevertree Drinks (LON:FEVR)
2019 accounts out today
Sraight over to balance sheet
Cash reserves £128 mill
reveibales owed in 60 mill - payables oued out 34 mill - surplus 26 mil
thats about it - £20 mill of inventories but these are needed to earn their crust.
I think someone was saying a while back that there is not such thinbg as abullet proof balance sheet , all i would say is the Fevertree Drinks (LON:FEVR) gets an A++ from me - lets hope rthe cash doesnt get stolen anytime soon :)
Note they have a very effective plan of outsourcing production which is one less headache to worry about (other than ensuring outsoucers do their job)
Basic earnings per share are 50p - down on previous year - very dissapointing and many will baulk at the something close to 30 * pe.
i for one am happy to hold due to non UK growth prospects , strong balance sheet and good quality brand that would be very attractive potentially to some of the big boys or allow them to expand product range to increase profits.
Ref 2020 earnings - i think are irrelevant in the scheme of things due to covid disrpution - safe to say they should still make decent profit this year whatever covid throws at the buisness.
Why make things complicated, premium x growth tonic in a recession, selling to a decimated global bar and restaurant industry....on 30x .... 50p of earnings you hope....
Fevertree Drinks (LON:FEVR)
RDHOWARTH
Why make things complicated, premium x growth tonic in a recession, selling to a decimated global bar and restaurant industry....on 30x .... 50p of earnings you hope....
What's your evidence for saying they are x growth? - i am presuming they are not x growth (covid issues aside) - i guess time will tell whether this is the case or not.
selling to a decimated global bar and restaurant industry
personally i think when things are back to normal bars and restaurants will still be there or have suitable replacements - if aren't drinking out and about they can always drink their sorrows away at home.
I apologise I was under the impression the UK business had stopped growing and was following the path of traditional drink fads that have come before it....
Fevertree Drinks (LON:FEVR)
I apologise I was under the impression the UK business had stopped growing and was following the path of traditional drink fads that have come before it....
No apologies needed and you might be correct in the assumption that uk growth may have peaked - you may also be correct that that the gin craze is a bit of a fad (how long has schweppes brand been earnings its buck though? fad or not) - however Fevertree do have a very decent record of overseas growth in many countries around the world - so to ignore the ROW growth that is now (2020 expectations) the majority of their sales seems to be missing the bigger picture IMHO. Here are the growth stats that paint a picture that is anything over than ex growth (ignoring covid) as a whole.
and rated accordingly.... will these numbers continue? Europe has got to be worry.
I assume that the numbers next quarter and beyond will be dire - restaurants and bars will account for a huge amount of sales although its easy to argue people will drink them at home. When we return to a more normal world though there is no reason why they wont penetrate more markets
Fevertree Drinks (LON:FEVR)
I assume that the numbers next quarter and beyond will be dire - restaurants and bars will account for a huge amount of sales although its easy to argue people will drink them at home. When we return to a more normal world though there is no reason why they wont penetrate more markets
I would agree - its a bit of a double whammy as well as they were doing reasonably well with overseas expansion - i am guessing the covid issue will completely stop that expansion of customer base in its tracks this year. Trade sales make up approx 50% of sales - so i am defaulting to profits probably being half 2019 at very best. Basically a complete writeoff year as far as the business plan is concerned. The only good news relatively speaking is that they have the balance sheet amd slimline buisness model to tough it out without that really being a problem.
Why make things complicated, premium x growth tonic in a recession, selling to a decimated global bar and restaurant industry....on 30x .... 50p of earnings you hope....
And on the plus side you have very shrewd long term focused investors such as Nick Train and Terry Smith filling their boots... Let's not pretend there are no positives. I managed to buy four cases of Fevertree last week as our stock had reached crisis levels and they were sold out in all the supermarkets earlier during lockdown. Some people worry about running out of bog roll, in our house it's tonic water :-)
BTW Another interesting episode of More or Less on Radio 4 this morning that's worth listening to.
All the best, Si
Paul, Please will you take a quick look at the adjustments in the figures for Ab Dynamics (LON:ABDP) in today's half-year report? They have reduced the operating profit from £8.6m to £3.6m which suggests overly aggressive profit reporting historically. Do you think today's fall in share price is reasonable, not enough or overdone?
this is from the financial review section
"Adjustments totalled £5.0m (2019: £0.1m) of which £1.8m related to amortisation of acquired intangible assets, £0.6m to non-cash costs in relation to acquisitions, including staff retention payments, £0.5m to share based payments and £0.2m to restructuring costs. A further £1.9m related to a write down of inventory. Following a detailed review of stock levels and usage, a number of items previously included in the carrying value have been written off and the system of accounting for inventory has been updated to better reflect the Group's current operations. "
Which all seems reasonable at face value. Although stock on balance sheet is ballooning ( I am thinking TED baker scenario here..)
With Ab Dynamics (LON:ABDP) growing rapidly in recent years, you have to consider its inventory relative to revenue; there is little to be gained form looking at it in isolation.
Apart from a spike up to 45.0% in 2018 H1, inventory / revenue has stayed in the range 30.5% to 37.4% for every half year period from 2016 H2 to 2020 H1. The latest figure is the lowest figure in that range. It would have been towards the top of the range (36%) without the write-off.
Overall, it looks like a problem fixed to me, certainly not a Ted Baker scenario.
that is super. thank you! EC
Hi Tic Tac Toe and Effortless Cool. Here is the chart for |AB Dynamics stock to turnover. Sorry its. bit crunched up - blue line is Stock and WIP % of Turnover, Black line Trade debtors to Turnover and Red Line Trade Creditors to Turnover. Hope it helps.
Richard
@tic_tac_toe Do you know what the amortisation of intangibles relates to? It's up a fair bit from the previous year.
FREng,
It relates to the two acquisitions that Ab Dynamics (LON:ABDP) made in 2019.
£1.9m inventory impairment is 17% of the inventory held as of August 2019. Seems like a lot to me - I think they should have given a more detailed explanation.
For me the oversized gap between statutory and adjusted profit is a red flag.
It would be good to understand why £1.8m is being written off the value of acquisitions - especially if this relates to the two recent acquisitions and even more so given the additional £0.6m related retention costs. If they can't justify the value on the balance sheet it suggests they've overpaid.
Share based payments and inventory are core costs of doing business. At best the inventory write off suggests over statement of prior year profits.
The ERP roll out will take up time and resources and the admin issues that drove the inventory and receivables problems suggest to me some internal challenges that need to be addressed, alongside the integration of two important acquisitions.
I've sold my holding as a result of these disappointing results.
Cuddlesticks,
£1.8m is not being written off the value of the acquisitions, it is being amortised according to normal accounting practice. There will be similar amounts amortised each half year for some time to come.
Ab Dynamics (LON:ABDP) may or may not have overpaid for the acquisitions; that will become apparent in due course through their impact on the P&L and operating profits and, particularly, should they ever write off any of the associated goodwill. However, you should be clear that the amortisation expense gives you no indication at all as to whether Ab Dynamics (LON:ABDP) have overpaid or underpaid.
I agree that the inventory write-off effectively means that prior years' profits were overstated. Had the inventory been valued properly previously, the write-off would not have been exceptional, so it is questionable to call it exceptional now, except to the extent that it not expected to be repeated in future.
I disagree that the share-based payment charge should not be added back for adjusting earnings. It is quite clear to me that it should be. It is not a cash cost but a fair value accounting adjustment of the cost to shareholders of the employee options. Because it is a fictional expense, you will see that it is subtracted from the income statement but added back in the retained earnings so it has no balance sheet impact at all. The proper way to account for the cost of employee options in valuing a share is to dilute the earnings calculation to reflect in-the-money options and increase the cash adjustment to reflect any money received by the business as and when those options are exercised. That approach reflects the economic reality of the transaction.
Morning Paul, any commentary on the Boohoo (LON:BOO) and Fevertree Drinks (LON:FEVR) results would be appreciated :)
Any chance of a gander on Xlmedia (LON:XLM) Paul you called it right last year or so would be interested in your thoughts as to whether you think it may survive or not without big dilution in the future.
re Boohoo (LON:BOO), I am interpreting their outlook statement that they were still growing in mid march, albeit at a lower rate, and that the growth has since picked up! Given the dramatic loss of revenue elsewhere in the industry that seems a great result.
Are others interpreting this similarly? I suppose the growth could have been (still be) negative, but this seems like it would be a spin too far...
A little bit vague for my liking. It arguable that they are just saying sales have improved March to April and are still negative.
just seen new research note from Zeus that confirms:
"Whilst YTD trading is described as mixed, we are encouraged by confirmation that the Group remains in positive growth YOY."
(LON:BOO) Outlook does seem a bit vague, although, maybe a crystal ball would be required in the current climate. Not seen any mention of furloughing thier staff (which I believe they have done - not sure on numbers) and will also be interesting to see how agile their supply chain is with potential shift in demand (increase in loungeware, sports / athleasure - decrease holiday clothes etc etc).
I've bought into them today. Took their results along similar lines. Great business model and management and shares somewhat discounted. Think they'll come out the other side in an excellent position.
I thought "performance has improved in more recent weeks and we are now seeing improved year-on-year growth of group sales during April." was ambiguous at first but then took it to mean April growth was even better than the pre-covid rate.
But now I'm not sure. It could mean improved from March.
Nothing on Research Tree yet to help.
I just heard confirmation on the conference call that it was positive (from Catto).
Also extremely interesting to hear that some Karen Millen coats are retailing at £1k.
My morning smallcap tweet: Cheers for boohoo
Wynnstay Properties (LON:WSP) Biome Technologies (LON:BIOM) Ebiquity (LON:EBQ) Boohoo (LON:BOO) Ab Dynamics (LON:ABDP) Moss Bros (LON:MOSB) Intelligent Ultrasound (LON:MED) Avacta (LON:AVCT) Batm Advanced Communications (LON:BVC)
Wynnstay Properties (WSP) value of freeholds down 3.4%. Co has received 70% of the total rental income due for Q1. Considering tenant rent holidays.
Biome Technologies (BIOM) Q1 in line with rev £1.3m (£2.1m) due to weak RF division demand (as reported). Limited covid impact. Net cash £1.8m.
Ebiquity (EBQ) covid affecting clients' businesses and their service requirement. Passing div.
boohoo (BOO) FY rev up 44%. Since the middle of March, trading has been mixed...initially with a marked decrease in year-on-year growth. Performance has improved in more recent weeks and we are now seeing *improved* year-on-year growth of group sales during April. Co has sufficient financial headroom with £241m net cash. I was short. Phew!
AB Dynamics (ABDP) H1 rev up 35% but only 11% U/L. Adj EPS 31.2p up 10%. H2 covid impact uncertain, both for demand and supply chain. No material reduction in order intake but seen a deferment of some larger orders. Passing div. No guidance.
Moss Bros (MOSB) offeror applies to Takeover Panel to pull bid. Co will oppose.
Intelligent Ultrasound (MED) case study of critical care simulation based training sessions using BodyWorks Point-of-Care Ultrasound Simulator with the newly installed COVID-19 lung module. A medic said "Having these COVID-19 specific cases available on the BodyWorks Eve ultrasound simulator in the early days of the pandemic has had a significant effect on our ability to quickly train clinicians on lung ultrasound in order to provide better patient care."
Avacta (AVCT) well ahead of schedule on developing an Affimer-based rapid test for COVID infection.
Also BATM Advanced Communications (BVC) wins $31m order to produce ventilators.
Welcome back Paul, just in time for the Boohoo (LON:BOO) results