Small Cap Value Report (Wed 22 Mar 2023) - SDRY, BOOT, HSW, FEVR, JDG, MPAC, BMS, ANP, BIRD, TEG, PDG, BYIT, NAH

Good morning from Paul & Graham.
Pretty much a clean sweep today, with 13 companies covered. That leaves us clear to focus on some backlog items from earlier this week in tomorrow's report. Sorry for the delays, but as you know, we can't cover everything. So today's report is now finished.
We're going to attempt to catch up today, with a few missed items from yesterday, but obviously we can't cover everything, especially if it's just trading in line with expectations (hence not price sensitive, so our previous opinion would usually be retained).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
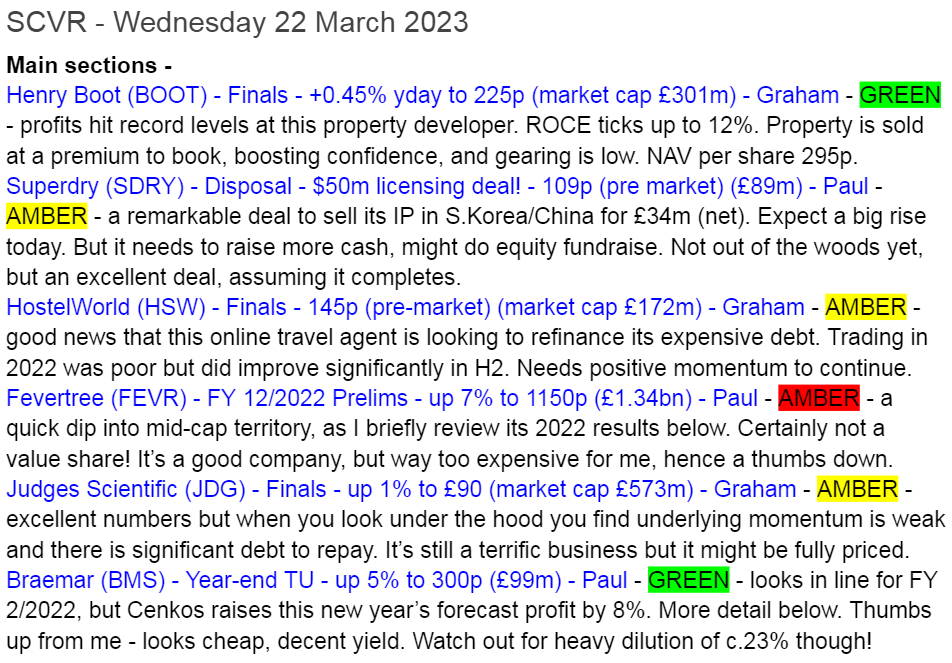
Here are our quick comments (i.e. no sections in the main report below), and what's left on the to do list -
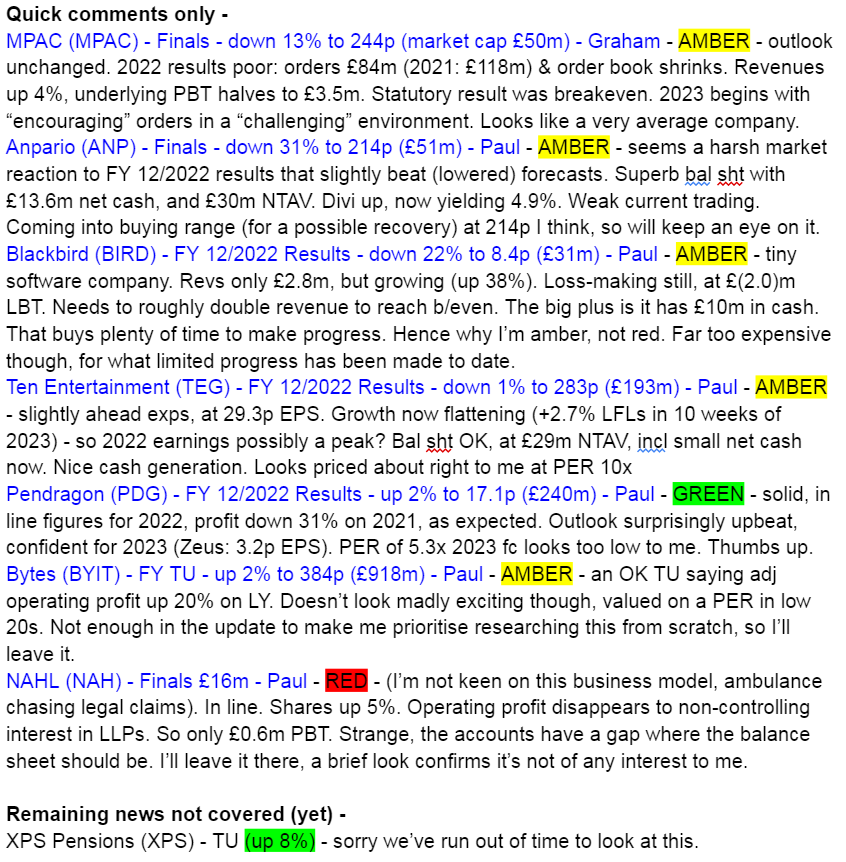
.
Paul’s Section:
Superdry (LON:SDRY)
108p (pre-market)
Market cap £89m
I’m rushing to get this section out before 08:00, as it looks significantly price sensitive - I suspect this share will open a good bit higher. Although it’s one of those RNSs where you have to read to the end, to get the full (good, but not quite so exciting as it initially looks!) story.
An upfront fee of $50m receivable by Superdry has been signed with a South Korean based company called Cowell Fashion Company Ltd, for the IP rights over the Superdry brand, in certain countries in the Asia Pacific (APAC) region. Cowell is listed on the S. Korean stock exchange, so we should be able to look up its finances. It is an established business which licences brands, and manufactures products.
The Agreement comprises the assignment of all of Superdry’s IP assets in the APAC region, but excludes India, Bangladesh, Pakistan, Sri Lanka, Australia and New Zealand where Superdry will retain its IP rights. Superdry will also retain all its IP rights outside of the APAC region.
The good bits - That’s a remarkable deal! Definitely pulling a gigantic rabbit out of the hat, for a business that is clearly struggling, despite the strenuous attempts of management to cover up that reality, in permanently upbeat presentations. I think this deal validates the value in the SDRY brand.
What is even better, is that it’s not as if SDRY is selling off the family silver. It is only foregoing £7.4m revenue, and £2.5m profit contribution (before central costs allocated) in this disposal. SDRY had previously attempted to expand into China through a partner, but abandoned it in 2020 after suffering “material losses”. So it makes a lot more sense to licence the brand to Cowell (for a substantial up-front fee, NB not yet received).
The bad bits - the net receivable amount is considerably lower, at £34m (after tax and costs).
Also, this is not going to be enough, and SDRY tells us it needs to raise more cash, which suggests to me that it’s probably trading badly still, and might breach banking covenants possibly? (why else would it need to potentially raise more equity?) -
The net proceeds from the Sale will be used to increase the strength of the Company’s balance sheet, boost liquidity, and fund its ongoing working capital requirements, including the implementation of a significant cost reduction programme. The Company is also considering additional steps to further strengthen its balance sheet in connection with its turnaround programme, which is being delivered in a challenging market, which could include a potential equity issue.
I should also point out that Cowell only has a market cap of about £290m, so paying a $50m cash up-front fee seems unusually large for a company of that relatively modest size. I'd want to see the cash actually in SDRY's bank account, before assuming this deal is a certainty.
My opinion - this is clearly a fantastic deal for SDRY, assuming that nothing goes wrong - remember the £34m net proceeds have not actually been received yet, and there are conditions to be met (shareholder vote, and lender agreement - but these should both be a formality. Also an escrow agreement has not yet been finalised).
The spanner in the works is that SDRY today says it could do an equity raise. The danger for private investors, is that today’s update could cause a large spike up in share price, followed quickly by a discounted placing to raise the additional cash the company has said it needs.
Recent news was that SDRY had called in Interpath Advisory to help it restructure & reduce costs. Again, suggesting a distressed situation.
Raising more cash doesn’t solve the problem of poor trading, which is SDRY’s fundamental issue. The last update on 27 Jan 2023 showed stabilised trading in the stores, but a collapse in wholesale orders. We’ve not heard anything since, so I’m assuming nothing has improved much, otherwise the company would have been shouting about it in today’s update.
Hence I suspect a big jump in share price today, which could provide a nice exit point for nervous holders, if it really goes bananas. SDRY seems to attract over-excitable punters, probably because the CEO/Founder is permanently super-bullish, and we’ve seen huge spikes up in share price before here (which tend not to stick). So today could be a really exciting day for holders.
But the company is not out of the woods yet, and we’ll have to see what terms an equity raise happens on. So enjoy the surge today, but keep expectations grounded, as this deal hasn’t fixed the underlying problem of poor trading. It’s just made it a lot less likely that the company would go bust if poor trading continues.
Each year that the company survives also means more onerous leases expire. Perhaps the long-term solution is to be a wholesale & brand licensing business, with just a handful of flagship stores?
Fevertree Drinks (LON:FEVR)
1150p (up 7% at 08:31)
Market cap £1.34bn
Preliminary Results to 31 Dec 2022
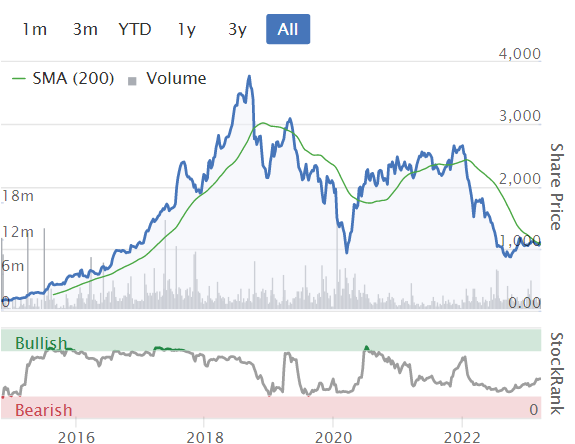
I’m happy to have a quick dip into mid-cap territory occasionally, if a company looks interesting. This premium branded non-alcoholic drinks (mixers, eg. tonic water) company has always intrigued me, and reached a sky high valuation in its heyday peaking at c.3775p in late 2018. Is it a bargain at less than a third of that price now?
In a word, no.
FY 12/2022 results key points -
Revenue £344m - split roughly evenly between 3 main markets of UK, US, and Europe.
Adj EBITDA fell from £63.0m in 2021, to £39.7m in 2022, due to cost increases - so a lower gross margin, and increased admin exps.
Profit before tax was £31m in 2022 - not much for a market cap of £1.34bn.
Good balance sheet, with NTAV of £186m, including £95m net cash (down sharply, as a 42.9 special divi was paid (May 2022) from surplus cash, not from cash generation in the year).
Guidance for FY 12/2023: revenues £390-405m, EBITDA £36-42m (so flat on 2022).
Valuation - it did 21.3p EPS in FY 12/2022, giving a PER of 54x so clearly investors are assuming a big increase in future profits.
Cashflow was poor in 2022, with operating cashflow down, and that was mainly sucked into increased inventories.
My opinion - I’ve seen enough to be clear that this is not a value share! Is it a GARP (growth at reasonable price) share though? Possibly. If we assume that it can pass on cost increases to customers (which it says is planned), and continue growing the huge US market, and achieve a dominant position there, as it claims to have done in the UK, then this share might be a long-term winner. The largest 2 shareholders are Lindsell Train, and Fundsmith, which (certainly in Fundsmith case), my perception is they focus more on long-term leading brands, and aren't shy about paying top dollar for the best companies, then sitting for the long-term for the companies to grow into the valuations.
Growth in the US was good in 2022, up 23% to £96m revenues.
Drinks brands that are seen as market leaders can have very big values.
Overall, I think the current market prices in too much future upside for me. FEVR has made amazing profit margins in the past, but then input cost inflation, and higher freight costs (since abated though) hit profits. So investors really have to hope that it beats existing, flat, forecasts for 2023 profitability. Why would you pay a PER of nearly 60x when there’s so much uncertainty? Thumbs down from me, purely on excessive valuation short-term. Long-term, it could be a big winner. I’ll keep an eye on it. Growth companies are never cheap though are they!?
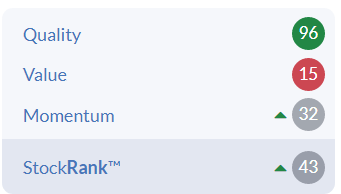
The StockRank exactly mirrors my thoughts - great quality, but poor value -
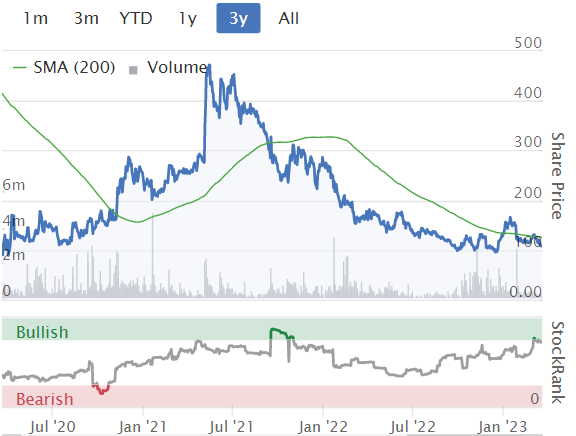
The long-term chart since it listed is remarkable! Timing was everything here -
Braemar (LON:BMS)
300p (up 5% at 10:04)
Market cap £99m
Trading update - a record year for Braemar
It’s certainly eye-catching when companies put something good in the actual title of the announcement! I expect we’ll see more of this happening as PRs latch onto the idea.
Braemar Plc (LSE: BMS), a provider of expert investment, chartering, and risk management advice to the shipping and energy markets, today announces an update on trading for the year ended 28 February 2023.
I think I’m right in saying there are 2 listed shipping services companies, a small one (Braemar) and a bigger one Clarkson. Both have been trading well, the sector seems buoyant.
I last looked at Clarkson here on 6 Mar 2023, and took a neutral view - good performance, but the deal-breaker for me is that over half the massive cash pile is apparently ear-marked for staff bonuses.
I last looked at Braemar here on 14 Feb 2023, complaining that its trading update was annoyingly vague, but positive in tone. Concluding that Braemar looked a good company, at a reasonable price.
Let’s hope we get some clearer guidance in today’s year end update -
Revenue at least £150m (up 48%+)
Underlying operating profit of £20m+ (doubled from LY) - very impressive indeed! Although this looks in line with expectations, looking back to a Cenkos note from Nov 2022.
Divis - 4p interim, 8p final, so 12p total = a decent yield of 4.0%, and more importantly I think this looks comfortably affordable (more than twice covered by earnings), and given the Feb 2023 net cash position of £6.9m (reversed from net debt of £9.3m a year earlier).
Balance sheet - just quickly checking the last reported one (Aug 2022), and it’s adequate - not strong. With NTAV of only about £2m. So depending on timing of monies in & out, I reckon it could be using its overdraft intermittently still. Remember that a year end net cash/debt figure is only a one day snapshot, often massaged into looking good.
Outlook -
Trading in the first few weeks of the financial year has started well and the board looks forward to the rest of the year with confidence.
Share options - this looks to be a problem, because in H1 there was a huge shortfall (far more than usual of say 5-10% for most companies) of over 23% between diluted EPS and basic EPS. So this needs to be checked out for anyone buying or holding this share, to make sure you’re comfortable with what looks like wildly excessive generosity to employees (same as Clarkson's huge bonuses).
My opinion - I need to see the full numbers in due course to give a more detailed view on Braemar.
It’s clearly had an excellent year in FY 2/2023, helped to some extent by dollar strength. So we need to understand better how much of the big profit growth is sustainable, and how much is one-off in nature? That’s the key area to research thoroughly.
As the numbers stand, it looks very good value. Cenkos (many thanks) is forecasting 36.1p fully diluted (essential to use the diluted number) EPS for this new year FY 2/2024, which at 300p puts Braemar on a PER of 8.3x
Together with a forecast 13p divi, that’s a yield of 4.3%
So it looks a decent value/GARP share, providing these strong numbers are sustainable, and not just a bonanza year due to external factors. I don’t have a view on that, but am giving a thumbs up for the numbers as they stand.
Graham’s Section:
Henry Boot (LON:BOOT)
Share price: 225p (+0.45%)
Market cap: £301m
Let's check in on the full-year results for 2022 from this property developer.
Revenue +48% to £341m, driven by the disposal of thousands of plots and the completion of urban development works.
Underlying profit nearly doubles to £56m
PBT +30% to £45.6m.
PBT was impacted by over £10m of negative revaluations caused by falling commercial property values.
ROCE - the company calculates its own ROCE as 12%, within its 10-15% target range.
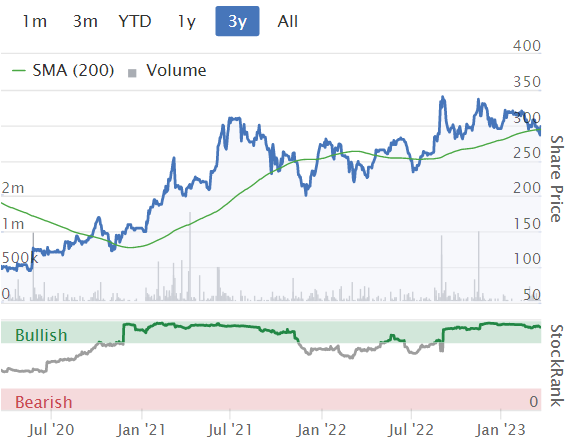
NAV per share - increases by 5% if you exclude gains on its pension scheme. Including those pension gains, NAV per share increased by 10.5% to 295p. The share price is at an interesting discount to this level.
Net debt - increases to £48.6m, “following strategic investments made during the year”.
The balance sheet shows £578m of total assets (almost entirely tangible) offset by £184m of total liabilities. Given the large surplus of assets over liabilities, it’s hard for me to imagine that BOOT’s net debt position should be a concern. The company says that its current level of gearing is at 12%, “at the bottom of our 10-20% target range”.
Speaking of the balance sheet, Boot also reports the following news within its “Property Investment and Development” division:
Well timed sales within the investment portfolio of £29.6m, at an average 17% premium to the last reported book value, contributed to total return outperformance of -1.5% versus CBRE Index of -9.1%
We do have to be careful not to get too excited about this, because the sales which took place might not be representative of the group’s portfolio as a whole. Indeed, these sales that took place at a 17% premium to book value are likely to represent a best-case scenario in terms of the value that can be realised. But I still think it augurs well for the value of the balance sheet in general, if these sorts of premiums can be achieved.
Land bank - is 96,000 plots, up from 93,000. Unfortunately, only 9,000 plots have planning permission. The CEO has this to say on the subject:
I am increasingly convinced that the UK planning system is in need of urgent reform. The delays and complexities can no longer be blamed on COVID. Whilst we would derive greatest satisfaction from a more efficient system on account of the benefits this would bring local communities, the challenges of the current situation mean that the land we successfully promote and the expertise we bring in navigating the planning system remain increasingly in demand.
Outlook
Profits in 2023 are set to be “more subdued” than 2022, due to the economic slowdown, but BOOT is already seeing signs of recovery.
The company’s remarks on the economic outlook should be of interest to investors generally, so I’ll quote them extensively:
Whilst the immediate outlook is uncertain, a number of leading indicators suggest that the economic slowdown will not be as severe as forecasts in the final quarter of last year predicted. It looks increasingly like interest rates are close to the so called 'pivot', we are seeing early signs that supply restrictions are lifting and with that some prospect of cost pressures easing.
There are early signs that our markets are improving. Occupier demand for I&L [GN note: Industrial and Logistics] has remained resilient, and whilst yields moved out quickly during the second half of 2022, there are investors already looking to buy, tempted by the strong fundamentals of the market.
Likewise, whilst data is available only for the first two months, housebuilders generally and SBH [GN note: this is Stonebridge Homes, a joint venture by BOOT] specifically, have seen a partial recovery in home buyer interest this year from the lows experienced in the final quarter of 2022. The march of the BtR sector, both in terms of customer and investor demand, continues.
My view
I’ve seen a lot to like here. We have a share price discount to NAV firstly, which I’m always happy to see.
Then we’ve got the company reporting a decent ROCE of 12%, and management who are keen to keep it at a respectable level. BOOT’s StockReport suggests that their ROCE is more often than not at a reasonable level.
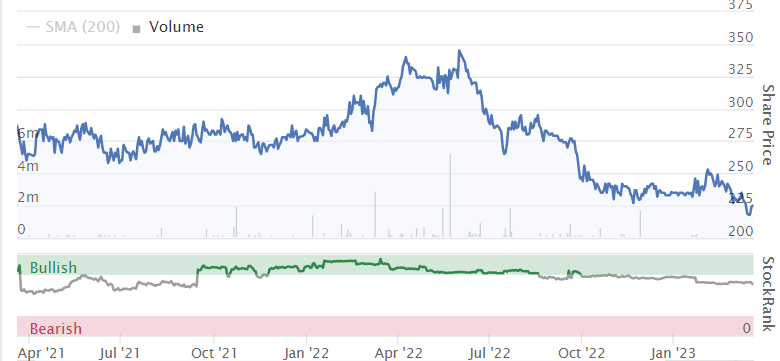
Also from the StockReport, I note that BOOT passes two bullish screens:
Finally, I like what I saw on the balance sheet with a huge surplus of assets over liabilities, so that I’m not concerned about the level of gearing.
I’ll give this company the thumbs up, thinking that it might be oversold due to economic worries. I can’t predict the economy, however, and it’s something that’s beyond BOOT’s control - in a severe recession, these shares could get cheaper still.
Hostelworld (LON:HSW)
Share price: 145p (pre-market)
Market cap £172m
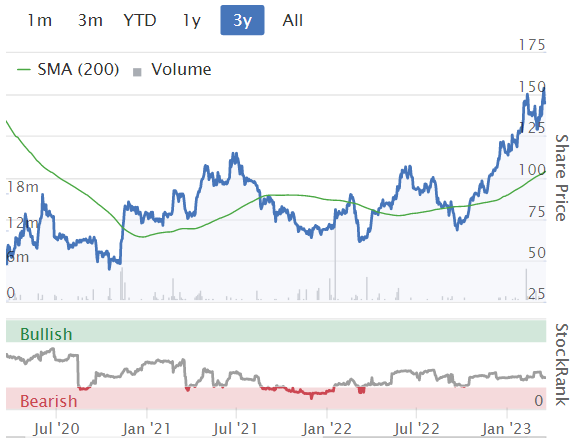
We looked at this online travel agent when it issued its full-year update in January. This morning sees the release of its full 2022 results.
Highlights:
Revenue €69.7m. Comparisons with 2021 are not relevant due to Covid impacts. Revenues from 2016-2020 were always in excess of €80m.
“Profitable adjusted EBITDA” - a good achievement for the year after a very poor H1, but the operating loss is still €13.6m.
Average booking value (ABV) is €14.90, up from €12.11 in 2021 due to “bed price inflation”. ABV hadn’t moved much for several years.
Balance sheet
I’ve been banging the drum about Hostelworld’s high-cost €30m loan. There is good news on that front this morning as we learn there is a refinance process underway:
The Group has borrowings of €31.1m (2021: €28.2m). In February 2021 the Group signed a €30m 5-year term loan facility with certain investment funds and accounts of HPS Investment Partners LLC (or subsidiaries or affiliates thereof). An amount of €28.8m, net of original issue discount, was drawn down on 23 February 2021. The facility bears interest at a margin of 9% per annum over EURIBOR. The Group will look to refinance the facility in 2023 to obtain lower margin interest rate costs.
This could help change my view on the stock, as I shuddered to think of the company paying millions of euros of interest while also generating an operating loss.
With a market cap of almost €200m equivalent, perhaps a small equity raise would help to fix the problem without diluting shareholder value too much?
Outlook
In 2023 we will continue to develop and progress the opportunities enabled by our social network strategy, while remaining committed to delivering high levels of operating performance and cost discipline. Hostelworld operates in a resilient and growing category with a loyal customer base that has a strong desire to travel and meet other people despite the uncertainties the economic cycle may present. We are encouraged by the trends we have seen since the start of the year and believe that the business is firmly on track to deliver the targets for FY 2023 presented at our Capital Markets Day in November 2022.
My view
I’m going to stay neutral on this stock for the time being.
I’m encouraged by the very positive trend of improved trading in H2 2022, and a refinancing of its overly expensive debt could cut the company’s interest bill significantly.
On the other hand, I’m still sceptical of the idea that the company is building a valuable social network - although I do think that it’s a nice bonus feature to help hostel travellers to meet each other online.
Finally, the financial results here have been poor for some time, albeit for reasons that were beyond the company’s control. Let’s see if the positive momentum can continue.
Judges Scientific (LON:JDG)
Share price: £90.00 (+1%)
Market cap: £573m
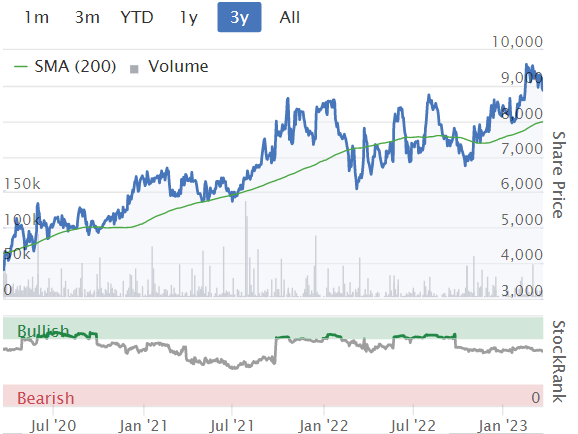
We have frequently covered this highly successful acquirer of companies in the scientific instruments sector. This morning it published full-year results for 2022.
Highlights:
Revenue +24% to £113m
Adjusted operating profit +60% to £30m
Statutory operating profit +17% to £18m
The very large acquisition, Geotek (£80m), “significantly enhanced full year earnings and achieved the maximum earn-out”.
The company finished the year with net debt (excluding leases) of £52m.
As I remarked at the time of the full-year update, there are signs of a slight loss of underlying momentum in the sense that organic order intake increased by only 0.5% year-on-year. A large part of the blame seemed to relate to Covid-related problems in China.
So I’m looking for signs of improvement on this front. The company says the following with respect to its outlook:
As we look ahead, the macro environment remains uncertain, with differing factors impacting our business both positively and negatively. Whilst we are encouraged that the market in China is more stable as Covid restrictions are eased and we continue to see Sterling benefit UK exporters, we are cognisant of continued geopolitical uncertainty and supply chain challenges, alongside higher levels of inflation and interest rates. In addition, the increase in UK headline corporation tax from 19% to 25% from April 2023 will affect EPS going forwards…
Our Group started the year with a record Organic order book and has since benefitted from solid growth in Organic intake versus the first two months of 2022.
My view
The company admits that the post-Covid recovery is “still a work in progress”, and I agree.
While operating profit bounced up to £18m, and cash from operations improved from £20m to £24m, this was done at a very significant cost that leaves the company with an unusually high debt load.
Return on invested capital has also reduced due to the Geotek acquisition.
However, I calculate the company’s Return on Equity (using unadjusted figures) as 26%, which is still excellent. There remain signs of high quality at Judges:
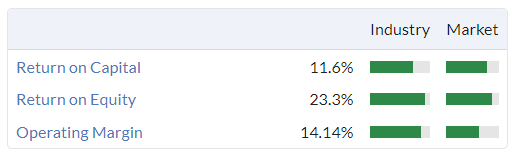
However, the ValueRank is only 4, and I also believe that the valuation is currently rather stretched. I was already nervous about it when the market cap was c. £500m (see my previous comments). As it approaches £600m, I’m forced to take a neutral stance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Like others, would like a SCS update please
Regards
Ray
It's on the list, please bear with me, I want to look at it too!!
My take on results from Ten Entertainment (LON:TEG) is that they are quite good. Adjusted EPS of 29.3p beats forecast of 27.8p. And :
· Six major refurbishments and five bowling upgrades creating best-in-class bowling centres ( Refurbs pay for themselves relatively quickly)
· World's first bowling loyalty and reward app launched
· Two new centres opened in 2022 with one more opened in February 2023. Expect to open four in 2023
The above does not correspond to them being ex growth. So I am surprised at the market reaction.
They are not ex growth. Like for like was always going to moderate against strong comparatives but remember this is still a fragmented industry so there is a continued roll out of new venues ongoing to increase revenues and profits.
EPS should be 34p this year so it is on a 12m fwd PE of 8 (not 10 that Paul alludes to)
I suspect it will get bought out if the share price doesn't increase soonish. We are in a slightly bizarre market whereby PE will pay a lot more than the public market, which is historically unusual. Im afraid I just don't think the UK market has any liquidity anymore unfortunately.
Hi
My Google chart just presented Somero Enterprises (LON:SOM) down over -29%. Is this a fat finger incident?
EDIT: Its back up again .... a fat finger incident !!!!!!!
Regards
Howard
Somero Enterprises (LON:SOM) There is a modified trade 13:04 370p so yes a corrected trade from 270p.
What would happen here if a SL had been hit on an a/c - either mainstream trading or a SB a/c?
£BMS re Share Options
Paul dont know if this is of interest or relevant taken from 222 Annual report.
To better align shareholder and employee interests and support the growth agenda, the board concluded that it should reduce the overall amount of deferred equity issued annually as part of employee remuneration arrangements. Under the previous scheme, deferred shares were awarded and issued to employed recipients over a three-year vesting period and generally settled by shares purchased in the market. Whilst this scheme will remain unchanged, the amount paid in such deferred shares will be halved with an increase in cash bonuses paid of the same amount for the current and future years. Future years will involve claw back arrangements on the additional cash payments to encourage employees to remain in Braemar’s employment. During the year, the ESOP acquired 2.7m shares. This reduced the Company’s exposure, and it ensures that all historic liabilities are now covered.
ESOP Trust During the previous year the Company requested that SG Kleinwort Hambros Trust Company (CI) Ltd, as Trustee of the Company’s ESOP Trust, purchase shares in Braemar Shipping Services Plc. During the year a total of 2,740,164 shares in the Company were purchased by the Trustee and 596,398 shares were released; as a result, at 28 February 2022, the ESOP held 2,669,603 shares (2021: 525,837 shares). The total cash outflow as a result of these share purchases was £6.3m (2021: £0.9m). Subsequent to the year end the ESOP purchased a further 1,670,000 shares. As at 10 August 2022 the ESOP held 4,339,603 shares and now contains sufficient shares as are expected to be needed to cover all current share awards as described in Notes 28 and 29 of the Financial Statements.
Seeing Machines (LON:SEE) share price grinding down but interestingly directors buying more and more stock. FD is relatively new and has bought millions as has one of the non execs. They are clearly very confident.
I looked at their director buying history and despite their being a lot of purchases, one of the directors SOLD £4,000,000 of shares at the end of 2022. He has bought back in since, but nowhere near £4M of shares. The product is interesting and could be a 'must fit', like airbags and ABS brakes, for cars of the future. One to watch.
No he didn't - this is a misconception. The NED in question is also involved in Lombardier Asset Mgmt. They went through a fund reorganisation (between the US and UK) and there was a part transfer of shareholdings to the UK entity with the rest in the US being sold as the UK fund had a full holding. The reason this was listed as a sale by the director was because he happened to be a connected person.
At a personal level he has been buying not selling.
I stand corrected and appreciate your insight. Many thanks.
….or could be an expected 'free' product like the camera on your phone that detects smiles, red eye, blinking and even identifies people! In fact, it’s not too big a stretch to imagine a cheap/free phone app that watches for sleepiness whilst driving. Yes, you can see this being a product but just not one of much value.
thats utterly ridiculous. Car safety standards now insist on this type of product being fitted globally and there are really only two market players. Seeing Machines (LON:SEE) will ultimately take 50% of this market. The car manufacturers have to fit driver monitoring products and the easiest place to fit them is in the rear view mirror. You have to have very high standards to get built into a new vehicle model and the lead time for adoption is measured in years to a decade, not just some cheap/free iPhone app. Clearly you haven't even begun to research this market.
Golly that's an angry post. Basic audible alarms already exist for 50 quid. I'm not saying there isn't a market, I'm saying the market for a camera and some software that monitors eyes is unlikely to be lucrative long term. Hopefully I'm wrong and a complete idiot!
"Car safety standards now insist on this type of product being fitted globally and there are really only two market players. Seeing Machines (LON:SEE) will ultimately take 50% of this market"
Interesting. How can this be stated so confidently?
"the lead time for adoption is measured in years to a decade,"
The auto industry can be very slow to adopt. Not sure investors would like to be reminded that it might be 10 years though.
No position.
look at the European car manufacturer regulations and NCAP safety for a start.
The lead for a new competitor is a decade. Seeing Machines (LON:SEE) are already there with hundreds of thousands of vehicles starting to move off the production line. That's why it is tough for new entrants. The company is winning circa 70% of new RFPs globally by volume.
You can't just do this as iain1234 says. It is way more complicated than that and regulators wouldn't accept it and car manufacturers wouldn't put it in their vehicles. Thats why that post is nonsense.
Thank you for the Braemar observations Paul, I got a bit over excited at actually seeing one of ours going up! I'm hoping you or Graham gets chance to look at Pendragon's results, note their comment about trading for the first two months this year being better than last year, I'm hoping there's a read across to Vertu (we hold).
Re Judges Scientific (LON:JDG) - It's no use measuring this one against value shares. The relevant comparisons are (typically) US life science tools companies on PERs in the mid 20s. I made this point a year or so ago when the forum complained about valuation and the shares were in the 60s, not 90s. In the UK the relevant comparison is with the more expensive Halma and it's worth noting that succession from the very capable hands of David Cicurel is being worked out with the appointment of Mark Lavelle and Tim Prestidge from, guess where, Halma*, where both became well-versed in the buy and build process so impressively perfected there. If you wish you had bought Halma when the market cap was only £500m then perhaps this is your opportunity.
For balance, I would observe that the Geotek acquisition may just have been well timed by the previous owners, selling at the top of an exceptional period for the oil and gas industry. Although the price paid was not high in terms of multiple, it's possible that weaker performance in the future makes that multiple much higher in retrospect. Nevertheless, I'm keeping faith in the management for now.
*International investors might want to note that the US equivalent of Halma is Idex (NYSE:IEX) in which I have had a sizeable position for several years and which was recently added to the Smithson fund of Terry Smith fame. Very impressive business.
Blackbird (LON:BIRD) makes me laugh. Delighted with 38% rev growth. (let's not mention 50% cost growth!)
Remember this isn't a early stage tech company. It has been enriching the directors for decades!
The tech on Blackbird (LON:BIRD) is world class in its field but management have consistently failed to deliver meaningful revenues despite many contracts. They have bought a lot of shares themselves at much higher prices and clearly believe it will take off....but when? Its another case of great tech, very poor commercialisation
They claimed they were years ahead of the market with their tech - many years ago. The business market doesn't seem to agree. I just don't think they solve a real problem, or they don 't solve it in a practical way. They only "solve" the problem of getting a salary and bonuses for the staff and directors.
If they have had world leading tech for 20 years and they are still unable to demonstrate benefits to buyers - one has to wonder why so many in the industry just don't see it, would love to see that feedback!
It is incredible that they have managed to persuade investors to fund their lifestyles and pensions for so long, without running out of cash. Got to have a bit of admiration for that.
I watched the investor presentation and it sounds like they recognise that they should have delivered more commercially and are trying to address that with recent senior hires. They were cagey on pipeline but made it clear that they wanted to reveal more but can't. It's only a small position for me, and typically one that has occupied my mind far more than it should, so I'm holding because I think they can realise the tech's potential.
They've always been cagey on financials - lots of "winning contracts with the top producers in ...." but it could be just £100 pm. for them to try it, who knows!
Hi Paul, do you think you'll have time to add your thoughts on MFX and SCS from yesterday? I appreciate you have a lot to do today as well. Thanks, Simon
What happened to SCS and STAFF?
Seem to have disappeared off the list...
I must admit I am left scratching my head as to Ten Entertainment (LON:TEG) valuation and seeming investor inertia towards it. Having survived the pandemic it has managed to keep the price of a bowling flat for the consumer (ie no inflation) whilst growing its revenues significantly and moving from a net debt to net cash position. Everyone knew the last year of 50% growth won't repeat but I was pleased to see like for like (against very strong comparators) is still up 2.7% in Q1.
so EPS for this year should be 33-35p. It has a strong net cash position which will presumably also build further. Strip out net cash and it is on a PE in the 7's !
They are second behind Hollywood Bowl (LON:BOWL) in the market size wise but the two of them are miles ahead of any other group but the former trades on 13* earnings versus Ten Entertainment (LON:TEG) now on just 8*. I am perplexed as to why it trades at a relative 50%+ discount. Surely 400p+ would be a fairer reflection of the business?
My sentiments exactly David!
Ten Entertainment (LON:TEG) and Hollywood Bowl (LON:BOWL) still have rising energy bills to come unlike us whos energy bills will fall in july.. Great 2 companies though, were results a one off and can they continue?
Actually Ten Entertainment (LON:TEG) is hedged until Sep 2024 so it doesn't have rising energy bills to come! Assuming energy costs have stabilised in the next year and a half then even at current rates revised energy costs would have minimal impact. Price trajectory though is normalising down.
I know O&G isn’t usually discussed here, but it might be worth taking a look at Arrow Exploration (LON:AXL) . They have just announced another successful well drill, adding another 750 bopd in the past three weeks. They’ll pay back in 2-3 months. They make approx $50 dollar net backs so adding $1.1m to the existing $2m of current monthly cash flows. They are still drilling and should be producing 5k bopd by the end of the year. That’s a run rate of approx $90m, all for a market cap of approx $40m. And that also ignores the $13m net cash they already have, fully funded drilling programme and some of the best management in the business that actually do what they say they’re going to do. In case it’s not obvious from my enthusiasm above, yes I do hold!
Arrow Exploration (LON:AXL) thanks for the intro. I think small miners/drillers eventually get bought out and see Canadian Canacol (MC £215m) hold 18% and work in Colombia. Presume "fully funded drill programme" means its upwards and onwards with no additional capital raises required.
On a macro level may be worth checking who their bankers are lol.
And perhaps wait for the two directors to take a bigger stake.
Will set alert for breakout at 20p.
Hi Pastybap this does look very interesting. Just working through the admission doc and I have noticed the following:
Ecopetrol’s Consent for the Tapir Interest Assignment
Samaria´s participating interest in the Tapir block and its ability to continue to manage operations and receive a 50% participation in revenues from the field derive from various private oil and gas agreements, and Samaria will not be a party to the Tapir contract until the interest is assigned by the relevant holder of record and approved by Ecopetrol in its sole discretion. There is a possibility that Ecopetrol could interpret the assignment of a private contractual interest as contrary to the assignment clause in the Tapir Association Contract.
Ecopetrol previously rejected the request for its consent to the assignment of Petrolco’s fifty per cent. (50%) participating interest and operatorship in the Tapir block to Samaria on the grounds that Samaria did not meet the technical and financial requirements established by it to qualify for the assignment which have not been made public by Ecopetrol. There is no guarantee that Samaria will be able to obtain Ecopetrol’s consent to the assignment.
Samaria being the following:
Samaria Llanos Exploration S.A., a Panamanian subsidiary of the Company conducting business in Colombia through its branch office, Samaria
That almost looks to me that at any point Ecopetrol could say unlucky you don't own 50% and it basically game over. I'm probably wrong as I haven't spent anywhere near enough time on this but thought you may have the answer.
Cheers
Luke
NAHL (LON:NAH) - Finals released this morning. I notice there's a note saying 'not keen on this one', but if you'd allow me to try to change your mind:
After years of investing through the P&L and in working capital, the group has begun to generate meaningful levels of free cash flow (£2.3m this year with £3m+ forecast for next year). Profits are still suppressed by investment, but earnings are expected to rise dramatically over the next couple of years (Allenby, house broker has them on 11p eps by 25 vs 36p share price now). Due to the nature of the group's businesses, these earnings are relatively predictable, as much of the work is done now for profits that are realised later.
Management have done an excellent job at navigating a difficult operating environment and finally the businesses seem to be firing on all cylinders. Yes, claims management has a bad rep, but NAH are the market leader, taking share, and one of the good guys. The second business in the group, Critical Care, earns £3m+ of operating profit and is itself worth far in excess of the entire EV of the group.
MassimoJ, those 2 words, 'finally' and seem' make me shake my head while saying nah like a cockney, when the company has treated the shareholder like part of the furniture and paid no dividends since May 2019. If I were fully invested in NAHL (LON:NAH) then I'd be visiting food banks but the directors see to it that they are doing alright.
I hold.
Good morning, results from Judges Scientific (LON:JDG) today. There is a webinar at 4pm this afternoon, register here.
And, full year 2022 results for Literacy Capital (LON:BOOK) an Investment Trust which IPO'd in June 2021, they will give us a presentation for the 9 months ended 31 December 2022 at 2pm today. Register here.
A bit more about them, they focus on opportunities to invest for the long-term in growing private businesses where a clear route to creating additional value can be seen. It also has a unique charitable objective to donate 0.9% of annual NAV to charities focused on improving literacy in UK children. £5.8 million has been donated or reserved for donation to charities since the trust's creation in 2017.
For those who tend to think that we are in a new bull market, there is some thought-provoking stuff by John Hussman in this commentary:
https://www.hussmanfunds.com/c...
Ricardo
Thanks will have a read - Hussman always interesting but he has been predicting a major bear market for the past decade...
Past century more likely
Re: John Hussman commentary on current & past banking crises
Man, that's a long read - I gave up in the end.
What I did read and understood I found compelling.
Skipping to the conclusion: S&P500 current valuation far too high to expect good long-term investment returns.
That's what I thought...
Thank you for this referral. I wonder how much read across there is for the UK market which is considered cheap at the moment. The US markets have seemed expensive to me for a long time and the prospect of a 58% slow collapse is certainly concerning. Perhaps the uk is around fair value and only looks cheap next to the US.
Interesting article Ricardow although a lot of information to digest and somewhat indepth for my understanding as a newbi investor, eventually scan read. If you took this article at face value then I doubt if anyone would invest in the markets at the present time and I suppose it all comes down to timing. I would also think it depends on if "you" are a glass half full or a glass have empty person in your investing approach. The one thing that I have taken from the article is that it would probably be advisable to take a cautious approach in the market at the present time as things continue to be volatile and one never knows what is round the corner. Article link much appreciated.
MPAC (LON:MPAC) - FY22 numbers and CEO appointment this morning - our new note with details is here: https://www.equitydevelopment....
Hello edmonda. MPAC (LON:MPAC) punished today even though predicted figures ahead of these results. Down a further 9%, 253p to buy. Not pretty.
Methinks edmonda Equity Link tends to be extra 'ambitious' in its forecasts for its 'customers'. Not always a good thing because it can affect your credibility. The near term future for MPAC (LON:MPAC) doesn't seem to be as bright as you are forecasting..
edmonda - can I ask what is your relation with Equity Development ?
Of course - all very transparent and no pseudonyms, thats my name and I run ED . Hence posting notes for public access when results are out / events happen etc.
Cheers
Hi, thanks for your reply. I have noticed a few posters that have an 'advisory' role here, and in general I find that this is good. A great example would be PiWorld, where it is very clear what Tamzin is about and the company presentations on her website are really great sources of information. There are others where the relationship is much less clear. As a novice investor, I am learning alot very quickly !! (as you can imagine in these choppy waters) - mostly to be extremely cynical about what I read / hear in any situation. I view the SCVR as a bit of a 'safe haven' where Paul and Graham do an excellent job of a transparent view on various companies (warts n all) - and I have no problem even when Pauls exuberence leads him up the garden path !!
There are also some posters on here that obviously have a great depth of experience (not only in investing) and have some pretty level headed points of view.
In the interest of transparency (as you point out), would it not be a good idea for Stockopedia to have two levels of subscription (I am not saying in price, but thats their business), where professional 'advisors' are clearly marked when they post ?
What do you think about this ? - just for you information, I didn't know that you ran ED - and I am sure that alot of other Stockopedia subscribers have not made this link.
Ask and you shall receive! It was a very long time ago that I/we created this account. I don't know who has Equity Development, but we're without the space!
Fair play to you, sir ! and thanks.
(and from personal experience...another suggestion I have for Stocko is that they are clear that the username chosen when signing up for the free trial is the one that you are likely to be stuck with for the next few years.... well live and learn I suppose.)
You can change this anytime, click on the icon at top right, next to the 'Bell button', on the drop down menu select 'edit profile'.
Da nada , and be careful with gender presumption !!
Yes, Andy could be a womans name, so my apologies. Imagine my surprise when looking on your website that I find Paul Hill is in your rogues gallery as well... dear me, what a web we weave.
"good idea for Stockopedia to have two levels of subscription" - Surely it is for you decide who adds value to your own approach and who doesn't regardless of whether they are professional whatever that means nowadays. I have met many people who would call themselves professional but add nothing to my process.
Hi Camtab,
Yes you are quite correct, and I think that taking anything on a bulletin board chat at anything more than face value is a recipe for disaster.
I would say however that if companies (as that is what we are talking about here) use chat rooms as a way of 'providing information', it would be in their interests as much as anyone else to do this as transparently as possible.
To be honest, I get irritated at the mountain of clickbait I am faced with with nearly every financial service that I try. Motley Fool's tired 'If I had 10k to invest now this is what I would do....' is a typical example. Yes I try to ignore it, and I have alot of other work to do, so a quick check on Stockopedia to update with news, and read over the chat with a coffee - great stuff. Today my annoyance got the better of me.... so sorry about that to all concerned. I have no axe to grind here - to my knowledge, I dont hold anything that ED have promoted / highlighted
On a more philosophical note, as Ben Hunt points out - if you are the the only one at the table in poker who doesn't know who the stooge is, then it is you. I wonder just how incestuous the UK small cap market is, and how much the prices are manipulated (liquidity is very small). I wonder also whether this is linked to how the likes of WANdisco (LON:WAND) happen - if everyone is in each others pocket, it is not surprising that transparency isn't at the top of the list.
Probably best to move on to mid - large caps, and the US market, what a shame for UK small companies trying to get a foot on the ladder - because that is what I would like to support (my own ESD criteria if you will).
As Robbie Burns said (no, the other one), what a parcel of rogues.
Chris
Andy Edmond is CEO and co-owner of Equity Development
Morning ! Is Alpha International (LON:ALPH) still small cap ? Can it be a read across to Argentex (LON:AGFX) ? Results look like a beat to me, even beating the increased forecast a while back...EPS coming out at either 70.1p or 86.8p depending which one you take...still beats the forecast 64.6p either way...
Another earnings beat today is Ten Entertainment (LON:TEG) , EPS coming in at 38.9p vs forecast 27.8p...giving a p/e of 7x using last nights 285p closing price ? Surely this can double ?
I hold both so quite pleased this morning...
Adjusted EPS is 29.3p vs forecast 27.8p
I know you have a back-log Paul but if you or Graham have time a comment on Braemar would be much appreciated. I was pleased to read their TU after yesterday's hammering of Luceco! We hold both. Braemar announces a record year with Op profit of 20m v 10m last year, Rev 150m v 101, cash of 6.9m against debt of 9.3m (after recent aquisition) and div up 33%.
Yep but only rises as much as the divi increase
Morning,
Outstanding results from Ten Entertainment (LON:TEG), net debt to net cash, revenues, profits and earnings soaring. An encouraging start to 2023. Plus a 7p final divi.
Cheap entertainment doing great augurs well forJ D Wetherspoon (LON:JDW) on 24th (Friday).