Small Cap Value Report (Wed 23 Oct 2019) - SPD/GOAL, SCT, 7DIG, NEXS

Good morning!
Today I'm looking at:
- Sports Direct International (LON:SPD) / Goals Soccer Centres (LON:GOAL)
- Softcat (LON:SCT)
- 7digital (LON:£7DIG)
- Nexus Infrastructure (LON:NEXS)
Sports Direct (LON:SPD)
- Share price: 317p (-1%)
- No. of shares: 522 million
- Market cap: £1,654 million
Statement re Goals Soccer Centre plc
Mike Ashley's thoughts on the fiasco at Goals Soccer Centres (LON:GOAL) do make for a dramatic RNS.
Goals Soccer Centres is just one of the many poor-quality businesses which Sports Direct has invested in. Goals admitted this year that its accounts were full of errors and that it was "in discussions with HMRC regarding a potential misdeclaration of VAT".
Sports Direct says today that the management at Goals didn't properly engage with them, when they were considering a bid for the entire company.
They go on to make some rather strong statements about what happened. I think it's worth pasting this in full:
"Given the issues within the Goals business, Sports Direct believes that it would be convenient for those concerned if Goals, and its corporate history, disappeared as a result of the AMA process.
[GN Note: AMA stands for "accelerated mergers and acquisitions" and refers to the attempt by the management of Goals to sell the company.]
From the beginning, the attitude of the Goals board made no sense, including proclamations to senior management of Sports Direct that the issues impacting on, and leading to the catastrophic failure of, the business had only been perpetuated by one person.
Sports Direct considers the Goals board members it was dealing with to be intelligent, and anyone with any common sense could tell it could not be only the result of one person's behaviour given the relative size and timeframe over which what would appear to be considerably more than "inappropriate actions" took place. This leads Sports Direct to conclude that the behaviour of the Goals board, and its apparent failure to spot and deal with the issues, amounts to incredible incompetence and ignorance, wilful or otherwise, at the very least and potentially far worse.
Sports Direct continues to believe that all relevant matters should be fully investigated, by both the AIM Regulators and an independently appointed third party, with no scope exclusions, and hopes that any eventual purchaser of the Goals business through the AMA process is not connected to the current management team given the investigations needed.
Yet again, the independent shareholders of a UK listed company get wiped out through the skulduggery of others; as these constant corporate failures show, the current rules and regulations do not do enough to protect independent shareholders or to prevent fiscal irresponsibility"
END
My view
I have some sympathy for Sports Direct and their statement. After all, they've been shafted by a company which published dodgy accounts. That always leaves a bad feeling.
On the other hand, Goals Soccer Centres has looked like a risky share for some time. See the archives and you will note that Paul and I discussed its high debt load on numerous occasions. It looked like it might be worth a speculative "punt" from time to time, but it was never a safe stock. For example, it was forced to stop paying dividends after FY 2012, and never paid another one after that.
The fact that the accounting was wrong only adds insult to injury, of course.
The bit where I take issue is that Sports Direct blames "the current rules and regulations" for what happened.
Instead of blaming the rules, I think it should take responsibility for its investments going wrong.
For example, during the collapse of Debenhams, Sports Direct also took issue with that Board not engaging with it properly.
Instead of blaming Boards of Directors for not engaging with it, it would be better off if it realised that this is a common experience for activist shareholders, and avoided putting itself in this position in the first place.
Being invested in publicly listed companies is risky, and that's particularly true when they are struggling, highly leveraged businesses like Goals Soccer Centres and Debenhams. If they don't blow up at some point, then you should count yourself lucky!
And expecting Boards of Directors to engage with you is unrealistic. Sometimes they will, sometimes they won't. But expecting any more co-operation then you are legally entitled to is setting yourself up for disappointment.
So that's the first reason I take issue with this statement. There is no shame in seeing an investment go bad, but Mike Ashley and Sports Direct should own their mistake, instead of blaming others. Nobody forced them to invest in these companies. And they knew (or should have known) the regulatory framework when they started investing in AIM and the LSE.
The second reason I take issue is a more pragmatic one: I'm sceptical of what changing the financial rules and regulations might achieve.
The statement doesn't spell out what changes Sports Direct is looking for, but I'm going to go out on a limb here and suggest that Goals Soccer Centres might have broken rules which already exist, e.g. as they relate to VAT and financial reporting.
The problem isn't that we don't have enough rules and regulations. The problem is that sometimes they get ignored! And the challenge we face as investors is how to identify those people who are publishing false accounts, as quickly as possible.
Unfortunately, I don't think there is an easy answer. It's a problem of enforcement and incentives: some companies have published fake accounts for years, without anybody blowing the whistle on them. And when they're eventually discovered, the authorities then have the problem of figuring out who did what, proving it, and coming up with appropriate sanctions which might prevent future instances of the crime taking place.
Improving the performance of financial regulators is the real challenge, and I simply doubt that it can be done by the introduction of even more rules.
At the end of the day, there is no substitute for finding good businesses run by trustworthy people. Unfortunately for its shareholders, Sports Direct has been overpaying for businesses which don't meet both of those criteria. It only has itself to blame.
Softcat (LON:SCT)
- Share price: 916.5p (-3%)
- No. of shares: 198 million
- Market cap: £1,817 million
I've never looked at this before, but readers have requested it.
It describes itself as "a leading provider of IT infrastructure products and services".
The solutions it offers fall under headings like "Business Intelligence and Analytics", "Networking and Security" and "Software Licensing".
Results
These results show revenue, operating profit and basic EPS all up by 24%, and healthy increases in the dividends.
Average headcount is up by 15%. A metric which investors might use in this case is revenue per employee. Always nice to see revenue growing faster than employees!
Its "key differentiator", according to Softcat, is "the attitude and ability of our people".
Customer satisfaction is at 96% and profit per customer grew by 17% during the year - good signs.
Net cash at year end is £79 million.
Outlook:
Softcat is in great health and strategically well-positioned. We think the structural drivers for growth in our industry will continue despite current political and economic uncertainty. The Board also remains confident in the Company's ability to gain market share and targets further growth during 2020. Trading in the first eleven weeks of the new financial year has been on track and we look forward to the rest of the year with confidence.
Brexit - the risk of operational disruption is considered to be low. The Board is monitoring developments.
Balance sheet - strong current asset position, mostly in receivables.
Average trade and other receivables were $225 million (see footnote 6), so receivables turnover is 4.4x (revenue/average receivables). This implies that it takes the company 82 days to get paid after it generates revenue.
However, this is complicated by the fact that the company generates far more invoices than it is allowed to record within revenue. So I suspect that the true "waiting time" for the average invoice will be materially lower than this.
My view - my first impressions are positive. It seems to be well-equipped to provide a truly comprehensive range of products and services to customers, making it a sort of one-stop shop for IT. If this has created a durable competitive advantage, then it's far more investable than the typical "managed IT services" business.
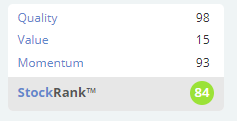
As you'd expect, it's a High Flyer:
7digital (LON:£7DIG)
- Share price: 0.18p
- No. of shares: 2.46 billion
- Market cap: £4.4 million
Contract to provide Music-as-a-Service Platform
I haven't covered this since August 2018, when the share price was 4.5p. So we have a 96% reduction in shareholder value in 14 months (significant dilution has occurred).
Maybe we can turn this into a game. Are there any companies which have used the phrase "as-a-Service" outside of a software context which have turned out positively for investors?
Argo Blockchain (LON:ARB) doesn't count - its recovery has been a consequence of abandoning the so-called "Mining-as-a-Service" strategy!
Nexus Infrastructure (LON:NEXS)
- Share price: 139p (+4.5%)
- No. of shares: 38 million
- Market cap: £53 million
This one has been listed since July 2017. It supplies physical infrastructure services through its three subsidiaries.
Profits for FY September 2019 will be in line with expectations.
The subsidiary with the largest order book, a multi-utility service provider called Triconnex, has seen growth of 26%, while the group as a whole has seen order book growth of 17%. Pretty good! Nexus says that this gives "good visibility of earnings for the year ahead".
Net cash is £22.6 million at year-end, accounting for a significant proportion of the current market cap.
Outlook is good:
The Board believes that the Group is in a strong position to deliver consistent organic growth, aided by the structural undersupply in the UK housebuilding market and Government stimulus for the sector but like many industry suppliers, we continue to experience caution as a result of the continuing political backdrop.
My view
Trailing EV/EBITDA is reported by Stocko to be less than 3x, giving rise to a ValueRank of 98.
I don't know if the stock would pass my quality filters, but it should definitely be of interest to value hunters at this market cap.
That's it from me for today. Cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
Nexus Infrastructure (LON:NEXS)
This link to invoice payment statistics may help in assessing the financial position of companies in the construction sector. While conceding that many factors can affect the timely payment of invoices, £NEXS (Tamdown) and Van Elle Holdings (LON:VANL) statistics look unhealthy.
https://builduk.org/priorities/improving-business-performance/duty-to-report/table/
Good analysis Gromley & rmillarie on Softcat (LON:SCT)
In addition to their customer & service focus they have, and I am am sure this is in a report I’ve read/heard the CEO state, a detailed, thorough corporate strategy created over many years and communicated to all, and I quote ‘sell more stuff, get more customers, and sell them more stuff’. Another possible reason to hold.
Graham,
Thanks for the Softcat (LON:SCT) analysis and I liked your possible software IT "one stop shop", observation. I suspect another Moat is their stated desire for customer intimacy and thus to love dealing with them. Would be interested to hear from anyone out there doing business with them?
re: SCT
You're welcome.
"Intimacy" - that is certainly an unusual phrase for a PLC to use! There seems to be something to it.
G
Irobot (nasdaq $irbt)
thanks for that WDWombat - with regard to the large drop in operating profit this year compared to last - i think that's pretty much exclusively down to trump increasing import tariff's up to a 25% level.
The company had previously quantified the specific tariff related hit for this year.
"CFO Allison Dean now puts the price tag of the increased tariffs for 2019 in a range of $35 million to $40 million".
Ok these tariff's costs are a real lost profit medium short/term but longterm i would expect the company to be able to minimise the hit by planning as appropriate - perhaps simply waiting till trump is impeached or puts his dummy back in and the hit will be back to a more manageable level.
I guess the main question is can they successfully branch from their core sales to other similar products like the new robotic lawnmower they have ? - i guess you might have to watch that one a bit more closely than your roomba if you have a boat load of flowers in the garden.
Graham - thanks for looking at Softcat (LON:SCT) . What impresses me about this company is that it has been buit up organically - many others would have increased by buying up competitors and ended with a balance sheet full of intangibles. Keith Ashworth-Lord says " ... it has been eating its competitors' lunches". He has been building up a stake for the Buffettology fund and his full comments on this company can be found here:
https://www.castlefield.com/media/2713/cfp-sdl-uk-buffettology-october-2019.pdf
"Maybe we can turn this into a game. Are there any companies which have used the phrase "as-a-Service" outside of a software context which have turned out positively for investors?"
I can tell you it doesn't always work out inside a software context either.
Irobot plc - nasdaq listed irbt ($irbt)
This company looks like a potentially interesting play (is it really 80 years since the original short stories that made the book turned up strewth im getting old)
Nasdaq listed - shares peaked at over $125 dollars not so long ago - and after yesterdays they may open around the $40-$45 dollar mark. i don't have access to overseas stocky number but looks like rthey may be on target for $3 dollars eps putting the pe at around 15 ish.
They are experiencing tariff issues hence the downer in shareprice - but other than that this does seem a decent growth company in a reasonably niche area. Ok i guess in 10 years we will all have a robot vacuum but i am guessing that they have enough technical nouse to make them something of an american dyson?? - the original members having come from MIT.
So without having done too much detailed research i am tempted to have a punt on these dimply due to the shareprice being somewhere in the doldrums - not an expert but it seems that most of these us tech companies that are still fundamentally growing seem to bounce back quickly when the share price takes a knock.
Anyone any thought on this random outfit?
from the company Q3 release
We now expect 2019 revenue between $1.2 to $1.21 billion on 10% to 11% growth, with an operating income between $75 million and $80 million, and EPS in the range of $2.60 to $2.80..... Although our third-quarter results were strong, sell-through following our late
July price increases was suboptimal. Given this outcome and our belief that the RVC category was at a growth inflection point prior to tariffs, we elected to roll back our pricing to pre-tariff levels on most of our products.
So they have basically dropped US prices back down. For the record there is also a suit they are bringing against a competitor (Shark) for patent infringement. Q3 apparently beat estimates and the guidance here is broadly in line with (what I think is) prior consensus, albeit at the bottom of the range. The p/e for 2019 is around x20. The company had been growing quickly but this seems to be a pretty hefty drop in OP from $106m in 2018. Latest numbers I can see had net cash of $165m, no debt. The average target price prior to the earnings release and comments therein was $70.
I have absolutely no view on the business but as you say has dropped severely since the Spring.
Graham,
Matters have reached a new low when Mike Ashley is berating others on corporate governance, VAT compliance and directors responsibilities.
He must have an incredibly short attention span: Belgian £605M VAT tax claim.
The auditors, Grant Thornton, have subsequently not sought re-appointment, no other firm of substance seems willing to fill the gap and the Chief Finance Officer has been sacked.
Bonitabeach
re: SPD
Bonitabeach, thanks for reminding me of that - couldn't make it up!
Graham
Yes, "interesting" thoughts from Mr Ashley.
On the subject of Goal's failure to "properly engage", I would have to observe that Mr Ashley does not always come across as particularly engaging.
Debenhams , also did not properly engage with him; but if I recall correctly he had already indicated that he might/would block any sale of Magasin du Nord, which could potentially have produced a sufficient cash pot to enable them to trade through their downsizing,
If Mr Ashley tried to "properly engage" with me, I might pretend to be out.
Softcat (LON:SCT)
Had a very quick look at this - as with other companies of this ilk i am always magnetically drawn to the trade and other receivables line as a starter for 10.
Sales for year £992 mill (prev year 797 mill)
Trade and other receivables £285 mill (prev year 206 mill)
Lets also make note of the payables line "deferred income" £15 mill - prev year 11 mill -(the higher tihs figure the better)
So sales up 24% and receivables up 38% - mini red flag based on the numbers.
there is a slightly confusing (on an initial quick look) note about "grossed invoice income" - a measure they like and a much higher total.
After my quick glance all i can presume from this is that it appears based on the above quoted numbers that the receivables total is not only high but increasing as a % faster than sales (not uncommon for fast growing stocks)
Note the increase in receivables in matched by increase in payables so the cash flow looks fine - if there is issues revenue recognition wise that tends to be where the problems get parked in the trade payables column.
Having said that the company quotes cash conversion of 92% which sounds reasonable.
Note the good news is that the amount of unbilled receivables and accrued/deferred costs bit is very modest - so i am guessing its a symptom of their customers get 60-90 days credit after they have been billed.
Does anyone else have any opinion on this relatively high receivables figure which i would normally see as a red flag,perhaps its just a symptom of standard payments terms in that industry - basically blue chip companies can presumably choose their own payments terms and no software company is really going to turn down the work.
I guess the only other interesting tidbit is the 2020 eps growth is only 5% - is this the future is is this a one off? for the pe we have i would like to thing growth was above 5% pa.
Softcat (LON:SCT)
Yes.
Firstly - I don't think the timescales seem excessively long (Graham calculates 82 days) - especially as milestone payments may become due during the course of a contract and therefore recognised as revenue, whether or not they are billed and paid at the time.
Probably more importantly though, I think it is important to consider the "grossed invoice income" rather than the revenue.
My understanding of how they describe this is that say they work on a customer contract for £15k but £5k of that is for (say) sisco kit for which Softcat place the order but create a contract between the customer and Cisco. That is not revenue but it is in the gross invoice income and therefore in the receivables as Softcat will collect the cash and pass it onto Cisco.
My understanding was that the key determinant was who carried the payment risk (if the customer defaults) - if Softcat carried that risk then it would be revenue, if it were Cisco then it would not be considered as Softcat revenue. Things may have changed however as they say :
"IFRS 15 requires some finely balanced judgements be made to determine whether Softcat acts as principal or agent in certain trading transactions."
If we look at receivables compared with the Gross Income using Graham's calculation this comes down to 58 days, which doesn't ring any alarm bells whatsoever for me personally.[No position currently, but potentially interested now]
Re Softcat (LON:SCT) in addition to a rather excellent name, they go on about customer service and staff a great deal, as do most companies but this from the CEO review, at the start of the final results, is quite something. These aren’t small awards. The CEO review is very well written & the results look very good to me.
Graham, would you have a look, or too big?
“Partner and industry recognition
We also saw strong growth in all our key vendors and received recognition for our performance from partners and other external parties. Dell awarded Softcat "Transformation Partner of the Year" across EMEA, and Sophos, Mimecast, VMware, Varonis, Ivanti and AlienVault all rated us their "Partner of the Year". We won the coveted "CRN Reseller of the Year" award, and were named "Best Performing Company for Infrastructure Services" and "EMEA Growth Partner" of the Year by Megabuyte and Canalys, respectively. We were also awarded "Company of the Year" at the PLC awards. Perhaps most pleasingly, CRN recognised a number of outstanding contributions from Softcat people in their inaugural Women in the Channel awards.”
John, The other Softcat (LON:SCT) phase that me struck today, which bears out their recent awards and would indicate a quite unusual sales strategy:
...Each year we develop greater customer intimacy and extend and deepen our technical know-how.
I can't see any of the FT100 companies risking putting this statement in their annual report!
re: Softcat (LON:SCT)
I'm intrigued by the number of requests for this £1.9 billion mkt cap company. Let's see what I can do.
Although past performance is no guide to the future, this company has been a class act for some time, having posted something like 40+ quarters of uninterrupted earnings growth. So whilst it has a racy valuation, I think many are backing a quality management team - I've topped up today on the SP drop today.
Hi All,
Seconding Nexus Infrastructure (LON:NEXS) . SR 89, PEG of 0.3, "contrarian" and passes 2 screens, one of which is Greenblatt's magic formula (quality+value) and the other is Ken Fisher price to sales (value, looking for growth). I hold and topped up a few weeks ago.
Would appreciate a gander at £NEXS, solid trading update in a neglected sector, tons of cash and a big order book
Hi Graham, would you be able to take a look at Softcat (LON:SCT) Softcat. Finals are looking extremely impressive. Considering buying. Thanks.
Yes agree Softcat (LON:SCT) results are good, but their price is off a bit first thing.
I did some research on them at the start of this year, which I believe still pertains - My notes/I hold...
Softcat (LON:SCT) hold 6% of a highly fragmented market and are growing fast. Likely to be doing well with the Cloud. Dynamic CEO who says they put excellent customer service and staff fun first. Glassdoor 4.2/5 with staff reporting long hours, stiff sales targets and high commission. Laddish rugby culture. Expanding staff numbers and regional offices. Atypically low 6% EPS increase forecast for 2020. Microsoft annual licence price rises will increase sales, but may dent future %margin.
I was looking at SCT yesterday as it matches most of my criteria, but I was put off by the considerable volume of selling by several directors over the last year.
Filtronic (LON:FTC) audited FY results to may 2019 out.
Last commented on in SCVR by Graham 29th Jan 2019. Poor results reflected in the SP. Will do better? Would be interested in further thoughts.