Small Cap Value Report (Wed 23 Sept 2020) - LOOP, SDI, ZOO, TEG, CALL, JOUL, W7L

Good morning, it's Paul here with the SCVR for Wednesday.
Timings - I think this is going to take most of the day, so I'll say finish time of 5pm but there should be plenty up by official finish time of 1pm. I have to take a longer lunch than usual, as the dogs need to be taken to the groomers for noon.
There are lots of trading updates today, so I can't cover everything. It's really helpful when readers who have a good understanding of particular companies post your own summaries of their results in the comments. Here are the ones that look most interesting to me today;
Agenda
Loopup (LON:LOOP) (I hold) - Half year results - this follows a very strong recent trading update, hence why it's top of my list.
Sdi (LON:SDI) - Trading update & IMC webinar
Zoo Digital (LON:ZOO) - AGM Statement
Ten Entertainment (LON:TEG) (I hold) - Half year results, 6 months to 28 June 2020
Cloudcall (LON:CALL) (I hold) - Interim results, 6 months to 30 June 2020
Joules (LON:JOUL) - Trading update
Warpaint London (LON:W7L) - Interim results
.
Loopup (LON:LOOP)
Share price: 228.5p (up 4% today, at 08:36)
No. shares: 55.4m
Market cap: £126.6m
(I hold)
LoopUp Group plc (AIM: LOOP), the premium cloud communications provider, is pleased to announce its unaudited interim results for the period ended 30 June 2020.
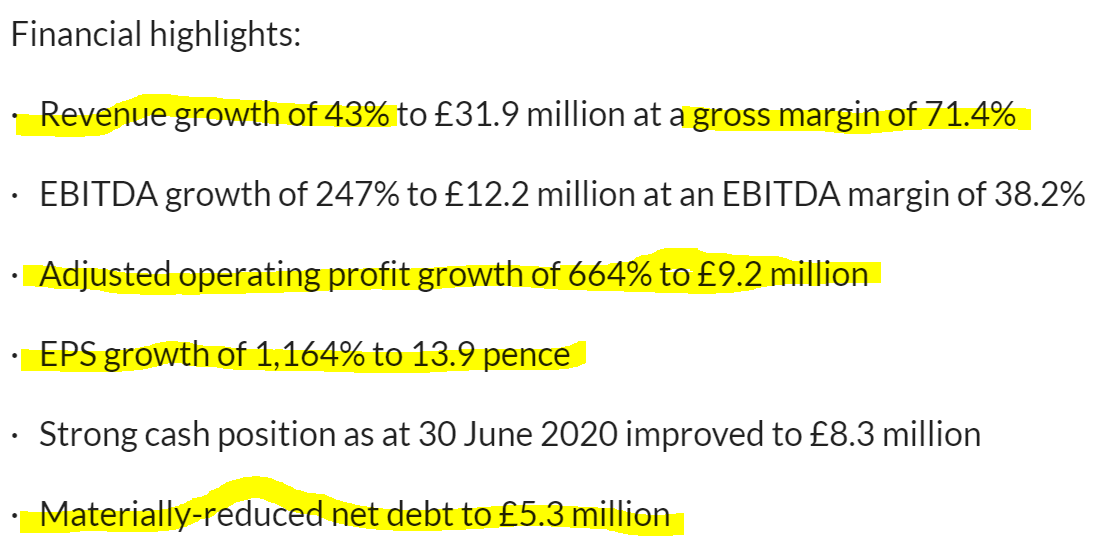
The financial highlights below look pretty stunning, but remember that the market has already been given these numbers, in a previous trading update which I reported on here, on 16 July 2020. That's worth revisiting actually, because I point out things like capitalised development spending (which flatters EBITDA).
There's also a H1 seasonal bias, and the company has benefited from the work from home ("WFH") trend. Worries that WFH was temporary have receded since yesterday's U-turn, in that the Govt is now telling people who can to work from home again, reversing what they told us a few weeks earlier that it was time to return to work.
LOOP has carved out a niche for high security conference calling. It is widely used by firms of lawyers & accountants.
Looking to the future, where I suspect people might tend to WFH for several days, then go into the office for the more collegiate experience for several days. Will LoopUp's service still be required then? Quite possibly, because you only need 1 key person to be working from home, and you would then need to use LoopUp, instead of having a physical meeting, even if everyone else is in the office.
.
.
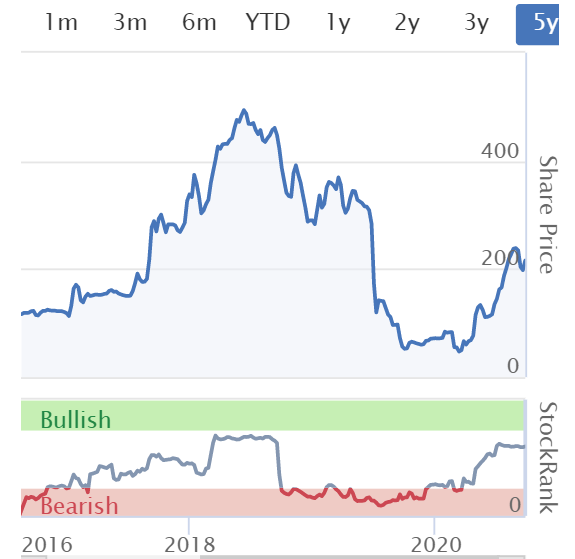
It seems to me that the share price of LOOP has not properly reflected this stunning improvement in performance. I bought some shares personally after the last very strong update, and am now worried that I didn't buy enough.
There are some good facts & figures in the narrative, e,g,
|
Outlook comments - the narrative today seems dripping with positive energy, whilst also recognising that the macro picture is uncertain. I suppose we have to be mindful with all WFH type shares, that if/when covid is defeated with treatments/vaccines, hopefully in 2021, then business could go into reverse. That said, I've tried out LOOP myself, and can see that when the features are properly used, it gives a level of control and security which may not be possible with other, mass market products like Zoom - coded in China, so not ideal if you want to discuss something sensitive.
Management sounded particularly excited about offering a telephony service within Microsoft Teams, in a webinar they did in July.
The narrative also talks about "investing for growth", so I think that means a big increase in overheads. Mgt has not always spent wisely in the past, with over-rapid expansion of sales teams being a problem a couple of years ago. Let's hope they strike a good balance between profitability, building up a cash pile, and expansion spending.
Balance sheet - greatly improved, but still weakish. NAV: 65.5m, less intangibles of c.£70m, gives negative NTAV £(4.5)m. I'd like to see cash retained within the business, and the NTAV to move into positive territory.
The working capital position looks fine, but I don't like the £11.9m in long term debt, and would like to see that paid off from cashflows in future.
Cashflow statement - a genuinely very cash generative half year, although note that about a third of cashflow was spent on capitalised development spending.
My opinion - I think the market cap is lagging behind developments here. The unknown factor is what happens post-covid, and will services like this be used so much afterwards?
In the meantime, LOOP has delivered an astonishingly good half year, and mgt sound optimistic about the future too. I'm very positive about these numbers, and will be adding to my long position when funds permit.
.
.
Sdi (LON:SDI)
68.3p (up 12%) - mkt cap £66.8m
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing control applications, is pleased to announce an update on trading for the current year.
[this covers FY 04/2021]
It's a reassuring update, in line with expectations, so it's surprising to see this trigger a 12% rise in share price, when logically it shouldn't really have moved the price at all.
The Group has made a very good start to the new financial year. Despite the ongoing economic headwinds, the Board is comfortable with current trading and in delivering financials in line with market expectations for the year.
Maybe people have interpreted this as meaning that the group might be ahead of expectations now, and keeping something in the bag in case there's a slowdown later in the year?
AGM online - bravo to the company for using the IMC platform to hold its AGM, and Q&A. We need to see more of this from all companies, not just small ones.
As described in the Company's announcement of 26 August 2020, existing and potential shareholders may listen to the formal AGM proceedings, and immediately following the formal business of the AGM participate in Q&A, via the digital platform Investor Meet Company at 11.00am today. Investors can sign up to Investor Meet Company without charge and add to meet SDI Group plc via: www.investormeetcompany.com/sdi-group-plc/register-investor
There's usually a recording put up on IMC later, for us to watch. I'm delighted the IMC platform was created, and am finding it a tremendously helpful additional resource, on top of the existing excellent output from PIWorld, and others. Unfortunately IMC doesn't put its videos on Research Tree, which is a pity. I've just emailed IMC to suggest they do so, as I'd like everything in one place to browse for interesting company reports.
My opinion - SDI seems a nice little acquisitive group. As with all acquisitive groups, you do have to keep a close eye on debt, and balance sheet strength, because the temptation is to load up on cheap debt, and see the balance sheet become too top heavy with intangibles.
Having confirmed guidance is in line with expectations, the PER of high teens for SDI looks about right to me.
.
Zoo Digital (LON:ZOO)
60.5p (up 6%) - mkt cap £45m
There was a lot of hype about this company a couple of years ago, but it subsequently didn't live up to expectations. It provides services for dubbing and subtitling video content, which sounds a pretty generic service to me, but Zoo claims to have technological advantages.
Today we get an AGM trading update. I'll summarise the main points;
TV/film sector is struggling, with new production suspended for almost 6 months
Zoo is benefiting from a focus on re-hashing existing content
We expect to deliver double-digit revenue growth in the six-month period to 30 September 2020 compared to the same period last year.
Sector uncertainty likely to continue into 2021
Rate of growth in subtitling and dubbing is less than expected, but still attracting new customers
Digital packaging has been a "major growth area" but no figures are given
Presentation slides that will accompany an investor update following the AGM will be available on the Company's website later today.
My opinion - neutral, because we're not given any figures, nor any guidance for performance against market expectations.
It sounds as if the company is managing well in the downturn affecting its sector, and it appears to be adaptable.
Looking at its historic track record, reliable profits seem elusive, and there are no divis. So it doesn't appeal to me. Maybe there's been too much hype, and not enough delivery?
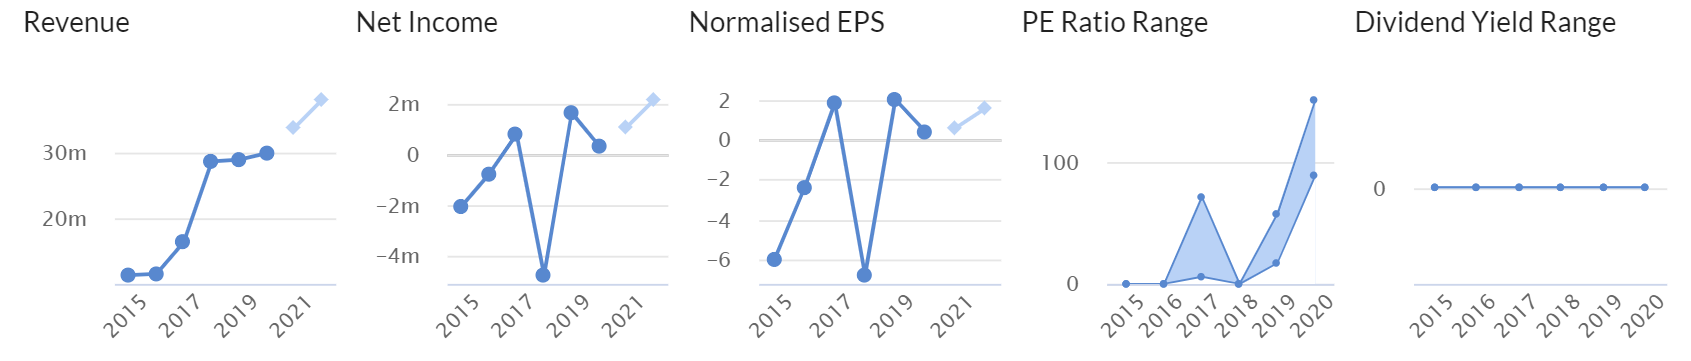
The historic graphs below emphasise that it's a small, only marginally profitable business. Performance would need to transform to the better to get me interested, and even then would higher profits be sustainable? I can imagine that dubbing and subtitling must be very competitive services, and everyone can do things over the internet these days, with probably plenty of people in the film/TV sector desperate for work and prepared to undercut on price.
.
.
Joules (LON:JOUL)
98p (up 7%) - mkt cap £106m
Joules, the premium British lifestyle brand, provides a trading update covering the 13 weeks from 1 June 2020 to 30 August 2020
[this is Q1 of FY 05/2021]
This strikes me as a good performance, in a very difficult period;
The Board is pleased with the Group's encouraging performance during the Period despite the highly challenging trading backdrop. Group revenue performance during the Period was ahead of the Board's expectations at £39.6m, with revenue from the Group's own e-commerce channels increasing 63%.
Overall Group revenue was down 18% reflecting the impact of Joules' stores, and those of many of our wholesale partners, not being open for a large part of the Period.
To be fair this doesn't cover the worst of the lockdown period, from late March, April & May, when all the stores would have been shut. But even so, to be only down 18% revenue, when we know that High Street footfall was low, and must mean that online has recouped a lot of the shortfall from the shops. Remember that Joules is very successful online, with about half all sales coming from that channel before covid. It's a very distinctive brand, with high customer loyalty, so it makes sense that some customers will have switched to buying online. That's one of the things I like about this brand, and why I see it as a long term success, not a problem retailer stuck with a load of uneconomic store leases, like so many other fashion chains.
The rest of this announcement is hopelessly confusing, giving a lot of different statistics, which don't seem to tie together. Instead of a lot of confusing text, why didn't they just provide a table, clearly setting out sales by channel?
From what I can make out, the key points seem to be;
Stores re-opened strongly, with sales down only 10% vs LY (ahead of expectations)
Wholesale seems to have have taken a much larger hit, with Q1 sales down heavily, at -59% vs LY
Liquidity - looks fine, with £8.5m net cash, and headroom of £57m (i.e. lots of available bank facilities)
Inventories - under control, and 16% lower than LY - so no worries about over-stocking
Outlook - cautious
My opinion - this update gets a D minus from me, for being so badly set out, and baffling me with an array of stats which don't properly explain the overall picture. If I've understood correctly though, it seems the stores are trading well since re-opening, which is good because the fixed costs are high. Whereas wholesale is lower margin, and has low fixed costs, so it doesn't really matter too much if wholesale revenue is poor for a while. Wholesale is only a worry re potential bad debts, if customers go bust, but nothing is said about that today.
With a very distinctive brand, and high online sales, this is a quality business, that should recover fully in time. So it should not be seen as a retail basket case at all.
Overall, it's potentially interesting. I just wish the company could get the hang of updating the market in a more clear, understandable way. Its updates are always badly worded & confusing.
There's a helpful update note available on Research Tree.
.
Ten Entertainment (LON:TEG)
(I hold)
126p (up 2%) - mkt cap £86.4m
Half Year Results
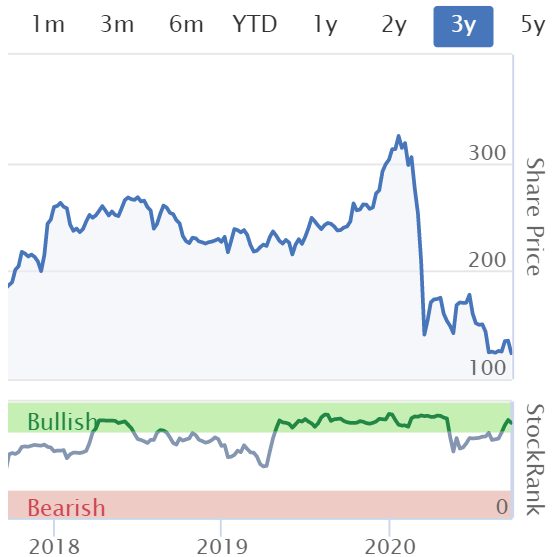
There was a reassuring update slipped out here on 8 Sept, indicating that re-opening of most (ten pin bowling) sites had gone very well, and they're already cashflow positive. I'm quite surprised the share price has remained so depressed. Maybe investors are fearing another lockdown, although that had been avoided for now.
Ten Entertainment Group plc ("Ten Entertainment" or "The Group"), a leading UK operator of 46 family entertainment centres, today announces its half-year results for the 26 weeks to 28 June 2020.
The results reflect a period of very significant disruption as a result of the enforced Government closure of all leisure and hospitality venues ("Lockdown") from 20 March 2020 as a result of the Covid-19 pandemic.
For this reason, the historic figures are not of great interest. All I'm looking for is that - losses are not too bad, the balance sheet is strong enough to survive, and that current trading is OK/improving.
H1 revenue almost halved, unsurprising since sites were forced to close for more than half of H1
Adj loss before tax of £(5.7)m - ouch, that's a hefty loss for the size of company
Modest net debt of £6.7m, and plenty of headroom on bank facilities
Profitable & cash generative since re-opening - that's fine, I just want to see the company not losing money at the moment, and it's achieving this whilst operating at 50% capacity
Balance sheet - is very badly presented, lumping together bank borrowings and IFRS 16 lease liabilities. This is ridiculous, as they are completely different in nature, so should be shown separately. Overall, NTAV is £15m, which is adequate, but not strong. The main risk here is obviously if covid were to get a lot worse, and the Govt once again required bowling alleys to close.
My opinion - as things stand at the moment, everything is fine - the sites are open, and are profitable & cash generative, at reduced capacity. I think that is perfectly satisfactory, because it means the business should be able to tread water until the covid crisis is over, hopefully at some point in 2021, then return to full capacity and enjoy a resumption to previous levels of profitability.
I'm quite surprised that investors can't see this, which strikes me as the most likely scenario. The current price is little above the March lows, which doesn't seem to match the reality of successful re-opening. Maybe people are terrified of a further lockdown?
.
.
.
Work-in-progress -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Not so much terrified of another lockdown as lack of confidence in the conflicting advice. Two bods from Oxford, one saying forget lock down and the other saying more stringent lockdown. Just listen to some of the poor people with businesses to run who are in utter despair, and then Boris comes out with patronising tosh 'this government will put its arm around the uk.' Its fine for corporates and I'm sure TEG will be ok, but the overall perception for unlisted small businesses is just awful and I'm so glad and lucky not to be amongst those ranks anymore.
I have not looked at Trackwise Designs (LON:TWD) before but a quick look at the chart says that the market places emphasis on the manufacturing agreement announced on Friday rather than today's results.
I need to understand more about the company as so was pleased to find a presentation. In total contrast to MichaelFBS's experience with Boohoo and Zeus, discussed here on Monday and yesterday, Trackwise introduces its Webinar on Investor Meet Company on Friday with the words:
"The Company is committed to ensuring that there are appropriate communication structures for all elements of its shareholder base so that its strategy, business model and performance are clearly understood".
How refreshing.
Hi spglet,
As Pratt123123 has mentioned this pipeline has been created in just two months.
So , early days and we'll have to see whether they can land these contracts with many unknowns. There is very likely to be a longer sales cycle, longer integration timeframe, and we can only speculate on the win ratio.
Would a great story but the “total” value of the 219 opportunities is 50m - not each!
Didn’t the review say the total of all opportunities was £50m? And where does one in three hit rate come from? And how repeatable on an annual basis is this growth? Should be able to model it.
Hi Maddox, the win ratio is the standard one used in the industry. It's not really a speculation, it's a factor that has stood the test of time. There might well be variation but more often than not it's a very fair basis to plan. Contract renewals also don't always happen as expected, client technology strategies change, their vendor preferences change, decision makers move on. So there is also a natural decay there as well as you might guess. But having said all that Microsoft Teams represents a good opportunity, so sales is going to be far from flat! Execution is all in these situations. Never underestimate the ability of software businesses to fail to develop opportunities as they should do. So many moving parts and personalities involved. I agree with others (and no doubt yourself) this probably a good one to buy for growth.
Hi spglet,
Yes absolutely, merely pointing out that we don't have any data as to what their win ratio might be as the Direct Routing proposition is very new.
Yes again, I've been buying LOOP as a growth opportunity - last purchase at 191p in the recent dip.
Hi Maddox, I'll be buying too. :-)
For anyone interested Progressive Research released an update on LOOP 's interim results today.
I would just point out that this is research commissioned by Loopup and therefore inevitably positive
Good point. Should have mentioned.
not a small cap but popular here, has anyone seen the JP Morgan note on Boohoo (LON:BOO)? Will be interesting to see if it can close above 320p, recent ceiling
Hi Hornblower, from my reading of the chart, 325 is the next resistance so if it holds above that, that would be good. JP Morgan have started with an overweight rating and target of 415
cheers
Francis
Someone I know in the Leicester rag trade is selling to Boohoo (many are) and he commented that it seems that they are trying to get their ethical house in order. Apparently, they have been asking for all sorts of certificates from up-stream suppliers.
Interestingly, they are also looking at Recycling of Plastics, particularly PET, which can be recycled into Polyester garments, etc and certified independently by 'Global Recycled Standard'
https://www.thetimes.co.uk/article/ef93272e-fcfc-11ea-8388-5bae8b4ec9a9?shareToken=6a172bc70b5103b1ff01fb62a22c0990
The Times market report today (near the bottom) mentions PH analysis of the proportion of pub, bar and restaurant group takings post 10pm. Apparently reckons Revolution Bars (LON:RBG) potentially the hardest hit with 18% of takings post 10 pm.
Revolution Bars (LON:RBG) share price floats even lower.
I have just managed to top up again, extremely small purchase but only paid £0.09724.
Mark Ward keeps buying, they are open, and they have enough money till next year to survive, so bargain of the year or punt gone wrong.....who knows.
I don’t own this stock. Unfortunately it’s future is now in the hands of government policy which has become completely unpredictable. It looked fine at the beginning of July but not now. The government is trying to shift the focus away from its own failings of testing and shielding the elderly.
"Completely unpredictable" because the scientists can't predict the course of the virus. We have them extrapolating huge numbers of cases and consequently deaths. The recent increases have surely been because it has been holiday season and people have been circulating more. Now that season is behind us I could expect the number of cases not to increase and even if they remain high then estimates of considerable deaths appear ludicrous. We are now better able to treat the virus and the early deaths were almost all amongst the most vulnerable. If my view is correct then in a months time they may be lifting some of these restrictions and if they pick up again around Christmas imposing them again. Unknowns are unpredictable.
Revolution Bars (LON:RBG) The market cap is now less then the recent placing ,and the original value of the entire company is now valued by the mkt at zero. I guess the question is how much the mkt cap should be? 5 million perhaps? Or ten? Can it survive or will the inevitable expenses wipe out the placing money and other monies / loans? Will the equity be completely wiped out? There must be a fair chance of that and perhaps the bars will be better off closed from mid January to near Easter next year? It certainly is getting into the risky buy level in my view albeit for punting money only. The punt here is on a vaccine I think.
Hi barnetpeter.
I still hold Revolution Bars, and now at big loss with share 50% below the Open Offer price where I applied for, and unfortunately got, more on top.
If the following is wrong then, you, Paul or someone might explain why; but wasn’t it a big mistake not having a lot of their bars open during the Eat Out to Help Out bonanza that others in the sector cashed in on big time? And have they compounded that mistake by extending the half price offer, but at their own expense? That surely means they are currently trading for little or no profit, or even at a loss. And now with closure at 10pm they are facing that hurdle too.
There are no Revolution Bars near where we live. I’ve looked at reviews for a number of them. Food seems very popular overall. But what a big and wide ranging menu. Is that sensible or would a smaller but still good quality range be more cost effective? And at several branches very slow and inefficient service seems frequent along with a couldn’t care less attitude from some staff.
So how competent are Management? After all they somehow messed up that agreed bid from Stonehouse around £2. That takes some doing.
Can they survive? If they can and if covid is over the worse soon, or vaccine quite near, chance of share going up 3 times or more? Chance of a low ball bid? Or is it more likely Revolution will go bust with any potential bidder waiting to clean up then, but after shareholders wiped out?
I haven’t held on to a share all the way to zero for many years. Beginning to fear Revolution could go that way.
btw....I also hold Saga. Can’t believe the share price is now below that (reduced from 15p) 12p Open Offer price! It’s now cheaper to buy in the market than take it up so presumably Roger De Haan will end up with an even bigger stake.
Surely SAGA is less likely to go bust than Revolution Bars, as their insurance business should help them survive even if cruises cancelled yet again and their main travel business also taking further big hit. They rejected an indicative bid at 32p. Could that bidder come back, albeit at a lower price? Could Saga go private, but again at a very low price? Or, my preferred outcome, once covid over would SAGA business, now with Roger De Haan back, recovering big time and share multi bagging.
Not really a basis for investment is it?
It's worth pointing out that Revolution Bars (LON:RBG) re-opened sites with an 11pm closing time already. So moving to 10pm now is definitely going to hurt, but maybe not as much as people might think, if they wrongly believed that the company was already trading late.
Also worth reminding people that the recent trading update indicated that performance was ahead of expectations given in the fundraising scenario.
I'm really surprised the price has fallen to just 10p, given that the situation is hardly any different to when the fundraising at 20p was successfully completed.
Revolution Bars (LON:RBG)
Paul, I hope you'll take this in this spirit intended - to challenge your thinking and encourage you to.
I think you are substantially under-estimating what has changed (and perhaps anchoring on your initial investment decision , which might have been right but unlucky?)
Even if they have already been closing at 11pm; it's not just an hour they are losing.
On peak days that last hour is the most lucrative for drinks sales. Maybe people will just go out an hour earlier and get steaming by 9:30 rather than 10:30, I'm not sure. If though that does happen, then there would likely be a further restriction applied. Also (in England) it is 'everyone out and doors closed' by 10pm so that's equivalent to last orders at 9:30. (I'm sure you remember double or triple rounds at last orders before licensing was liberalised!)
On food (I'm not sure how important this is to RBG) there is a concern that maybe the earlier close means only one rather than two evening sittings.
So from my view, there has been a profound change in the last month.
I do think that Pubcos and restraruants, will become a massive value opportunity at some point - maybe that is now, but I am not convinced. (FWIW I think this weeks virus response will have very little impact, so for better or worse there is potentially more to come)
But Gromley you are missing that management said all this as part of the raising. They said the after 11pm trading was 20% of profits. They also said that this meant they needed to work harder to spread some of this into the rest of the day, focus on food and other brunch type initiatives. They have now said they are trading ahead of that base expectation. There has been no negative change apart from perhaps your understanding of how the business operates (ps I don't mean that rudely).
The article in the press today was typically lazy journalism in my view. It said Revolution Bars (LON:RBG) would suffer most from a 10pm close as 18% of their profits come from the last hour of trading. That isn't quite factual. The last 18% of their profits came from late night opening (rounded up to 20% by me above). They have suffered that already and mitigated some of it. Unfortunately readers of said article don't do research properly, take it as gospel and sell out.
Now, a 10pm closure time is likely to worsen trading but may actually have minimal impact. There is a school of thought that people will just start earlier and potentially drink more quickly as they know timing is restricted. They can't go elsewhere as no-one is allowed to open. So whilst I accept that a 10pm close is unlikely to be positive there is a lot of nonsense being spouted about the actual impact of 11pm to 10pm and seemingly much of it made up!
Interestingly as a little side note I am told that statistically most cases of Covid being passed on is between friends and families in the home. This actually makes some sense - hospitality venues are covid secure, homes are not. So actually the Government might have been better banning visits between households and telling them to go to the pub or restaurants instead. Kill two birds with one stone - reduce R and encourage hospitality spending/preserve jobs..........another opportunity missed????? oh well............
david,
You are probably more engaged with the detail than me, as I haven't done a detailed review.
I had not realised that RBG had said that 18% of their profits came after 11pm - from my exerience of the industry (quite old and dusty now) that seems quite low. I would be interested in how they classified "profits" there - the key metric imho would be gross profits less variable staff costs ; if they were looking to put a positive spin on the situation they might have spread the rest of their costs evenly across total opening hours.
I should be clear that I do not know the answers here, but it does seem to me that things have profoundly changed in the last the month. We have gone from, limited re-opening and a path to business as usual to ; renewed restrictions and a total pub shutdown a quite likely prospect.
IMHO RBG and any other pubco have become significantly riskier propositions in the last few weeks.
David, I don’t think the market is reacting to the earlier closing time so much as the six month estimate on timelines from the prime minister and the obvious threat that if this worsens, pubs will be the first sector to face further restrictions. While early closing hurts, certainly within the industry this Six Month Timeline is what is causing most concern to both myself and people I talk to for three main reasons:
1) it brings home that there is no clear end to this. That should have been clear before but for whatever reason it wasn’t getting through. Remember, pubs will not be deemed a safe environment until jabs are actually distributed and that will be at least 6 months away at this point.
2) that timeline brings us through the Christmas period - as I pointed out before, this is the pubs main period, estimated to be when they generate over a third of their trade (and for a drink focused venue like RBG, more of their profits). Coupled with the limits on people sharing tables from different households. BJ just cancelled Christmas
3) while I’ve no doubt they are improving their food offering, this is no simple fix. Competition is fierce and consumers do not naturally associate them with good food.
I don’t have any position on RBG but everything I see here makes this share extremely risky at this point. What do you do as a pub if furlough is gone at the end of October and you are leaking money quickly? Or more pertinently what does your bank do? Rishi has to decide if he is saving the industry (and jobs) or if he can’t - 20% of Whitbread’s staff was the tip of the iceberg. Pubs cannot open their doors and trade profitably with the current restrictions.
I to agree that the change in trading hours will not make a significant change in revenue. However their are many who will be put off going at all and the prospect of this continuing for another 6 months will be the death knell for many unless there is an extension to the furlough scheme and/or some other support such as a VAT freeze .
It’s all a ridiculous overreaction and another example of poor leadership .
By all means protect the vulnerable and insist on them being in lockdown,but allow the majority to go to work and live as normally as possible but ensure they do not visit the vulnerable . The latter to be helped by social workers etc organising shopping/medical supplies etc. Of course a lot of the latter was done by the community in any event,at least where I live.
Down here in Cornwall life goes on as normal. The place is packed and it’s impossible to get a decent restaurant booking for a month or so. Little evidence of any Covid paranoia apart from the face masks in shops .
Loopup (LON:LOOP) - They have a pipeline of 219 opportunities of potential contract value of £50m - whereas their H1 revenue was £32m!! We don't know their win rate or the prospective contracted period (but say 5 years) - all the same that is one hell of a pipeline!?!
I have some sympathy for the Analysts - very difficult to call - but I reckon that they can afford to be a bit more bullish - and thus we can expect some upgrades.
Another factor is we do not know the potential of the new MS Teams integrated global telephony offering - or how well those sales are going. There will be an insignificant contribution from this in the H1 figures as it's only just been launched.
Also, H1 will have benefitted from Covid-19 for only 4 of the 6 months and H2 will likely benefit for a full six months - as we're back to 'work from home if you can'.
I cannot agree more. Work in the Telecoms industry myself (B2B) and the demand for Voice services in the last 6 months has been ridiculous. The other key element to note is that with the integration with Teams, there is the potential lucrative opportunity of getting into the 'subscription' based model of revenues that Satya Nadella at Microsoft so successfully used to transform their fortunes in the last few years. The shift in the way we work is without a doubt permanent (to what extent is debateable) but in my opinion there's easily another 12 months or so of strong growth left before we know anything more about a way out of Covid.
I see Progessive has reduced its FY20 revenue for £LOOP forecast by £1m (2%), reflecting fx and l-t contract pricing headwinds (as mentioned in the RNS). Earnings forecasts for FY20 are not changed. Progressive is still very cautious around FY21, seeing a small increase in revenues but a large fall in EPS to 9.5p.
Glad to hear some comment relevant to Loopup from someone who works in the telecoms industry. I think the trends mentioned will also benefit Gamma Communications to a considerable degree.
Yes, I'd tend to agree. Gamma is pretty established in SIP Trunking, which has seen soaring demand during the pandemic. I guess the million dollar question for most of the companies is, how sustainable is all this growth this year and how do you derive a useful valuation?
GAMA are very well established in the Cloud telecoms space are on a p/e of 29.5 versus Loopup (LON:LOOP) on a prospective p/e of c. 10 (being somewhat more optimistic than the Analysts on the H2 eps). So looking comparatively cheap.
My problem with £Loop is the competition from Microsoft Teams. I am no doubt missing something (I usually am!) but in the enterprise space, at least, the majority of organisations have Microsoft 365 and get Teams as a free add-on (that is the deal my org has so I assume that is generally available). Why would you therefore take Loopup? Is it mainly smaller orgs with non-MS stacks? Does it have better security? This https://www.gartner.com/review... indicates very similar capability.
That pipeline isn't so very high. Assuming the pipeline only consists of qualified prospects (budget, timescale, senior approval/signoff) rather than a mix of prospects and suspects, the rule of thumb is 1:3 sales conversion. So a pipeline of £96m will typically give you revenue of £32m.
Hi spglet. Agree with your analysis here... however what you forget it that this is just the pipeline for MS Teams integrated Direct Routing element, which was only announced a few months ago. Hence, this is 'post period'. A few more quarters where we see this coming to fruition, followed by further growth and I think the current levels of trading will be dwarfed.
Hello P123, yes. The MS Teams integration will pull in more business as you say. The extent of it depends upon execution. Microsoft also have a history of building "competitor" or "partner" functionality into their own products sets where the revenue/size of opportunity justifies this, or simply to fulfill strategy objectives (domination). Their Skype organisation will be looking at what is going on at LOOPUP. Don't get me wrong, the opportunity looks very good but I've quite a lot of experience of this kind of thing and with Microsoft in particular.
I'm also in the industry and agree with your rule of thumb. Microsoft are actively avoiding the Telco market and keeping away from trying to dominate it. Could be a wise long term move (low margins) or the missing a huge opportunity (become biggest b2b Telco in the world). Either way they have set Teams pricing to be uncompetitive and encourage competition via direct route. I see Loop as an international Microsoft partner with a successful focus on law firms. Can't see much else really. You could argue Teams will erode some of their legacy revenue streams. Also 2-3 years down the road after all the hard integration is done, contract resigns will be a commodity sale with lower margins.
on reflection I didn't highlight that they have their own network and international agreements with telcos. Whilst not unique, that could be their niche as most competition in this space would be the big international players who are hardly cheap, focused or flexible. So probably a better opportunity than I painted above.
Thanks for your insight. Interesting.
Re Loopup (LON:LOOP) and Paul's comment "Management sounded particularly excited about offering a telephony service within Microsoft Teams, in a webinar they did in July."
I no longer work in a corporate role and sold out of Loopup (LON:LOOP) in April because it had done well for me and I feared MS Teams was going to incorporate Loop Ups key features of a simple dial in via email feature. Was this a mis-understanding by me?
Morning all, does anyone have any view on Strix (LON:KETL): revenue, profits, eps all down , debt up but price not off much so would appear market had factored in next update not being great.
Any views on future upside or downside appreciated.
It seems to have ' run out of steam' . The share price was 'boiling over' since its rise from the lows in March... ( Pardon all those puns ) But seriously. its come a long way and probably needs a period of consolidation
interesting acquisition today as well in separate RNS
I think we would be mugs to consider Strix (LON:KETL) as anything but a company full of self-e-steam and still frothing
The share price is not as piping hot as it has been, but a 70% increase in the last year shows how it has scaled up.
With the purchase of Laica, Strix (LON:KETL) can grind out more profits due to cost synergies, they both have factories in China for instance.
What really excites me though, is we know about halopure which seems to be well received, but what are the other 14 new products brewing that they still have to bring to market, how much more growth once they percolate through the market?
Strix (LON:KETL) is a different kettle of fish to other companies, and will soon be singing again.
I'll get my coat.
Very good Bob are you here all week ? I seem to remember someone on Stocko saying a few weeks back that the new water filtration business which gave the stock a boost was picked up from the Woodford fire sale hopefully they won't be over stretching themselves by taking on to many new markets/products at once.
On leave this week, too much time on my hands, but no more puns from me, I promise.
Here is a link to Strix (LON:KETL) CEO interview today on the purchase of LAICA
https://www.directorstalk.net/strix-group-seeks-to-enhance-its-position-with-conditional-acquisition-of-laica-interview/
Strix (LON:KETL) You're also welcome to join us at 3.30 to speak directly with management https://zoom.us/webinar/register/WN_7warbRuhRFGMd44Yc8oSJw or watch back the recording tomorrow at https://research.equitydevelopment.co.uk/research/tag/Strix-Group-PLC
excellent post
groan!
Strix (LON:KETL) Record sales in Q3, with a full year profitability expectation the same as the prior year looks outstanding to me given the shutdowns in HI
Morning Paul,
Many thanks for your continued reports, I thoroughly enjoy reading these with my morning coffee!
Do you have any thoughts on Nahl (LON:NAH) and the tentative offer from Frenkel Topping (LON:FEN) this morning.
Nahl (LON:NAH) possible offer from Frenkel looks an excellent tie up. As I looked through the Frenkel results yesterday a thought crossed my mind that they might bid for the Critical Care element of NAH, which similarly focuses on providing expert witnesses. As a separate division this could be extracted fairly easily - it operates from a different set of offices with its own management team.
Might be that the only way they can get this is to buy the whole business - and maybe sell on what they don't want from PI (Personal Injury) and the smaller residential property section, which has now been folded into PI under 'Consumer Law' as not strong enough to stand alone.
Frenkel Topping (LON:FEN) The RNS confirms that they will sell on the non-expert witness part
No, I don't follow £NAHL or Frenkel Topping (LON:FEN) , sorry.
Ten Entertainment (LON:TEG)
Update seems just about as good as i could have hoped for, wasn't convinced if customers need to wear masks they would be able to get to cashflow neutral position with current restrictions in place. Looks like my worries were unfounded. Not tempted to top up here due to ongoing uncertainties and "safer" bargains elsewhere and the fact i am already over exposed to travel and leisure pre covid (doh)
Greggs (LON:GRG)
Bit OT this one as no news today but the shareprice is entering my tempting zone (post covid low) - at 1130p (better than BOGOF compared to recent peak price) - if we say they can get back to 2019 levels of earnings (85p or 93p per stocky take your pick) - thats pe of just over 12. They were doing well pre lockdown so 2020 would have likely beaten those 2019 numbers. Seems to be reasonably entry point for a quality outfit.
My slight niggling worry here is that that last 10%/20% of sales per store seems to be the real (whole?) profit earner - so if they fail to get back to peak per store sales due to ongoing issues it may be a long slog back. Has there been a structural change in their pass by customer base if more people will be working from home ? (could be) - some food for thought. If price does go much lower this may end up top of my BOGOF shopping list. Maybe they need to offer BOGOF sausage rolls to get the customers back through the door.
As a random thought, my nephew is one of these cycle food deliverers in Newcastle (Tyne not Lyme), and Gregg's is on the list of companies he delivers from so folks are getting stuff delivered, probably only a small fraction of the big Friday morning office queues for the Bacon Butty's though.
Loopup (LON:LOOP) scratching my head on this one (I hold). Results look very strong. They will be back to net cash by y/e from looks of things with an eps closing on 30p. Some good new wins increasing momentum. Seems remarkably cheap - a telecoms tech disruptor on a PE of sub 8 with cash??!!
Surely I’ve missed something material here?
LoopUp (LON:LOOP)
Would agree these results look stunning (particularly when compare to Cloudcall who have been slowed down by covid! - that may not be fair lfl comparison)
Main plus point here is that the results look very "clean" - nothing sneakily capitalised that doesnt have matching emntry on profit and loss (non current assets down)
Comments per Paul
although note that about a third of cashflow was spent on capitalised development spending.
I think this comment in isolation could be slightly misinterpreted albeit technically 100% true - the cashflow statement excludes (adds back) £3.65 mill of depreciation before inlcuding £3.62 mill of development + capital spending - so there is actually a net positive cashflow effect from the capitalisation/deprectiation "combo" i n this period - i am 100%+ plus happy with that for a growth company.
The only drag on cashflow was the debtors increase which seems fine with near 50% sales uplift.
My one concern is why are broker forecasts on stocky are so low for next year ? - is company expecting that good year is one off? Drop from 8m this year to £5 mill next year seems bizarre without specific comment from company today that this year is "exceptional one" not to be repeated (Even Jose struggles). Anyone any clues on what to expect next year and why forecasts are so low?. Are sales genuinley recurring here or do they book big wad when they first sign up clients and need new clients to keep the profits flowing?
Kinds feel like i need to find some cash from down the back of the sofa if next years estimates are simply old figures due to company keeping stumm ref 2021.
I suspect the 2021 forecasts are old because Loopup (LON:LOOP) refrained from reinstating guidance.
Find it hard to reconcile why it doesn't trade higher. 30% of revenues are now on term contracts of 24+months so that provides some visibility and they are growing that number. Prices are lower so that will have some downward pressure on eps. They've just signed up another top tier law firm and will benefit from Teams integration/sales with £50m pipelines. I also find it hard to see why they would have any significant churn even as people return to work. More likely businesses who find it useful will retain it both for flexibility around home working and contingency in my opinion.
I fully expect growth to moderate but that's ok - anything in the mid teens from here is fine and that doesn't seem a big stretch. I suspect upgrades will start coming post Q3 trading update but we'll see.
It's one of those stocks that were if it was listed on the NASDAQ it would be flying. It is however up over 200% in the last 6 months so perhaps there's a psychological barrier for new buyers given the strong performance?
Given comp Cloudcall (LON:CALL) sits on 20x FY21 earnings, applying the same to Loopup (LON:LOOP) FY21 EPS estimates of 15.1p (as per Simon Thompson's IC article a few weeks ago and only a minor increase on the interim results), this gives a target price of 302p. I continue to hold as I believe the Teams service is genuinely transformational for the business. My one concern is whether larger institutions (say big financial services companies) would be prepared to pay for LoopUp's service on top of Teams and whether that may stunt long term growth.
Would the end customer have to pay for LoopUp separately? Or will it be part of the Teams offering (i.e LoopUp is a supplier to MS) to the end customer ? In either case, with 10% penetration today for Direct Routing, forecasted to increase to 90% by 2022 (Source: Gartner), even if LoopUp gets portion of this growth, we're talking transformational growth. I suspect the Board is playing it cool as lots of factors outside their control (macro) and nobody wants to get ahead of themselves. I like the Risk Reward here but due to low float % out there, this could be a bumpy ride.
The way it works is you pay Microsoft for basic Teams packages then have the option of buying the "phone system" (calls to/from normal numbers) from either Microsoft or direct connect supplier. I could name >10 UK direct connect providers without much effort. Not all direct connect providers will have LoopUp experience as a Microsoft partner but Gamma supply direct route and are targeting Microsoft resellers to resell Gamma service.
"I suspect the 2021 forecasts are old because LoopUp (LON:LOOP) refrained from reinstating guidance".
Progressive has issued a note this morning giving estimated EPS 17.2 this and 9.3 next - a little above but a similar drop to the consensus on Stocko. The drop is partly explained by large customers moving to lower priced deals. See:
https://www.progressive-resear...
(You will need to be registered).
LoopUp (LON:LOOP)
Cheers for that sharw/Wimbledonsprinter - i guess that makes the current price look closer to what i would have expected compared to what i would have expected had the earnings been expected to stay at or increase from current year levels next year. Hopefully for holders the numbers are doing the talking now and they have no need to go anything above really conservative with regard to next year?
Loopup (LON:LOOP) have promised but failed to deliver too often in the past. The market is probably just being cautious in case this is just another example of over-optimism. Having said which, these results do look good. I have opened a small position
We don't know whether businesses will go back to normal once / if Covid is beaten. My personal guess is that the moves to Working from home, cloud computing, online shopping etc. are permanent. These areas were growing anyway and Covid has just accelerated the growth that was going to happen even without Covid. If Loopup (LON:LOOP) executes well on its potential it should be one of the beneficiaries of this long term trend.
Repeated from yesterday afternoon as I only posted at 4.30pm:
I know that SCVR is not interested in Natural Resources stocks, but in case anyone else is, I have done a Note called Horses for courses in Natural Resources - Power Metal Resources plc (POW), just published on the Discuss page. I hope you enjoy it, and would welcome comments/feedback/views
My morning smallcap tweet:
AA (LON:AA.) Mobile Tornado (LON:MBT) Zoo Digital (LON:ZOO) Gulf Marine Services (LON:GMS) Real Good Food (LON:RGD) Hyve (LON:HYVE) NAHL (LON:NAH) ValiRx (LON:VAL) Angle (LON:AGL) Fulcrum Utility Services (LON:FCRM) Joules (LON:JOUL) Bigblu Broadband (LON:BBB) Hornby (LON:HRN) Ilika (LON:IKA) St James House (LON:SJH) ECSC (LON:ECSC), SDI (LON:SDI), First Property (LON:FPO), Hardide (LON:HDD), Staffline (LON:STAF), Cloudcall (LON:CALL)
AA (AA.) one bidder pulls out of talks. [SP=34.7 Cap=216m]. I hold.
Mobile Tornado (MBT) a COVID track and trace program, utilising co's PTT solution, implemented in The Bahamas. "The system will operate for an initial period through to at least February 2021 and is currently protecting and controlling over 3,000 inhabitants. Planning is in place to roll this out further as restrictions are lifted." [SP=4.6 Cap=17m]
ZOO Digital (ZOO) guides H1 rev up 'double-digit' with significant growth in dubbing. Orders for delivery in Q3 significantly ahead of any previous Q. [SP=57 Cap=42m]
Gulf Marine Services (GMS) Seafox seeking to remove a raft of directors. "Seafox's letter contains a mixture of factual inaccuracies, irrelevant allegations and hyperbole." [SP=9.18 Cap=32m]
Real Good Food (RGD) Aug rev down 7%. Five months to Aug down 28% with pretax -£3.8m (-£1.9m). Co trading modestly ahead of covid budget expectations. [SP=5.4 Cap=5m]
Hyve (HYVE) fuides FY(Sep) rev c.£105m (£221m), net debt £80m max. CFO scarpers, will aid handover. He is thanked. [SP=67.25 Cap=178m]
NAHL (NAH) Frenkel Topping buys 6%, makes a merger approach. [SP=47.44 Cap=22m]. I hold.
ValiRx (VAL) re:SP rise - confirms it still expects to receive and notify the headline VAL 201 prostate cancer trial results by end Sept. [SP=40 Cap=23m]
Angle (AGL) breakthrough research published, using Parsortix system, into the role of hypoxia in promoting breast cancer metastasis. [SP=53 Cap=92m]
Fulcrum Utility Services (FCRM) activity levels now returned to pre-COVID levels. Order book up 5% at end Aug. [SP=36.5 Cap=81m]
Joules (JOUL) Q1 rev ahead of the Board's expectations at £39.6m, down 18%. Net cash of £8.5m, significantly ahead of mgmt expectations. Inventory down 16%. [SP=91.14 Cap=99m]
Bigblu Broadband (BBB) wins tender to provide fixed wireless access across Lincolnshire at a cost up to £8.1m, grant up to £6.1m. [SP=86.33 Cap=50m]
Hornby (HRN) 5 months to Aug sales and margins up and higher than internal budgets. [SP=32.36 Cap=56m]
Ilika (IKA) framework agreement with the UK Battery Industrialisation Centre for the production of co's Goliath solid-state pouch cells. "Will support the of scale up of Ilika's production of large-format solid-state lithium-ion cell technology, which has the potential to transform the performance and safety of domestic appliances as well as electric vehicles." [SP=81 Cap=112m]
St James House (SJH) trading of various divisions. [SP=40.5 Cap=2m]
ECSC (ECSC) H1(June) rev flat, pretax -£340k (-£558k). "We have so far exceeded our stated objective of maintaining a break-even Adjusted EBITDA position throughout the COVID-19 crisis." [SP=60.5 Cap=6m]
In line: SDI (LON:SDI) First Property (LON:FPO) Hardide (LON:HDD) Staffline (LON:STAF) Cloudcall (LON:CALL)
Morning Paul.
Cambridge Cognition:
Thanks for your reply yesterday.
I have a call arranged with CEO Matthew Stork and also CFO tomorrow morning.
Do you or anyone else have any questions?
I hold
Michael
Hello, todays link are now pointing at the www.londonstockexchange.com. I dont know if this makes a big difference to people or if theres a group preference, but i now have 3 scripts to different websites for full backup. I still dont know how i can monetize this, or if i ever will. Anyways, cheers! :)
Since you are posting this on Stockopedia it would be polite to link to the relevant news item on Stockopedia, if available.
Morning Paul, Loopup please as their update today looks really interesting.. many thanks!
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.
interims on LOOP (LOOP UP) today. Might be a few surprises in there. A Paul analysis on todays announcement would be appreciated.
crikey, just had a read through the results.... does not get much better than that!!!!