Small Cap Value Report (Wed 25 Apr 2018) - BOO, W7L, CLG, BEG

Good evening/morning, it's Paul here.
There's no rambling introduction today, pondering life, the universe & everything!
Mello Derby
I'm getting into a frenzy, trying to prepare for Mello Derby. I think there might be a handful of tickets left, so if you can join us, here's the link.
The quality of the companies presenting is far higher than any other investor show. The reason being that David Stredder hand-picks companies that are known to be decent. Also, he refuses entry to the spivvy junior resource stocks which usually want to come along to investor shows. So the theme with Mello is very much quality, ahead of commercial considerations. Isn't that refreshing!
Someone said that a lot of the speakers are the same as in 2014. That's true to a certain extent, but we're not going to be saying the same things! Graham and I will be dragged on stage at 9am this Thursday & Friday, to do Small Cap Value Reports live. Whose idea was that?! Grrrrr! Still I'm sure we can have some fun, providing I'm supplied with enough coffee & bananas.
My main presentation will be a review of the last few years in small caps - things I've learned, interesting themes, opportunities & threats, etc. Hopefully that should be interesting too. Although at this stage I only have 2 pages of rough notes, so need to flesh that out into a proper talk very soon.
As I'll be preparing for Derby, and travelling there tomorrow, this report will have to be a bit shorter than usual.
A big thank you to those of you who kindly donated to Brian Basham's prostate charity London Marathon donations page. He emailed me today to say how much he appreciates our support. Also, I'm delighted that readers here chipped in a decent amount, so thank you from me too.
Boohoo.Com (LON:BOO)
Share price: 177.6p (up 15% at 08:26)
No. shares: 1,149.5m
Market cap: £2,041.5m
(at the time of writing, I hold a long position in this share)
Final results - for the year-ended 28 Feb 2018.
This is a leading online fashion group, currently with 4 fast-growing brands - BooHoo, PrettyLittleThing, Nasty Gal, and BooHooMan.
This share occupies a special place in my heart, as it was a stupendous performer for me, and many readers, when we spotted the wonderful buying opportunity at 24p, in Jan 2015 - after a profit warning.
Today's results are sparkling, and look well ahead of market expectations.
Adjusted diluted EPS came in at 3.23p, well ahead of forecast of 2.78p
There's a broker update note on Research Tree, which confirms the out-performance. It also raises its current year forecast by 12% to 3.68p.
Given that the company has a history of beating forecasts, sometimes by a lot, then I imagine the out-turn for this year (ending 02/2019) would probably be nearer 4.0p EPS.
If I'm right about 4.0p EPS for this year, then at the current price of c.177p, the PER is 44.3 - expensive by normal standards, but good value for a rapidly-growing, decently profitable eCommerce company. It's cheaper than Asos (where I have a short position), which doesn't make any sense to me - given that BOO is growing faster, cash generative, and makes a much higher EBIT margin than Asos.
Other key points;
Balance sheet is strong, with net cash of £133m
Warehouse automation is coming in, with quick payback. This should drive margin improvements in future. Criticism of working conditions sounds wide of the mark;
We have also opened substantial employee welfare facilities at the distribution and customer services centre, which includes a gym, exercise studio, leisure facilities and subsidised canteen.
Cash generation is very good, but flattered by favourable working capital movement (increase in trade creditors). The business model has an inherently positive cashflow bias, because goods are sold online for cash, before the suppliers have been paid. So growth actually improves working capital.
International growth is impressive - especially in the USA.
Outlook - sounds encouraging;
Trading in the first few weeks of the 2019 financial year has made a strong start. Group revenue growth for the next financial year (FY19) is expected to be 35% to 40% with adjusted EBITDA margin between 9% to 10% and capital expenditure of £50 to £60 million.
GDPR - these new regulations, over data privacy, are coming into force shortly.
Worries about this could well be behind the considerable fall in BOO shares since last summer. Although looking at the chart, it strikes me that the price overshot in what was then a raging bull market;
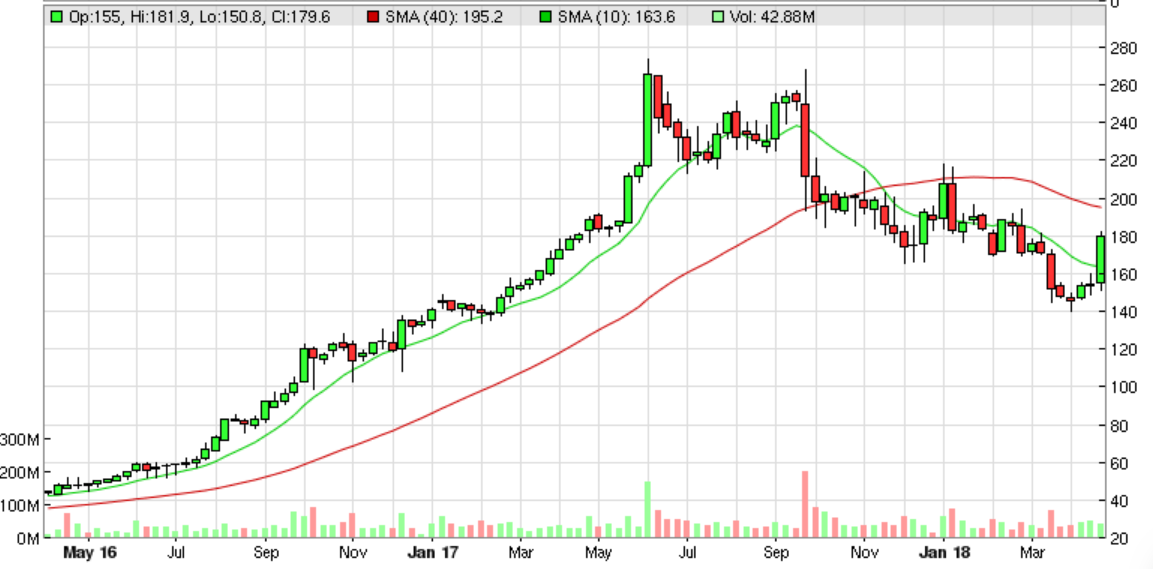
I put the question to BOO management today, and was reassured that they're on the case with GDPR. They don't see it as a worry, although didn't give me any specifics on how they're dealing with it.
My opinion - I'm kicking myself for reducing my position size recently, over GDPR worries, and also the downward drift in the share price. Other investors may not be aware of how incredibly ambitious this group is. They're seriously disrupting the High Street, with lower prices, and a much faster product cycle of "test and repeat". I think there is still a role for High Street clothes shopping, as it's more instant, and enjoyable as a leisure activity. However, the best online operators such as BooHoo are grabbing more market share, which is bound to cause some weaker High Street operators to disappear over time.
Overall, I'm very happy to hold, and will be adding more to my position if the price drifts back down again.
I'm listening to the results webinar now. Lots of interesting points;
- Low customer churn is impressive, at only 13% p.a. - so this group has a loyal customer base - which reduces my concerns about GDPR hurting the business.
- Use of celebrities, musicians, bloggers, etc - reach customers in new & engaging ways.This is also a barrier to scale for competitors, as they can't afford to pay top celebrities.
- Instagram is becoming very important, and customers can now buy product through it.
- "Well on our way to dominating this space in the UK" - i.e. youth fashion.
- Investing in many areas - distribution, IT, product designers
- Burnley warehouse(s) will be able to handle £1bn net sales by end of this year, plus big new extra capacity for PrettyLittleThing in Sheffield, with Clipper Logistics.
- Longer term plans to grow to £3bn annual sales
- 35-40% sales growth expected this year
- Medium term growth - at least 25% p.a., and 10% EBITDA margin
- Adjusted EBITDA margins 9-10% this year
- "Only scratching the surface of our potential in international sales" - better & faster delivery, and hassle-free returns - "massive opportunities overseas".
- Re-platformed websites to "demandware"(???)
- We're taking market share by being so competitive on price, but we still have good gross margins
- Long Q&A session, but not a single analyst asked about GDPR! Very surprising
Warpaint London
Share price: 192.5p (up 1.3% today, at 9:54)
No. shares: 76.7m
Market cap: £147.6m
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands, is pleased to announce its audited results for the year ended 31 December 2017.
These figures don't look madly exciting.
- Pro forma adjusted EPS is up 8.0%, to 9.4p - this seems behind forecast, of 9.8p
- This gives a historic PER of 20.5 - seems expensive for limited earnings growth
- Forecast for 2018 is 13.1p EPS, which reduces the PER to 14.7
- Very good operating profit margin of 22.8% (pre-exceptional)
- A large acquisition ("Retra") was made end Nov 2017, which is probably why earnings forecasts for 2018 show stronger profit growth. Retra is heavily weighted to H2, which will affect group results in future (increased H2 bias)
Positive outlook comments -
"After a successful first year as a quoted company, we look to the future with considerable optimism. We have had a promising start to the current year, in line with the Board's expectations, and with a sound financial base, including net cash, prospects are encouraging.
I believe we are well positioned to continue to deliver increasing shareholder value in 2018 and the outlook for the Group remains positive."
Balance sheet - is excellent.
Intangible assets have shot up, due to the acquisition, from £1.9m to £18.6m.
NAV: £40.4m
NTAV: £21.8m
Current ratio: 5.5 - this is extremely high, which I think is probably distorted by the acquisition made near the end of the year. This is because the acquired company's inventories & receivables are included in the year end balance sheet, but there wouldn't have been much impact on the P&L.
Share capital has risen, indicating that new shares were issued. Checking the archive of RNSs, in Nov 2017 the company did a placing of £21.2m (before costs) to fund the acquisition. I like this, it's a nice prudent way of doing things. Although an increased share count will inevitably dampen EPS in future years, compared with if the acquisition has been debt-funded.
My opinion - I can't get excited about this share - possibly because I know nothing about its market.
It looks a reasonably good business - with a very strong operating profit margin, and a great balance sheet. If it achieves 2018 forecast earnings, then the PER would be reasonable.
Overall then, it might be worth a look, if you understand the sector.

Clipper Logistics (LON:CLG)
Share price: 456p (up 3.6% today, at 10:57)
No. shares: 100.4m
Market cap: £457.8m
Trading update & new contract win
Clipper Logistics plc ("Clipper", "the Group" or "the "Company"), a leading provider of value-added logistics solutions and e-fulfilment to the retail sector...
It's an in line update;
Clipper is also pleased to announce that trading for the year to 30 April 2018 is expected to be in line with the Board's expectations, with continued growth in revenue, operating profit and net earnings. Results for the year are expected to be announced in July 2018.
Also, a new contract with PrettyLittleThing (part of BooHoo group) is announced, for a large warehouse in Sheffield.
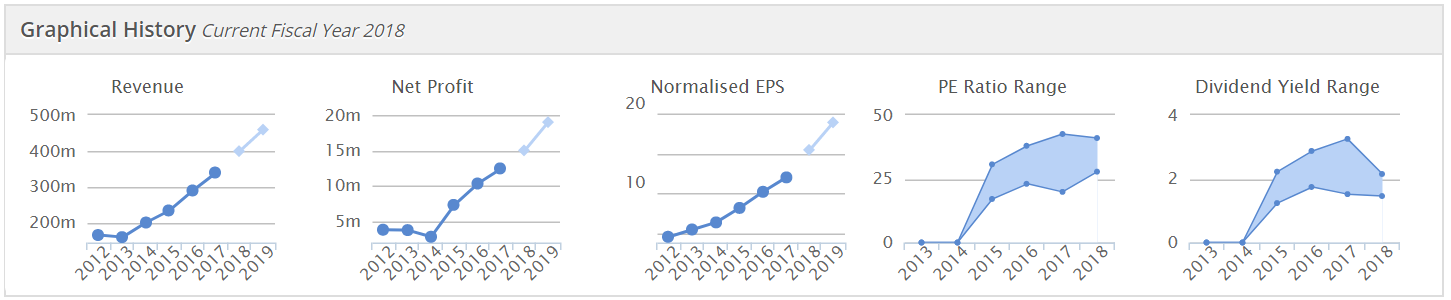
Clipper has an excellent track record, as you can see;
As you would expect, a strong track record means the shares are not cheap;
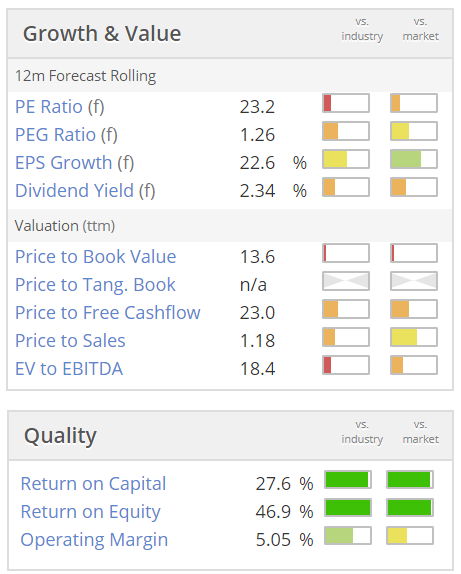
My opinion - this company seems to be providing services which are attractive to retailers, and eCommerce businesses. Therefore the growth of the latter gives a lovely tailwind to Clipper's figures, as its customers grow strongly.
The PrettyLittleThing contract win is impressive, as it's a shrewd customer.
Logistics is becoming an interesting area, as it's seeing increased automation. This means that small companies with manual procedures are likely to be driven out of business by more sophisticated operators like Clipper.
It's looks interesting, and is one I'll keep an eye on.
Begbies Traynor (LON:BEG)
Red flag report - rather a strange report this quarter. The writer seems to have decided to use the report as a way of blaming all company problems on Brexit. It may be a factor affecting some companies. However in reality, I think many companies in financial distress are actually suffering from;
- over-capacity, particularly in sectors like hospitality & retail
- online disruption - which is harming many traditional sectors, including estate agents, retailers, etc
- slow payment by large customers, damaging cashflow
- insolvency of Carillion, which hit many smaller subcontractors
- Government & EU regulations, creating never-ending red tape
- Rising business rates
- Above-inflation increases in minimum & living wage, plus apprenticeship levy, and workplace pensions
Many smaller businesses are focused on those issues, and don't give 2 hoots about Brexit.
If Begbies has decided to politicise its red flag reports, then I won't bother reading them in future.
Anyway, whether Article 50 is the main factor or not, the figures are not good;
According to Begbies Traynor's Red Flag Alert research for Q1 2018, which monitors the financial health of UK companies, 477,210 businesses were experiencing 'Significant' financial distress at the end of March 2018, up 33% compared to when Article 50 was triggered on 29 March last year (Q1 2017: 358,943).
I have to leave it there due to time constraints.
Hopefully see lots of you in Derby!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Thorough write up on Boohoo.Com (LON:BOO) in Phil Oakley’s weekly newsletter at the attached link:-
https://download.sharescope.co.uk/doc/2018_04_26.pdf
Also covers Lok'n Store (LON:LOK) and Ab Dynamics (LON:ABDP) this week. Some of you might have had chance to catch up with him at Mello.
Gus.
There are loads of sensible points in that Begbies red flag report. You just don't like the message, which is that Brexit is causing a lot of damage already and will continue to do so.
I too hold a position in Boohoo.Com (LON:BOO) and pleased to see the performance. They have re-platformed to demandware Paul (now called salesforce commerce cloud) which is enterprise level as you would expect for this size of business.
As someone also going through GDPR compliance in my day job in the e-commerce world I don't see this as a big threat to Boohoo and certainly not the reason for the share price falling since last year. I actually see high street business trying to capture your details when you buy in store as more of an issue than a pureplay ecom business. If they've been compliant all along (no pre-ticked opt-in boxes for instance), then there isn't any risk to the email list size and their current privacy policy looks fairly comprehensive. You've also got the issue that the ICO (who are going to be 'enforcing' this), have openly admitted that they don't have the resource to go looking for companies who are falling foul of this once it becomes law. There will be individuals with more time on their hand than they know what to do with making life difficult for businesses but I don't think this is the immediate smoking gun that many fear. Anyway, this is too long a dull GDPR message!
A confident holder here, but I'm not adding as my portfolio is small and I don't want too much exposure to a single share!
I hadn't appreciated that Clipper Logistics are a quoted company. FWIW, the Sosander team explained at the UKIS on Saturday that Clipper are also their logistics solution provider. As an overall model it's an interesting approach to assist small companies in taking on Amazon.
I managed to get a small position in Water Intelligence (LON:WATR) , but it does seem clear that there is not much liquidity, so perhaps a small position is the place to be from a risk management perspective
.
On the downside, I had to pay more than twice the price that when I first rejected this as an investment about six months ago on the basis of not likely the Directorspeak and particularly what seemed like too much focus on the top line and not bottom line. So well done to Effortless Cool who I know has been bullish for quite some time.
I have no luck. I have been trying all morning even down to £500 worth.
Thanks, Gromley.
Liquidity comes and goes in Water Intelligence (LON:WATR) - I was able to buy almost 8000 shares in one block this lunchtime. The trick is to be patient and grab the liquidity when the opportunity presents itself.
Yes finally managed to grab a few just before close.
See you all for a great time together in Derby....
Just 24 hours to go to Paul and Graham live in Derby.....There is still the chance to join us before the start of #Mello2018 We have just 23 places available for Thursday & 41 left for Friday so if any of you need a ticket for either or both days the Mello team are happy to offer one day tickets for just £30 ( normal price £69) using this link https://mello-offer30.ticketswitch.com/4FHW-mello2018
If you want to come both days you can always buy two !
Those tickets allow you into the pre event entertainment tonight so why not join early and avoid the queue tomorrow. The place will be positively bouncing with investor energy.
David
Water Intelligence (LON:WATR)
Any thoughts on this company from the community.
Had a read through update - very positive market reaction.
But based on 0.6m for Q1, they should be on course for $2m full year which is 80% ahead of estimates (2018, stocko).
On that basis, we have forward PE of 18 (before today's rise) and current closer to 25, for a business that seems to be growing at 30 - 40% bottom line and is well funded (I think).
No position and I am not comfortable with valuation given market cap, but with these number's at yesterday's valuation - a screaming buy??. Whether, we get back to that price - would people pay up here?
Any insights on competition? Has potential to become a Somero Enterprises Inc (LON:SOM) (or maybe that is just the US association!).
Many thanks for any views in advance.
sharmvr,
Is Water Intelligence (LON:WATR) "a screaming buy??". I certainly think so, to the extent that I had already bought over 0.5% of the company and added more on the back of today's trading statement.
My full reasoning is set out in this thread, (which I will update after the full-year results are published) ....
https://www.stockopedia.com/content/water-intelligence-the-long-story-195763/
.... but, to summarise:
- genuine small cap, with multibag possibilities;
- already profitable, with rapidly growing revenue (40% in 2018 q1);
- annuity-like income from franchisees provides robust downside protection; and
- franchisee base provides strong foundation for investing in high growth areas, either by generating reliable cash flow to plough into other divisions or through the opportunities from buying up the franchisees themselves.
It has also been almost entirely overlooked by the market so far, and will inevitably be picked up by some tipsters in due course.
I'm sorry if this all seems a bit fervid, but Water Intelligence (LON:WATR) is the most exciting small cap opportunity I have come across since Lo-Q (accesso Technology (LON:ACSO) nowadays) and I intend to make the most of it.
Thanks for this - and certainly the thesis from your article seems to be playing out, with your and market forecasts being beat. Added bonus, a real world problem being solved.
I see enough to open a start position with hopefully better entry points and actual financials to make bigger if think worthy.
Struggling to get a quote! I can't get a price through HL, tried for 1000 / 2000 / 4000 - nada.
Even smaller amounts not possible, I have come across this before with Water Intelligence (LON:WATR). I think a "fill or kill order" is the best way.
Fill or Kill pending - not expecting a fill, given I am being quite stingy. Looks like there is a market at 100 shares at most, but then spread and trading costs would be approaching 20%!
Effortless - I think I can see your 8 k - 7960 @ 251.09?? - clearly one of the whales moving the market!!!!
Thank you all for your responses/insights/suggestions
Agree with much of that but..........
The technologies, acoustic, thermal, etc are pretty much available to anyone, I don’t think they really have anything that different to other companies from a technical standpoint. What they do have is a franchise model working well that has allowed them to expand. Furthermore margins seem to be declining, the cash flow seems to be eaten up by capex and their UK leak detection business, Target Leak Detection, seems not to exist in any meaningful form (link from their website is broken and google search produces nothing of substance).
I think that this is mainly a bet on the further success of their franchise model in the USA and I find the prospects for that hard to evaluate.
I find this more like evaluating a pizza franchise business than a construction equipment business like Somero. The model has clearly worked so far, is there info on their market share and how many areas they have with no franchisee available?
Graham,
I'm don't know about Target Leak Protection - their website definitely needs updating in that regard. The Water Intelligence (LON:WATR) UK business is NRW Utilities, which they bought in 2016. It is small, however, and the vast majority of the business does indeed come from their US franchise model.
Note that the cash flow is being deployed to fund investment, mainly in buying up franchisees. The nice thing about this aspect of the business is that the franchisees take the risk of building each franchise but then Water Intelligence (LON:WATR) can, to some extent, pick and choose regarding where it can most beneficially bring a franchise back in-house.
I sold my Water Intelligence (LON:WATR) over concerns about valuation, equity issuance and some very rampy language in their Q4 trading update. I disagree about it being overlooked by the market since I made over 50% in 2-3 months. The Q1 trading update seems much more level headed and I may yet buy back in.
10 year US treasury yield above 3% could lead to some renewed February-style volatility
countrywide (LON:CWD) Q1 rev -10% FY18 consensus -2%. going to be hard work to reach that! short
“There's no rambling introduction today, pondering life, the universe & everything!“ What a shame! :-) but as a long term (well three years) holder of Boohoo.Com (LON:BOO) (it is 12% of my portfolio and my third largest holding and I have not sold any in the recent sell off) I am pleased to read your comments.
I am going through GDPR pains with my own company and my view is that this is a pain in the arse (and was initially deeply worried and negative about it) but now feel that worries have been wildly over done and that once things have settled down, it will probably be of net benefit to business in terms more trust from customers and a more engaged, if smaller, customer base and target market.
Do you know if Graham’s and your live SCVR’s at Mello Derby will be videoed and available on YouTube at some point, for those who cannot get there?
Thank you.
Michael
Morning all,
Sorry but I'm too busy to take reader requests today.
I'll cover what I can, then have to travel up to Derby for Mello 2018.
Best wishes, Paul.
Your view on Keystone Law (LON:KEYS) would also be appreciated. KEYS today issued their maiden set of full year results since their IPO in November 2017.
Keystone Law (LON:KEYS) is definitely an interesting business model, its profitable and seems to be delivering.
I think today was an inline FY report, back in the Feb trading statement the company said they would be comfortably ahead of market expectations - the house broker promptly increased these expectations (which have been met today). Expectations are pretty high for FY19, need to hit over 30% revenue growth and 40-50% net profit growth.
I'm happy to continue to hold because the results look good, but i wouldn't add as the company is appropriately priced. If they were more aggressive in their growth targets (revenue growth hits 60%+) and they maintain their gross margin of 28%, then that would be a single to invest more (for me). The positive aspect is this could be achieved as they are starting this year from a low base of lawyers (266) and the business model seems scalable.
So i will be very interested in their next trading update likely due in later summer (my estimate).
£W7L announce results. Seem to me to miss most of the forecast targets on their Stock Report.
Looking forward to the report being updated.
Edit:
Any of you clever people know why the ticker trick didn’t work for this share?
The system does not like mixtures of letters and numbers.
Clipper Logistics (LON:CLG) announce what sounds like a huge contract to provide logistics for PLT from a new Sheffield warehouse starting July.
Clipper’s share price jumped from 380 to 440 last week. What a coincidence :/
Posted for information rather than inviting comment, here’s a link to the latest Begbies Traynor (LON:BEG) “red flag” report on the state of small cap UK PLC.
https://www.investegate.co.uk/begbies-traynor--beg-/rns/latest-red-flag-alert-report-for-q1-2018/201804250700129982L/
Pretty downbeat assessment with various headwinds identified and a few icebergs on the horizon.
Gus.
My morning smallcap tweet: Mission statements don't make money.
Countrywide (LON:CWD), Franchise Brands (LON:FRAN), Water Intelligence (LON:WATR), Crawshaw (LON:CRAW)
Countrywide (CWD) Q1 rev down 10%. "The Group has moved swiftly to restore expertise in Sales and Lettings following the appointment of Paul Creffield as Group Operations Director...In Sales, we have seen an improvement in both the register of properties available for sale and in our market share of listings compared with Q4 2017. In Lettings, our share of listings is also ahead of Q4 2017." I'm short.
Franchise Brands (FRAN) Q1 trading marginally ahead of management's expectations. No of jobs completed by Metro Rod and Metro Plumb up 16%, although the average order size was slightly lower.
Water Intelligence (WATR) Q1 rev up 40%, pretax up 50%. "Comfortably in-line with our expectations."
Crawshaw Group (CRAW) FY rev up 1%. Pretax pre exceptional & write offs -£1.9m (-£1.4m). Recent 12 weeks: high street has remained challenging but factory shop format continues to perform well. "Our Mission: To use our expertise to source, prepare, produce and retail quality fresh meat products at a price and a service level that continues to delight our customers." You are just a butchers. What about delighting shareholders?
Boohoo.Com (LON:BOO)
Revenue: +97% (+92% constant currency) vs guidance +90% (next year's guidance 35-40%, medium term 25%+)
EBITDA margin: 9.8% vs guidance 9.25% to 9.75% (next year's guidance 9-10%, medium term 10%).
So that looks like a slight beat with a reasonable outlook. My concern is over diluted EPS of only +25% and whether there are one off factors this year which may point to a better performance next year. I'm looking into this although they did of course issue more shares and amortisation of acquired businesses is noted.
Edit: It looks like PLT was bought near the end of FY2017 and so the first significant amortisation was FY2018. Trademarks are amortised over 10 years, customer lists over 3, thus thus the relatively high charge. £4.5m is shown as amortised for PLT and NG, so I think you could add that back in which I make a 0.4p adjustment and about 40% "true" EPS growth (not stripping out share based payments or anything else that might repeat). So while the true EPS is the unadjusted 2.71p, the same performance next year would result in a genuine 40% growth. And in 2 years time you will get a one-off jump as the customer lists are fully amortised.
High growth seems largely dependant on PLT which in turn seems to be dependant on celebrity endorsements, which are a more fragile way of gaining business than I would prefer.
Thanks leoleo73 for the analysis on Boohoo.Com (LON:BOO), very interesting, and all in 23 minutes!
Paul,
Your view on Water Intelligence (LON:WATR) would be much appreciated. Q1 trading statement out this morning, with revenues up 40% and profits up 50%.
https://www.investegate.co.uk/water-intelligence--watr-/rns/q1-trading-update/201804250700110078M/
Morning!,
Can I suggest £CCY today? interims out SP down a little. I hold! Looking forward to Boohoo.Com (LON:BOO) 0 where I bought just recently, thinking I had a good entry point!
I too will be at Mello - looking forward to your sessions tomorrow Paul although I'm going to struggle to make the 9am one!
I do hold Boohoo.Com (LON:BOO), and will be interested in the results, but I don't think I will care what they are. If surprisingly bad, the price will fall and I might buy more. Otherwise I will just stick. I'd only consider selling if something emerges that challenges what I think I know.
This doesn’t look good. Let’s hope it’s just a pop up....
https://mobile.twitter.com/UmarKamani/status/988866765294850048
Hi IGotPoesJacket
Re;
This doesn’t look good. Let’s hope it’s just a pop up....
https://mobile.twitter.com/UmarKamani/status/988866765294850048
Can you explain what you mean and why?
thank you.
Sure,
I was speculating that results might have details about them moving into bricks and mortar shops, which I think would've been damaging to the share price in the short term.
Speculation is fine if it's well reasoned. However you failed to say what Umar Kamani said on Twitter to this speculation. To quote, he tweeted "who said it's a shop".
I agree.
It was after market close, before results.
Nothing in the results about a change of strategy so, as Boo makes 40% of my holdings I am happy with that.
But if it’s not a shop, what is it? And why bait people the night before results?
Boohoo.Com (LON:BOO) Thanks IGotPoesJacket. I would be surprised but it is necessarly a negative if they do. It can raise brand awarness if the right place. Seems to work for Apple!
And look at the responses to the Tweet the idea seems to be well received.
https://twitter.com/OfficialPL...
Hi Purpleski,
In the long term, and if they pull it off, I agree it could be “a nice little earner” (sorry - been watching Only Fools and Horses repeats).
But in the short term, with the share price coming under pressure which is claimed is due to fears of margin slippage and increasing costs, plus with what we have seen happen to High St in the UK, I think a move to bricks and mortar would have been received negatively by Mr. Market.
The UK leads the world in e-tailing. I think this is due several factors; the fact the UK is small, logistics are relatively easy and resultant delivery costs are thus relatively low, essential for offering free returns.
Getting into shopping areas on a weekend is a complete pita, most town/city centres and retail parks become car parks way before you park your car.
The UK has some of the best IT solutions capability. I work for a big software company as a consultant, as far as I can tell most major companies, even some of the big American and European ones, run IT operations out of the UK, we’re the best at it, the fact the UK is the biggest market outside America for licensing and services tells you everything you need to know.
I believe Boohoo.Com (LON:BOO) have an announcement scheduled.
I think the share price has fallen back to a level where the valuation is interesting, providing they are maintaining high growth.
Disclosure: No current holding, but have held previously.
Tern...lots were asking about this soaring stock yesterday.
I have been buying tern this year since 2p and also bought plenty in a recent primary bid share placing at 6.6p. Been selling quite a few and got 16.75p today for more than an 8 fold on my cheapest buy. Happy days. It closed above 18p tonight. Tern is a majority holder in a company called Device Authority (DA) which looks to have some excellent technology. Some think a huge bid for DA is on the way from the US. Tern is very volatile.....it previously rose from about 0.8 to 26p a couple of years ago...I think I cashed in at 15p.Then it fell all the way back.
Tern has little or no cash and will probably need to raise funds or maybe do a placing soon. I think it may hit 25p or even higher but just on momentum and I notice the big hitting bears are now taking an interest. The price is now well ahead of events in my view with mkt cap of approx. 35 million against 10 million in assets but of course that does not mean it won't double or treble again! DA might just be a life changer and the company has been very quiet in the face of this huge rise although pushing out news daily so will hold some of my now free stock long term but it may just fall away to oblivion too.
I have to laugh because I had a twitter battle today with Tom W on tern. I pointed out that share prophets has always got this one wrong. They were telling readers recently to sell out at about 1.88p and less. It happens of course; I was merely pointing out that they publicise when they get things right (which they do in fact...on the Chinese duds for instance) so should put hands up when they suggest selling the biggest winner in the Stock Market so far this year at its lows!
Former SCVR favourites Boo release results in the morning :D or maybe xD
OK thanks, I'll definitely take a look at BooHoo results in the morning (in which I hold a long position)
I'm a bit worried about what impact the imminent GDPR rules might have on companies like BOO, which rely heavily on email offers to stimulate customer demand. Hence why currently I'm keeping my position size fairly modest in BOO, so that a say 30% drop on a profit warning wouldn't hurt me too much.
Fingers crossed!
Paul.
Good morning Paul
I'm very much looking forward to Mello tomorrow and Friday. I will try to get to your 9:00am SCVR. Might still be in my pyjamas - 9:00am is a bit early for me too.
On Boohoo.Com (LON:BOO) your concerns about GDPR are interesting. Do they do much email marketing? Presumably their Twitter and Facebook advertising (via celebrity endorsements) should still be fine. The thing that worries me is how they are going to be able to continue to service a global business through a single warehouse (in Burnley). Won't that slow down delivery times outside the UK especially if Brexit (sorry to mention the dreaded B word but it might be relevant here) imposes additional paperwork and customs clearance requirements. I wrote in to Boohoo.Com (LON:BOO) to ask about this. A PR flunky sent me a friendly reply referring me to a note in the last results which said absolutely nothing.
See post 13 and the results RNS.
They have a huge new warehouse in Sheffield that PLT will migrate to from July.
Hi Julianh RE Boohoo.Com (LON:BOO) “Won't that slow down delivery times outside the UK” - my only comment on this is that they, Kamani and Kane, seem to have executed pretty well over the past 3 years and that they must have factored this into their model. It is a leap of faith I know but I trust management and assume that they will grow the company into their new facility. As for the B word I am not going there!!
On GDPR as I have mentioned elsewhere I think that this is a non issue medium term after the initial compliance issues have been resolved.
I hold.
Hi Paul
On Boohoo.Com (LON:BOO) /GDPR I do think it is over done on the worry front. My modest mailing list to which I have been sending newsletters for decades and on each one the recipient has had the opportunity to unsubscribe, is I think likely to shrink from around 7,000 to 1,200 maybe 2,000 if I am lucky. But I suspect that the 5,000+ that do not give consent were never going to buy my product (assuming the email is going to a live mail box) and that therefore I have not really suffered a shrinkage in the market that I am mailing.
As for retaining of data, again if I want to buy from Boohoo.Com (LON:BOO) and for that process to be easy and deliver stuff suitable for me, I am going to be happy with them holding some data on me.
That’s my penny worth anyway!!
KR
Michael
Hi Purpleski
Yes, it is pointless anyone having a mailing list of people who are no longer interested and I think some people are pleased to have a reason to cleanse their mailing list. However, I do think the whole issue has caused undue consternation. There is the get out of "legitimate interest" which can be the interest of the person holding the mailing list. Provided you are simply holding names and addresses of persons who may be interested in your product as opposed to holding their personal financial details then it is my opinion at least that there is nothing to worry about.
Hi doublelutz
Interesting. I read fairly widely on GDPR but has not seen the “legitimate interest” clause. I will investigate further.
Thank you
Hi Doublelutz
I just wanted to thank you again for this. It so helpful to me personally in my business but also generaly. I cannot tell you how relieved I feel.
Having read the ICO web site:
https://ico.org.uk/for-organisations/guide-to-the-general-data-protection-regulation-gdpr/lawful-basis-for-processing/legitimate-interests/
I am more than ever, like you, conbvinced that this thing has been over done.
Thank you.
Kind regards
Michael
PS Good old Stockopedia
No rambling commentary Paul? In the style of R. Woodbine Parish from El Oro: https://www.investegate.co.uk/el-oro-ltd--elx-/rns/half-year-report/201803151145018557H/
I only come here for the anecdotes - you know that!