Small Cap Value Report (Wed 25 Jan 2023) - STAF, SUR, PEB, CMCX, XPF, PDG, VANL, HVO, FNX

Good morning from Paul & Graham!
Today's report is now finished.
Sorry we didn't get round to doing everything, it's just too busy at the moment, so we have to prioritise.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Firstly, 3 stragglers from yesterday:
Staffline (LON:STAF)
33p - market cap £55m
Summary: FY12/2022 slightly ahead, cashflow lots ahead, 2023 outlook cautious. Broker slashes 2023 profit forecast by half.
FY 12/2022 underlying operating profit guided at £11.6m (up 13% on 2021), which becomes adj PBT of £9.0m, or 4.7p adj EPS.
Net cash £5.0m (but large working capital, so this could swing about a lot, I reckon - average daily net debt/cash would be more meaningful to report the true picture).
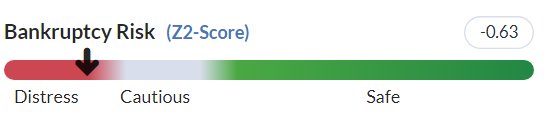
Claims balance sheet is strong, which it isn’t (so how can I trust anything else they say?) - last reported NTAV was negative at £(2)m. Zeus appointed to join Liberum as joint broker - why? Fundraising maybe? Altman agrees with me, not STAF management, with a Z-score that is alerting us to a weak balance sheet -
All was looking reasonably good, until I read broker update today - FY 12/2023 forecast slashed by almost half! (from 5.8p adj EPS to 3.1p) - a tiny sliver of profit, PBT margin is under 1% of revenues.
Says that macro conditions are worsening.
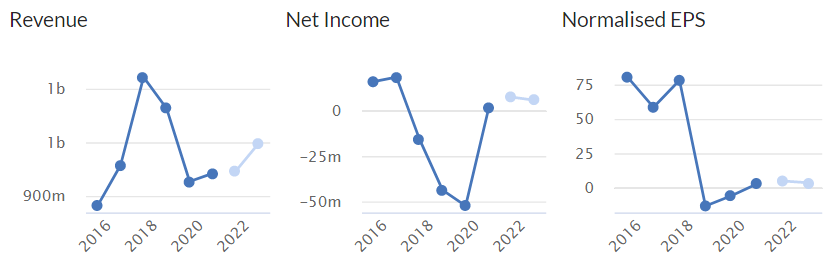
The wheels fell off in 2019 (pre-pandemic) as you can see below. Just after the former CEO had exited, banking his £10m at 1020p per share - not a typo (31x the current price!) leaving behind what turned out to be a shambles. See EPS graph 3 below - this is unlikely to ever recover to previous highs, because there are now 166m shares in issue, up from 34m in 2018, after a series of emergency placings to keep it afloat. Plus a generous taxpayer loan was key during the pandemic (deferred VAT, which has since been repaid).
My opinion - initially it looked interesting, but the mode I dug, the less attractive STAF seems. Overall, this looks a poor quality business, with no pricing power. Are they just busy fools? Historically there were loads of problems, and it’s not paid divis since 2018. There are much better shares in this sector to hold long-term, but as a short term trade, it might bounce at some point, who knows? On fundamentals though, I have to give it a thumbs down I’m afraid.
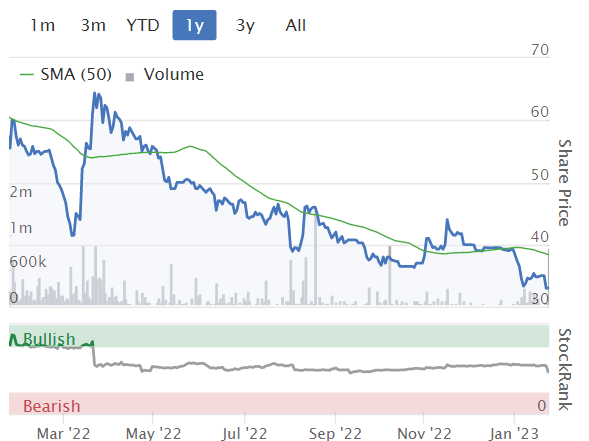
STAF shares have not participated in the recent everything rally, and note the deteriorating StockRank too -
Sureserve (LON:SUR)
87.5p (up 4% y'day) - mkt cap £146m.
I have a generally positive impression of this share. Although reading Graham’s brief notes here from Oct 2022, he reminded us that it’s a low margin business, in a competitive sector. Also the business (formerly called Lakehouse) had a lot of historic problems, which emerged about a year after its 2015 float. That's now receded into history though, it seems a better business now.
Results for FY 9/2022 are out.
Big increase in revenues, up 27% to £275m
Low gross margin
Few adjustments to headline numbers - good
PBT (continuing operations) £15.6m - up 41%
Discontinued operations £2.0m loss (vs £2.3m profit LY)
EPS diluted, continuing ops 7.8p (LY: 5.6p) - PER of 11.2x - looks priced about right.
Net cash £23.3m
Huge order book of £594m
Average contract length now 6 years - doesn’t seem to tie in with above numbers, revenues £275m, and order book of £594m is just over 2 years’ contracted work, surely?
Going concern statement - is fine.
Contracts mostly have inflation-linked cost clauses.
Current trading is said to be good.
Outlook - Board remains confident for FY23.
Balance sheet looks fine to me, ungeared, and with £19.3m cash. Clients are mainly local authorities, and housing associations, which tend to be good payers, and little to no customer insolvency risk. Sticky clients too, probably.
Dividends - historically divis were small, so it hasn’t got much of a track record of cash generation, but that’s improved in the last couple of years. So it should have the capacity to start paying divis, although not huge ones, judging from the cashflow statements. Nothing was paid in divis during FY 9/2022. The results commentary doesn’t mention dividend policy, which is a surprising omission.
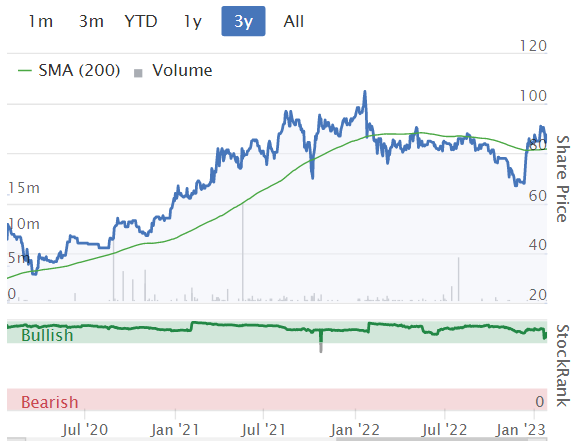
My opinion - no strong view either way. The revenues & profit growth are impressive, and I like the longer contracts being signed, which should give dependable income streams, and thus (hopefully) profits that repeat reliably, and hopefully continue growing. So is this a GARP (growth at reasonable price) share? I’d say it’s looking that way, so I’ll be more generous than Graham, and go green with my current view of this share.
Pebble Beach Systems (LON:PEB)
8.5p (up 6% y'day) - market cap £11m
Does software for broadcasters. FY 12/2022 TU - is in line with market expectations. Guidance: £11.2m revenue (up 6% on 2021), adj EBITDA £3.3m (LY: £3.2m), which the broker says is £1.7m adj PBT.
Order intake in H2 up 24% on H1, as trade shows opened up again. “Excellent visibility” for 2023, due to strong order book, and recurring revenues (no figures given). Bank debt has been too high previously, coming down, but still hefty for size of company at £5.8m net debt - but refinanced in H1 to Sept 2024. Expecting this to reduce further in 2023.
Last balance sheet is really weak, with negative NTAV of £(7.7)m, so it’s totally dependent on the bank, and really does need to raise fresh equity at some stage. So quite high risk, especially if trading were to deteriorate.
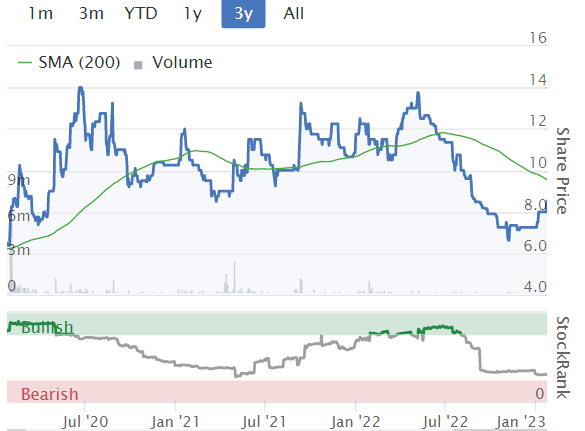
My opinion - if it didn’t have the debt, it would be much better. But it looks a decent enough, profitable company. The weak balance sheet does increase risk though. Revenue has been fairly static for 6 years, so it needs to scale up the growth to drive a big share price rise, in my view.
hVIVO (LON:HVO)
17.3p (up 16% at 09:59)
Market cap £116m
hVIVO plc (AIM & Euronext: HVO) (formerly Open Orphan plc), a rapidly growing specialist contract research organisation (CRO) and world leader in testing infectious and respiratory disease products using human challenge clinical trials, announces a trading update for the period ended 31 December 2022.
I don’t know anything about this company, or sector, so am approaching this with trepidation, and I’m purely looking at the numbers.
Historically, this company was a loss-making cash burner, and increased its share count 11x from 60m in 2017, to 671m now.
Scanning through the RNS, there have been 8 announcements about £multi-million contract wins in the last year, so something interesting seems to be going on here.
For background, here’s my quick review of the H1 results to June 2022 (published Sept 2022) -
H1 revenue £18.9m (down 19%)
FY 12/2022 guidance was for £50m revenues (as announced on 8 Sept 2022)
H1 EBITDA up 10% to £2.3m, a margin of 12.1%
Cash of £15.9m at 30 June 2022.
Does EBITDA turn into profit? Not really, with £2.3m EBITDA becoming only £453k PBT in H1.
Balance sheet - is it strong? Not particularly. NAV (at June 2022) was £20.8m. Take off £6.2m intangibles, to get NTAV of £14.6m, and that includes £7.0m “investment in associates”, which would need scrutiny to see if it has any real world value.
There was £15.9m cash, with no interest-bearing debt, but it looks as if this has probably come from customers paying up-front, as it’s more than offset by £23.7m trade & other payables (which is usually deferred income - customers paying up-front, for this type of business). So I would say it doesn’t really have any of its own cash that it could safely spend.
Cashflow statement - note that it puts £724k R&D Credit into other income on the P&L, and not as a negative tax charge, a way of presenting it that I’ve not seen before.
Is it capitalising a lot of costs into intangible assets? Good news here, it’s a no. Also, there was £0.9m of physical capex in H1, which is modest - so it seems a capital-light, know-how-heavy business model. Overall it was roughly cashflow neutral in H1, and the prior year FY 12/2021 figures show £3.5m of cash was used. So it was not a cash generative business, up to June 2022 anyway.
Latest update today - some very impressive stuff here in these headlines -

.
EBITDA of 17% on £50.6m revenues gives £8.6m. £1m of this was one-off cancellation fees, so underlying EBITDA is £7.6m, a 15.0% EBITDA margin, 9% above forecast.
Finncap (many thanks for crunching the numbers for us!) shows adj PBT of £5.3m, making this very much a breakthrough year for profitability - the key questions being (if you know the answers, please post a comment!) -
- How has this been achieved? (serial loss-maker suddenly starts winning loads of contracts & becomes profitable - great, but what’s driving that?)
- Are profits now sustainable?
The good visibility of contract earnings shown above suggests that things might continue to look good.
hVIVO claims to be a world leader - so we would need to know who the competition is, and what HVO is doing better, and will the competition erode HVO's advantage over time? -
The significant growth in revenue provides further validation of the long-term sustainable growth in the human challenge trial market, for which hVIVO is the world leader.
Outlook -
The Group has entered 2023 well capitalised, debt free, and with record visibility into the current financial year. hVIVO is firmly placed to build on the growth in the human challenge trial market and further strengthen its position as the world leader in the field. The growing orderbook from new and existing Big Pharma and biotech clients provides excellent forward visibility with over 95% of forecasted revenue for 2023 contracted, and further revenue visibility into 2024. The Board is confident that the Group will continue to leverage its competitive position amidst favourable market dynamics and maintain its strong operational execution, orderbook revenue conversion and focus on profit generation into 2023 and beyond.
That sounds like 2023 forecasts are likely to be raised, as new contracts are won.
Webinar - tonight at 18:00 on InvestorMeetCompany, so I’ll watch that to find out more.
My opinion - HVO has sparked my interest, so thanks to MrContrarian, richardho, davidjhill, and JanesKerr1 - who all flagged this share in the reader comments below, which is why I followed up on it.
As I know nothing about the sector, I’ll be looking to you for guidance on the company, not the other way around! From my perspective though, I can see potential in these numbers, and am tempted to dip my toe in, with a starter sized opening position. So I’ll go green, and give it a thumbs up.
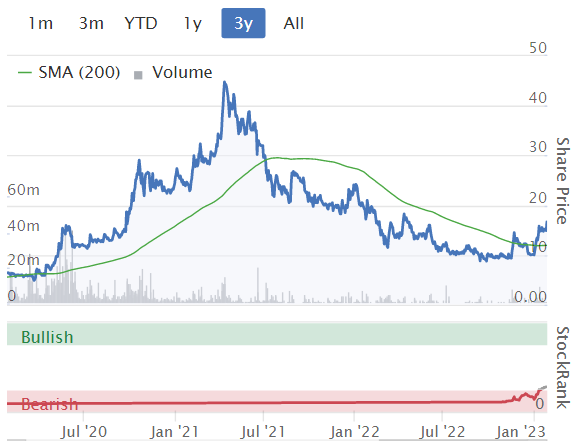
Note that the very low StockRank is starting to creep up - expect that to rise a lot, I'd say -
Brief comments -
Fonix Mobile (LON:FNX)
Fonix Mobile - down 2% to 219p - mkt cap £220m - FY 6/2023.
H1 Trading Update - this needs to be good, because Fonix shares are quite aggressively priced (based on existing forecasts, fwd PER is 24.6x).
I won’t go into the detail, but this all sounds fine to me. “Largely unaffected” by consumer spending. International expansion is “particuarly encouraging”, and could drive further growth, and it says “incurring minimal additional overhead”. H! EBITDA up 12% to £6.2m. Strong cashflows, so will increase divis. High repeating business, and very sticky clients, as mentioned before here in previous reviews. Significant new clients launching imminently.
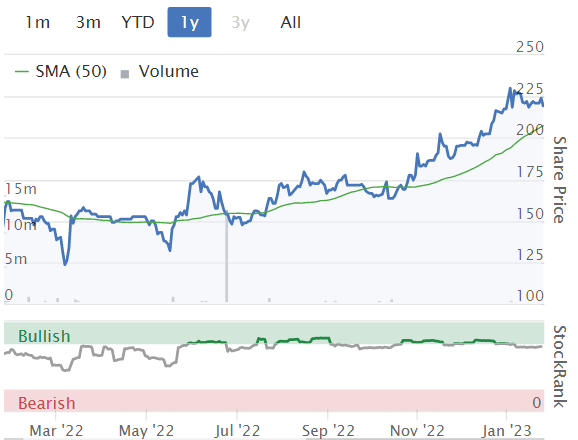
Thumbs up from me, this looks good, but remember it’s not cheap, so would probably fall a lot if future performance were to disappoint. So far though, so good!
Graham’s Section:
CMC Markets (LON:CMCX)
Share price: 243.5p (pre-market)
Market cap: £681m
Full disclosure - I’m a shareholder in IG group (LON:IGG) who are CMC’s biggest rival. IG is my third-largest position. You may wish to bear this in mind!
Today we have an update from CMC for the period 1st October to 23rd January. The financial year for the company is at the end of March, so this is Q3 and the beginning of Q4.
The main point is that net operating income is tracking in line with expectations, and expectations for operating expenses are also unchanged.
While net operating income was weaker towards the end of the calendar year, it has recovered strongly in January. Monthly active clients, client money ("AuM") and assets under administration ("AuA") in our investing and trading businesses remain stable versus H1 2023.
I wonder if the World Cup was a distraction from financial trading at the end of the calendar year?
Strategically, CMC UK Invest (their share dealing platform) has expanded its offering, and CMC Singapore Invest is moving towards launch.
I was previously very excited about the spread betting companies launching share dealing platforms. However, it’s worth noting that share dealing itself is not very profitable for these companies, at least not compared to spread betting! So I think the value is more to do with the cross-selling of more profitable products, and getting users into the habit of logging in.
To give you an example of how profitable spread betting is, I recently investigated the overnight cost of holding a daily rolling spread bet, to see whether it could possibly be used as a tax-free alternative to buying physical shares.
It turned out that the bid-ask spread was the least of my worries! I calculated that the holding cost of the position was nearly 6.4% p.a. of its notional value, i.e. utterly prohibitive for someone trying to make a “normal” investment in this way. But you can imagine that with so many customers holding so many positions with large notional values overnight, these charges are wonderfully lucrative for the spread bet platforms.
Anyway, let’s get back to CMC and the commentary by Lord Cruddas (Founder, CEO and 59% shareholder):
2023 is set to be an exciting year for CMC as we continue our growth strategy. Our core initiatives of product expansion, new trading analytics, new pricing functions and enhanced onboarding initiatives remain on track across both our investing and trading platforms. Expansion of CMC Invest continues, with UK marketing spend accelerating over coming months coinciding with delivery of a steady stream of new products and functionality.
My view
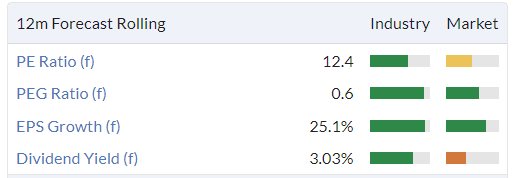
Despite being a long-term IG shareholder, I also view CMC as a high-quality business (see its ROCE/ROE scores) and I think the market is being overly sceptical by awarding it these valuation metrics:
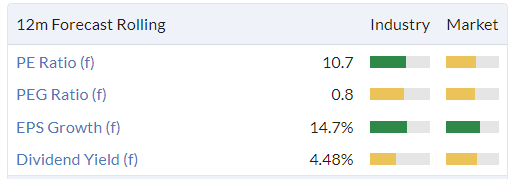
The StockRanks also think it looks good:
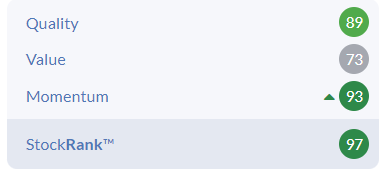
In October, I discussed some of the key themes around the stock, and why investors may be sceptical. One of these was volatility and whether it might fall back to pre-Covid levels.
Here’s the latest reading from the VIX (Volatility Index): 19, which is still above pre-Covid levels. Spread bet companies have been great beneficiaries of the volatility boom since 2020:
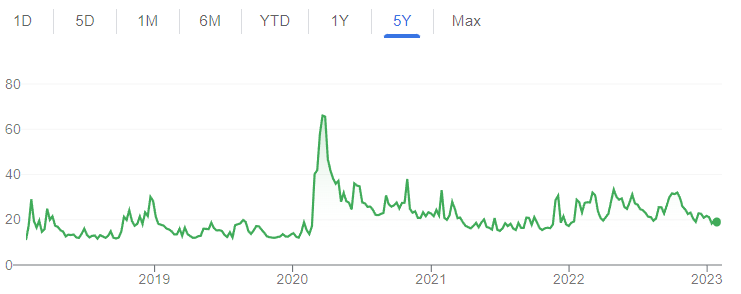
Given the macro forces at work (e.g. US government debt at $31 trillion, inflation, interest rates), I personally don’t see volatility returning to “normal” any time soon. But nobody really knows!
So for me, this is a quality company that’s trading well and is probably too cheap. Although not without risks, of course.
Pendragon (LON:PDG)
Share price: 20p (+2%)
Market cap: £279m
This motor retailer issues a full-year update for 2022.
Performance is slightly ahead of expectations, with underlying PBT of c. £57m (versus expectations of £53m - £55.3m).
The reasons given:
Trading during [Q4] was underpinned by strong volume growth in new cars, with the Group delivering like-for-like volume growth of 4.6%, and outperforming the retail new car market growth of 1.0%. Used car volumes also grew by 5.2% on a like-for-like basis in Q4, a notable improvement on the declines seen in the third quarter.
Outlook is “confident”, as “there are some early signs that new car supply may be beginning to improve which we expect to drive growth in new car volumes during 2023”.
Underlying PBT forecasts by Zeus Capital were recently reduced as follows (using round numbers):
FY 2023 PBT reduced 15% to £49m
FY 2024 PBT reduced 12% to £56m
My view
This is a brief update so there’s little reason to change your existing view on this stock. Paul recently noted the takeover interest (now expired) from the largest shareholder at 29p.
Car market statistics were gloomy in 2022. However, the “early signs” of improvement in supply, mentioned by Pendragon, are backed up by the national numbers, as new car volumes improved towards the end of the year.
Could 2023 be the year that the car market returns to normality? I’m not sure about that - even if supply returned to full health, what about demand? Is the consumer strong enough?
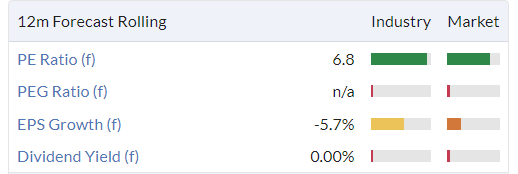
This is an interesting sector for those who like cheap earnings multiples and don’t mind taking on lots of economic risks:
Van Elle Holdings (LON:VANL)
Share price:47p (-12%)
Market cap: £50m
This is “the UK’s largest ground engineering contractor”.
H1 results (for the period to October) look good:
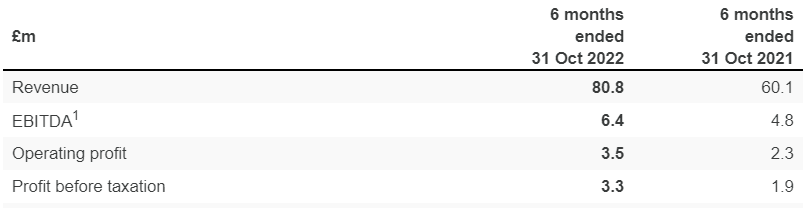
But of course these numbers are backward-looking. Why are the shares down 12% today?
We have the following outlook statement:
Trading is in line with expectations in H2 so far, and the company is “confident” it will achieve full-year expectations.
“The housing sector is expected to deliver lower volumes in the short-term, however, Van Elle’s Infrastructure and Construction markets remain healthy and typically deliver an improved margin mix”
Visibility is “much improved” out to FY 2025, thanks in particular to some highway and rail projects.
The CEO expands on these statements, confirming that “market conditions in the short term, especially in respect of new build housing, are expected to be more challenging”.
Kudos to Paul who emphasised the possibility that new building projects might struggle in November, despite Van Elle trading perfectly well at the time.
A broker note published today, again from Zeus Capital, sees FY April 2024 and FY April 2025 revenue forecasts each reduced by 3%. Underlying PBT forecasts for each year are reduced by c. 8% (to £6m and £6.6m, respectively).
My view
The good news is that Van Elle is not solely dependent on the residential sector for its revenues and indeed residential is only responsible for about 40% of the total.
What concerns me more is the lack of a substantial operating margin at the business, and the low returns.
The left-most column is FY April 2017, and the right-most column is FY April 2022:
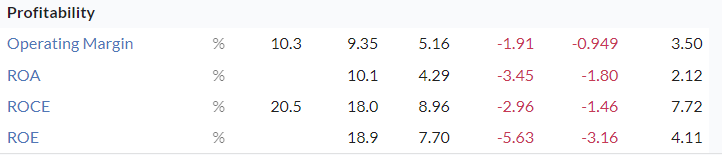
For businesses in the construction industry, I don’t automatically expect high returns, but neither do I think they should trade at expensive multiples. So perhaps the market is pricing this one about right currently?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Rotala (LON:ROL) Fabulous announcement for those who hold these. Tender offer at 55p for 35% of your holding, financed by a £10m loan.
hVIVO (LON:HVO) came across well on the InvestorMeetCompany webinar tonight I thought. Made it clear that 2023 forecasts are set low, and with 95% (?) revenues already contracted, hoping to beat forecasts. Did anyone else watch it, if so what did you think?
yes Paul - great company. Cathal was too promotional initially so sent the share up and then down again but that's noise. The reality is it is now being run by a high quality veteran of CRO's and is the world leader in what it does. ie in excess of 90% of the worlds challenge studies. Revenue visibility 1-2 years out is very high and margins are now coming up to a good standard - ie 20% (currently 17%). I can see them doing £70m at 18% margins or £12.5m PBT with in excess of £35m cash. in next 12 -18 months. So a base valuation for me of £225m market cap which is around 32p I think. There is hidden value too that I suspect will ultimately be spun off when market conditions are right for another 5-10p.
I don't understand why they trade as lowly as they do (aside from the scepticism associated with Cathals over enthusiasm!). I think with Mo you can expect several beats over the next 18 months as I believe the forecasts have been positioned that way. They have a decent moat too and are now starting to win high value consultancy through Venn as a cross sell to their client base. I hold and intend to stay that way.
Thanks david,
The EBITDA margin was really 15%, because it was one-off canx fee that took it to 17%.
The order visibility impresses me very much. As does the obviously too low forecasts, so it's now highly likely that they beat forecasts, so we're nicely set up for ahead of expectations updates peppering 2023.
I'm worried about competitors setting up. He said there are large barriers to entry, but it doesn't sound like it to me (a non-expert).
Overall, I think this could double in value (similar to your figures), which is my rough criteria for taking an opening starter position, which I did this morning, using some of my BUMP loot!!
Regards, Paul.
ha - very nice :)
Re barriers to entry - it is pretty hard to jump into this space and expect success. First you have to throw a lot of money at it to set up, then you need to be able to gain regulator approvals- neither easy. Once you've done that you have to persuade pharma and bio-tech to use you and thats the really hard part. They aren't price sensitive (to a large degree) - they want guaranteed quality and results. They get that with hVIVO (LON:HVO) and clearly trust them - someone new would have an almighty uphill battle to displace them. The most likely way a competitor gets in and gets traction in my view is if hVIVO (LON:HVO) screw up their capacity management and were full for say 2 years. At that point pharma may be tempted to switch away purely from a timeliness perspective and clearly if they did a good job then credibility might follow.
Their capacity right now is £70m revenue p/a : forecasts are £55m (but virtually full already) so I expect between £60-65m with 10%+ growth the following year. I think they need to be increasing capacity in the next 12 months.
Forgive me if my memory is patchy but I think hVIVO (LON:HVO) was flotsam from the Woodford debacle and was merged with Venn Life Sciences into Cathal Friel's Open Orphan back in 2019. Since then it has been working to establish its presence in running human challenge trials, alongside spinning off satellite assets - the first of which was Poolbeg Pharma. A new CEO came in relatively recently which has strengthened management . They've increased the size of their facilities, and said in a previous presentation that one of the keys to generating real profit would be through maximising productivity, both in terms of facilities and staff resources. They do seem to have a nice niche, and point to significant structural growth in their markets. I've held since 2020 and was badly underwater at one point, but have held on and will continue to hold, as they do seem to be over the cash burn. They are doing an Investor Meet Company presentation tonight.
Anybody else puzzled by the >10% rise in SDI (LON:SDI) today on the back of precisely no news? I (happily) hold but would appreciate any views/thoughts on this jump. Ta
SDI (LON:SDI) Tipped as a buy in the Daily Telegraph Questor Column
ww.telegraph.co.uk/investing/shares/hidden-feature-stock-allows-us-predict-100pc-rise-share-price/
hVIVO (LON:HVO) have expanded their capacity. So now they can conduct a trial / study on more volunteer patients at once, as their customers (like drug companies or biotechnology companies) are requesting. Alternatively they can run more than one trial at a time. From what I can see, they have little competition and are the world leaders in conducting human challenge trials in which the volunteers are deliberately infected with a disease such as caronavirus, or other diseases. The progress of the disease is very closely monitored with the patients on site. Lots of complicated blood tests or other tests are conducted in their labs. The effect of giving the patients various trial treatments can be evaluated. I am a holder and very pleased with today's announcement.
In this evening's presentation the question was asked about the upfront payments and whether the cash was the company's to use and the answer was yes as it's a pre-payment (my recollection) and any cancellations would lead to a retention as no refunds are given.
Hi Graham, in regard to the spreadbetting fees if to treat like a regular stock portfolio. I am guessing your analysis may be due to the no tax free investing accounts in Ireland like the UK ISA. Having recently moved back, this is something I am finding quite frustrating. It seems the only tax free way to invest is to create a self driven pension account but nothing in regard to an account where able to access money instantly if needed (unless dealing with tax returns and capital gains tax). Have you found the best way to invest located here or does spreadbetting seem the only way to avoid the tax system. Cheers
Stocks & Shares ISA. Tax-free. But only £20k a year into them.
SIPPs also have a limit to the amount you can put in a year, £40k. But the benefit is that if you're paying income tax, you can contribute to SIPPs from your gross income, avoiding income tax.
Velocys (LON:VLS) jumps on Bechtel agreement just announced. Sustainable Aviation Fuel is going to happen. VLS seem well placed to be a player and recently got gov funding. Holding and watching.
Graham, CMC Markets (LON:CMCX) I did a similar thing re annual cost of holding the position + the (what looks like) enlarged spreads. very unrealistic costs for holding 'long' term, which drives the shorter term mindset of 'trading' rather than 'investing'. Interesting though if the gov do start hammering the ISA allowances & tax efficiencies may potentially drive people towards CMC / IGG type spreadbetting services. (I hold)
Does anyone have any thoughts behind the Polarean Imaging (LON:POLX) share price weakness? All it's share price gains since phase III approval are now gone.
Surely even if they need to raise funds it would be on relatively attractive terms or be via a royalty/partnership agreement given they now have approval?
Polarean Imaging (LON:POLX)
Buy the news sell the fact seems to be the order of the day here. They were hyped up as revolutionary before the FDA declined the approval of their original submission. Fell heavily as you'd expect and then climbed again as investors anticipated it would ultimately get through. There were a lot of retail shareholders glued avidly to the FDA website ahead of approval at Christmas, so whilst there was a big initial jump that also tells you it was a crowded trade betting on approval. Once the excitement wanes those with profits start banking them. That inevitably leads to declines unless you've got natural buyers and the question is why would you buy them right now?
Revenue is negligible and cash burn is $12m p/a. Cash will be about $18m so doesn't look like they are in any danger but equally that cash appears as though it will get spent whilst orders come in so will be discounted to zero.
So a $125m market cap with great tech but negligible revenue and a little over a years worth of runway. Frankly I'd need to see some significant orders with revenue attached before I'd be inclined to even dip a toe in here. This market is fairly unforgiving - there is lots of great tech out there and not all of it will reach good commercialisation. All long duration assets have declined significantly so for these guys to still have a $125m market cap given the negligible revenue I find surprising.
All that said if it does start bringing in strong orders then I can see it doing well but to be in it now you need to be a firm believer in the product, marketplace and management ability to execute. There is little margin for error. I am watching it for signs of commercialisation but have no interest in taking a stake here.
Polarean Imaging (LON:POLX)
Thank you David
Hello DavidJHill. Shades of Angle (LON:AGL) do you agree?
almost identical I'd say. Brilliant tech but do they have enough runway to commercialise it as it always takes far longer than investors anticipate
Shades of Angle (LON:AGL) do you agree?
No, I don’t see it that way. Angle (LON:AGL) , as I understand it, offers a platform for disease detection. And is in competition with competitive liquid biopsies, for example. The winner might take all and the losers fall. hVIVO (LON:HVO) is a picks and shovels play on drug development in general with a strong presence in its specialist niche of human challenge studies. The risk/reward is fundamentally different IMO. One could make you quite wealthy or lose your stake. The other will more likely accumulate.
Does anyone here know what is driving the upward momentum in Rockwood Strategic (LON:RKW) now that the substantial discount to NAV has been eliminated? (I hold, increasingly nervously).
Rua Life Sciences (LON:RUA) - Commercialisation partnership signed (Full note & audio summary here: https://www.equitydevelopment....). RUA’s global commercialisation partner for its range of large bore vascular grafts has been announced as Corcym SRL. Corcym is the heart valve business bought out from Sorin/Livanova in 2021 and is a specialist cardiovascular medical device company with complementary products – like sutureless/minimally invasive aortic valves, mechanical heart valves, aortic prostheses and mitral valves and repair devices. RUA Vascular’s products for straight and aortic root grafts will fit perfectly into Corcym’s catalogue of products servicing the needs of heart surgeons that are sold in over 100 countries.
This transaction with a proven cardiovascular specialist provides RUA with significant validation and should banish the cloud that hovered over RUA since its regulatory stumble on the 510(k) submission for its large bore vascular graft. We estimate that the cost of establishing a cardiovascular sales network for the US alone would have been in excess of $10 million. The details released on the transaction note the sharing of gross margin on global sales equally between RUA and Corcym. Investors will remember the investments that RUA has made in clean room manufacturing capacity which we had assumed at the time were not just for clinical trial supplies, but eventually for commercialisation. With the deal in place, it appears that RUA’s manufacturing capacity will be matched to Corcym’s global commercialisation network.
For the moment, our valuation remains unchanged at £121.0m or 545p per share but we expect to update this shortly taking into account the new commercialisation agreement.
Another solid update from alternative asset manager Gresham House (LON:GHE) with AUM up 20% in last year and profit at top end of expectations. With their focus on specialist, sustainable assets (such as forestry, battery storage, etc) I think they're really well placed to grow AUM (Foresight group (LON:FSG) is another one) and yet very reasonably priced. Revenues are sticky and they're far less exposed to market volatility and outflows versus the more traditional equity asset managers. No idea why Gresham don't get more attention on this forum, but very happy to hold.
Thanks for the comments on Gresham House (LON:GHE) Bouden54. Planetx was similarly positive last April when the SP was 1000p. GHE isn't rated very highly by Stockopedia's algorithms; do you know what is holding it back from appearing to be higher quality and better value?
Not sure to be honest, I don't tend to pay too much attention to the stock ranks as they are very hit and miss. The low value rank appears to be due to a low dividend yield and low price to tangible book (both marked red) although can't see exactly what's driving it.
Pebble Beach Systems (LON:PEB) . thanks for covering Paul. a big reason for the poor balance sheet is that they were left with the issues from the mess that was Vislink - this explains the intangibles and the debt.
Pebble Beach Systems (LON:PEB) obviously have a decent product with their high margins and have reduced debt from over 12m to sub 6m in the last 8 years. to me, thats evidence of a decent, albeit modest, consistent post tax return from the business, whilst revenue has grown modestly from c.9m to 12+ near year.
i dont think they will have that equity raise as the banks and Kestrel (30% shareholder) have been supportive to date. you could say that they have already been thru tough trading with the lockdown years. to me its a sign of strength that they didn't raise funds during the pandemic.
i'm holding on the hope of a bid. what would that business be worth less PLC costs and cash drain to a larger player? my guess is at least double current equity price - so i'm prepared to give it 2 years for a possible 100% return, especially as their broadcasting technology is in a sweet spot at the moment in the change to digital.
brokers targets are 20p.
Van Elle Holdings posted record half-year revenue with operating profit significantly ahead of the prior year, however, its share price is tanking this morning
H Graham,
Really enjoyed the CMC Markets (LON:CMCX) update, and hold the same view as you with regard to the company being undervalued.
'I was previously very excited about the spread betting companies launching share dealing platforms. However, it’s worth noting that share dealing itself is not very profitable for these companies, at least not compared to spread betting! So I think the value is more to do with the cross-selling of more profitable products and getting users into the habit of logging in.'
I am not sure the log-in frequency would increase.
I personally suspect their white-label offering for UK banking/investment which is the real drive for growth in the UK. If they could land a UK bank/investment company offering a white lab offering with ISA and SIPP wrappers, this could be a step change in UK revenues.
BSV
Nice inline update from Fonix Mobile (LON:FNX) this morning:
Gross profit grew by 12% to £7.8m.
Increased interim dividend.
Interesting that although the volume of mobile payments was pretty much flat (£137m v £138m in H1 FY22), there was a sizeable increase in payments from commercial clients which offset a 36% decline in charity payments.
Active customer count increased to 121 (H1 FY22: 116).
Plenty of upbeat commentary e.g. "..growing pipeline of significant client prospects going into H2 FY23"
Decent stock rank and lovely chart but not looking particularly cheap now.
If there's time, I'd be interested to hear Paul or Graham's take on the numbers.
I've been holding a starter position for a little under a year but I'm disinclined to increase at these levels.
Fonix Mobile (LON:FNX) nice business john -I've held for some time. Comfortably in-line and international expansion seems to be taking off, which is needed to ensure they can continue to grow and reduce dependency on the UK as a service
I have posted previously about Oakley Capital Investments (LON:OCI) . I have a substantial holding.
Really good results out of Oakley Capital Investments (LON:OCI) in a trading statement. NAV +24% in the last year. The share price has, of course, risen substantially over the last week. I wonder why. One very big holding in IU Group. This is not for everyone, it's a higher risk private equity group, but I'm a believer.
I would like to confirm that the City of London Investment (LON:CLIG) year end results day, I hold, is February 22nd, as noted in their recent trading statement.
My morning smallcap tweet: Big Bother
Inland Homes (LON:INL) Home Reit (LON:HOME) Biome Technologies (LON:BIOM) Rurelec (LON:RUR) Rua Life Sciences (LON:RUA) Epwin (LON:EPWN) hVIVO (LON:HVO) t42 IoT Tracking Solutions (LON:TRAC) Discoverie (LON:DSCV) Fonix Mobile (LON:FNX) Pendragon (LON:PDG) £EEAS Gresham House (LON:GHE) Lords Trading (LON:LORD), XP Factory (LON:XPF), OnTheMarket (LON:OTMP), Next Fifteen Communications (LON:NFC)
◄Inland Homes (INL)► warns FY-Sept pretax loss c.£91m and NAV (IFRS) 40p/sh. sells greenfield "strategic land" option portfolio for £9.5m, a £3.5m profit (excludes any EPRA uplift). Obtains covenant waiver to June. "The Group has experienced an extremely disappointing year. However, we continue to see good interest for our new homes and valuable consented land in the South and South East of the UK" [SP=17.6 Cap=39m]
◄Home REIT (HOME)► re reports of delays in the approval of exempt housing benefit applications to one of its tenants, Lotus Sanctuary CIC. Lotus has not paid any rent for the quarter to Nov. If Lotus goes bust HOME will seek to assign leases to alternative providers. [SP=38.7 Cap=301m]
◄Biome Technologies (BIOM)► guides FY-Dec rev £6.2m, in line. Adj EBITDA in line and 'cash balance' (?) £0.8m, ahead. Outlook - substantial increase of bioplastic quantities received for delivery in Q4 and increased demand has continued. Stanelco has a much lower confirmed order book YoY. [SP=89.75 Cap=3m]
◄Rurelec (RUR)► no improvement in Sept update with no further receipt of cash from Argentina. Cash will run out middle of Q2. Its majority shareholder rubuffed request to allow share issues. Talks to sell interest in EdS in Argentina. Co would become a cash shell if sold. [SP=0.55 Cap=3m]
◄RUA Life Sciences (RUA)► appoints Corcym, a global medical device company focussed on the structural heart area, to bring R large bore vascular grafts to market. RUA and Corcym share the gross margin 50:50. [SP=44.7 Cap=10m]
◄Epwin (EPWN)► guides FY-Dec rev up 8%. Adj pretax in line, cash ahead. Current trading in line. [SP=74.42 Cap=108m]
◄hVIVO (HVO)► guides FY-Dec rev up 30%. EBITDA margin 17%+, significantly ahead of guidance of 13-15%. Will return capital. [SP=14.97 Cap=100m]
◄T42 IOT Tracking Solutions (TRAC)► irst order of 1,000 Tetis units, from USA. No £££. [SP=5.69 Cap=3m]
◄discoverIE (DSCV)► guides FY-Mar U/L earnings ahead of mgmt exp. [SP=786 Cap=757m]
◄Fonix Mobile (FNX)► guides H1-Dec comfortably in line with mgmt expectations. Adj EBITDA up 12%. [SP=218 Cap=218m]
◄Pendragon (PDG)► guides FY-Dec U/L pretax £57m, slightly ahead of market expectations. Outlook confident. [SP=19.55 Cap=273m]
◄eEnergy (EEAS)► guides H1-Dec rev up 58% and adj EBITDA up 87% to £1.5m. Outlook is cautiously optimistic. [SP=NA Cap=NA]
◄Gresham House (GHE)► guides FY-Dec AuM up 20%. Adj op profit over £26.5m, at the top end of market expectations, [SP=760 Cap=291m]
◄Lords Group Trading (LORD)► guides FY-Dec rev up 24% and adj pretax at least £16m, both ahead of market expectations of £436.7m and £15.7m. Outlook "While market conditions in 2023 may become more challenging in the short term, the Group has substantial organic growth levers through new geographies and product range extension that provide our Group with the opportunity to continue its track record of growth." [SP=78 Cap=127m]
In line: XPF, OTMP, NFC
Good morning Paul, Graham,
Hargreaves Services (LON:HSP) have issued an update today.
Seems rather positive, having skimmed through the Chairman’s report this morning. It seems that a number of their large contracts have inflation-increases clauses built in, thus allowing them to keep a decent profit margin.
Will you have time to review it today? I would appreciate it.
Me too if possible please Paul/Graham
I'll try, but must admit I'm feeling completely overwhelmed with the volume of updates at the moment, and can't seem to focus. Leave it with me, hopefully I'll get my brains into gear shortly!
Paul you and the Graham have been working like Trojans recently. If you need to go back to bed and have a rest do it. Nothing's worth getting overwhelmed about. The markets will still be there tomorrow.
Paul, I really do not know how you produce the volume and quality of work that you do.
Maybe it is my age, but I am really struggling with information overload, one of the downsides to t'internet!
I read your blogs here, the small caps podcast and of course any articles here on Stockopedia or posted by subscribers.
I look at macro news on Reuters and Bloomberg as well as the Telegraph and the Times. I am on Twitter where I follow a few key people and occasionally find something good on advfn. I access brokers reports via ResearchTree and a number of brokers make their research freely available elsewhere. There are sites offering company presentations and of course a regular flow of RNS news to absorb.
I am constantly scribbling notes on companies that I intend to research in more detail only to find that whether it is on a spreadsheet or a scrap of paper I never revisit it. I also look at investment vehicles and whether that should be ETFs, Unit Trusts or Investment Trusts. I look at commodities and specialist funds where I have no expertise whatsoever but feel it will be much needed diversification from UK small caps.
So, you have my every sympathy and gratitude for the time you spend producing such research. But can I ask am I the only one suffering from this problem, I imagine everyone else to be supremely organised and focused, or is this a more general problem?
You're not alone, I'm 42 and my mind-tank overflows and disappears down the drain every day! I don't know how he does it all (and that early in the morning to boot!!!)
Hi Tiswas,
Yes - I feel very similar. There is so much to read and ponder that I almost feel paralysed by over analysis.
I have decided that the best thing for me at the moment is to stick with what I have got, monitor it closely and add/cut as necessary.
I am beggining to make a list of Investment Trusts to slowly buy into and potentially move back to having more of an IT heavy PF - whilst I love small-caps I've recently got a new job and find I am having to focus on that a lot more and therefore have far less time to research.
I will still keep a decent sized/spread of small co's in my PF but am going to leave a lot of the heavy lifting to others, leaving myself with a much smaller PF which I hope to be able to focus in on.
Hello mcav82. Re Hargreaves Services (LON:HSP) not sure I agree. The profit from Germany has been very substantial and they are now downplaying that and the trading side. Not sure that the nice free profit from those sources are going to come so easily from the HS2 project, nor the renewables land opportunities.
Someone once said that this share was not great before the German JV and they were right if you go back. So.....we will see.
Good solid company but.........
Good morning Paul and Graham, three of direct interest to us this morning interest so any comments from you, or Stockopedia subscribers on them appreciated. rmillaree has picked up on Epwin which also seems pretty good to me, the other two are Watkin Jones where we're happy to wait for better times having bought back into it (once again) when the shares went below 100, finally the grim read on Inland Homes, commiserations to fellow sufferers. We got into this one years ago basically thinking Brownfield sites in London what could possibly go wrong? it also had a decent balance sheet then. but it's been a wild ride and we should have sold a long time ago.
Inland Homes (LON:INL) crikey now we know why the “new” ceo legged it after about a week in the job! Probably didn’t want his name associated with this disaster. I too should have sold a long time ago but also bought for the same reasons as JASVFS. Looks rather precipitous.
XP Factory (LON:XPF) Looks like a good update to me, slight miss on revenue but building a strong business. Be good to read your assessment on that one Paul
Cracking update from hVIVO (LON:HVO) now profitable but why has cash risen so much are they being paid in advance? Hence expense to follow. Is potential dividend wise at this time
They had a one off payment from cancellations and postponements of £1m - I’d assume that is close to 100% margin. They also take partial upfront deposits for trials and with record sales I expect them to be good on cash. They have a great order book and coverage for at least the next 18-24 months. I’m happy to hear they will return some cash, another nice return hopefully since the first spin out on Poolbeg.
hVIVO (LON:HVO) top quality share in my opinion and well run by the CEO Mo Khan. For EBITDA margins to already be 17% ahead of previous guidance of 13-15% is excellent. They target 20%+ over medium term but I hadn't expected 17% so quickly.
Moreover next year revenue is already 95% visible with a good chunk of 2024 also in the bag. There aren't that many businesses that can show that so this should really trade at a premium.
Cash generation is great - £28m net cash which does include some pre-payments (but non cancelable) and now moving into the dividend payers.
As the global leader in challenge studies and a CRO I am surprised they trade at discount to other CROs particularly as they are growing at circa 20% I think. I'd hope to see them north of 30p this year but who knows!
Epwin (LON:EPWN)
Solid update today - the company seems to be doing everything right with regard to getting on with the job of running their business and slowly expanding via bolt on acquisitions - business model is about as simple as you can get. I guess the market probably thinks they need to run to stand still ref profits but I think they have done a very decent job with supply chain constraints and cost inflation. Mini fanboy I am here.
Hi Guys, a cracking update from hVIVO (LON:HVO) this morning. They've been flying under the radar for a while - any chance of taking a look?
Would definitely be interested on you views on hVIVO
A cautious but encouraging update from Eenergy (LON:EAAS)
But thanks for write up
Paul, ticker is SUR, not SURE
Just checked pal... SUR ticker is Sureserve (LON:SUR) Bob'ster.
Thanks, I just spotted that & corrected it!
Not in the heading
Ah yes, I'll fix that now too. Thanks!