Small Cap Value Report (Wed 25 May 2022) - DRV, ZTF, MAB1, ELCO, BOWL

Good morning, it's Paul & Jack here again today.
Mello Update - Day 1 of the main show is underway as we speak. David has said it's sold out for today, but there are few remaining tickets for tomorrow discounted to just £40, using code: M2240 - here.
Agenda -
Paul's Section -
Driver (LON:DRV) - from 2 days ago, I give my view on the Middle East region restructuring. This share looks an interesting special situation, and I see more upside than downside, a thumbs up from me. Although the tiny market cap, and concentrated major holdings, mean liquidity is probably very thin.
Eleco (LON:ELCO) - a reassuring, in line update. However, the valuation looks much too high, given that profits are now falling.
Hollywood Bowl (LON:BOWL) - as expected, very strong interim results. Outlook comments indicate strong trading is expected to continue in H2, no sign of a downturn (yet, anyway). It looks reasonably priced, has plenty of cash, plus announces an entry into the Canadian market today. In normal markets, I would give this a firm thumbs up, but due to macro worries, probably a more tentative thumbs up today!
Jack's Section:
Zotefoams (LON:ZTF) - a reassuring update which sees the company using price increases to recoup inflationary costs. The group has invested significant amounts of capex into its operations and has IP-backed products, so it’s possible that future results look much better than historic figures. Given the shares have fallen by about 60% over the past year, it could be worth re-evaluating.
Mortgage Advice Bureau (Holdings) (LON:MAB1) - strikes me as a good company, highly profitable, with a strong Quality Rank. I do wonder how market sentiment might play on the share price in the shorter term, given rising rates and the potential impact on housing demand. But there are factors offsetting that, including high employment and inadequate supply.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Driver (LON:DRV)
31.5p
Market cap £17m
This minnow has bounced from a recent low of 24p, and readers helpfully flagged up that I’d missed a positive-sounding update. So I took a look after hours yesterday, here are my notes.
I last looked at DRV here in March 2022, and despite a profit warning, I concluded that it might be worth a punt, whilst also questioning why something so small was listed on the stock market at all?
This profit warning in March flagged a problem contract in the APAC (Asia-Pacific) region, and “an unexpected drop in revenues in the Middle East regions”.
Restructuring was said to be “starting immediately”, with £1m cost savings identified, with a “significant improvement” expected for H2 trading.
The CFO resigned.
Moving on to the latest announcement, which came out 2 days ago -
Driver Group plc (AIM: DRV), the leading global professional services consultancy to the construction and engineering industries providing multi-disciplinary consultancy services including expert witness, claims and dispute resolution services, today provides an update on its operational review in the Middle East region, and in particular the UAE.
25 employees in the M.East will be moved to an unnamed counter-party on 1 June 2022, leaving 9 remaining fee earners.
This avoids employment termination costs, so seems to be a good solution for this problematic region.
Receivables book in the M.East is £3.5m, of which DRV will receive £2.0m up-front from the counter-party, and it will assist in collecting the remaining £1.5m. That sounds to me as if there must be some disputed invoices, and a third party presumably won’t be terribly motivated to collect that in for DRV, so I reckon there could be an exceptional write-off to follow, for at least some of that £1.5m.
Annualised cost savings are £3m, better than the previous expected £1m. However, bear in mind DRV will also be losing future revenues, since it’s getting rid of most of the M.East staff, so it’s not clear how comparable these numbers are, in terms of overall profit benefit.
Interim profit guidance unchanged, at £0.3-0.5m for H1.
No full year guidance, as overall benefit of restructuring will take time to work through - that strikes me as rather weak.
Working capital will reduce.
Projected net cash of £5.3m (material to the £17m market cap) will be more than required, so actively looking at returning surplus cash to shareholders (special divi, and/or buybacks). Whilst good, this also emphasises that there's not much growth potential.
Outlook - my summary -
- Higher utilisation (i.e. more fees from each employee)
- Significantly improved profits
- Improved certainty on M.East collection of receivables
- Substantially de-risked M.East region
My opinion - this update is a little vague in parts, but overall it seems a positive down-sizing of a problem region, without termination costs.
At a guess, shareholders might get say 20% of the current share price as a special divi and/or buybacks, so the business is only being valued at c.£13-14m. That looks cheap, given that historically it’s made £2-3m p.a. profits.
My worry remains that this business seems very small to be listed, and might be better off in private ownership. Although that could be a catalyst for selling the company, once it’s been restructured?
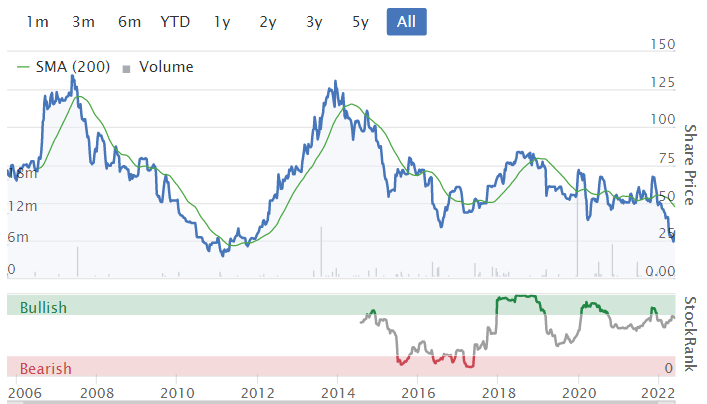
At the current tiny market cap, and a concentrated shareholder register, maybe the “for sale” sign might go up? I think there could be reasonable upside here, so it gets a thumbs up from me, as a recovery situation, and possible takeover target maybe? Probably not one to hold long term though, as it's gone nowhere in 16 years, as you can see below. This looks more of a trade, for a re-rating or takeover bid, I would say.
.
.
Eleco (LON:ELCO)
88.5p (little changed today at 08:50)
Market cap £74m
Eleco Plc (AIM: ELCO), the AIM-listed construction software specialist…
The current financial year is FY 12/2022.
Today’s update is nice and clear, and looks OK -

.
Actively seeking acquisitions.
Transition to SaaS is causing temporary softening of revenue growth - that’s fine, lots of software companies are doing the same thing, which makes future revenue/profit more stable, in return for a short-term reduction in one-off licence fees.
Outlook - reassuring -
The board remains confident in delivering results in line with market expectations for the full year."
Valuation - this is the difficult bit. Forecasts from Finncap (many thanks) and Equity Development show a considerable fall in profitability from c. £5m in 2020 and 2021, to just c.£3m in 2022 and 2023.
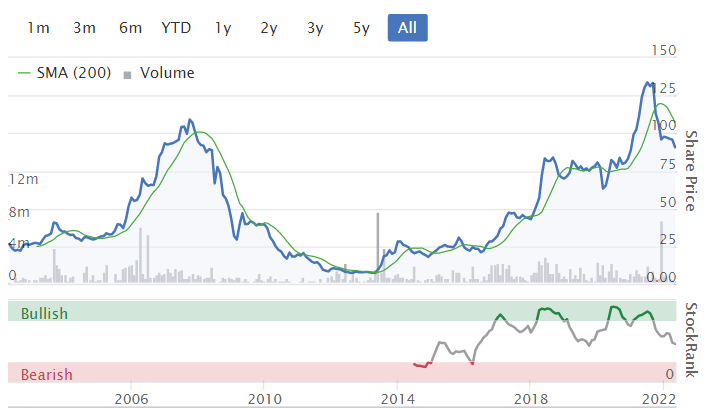
That’s about 3.0p EPS this year, so a PER of 29.5 - that’s too expensive in my opinion, given that we’re in a bear market, and the macro environment is unclear. Although the business should be more protected from any downturn, from recurring, SaaS revenues. Whereas in the 2008 recession, the ELCO share price collapsed, and lost 90%+ of its value until bottoming out in 2013.
My opinion - given that we’ve seen so many share prices plunge hugely in the last 9 months or so, I’m being super-selective for any new purchases.
ELCO looks really expensive to me, for a non-growth company, that’s seeing falling profits. Why would I pay a PER of nearly 30 times, and then sit and wait for several years for earnings to start rising? When there are so many other bargains around?
It doesn’t make sense to me, so in the harsh new environment we find ourselves in, I think we need to be much more sceptical about valuations, and this one looks like it could drop by a third to a half from current levels before even starting to look good value to me.
Remember that tech companies are facing big rises in staff costs, so with no revenue growth, that’s not a good situation to be in. The last balance sheet showed NTAV of only about £2m, but like most software companies it has favourable working capital, getting paid up-front, hence the cash pile.
Hopefully some growth can be bolted on via acquisitions.
On the upside, software companies are often acquired for their strategic value, and client relationships, so a takeover bid might come along, who knows? But on a standalone basis, I don’t see this share as good value.
.
.
Hollywood Bowl (LON:BOWL)
247p (up 4% at 09:53)
Market cap £422m
I remember writing something positive about this bowling chain recently, and have looked it up in the archive - it was here on 8 April, with a very good (ahead of expectations) H1 trading update, benefiting from pent-up demand. It also had a strong balance sheet with plenty of net cash, expansion plans, and looked reasonably priced on an estimated (by me) PER of about 14.
There are 2 announcements today -
Of Teaquinn Holdings Inc, a Canadian bowling operator. I think it’s correct that BOWL currently only operates in the UK. The acquisition is only small, at £10.6m, 80% payable now, and 20% deferred. This can be funded from BOWL’s existing cash pile. It operates 5 large sites (2 are freehold), with potential for 10 new sites over the next 5 years. It made a 22% EBITDA margin prior to covid. It’s now trading above 2019 comps. The price is 6.3x EBITDA for FY 12/2021, which looks a good deal. BOWL says the Canadian market is fragmented & ripe for consolidation.
This strikes [geddit?!] me as an interesting deal, with a credible explanation, and some limited figures provided today. Canada seems to open up a new growth avenue, and I can’t imagine there being much difference between how bowling sites operate in the UK and in Canada. Especially as existing management are staying on, and incentivised with a 2025 earn-out.
Hollywood Bowl, the UK's largest ten-pin bowling operator, is pleased to announce its Interim Results for the six-month period ended 31 March 2022 ("H1 FY2022").
I’ve not seen this before, but BOWL provides a very useful table showing the benefit of temporarily reduced VAT during the pandemic. This is great transparency, as it allows us to see the underlying profitability now that VAT has returned to normal -

.
As you can see, there’s a substantial £8.9m benefit to statutory revenue, which was money that would otherwise be payable to the Govt. This doesn’t tie in with a reduction in VAT from 20% to 12.5%, so I googled it, and discovered (I’d forgotten!) that leisure had a deeper reduced VAT rate of just 5%.
This £8.9m benefit should just flow straight down to profit before tax, which it roughly does, boosting statutory profit before tax by £8.6m.
My only query is why the EBITDA numbers are only boosted by £3.0m, which doesn’t look right to me. I’ve just emailed the company’s advisors to ask why the EBITDA figures show a much lower VAT benefit, only for it to reappear at the profit before tax level. It’s just a detail point, nothing too important.
Revenue growth of +26.8% on pre-pandemic, on a LFL (same store) basis is outstandingly good, but previously reported in the 8 April trading update, so not a surprise.
Dividend - resumption, with a 3.0p interim divi.
Outlook - we know H1 was superbly profitable, but the big question is whether that’s sustainable, especially given the growing disposable income squeeze, which is particularly hitting poorer households, less so for the middle class who can get decent pay rises, and who have a lower rate of inflation because food/energy are a lower proportion of their outgoings.
So any downturn may not necessarily be as gloomy as investors currently seem to think.
Add in another package of support measures from Govt which seems imminent. Let’s hope they’re a bit more decisive this time, rather than tinkering around the edges. The core problem is that energy bills are rising too much, and fast, so it seems to me direct policy measures to get those bills down, is the best approach. That would also have the knock on benefit of trimming the overall rate of inflation, thereby reducing the Govt’s index-linked cost increases (e.g. benefits & public sector salaries). They don’t seem to have thought about that yet!
Here’s BOWL’s all-important outlook statement today -
While we are mindful of the challenges many of our customers are facing in this higher inflationary environment, we continue to provide great value for money. This clearly resonated with our customers in the first half of FY2022 and I am confident this momentum will carry into the second half of the year.
We will continue to invest in all areas across the business which, coupled with our sustainable growth strategy, gives the Board confidence in the outlook of the business.
I am encouraged by the progress we are making with our key strategic priorities, and we are on track to meet Board expectations for the full year.
That sounds good to me. We always have to read between the lines with outlook comments, and take into account management track record of being realistic, or delusionally positive! I get the impression mgt at BOWL seem pretty straightforward.
Bear in mind that Restaurant (LON:RTN) (also discretionary spending) said something similar this week - demand is holding up well.
Therefore I’m leaning towards the view that, so far anyway, the much vaunted spending crisis doesn’t seem to be impacting the best in class operators.
Also, I think surveys where consumers say what they’re going to cut back on, are pretty worthless. The reason being that people tend to answer surveys in line with what they think they’re supposed to say. What they actually do, can be very different indeed.
From all the information that we get bombarded with, it seems to me households still want to enjoy experiences, especially holidays, and leisure. Maybe they’re cutting back on buying other stuff? So a reversal of what happened in the pandemic, when we couldn’t enjoy experiences, so people sat on the internet buying all sorts of things (guilty as charged!).
It’ll become clearer in time, but my only conclusion is that it’s incredibly difficult to predict which companies are going to blame the spending squeeze for under-performance, and announce operationally geared plunges in profits, and which companies will sail through the choppy waters with barely a scratch. That’s making me think more in terms of focusing on quality operators, rather than companies that are already struggling, but blaming external factors.
Valuation - the forward PER is about 15-16, but that’s based on forecasts which I reckon are still light. So the actual PER could turn out to be lower.
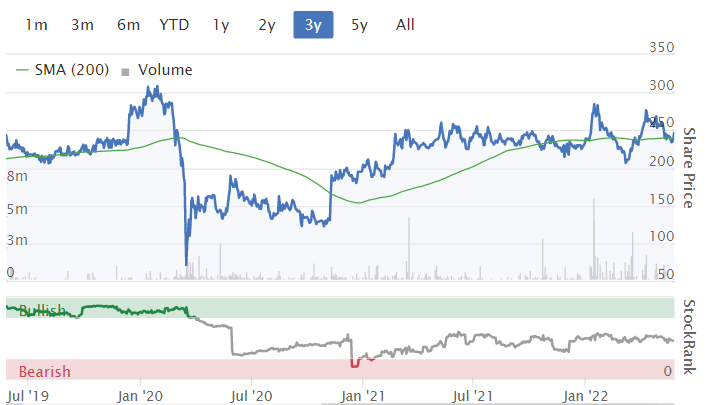
My opinion - BOWL shares have held up very well, in a nasty bear market - with a couple of spikes up, but essentially sideways over the last year. Very good, considering the carnage in most consumer-facing shares.
So it gets a tentative thumbs up from me again, but obviously holders will be fully aware that macro developments could prove difficult in the short term.
It's unusual to see a consumer share which has not wilted in the last 6-9 months -
 .
Jack’s section
Zotefoams (LON:ZTF)
Share price: 302.12p (+6.01%)
Shares in issue: 48,621,234
Market cap: £146.9m
Trading update for the four months to 30 April 2022
Zotefoams owns and licenses cellular materials technology, which it develops and sells for industrial uses, recyclable barrier packaging, and more.
In line with the outlook statement in our 2021 preliminary results announcement, we have experienced good demand in the first four months of 2022, resulting in Group revenue for the period being approximately 13% ahead of the comparative period.
Polyolefin Foams sales increased by 20% with volumes up by 5%, so the majority of the sales uplift has been driven by increased prices
High-Performance Products (HPP) sales increased by 6%. Within this range, Footwear sales were at similar levels to last year, Aviation sales improved ‘from a low base’, and T-FIT® insulation products sales increased by 18%.
On the challenging macro environment, Zotefoams comments:
The macroeconomic environment remains difficult, with input cost inflation both significant and unpredictable and supply chains prone to disruption. We have been reacting to input-price movements by increasing our selling prices as well as focusing on internal efficiencies and controllable costs, while proactively implementing actions to mitigate supply chain risks. There has been no material disruption to the Footwear supply chain or to our major facilities in the UK, USA and Poland, although there was a 5-week enforced shutdown of our China T-FIT facility due to COVID-19.
I’m not surprised that Zotefoams has been able to push through some price increases given its intellectual property and patents over some of the lightweight foam products, but it’s good to see concrete evidence of its ability to do so.
Outlook
While it is still early in the year, we anticipate Group revenue to be ahead of market expectations for the full year, with demand in line and higher prices recovering cost inflation. Current foreign exchange rates, net of hedging, may also provide some additional benefit. Consequently, we are comfortable with expectations for growth in profit and remain confident about the long-term prospects of the business.
Higher revenue and in line profits - that sounds in keeping with the group’s use of price increases to recover cost inflation.
Conclusion
The shares remain well off their all time highs, set in 2018 under altogether more bullish market conditions.

But this update strikes me as decent and, although current year earnings forecasts have come down, I suspect the quality of Zotefoam’s products and technology will put it in a better position than some other firms out there.

So at c17x forecast rolling earnings it is becoming more interesting, although I wouldn’t say it is cheap. The group has been investing heavily in its operations in recent years, which has impacted ROCE measures but this period of investment appears to be tailing off. Relying on solely on a PE ratio does not reflect medium term growth prospects.

Higher revenue and less capex should lead to higher returns on capital in future, assuming Zotefoams can handle what is no doubt a difficult and evolving macro environment. It has intellectual property and patents and has also invested in a significant operational expansion, so I think that at these lower levels the shares are worth looking at more closely.
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Share price: 981p (unchanged)
Shares in issue: 57,014,144
Market cap: £559.3m
Adviser numbers have continued to grow since the final results on 28 March and are up 9% year to date to 2,046.
The current pipeline of incoming new Appointed Representatives and advisers is strong, as is our pipeline of written new business that will complete over the coming months. New customer leads are up, which should deliver further market share growth.
MAB's mortgage completions for Q1 2022 were £5.8bn, representing an increase of 11% on a notably strong Q1 2021 (which in no small part was driven by stamp duty relief) and 44% on Q1 2020. We are pleased with this performance, especially when compared to the exceptional market performance we saw in the first half of 2021.
… As expected, increases in interest rates have stimulated more refinancing activity, with mortgage borrowers now more motivated than ever to secure the best rate possible to help their household budgeting.
Conclusion
The property market is hugely important, so this is a good opportunity to get some commentary on this part of the economy. People are still moving homes, despite macro concerns. Consumer demand for housing remains high and activity is strong.
The resilience shown by people who continue to move home is helped by the fact that employment is high, household savings are high and for those who are subsequent movers, housing equity levels have also risen over recent years. Although interest rates have risen and will most likely continue to rise over the next 12 months, current interest rates remain near historical lows. Lenders also have strong liquidity levels, meaning mortgage availability is now close to pre-pandemic highs, thereby helping the market to remain buoyant.
I’ve highlighted possibly the most important dynamic that could lead to some form of housing market slowdown. This must be balanced, though, against high levels of employment and a strong supply-demand picture. It’s an area that requires some deeper thought as the effects of how this all plays out could be profound.
Mortgage Advice Bureau itself is a highly profitable company with a Quality Rank of 98 and a share price that remains well above its pre-pandemic highs.

Its ROCE measure is among the best in the market, but the company has also been operating in an historically unusual interest rate environment which is set to change. A good company, but I wonder if rising rates and future property market headlines will at some point make for a better entry point?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
Relentless fall continues at Luceco (LON:LUCE) - surely has to be overdone now. Yes we know yes this year's earnings will be poor, but still a good quality company with good growth prospects (for those willing to look beyond the very short term)
Luceco (LON:LUCE)
The thing is we never know - each individual company might have some poor news that is leaking out ahead of that news being announced , or it just may be the dawning reality the future won't be as brightas previouly thought. Looking at the forecast eps numbers on stocky they have taken a decent battering recently so its not as if there is no bad news if the battering is real - and those numebrs are for calendar year 2023 . Luceco has pe of 7.3 per stocky - Norcros one of my holdings has pe of 6.3 (with steady stream of upgrades and they bear on earnings as recently as last month ) - so i would never say it cant get cheaper however compelling it looks now - at this stage i would probably be more after diversification rather than loading up the boat on any stock or sector. Hey ho sometimes having big kahunas gets its rewards and if you know the stock inside out then ..... . PS thanks for flagging up this one its nice to be slapped in the face when the price is looking compelling for populare (or unpopular) shares. Buy the dip just dont double dip perhaps ??
I'm sure some of the questions Paul poses for Driver (LON:DRV) will be addressed at their results presentation - you can register here: https://www.equitydevelopment....
Driver (LON:DRV) looks risky here - tiny free float, high PE for what is potentially a volatile business, with low visibility over the portfolio of cases it runs. It desperately needs to return cash to shareholders but after that, the historic dividend yield and rating is not attractive.
Angle (LON:AGL) RNS 12.30 today FDA approval granted, well done to all fellow holders!
£AGL You can register for the company webcast at 3pm via the Website. Should make interesting listening.
Well JimMcLad. That was worth waiting for - my single biggest holding, and not just for financial reasons. For reasons of Covid 19 and other factors, the benefits of the Angle (LON:AGL) process have been denied to many tens of thousands of people who deserve better diagnostic tools than have been on offer by the big providers. Lets hope they can go forward with their other offerings - in the fields of prostate cancer - a new study just beginning at Barts - and lung and ovarian cancers. The pay off is far less numbers of unnecessary invasive ops and far better targeted treatments.
Could someone possibly recap the salient points from the Angle (LON:AGL) webcast? I'm out in the sticks with an extremely poor internet connection. Any sign of a fundraising? Thanks a lot
Rogerh
I didn’t make any notes but salient points included:
FDA approval will generate more work for Angle (LON:AGL) labs and will make FDA approvals for other cancer types much quicker
Stressing they want to work with big pharmas (ie no mention of takeover)
No mention of fundraising (but I wouldn’t dismiss the possibility)
My only minor disappointment was that is seems getting major deployment of the device and assays etc into the ‘real’ world could still take over 2 years. However, from a financial perspective, the company would still be increasing revenue during that period via the labs and involvement with drug trials .
If your broadband perks up there should be a recording of the session on the WEB site soon.
Thanks a lot, Jim!
£AGL has got FDA approval, up 50%. Thanks to Mello I picked up a few.
Tekcapital (LON:TEK) (I hold) Another placing of shares at a significant discount to NAV. Oversubscribed, I wonder why! Sadly not offered to P.I.s who once again get their investment diluted. Annoying.
It is, I will be selling at some stage as a result.
Charles Mitchell. I certainly won't be selling as still like what they are doing, still well below NAV and I hope that in due course it will have provided significant upside. Doesn't mean I'm not annoyed and not being invited to the party.
Agree with this Roger. Having bought in around 10p I have very little to really complain about and feel long term this will be much higher than it is today. There is an element of getting it placed quickly is easier and less costly but others may know more about the process than I
Spectra Systems (LON:SPSY) (I hold) goes ex-div on 1st June. Paying $0.11 which equates to approx 8.8p or 6% at current exchange rates. No tax to pay if held in a SIPP.
Very solid little company, consistently growing its dividend. Products are not too exposed to consumer slowdown IMO. Forecast EPS growing at a modest rate.
Share price has consolidated since it got ahead of itself in late 2020. Forward PE now less than 16.
Also, the outgoing CFO of Spectra Systems (LON:SPSY) has just exercised options, and kept them (after a cashless exercise for taxes etc). Which is a big sign of confidence IMO that the shares are currently undervalued, as most outgoing directors would take the opportunity to cash out everything.
(I hold in the Boon Fund)
As I mentioned in a comment a few days ago, they will definitely benefit from the strong dollar / weak pound. And this hasn't been updated into the analyst forecasts yet.
re Volvere (LON:VLE) not much to say.
Clearly the discount to NAV offers short term potential and will be interesting to see if the co continues to buy back stock in the coming days. If they do... then together will purchases already made this year ... will be supportive of NAV. However, perhaps better news if they don't, even though shares are lower than previous purchases since this "could" mean an acquisition is close.
For me, you can sleep at night with this one even if shares are have fallen. Id be very surprised if they don't add a business or two in the next six months.
Has anyone else had a look at Volvere? I keep looking at it and thinking it offers a good opportunity. Graham Neary first highlighted it in this column. The Lander bros are in it for nearly 15% and they seem to have a good record. It is a acquirer and developer of businesses although only has Shire Foods for some time now. Perhaps if the logic is right for Begbie Traynor it is for these guys too. Should be some good ops arise. Good Balance sheet over £34m cash. Tricky one. I keep looking and nearly pressing the buy button but to date cannot quite get the confidence. Interested to hear others thoughts if got the time. Mkt cap circa £26m enterprise value £8m. P/B 0.76.
Further re Volvere (LON:VLE)
Cash as per statement is £22m. I think they have spent just over £660k on 55k shares.
NAV is 1350. The buyback nudges this up.
Shire (80%) £30m rev £2m profit = £15 (80%) = 12
Indulgence = they paid £1m + investments £1m + losses £2m - this has not gone well so far, not helped by covid. I do remember it took some time to get Shire performing. You need to get the plant operating well but it does £5m rev.... Id say it has value £2m.
The company last paid 1150 ish for stock. Nearly a 20% discount to NAV is attractive enough. They have had quiet deal periods before and so whilst frustrating after Covid the flood of money to support business in distress did not help. Now should be a good time. I believe there must remain good ops to add to the food business and accelerate revenues towards £50m and then £100m. However given todays comment I wouldn't be surprised if they havent also now found something interesting away from food. companies will be struggling to access money at the moment, especially companies on the cusp of profitability which is where they hunt.
In the past as acquisitions grow they have value to the group that isn't captured in balance sheet NAV. During these periods the stocks trades at a huge premium. The premium clearly reflects the value the market attributes to these businesses. It would be nice if indulgence could start to fair better and another business or two contribute to value which over time drives a premium before they are sold.
Yes sorry I was sloppy there reading off stocko page. Your comments are helpful and I thank you for that.
No worries - a vehicle like this will experience lumpy returns. That’s ok for me but obvs it gets frustrating when they do nothing. One day you will walk in and it will pop, and then u make your money. At the moment it’s reassuring to know u have a pretty cheap business and a load of cash.
Morning Paul and Jack.
Wondered if you might take a look at Pennant International (LON: PEN)
FY results were out today.
Turnaround as suffered for years with a massive legacy contract which is now concluded.
Won a £9m Boeing contract this year and its software acquisition made in 2018 is growing nicely.
Expected rev for 2022 is £16m.
Contracted order book is £32m (£21m) of which £13m for 2022 and £13m next year, £6m for 2024.
Defence training ought to have a tailwind medium term.
I hold
Morning Michael,
Thanks for the interesting comment on Pennant International (LON:PEN)
We're tending to focus on larger, more liquid small caps these days. PEN is only £14m market cap. So if we write about it, readers might not be able to buy any, or might cause a spike up in price, and then blame us when it goes back down again!
I've covered PEN a lot in the past, but its results proved lumpy, with the occasional bull run in the shares, before they came back down again.
It sounds like things might be improving though, from your comments, so good luck with it!
Regards, Paul.
Thanks Paul
Company outlook statements are starting to reflect what's been obvious in the macro outlook for months. Marks and Spencer (LON:MKS) say that "given the increasing cost pressures and consumer uncertainty, we do not currently expect to progress from this lower profit base." It wont be the last time we hear something like that.
The problem is that there's a lot more of this kind of stuff to go before we catch up with reality. The median estimate of forward eps growth for the FTSE all share is still over 10%. Is that realistic? Are company earnings going to massively outperform any reasonable estimate of GDP growth? I find it hard to see how that can happen when, for example, retail sales volumes have fallen by 5% and companies are starting to talk about pressure on margins.
In basically every economic slowdown in history, we see a combination of lower forward eps guidance and lower price multiples of those lower earnings, resulting in a ongoing downward slide in share prices. I think the same will happen this time: the slow motion train wreck is likely to be with us for a while yet and while it's ongoing, there's an increased risk that it will speed up.
Hi cmpeckham,
Great post, I'm thinking along the same lines. Broker forecasts should be falling for cyclical companies, not rising or static, for many companies. Hence elevated risk of profit warnings, but the share price is punished twice in anticipation of the profit warning, then again when it happens.
At some point, investors will look beyond the short term, and start buying the recovery potential, but it really doesn't feel as if we're anywhere near that stage, but who knows what's going to happen.
A key thing is what Govts do. As mentioned before, Powell (Fed Chair) has already said that when the next recession hits, he'll do more QE. So perhaps once inflation begins falling, then we could start the same cycle again of more money printing, and asset markets that get pumped up on steriods again. Who knows?!
I'm looking for early signs that bad updates are met with small drops in share prices, which gradually recover, indicating that anyone likely to sell has already done so. Boohoo (LON:BOO) (I hold) seems to have found a floor, despite rubbish numbers.
My broker says it's not so much selling now, but a buyers' strike.
It will be fascinating to see how this all pans out. I remember the 2000-2002 tech boom & bust very well. It was similar to what we've recently experienced - insane valuations on tech, which collapsed over time. It seems to be happening faster this time in the US. Back in 2000-2002, shares just ground down relentlessly, and after every powerful rally, further falls happened. But once all that froth was flushed away, it set us up for a fantastic bull market in 2003 and beyond, with multibaggers galore, sitting on a plate, because so many people had left the market in despondence.
Regards, Paul.
I agree. At some point there will be bargains galore, but for me, we haven't reached that point yet, and probably when we do, the bargains won't look like bargains. They will look like basket cases. Unfortunately, we need more despondency and revulsion at all things related to the stock market, as we've seen at the bottom of bear markets like 2003 and 2009. So, can we have some more despondency please?!
A key pointer to where we are in the cycle, is that the Fed now actually want the US stock market to go down. Their logic for starting QE included the fact that "wealth effects" from higher asset prices would drive consumption and lift the economy out of deflation, as it was at the time. By the same logic, they now need to see that go in to reverse . They will be happy to see the stock market fall, as they think it makes their job easier. They can then tame inflation without over-doing the rate rises, which only act with a 6-9 months lag and so are easy to make mistakes with.
In the years 2009 to 2020, the Fed was terrified of deflation and went dovish when the stock market had a tantrum. Those days are over, the "Fed put" is no more. For now, it's all about taming inflation and while that's the case, I will take heed of the old market saying: "don't fight the Fed".
Thanks Paul S and Mr Peckham. I read Naked trader saying the other day it might well be worth taking the Summer to enjoy the sun...seems a reasonable appraisal.
Sat in my hands, but shite its so hard as my watch list has plenty of bargins, but are they really bargins? It would appear perhaps not yet.
I note the S & P 500 is close to wiping off all the gains of 2021...seems a reasonable start of a staged ETF buy in to me, as perhaps a 10 year hold.
I believe most commentators are saying recession is inevitable, and calling the bottom is going to be a fool's game. If we get indiscriminate price collapse in shares and indexes it is worth having some dry gun powder and a list of stocks with a plan to buy.
BSV
There is an enormous difference between "calling the bottom" which can't be done, and buying when the odds are on your side, which has been profitable in previous market cycles and I see no reason why it would not be so again.
I would be very grateful if anyone on here could give me a heads up when we hit that point.
Apologies for being slightly off topic, however as Thursday 2/6 is a Public Holiday and markets in the UK will be closed what is the position with shares that were due to be Ex Dividend on Thursday ?
Will the day be bought forward to 1/6 or pushed back to the following week?
Thank you .
Great question ! They all go ex div on Wednesday instead apparantly :
https://www.dividenddata.co.uk...
I see Purplebricks (LON:PURP) have also published their results today.
I recently put my flat in London up for sale and it is currently under offer, so thought I'd share some personal feedback on why I think Purplebricks (LON:PURP) might be facing a fundamental challenge to its business model. I live in an area which is reasonably sought after, including for flats, so decided that there was no point wasting thousands of pounds on a traditional estate agent and went instead for a cheap online agent. IMO traditional agents add much less value to the process for sought after properties where a rightmove listing and decent photos are the main thing you need.
I researched online agents and decided to go with Strike. Strike offer an entirely 'free' service, including a Rightmove listing, although in practice it is only free if you are a professional photographer with a wide camera lens and you have the technology to produce a floorplan yourself. So in reality you have to spend some money - I booked one of their packages which offered professional photography, 360 degree photos, a floorplan, and a premium Rightmove listing. This cost me £799 which is the grand total of what I have spent with Strike - still far below Purplebricks' £1499 for London (which offers a similar package but doesn't include a premium listing).
Strike have been pretty good. They respond to my queries at weekends and bank holidays, and in fact uploaded my advert on the May bank holiday. I got viewers pretty quickly and accepted a best and final offer on my flat within 10 days of listing. The Strike team dealing with the selling paperwork have been less efficient but I am willing to give them a bit of slack given I am saving about £4k+ versus a traditional agent. Perhaps a traditional agent might have got me more viewings from their database but probably from people not really that interested but who the estate agent has talked around.
Strike undercutting Purplebricks (LON:PURP), and with a good service, is surely problematic for £PURP. On the one hand they could get squeezed by Strike and other cheaper online agents in a 'race to the bottom' on price, and on the other hand get squeezed out by traditional agents who might continue to add value on hard-to-shift properties where you need more than a Rightmove listing. They're caught in the middle. Purplebricks (LON:PURP) do have a big marketing budget and brand recognition but Strike is surely eating into that and I have personally noticed more Strike properties for sale than Purplebricks (LON:PURP) in my area anyway (SW London / north Surrey where Strike only started last year according to my agent).
I think Strike and Purplebricks (LON:PURP) are also bad news for traditional agents who risk getting stuck with clients whose properties are much harder to sell. I wouldn't touch any estate agent shares unless they looked very cheap.
I made decent profits from Purplebricks (LON:PURP) in the past when it was an exciting story stock so I am naturally inclined to be a bit biased to them, but have no overall position.
I hope this is helpful.
Edit: p.s. I meant to say I have also seen the rise of specialist national estate agents like Modern house and Inigo that focus on modern and historic properties respectively and those agents have fantastic marketing - check them out on Instagram! Again, surely another threat to local agents. And recently I have noticed there is an 'off market' agent called 'Invisible Homes' that bypasses Rightmove and essentially has the same model as Strike.
I think the short answer is that Purplebricks (LON:PURP) have absolutely no moat - anyone can set up as an online agent and consumers will always look for best value provider so is going to be competitive sector. Always avoided for that simple reason.
Purplebricks (LON:PURP)
Hi Patrick
It might partly explain why most of their business takes place outside of London, where presumably their services are more sought after, and why they have struggled to get a foothold in the South.
Below is an extract from their last published accounts for the year ending March 2021.
Note the loss for the year of c£5m, which really should have been boom time for them:
Source: https://find-and-update.compan...
There's no P&L in the accounts, so presumably revenue is less than £10.2m (as per Small Company Account submissions.)
That's vs Purplebricks (LON:PURP) 's £70m announced today.
Great research - thank you for sharing. As per Paul's update on Purplebricks (LON:PURP) (the day after this report for those coming to this later) - maybe Purplebricks (LON:PURP) will be the last man standing?!
Thanks Jack for the write up on MAB1
I’ve been in thus one since 2015 but sold down about 75% of my holding in January on the basis that the housing market transaction volumes were starting to moderate after the high level of activity seen post the first COVID wave.
But I continue to hold some as I believe that this company will continue to be a very good long term investment having very strong ROCE and a highly competent, no nonsense management.
As regards entry point, I do think that it may have further to fall in the short term as the possibility of recession starts to weigh more heavily on high P/E shares.
Hi Graham
I agree on the longer term investment for Mortgage Advice Bureau (Holdings) (LON:MAB1)
I think that we must remember what percentage of the mortgages held now are on shorter term fixed rate deals, so similar to the narrative below on "ouch this hurts" when your mortgage or energy deal comes to an end. Is this not the time that more people will be frantically looking around for the best deal and not just going with the same bank, so advisors become worth their weight in bricks?
So whilst there may be a slower turnover in houses, we also have to remember the massive existing mortgage market that is out there and how many deals a year come up for renewal and how do folks go about those, e.g. price comparison websites and brokers, not just the lady in the local branch.
My anecdotal 5p, was I saw a great deal with Santander a couple of months back, I am a Select customer so called them up the supposed service excellent. The response was that deal is only available via a broker, you cannot get it direct as a customer.
Tommy
Hey…if people at Mello, say hello (…only if you want to…). Ciao
I bought Esken (LON:ESKN) several months ago at 15p, thinking it was a cheap (but speculative) play on the re-opening trade. Given the shareholder register and financial backers, I figured there was some potential upside as a special situation. The inital broker note published at the time gave a target share price of 36p if I recall (with the big caveat that air traffic volumes recovered post-Covid) and it looked likely that new airlines would sign up for the 2022 Summer season. I thought the energy division would provide some desperately needed cashflow to support the business through the next 1-2 years. How wrong I was. I sold a few months back at 11p when management confirmed that Southend Airport would remain empty for a further year. It was therefore not a surprise to see another big loss announced today. Given the short cash runway remaining it does seem that going concern status is in jeopardy, and another deeply discounted rights issue is on the way. Does anyone see an opportunity in this distressed scenario as the price drops down towards mid single digit pennies, and a rights issue on the way at an even lower price? Buying an energy business and getting a strategic airport asset for free?
Hi BE70,
I've just taken a quick look at Esken (LON:ESKN) results, and it looks high risk, and very complicated! So a 2-day research job I'd say. Very much a special situation. Occasionally these things pay off big time, but you have to be prepared to lose some or all of your money with special situations like this. The terms of the convertible loan look key.
Regards, Paul.
Thanks Paul. My thoughts on mortgage rates. My 1.16% fixed rate comes to an end in November, and I'm in the processes of refinancing at double that rate! As an illustration the 10yr fixed rate with Lloyd's was 1.66% in feb but now 2.31% (i got slightly lower as my application was done last week). Yes rates are low but it is relative. I am currently paying 500 in interest a month, now more like 1k (ignoring the capital repayment part). This may be more of a london issue, but how are people going to afford an extra few hundred a month with everything else rising? Also this was my 3rd attempt to get a mortgage as the previous deals were removed before I got the application in!
I think it was Jack talking about the mortgages.
Hi Nano,
Just done something very similar. Mortgage adds approx £1200 to my annual payments. Add this to the £2500 extra on the utility bills and that is the price of a family summer holiday with nothing to show for it.
My wife had a pay-rise recently but the additional NI nabbed half of it.
Assuming this is happening to everyone then there is simply going to be less money in the system.
Fortunately, we are only having to cut back on discretionary spending. I feel for those who are now having to make serious choices between buying clothes/food/fuel etc.
"My wife had a pay-rise recently but the additional NI nabbed half of it."
Lol NI rate only went up by 1.25% so thats quite a bit out on the maths there - so thats an extra 1.25% deducted on top of normal % charged - note from July most peeps will be able to earn over £50 per week extra before they are charged NI too - so for those on very modest income NI rise isnt particularly material. Not nice though that NI increase in april was done as ssame time as "pa frozen" - cant remember the last time low paid peeps would have had pay cut going into new tax year presuming they got no pay rise.
Hi rmillaree
You shouldn’t make fun of what you don’t understand. Pay rise after tax was £120 pm but extra £60 to pay in NI. that is 50% by my maths.
Revs
You shouldn’t make fun of what you don’t understand. Pay rise after tax was £120 pm but extra £60 to pay in NI. that is 50% by my maths.
Who says i dont understand it - i fully understand how ni works - i was stating facts .
Facts are if you earn £1 of gross pay the most NI you can pay as employee normally on that £1 is 13.25% of that gross pay. talk of 50% ni charge is pure nonsense end of.
If you earn marginal £1 gross and pay 60p tax and 13.25 p NI net pay 26.75p you are most certainly not paying 50% ni in my books - 50% tax yes 50% ni most certainly not.
As i previously stated the NI increase this tax year compared to last year is only 1.25%
If i have a slice of cake give 80% away to fat bob who has eats his share immediately (apologies bob's) and give you 10% and 10% is left - you havent been given half the cake despite the fact it may look like that is what has happened to someone who hasnt seen bob eat 80% of the whole and turns up and sees two euqal slices of 10% each- hey ho.
Maths damns maths and statistics and all that happy to agree to disagree though if you still want to think someone is paying 50% NI - my piece has been said.
Who said anything about 50% NI?
Read what I said. Half her pay rise was taken to cover the additional NI. This is why the NI rise is significant.
£60 from £120 is simple maths.
There was no need to comment in such a way. My comment was purely to highlight that people are not feeling the benefit of pay rises and was accurate.
Now you have just made things ugly by defending your misunderstanding.
Who said anything about 50% NI?
We will just have to agree to disagree as per earlier posting not worth arguing over this spilt milk
When you said
Half her pay rise was taken to cover the additional NI.
i read that as meaning 50% - apologies if when you said half you did not mean 50%
hi revs, so I got a pay rise to tackle inflation, but it only adds 100 net to my monthly pay. Some companies have been more smart and given a fixed amount to each staff below a certain pay. This makes sense all round, for the employer it is a one off cost..vs the likes of Tesco who have given 6% permanent increase in pay, which they will be paying for in years to come.... It is what has put me off investing in Royal Mail
Maybe too big for Jack or Paul to cover, but what does anyone make of the Pets at Home (LON:PETS) update this morning. Shares look to be at the bottom of their valuation range - but which name isn’t?! Market seems to have shrugged off the cautious comment on inflationary risks.
Agree, it is looking cheap but its my understanding it got pegged back because of the number of unwanted post-lockdown pets and supply issues. Not sure either issue has gone away yet. Pets are allegedly one of the last things people cut back on so maybe inflation will have less of an impact. In short not without risks but a good Co IMO (I hold)
For those who have missed it
Randall & Quilter Investment Holdings (LON:RQIH) take over looks to have hit the rocks, Brickell pulled out last night alleging "breach"
https://www.stockopedia.com/sh...
Sold this morning and just took the hit
Tommy
As a holder of Marks and Spencer (LON:MKS) I thought I'd share my summary and some snippets from their FY22 results (up to beginning of April) both for interest in Marks and Spencer (LON:MKS) but also for wider read-across to the retail sector.
Positively, Marks and Spencer (LON:MKS) in my opinion has now successfully turned around its clothing and home business which is now growing - with growth up 3.8% versus pre-pandemic, driven heavily by online growth of 55%. Importantly, the profit margins have improved for both clothing and home and the food business with less discounting.
Food also grew strongly at 10.1% growth versus pre-pandemic. Excluding hospital and travel (which during FY23 should presumably grow back) this would be even higher at 14.7% revenue growth.
Ocado is providing decent additional revenue although I am surprised the contribution to profits isn't higher at only £13.9m net income.
Adjusted EPS is 21.7p which is great although I think this includes business rates relief. I need to check. I haven't calculated what profitability levels would be without that (yet) as that might be a helpful guide for the future too.
Clearly the market is now focused on the future. I see in Q4 it looks like there might have been a very slightly softening of food sales but clothing and home grew further - that period and late Q3 covered Omicron don't forget.
This is what they say on the outlook:
'Overall trading in the first six weeks of the financial year has been ahead of the comparable periods in 2021/22, including the period from 12 April 2021 when non-essential retail reopened.' BUT 'This year the business will not receive business rates relief and International will not have the profit contribution from Russia [which with the Ukraine operation delivered £5.2m adjusted profit]. As we invest in capacity growth at Ocado Retail, we anticipate a minimal contribution of share of net income to group results. Consequently, we start 2022/23 from a lower adjusted profit base. The business is now much better positioned and has had an encouraging start to the year. However, given the increasing cost pressures and consumer uncertainty we do not currently expect to progress from this lower profit base in 2022/23.'
They go on to say 'There is no current sign of inflation abating, although we believe the rate of cost growth will subside by the third quarter.'
Edit: I forgot to mention that net debt excluding lease liabilities now down to £420m. A fellow investor on Twitter notes the freehold property exceeds the market cap at present.
My summary: I think these are great results for FY22 and the outgoing CEO has done a good job at improving margins and revenue growth. The Ocado contribution looks disappointing - it starts to raise questions about whether it's worth it! The FY23 outlook sounds very nervous but the share price already reflects that in part. I think this is a good long-term hold given the turnaround and worth keeping in mind that FY23 should be better for their hospitality (in-store cafes) and travel as people return to the office and are less nervous about going out. I haven't seen any broker targets for FY23 which I'd be keen to see. 130p share price this morning is probably fair on the outlook but hopefully a good entry point for 18-24 months' time?
Thankyou for taking the time to do that. I am encouraged by their clothing performance and the fact margins are improving. Perhaps a good sign for SOS?!
Paul can you look at Hollywood Bowl (LON:BOWL) results i added Ten Entertainment (LON:TEG) today instead.
For anyone wanting to see the FY22 Full Year Results for De La Rue (LON:DLAR) (I hold) that have not appeared on the feeds they are on their website. A slight top line profit miss but otherwise they read well to me, but seems they are being punished in the market being down 8% at time of writing. Would be keen to see comment on the figures from Paul.
Outlook promising, reduced cash payments to pension funds and strong cash generation - though continuing headwinds due to supply chain issues.
Good morning Paul and Jack, grateful if you could cast your eyes over the trading update from Bakkavor (LON:BAKK) - a mid-cap, but within SCVR realms.
Edit: I hold
Re Morses Club (LON:MCL) - "The Company's full-year results for the 52-week period ending 26 February 2022, which were planned for release in May, will now be announced no later than 26 August 2022. An update on the expected date of results will be provided in due course following the completion of the audit process. "
Clearly, there is a problem. However, this non-announcement gives no indication as to why, the scale or, in short, any useful information for me as the share owner. Is it related to a Home Credit pile on by claims companies - Provident and NSF have already exited the market. Is it that impairments have spiralled at the newer Digital Division as the cost of living crisis bites? Who knows - I don't! Others do.
Furthermore, neither of these are reasons to not be able to give a statement of results from last year - although it might give rise to a Going Concern statement or to a very wide range of outcomes.
What I can't accept is effectively no communication at all. I am writing to the company, their PR and the FCA to complain and I hope others do the same. I am powerless to do more beyond selling my remaining shares (which might then be a bargain for the people on the inside) but this sort of thing needs to be changed.
If you extrapolate claim figures MCL should be loosing circa 1m a month. It sounds ridiculous as it's a huge increase from the medium figure. Until they clarify this MCL are on the barge poll list. Add in Paul Smith selling up and delayed results... It smells fishy.
Re Morses Club (LON:MCL) being on a barge pole list, I think as a holder, it is more serious. If the regulators fail to back MCL's interpretation of the regulations, and thus that relatively few claims are payable because they were doing nothing wrong and "following the guidelines", then the old Home Credit industry is toast (and a large group will swing back to having no credit, getting black market credit or getting online credit with an even higher incidence of non-repayment and thus, long term higher credit costs. The newer Digital business relies on the Home Credit as it it builds up and so might go under as well. I think the outcome is now binary: rebound and a multi-bagger or slow fade to closure. From previous utterances from the FCA, I thought they liked the interactive model of talking face to face and forebearance. Now I am not sure.
My problem, which is why I got out, was this: although there is a need for such lenders - the success of the claims highlights the wider communities revulsion of the business as a whole. I cannot fathom any government coming to it's rescue with regulation until the reverse situation of unregulated lenders plays out to detrimental effect. Morse now being the number one is the primary target until it is eliminated and then those claim businesses will move on to the next until they are regulated fairly. The claim businesses, currently, have everything going for them.
In effect, and sadly, the consumers of the product are ultimately aiding their own downfall as they go for the short term win of writing off loans only to go into the arms of the unregulated money lenders, in the longer term.
I am not shorting this business - I am a long only investor.
There is a technical hitch with the RNS system this morning so many expected results have not yet appeared.
Do you mean on Stocko, Investegate or the LSE (https://www.londonstockexchang...)?
Contacted CEO of one of my investments as RNS expected. He said " Glitch with RNS system this morning. Many RNSs not yet appeared."
May be worth checking company websites as they also publish.
These were missing for me:
Results and Reports - De La Rue #DLAR
Preliminary-Results-FY21-FINAL-v2.pdf (pennantplc.co.uk) #PEN
Reports, Results & Presentations (marksandspencer.com) #MKS
Results and Presentations - Investors - Pets at Home Group plc #PETS
Were Pets at Home (LON:PETS) and Marks and Spencer (LON:MKS) RNSs missing for anyone else this morning from LSE / investegate etc?
Yes. Don't know what's going on with LSE.
I'm at the Mello Show in London. Come and say hello. I'm often sitting in the corner of the exhibitors hall, near the bar.
Late results: Volvere (LON:VLE) and De La Rue (LON:DLAR)
◄Volvere (VLE)►FY(Dec). Outlook "The inevitable lag in the recovery from our customers of input cost increases. Shire, which is the most substantial part of our trading activity, has a more established position in the market compared to Indulgence and so the challenges in passing on those increases there have been lower. Indulgence is rebuilding its market position and we are cognisant of the need to build deeper and wider relationships with our key customers for the longer term. Furthermore, Indulgence's success depends on a number of factors, not all of which are easy to predict at this stage...The inflationary environment has created challenges but has also created a much bigger pool of distressed targets.". I hold
◄De La Rue (DLAR)► FY(Mar). Guides FY23 adj op profit broadly flat, and H2 weighted. Blames supply chain inflation and poss disruption. I hold.
Gulf Keystone Petroleum (LON:GKP) paying another special dividend