Small Cap Value Report (Wed 26 July 2023) - RBG, MAB1, NICL, WIL, NXR, MOTR, FRP, HVO, LTG

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections below
Mortgage Advice Bureau (Holdings) (LON:MAB1) - 564p (pre-market) - Trading update (in line currently, poor outlook) - Graham - GREEN
Mixed messages from MAB today as it says trading is “currently” in line with expectations, but there are “strengthening H2 headwinds”. Residential property has not yet seen the expected improvement in demand/activity. A frustrating delay, but I still like the stock.
Revolution Bars (LON:RBG) (Paul holds) - 5.85p pre-market (£13m) - FY 6/2023 Trading Update - Paul - AMBER
In line with market expectations. Bank debt is still worryingly high, but has come down from the March 2023 peak. Outlook "remains challenging". Peach Pubs acquisitions sounds like it's going well, with the core business struggling. Doesn't disclose proper LfLs, so I assume they're bad! But bottom line, it's trading in line with exps, which isn't bad for a tiny mkt cap. Special situation, only for risk-takers (I hold).
Nichols (LON:NICL) - 1035p (+3.5%) (£377m) - Interim Results (in line) - Graham - GREEN
Expectations are unchanged at this old beverage company, the maker of Vimto. The Out of Home segment continues to struggle but a completed strategic review should hopefully boost performance next year. As inflation cools, I think this stock can see better days.
Wilmington (LON:WIL) - Up 17% to 304p (£268m) - FY 6/2023 Trading Update - Paul - GREEN
Ahead of expectations update today for FY 6/2023. I think this looks very good - strong profit growth, and a reasonable valuation - seems a nice GARP share. Thumbs up from me.
Norcros (LON:NXR) - 167p (-2%) (£149m) - AGM Trading Statement (in line) - Graham - AMBER
This bathroom and kitchen products supplier owns well-known brands such as Triton. The stock usually looks cheap and is currently depressed. I can’t bring myself to give it the green light, preferring to look for cheap stocks with better performance and fewer complications
Motorpoint (LON:MOTR) - Up 6% to 108p (£98m) - AGM Trading Update - Paul - AMBER/GREEN
Strategy has been changed to focus on profit/cashflow and cost control, which I'm pleased to see. Motorpoint says this is working, with upbeat noises about Q1 and Q2. House broker has left forecasts unchanged, possibly laying the groundwork for an ahead of exps update later this year? I'm leaning towards being moderately positive on this, medium term.
Agenda - is huuuuge! We'll do what we can, prioritising not in line, price movers, and anything that we think looks interesting -
We've had a look (however brief), at everything!
Paul’s Section:
Not a small cap but…
Rolls-Royce Holdings (LON:RR.) - a striking 24% share price rise to 189p. Triggered by a very positive H1 trading update (materially ahead) and a big uplift in full year guidance. Might be worth readers having a look at this one?
Revolution Bars (LON:RBG) (Paul holds)
5.85p pre-market (£13m) - FY 6/2023 Trading Update - Paul - AMBER
Revolution Bars Group plc ("the Group"), a leading operator of 68 premium bars and 21 beautiful pubs, trading mainly under the Revolution, Revolución de Cuba and Peach Pubs brands, is pleased to update on the year ended 2 July 2023 ("FY23") which is anticipated to be in line with market expectations.
Sorry, I have to cover this one first, as it’s a personal holding, so I'd be looking at it anyway, hence might as well share my notes here.
The core business is late night bars. Like a lot of hospitality businesses, it got into trouble in the pandemic, and had to do 2 placings, both at 20p per share, which cleared its bank debt. Then more recently I was shocked when management maxed out the bank borrowings again, to buy Peach Pubs. This has not gone down well with the market, and the share price has been very weak since, mainly I think due to management voluntarily making the share high risk again, through a debt-fuelled acquisition, at precisely the wrong point in the cycle.
So this share is I would say a special situation, higher risk, in a horrible sector where it’s extremely difficult to make any money right now. So why get involved? Because the market cap of £13m is tiny, giving big % upside once recovery begins. Just for full disclosure, I bought these at c.6p a few months ago, as a turnaround/recovery/special situation, fully aware of the risk. I’m targeting an exit c.20p if recovery gets established, with a say 1-2 year timeframe.
The news today is quite reassuring to me, given the extremely low market cap of only £13m, although net bank debt still looks too high, at just over 3x EBITDA (old basis, IAS 17, which is the only basis that makes any sense!) -
With a positive contribution from Peach Pubs, and notwithstanding the challenging trading conditions for our late-night bars, we are pleased to be able to confirm FY23 EBITDA (IAS 17) is expected to be in line with market expectations of £6.6m. The Group had net bank debt of £20.8m as at 25 July 2023…FY23 has been very challenging, however we have controlled costs and limited capex in the second half to reduce net debt.
EDIT: Note that £6.6m EBITDA turns into a forecast loss before tax of £(2.7)m, due to large depreciation charges on the multiple sites.
Bank debt - that’s strange, as 6 months earlier, at Dec 2022, net bank debt was disclosed as £18.5m, so it seems to have gone up to £20.8m, not down! However, there is a disclosure in the interim results that net debt was £23.1m at 6 March 2023, so the latest figure of £20.8m at 25 July 2023 has indeed come down usefully from that earlier peak.However, single day snapshots can be very unreliable, because it all depends on when supplier payment runs, VAT payments, and payroll are run. Whereas money coming in would be on a daily basis, from the card processing merchants (hardly any cash or cheques these days, I think they’ve gone cashless in my local Revs, which I mystery shop regularly).
The interim results disclosed a facility of £27m [EDIT: Finncap note today says the bank facility is £30m] , so it’s still utilising the bulk of the facility, which makes me nervous. The fact that capex is being restricted is clear evidence that management knows borrowings are stretched.
Overall though, I think today’s update has reduced my worries about the bank debt from high, to medium-high. It’s coming down from the peak in March, but I’d like to know more about the covenants (which we were told were relaxed, in the interim statement).
As it’s not doing any more new sites, or refurbs at the moment, then it should generate positive cashflow.
Outlook -
We expect the trading conditions we operate in to remain challenging for FY24 and look forward to the all-important peak trading period at Christmas which we hope will be the first uninterrupted peak period since 2019.
The commentary seems to suggest that Revs’ generally younger customers have somehow been hurt the most by the cost of living squeeze, whereas I would have thought largely the opposite! They’ve benefited from c.10% minimum wage increases recently, and generally don’t have to worry about mortgages.
LfL sales - we need LfL figures vs last year, which I assume must be bad, as they’re not provided! Instead we’re given a comparison with pre-covid, which is not useful any more, as that’s c.4 years ago, during which time many costs (esp. food/drink & wages have increased greatly). Anyway, these pre-covid LfL sales comparisons are -
Peach Pubs +14%
Overall group -8.7%
Nicely dodging disclosing the Revs figures I see! So what might those be, worse than -10%, maybe nearer -15%? That’s pretty awful.
Still bottom line, is that it’s overall traded in line with expectations, so the forecasts must have been anticipating soft trading.
Paul’s opinion - obviously a tough sector at the moment. In line with expectations is good enough for me, and with net debt high, but reduced from the March high, I’m less worried than I was.
Not for widows & orphans this one, but if it can continue reducing bank debt, with trading not getting any worse, then the shares should recover.
Downside risk is if the bank panics again, and demands another placing.
Some of the larger pubs groups have had big rebounds, and I think there’s a decent chance this might too. As I say, very much a special situation, not a regular investment.
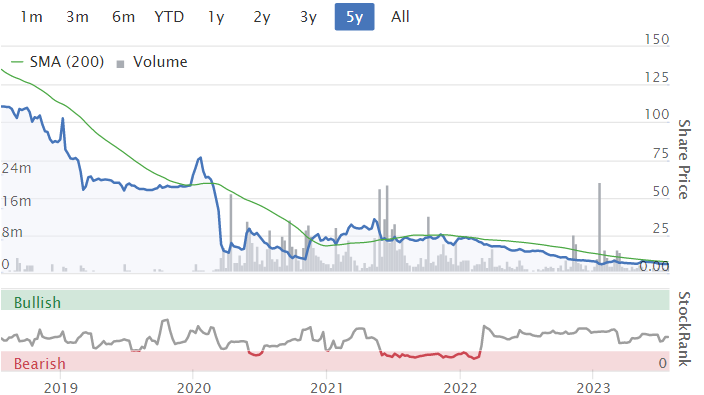
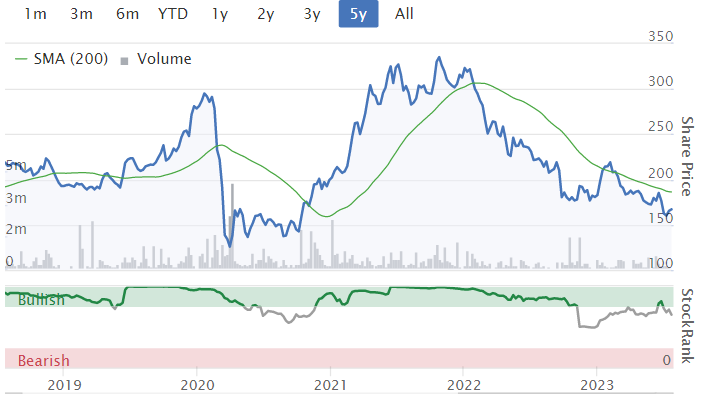
Note from 5-year chart below, the shareholder value destruction from increasing share count from 57m to 230m, via two placings at 20p. So the price will never get back to previous highs probably, so no point in drawing lines on any chart where there's been heavy dilution. Still, we can buy now at 6p, clearly a better price than the emergency bailouts, with the business stabilised post-covid now too.
Wilmington (LON:WIL)
Up 17% to 304p (£268m) - FY 6/2023 Trading Update - Paul - GREEN
Wilmington plc, (LSE: WIL, 'Wilmington', 'the Group') the provider of data, information, education and training in the global Governance, Risk and Compliance ('GRC') markets, today provides a trading update for the year ended 30 June 2023.
We’re overdue a catch up with this share, having not reviewed it yet in 2023.
I last (briefly) looked at Wilmington here in July 2022, liking its ahead of expectations update, cash pile (previous debt cleared), and an attractive valuation (at 272p/share), giving it a thumbs up at the time.
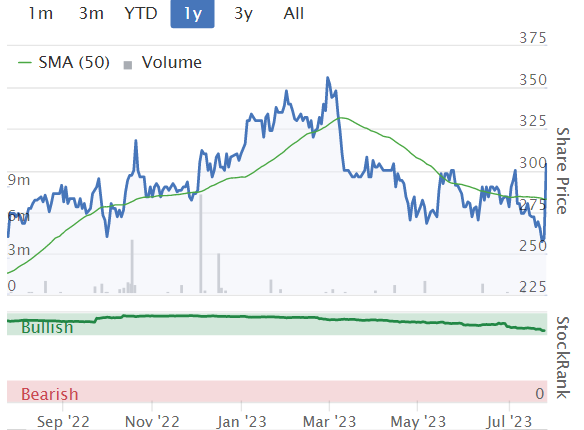
In the last year, the share price steadily rose from 272p, peaking at about 350p in Feb 2023, before falling all the way back down again by yesterday. Today’s sharp 17% rise has caught my eye.
Trading Update today - FY 6/2023.
This is good, ahead of expectations -
Adjusted* profit before tax (unaudited) from continuing operations is expected to be £24.1m, up 30% on last year.
Adjusted profit before tax (unaudited) is likely to be ahead of expectations at £24.3m* (2022: £20.7m), up some 18%.
*Adjusted profit before tax (PBT) is calculated as PBT after adding back amortisation of intangible assets except computer software and profits/losses on disposals and business closures. Market consensus Adjusted profit before tax is £22.8m.
Isn’t it great when companies report precisely like this? This is the gold standard of reporting, that all companies should do - tell us what profit is going to be, and tell us what market expectations are, rather than leaking the information to brokers with restricted distribution - which I've always thought is questionable legally, as it breaks the principle of all shareholders being told the same information simultaneously.
I’m not sure what the £0.2m discrepancy above is, maybe discontinued operations? It’s not significant though, so let’s move on.
Net cash - is strikingly higher, both on 6m and 12m view - although we need to see the full accounts to ascertain if there have been any other balance sheet movements which might have helped flatter this figure. This is significant, with £42.2m net cash being c.16% of the market cap -
Cash conversion continued to be strong with Group net cash on 30 June 2023 at £42.2m (31 December 2022: £22.9m; 30 June 2022: £20.5m).
CEO comments read very positively -
Mark Milner, Chief Executive Officer, commented:
"We continue to execute our strategy which has resulted in another year of strong organic revenue and profit growth - our revenues were up by 9% and profits were up by 30%. We have also continued to see good growth in our recurring revenues and strong cash conversion of profits.
"Over the last two years, the business has seen a solid growth in its international scale and reach which has resulted in our profits growing in each quarter."
It will be interesting to see the full accounts, so we can see whether the 30% profit growth has come from operational gearing, margin improvement, or cost-cutting? Or a mixture of those perhaps?
Paul’s opinion - I’ve commented before on Wilmington’s erratic prior year performance, and I would have expected this type of business to suffer badly in the pandemic.
Performance now seems dramatically better than even pre-pandemic, so it looks as if there must have been a turnaround (was management changed maybe?) to deliver much stronger profitability from fairly static revenues over the period in the graphs below -
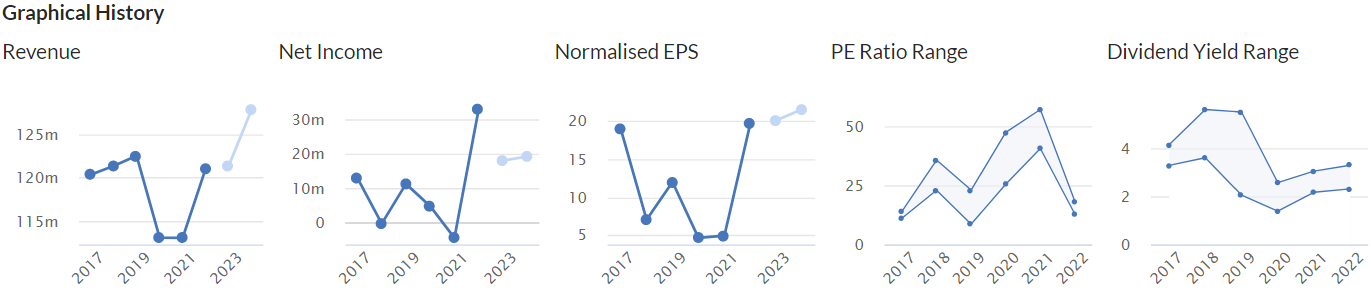
With revenues now growing, and margins high, this looks an interesting situation, and still priced reasonably I’d say (as of last night) - note the high quality measures, and a very reasonable PER of 12.0, for a company that is also cash rich. Although note that the last balance sheet only had negligible NTAV of c.£2m. The cash pile comes from advance customer payments.
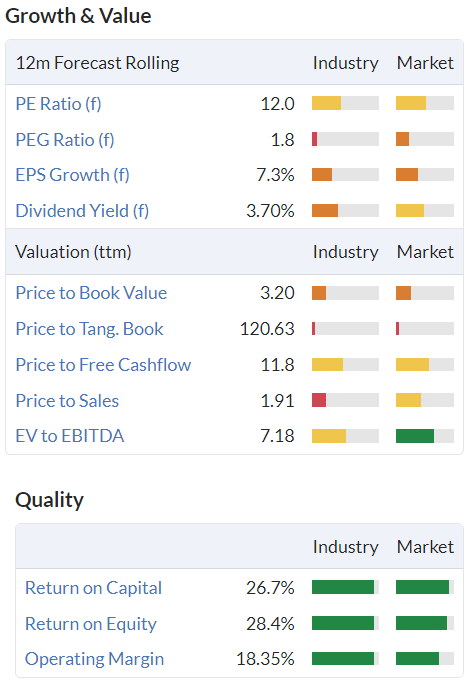
There’s a helpful forecast divi yield of 3.7% - maybe not that exciting now with inflation at c.8%, but once inflation is down below 5% probably in early 2024, then yields on shares would be looking more attractive again, especially as they have built-in inflation protection, and should rise over time, all being well.
Overall - this looks an interesting, high margin niche business. I like the numbers a lot here, at a reasonable valuation. Thumbs up from me, on an initial review - as always the detailed research work needs to be done by you.
Bear in mind today’s 17% share price rise is based on a c.7% out-performance in profits vs expectations. So maybe it needs to pause for breath, or retrace a little in the very short term?
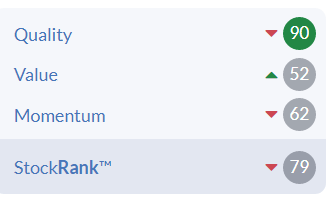
Stockopedia likes it too, and I imagine the value and momentum scores might rise once higher forecasts, and share price bounce, feed through in the coming days?
Motorpoint (LON:MOTR)
Up 6% to 108p (£98m) - AGM Trading Update - Paul - AMBER/GREEN
Motorpoint Group PLC, the UK's leading independent omnichannel used vehicle retailer…
To clarify, Motorpoint sells nearly new cars from large out of town sites, car supermarkets. Also selling online.
This share is in our “potentially interesting” tray, in terms of the business model, but the previous strategy was a dash for growth, at the expense of profitability.
To set the scene, here are our previous comments on MOTR shares this year -
27 Jan 2023 - AMBER - 144p - Profit warning, only breakeven. Shares didn’t move, strangely.
6 Apr 2023 - AMBER - 131p - (Roland) - record sales, but only breakeven.
14 Jun 2023 - AMBER - 120p - Breakeven FY 3/2023 results on £1.44bn revenues. Potentially interesting if margins can be increased.
Shares recently touched 100p, but are up to 108p at the time of writing (11:47).
Is it cheap enough for us to push from amber to green? Let’s see.
Today’s update covers Q1 (Apr-Jun 2023) of FY 3/2024.
Difficult macroeconomic conditions continued into Q1.
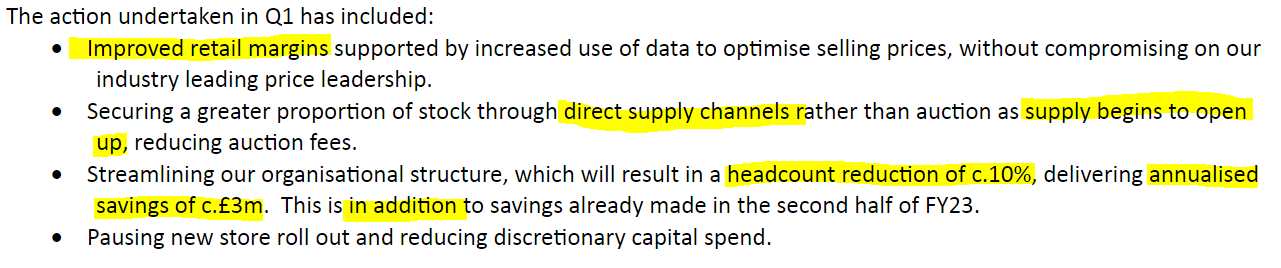
Short term focus on higher margins, and reduced overheads, to improve profit/cashflow.
Looks like this is working -
Trading performance improved throughout Q1 and we expect this trend to continue in Q2 reflecting further improvements in margin and cost base reductions.
Liquidity - negligible net cash of £2.2m at end June 2023. Also has £35m facility headroom.
Balance sheet - not mentioned today, but I’ve looked back and see the last balance sheet at March 2023 is very light compared with the franchised dealer groups, which tend to own loads of freehold property, so have tremendous asset backing.
MOTR doesn’t, and NTAV is only about £35m. Something to bear in mind, when weighing up risk:reward.
Outlook -
As previously communicated, the impacts of high inflation, rising interest rates, and consumer uncertainty continue to affect demand for used cars. However, like others in the industry, we are encouraged by the growing number of vehicle supply options which, coupled with our increased use of data to determine optimum selling prices, has resulted in an improvement in retail margin. This will, in part, be tempered by lower finance commission as consumer uptake for finance reduces due to increased APR rates.
The Group has also focused on the costs of the business to ensure they are aligned with current market activity and, utilising the investment in technology to date, we are able to maintain a lower headcount as we conserve cash and return to profitability, whilst ensuring we are ready to invest for growth as more favourable market conditions return.
The Group continues to be confident it will emerge in a normalised market as a leaner and more valuable business ready to seize a significant opportunity.
Broker update - Shore Capital is house broker, and thanks for their update note today. I’m a bit surprised they’ve left forecasts unchanged, for a £(3.0)m loss before tax for FY 3/2024. That seems rather pessimistic, given that the company has just told us that trading is improving, and it's moving back into profit. Maybe they want to keep expectations grounded, in case macro worsens? If I were to invest here, I’d be expecting something like £3-6m PBT for FY 3/2024 - so chance of a beat in future maybe? Or at least room for some slippage.
Paul’s opinion - I’m glad MOTR has reined in its aggressive growth strategy, which saw profits disappear to breakeven. I suspect they might have been urged to do the rapid growth by an influx of American shareholders. The recent focus on improving margins, and curbing costs, I think better reflects current market conditions, and I’m sure shareholders wouldn’t want to be diluted with an equity raise at the current c.£100m market cap.
With new car supply now starting to improve (but other dealers have said they expect constraints on used cars to continue for c.2-3 years), MOTR could find it tough to eke out even a small profit for now.
Longer term, I think the car supermarket + online strategy is excellent, and could well be a winner, especially as the online-only proliferation of VC-funded competition run out of money and disappear one by one, which I expect to see happen.
Since trading is now improving, above breakeven, I’ll ease the boat out a little, so will move from amber to AMBER/GREEN - moderately positive, and reflecting that there’s nothing in the short-term to get excited about, but medium to longer term, this share could have promise.
If it manages to make a 1-2% profit margin on £2bn future sales, you can do the maths! Shares would then justify a price maybe 3-5x the current price. Although to actually get there, won’t be easy, with so much competition in the sector.
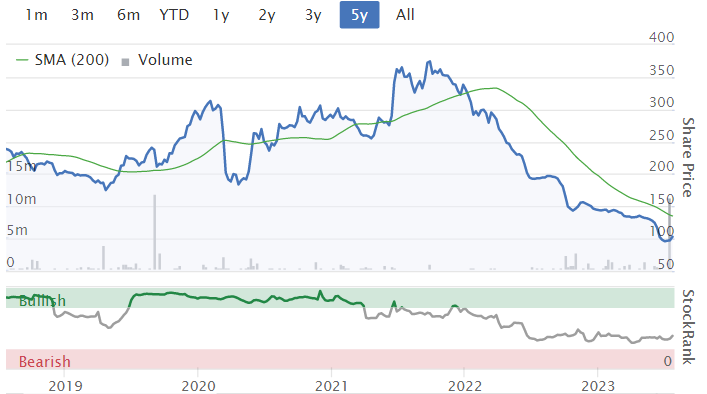
This 5-year chart below reflects that, so far, the original business model hasn't really worked. But it also gives an idea of the upside potential in an economic and stock market recovery maybe, once people start anticipating future growth. Note there hasn't been dilution, with the share count actually falling due to buybacks - so the bull case as mentioned above, is an eventual possible return to 300-500p if everything goes well. It might not of course, we don't know.
Quick Comments
Frp Advisory (LON:FRP)
Down 1% to 120p (£299m) - FY 4/2023 Results - Paul - AMBER
Mid-market insolvency practitioners. Results show a small improvement in adj profitability, to 7.83 adj EPS - PER of 15.3x - looks about right to me. Outlook - in line with expectations so far, and upbeat given favourable macro conditions for insolvency firms.
Paul’s opinion - FRP, and Begbies Traynor (LON:BEG) might be a nice safe place to park some money, if you think the economy is really going to tank.
hVIVO (LON:HVO)
Up 4% to 16.6p (£113m) - Trading Update - Paul - AMBER/GREEN
hVIVO plc (AIM & Euronext: HVO), the world leader in testing infectious and respiratory disease products using human challenge clinical trials, announces a trading update for the six-month period ended 30 June 2023.
This looks pretty interesting, although only in line with expectations -

Paul’s opinion - short of time today to go into any more detail, but I just wanted to flag this to readers. I’ve looked at it in more depth before (see our archive), and think it’s a very interesting story. Putting me off a little, is the CEO seems too promotional in webinars, which I’m wary of.
For more detail on the numbers, see Liberum’s helpful update note today.
I can’t make up my mind whether to be green (as on 25 Jan 2023, and 6 Feb), or amber (per 10 May SCVR). Let’s split the difference, and go AMBER/GREEN.
Learning Technologies (LON:LTG)
Down 20% to 67.7p (£535m) - H1 Trading Update (profit warning) - Paul - AMBER
LTG, the leading provider of services and technologies for digital learning and talent management, announces a trading update for the six months to 30 June 2023.
LTG has previously warned of slower growth this year, hence the share price falling.
Today it guides H1 revenue will only be up 2% vs H1 LY, and flat on a LfL basis.
H1 adj operating profit (EBIT) £43m+, flat vs LY £43.5m.
Revised full year guidance (FY 12/2023) -
In light of the first half performance, for the full year ending 31 December 2023 we now expect Group revenues in the range of £550 million to £570 million and adjusted EBIT in the range of £98 million to £103 million (based on an average GBP:USD rate of 1.28 for H2 2023).
Looking back at FY 12/2022 accounts, a similar adj EBIT of £100.9m became only £40.5m statutory PBT, but most of the adjs look valid, being acquisition-related. Not the simplest of accounts to make sense of though.
LTG’s balance sheet is not good, with negative NTAV, and a fair bit of debt, which of course is more expensive now, so adj EBIT ignores finance charges, hence isn’t a good profit measure.
Balance sheet - is weak, but management falsely claim again today that it is strong. In the same sentence they then emphasise de-gearing, to net debt of £108.4m, which of course contradicts itself! The truth as I see it, is that a negative NTAV, with over £100m in debt, is clearly weak. However, the business remains sufficiently profitable to be able to cope, providing things don’t get any worse. So I’m not alarmed by the debt at this stage.
Paul’s opinion - looking at our archive, we were amber on 26 April 2023, and amber/green on 12 June, thinking the drop in share price to 99p meant the shares looked potentially interesting. Another lurch down 20% today to 68p, on what seems a fairly mild profit warning (understandable given macro conditions) could be lining up a possible buying opportunity, if you like the company and what it does. Investors can’t expect companies like this to just keep growing, regardless of macro. There are bound to be customers retrenching in some sectors. So I remain of the view that LTG might be potentially interesting to research further.
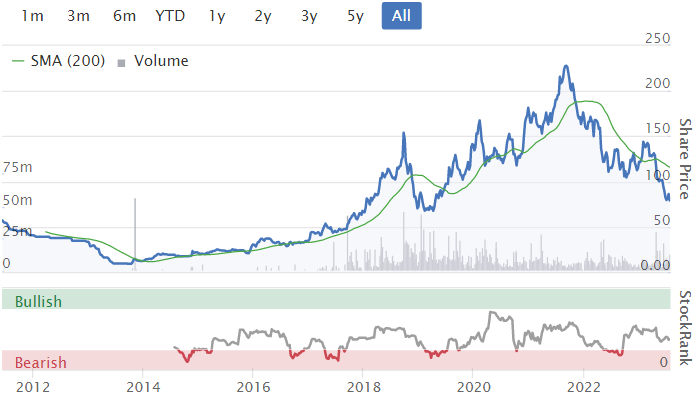
All the way back down to 2018 price. Did it expand & acquire too aggressively?
Graham’s Section:
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Share price: 564p (pre-market)
Market cap: £322m
Trading is in line with expectations at the Mortgage Advice Bureau, and yet this is a gloomy update as far as the H2 outlook is concerned. This is how the company puts it:
Despite the strengthening H2 headwinds, trading is currently in line with market expectations and the Group is well positioned to deliver further growth as the market recovers.
Let’s take a step back and see how the company did in H1:
Organic revenue growth +1%.
Total revenue +21% to £116m.
The number of advisers working at MAB’s franchisees fell slightly (4%), but they individually delivered more revenue (5%), adding up to that 1% organic revenue growth. That’s in line with expectations and surely a decent result in the circumstances? The company provides this table showing the sharp fall in new mortgage lending in early 2023:
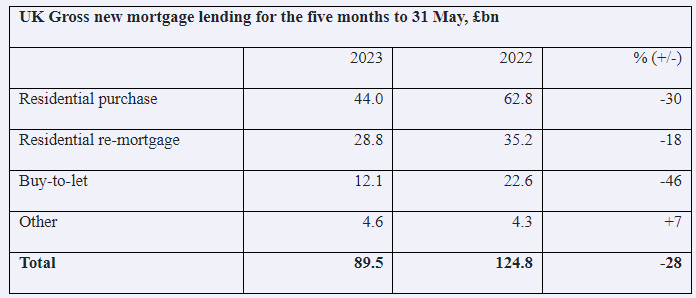
MAB estimates that its market share of new mortgage lending rose to 8% in the first five months of 2023 (from 6.8% in H1 of last year).
Outlook
The H1 picture is clear enough: MAB grew market share in a declining market and met its expectations.
Unfortunately, the outlook for H2 appears to have deteriorated. The company had previously guided that H2 would see an improvement in performance:
The new mortgage approvals reported in Q2 2023 suggested that activity levels had started to improve. However, market conditions are now likely to toughen further in H2 2023, driven by a continued rise in interest rates and fewer consumers opting to purchase or move home at a time when mortgage rates are at or close to peak levels in this current interest rate cycle. However, we expect re-financing will continue to perform strongly
MAB now says “it is too early to anticipate” when demand and activity will strengthen again.
CEO comment excerpt:
…we find ourselves in an environment of continuing interest rate rises, reduced affordability, and cost of living increases, all of which are naturally impacting consumer confidence. Despite strong underlying demand for property, some buying decisions are understandably being delayed by our customers until we have a more stable economic and interest rate environment.
"Despite the additional market pressure, I am delighted with how MAB is performing and how our market share continues to grow. Re-mortgages and increasing numbers of product transfers currently represent around 60% of our written transaction volumes.
Graham’s view
I’ve had a consistently positive view on this company and I’m inclined to keep that today. There is no organic growth from it currently but it does appear to be outperforming the wider market. The acquisitions will hopefully boost the results too, e.g. Fluent Money (acquired last year) was expected to be “significantly earnings enhancing” in 2023.
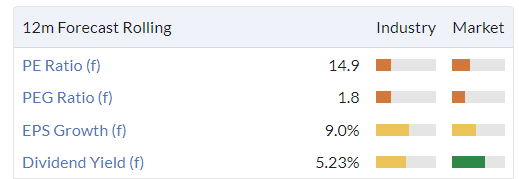
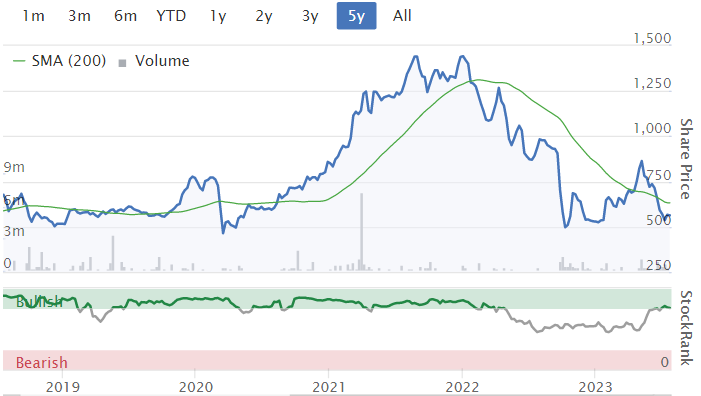
I view this as a quality stock in a cyclical market, so I think it’s interesting around these levels.
Nichols (LON:NICL)
Share price: 1035p (+3.5%)
Market cap: £377m
This is an old beverage company that has struggled with profit margins in recent years. I’ve been positive on it, thinking that a recovery in margins should occur sooner or later.
Today’s H1 results show the gross margin falling to 41.1%, but at the same time the adjusted pre-tax profit margin improves slightly to 14.4%. So it’s not all bad news on that front, but there’s still hopefully going to be margin improvement in the company’s future.
Inflation is mentioned nine times in today’s report: the company says that the underlying cost of goods inflation is around 16%. Of course the effect of that on margins is going to be tremendous - I think that Nichols has done well in the circumstances.
Revenues rose 6.6% to £85.5m. The company says it has a “value over volume” strategy, so volumes are presumably falling, although this is not disclosed.
The company remains cash-rich, sitting on £56m.
Expectations for 2023 are unchanged. The consensus adjusted PBT figure for the year is £25.2m.
The CEO updates on some improvements to strategy:
The Group achieved significant strategic progress during the period, particularly in relation to our Out of Home business where we are making positive changes to simplify operations and focus on the areas of greatest opportunity and profitability. We are on-track to deliver the material benefits of these changes from FY 2024…
About three quarters of revenues are from the “Packaged” segment, with the rest being “Out of Home” (OoH).
As you’ll note from the CEO’s comments above, OoH has been the focus of much strategic thinking. The following disclosure of profits in each segment, which the company has never published before, helps to show why OoH has been focused on. It isn’t nearly as profitable as it should be:

Graham’s view
It’s possible that I was too optimistic on a quick recovery in margins at Nichols, but at the end of the day these results are in line with expectations. In my view, the company is still recovering from the incredible shock brought by Covid, but it is getting there:
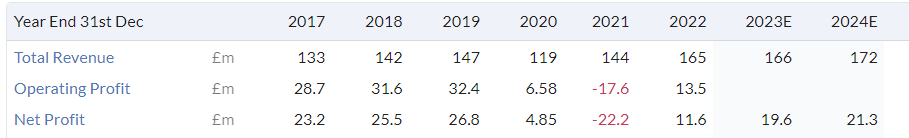
Inflation is the key driver that is beyond the company’s control. It both disrupts profit margins and affects demand.
While we wait for things to normalise, I’m going to keep my positive stance. I still think of this one as a family business (there are two Nichols on the Board) and as a high-class investment.
Norcros (LON:NXR)
Share price: 167p (-2%)
Market cap: £149m
Norcros plc ("Norcros" or the "Group"), a market leading supplier of high quality and innovative bathroom and kitchen products, issues the following trading update covering the 13 week trading period to 2 July 2023
Full-year expectations are unchanged at Norcros. Performance in Q1 (April/May/June) is described as “resilient”.
However, like-for-like revenues are down:
Group LfL revenue down 4.2% “compared to the strong prior year comparator”.
UK LfL revenue “broadly in line with the previous year despite the tougher demand environment”.
South Africa LfL revenue down 10.9%, impacted by electricity supply interruptions.
CEO comment
We remain confident that our market leading brands, diverse channels and end markets, and excellent customer service proposition will continue to deliver market share gains for the year ending 31 March 2024
Graham’s view
I’m going to agree with Roland’s neutral stance from June.
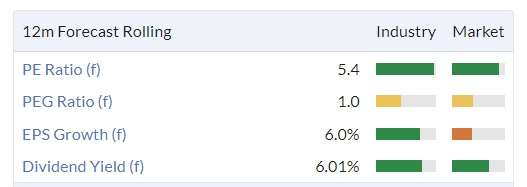
Arguably it is too cheap, but the well-worn issues with the stock seem destined to keep it so. The dividend yield is interesting but in a high interest rate environment I think it’s reasonable to expect some sweeteners to go with a 6% dividend yield. Norcros has net debt (£50m as of March 2023), falling like-for-like revenues in a high-inflation economy, and a complicated pension scheme requiring a few million pounds of deficit repair contributions every year.
So unfortunately, this stock doesn’t offer enough to get the thumbs up from me, despite a mid-single digit P/E ratio.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
A big fall this afternoon for Litigation Capital Management (LON:LIT.
Here is a link below to an article which is to do with the legality of enforcing payment over DBAs (damages-based agreements).
'Shockwaves' as Supreme Court rules litigation funding deals unenforceable | News | Law Gazette
I have no idea how many cases this could affect (it seems UK only), and if this will be easy to resolve with its clients. It seems this does not impact the courts decisions, but could impact litigation funders collecting their fees from their clients. I'm not really sure what to make of it (I hold and will await further details, I assume an imminent announcement from Lit). The rest of the sector appears unmoved for now.
No impact whatsoever.a classic case of the 2 + 2 = 11 brigade bailing out desperately over a case they don’t understand, nor the business model of Litigation Capital Management (LON:LIT) it seems.
Someone is going to get a few bargains
Congratulations and thanks, Paul and Graham! That’s heroic work. Please take care not to burn out - we need you and so does Stockopedia.
Thank you FREng! It's a genuine pleasure at the moment, as we're finding so many good companies, trading at attractive prices, so we enjoy flagging them up here. Whereas in 2021 and early 2022 I felt like a stuck record, saying every day that I liked some companies, but they mostly looked over-priced. Now so many of those companies are priced at levels I would be happy to pay. Just need to find some money to buy them next!!
Not sure if anyone follows Entain (LON:ENT) but they had a lunchtime BetMGM update - looks like Q2 is now profitable a quarter ahead of schedule and upper end of $1.8-2bn revenues for full year expected. No more capital support needed. Looks good and market seems to like it too for a change!
Yu (LON:YU.) SP ANGEL rate as Strong Buy with target price of 1300p
https://www.yugroupplc.com/wp-...
SP responding positively to yesterday's update.
eP
Thanks for sharing.
Yu (LON:YU.)
Future (LON:FUTR)
Has anyone got any knowledge on what is happening here - this company is starting to look very cheap/oversold? Yes, there is a high level of debt. Very little broker info available to PI's hence my question.
New CEO has made a large purchase of shares (c£800,00 May 23), P/E now only 5.4 but Stockopedia's forecasts show a significant up tick in Net Profit and EPS this year and next. Company is now doing buy backs (c£45M) as well, so presumably they think it is cheap too? What am I missing here?
(Just squeezes in to our territory with the recently reduced market cap).
Off topic: I'm trading WAND - wish me luck .Ignoring fundamentals ,just looking at sentiment and momentum
I'm trading WAND - wish me luck .Ignoring fundamentals ,just looking at sentiment and momentum
Haha, me too! I've broken the golden rule of not averaging down, and increased my position size by 36x, which has brought my breakeven price down from 950p to 71p.
My rationale being that now it's refinanced, with the 50p placing, insolvency risk has gone for now. Also, the fact that instis were prepared to refinance it, and lots of very rich, smart people had big positions in it, there's a chance they'll be wanting to buy in the market, rather than sell, to save face as much as anything.
Despite all the shenanigans of the past, all the bad news is out. Yet the big shareholders still wanted to save the business, and keep the listing. That tells me they think there's something good here.
Obviously not value, or GARP, just a trade as you say.
Regards, Paul.
There's quite a bit of IP with these guys and the anchoring effect (they were 13 quid) is going to create the desire to return to that- however unrealistic ! Enjoy the ride
Currently 71.26...Well done!
WANdisco (LON:WAND) Paul, is your goal to break even and sell out at circa. 71p or keep for longer to see what happens?
WANdisco (LON:WAND) Paul, is your goal to break even and sell out at circa. 71p or keep for longer to see what happens?
I'm planning on running with WAND, and see what happens, so I've not sold any so far (bought them yesterday at 47-62p). As a trade only, I think risk:reward could be quite good. So I was thinking about selling in steps if it gets into the 100-150p range, which I think is possible. This thing has a lot of very wealthy backers, who brought it back from the dead with that 50p placing. Bit of a unique situation really, so they would have only done that if they thought there was considerable upside from 50p.
Total punt, but it's now refinanced with the 50p placing. I would never have averaged down unless it had properly refinanced as part of coming back from suspension.
Maybe there were forced closures from spread betters yesterday? I was very surprised to be able to buy at, and even slightly below the 50p placing price.
Anyway, I'll shut up now, as this runs the risk of "triggering" some of the value investors! For clarity, I split my own money informally into different pots, and have some in value, some in GARP, and some for hopefully calculated punts like this!
I think averaging down splits into 2 distinct types -
1) Mindless averaging down - when you just keep buying, despite a falling share price, chasing your losses. Usually ends in disaster. This is often the case immediately after a profit warning.
2) Calculated averaging down - where you've weighed up risk:reward in a rational way, and made a buying decision based on that.
Some of my best investments have been the latter, and some of my worst have been the former!
I also like the key question someone else mentioned yesterday - ask yourself would I buy now, if I didn't hold any already? That's often a crucial point I find.
Anyway, I'm now only 2% down on WAND, as opposed to 96% down yesterday, so that's rather pleasing! :-)
Regards, Paul.
Whilst I'm happy the trade has worked for you (so far) I notice your rationale is completely absent of any comment on company metrics. You're basically punting that richer or more knowledgeable investors than you know what they're doing.
How is that calculated averaging down?
I think you answered your own question.
I'm just punting on WAND as a short term trade on sentiment, not an investment.
Destiny Pharma (LON:DEST) shares have suffered like many smaller biotechs, but attracted recent attention by gaining the extremely well regarded Sir Nigel Rudd back as Chairman, plus a new CEO with $mega-cap sector experience. Why would they join a £30m cap AIM co ? New research note out today has some insight:
https://www.equitydevelopment....
Rua Life Sciences (LON:RUA) issued unqualified audited results today. Not bad in themselves, but they've been issued without new funding, and it appears that the management have qualified their own accounts. As I understand it, in the 'unlikely' event that new funding is not available, the management will take 'mitigating action' which may or may not be successful. But I imagine they've been already been mitigating hard for months as money has got tighter. I still hold, and the price hasn't yet fallen through the floor so perhaps the management still has some credibility.
A very interesting turnaround at NAHL (LON:NAH) (I hold). As noted by MassimoJ below profits and cash flow at the business should increase dramatically over the next 2 years, with the business trading currently at around 2.5 x expected 2025 free cash flow.
A previous write up by Paul mentioned a concern that a large amount of cash goes to non controlling partners. This is a legacy format which is winding down substantially down now YOY (30% reduction this year already).likely moving down close to zero by 2026.
By 2025 there is a high probability that the business will be largely debt free, generating £8mill plus in cash flow, with 2 industry leading businesses.
The high probability of the outcome comes from the fact that a lot of future revenue is already baked in and therefore highly predictable. And also from the strength and growing market leading positions of its 2 brands.
It’s a small business though so often flies under the radar and dismissed as an ambulance chaser, which confuses because in reality it doesn’t chase leads they are all incoming. And it ignores the seperate business which the company owns bush and co which is a highly cash generative critical care business with a leading market position.
Christopher mills who I know a lot of people value his opinion values just tge bush and co business on its own around £40 million, twice current market cap (which complexly leaves out the national accident helpline and in house law business)it’s worth a closer look for those who have an interest
Rua Life Sciences (LON:RUA) - new report here: https://www.equitydevelopment.... *** RUA Life Sciences final results for FY 2023 were in line with the earlier trading statement and reflect the costs associated with the development of its vascular and heart valve products, its cash-generative business segments, cash conservation and a higher R&D tax credit.
Outside the financial results which conformed with the recent trading statement where contract manufacture revenues were ahead of our estimates and total administrative expenses were below, there have been interesting advances at RUA’s Structural Heart division. Our note discusses the rising tempo of the developments in RUA’s replacement aortic heart valve product, the emergence of the composite leaflet version as the preferred prototype and its advantages and attractions.
Our fair value has changed from £121 million (or 545 pence a share) to £120.3 million (or 542 pence per share).
Rua Life Sciences (LON:RUA) . Yes, but see my note below. The qualification comes right at the end of the report.
Interestingly Marston's (LON:MARS) (I hold) came out with a trading update today as well as Revolution Bars (LON:RBG) . Both have a large amount of debt. The former though has a reported NAV of 98p so falls into the "better dead than alive category". Pub turnover seem to be holding up well, as indicated by J D Wetherspoon (LON:JDW recently.
hVIVO (LON:HVO) decent half year and trading in line with a growing order book, that alongside yesterdays £13m order has effectively de-risked next years numbers as well.
I had hoped for a bit of a beat but that came from the net cash position of £31m after the special dividend.
So looks like cash adjusted PER of 10* which for me is just way too cheap. Unsurprised to see a tick up this morning. My suspicion though is that the most likely route to shareholder value here will ultimately be a sale to another larger CRO.
See Rolls-Royce Holdings (LON:RR.) up 20% Thats a huge increase in forecast free cash flow. I should have just bit the bullet and bought when they had a rights issue . Up 190% since October lows.
"The London-based jet engine and power plant manufacturer said it expects to report underlying operating profit of GBP660 million to GBP680 million, well above consensus of GBP328 million and GBP125 million in the first half of 2022. Free cash flow is estimated at GP340 million to GBP360 million, versus consensus of GBP50 million"
Completely wrong footed me - their Rights issue was Mahooosive and frightened me off !
Rolls-Royce Holdings (LON:RR.)
Limited research but saw on youtube their F130 engine has been adopted to extend the life of the stratofortress for for another long time (don't need it but thats another story). Stiff competition from Pratt Witney (Raytheon).
The Trent engine had issues but believe ironed out with the XWB97. RR were at the top of their game at one time.
Air travel holiday wise has sustained so get the cash from maintenance.
Have Small Modular Reactors in their arsenal - govt support (shh!) if they can get one on the ground working by 2025 then should be a 'spark'. Competition is there from Asia/Canada/USA partnerships but hopefully our govt has finally smelt the coffee.
Technical analysis (share price with teal leaves) says good to go to the next round number say 200 but not clear will go much further at this time.
Thank you for your thoughts on MAB1 - very helpful and clear.
I hope that DATA has not really dropped over 80%
and this is due to “8,450,277 Ordinary Shares and be sub-divided into 100 Ordinary Shares of0.0001 GBP each”
GlobalData (LON:DATA) is a Mid-Cap share but still not immune to the machinations I have experienced in the Small Cap world. I don't hold.
GlobalData (LON:DATA) did a consolidation. Effectively 7 for 1 so divide last nights share price of 1250p by 7 and you get 175p which is where it is trading today….ie no change. You own 7* the number of shares you did at 1/7th of the share price.
nb: I had thought this was a 14 for 1 rather than 7 for 1 but looking at the share price that just be wrong else the share price has doubled overnight which I very much doubt!!
David what is the opposite of a Consolidation? GlobalData (LON:DATA) have done a Split, hence more shares in issue, just to avoid confusion.
Haha - yes, quite right. I meant a split rather than consolidation (clearly I’m too used to companies with more shares than confetti consolidating).
This split is being done because GlobalData (LON:DATA) believe the old share price was putting off retail investors both with size of spread and the absolute price of one share being prohibitive. Thus liquidity is lower.
I buy the spread story but not so sure on the price. Ok it’s not a penny share but I can’t believe retail investors are put off by paying £12.50 per share. I can understand buying into Buffett requires a big investment for a single share but this is £12.50!! The market cap and P&L doesn’t change…….
Revolution Bars (LON:RBG) I read the RNS this morning & concluded that if they hadn’t recklessly acquired Peach it would potentially be game over as business in the core Revs biz has fallen off its barstool & may struggle to remount
Thats what I thought too, purchased an expensive life raft. I can see in theory why revolution bars should do well with a younger customer base, many living with parents so less exposed to cost of living challenges and in theory more spare cash. Hasnt worked out that way tho by the looks of things, the oldies have rode to the rescue. Viva La Revolución
So glad I gave up on this crock 4 yrs ago when I'd only lost 60%.
"Revolution Bars Group is in great shape. The business is well positioned with a net cash position to fund our new site and refurbishment programme." - CEO a year ago. SP 15p.
A few days ago Revolution started a £2.99 Meal Deal. £2 extra for a pint. https://rev-website-admin.revo... Serving up desperate measures!
That reminds me, I had to mystery shop the £2.99 meal deal from Revolution Bars (it's only at quiet times on weekdays, when it would normally be empty). You can upgrade it to £4.99 to include a pint of Amstel. So I tried the fish + chips with mushy peas & tartar sauce -
Obviously it's a small portion for £2.99, what do you expect? But quite tasty (fish batter was rock hard though, as fried for too long). Basically like a big fish finger, with some chips. I enjoyed it though, but had to order a second lunch to properly satisfy my hunger (and thirst) -
The chicken wrap, with chips, and a pint of Amstel -
This was very nice actually, with a decent sized breaded goujon type of chicken, with some salad and sauces (BBQ, mayonaisse). Very tasty, I enjoyed it! Staff bring the food over to you, and offer sauces, etc.
Hence 2 hot (small) meals and 2 pints of Amstel for a tenner - not bad at all, I might return today actually.
Why are they doing this? To get people in, at off-peak times, and hope they'll take root and order more drinks, I suppose. They're having to heat/light/staff the bar anyway, so any additional business helps.
I think there's a lot to be said for just closing during the day in the early part of the week. Mind you, in Bournemouth at the moment there are lots of tourists, it's really busy, so maybe worth keeping open all the time?
It's so tough to make money in this sector, we all know that. It's what the recovery over the next say 5 years looks like, that will be interesting!
£13m mkt cap is a lot of business for the money, if it manages to keep the bank manager onside. Risky though, that's why the equity is so cheap! Not for widows & orphans this one, obviously (I hold).
Regards, Paul.
Paul, I think Revolution Bars (LON:RBG) is in danger of getting stuck in a Catch 22 situation. You can't refurbish more bars until they trade better, but they aren't going to trade better if they are tired looking. Our local branch got a makeover last year and seems to be trading quite well - but with plenty of competition and the majority of the estate in need of a freshen up, their younger cliente has plenty of other city centre options rather than a tired Revs. (No position.)
On hVIVO (LON:HVO) (I hold) I think the strength of the order book has allowed them to juggle a bit and thus hit their target, offsetting some disruption caused by the noted approval delays. Will be interesting to see how the second half pans out - their target for this year was not that stretching given the order book, and I have been hoping for a modest beat. Still generating good cash though.
Weren't you heavy on this one for much more than 6p though!!?
Hi ben,
I've been in & out of Revolution Bars (LON:RBG) (I hold) quite a few times, over quite a few years. Making, then losing loads, then getting it all back again when I bought shed loads at 11p and sold at about 35p, just before it crashed again. It's been very volatile, so I think it's one to trade now rather than buy & hold.
As I said in the main article, long-term there has been great value destruction, and it's just not a very good business. Investors were crazy to turn down the c.200p takeover bid years ago, but it looked cheap at the time. But wasn't, as the bars were being neglected instead of being refitted regularly.
I've not touched it for a while, but went back in recently at just under 6p. So that's my current buying price, about 7% down currently. As mentioned, I'm hoping for upside case to 20p, but fully aware there's considerable downside risk too.
Definitely one of my riskier punts, as I say every week in my podcasts too!
But actually, today's update was not as bad as I was expecting. Whatever all the background noise is, the update was in line with expectations, and they've managed to reduce debt a bit since March. So I'm a little less uncomfortable than I was yesterday.
Regards! Paul.
Excellent value offering, and sufficiently enticing to bring Go Dry this July to a slightly premature end . . . . .
Oh yes, that went out the window I'm afraid! ;-)
Appreciate its a busy morning today, but NAHL (LON:NAH) trading update is an interesting one.
The long awaited transformation of the group is starting to pick up pace and cash generation is starting to show through, with £1.7m generated in the 6 months to June. That’s against a market cap of £20m. Due to the nature of their Personal Injury division, earnings and cash flow should see a hockey stick increase over the next 1-2 years.
Allenby (house broker) have them at 6p of earnings for next year and 11p for the year after (43p sp). Because much of those earnings are the result of cases that are already underway, they are predictable too.
Good morning Gents, any thoughts on MAB1's update from this morning would be appreciated. Thanks!
Marston's (LON:MARS)
Reasonably solid trading update here - this company is presentlya walking zombie with its debt levels and expected profit levels (if stocky is to be believed) well down from pre cvoid level. Glimmer of hope in that they finallyu expect to make soem headway in the debt - but unless they can ramp profits up quickly and keep financing costs down medium term i can't really see this company as being anything other than a punt at present - there isnt even the divi anymore to bribe peeps to hold. Hey ho as long as they keep teh lights on here who knows.
Also, if they are relying on food to help drive profits - Marston's (LON:MARS) is one of the worst pubs for food. Microwaved and fried, sometimes both!
Marston's (LON:MARS)
I dont think the masses are particularly fussy with food if i am being honest - Marstons has been around for along time and done ok (not good they lost control of the beer) - is their food any worse than wetherspoons for example?
having traded previously in these, I bought a chunk last week as I believe there is a potential here. Directors bought recently and last year. Significantly H2 weighted. Their focus has been on cash generation and debt reduction. Importantly 93% of financing is hedged, interest on debt is 1%-4%, so they could manage that. Historically they have high debt but also large tangible assets. The elec (till 2024) & gas (till 2025) both are locked in. Once things normalise (hopefully by early next year), and if they restore the dividend one could lock in a yield of 9%+
Marston's (LON:MARS)
the problems with marstons is that pre covid they were in control and making enough profits (say £80 millpa) that the debt could be serviced and paid down (when expansion slowed) and sensible divi perhaps paid.
Post covid the safety net has gone and to boot they have sold their crown jewels by letting carslberg decide what crap beers they sell in their pubs. However long dated the debt its huge amount and increases in interest rates will hurt however far in the future that is - and be factored in by the market as they get closer to having to renegotiate. Really they are teetering on the edge of being in control now - they need purple patch paying no divis and paying debt down not to be one banana skin away from wiping out shareholders via forced rights isue at what could be a fraction of the current price. So whilst agreeing somewhat that in theory they can cope there is really zero margin for error here imho as far as avoiding dilution. So anyone investing here realy cant complain if sharecount trebles in 18 monthns time with funds being raised at fraction of curernt price. On the flipside if they do get debt down and get profits back up and estate values rise its not a no hope share. Note i do hold here but its not by any means a sensible hold - if i had had any sense i would have sold out at £1 when i had the opportunity (albeit then i didnt see the current situation where inflation and costs have gone up more than would have ben expected). High yeild with high debt/high liabilities is very risky play - look atbtis companies own history of diluting shareholders in the past to see how quickly you can lose more than dividend received when they dilute your ownershiup to pay for cash they shoudnt have given you in the first place !
Yeah debt is an issue but the management recognises it and working aggressively towards mitigating this risk. "anticipate that net debt, excluding IFRS 16 lease liabilities, will have reduced by £50-£60 million at the end of FY2023. We expect the same level of debt reduction in FY2024. "
Not huge but still significant. Along with costs control, another lever that management is focused on, there is a good chance of them riding out storm.
Regarding "letting carslberg decide what crap beers they sell in their pubs", in which case we should probably seen decline in sales now that this venture is over 3 years old. Plus they are expected to see £11 million in dividends from this venture in H2 2023.
Marston's (LON:MARS)
will have reduced by £50-£60 million at the end of FY2023 Not huge but still significant.
Every little helps but they have £1.2 billion in debt (excl lease liabilities) so £50mill reduction is only 4% - thats probably below what i would call significant. Note when you own your own pubs (no rent !!) you want to very well be hoping the cashflows in nicely to reduce debt when you are on maximise cashflow tickover (i am preuming debt reduction is now rightly top priority now). I wont knock the reductions but really debt over £800 mill is probably a level at which we should not be comfrotable with right now. Note in real terms with high inflation they could score if debt does come down in actual amount owed and also in real tems due to inflation.
Regarding "letting carslberg decide what crap beers they sell in their pubs", in which case we should probably seen decline in sales now that this venture is over 3 years old. Plus they are expected to see £11 million in dividends from this venture in H2 2023.
from memory the whole brewing side used to generate £30 mill plus profits per year ??- they previously sold vast quantities of their own beer which would produce profit on brewing side and retail side. To give that away for £11 mill pa of divi income is not any sort of good deal from the viewpoint i am looking at. Covid was what it was though - so they had little wiggle room there (due to high debt). They have alos lost the valuable intangible brand licences they used to have.
Norcros (LON:NXR)
Another sound agm trading update today.
The Group's overall trading performance for the first quarter was resilient, with the Board's expectations for the full year remaining unchanged.
Note there there is the previously flagged decrease in future expectations here so they are going backwards somewhat - overall i think the group has managed the change from tailwinds (they did very well through covid) into headwinds (up against strong comparatives and South Africa issues) very well. South Africa has has some troubles recently so then issues mentioned in SA today are no surprise but nothing to suggest that these probelms are anything other than a blip on the radar. So perhaps back to anemic like for like trading figures near term but the company is a well run sound cash making machine paying some nice divis and reducing debt readying itself for the next complimentary acquisition.
Group organic revenue growth is expected to be 9%, with reported revenues in the order of £123.5m (2021: £121.0m). Recurring revenue up 7% underpinned by strong retention rates.
Adjusted* profit before tax (unaudited) from continuing operations is expected to be £24.1m, up 30% on last year. Adjusted profit before tax (unaudited) is likely to be ahead of expectations (my bold) at £24.3m* (2022: £20.7m), up some 18%.
Market consensus Adjusted profit before tax is £22.8m.
Cash conversion continued to be strong with Group net cash on 30 June 2023 at £42.2m (31 December 2022: £22.9m; 30 June 2022: £20.5m)."
Good enough for me these days, and looks reasonable value on a Stock forecast P/E of 12 and div yield of 3.7%. I don't recall much coverage here, and would be interested in others' comments.
Richard
I have not followed this one before but has many characteristics i like. Given these figures look like a solid beat - the sell off from earlier year peak looks a bit violent - any reason for that - thanks
Wilmington (LON:WIL)
I have not followed this one before but has many characteristics i like. Given these figures look like a solid beat - the sell off from earlier year peak looks a bit violent - any reason for that - thanks
I own this. Looks like profit-taking in a bear market more than any specific issues in the previous TU. I don’t remember anything to have shaken me out of the name. Market pretty positive this morning. Maybe the guys will take a look if newsflow is not too dense.
I also hold this company and noted there was concern about the impact of AI. However, I wonder if instead of this being a negative it might be something the company could take advantage of in a positive way. There's no complaints about last year's performance.
Britain will outperform Germany this year, according to the International Monetary Fund, after its worst fears for the UK economy failed to materialize. From the telegraph.
The actual IMF report is here, if anyone's interested: https://www.imf.org/en/Publica...
Growth in the United Kingdom is projected to decline from 4.1 percent in 2022 to 0.4 percent in 2023, then to rise to 1.0 percent in 2024. This is an upward revision of 0.7 percentage point for 2023, reflecting stronger-than-expected consumption and investment from the confidence effects of falling energy prices, lower post-Brexit uncertainty (following the Windsor Framework agreement), and a resilient financial sector as the March global banking stress dissipates.
timarr
Uk growth forecast to be second worst in the developed world this year, after Germany. Same again next year. I don't suppose The Telegraph mentioned that!
The forecasts are always wrong, so why give them any credence?! Personally, I like to be a little bit positive about my own country, and look on the bright side.
What I find interesting are the serious rumbles among heavy hitting professionals that we may settle on a tacit inflation target of 4%, with capital investment accelerating.
4% allows governments to rob savers, twas ever thus, but also to get their debt ratios down.
4% also means growth, which is good for equity investors.
4% most likely means interest rates settling at 4% to 5%. Good for some, bad for others. The real value of house prices will be eroded, which is good in my view.
Is there any reason to belive medium to long term we will not match other counties like then us (is inflation their already trending down to towards 2%?). What leads you to believe medium term our inflation should be different from the us ?. At present everything is very non normal - for example government setting fixed energy prices right at the peak and making no effort to ensure lower enery prices flow through to customers super pronto.
At some stage one would expect reversion to the mean if the backround in then rest of the world is such that rates are low. Economist i aint though i must admit - and i thought inflation would come back down quicker here than it has and i was wrong (i think powers that be massively messed up though doing everything to ensure pricves are higher for average joe bloggs)
The cynical view would be that there is now so much debt (government and otherwise) that the only way to get out of it is to reduce the value of money (i.e. inflation).
I have been looking at index-linked gilts over the last few days as a consequence but never having bought them before, I must confess I don't quite understand how they are priced in the market. My understanding is that each year (HY?) the principal and the interest payment are adjusted by RPI. So if they are sold at nominal £100 and 1% interest and RPI is 10% at end of year 1 then the nominal value would be £110 and the interest to be paid would be £1.10.
Then looking at the market I can see this (for example) and if I were to buy, I am not clear what my return would be at 22/03/20204.
I assume the price is adjusted for RPI (otherwise it would be much higher). I also assume the price at maturity is £100.
But how does RPI get applied? Does it get adjusted at each HY? And how do I see the "raw" unadjusted price?
Would I be correct in saying that my return at 22/03/2024 (i.e. held to maturity) would be (100/98.19) + (the small coupon x 2) + RPI between now and then? If so, in my mind, that would be quite a good place to store some cash.
Anyway, if anyone can explain this to me or direct me to somewhere that does it explain it, I would be much obliged. (I have looked and haven't found anything that works for me.)
Rob.
I think the indexation is added to the rolled up interest that gets paid at the end of the bond. I haven't bought any index linked stock directly but I suspect you have to pay the quoted price plus the accrued interest on the day.
A detailed explanation of how index linked gilts work is provided on the debt management office site https://www.dmo.gov.uk/data/gi.... There is some pretty complicated maths but it does explain how it all works in terms of coupon cash flows. As to real time pricing that is determined by interest rate levels, inflation expectations and other market factors which I don’t entirely understand!. I have developed a forecasting model for the Index linked bonds with an 8 month lag (2024 & 2030) which provides a cash flow (coupon forecast) and gives me a yield to maturity estimate. However, this is entirely dependent on the forecast for RPI. I bought the 8 month lag July 2024 issue in early February and am expecting about a 5.5% YTM return which is pretty nailed on as the last coupon in July 2024 and the repayment of inflation adjusted principal is only dependent on November 2023 RPI coming in at 6% or more. The odds on that are looking pretty good at the moment!
Greedflation is IMHO a major factor. Edmund Shing in his weekly podcast referred to both Covid and then the war in Ukraine as a smokescreen for businesses to raise prices above the rate of inflation. The quality of products and services go down, prices go up. Business owners have been opportunistic in this regard. I wonder how and when it will end.
I suspectour trade friction and low productivity will count against us over the longer term. We don't all revert to the mean, some countries enjoy consistently stronger growth in GDP per head than others based on their compeitiveness due to good infrastructure, high investment levels, good education and advantageous trade relationships. I don't think that includes us!
I've noticed this, when figures are bad people are all over them, when they are adjusted to the better people won't believe them.
It seems to me like they take great pleasure in predicting the worst possible outcome for the uk for some narcassistic reasons. Note ref inflation and interest rates we have had a bad run here is the uk (compared to us say) so in some repects i would be expecting 2023 forecasts to get worse - and yet they are now doing very material upgrades for this year now they cant avod the fact its not as bad as their gloomy predictioons told us it would be.
Hey ho as long as we we beat the Germans does anything else really matter?
The reason why the Telegraph optimism is important is that it leads to people thinking everything is rosey in the garden and change is not needed. What concerns me is that the UK stockmarket appears to be on a cheap rating partly because international investors are underweight. That may not change until the political parties (Conservative and Labour) recognise the underlying problems that are hampering UK growth.
If forecasts were always right we could trade on that info and be very smug ....but theyre not and we cannot .10 experts = 10 opinions
Big Deal! There are a lot of other countries that are outperforming the U.K. Don’t think Germany is much of a benchmark at the moment.
"Don’t think Germany is much of a benchmark at the moment"
Please explain? If Germany isn't a benchmark, then why bother benchmarking against any of the countries in that list.
“Don’t think Germany is much of a benchmark at the moment"
Please explain?
For idiosyncratic reasons Germany sits at the very bottom of the developed economy pile in the latest output forecasts. A sensible benchmark would be at the mean or median level.
Indeed, why bother?. just get on with it…..who cares if we beat Germany!
My morning smallcap tweet: Fat RNS sandwich with sour toppings.
Velocity Composites (LON:VEL) Learning Technologies (LON:LTG) Smarttech247 (LON:S247) Palace Capital (LON:PCA) Wilmington (LON:WIL) Yourgene Health (LON:YGEN) Marston's (LON:MARS) Saietta (LON:SED) Oakley Capital Investments (LON:OCI) Motorpoint (LON:MOTR) Graft Polymer (UK) (LON:GPL) SEEEN (LON:SEEN), Revolution Bars (LON:RBG), Tialis Essential IT (LON:TIA), Mortgage Advice Bureau (Holdings) (LON:MAB1), LBG Media (LON:LBG), hVIVO (LON:HVO), EKF Diagnostics Holdings (LON:EKF), Gresham House (LON:GHE), Norcros (LON:NXR), Biome Technologies (LON:BIOM), Iqe (LON:IQE)
◄Velocity Composites (VEL)► $100m, five-year Work Package Agreement (see Dec RNS) warns FY23 only £15-17m and EBITDA loss £1.2-1.6m due to delay in $100m contract (see Dec RNS). Cuts expected rev in FY23 to £2.2m from £5m. "Once the programme transfer from the Customer to Velocity is completed, revenues under the Agreement will be more predictable." [SP=51.2 Cap=19m]
◄Learning Technologies (LTG)► warns FY-H1 organic rev flat. Rev-cont up 2%. Blames "lower than expected level of transactional and project-based work due to the lengthening of sales cycles, particularly for our financial services and technology clients". Guides FY-Dc rev £550-570m and edj EBIT £98-103m. F/C were £609.2m and £109.4m. [SP=84.82 Cap=671m]. I hold.
◄Smarttech247 (S247)► $3m 3 year order for security intelligence technology. [SP=31 Cap=38m]
◄Palace Capital (PCA)► AGM stmt - proforma EPRA NTA is 304p. [SP=237 Cap=99m]
◄Wilmington (WIL)► guides FY-June rev organic up 9%. Adj pretax £24.3m ahead of F/C £22.8m. [SP=250 Cap=220m]
◄Yourgene Health (YGEN)► five-year contract extension with Illumina. No £££. [SP=0.5 Cap=16m]
◄Marston's (MARS)► last 42 rev LFL up 11%. In line? [SP=31.9 Cap=202m]
◄Saietta (SED)► Letter of Assignment for a third vehicle line with its existing Indian client. Expects 60k units over 5 yrs. [SP=35.4 Cap=36m]
◄Oakley Capital Investments (OCI)► NAV 663p/sh. [SP=447.67 Cap=790m]
◄Motorpoint (MOTR)► AGM stmt - mixed. "We are able to maintain a lower headcount as we conserve cash and return to profitability, whilst ensuring we are ready to invest for growth as more favourable market conditions return. The Group continues to be confident it will emerge in a normalised market as a leaner and more valuable business ready to seize a significant opportunity." [SP=102 Cap=92m]
◄Graft Polymer UK (GPL)► distribution agreement with leading US veterinary products company Inter-Technologies. "The agreement is a major step forward in expanding the penetration of the Company's GraftBio products." [SP=1.7 Cap=2m]
◄SEEEN (SEEN)► AGM stmt - commercial readiness of CreatorSuite 2.0. [SP=2.5 Cap=2m]
In line: RBG, TIA, MAB1, LBG, HVO, EKF, GHE, NXR, BIOM, IQE
Revolution Bars (LON:RBG) in line but debt still a potential issue given they flag concerns over economic slow-down and its impact on the their customers.
I hold (small, opening position).
hVIVO (LON:HVO) trading update looking good, happy to keep holding that one.