Small Cap Value Report (Wed 27 Sept 2023) - EMAN, CARD, SYS1

Good morning from Graham and Paul! It's a busy morning for updates, and we will both be presenting at Mello later today.
12pm: I'm wrapping this up now. Hopefully we will get a chance to catch up with the backlog tomorrow. Cheers! Graham
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Everyman Media (LON:EMAN) - down 1% to 55p (£50m) - Interim Results (in line) - Graham - RED
I remain negative on this one as it continues with its ambitious expansion plans despite seeming to be unable to make any money from its existing estate. At some point the capex spend will need to calm down, or else I’m worried for this company’s shareholders.
System1 (LON:SYS1) - up 1% to 212.6p (£30m) - Trading update (ahead) - Graham - AMBER
This marketing company says that it’s set to beat expectations for the current financial year (FY March 2024). That’s good, because those expectations are for adjusted PBT of less than £1m. I continue to wait for this company to prove its quality by showing material profits.
Paul's Section
Card Factory (LON:CARD) (Paul holds) - down 10% to 100p y’day (£343m) - Interim Results (July 2023) - Paul - GREEN
I lowered the priority for this share when the market seemed to baulk at its interim results yesterday, with it slipping downwards as the day went on, usually a sign of lacklustre figures/outlook.
After battling most of the day with intermittent WiFi in my AirBnB in Gozo, and a small number of equally annoying reader comments here, in desperation I headed for a historic town square in Victoria (Gozo), and set myself up for a few hours with a smartphone hotspot, laptop, and some red wine, to review the interim results from Card Factory, the low prices greetings card & gifts retailer.
By mid-afternoon, I really couldn’t fathom why CARD shares were constantly falling. There didn’t seem to be anything amiss in the numbers or the commentary. Several investor friends had already messaged me, asking what’s going on - they couldn’t see anything wrong, so why are people selling? Does it matter? Not if you’re taking a medium to long-term view.
The newswires like to give a quick judgement, and they said “Card Factory falls on weak online sales”. That doesn’t sound credible to me, as online sales are not material at CARD, but were down 13% in H1. I do think CARD has missed a trick with online, and could do far more in this area - having allowed Moonpig (LON:MOON) and others to carve out a large, and profitable niche.
Anyway, here are my notes from reviewing the interim results -
H1 revenue £221m, up 11.5%, with LFL (like-for-like) up about 10% - a very impressive performance in my view, revenues fully keeping up with inflation (not many retailers have managed that).
H1 adj PBT is up 105% to £22.1m
Adj EPS doubled from 2.5p to 5.0p, but bear in mind H1 is the seasonally slower half, with H2 including the bumper Christmas period, so tends to be much more profitable.
Forecast (consensus) for FY 1/2024 is 13.3p, which I think should be comfortably achievable, once we allow for 5.0p done in H1, and the seasonal bias to H2. Could be more, who knows?
Operational things I like - click and collect has been introduced, store refits planned, and 11 net new stores opened.
Outlook - there’s been some criticism of the wording, “confident in delivering a good outturn for the year”, and current trading in line with expectations since the Aug 2023 update. I think people are over-analysing the wording. It looks OK to me.
Confidence in longer term targets set at the Capital Markets event in May 2023.
Investor/analyst meeting at 10am yesterday was recorded and should be up on IR website. It doesn’t seem to be up there yet, but the slide deck is, see here.
Balance sheet - isn’t the best, but it’s actually fine, given the profitable & cash generative nature of the business. NAV of £286m includes £331m of intangible assets, so NTAV is negative at £(45)m. I don’t have a problem with that at all. Fixed assets are modest at only £41m. Note that lease liabilities are modest for the size of business, and RoU assets is almost the same as the lease liabilities, which suggests CARD probably has hardly any loss-making sites. They’re smallish units, on low rents I think, so it has considerable flexibility - the complete opposite of say Superdry, burdened with hideously expensive flagship stores that it cannot afford any more. CARD is more like a Shoezone - nimble, cheap leases.
Dividends - none at the moment, as the tranche A term loan has to be repaid first, on 31 Jan 2024, which then opens the way for divis in FY 1/2025, which of course effectively means calendar 2024 - ie soon!
Paul’s opinion - there’s nothing wrong in these numbers, in my opinion. So why has the share price fallen? Maybe because it’s had a great run, and just needs to consolidate? The biggest shareholder seems to be selling repeatedly in the market, so that looks like an overhang that could persist for a while. Do they know something we don’t? Or do they just need liquidity for any number of reasons? No idea! But if a seller lets me have a good share at a bargain price, I’ll take that trade. So I did top-up a little at c.100p yesterday. I’m keeping some powder dry for more top-ups, if the seller keeps depressing the price.
Also I think a lot of traders latched onto this share, and maybe sold because they didn’t get an instant pop on the results statement, or maybe they hoped for another out-perform update? Again, who knows, we don’t have to fill in a form to disclose why we sell, there are any number of reasons.
What are CARD shares worth? I reckon it’s a 150p share. We can currently buy at 100p, so I think that’s a very nice opportunity.
As always, I’m basing my view on the 3 “f’s” - facts, figures, and forecasts, as they stand today. All of those will change over time, so we have to continuously reassess everything.
The product is very cheap, so I’m not worried about it being discretionary spending. I bought some happy birthday stuff for an elderly relative recently, balloons, sashes, banners, etc, put them up with blu-tak, and for less than a £tenner, it created a lovely surprise. Products are high gross margin, and the whole business model stacks up very nicely I think - especially the focus on improving product ranges into complementary impulse gifts.
Thumbs up from me - there’s nothing wrong in these numbers, and CARD shares are cheap, I reckon. But the persistent seller is keeping a lid on the price for the time being.
Graham's Section
Everyman Media (LON:EMAN)
- Share price: 55.5p (pre-market)
- Market cap: £51m
Everyman Media Group PLC, the independent, premium cinema group, reports its unaudited interim results for the 26 weeks ended 29 June 2023.
Paul had a good look at this one in August on the day of its trading update. I looked at it back in April.
Here are the interim results:
Revenue down 6% to £38m
Adjusted EBITDA (a meaningless number for this company) down 23% to £5.8m
Cash generated from operating activities (another meaningless number, due to high capex which it excludes) down 21% to £7.2m
Scrolling down to the income statement, there is a loss of £4.3 million (much worse than the £0.8m loss in H1 last year).
The cash flow statement shows the £7.2m generated from operating activities. It also shows £12.1m of capex spending, offset by an inflow from the sale of freehold property - a sale and leaseback deal in Crystal Palace.
The only real bright spot in terms of cash flow is nearly £3m received in the form of landlord capital contributions, helping to fund Everyman’s lease payments.
Excluding the additional cash it borrowed from its lenders, Everyman generated a net cash outflow during the period of £2.7m.
If we also wanted to exclude the proceeds from the sale and leaseback deal, the net cash outflow was £6.6m. A far cry from the number posted in the company’s highlights.
Post-period and outlook
Barbie and Oppenheimer were released in July, i.e. after the period covered by these results. They do seem to have boosted the revenue performance significantly:
August YTD Revenue £60.2m (2022: £53.1m)
As discussed in August, the company now has a £35m loan facility with Barclays and NatWest.
Additionally:
The Board remains confident that the financial performance of the Group for the full year ending 28 December 2023 will be in line with market expectations.
The company helpfully discloses that current market forecasts suggest revenues of £94.4m (last year: £78.8m). They also say that the adjusted EBITDA forecast is £17.2m (last year: £14.5m).
CEO comment:
The recent and resounding Box Office success of Barbie and Oppenheimer drove exceptional performance throughout July and August, highlighting the value of high-quality original content. Everyman's strong year to date performance underpins our confidence in meeting market expectations for the full year, whilst equally demonstrating that the UK cinema sector is as vibrant as ever.
We remain confident in our prospects as we continue to be supported by a slate of high-quality second half releases, a carefully expanded estate and new banking facilities which ensure we are well configured to take advantage of future opportunities.
Personally, I share his optimism that H2 film releases will be very good - I’m looking forward to Ridley Scott’s Napoleon and Martin Scorsese’s Killers of the Flower Moon. It should be a good year for cinema!
Food and beverage spend per head increased from £8.96 to £10.25, which seems fine in the context of high inflation and the cost-of-living issues. Everyman also launched a new website, with average monthly visitors of 940,000 (up nearly 18% since launch). Partnerships/working relationships with Jaguar, Green & Black’s and Apple TV+ continue.
Expansion - with 41 cinemas currently, they have six others due to open by the end of the next financial year. On top of that, ”the pipeline for 2025 is well-developed, with several venues at advanced stages of negotiation”.
Graham’s view
The company’s year-to-date revenue performance seems reasonably good, especially considering the current consumer environment. But then Barbie and Oppenheimer were landmark events in cinema and can almost be considered one-off events. I don’t know if 2024/2025 will have anything to match them.
Also, the strikes in Hollywood could become a concern if production does not begin again soon; the company says there has been “minimal disruption” to 2023 but I think the effects will start to feed through if they are not resolved soon (actors and writers have been on strike since May).
But at the end of the day, the biggest problem with this company is that it doesn’t make enough money: not on the income statement, and not on the cash flow statement.
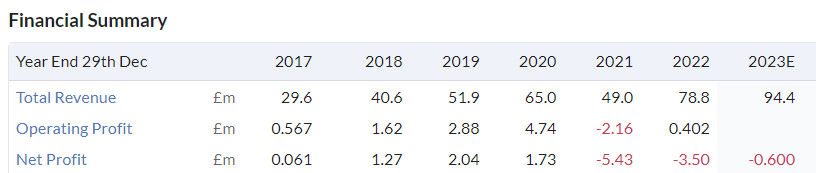
The StockReport also shows cash flow numbers (these are for 2017 to 2022 inclusive).
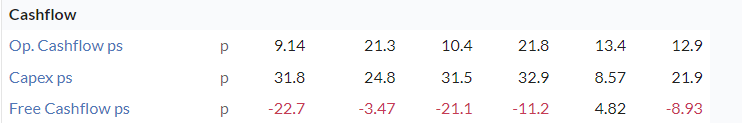
I’d have more confidence in the company if it didn’t trumpet EBITDA and operating cash numbers which I believe are meaningless to shareholders.
Net debt at the end of August was £17.9m. Balance sheet leases are also valued at over £90m.
It’s possible that free cash flow will turn positive if the company can afford to reduce its capex spend in future; bulls could argue that the company has been in expansion mode, and that the investments made in recent years will pay off handsomely in the years to come.
Perhaps that is true, but personally I’m not convinced and therefore I’m going to maintain the negative stance that I took in April, when the share price was 66p. If the company had net cash that would be one thing. We’ve been down this road before with capital-intensive, financially leveraged companies.

System1 (LON:SYS1)
- Share price: 212.6p (+1%)
- Market cap: £30m
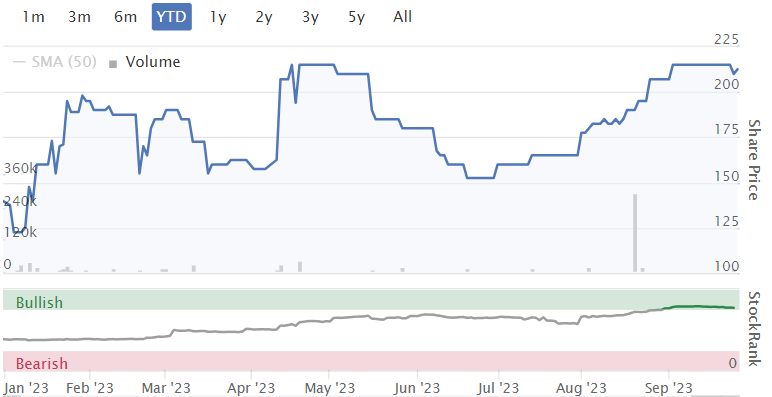
This company’s share price has recovered well since I covered its full-year results in August.
The year-to-date chart shows increasing confidence:
Let’s take a look at the AGM trading statement:
With three trading days left in FY24 H1, it is pleasing to report Platform revenue is approximately 40% above the comparable period in FY23, albeit 2022 was affected by customers' budgetary response to the Ukraine invasion and associated economic shocks.
As I noted in August, what the company refers to as “Platform revenue” includes what it calls “data-led consultancy”.
It argues that this is of a higher quality than the “bespoke consultancy” which it has allowed to decline.
Platform revenue is up 40% compared to the weak H1 period last year. Compared to last year’s H2 period, it is only up by “low double digits”.
Total revenue, including the declining consultancy work, “is projected to rise modestly”.
So again, it comes back to whether you believe that the lost revenue stream is being replaced by a much higher quality revenue stream.
Outlook
The Board is encouraged by trading in FY24 H1 and believes that the Group is well set to outperform the current consensus numbers for Revenue and Adjusted Profit Before Taxation for the current financial year.
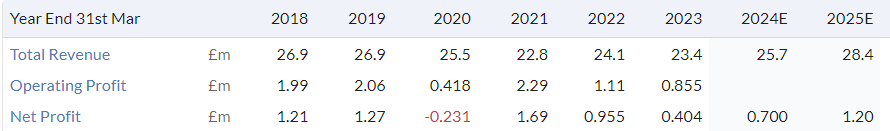
Kudos to the company for sharing its view of consensus numbers: revenues £25.7m, adjusted PBT £0.9m.
Last year, it achieved revenues of £23.4m and adjusted PBT of £0.8m.
Chairman’s comment:
The sustained improvement in performance over the past 9 months reflects the clarity on strategy achieved in last year's review of strategic options and the executive team's focus on delivering the plan.
Graham’s view
The struggle for power in the Boardroom has ended here, with the incumbents remaining in charge. They clearly have aspirations to build a high-quality company, but my impression of their work is that it remains quite labour-intensive. Swapping out one form of consultancy for another may be an improvement but it does not, in my mind, create a radically better investment proposition than what the company offered before.
The very low pre-tax profit margin hints at what I’m saying here.
So I’m still neutral on this one. For many years, it has promised to come good, but profits are still barely even high enough to justify a stock market listing.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
I don't hold but I see on the fallers list that Shield Therapeutics is down 20% today. Funny coincidence that half year results are out tomorrow. I can only guess that the results will be poor, and once again inside information and a leaky ship leaves the private investor feeling bamboozled. It could just be a nervous seller (pre results) in an illiquid market. But this stock has had previous for these kind of inside info price moves. Will be interesting to see what tomorrows results are like. For some of these companies its like a soap opera, after todays dum dums, can't wait to see tomorrows episode.
As an update on Shield Therapeutics (LON:STX) for anyone looking through the archive - it has opened today with its half year trading update almost 20% down with an announced fundraise at 8p a share. Yesterdays drop of 20% one day before the announcement is possibly the most blatantly obvious insider trading that I have ever seen (now down about 40% over 2 days). When will the authorities start to take action against these bad actors! I have been reading on a forum this morning - the usually staunch holders seem mightily pissed and are discussing group action against the company via the FCA (which will obviously come to nothing as they are an impotent organisation that do not seem to care about protecting private investors or protecting the integrity of the small cap market - so with these kinds of antics, its not a surprise that global money views the UK as not tempting, believable or investible!)
Pendragon (LON:PDG) Lookers (LON:LOOK) Vertu Motors (LON:VTU) ( I don't hold any of them anymore)
I was wondering if anyone has any views/opinions on why nobody is showing any apparent bid interest in Vertu Motors (LON:VTU) - I had a look at them all last night and the only thing I could come up with was Vertu Motors (LON:VTU) lack of premium brand product (I know they bought Helston) but I don't think that compares with Pendragon (LON:PDG) Stratstone or Lookers (LON:LOOK)
Thanks Alb
That's a good question, and something I've been scratching my head over. Seemed to be almost constant stories about potential or actual bids for Lookers and Pendragon, but nothing on Vertu. Of course, there may have stuff been going on behind the scenes but nothing I'm aware of.
I am a big fan of Stockopedia but when it comes to the Stock Ranks for Burford Capital (LON:BUR) and Litigation Capital Management (LON:LIT) I long ago realised that the Algorithms do not comprehend the numbers.
Burford is my biggest holding and I believe its prospects over a 3 year timeframe are very attractive. I keep thinking of the saying "patience is a virtue sought by many but possessed by few."
"I long ago realised that the Algorithms do not comprehend the numbers."
Fair play for those that dont mind losing their shirt and have big kahunas but i think it is to the great credit of the stocky rankings that Burford is flagged up as a terrible investment by the its ranks - one only has to look at cashflow to see that the entire market cap is reliant profits than have never turned to cash overall** . To me stocky is doing its job here and saying sorry this company never turns profits to cash therefore we will flag it up as being pants - dont think anyone can argue this company has proved it can turn profits into real cash consistently**
I aint saying this a is a bad investment but its exactly the kind of stuff that should be picked after doing thorough research and choosing to ignore things like woeful cashflow and woreful rankings - rather than stocky saying that its brillaint as its had loads of profits - just a shame they cant collected them as cash.
** in this regard i am looking at the overall numbers - i am well aware that sales are flowing through to cash - its just that each year its never for one reason or another showing good cashflow (per stocky)
Burford Capital (LON:BUR) is my largest holding and I have the same opinion on its prospects but I can well understand why the Stocko algorithms are not positive. They work off historic figures. Burford's for the last few years have been poor as court delays caused by the lockdowns have delayed cases and reduced income whilst their costs have increased as they expand. Their YPF victory and the estimation of how much they can actually collect is outside what the Stocko algorithms do.
Burford has been trying patience for a few years now.
Card Factory (LON:CARD)
Cockney Rebel has done a write up of yesterday's Interim Results.
For those who may be interested, here is the link;
https://cockneyrebel.substack....
(I hold)
Snazzy
MTI Wireless Edge (LON:MWE) (I hold) - if of interest - contract win of (edit to $ from £) $0.6m in India for their 5G Antenna business this morning, along with some bullish commentary for the same space. Share price beaten down of late but have businesses operating in nice growth sectors - 5G, Water and Defence.
Israeli based which will put a lot off and go someway to explaining lower PE, but CEO has large stake and business has long track record. Pays generous dividend too.
Everyman Media (LON:EMAN)
Thanks for the write-up Graham, I found it most insightful.
I must admit to being tempted to buy a small position today.
I think I've done this correctly with the information provided today and which subsequently showed underlying cash burn in H1.
That's not great for a company in expansion mode.
2022 - https://www.boxofficemojo.com/...
2023 - https://www.boxofficemojo.com/...
Indeed the company just did this with their Crystal Palace venue.
I guess the issue is whether market sentiment agree with me.
As someone looking to invest with a slightly longer time horizon though, should that matter?
Litigation Capital Management (LON:LIT)
A big re-rating today by the stocko algorithm. Lit has gone from a momentum trap to a super stock and the stock rank has moved up from 33 to 94! I think it was thought that the stocko algorithm didn't really understand the litigation funders - but clearly the progress made in recent times is now being recognised. Its quite an interesting re-rating, as from my experience the sector is usually lowly rated by the algorithm - Burford is still rated lowly (stock rank 23) as a momentum trap.
Very odd : if you do a 'mano a mano' Burford Capital (LON:BUR) to Litigation Capital Management (LON:LIT) BUR 'wins' 5 of the 7 'momentum' metrics...
And BUR scores a respectable 18/39 to LIT's 21/39 overall, for an SR of 21 vs. 93.
It would seem that 'Mr Market' isn't the only one who doesn't quite 'get' Burford !
I think in general these companies are likley to have highly individual valuations calculated by those that are clever enough to know more than us (Burford , LCM) . All i do know with these companies is that i know there are plenty of peeps that are likely to have much more useful info than me - if the price seems wrong i would default to presuming thats me not knowing what soemone clever knows.
Having said that burford has doubled in price since lowpoint this year so perhaps its simply peeps reluctant to invest not believing the story till good news is more in the bag
Great to see the site catch up - hopefully it will be on more peoples radars, now.
Not only has the 2023 figures updated but the 2022 figures have changed, too. This indicates a very slight drop in YoY profits as a result of the FY presentation restating 2022.
Saga (LON:SAGA)
I’d be interested in any thoughts re Saga? Having skimmed the statement….£50m of debt repayment seemed good. Though I’m not quite sure why the bond due next year will require partial drawdown of the loan facility? Most of the travel element seems under control but still a bit murkier on insurance outlook. With regards to insurance, I notice Sabre has inflected as pricing begins to strengthen to offset claims inflation. Management seem to allude to this.
I did not manage to dial in to the call unfortunately. However, travel performing, I suspect Insurance gets better from here, debt being repaid and the bond repayment all under control makes me think it may be worth revisiting. The chart looks to me as if it’s trying to form a bit of a base.
Saga (LON:SAGA)
"£50m of debt repayment seemed good."
Errrrr without full details i wouldnt presume this is good news - its a given that they need to be paying down debt fast as their cruiose ships depreciate just to stand still - its not like normal business where any reduction in debt is good all other things being equal - saga should have minimum reductions each period that at least match cruise ship debt profile/ depreciation charge (in years when they are not buying new ships)
Note they need to be in purple patch ref reducing debt and the fact they seem to be saying they may need to be going cap in hand to Jolly Roger sounds like the debt repayment plans are waaaaay of track. Jolly Roger is presumably currently willing to bail out the company that cant manage its own cashflow - but his largess shoudl not be presumed to last forever !
"The Group expects to meet the £150m bond repayment due in May 2024 through a combination of Available Cash4 resources and drawdown of the loan facility with Roger De Haan. To provide additional financial flexibility following repayment of the bond, the Group has agreed a £35m increase to the facility, taking the total to £85m, and an extension to the expiry date, to 31 December 2025."
Being frank this company is bl oody hard work to follow they hate giving out straight talking updates.
Today they do say the following
For the full year, we expect to achieve significant double-digit growth in revenue and Underlying Profit Before Tax2 when compared with the prior year, ahead of current estimates.
As far as i can see thats its - thanks not for not saying what current estimates are or what last years outcome was - as small shareholder if the info aint there i find that lack of courtesey unacceptable - have i missed info ?
some decent companies update current expectations on their website i cant see owt there either ( i could easily have missed)
ok h1 they did underlying pbt £8.00 mill
last year per annual report that was £21.00 mill
so looks like they will do perhaps £25 mill plus this year underlying - thats nota great level of profit. Right now they should be in purple patch of no headwinds - they seem to be busy selling cruises and they can still only make £35 mill profit. Note not so long ago peps were predicting £100 mill plus pa profits - anything below £50 mil pa in normal year and i doubt anyone would lend em money to buiy their next ship !!!
The reasons for poor performance are that cruising doesnt seem to be making profits i would like to think they would be making in a good year (this is agood year !) and the insurance side of things is woeful at present. One would hope insurance woes are a blip but they seem very downbeat with regard to insurance - compare this to Hiscox who only last month said "Our diversified business portfolio is well positioned to deliver high-quality growth in revenue and earnings,"
I am not saying this comapny wont bounce back and the trend other tyghan insurance seems solid - but te profits arent there end of and thats aht they need if they want to be able to pay down 2026 bond debt and get shiny new ships.
Note stocky indicates profits 2024 will be £37 mill annd £44 mill next year - so perhaps "double digits" growth is closer to 50% plus - very annoying that they make a point of not telling us what they think they will make even though they are clearly referencing "a figure"
Any views on Zoo Digital (LON:ZOO) here? Could there be a recovery with the Writers' strike ending? Mkt cap £53m and a decent cash balance. SP totally floored at mo.
In last years annual report for Zoo Digital (LON:ZOO) they noted that 74% of their revenue came from a single customer. I believe this to be Walt Disney Co (NYQ:DIS),and as many will know Disney is in turmoil as it tries to decide how to allocate its capital to engineer a recovery amidst park stagnation, a hit to the growth of its streaming offer and rumours around ESPN. For a company with $35bn of net debt, the recent announcement that it will spend $60bn on new park investment has not been unalloyed joy.
So, in my opinion, although Zoo has large an growing addressable markets and the growth in streaming has still to negotiate their way to them while handling the Disney questions. I used to hold but got out while I get a better feeling of how they get through the next 18 months.
Thanks Aislabie. Much appreciated and I think you’re onto something here. To not have an uptick on the back of the strikes finishing. Incredible really.
I also know the timing of the placing went down very badly with holders. Management are going to have to rebuild trust!
I’ve sold.
There is also the Actors' strike which has yet to be resolved. After that I would assume more of a bounce but not. sure it is an immediate upward trend for ZOO as there will be a lag time for the studios to get back up and running one would think. Zoo Digital (LON:ZOO) 's AGM is tomorrow and I expect they will receive some tough questions they will hopefully have truthful answers to:)
Facilities by ADF (LON:ADF)
Hollywood actors strike end today, may help.
'Union leaders “voted unanimously to lift the restraining order and end the strike as of 12:01 am PT/3:01 am ET on Wednesday, September 27th,”
the WGA said in a statement. The deal will last until May 2026 and
includes a 5% minimum pay increase upon the ratification of the
contract.'
Facilities by ADF (LON:ADF)
Hollywood actors strike end today, may help.
I believe it's the writers' strike that has ended, not the actors', although the former may pave the way for the latter.
timarr
timarr, yes you are of course correct. It may, as you suggest, force the actors union back to table as I believe there have been no talks for some time.
Thanks for the review of Card Factory (LON:CARD) - I also thought the results looked good and topped up yesterday. There do seem to be a lot of short-term momentum traders in CARD and I suspect that is the reason for the fall - exactly the same thing happened a few months ago. Some have suggested it could be concern over rising costs (eg, rise in living wages, plus the fall in pound pushing up raw material costs), but this should have all been known about and don't think it can explain yesterday's fall.
Re Card Factory (LON:CARD) in the August update they said trading for the full year would be materially ahead of expectations but in the results they said only it would be a 'good' outturn. Isn't this the reason for the drop? Seems a reasonable reason.
If the 'outturn' comment from Card Factory (LON:CARD) is an indication of a step back from August's optimism then that's a pretty rapid change in the management's outlook. [I hold]
Card Factory (LON:CARD) My guess for the reason for the price drop is that a lot of traders had bought in anticipation and would sell on results, even if good. I don't hold but am about to!
I was wondering if anyone has any thoughts on Bloomsbury Publishing (LON:BMY) . I have always admired the share from a distance hoping for a pullback so I could get on board. Today a long standing alert has just gone off for me at 375p. Before I pull the trigger I thought I'd see if there is anything beyond current macro factors that may have contributed to the drop from over 450p just a few months ago that anyone with sector or company specific insight might be aware of.
Bloomsbury
Great company share price just a bit unloved at the moment . They always deliver but don’t do much except run a good solid business in a good sector .
I hold and think 375 good entry point if I had cash would buy .
Bloomsbury Publishing (LON:BMY) I am wondering exactly the same thing. The figures still loook good and I don't know of any problems. But there are a lot of quite big recent sales.
Regarding Bloomsbury Publishing (LON:BMY) , when a see a holding of mine starting to roll over, I usually check the institutional and director activity and there have been some big sells from both since the turn of the year. I have no idea why - maybe just profit taking after a good run up, but they’ll know more than me so I followed their lead and will sit on the sidelines until the dust settles on the share price. Overall though it’s a business I like and would certainly buy back into when sentiment improves or when directors show some confidence with their own holdings.
Pretty sure the director sales seen this year and last were to cover the tax implications of the options they received.
Bloomsbury Publishing (LON:BMY) (I hold)
Hi Ben
This doesn't seem expensive to me, especially as I'm hoping for more growth this year.
---
Here's the link for last week:
https://www.amazon.com/charts/...
It has appeared for 9 weeks in total in FY23.
10 of those weeks were in FY22, with 27 weeks in FY23.
Note that Maas has another book due to be published in this financial year.
By my estimates Sarah J Maas generated £51m of revenue for Bloomsbury in FY22 (a year in which she didn't publish any new books), and I'm therefore hoping for a big increase in FY23 based on the above.
All guesswork of course as Bloomsbury is more than one author (or two if you include JK Rowling), but fingers crossed.
Abs
Thanks to all for your responses on Bloomsbury Publishing (LON:BMY) - I hadn't thought to look at the specifics of the books being sold as an insight to potential earnings, Abs, so thanks in particular for that insight. I must say that I myself have started reading and playing video games more than usual in the evenings as TV is pretty poor at the moment with most new content being of low quality - probably due to the writers strike. Hopefully more people are the same and buying more books as a consequence! I have put in a buy order using the cash I got from selling Supreme (LON:SUP) on yesterdays bounce - my conscious couldn't allow me to stay invested in them any longer.
Re: Bloomsbury Publishing (LON:BMY).
Hi Ben, I like successful serial acquirers as some of these companies have produced remarkable results over the long term. Whilst a siginificant amount of growth at Bloomsbury is organic, the company web site says it has purchased 19 publishers and imprints since 2008 so it is benefitting from the fragmentary nature of the sector it operates in. It's ROCE is OK (although not spectacular) which tends to confirm that that acquisitions have been successful and I would suggest that this is a good reason to hold this company as it provides a long runway for growth.
The UK market is so illiquid that a forced seller drives the prices massively down.
I believe this is the case here as well and a great buying opportunity at these levels.
Bloomsbury Publishing (LON:BMY)
By my estimates Sarah J Maas generated £51m of revenue for Bloomsbury in FY22 (a year in which she didn't publish any new books), and I'm therefore hoping for a big increase in FY23 based on the above.
Wowsers i didnt really appreciate how individual names could be such a big % of turnover - for my sins didnt even realise they did harry potter either :).
Does anyone know how it works ref book "signings" - when current deal is over presumably Sarah J Maas could perhaps take future stuff elsewhere? will they always have harry potter stuff theyr have relased even if JK did go for future stuff?
I suspect JK may be with Bloomsbury for life if they backed her at the start when no one else did? - ref the others could they be tempted away to the equivalent of man city (or the toon yay)? - i take it as a big plus point that JK has hung around with Blomsbury forever - if they do the basics right should really be temptred elsewhere for a quick buck and the fact she has hung around says to the others no need to up sticks and leave?
hi rmillaree
Bloomsbury Publishing (LON:BMY)
Here is a link to the latest Sarah J Maas book deal with Bloomsbury;
https://www.publishersweekly.c...
(I hold)
Snazzy
Bloomsbury Publishing (LON:BMY)
cheers snazzy - looks like it is a bit like football - good to see Sarah seems to have recently resigned hopefully she is more Anthony G than Jadon S ref current form now she has signed a new deal.
One thing this pullback has done is given us that missed out a chance to get on board - i was always a bit annoyed at myself for missing out on this one before the big price appreciation since covid. Its probably natural to presume they had some covid tailwinds so the fact earnings are still in forward direction is credit to them. Perhaps lack of future growth penciled in for 2025 is counting against them - i suspect they may start off without having glass rammed full ref future predictions? i like companies that dont over promise and under deliver.
I would slightly worry there could be bad news brewing that isnt confifmed yet - so i think for this share i would want current update to confirm nowt new to say before takingb the plunge - risk you can miss out on ten bottom when you do that.
I aint a chartist but the chart doesnt look amazing (kinda the opposite)
Bloomsbury Publishing (LON:BMY)
I don't think they are ever going to shoot the lights out but there's plenty to like.
Rock solid balance sheet with plenty of net cash / down to earth Management who seem very straightforward / founder CEO with skin in the game / Harry Potter cash cow and Sarah J Maas a great signing / easy to understand business model = a sleep easy investment.
Share price pullback looks a good entry point. I've topped up today having set myself a 390p target.
Snazzy
Bloomsbury Publishing (LON:BMY)
I have held this for several years and think that it is one of those small companies that drifts between trading announcements. We had a brief 'in line' AGM statement on 18/7 and do not expect anything until the interims on 26/10.
The drop appears to be seasonal:
2022 19 Aug 425 03 Oct 366
2021 26 July 391 04 Oct 319
abtan says there has been no news - well, no RNS but a very bad piece of news in early August - the sudden accidental death of Adrienne Vaughan who was in charge of BMY's US operations and in her three years there saw it become BMY's biggest market. If you google her name you will see from her previous works what a standing she had (and thus had all the connections).
https://www.bloomsbury.com/uk/...
johnsmith68 says there have been big sells since the beginning of the year. Well, there were only two director sales and those were to cover tax from the excercise of options, which is normal. There has only been one institution that has sold down - Cannacord from 11.97% to 9.99% but we do not know the reason - it may be that their clients are withdrawing money from the market generally.
Oh my goodness. Thank you for sharing the news regarding Adrienne Vaughan. An important strategic risk to consider - but first and foremost my genuinely heartfelt condolences to Adrienne's family. Sounds like a horrific and tragic accident whilst on holiday in Italy. What a shocker and a real reminder to not take life for granted - especially if you're rightfully living life to the full.
**Mello Results Special starts at noon today**
There will be something to enjoy for every investor in this show. It will be a Results show special for September featuring about 20 companies that have reported their results during the month and we have a record eight companies actually presenting with Q&A during Wednesday afternoon. The show features Paul Scott, Graham Neary and Steve Clapham all very well known to Stockopedia subscribers....
As a one time offer, you can get 75% off this Results Special on Wednesday 27th September at 12pm with the code Stocko75OFF. https://www.tickettailor.com/events/melloeventslimited/970931
The very comprehensive programme is as follows:
12.00 pm Keynote presentation from Steve Clapham ‘Is Valuation still an anchor?’
12.20 pm Company presentation by Getech
1.00 pm Company presentation by tinyBuild
1.40 pm Results Round up 1 with Graham Neary
1.50 pm Company presentation by Warpaint
2.20 pm Company presentation by Eleco
2.50 pm Results Round up 2 with Paul Scott
3.00 pm Company presentation by Dillistone Group plc
3.30 pm Company presentation by Galliford Try
4.00 pm Results Round up 3 with Paul Scott
4.10 pm Company presentation by STV
4.50 pm Company presentation by Belvoir
5.20 pm Results Round up 4 with Graham Neary
5.30 pm Mello competition Draw...We will give away at least three tickets for Mello London in Chiswick on the 29th and 30th November
For more information, click here: https://melloevents.com/melloresults2709/
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering.
We hope you can join us
David
Morning Graham and Paul
You might want to edit the date as it is Wednesday 27th today.
Avingtrans (LON:AVG) Positive prelims; look a slight beat to me on Stocko figures, although I haven't delved in to the detail; revenue £116.4m, adjusted diluted eps of 23.4p. The company has significant potential given its recent acquisitions.
"We are delighted to report a robust set of results. It has been a challenging year in many ways however Avingtrans has again delivered and met market expectations. We used our strong balance sheet wisely in the year and bought HES/HEVAC, which is already successfully integrated with Ormandy. Post year end, we acquired the assets of Slack and Parr, a specialist pump manufacturer and also completed the acquisition of X-ray specialist Adaptix, as well as further investing in Magnetica's novel MRI systems. We entered FY24 with a healthy order book and we look forward to further progress across the Group this year, with macro developments in the energy, infrastructure and medical markets being tilted in our favour."
Also companies that treat their employees fairly usually do well. I think the following is noteworthy
"Profit was suppressed by £0.4m in the year, by the Board's proactive decision to make an ex gratia payment of £500 each to all employees in December 2023, to help with the cost of living in various countries."
Hi jonno
I agree that companies that treat their employees well, tend to be good companies and perform better.
Conversely, treating employees meanly is not usually a good sign.
Wednesday 27th Sept.......
Good morning, not a share topic but just about the comment thread on here. Maybe I'm alone but I do find it difficult to follow conversation threads relating to specific companies especially where there are lots of comments .
For example the original comment will reference the name of the share in question but subsequent responses are in reply to the name of the original person posting rather than reference the share identifier which is often not easy to follow where there are lots of comments.
As a suggestion to Stocko HQ, could the conversation thread contain a link somehow to the share identifier? It would then be easier to track conversations on specific shares.
Thanks, Bris.
If you change the settings in the comments to 'threaded' it links subsequent comments to the original post. That seems to keep them all organised for me.
On that theme - is it possible to view all posts for a particular company? The closest I can get to doing that is to click on the individual share and then the 'Discussions' link. However, that doesn't bring up all posts / discussions. For example, AVG brings up posts by Paul Scott and Paul Hill (and one or two others from years ago )but does not show such comments as those made today by Jonno and Shopping365. Is there anyway to view ALL posts for a particular company? If not, then Bristolians suggestion might just facilitate that additional resource.
There is no way to view ALL comments for a particular company and people have been asking for this ever since I joined 2 or 3 years ago. The request is constantly ignored by the Stocko team
Good set of interims from XP Factory (LON:XPF). Sounds like a transformational year for them - cash generative, reduced loss even as they scale, would prefer some cash in the bank of course - to underpin their growth but it sounds like they are managing financing without going to the market for more. Impressive given the macro environment and outlook sounds positive.
The figures also include a substantial payment to the former owners of Boom Battle Bars - which is a one off
When was that payment made?
XP Factory (LON:XPF)
CFO should be embarrassed...
https://twitter.com/growth_inv...
A bit negative but I won't invest in this sector. It seems to me it is so hit and miss. Sure cash generative but a bit like fashion on steroids. An idea goes mad for a couple of years and then the fad moves on.
Decent update from Avingtrans (LON:AVG) this morning in line with management expectations. Revenue up 16.8% and dividend raised slightly too. I do like their “Pinpoint Invest Exit (PIE)” strategy, a bit like a mini Melrose ( I hold both). Medical divisions expanding fast and good to see them planning to expand their apprenticeship program.
Avingtrans (LON:AVG) . Great interview with management here. https://www.voxmarkets.co.uk/a...
Chapel Down (OFEX:CDGP) announced their HY23 figures this morning. Highlights, numbers wise were ;
net sales rev up 21%, gross margin up 3% to 55%, operating profit up 27% to £685,000 and diluted eps up to 3.87p from 2.95.
This years harvest looks like it will be a record in both quality and quantity. I feel CEO Andrew Carter has gone a great job with increasing brand awareness, a fact confirmed by my local Majestic and M&S food hall where I have recently had to get them to refill the shelves with product on a few occasions !
They have also been granted planning permission for the new plant at Canterbury . Climate change would seem to be a tailwind for Chapel Down in the medium term.
http://newsfile.refinitiv.com/...
Morning chaps. My PC says it's the 27th...
Looks as though Chapel Down (OFEX:CDGP) have increased their vineyard area by more than 25% this year alone...this won't become productive & profitable for another few years at least...they are also considering listing on AIM...Additionally they state that the 2023 harvest is expected to be of "exceptional quality, with a record-breaking volume and yield".....
Chapel Down (OFEX:CDGP) have said in the past that it becomes productive within 4 years of planting.
For Chapel Down (OFEX:CDGP) , don't forget that after harvesting, they only sell the sparkling wine 3 years later. Still wines the next year, but they're shifting more and more stock away from this to the more lucrative sparkling wines.
Hence why today's update that this year's harvest will help the 2026 ambitions... but mostly only in the year 2026!
(last year's harvest was bumper volume and quality too, so that will start to feed through in sparkling wine volumes in 2025).
Think the shares currently are a bit priced in all the good news and expectations; likely to fall back to the 35p range within the next few months, IMO.
#XPF continues to scale, with solid cash generation from operations my favourite bit.
Still loss making though XP Factory (LON:XPF)
Loss making mainly due to depreciation of their assets. When you strip out the fact they are investing for growth (scaling the estate) the cash generation is good (i.e. c.3.5m so potentially £7-8m for the full year. That's 33% of their MC
I believe this is wrong and misleading.
There is no plc that generates in cash 1/3 of its market cap unless you believe in Santa.
You do not take into account the new loan and the increase in payables.
These kind of businesses have to scale their estate year after year (as older sites become unfavourable or even being closed down) and the cash generation amount you are referring to is completely unrealistic (the company’s future estimates are a fantasy).
Thanks
Still burning cash.
yiannos1 - XP Factory (LON:XPF) (I hold) is not burning cash. You don't understand what that term means.
I certainly do understand what that term means!
Someone else though clearly doesn’t.
Yes I thought operating cash flow was excellent as well and I think it looks very good value on a price to cash flow basis,
With strong bookings they look well set to have a good Christmas, so perhaps it's a little disappointing that they say full year numbers will only be in line with market expectations.
The Going concern statement for 45 Months is nice to read too, and they see scope for 100BBB and 50 EH in the UK alone.
Happy holder on this one.
Is the forecast of 8.8p next year realistic ? Presumably not given the current share price ?
Based on management's performance over the last few years is say yes.. They haven't missed a goal yet in very difficult circumstances.
2023 was always going to be a struggle with this dilution, they won't care what price they get....
"The total aggregate consideration payable for the Acquisition is £17.38 million, to be satisfied by the initial payment of £9.88 million in cash and deferred consideration through the issue of up to 25,000,000 Consideration Shares.
· The Consideration Shares are subject to an earn-out and will only be issued if the performance of the Boom Battle Bars Group in the financial year ending 31 December 2022 meets a combination of turnover and site roll-out targets. The number of Consideration Shares to be issued is subject to a sliding scale based on the extent to which the targets are met."
I think they would be rash to increase guidance in the current climate.
Yes, I think they are just being cautious, perhaps overly so