Small Cap Value Report (Wed 28 Feb 2024) - HFD, ABDP, ANCR, ENSI, SND, AML, TW., DLG, STJ, KITW

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
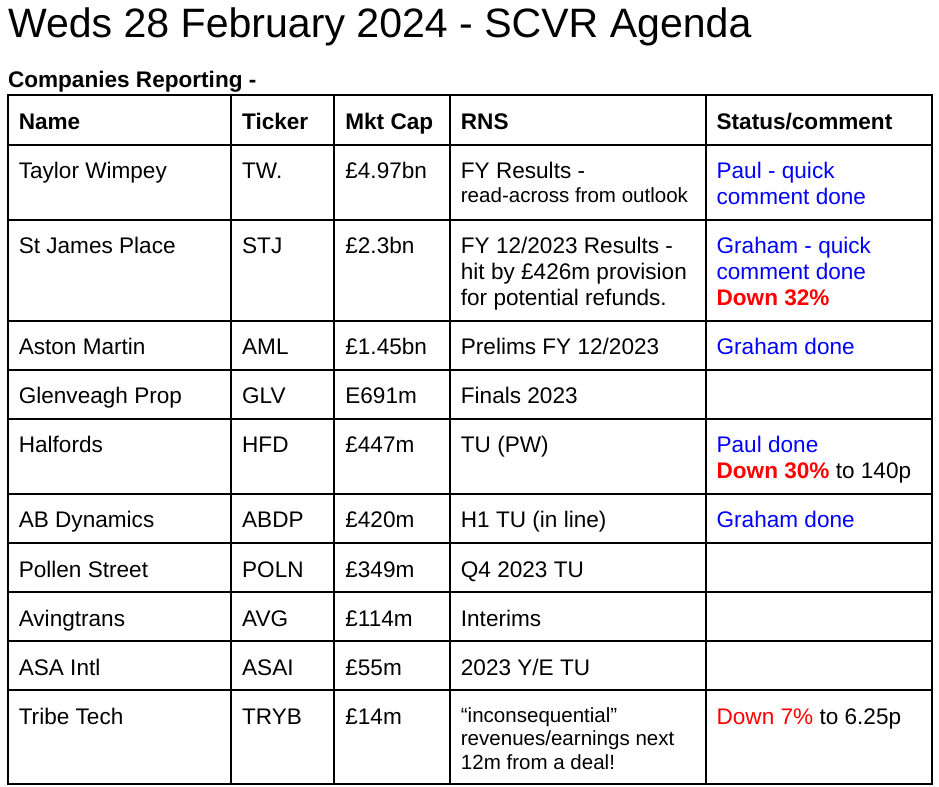
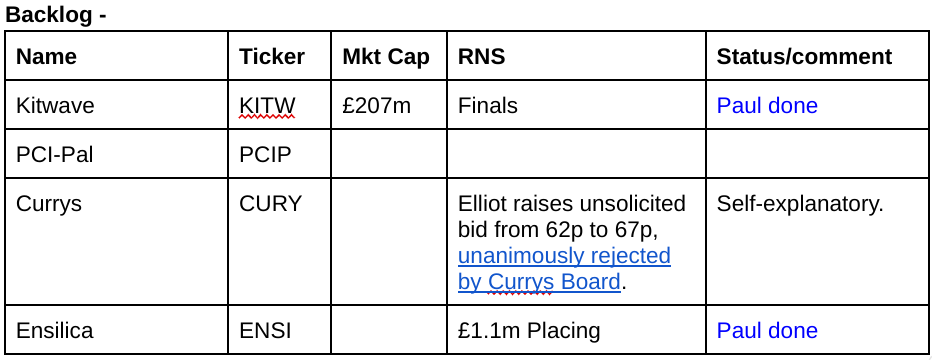
Morning Movers -
Animalcare (LON:ANCR) - up 16% to 223p (£134m) - Disposal of Identicare - for £24.9m cash, selling a “non-core asset”. ANCR net cash after this deal with be £27m (c.20% of mkt cap), says this will allow it to “accelerate our organic and inorganic growth initiatives” . Looks a good deal, as Identicare was only trading slightly above breakeven. TU 25/1/2024 was in line. Paul’s view - this looks an interesting company, skimming its H1 results. Nicely profitable. Has some smart instis (eg Harwood) on the register, and a NED Marc Coucke owns 25% (pharma expert). Worth a closer look I think.
EnSilica (LON:ENSI) - up 11% to 68p (£56m) - “Significant $20m supply win” - sounds impressive, as $20m over 2 years (2025 & 2026) is material vs historical numbers. Says it hopes to secure more orders from USA. Not clear if this deal is already in the forecasts or not?
ENSI we reviewed H1 numbers here on Monday - exciting pipeline/commentary, but weak balance sheet & needs more cash. Shares shot up 20%, and it did a cheeky £1.1m placing yesterday at 50p. I think it needs more, but with great momentum in the newsflow and a rising share price, it should be able to get another placing away. Tricky to value at this stage, as no track record of proper profits. Sexy sector, so share price could go anywhere!
Sondrel (Holdings) (LON:SND) - down 10% to 9.25p - still no news on its urgent refinancing. Remember it told us yesterday that it has to raise fresh funds TODAY to meet its payroll. If a company cannot meet its liabilities as they fall due, then that is the legal definition of insolvency, so there’s a possibility the Directors could find themselves obliged to place the company into administration imminently. Let’s hope a last minute deal can be sorted. Although a pre-pack administration could also be a possibility, in order to ditch onerous liabilities - especially expensive commitments to software licensing. Super high-risk until we know more, but good luck to everyone involved - I hope to be able to update this section later with some good news, but am very glad I don't have any of my money hanging by this thread.
Taylor Wimpey (LON:TW.) - down 3% to 136.6p (£4.8bn) - FY 12/2023 Results - in line with expectations. Revenue down 21% to £3.5bn, and PBT almost halved to £474m. Adj EPS halved to 9.9p, so PER is about 14x. Stunning balance sheet with £4.5bn NTAV (only a bit below the market cap), mostly inventories, but also containing £678m net cash.
Outlook - macro uncertain. “Some signs of improvement in the market”, from reduced mortgage rates. Planning system “remains challenging”. “Significant underlying demand”. “Poised for growth from 2025”. Expecting a further (modest) drop in completions for 2024. Opening order book in 2024 c.10% down vs LY. Build cost inflation now down to zero. Paul’s view - nothing new here. Sounds like we should be thinking about 2025 rather than 2024 for an earnings upgrade cycle to start? Maybe the strong sector recovery in share prices recently has been a little too early, who knows? Similarly for building supplies companies, if price rises have stopped, and demand unlikely to properly pick up until 2025, again maybe it’s too early to start hunting for bargains there too? Tricky to get the timing right, as markets are supposed to anticipate things c.6 months ahead.
Political risk also worth pondering. With the CMA looking into planning restrictions, alleged price collusion, and shoddy build quality, might a new Govt attack the bumper profits & shareholder returns in this sector?
Direct Line Insurance (LON:DLG) - up 18% to 193p (£2.53bn) - Bloomberg reports that DLG has rejected a takeover approach from Belgian insurer Ageas. I don’t have any more details at present, will add more when it becomes available.
UPDATE: Ageas has issued a statement - possible offer for DLG, mixture of cash (100p/share) and newly issued Ageas shares. Implied value is 233p per DLG share, a 43% premium - but of course that price is variable, depending on the share price movements from now of Ageas shares, and £:Euro exchange rate (which is usually quite stable). Ageas shares are slightly down (2%) so far today. Presumably Ageas has gone over the heads of DLG management, with this market announcement, to appeal directly to DLG investors, given that it sounds like it's been rebuffed by DLG's Directors. Yet another UK mid-cap is now "in play".
St James's Place (LON:STJ) - down 26% to 458.6p (£2.5bn) - Final Results - Graham
It’s still not a small-cap but today’s results from St. James’s Place have resulted in a calamitous share price fall. The company leads the announcement with “robust underlying financial performance” and a “pre-tax underlying cash result of £483m”, which doesn’t really help investors to understand the company’s position. In fairness to the company, its focus on this so-called “cash result” metric isn’t anything new.
STJ has now conceded that “evidence of ongoing client servicing was less complete in the years preceding investment into our Salesforce CRM system in 2021”. I suggest that you google “how to get a st james’s place refund”, and you will find law firms seeking to help customers with claims, e.g. if they did not receive annual reviews. They have made a £426m provision without appearing to admit that clients failed to receive the services they were paying for, instead only admitting that there is a deficiency when it comes to the evidence of service provision.
The final dividend has been slashed to 8p (last year: 37p) and the company is now anticipating lower profit growth in the years ahead as it changes its charging structure. It has received a media battering for excessive charges over the past year. STJ shares may offer value at this level but I am neutral as it’s not clear to me how much brand damage the company has suffered and where profitability might sit once the dust has settled.
Summaries of Main Sections
Halfords (LON:HFD) - down 22% to 156p (08:25) - £342m - Trading Update (PW) - Paul - BLACK (profit warning) - AMBER/GREEN on fundamentals
Profit warning, with PBT guidance reduced from £48-53m to £35-40m. Weak consumer confidence, and exceptionally wet weather are blamed for reduced footfall. Also the cycling market is having a tough time, which we already knew. I'm seeing the glass half-full here, as I think the market cap could now be attractive to a bidder, and we might see a consumer recovery in 2024. But a more negative view can also be argued justifiably, so take your pick from bull or bear!
Ab Dynamics (LON:ABDP) - down 3% to £18.47 (£424m) - Trading Update [in line] - Graham - AMBER
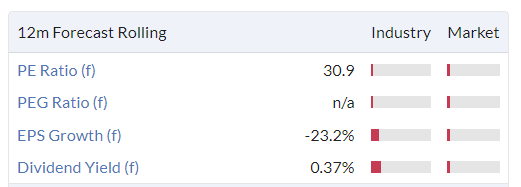
These shares are soft this morning despite an in-line update, which to my eyes highlights the demanding expectations baked into ABDP’s valuation. Trading at 30x earnings despite only 5% revenue growth in H1 and ordinary historical ROCE returns, I must stay neutral.
Aston Martin Lagonda Global Holdings (LON:AML) - down 2% to 173p (£1.4 billion) - Preliminary Results - Graham - RED
Losses have reduced and guidance for the current year includes positive free cash flow in H2, with profit margins continuing to improve. Historic financials are very poor and debt levels remain high; perhaps this one is about to turn the corner but I wouldn’t bet on it.
Kitwave (LON:KITW) - down 3% to 297p y’day (£207m) - Final Results [in line] - Paul - GREEN
I run through the FY 10/2023 results, and it all looks fine to me. Reasonable valuation, I think this remains a decent GARP share.
Halfords (LON:HFD)
Down 22% to 156p (08:25) - £342m - Trading Update (PW) - Paul - BLACK (profit warning) - AMBER/GREEN on fundamentals
Halfords Group plc (“Halfords” or the “Group”), the UK’s leading provider of Motoring and Cycling services and products, today issues the following trading update.
Halfords current financial year is FY 3/2024.
Commendably clear reduced guidance is provided today -
At our Q3 trading update on 25 January 2024 we indicated that we expected Underlying Profit Before Tax1 (“PBT”) for the 52-week period ending 29 March 2024 to be between £48m and £53m, assuming markets did not weaken further in Q4. Since that update, we have seen a further material weakening in three of our four core markets (i.e. Cycling, Retail Motoring and Consumer Tyres), resulting in a significant drop in like-for-like (“LFL”) revenue growth in our Retail business.
As a result, we now expect PBT to fall in the range of £35-40m.
Clearly that’s a setback, and shares have taken a tumble today.
Reasons given -
Unusually mild & very wet weather.
Weak consumer confidence (not hugely convincing, given that plenty of other consumer businesses are seeing sales rise - eg holidays, pub chains)
Challenging & competitive cycling market, hence lower margins.
Outlook - FY 3/2024 -
Our FY24 PBT forecast assumes the same challenging market conditions continue for the rest of Q4, including through our peak Easter cycling period in March. We have continued to take decisive action on cost, but in the short period between now and the end of the financial year this will not be sufficient to offset the significant market deterioration we have seen.
Outlook - FY 3/2025 - strange wording here, is it saying PBT £35-40m (flat) for this year too? It sounds to me as if they could be preparing us for another profit warning, if market conditions don’t improve -
Looking ahead to FY25, we remain cautious on market recovery in the short-term, and the current significant volatility in market conditions means that forecasting accurately is challenging. Notwithstanding this, we anticipate that underlying PBT in FY25 will be broadly in line with that forecast in FY24 assuming that: 1) There is marginal year-on-year growth in our core markets, with trading conditions seen in Q4 proving anomalous; and 2) The Cycling market normalises and margin pressure dissipates through the year. FY25 PBT will be supported by cost savings that more than offset net inflationary headwinds.
Paul’s opinion - I was hopeful of Halfords attracting a takeover bid, especially after the recent interest shown in CURY (despite it also being only marginally profitable (as a percentage of revenue) at the moment. Bidders seem to be looking ahead to a consumer recovery, and a lower share price after today’s profit warning could allow a bidder more room to offer a premium to a bombed out share price.
That said, investing purely on hopes of a takeover bid can be risky.
Halfords has an OK balance sheet, with very little interest-bearing debt. You can see that from the notes to the accounts, where nearly all the finance costs on the P&L relate to leases, with only £1.4m interest paid on bank borrowings in FY 3/2023.
Shares are down 23% to 155p in early trades today, which makes sense given the reduced outlook for both this year and the new year starting in April.
However, I think the lower HFD shares go, the more likely a takeover bid becomes. It’s soundly financed too, and still modestly profitable, so I don’t see today’s update as a cause for alarm. I also like the strategy of diversifying into autocentres, doing MoTs & repairs, etc, which leverages its brand strength.
It’s up to you whether you focus on the negatives today, or the upside potential from a consumer recovery and a possible takeover bid.
Roland was AMBER when reviewing H1 results here on 29/11/2023, astutely flagging concern over the expected H2 weighting.
I’ve obviously got to mark it as BLACK today, for a profit warning. Although on fundamentals, personally I see good potential upside here, so I view it as AMBER/GREEN.
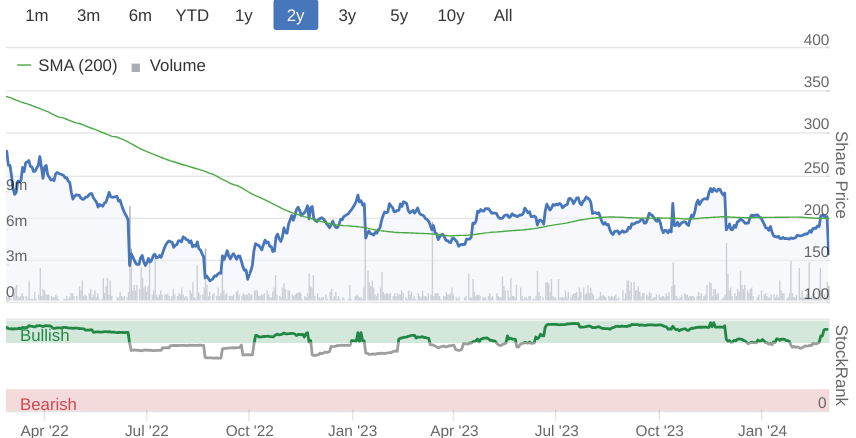
Shares are now back down at the low part of the 150-250p range they seem to have settled in over the last 2 years -
Kitwave (LON:KITW)
Down 3% to 297p y’day (£207m) - Final Results [in line] - Paul - GREEN
Kitwave Group plc (AIM: KITW), the delivered wholesale business, is pleased to announce its final results for the twelve months ended 31 October 2023.
Revenue £602m (LY: £503m)
Three acquisitions have been made since IPO in May 2021 (11 since 2011)
Profit is in line -
“... results in line with the significantly upgraded market expectations that were established after the Group's interim results, published in July 2023.”
As you can see - very impressive -
Dividends -
The Board has declared that it is recommending a final dividend of 7.45 pence per ordinary share, subject to approval at the Annual General Meeting ("AGM") to be held on 22 March 2024, which will, if approved, result in a total dividend for the financial year ended 31 October 2023 of 11.20 pence per ordinary share.
Yield is 297p share price divided by 11.2p = 3.8%
Balance sheet - NTAV is only about £20m, but that looks OK to me.
Note that net debt has risen from £18.5m to £33.2m, which is probably high enough for my taste, but the company says it’s only 0.8x adj EBITDA.
Outlook - doesn’t say much of any consequence, is more general, concluding -
There remain many more acquisition opportunities in the UK's fragmented wholesale market, and Kitwave is well-positioned to capitalise on these opportunities and deliver further value to the Group and its shareholders.
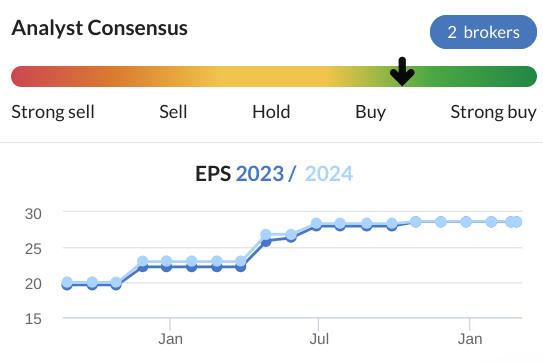
Broker note - many thanks to Canaccord. It’s showing adj EPS of 28.7p actual for FY 10/2023, with only small forecast rises to 29.3p and 30.6p in following years. Hopefully that’s set conservatively, and might be beaten, especially if more bolt on acquisitions are done.
If we say it’s about 30p, then at c.300p the PER is 10x - I think that looks decent value.
Paul’s opinion - I like this a lot. The only fly in the ointment was some Director selling last year, so you can make up your own mind if you think that’s significant or not.
On fundamentals, I’m happy to go GREEN, as I think this is a decent GARP share, growing through sensible acquisitions.
Graham’s Section:
Ab Dynamics (LON:ABDP)
Share price: £18.47 (-3%)
Market cap: £424m
Today’s update from AB Dynamics, the vehicle testing and simulation group, is in line with expectations.
Key points:
H1 revenue +5% to c. £51m
Improved adjusted operating margin (H1 last year: adjusted operating margin was 15.9%
“Good demand” for Testing Products, and a return to growth for Testing Services
Simulation will be H2-weighted as systems manufactured in H1 will be delivered to customers in H2.
Net cash rises year-on-year to £27m. The company signals an intent for “further value enhancing acquisitions”.
Outlook
The Group delivered strong order intake during the first half and has a solid order book, providing good visibility into the second half of the year. The Board remains confident that the Group will make further financial and strategic progress this year, with its expectations for FY 2024 performance unchanged at this stage. Future growth prospects remain supported by long-term structural and regulatory growth drivers in active safety, autonomous systems and the automation of vehicle applications.
Graham’s view
Nothing new to add here, and I don’t want to come across as a broken record. For example, see my comments in September.
In summary, I think I understand some of the attractions of this share - in particular the long-term structural growth drivers from the increased proliferation of autonomous driving and advanced driver-assistance systems. It has been profitable for many years, and has funded acquisitions without diluting its shareholders.
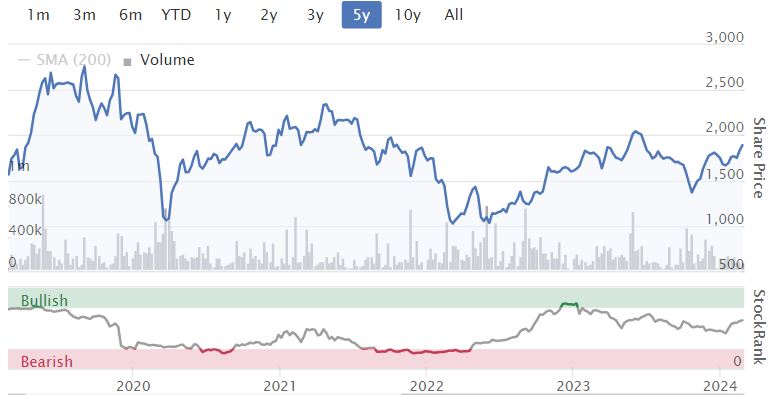
Unfortunately I still can’t get over the valuation here, especially considering that it’s not really growing very quickly in the short-term.
So far, I do think we’ve been right to be cautious on ABDP’s valuation. Here’s the 5-year chart:
There’s an interesting note from Zeus Capital, published at the end of October 2023, where they argued that the shares finally offered good value on a forward P/E multiple of 21x, or 19x on a cash-adjusted basis.
However, you would have needed very good timing to catch that low, maybe involving some clever price alerts. Here’s the 1-year which clearly shows that spike lower towards the end of October 2023.
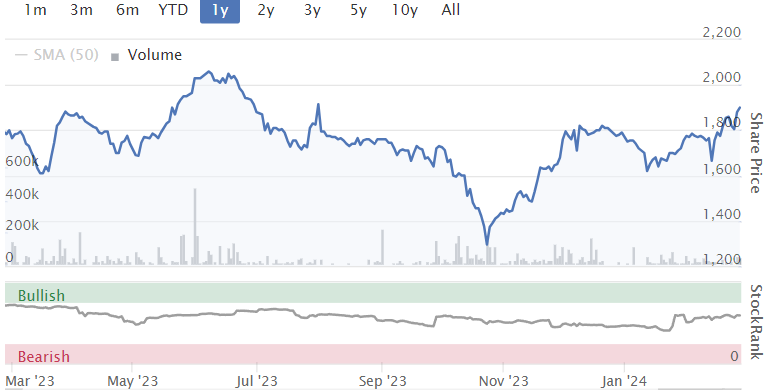
Maybe the lesson is that if this stock gets to a PER of 20x or less, it could be a rare buying opportunity! At 30x or more, “I’m out”.
Aston Martin Lagonda Global Holdings (LON:AML)
Share price: 173p (-2%)
Market cap: £1.4 billion
I’m opening up today’s full-year results from Aston Martin with very low expectations.
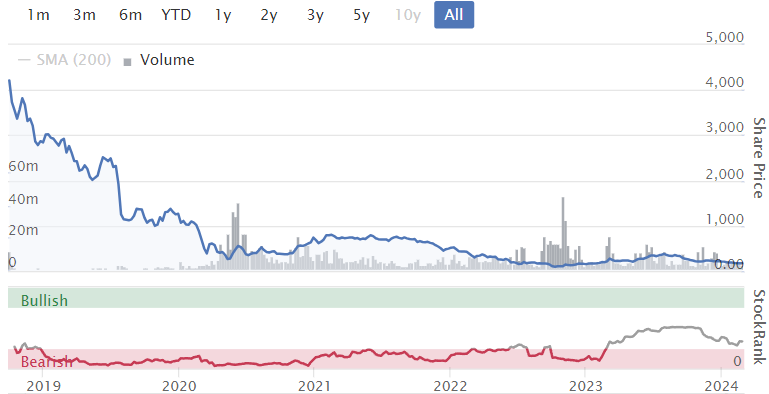
Here is the share price since flotation in late 2018:
And here is the share count:
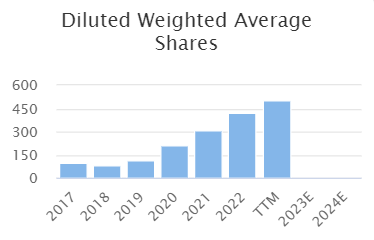
This stock has been a money pit for its major investors, who are now arranged as follows:
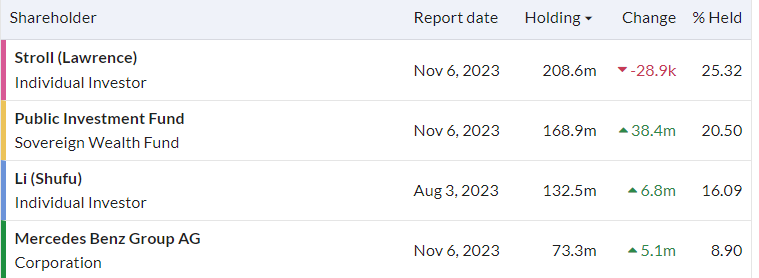
Public Investment Fund is the sovereign wealth fund for Saudi Arabia, while Shufu Li is a Chinese billionaire.
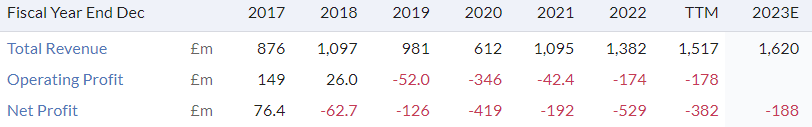
Today’s highlights show revenues and gross profits picking up, but it’s still loss-making:
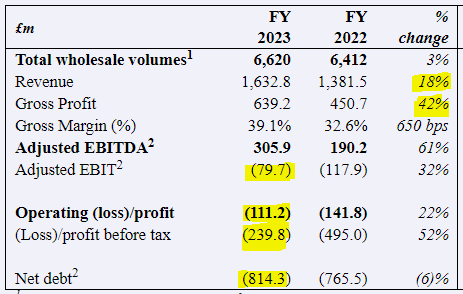
Being a luxury brand, total delivery volumes are tiny.
Comment by Executive Chairman Lawrence Stroll (excerpt; bold is mine):
"In 2023, Aston Martin delivered significant strategic milestones and further financial progress, driven by continued strong demand for our ultra-luxury, high-performance products. The rich mix of sales, driven by our ongoing commitment to product innovation, supported growth in average selling prices to record levels. This, combined with our ongoing portfolio transformation, resulted in a significantly enhanced gross margin, remaining on track to achieve our longstanding target of around 40% gross margin in 2024.”
They were very close to this gross margin target (39.1% in 2023).
Continuing, he says the new line-up of front-engine sports cars, along with other advances, “will support the delivery of the Company's near- and medium-term financial targets, including positive FCF generation in H2'24”.
Let’s skip down to today’s cash flow statement and see how it looks.
Key elements are as follows:
Net cash inflow from operating activities: plus £146m.
I see that this includes a £66m decrease in “advances and customer deposits”. Perhaps not very important and something that could reverse in future years, but it can’t be a good thing to see a decline in this cheap form of financing.
Net cash used in investing activities: outflow of £383m.
The great argument against investing in any car company is the capital intensity of the sector. Interestingly, AML didn’t spend all that much on PPE (£91m). It spent far more (£306m) on “technology and development expenditure”.
Cash flows from financing activities: these were positive, thanks to over £300m raised from the issuance of new shares and warrants. The interest bill on outstanding debt was £122m.
Overall, therefore, it’s a pretty poor cash flow performance. Of course the company is betting that its enormous tech/development spending will yield strong results in the years ahead. But for investors who want to see strong performance before investing, this cash flow statement doesn’t support that.
I also don’t see the performance for 2023 as an improvement over the performance in 2022, from a cash flow perspective. In 2022, the company spent £100m less on investing activities (£285m spent in 2022, vs. £383m spent in 2023).
Balance sheet is weak, as expected: net assets of less than £1 billion, with negative tangible net worth after deducting c. £1.6 billion of intangible assets.
Let’s now consider the debt mix.
From the going concern note:
The Group meets its day-to-day working capital requirements and medium term funding requirements through a mixture of $1,143.7m First Lien notes at 10.5% which mature in November 2025, $121.7m of Second Lien split coupon notes at 15% per annum (8.89 % cash and 6.11% Payment in Kind) which mature in November 2026, a Revolving Credit Facility (£99.6m) which matures August 2025, facilities to finance inventory, a bilateral RCF facility and a wholesale vehicle financing facility.
I’ve always viewed Payment in Kind (PIK) notes with suspicion. They involve adding on interest costs to the principal, instead of actually making the interest payment. I see them as the corporate equivalent of paying your debt “on the never-never”.
As described above, AML has a large senior note maturing next year, along with a junior note at a much higher rate (15%) where the PIK strategy has been deployed.
The directors are satisfied that even in a “severe but plausible downside scenario”, they would be able to take actions to safeguard the company’s financial position.
Outlook for 2024.
Near- and medium-term guidance is maintained:
2024 is expected to deliver another year of significant strategic and financial progress as we continue the ongoing product portfolio transformation. Enhanced profitability and EBITDA will be driven by high single-digit percentage wholesale volume growth, gross margin further improving to achieve our longstanding target of c. 40% and EBITDA margin expansion continuing into the low 20s%.
This year, there will be another £350m of “capital investment in product developments”, i.e. another large investing cash outflow.
Even so, free cash flow (FCF) is expected to “materially improve”, with positive FCF in H2 of this year, thanks to the timing of wholesale volumes.
They will attempt to refinance their debts in H1 and improved financial performance should see net leverage (net debt to EBITDA) reduce towards c. 1.5x. This multiple was 2.7x in 2023, which is uncomfortably high.
Graham’s view
I was hoping that I might not give this one the thumbs down, but I don’t see how I have any other choice.
Readers should bear in mind that I tend to be very bearish on unprofitable car companies; I was bearish on Tesla for a long time and the market disagreed with me.
If AML had a positive tangible net worth, or a large cash pile, maybe I’d be willing to think in terms of valuation multiples on forecast earnings or even a multiple on forecast sales.
But with a large net debt position (even after raising huge amounts of equity) and with profitability still some time away, I’m afraid I can’t do that. Even the promise of positive FCF in H2 seems more like an accident of timing rather than sustainable success.
I would leave this share to Formula One fans and drivers of luxury vehicles who will enjoy being part of the Aston Martin story. When it comes to making money, I’m afraid to say that I have no faith in this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

103 comments
Avacta (LON:AVCT) Placing @ 50p - egregious! Sorry for s-hers.
Another stock “promoted” as best in class by Vox/Paul H. Anyone tracking the performance of Hotstocks? Could you short them as a basket?
At 50p that puts the co. on a market cap of around £170m - that's very generous for a cash burning hope share thats only real salvation lies in a product that has only passed phase 1 trials. Any claims of efficacy that the co. has made are pure conjecture yet the SP has risen to ridiculous heights because of these mis-leading statements. There has been no double blind trials and phase 2 and 3 are yet to be passed. The vast majority of products fail to reach market. Wouldn't suprise me if the co. needed more fund raises yet, they can burn through cash, that's for sure. I hope this drug does succeed but the value of the co. at the moment is toppy at this early stage.
Luceco - Sharepad trading data is showing a flurry of activity in the last half hour, dragging the price down nearly a tenth. It could be a head fake by the data and it'll open back up to the price prevailing mid-afternoon. Or there could be a breaking story that isn't in the rns feed.
My stop triggered on Luceco (LON:LUCE) this morning. I didn't like how the price was drifting downward in a descending triangle formation for an extended period, and there were some unusually large drops in the price earlier today. I sell first, then ask question later.
Also, my stop in Arm Holdings (NSQ:ARM) was triggered quite quickly yesterday too, as I didn't like the lack of follow through action. My excitement to trade the US markets got the better of my patience. I might just trade safe old Barclays (LON:BARC) next time, that's been range bound for years, buy the bottom of the range and sell the top.
Arm Holdings (NSQ:ARM) is incredibly volatile. Only the brave would trade. I have a tiny holding in my US portfolio and it just whipsaws up and down every few days by 5-10% or so.
Jeez, just logged on, what did I miss today? Just another POS day for UK stocks, should have just kept the bitcoin I sold at $18k
POS all right, ,look at AIM, down around 4% in last few trading days...sigh
Another example of the ridiculousness of the current takeover rules!
Direct Line Insurance (LON:DLG) received the approach and offer from Ageas on the 19th Jan. Rejected it days later. And decided it wasn't worth updating shareholders at all! And we only get news now more than a month later because Ageas has gone public.
The interesting thing is that it looks like Ageas has not gone back in the interim for further talks / negotiations / offers. So why go public now? It seems like maybe they are not looking to up their offer, but looking to see if they can pressure shareholders of DLG to pressure the board? However, I note that the shareholder base is relatively fragmented...
Hopefully, this flushes out other interested bidders, although Ageas seems confident it won't given they have proactively revealed their hand.
(I hold in the Boon Fund)
Random thought on Equals (LON:EQLS), prompted by an apparent slight uptick in volume compared to the last few days. Given how long this situation has dragged on, almost whatever the reason, I think it has to have played into the hands of Madison Dearborn. I think management's heads will have turned too much to thinking of life under VC ownership and it will be hard for the board to get their focus on being plain old boring managers of a plc. It would be interesting to know how this whole process started, but think the board are likely now boxed in a corner.
Simon Thompson of Investors Chronicle continues to rate Avingtrans (LON:AVG) as a BUY.
https://www.investorschronicle...
6% margins on nuclear waste.
Not NVIDIA (NSQ:NVDA) then. :)
Epwin (LON:EPWN)
any chartists have an opinion on whether the chart here is good or bad ?
seems to be hovering just below (or on) the green line that stocky drawns in.
The 200ma has turned upwards so the bottom was in at 65 maybe 70.
It will hit a ceiling at 80, as tested back in March. Stocko's charts are really clear - let the price tell the story.
The base however looks set.
And a nice SR of 97 - wow.
But gearing at 102% with lots of pension as well then suggest there are better growth ops out there and 5% divi - not going to retire on that methinks.
Ask insiders.
Taylor Wimpey (LON:TW.) and housebuilders in general. Given the long term structural shortage of housing in this country , and despite the the recent CMA announcement, I am still very much a long term bull of this sector. TW is a cornerstone investment for my SIPP and the re-invested dividends offer a superb compounding return which are quite staggering over a 20 year time horizon. Long and (hopefully) strong.
Interesting announcement on the £4,000 million of 4% Treasury Gilt 2031 auction which retail investors had access to for the first time. There was £12bn of demand bid or x3 the amount available!
Average yield was only 4.1%, proving the inverted yield curve. Is it just me thinking this, but this is not very attractive to park money either short-term or for 7 years, when you can get 8-10% yields on many investment companies or quality businesses, all of which are on a discount as well.
It shows the level of risk-off demand there is. Also, there is a more than insignificant risk that most of the return is eaten by inflation. Finally, the tax position is very unattractive: for a higher rate tax payer the net return is possibly below inflation as you wouldn't really want to waste your ISA allowance on this! Any thoughts? TG24 and TN25 are much better homes for cash on the sidelines, in my view!
The SCVR is for those 'gamblers' out there of which to my cost fully own up - but fun and learning (don't tell the wife or grandkids).
Treasury stuff - well if had shed loads of cash the a small % of the portfolio maybe.
I'm 65 and want to make shed load of cash asap. Retire and play the stockmarket from a beach hut. Not sure govt treasuries will do that - sorry they won't.
Even worry about my pension fund with losers in control of huge funds.
The Grim Reaper awaits so lets have some fun ..............
Keywords Studios (LON:KWS) - Down 8% as I write. II sellings loads today. Anyone have an insight as to why, today? A broker downgrade, perhaps?
Keywords Studios (LON:KWS) - perhaps the recent announcement from Sony is a factor:
Sony has announced it will lay off 8% of PlayStation employees globally, amounting to approximately 900 people.
In addition to cuts in the US and Japan, the gaming giant said this would mean closing PlayStation's London Studio entirely.
In a blog post sharing an email sent to employees, boss Jim Ryan called the move "sad news" and said it was "a difficult day at our company".
"We have concluded that tough decisions have become inevitable," he said.
"The leadership team and I made the incredibly difficult decision to restructure operations, which regrettably includes a reduction in our workforce impacting very talented individuals who have contributed to our success."
The cuts come a month after rival Microsoft revealed plans to lay off 1,900 people in its gaming division, which included those at recently-acquired Activision-Blizzard.
"Sony is one of the big pillars of UK game development culture so it's massive to see the legendary Sony London studio close in particular," said Halli Bjornsson, head of UK developer Lockwood Publishing.
"It's a challenging time for our industry as it continues to go through major changes.
"However, UK games talent and heritage is world class, and if we continue to foster it, we'll rebound and be in a good place to build upon the opportunities that are on the horizon."
Always though the language AI would eat their lunch.
They are leveraging AI though?
Pollen Street (LON:POLN) trading update is strong today with Fee paying AUM now £3.4bn and an average of £2.9bn in the year which is up about a third over the year. This appears to be under the radar given the reverse into Honeycomb Investment Trust not going down very well. However, I've been attracted to it because it looks like Intermediate Capital (LON:ICP) 10 years ago. They are using the asset owner to seed new private equity and credit funds. Risk is that it turns into Tetragon Financial (LON:TFGS) (who are gradually taking out minority holders) instead...hopefully not! Anyway, there is a >10% dividend yield as well. Long-term its backing the alternative asset manager, Pollen Street, who seem very well regarded. I now have a full size position until I decide whether they can be trusted to be an ICP rather than a TFGS!
Also invested in this name - seems so cheap. Still trading at a discount to the old investment company NAV, without considering the asset manager.
HFD It doesn't seem like a company that has anywhere to go. I took a lot around a shop a number of years ago, and it was dead. Net debt has been creeping up.
My simple sanity check on debt levels is to compare EV to mkt cap, which is conveniently right at the top of the Stock reports. The debt looks too high.
Getting a little fancier, I like to compare net debt against net profits. Anything above 5 looks a little risky. HFD fails on that test, too. Interest cover is less than I'd hope for, too. So I'm not keen.
Hi Mark,
As mentioned below, the net debt figures include, in fact are mostly, lease liabilities. HFD has very little bank debt, as I mentioned in the main report.
As I also explained in the main report, nearly all the interest costs also relate to lease notional finance costs. So you've come to the wrong conclusion over debt levels, and interest cover I'm afraid.
Although maybe you work on IFRS 16 figures, but very few investors do.
Regards, Paul.
I do wonder if its something that Stockopedia could work on, Pre & Post IFRS 16 figures for the Stock Reports - would be simpler for most of us when analysing real and 'real' debt
This is why we really appreciate yours and Graham's efforts in these reports they are really useful especially when the metrics in the Stockopedia scans can give high debt ratios that can put you off investigating further. It takes more skill to break this down in order to establish the real risk / reward.
This is one area where I've fed back how invaluable your reports are to supplement my analysis of Stockopedia metrics, recent RNS inbetween earnings releases, current news, chart trends. The scans merely output a list of potential candidates to investigate further.
Thanks ettrader!
That's exactly what we're trying to achieve here, so it's great you confirmed it - screening & StockReports as the first steps, then SCVR archives are full of more interpretation & nuance on the numbers, outlook & forecasts. A good combination I think! Then of course your own much more detailed research on the business model, markets, competition, etc.
Regards, Paul.
For those who think I am negative on Avingtrans, I was already a holder before this morning with half a position and I bought the other half at open. My assessment on a SOTP valuation is that the engineering side alone is undervalued against the market cap, and the medical division is in for free. I simply wanted to recognise the uncertainties which are dragging on sentiment, and could become a drag on management time, if plans do not bear fruit. Good luck to my fellow holders.
I suspect you are right BnB with Avingtrans (LON:AVG) . I continue to watch - I don’t see many catalysts in next 6-12 months though so am waiting to open a position but management are very good and at some point that SoTP value will get realised I feel sure, I just don;t know how long its dead money
Hi David
My view on Avingtrans (LON:AVG) is I believe well know.
All I would say with regards to waiting to open a position is that if you wait until there is a sale of, for example Booths Industries, which it has been suggested would fetch £20m to £25m or the successful roll out of the Adaptix 3D X-ray scanner, assuming it happens, which I believe it will, you will end up paying the proverbial 'pretty penny'.
The Advanced Engineering Division is in my view worth more, by some distance that the current share price, the medical division being the potential fat cherry on top of the already profitable cake.
I have been out all day and have yet to watch the Vox Markets interview that Paul Hill did with the 'two Steves'. Also I have yet to read Simon Thompson's write up in Investor's Chronicle. Both of which I am off to do now.
Just my view and I may off course end up with egg on my face, but hopefully not.
All the best
I suspect you are right BnB with Avingtrans (LON:AVG) ... management are very good and at some point that SoTP value will get realised I feel sure, I just don't know how long its dead money
If you run a concentrated portfolio, then I can see that you'd want to see all your active investments working for you concurrently and right now. With my diversified approach, I'm happy to bag an apparently attractive entry price without worrying too much about the duration of the payback. It's a quality tech industrial compounder at a fair price. Buy and hold for at least a couple of years, ideally five, before worrying about the score. Although I do enjoy my engagement with their journey.
Avingtrans (LON:AVG)
This may be of interest to fellow holders - interview with the two Steve’s with Paul Hill.
https://www.voxmarkets.co.uk/a...
Excellent to see the Steves agreeing that they need to license out their technology.
thanks for this!!
EnSilica (LON:ENSI) Sunday Times tipster quite often tips shares- that have fund raising's soon after. Uncanny.
The BBC is reporting on their News app that they have found that Drax (LON:DRX) "has kept burning wood from rare forests in Canada it had claimed were 'no go areas' "
Drax has denied taking wood from primary forests .....
The BBC article is long and detailed and seems to be a Panorama re-investigation.
(I do not hold Drax)
£Drax is an environmental scam for subsidies - they found a way of switching from coal and retaining a green look whilst still being allowed to burn stuff. Its only because the UK have so little other infrastructure in place that it survives. I would have a very high discount rate on future cash earnings beyond 5-10 years. The same subsidies put into building up the grid/wind farms etc will be much more popular as generational change occurs and politics moves on.
Some concern in the press today that Britains energy will fail to meet demand in 2028.
"Analysis by Public First predicts that the UK’s demand for power will exceed baseload capacity by 7.5GW at peak times by 2028 – a shortfall equivalent to the power used by more than 7 million homes.
A shortfall is expected as ageing British power infrastructure is set to close in the coming years. Ratcliffe-on-Soar, the UK’s last remaining coal-fired power station, is scheduled to shut down this year." - Daily Telegraph
Dont hold Drax but suspect that we will be relying on its ouput longer than envisaged.
So many conflicting stories in the press -often within the same newspaper, you could end up Schizophrenic! For example in the Telegraph there is a story of falling Energy consumption in the UK. The article says that various sources claim this is a signal of dwindling economic growth (increased electricity consumption being a marker of growth they claim) rather than a more positive interpretation of growing Energy efficiency, though a warmer February is also mooted.
Eeyore or Tigger? Take your pick!
I like Cameco (NYQ:CCJ) (Canada safe ish) but UK is useless so do not need the supply for many years (although have to buy in advance) - like buying petrol for your car that you wont use for 10 years plus. Idiocy.
Ok the saviour is small bombs next to cities. Ok. But Asia and Westinghouse are ahead of that game. Maybe Rolls-Royce Holdings (LON:RR.) but have yet so see evidence substance. BAE Systems (LON:BA.) good as actually have this kit floating around in submarines, but then then their share price has already known that.
Halfords (LON:HFD) .PlanetX has been helpful with info about the cycling market.US listed Fox Factory Holding (NSQ:FOXF) which does suspension kits for the cycling market has had 2 successive profit warnings last couple of quarters, which made me wonder as a non expert (although doubt/doubted the straight read across).However, the volatility of today's move for Halfords is definitely not a normal standard deviation for the share!Market spooked indeed.
St James's Place (LON:STJ) has taken a bit of a tumble again this morning too.I still hold the very out of favour Jupiter Fund Management (LON:JUP) and some definitely are still market darlings, a bit like NVIDIA (NSQ:NVDA) and Nasdaq (NSQ:NDAQ) right now and some more like Macy's (NYQ:M) until their recent bid and switch to focussing on more high end, 'luxury' stores.
For all the bashing Boohoo (LON:BOO) and others get about working conditions, it seems Jeremy Hunt and the LSE are willing to overlook ESG issues pursuing SHEIN to float in London. Clearly the US think otherwise.
https://www.retailgazette.co.u...
Both government and LSE are so desperate to accept this floatation that will probably be overpriced as well.
Quite extraordinary!
More liquidity would be great.You need buyers to step in on profit warnings, which i can't do alone!It would allow more loss making UK tech companies to grow over here too.Strong, healthy capital markets are important to growth and a country's prosperity and alot of big money doesn't even hate and short the UK, they just ignore it
!Shein is seen as a tech company i guess and priced so.Here's hoping it isn't a THG (LON:THG!Though if they get the price they want in these market conditions, i doubt.The Chinese are great at technology, even though i think Chinese big tech might be a value trap currently.
The great transfer of wealth from West to East. And we continue to think it is ok....
ref shein - even if they dont get their comeuppance now - they will have to up their game if they list in london. In summary is Hunt not presuming the relevant stuff will be their for public show and sorted as approrpiate if their standards needs upping later. at least our free press will not shy away from highlighting any issues !!
I have mixed feelings whether our press expecting companies to apply uk standards to worldwide activities is always a good thing , if that simply means that companies decide not to have the hassle of listing in then uk to avoid peeps trying to tell them how they should run their business in other parts of the world.
Hey ho in some respects if company wants to do the right thing then facing the hassle of finding acceptable position (as booho have done) isnt probably the worst for all. Slightly surprised that Shein would want the hassle of being listed here unless they cant get listing elsewhere that has similar kudos ? - hopefully they want to do the right thing - ie acting to relevant legal standards in each country.
Couldn't agree more! Boohoo (LON:BOO) came in for massive criticism over working conditions and yet this government is keen to attract SHEIN which has a very dubious ESG background (see: https://www.bbc.co.uk/news/bus... Also see in the press today that Gen Z are massive fans of Shein. Whatever happened to their desire to save the planet - Fast Fashion and human rights questions overridden if something is cheap it seems !
To add insult to injury, Shein have approached the suppliers of BooHoo and ASOS asking to explore supply opportunities.
Shein have approached the suppliers of BooHoo and ASOS asking to explore supply opportunities.
they aint silly are they - business is business as they say - if suppliers have done all the relevant info (jumping through hoops to prove they arent paying cash amounts below minimum wage etc) to satisfy Boohoo and ASOS - certainly makes life simple for Shein conducting the same due diligence - they probably just say just send us what you sent boohoo cheers that will do !
Would be odd if Bohoo hadnt at least tried to protect themselves in some manner - reality is there is probably very little they can do other than threaten to take business elswhere.
hey ho - the whole attraction of boohoo was that it was meant to be able to deliver the operational excellence that competition wouldnt be a problem. i think they were deffo clear leaders in the uk back in the day - now though there are more rules more competitors and they certainly got delusions of gradeur ref overseas
Halfords (LON:HFD) tumble looks a decent entry point bet to me. As interest rates fall later in the year, the cost of servicing any floating rate debt will decline. The massive increase in wages already plumbed in from April will give folk more cash to spend, as will falling mortgage rates. I think there is a big opportunity for improving results here over the next couple of years. The only negative is the amount of debt they carry, bad enough in itself, but might also limit the amount private equity could raise against its balance sheet to buy it. I’m taking a glass half full on this one and bought a chunk at 152p.
Beginning to look cheap, although never been a fan of Halfords, always considered the products they sell as too expensive for what they are. Just don't see why people buy there.
Had that same opinion about Mothercare.
Hi Rhodie,
Halfords (LON:HFD) has very little bank debt, as I explained in the main report.
It sounds like you're including lease liabilities on its property portfolio within debt, which of course are not actually debt they're future operating costs. But absurd accounting standards require them to be disclosed as debt.
This is a key point to remember when looking at any multi-site business.
As with most retailers, HFD is funded by its trade creditors (money owed to suppliers), which of course is not interest-bearing. In an ideal world, retailers sell the stuff in their shops before they have to pay the supplier's invoice. I kept a retail business operating for years back in the 1990s by paying suppliers with post-dated cheques that never bounced, so their own banks would lend against the security of my cheques! Sounds crazy now.
Regards, Paul.
Halfords
Bike market Armageddon that I have talked about appears to have further to run .
I’m in Italy and Holland this week seeing some old suppliers and industry people .
Absolute horror stories about the quantity of stock in Taiwan / China that all companies keep “delaying”
The huge orders just sat there. There’s a factory - brand stand off going on with brands “delaying” because they can’t cancel and factories with no work or new production sat on literally millions of bikes that are gradually going out of date .
No end in sight, maybe 3 years of stock to work through so I’d say you can take it that Halfords , Tandem etc have 3 years of at best treading water on their bike side but more likely downwards .
Meanwhile Mike Ashley appears to have taken the “buy everything because it’s so cheap” approach having now acquired the IP of wiggle / CRC (in what actually looks a total stitch up ). I actually don’t think they have a plan but he knows when there is something cheap that throws up an opportunity .
Wonder if there is a point when Halfords becomes so cheap that Mike Ashley “nicks it”
If Ashley had Halfords on top of his other cycling assets he has effectively taken out and acquired the Uk cycling market at very distressed prices at a time it was totally under pressure and out of fashion .
So I think Ashley will try to take out Halfords and his coup d etat of the cycling market is complete .
They did once try to buy PX in one December for a pound from me but alllow me to keep 49% and I sent a message along the lines
“I am still surprised that at the tender age of 55 years old Mike believes that Santa will bring him free gift but I can assure you that is not the case .
On that basis let’s enjoy Christmas and I hope Mike finds something nice under his Christmas tree”
planetx
Re Halfords (LON:HFD) and the overall UK cycling market. As you have alluded to previously the UK bike/cycling accessory market has been hugely distorted by the Covid boom and bust. I am assuming that because of the size of the country the N.American market is quite different to UK but what is happening in Europe? Is it affected by the same factors as it is here? Interested in your trade knowledge.
Just as bad in Europe and USA
Same problem but magnified for the bigger brands .
Specialised., Trek,, Scott group total worldwide carnage .
Just massive over ordering on huge leadtimes during covid then huge drop off post covid
Easy to understand and explain -
Imagine you are purchasing manager at bike co
Pre covid you sell 100 black pedals every month
Leadtime is 3 months
Stock turn you work to say 4 months
So you would order 400 pedals every 3 months .
Easy Peasy
covid boom .
- you start sellling 500 pedals in a month
- customers have big demand
- you try to order 500 pedals
- but so do all your competitors
- factory say “thanks for order but lesdtime now 18 months please give us big deposit and schedule order so you can get guaranteed delivery
- you think oh shit so place order schedule
- 500 pcs in 18 months , 500 pcs in 21 months , 500 pcs in 24 months , 500 pcs in 27 months
You meet your ceo and say “don’t worry we have our orders scheduled and we are covered , but you need to send 30% deposit asap”
then 18 months later
factory say “order ready please pay”
You say ok and ship 500-1000 pedal
then putin invades Ukraine , liz truss does something silly, interest rates go up , everyone stops cycling and have a new bike anyway
even worse your post covid run rate is not 100 pcs , it’s 20 pcs a month because market is soft
and you have 1000 pedals on the water (2 year stock turn) that need paying and 1500 pedals at the factory
no cash . Too much stock and Armageddon .
You killed the company because of Billy big ballls orders placed based on covid sales .
I don’t know a single purchasing manager or FD that was prepared to sit back and say “we’re not ordering because this is unsustainable”
I did predict this and do like to think I would have called it but I was on a non compete watching it happen so who knows .
planetx
I sell premium lightweight kids' bikes. In fact, that's all my business sells, so no adult bikes and no e-bikes.
I'm not seeing a bloodbath in my sector of the bicycle market, so I don't know if kids' bikes are more immune to the general bicycle industry malaise? A possible reason might be that kids keep growing so they need replacements every other year, unlike adult bikes.
Although Tandem (LON:TND) as a whole isn't doing particularly well at the moment, Squish bikes (a kids only brand) appear to be an exception in their cycling division. I cannot speak of Halfords (LON:HFD) as I don't sell any of the brands they sell (they focus more on the lower end of the market).
Fingers crossed it continues and is not a delayed reaction coming my way!
Kids bikes hopefully less exposed .
Though note that Isla who were a great company making the best children bikes shut up shop last year .
You might even have been a beneficiary of that .
Don’t think Isla bikes went bust or anything just packed in, think they had a go at setting up in USA that hurt them .
But looks like you have a good niche .
Tandem I think have blown their cash pile on a supposed lovely state of the art warehouse that is now too big for them .
Warehouse is a prime asset for an interested buyer but pension deficit was also an issue .
Yes, I was surprised by Islabikes' decision to shut up shop and sell their existing stock. They were considered the best of the best in lightweight kids' bikes by many. The Islabikes void will no doubt be filled by Woom or Frog for the new Top Dog.
I asked Islabikes on numerous occasions to be a UK dealer but they never seemed interested in the idea of a UK dealer network. Shame really, as I always thought selling D2C only would limit their sales growth.
Yes, Tandem (LON:TND) has taken a risk by spending so much on their new warehouse as it's too big for them at the moment. Indeed, I regularly speak to them and they say they have plenty of warehouse space available if I want to make use of it!
I think the e-bike manufacturers have killed their own golden goose.
In 2019 I paid £3k for a decent e-bike. Then in 2023 I replaced it with a slightly better spec bike, but that cost nearly £6k.
Today, when looking at a similar bike with slightly better components its nearly £10k.
Things have got out of hand and as far as I can tell the greed of the manufacturers has resulted in pricing themselves out of the market.
Nobody I know is buying new bikes at the current prices. Somebody somewhere is making good money, but that only happens if you get the sales and at these prices I cannot see there being a big demand.
Frog bikes?
Wales based outfit.
Good bike well made and set up good for smaller light kids
Daughter has one and loves it and several friends do too
Really interesting, thanks. I live in NL and e-bikes are everywhere and the gov improving and widening bike lanes for e-bike commuters. Rad Power Just pulled out of EU to concentrate on Us market. Fire sale, all e-bikes half price.
In Milan this week. New bike lanes everywhere.
it’s about infrastructure. Build that and people will be more likely to bike more.
agree
It’s still a long term rising tide
Mike Ashley knows this .
Buy when there’s blood on the streets .
Needs vision and gonads - he has both
On my nearest retail park, the Halfords store is right next to the Sports Direct one, and there must be loads like that. The potential synergies from merging the operations must be massive, maybe sell off the autocentres/tyres business for a bit of cash. Bit of a no brainer, just a question of price i think.
Hi M48
I have no investment interests in Sports Direct or Halfords.
However, your comment and various others on the thread discussing what Mike Ashely's intentions might be, prompted me to ponder whether he has sights on competing with Decathlon.
https://www.decathlon.co.uk/
From Google .. 'Decathlon is a French sporting goods retailer. With over 2,080 stores in 56 countries and regions, it is the largest sporting goods retailer in the world'
Having visited several of these stores - they are large retail sheds whereby every form of sport and thus equipment and clothes are all under one roof - they always seem to be busy and offering what people want. Not just the goods, but a great shopping experience.
Just a thought.
Regards
Howard
Hi Howard. I agree, I can already visualise the store. Slightly different offerings (decathlon in my experience has less branded goods, but is possibly a friendlier shopping experience). Don't know if you saw that Ashley took a stake in Hornby, I can easily see a vision for an all encompassing sports and hobbies offer.
On Beach group (LON:OTB) litigation with Ryanair costing £2m per year since 2010. That cost now drops straight to the bottom line.
https://www.thetimes.co.uk/art...
That’s useful info - thanks eParo
On Beach group (LON:OTB)
On Beach group (LON:OTB) litigation with Ryanair costing £2m per year since 2010. That cost now drops straight to the bottom line.
are you sure thats the case on lfl basis -?? is it not possible that the settlement means that they will pay over £2 million per year more to Ryanair in fees , kickbacks or whatever going forward?. I would NOT presume any company would be getting the better of compromise arranagement with ryanair - i think we all know how ryanair do business !
Halfords (LON:HFD) comments on 'Consumer Tyre' sales saying sales down 4.3% in Q4 after being 2.6% lower in Q3. With the awful state of our roads causing many drivers to have to replace tyres due to pothole damage I would suggest this speaks of driver miles being increasingly lower, a read across to the motor trade in general. Less miles driven less need to replace your car?
My 87 year old dad was at a Halfords (LON:HFD) in Edinburgh recently for a tyre and they told him business was booming because of the potholes…which coincidentally was why he was there!
Aberdeeshire council seem to adopted the technique of putting traffic cones into the worst of the potholes. My dad excused them by saying that they probably just haven't gotten around to it yet. I cynically enquired as to when precisely the council planned to fix them.
There was a snippet the other day about a guy who got a pothole fixed by taking a birthday cake with candles to his worst pothole and whacking it into the local paper!
A quick google enables one to cunningly link in both Halfords (LON:HFD) and Taylor Wimpey (LON:TW.) both of which reported poor trading today.
https://www.itv.com/news/centr...
Tata confirm Bridgwater as the site for their 2026 gigafactory. I thought this was a done deal a while back. Great news for this area. It needed it.
The amount of money going into Bridgewater and surrounding areas from the Hinckley nuclear plant is staggering already. Now Tata have confirmed they are coming then that's terrific news for the South West!
A positive update today from Gulf Marine Services (LON:GMS) (I hold) together with a nice share price bounce
Firstly commiserations to holders of Halfords (LON:HFD) it looks as if the shares will take a bruising today.
Regarding Avingtrans (LON:AVG) which I hold. I am happy to remain invested. I view the interims as positive. There is much speculation about the medical division and the investment in Adaptix and Magnetica, I am happy to trust management with the allocation of funds and time will tell if they are right and my trust is rewarded.
On the subject of Adaptix, I would point out that the X-ray device provides 3 dimensional images (3D) similar to a CT scan (computed tomography) not 2 dimensional. A 3D scan provides medical staff with much greater diagnostic detail. A personal anecdote from a visit to my dentist last week confirmed this view. As I sat in the chair, I commented on a sophisticated but quite large X-ray machine standing in the corner. My dentist replied that it is almost never used as it only provides 2D images and that he refers patients for 3D X-ray where greater detail is required for root canal and other more complex treatments.
I stand to be corrected but suspect the X-ray device in the link provided by jeessowens provides 2D imaging.
See below regarding the development of 3D X-ray scanners. I wouldn't necessarily put a lot of faith in Matt Hancock, but Adaptix is at the forefront of this innovation
"Technology used to scan stars across distant galaxies will be incorporated into a portable 3D medical X-ray machine to be used in GP surgeries across the UK.
The UK Space Agency will funnel 1 million into developing equipment that can allow doctors to more comprehensively scan for tumours than existing 2D scanning technology.
These next-gen scanners will also be miniaturised, portable and satellite-linked, meaning patients can be examined via X-Rays in GP surgeries immediately instead of having to wait for hospital referral.
This is the latest digital transformation project the NHS will undertake following a string of government commitments to integrate technology into the healthcare sector.
Health secretary Matt Hancock, in particular, has advanced the need for the NHS to make better use of emerging technologies being developed by the UK's digital sector.
"Technology has enormous potential to save lives. This is a brilliant example of how innovators can work with the NHS to help save lives with more early diagnosis of cancer," Hancock said.
"It's all part of our NHS Long Term Plan, building on the work of NHSX, our new organisation built to drive new technology through the NHS.
"We will deliver by opening the doors of the NHS to the best technologies like this, to build a preventative, personalised and world-leading health and care service."
The 3D X-ray machine is based on technologies currently used to scan distant stars. These include field emitters etched onto silicon wafers, used in ion thrusters, as well as X-ray optics deployed in star mapping missions.
The NHS hopes that repurposing this technology into a form that can be used in practical healthcare settings will save clinicians and patients time, as well as improve detection rates for cancer.
The scanner, built by Adaptix, is the first of four projects to receive a share of 4 million innovation fund put forward by the European Space Agency's (ESA) Business Applications and Space Solutions programme.
"Being incubated at the world-renowned Rutherford Appleton Laboratory in Oxfordshire's Harwell Campus, a major centre for the UK Space industry, has given us access to fantastic facilities and leading minds to support the development of our space-heritage technology," said Adaptix's CEO Mark Evans.
"Our vision is to create a business that will Transform Radiology through the export of high-science-content high-value products to achieve revenues of more than $100m.
"X-ray is the primary diagnostic in healthcare - one day we hope that Adaptix technology will touch the lives of everyone that you know and being supported by the NHS through this grant will help our team realise this vision."
This joint venture between the UK Space Agency, the ESA, and NHS England was launched in June 2018. This collective asked companies to bid for a portion of the 4 million to translate technology originally built for space into medical equipment that can improve patient care."
Regarding MRI scanners, Magnetica is developing a portable helium free device for use in clinics, surgeries etc, the MRI scanner in the link provided by jesseowens weighs over half a ton hardly portable.
"The cylindrical machine stands chest high and could be the brooding older brother of R2D2, the Star Wars robot. One of the researchers carefully guides the 630-kilogram self-propelled scanner up to the head of the bed, ..."
As I previously mentioned the challenge now is in successfully commercialising these devices. Over to the two Steves at Avingtrans. My view only I will leave others to their own decision making.
All the best
I like the longer term prospects forAvingtrans (LON:AVG) But do not see the triggers for rerating in the next twelve months. Like with many other of my UK holdings. I have reduced the exposure.
Hi Paul,
Would be good if you could take a look at the Animalcare (LON:ANCR) RNS. They have disposed of a non core part of the business for what looks like a very good price which will significantly strengthen their balance sheet. Cheers Andy
Usual gibberish from Nexxen International (LON:NEXN) sounds positive but what's actually going on.
Nexxen previously, Tremor were claiming c$65m from Alphonso and LG (court documents were interesting). A disconcertingly vague settlement annoucement today stating that there is a financial component and a 3 year "partnership" which will give Nexxen access to a portion of LG's CTV inventory. If the lack of data supply, as a result of Alphonso/LG#s actions, is truly what hobbled Nexxen/Tremor's business it will be interesting to see what they can now make of it.
Nexxen International (LON:NEXN) : personally don’t think Alphonso/LG had any real impact on the business. I do think that settling the legal action is helpful and re-activating a portion of the CTV inventory is useful in the future. No numbers given but I’m not sure the cash element was ever really the point. Protecting contracts vigorously is a good thing from a business perspective as it ensures the company is not seen as a pushover.
So in my view this is mildly positive but broadly irrelevant. What Nexxen International (LON:NEXN) really needs is advertising markets to move out of the cyclical trough.
The last time I mentioned a discussion post outside SCVR I discovered there were those who came straight into here from the home page and didn't know there was anything else!! (I always open Stocko at https://www.stockopedia.com/di... )
So in case you are missing out there is an excellent discussion betwen the two Pauls here:
https://www.stockopedia.com/co...
Covering:
Halfords (LON:HFD) reporting three of their four markets weakened into Q3, with only Autocentres seeing any resilience. Cautious outlook statement, FY guidance narrowed materially. Recent share price action will have left quite a few lured in by an apparent cup and handle nursiing sore heads.
shocking statement from Halfords certainly not having a goodyear, thought they would rule in car tyres due to number of sites.
Halfords (LON:HFD)
I used to own halfords years ago and they have always been prone to have poor/patchy trading for long periods of time when compared to their few "purple patches" when things look positive for the future - when they aint in ten sweet spot the reality is this business makes less than it did 10 yeaers ago on close to double the turnover. In the old days their werent nearly as good in automative either. Ok looking at history doesnt help and perhaps they may have now past inflection point where the decline in the old skool stuff has finished and whats left now might offer potential for above inflation increases at some stage - but their long term clear poor track record (heck they even have 10% more shares in issue now that 2018!) doesnt really over intice me to buy back in particularly.
I wouldnt argue though with the logic that if commerical B2bB automative takes off bikes bounce back and there is bidder in background (we kinda know that is the case anyway with reddes recent enquiry) then shareprice could easily be back over 200p.
Looking forward to next trading update which is probably more important now if we dont want shareprice to be at 120p - am i positive things will not stay subdued as they are now - hell no. So i am not likely to buy even though i do have some spare cash ready and waiting to deploy.
Halfords (LON:HFD) Not having a Goodyear but really out of the frying pan onto the Firestone now. I hold but not jumping off the Bridgestone yet…
Like all investment vehicles now and again need to “kick the tyres”.
Agree re Halfords. Wouldnt be so bad if they pointed to some green shoots but they seem to be rolling the pitch for another possible warning in '25.
Avingtrans (LON:AVG) operational performance in line with expectations and full year outlook reiterated, I thought with strong confidence, but Cavendish says cautiously confident - better go with them. Slight margin deterioration on product mix and MII investment. Continued strong order book. All tempered by the uncertainty surrounding the MII investments, which, though anticipated to be highly profitable, must today be rated blue sky and cash burning. Any guesses as to the market response?
Avingtrans (LON:AVG) are up against competitors who already have FDA approved compact MRI products in the market
https://www.science.org/conten...
Perhaps they have made a technological advance , but it certainly seems like the kind of product that would need tens of millions invested to succeed as they need to drive significant behavioural change and beat out their competitors
Seems like a similar story with small form X ray machines https://nhsforthvalley.com/new...
Avingtrans (LON:AVG) are up against competitors who already have FDA approved compact MRI products in the market
Exactly. And even if there were none, the path to commercialisation is fraught with obstacles and inevitably longer than initially envisaged.
They really need to commercialise their operation by licensing or just selling it off.
There were no other takers when Avingtrans (LON:AVG) acquired the majority of Adaptix for £3 million in July, suggests the tech is nothing special to me
Avingtrans
The thing that is with Avingtrans is that you guys appear to be treating management like the founders of a jam tomorrow typical AIM cash burning hope and hype company .
There is nothing further from the truth and the guys running through show are hard core proven operators that know how to run a business .
Share price is fully underpinned by the engineering businesses (and more on top) that they sell off when the right offer comes in .
Then it is rinse and repeat on future turnarounds .
Frankly I think the current valuation is stupidly low and I added heavily at 334 last week .
In terms of solid assets, in what I consider the best management team on AIM , with potential upside on the Imaging side my strongest holding current my only 10/10 ranked share this week in my portfolio weekly ranking .
Mr Market and investors focussing incorrectly on the new division is in my mind throwing up a real opportunity .
I quite liked it being talked down and down and had some Warren Buffet swinging Billy big balls to increase further .
Could be wrong of course and DYOR but think the management are just so good here , they’re “investable”
I agree Planetx - but if time is money what is the time?
I think the question with Avingtrans (LON:AVG) is why buy now? What are the upcoming catalysts that will drive outperformance this year? - I don’t really see any.
Love the management, think the SoTP makes it undervalued and the engineering division is being prepped for sale, but my guess is not this year and poss not next. If you look at it on a PER basis 15* this years EPS doesn’t scream value so I think you have a chicken and egg situation. I anticipate there will be a big step in share price but I suspect not for a while so money maybe better allocated elsewhere for a while. Question is when to buy……
If you take a long term view (3-5 years) of course that’s fine but then you need to make sure your compound growth target can be met if it takes 3 years+ to get there.
Not sure I’m clever enough to time and guess the market .
And anyone sat on the sidelines waiting for the right moment is let’s be honest never going to time it perfectly .
When the market has moved it’s too late .
If you like the company and vakuation and management and want to own part of a company then that’s what you should do
If yiur trying to time the market and catch lows / highs it’s pretty much a skillset most don’t have
Hello planetx,
Good point, it's something i do too much, wait for the opprtune moment to buy. Mind you, if you had waited today from yesterday, a lot of equities would have been cheaper...
It’s all very simple. Currently the SP is below the 200dma which is pointing downwards.
Im setting an alert for 400 and forget about. Thanks for putting on the radar sounds very interesting.
Whilst I do appreciate your views, as a small cap this is possibly the attraction to larger businesses that could easily push for FDA approval. I'm not sitting here waiting for a take over, but if a company's revenue is steadily growing with profits in a tough market then *maybe* this is a long term play.
I'm not a huge holder of Avingtrans (LON:AVG) but it is a speculative play to see what happens in the coming months. If it's a steady grower, I shall keep. However, should negativity and troubles start to show, then yes I will cut my losses.
My overall message is don't be put off a stock due to ongoing challenges, especially if the company is steadily growing.
I shall hold and review again by the next quarter. With alerts/stop losses set should bad news come out.
(Just my luck Stockopedia have now rated at "falling star")