Small Cap Value Report (Wed 29 August 2018) - GYM, BKS, IQE, JPR, RIC

Good morning!
Thanks for getting all your requests in.
Today I'm planning to look at:
- GYM (LON:GYM)
- Beeks Financial Cloud (LON:BKS)
- IQE (LON:IQE)
- Johnston Press (LON:JPR)
- Richoux (LON:RIC)
GYM (LON:GYM)
- Share price: 325p (unch.)
- No. of shares: 138 million
- Market cap: £448 million
This is the innovative low-cost gym chain which is currently experiencing rapid growth.
It's one that got away from me, as I was dabbling in the shares below 200p last year. I couldn't quite convince myself to hold on to them, however. I'd be up by nearly 80% if I had.
There could still be a fine opportunity from current levels. So let's take a look at these results.
The company says it is on track to meet market expectations.
Headlines:
- Revenue +36%. An important figure but the group is expanding its estate and has grown by acquisition. So it's not a "like-for-like" number.
- EBITDA margin falls to 30%, "reflecting immature estate profile" and the effect of converting gyms from an acquisition it made last year.
- Adjusted PBT of £7 million.
The adjusted PBT is calculated after adding back in amortisation of acquired intangibles plus exceptional items.
Having looked into it, I think the adjustments aren't terribly out of the ordinary. Note however that exceptional items were pretty big last year (£1.7 million) and are already £1 million in H1 of this year. They are likely to drag on results for as long as The Gym is making acquisitions and lots of changes to its estate. But hopefully these expenses will lead to a lot more profits in the future.
- Small interim dividend. The company has been raising new equity for growth, so the dividend doesn't really matter. It's all about getting bigger for now, rather than producing an income stream.
- 6 new gyms and 13 gyms acquired (total: 147). Still targeting 15 to 20 organic openings for 2018 (will need to do better than 6 in H2!)
- CFO becoming CEO.
There's no reason for the shares to move anywhere today as things are motoring along as expected.
It's a fine pace of growth. As the CEO points out, the number of sites has increased from 100 in October 2017 to already close to 150.
But more than 30 of those sites were acquired from other chains (18 from Lifestyle and 13 from easyGym), so the organic growth rate is much more relaxed than the headline rate.
The strategy is to be "the lowest cost high quality operator" - i.e. it is competing heavily on price against other gyms. From all appearances, this strategy is working. Maybe we can call it the Ryanair of gyms?
Software - it has started using the Workday ($WDAY) ERP system, and is excited about the potential benefits. Sounds good.
New sites - we are guided for an H2 weighting for sites within the M25. Sounds like things are possibly a little slower than expected.
There's an opportunity to rent some sites that have been vacated following retail CVAs. This is a theme we've touched on before - retailers being replaced by experiences.
Premium model - aiming to increase revenue per member with a premium option called "LIVE IT" (link). I can see this having some merit, especially the freedom to use more gyms.
Cash flow - very helpfully, GYM breaks down maintenance capex and expansionary capex.
Having done so, it reckons that after-tax free cash flow generated over the six months was £13.6 million. Another good result, I think.
My view
Based on price action over the past year, I regret not holding on to this. I continue to think it's a good company, executing well, with good growth potential. I would like to see a bit more emphasis on organic growth rather than buying up sites from other chains, although I accept that the acquisitions it made probably had a sound strategic rationale.
EPS is forecast at 12.7p in 2019. With continued growth in market share and the size of the overall low-cost gym segment, I don't consider these shares to be overvalued.
Anecdotally, I happen to be a member of a luxury gym chain (it's one of the select few things that I like to spend on). It's mostly empty throughout the day, which is great, but I've been wondering why. I've concluded that its business model must be to sign up people who don't bother coming in!
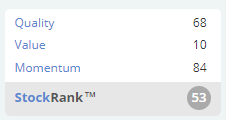
Anyway, here's GYM's StockRank. I'd certainly be interested to buy it at lower levels. For now, I retain a watching brief.
Beeks Financial Cloud (LON:BKS)
- Share price: 84p (+8%)
- No. of shares: 50 million
- Market cap: £42 million
This is still a relatively new stock. If offers facilities for low-latency financial trading, through placing its servers in close to proximity to exchanges around the world. It caters to banks, brokers, hedge funds and private individuals.
Underlying PBT has shot up to £1.2 million for FY 2018 (ending June), excluding IPO costs and amortisation.
As has been mentioned already in the comment thread, the current market cap doesn't enjoy much balance sheet support, as net assets amount to less than £5 million. Tangible net assets are about £4 million.
So this is all about earnings. Beeks has a KPI called "Annualised Committed Monthly Recurring Revenue", which is basically the run rate of revenues, and this is up 47% to £6.9 million.
These are back of the envelope calculations but if revenue was say £8 million in 2019, at a fixed gross margin and with other expenses fixed too, then I estimate that underlying PBT would improve to somewhere in the region of £2.5 million.
(The existing Stocko consensus forecast for FY 2019 revenues is £8.6 million, which is looking a bit optimistic after FY 2018 revenues missed consensus by £0.6 million).
The point is that the forward earnings multiple is not extreme when you look at it this way, and the company is very confident of "continued momentum" and "strong market drivers". It's riding a growth wave that looks set to continue, basically.
I'm not personally tempted to participate, because I feel unable to predict whether this service will be relevant many years from now. The pace of change in automated trading is simply relentless, and I can't imagine what the competitive landscape will look like as communications technologies continue to improve. I'll probably miss out an exciting investment, as a result. But I wish the company every success.
Paul Scott's view (Paul owns BKS shares).
This is a very interesting company, which floated on AIM in Nov 2017. I'm generally very sceptical about new issues, but made an exception in this case, after a friend recommended that I read the Admission Document. Also, I was very impressed with the CEO's presentation at Mello Derby, and increased my position size from small to medium shortly afterwards.
Results today look terrific to me.
- Revenue growth (organic) of 41% - this is a little below forecast, but still highly impressive
- Big rise in gross margin, resulting in gross profit up 90% on last year
- Underlying EPS of 2.27p, giving a PER of just under 38. I've checked the way underlying EPS is calculated, in note 23, and am happy with it. The main adjustment is for one-off IPO-related costs, which is perfectly reasonable to exclude from the number used to value the business
- Maiden dividend of 0.3p, in line with forecast
- Crypto-currency markets may be providing a short term boost to performance. Although the narrative says that most revenues are derived from forex and futures markets
- Possible acquisitions have been assessed, but none has met the company's investment criteria. It sounds as if there might be future acquisitions, which would probably result in some dilution. The CEO's dominant shareholding should however protect us from anything reckless or too dilutive being done
- Balance sheet is small, but strong. No issues there
- Modest Director remuneration, as is often the case with Scottish smaller companies
- Only 821k share options outstanding, which is minimal compared with 50.0m existing shares in issue - good, as it means little dilution in future
- Note that there is a minimal tax charge, so forecasts need to factor in a higher future tax charge. So this flatters EPS at this stage
Paul's Opinion - this is exactly the type of company that I search for, and want to invest in. It's growing strongly, organically. Not only are sales rising, but gross margins are too, giving fantastic operational leverage. The outlook comments are confident.
How to value it? Personally, I see this as an exceptionally good growth company, hence in a bull market, I'm prepared to push the boat out on valuation. This can be risky, if anything goes wrong, but plenty of lowly valued companies also drop heavily on disappointments, and are arguably more likely to disappoint in the first place.
For me, I think this company deserves a premium PER of 50, which based on EPS forecast of 3.6p for the current year, ending 06/2019, suggests a price target of 180p - about double the current share price. Some readers may recoil at paying a PER of 50. However, given that the company has just reported such strong figures, I think it's justified.
There's an update note from a good quality broker today on Research Tree. I think perhaps some investors baulked at the revenue miss, and sold early on today. However, in my view, the more important numbers are gross profit and EPS, which came in ahead of forecast. Indeed the main broker has today increased its 06/2019 EPS forecast.
This share is a reminder that when picking small caps, it's really all about;
- Backing top quality management,
- with a great business model,
- going for a lucrative & perhaps overlooked niche.
Over my sabbatical this summer, I've had lots of thinking time, which has helped me focus more on the above simple 3 points. Short term valuation is less important than the above factors, in my view. So these days I'm more inclined to pass on almost all share ideas. However, for the shares that do meet my rigorous investment criteria, I tend to concentrate my funds into them more heavily than in the past. So when funds permit (am fully invested at present), then I'll be looking to buy the dips with Beeks. As always, this is just my personal opinion, which is not a substitute for readers doing your own research, because sometimes I will be wrong!
IQE (LON:IQE)
- Share price: 102.5p (-1%)
- No. of shares: 761 million
- Market cap: £780 million
Graham here again, taking a look at this heavily-shorted manufacturer of semiconductor wafers. Disclosed short positions persist at 11% of shares outstanding.
(I don't mention this because short-sellers are necessarily correct, but because it means there must be some good arguments in favour of shorting it.)
Results:
- revenue from wafers up 5.4%. Held back by currency headwind of c. 10%.
- gross profit margin down by 1.4 percentage points.
- adjusted PBT down 21% to £7.6 million (after £1 million of adjustments).
- the company suffers a tax charge instead of receiving a tax credit, so reported net income is down 50% to £4.2 million.
Balance sheet - net cash of £40.6 million. It raised almost £100 million in November.
Operations - 7 new reactors so far this year in Newport. Another 3 scheduled during the rest of H2.
CEO comment. The company also provides a second version of adjusted PBT, with another £3.5 million of adjusted expenses, including a currency headwind of £2 million. If you're happy to look at it that way, adjusted PBT is up.
In relation to the additional expenses taken on during the period, the CEO says:
Although the costs of these investments have impacted first half profitability, we are confident they will be pivotal in delivering strong increases in revenue, margin expansion and profitability as 3D sensing is widely adopted in global mobile platforms and other large volume applications.”
Joint ventures
IQE's Singapore and Cardiff joint ventures were the subject of bear speculation earlier this year. The final footnote of today's report details the related party transactions which took place over the last six months with them.
Once again, I don't see any smoking gun as far as these JVs are concerned. The movement in cash is a bit circular (IQE making purchases from the Cardiff JV and also recharging costs to it), but you'd need some very detailed, specific info to prove that something untoward was going on.
My view
I'm impressed by the 55% market share the company claims to have in the wireless market. It's now moving to produce for Android manufacturers - encouraging. It says it's positioned strongly for 3D sensing applications - also very interesting.
Regular readers will know that I love to see big ROCE/ROE numbers. They are associated with growth and free cash flow (because you need to reinvest less of your earnings to get the same result).
IQE has a mixed track record on this front, for reasons we've discussed before (it's in a heavy industry and has had to do a lot of capex spending).
Maybe 3D sensing will be the opportunity that sparks improved returns for shareholders? I'm neutral.
Johnston Press (LON:JPR)
- Share price: 4.1p (-20%)
- No. of shares: 106 million
- Market cap: £4 million
A footnote of a different kind, as JPR looks set to disappear before too long.
Outstanding borrowings of £220 million junk bonds are coming due on 1 June 2019.
There has been no agreement as of yet about what to do with this problem.
Bondholders don't seem terribly interested in a refinancing, and if they want the equity then it is surely theirs for the taking.
JPR shares are equivalent to out-of-the-money call options. In other words, they are likely to expire worthless.
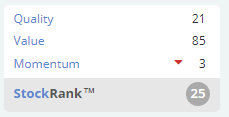
It's reassuring to see that despite superficial value, the StockRanks can detect the danger and classify this as a Value Trap.
Richoux (LON:RIC)
- Share price: 6p (-14%)
- No. of shares: 125 million (before fundraising)
- Market cap: £7.5 million
Subscription to raise approximately £1 million
Richoux Group plc, the owner and operator of 18 restaurants under the Richoux, Villagio, Friendly Phil's, Zintino and The Broadwick brands, today provides a trading update for the 26-week period ended 1 July 2018
This is a small, unprofitable restaurant chain.
H1 revenues will be flat and losses will reduce. Times remain tough.
There is an equity raise for £1.1 million at 6p. A discount to the prevailing share price was understandable in the circumstances.
It's also attempting to conclude a lease sale for £1.35 million in Central London.
In combination with the fundraise, it sounds like the immediate financial strain has been dealt with.
Worth noting that the CEO and his concert party (family members) are subscribing for 6 million of the 18 million new shares, taking their aggregate holding to 29.5%.
Non-executive directors are also subscribing for 7 million of the new shares.
Insiders are invested and are buying - maybe prospects aren't as bad as they first appear?
All done for today. Thanks for dropping by!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
I bought into Beeks because I think the CEO was everything that I look for. An understated Glaswegian with a mean eye; a numerate and financially savvy version of Gordon Brown. I thought his presentation was excellent.
Jim Slater used to say that there is only one job for a share price and that is that it has to go up.
Go for it beeks!
My thoughts and questions on IQE (LON:IQE).
Its clear that the company is spending alot on Capex, whilst some are happy with this I can see why other's wouldn't be, each to their own I suppose. I have to agree with Graham Fords comment about the interpretation of spending heavily on capex to fuel its growth. There is obviously a space the company is growing into, and I find it very re assuring that the company currently doesn't require the banks fuel this, as there was plenty of take up at the last offering. I would also much rather invest in this space than a highly acquisitive company that has ran out of room to grow.
Although this Half year report doesn't look exciting I am happy to see past this, as the top line growth is still very good. Wireless up 11%, Photonics 30% and infrared 11%.
I intrigued by the comment:
Revenue at constant currency from the largest photonics customer was flat H1 2018 on H1 2017 as inventory from the very successful and aggressive first mass market ramp of VCSEL epiwafers in H2 2017 was consumed in the supply chain. Other photonics customers were up 40% H1 2018 on H1 2017 in constant currency demonstrating the breadth and depth of photonics engagements.
So if this was flat due to their largest customer consuming the inventory levels, would this produce an uplift in revenue for the full year as they have to start producing them again?
Intangible's. This often causes a divide amongst investors, but If there is anyone with a greater knowledge of IQE's industry as mine is very limited. I would be really keen to understand about their intangible value. Its quite a significant figure on their balance sheet at £116m, and I understand that most investors would write this off from the valuation from a typical stock.
However is this a typical stock given its in the technology sector? As there is proberlya lot of intellectual property to be considered here?
Inventory. There is another comment 'Transition the company from leading supplier of semiconductor wafers to a global leader in advanced materials'
With the pace of their technology growing so fast, is there a greater chance their inventory could be out of date very quickly and deemed worthless?
Also for those who have the patience to learn about a small part about their GaN technology. this is worth a read. Even a shift in improving the battery life for the mobile phone market could be enormous. Yet not a great deal is mentioned in their statements about it.
https://epc-co.com/epc/Gallium...
Reagards
Sean
Tongue in check (slightly) - If IQE (LON:IQE) was worth double it is now wouldn't Apple have just bought it - GYM (LON:GYM) - Perhaps they will start charging more for a big gym bag than a back-pack :) - Sorry !
“If IQE (LON:IQE) was worth double it is now wouldn't Apple have just bought it”
Er no, Matylda. Tongue-in-cheek, that would be like a Tesla buying a tyre manufacturer. I.e. not their business.
Each to their own
Interesting views on GYM (LON:GYM) and IQE (LON:IQE).
To me GYM are another example of a retail roll out. Having built a business model that works they were ploughing the cash generated from existing sites into new sites. When the expansion starts to slow the business will throw off impressive amounts of profits and cash. The slight deviation from this is that they have made a couple of acquisitions from weaker competitors that has given them a somewhat different set of numbers this time round. Overall this is very positive. I notice Graham referred to them as the Ryanair of gyms. Perhaps that was because one of the purchases was easyGym. However, I think they are aiming to provide their customers with better customer service than Mr O’Leary. Operating a no contract model they are well aware that they cannot afford to give poor customer service lest their customers walk away. It looks like the low cost part of the gym market is moving towards being dominated by these guys and Pure-gym. I continue to hold.
IQE is a funny beast. I can’t help feeling that if they were spending large sums on marketing, like some internet retailers, rather than on Capex, they would get less stick. To me this is not a story of continuous capex being a continuing drain on cash and profits. Rather it is a spurt in capex to service growth in exciting new markets. In time the capex will moderate and profitability will be good. It should be noted that they have previously stated a payback of around 18 months for each new tool/MOCVD machine. So nothing much wrong with that. Equally their steady increase in installation of these machines shows they are not putting in new kit too far ahead of sales coming in. The projected growth rates in their business buried further down the statement look very good and the confirmation that their wafers for VCSELs for facial recognition etc in Android phone is commencing is great news. Previously people were fixated on the VCSEL sales all being dominated by the iPhone X. Well with Android OEMs now coming on board too that’s no longer a concern.
I ask myself. Do I want a stake in the VCSEL market for facial recognition, augmented reality, LiDAR for autonomous vehicles and fibre optic communications? Do I want a stake in 5G communications? These are great growth markets that IQE are tapping into and the answer is yes I do. IQE have other irons in the fire too. So, although the share price is a roller coaster, I’m hanging on for the longer term and will continue to hold.
My primary concern with IQE (LON:IQE) is the poor ROC which capital is being deployed at. If the company doesn't improve its ROC beyond its cost of capital in the future, then growth will not add any value and the company will be worth substantially less than what it's currently valued at by the market.
Hi Graham,
Very restrained comments on IQE (LON:IQE) I thought - I hope you don't feel brow beaten; I know I had a bit of a moan at you in the past for being IMHO insufficiently questioning of one of the bear notes (which I remain of the view was mischievous) but I certainly wouldn't want you to 'hold back' on your views, they are always valuable to me.
Anyway, it's certainly reasonable to comment on the continuing high level of short interest here, it is certainly food for thought for those considering an investment - personally I've taken the opposite view to significant short positions in the past and come out winning so I don't regard them more as a trigger to review the investment case rather than a red flag; on the other hand I also don't subscribe to the view that they create a pool of forced future buyers that create a "coiled spring" - people like to remember the VW Porsche short squeeze, but there are many more cases where short positions exit calmly and quietly even when wrong.
Anyways, I think the results were fairly well signalled in earlier trading statements so there's not a really an awful amount to discuss at this point. Although there are two points that I would highlight :
Those questions aside, operationally there is no real news here - I remain "long" on the basis that the earnings trajectory looks to be absolutely still on track, but I accept that even if I am correct, there is likely to be a much smarter time to buy once more compelling evidence is in (hence why I reduced my position earlier in the year). As an investment IQE is hard work and with the help of Stockopedia I'm very much warming to the idea that there are many "easier" investments to consider, so if I had not already done my homework, I would probably walk on by and ignore IQE completely.
Hi Gromley, yes you did give me a bit of a hard time previously on IQE (LON:IQE). Thanks for acknowledging! But you're entitled to do that, it goes with the territory of writing publicly about things.
I've never had a strong opinion on the stock, as you probably know. The short attack was interesting for the drama it created and for the puzzle as to whether they had found anything conclusive. I made it clear that I didn't think they had found any damning evidence. In the end, it was a damp squib.
Good luck with IQE. I'm happy on the sidelines. G
Ah Graham your recall of the event, tells me clearly that I ought to go further than an acknowledgement and give a more direct apology. Whilst I was critical of what you wrote, I did not intend personal criticism of you, although in retrospect I can understand that my wording was poor.
So I apologise unreservedly if I caused offence and I would reiterate the point that in no way would I want you to hold back on your ever valuable views.
At the risk though of appearing churlish, I have to report on something I discovered on searching to remind myself of the chain of events and I cannot therefore recant the substance of my criticism
5-Feb-18 - You reported on a note on IQE by Matthew Earl, who you described as a "respected analyst" - it was the bolded word that I objected to, particularly given that I had evidence that his report contained a material factual error that would be very hard to explain away as an error.
But there is more
7-Feb-18 "Muddy Waters" declared a short position in IQE of 0.93%
8-feb-18 Muddy Waters short position reduced to 0.68%
9-feb-18 Muddy Waters publish their short dossier - mostly rehashing what Matther Earl had written a few days ago.
15-Feb-18 Muddy Waters short position reduced to 0.48%
This one from memory as "shorttracker" does not make it easier to track when positions are closed, but as far as I recall, Muddy Waters closed out the short on 16th or 17th of feb.
What I now discover from looking back is that there is an IQE bear note on the Muddy Waters website dated 2-feb-18 (I extensively looked at the MW website at the time and it was not there then - this is probably provable) authored by Matthew Earl.
As far as I know, there was no disclosure at the time (or since) of any links between Matthew Earl and Carson Block (Muddy Waters).
In intend no direct comment on the character of either of these two individuals, everyone needs to form their own decisions, but if either of these two "gentlemen" ask me the time I will definitely be checking that I still have my wristwatch before I move on.
Sorry to have diverted massively from what was a heat-felt apology to Graham which I'm happy to reiterate.
The history of the Muddy Waters short positions on IQE can be seen here:
https://shorttracker.co.uk/man...
Your memory is pretty accurate - the only difference is that they reduced to 0.48% on 9th Feb, the day after they published their short thesis.
Where are you seeing the 2nd Feb report on the Muddy Waters website? the only relevant page I can see is the 8th Feb one:
http://www.muddywatersresearch...
which includes this statement:
Is it just me or does Graham vs. Paul on Beeks Financial Cloud (LON:BKS) remind anyone else of Eeyore and Tigger?
I feel inclined to the Tiggerish view on this one, but it's great to see both cases presented.
Graham
Being empty during the day is a problem not confined to GYM (LON:GYM) or your gym. That's why a lot of (still) local authority/outsourced gyms are dual use with school use during the day. The only use during the day is shift workers and the retired. Speaking for the retired most gyms are too expensive, which why I use Age UK. Gyms use to sign up the mass in January and then see the money come in for the year even is the client did not. That's why most gyms have listened to their members and now work on a rolling monthly dd and membership. Having tried to solve the absentee daytime membership our only solution was to elongate the opening day albeit at extra staff costs.
Just one of those facts of life
Steve
Re GYM (LON:GYM). Just as an FYI, the other tool gyms use is the Cinema/Budget Airline model of charging less to use the gym during the day, but more for early evening when most employed people want to use it. Smart differential pricing IMO since for a fixed cost business marginal revenue flows directly to profit
Hi Steve, re: GYM (LON:GYM) many thanks for the input and the points made regarding the lack of daytime use.
IQE....I am short of this from 124p. So I am interested in comments. Personally I see little of value here to shareholders. Directors maybe. Each to their own.
Re IQE (LON:IQE) - it dawned on me, some time ago, that I really don't understand this sector, and hence have no competitive edge, in terms of buying/selling the shares. Hence I've put my profits last year from IQE shares down to little more than good luck, and responding in a timely fashion to a positive trading update at the time.
These days, I can no longer access Peel Hunt research, thanks to the idiocy of MiFID II. I bought IQE mainly because of the bullish PH forecasts. Now that has gone, then the stock doesn't interest me at all.
Also, I think some of the bearish commentary was very useful in helping me change my mind, and selling at higher prices than today - e.g. Tom Winnifrith pointing out that other companies operate in the same space. So even if IQE has a competitive advantage in the shorter term, then this is likely to be eroded over time. It's also too capex-hungry for my liking.
Good luck to holders, but IQE is not one that I'll be revisiting, for the above reasons.
Regards, Paul.
P.S. I like the way Graham is more willing to say, "I'm neutral" on a share, than me. Also, I find it very interesting to read about how other investors that I respect have responded to results or trading updates. It's amazing how different the interpretations can be from various people.
Hear what you are saying Paul.
Just on the issue of competition there are very few companies operating at significant scale in the compound semiconductor wafer market for VCSELs with the level of IP that IQE (LON:IQE) have. Hence their comment about their market share. Agree there may be reasons to stay away from this one but the level of competition isn’t one of them. I don’t read TW so cannot comment on other matters he may have raised but I think he has misunderstood about the competition.
Beeks Financial Cloud (LON:BKS), why does my broker class it as a Complex Investment? I had to complete a questionnaire before I could deal.
I had the same thing with HL when I purchased earlier this year. just had to click continue a few times and was able to purchase.
I think its mainly because its involved with crypto, so just more of a high risk warning message I think.
But im a holder for the long run, very impressive strong results today.
Absurd. No problem trading it with IG.
This section written by Paul Scott
Beeks Financial Cloud (LON:BKS)
Share price: 85.5p (up 9.6% todat, at 12:53)
No. shares: 50.0m
Market cap: £42.8m
(at the time of writing, Paul Scott holds a long position in this share)
Final Results
This is a very interesting company, which floated on AIM in Nov 2017. I'm generally very sceptical about new issues, but made an exception in this case, after a friend recommended that I read the Admission Document. Also, I was very impressed with the CEO's presentation at Mello Derby, and increased my position size from small to medium shortly afterwards.
Results today look terrific to me.
My (Paul Scott) opinion - this is exactly the type of company that I search for, and want to invest in. It's growing strongly, organically. Not only are sales rising, but gross margins are too, giving fantastic operational leverage. The outlook comments are confident.
How to value it? Personally, I see this as an exceptionally good growth company, hence in a bull market, I'm prepared to push the boat out on valuation. This can be risky, if anything goes wrong, but plenty of lowly valued companies also drop heavily on disappointments, and are arguably more likely to disappoint in the first place.
For me, I think this company deserves a premium PER of 50, which based on EPS forecast of 3.6p for the current year, ending 06/2019, suggests a price target of 180p - about double the current share price. Some readers may recoil at paying a PER of 50. However, given that the company has just reported such strong figures, I think it's justified.
There's an update note from a good quality broker today on Research Tree. I think perhaps some investors baulked at the revenue miss, and sold early on today. However, in my view, the more important numbers are gross profit and EPS, which came in ahead of forecast. Indeed the main broker has today increased its 06/2019 EPS forecast.
This share is a reminder that when picking small caps, it's really all about;
Over my sabbatical this summer, I've had lots of thinking time, which has helped me focus more on the above simple 3 points. Short term valuation is less important than the above factors, in my view. So these days I'm more inclined to pass on almost all share ideas. However, for the shares that do meet my rigorous investment criteria, I tend to concentrate my funds into more heavily than in the past. So when funds permit (am fully invested at present), then I'll be looking to buy the dips with Beeks. As always, this is just my personal opinion, which is not a substitute for readers doing your own research, because sometimes I will be wrong!
Great analysis on Beeks Financial Cloud (LON:BKS) by Paul and Graham! It's hard to find such in-depth analysis showing two different perspectives.
Many thanks!
Hi Paul,
Thanks for such a great write up on Beeks Financial Cloud (LON:BKS), I topped up today off the back of the positive results with the hope that over the next few years it will continue to grow at a decent clip given the volatility in the markets should suit their client base.
Their capex over the last couple of years has been consistently more than their depreciation charge. So I guess their investing a lot for future growth, I think in their Mello presentation they the CEO mentioned that for each £1M they spend on infrastructure they get an added £3M capacity of extra turnover.
On an unrelated note, seems like a lot of buying up of Sosandar (LON:SOS) they're up over 30% in the last week off the back of no news, do you have a take on this?
Re IQE (LON:IQE) , interesting non-story that I suspect will find its own thread. But agree with earlier comments that this is a mixed report.
Short term result is not too clever but long term story remains intact. I bought 2 years ago expecting to hold for 5 (or be bought out on the way!) and still feel happy at the (high) risk/reward ratio on this basis. The demand is coming from an ever wider base, the technology and market position is still strong and the CAPEX to supply a much bigger business is nearly in place. Interpretation of results depends if you are a trader or investor.
...But some worry at the edges! Results always always reads like (the same) PR story and I'm not impressed by a .pdf on website that cannot even align columns of figures correctly. New CFO (following accidental death of former CFO) brings an opportunity to step up. I would also not mind some further changes/additions to the board eg a US or Asian heaviweight to add some more gravitas and reflect a maturing and expanded business. Need to convert story into cash/results over next 18 months.
Your point, Zipmanpeter, about worrying about whether IQE (LON:IQE) are ever going to make a decent profit is one with which I concur. I can see the potential for large profits at IQE (LON:IQE), but also the temptation for them to continue ploughing virtually all their profits into director remunerations and further infrastructure investments ad infinitum. Rewarding their share holders does not seem to be a priority for them either now or in the future.
At this point as a shareholder I want IQE (LON:IQE) to do exactly what it is doing...ie going flat out to capitalise on their leadership position by continuing targeted Capex , broadening their customer base, commercialising their wider IP assets into new high growth areas..and as a result I expect them to enjoy rapid growth for years to come.
The share price willl progressively/ultimately reflect the cash flow from all these investments taking place
I’m also happy to have a share in an investment that is so manifestly benefiting from trends that are here/now & not reliant on hypothetical trends that may or may not occur in reality.
Couldn't agree more about columns not aligning with the figures, my ocd levels go through the roof here. Glad its not just me!
Another vote for IQE please. Cap ex seems to be their achilles heal with details emerging of more spend in Mass and Taiwan on top of Newport. Positive cash generation seems to be as far away as ever which I guess is not a surprise given the industry it operates in. Any comments on the large increase in creditors in H1 would be appreciated.
Many thanks
@rmillaree - Post #16
I also have/had the problem of selling too soon - Not running winners. Also holding onto the fallers in the hope that they'll recover. Both of these I'm getting better at doing (I think!). I do now have a 'watchlist folio' of those I've sold and at what price - It's pleasant to see a majority of these 'dregs' still falling.
With GYM (LON:GYM), I'll most probably put a manual stop-loss alert in for if it drops down to a level where I'm just 50% up, then evaluate and possibly sell half my holding to lock in some profit, which also provides some cash in reserve for re-buying if it drops much lower.
Beeks Financial Cloud (LON:BKS)
I can't remember which informed member of this community put me onto Beeks Financial Cloud (LON:BKS) following Mello which, I alas couldn't attend, but thank you!
Results are great and the business model / demand for service is such that there should be no impediment to strong double digit growth for several years to come. Having direct pipes into exchanges is a big impediment to competition if done well and resilient. Have a feeling this will ultimately get taken out by an a financial infrastructure player.
Really like this. Not cheap on a trailing eps basis but given growth profile it looks pretty reasonable value 12 months out.
James Fisher & Sons
Turnover up 11%
Operating Profit up at £24.5m
Margin up
Look at the 10 year chart . This has been a very profitable long term hold for me and looks like it is still going to be core holding going forward
Morning Graham,
Another request for Beeks Financial Cloud (LON:BKS) analysis, please Sir!
Thanks,
IG
Disclosure - I hold shares in £BKS
IQE (LON:IQE) - Cash down £5m to £40m. No growth in photonics due to Apple supply chain overstuffing. H2 weighting.
On the plus side: Potential currency upside in FY / next year, technology adopted by Android as well as Apple, restates 40-60% CAGR over 3-5 years in photonics. PE of 22 OK if it grows and ever starts making cash.
I have a small speculative holding. I suspect I should be selling and buying back in a couple of months.
GYM (LON:GYM) if you would please Graham. One that's been covered before on the SCVR.
As a taster (as I'm still going through statement):
Revenue of £58.3 million, an increase of 36.1%
Group Adjusted EBITDA of £17.5 million, an increase of 28.0%
Adjusted profit before tax of £7.0 million, up 8.4%
Interim dividend of 0.35 pence per share declared, up 16.7%
Group Operating Cash Flow £16,421m (+26.5%)
Total number of gyms 134 (+41.1%)
But:
Statutory profit before tax decreased by 14.4% to £5.1 million (H1 2017: £5.9 million), due to increase in exceptional costs to £1.0 million
(Even adding back the exceptionals would have only put the profit (£6.1m) slightly up on the prior HY.)
Another But:
Proforma members (including easyGym sites) of 720,000 (June 2017: 508,000) +41.7%
(Quite a rise in members, although don't like the 'Proforma' part until I find out what it means in this context - Average members have increased 34.1%)
Positive forward statement, although seems to be alluding to the dreaded 'H2 will be better' speak.
I've held for nearly a year, from 209p, so the current 318p is a reasonable success, and GYM (LON:GYM) is now my 3rd largest holding.
Hello DJPC
Ref GYM (LON:GYM)
This company do seem to have a decent handle on the numbers and financials so i wouldn't have any particular concerns with these results unless there is broker downgrades on the back of these numbers, which i would have thought would be unlikely.
Having said that i have now sold out of this company purely due to the share price appreciation that has been pretty decent over the time i have held. It's a bit of a shame to sell up as they seem to be delivering as a business with a simple model they should be able to replicate and show improved efficiencies as they expand. I like to sell out too soon does I.
Good morning Graham, this is another request for Beeks Financial Cloud (LON:BKS) if you would be so kind.
Seeing Machines (LON:SEE) - Not a proper RNS, but interesting to see again the focus on the value of data. Unlike intellectual property created by workers of the company, this data is created by its customers. It is similar to the argument I was making the other day about Wey Education (LON:WEY) having (or at least, should have) data on every question asked by every student as well as the answers given by the teacher and of course ownership of the delivered lesson.
Unless traded, these types of asset are never likely to appear on a balance sheet, but they have real value to shareholders.
Here's my take on Beeks Financial Cloud (LON:BKS) . Obviously this is somewhat rushed!
Some truly impressive growth figures - +41% revenue and +90% gross profit with a strong outlook. Margins are high, have risen and should rise further e.g. as finance costs are eliminated.
I'm not happy with the prominence given to EBITDA given the heavy depreciation of IT Hardware [1] and am ignoring those figures. I'm fine with the underlying figures which show EPS of 2.27p (2.20p diluted), a historic PE of 35.
I don't have access to brokers' forecasts, but Stockopedia is currently showing a 12 month rolling PE of 23.3 which implies 66% profit growth for next year. That seems achievable.
The concentration of customers is higher than I would like and continues to worsen. If they set their margins too high it would be economic for top customers to set up hosting / connectivity themselves. One of the key economic moats and hidden value of Beek's is the time to set up such arrangements, but it can be done.
Since there is very little valuation support from net assets and the latent value of the connectivity arrangements with exchanges are key.
Cashflow looks poor mostly due to a decrease in payables. Probably they were on extended payment terms with some suppliers prior to raising cash at the float. Hopefully this is a one cash-flow hit that will also facilitate better purchase pricing and still higher margins in future. Receivables have increased, but this is mostly in proportion to turnover.
I suspect the small dividend has been declared mostly for benefit of the founder - and he certainly deserves it!
No mention of China - I thought they were expanding there?
Focus will now start shifting to FY2010 where, at current growth rates, Beeks will start to look cheap for a growth share on an P/E basis.
I hold and have a small buy order in.
---
[1] Although hardware innovation / cost reductions and therefore depreciation had slowed over the last few years, arguably due to a lack of competition, there are strong indications that this has changed in the last 6 months with the release of new AMD server chips. I don't think the long tail in the value you often see with equipment exists (any longer) in IT as it is cheaper to replace with new energy efficient designs than to run old hardware.
Excellent analysis Leoleo73. Thanks for sharing. I'm a bit puzzled on your 66% profit growth number. I can't seem to solve for this (probably being stupid) but could you share the working? Thanks.
Re: My Beeks Financial Cloud (LON:BKS) 66% profit growth estimate. This is how I should have calculated it:
Stockopedia showed a forecast rolling PE of 23.3 this morning. The Stockopedia help explains:
Given the time of year, this should be the same or close to the FY2 i.e. FY2019 forecast.
This implies FY2019 estimated earnings of P / P / E = 80p / 23.3 = 3.43p
FY2018 earnings: 2.27p
3.43p / 2.27p = 1.51 so a 51% increase.
I can't be certain, but I think I divided the wrong way in my haste. It was only supposed to be a sanity check against the forecast PE. BTW, the current FY2019 estimate is higher than 3.43p.
Thanks for clarifying. That is what I got (c51%) but presumed there was something I had missed that was obvious. Cheers. Paul
Also saw today's RNS announcing the intention of Aston Martin (luxury car maker) to float, as well as reporting 8% YoY increase in revenues and 14% increase in EBITDA. Sounds like an interesting growth opportunity, would be interested in your thoughts Graham.
I'm pretty sure any company looking to float will employ some accounting trickery to make it look like they are suddenly growing much faster than reality.
bwakem,
Blanket statements don't seem to be popular here :)
I'm sure there are companies that used accounting trickery around the time of flotation, but I can't think of any off hand.
What does seem quite common is:
a) companies who have wanted to float for a while waiting until they have a good year before going ahead. That year might then turn out to have been a one-off.
b) companies who, after deciding the float, run their business hard in order to produce the best figures and highest flotation valuation. This can be unsustainable and/or short-termism can cause problems after flotation.
c) flotations which are more focused on selling the previous owner's stake rather than ensuring they have enough working / investment capital.
My morning smallcap tweet: Toople topple turning point?
Toople (LON:TOOP), Richoux (LON:RIC), Johnston Press (LON:JPR), Integumen (LON:SKIN)
Toople (TOOP) A 'major' new wholesale telephony and superfast broadband contract with a well-known wholesaler worth at least £3.5m over 3 years. That should reverse a little of the 98% loss since listing 2 years ago.
Richoux Group (RIC) Tiny restaurant chain suffering: "continued pressure on trading during the period, with further impact from temporary restaurant closures due to conversion or refurbishment." Guides rev flat YoY. Fundraise at 6p, a 14% discount.
Johnston Press (JPR) The i paper is the only bright spot in H1 with adjusted EBITDA from that paper £6m up 61%. Adj ad rev(cont) down 15.0%. Group rev down 10%, EPS 3.6 (-5.4). Still trying to refinance or restructure the huge debt but no decisions have been made nor agreements reached.
Integumen (SKIN) H1 rev £149k (£124k). Pretax -£1.5m (-£1.4m). Sales and marketing efforts of Visible Youth failed to meet expectations. TSPro sales forecasts [eh?] did not meet the expectations of the Board. Rejected offer from director for the skin care businesses. He has resigned to avoid the conflict of interest. Talks on other potential offers for one or more of the skin care assets.
Morning!
Seeing Machines (LON:SEE) 's driver monitoring systems have covered 1million km, not material but for the AI data it's all good stuff, dear. I hold.
Richoux (LON:RIC) MIGHT be selling a London lease for £1.3odd million, are definitely doing a keep the lights on placing at 6p. Troubles in the dining sector are not over.
IQE (LON:IQE) HY results - on the face of it disastrous with profits halved yoy but read further, and it's not AS bad - they now have 90% of the VCSEL market, 'Currency headwind [of 10%], accelerated customer qualification programs and Newport Foundry pre-production costs results in drag on H1 2018 profits of approximately £3.5m. Excluding these factors, Profit Before Tax would have increased by 14.4% to £11.1m (H1 2017: £9.7m).. But perhaps I'm looking on the bright side because I hold. Paul will be tutting and very glad he sold near peaks... your views would be appreciated! Cheers joules
Re: IQE (LON:IQE): Even 14.4% doesn't sound that impressive. Are IQE going to end up perpetually getting squeezed on their margins, to the extent that they never deliver really decent growth? I would be interested in the bull view, as I know that IQE (LON:IQE) are not a one trick pony and that Apple and phones are by no means their only customer and potential application area.
IQE (LON:IQE)
results more or less exactly as flagged and expected. nothing to concern me here.
H1 was characterised by a big investment for 2019 onwards demand for photonics and this was well known/publicised. Created a drag on margins and profits. Growth always likely to be low double digits as H2 of 2017 was the first major ramp up - i.e. Apples iPhone X and subsequent inventory build. Also, upfront spend on new customers.
H2 should be much bigger growth and they are flagging results to be as expected as volume shifts gear. Note they also flagged that this has started to happen as expected. Again volume growth profile very consistent with iPhone sales patterns and new iPhone models.
Other photonics customers grew 40% - this is great longer term for anyone thinking they are just an apple supplier. Also note statement on Android customers.
"Since period end, qualification of a further two major supply chain partners has been completed, with initial production for Android OEMs now commenced."
H2 2018 and 2019 numbers are far more relevant in terms of volumes, profits and cashflow and so far company is flagging everything going to plan.
Hi Graham, Beeks Financial Cloud (LON:BKS) have released their results for Y/E 30/6/18 having recently IPO'd. Underlying ENITDA was £1.95m which grew by 258% and resulted in a margin of 35%.
My understanding of their service is they house their trading platform at exchanges. Clients then buy space to house their trading algorithms at BKS thereby resulting in lower latency i.e. Minimising the speed of where they reside to instructions being sent to the exchange.
It's not aimed at the large institutional traders but perhaps the smaller and medium sized businesses.
BKS have expanded their geographies and product offerings. It also has recurring revenues as it offers a subscription service.
I would appreciate your, and others, views on BKS.
Thanks
Good morning Graham, a request for Beeks Financial Cloud (LON:BKS) and IQE (LON:IQE) please.
Beeks Financial Cloud (LON:BKS) results look great, possibly a small miss on revenue but EPS above forecast and the announcement of a maiden dividend of 0.3p per share is positive. I hold.
IQE (LON:IQE) looks underwhelming but I'm sure someone else will disagree. I don't hold.
Cheers
Francis