Small Cap Value Report (Wed 3 Aug 2022) - VARE, GRG, GDWN, VCP, CREO

Good morning from Paul & Graham.
Agenda -
Paul's Section:
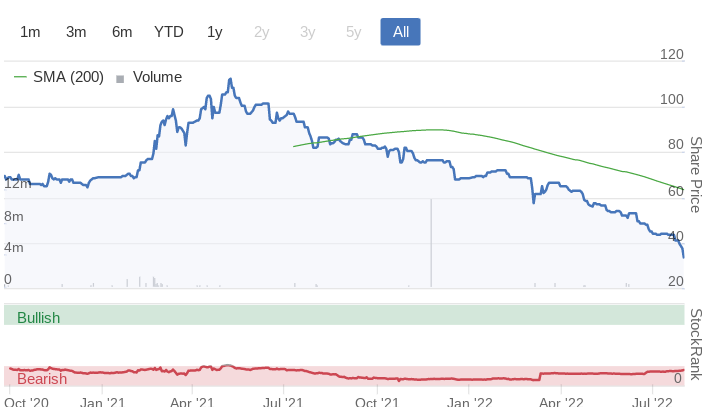
Various Eateries (LON:VARE) - this share slipped through the net in June, on a busy day, so I've gone back to look at its last interim results. With the share price in freefall, is there a value opportunity for shares in this expanding clubhouse style bar/restaurant group? The short version is no, not really. It's still unproven (loss-making to date), and almost all the cash pile has come from a related party loan. So I think there are better alternatives in the hospitality sector (e.g. Brighton Pier (LON:PIER) which reported positively last week), and Revolution Bars (LON:RBG) (I hold) which reported positively yesterday, and is similar market cap to VARE but much bigger, profitable and debt-free.
Greggs (LON:GRG) (£2.18bn at 2131p) [no section below] - not a small cap but… I had a quick look at interim results from this on the go food retailer yesterday. It’s a good business, and shares have lost a third of their (over-priced) peak 2021 value, and now look more sensibly priced (not cheap though). I’m mentioning it for read-across to other retail/hospitality shares. Sales shot up 27%, but profits were only flat against last year. This is due to “the re-introduction of business rates, increase in VAT and higher levels of cost inflation”. FY 12/2022 outlook is in line with expectations - which is EPS flat vs 2021. If one of the best operators can only achieve flat profitability against all these cost headwinds, and withdrawal of large Govt support, then what chance do lesser hospitality/retail businesses have? Hence I think it’s best to assume that profits remain under pressure for this sector for 2022 and 2023. Providing forecasts are set realistically modestly, that’s fine. But racy forecasts expecting big profit growth could be an accident waiting to happen. It’s like a minefield at the moment, we have to pick our way through very carefully.
Graham's Section:
Goodwin (LON:GDWN) (£213m) - this family business reports full-year results that show a small improvement over the prior year, but are held back by rising energy costs. In addition, the company’s mechanical division suffered from volatile energy and commodity prices (fortunately, the company was able to renegotiate contracts for this division). The outlook statement is unusually strong and is based on some exciting developments and contract wins in the mechanical division, along with strong momentum in the refractory division and energy hedges in place. There are lots of moving parts to consider, but my instincts are that the valuation here is on the low side - analysts, institutions and the City have no interest in this share.
Victoria (LON:VCP) (£379m) [no section below] - No news from Victoria today, but I thought it was worth mentioning that a short-seller has published a note on the company, claiming that two of Victoria’s acquisitions (one cost £25m, the other £17m) were dubious. Specifically, the note alleges that the two companies were already Victoria subsidiaries, and that the deals were structured so as to hide this fact from investors. It’s unclear why Victoria might have done this, but the possibilities are worrying. However, I’ve not verified any of these claims, and I expect that Victoria’s Chairman Geoff Wilding will be eager to respond to them and refute them. I’ve always found this company’s aggressive, leverage-driven growth to be unsettling; if I were a shareholder, I would now be anxiously awaiting Victoria’s response to these claims.
Creo Medical (LON:CREO) (£140m) (+3%) [no section below] - this medical device company gives an H1 update: revenues +10% versus H2 last year, gross margins are up, and costs are down. However, this is an early-stage company and will report a meaningful loss at the EBITDA level, albeit a smaller loss than the previous year. Last year, the company used up nearly £34m in cash across its operating and investing activities, and finished the year with £43.5m of cash at year-end. Quantitatively, this is extremely high-risk: the StockRank is only 3 (i.e. it’s a “Sucker Stock”), and it passes two of Stockopedia’s short-selling screens, one of which relates to bankruptcy risk.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Various Eateries (LON:VARE)
34p
Market cap £30m
This expanding chain of clubhouse style all-day, upscale bar/restaurants caught my eye when it floated, but was so obviously over-priced, that it has not as yet been of any interest to us here at the SCVR.
I last looked at it here in March 2022, on publication of FY 10/2021 results, and wasn’t impressed with the valuation at 57p per share. Although, given pandemic disruption, small scale, and lack of track record, it’s difficult to value. There seemed an excess premium for experienced management, and not enough substance to the valuation.
The price has been in freefall, along with a lot of the hospitality sector, which makes me wonder if the time might be right to take a fresh look? Are there bargains here? Nightcap (LON:NGHT) is another one which floated at too high a price, and has since come down a lot.
VARE put out interim results (26 wks to 3 April 2022) on 23 June, and I’ve been meaning to circle back to it ever since.
Here are my notes on H1 results -
Trading in line with FY 9/2022 expectations.
H1 revenues £17.8m
Adj EBITDA (IFRS 16 - i.e. the totally meaningless figure!) of £1.7m
Loss before tax of £(2.6)m.
Remember impact of omicron in this period, which won’t have helped, but there would have been support from Govt measures, e.g. business rates relief.
Balance sheet - not great, and a possibly concerning structure. NTAV is only £9.4m, bear in mind for a start up like this, the market cap is now over 3 times NTAV, which means two thirds of the market cap is hope, not fact as yet.
Freehold property is £2.3m, but most sites are leased. RoUA is £22.9m, less lease liabilities of £27.6m, so a deficit of £4.7m on the balance sheet re leases - suggesting that not all sites are properly profitable.
This is what concerns me - cash was £14.5m in early April 2022, which is being used to acquire & fit out new sites. Fine. But there’s a “connected party” borrowing of £12.6m. So net cash is hardly anything probably by now, as it’s rolling out new sites.
Therefore the exact terms of this loan are of crucial importance - e.g. if the loan could be called in, that could trigger administration, and allow the assets to be bought in a pre-pack for a lot less than they cost to build. I’m not for a moment suggesting that is likely, but it could be possible, depending on the terms of the related party loan. It’s probably fine, but this kind of thing absolutely has to be carefully checked before buying a share. It's not a good structure, in my view. I would prefer to see an expanding bars chain ideally debt-free, and using its own cash, not borrowing money for expansion from a connected party.
Broker forecasts - WH Ireland help us with forecasts. It’s all rather uninspiring. VARE is forecast to make a loss before tax of £(2.7)m this year FY 9/2022, and a reduced loss of £(1.8)m next year. That really concerns me. Why is the company rolling out a format, that has yet to prove it can make any money? Particularly when it’s spending a fortune on fitting out quite large sites, in premium locations? When they’re all spangly & new, is when they should be generating big profits. If they can’t make money collectively when brand new, they definitely won’t make money once all the fittings are starting to look worn out.
My opinion - we’ve not yet seen clean figures for post-pandemic trading yet. As things stand though, I cannot see any evidence that there’s a decent, profitable format here with VARE, that is worth rolling out. That could only be ascertained from seeing the management accounts, in particular site by site economics, which of course we’re not privy to.
That said, several industry insiders have told me that this is a golden era to be opening new sites in hospitality, because the deals available (rents, reverse premiums, rent-free periods) are once in a lifetime good. Plus there will be many more to come, when evictions begin in earnest following the end of the rent moratorium.
I’ll keep an open mind, and half an eye on VARE, to see how things progress. At the moment though, I cannot see any reason to pay more than NTAV, which is £9.4m, or less than a third of the current share price.
For further research, here’s the interims video presentation:
.
Graham’s Section:
Goodwin (LON:GDWN)
- Share price: 2770p (+11%)
- Market cap: £213m
This is an engineering group with a very long track record of dividends and profitability. The oldest company in the group, Goodwin Steel Castings, was incorporated back in 1883.
(Since I’m a “sleep sound” investor, this is something I look for - companies with an extremely long heritage. If they’ve lasted this long, there’s a decent chance that they will still be around when I retire!)
The company is still heavily owned by members of the Goodwin family, and is managed by them - something that is all too rare.
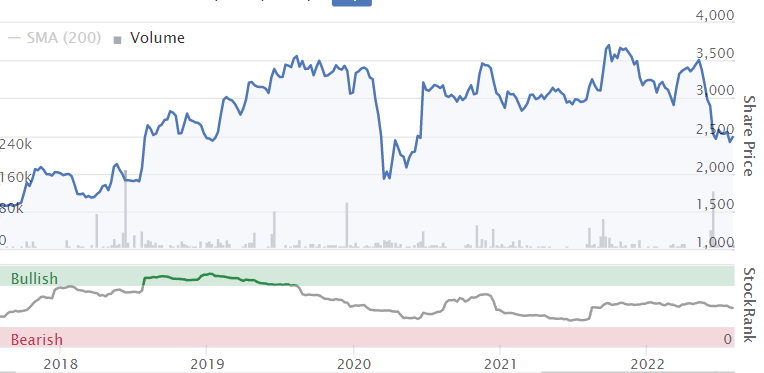
As for the share price performance, the past five years have been somewhat pedestrian.
The all-time high was reached all the way back in 2014 (during an oil and gas boom), and financial progress has slowed since then:
Let’s bring you up to speed with today’s results for FY April 2022:
- Revenue £144m (+10%)
- “Trading profit” (excluding the impact of an interest rate hedge) £17.2m (+4%)
- The dividend increases to 107.8p and will be paid bi-annually from now on (one nice feature of family businesses is that family members tend to live off their dividends - so these businesses truly are run for the benefit of shareholders!)
At the very top of the statement, the Chairman points out that energy costs increased by £3.8m compared to the prior year. Without that obstacle, we can imagine that profits would have been significantly higher. But should companies be valued on the basis of lower energy costs, or are higher energy costs the new normal?
Refractory Division - see here. This provides materials used in the production of jewellery and in various other industrial processes.
Refractory is outperforming Goodwin’s Mechanical Division by some distance: the numbers below are from a footnote in today’s RNS:
- Mechanical Revenue £105m (down 2%)
- Mechanical Operating Profit £9m (down 16%)
- Refractory Revenue £72m (+28%)
- Refractory Operating Profit £13m (+36%)
In Refractory, Goodwin reports that cost increases have been passed on to customers, that both existing and newer products are performing well, and finished by saying:
Whilst the success of the Division has been seen across all companies, special mention should be made of our jewellery investment casting powder companies in China and in India having generated record profits in the year, even though the domestic market in China is still depressed due to the prolonged lockdowns and travel restrictions.
In Mechanical, the volatility of commodity and energy prices required contracts to be renegotiated. This division has been forced to evolve, and management sound very confident in its future:
Despite… the demise of our product sales to the non green oil and coal sectors, our re-aligned business offerings are more in demand than they ever have been, which is seen by the growing workload that customers are booking up to be delivered now years in advance. With the confidence of a solid and growing forward order book the tide has turned; all things being equal, the next few years should see the Mechanical Engineering Division returning to its former glory with even higher levels of turnover than at the peak of the oil and gas industry in 2014.
Forward orders, by the end of this year, should be “in excess of the levels the Group experienced when it was really busy a decade ago”, although the industries it serves have changed.
There’s a lot happening in the Mechanical division:
- Information about a large nuclear storage contract won by this division can be found here. I see that Carr's (LON:CARR) also won this contract.
- There are positive noises around Goodwin’s Radar subsidiary (link), the Chairman saying “I believe there will be a workload for Easat, the likes of which readers of their accounts for the past thirty years have never seen”.
- The company is also excited about its new Polymer manufacturer.
Energy and Outlook - having been hurt by energy prices in FY 2022, this risk exposure has been reduced:
...now armed with a multitude of short and long - term hedges in place the Group is set to deliver substantially higher profitability in the current year, partly as a result of not having to absorb the price volatility of the energy markets that have been seen over the past twelve months, irrespective of the improving performance
Net debt is £29.8m, in line with the Board’s expectations.
My view
There’s a lot to digest with these results, particularly since Goodwin is not a stock I’ve covered regularly.
But it’s always interesting to get a chance to look at a solid family business - in principle, I’d be eager to invest in something like this.
The main drawback for me is complexity: I prefer when I can say in one sentence what a company does. In the case of Goodwin, what would that sentence be? The array of subsidiaries across two divisions is a lot for one person to understand, and a lot to keep track of.
Putting that issue to one side, the outlook statements published today are greatly encouraging, as the Chairman sets out the case for “substantially higher profitability” in the current year.
There’s another green flag which I always like to mention when I find it; this company has zero analyst coverage. It’s on the main market, rather than AIM, so it doesn’t even have a Nomad analysing it.
Zero coverage is a sign that institutional investors have no interest in it (remember that Goodwin is majority owned by insiders). It’s also a sign that the company itself has no interest in marketing its shares.
If you want a stock that few other investors are interested in, and that is not bothered to try to stimulate its own share price, then stocks with zero coverage are a good place to start!
Stockopedia leaves blank the spaces where the estimates normally go:
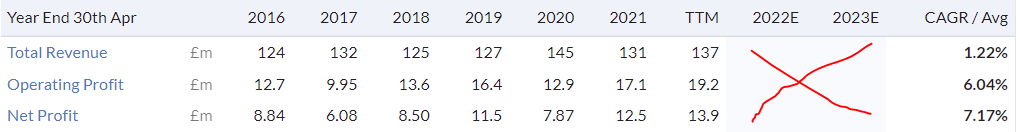
This means it’s up to us to come up with our own forecasts. The range of possible outcomes is likely to be very high, but I keep coming back to the Chairman and his outlook for “substantially higher profits”.
EPS reported today was 169p. If we round that up to 200p for the current year, we get a current PE ratio of 14x (using the latest share price).
That’s reasonable, given the sector, but maybe doesn’t give enough credit for a proven management team who are likely to control risks very well and are heavily invested in a successful outcome for shareholders?
With energy hedges in place, what is left to worry about?
[Comment from Paul: Thanks Graham, very interesting section. A broker note on Goodwin (LON:GDWN) (I hold) has just come through via Research Tree, from Shore Capital. Unfortunately, it's just a summary of today's results, and doesn't contain any forecasts. But at least it's the first sign of any broker coverage for a long time. Hopefully Shore might publish forecasts in due course].
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
my impression of VARE is much better than yours though i don’t invest in this sector at all. There was a reasonably impressive video presentation after the results, they seemed to be investing at a very good time - excellent rent deals - but i confess I don’t know if the format(s) work(s). One has recently opened in my town and when i get back from Canada I am intending to give it a whirl. I also thought they had a load of cash to fund the expansion rather than a skinny bs. Incidentally Canada has exactly the same underlying problem as the UK in hospitality. Can’t get the staff.
What have I missed in the news? Seems to be a "dash to trash" day with the AIM up well and my punts portfolio up about 5%!
Strong US data, ( not sure that is altogether a good thing,( more inflation?) )
Nancy Pelosi has left Taiwan !! without getting everyone nuked (yet)
No...the reason is quite simply I put a small short on the FTSE earlier today. My usual stock-picking skills have jinxed me again. If I close it tomorrow the FTSE is bound to plummet.
agree re family listed companies ,a great placed to invest long term monies and GDWN looks a good example
Thanks Graham for flagging the report on £VCP.
It certainly makes for interesting reading. It goes to show how wary investors need to be when analysing companies. But it has raised a few questions that Victoria need to answer and also raises questions on the effectiveness of the auditors (Grant Thornton in this case).
Interestingly the share price has not reacted to the allegations so far. Perhaps the market has missed this?
Victoria (LON:VCP)
Fell 11% yesterday based on Twitter reports.
For those that want to go over to the dark side, ADVFN's BB on Victoria has at post 1875 a reply (purportedly from the company) to the allegations to mysteronz .
Phil
(No holding)
Paul, thankyou for your thoughts on Greggs (LON:GRG) (I hold). It will be interesting to see how their plans to grow trade from 4 P.M. onwards (a traditionally quiet time for them) pan out. I'm hopeful that their value proposition holds up in the coming months, potentially seeing customers of more expensive "food on the go" retailers trade down to the Greggs offering. I recently visited the Northampton eco site referred to in yesterday's update, I cannot seem to leave the bacon sandwich and coffee offering alone ! I have to say that I'm always impressed with the quality of the customer service at Greggs and it does seem to attract a wider audience these days than it used to. That said I agree that the share price got ahead of itself in 2021.
Just some anecdotes on the challenge facing hospitality. I was up in Blackpool last week and had a few conversations with a hotel owner. They are having to swallow significant cost inflation for bacon/beans etc, a program to refurb some of the older rooms has been put on hold due to inflation in some of the decorating materials, the base cost of things like laundry has gone up significantly and of course the hotel will face sizeable energy costs going forward (unless they have fixed rates in advance of course). They will have limited opportunity to pass this onto the consumer. This was against a backdrop of higher cancellations this year against historic, especially from family room bookings - many of whom were citing concerns about future energy costs as a reason. I know this is anecdotal and specific but it certainly got me thinking about some of the challenges that lie ahead.
Phil Mc mentioned demand from families. We still own 50% of a visitor attraction which we built in 1995-6 and sold to the manager when we retired in 2014. The market is families with young children, principally day trips from a 70 mile radius + local accommodation, camping & caravanning. This summer season is dreadful. The last few days have not been quite so bad but the last 2 months have been dire, not even covering variable costs such as wages in some weeks. The first thing to do when unexpected things happen is find out whether it's just our place. This time it isn't, it's all the family attractions in our region. We do not think it's just people going abroad. People have always gone abroad in the 24 summers this business operated before the lockdowns. For a read across to other consumer-facing businesses I would comment that the ancillary spend per customer is holding up, which means the people who do come are not worried about saving a few quid. What has happened is that some customers are just not coming, or they are visiting only one place on a day out, not two as they usually do round here (all the attractions are low cost and quite small). It takes a lot to make people cut back on trips for the kids in the summer, but that's what is happening. By the way, the fixed price electrical deal has run out and there is talk of turning off all but one fridge and slashing the catering offer. The ice cream offer will have to go when the business isn't open 7 days a week. He says it frightens him when he goes into the buildings after closing time and hears all the compressors running.
I live near a seaside town in Suffolk, last year in July and August it was packed, this year numbers are well down, probably half, despite the weather being much better. Prices are high here which may put some people off but I think petrol prices and energy costs that are stopping people coming here.
One of the Southwold gentry Rustbucket ?
No way, house prices there are crazy.
Beautiful town but as you say top dollar 700k for mid terrace seems the going rate
I did my usual evening walk along Bournemouth beach last night, and wandered through the town, noticing how busy it was everywhere. Restaurants & bars are packed. I stopped for a curry at my favourite, Lahore on Christchurch Road, where I had to wait outside for a table, then had my meal (delicious!) in a restaurant that was rammed all the time, all tables full, and a constant stream of delivery drivers coming in too, to collect takeaways. It was amazing how the staff coped. He's put up his prices substantially too, the Set Meal For One (yes I'm Billynomates!!) was £11.95 last year, it's now £15.95, although portion sizes (which were already huge) are even bigger.
Bou'mth looks like we're in an economic boom, not a recession! There seems to be a lot more here too, e.g. there are about 4 large, pop-up bar/restaurants actually on the beach this year, which were really busy last night. There's also a pop-up bar/bowling alley in the town square (which is round), with live music playing & salsa dancing.
The whole town centre & beach area seem to be buzzing, more so than usual at this time of year (subjectively). I can't reconcile that at all with what people above are saying about everything being doom & gloom. Maybe people are getting more nervous up north, where utility bills would probably be a larger % of household expenditure, with it being considerably colder than on the south coast, and earnings somewhat lower? Just a guess.
Regards, Paul.
On your North comments that’s a definite big NO.
Manchester is booming , Liverpool’s busy everywhere , Cheshire Oaks you must be lucky to find a table anywhere , Trafford Centre’s restaurants are so so busy and in Chester City you have to be so lucky to find parking.
We are definitely in recession!
I'll agree with Y on Chester - hospitality is going great guns. However my observation is that retail is not doing so well - quite a lot of vacant shops.
Very interesting note by Graham on Victoria (LON:VCP) and the reference to a shorter's research.
I seem to have lost photome £PHTM from my portfolio today Anyone any idea why?
Name changed to ME Group International - just change the code to MEGP
Quiz (LON:QUIZ) - Bonkers valuation?
fcst p/e 5.7, peg 0.1, mkt cap £15m, cash £5.8m, book value 15p. Talk about beaten up retail!
Actually cash is a lot higher as per last update:
"- Total liquidity headroom at 4 July 2022 of GBP11.8 million, being a cash balance of GBP8.3 million and GBP3.5 million of undrawn banking facilities, a GBP5.3 million increase since 31 March 2022"
Hi eParo,
I asked Quiz (LON:QUIZ) (I hold) about the big increase in cash to £8.3m after the year end. They said some of that is short term timing differences, so don't expect it to stay that high.
The cash position is still comfortable though, so no issue there re solvency or dilution risk.
It's weird how I've been banging on about how cheap QUIZ is, and performing well, for a long time, and nobody was interested! Then suddenly in one day, today, it goes up 17%. Bizarre how things work in small caps!
Regards, Paul.
Thanks for the cash clarification Paul. Nonetheless it's cheap. Maybe retail bashing coming to an end. Keep banging!
The increase was due to the rebel tweets effect over the weekend and started early on Monday morning.
Paul, I know it is a micro-cap, but I would love to hear some thoughts from you on Comptoir (LON:COM) and the intriguing saga at the moment of both of the Chairman and the CEO being forced out, despite keeping the business afloat through the pandemic, against all odds.
I'm barge-poling it based on the behaviour of the majority shareholder (Founder), but would love to hear some thoughts on this, from Paul or others!
Hi Boon,
I don't rate Comptoir (LON:COM) at all. The crux is, it was a marginal business pre-pandemic, so why would it suddenly have become a great business now?
Restaurants got massive support during the pandemic, which flattered their numbers big time (VAT reduction, and business rates in particular). So the most recent results look fantastic, but once the benefit of those measures, plus the impact of heavy cost inflation on ingredients & wages come through, I doubt Comptoir will be profitable at all.
I did pick through the most recent numbers from Comptoir, and published something on it here, but unfortunately I can't find it - might have been in the comments section, so not flagged in the discussion section unfortunately.
As I mentioned above re Greggs (LON:GRG) - there are so many headwinds facing retail/hospitality, and withdrawal of (substantial) Govt support is something that I think some people have forgotten, will be a big drag on profits. That's why lots of 2023 forecasts are low, because analysts have factored in ending of Govt support. So it's not necessarily the case that they're being too cautious and companies will smash forecasts. The forecasts are low for a reason.
Regards, Paul.
Comptoir (LON:COM)
"... unfortunately I can't find it..."
Then you will have to let your research slaves find it for you:
https://www.stockopedia.com/co...
Haha, thanks sharw! I've just edited 30 May SCVR to include a tag for Comptoir (LON:COM) so it should now be picked up on future searches.
Best wishes, Paul.
I recently asked Stocko to see if the site search engine can search comments as well as headlines and tags and I got a positive response.
So how do you do it? When I have searched in the past it never worked unless it was tagged.
Sorry for confusion. I asked if it was possible to make the change and they thought it might be, they didn't reject the idea. I haven't heard any more.
Oh I see.
What I'll try to do, if there are any particularly useful comments on companies that are not already tagged, then I'll add a tag.
Also, by all means readers can ask me to add a tag for any companies discussed which are not already tagged that day.
Also, if you spot any missing tags (they occasionally vanish into thin air, we don't know why), then do flag it up, as I can add a tag very easily.
Regards, Paul.
(for anyone not aware, tags are the company tickers for companies discussed in that article. So when you search for a company on the discussion area, the list is populated by posts which have that company's ticker tagged in the article. It's a field which usually populates automatically from all £TICKER entries in the article, but sometimes the IT has a gremlin and tags are omitted or disappear)
NWF (LON:NWF) reported yesterday here is their presentation video & podcast.
The results were significantly ahead of the original market expectations it's been an outstanding year for them. Their headline figures are extraordinary but these exclude exceptionals, amortisation and finance cost in respect of the defined benefit, so I include both headline and statutory figures where relevant:
Significant outperformance in fuels from a supply constrained market where they galvanised their network to ensure supply which enabled additional margin and profit (2.6p /l), which they don't expect going forward. Although volumes were less due to the mild weather. Food was ahead of expectations due to operational efficiency and a great payback on the expanded Crewe warehouse; they will look to more investment in warehousing tied with demand from FMCG clients. Feeds had a strong H2 recovery when they were able to pass on inflation. The higher milk prices helps the customers so is good for NWF. Going forward growth will come from acquisitions in fuel, they were disappointed there were none in the period. Increasing the scale of Food, and in Feeds the academy is building the talent to drive sales. The period has provided a healthy cash balance for acquisitions or investment. Outlook at this stage, in line for FY23.
Encouraging results from Goodwin (LON:GDWN) (I hold) this morning. A slight increase in trading profits despite a big jump in energy costs, refractory engineering doing well, mechanical engineering continuing to pivot away from oil and gas, with a number of initiatives getting closer to bearing fruit. Plenty going on 'under the bonnet' but still manages to keep debt under control and pay a reasonable divi. Will never blow the lights out, but a reasonably priced and conservatively run company that I'm hoping will be a long term hold.
Positive announcement for this minnow this morning. EnSilica (LON:ENSI) which has recently launched on AIM. SP returning to close to the launch price.
EnSilica (LON:ENSI)
Had very quick look at numbers today - typical new listing very very little detail provided.
What were prior estimates - why are these not benchmarked ? - ridiculous - i did look on company website and stocky and could find no prior estimates.
H1 sales were 7 million H2 8.1 mill - with only £8.6 mill sales ye 31/5/2021 seems like growth rate has massively dropped H2 compared to H1 - albeit i dont know if sales are seasonal - i would have hoped for better with doubling of sales compared to last year . Yet they are ahead of expectations.
No menmtion of underlying profits.
Can't see any figures pencilled in for current year - very little comment to say they are spefifically on track - do they even have forecasts for current year
Compare this to company like bango where they have "shareholder consensus" section on website and i feel like we have absolutely zero to go on with this company - perhaps it is too early days and that will come. With new entity though why not do all of that as soon as listed ?
https://bangoinvestor.com/anal...
On a more positive note does seem sexy sector and market cap seems very modest - so i am not in any way knocking the potential of this company so thanks for flagging peeps.
Positive announcement for this minnow this morning -- EnSilica (LON:ENSI) which has recently launched on AIM. SP returning to close to the launch price.
I looked at Seraphine (LON:BUMP) (I hold) on Monday.
Bull:
Oversold? Valuation only £14m, for a profitable, niche eCommerce business, seems too cheap.
High gross margin (c.63%) indicates pricing power.
Well-known, longstanding brand, specialised fit, fashionable maternity-wear, little competition.
Bear:
4 profit warnings since listing!
Private equity backer still owns about 43% - what are their intentions?
Poor financial controls, led to departure of CFO (replaced with Lee Williams, ex FCCN & Asos)
Dependent on £6m HSBC facility (£5m drawn down)
Excessive inventories (see SCVR Monday this week)
Problems with logistics - esp customer returns (see poor TrustPilot reviews)
Deteriorating trading (now guiding little growth in 2022)
Increased marketing spend.
Director buy - announced this morning - CEO David Williams has bought a meaningful amount - 850k shares at 28.75p = £244k-worth. CEO's total holding is now 2.7m shares (50.9m total in issue) so 5.3% now held by the CEO (who's smart, I had a good call with him a while back).
Interesting maybe? Risky though, so DYOR more than usual!
Regards, Paul.
Re Seraphine (LON:BUMP) it doesn't seem very smart to have 4 profit warnings in a year. Can that really all be blamed on the CFO?
one other bear point is that Seraphine (LON:BUMP) customers might only shop here for 9 months, probably once or twice in their lifetime, so their marketing spend to refill the bucket must be high.
Hi 55555,
Re Seraphine (LON:BUMP) (I hold) - the Prospectus (it's a full listing) has some interesting stuff about customer lifetime value, and it's a good bit longer than 9 months, because it's not just pregnancy wear, but also post-birth mother & baby clothing, e.g. a product with a zipped flap for breast feeding, a neat idea! Also of course many women have several children, over a few years, during which time the woman can be a repeat customer for BUMP.
The Prospectus doesn't give a lifetime customer value that I can find, but on page 55 it says "average spend" is £498, which strikes me as a lot, especially as it's making a 63% gross margin. And CAC was £13, but I think has now risen to £26?
Re marketing, these costs have since gone up (see Monday's SCVR), but the Prospectus says -
"...low average blended customer acquisition cost (“CAC”), at £13, compared to a
blended average contribution per order of £43, meaning that Seraphine is profitable from the first average customer order" [part 7, section 1)
Just re-reading it now, this bit alleviates my concern about over-stocking currently -
"This broad product offering is underpinned by Seraphine’s core “Continuity” range, which comprises timeless staple pieces which are repeated year-after-year for the relevant seasons and accounts for approximately 70 per cent. of the product range.
This focus on its “Continuity” products, also helps drive Seraphine’s gross margin given its focus on a repeatable set of products which drives efficiencies in the development, procurement and marketing, which the Directors believe, would be difficult for its competitors to replicate. Seraphine has also organically grown a long-list of royal and celebrity followers which has helped to drive brand visibility internationally.
Seraphine’s products are designed not only to flatter and give confidence to women in their changing bodies but provide technical innovations such as concealed nursing access, support and (post-partum) compression, to assist the journey of motherhood."
[page 39, Prospectus]
I had a chat with the CEO a while ago, and he talked about how major retailers sometimes introduce maternity ranges, but often subsequently withdraw from the sector, because the sales densities are not high enough to justify the product being sold in prime retail space. This gives BUMP a competitive advantage, selling online, and high gross margins and high average transaction value, so it can afford to offer free returns, due to each parcel being something like (roughly) £80 gross profit.
BUMP was decently profitable before the pandemic, when quite small. Must have got a boost in the pandemic, like all the eCommerce businesses that floated at that time. But it's fallen 90% from the 295p float price, which I think is an overshoot on the downside. Hence why I like BUMP shares, and think it could be a nice recovery from here. Although as mentioned before, plenty of problems to overcome too.
It's not going to appeal to everyone, but of the bombed out eCommerce shares I've looked at, this strikes me as one of the best recovery situations, because it's niche, and high margin, and selling globally.
The CEO buying £244k-worth today makes me more confident I could be right, but it's uncertain still, and things could go wrong.
It's all down to valuation. Is this business really only worth £14m now? I think that's too low, but it depends on how trading goes this year/ next year.
Regards, Paul.
Paul
On Seraphine the big risk is surejy HSBC .
If they pull the plug it will only after a good hard look at that stock file .
If 70% of the stock is ongoing good sellers then looks ok, however letting the stock bloat so much can only happen once (covid , leadtimes etc)
I know of one major player in cycling who has gone to the wall (Saris cycling) as companies faced a very tricky task in the covid boom .
Do we order based on historic sales and play safe but risk being out of stock all the time and potentially damaging our reputation / profits , “play it safe Sam”
Or
Do we order like Billy Big Balls and place chunky orders based on increased run rates, and longer leadtimes and “go for it”
It was of course a no win question and a simple informed guess .
Turns out the market has overshot negativity and Putin put a nail in the coffin.
So Bily Big Balls has lost out to Play it Safe Sam
A well run company with a good CFO can get this under control in around 12 months and the bank will be all over this during the process .
I’m hearing also that banks are very very nervous right now and they have big exposure and leant based on business forecasts that are now being missed . At the moment I believe banks are “running with it” but if the mindset of the lenders changes expect sone blood .
Seraphine I think is too much of a punt right now, we need to see them confirm tte bank support for 12-24 months three simply work through the stock file and get it balanced .
Hi planetx,
That all makes sense, thanks.
The going concern note on Monday's results from Seraphine (LON:BUMP) was very reassuring - specifying that covenants wouldn't be breached, even on a plausible downside scenario.
Also reassuring today, is both the CEO & Chairman announced meaningful share purchases. Presumably they weren't allowed to trade until the results had been released on Monday, and they've together bought about £280k of shares - that's not a PR stunt, at a £14m market cap company.
Hence, whilst there are risks (as I've covered in my review here on Monday), I'm gaining in confidence now due to the going concern note, and the big Dir buys.
Given its high margins, and historic profit ability, I think BUMP should be valued at about 1x revenues, which would make it c.100p reasonable valuation once current issues are resolved with supply chain, etc. So I'm looking for a 3-bagger. At which point, I'd probably reduce my position size from large to small.
Regards, Paul.
Thinksmart (LON:TSL)
Simon Thompson tipped Think Smart some time ago and it did well, His recent article says vote against (for all the affect that will have).
I held but exited a while ago - lucky escape!
It looks like Thinksmart (LON:TSL) is 50/50 on all counts, I don't hold so count me out.
I notice the Zinc Media (LON:ZIN) retail offer is being done through Peel Hunt’s Retail portal REX (not PrimaryBid). This is the first time I have seen this portal used. It seems to allow applications to be made directly from II, HL and AJ Bell platforms.
What was the point of Zinc launching a retail offer to small investors at 7.0am this morning and closing it just 5 1/2 hours later at 12.30 pm when the £5m placing was completed?
Most small shareholders will never have realised that there was the chance to participate in a fund raising at a 7% discount given the speed with which the offer was open and closed. The net result was that Zinc raised a paltry £37,000 from small investors which was pretty pointless.
One senses that the professional brokers, such as Singer Capital Markets who ran the offer, have no real interest in trying to promote retail offers, and still much prefer capital raising exercises at a chunky discount reserved for their institutional friends.
Technology Minerals (LON:TM1) is an interesting one. A tiny company but in an area (battery recycling) which will necessarily have to grow significantly in the next 10-20 years if the push for ev's is to be successful without creating a mountain of used batteries and a new ecological problem.
The lack of charging infrastructure to support the ev transition is well known, while the recycling infrastructure is just as important but doesn't get mentioned as much. China have invested heavily in battery recycling, we haven't (so far), but will need to.
I have a small position in technology minerals which is admittedly something of a punt, but it's likely to be a growth industry and worth following imo.
Van Elle (LON:VANL)
UK's largest ground engineering contractor
Nice set of results today.
'Record revenues and return to profit following a strong recovery
driven by high levels of activity across all divisions'
Metrics impressive against 2021
Good balance sheet
Net cash £5.9m
Reinstatement of dividends with final dividend of 1p per share recommended.
Record activity levels and revenues following strategic targeting of structurally growing end markets.
Significant growth across all divisions, notably in higher margin Specialist Piling, Rail and Ground Engineering Services.
Piling work commenced on the Core Valley Lines rail network, the Group's first major electrification project since 2018 - electrification of the railways is high margin work for Van Elle
Success in passing on cost and managing the inflationary environment and supply chain challenges.
Outlook:
Trading momentum in FY2022 has continued into FY2023 with all divisions operating at high activity levels.
Supply chain challenges moderating, albeit inflationary pressures remain.
Investment in infrastructure, including the decarbonisation and electrification of the rail network, where the Group has established a market-leading position, expected to continue in the longer term.
IMC meeting at 3.30 today
I hold