Small Cap Value Report (Wed 3 Jan 2024) - IGP

Good morning from Paul & Graham!
Today's report is now finished.
Graham and I agreed that the other micro caps on the news list today weren't worth covering, and we've both got loads of other things to write about (I'm part-way through a mammoth article on my 2024 shares ideas, so would rather focus on that). Also Graham's agreed to put his top 10 onto that same spreadsheet, on a different tab, so we can monitor both lists with real time prices.
Graham's eagerly anticipated Top 10 list of share ideas for 2024 is up! I'm sure we'll all be carefully scrutinising these, given Graham's stellar +25% result in 2023. It's also interesting to see how Graham whittles down a large shortlist to a top 10.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Agenda - nothing much today, just Intercede (LON:IGP)
Paul’s Section:
Intercede (LON:IGP)
93p (pre-market) £54m - Major New Contract Win - Paul - GREEN
Intercede, the leading specialist in digital identity, credential management and secure mobility, is pleased to announce that the Group has been awarded a major licence order with associated support and maintenance totalling approximately $1.0 million for a new client in the US Intelligence Community. In addition to the perpetual licence order, the client is also contracted for a separate annual subscription of $0.2 million.
Better still, this means IGP is ahead of expectations again (after a monster contract win in Dec 2023) -
This order, combined with expected additional conversion of our existing pipeline in Q4, means that the Company now expects financial performance to be ahead of market expectations for FY24* and further underpins FY25.
* The current market forecast for the year ending 31 March 2024 is revenue of £18 million and adjusted EBITDA of £5.2 million.
"We are particularly pleased to secure this order because it has potential to grow further and the fact that there is a subscription element associated with it.
Annoyingly, they quote adj EBITDA, which is not the figure most private investors (and many fund managers too) actually want. Especially not in the software sector, where EBITDA is often totally meaningless, as half the payroll ends up on the balance sheet.
I’ve lodged a complaint with both the company and broker!
EDIT: This focus on EBITDA doesn't make sense to me, as IGP actually has very conservative accounting, expensing its development spend. So forecast adj EBITDA of £5.6m (FY 3/2024) almost all flows through to adj PBT of £5.3m. End of edit.
Broker update - Cavendish helpfully updates us, with another increase in forecasts -
FY 3/2024 - revenue upped by 7% to £19.2m. Adj PBT upped from £5.0m to £5.3m - that seems only a modest increase in profits, I would have expected more operational gearing from a big new contract win. Maybe they’re keeping something back to have a final out-perform flourish at the year end?
Importantly, remember that FY 3/2024 has a one-off element to the profits, due to the large perpetual licence won in Dec 2023. So FY 3/2025 forecast is for adj PBT to fall back to £3.0m (unchanged today). This is a more normal year for valuation purposes, and the FY 3/2025 adj EPS is 3.7p. So the current PER at 93p per share is a punchy 25x. Actually that’s not really punchy for a company growing so strongly, so I think that’s a perfectly reasonable valuation.
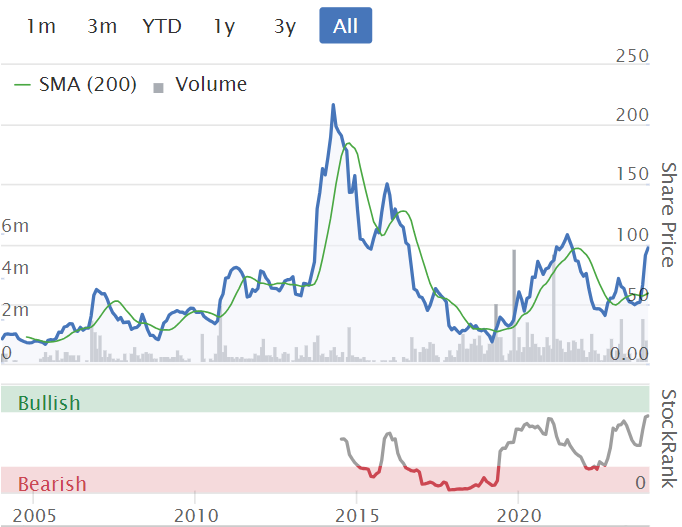
Paul’s view - the major contract win in Dec 2023 so impressed me, that IGP ended up in my Top 20 share ideas for 2024. We’ve followed Intercede closely in these reports for over 5 years, and liked the turnaround under Klaas van der Leest, a particularly strong CEO for a small cap in my judgement. It’s great to see the long-awaited growth now coming through, in a big recent surge. Nearly all IGP’s business is in the US, and mostly with Govt agencies - astonishing for a little UK company. Could this make IGP a bid target I wonder? There’s a 28% major shareholder who would probably need to agree any bid, plus of course key approval from the US Govt, who wouldn’t let anyone from a hostile state buy IGP.
I imagine today’s good news could propel IGP shares to 100p, maybe more. Some shareholders might be tempted to bank profits, but that might prove shortsighted. In my experience when contract wins start flowing through channel partners, it can often become a process, where more follow (providing execution is good, and clients happy with the outcome). IGP already has many very longstanding customers, which suggests to me high levels of client satisfaction.
It’s lovely to see this share developing so well. Pity I sold out a while back, and I wasn’t quick enough to catch this latest move, but it’s top of my informal “buy the dips” list! Well done to shareholders, I hope to join you at some stage.
There have been false dawns with IGP in the past, but I think this current bull run is much more solidly backed -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

79 comments
The other one to watch this year imo is Huddled (LON:HUD) : the old Immotion : I was trying to buy a chunk more at 2p just before the deal went through for the discount retailer but they wanted 2.2p and spread was 15% which put me off. Looking back that was an error given they are 3p bid today and up 15% but given a lot of the market cap is in net cash and the business revenue growth appears to be rocketing I have a sneaky suspicion they are going to do well in 2024 all things being equal. Would hope for a trading update soon. Having tendered 2/3rds of mine I only have a rump left so they will have to do extraordinarily well to be meaningful for me but in a dilemma whether to buy more or not. I see the CEO Higginson bought 2.5m shares recently so clearly he is optimistic. What's that about 70k worth at the price I think.
Huddled (LON:HUD)
For what it is worth, I bought diverse collections of goodies via their on line discount service twice before Christmas. Nice savings if they happen to have what you want in stock. Probably very seasonally weighted with booze and chocolates. Efficient delivery so no complaints there.
I did try to buy an initial stake but market was completely illiquid at the. time.
Good feedback Cricketfan. Thanks
Yes, I have heard decent things so good to hear from a fellow reader who has used the service. Also - if you are a shareholder you apparently get a discount too when you order btw!
Huddled (LON:HUD)
Thanks David and all the best for the new year.
It’s one of those that we will probably be looking back in a couple of years and wondering why we did not buy more. High margins here compared to supermarkets.
Just a personal opinion as well, but if they manage to take just a tiny portion of that £250b market then this will be a multi multi bagger; especially if they can built on their capacity in their new warehouse.
I hold.
What makes Discount Dragon so special? What is their moat?
There hasn't been a successful home delivery discount retailer because the economics of it just don't work - see ongoing EBITDA losses.
The Directors would have been better giving IMMO shareholders all the cash back - that's what the share price was telling them. They ignored and this was just a convenient way for them to get Director loans repaid and fund ongoing losses at failing Discount Dragon.
A really terrible business in my view. I'm struggling to think of a listed company with a less appealing business model.
It’s the cost of good sold and their gross margin , but in order to understand this better you have to study in detail the accounts of Motato.
But , If you think Huddled (LON:HUD) has the less appealing business model of any listed company then you have to short it!
All the best for the new year.
Motato exited the UK market because they couldn't make the model work. What makes you think the Directors here will make Discount Dragon work?
That’s not exactly what I have said; you have to study their accounts in detail and obviously you haven’t-Motatos exited to concentrate in other territories (Germany, Austria, Sweden).
This is a new management now and if they achieve £10m sales pa then this will work and price will move higher-I believe they will easily achieve that and this is the reason I invested (already up 47% and have added today).
Comparing a company business model , with a totally different management , for an investment thesis is something I would never do. It’s like not getting married again cause the first one did not work out!
As I said though just go short on it-I am sure there are a lot wiling to take you on out there.
All the best
"Comparing a company business model , with a totally different management , for an investment thesis is something I would never do."
Erm, isn't that what you just asked me to do - compare it with Motato in their overseas territories.
Whatever the markets in overseas territories, the UK market here is completely different. I'm not lying when I say I have the following stores within a 3 mile radius of where I live:
- Farmfoods
- Tesco
- Lidl
- Aldi
- Poundland
- One Below
- B&M Bargains
- Home Bargains
Much of the UK the same. Why on earth would someone visit Discount Dragon to pay £2.99 for a box of Coco Pops?
Well done on making a profit on investing in a rubbish, loss making company.
Erm , No - I just asked kindly if you can have a look at Motatos accounts , their cost of goods sold and their margins.
By the way you have listed 8 different brands all very busy with millions of sales!
All the best
None of whom do home delivery (apart from Tesco). Have you considered why that might be?
aside from Yiannos point have you seen the monthly revenue growth rates of the discount business Edward? I'm not sure why you consider that a "failing" business
Nor would I imagine Higginson purchasing 2.5m shares recently if he considered it failing either.
Anyway - we will see
Anyone can sell £1 coins for 90p. Revenue growth means nothing if the model doesn't work.
"For the year ended 31 May 2022, Huddled recorded a loss before tax of £160k on revenue of £465k. In the year to 31 July 2023, Discount Dragon's unaudited results showed an EBITDA loss of £0.7m on revenue of £3.3m."
That tells me the model doesn't work.
It looks to me to be an Ocado without the product range, brand recognition and technology. Most of the offers on Discount Dragon aren't even good.
Thanks Yiannos - and HNY to you as well.
Yep I agree - I am kicking myself for not taking the price at 2.2p so now I have to try and reset my mind and think about it 50% higher. I was hoping it would stay where it was for a while until a trading update on the new business so I could see growth rates and add quickly before any hot money but seems I screwed up that strategy!!! hey - ho I do hold so not a complete disaster.
Discounters, as you say, have high relative margins and if done efficiently (aka the new warehouse and technology) can scale rapidly and profitably. I think there is a serious gap in the market for the Huddled (LON:HUD) offering so I can also see the potential for a multi-bag here, but that will depend heavily on execution.
I will wait now for an update and then take a call whether to buy more. If they are knocking the lights out then 2.2p or 3.5p will be prove to be a rounding error anyway I guess.
Interesting concept. Took a look at the website and saw one or two things where I though the products offered good value but not enough of a hook where I personally would put an order in. I shared the link on my friendship group WhatsApp and asked for people's thoughts, 4 friends got back to me and all of them noted they didn't feel there was enough there for them to sign up and put an order in, interestingly 3 noted a lack of stuff they actually wanted or needed on the site. I feel it's on the precipice of potentially drawing in a lot of new customers but what they would need to offer to get those customers signed up and using the service would probably really hit margins. It is worth noting that my friends are very much comfortable financially, have decent income and are maybe are not the target clientele.
Interesting goings on at Entain (LON:ENT)
They've appointed Ricky Sandler of Eminence Capital (US based) who is an activist investor as a NED and they are appointing another one who must be jointly agreed. Eminence have been stake building.
This looks to me like it is being geared for corporate activity. Would not be surprised to see it bought out before the year is out now. My suspicion is somewhere between 1500 & 2000p
At the moment the BetMGM JV in US/Canada is in the price for nothing - looking at other US peers that is a material oversight by UK investors. I bet (geddit!!) that the plan is to get this in the share price, whilst ensuring the rest of the business improves margins per the capital markets day.
Good spot by Wolf Of Small Street last Friday w.r.t surge in volume at Nexteq (LON:NXQ). SP was up nicely yesterday, so perhaps a seller has cleared. It qualifies for Benjamin Graham's Deep Value screen. EV of £58.46m against a mkt cap of £71.77m.
Anyone know why the EV value for a stock is not visible on a mobile device? I can't see it on my Android phone.
Anyone know why the EV value for a stock is not visible on a mobile device? I can't see it on my Android phone.
Turn your phone to landscape view. You get a lot more info like the desktop view.
Doesn't show Enterprise Value in either Portrait or Landscape :-(
I've sent a message to support.
Nexteq (LON:NXQ) agree. It has appeared on one of my screens and looks good value (I now hold).
Yes thanks WoWS I looked into it after his comment and it deffo looked like a market clear out and ripe for a good bounce , but I didn’t know the company and then did some research only to discover they are in part the old Densitron…a name that always brought me out in a cold sweat perennial jam tomorrow and/or profit warner, at least that’s my memory of them.
Mothercare (LON:MTC) is up by around 65% in the last 3 months. Interims showed H1 PBT of £1.8m adjusted. M&G have been reducing, but no news otherwise. Market knows something?
Foxtons (LON:FOXT) is top of leader board up by 6.2p to 53.1p, +13%, can't find any news. Last comment from Graham was 28 July, green at 38.6p, thus up 38% from then.
In same sector I hold both Belvoir (LON:BLV) and Property Franchise (LON:TPFG) , both are unchanged today.
Anybody got any idea why Foxtons (LON:FOXT) is up so much today?
A quick search shows that Foxtons (LON:FOXT) were tipped in the The Telegraph on the 1st January 2024 and a few news articles this morning mentioning that they were the fastest growing lettings and sales agent in the UK in 2023.
Thanks Aron101, just read the Telegraph tips, last year's £10000 turned into £9940, perhaps Paul and Graham should submit their CVs ;-)
This article is not behind a pay wall, just Google "Where to Inveat in 2024" and"Telegraph".
The best was Telegraphs Questor "The 11 stocks we put in your child’s Christmas stocking – and how they performed"
"To recap, two years ago we named 10 stocks chosen to appeal in various ways to readers’ offspring. The idea was that, by selecting businesses such as football teams or fashion brands, an interest would be sparked in the idea of stock market investment as a means to save for future goals – and that actual profits would be generated to help recipients buy a house or car, or pay their way through university, when they came of age."
Contained a -99%, -76%, -59% and -82%
Tiny Tim must have had slim pickings this Christmas. Maybe should have bought him a stop loss :)
My Godchildren are 5 and 4, I was asked to invest their money in stocks. As they are Australian, I said no, but persuaded parents to look at ETFs. We jointly decided on a mix of Vanguard ETFs. Already the dividends are compounding, and hopefully birthday and Christmas money will compound much further until they are 18, and hopefully pay for part of further education or be able to put a deposit down on a property. Buying individual shares for children over a +10 year time horizon seems crazy, especially in fashion and football.....
Orval, I agree, that's the way I'd do it.
If you can put spare cash in every month or two and give it at least 10 years then it's a safe way to invest.
Nice calculator here. www.dqydj.com/sp-500-periodic-...
Interesting conversation Every Christmas I put money into my grandchildren’s JISAs. Exactly the same long term outlook as you Orvel and for similar purposes. They are currently three and six. I like dividend payers which offer good prospects for capital growth - get rich slowly!
Their parents are very green in outlook so oil stocks are out of the question. This year I have chosen CORD AND GSF to add to NESF, UKCM and a Slater Growth Fund from previous years.
As we're on to JISAs for grandchildren, just chucking in that I've made a balance between boring infrastructure GCP Infrastructure Investments (LON:GCP) and PE Trusts like Oakley Capital Investments (LON:OCI) and NB Private Equity Partners (LON:NBPE) , as things I think are good for 10-year outlooks.
Foxton's was one of the Telegraph 2024 tips
Answering my own question earlier re Foxtons (LON:FOXT) , the rise is probably attributable to this article posted by Guy Gittins
https://www.linkedin.com/posts/guygittins_wegetitdone-activity-7148014046477291522-f5vJ?trk=public_profile
Everyone is jumping aboard (including me) because it has broken out of a range it’s been stuck in since the end of 2022.
I had my first major cut of the year yesterday; Plexus Holdings (LON:POS) …I took the view that if they didn’t have the wherewithal to sweet talk and explain the situation properly to one of their biggest private shareholders and champions then they were very foolish or they are hiding the extent 0f the bad news, but I wish especially Paul and any other holders here the very best.
Hi TheOx,
Well that's not quite right. As I mentioned yesterday, the key points from my Q&A with Plexus Holdings (LON:POS) management yesterday were -
1) They knew the RNS yesterday explained it badly. That's because an original, much more detailed RNS couldn't be published, due to client confidentiality. So many details of the revised licence cannot be revealed to the market, nor to me obviously (I never ask for inside information when talking to mgt). So they're asking shareholders to trust them that they did a good deal.
2) Yes SLB drove a hard bargain, but management took a commercial decision that completely resolving the cash/dilution risk now, enables them to achieve more, as opposed to waiting potentially years for a royalty stream of unknown size & timing, and in the meantime not having the cash to develop lots of promising areas.
3) Cheap, high volume wellheads that SLB is planning on launching, is not an activity Plexus is involved in. So Plexus are happy to see SLB take these products forward globally, and in (hopefully) making them the industry standard, that should open up numerous, lucrative opportunities for Plexus to engineer bespoke products - like the £8m special project currently underway (which the CEO raved about, saying Plexus was doing a fantastic job for the client).
4) CEO adamant that the revised deal is good for Plexus, and "has not diminished the upside one bit".
5) The company has never given any forecast as to what royalties it was expecting from the original SLB deal, and pointed that nothing had been earned to date from it. So an up-front $5.2m is better for Plexus, and means the technology is being more aggressively developed by SLB, as they're putting more funding behind it.
6) Plexus tech has sailed through all tests with flying colours - see the quote from SLB in yesterday's announcement. There are numerous other areas where POS-GRIP can be used, they have only sold off partial rights to SLB in certain areas.
Ultimately I trust management, as they've been straight with me about everything.
The way I look at it, is that at end 2023, I had a high risk - high reward share. After yesterday's update, I can now completely relax about the cash position and dilution. So risk has enormously reduced.
How much upside has been lost with the new SLB licence? I honestly don't know. But the CEO is emphatic that it was a non-core area, and the upside hasn't been impacted at all.
Market cap now down to £15m strikes me as bonkers, now the cash/dilution risk has been resolved.
DYOR as usual obviously, just my personal opinions.
Regards, Paul.
P.S. There's a new video from the CEO on Proactive just published, where he tries to clarify misconceptions about the update. I can't view it, as on a train currently.
Thanks for the detailed update Paul.Not a holder of Plexus Holdings (LON:POS) but the mr.market is still in a very harsh mood today.Another general indices red day!If the market punishes a company’s share for one day, it usually doesn’t stop there in this market!
.Bring on the nadir of the bear market!Still lots of bargains available for those willing to bear the volatility.
Well that flipped quickly! Plexus Holdings (LON:POS)
Plexus Holdings (LON:POS)
https://www.proactiveinvestors...
plexus CEO interview with proactive investors
Plexus CEO interview
Fair enough Paul and I certainly didn’t want to misquote.misrepresent you or put words in your mouth, but you’ve certainly clarified matters here. And it looks though the CEO has also done a good job of putting matters right, the share rallied very nicely!
Just watched the Proactive Investors interview. I have to say I found the CEO very credible. He seems honest about his concern about the North Sea prospects and needing to go to other waters, and clear on his business model insisting that Plexus is a low volume supplier and will continue to be. I think his view on the Schlumberger "partnership" (his words) opening doors as a gatekeeper in the industry is promising. I hold (small position) and will continue to root for this business. It's the only oil stock I am willing to invest in - why shouldn't leak-proof wellheads be the standard?
Big volume spike in Zotefoams (LON:ZTF) if anyone's interested. Probably cleared out Invesco.
5.1million - wow - hopefully that gets the SP moving. Nice spot Wolf.
So much for my "thin trading" post on Zotefoams earlier.
I've had this before, I put up a post on something and the exact opposite happens. Bit like Nick Train and Diageo recently :-)
Are these the trades?
If so, 7.2% of the shares (edited). From the FY22 accounts:
I wonder who the buyer is.
It was actually one of three large trades:
Total - 4,083,182shares
Slightly more than Invesco hold on your figure, but could still likely be them
The share price has not moved, still can sell at 347p. Stockopedia prices are misleading.
Zotefoams (LON:ZTF) - and the London small cap market generally:
I use https://stockcharts.com/ for charting and I wondered why it showed no information for Zotefoams yesterday, so I sent a query. They answered promptly:-
'The chart had not updated because there had been no official trading at the time you wrote in. ZTF.L is a very thinly traded stock and had no on-exchange executed trades until very recently, we typically do not collect off-exchange executed trades as the time of reporting may not match the time of the actual execution which will distort the graphs. The chart has now been updated with the official data for today.'
People have been commenting on lack of market liquidity for months and every day when I look at the LSE page for companies I follow I see almost all the trades are "Off Book". Apart from the risk of companies de-listing (or moving to other exchanges)I'm worried that the number of market makers will fall and we'll see wider spreads for PIs? How will this affect Private Equity and Venture Capital if the IPO exit route becomes unviable?
By the way, I've had a Buy Limit Order for Zotefoams for ages, adjusting the price from time to time. It filled this morning so I now hold - showing an instant 3% loss. There's the spread problem.
(edited)
Foxtons (LON:FOXT) up 13%, which is a very un-Foxtonsy type of move. Any theories?
They were a year end tip somewhere..
Foxtons (LON:FOXT)
I think it was a tip of the year somewhere I read. Might have been The Times or Telegraph, cannot remember.
ME International (LON:MEGP) another day, another move down. 3 month chart looks awful, i keep thinking this will bounce, but no sign of that happening yet.
I feel you, bought in a week ago hoping to hit a recovery over the next couple of months as it looked to have flatlined on the chart... already down 8%! Can't win them all!
I bought at 75p so no need to feel for me! But up 100% to now just above 50%. Should have sold at 135p when support at 140p broken.
Forward PE of 8, divi yield of 6%, yes food division stumbling but only accounts for 4% of revenue...
Seems to be a robust resistance at 117p, strong volume going through today, maybe there is a big seller looking to jump ship. A sell of 50k just gone through and a buy of 57k. I just re-read the latest RNS and have come to similar conclusion as you. A lot seems to be made of the food division but as you say it makes up such a small percentage of revenue.
Yes, 117-118p has been a historically significant level, acting as resistance a couple of times.
May well bounce here as we retest it.
Checked across various platforms, chat rooms and even Twitter and nothing out there in terms of negative news I can see. Schroders increased their holding in December to 11.68% so institutional support is there. Results due 27 Feb. Until then I guess we enjoy the increased divi yield or hope for a takeover!!! For now I console myself with their interim statement:
"For the 12 months to 31 October 2023, the Group expects revenue to be marginally below the lower end of the previous guidance range but to be no less than £298 million. Nevertheless, given the Group’s focus on profitability, EBITDA remains in line with the previously stated guidance range and the Group expects it to be significantly above £100 million. Profit Before Tax is expected to be towards the top end of the previous guided range1 and no less than £67 million."
I have held ME International (LON:MEGP) for around 18 months. Prior to the trading update that Gimmers helpfully reminds us of (it is a full year TU btw, not interim) the share price had risen a fair bit and clearly that statement disappointed, perhaps a perception that the company has gone ex-growth due to revenue flatlining. The reaction ignores that the results in February will be a company record and a significant improvement on the previous year (~20% iirc). But the market is forward looking and therefore, outlook/guidance will be key to reversing the currently negative sentiment.
I expect it to lead to upgraded forecasts but obviously I’m biased as it remains a top 10 holding in my portfolio despite recent share price weakness.
I am with you, bought a while ago and also averaged up along the way. I was up over 50% at one point. I should have sold on the way down, but expected a bounce. All very easy to say in hindsight I guess. One of Paul's picks for 2024.
Happy New Year everyone.
I wondered if anyone had any views on Stelrad (LON:SRAD) . The debt concerns me against net profits but the momentum is strong and it's still below its initial offer price. A quick appraisal of their website suggests strong growth.
Thanks for this morning's write up Paul. Intercede (LON:IGP) is starting to bear some striking similarities to Cerillion (LON:CER) where the costs of maintaining the code base are largely fixed and consistent large contract wins cause the "jaws" between the high GM and lower operating margin to close.
Looking at the way the numbers are presented:
EBITDA is a very unfavourable metric for IGP, so its use is super conservative. EBITDA is unfavourable because IGP expenses all of its development costs (unlike, as you say, many software companies), so the DA is limited to a small non cash charge for amortisation of acquired intangibles from the Authlogics deal. T is a cash inflow from tax credits (and there are unutilised tax losses available as well for IGP). And I is an income because of the large cash balances.
The adjusted EPS number quoted by Cavendish is also conservative because they have a house policy of stripping out tax credits. I disagree with them because the cash inflow is a consequence of carrying on business in the normal course and will recur in future years. Also, tax is a line item before EPS and the nature of the payment is not affected by whether the number is positive or negative. More generally, HMG incentivises companies to invest in the UK (at relatively higher cost) rather than (say) India, Poland or the Philippines in the case of software development, by offering a tax credit. If the tax credit did not exist, IGP and others could, at least in theory, migrate some or all of its costs to these lower costs territories. Stripping out the tax credit from adjusted EPS ignores this business reality that the decision to locate / remain located in the UK at higher cost is influenced by the tax credit.
Cavendish's note today shows opex for FY24 increasing by £600k following the award of this $1.0m contract. It does not explain why the contract has such high implementation costs. There is perhaps some pulling forward of costs.
My morning smallcap tweet: Fishing in foul waters
Supply@Me Capital (LON:SYME) East Imperial (LON:EISB) Intercede (LON:IGP) Aurrigo International (LON:AURR) C4X Discovery Holdings (LON:C4XD) Chill Brands (LON:CHLL) Ondo InsurTech (LON:ONDO) Getech (LON:GTC) Hercules Site Services (LON:HERC) Learning Technologies (LON:LTG)
◄Supply@ME Capital (SYME)► commitment (not a contract yet) provided by Italy's Banco BPM to fund an initial IMInventory Monetisation transaction up to €10m of an existing client of BBPM. [SP=0.07 Cap=40m]
◄East Imperial (EISB)► wins accounts at 3 new New Zealand premises. Gives travel-magazine type hyperbolic descriptions of these including the fact that one has 'a cellar door'. Er, so what? Also on-trade channel rebounded strongly from Oct. Seeing significant margin improvement. Googling reveals a 'cellar door' is a local term for a winery tasting outlet with food. [SP=2.3 Cap=8m]
◄Intercede (IGP)► $1m licence order with associated support and maintenance + $0.2m PA subscription. Guides FY24 ahead of market expectations (rev £18m and adj EBITDA £5.2m). [SP=94.8 Cap=55m]
◄Aurrigo (AURR)► formal project agreement worth €0.58m with Schiphol airport for the deployment and demonstration of autonomous aviation solutions. [SP=91 Cap=42m]
◄C4X Discovery (C4XD)► $11m preclinical milestone payment from AstraZeneca. [SP=8.88 Cap=22m]
◄Chill Brands (CHLL)► re-iterates Jan launch into initial WH Smith travel locations, Morrisons stores and fuel stations. Talks on selling in select European markets. Developing an expanded range of reusable and rechargeable products. [SP=4.9 Cap=22m]
◄Ondo InsurTech (ONDO)► deal with Danish mutual insurance company LB Forsikring to accelerate the distribution of the LeakBot system to its members. [SP=22.74 Cap=20m]
◄GETECH (GTC)► eight contract wins worth £1.8m. Expects to book £0.6m in FY23 making FY23 rev c.£4m. ARR £2.8m (FY22 £2.4m). [SP=5.4 Cap=4m]
◄Hercules Site Services (HERC)► Civils div won £5.75m of contracts in Q1-Dec [SP=23.5 Cap=15m]
◄Learning Technologies (LTG)► completes disposal of Lorien Engineering Solutions. [SP=78.05 Cap=617m]. I hold.
"It's also interesting to see how Graham whittles down a large shortlist down to a top 10." - Yes it was and thanks for the list Graham - All the best!
Yes nice prompt. I've removed the second "down". Thanks!
Thanks for your list Graham.
Quick check against Paul's list of 20 stock ideas for 2024 and I think there is just one stock that appears on both lists i.e. CMC Markets (LON:CMCX) which I look upon most favourably as...... (I hold)
I noticed CMC Markets (LON:CMCX) and had been watching them for a while and they look very good value on many metrics but what about the concern of a major dominant shareholder ? He’s also the sort of character who I’m sure wouldn’t baulk at upsetting the mkt with a takeunder…I know one of Paul’s constant bug bears last year was the dominant shareholder…
CMC Markets (LON:CMCX) not sure about this really - cheap on a book value basis, but trading has been really poor and much worse than say IG or PLUS 500 (I hold) - I'm sceptical that their poor trading performance can all be blamed on a soft market when peers seem to be doing ok. Costs also seem to be somewhat out of control. Also a nasty habit of delivering bad news or profit warnings completely out of the blue. That said, at current price I might still be tempted.
Didn't even notice it to be honest LOL!