Small Cap Value Report (Wed 3 May 2023) - SDRY, VID, BDEV, RCH, WIX, TIFS, CARD, LORD

Good morning from Paul & Graham!
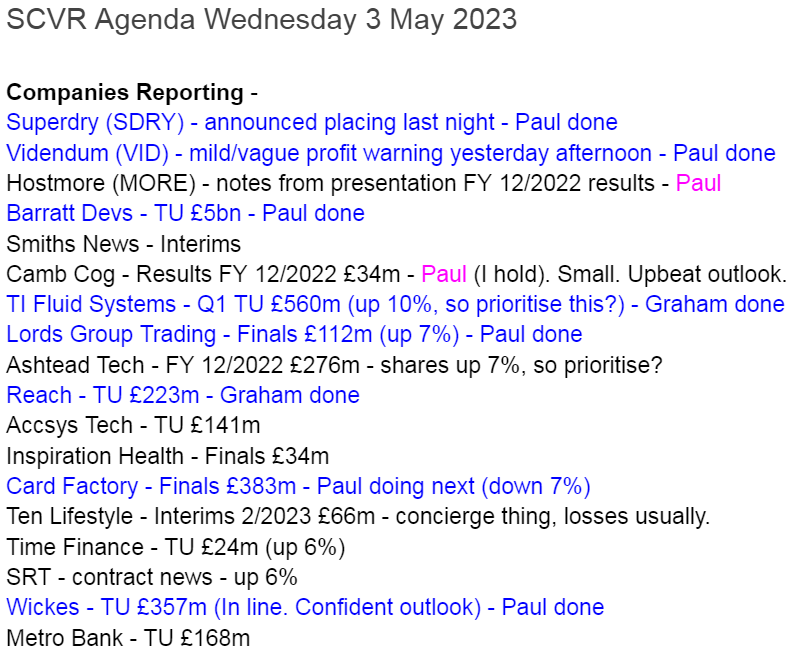
Today's report is now finished at 13:53
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Main Section Summaries
(more detail in sections below)
Superdry (LON:SDRY) - down 5% to 80p (£67m) - equity fundraise - Paul - AMBER
As expected, it’s doing an equity fundraise. Only c.£12m, although that’s flexible. Underwritten by Julian Dunkerton. Priced at a 10% discount, at 76.3p. My thoughts are below. A step in the right direction, but SDRY is not out of the woods yet.
Videndum (LON:VID) - down 9% to 713p y’day (£333m) - mild profit warning - Paul - AMBER
Issued a rather vague, but seemingly mild profit warning yesterday afternoon. I can’t quantify it yet, as no figures or broker updates available. I’m worried about excessive debt after an acquisition spree - not a good look when combined with now softer trading.
Reach (LON:RCH) - unchanged at 82p (£260m) - trading update in line - Graham - AMBER
This newspaper group is on track for large adjusted operating profits of c. £95m this year. They are bravely expanding in the US and the shares are superficially very cheap. This could get very interesting if revenues stabilise and as the pension deficit is reduced further.
TI Fluid Systems (LON:TIFS) - up 15% to 124p (£639m / €714m) - trading update in line - Graham - GREEN
This auto parts manufacturer enjoys a share price rally despite making no change to its 2023 outlook. Recovery is expected in profit margins as inflation feeds through to revenues. It has a large €600m debt load but with robust trading could be underpriced at this P/S multiple.
Card Factory (LON:CARD) - down 7% to 104p (£354m) - FY 1/2023 results - Paul - GREEN
Results are in line with expectations, and current trading slightly ahead. I have a good rummage through the accounts, and find nice clean figures. I no longer have any concerns about the balance sheet. Valuation is still quite modest, and I see decent medium-term upside on this share for patient investors, providing nothing goes wrong.
Lords Trading (LON:LORD) - up 6% to 73p (£118m) - FY 12/2022 results - Paul - GREEN
This builders merchant is growing through multiple acquisitions, and I'm quite impressed with the 2022 figures, and the modest valuation. Could be interesting. But beware the tiny free float, and highly concentrated major shareholder list.
Quick Comments
Barratt Developments (LON:BDEV) - down 1% to 499p (£4.9bn) - TU - Paul - GREEN
Another mid-cap housebuilder reporting that things are improving after a nasty patch triggered by global factors (higher interest rates & inflation), and worsened by the UK mini budget. In line trading for FY 6/2023. Net cash of £0.9bn. Demand supported by energy efficiency of new homes, and increased cost of renting.
Paul’s view - I’m keen on this sector, as the housing market is clearly now recovering from a sharp downturn. Bad news is in the forecasts, so reports now are in line, could maybe be above later this year? BDEV shares have had a v strong rebound since last autumn, but still look quite good value, and copper-bottomed by NTAV. Shares are only priced at 1.08 NTAV, which gives rock solid downside protection, providing house prices don’t fall sharply, which looks to be receding as a risk. Especially as Govt mooting reintroduction of Help To Buy scheme. Right now Persimmon (LON:PSN) and MJ GLEESON (LON:GLE) look attractive value to me, and might do a catch up with rest of the sector that have bounced much more strongly, perhaps?
Wickes (LON:WIX) - unch at 137.5p (£358m) - TU - Paul - GREEN
Wickes is a chain of 230 home improvement stores, and online. Today’s TU is for the 16 weeks to 22 April 2022.
It’s in line with expectations, despite some adverse weather effects, and LFL sales down 0.5% (not good when inflation is 10%). It seems to have a nice balance of business, with softer DIY demand being offset by good trade demand. Cost savings achieved.
Outlook comments sound confident.
Paul’s opinion - WIX, and ECEL were on my top value/GARP list for 2023 (and beyond). I think investors are too gloomy on valuation, due to worries over demand. However, this overlooks big favourable tailwinds on margins, from cheaper sea freight, firmer sterling vs dollar, etc. Hence I think it’s possible that earnings forecast for 2024 (16.6p EPS) could be too gloomy now, set at 29% below 2023 forecast (23.5p). Nice solid balance sheet, and a lovely 5.8% yield too. So WIX continues to earn a thumbs up from me. This strikes me as a nice solid value share. It’s not exciting though, so won’t be a multibagger.
Paul's Section:
Superdry (LON:SDRY)
85p (£70m) pre-market - last night: equity fundraising - Paul - AMBER
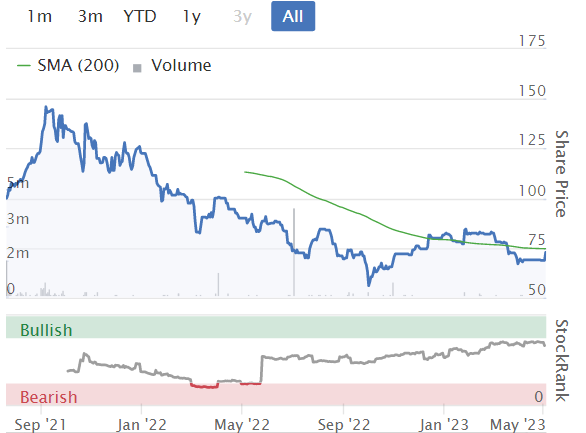
I’m oscillating between red and amber on this unconvincing turnaround. This struggling mid-market fashion brand had already told the market that a placing was coming, and the likely dilution, so this isn’t a surprise. A placing is being done, at a 10% discount, so 76.3p per share. 15.7m new shares are to be issued (but this is flexible), which is 19.1% expansion of the existing share count. It’s being underwritten by founder Julian Dunkerton. To raise gross £12m, which doesn’t radically change the financial position.
Paul’s opinion - of more importance to me is the expected net proceeds of £34m from selling its IP in the Far East. I’d want to see that cash in the bank, before even considering punting on this share. However, once both the placing (plus retail offer via REX), and the £34m IP sale have completed, then risk would possibly be low enough to risk having a punt. The argument being that if the turnaround does work, then it could be a multibagger. There’s a lot to sort out though - and I think Dunkerton’s explanations of how well his brand reset is going are considerably detached from reality, so it’s best to ignore him completely and instead look at the numbers, which are bad. Worth keeping an eye on though, and punters who get lucky, and time an entry right, could do well possibly.
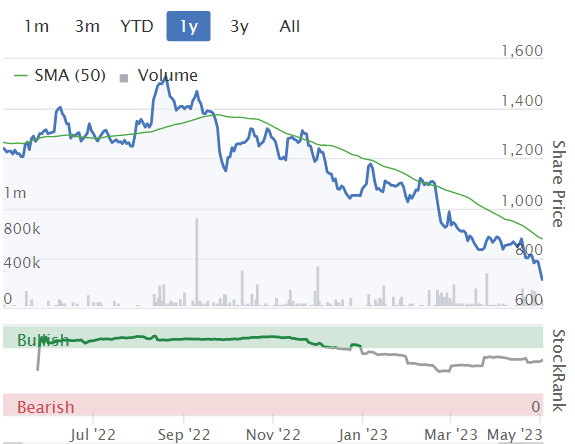
Note that, until now, there hasn't been any dilution, and even the 20% dilution being done now is not excessive. So if the brand returns to former glories, as you can see below, this share could be a multibagger - that's what is attracting some punters towards this share, I think. Or, as lots of people think, is the brand now old-fashioned and tired? The wholesale customers seem to think that, with reduced orders for this season. Had to bring in consultants to suggest cost cuts, which smacks of a badly run business to me - good management should be all over their cost base all the time.
EDIT: Drapers Record reports today that SDRY's COO, Silvana Bonello, has stepped down, which hardly inspires confidence in current trading.
Videndum (LON:VID)
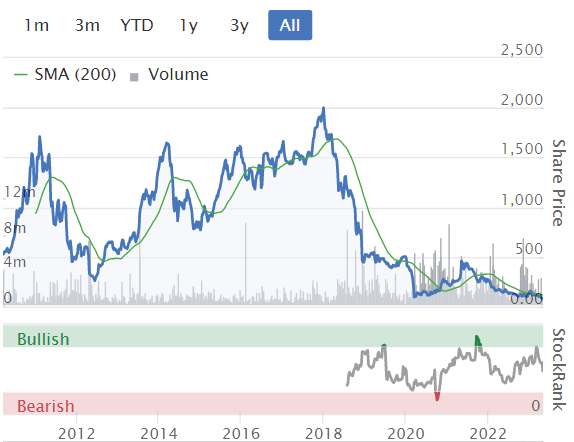
Down 9% to 713p y’day (£333m) - mild profit warning - Paul - AMBER
“the international provider of premium branded hardware products and software solutions to the content creation market”
A mild profit warning was Issued during market hours, at 15:14 yesterday, a bad start. The warning seems vague - saying that FY 12/2023 is being impacted by macro factors, and more specifically a US writers’ strike (film and TV), which has apparently deferred some sales for equipment that VID supplies (a category which is 20% of its revenues).
VID is now saying this will result in a wider range of outcomes for FY 12/2023, and a larger than usual H2 weighting. It is uncertain about the extent at this stage, and it could worsen if the writers’ strike is prolonged.
I’m a little concerned that it mentions bank covenants, and that it’s conserving cash, and seeking to reduce debt.
There are also some positive elements in the detailed announcement, including new product launches in the last 3 years generating around half current revenues. It reminds me a bit of Focusrite (LON:TUNE) which has also reported a slowdown recently, and has to constantly innovate with new products.
Paul’s opinion - neutral at the moment, it’s not a share I follow that closely. The value metrics on the StockReport look attractive - low PER, and nice yield. Although these are now likely to be reduced, but there aren’t any research notes available on Research Tree. So we’ll just have to wait and see what happens to the broker consensus forecasts.
The main risk here is that net debt is too high. Looking at its FY 12/2022 numbers, the P&L is good (big profit, and a high margin), but it looks as if management has overdone the acquisition spree, leaving a weak balance sheet (only £6m NTAV), and bank debt that could be excessive if profitability drops a lot from what might be last year’s high water mark.
I think we need more clarity here on likely performance, and with the heavy debt burden, I’m leaning more towards a RED point of view, but will go with AMBER for now. Hopefully the slower trading indicated at the moment might bounce back once this writers' strike is resolved?
Card Factory (LON:CARD)
Down 7% to 104p (at 10:04)
Market cap £354m
cardfactory, the UK's leading specialist retailer of greeting cards, gifts and celebration essentials, announces its preliminary results for the year ended 31 January 2023 ('FY23').
There’s been a fair bit of two-way business this morning, with the share price hunting for direction, and about 1.6m shares traded so far (plus of course whatever larger orders are being worked in the market behind the scenes, which are only reported once they’re complete).
We’ve had several ahead of expectations trading updates from CARD in recent months, and there seems to be a very convincing turnaround underway.
The figures today look in line with the recent trading update -
Revenue £463m (up 27%)
Profit before tax (PBT) £52.4m (up hugely from £11.1m LY) - includes £3.5m of one-off benefits, as previously disclosed.
Gross margin (on product) is very strong, at 68.6% - one of the highest I’ve seen for a retailer, because CARD is vertically integrated, making some high margin products itself. There could even be scope to raise that further, I reckon, now forex and freight costs have turned from headwinds into tailwinds.
Current trading/ outlook -
Trading in the first weeks of the new financial year has been encouraging and slightly ahead of the Board's expectations…
… we continue to have confidence in our ability to mitigate cost inflation through a combination of productivity initiatives and targeted price actions. This approach, together with our clear growth strategy and compelling value-led proposition, gives us confidence the Group will continue to make strategic and financial progress in the year ahead.
Medium term targets -
As part of our Capital Markets Strategy Update, we will outline a pathway for revenues of around £650m and margins around 14% in FY27, supported by a capital investment plan of £24m per annum, over the next three years.
I need some clarity on what measure it is referring to with “margins around 14%”? Presumably operating profit or profit before tax. It would have been helpful to be more specific, maybe it’s somewhere else in the announcement? If any readers know, do post a comment.
Balance sheet - is still weakish, but we knew that already.
NAV of £268m, becomes NTAV of negative £(58)m, which given the nature of the business (selling for cash, so little in receivables), and its now high level of profitability, is no longer a concern to me. Although I would ideally like CARD to hold back on paying divis for a while longer, to fully repair its balance sheet. This is important because companies need to be financially stronger in preparation for whatever the next major shock is (another pandemic, or a banking collapse, wars, it could be anything. Companies should never go into a crisis up to their eyeballs in debt, as CARD did in 2020).
Also debt is now more expensive, as the free money era of 2008-2022 appears to be over.
Gross bank debt at CARD was £67.5m, which is moderate given the big increase in profit to £52m, and cash of £11.7m takes it to a net bank debt position of £(55.8)m - I’m comfortable with that. There’s little to no dilution risk now, as opposed to this being a very high risk a couple of years ago. Investors who gambled on it not having to dilute got lucky that the bank was so accommodating!
Lease entries - the IFRS 16 numbers intrigue me. I was wondering previously if, recovering from the pandemic, multi-site chains like retailers, pubs, etc, might boost their profits from writing up the bombed out right of use asset values ascribed during the pandemic.
Doing a little digging into CARD today, note 10, this assuages my fears -
Application of these assumptions resulted in a net impairment charge of £1.3 million (2022: £5.0 million), comprised of impairment charges of £3.7 million (2022: £5.0 million) and the reversal of previous impairment charges of £2.4 million (2022: £nil).
This means CARD does still have some loss-making sites. Although this is probably only a small number of sites, since the RoU asset totals £100.3m, and the total property lease liabilities total £105.4m. That means a net deficit of £5.1m, which I see as pretty trivial. Therefore we can probably forget about property leases, as there don’t seem to be any issues there, good or bad, so it’s reassuring overall.
Dividends - note 7 indicates loan arrangements mean that it is currently prohibited from paying divis. That should be only a temporary issue, and if trading continues at anything like the current strong level, CARD should be back on the divi list, sustainably, fairly soon I reckon.
Software capex - note that CARD capitalised a hefty £9.4m into software intangible assets in FY 1/2023, up from £3.3m LY. That boosted profit, since the amortisation charge was only £2.3m + £1.5m impairment charge. I’d like to know the nature of that software spend, because about 10% of total profit has come from this diverting of costs onto the balance sheet, compared with if they were expensed. No doubt the accounting policy is allowable, but it has helped boost profit.
EPS - it doesn’t seem to produce adjusted EPS figures. That’s probably because there’s no amortisation of goodwill, so nothing needs adjusting out. We like nice clean numbers, with no adjustments, here at the SCVR.
Diluted EPS is 12.8p, up big-time from 2.4p the prior year. So at 104p per share, the PER is only 8.1, which seems cheap for a company performing so well.
It’s almost as if the market isn’t yet convinced that this level of profit is sustainable. If it is, then I would expect this share to re-rate to something more like a PER of 12+, which implies a share price of 154p+, which is 48% higher than the current share price. Looks interesting!
Cashflow statements - are totally messed up by IFRS 16 entries. The only thing that matters to me is that net debt is being paid down at an encouraging rate. In future that will be able to fund divis, I reckon a c.5% yield is possible from next year onwards maybe? Historically CARD overpaid divis, and weakened its balance sheet, putting it in a highly precarious situation during covid, which it only survived thanks to Govt, and bank support. They mustn’t get into that mess again, so I hope new management appreciate the need to be more careful.
Paul’s opinion - thumbs up from me. It’s still cheap, I think. Plus there’s potential upside if various growth strategies can deliver results. The half-hearted online efforts of the past have given away huge upside to companies like Moonpig (LON:MOON) - which is itself now in a financial mess after making a bad, debt-fuelled acquisition. So maybe CARD can start eating some of MOON’s lunch, instead of the other way around?
In the short-term, maybe the big jump in profits has already happened? So I think the opportunity here is more about the market giving it a higher PERx as confidence builds, and then maybe another benefit from medium term earnings growth? So I’d be pencilling in a share price target of maybe 150-200p, if you’re prepared to be patient (say over a year or two). That seems realistic to me, providing nothing goes wrong, as with everything.
Stockopedia's computers love it too, with a StockRank of 97.
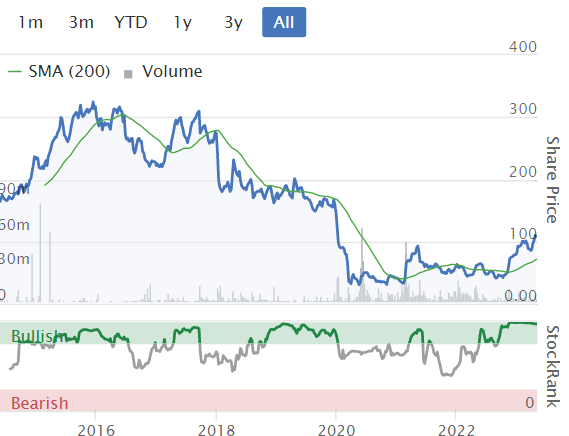
There's been no dilution since 2017, so in theory there's no reason why the share price couldn't recover previous highs, if profit growth continues back to pre-pandemic levels. Also, I think it's now clear that online has not killed off physical card sales. So CARD might be viewed as a GARP share, rather than a cigar butt value share (in slow decline) which was how it was viewed pre-2020, as I recall.
Plenty of stuff to like with CARD. I'll try to put some in my own portfolio, when funds become available.
.
Lords Trading (LON:LORD)
Up 6% to 73p
Market cap £118m
Lords, a leading distributor of building materials in the UK, is pleased to announce its annual results for the year ended 31 December 2022 ('FY22' or the 'year').
I’ve only reviewed this share once, here on 24 May 2022, when I concluded that it looked quite good! Here we are a year later, and I’ve quickly whizzed through the FY 12/2022 figures & commentary. Here are my notes -
April 2023 - refinanced “enhanced” bank facilities, 3 year term, with consortium of 3 banks. Using debt to fund multiple acquisitions.
Webinar recordings are on IMC.
25 Jan 2023 - ahead exps trading update.
Revenues £450m (+24% thanks to acquisitions, I can’t find the exact split of organic/acquisitions growth)
Good profit performance - adj PBT up 42% to £17.4m. Adjs look fine - mainly relating to amortisation re acquisitions. Only £400k share-based payments adjusted, which looks reasonable.
Adj basic EPS is 8.0p (up 32%), so a PER of 9.1x which looks a modest valuation, although this sector doesn’t tend to attract high valuation multiples.
Dividend per share 2.0p, for a yield of 2.7% - probably not a great idea to be paying divis, on top of making multiple acquisitions fuelled by increasing debt!
Net debt has soared to £19.4m, from a net cash position a year earlier of £6.5m - but this is a reasonable level of debt relative to EBITDA, the customary method of assessing debt reasonableness.
Plumbing & heating division is about half revenues, and saw a marked improvement in EBITDA margin from 4.4% to 6.0% (overall target is 7.5%)
Shortage of new boilers in 2022.
Current trading & outlook - in line with expectations - reiterates FY 12/2023 guidance.
Consolidator - only has 1% of a large, fragmented market. 40% of builders merchants are independent, so there’s an obvious role for a consolidator in the sector, which is LORD’s strategy. The business model makes a lot of sense to me. Of course it’s all down to execution now - this share’s success or failure will depend on how good mgt is at acquiring, integrating, and managing multiple businesses. That’s the key part to research.
Ownership - it’s family controlled. Only 7% free float. Top 5 shareholders (only 1 is an institution, the rest individuals) have over 75%, so risk to small shareholders is elevated - the big holders can do whatever they want with the company, so you have to trust them, or don't buy the shares!
Balance sheet - is OK overall. Although note that the NTAV is falling with all the acquisitions, and intangibles are piling up - this is the drawback with acquisitive groups.
Paul’s opinion - thumbs up. It looks cheap for an acquisitive group. I’d like to know more about who management are, how experienced, competent and trustworthy are they? That’s what will determine success or failure long term here. Mgt owns a controlling stake, so outside shareholders are totally in their hands.
The numbers look fine - good progress has been made in 2022, so I’ll hand it over to subscribers here for you to do your own, hopefully much more detailed research.
StockRank is 66.
Graham’s Section
Reach (LON:RCH)
Share price: 82p (unch.)
Market cap: £260m
Let’s review the trading update from this well-known newspaper group.
Reach plc ('the Group') is issuing a trading update for the 4-month period to 23 April 2023 ('the period'), ahead of its 2023 Annual General Meeting today.
Trading is in line with expectations, so adjusted operating profit is still expected to be within a range of £93.7 - 96.5m this year.
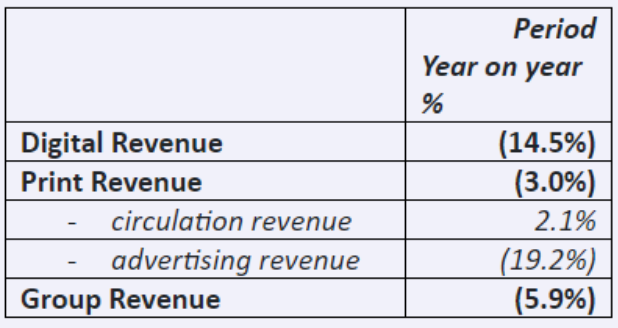
Here is the revenue table published today:
I wonder what the table showed us at the corresponding 2022 update…? Here it is:
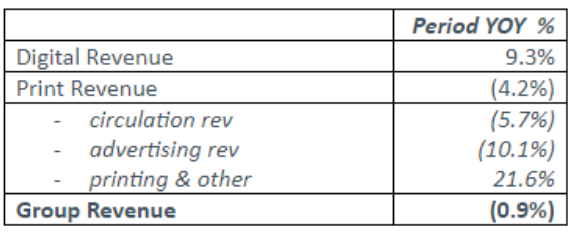
Comparing the two tables, there is little comfort to be had from the “second derivative” - i.e. not only are revenues falling in 2023, but the fall is noticeably worse than in 2022.
Circulation revenue is the only category with rising nominal revenues. This category will also have some of the highest input cost increases, so inflation must be passed on:
Print revenue has remained strong. Volumes remain robust, with circulation revenue benefitting from cover price increases during FY22, with advertising slightly ahead of our expectations.
Digital revenue is suffering from some of Facebook’s decisions, a reminder that it's the monopolistic platforms who have all the power in online media:
The page view slowdown, referred to in March, has continued, with recent changes to the way Facebook presents news content, causing a reduction in referred traffic across the sector.
Cost cuts: operating costs to be cut by 5 - 6% this year.
Outlook
Looking forward we expect to benefit from strategic actions to address the decline in page views, expansion in the US and a reduction in operating costs. In addition, H2 digital comparatives are less demanding, mainly due to suppressed Black Friday and Christmas trading last year.
My view
Paul had a look at the full-year results here, noting the P/E ratio of circa 3x.
Against that you have to consider that there could, once again, be very significant adjustments applied to earnings. Investors also need to consider the declining revenue profile and a balance sheet with negative tangible net assets (minus £200m+). This includes a large, billion-pound pension scheme in deficit.
The attempt to launch a larger US operation is noteworthy for a UK company that investors generally consider to be in decline. They are trying to build the American audience for the Mirror, Express and Irish Star, and also trying to serve American soccer fans. Maybe it can work?
I’m going to stay neutral on this stock. I can see the multi-bagging potential, but I wouldn’t be brave enough to buy into it myself.
For example, they made cash contributions to their pension schemes of £55m last year, and £64m in the prior year.
I’m hopeful that rising interest rates and the passing of time will help to make this pension issue go away, but these schemes have been sucking lots of cash out of the business and so the P/E ratio is currently something of a mirage.
Perhaps I’ll miss the rally, but I’d prefer to go green on this one when there was better evidence of stabilisation - firmer revenues, and an even stronger balance sheet.
TI Fluid Systems (LON:TIFS)
Share price: 124p (+15%)
Market cap: £639m / €714m
This is a former midcap that became a smallcap:
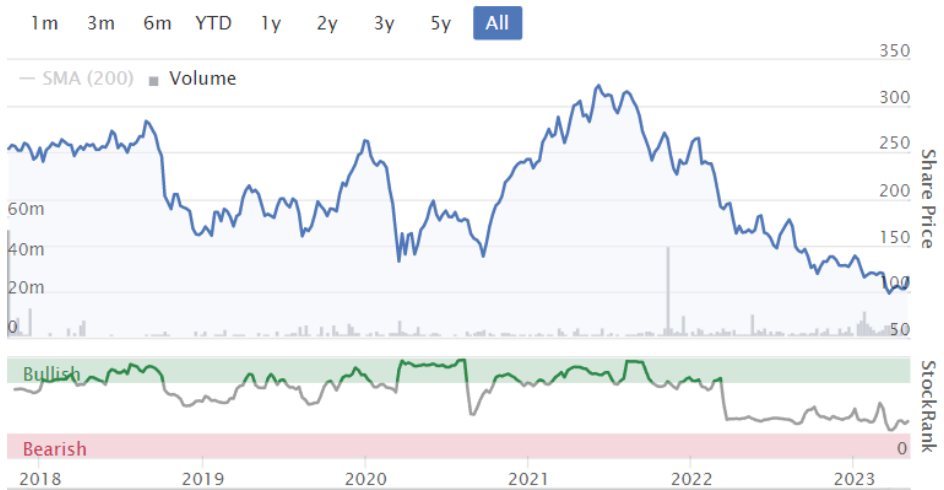
We’ve discussed it twice previously in the SCVR: I opened coverage of it in November 2022, and Paul looked at it in January 2023.
It’s “the industry leader in thermal solutions and fluid systems for vehicle manufacturers across the world”, with an HQ in Oxford and a main office in the United States.
I’ve noted previously that it’s very cheap on price/sales, but profit margins have been lacking.
Here is its Q1 2023 update:
Group revenue for Q1 2023 was €869.8 million, an increase of 15.2% versus Q1 2022 at actual exchange rates. At constant currency, revenue grew 14.9%...
With light vehicle production (LVP) volumes increasing by 5.7% in the quarter, revenue outperformance, at constant currency, was 920 basis points (bps). This outperformance was supported by product launches, favourable regional mix as well as our inflationary recoveries which delivered the expected benefits in the first quarter.
The company did previously signal that it had negotiated price increases with customers, and these increases are now bearing fruit with very decent revenue growth.
Geographic breakdown: growth is particularly strong in Europe and Africa (+20.5%), including benefits from higher volumes of hybrid vehicles and battery EVs. Again, we have possible grounds for optimism that TIFS is able to make the transition to a world where EVs are more mainstream.
The only weak point geographically is China, although even here TIFS says that its revenue decline was not as sharp as the broader market decline. It remains confident for full-year performance in China and reports €332m of new BEV bookings, of which more than half are in China (with Chinese manufacturers).
Outlook: no change to outlook.
…the Group continues to make good progress with inflationary recoveries which, together with a larger number of launches this year, underpins our expectation that the Group will outperform LVP [light vehicle production] growth in the year.
The adjusted EBIT margin is expected to get above 6% this year, an improvement on last year’s 5.5% (though still below 2021’s 7.2%).
My view
It seems important that these shares are up by 12% despite no change to the company’s full year outlook. If I was looking for some confirmation bias, I would say that it confirms the market became excessively pessimistic on this stock, and priced in an imaginary profit warning!
I remain drawn to this company’s price to sales multiple:
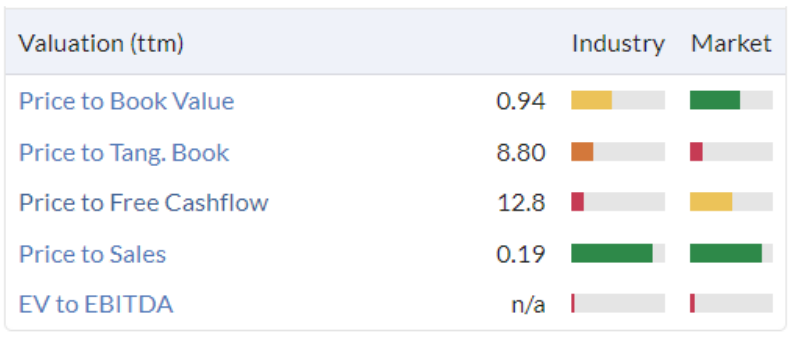
A major bear point could be the net debt figure, which was €625m as of the year-end 2022. The company reported this as 1.9x adjusted EBITDA. This is a private equity float, after all. So the enterprise value is around €1.3 billion.
I’m getting splinters from sitting on the fence for too many stocks, so I’m going to give this one the thumbs up. I wouldn’t have the confidence to bet heavily on it, but it looks like a very large company trading at a small-cap valuation. It needs to continue to handle the challenges of inflation/margin recovery, the transition to electric vehicles, and a significant debt load, but it appears to be doing all of this currently.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Paul, any thoughts on the Cambridge Cognition Holdings (LON:COG) results. If my memory is serving me this is a share you like and maybe even own.
Hi Julianh,
Yes I had a very quick look at the Cambridge Cognition Holdings (LON:COG) (I hold) results, and thought they looked quite encouraging. I don't think this bearish market would be very receptive to taking the valuation much higher for the time being though. Hence why we didn't prioritise writing about it today, with so many other probably better value things to look at.
Sorry about that.
Regards, Paul.
I listened to the Podcast today on Investor Meet with Smiths News (LON:SNWS) which I hold.
Clear and concise from the CEO and CFO. Net debt is now down to £26.3m from nearly £100m just 30 months ago. It looks as if the max Dividend cap of £10m imposed by the Banks will come to an end by August 2025 or sooner if Net debt is eliminated which looks likely by 2024.
Driver shortages have eased back to pre covid numbers. An interesting point made by the CFO was that the Company received a cash receipt of £5 million on the second day of their new financial year 2nd March 2023.
For Income Investors this share is a very tasty morsel!!
Great CARD write-up Paul - Thanks for that - By the way "So maybe MOON can start eating some of MOON’s lunch, instead of the other way around?" should maybe read "So maybe CARD can start eating some of MOON’s lunch, instead of the other way around?"
Well done matylda! I was wondering who would be the first to spot that!! ;-)
(I'll fix it now...)
Paul, you were asking what their quoted forecast FY27 14% margin was referring to, it’s PBT margin.
Hi Paul, Thank you for your Card Factory (LON:CARD) write-up. I hold and do believe its good value at the current SP.
Can't really believe £CARD are only targeting sales compound growth of circa 8.9% p.a. over the next 4 years £640m in FY27 vs £463m in FY23. The tranformation they're currently describing in the Capital Markets session certainly suggests they're aiming for far more? If not, why bother?
Paul. There's a typo you might want to correct in your write-up of Card Factory (LON:CARD. You wrote "So maybe MOON can start eating some of MOON’s lunch, instead of the other way around?". Of course, you meant the first MOON to be CARD.
Also, re Smiths News (LON:SNWS) , they state the £10m divs is limited by bank covenants, which relate to their debt. The debt is being rapidly reduced, which suggests a possiblity of a larger div pile being available in the near/mid future.
Smiths News (LON:SNWS) has an uninspiring record in my own investing history having first bought in 2011 when it was known as Connect. The name has changed but the good news is that it hasn't been taken over by a predator during this time, nor suffered from dilution. I think its prospects now are better now than ever.
Worth contrasting Ashstead Technology’s (AT.) excellent results today, with the recent dire performance of James Fisher (FSJ), the 175-year-old marine services company, which operates in several of the same markets as Ashstead. It finally posted its 2022 results last week underling the scale of the challenge facing its new management team.
Fisher, a former small share cap star, is saddled with far too much debt from ill-thought out acquisitions and has been selling off businesses in a bid to reduce its balance sheet leverage (net debt to ebitda) from 2.7 times to a long-term target of 1- 1.5 times. Its return on capital employed of 3.9% contrasts with the 12-13% it was reporting five years ago. Meanwhile its operating margin has slipped to 5.5%, compared with the 10% plus it used to regularly generate, and it has not paid a dividend for several years.
Fisher is being slimmed down into three divisions. The biggest is energy, made up of marine contracting and offshore oil, and will account for 50% of revenues. It is forecast to be the fastest growing part of the business with double digit growth rates.
Marine Transport, Fisher’s traditional shipping business, plus Fendercare and a small South coast port, will account for 35% of the revenues and the defence business, which has a specialist submarine rescue service, will make up the final 15% of revenues. Quite why Fisher is hanging on to this last business, which does not have any obvious synergies with the rest of the group, is a mystery.
Jean Vernet, Fisher’s new ceo, has a strong background in the offshore business, and has brought in new executives to head the energy and defence businesses, two of the three new divisions, accounting for around two thirds of group revenues.
Vernet said last week that he expected the turnaround to take 36 months by which time Fisher should be meeting its targets of a 15% return on capital and a 10% plus operating margin.
The contrast between Ashstead, with a market cap of £275m and revenues of £73m, and FSJ with a market cap of £175m and revenues of around £500m, highlights the potential value in Fisher if the new management team really can turn the company around.
Early days yet but the announcement that Odyssean Investment Trust (OIT), a shrewd long-term investor, had topped up its FSJ stake to 5.0% in March, suggests that Fisher’s long overdue turnaround is finally under way.
If put and 'at' in front then gives a link - James Fisher And Sons (LON:FSJ) and thanks for the heads up. Subwater and nuclear connections. Nordstream on topic. Who repairs this stuff.
So who else operates in the deep blue sea moat - Tidewater (NYQ:TDW) and Equinor ASA (NYQ:EQNR) Equinor ASA (OSL:EQNR).
Appreciate any other intel, no expert is me, and maybe not a capital appreciation area but we all aspire to "live in a yellow submarine".
Hi
Mirriad Advertising (LON:MIRI) up +118% as I type.
Current trade volumes as per Stocko over 22m average 890k. Spread according to Stocko 1818bps.
I suspect this will fall back in near future, but some might be interested.
As investigate is a bit dodgy I'll post my newsfeed RNS version .....
Mirriad collaborates with Microsoft to introduce new API
New API facilitates adtech platforms' interoperability with Mirriad's new
Fusion technology.
First release within the new cloud and technology collaboration with Microsoft
is geared to drive product innovation, improved scale and mutual customer
benefits.
Mirriad, the leading in-content advertising company, has worked with Microsoft
to build a new API, establishing a roadmap for adopting Microsoft Azure and
its AI capabilities for various use-cases.
The Company's new Application Programming Interface (API) is a first release
within the collaboration with Microsoft. The resulting interoperability with
Mirriad's Fusion technology, which enables dynamic insertions by media
partners, is able to support high volumes of real-time data exchange.
In practical terms, this enhanced connectivity between media partners and the
wider adtech ecosystem is designed to increase the potential scale of the
programmatic advertising opportunity.
Mirriad integrates Microsoft Azure API Management to drive this new
functionality and support Mirriad's ability to further integrate with
complementary Azure services, quickly and securely building new scalable
solutions.
Mirriad will also work with Microsoft on technical briefings and closely align
on product roadmaps to exploit the opportunities of the collaboration.
Stephan Beringer, CEO at Mirriad, said: "Partnering with Microsoft is an
important milestone for the further development of our in-content advertising
platform, proposition and business.
"Microsoft is a leader in cloud technology, cognitive and generative AI, which
are key elements to the new marketing frontier that we're building. The new
API is our first release in the collaboration with Microsoft and a main step
on our path to scale through automation and integration with the programmatic
ecosystem. The wide-ranging agreement with Microsoft can unlock significant
benefits and opportunities for both parties as we continue to develop our
technical capabilities and scale the creation and delivery of contextually
relevant ad experiences in content."
I do not hold (did so a long time ago).
Regards
Howard
Hi
Mirriad Advertising (LON:MIRI) now up over +232% as I type.
REgards
Howard
Vox podcasts interview today. Sounds interesting. Need more numbers.
Mirriad Advertising (LON:MIRI) is very close to going bust. So be careful with it. Check the archive here for the facts & figures.
Yes, saw that thanks. Basket case.
I would like to add to the request for Ashtead Technology [AT.] I hold. Its capitalisation (£240 million) isn't too small, and there has been good momentum. It is well niched, and there seems room for good uplift. But I'm a bit put off for further investment because of fairly whopping sales by directors.
Paul I just wanted to add a word of warning from my perspective with regard to the housing market. Talking to friends in the trade the situastion has changed quite significantly not only from the interest rate end. The profits they were able to make prior to recent macro changes was impressive. However inflation has been particularly hard on building products which has changed the dynamic for small builders. Large cos maybe able to use economies of scale. Three years ago I looked at developing a piece of land. We modelled the process very broadly on one third for the land, one third for the build an done third profit (less costs of sale etc). My information is that were we to do that now the cost of build has risen above 50% which will impact somewhere either the land price or the profit. Either way the developers will probably feel this.
Thanks for this. Further base rate rises on the way. I wonder at what point they become the straw that breaks the camel's back. Interest rates below 4% were irrelevant but once above this, they make a large impact on the house market.
Housebuilder profits anecdote
I am in the position of selling a brownfield site for housing and concur with what Camtab has said. I was also counting on one-third, one-third, one-third which was the traditional model. The developer says that the build costs have gone up steeply (timber down from its previous highs, but wages/cement/plasterboard and other materials haven't moved). Prices haven't really shifted either way (West Midlands). So it's the land value that is getting squeezed.
Another factor the developer mentioned is the cost of compliance with new energy efficiency regs. I support these by the way, but the impact is to increase build costs without leading to any increase in selling price. It should do - an energy-efficient house ought to command a premium - but that's not the reality. So that means a reduction in margins.
Conclusion - housebuilder shares may now be priced about right, even if they were clearly too low last Autumn.
"Impressive"? Other adjectives are available.
I would add an anecdotal to this, my nephew works for a regional (Northeast) company, he is currently on a plot with 120 sites to buildout, they are working on 12 currently, so very much in a go slow and only starting new plots once they have the orders secured.
The problem is who can afford to buy a property or more specifically get 'on the ladder' in an area where can get gainful employment.
Answers on a postcard.
Thanks for your comments on Reach (LON:RCH) graham. I wish they had made some comment on the pension position. Does anyone know when the next pension review is ? I am hopeful for this share and given the current mv may well be a takeover target. I hold in my granddaughters fund.
Basically a big pension company with a small print business on the side.
Some comments on Smiths News (LON:SNWS) please. Buybacks reduce cost of dividends, so I reckon promised £10m divs in current FY = 8% yield, <5x PE; good visiblility on revenue given proportion of contracts secured. Good cash generation.
Smiths News (LON:SNWS)
Thanks for the heads up grumpy5. Looks interesting and the high proportion of publisher contracts secured a long way ahead seems admirable.
They are appearing on Investor Meets Company at noon today whilst a video of their presentation to analysts is promised for this afternoon on the Investor Relations part of their website.
I would add that Mark Simpson did a good write up of Smiths News (LON:SNWS) a few weeks back, giving a balanced view of current and future opportunities.
https://www.stockopedia.com/co...
Re the comments on housing sector, i recently took an entry in Springfield Properties (LON:SPR) , looks attractively priced just now imo, with decent growth prospects down the road following two acquisitions last year (Tulloch & Mickelmarsh). Land bank looks excellent too with over 50% of it 'with planning permission'. Scots law also tends to give greater security over forward sales numbers as contracts to buy are legally binding far earlier in the sales process than elsewhere in the U.K. Housing market up here is also very strong just now. Debt is a little high hence the cheap sp, it's likely this can be managed though via land sales or higher prices in private housing sales.
Edit: apologies, that 'should have read Mactaggart & Mickels' , i must have been thinking about bricks when i wrote it - although, maybe one of the house builders should start buying brick co's to vertically integrate production costs!
One not on your list is Ashtead Technology Holdings (LON:AT.) that could be of interest.
the £275m m cap company, based in Scotland operates as a picks and shovels business in the global offshore energy industry and today they reported FY22 rev up 31% to £73m, gross margins up slightly to 73%, adjusted eps up 50% to 19.6p and a maiden dividend declared , albeit only 1p.
In their outlook statement they 'expect FY23 to be materially ahead of its previous expectations'
could be worth a look if either of you get the time.
Thank you.
Still working through the delayed prelims from Lords Trading (LON:LORD). On balance they read well given the challenging economic backdrop.
It is a family run business and operates a buy and build strategy in a fragmented market and to-date looks to be executing well. Hopefully it will continue to make acquisitions using cash flow augmented where necessary by moderate debt and avoid diluting share holders.
Trading update today from Accsys Technologies (LON:AXS) - doing well but of concern to me is the Tricoya plant at Hull where they have already spent a deal of money Any thoughts on this ?
It sounds to me from the update that the focus at the moment is on bringing the Tennessee project onstream next year. This is presumably lower risk, since they must know by now how to build an Accoya plant, and clearly the Tricoya plant has hit some technical snags. My guess is that they will resume work at Hull in 2024. Given the cash flow in the half year, finance should be soluble, but they may not have the engineer resources to be taking on more than one big project at a time.
What worries me about Accsys Technologies (LON:AXS) is that all their previous factory builds have been disasters - huge delays, and cost over-runs.
It looks like the USA plant build has hit some delays and cost increases too... and it'll be a brave person to bet that this is the first, and last, issue that Accsys will have before the plant goes live.
They're playing a dicey game. Without huge cash buffers on the balance sheet and also minimal profitability record at the moment, and weak capital markets, it'll be a punishing drop in the SP if they need to raise more equity, if they need to inject more cash into the USA plant.
Hopefully a meaningful update from SRT Marine Systems (LON:SRT) today. Signed off phase 1 of £40m project. £24m to go . As a holder - it's about b****y time!
And I hope not a WANdisco (LON:WAND) or heap of other AIM companies type of scenario!
Do you think that they will need some more cash before revenues start to turn positive ?
Not knowing the size of the invoice ... but I hope not.
:o) I have looked at SRT a few times, but I am still not convinced. Hope it turns out well, the news lately seems more positive than usual. I am not one to talk though, having managed to buy both Volex (LON:VLX) and Fireangel Safety Technology (LON:FA.) at near bottom prices. I chose to sell VLX on lack of news, and hold on to FA. with quite a handsome profit .. well what an idiot that makes me... live and learn.
There was discussion on yesterday's SCVR started by Quilleron about the disastrous reboot of Investegate. Wondering what had happened I looked at Google and got a statement that when you clicked through was no longer there but managed to get it from cache so here is the reason behind change and an email address that was probably so overwhelmed that the whole was withdrawn!
Investegate is under new ownership
In May, Investegate becomes part of Stockomendation Limited, the popular UK-based investment & trading website, as well as the operators of the UK Share Picking Game.
You may not have even noticed the change, because we have made a conscious decision to make gradual improvements to the site in consultation with you, the service users. But we couldn’t resist making the search function just a little bit better, the site speed quicker and a couple of other enhancements you may notice, as you look around the site. If there’s something you want to see included or improved on your Investegate service over the following months, make contact at: improvements@investegate.co.uk
Thanks for the information. Yesterday was a disaster with Inevestegate as information didn’t come through. Even today, trying to see results is difficult: it’s not clearly displayed on my iPad (admittedly very old) and the search function is clunky. I’ll try on the laptop later.
Is anyone else experiencing issues today? Are there any other alternative sites that are good?
Thanks
The issues are the same today. Hardly any feeds coming through on AIM Stocks. the nos do not correlate with what went on before the 28th April. As far as I'm concerned, its been an absolute disaster. A complete and unnecessary upgrade that has just tanked. The Archive function is useless. You can't source a company's RNS history before the 1st May. It's completely unusable. I could use far more colourful language but I wont. If anyone wants to vent their feelings on Twitter, use the following Twitter handle @Stockomendation
its truely awful now, as bad as the LSE RNS feed !
I looked at LSE yesterday and there is also a subscription service for RNSs. LSE charges companies to post and users to access information that is in a sensible format.
Perhaps LSE worthy of an investment with this double revenue source.
Re Investegate.
Speed ha improved today from yesterday's unusable disaster. Not sure it's better than it was before.
Layout is terrible, takes molre space per entry than before. You used to be able to choose to have all the day's items on a single long page to scroll through. That appears not to be possible now, so would have to select 77 pages one after the other to scan the day's items. If you try and do a search on specific categories to bring the numbers down it's hopeless.
I've used LSE to send me email notifications of news of companies I'm interested in for a long time. It works well and reliably. I used to use Investegate for a scan some days to see if I was missing anything interesting. I think they've made that impossible.
I've emailed them asking for the old site back, but I'm not holding my breath!
Layout is terrible, takes molre space per entry than before. You used to be able to choose to have all the day's items on a single long page to scroll through. That appears not to be possible now, so would have to select 77 pages one after the other to scan the day's items. If you try and do a search on specific categories to bring the numbers down it's hopeless.
Hi Peter,
As always this is a byproduct of making a website “mobile device friendly”. As with the Stockopedia “upgrade” it always decreases the amount of information on the screen, and in particular, greatly degrades the desktop user experience. I do wish that Stockopedia could improve their own RNS news interface as it is IMO the one feature upgrade that would benefit the largest number of subscribers.
All the best, Si
Investegate was perfectly ok to use on an IPad. Isn't that a 'mobile' device? The impression I get is that the changes were made just to satisfy people's access on a mobile phone...
Investegate doesn't work on my mobile phone or iPad. Even on my laptop the "results and trading reports" filter doesn't work. Everything worked fine until yesterday.
Does anyone know of any other sites?
News by 1st Quarter Results, 3rd Quarter Results, Acquisition, AGM Statement, Agreement, Contract, Director/PDMR Shareholding, Disposal, Final Results, Final RNS Announcement Released, Further re , GM Statement, Half-year/Interim Report, Intention to Float, Intention to Float - AIM, Letter of Intent Signed, Offer by , Offer for , Offer Lapsed, Offer Rejection, Offer Talks Terminated, Offer Update, Response to Statement/Event, Restoration of Listing, Restructure Proposals, Statement re Company Event, Statement re Possible Offer, Statement re Press Comment, Statement re Share Price Movement, Statement re. Suspension, Strategy/Company/Operations Update, Temporary Suspension, Trading Statement Headline type Today's News | London Stock Exchange
Paul linked this in yesterday's SCVR .
Tried to send them my feedback via their Contact page but it has a 200 character limit and wasn't working anyway. We've lost the ability to change the RNS feed you're looking at by changing the EPIC code in the URL (they now have numbers) and the EPIC is no longer displayed in the list. Text is grey and layout is expansive so readability is way down.
What a bunch of muppets. I'm desparately looking for a replacement.
I received a reply to an email i sent this morning stating the site was not functioning:
"We are extremely sorry for the inconvenience you have experienced in the last day or so using Investegate.
It was essential for the Investegate technology to move from its legacy platform and be upgraded, otherwise it would have ceased to operate at all this week.
We acknowledge this is not an ideal situation for you, but please bear with us as we restore the full functionality that you are used to over the coming days.
Thank you for your patience and understanding"
I got exactly the same mail. If that's called an 'upgrade', I'd hate to think what it would look like if unfortunately, down graded. Let's face it it's crap and the more people complain, perhaps they might do something about it. I don't believe their bullshit about the site ceasing 'to operate at all this week'. I think they're playing for time. Whoever allowed this crock to be signed off and 'go live' should be sacked. It's abysmal for all the reasons mentioned above.
Does Osb (LON:OSB) count as a small cap? Decent TU from them today.
Osb (LON:OSB) very under loved and misunderstood imo. Has a simple business model with superb cost to income ratio. Almost all of its retail deposits sit below the government guarantee so a run would appear very unlikely. Strong liquidity ratio. Excellent shareholder returns. Has quite a high bar in its credit policy so loan growth is not achieved through lowering credit quality, which is why 90 day delinquencies remains around 1% which is good management.
The naysayers keep pointing to the high focus on buy to let loan segment but miss the fact that the company focuses on professional landlords with many properties, which is not the part of the market under pressure. Low LTV's also give them a very robust asset backing.
Have been surprised these have never run up higher but as a holder I'm still pretty happy with annualised returns.
Osb (LON:OSB) Have a look at the directors dealings. They continuously exercise options at nil cost and then sell half. Why aren't they holding onto them?
Options lapse a certain period after vesting so they need to exercise. Exercising triggers tax liability (Income tax) so they are selling half to cover IT/NI, and keeping the net of tax value of shares. You would be more concerned if they were selling all of their exercised quantity.
exactly right eddcross80
When options vest the trustee form for the exercise comes with an option to sell sufficient numbers of the vested shares to meet the tax obligations. The residual is the directors to keep unencumbered. Most directors take this option as otherwise they have a crystallised tax liability against the shares.
Dividend yield on this share approaching an easily coverable 10% p/a and yet on a PE of 4 (despite a negative EV). In an ISA and happy for it to compound
Why do they sell half? Because they have to pay tax on them...
OSB are in a good niche - lending to professional landlords, typically with around 20-30 properties. This is a real growth area since private landlords are rapidly leaving the sector due to onerous regulations. The big banks don't really get involved here as it requires a hands-on approach where you have to get to know the companies, and can't be easily automated in the way individual mortgages are. Also a pretty resilient area - loans are all secured on modest LTVs and rising rents provides a good tailwind.
Ashtead Technology Holdings (LON:AT.) Given the performance to date, the Board expects the outturn for the full year to be materially ahead of its previous expectations
I like this share and have a full position. Delighted if Paul or Graham would share their views. Thanks.
Assuming they do eps of, say, 26p (consensus of 23.5p plus 10% materially ahead), Ashtead Technology Holdings (LON:AT.) is now on a forward p/e of around 14. Previous negative comments have noted high customer concentration, flotation by private equity at peak energy prices and insignificant director shareholdings. If you can accept those risks, on the face of it, this looks cheap with some future runway of increasing profitability to support the price.
I hold.
Super results from Ashtead Technology Holdings (LON:AT.) (I hold).
Ashtead Technology Holdings (LON:AT.) is benefiting from both the secular shift to renewables and the investment catch up in the oil and gas sector. The positive outlook indicates these drivers are still overwhelming any economic uncertainty. Growth is strong across Europe, US, Middle East and Asia.
Revenues up 31%, with gross profit 74% and operating profit margin 25% driving a ROIC of 21%.
I calculate Free Cash Flow of £18.9m (that's after investing £13m in Capex) and a FCF yield of over 6% given an EV of circa £300m and a market cap of £275m.
Some profit taking after a nice rise and downward pressure potentially from pre IPO holders continuing to reduce their stake may hold the share price back today despite the strong results. Could be a good point to enter or add given the board's positive outlook and the potential for FY24 upgrades.
Sorry BnB, we had that on the list, but just ran out of time. We'll try to circle back to it tomorrow or Friday, it does look interesting, and we try to focus on things that respond well to newsflow.
Regards, Paul.
No worries Paul. Hopefully a lighter load tomorrow. Thanks for trying.