Small Cap Value Report (Wed 31 July 2024) - IPF (Mgmt interview), RCH

Good morning! Apologies for the delay.
I'll hang up the pen there. See you tomorrow! Cheers.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
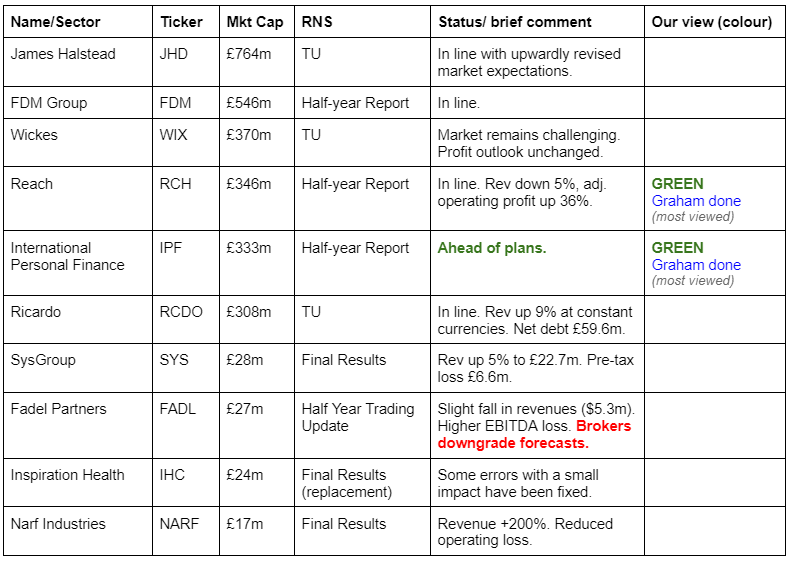
Summaries
International Personal Finance (LON:IPF) - up 8% to 149p (£338m) - Half-year Report - Graham - GREEN
Excellent H1 results with profits setting up to be ahead of expectations for the full year. The dividend is increased and the company initiates a £15m buyback, ensuring that its balance sheet will remain efficient so that it can keep earning decent ROE for investors. I had the chance to speak with management this morning and my notes have been typed up below.
Reach (LON:RCH) - up 1% to 105.3p (£335m) - Half-year Report - Graham - GREEN
A very good half-year report from Reach with a strong outlook statement. The main thing is that the company remains on track to deliver full-year expectations of adj. operating profit. As profits remain stubbornly high and as the obligations to Reach's pension schemes continue to reduce, I'm happy to maintain my sunny disposition here.
Graham's Section
International Personal Finance (LON:IPF)
Up 8% to 149p (£338m) - Half-year Report - Graham - GREEN
I was up early this morning for a conference call with IPF’s management and investor relations teams - an exciting opportunity as this is a company I’ve been covering for Stockopedia for several years.
Before typing up the notes to my Q&A, here is an overview of the first-half results.
Pre-exceptional profit before tax up 25% to £47.3m, ahead of IPF’s internal plans.
Interim dividend up 9.7%, in line with the policy to pay 33% of prior year full dividend per share as the following year’s interim.
£15m buyback announced to return excess capital to shareholders.
Operationally, a summary of the company’s achievements is as follows.
Customer lending up 7% excluding Poland.
Receivables up 12% excluding Poland.
Receivables in Poland are stabilising. 180,000 credit cards issued there.
Impairment rate of 10.5% (H1 last year: 11.4%) thanks to “exceptional customer repayment performance and excellent credit quality”.
Outlook is ahead of expectations.
Confidence in delivering an acceleration in growth through the remainder of the year.
Expect full year pre-exceptional profit before tax of between £78m and £82m for 2024, ahead of current market expectations.
Market expectations were pre-exceptional profit before tax of £71.4m. So this is heading for a significant beat of at least 9%.
CEO comment excerpt:
"I am delighted to announce very strong financial and operational progress for IPF in the first half of the year. Executing on our Next Gen strategy has delivered good growth momentum, exceptional customer repayment performance and pre-exceptional profit before tax…. The successful refinancing of our €341m Eurobond, which attracted very good demand and over 150 investors, ensures that we have a strong funding position to support our ambitious growth plans…
We continue to see substantial demand for our broadening portfolio of credit and insurance services from underserved consumers and we are confident that there are further attractive growth opportunities as we continue to execute on our strategy. I would like to say thank you to all my hard-working colleagues whose commitment ensures we continue to increase financial inclusion for our customers in all our markets."
Management Q&A
Before going any further, here are the notes from my meeting with management at 8am this morning. Answers were provided both by CEO Gerard Ryan and by CFO Gary Thompson.
Company intro by CEO Gerard Ryan
Our company has been around for decades and has a very clear purpose everyone is focused on - financial inclusion. Customers are those who are not welcomed by or who choose not to use high street banks. IPF treats them in a very fair and transparent way and unlike other lenders, IPF does not want to keep its customers in perpetual debt. Instead the loans are paid back in instalments, as IPF wants to help its customers to get back out of debt.
IPF is active in 9 countries. 16,000 customer representatives provide Home Credit, while IPF Digital provides loans through people’s phones or online. Circa 1.6 million customers.
The average loan size is €1,000 in Europe, €400 in Mexico.
Unusually, IPF doesn’t penalise late payments. Even if contractually loans are supposed to be paid back in 70 weeks, they know that the average time to repay will be 76 weeks, and customers aren’t charged for this.
Customer representatives are incentivised to earn commission by collecting loans, not by making loans. So the customer representatives are incentivised to arrange loans that customers can afford.
Financially the company is strong with 56% of the receivables balance backed up by IPF’s equity, and it seeks to earn a return on required equity of 15-20%. So it delivers for its customers while also providing its shareholders with a good return.
Q1. What would management say to potential investors who are nervous about investing abroad, e.g. in Eastern Europe?
A. IPF is spread over nine economies, and therefore its risk is balanced across these different countries. So arguably it is safer than purely domestic-focused stocks which have exposure to only one economy. A purely UK-focused bank, for example, could be impacted by national regulations or decisions that affected its entire business, which is not the case with IPF. So potential IPF investors could think of IPF as a fund containing a spread of different company and country exposures.
At the same time, IPF is a UK-listed entity with many UK-based employees, so it does benefit from the governance associated with being a UK company.
Q2. I noted that there were some exceptional charges, £5m associated with restructuring in Poland and another charge related to the refinancing of a bond. As these are classified as exceptional charges, can investors rest assured that these charges are finished for the time being?
A. No, the restructuring in Poland is not finished yet. The company has unfortunately had to make 215 redundancies. There has been 2-3 years of ongoing restructuring in that country and there is likely to be more restructuring in the current year. However the company is going to benefit from greater efficiencies thanks to its Next Gen strategy. The processes it uses in one country will be replicated in other countries.
With respect to the exceptional refinancing charge, the company had to pay up to exercise its call option to redeem its Eurobond in H1. The new bond which replaced it has a 5½ year maturity, including a six-month window during which it can be refinanced without paying up. So the company hopes to avoid a similar refinancing charge the next time it wishes to refinance.
Q3. Some investors may be unclear as to why your target impairment rate (14% to 16%) is so much higher than your current impairment rate (10.5%). Why would you want your impairment rate to rise from current levels?
A. One of the company’s key growth opportunities is in Mexico. However, the impairment rate in Mexico is around 30%. In Mexico, IPF can take more risk as there is no lending cap, and it can look for a faster growth rate of 10-15%. So growth in Mexico is a key reason why the impairment rate would rise.
More broadly, IPF wants to grow and to serve more customers. This mission will likely see a rise in the impairment rate towards the target rate.
Q4. On the subject of regulations, you’ve mentioned that you do not expect draft regulations in Romania to have a material impact on your business. Is IPF currently feeling comfortable with the regulatory backdrop in general and not expecting any major changes?
A. Companies such as ours can never feel “comfortable” as regulations are beyond our control. However, only one of our European countries doesn’t have a rate cap: the Czech Republic. We expect that it will eventually have one. For now, there does seem to be less planned activity in terms of new regulations. The only noteworthy change is the CCCD2 (Consumer Credit Directive 2) from the EU.
Q5. For those investors who may be interested in your retail bond, is your recent credit rating upgrade the main attraction?
A. We are strong from a capital perspective and strong from a funding perspective, always getting refinanced 6-9 months in advance. We also have a track record of cash generation: our profits are cash profits. And even in a worst case scenario, if we were forced to leave a country, we would still be able to convert our receivables into cash as we exited that country. Of course the equity would react differently in that scenario but even equity holders could see cash flow to them in that worst case scenario.
In the bigger picture we offer longevity and sustainability, and our products are not going to go out of fashion.
Graham’s view
It won’t come as a shock to readers that I’m going to be bullish on this stock today, as I’ve already been bullish on it. Today it announces that results are ahead of expectations, and a £15m share buyback due to holding excess capital. So this is hardly going to be the day that I change my mind on it!
The valuation metrics here have been cheap for quite some time, although of course many financial stocks are cheap in this environment:

Stockopedia gives it a near-perfect score:

Granted that it’s not as cheap as it was, but I thought that it was firmly in value territory before. And with an improved profit outlook, it’s only fair that the share price would increase:

Balance sheet net assets are £480m, still much higher than the current market cap. It’s reasonable if investors wish to discount the valuation for foreign currency risk, for regulatory risk, etc. But the return on equity numbers here are solid, from a company with a long track record. Even if future growth were to disappoint, I would see that possibility as being priced in here. If you disagree, feel free to let me know in the comments!
Reach (LON:RCH)
Up 1% to 105.3p (£335m) - Half-year Report - Graham - GREEN
It’s been a few months since we looked at Reach’s H1 trading update here.
The share price has been in a nice uptrend since then:

The company confirms again today that it is on track to deliver full-year expectations. These expectations are for an adj. operating profit of £97.8m.
It’s a remarkable level of profitability for a company whose total revenues are falling (down 5% in H1) and which many investors view as a legacy business.
Print: The company says that the volume decline in the print business is “in line with historical standards”. Revenue from the print business is declining, but is not falling as quickly as the decline in volumes.
Digital: Digital revenue has also declined in H1, but at a low rate of only 1%, and Q2 this year was positive against Q2 last year. Some major events (Euro Football Championships, UK general election etc.) boosted performance, so perhaps Q2 should be treated as exceptional?
The success story here is really all about cost control, as operating costs fell by 9% (on an adjusted basis) or 15% (on an unadjusted basis).
Outlook seems very positive:
We are trending slightly ahead of a full year reduction in operating costs of 5-6%. The phasing of cost initiatives and inflation during 2023 and 2024 means that operating profits will be more equally weighted between the first and second half of the year.
At the end of the period, we saw elevated levels of advertising spend supported by events such as the European Football Championships. July is trading in line with our expectations.
We continue to work against the backdrop of the dominant tech platforms and their impact on search and referral traffic. As we have seen, this dynamic can create some volatility across our distribution, however, we are building more resilience through our Customer Value Strategy and we remain on track to deliver market expectations.
Graham’s view
Remember that Reach is paying about £60m p.a. to fund its pension schemes, and needs to do so until 2027. From 2028, contributions will shrink.
The way I value Reach is by adding on the pension contributions until 2027 to the market cap, treating them as a form of debt and adding them to get a type of enterprise value figure.
Let’s check for news with respect to the pension schemes, as this issue is the main overhang on the stock.
Pension news:
Firstly, the accounting deficit has fallen (to £35m from £77m). I don’t care about this too much as it doesn't directly cause any fall in the required cash contributions.
Reach made pension contributions of £31m in H1, which makes sense as I previously calculated that the total cost would be about £60m p.a. The total cost this year is expected to be £61.1m.
With £31m having been paid off in H1, I can reduce my estimate of the outstanding “pension debt” owed by Reach.
I roughly estimate the outstanding pension contributions until the end of 2027 as £210m - let me emphasise that this is not an exact figure!
After 2027, contributions may still be required, but they should be much smaller.
There is also some financial net debt but it is only £12m (excluding lease liabilities), so shouldn’t be too important here.
Overall therefore I think the valuation here remains very interesting, even at a higher share price. You can add together pension contributions (until 2027) and net debt to the market cap and get a number in the region of £560m. With operating profit stubbornly high at close to £100m, it’s an interesting deleveraging story. I’m staying GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Reach (LON:RCH) Many thanks for your report on Reach Graham. Just one thing if I remember correctly (not a certainty) the pension payments end in January 2027, so if I remember correctly we can knock £60m off the pension contribution.
#BMY (I hold) very large trade of 1,257,000 shares, about 1.5% of the share cap, in the uncrossing at 744p. Which was about 20p above the share price and the buyer went on.
I saw someone suggest that it will enter the FT250 tomorrow, so maybe trackers are buying.
Fun factoid for today: Siegel says (page 172) that the ERP (Equity Risk Premium) for the (US) market averages about 3%. I calculate the ERP for UK is +2.8%, about average, whilst for the US it is -0.5%. US investors are clearly willing to pay a lot for anticipated growth.
I base my figures on the inverse of the trailing PE ratio minus the yield on long-term gilts/treasuries.
Zotefoams (LON:ZTF) have risen 10% today on no news and trading not possible currently. No RNS's today, so what could be happening?
Trading's just resumed...
Zotefoams (LON:ZTF) It went into auction, that can happen when a share rises more than 10%.
This could be a contributing factor. It is always worth following any smaller caps you hold in LinkedIn. It can be a the first place they post some information.
Looks like that's the reason for the share price jump - thanks for the info
International Personal Finance (LON:IPF) - yes, interesting interview. The interest rate charged on the loans is very high though, despite the ethical pitch. I have a very old residual holding but will exit when I get the chance. I will follow Aberforth as they will be selling when their valuation is reached. Not a bad company, but big regulatory risks. This was all part of Vanquis Banking (LON:VANQ) at one time. They are the overseas part of the Provident Financial business in the UK which was effectively closed down. Probably only a matter of time before UK regulation squeezes less developed overseas markets in my view.
SysGroup (LON:SYS) reported today. An interesting micro cap play on the AI boom. Previously a company focused on cybersecurity solutions they have done a real kitchen sink job on the company. New CEO, HeeJae Chae has 14% skin in the game and although I dont know the details on his history, he has held long term positions in senior roles at larger companies Volex (LON:VLX) and Scapa (LON:SCPA^D21). A recent equity raise of 11mil, which is more than half the market cap, for an encouragingly small discount (6%) really sorted out the balance sheet - HeeJae and his new team clearly know how to sell the story to investors. It is admittedly hard to foresee how future revenues and profits might look, although revenues are moving in the right direction (up 5% to 22.7mil, up 14% in H2 compared to FY23) and recurring revenues are stable at 75%, which should help to put a floor under the SP for now should they continue to be maintained. Bearish points saw adjusted EBITDA take a big drop from 3.1mil to 2.0mil and gross margins declined from 50% to 46%.
The CEO stated “I am very excited about the Company’s potential and future prospects. AI will be the transformational technology of our generation and will continue to gather momentum as the technology improves and benefits are crystallised. As with any innovation, its adoption will not be a straight line and will follow a J-curve. Our mission is to inform and support British SMBs which accounts for 99.2% of total business population in this journey.”
I hold a small position in SysGroup (LON:SYS) with the logic being that the new fundraise and recurring revenues give it a safe balance sheet and it is therefore a pretty low risk play on AI within the UK. It certainly has multibagger potential if management can pull off the turnaround, although I admit it's unlikely to happen quickly. One to tuck away and forget for a few years rather than jump into for a quick trade. I know Paul mentioned in his podcast that some big players are suggesting AI might not be all it's hyped up to be. I understandthat argument, however, it will continue to advance and evolve and having at least some AI exposure is definitely a good thing in my opinion.
Hi Ben.
I was ready to write something very similar on SysGroup (LON:SYS)!
AI will definitely advance and grow for at least the next 10 years! In order to understand it though one should listen carefully to what CEO’s over in the US have to say. Advanced Micro Devices (NSQ:AMD) CEO Lisa Su interview today (after their excellent results) was very informative and bullish indeed.
I hold SysGroup (LON:SYS) and I will be adding to my position in the next days. It’s one of those that with a couple of large contracts will easily accelerate. I can this as a multibagger and one to hold for the next 3-4 years.
All the best
Hi yiannos1,
Do you have a link for the interview or where we can find it?
Cheers, Graham.
Was on CNBC today on Squawk On The Street.
Should be on You Tube.
All the best
Cheers Yiannos, I will certainly check that out at some point this week. Glad to hear you are also positive on SysGroup (LON:SYS) and are increasing your holding. I always value your opinion.
Afternoon Graham a really interesting interview with International Personal Finance (LON:IPF) …a point that struck me as unique was that they pay agents on the basis of repayments not origination…I don’t think I’ve ever seen that before….also the seemingly ethical approach they bring to a customer base that often only has more shark like alternatives suggests an admirable corporate citizen is available at a v modest valuation…along with some really thoughtful risk management
Many thanks rhomboid. I've been a fan of IPF stock but never fully appreciated their approach to ethical lending until today. It was an eye-opener. Cheers. G
IPF3 now 107p offered. Looks solid with a decent yield
Thank you Graham,
For all your hard work on the reports and TU comments today. Also for the written notes from your interview with the management of International Personal Finance (LON:IPF) . I had just bought a small position prior to reading your report and notes, so much appreciated. As was all the other content today.
Graham.
A lot of subscribers seem either to be unaware of the many threads here except for this one, and/or have problems finding them. This link brings up all the threads that have seen recent posts, and new threads too. I log in to Stockopedia using this link:-
https://www.stockopedia.com/di...
Today we initiate coverage on Restore (LON:RST), the UK’s leading provider of records management, digitisation and secure recycling services.
The last twelve months have seen a management overhaul with the return of former CEO Charles Skinner, bringing a refreshed strategic focus to address a disappointing trading performance in 2023.
Restore is a high-quality business operating in markets characterised by high barriers to entry, recurring revenues, attractive margins and sticky customer relationships. Under a proven, driven and experienced management team, we see scope for consistent earnings growth over the medium term, which in-turn should see a rerating of the shares.
It is clear to us that the share price does not yet reflect confidence in earnings forecasts, or the upside potential of management’s medium-term targets.
We initiate coverage with a 400p Fair Value estimate which represents an FY25 P/E rating of 20x, in line with Restore’s historic average rating and peer group multiples.
https://www.equitydevelopment....
We're also hosting a presentation this Friday at 9am
https://www.equitydevelopment....
Flowtech Fluidpower (LON:FLO)
I see that the Harwood stable of investment trusts Rockwood Strategic (LON:RKW) Odyssean Investment Trust (LON:OIT) and Oryx International Growth Fund (LON:OIG) have increased their holding to over 10% following yesterday's results. They obviously have confidence that the turnaround is starting to gather traction.
I am riding on their coat tails and have a good sized position.
Maybe a buy if it takes out the 145p line.
Flowtech Fluidpower (LON:FLO)
Maybe a buy if it takes out the 145p line.
Not sure what you mean. If you mean wait until 145p to buy, you will have already missed out on a large % increase. Surely now is the time to buy and set a stop loss. Apologies if i misunderstood you Big Spender71
Equals (LON:EQLS) - courtesy of a poster on the EQLS BB on ADVFN
Peel Hunt note today...
An elevated interest rate environment has been a tailwind to Equals’ top-line growth (+33% YoY in 1H24). We expect normalisation in 2H.
Net Interest Income is a tailwind to profits as well. We raise our FY24E Adjusted EBITDA by 7%.
Equals is valued at c.22x 2024E EV/EBITDA at the current non-binding proposal price of 135p, after valuing NII at 6x PE.
We raise our estimates for strong 1H growth and drop through of NII to profits. The overall business of Equals (including NII) currently trades at c.8x CY24E EV/EBITDA, a premium to its closest cross-border payments peers. We believe that near-term share performance is contingent on the result of the ongoing strategic review. The next PUSU deadline is 7 August. We retain our Hold rating with an unchanged TP of 160p.
Given the likely trajectory of the economy, I'm more than slightly surprised to see a greater than 20 % pullback to Billington Holdings (LON:BILN) over the last few weeks ... giving a chance to buy just above the 200 day m.a...... definitely one that I have got wrong short term, expected it to out perform...
Hi Cancun. Thanks for highlighting Billington Holdings (LON:BILN). I agree with your logic and it ticks all my boxes. SR over 90, super stock and testing significant resistance. There is also positive divergence on the RSI. I’m not an expert on Eliot Wave theory but it looks like a wave 4 test at the top of wave 1.
The only concern is that a director sold a significant holding recently at 460p.
However, I like buying quality at what looks like a turning point so I’ve opened a position. Stop loss if it loses the 200dma. Buy more if the MACD crosses upwards.
PS I can’t find Paul and Grahams opinion on Billington Holdings (LON:BILN) . I’d be surprised if it wasn’t green
Hi Revs8, The last report for Billington Holdings (LON:BILN) was on the 22nd March and was amber/green. Cheers
"I can’t find Paul and Grahams opinion on........"
There seems to be a problem with people finding their way around Stocko as highlighted separately this morning by Ken Mitchell regarding posts other than SCVRs.
Anyone creating a post is asked to flag individual shares and/or topics and Paul, Graham and Roland are very good at doing that.
In the case of a particular share all you need do is click 'Discussions' on the Stock Report page:
In the case of Billington you will find no less than 13 SCVRs going back to 2014 plus all the other posts you've never heard of because you only go to SCVR. For long term readers there is a touch of nostalgia here with the predecessor of Mr. C - matylda's I Read The News Today Oh Boy!
https://www.stockopedia.com/sh...
I've been considering buying into Billington Holdings (LON:BILN) What put me off were two things, one there was no trading update with their AGM this year, whereas last year they did issue a trading statement at the AGM. Also from a technical point, it's just broken downwards through a trendline on the weekly chart. Stocko ratings are very good and the founder still has 20% despite the recent sale. I've set an alert for when the price reverses higher.
For Paul’s occasional award of Worst Presented Trading Update may I nominate today’s statement from Ricardo (LON:RCDO) ( I hold). The actual performance of Ricardo may or may not be satisfactory, but the statement is, intentionally or not, obfuscatory and confusing.
There is no sequential flow, the numbers appear arbitrarily, interspersed with percentages, compared to forecasts that are not referenced . There is no table to compare years for key financial numbers and most of these are, I think, not mentioned.
SEC Newgate are the PR firm charged with this mess, and either they promoted it or failed to stop the management letting this be published. It does not reflect well on either party.
Ukrainian iron ore pellet producer Ferrexpo (LON:FXPO) share price, (up 12% to 61p just now) has responded well to their surprisingly resilient Results today.
https://www.stockopedia.com/sh...
Some signs of a peace deal has already seen the share price bounce. The share price peaked at around £4 well ahead of the Russian invasion.
I sold immediately after the invasion but bought back recently on those peace hopes. The share price will likely rise fast if serious peace talks take place, or on a Trump win as investors buy hoping he is able to carry out his pledge to bring the War to an end very quickly. I wonder! And if the war ends then upside potential is huge as Ferrexpo was a big dividend payer before the war.
The Executive Chair’s comments pasted below are an interesting example of how well Companies seem to be able to adapt to near impossible situations, with covid another example. That comment is also revealing on how Ukraine itself is managing to adapt. e.g electricity supply.
“Ferrexpo continues to demonstrate resilience, retaining the entire workforce during a time of war, whilst increasing production and ensuring exports to our customers around the world. The significance of our operations has never been greater to our people, local communities and Ukraine.
From a corporate perspective, we are adapting to the complexities of a prolonged war. We have learnt how to operate a large-scale business more nimbly, embedding flexibility into our operations and working practices. This means that we are able to adapt to the constant challenges that confront us. With access to Ukrainian Black Sea ports returning during the period, we were able to respond quickly, bringing idled production capacity back on line and exporting to our customers via seaborne routes, thereby achieving our best production result since the start of Russia's full-scale invasion.
Revenues and EBITDA also improved in the first six months and underscore the extraordinary effort and commitment of our workforce. 8,000 people, across every business function, co-ordinating their skills and expertise, time and resources, to realise these tremendous results. The fact that we can achieve so much in such challenging conditions is testament to our resilience and perseverance today, and in the future.
During the period, we deployed cash to increase production and preserve the integrity of our assets. Nevertheless, despite adding volume and lowering our controllable unit costs, we must accept that we are operating in an environment where lower iron ore prices and significantly higher electricity prices put pressure on our margins. It is therefore pleasing to note that we were able to end the period with a modest increase in our net cash position.
For the remainder of the year, we will focus on optimising current production levels. We remain hopeful that domestic electricity supply will improve during the third quarter when power plants that were shut for maintenance come back on-line.
Since the start of the full-scale invasion, we have demonstrated our ability to operate flexibly and adapt to ever changing circumstances. I am confident that should we see an opportunity to benefit from changes in iron ore pellet prices, we will adjust our production accordingly."
Does anyone have any insight as to what is going on with Amedeo Air Four Plus (LON:AA4) ? Stock has been on fire the last few sessions.
Have a look at the Investment Trust Board - both the Charles's discuss it regularly and I think there was a big discussion yesterday.
Thanks Kevin
Tipped by Simon T. at Investors Chronicle . See comments on the trust board https://www.stockopedia.com/co...
That’s much appreciated Charles. I was struggling to find the link on Stocko. Thank you.
Simon Thompson write-up in the IC.
Simon Thompson at IC gave it a thumbs up?
Simon Thompson tipped it again I missed getting back in
recommended by Simon Thompson investors chronicle
Genedrive (LON:GDR) market cap £20m with £6m net cash (I raised here recently). Their stroke test was recommended by NICE in guidance released today. This was expected per the draft guidance but is a major validation of their platform and opens up a £100m initial market opportunity for GDR which has the best point of care test available. They’ve also been given fast track novel device status in the US for their other test that checks suitability of an antibiotic given to newborns who can suffer hearing loss if they’re susceptible. In total the market opportunity exceeds £300m.
With two approved and unique tests addressing large unmet clinical needs and a strong cash balance I feel this is excellent risk/reward. There is a clear commercialisation plan and demand for their products. Even a 10% market share at 25% margins would generate £7.5m. Multiple of 15 = £115m, five times the market cap. All back of the envelope and clearly commercialising new medical devices is a bumpy path. Initial market reaction was a 30% rally but that’s given way to profit taking and now only 10% up today. I feel this is an excellent entry point and that these could double or triple over the coming weeks. Not a recommendation and obviously a risky play but I do feel that the NICE guidance and FDA award are very supportive of the quality and need for the tests.
I should add that I hold (in case there was any doubt!) and have added more today.
Maybe on Genedrive (LON:GDR) but it has a horrible history of great product and zero commercialisation.
I’m afraid I got burnt on it which mars my view and of course they only now have cash because they diluted their long suffering shareholders badly, which they’ve also done multiple times btw so no guarantee this is the last.
Until they demonstrate they can actually grow revenues exponentially from a tiny base then I’m afraid their very poor track record takes precedence for me. there has always been a lot of fanfare about their tests but each time it has fallen badly short - until people are actually prepared to pay for it and repeat order it’s a definite no go for me. Of course that doesn’t mean it won’t go up - I should probably have taken up the recent offer and averaged down for a trade but despite the NICE recommendations I just don’t trust them to ever make any money.
All fair comment. I am certainly not backing them to their ultimate success. I do however think that the risk adjusted valuation is very low and I like the share price momentum and traded volumes which in my experience tend to indicate further gains in the short term. Not in all cases though !!
Reach (LON:RCH) doing what it says it will be doing, whilst revenues are down, excellent increase in profit and more importnantly, data drive digital revenue starting to take off. Still holding.
I do feel that once Reach (LON:RCH) can show the expected significant drop in actuarial deficit on the pension it re-rates. Can see 50-100% upside personally so I quite like it.
Not a normal one for the board but Arrow Exploration (LON:AXL) really are doing some incredible things and the news today is again superb. It was flagged in a SCVR report (comments) a few years back so thanks to whoever that was! Their 1st horizontal well has produced some incredible figures, and has paid for itself in 30 days. FCF is something to behold. Worth taking a look at the latest presentation to get an idea of the scale of things and future trajectory.
long time holder of Arrow Exploration (LON:AXL) . their success with the drill bit is impressive. pity SCVR don't cover small cap oilers.
Hi SmallCappy
We could always set up a separate thread for Oil and Gas like Charles Mitchell has done for Investment Trusts or Wolf has for his Summer Strategy Stage 2's. Not sure there would be enough interest or anyone prepared to take it on. Perhaps those who would be interested in such a thread could like this post and we'll guage level of interest?
Like you I hold and believe Arrow Exploration (LON:AXL) is likely to do very well this year. I'm hoping for 50p by year end though that may be slightly optimistic. These Horizontal wells they are currently drilling from the established pad are classed as development not exploration and their success seems to be a given, if anything ever is in O&G.
If the next exploration well on the Baquiano hits could give them an even longer development runway. Exciting times.
In contrast the sp performance at Petrotal (LON:PTAL) has been rather disappointing. Fabulous divi and continuing drilling success offset by extra spend on erosion control and concern over variable Amazon river levels. They seem to have built the latter into their forecasts and are developing additional export routes but the market doesn't seem to be impressed. Another potentially worth double the current sp? And without the idiot Milliband to cause the chaos he is reeking in the North Sea.
Hi sevenccc,
A separate thread would be good if there was enough interest. I3 Energy (LON:I3E) are another small cap oil & gas company in that space worth doing a bit of research on. They've diversified their earnings away from the North Sea and the crazy EPL levies wreaking the industry here to Canada. They still hold a NS license (Serenity) that's not being developed just now and have a portfolio of large acreage's in some of the best oil and gas producing areas in Alberta.
This is all from memory so it's worth checking the details for yourself but production levels were roughly ~ 19 - 20k boe/day with the mix slightly weighted to the gas side for now. Recently they sold off some royalty interests wiping out their debt and now have better finance terms in place with a tier one Canadian bank to draw on for the planned Q3 & 4 24 & Q1 25 drilling program.
Hopefully the share price is starting to base out of year long downtrend but who knows... Full disclosure I'm happy reinvesting the nice quarterly divi's for now and continuing to build a position.
Hi UncleG
With you on I3 Energy (LON:I3E) . Have been in that one before and fortunately sold out somewhere along the long way down - can't remember where so won't claim any success! Have been looking for a suitable entry point and felt I'd missed it 2 or 3 times in the last few months but here we are again around that 9.5p mark. Every time the AECO gas price looks like it might be about to make the upward move forecast with the Canadian West Coast LNG developments it seems to lose traction again.
On other BBs there is significant dissatisfaction expressed at their capital allocation. I sense they know they missed a trick this year but have a decent plan in place for the next 18 months. The worsening annual Wild Fire seasons don't bode well, especially for flammable fuels in their path! Do think the Canadians need to think hard about reducing and eventually closing down their revolting and highly polluting Oil tar sands business. Unfortunately the Calgary powers that be seem even deafer than Trump and Co with little care for the world. Should this change a move toward gas would be a big step forward and hopefully at some point the likes of I3E will be beneficiaries.
Like divi here and would expect to see the sp move back up through early 25 but how much and when always difficult to judge.
Thanks sevenccc,
Hopefully the AECO improves in time and they can target the right commodity mix to improve production volumes in the near future. Totally agree about I3 Energy (LON:I3E) skipping a beat this year and think they know it too. At least on the bright side though they managed to improve the balance sheet during that time to support future endeavours.
Hi Sevenccc,
I agree a new thread on oil and gas plays (similar to the Trusts thread) would be useful and would enhance the stocko’ community for those interested.
I don’t have the time and technical know how to set it up but would gladly vist and contribute.
I hold Serica Energy (LON:SQZ), Petrotal (LON:PTAL) and Diversified Energy (LON:DEC) as I think we will be using oil and gas for a while and other countries and communities even longer.
Graham.
Be interesting to see if there is any comment on International Personal Finance ( IPF ). Cracking interims and with a Stockrank of 99.
You won't be disappointed!!
Agreed. You don't often see figures as good as those published by IPF today. The only possible negative was Poland where I had hoped for better than "beginning to stabilise" but that apart absolutely crackerjack..
I had a look at this it its certainly interesting - it would have been nice to see a higher level of Director holdings - CEO has just over 1% and that is the largest insider holding
Thanks Stoph,
For highlighting this one this morning.
l checked it out and was impressed with the results and the company comments and bought in before Graham’s brilliant interview notes. The only danger I can see is the situation with Poland but they seem to be sorting that out ok at the moment.
They also pay a large dividend, with a policy to significantly increase it each year, which also supports their growth. So I think if they keep producing great results, this one could really pay off.
Graham.
Half year results out of Conduit Holdings (LON:CRE) today, my largest individual holding.
In summary:
Income +25% at £76.4m net
NTA £5.21 v £4.46 (+17%)
EPS +26% 48.4p
Divi unchanged at 14p
Combined ratio 75% v 72%, so a little worse but still excellent
Investment return 1.5% v 2.1% due to lower interest rates
In summary, a solid return, a company trading at a fraction over NTA. I read this as a vehicle being built in order to be sold. A strong Hold for me. Always a risk of miss-pricing a risk, but a very experience management team of Brits, on big options and holdings.
It’s NTA progression that I look for; it’s the ultimate measure of performance.
The rating environment is still good, but not absolutely exceptional. Lower interest rates are unhelpful to this industry due to lower investment returns and greater capital availability, in my opinion.
Other views valued by me………
Re Conduit Holdings (LON:CRE)
I had not thought about build to sell but the main guys in charge have done that before so good shout. Also I remember a few years ago companies like Catlin and others getting taken out as there was lots of capital chasing good returns in this sector.
Two other plus points are that they only have one office so easy communications and the fact that staffing is up to the mark now so very little extra cost to increase revenues which leads to net growth. And of course no tail.
I see they are concentrating on property where the market dynamics are robust and being very wary of catastrophe which having seen them present a few times fits their character.
Shame though that an extra cent or two of dividend did not arise, but caution against the next big claim is also sensible. Good yield though.
Surprisingly I hold and have added recently - now in my Top 10 along with Beazley (LON:BEZ)