Small Cap Value Report (Wed 4 Sept 2024) - DAL, GMS, CRW, ECEL

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 26/8/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
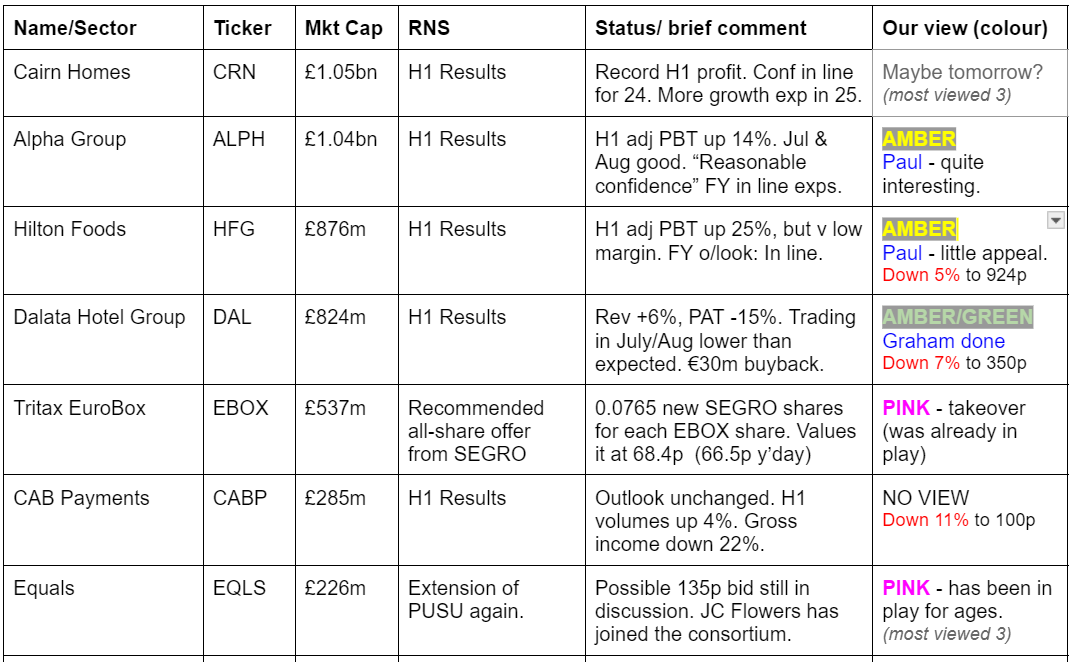
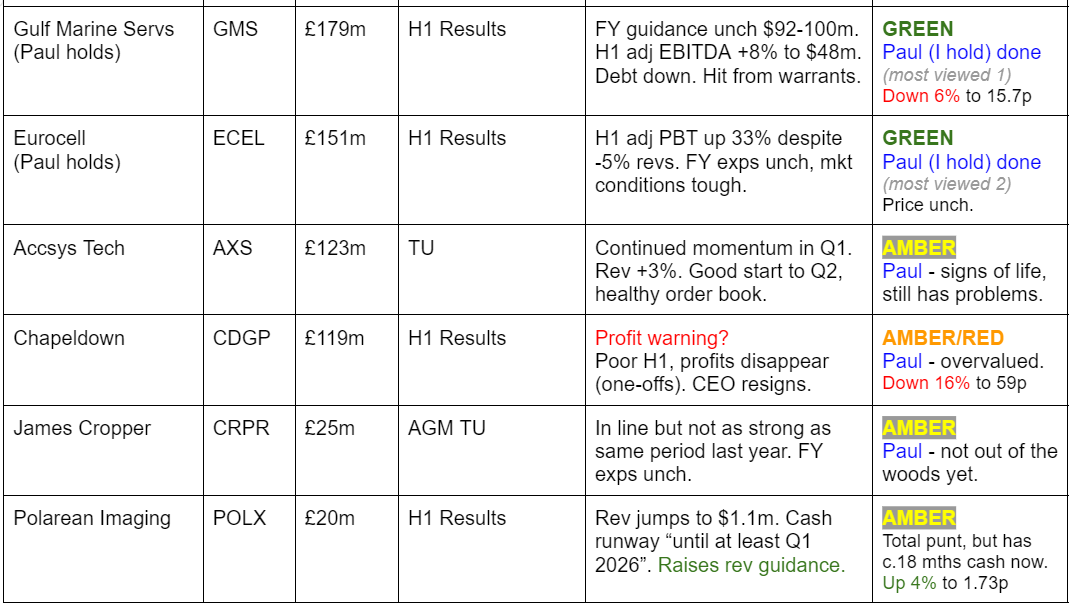
Summaries
Dalata Hotel (LON:DAL) - down 4% to 351p (€930m) - H1 Results - Graham - AMBER/GREEN
This hotel group has seen some softness of demand in July/August. Taking a bigger-picture view, however, the company is still earning respectable profit margins despite the challenge of payroll inflation and inflation more generally. UK growth plans are rolling out and the shares offer a material discount to balance sheet equity. This one seems worthy of further investigation to me.
Gulf Marine Services (LON:GMS) (Paul holds) - down 6% to 15.7p (£168m) - H1 Results & Changes re Seafox - Paul - GREEN
More developments with the overhang from major shareholder Seafox. However, I think the more important thing is that trading continues to be strong, and in line with expectations for FY 12/2024. Deleveraging is proceeding well, and new bank facilities are agreed (but not yet signed). Very good visibility with a growing contracted order book that looks sufficient to give a clear run of 2-3 years more prodigious cashflows, which should eliminate net debt altogether, or enable divis, reinvestment, and some debt reduction. I remain bullish.
Craneware (LON:CRW) - £21.96 (£788m) - Management Q&A - Graham - AMBER
Please see below for the notes I took during my management call with this highly-rated software business serving the US healthcare industry.
Eurocell (LON:ECEL) (Paul holds) - unch 145p (£151m) - H1 Results & Buyback extended - Paul - GREEN
Tough sector, but adj PBT for H1 is actually up 33%, despite revenues down 5%. That's due to careful management, and some reduced costs. Lovely balance sheet, and strong cashflows have enabled both generous divis and buybacks of c.10% of the shares. Lots to like here, with a modest valuation, and sector recovery upside in for free. I remain keen GREEN.
Paul's Section
Eurocell (LON:ECEL) - Paul holds
Unch 145p (£151m) - H1 Results & Buyback extended - Paul - GREEN
Eurocell plc, the market leading, vertically integrated UK manufacturer, recycler and distributor of PVC window, door and roofline products, today announces its results for the six months ending 30 June 2024.
Given that we know the housebuilding & building materials sector generally is in the doldrums, I was expecting weak numbers from Eurocell. However, it has surprised me on the upside, with a 33% increase in adj PBT from £6.0m to £8.0m in H1 2024, despite revenues being down 5%. It says this is due to reduced input costs. There’s also been self-help by ECEL, which reduced overheads very quickly when this downturn started a while ago. I find this encouraging. Adjustments are small this year.
Dividends & Buybacks - H1 divi is raised 10% to 2.2p. In 2023 the divis were split 2.0p H1, 3.5p final. Assuming both rise 10% this year, then I make that c.6.0p, providing a yield c. 4.1%. Whereas Stockopedia is showing a forecast yield of 6.0%, which is partly explained by it blending 2024 & 2025 forecasts, but also suggests to me that maybe the broker consensus data might be picking up an unrealistically high forecast? We don’t have access to any broker notes, something ECEL clearly needs to address.
Buybacks have been large - £10m done in H1, and announced today a further £5m. Total thus £15m, which is 10% of the market cap of £150m! Very significant, and a great use of cashflow in my view, whilst shares are cheap. Remember it’s doing this at the (probable) bottom of the economic cycle for the sector.
Outlook for FY 12/2024 -
“Trading conditions continue to be tough in 2024, with ongoing macroeconomic uncertainty impacting our key markets, exacerbated by wet weather and the General Election. Customers remain cautious, resulting in lower investment in home improvements and subdued activity levels in the residential construction market. As a result, H1 sales were 5% below H1 2023.
However, first half adjusted profit before tax was up 33% on H1 2023, as we continue to proactively manage our gross margin and cost base, which has supported a reduction in input cost pricing, and our expectations for the full year remain unchanged.”
"Earlier this year we launched our new strategy, which identified a pathway to building a £500 million revenue business, generating a 10% operating margin, over a five-year period. We have good early momentum with our new strategic initiatives and are becoming increasingly confident that, whilst this is an ambitious target, it is achievable.
"The UK construction market continues to have attractive medium and long-term growth prospects, driven by the structural deficit in new build housing and an ageing housing stock that requires increased repair and maintenance. Overall, we believe the progression of our strategy, together with the actions we have taken on cost and cash flow over the last eighteen months, leave the business well positioned to drive sustainable growth in shareholder value."
Adj basic EPS was 5.6p in H1. It’s not clear from the historic data whether there’s a settled H1:H2 trading bias, as the pandemic messed up all the numbers. 2023 showed a strong H2 bias to profits. The broker consensus this year does this too, pencilling in 14.8p EPS For FY 12/2024. Hopefully that’s the same number that ECEL are working on too - this is where a footnote in RNSs is so helpful, clearly stating what numbers are expected. That’s missing here.
Anyway, assuming that 14.8p FY 12/2024 estimate is accurate, I get a PER of 9.8x which looks good value.
It’s expanding too -
“Branch network expansion: locations identified for 8 new sites, with 2 to be opened in Q4 2024 and 6 in Q1 2025”
Balance sheet - is really strong, as I’ve mentioned many times before. NAV of £106.8m becomes NTAV of £91.6m after eliminating £15.2m of intangible assets.
There’s a little freehold property, £6.9m at end 2023, with most of its sites leased.
Working capital is healthy, with a current ratio of 1.58x, and negligible long-term debt (excl leases).
Overall net bank debt is only £4.3m, improved a lot from £15.2m a year earlier - despite the generous divis and big buyback. That’s been achieved by tight control of working capital - with inventories and receivables both nicely reduced vs a year ago, but trade creditors unchanged. Note that cashflow might deteriorate as sector recovery begins, as cash is likely to be sucked back into working capital.
Cashflow statement - is strong, but remember the lease cash outflows are about £8m in H1, and these appear low down in the statement, so we have to adjust those out of the higher numbers to get something vaguely close to commercial reality!
Paul’s opinion - this strikes me as a well-managed, good quality business. It looks like the sort of thing where management have taken sensible actions to make the business more efficient during this downturn. That could really pay off once demand recovers. Finances are strong, cashflows good, and the shareholder returns have been tremendous, especially the buybacks of c.10% of the company (including today’s newly announced additional buyback of £5m). That will nicely enhance future EPS.
I only have a tiny scrap of shares currently, but ECEL is right up there on my wishlist of positions to add to, in advance of a sector recovery that looks likely in 2025.
What’s it worth? I wouldn’t be surprised if the share price starts with a 2, not a 1, in say 2025 or 2026. And it’s paying decent divis whilst we wait. It’s got to be another GREEN from me.
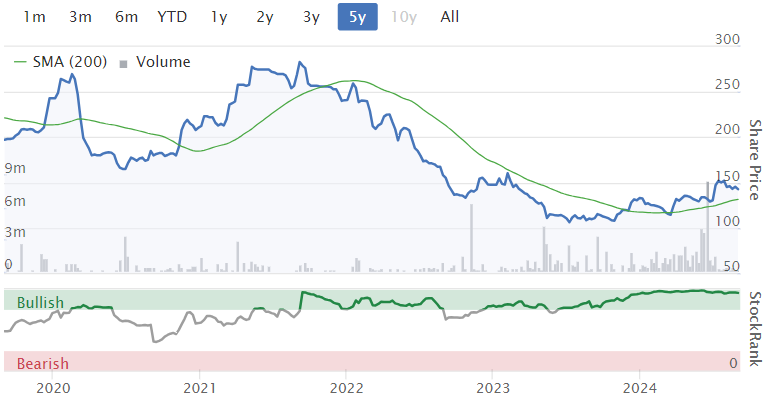
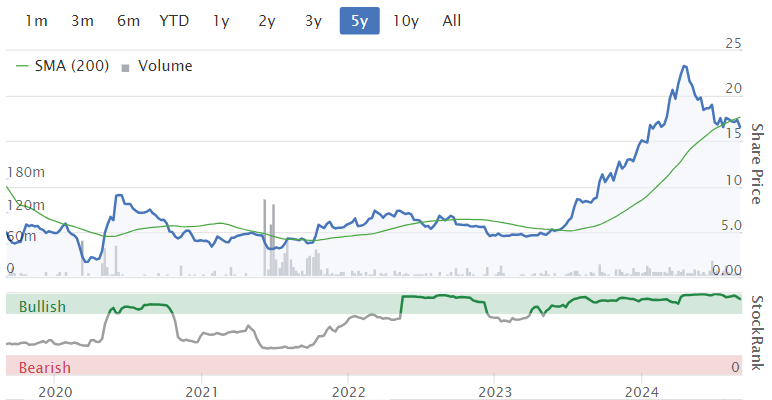
Chartists can tell you more, but this looks like it's bottomed out, and is now in a fresh uptrend, and above the 200-day moving average. StockRank almost jammed on maximum too, so we've got our proverbial mallards neatly lined up!
Gulf Marine Services (LON:GMS) (Paul holds)
Down 6% to 15.7p (£168m) - H1 Results & Changes re Seafox - Paul - GREEN
GMS, a leading provider of advanced self-propelled, self-elevating support vessels serving the offshore oil, gas and renewables industries, is pleased to announce its interim results for the six months period ended 30 June 2024 (H1 2024).
There’s no company headline, it lets the key numbers (in US dollars) do the talking!
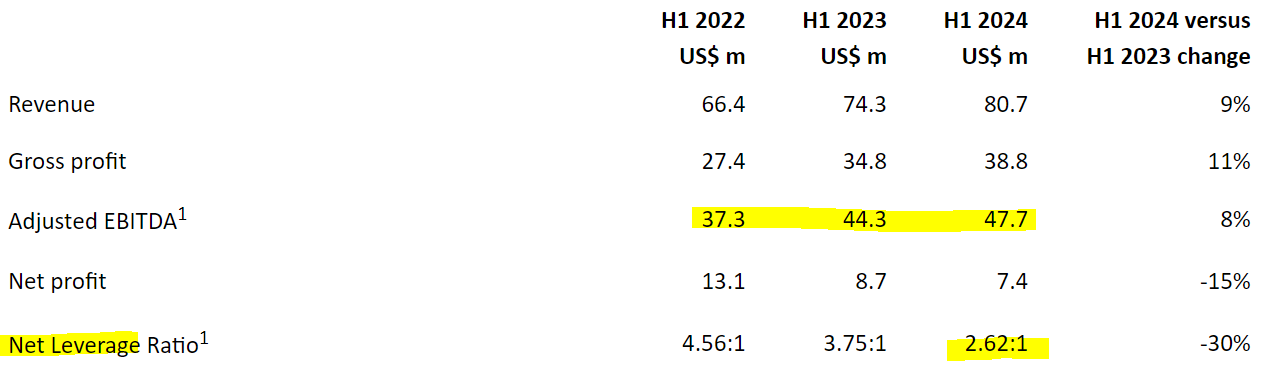
These below show an upward trend in EBITDA, a high EBITDA margin vs revenues, and impressive deleveraging at the last 3 years half year ends -
Key metrics -
Average daily hire rate - up 7% to $32.4k, reflecting strong demand and an industry shortage.
Utilisation rate - fell slightly from 93% to 91%, which reflects “planned downtime for maintenance”.
The large fall from $47.7m adj EBITDA to only $7.4m net profit is due to (as I would expect) heavy depreciation charges on a (still fairly new) fleet of capital equipment. Also there was $12.3m in H1 finance expenses, due to the still high debt load. Although note this is reducing well, down from $17.5m in H1 LY, and of course this will continue falling as GMS continues to quite rapidly deleverage, as well as having secured savings on the interest rates due to achieving more favourable leverage ratios.
Note there is also a $7.5m P&L charge for fair value of derivatives. Note 17 explains this. It’s warrants that GMS had to issue to lenders, as part of a deal in early 2023. The warrant holders could opt to subscribe for 137.1m new shares at only 5.75p (now a big discount to the 15.7p share price). The last date to exercise is 30 June 2025, and being well in the money, we should expect all the warrants to be exercised before the deadline.
The P&L charge is a non-cash amount that reflects the discount gained by the holder of the warrants when they’re exercised, with 53.5m shares having been issued in H1 out of the 137.1m total possible. It’s complicated by the fact that instead of being the usual 1 new share for 1 warrant, it’s 1.56 new shares per warrant here. Anyway remember to allow for further dilution at 5.75p when you value this share.
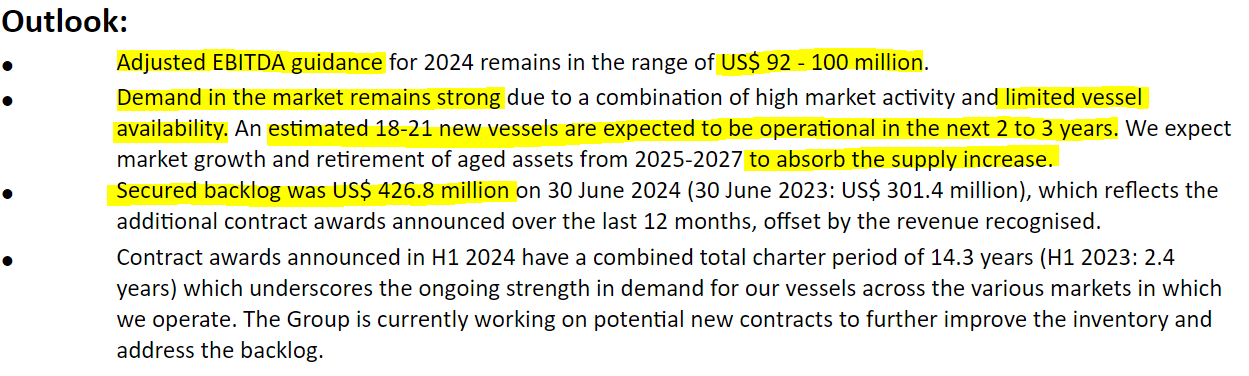
Outlook - this sounds good to me, in particular the growing secured backlog is 2-3 years revenue, nice visibility here -
“Given the Group's improved performance in H1 2024, we reaffirm our adjusted EBITDA guidance for 2024, projecting a range between US$ 92 million and US$ 100 million. This guidance is aligned with our current market conditions and expectations. We are also working on revisiting our EBITDA guidance for 2025 towards year end. Further, our secured backlog improved to US$ 426.8 million on 30 June 2024 (30 June 2023: US$ 301.4 million).”
More outlook detail - point 2 below particularly sounds significantly positive, as I worried about the risk of new vessels coming into the market. It sounds as if customers are locking in the use of GMS’s fleet for several years (at high rates), which should give it time to completely de-gear in c.3 years’ time, which I find highly positive. Longer term, there’s the obvious risk that rates and utilisation may drop back again, but since the debt should have been paid off by then, I don’t really care about that.
Balance sheet - is fine now I think. NAV $349m is nearly all tangible, apart from $14m of capitalised “dry docking expenditure”.
Note all the bank debt is shown within current liabilities, because renewed bank facilities (previously RNS’d) have been agreed but not yet finalised. Let’s hope nothing goes wrong there, but it shouldn’t do, as GMS is now a vanilla borrower with normal level of leverage, demonstrating prodigious cashflows which are enabling it to repay debt fast, and ahead of schedule. So I imagine plenty of lenders would be happy to lend on reasonable terms. I covered its refinancing here on 1/8/2024. Today it says -
“This potential transaction is commercially approved by all parties and the contractual arrangements, currently in progress, are expected to be finalised within the next couple of months. Management is confident that the deal will be signed consistent with the agreed term sheet.”
Going concern statement assumes that the bank facilities will renew, and will be sufficient.
Paul’s opinion - rightly or wrongly, I’m comfortable that the selling overhang is probably creating more of an opportunity than a threat in the medium term. There is a good argument though that Seafox are experts in this field, and want to exit, which could be a warning. However, there could be any number of reasons why Seafox want to move on, and handing over GMS shares to their own shareholders could create an overhang, or it might not, we don’t know.
For me the key point is that GMS is a deleveraging situation. It’s making excellent progress, and with such good (and growing visibility) on the order book, there’s a clear line of sight to it being debt-free in 2-3 years. I think that’s quite exciting, as the cashflows could then be used to start paying potentially big divis. There’s useful additional detail in a note from Zeus today, covering these points. A dividend policy of 20-30% of PAT plus buybacks is mooted.
Overall, I’ve no idea what the short-term share price will do (it could be choppy if the in specie holders try to sell), and my hunch is there’s probably not a great rush to buy more of these. That said at £168m market cap, any overhang of shares could be taken out in one fell swoop by an institution of even moderate size. Hence I don’t want to wait too long, to try to be too clever on price, before adding to my existing (small) position in GMS.
For me it’s clearly another GREEN. This is one of the best cashflow/deleveraging shares I’ve seen for a while.
In a separate announcement today -
Seafox changes - Seafox is the largest shareholder in GMS. It caused a problem when it did a secondary placing of 51m shares (about one sixth of its total holding, reducing from 28.5% to 23.7%) in late June 2024, which I reported on here. The problem was that it accepted a 15% discount, selling at 17p, when the share price was 20p. That, combined with a very short lock-in of only 75 days (from 30/6/2024) gave the distinct impression that the remaining Seafox holding was probably now best viewed as an overhang, casting a shadow over the share price. That could be viewed as a problem, putting downward pressure on the share price, or a buying opportunity given that GMS has been trading well and deleveraging.
Today’s news is that Seafox’ Chairman Hassan Heikal is stepping down as Seafox’ representative on GMS’s board (Deputy Chairman at GMS). There’s some interesting background about Seafox today -
“Mr Heikal's appointment to the Board followed a period of shareholder activism, commencing in 2019, during which Seafox became the Company's largest shareholder and which led to changes in the composition of the Board, including the appointment of Mansour Al Alami as Executive Chairman. These changes led to the financial restructuring of the Company. Seafox also participated in the June 2021 capital raise, maintaining its proportionate shareholding, which further enhanced the Company's capital base. As a result, EBITDA grew significantly, and the Company was able to substantially deleverage which has repositioned the Group to its current sustainability. “
Since this RNS has been written by MAnsour Al Alami, who was put in charge of GMS by Seafox, it’s not surprising that he speaks highly of Seafox, who for whatever reason now seem to be trying to further exit from their GMS position.
Seafox distribution - Seafox announces today it is giving 150m of its c.254m shares in GMS to its own shareholders as an in specie dividend. In specie means transferring an asset in its current form, ie not selling it for cash (as I’ve just been informed by google!) -
“distribute 150 million of the shares that it owns in the Company pro-rata in the form of an in specie dividend to Seafox's shareholders, which include prominent family offices, such distribution to take place on or after the 15th of September 2024”
The remaining 103.7m holding in GMS by Seafox is loosely retained -
“ retain (directly and through its subsidiaries) the remaining 103,686,385 shares in GMS (representing a 9.69% equity interest in the Company). Whilst acknowledging that circumstances can change, Seafox has confirmed that it has no current intention to make further disposals in the short-term, given the positive outlook for the Company.”
Those two changes suggest to me that there’s likely to be an ongoing overhang of sellers in the market, as it stands to reason that some of the new shareholders may not necessarily want to keep their GMS shares. Although an optimist might conclude that the new shareholders might like the obvious attractions of GMS shares, and be follow-on buyers in the market, we just don’t know. Long-term it won’t matter anyway, as short-term considerations like this give way to the company fundamentals longer term.
I reckon GMS shares would be much higher if it hadn't been for the clumsy selling by Seafox in late June. So GMS is one for patient, unflappable investors.
Graham’s Section:
Dalata Hotel (LON:DAL)
Down 4% to 351p (€930m) - H1 Results - Graham - AMBER/GREEN
Continuing the hotel theme we’ve been looking at recently, let’s take a look at the interim results from Dalata.
Dalata is “the largest hotel operator in Ireland, with a growing presence in the United Kingdom and Continental Europe”.
One of its brands, Maldron, hit the headlines a week ago when customers complained that their bookings for Manchester at the time of the Oasis concerts had been unfairly cancelled. Maldron said that a technical error resulted in more rooms being available for booking than were available, and denied any wrongdoing.
Let’s check out the interim results to June:
Revenue +6% to €302.3m
Profit after tax down 15% to €35.8m
RevPAR (revenue per available room): +1% to €110.77.
RevPAR is the combination of room rates and occupancy.
There’s an important difference between Dalata’s performance and PPHE Hotel (LON:PPH) (covered recently). PPHE has seen room rates (i.e. average prices) decline, but occupancy has increased.
Dalata has seen the opposite. Its room rates are up 2%, while its occupancy has reduced a little..
The result is that Dalata’s RevPAR has increased in H1. Again this is in contrast to PPHE, whose RevPAR was down marginally in H1.
Inflation in Ireland is higher than in the UK, so Dalata’s greater weighting in Ireland could be a factor in this. Which brings us to…
Profitability: the EBITDAR margin (EBITDA also excluding rents) falls from 40.6% to 39.4%, but Dalata says there has been “excellent progress made reducing the impact of payroll inflation through innovation and efficiency projects, in addition to reduced energy pricing”.
Profit after tax falls by €6.2m; of this €4.2m is adjusting items and the rest is underlying performance at like-for-like hotels.
So it’s important to put the company’s good revenue/RevPAR performance in the context of higher costs and lower profits.
Growth plans: four new UK Maldron hotels opened this summer. Three leaseholds, one freehold. Four other projects in progress. “Considerable financial firepower to fund plans for further expansion in the UK, large European cities as well as maintaining our market share in the larger Irish cities.”
Dividend/buyback: the company announces a small increase in the interim dividend, and a €30m buyback. This buyback is much larger than what we saw at PPHE Hotel (LON:PPH) recently, both on an absolute level and relative to Dalata’s market cap.
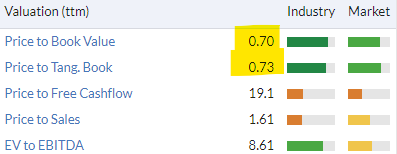
Balance sheet: there is official balance sheet equity of €1.4 billion (almost entirely tangible), a more than 40% premium to the market cap. The company is carrying financial net debt of €228m, plus leases.
Outlook contains some bad news. Trade was “lower than expected” in July/August, with RevPAR up by just 1%, due to “more measured consumer spending”.
Some of the detail:
Demand from corporate and international visitors remains strong but we are seeing a softening from more cost conscious domestic customers relative to last year. We continue to see periods of good leisure demand around events. As we look ahead to the balance of the year, we expect these recent trends to continue. The events calendar for the remainder of 2024 looks strong particularly in Dublin. In addition, the impact of the 4.5% Irish VAT rate increase will be fully absorbed from 1 September 2024.
Graham’s view
I have a generally favourable view of Dalata. One thing I’ve noticed is that leasehold assets are more important here at Dalata, compared to PPHE Hotel (LON:PPH). It’s just a slightly different business model, but I do prefer the PPHE emphasis on freeholds.
Also, the valuation at Dalata involves a smaller discount to balance sheet NAV, compared to PPHE which strikes me as more of a bargain.
At this stage, I’m most comfortable taking an AMBER/GREEN stance here. The company is managing the challenge of inflation and has well-known, mainstream hotel brands with good growth potential. So I think there’s a lot to like here.
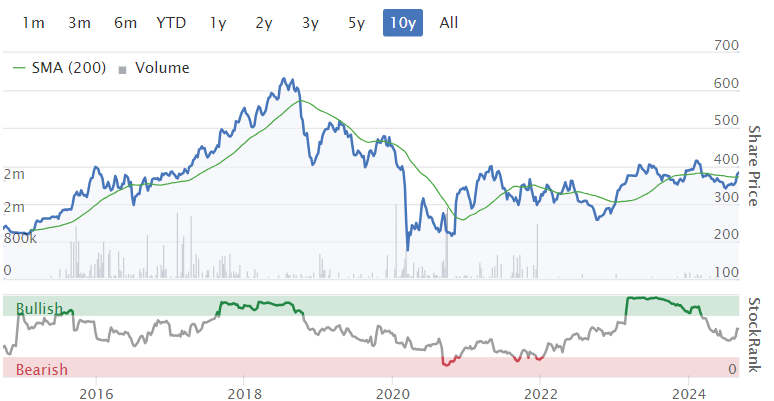
Craneware (LON:CRW)
£21.96 (£788m) - Management Q&A - Graham - AMBER
I had the chance to catch up with Craneware management yesterday, following their full-year results (covered here). Huge thanks to CEO Keith Neilson and CFO Craig Preston for taking the time to speak with me.
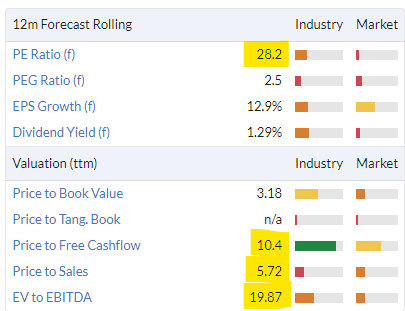
We covered three topics, focusing on the company’s growth potential. I have little doubt that this is a high-quality business, but I wanted to explore if its growth prospects could justify the US-style valuation multiples it trades at.
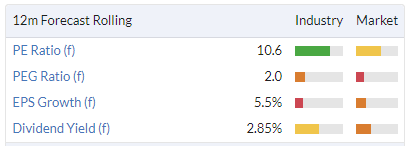
A reminder of these multiples:
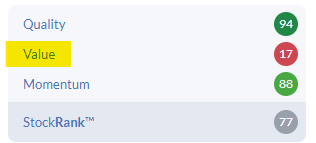
The StockRank has noticed that it trades expensively:
Q1. How important is the 3rd-party use of Craneware’s data when it comes to achieving double-digit revenue growth?
A. Craneware hasn’t emptied the tank yet in terms of revenue growth. When it comes to the 3rd-party use of Craneware data (that has jumped from $1m to nearly $14m over the past year), note that the users of this data have generated higher revenues on top of that, and the end-customers (hospitals) have generated much higher cost savings as a result of this activity. Under the “Shelter” programme, hospitals have enjoyed over $250m of benefit that can be reinvested into care. This is scalable, going forward.
An important change over the past six months is the hiring of an SVP of strategic partnerships. The person hired for this role has great relevant experience, e.g. with Oracle deals and with the NHS outsourcing of salaries.
Craneware’s underlying business is growing. c. 90% of revenue is recurring. Underlying sales growth is more than 10% and this will translate into ARR and ultimately revenue growth.
Q2. Can we have more detail on the relationship between Craneware and Microsoft, how you are working together and how this leads to development/innovation?
There are multiple layers to the relationship. Firstly, Craneware has a consumption commitment with Azure, meaning that it has a discount on the computing power it buys from Microsoft.
Secondly, customers are able to purchase Craneware software at a discount, when they use their own consumption commitment on Azure.
Thirdly, Azure is used as a platform for sales. Microsoft is bound to promote Craneware products and will promote it e.g. to the CIO of hospitals, opening up new partnership opportunities.
Fourthly, Craneware enjoys “unified support” from Azure. If there is ever a problem, Craneware products will see very little interruption due to the premium support provided by Microsoft under this plan. Furthermore, Craneware gets the best help when it comes to Microsoft architecture. This means they get product development proof-of-concept, a desktop review, and can understand if the use of AI will really work.
Q3. Can you talk a little about the importance of the Shelter programme?
Yes, the Shelter programme is an example of how our data can be leveraged for customers and for ourselves. The delta (or the difference it makes) is in the price hospitals pay for drugs. Craneware enables hospitals to understand the timing/quantity of needed drug deliveries and to most efficiently use their distributors, cutting down on waste and saving on storage costs. Drugs can be transported to the right place, at the right time.
An example was that in one hospital system in a disadvantaged area, Craneware enabled $30m of savings plus another $12-15m of annualised cost reductions.
A key differentiating factor between Craneware and other AI/software companies that might want to provide this type of service is that Craneware already has the data needed to do it.
Graham’s conclusion - huge thanks to Keith and Craig once again for talking me through their company’s achievements and plans. I remain a fan of their work and am comfortable with the stance on the stock that I took yesterday.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

89 comments
Just noticed a bid on Balanced Commercial Property Trust (LON:BCPT) - 96p cash. The only return has been through dividends here, so a disappointing investment over the last 10 years or so. https://www.stockopedia.com/sh...
TBF The trading sites hated the idea as being too complicated, nice idea but I don't think it worked in practice
This is very disappointing news. British ISA scrapped. Another u-turn. https://www.cityam.com/u-turn-...
Not as disappointing as when they reduce the ISA allowance to help fill the ‘£22bn black hole’!! I suspect that the various platform providers are being a bit naive in praising this move. They should be careful what they wish for when Reeves outlines her proposals for ISAs and SIPPs in the October budget.
To be fair I found the British ISA idea very unclear and half-baked - as it stood it was unlikely to have any significant impact on revitalising the UK market Ideally the government will come up with something better instead, although not counting on it! What they really need to focus on is the pension market, and trying to divert some of that back to UK equities. Getting rid of stamp duty on UK shares (at least mid and small caps) would be another game changer, but that's probably unlikely.
It was a bit of a nonsense- I could buy a British investment trust with assets in any where in the world. Unless they excluded all Trusts- and private equity- and companies that earned most of their income abroad !
Views on Cairn Homes (LON:CRN) H1 results please. Look very good to me.
Cairn Homes (LON:CRN)
Hopefully Graham, who normally takes a look at Cairn Homes numbers, will have time to do the same tomorrow with the H12024 figures that were released this morning. The growth looks impressive but I do not understand the very large H2 weighting that has been evident for a long time. Why would this be for a house builder? I have checked the UK equivalents and there is no obvious weighting either way, however Glenveagh Properties (LON:GLV) another large Irish home builder has an even more pronounced H2 bias.
Would it be the weather in Ireland possibly affecting construction or something more financial?
If anyone knows I would be very grateful for some insight.
Hi Charles. I used to hold Chapel Down (LON: CDGP) but sold about a year ago - when it rapidly peaked up to about 75p. But this was less good timing and more to do with my sampling the wine itself - I bought one bottle of each type (the basic fizz, the dry white, the rose, the pink fizz, the reserve pink fizz and their flagship Kit's Coty - which I think was going for about £60 a bottle even with the shareholder discount. And I was really unimpressed. I thought they were all pretty ordinary and, for what they were, they were all extortionately expensive. I can get far superior cremant or sparkling saumur from Naked Wines or The Wine Society for less than half the price, and the WS will flog me Pol Roger reserve for less than the Kit's Coty. I wouldn't buy from them again, and I doubt I'm alone. Best wishes and good luck.
Paul
I do hold Chapel Down (LON:CDGP) and enjoy their fizz, for which I am a regular customer. I do not claim to be a tasting expert but their climbing sales and increasing awards (this year’s Wine Decanter “Best in Show”) suggest that not everyone finds their product “unimpressive” . You say that the prices are quite high, but given, as Paul has noted, the lousy business model of buying land and then spending three to five years getting a product, while building enough inventory to carry over bad harvest years, I entirely support getting the business built by keeping your prices as high as the balance of market and production will bear. Only 70% of the land they have bought is now producing saleable product and they have built inventory to 130% of annual sales. I do of course benefit from the 30% discount, but the level of sales has risen far beyond the buying capacity of the shareholders. Cheers!
We must beg to differ on the quality. I would not buy from Naked Wines- but am a member of the Wine Society.
Its frankly incredible how much the hyper-scalers (eg AWS, Google & Microsoft) are spending on AI chips & related hard/software in order to upgrade their data centres (see below - source LinkedIn).
Little wonder therefore that NVIDIA (NSQ:NVDA)'s sales, EBIT margins and shareprice have all rocketed over the past 2 years.
However my hunch is that a large part of this exponential growth has simply brought forward (or stole) a big chunk of demand from future periods, and ultimately won't be sustainable.
'my hunch is that a large part of this exponential growth has simply brought forward (or stole) a big chunk of demand from future periods, and ultimately won't be sustainable'
To quote from the NVIDIA (NSQ:NVDA) web site, 'the NVIDIA Blackwell platform has arrived — enabling organizations everywhere to build and run real-time generative AI on trillion-parameter large language models at up to 25x less cost and energy consumption than its predecessor'.
There have been problems encountered manufacturing the new Blackwell chip at scale, and it may not arrive until next January. However, the improvements in speed and energy consumption will guarantee a substantial take up. Energy consumption is a really significant factor - large data centres require vast amounts of cooling to support their servers.
I think a question that nobody's asking is what is this AI expected to do? Nobody has come up with an answer to that. Generate pictures? That's worth billions, is it, because I don't think so.
I was talking to my mate Dave. He came up with the following quite interesting observation: all these GPU installations seems like a massive overbuild like we had with cabling back in the dot com boom. We might eventually might find some use for all this capacity, but it could come from some unexpected application that no-one has though of.
I personally think AI will fall far far short of expectations. Remember 3D printing, which was set to disrupt manufacturing entirely? Well, it didn't, although it did have some use for niche low-volume products.
AI is not new. We've experimented with it before over decades. Every time it has fallen short. The vodka is good but the meat is rotten. https://en.wikipedia.org/wiki/...
'I think a question that nobody's asking is what is this AI expected to do?'
From an investment point of view, that's irrelevant. The bandwagon is rolling, so jump on it (when the time is right).
I think a question that nobody's asking is what is this AI expected to do?
News today in the FT that a new AI model can massively accelerate cancer diagnoses. The benefits here to health systems are immeasurably large. Think how much money can be saved with simple, early diagnosis, bypassing the expense of dna sequencing, followed by swift life-saving treatment (catching it early) as opposed to years of labour-intensive care and excruciatingly expensive radiotherapy and chemotherapy. Not to mention the longevity and life-enhancing benefits.
There is no doubt that AI can perform certain functions very well. The question is, is the hype justified? I have no idea.
Klarna, the buy now pay later company are already using AI chat bots successfully and have cut employee numbers amongst other things.Admittefly the employee tasks could well be limited in scope and more on the basic level I'm assuming.
Thank you for the Eurocell comments Paul, keen green made me smile. We are holders and were doubly rewarded by the building trade twice today as holders of Cairn too. I would appreciate it being covered tomorrow if time allows. Graham covered it on 29/2/24 and suggested it might be fully valued if it reached £2, it was then trading at 126p. I thought today's results were really good but market reaction was very muted on a down day for shares.
Paul looked at Norcros (LON:NXR) on 18 June 2024 when the price was 212p (£190m) and gave it a GREEN rating
"FY 3/2024 results from last week were in line, and the outlook, but the value metrics are so favourable that I've circled back to it. I'm really encouraged that the legacy issues dictating a low valuation are now small, and maybe even resolved. That leaves a PER of only 6.7x, a yield of 4.8%, and recovery potential. It looks very attractive to me. Although we've been saying that for years and nothing ever happens! So one for patient value investors only."
A summary of his opinion:
(I have bought some today and am hoping to exercise some patience in order to reap rewards.)
The two Mello Autumn networking events have launched and the links and info are on the Mello website
Mello Events – The UKs Premier Investment Events Company
For those who want a loyalty ticket for the anniversary event do book early as there are just 100 available and 57 have gone already. This is the link to the two day Anniversary show
Mello 10th Anniversary tickets – Mello Events
This is the one day London show...
Mello @ LIS tickets – Mello Events
Question on Preference Shares, apologies I know nothing about the differences between normal and preference shares.
So if I take a working example
If I were to buy EJF Investments (LON:EJFI) you are buying at £1.01, locking in a forecast dividend of ~10% with a quantum of risk with exposure to the underlying investments
If I were to buy EJF Investments (LON:EJF0) you are buying at £1.31 stocko is showing no dividend, what is the bit that I am missing here?
Thank you
Tommy
Hi Tommy, If you look at the last publication of their Report and Accounts it states what the difference is under note 10 and 11. The ordinary shares have one voting right each and are entitled to reive a dividend when declared. It would appear that the EJFI.L are ZDP shares. I am assuming that ZDP stands for Zero Dividend Preference shares, The ZDP shares, are explained in note 10 which you need to read to understand it better. On a casual glance it seems quite complicated.
Thank you
Eurocell (LON:ECEL)
The market for building materials continues to be tough. This is reflected in the share prices of companies supplying construction and house building. At some point this will change, but clearly is taking longer than anticipated, certainly by yours truly. Anyway on the basis that circumstances are always changing and the political motivation to address the housing shortage and improve the nation's infrastructure, I bought an opening position in Eurocell (LON:ECEL) .
It announced a further £5m share buy back this morning plus an increased dividend, discounting IFRS 16 debt is negligible and it has aspirations to increase revenue to £500m with a 10% operating margin, ambitious, but at least management under Derek Mapp is on the front foot. Also I am a fan of its recycling of PVC windows that now makes up 33% of materials consumed in production.
Eurocell (LON:ECEL) is an addition to my picks and shovels approach to the UK housing, construction and infrastructure industries that includes Van Elle Holdings (LON:VANL) VP (LON:VP.) Michelmersh Brick Holdings (LON:MBH) Brickability (LON:BRCK) and Sigmaroc (LON:SRC) all bought at or below current prices, fortunately! Hopefully in time this approach will bear fruit?
Incidentally can anyone shed light on why the UK market has fallen out of bed this morning!
Incidentally can anyone shed light on why the UK market has fallen out of bed this morning!
You only have to look at the US overnight for your answer. This fell on poor manufacturing data that was no worse than any of the previous 4 months. But sometimes investors - or more likely high frequency traders - just need an excuse to take some gains. The shift from summer into September - historically a poor month for returns - and the looming election won’t have helped.
I am a bit baffled, Jonno. Why invest in six different small cap stocks in the same sector? Surely this must lead you to one of two possible outcomes; too many holdings in a balanced portfolio or a risky bias towards one sector? Of course this is your prerogative, but I'm just curious as to why you want all of the above? For example, why hold both Michelmersh Brick Holdings (LON:MBH) and Brickability (LON:BRCK) ?
Hi Sparkler, a good question. The common theme is that all the companies mentioned supply the housing, construction and infrastructure industries. However if u look under the 'bonnet' you will find that apart from that and the share prices being depressed and as a result the investment metrics being attractive, they are all very different.
I am time constrained at present, but will reply more fully when I get home.
All the best
Gulf Marine Services (LON:GMS)
Hi Paul thanks for your comments today on GMS I almost jumped in this morning but was surprised to see the price drop on what looked like good news. Net Profit is probably the main issue here for those that haven't dug in as deeply as you in their analysis. Your analysis unpicks nicely a relatively complex situation, I totally agree the fundamentals look great and wonder whether Seafox is just cashing in on the x3 jump it has already received and if they are passing on shares rather than cash as dividend maybe their free cash is under pressure for one reason or another. I am going to continue to watch this one and jump in when I see it settle the Market could be fairly depressed anyway until we know what Labour are going to do with CGT.
Gulf Marine Services (LON:GMS) I Hold
I second that Archer. I have not come across this situation before and Paul has made sense of it all - thank you Paul!
Whilst this strikes me as a bit of a bump in the road, the revenue visibility, free cash flow generation leading to debt reduction does look like a fairly compelling case. I will add to my position at some point but I think I might wait until after 15th September when Seafox's GMS shares are distributed.
On another point, I do like the layout and clarity of the table comparing this year's 6 month's results alongside the previous two 6 month periods, giving a clear picture of where things have been and are heading. It would be nice to see other companies adopting a similar, straightforward presentation of financial information.
LDG
Tricky share to understand I used to own but seemed to be a bit insular with 29% holder Dbay also being connected to Esken and using funds to invest in connected companies whilst earning management fees for their anazing efforts and ni doubt a board of directors of cronies .
Looks like 6% shareholder has called a general meeting to stir the pot , reduce fees, add a director and liquidate / stop investing .
Richard griffiths is on 15% and youd assume he will support .
NAV seems to be circa 19p .
Fair play to them for getting things moving .
Very illiquid though and any decent purchase spikes the price .
Probably limited downside and maybe 30% upside on say a 2 year period .
Chapel Down (LON:CDGP)(I hold) Not sure why the price has fallen so much. The company is discussing options for the future, which may involve a take over. The fact the CEO has now resigned makes me suspect-sadly-the latter may be the case. I was expecting figures not to be great this time, but future for CDGP and the english wine industry looks good. At the moment at least still get the 30% discount of wine as a shareholder.
And look where the CEO is going - to Timothy Taylor brewery in Yorkshire - and of course they are offering a 30% discount to shareholders - their prices are hiked up so they can rely on discounts to sell.
Equals
I spoke to a well known fund manager at Mello and asked if they had considered investing in Equals .
He said “actually yes but we found it uninvestable due to such a part of their revenue coming from onlyfans”
Maybe thats an interesting question to ask management .
Would worry quite a few potential buyers with corporate due dilligence etc .
Maybe we could ask for a stockopedia onlyfans discount
And there we have it. Both niche (questionable runway) and potentially riske….
Can you point me to a link where Equals (LON:EQLS) mention revenue from onlyfans? tia
They never mention it
It was highlighted (unearthed) by the well respected fund manager in their due dilligence
Indeed - impressive results Cairn Homes (LON:CRN) ("stellar", as they say)! So why on Earth has the share price fallen back today? Mr Market is an unpredictable beast. Alumasc (LON:ALU) saw a decent lift yesterday with lesser performance. Weird. Anyway - to be optimistic - nice opportunity to buy more!
Unfortunately UK equity funds continued to suffer outflows in August (see below).
In fact net selling of -£510m was more than double July's figure - and not too different either compared to the -£660m monthly average since outflows began in Sept'21.
I wonder if the trumpeted Tax increases are spooking people to take early gains?
Thanks - Great point Trident. The answer is certainly yes
I was listening to another excellent podcast from Paul Scott last night and he was extolling the virtues of private investors meeting companies face to face. Yellowstone Advisory is organising an in person event with 3 listed smaller companies on 25 September and you are invited to attend.
Management teams from Checkit (LON:CKT), Safestay (LON:SSTY) , Light Science Technologies Holdings (LON:LST) and 1 other will be presenting and there will be plenty of time after the presentations for informal discussions with the management teams over drinks and canapes following the formal presentations.
The event starts at 5.30pm at the offices of Hudson Sandler, 25 Charterhouse Square, London, EC1M 6AE
You can get your tickets here (no charge) Private Investor Evening | Yellowstone Advisory
Equals (LON:EQLS, how do you interpret ‘fully equity financed bid’? An all share acquisition rather than cash is my take, but it’s far from clear. Feels like it’s been cleverly worded.
I'm biased here M48 as Equals (LON:EQLS) is still my largest position.
This is what I wrote earlier on social media.
----------------------------------------------------------------------
What I love about investing, is that it teaches you patience - & tons of it. Take Equals Money, a leading fintech forex/payments platform.
The business is undoubtedly performing well. Indeed in H1’24, revenues jumped 33% to £59.96m (£45.0m LY) and cash closed Jun’24 at £20.5m
(or 10p/diluted share) augmented by an exit Q2’24 sales run-rate of £32.6m
(+40% YoY).
Yet the shares at 118p are surprisingly flat YTD. Why?
Well to me, this underperformance (+7% FTSE All Share) is simply due to the uncertainty created by the ongoing Strategic Review process, which started in Nov’23.
Moreover today the ‘Put Up or Shut Up’ period was extended by a further 4 weeks to 5pm 2nd Oct. Here American private equity house JC Flowers (re owner of UK investment platform ‘interactive investor’) has now also joined the bidding consortium (re TowerBrook Capital Partners L.P. / Railsr) in order to progress a “fully equity financed” offer, with negotiations, financing & due diligence all “at an advanced stage”.
No take-out price was detailed. Albeit on 10th July, an indicative, non-binding proposal of 135p/share (£276m fully diluted) in cash was mentioned.
Meaning that unless something crops up late in the day, then I’d expect a firm offer to be submitted to the Board shortly after Equals Money releases its H1’24 results sometime next week. The strategic logic (re cost/sales synergies) of combining the company's best-in-class forex/banking platform with both Railsr and interactive investor seems to make perfect sense.
Watch this space.
May be I've missed in past posts, but never understood how Equals managed to grow business at such a pace given it is a crowded and competitive space. Till I come someone who worked with them in past, seems their fortunes are linked to the stupendous growth of certain platforms during Covid and offering services to the these platforms/businesses (content creators) where such businesses may not have made the cut with the traditional FS providers. Question - the sources of such revenue is still growing and/or sustainable going forward? Railsr themselves have gone bust and were desperate for a buyer when the cheap credit disappeared, somehow they managed to survive (raising GBP20 mill)) and doubt the original investors made any money. The urgency to merge is likely to be driven by acquiring a customer base and improving the story and hence the valuation of the company. B2B businesses are very tricky and these fintechs are cash hogging needing a continuous dose of cash injection.
Paul, you’re no doubt right about synergies driving the deal, but be aware that Flower sold interactive investor to Abrdn (LON:ABDN) in 2022 and I’m not aware they have any residual interest.
I was an exec and investor at a large competitor to Equals for many years and while I have no detailed knowledge of this firm I do know the sector very well. The big DD hurdles are likely to be in the areas of compliance, credit or perceived runway.
Do they operate in high risk segments? Almost certainly yes from what I understand. Is this sustainable for their provisioning banks (who are almost the defacto regulators of the sector) or will banks recoil from certain providers next time there’s a sector specific scandal, which there always is within the MSB space (credit driven issues, AML, crypto, suitability etc etc). How many major banks supply Equals? We had several so were insulated to an extent, but banks can become very fickle when a problem arises. I’m not saying that there are any issues here.
My own take on equals is that credit is not the problem here as they aren’t heavily into hedging, it’s a payments driven business which is more attractive than hedging providers in my view. There are many hedging focussed bucket shops in this sector. Hedging is cash consumptive, commoditised and high risk. PE firms struggle to understand those risks.
I participated in several sale processes and our PE investors were very focussed on runway. If Equals are selling into a niche and clearing up as a result the big question will be market size within that niche. Have they already landed the big customers? There are many payments firms who break into nuanced areas with slightly tailored product/service and do well for a while but fail to develop that into a deep market opportunity. It’s hard to prove the size and addressability of a niche, I had experience of this several times.
It’s most likely to be the sectors they service that are vexing buyers. The usual culprits are gambling, other money service businesses or clients in high risk jurisdictions. Basically, clients that other firms won’t service because they are too scared of their banks giving notice. All payments firms rely completely on the banks providing them with payment rails, and banks tend to offload firms that don’t meet their shifting risk criteria. Ok firms can also use aggregators like Earthport/CurrencyCloud/Railsr, but who provides the rails for them? The big banks! Given the strong growth it also seems perplexing that they haven’t been able to drum up a proper competitive process. Any PE firm would have taken a look based on the growth rate, which means that many have likely passed on the opportunity leaving only two in the dance. This reminds me of a saying from a book I once read. ‘If you can keep your head while all around are loosing theirs, perhaps you’ve misunderstood the situation’.
For me this may well get over the line at 135, and if it doesn’t it still looks good value on the surface considering the growth rate, so there seems to be some downside protection. But I don’t hold any shares because I know that doing something a little different in this sector can present existential risks, and I suspect the impressive growth is in the nature of the client base rather than application of novel payments technologies. Just my hunch and happy to be proven wrong. While I knew most firms in the sector intimately I didn’t pay much attention to Equals and the recent growth has come rather from left field, so I do not have enough detailed knowledge to say for sure whether it’s a sector issue that’s holding up this process. Good luck to holders.
See post i just made, onlyfans apoarently a significant income stream .
That would be a red flag for many .
ii (interactive investor) is actually now owned by abdrn following a silly buy price. (and has been for some time)
Apologies.
Despite listing Interactive Investor on its corporate website, it appears JC Flowers actually sold Interactive Investor to abrdn last year.
That said elsewhere, JC Flowers does also appear to own Castle Trust Bank in the UK (re synergies with Equals)
Hi M48. To me a fully equity financed bid’ makes perfect sense.
As the PE backed consortium probably intend initially to buy Equals for cash - & then load up the balance sheet with lower priced debt once interest rates have declined in 2025.
That’s unusual and strange given the amount of time they’ve had to get lenders in place. PE never use their own cash when they can use leverage as it dilutes their IRRs. It seems more likely that they have struggled to get lenders on board and are taking the risk that they can do so after closing.
I have no idea what structure they have in mind, but was really trying to highlight wording that is (possibly deliberately chosen to be) ambiguous.
Like Jon, I’d also find it odd for debt to be introduced later given how much time has already elapsed.
What I didn’t spell out is that Flower have history here that I was previously on the end of. Paul mentioned interactive investor. Back in 2020 they were majority owned by Flower and interactive investor bid for Share plc where I was a shareholder. The bid was a fraction in cash but mostly shares in interactive investor which was unlisted.
So for a few years, I held shares in interactive investor (alongside Flower) until they organised for the ii business to be sold for cash to Abdn. Worked out well in the end, but for a fair while, I held shares that weren’t easily tradeable. I just wouldn’t rule out Equals (LON:EQLS) shareholders ending up with an offer that is dissimilar.
That said, I’m not following Equals (LON:EQLS) bid or suitors carefully so might be barking up the wrong tree. My ears were pricked by the wording though.
Gulf Marine Services (LON:GMS)
Throwing off huge amounts of cash and reducing their debts by over $5 million a month.
Trading a huge discount to their NAV.
Firming rate market with utilisation at very high levels, allowing for maintenance.
Hard to find a stock on such a low rating with such a positive outlook.
Seafox appear to be giving its shares away or have I missed something? Whenever I see something that looks particularly generous my spidey senses tingle. In any case the perceived overhang looks to be removed now.
Re GMS I hold
Excuse my ignorance Michael but what do you mean by Seafox appear to be giving it's shares away? Is it the removal of their representative on the board?
Can't understand the sp reaction this morning to what looks like another set of excellent results?
Divesting 60% of their shares to their shareholders. Some will sell and some will hold (I guess).
Debt now circa $225 million.
Assets valued at $600 million
Ebitda circa $95 million p/a.
CEO says lots of institutional interest. Let's see it.
Allows Seafox’s individual shareholders to make their own decisions, and some will sell. However, if institutional demand was so high this would not be necessary as Seafox could make disposals via placing. Seems an odd way to do it. GMS looks a bargain though.
Think it works well for both parties. Seafood can reduce their holding without dumping a large stake on the market and taking a lower price. Some of these family offices will retain and so there is less of an overhang which obviously is beneficial to GMS and it's shareholders.
That makes sense as their initial disposal was at a 15% discount. Pure speculation, but perhaps Seafox is one of the purchasers of the "estimated 18-21 new vessels" becoming operational in the next 2-3 years?
Agreed, but this in specie distribution looks pretty tax inefficient to me. Seafox will I assume pay CGT on the "book gain" and the shareholders will pay income tax on the in specie "dividend". Or am I missing something?
Eurocell (LON:ECEL) (I hold)
I've tried to limit my exposure to the building material sector as I thought the market got ahead of itself with expectations of a rapid recovery however the management here are doing an excellent job.
Focusing on operational efficiencies they are improving margins, enlarging the estate to gain future market share, paid down cash debt to negligible levels, increased the dividend and all the time have been buying back shares to enhance eps.
It has to be up there with Alumasc (LON:ALU) (which I missed) as one of the best plays in the sector in my opinion.
Thank you Paul for highlighting this one well over a year ago now.
Accsys Technologies (LON:AXS) - TU out today - short on detail - think Paul would like this - another example of big words little info with just a 3% increase in revenues. I suspect they are suffering competition from newcomers and the fact that although its producing a wood product its not actually got very green credentials. And still no word on the future of that plant in Hull.
Re Accys
Would be a reasonable investment if they could scale up manufacturing to supply potential demand. Never happened.
I actually think on a through costed basis that it is very green if you take into account the full cost of replacement of ordinary wood (circa 25 years) with the 70 year expected life of Accoya.
One for the very patient and optimistic investor.
Bit surprised at this from the FT:
Barratt’s profits fall 75% as housebuilding slows
Barratt’s profits dropped 75 per cent in the year to June as the number of homes it built fell almost a fifth and new provisions for legacy building safety issues hit its bottom line.
Housebuilders. I got them completely wrong by missing buying the 2022 lows. I haven't invested in housebuilders for a long time. I had been reluctant to load up since then, fearing I was too late.
I'm building up an approach to investing in cyclicals. For something like housebuilders, wait until you hit a five-year low in share price and PBV<1. Then buy. I haven't gotten as far as figuring out a sell strategy.
It's a similar approach I adopted for SHEL. Buy when Brent is below $40, sell when above $80. It's not a recipe for instant profit, though you should do well. I hung around with SHEL when the price was above $80, Buffett was buying oilers, and we had worldwide conflicts that pushed the price up. I hung around because I wanted to prove to myself that I had the patience to hold, even though I had figured I had made the bulk of my money. Come the new ISA season I figured it was OK to sell.
I didn't hit the exact top, but I got it pretty good, slightly more than doubling my money. Anyway, Brent is now $73, so I am very happy with my call.
The upshot is, I think, that there is a lot of money to be made in cyclicals if there's a lot of doom in the sector and price is clearly cheap.
I think they're targets of opportunity, though. You either get the "fat pitch" opportunities, or you don't. Most of the time, you don't.
I'm also sceptical of the narrative that interest rates are going to go down. The UK and US seem to be pursuing inflationary policies to me, so I think it is less than obvious that the market consensus of reduced interest rates will come to pass.
I get the argument that there is a structural shortage of housing in the UK. I'm still not in housebuilders, though. I do have a small position in British Land (LON:BLND) though, where I had miraculous timing on buying.
Another worthwhile strategy, I think, it to look at REITs. TR Property Investment Trust (LON:TRY) seems really well managed to me. There are lots of good ones in the sector, I think. Here, I think the trick is to wait until they post a loss, and then buy. Again, we're not at that stage at the moment.
Just food for thought.
Pollen Street (LON:POLN) interim results look solid. Growing AUM steadily. £4.8bn at end of July. High dividend, although lower on a per share basis because of prior year waivers. Share buy-backs. I hold. It would be good if Graham could cover today.
My morning smallcap tweet: The wages of spin
Smarttech247 (LON:S247) Eurocell (LON:ECEL) Gelion (LON:GELN) Accsys Technologies (LON:AXS) EQTEC (LON:EQT) Logistics Development (LON:LDG) Pinewood Technologies (LON:PINE) Chapel Down (LON:CDGP) Shield Therapeutics (LON:STX) Equals (LON:EQLS), James Cropper (LON:CRPR), Pollen Street (LON:POLN), Cab Payments Holdings (LON:CABP), Cirata (LON:CRTA)
◄Smarttech247 (S247)► adopts new route to market strategy as part of its wider growth plans. Will hire more staff over next 12 months. "Greater emphasis on channel and strategic partnerships to target rapid expansion whilst enhancing customer value across its global customer base...empower partners...leverage the successful partnerships the Company has curated." Curated? I'm out. [SP=15 Cap=19m]
◄Eurocell (ECEL)► another buyback, £5m max. Trading in line. [SP=145 Cap=151m]
◄Gelion (GELN)► reaches energy density milestone of 402 Wh/Kg in a 12 Ah Lithium-Sulfur battery. [SP=22 Cap=30m]
◄Accsys Technologies (AXS)► Q1 rev up 3%. "A good start to Q2 and a healthy order book across the regions, providing confidence the Group is back on a growth trajectory." [SP=52 Cap=124m]
◄EQTEC (EQT)► full amount (£2m) received under the settlement agreement with Logik Developments. [SP=1.22 Cap=3m]
◄Logistics Development (LDG)► gets GM requisition with motion to "cease making new investments and prioritise the timely return of capital to shareholders". [SP=11.13 Cap=58m]
◄Pinewood Technologies (PINE)► to buy unspecified stake in Seez App Holding for $4.2m. "Seez is one of the world's leading automotive AI companies." [SP=345 Cap=301m]
◄Chapel Down (CDGP)► H1-June rev down 11%. Pretax down 98%. Stock up up 49% to c.£22m after exceptional harvest. Outlook - "One-off factors have impacted H1 trading, so the Board is now expecting single digit net sales revenue growth for the year, with a previously noted return to normalised profit levels." [SP=69.66 Cap=119m]
◄Shield Therapeutics (STX)► H1-June rev up 3.2x. Outlook - unspecific with lots of hope. "Based on our internal assumptions we remain funded to deliver on our growth plans." [SP=5.3 Cap=41m]
◄Equals (EQLS)► PUSU extended to 2 Oct. Insane. JC Flowers joins bidding consortium. [SP=119 Cap=224m]. I hold.
In line: CRPR, POLN, CABP, CRTA
Thanks as always for your superb summaries. EQTEC (LON:EQT) is also raising £1.1m to £1.3m through a placing and retail offer at 1p.
Can't see Mr Contrarian comment. Hope he's alright.
Cairn Homes (LON:CRN) appears to have smashed it out of the park. The only thing down is net debt. Hopefully Graham gets a chance to have a look.
Cairn Homes (LON:CRN) is benefiting from a comprehensive Irish housing initive developed in 2021 called, "Housing for All" . The summary of this initiative is....
The State must act decisively to increase supply of both private and public housing. An average of 33,000 homes must be provided every year between now and 2030.
It a shame that the UK lacks the same focus.
The UK is aligned with NATO ( No Action Talk Only )
Thanks Bob - a timely reminder as this has been on my Watchlist for a while.
Another PUSU extension at Equals (LON:EQLS). Yawn
I've been reading the 6 months results for Cairn Homes (LON:CRN) (I hold) and I've actually had to reread this a few times as I cannot recall such an impressive update on all metrics!
Profit up. Cashflow up (quite a lot). Margins up. Forward sales up. Debt down. I did try to put some figures in but my laptop crashed and the kids obviously want a full english this morning.
And it's STILL cheap! Div is still at over 5% with easy room for more.
I'd love to add more, but need to sell and when I bought it was initially for the divis with a view to a rerating, my avg buy in price is just over £1. Might have to top up the missus' ISA!
Whilst this is at a 52 week high there should be rocket under this today.
Viz , I also hold [one of my largest positions these days] . Found from using CDRefs sieve ,at some where in the 90p's ,and adding up to 130p ..
I would add to your every metric 'up' comment, divi increase 23% . Also , I think it's since my original buy they have daily bought back shares - so take that into additional consideration when you mention debt reduction . The volume DAILY has been between 100000,and 200000 shares / DAY
Satisfied holder .Tony
Yes, Tony I have spent this morning reflecting on this. As you say, the drop in sharecount and increased divi has seen me add to my already large(ish) position, I have increased by about 30% today.
One other small point ,I should have included, subject of course to costs remaining steady. I believe we will see an upgrade for 2025 figs
In the Times recently, they did a write up on them buying another substantial site with planning permission. It was behind a firewall ,but the BB'er was suggesting the developement was for a further 800 units ,and there was a further substantial site alongside ,for sale .
Next years figs are good ,but I'm hoping they might be even better.
At 162p. I sold a few £K ,and added a few Epwin , which gets a decent set of figs, from stoko too . Just got worried about the portfolio %age.
Best of luck with your decision , for myself I have no plans to reduce further till we hit 200p ,as the %age could could get a trifle worrying in case of any downturn.
Currently Ireland financially, is smashing it by comparison with UK although they are in a similar housing shortage ,as CRN report. Cheers Tony
Following some reading on here recently, I like the idea of running a more concentrated portfolio, so makes me consider what investments I have and what for. In this case, I sold a high ex div stock, and then upped my holdings. It's a new world out there when you buy at the top - but again, buying into momentum is also another takeaway from me in the last couple of year + the dividend was the clincher.
Whilst I don't think we'll return to Celtic Tiger levels, I do think currently building in Ireland is on the up and has the potential to increase when the government is pumping money into projects together with foreign investment. I have been looking at buying a house there and have been surprised by the levels of demand, north and south.
Thanks Viv re Cairn Homes (LON:CRN), and yet no change at 4.25
In line with the US East coast hurricane season - Autumn is traditionally painful for investors. Think Black Monday on 19th Oct'87!
So with a barrage of key economic data coming out over the next few weeks - not least Friday's crucial US payrolls report for August (Est +160k vs 114k July, 4.2% unemployment vs 4.3% July).
Then its not too surprisingly that markets are again in skittish mood (see below).
That said on the economic front, little seems to have changed over the past few weeks.
American GDP is slowing (Est Q3 at 2.0% - Atlanta Fed) & may (at worst) suffer a short technical recession after a period of over-consumption. Whereas the UK, Europe & Japan all appear to have stabilised, & if anything are likely to continue chugging along.
To me, the big wild-card is China, & whether they'll try to export themselves (eg EVs, chemicals, electronics, steel, etc) back to prosperity. Despite facing an avalanche of import tariffs from other countries - & potentially triggering a major global trade war.
Big picture though, this type of 'volatility' is 'normal' - and simply part of the many 'joys' of long term investing.
Does anyone have a spare hard hat!
Cant see how any of the above affects a single company I own .
Croma will open their doors today at 9am and sell a bit of stuff
Wynnstay will sell some stuff to farmers
Bloomsbury will sell a few books .
Does make me wonder how anyone can cope trying to interpret world economic events into a company valuation metrics .
Sure the stock markets might be choppy and I do hope the big 7 get a good kicking .
You're right Planetx it doesn't affect your companies on a trading basis but it does affect appetite for risk and flows into equities which affects how they are priced.
But I agree with you and as a long term investor I try to think like an owner, this is short term noise, head down and get on with it.
Market volatility is good for PIs like us as it creates cheaper buying opportunities in companies we know and like.
Yes, agreed that there could be a very choppy Q4. I'm not a charting expert, but it looks a possible double-top on the S&P500 and Nvidia. Time will tell as there is no bell at the top! In my view, there is considerably more downside risk in the US (the only market that matters at the moment) than upside potential.
Dr Sandy Nairn's brief commentary is always worth reading - Global Opportunities Trust (LON:GOT) half year results today. You can see what he thinks is going to happen!
October 19th 87 is burnt into my brain Paul, I'd been writing put options way beyond my expertise and balance sheet. The sky fell in for several days - this does not feel like 87 to me as it's a calmer retreat so far, in some cases from over extended levels. I'm with planetx on this, Cairn will be slapping mortar between bricks today and Eurocell will sell a few more garden rooms. Payrolls on Friday will be interesting and I agree with your overall summary, thank you for the heads-up.
In my view the perception of facts are more important than the facts. I am pretty bearish, i think we are entering a risk off phase in the US market especially because the election is likely to be so close. The UK market will not be unscathed but does have the advantage of being on a modest rating. I think cash / gold/ silver is the place to be.
Sept / Oct seemingly does have one event or another which hammers markets and as stated in others responses, good companies remain good companies even if their share price is affected in the short term.
It does appear that every bit of macros data is having a pronounced effect. Maybe fear of the stellar run in US markets being due a correction alongside nervouness around the US election and our forthcoming budget in the UK?
Whatever the cause, this will hopefully be one of those occasions that presents good buying opportunities for investors with a view beyond the next few months.